Spain Stainless Steel Seamless Pipes Market (2024-2029)

The Spain Stainless Steel Seamless Pipes Market was valued at $63 Million in 2024 and projected to reach to $69 Million by 2029, representing a compound annual growth rate of 4.3%. Spain's stainless steel seamless pipes market is positioned for steady growth through 2029, supported by ongoing investments in chemical processing infrastructure and industrial manufacturing modernization.


| Market Size in | USD 26.32 MN |
| Market Forecast in | |
| CAGR | |
| Forecast Period | |
| Units Considered | Value (USD MN) |
Spain Stainless Steel Seamless Pipes Market Trends and Insights
- Spain's market is driven by demand from the oil and gas, chemical processing, and industrial manufacturing sectors, which rely on seamless pipes for high-pressure and corrosion-resistant applications.
- The Spanish market benefits from the country's established industrial base and proximity to key European supply chains. During the forecast period from 2024 to 2029, Spain is expected to experience steady growth supported by infrastructure investments and increased adoption of stainless steel seamless pipes in renewable energy projects and desalination plants.
- Spain's strategic position within the European Union enhances its role as both a consumer and distribution hub for seamless pipe products.
- Market expansion in Spain will be influenced by regulatory standards, raw material availability, and the country's industrial modernization..
Key Market Statistics
- CAGR (2024-2029) 4.3% CAGR
- Market Size, 2024 ~USD 63 Million
- Forecast, 2029 ~USD 69 Million
- Country Spain
Spain Stainless Steel Seamless Pipes Market Overview
Market Valuation :
Spain's stainless steel seamless pipes market reached USD 63.0 million in 2024, with steady growth projected to USD 69.0 million by 2029.
Growth Rate :
The Spanish market is expanding at a CAGR of 4.3%, slightly below the global average of 5.8%, indicating moderate but consistent demand growth.
Key End-Use Sectors :
Spain's market is primarily driven by oil and gas, chemical processing, and industrial manufacturing sectors requiring high-pressure and corrosion-resistant piping solutions.
Application Focus :
Seamless pipes in Spain are essential for demanding applications requiring superior reliability, pressure handling, and resistance to corrosive environments across multiple industries.
Spain Stainless Steel Seamless Pipes Market Dynamics
- The country's strategic location within Europe and established industrial base continue to drive demand for high-quality seamless pipe solutions.
- However, growth remains moderate compared to global trends, reflecting Spain's mature industrial landscape and competitive market dynamics.
- Regional economic conditions and European industrial policies will significantly influence market trajectory over the forecast period..
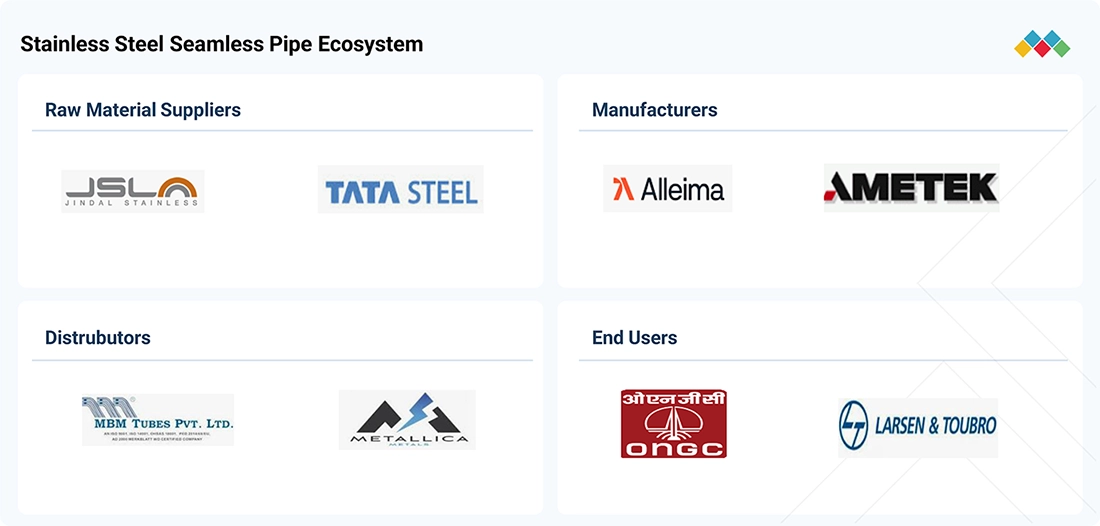
Market Ecosystem
STAINLESS STEEL SEAMLESS PIPES MARKET: COMMERCIAL USE CASES ACROSS INDUSTRIES
| COMPANY | USE CASE DESCRIPTION | BENEFITS |
|---|---|---|
 |
Seamless stainless steel and high-alloy pipes and tubes, including austenitic and duplex grades such as 304/304L, 316/316L, and 2205, used in oil & gas, chemical & petrochemical, power generation, and industrial process applications | Provides high corrosion resistance and strength under high pressure and temperature, improves dimensional accuracy and quality consistency, and supports longer service life in harsh, chloride-rich environments and offers a broad grade and size range for demanding process piping |
 |
Seamless stainless steel and duplex tubes and pipes, including 2205 and super duplex grades, used in oil & gas, chemical & petrochemical, power, and aerospace applications, as well as in heat exchangers and process instrumentation | Delivers high strength, excellent resistance to pitting and stress corrosion cracking, and thinner-wall designs that reduce weight and material cost; supports reliable long-term performance in aggressive environments due to tight tolerances and consistent quality support |
 |
Seamless tubular solutions, including high-alloy and corrosion-resistant grades, used in oil & gas, power generation, chemical & petrochemical, and industrial equipment applications | Offers reliable performance under high pressure, temperature, and corrosive conditions; supports safety, durability, and lower maintenance; and serves emerging applications such as hydrogen and carbon capture |
 |
Precision stainless steel seamless tubing, through its specialty metals business (Superior Tube), used in aerospace & defense, automotive, medical, and industrial equipment applications | Enables tight dimensional tolerances, high strength-to-weight ratio and consistent metallurgical quality and supports lightweight, heat-resistant, high-precision components for critical, high-performance applications |
Logos and trademarks shown above are the property of their respective owners. Their use here is for informational and illustrative purposes only.
Related Ecosystem
Equipment Machine And Tooling
- Wastewater Treatment
- Air Cooled Heat Exchangers
- Diaphragm Pumps
- Fiberglass
- HVAC System
- Alfa Laval Corporate AB
- Veolia
- Johnson Controls International plc
- Daikin Industries,Ltd.
- Parker-Hannifin Corporation
Infrastructure Material
- Alumina Ceramics
- Ceramic Coatings
- Monolithic Ceramics
- Polyphenylene Sulfide (PPS)
- Titanate Ceramics
- Saint-gobain
- Simpson Manufacturing Co., Inc.
- DOW CHEMICAL COMPANY
- Basf se
- Sika ag
Key Takeaways
- Spain's stainless steel seamless pipes market is valued at USD 63.0 million in 2024 and will reach USD 69.0 million by 2029 at a 4.3% CAGR.
- Spain's market growth is driven by demand from oil and gas, chemical processing, and renewable energy sectors requiring corrosion-resistant piping solutions.
- Spain's EU membership and industrial infrastructure position the country as a key distribution and manufacturing hub for seamless pipes in Europe.
- Infrastructure investments and desalination projects in Spain are expected to support steady market expansion through 2029.
Stainless Steel Seamless Pipes Market Report Scope
| Report Metric | Details |
|---|---|
| Base Year | 2024 |
| Fastest Growing Segment | 2205 (Grade) |
| Forecast Period | 2024–2029 |
| Growth Rate | CAGR of 5.8% from 2024 to 2029 |
| Largest Segment | PIERCING (Technology) |
| Market Size Base Year (Billions) | ~USD 3.67 (2024) |
| Revenue Forecast (Billions) | ~USD 5.15 (2029) |
| Segments Covered | End-Use Industry, Grade, Technology |
Spain Stainless Steel Seamless Pipes Market Report Segmentation
3 segment dimensions are covered across the global market.
By End-Use Industry
- Aerospace & Defense
- Automotive
- Chemical & Petrochemical
- Energy & Power
- Energy & Power (Exc. Nuclear)
- Food & Beverage
- Industrial Equipment
- Oil & Gas
- Other End-Use Industries
- Water & Wastewater Treatment
By Grade
- 2205
- 304/304L
- 316/316L
- 430
- Other Grades
By Technology
- Extrusion
- Piercing
SPAIN: STAINLESS STEEL SEAMLESS PIPES MARKET, BY END-USE INDUSTRY, 2025–2030
| Segment | 2025 | 2026 | 2027 | 2028 | 2029 | 2030 | CAGR (%) |
|---|---|---|---|---|---|---|---|
| AEROSPACE & DEFENSE | 1.6 | 1.7 | 1.8 | 2 | 2.1 | 2.3 | 7.4 |
| AUTOMOTIVE | 11.3 | 11.6 | 12.2 | 12.8 | 13.4 | 14.1 | 4.5 |
| CHEMICAL & PETROCHEMICAL | 8.9 | 9.2 | 9.6 | 10 | 10.4 | 10.9 | 4 |
| ENERGY & POWER (EXC. NUCLEAR) | 14.5 | 14.9 | 15.6 | 16.3 | 17 | 17.8 | 4.1 |
| FOOD & BEVERAGE | 7 | 7.2 | 7.5 | 7.8 | 8.2 | 8.5 | 4.1 |
| INDUSTRIAL EQUIPMENT | 5.3 | 5.4 | 5.7 | 5.9 | 6.2 | 6.5 | 4.5 |
| OIL & GAS | 1.5 | 1.6 | 1.6 | 1.7 | 1.8 | 1.9 | 4 |
| OTHER END-USE INDUSTRIES | 1.4 | 1.4 | 1.5 | 1.5 | 1.6 | 1.7 | 3.5 |
| WATER & WASTEWATER TREATMENT | 4.4 | 4.5 | 4.7 | 4.9 | 5.2 | 5.4 | 4.4 |
| TOTAL | 55.9 | 57.6 | 60.2 | 63 | 65.8 | 69 | 4.3 |
Target Audience
- Stainless Steel Manufacturers : Spanish and European seamless pipe producers need market sizing and growth forecasts to optimize production capacity, R&D investments, and competitive strategies.
- Oil & Gas Operators : Companies operating in Spain's oil and gas sector require market intelligence to assess supplier availability, pricing trends, and sourcing opportunities for seamless pipes.
- Chemical Processing Companies : Spanish chemical manufacturers and processors need data on seamless pipe availability and market dynamics to plan infrastructure upgrades and equipment procurement.
- Industrial Distributors : Pipe distributors and trading companies in Spain require market forecasts and segment analysis to optimize inventory, identify growth opportunities, and plan expansion.
- Investment & Strategy Teams : Private equity, venture capital, and corporate strategy teams evaluating Spain's industrial materials sector need market validation and growth projections for investment decisions.
Key Companies in the Spain Stainless Steel Seamless Pipes Market
| Company | HQ | Ownership | Strongest segments |
|---|---|---|---|
| NIPPON STEEL CORPORATION | Japan | Public Company | Austenitic stainless seamless pipes,Ferritic stainless seamless pipes,Duplex and super-duplex stainless seamless pipes, |
| ALLEIMA | Sweden | Public Company | Austenitic stainless seamless pipes,Duplex stainless seamless pipes,Ferritic stainless seamless pipes, |
| VALLOUREC | France | Public Company | Austenitic Stainless Steel Seamless Pipes,Ferritic Stainless Steel Seamless Pipes,Duplex Stainless Steel Seamless Pipes, |
| AMETEK, INC. | United States | Public Company | Austenitic stainless seamless pipes,Duplex stainless seamless pipes,Ferritic stainless seamless pipes, |
| JFE STEEL CORPORATION | Japan | Private Company | Austenitic stainless seamless pipes,Ferritic stainless seamless pipes,Duplex and super-duplex stainless seamless pipes, |
| TENARIS | Luxembourg | Public Company | Austenitic stainless seamless pipes,Ferritic stainless seamless pipes,Duplex and super-duplex stainless seamless pipes, |
| JINDAL SAW LTD. | India | Public Company | Austenitic stainless seamless pipes,Ferritic stainless seamless pipes,Duplex and super-duplex stainless seamless pipes, |
| ISMT LIMITED | India | Private Company | Austenitic stainless seamless pipes,Ferritic stainless seamless pipes,Duplex stainless seamless pipes, |
| TUBACEX S.A. | Spain | Public Company | Austenitic stainless seamless pipes and tubes,Ferritic stainless seamless pipes and tubes,Duplex and super-duplex stainless seamless pipes and tubes, |
| RATNAMANI METALS & TUBES LTD. | India | Public Company | Austenitic stainless seamless pipes & tubes (incl. heat exchanger/boiler/instrumentation),Ferritic stainless seamless pipes & tubes,Duplex and high-alloy stainless seamless pipes & tubes, |
| VENUS PIPES AND TUBES | India | Public Company | Austenitic seamless pipes & tubes,Ferritic seamless pipes & tubes,Duplex and higher-alloy seamless, |
NIPPON STEEL CORPORATION
Nippon Steel Corporation is a Japanese public company founded in 1950 with 138,453 employees, serving as one of Japan's major steel manufacturers.
ALLEIMA
Alleima is a Swedish public company established in 1862, operating in the industrial materials and engineering sector.
VALLOUREC
Vallourec is a French public company founded in 1890 with 13,000 employees, specializing in steel pipe manufacturing and related products.
AMETEK, INC.
AMETEK, Inc. is a United States-based public company founded in 1930 with 22,500 employees, providing electronic instruments and electromechanical devices.
JFE STEEL CORPORATION
JFE Steel Corporation is a Japanese private company founded in 1950 with 42,923 employees, operating as a major steel producer.
TENARIS
Tenaris is a Luxembourg-based public company founded in 2001 with 25,169 employees, specializing in steel pipe manufacturing and services.
JINDAL SAW LTD.
Jindal SAW Ltd. is an Indian public company founded in 1984 with 7,565 employees, engaged in the manufacture of welded steel pipes and tubes.
ISMT LIMITED
ISMT Limited is an Indian private company founded in 1977 with 1,878 employees, operating in the steel and manufacturing sector.
TUBACEX S.A.
Tubacex S.A. is a Spanish public company founded in 1963 with 2,755 employees, specializing in the production of stainless steel tubes.
RATNAMANI METALS & TUBES LTD.
Ratnamani Metals & Tubes Ltd. is an Indian public company founded in 1983 with 3,324 employees, manufacturing seamless steel tubes and pipes.
VENUS PIPES AND TUBES
Venus Pipes and Tubes is an Indian public company founded in 2015 with 825 employees, engaged in the manufacture of steel pipes and tubes.
Reasons to Buy this Report
- Market-Specific Sizing Data : Access precise valuation figures for Spain's market (USD 63M in 2024) with detailed 5-year forecasts, enabling accurate budget allocation and investment planning.
- Sector-Focused Insights : Understand demand drivers specific to Spain's oil and gas, chemical processing, and manufacturing sectors to identify high-potential customer segments and applications.
- Competitive Positioning : Benchmark Spain's 4.3% CAGR against global growth rates to assess market maturity, competitive intensity, and opportunities for market share expansion.
- Strategic Market Entry : Leverage Spain-specific market intelligence to develop localized go-to-market strategies, distribution partnerships, and product positioning for the European market.
- Forecast-Driven Planning : Utilize 2029 projections (USD 69M) to align production capacity, supply chain investments, and sales targets with anticipated market growth trajectories.
Frequently asked questions
What is the current market size of stainless steel seamless pipes in Spain?
Spain's stainless steel seamless pipes market was valued at USD 63.0 million in 2024.
What is the projected market size for stainless steel seamless pipes in Spain by 2029?
Spain's stainless steel seamless pipes market is projected to reach USD 69.0 million by 2029.
What is the CAGR for Spain's stainless steel seamless pipes market?
Spain's stainless steel seamless pipes market is expected to grow at a compound annual growth rate (CAGR) of 4.3% from 2024 to 2029.
Which industries drive demand for seamless pipes in Spain?
Spain's demand for stainless steel seamless pipes is primarily driven by the oil and gas, chemical processing, industrial manufacturing, renewable energy, and desalination sectors.
Why is Spain an important market for stainless steel seamless pipes?
Spain's established industrial base, EU membership, strategic location within Europe, and ongoing infrastructure and renewable energy investments make it a significant market for seamless pipe products.
RESEARCH METHODOLOGY
The study involved four major activities in estimating the market size of the stainless steel seamless pipes market. Exhaustive secondary research was done to collect information on the market, the peer market, and the parent market. The next step was to validate these findings, assumptions, and sizing with industry experts across the value chain through primary research. Both top-down and bottom-up approaches were employed to estimate the complete market size. Thereafter, the market breakdown and data triangulation procedures were used to estimate the market size of the segments and subsegments.
Secondary Research
In the secondary research process, various secondary sources were referred to for identifying and collecting information for this study. These secondary sources include annual reports, press releases, investor presentations of companies, white papers, certified publications, trade directories, articles from recognized authors, the gold standard and silver standard websites, and databases.
Secondary research was used to obtain key information about the value chain of the industry, the monetary chain of the market, the total pool of key players, market classification, and segmentation according to industry trends to the bottom-most level and regional markets. It was also used to obtain information about the key developments from a market-oriented perspective.
Primary Research
The stainless steel seamless pipes market comprises several stakeholders in the value chain, which include raw material suppliers, manufacturers, distributors, and end users. Various primary sources from the supply and demand sides of the stainless steel seamless pipes market were interviewed to obtain qualitative and quantitative information. The primary interviewees from the demand side include key opinion leaders in the chemicals sectors. The primary sources from the supply side include manufacturers, associations, and institutions involved in the stainless steel seamless pipes industry.
Primary interviews were conducted to gather insights such as market statistics, data on revenue collected from the products and services, market breakdowns, market size estimations, market forecasting, and data triangulation. Primary research also helped in understanding the various trends related to grade, technology, end-use industry, and region. Stakeholders from the demand side, such as CIOs, CTOs, and CSOs, were interviewed to understand the buyer’s perspective on the suppliers, products, fabricators, and their current usage of the stainless steel seamless pipes market and the outlook of their business, which will affect the overall market.
The breakdown of profiles of the primary interviewees is illustrated in the figure below:
Note: Tier 1, Tier 2, and Tier 3 companies are classified based on their market revenue in 2025 available in the public domain, product portfolios, and geographical presence.
To know about the assumptions considered for the study, download the pdf brochure
Market Size Estimation
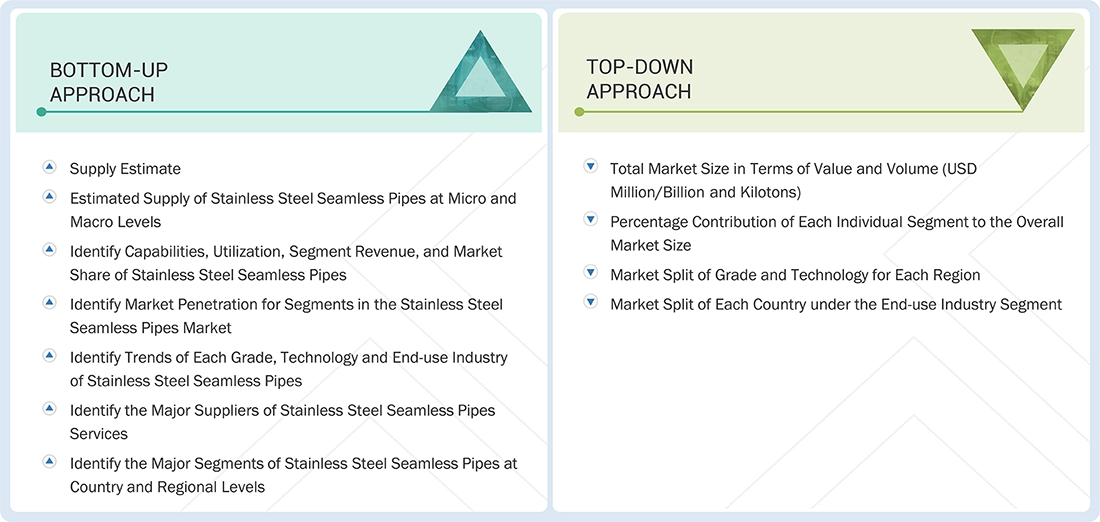
The top-down approach was used to estimate and validate the size of various submarkets for stainless steel seamless pipes for each region. The research methodology used to estimate the market size included the following steps:
The key players in the industry were identified through extensive secondary research.
The industry's supply chain was determined through primary and secondary research.
All percentage shares, splits, and breakdowns were determined using secondary sources and verified through primary sources.
All possible parameters that affect the markets covered in this research study were accounted for, viewed in extensive detail, verified through primary research, and analyzed to obtain the final quantitative and qualitative data.
The research includes the study of reports, reviews, and newsletters of the key market players, along with extensive interviews for opinions with leaders such as directors and marketing executives.
Stainless Steel Seamless Pipes Market: Top-Down and Bottom-Up Approach
Data Triangulation
After arriving at the overall market size using the market size estimation processes explained above, the market was split into several segments and subsegments. The data triangulation and market breakup procedures were employed, wherever applicable, to complete the overall market engineering process and arrive at the exact statistics of each market segment and subsegment. The data was triangulated by studying various factors and trends from both the demand and supply sides.
Market Definition
The stainless steel seamless pipes market encompasses the manufacturing, distribution, and consumption of seamless pipes made from stainless steel without welded joints. These pipes offer high corrosion resistance, mechanical strength, and durability, making them suitable for demanding applications across the oil & gas, chemical processing, power generation, automotive, construction, and food processing industries. Market growth is driven by increasing demand for high-performance materials, advancements in manufacturing technologies, and the need for reliable piping solutions capable of withstanding harsh operating conditions. Industrial development, material innovations, and stringent environmental regulations further influence market growth.
Key Stakeholders
- Stainless steel seamless pipes manufacturers
- Distributors and suppliers of stainless steel seamless pipes
- End users of stainless steel seamless pipes
- Retailers of stainless steel seamless pipes
Report Objectives
- To define, describe, and forecast the size of the stainless steel seamless pipes market, in terms of value and volume
- To provide detailed information regarding the major factors (drivers, opportunities, restraints, and challenges) influencing the growth of the market
- To estimate and forecast the market size based on grade, technology, end-use industry, and region
- To forecast the size of the market with respect to major regions, namely, Europe, North America, Asia Pacific, Middle East & Africa, and South America, along with their key countries
- To strategically analyze micromarkets with respect to individual growth trends, prospects, and their contribution to the overall market
- To analyze opportunities in the market for stakeholders and provide a competitive landscape of market leaders
- To analyze recent developments such as expansions, product launches, partnerships & agreements, and acquisitions in the market
- To strategically profile key market players and comprehensively analyze their core competencies
Available customizations:
Along with the given market data, MarketsandMarkets offers customizations according to the company’s specific needs. The following customization options are available for the report:
Regional Analysis
- Further breakdown of a region with respect to a particular country or additional grade
Company Information
- Detailed analysis and profiles of additional market players
Tariff and Regulations
-
Regulations and impact on the stainless steel seamless pipes market
Get the Full Stainless Steel Seamless Pipes Market Report
Full forecast, segment splits, and company analysis for all Stainless Steel Seamless Pipes Market.
- China Stainless Steel Seamless Pipes Market
- Japan Stainless Steel Seamless Pipes Market
- India Stainless Steel Seamless Pipes Market
- South Korea Stainless Steel Seamless Pipes Market
- Canada Stainless Steel Seamless Pipes Market
- Mexico Stainless Steel Seamless Pipes Market
- US Stainless Steel Seamless Pipes Market
- Germany Stainless Steel Seamless Pipes Market
- Italy Stainless Steel Seamless Pipes Market
- France Stainless Steel Seamless Pipes Market
- UK Stainless Steel Seamless Pipes Market
- South Africa Stainless Steel Seamless Pipes Market
- Argentina Stainless Steel Seamless Pipes Market
- Brazil Stainless Steel Seamless Pipes Market
- Rest Of Europe Stainless Steel Seamless Pipes Market
- Rest Of Asia Pacific Stainless Steel Seamless Pipes Market
- GCC Countries Stainless Steel Seamless Pipes Market
- –Rest Of GCC Countries Stainless Steel Seamless Pipes Market
Need a Tailored Report?
Customize this report to your needs
Get 10% FREE Customization
Customize This Report
