North America Welding Equipment, Accessories, and Consumables Market (2025-2030)

The North America Welding Equipment, Accessories, and Consumables Market was valued at $7886.5 Million in 2025 and projected to reach to $9377.8 Million by 2030, representing a compound annual growth rate of 3.52%. North America's welding equipment market is positioned for steady expansion through 2030, driven by sustained infrastructure investments, manufacturing recovery, and technological advancements in welding processes.


| Market Size in | USD 26.32 MN |
| Market Forecast in | |
| CAGR | |
| Forecast Period | |
| Units Considered | Value (USD MN) |
North America Welding Equipment, Accessories, and Consumables Market Trends and Insights
- This regional market benefits from robust demand across packaging, construction, mining, and gases sectors, where welding remains a critical manufacturing and infrastructure process.
- North America's established industrial base, coupled with ongoing infrastructure investments and manufacturing modernization, supports steady market expansion through the forecast period. The North America welding market is characterized by mature supply chains, technological advancement, and strong regulatory frameworks that drive adoption of high-performance equipment and consumables.
- North America's competitive landscape includes both multinational equipment manufacturers and specialized regional suppliers serving diverse end-user segments.
- Growth in North America is underpinned by replacement cycles for aging equipment, increased automation in manufacturing, and rising demand from construction and mining sectors recovering post-pandemic..
Key Market Statistics
- CAGR (2025-2030) 3.52% CAGR
- Market Size, 2025 ~USD 7886.5 Million
- Forecast, 2030 ~USD 9377.8 Million
- Geography North America
North America Welding Equipment, Accessories, and Consumables Market Overview
Market Valuation & Growth :
North America's welding equipment, accessories, and consumables market is valued at $7,886.5 million in 2025, with a projected expansion to $9,377.8 million by 2030, demonstrating steady growth at a 3.52% CAGR.
US Market Dominance :
The United States represents the largest market segment in North America at $7,357 million, driving regional demand through advanced manufacturing, infrastructure development, and industrial construction projects.
Multi-Sector Demand :
Robust demand across packaging, construction, mining, and gases sectors sustains market growth, with welding remaining a critical process for manufacturing and infrastructure development throughout the region.
Regional Growth Outpacing Global :
North America's 3.52% CAGR exceeds the global market growth rate of 3.29%, indicating stronger regional economic activity and industrial investment compared to worldwide trends.
North America Welding Equipment, Accessories, and Consumables Market Dynamics
- The region's mature industrial base and stringent quality standards support premium equipment adoption and consumables demand across construction, mining, and packaging sectors. Canada and Mexico contribute significantly to regional growth, complementing the dominant US market.
- Increasing automation in manufacturing, coupled with infrastructure modernization initiatives, will continue to fuel demand for advanced welding solutions.
- The market's resilience reflects North America's commitment to maintaining competitive manufacturing capabilities and infrastructure development..
Market Ecosystem

Welding Equipment, Accessories, and Consumables Market: COMMERCIAL USE CASES ACROSS INDUSTRIES
| COMPANY | USE CASE DESCRIPTION | BENEFITS |
|---|---|---|
 |
Lou-Rich deployed a series of automated robotic welding cells at its fabrication facilities to streamline its welding operations. The cells integrate robotic arms, precision positioners, automated wire feeders, and motion control to weld repetitive assemblies (such as structural frames, chassis components, and sheet-metal subassemblies). This mechanized setup enables continuous operation across shifts and ensures consistent weld quality across high volume runs. | The robotic welding cells enabled Lou-Rich to achieve higher throughput through continuous, unattended operation. They ensured uniform weld quality and reduced variability across production batches. By automating repetitive welds, the company reduced dependency on skilled manual welders, addressed labor shortages, and minimized scrap and rework. Overall, the solution improved production efficiency while delivering long-term cost savings and return on investment. |
 |
Kawasaki Motors Manufacturing (KMM) implemented multiple robotic arc welding systems across its ATV and utility vehicle frame production lines. These included dedicated cells handling small to large components and feeding into a centralized robotic welding station. The goal was maintaining high production volumes while enhancing consistency and minimizing reliance on manual welding. | By automating approximately 80% of its arc welding operations, KMM significantly reduced weld inconsistency and frame distortion. The robots delivered high repeatability, enabling precise and consistent welds without requiring advanced vision systems. The cells' flexibility allowed the company to handle different part geometries with minimal setup changes. This improved product quality and allowed skilled welders to shift focus to critical inspections and complex welds, improving overall workflow efficiency. |
 |
McCorvey Sheet Metal evaluated WeldComputer’s adaptive welding control system by integrating it into existing resistance seam welders. This temporary, noninvasive installation enabled real-world testing of the technology's impact on performance and energy efficiency within the company’s production environment. | The evaluation showed significant improvements in electrical efficiency, with power factor consistently maintained between 85–90% and peak energy demand reduced by up to 74%. The RMS current draw dropped significantly, cutting overall energy consumption. In addition to energy savings, the adaptive controls enhanced weld consistency and stability, improving product quality. The low-risk evaluation approach allowed McCorvey to validate the technology's benefits before committing to a full-scale rollout. |
Logos and trademarks shown above are the property of their respective owners. Their use here is for informational and illustrative purposes only.
Related Ecosystem
Mining Minerals And Metals
- Wastewater Treatment
- Fiberglass
- Light Commercial Vehicles (LCVs)
- Nitrogen
- Acetic Acid
- LHOIST S.A
- SEVERSTAL JSC
- ArcelorMittal S.A.
- TW METALS, INC.
- Linde plc
Key Takeaways
- North America's welding market is valued at $7.89 billion in 2025 and will grow to $9.38 billion by 2030 at a 3.52% CAGR.
- North America benefits from strong demand across construction, mining, packaging, and industrial gases sectors driving equipment and consumables adoption.
- North America's mature industrial infrastructure and regulatory standards support premium equipment sales and advanced consumables uptake.
- North America's market growth is fueled by equipment replacement cycles, manufacturing automation, and post-pandemic sector recovery.
Welding Equipment, Accessories, and Consumables Market Report Scope
| Report Metric | Details |
|---|---|
| Base Year | 2025 |
| Fastest Growing Segment | 50-150 KILOGRAM PAYLOAD (Payload) |
| Forecast Period | 2025-2030 |
| Growth Rate | CAGR of 3.29% from 2025 to 2030 |
| Largest Segment | ARC WELDING (Technology) |
| Market Size Base Year (Billions) | ~USD 35.84 (2025) |
| Revenue Forecast (Billions) | ~USD 42.14 (2030) |
| Segments Covered | Equipment, Accessory, Consumable, Technology, End-Use Industry, Type, Payload, End User |
North America Welding Equipment, Accessories, and Consumables Market Report Segmentation
8 segment dimensions are covered across the global market.
By Equipment
- Electrode & Filler Material Equipment
- Laser Equipment
- Other Equipment
- Oxy- Fuel Gas Equipment
- Oxy-Fuel Gas Equipment
- Welding Electrode & Filler Material Equipment
By Accessory
- Flow Controllers
- Fume Extraction Equipment
- Gas Cabinets
- Gas Filters
- Gas Flow Meters
- Gas Manifolds
- Gas Panels
- Gas Regulators
- Gas Valves
- Protective Gear
By Consumable
- Electrode & Filler Materials
- Electrodes & Filler Materials
- Fluxes & Wires
- Gases
- Laser Equipment
- Other Equipment
- Oxy-Fuel Gas Equipment
- Welding Electrode & Filler Material Equipment
By Technology
- Arc Welding
- Other Technologies
- Oxy-Fuel Welding
By End-Use Industry
- Aerospace
- Automotive
- Construction & Infrastructure
- General Manufacturing
- Heavy Equipment/Earth Moving Equipment
- Maintenance & Repair
- Marine & Shipbuilding
- Oil & Gas
- Pipelines
- Power Generation
- Rail
- Tanks & Pressure Vessels
- Trucks & Trailers
By Type
- Arc Welding Robots
- Spot Welding Robots
- Welding Accessories
- Welding Consumables
- Welding Equipment
By Payload
- 50-150 Kilogram Payload
- <50 Kilogram Payload
- >150 Kilogram Payload
By End User
- Aerospace & Defense
- Automotive & Transportation
- Electrical & Electronics
- Metals & Machinery
Target Audience
- Equipment Manufacturers : Welding equipment manufacturers need North America market data to optimize product portfolios, identify regional demand trends, and develop competitive strategies for the US, Canadian, and Mexican markets.
- Construction & Mining Companies : Construction and mining operators require market insights to forecast equipment procurement needs, evaluate supplier options, and plan capital expenditures for welding infrastructure across North America.
- Distributors & Retailers : Regional distributors and retailers need detailed market segmentation to optimize inventory management, identify growth sectors, and develop targeted sales strategies for packaging, construction, and mining segments.
- Investment & Private Equity Firms : Investors evaluating North America's welding sector require comprehensive market data to assess acquisition targets, evaluate growth potential, and make informed capital allocation decisions across the region.
- Supply Chain & Procurement Teams : Corporate procurement professionals need regional market intelligence to negotiate supplier contracts, identify alternative sources, and optimize sourcing strategies for welding consumables and equipment in North America.
Countries within North America - compare and drill down
| Country | 2025 size (native) |
|---|---|
| US | USD 7357 Million |
| Canada | USD 887.6 Million |
| Mexico | USD 1133.2 Million |
Country market size visualization
Reasons to Buy this Report
- Regional Market Segmentation : Gain detailed insights into North America's welding market dynamics, including country-level breakdowns for the US, Canada, and Mexico to identify localized growth opportunities and sector-specific demand patterns.
- Competitive Landscape Analysis : Understand market positioning and competitive strategies specific to North America's packaging, construction, mining, and gases sectors to benchmark against regional players and identify market gaps.
- Forecast-Driven Strategy : Leverage 2025-2030 projections showing growth from $7.9B to $9.4B to develop targeted expansion plans, product development roadmaps, and investment decisions aligned with regional growth trajectories.
- Sector-Specific Insights : Access detailed analysis of welding demand across packaging, construction, mining, and gases industries in North America to tailor solutions and marketing strategies to high-growth verticals.
- Investment & Partnership Opportunities : Identify emerging opportunities in Canada and Mexico markets, assess regional supply chain dynamics, and evaluate partnership potential with established North American welding equipment manufacturers.
Frequently asked questions
What is the current size of the North America welding equipment market?
North America's welding equipment, accessories, and consumables market is valued at $7,886.5 million in 2025.
What is the projected market size for North America by 2030?
North America's welding market is forecast to reach $9,377.8 million by 2030, growing at a 3.52% CAGR.
Which industries drive demand in North America's welding market?
North America's welding market is primarily driven by packaging, construction, mining, and industrial gases sectors.
What growth rate is North America experiencing in the welding market?
North America's welding equipment market is growing at a compound annual growth rate of 3.52% from 2025 to 2030.
What factors support growth in North America's welding market?
North America's market growth is supported by equipment replacement cycles, manufacturing automation initiatives, infrastructure investments, and sector recovery.
RESEARCH METHODOLOGY
The study involved four main activities to estimate the current size of the global market for welding equipment, accessories, and consumables. Comprehensive secondary research was conducted to gather information on the market, the related product markets, and the parent product group market. The next step was to validate these findings, assumptions, and estimates with industry experts across the value chain of welding equipment, accessories, and consumables through primary research. Both top-down and bottom-up approaches were used to determine the overall market size. Subsequently, market breakdown and data triangulation procedures helped identify the sizes of various segments and sub-segments of the market.
Secondary Research
The market for companies offering welding equipment, accessories, and consumables is determined using secondary data from both paid and unpaid sources. This involves analyzing the product portfolios of major companies in the industry and rating them based on their performance and quality. Various secondary sources, such as Business Standard, Bloomberg, World Bank, and Factiva, were consulted to gather information for this study on the welding equipment, accessories, and consumables market. Multiple sources were reviewed during the secondary research process to collect relevant data. These sources included annual reports, press releases, investor presentations from welding manufacturers, forums, certified publications, and whitepapers. This secondary research provided essential information on the industry’s value chain, the key players, market classifications, and segmentation from both market and technology perspectives.
Primary Research
During the primary research process, various primary sources from both the supply and demand sides were interviewed to gather qualitative and quantitative information for this report. The supply-side sources included industry experts such as Chief Executive Officers (CEOs), Vice Presidents (VPs), marketing directors, technology and innovation directors, and other key executives from several leading companies and organizations operating in the welding equipment, accessories, and consumables market. After completing the market engineering calculations—covering market statistics, market breakdown, size estimations, forecasting, and data triangulation—extensive primary research was conducted to verify and validate the critical data points. This research also aimed to identify segmentation types, industry trends, the competitive landscape of welding equipment, accessories, and consumables offered by various market players, as well as key market dynamics like drivers, restraints, opportunities, challenges, industry trends, and strategies of major players. Throughout the entire market engineering process, top-down and bottom-up approaches and multiple data triangulation methods were extensively employed to perform market estimations and forecasts for the overall market segments and subsegments outlined in this report. A comprehensive blend of qualitative and quantitative analysis was conducted to generate key insights and information throughout the report.
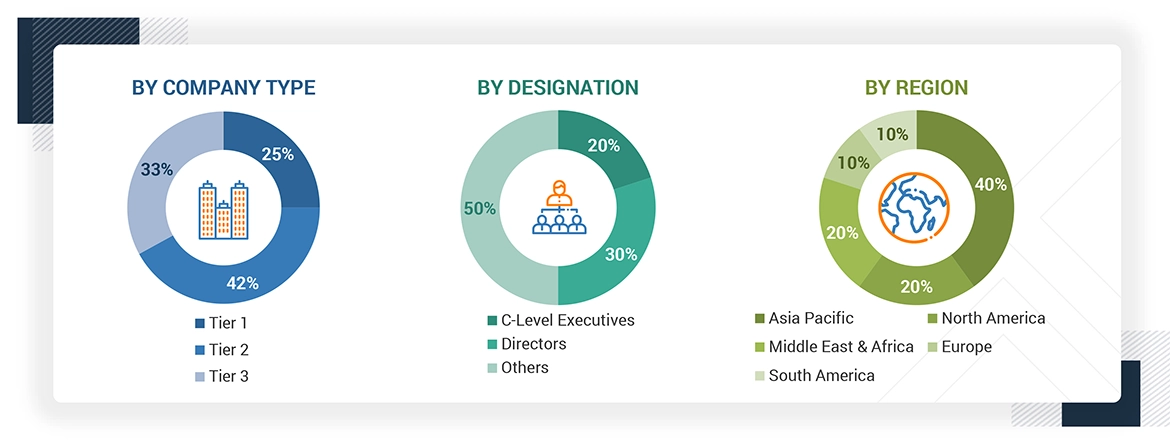
Notes: Other designations include sales, marketing, and product managers.
Tier 1: >USD 1 Billion; Tier 2: USD 500 million–1 Billion; and Tier 3: < USD 500 million
To know about the assumptions considered for the study, download the pdf brochure
Market Size Estimation
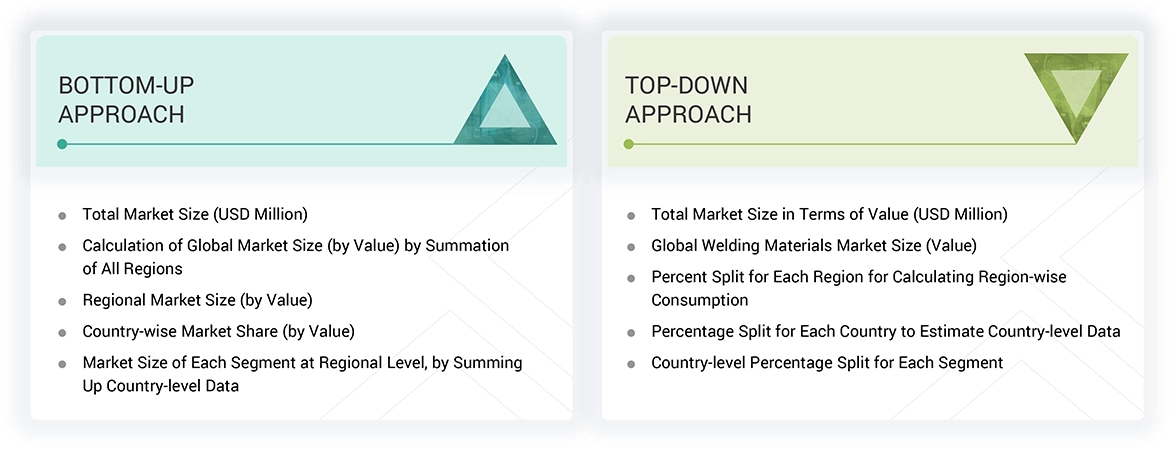
The top-down and bottom-up approaches were used to estimate and validate the global welding equipment, accessories, and consumables market. size These approaches were also extensively used to estimate the size of various related market segments. The research methodology used to estimate the market size included the following:
Data Triangulation
After estimating the overall market size using the appropriate processes, the market was divided into various segments and subsegments. Data triangulation and market breakup methods were used, where applicable, to complete the entire market analysis and obtain accurate statistics for each segment and subsegment. The data was triangulated by examining different factors and trends from both the demand and supply sides.
Market Definition
Welding is the process of joining two materials through mechanical force, friction, or heat caused by sparks or fluxes produced by a torch tip. There are three basic types of welding processes — gas welding, arc welding, and oxy-fuel welding. Machines, jigs, and other devices are called welding equipment for fabricating welding articles from semi-finished stock to final products.
Stakeholders
- Welding equipment, accessory, and consumable manufacturers
- Raw material suppliers
- Traders and distributors
- Industry associations
- Research organizations, trade associations, and government agencies
- R&D institutes
- Regulatory bodies
- End-use industries
Report Objectives
- To define, describe, and forecast the size of the global welding equipment, accessories, and consumables market based on equipment, consumable, accessory, technology, end-use industry, and region in terms of value
- To provide detailed information on the significant drivers, restraints, opportunities, and challenges influencing the market
- To strategically analyze micromarkets concerning individual growth trends, prospects, and their contribution to the market
- To assess the growth opportunities in the market for stakeholders and provide details on the competitive landscape for market leaders
- To forecast the market size of segments and subsegments for North America, Europe, Asia Pacific, South America, and the Middle East & Africa
- To strategically profile key players and comprehensively analyze their market shares and core competencies
- To analyze competitive developments such as product launches, acquisitions, expansions, partnerships, and agreements in the welding equipment, accessories, and consumables market
- To provide the impact of AI/Gen AI on the market
Get the Full Welding Equipment, Accessories, and Consumables Market Report
Full forecast, segment splits, and company analysis for all Welding Equipment, Accessories, and Consumables Market.
- India Welding Equipment, Accessories, and Consumables Market
- Australia Welding Equipment, Accessories, and Consumables Market
- Canada Welding Equipment, Accessories, and Consumables Market
- Mexico Welding Equipment, Accessories, and Consumables Market
- US Welding Equipment, Accessories, and Consumables Market
- Germany Welding Equipment, Accessories, and Consumables Market
- UK Welding Equipment, Accessories, and Consumables Market
- France Welding Equipment, Accessories, and Consumables Market
- Italy Welding Equipment, Accessories, and Consumables Market
- South Africa Welding Equipment, Accessories, and Consumables Market
- Brazil Welding Equipment, Accessories, and Consumables Market
- Argentina Welding Equipment, Accessories, and Consumables Market
- Rest Of Europe Welding Equipment, Accessories, and Consumables Market
- Rest Of Asia Pacific Welding Equipment, Accessories, and Consumables Market
- GCC Countries Welding Equipment, Accessories, and Consumables Market
- -Rest Of GCC Countries Welding Equipment, Accessories, and Consumables Market
- Rest Of South America Welding Equipment, Accessories, and Consumables Market
- China Welding Equipment, Accessories, and Consumables Market
- Japan Welding Equipment, Accessories, and Consumables Market
Need a Tailored Report?
Customize this report to your needs
Get 10% FREE Customization
Customize This Report
