Grease Market by Base Oil (Mineral, Synthetic, Bio-based), Thickener Type (Metallic Soap, Non-soap, Inorganic), End-Use Industry (Automotive, Construction, General Manufacturing, Agriculture, Mining, Power Generation) - Global Forecast to 2031

icon1
USD 7.96 BN
MARKET SIZE, 2031
icon2
CAGR 3.60%
(2026-2031)
icon3
298
REPORT PAGES
icon4
270
MARKET TABLES

OVERVIEW

grease-market Overview

Source: Secondary Research, Interviews with Experts, MarketsandMarkets Analysis

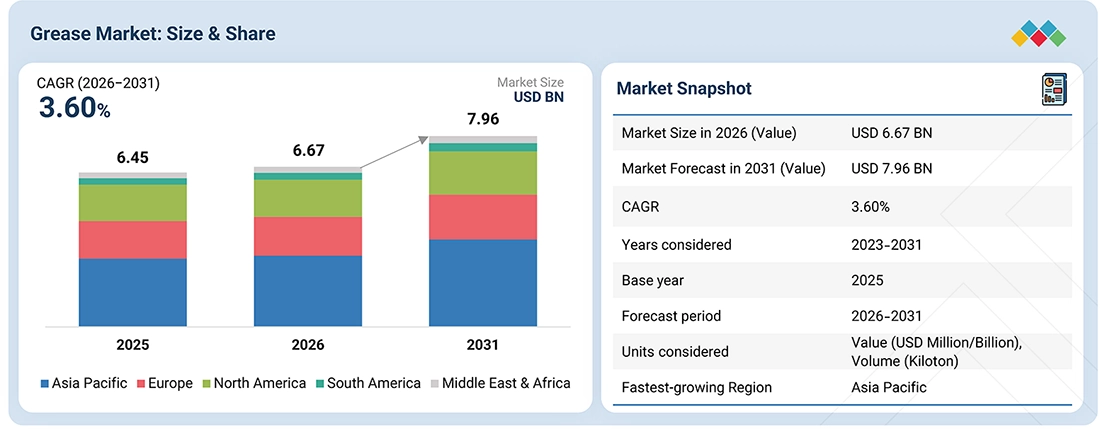
The grease market is estimated to grow from USD 6.67 billion in 2026 to USD 7.96 billion by 2031, at a CAGR of 3.60%. This growth is driven by increasing demand for high-performance lubrication, equipment reliability, and extended maintenance intervals across automotive and industrial applications. Market expansion is supported by innovations in synthetic and bio-based formulations, advanced thickener technologies, and greases designed for high-temperature, heavy-load, and extreme operating conditions. The growing focus on reducing equipment downtime, improving lubricant efficiency, and enhancing sustainability through advanced grease formulations is further contributing to market growth over the forecast period.

KEY TAKEAWAYS

  • BY REGION
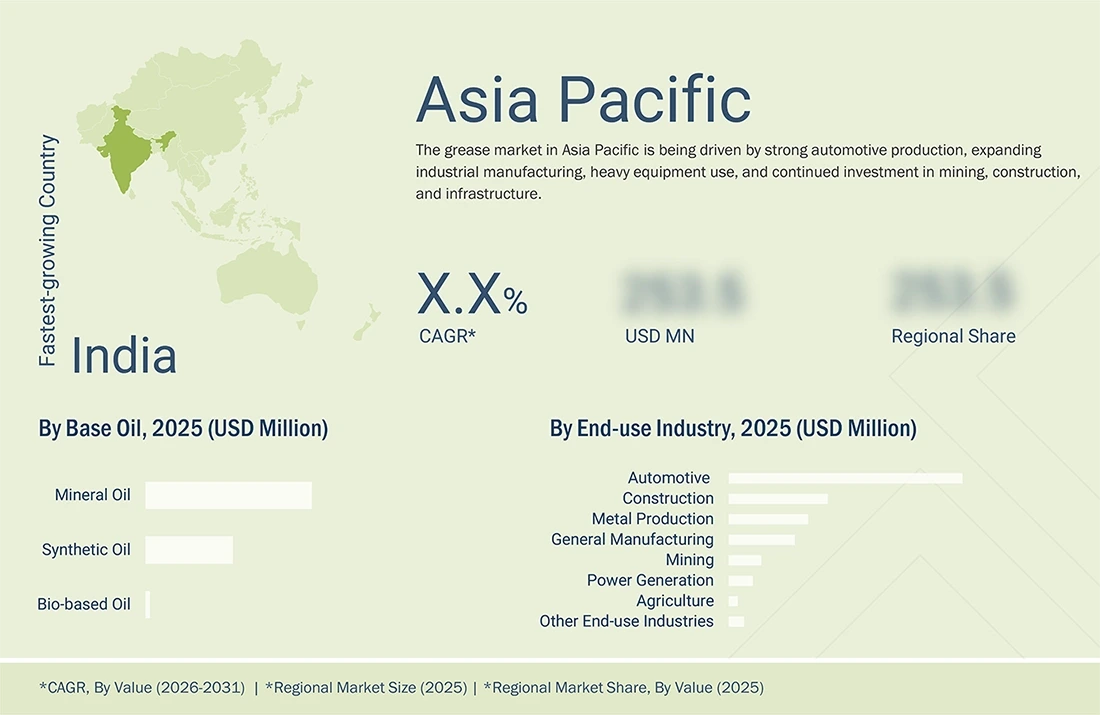
    Asia Pacific dominated the global grease market in 2025, accounting for a market share of 44.5%, in terms of value.
  • BY BASE OIL
    The synthetic oil segment is projected to be the fastest-growing segment in the grease market with a CAGR of 3.89%, in terms of value, during the forecast period
  • BY THICKENER TYPE
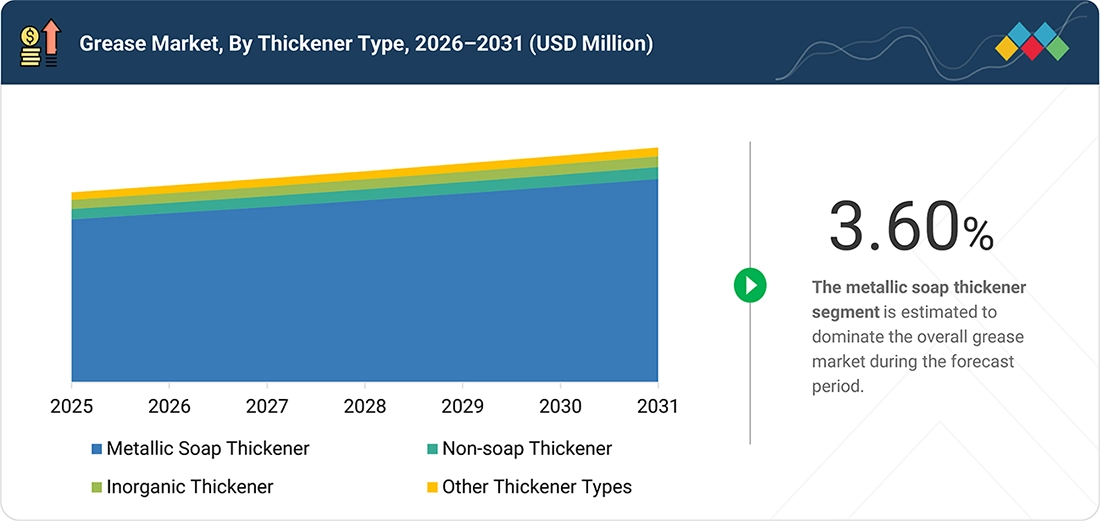
    In 2025, metallic soap thickener led the global grease market in terms of value.
  • BY END-USE INDUSTRY
    The agriculture industry is projected to be the fastest-growing segment of the grease market with a CAGR of 4.46%, in terms of value, between 2026 and 2031.
  • COMPETITIVE LANDSCAPE - KEY PLAYERS
    Shell plc (UK), Exxon Mobil Corporation (US), and Idemitsu Kosan Co., Ltd. (Japan) are identified as key players in the global grease market. These companies have strong market presence and extensive product portfolios.
  • COMPETITIVE LANDSCAPE - STARTUPS
    AXEL Americas LLC (US), Balmer Lawrie & Co. Ltd. (India), and PJCS “LUKOIL” (Russia) among other emerging players, have carved out solid positions within specialized niche segments, highlighting their potential to evolve into future market leaders.

The growth potential for the grease market remains strong, supported by increasing demand for high-performance lubrication, technological advancements in grease formulations, and the shift toward efficient, durable, and sustainable lubrication solutions. A key trend shaping the market is the development of advanced grease technologies, including synthetic, bio-based, high-temperature, and long-life formulations, to meet evolving environmental standards and equipment requirements. Greases are increasingly preferred for their ability to reduce friction, protect components, extend service intervals, and improve equipment reliability while minimizing maintenance requirements, downtime, and overall operating costs.

TRENDS & DISRUPTIONS IMPACTING CUSTOMERS' CUSTOMERS

The impact on the grease market largely depends on activity trends across major end-use industries, advancements in lubrication technologies, and changes in industrial and transportation patterns. Major users of greases include the automotive, construction, general manufacturing, agriculture, mining, and power generation industries. These users rely on greases for component protection, friction reduction, wear resistance, temperature management, and extended equipment life. The increasing adoption of automated lubrication systems, high-performance formulations, synthetic greases, sustainable alternatives, and application-specific technologies is influencing market growth. Any slowdown in vehicle production, industrial activity, construction projects, equipment investments, or raw material availability can impact grease consumption patterns and affect revenues across the grease market value chain.
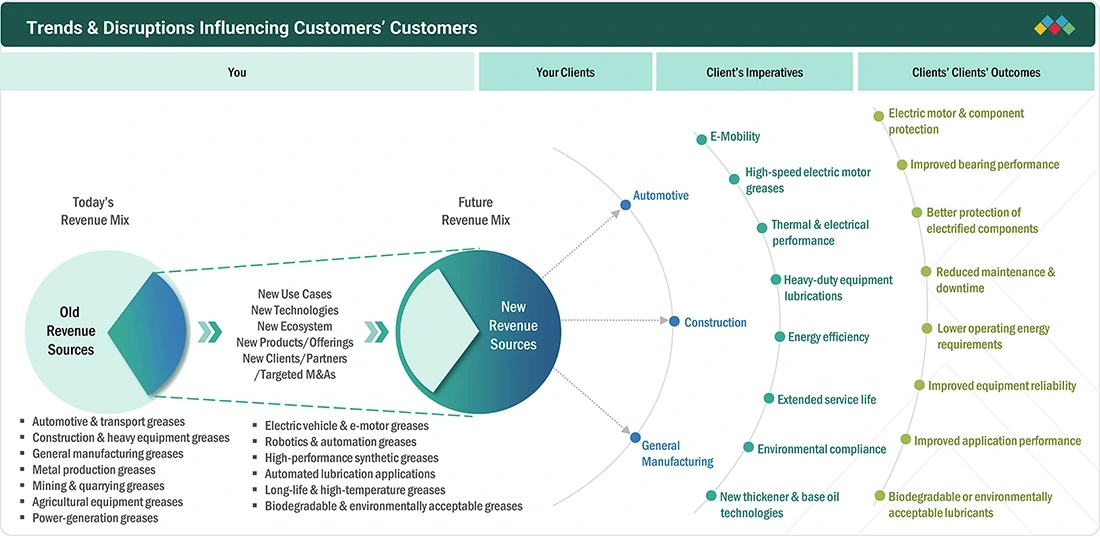
grease-market Disruptions

Source: Secondary Research, Interviews with Experts, MarketsandMarkets Analysis

MARKET DYNAMICS

Drivers
Impact
Level
  • Rise in automation in various industries
  • Accelerating wind energy deployment and specialized turbine grease demand
RESTRAINTS
Impact
Level
  • Accelerating electrification of the vehicle fleet displacing conventional grease demand
  • Lithium thickener supply constraints disrupting grease production economics
OPPORTUNITIES
Impact
Level
  • Leveraging e-commerce industry to increase customer reach
  • Rising trend of polyurea grease over lithium grease
CHALLENGES
Impact
Level
  • Reformulation complexity for electric vehicle drivetrain applications
  • Base oil and raw material price volatility

Source: Secondary Research, Interviews with Experts, MarketsandMarkets Analysis

Driver: Rise in automation in various industries

The increasing adoption of industrial automation, robotics, and automated machinery is driving demand for high-performance grease in the grease market. Automated equipment operates for longer hours and often at higher speeds, requiring greases that provide extended lubrication intervals, wear protection, and temperature stability. Robotics, conveyor systems, automated production lines, bearings, gears, and electric motors are key application areas. This is also increasing demand for specialty greases, including synthetic, high-temperature, low-noise, and food-grade formulations. As manufacturers focus on reducing equipment downtime and maintenance costs, the need for reliable, long-life greases is expected to increase.

Restraint: Accelerating electrification of the vehicle fleet displacing conventional grease demand

The shift toward electric vehicles (EVs) is creating a restraint for conventional automotive grease demand, particularly greases used in traditional internal-combustion-engine vehicles. EVs have fewer mechanical components such as engine-related bearings, transmissions, and certain drivetrain parts that traditionally require lubrication. As a result, demand for some conventional automotive greases used in chassis, engine-adjacent, and drivetrain applications may decline as EV penetration increases. However, EVs still require specialized greases for wheel bearings, constant-velocity joints, electric motors, reduction gears, and other components. Therefore, electrification is shifting the market from volume-driven conventional greases toward more specialized, higher-value EV-compatible formulations.

Opportunity: Leveraging e-commerce industry to increase customer reach

The growth of e-commerce and digital distribution channels presents an opportunity for grease manufacturers to expand their customer base beyond traditional distributors and industrial suppliers. Automotive greases, multipurpose greases, specialty greases, and smaller-pack industrial products can be marketed directly to workshops, fleet operators, farmers, maintenance professionals, and small industrial users. Online channels also allow manufacturers to provide detailed information on NLGI grades, base oils, thickener types, operating temperatures, and application suitability. This can improve product visibility and enable manufacturers to reach customers in regions where physical distribution networks are limited.

Challenge: Reformulation complexity for electric vehicle drivetrain applications

The development of greases for EV drivetrains and electric motors is a major technical challenge for the grease market. Conventional greases may not be suitable because EV components can experience high rotational speeds, elevated temperatures, electrical currents, and electromagnetic compatibility requirements. EV greases must balance lubrication, thermal stability, wear protection, low noise, and material compatibility while avoiding undesirable electrical conductivity or leakage. Manufacturers therefore need to invest heavily in R&D, testing, formulation expertise, and OEM qualification to develop EV-specific products. Meeting different performance requirements across electric motors, reduction gears, bearings, and CV joints also increases formulation complexity and development costs.

GREASE MARKET: COMMERCIAL USE CASES ACROSS INDUSTRIES

COMPANY USE CASE DESCRIPTION BENEFITS
company logo
Uses grease lubrication across automotive manufacturing and vehicle applications, including wheel bearings, propeller shafts, universal joints, axle and hub assemblies, and other chassis/driveline components. Toyota specifies dedicated greases for applications where controlled lubrication is required to maintain smooth movement and protect components from friction and wear.  Reduced friction and wear, smooth component operation, improved protection of bearings and joints, reduced risk of premature component failure, enhanced vehicle reliability, and longer component service life.
company logo
Uses grease extensively for bearings and critical equipment in steel-production operations. At its Merchant Mill, grease used for work-roll bearings was being washed out by heavy cooling-water spray, contributing to bearing failures and high grease consumption. Following a grease optimization program, the mill adopted a higher-viscosity lithium-complex grease through its centralized lubrication system. 38% reduction in grease consumption and 70% reduction in bearing failures, alongside improved productivity, better grease pumpability through centralized lubrication, reduced maintenance requirements, improved safety, and lower waste generation. 
company logo
Uses grease lubrication as part of maintenance of construction, infrastructure, and heavy equipment operated across its businesses. Grease is applied to lubrication points such as bearings, pins, bushings, joints, and other moving components exposed to heavy loads, dust, water, and demanding construction-site conditions. Reduced friction and component wear, protection against water and contaminants, improved reliability of heavy equipment, extended service life of pins, bushings and bearings, reduced unplanned downtime, and lower maintenance requirements.
company logo
Uses lubrication systems for critical equipment across its steel-production operations. At an ArcelorMittal rolling mill, lubrication-system improvements were implemented to address bearing failures and operational issues associated with the existing lubrication arrangement. Reduced bearing-related stoppages, improved lubrication consistency, enhanced equipment reliability, reduced maintenance intervention, improved operating conditions, and higher production availability

Logos and trademarks shown above are the property of their respective owners. Their use here is for informational and illustrative purposes only.

MARKET ECOSYSTEM

The grease market ecosystem comprises base oil suppliers, thickener and additive manufacturers, grease formulators, lubricant producers, application equipment providers, distributors, and end-use industries. These stakeholders collaborate across the value chain to develop and supply grease solutions for automotive, industrial, construction, mining, agriculture, and power generation applications. The market is driven by increasing demand for reliable lubrication, equipment longevity, reduced maintenance, efficient operations, high-performance formulations, and environmentally responsible lubrication technologies. Collaboration among ecosystem participants enables the development of application-specific greases with enhanced properties such as load-carrying capacity, temperature resistance, water resistance, adhesion, corrosion protection, durability, and sustainability while supporting compliance with evolving environmental and performance standards.
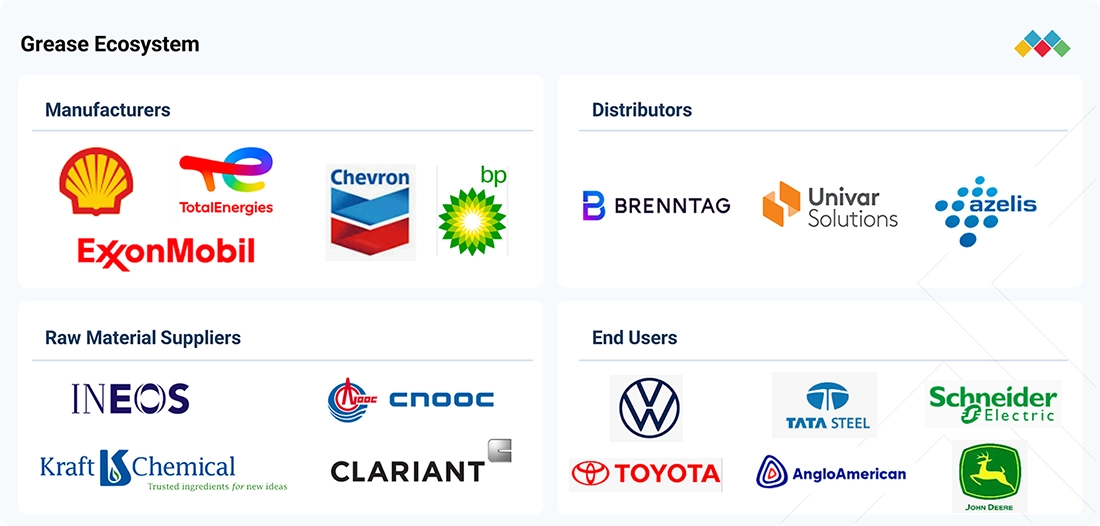
grease-market Ecosystem

Logos and trademarks shown above are the property of their respective owners. Their use here is for informational and illustrative purposes only.

MARKET SEGMENTS
grease-market Segments

Source: Secondary Research, Interviews with Experts, MarketsandMarkets Analysis

Grease Market, By Base Oil

The mineral oil segment held the largest share of the grease market in terms of value in 2025. This dominance is led by its cost-effectiveness, wide availability, established supply chain, and compatibility with a broad range of automotive and industrial applications. Mineral oil-based greases offer reliable lubrication, good load-carrying capacity, and adequate thermal and mechanical stability for conventional operating conditions. Their extensive use in automotive, manufacturing, construction, agriculture, and mining equipment further supports their leading market position.

Grease Market, By Thickener Type

In 2025, the metallic soap thickener was the largest segment in the grease market in terms of value. This leadership is attributed to its versatility across diverse operating conditions and strong adoption in high-volume lubrication applications. Metallic soap thickeners provide consistent grease structure and effective retention within lubricated components, supporting dependable performance under varying loads and speeds. Their extensive application in bearings, gears, joints, and other machinery components reinforces their dominant market position.

Grease Market, By End-Use Industry

The automotive industry accounted for the largest market share of the grease market in terms of value in 2025. This dominance is primarily attributed to the large installed base of passenger vehicles and commercial fleets, along with extensive grease requirements across wheel bearings, chassis systems, joints, and other moving components. Rising vehicle production, expanding commercial transportation, and growing maintenance requirements further sustain grease consumption across the automotive sector.

REGION

Asia Pacific held the largest market share of grease market

In 2025, Asia Pacific held the largest value share of the grease market, driven by rapid industrialization, expanding automotive production, infrastructure development, and increasing manufacturing activity across major economies such as China, India, and Japan. The region’s large base of industrial machinery, construction equipment, commercial vehicles, and agricultural machinery generates substantial demand for lubricating greases. In addition, continued investments in mining, power generation, and transportation infrastructure are supporting grease consumption across diverse end-use applications.
grease-market Region

GREASE MARKET: COMPANY EVALUATION MATRIX

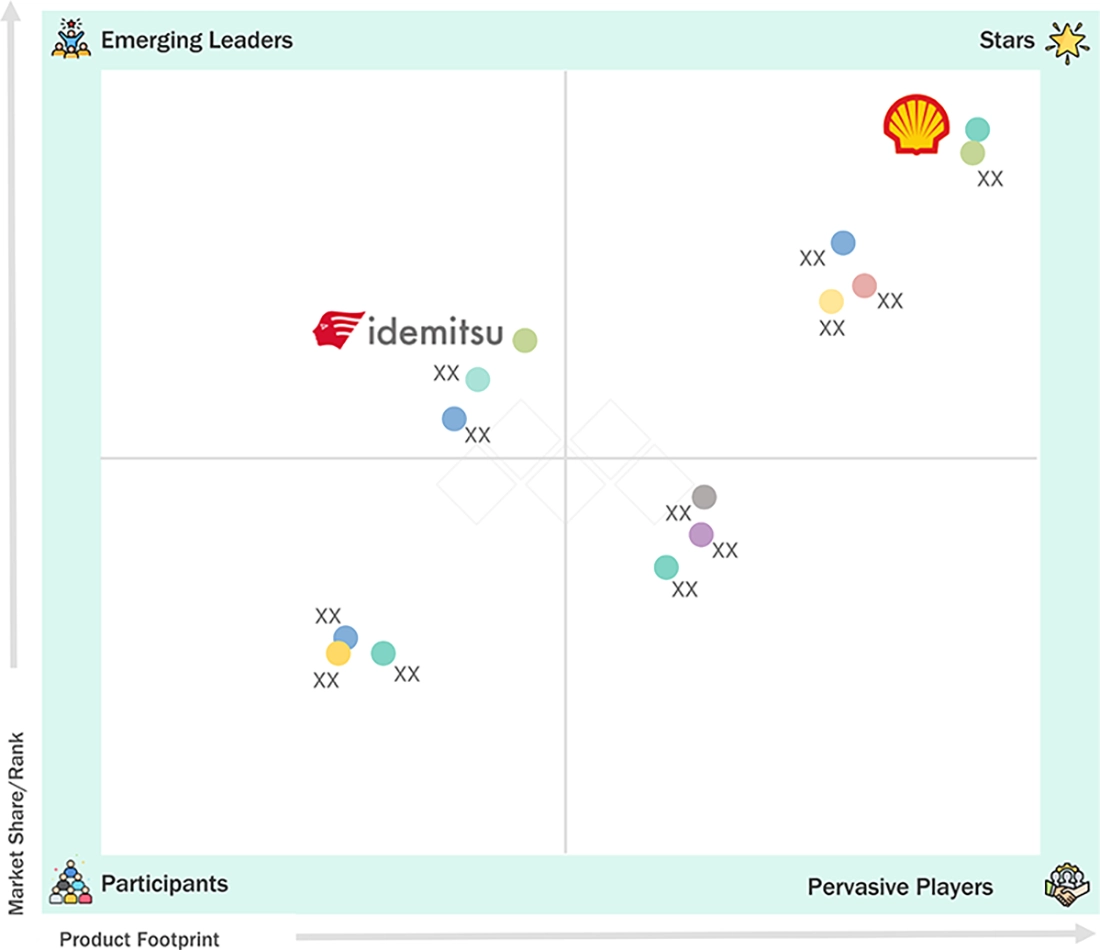
Shell plc (Star) holds a leading position in the grease market due to its strong production capabilities, extensive product portfolio, and well-established global distribution network. The company benefits from established relationships with OEMs and industrial customers and a broad presence across key regional markets, supporting its strong market position. Idemitsu Kosan Co., Ltd. (Emerging) is also strengthening its position in the grease market by expanding its lubricant portfolio and enhancing product development capabilities. With rising demand for high-performance, durable, and environmentally responsible greases, both companies are expected to enhance their competitive standing in the market going forward.
grease-market Evaluation Metrics

Source: Secondary Research, Interviews with Experts, MarketsandMarkets Analysis

MARKET SCOPE

REPORT METRIC DETAILS
Market Size in 2025 (Value) USD 6.45 Billion
Market Size in 2026 (Value) USD 6.67 Billion
Market Size in 2031 (Value) USD 7.96 Billion
Growth Rate CAGR of 3.60% from 2026 to 2031
Years Considered 2023–2031
Base Year 2025
Forecast Period 2026–2031
Units Considered Value (USD Million/Billion), Volume (Kiloton)
Report Coverage Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments Covered By Base Oil: Mineral Oil, Synthetic Oil, Bio-based Oil By Thickener Tye: Metallic Soap Thickener, Non-soap Thickener, Inorganic Thickener, and Other Thickener Types By End-Use Industry: Automotive, Construction, General Manufacturing, Mining, Power Generation, Metal Production, Agriculture, and Other end-use industries
Regional Scope Asia Pacific, Europe, North America, Middle East & Africa, South America

WHAT IS IN IT FOR YOU: GREASE MARKET REPORT CONTENT GUIDE
grease-market Content Guide

DELIVERED CUSTOMIZATIONS

We have successfully delivered the following deep-dive customizations:

CLIENT REQUEST CUSTOMIZATION DELIVERED VALUE ADDS
North America-based Grease Manufacturer
  • Detailed North America-based company profiles of competitors (financials, product portfolio)
  • Customer landscape mapping by end-use sector
  • Identify interconnections and supply chain blind spots
  • Track customer switching trends
  • Highlight untapped customer clusters for market entry
Asia Pacific-based Grease Manufacturer
  • Global & regional production capacity benchmarking
  • Customer base profiling across the application industries
  • Identify high-demand customers for long-term supply contracts
  • Assess supply-demand gaps for competitive advantage

RECENT DEVELOPMENTS

  • August 2026 : Digiworld announced a partnership with Shell plc to distribute Shell lubricants in Vietnam, marking Digiworld’s entry into the country’s lubricants market. This collaboration expands Shell’s downstream reach for oils and greases in a market with growing automotive and industrial lubrication demand.
  • July 2025 : Shell plc completed the acquisition of Indian lubricants company Raj Petro Specialities, enhancing its lubricants portfolio and manufacturing footprint in India. This acquisition broadens Shell’s range of specialty oils and greases and improves access to industrial and automotive lubrication customers in the region.
  • June 2025 : TotalEnergies SE inaugurated a new grease manufacturing unit at its Lubricants Blending Plant in Rockingham, North Carolina, as part of a more than USD 12 million investment. The expansion strengthened the facility’s role as a major US production hub for lubricants and grease.
  • April 2026 : PETRONAS introduced ProGris, an industrial grease under its new PRO Series, designed to deliver reliable protection, enhanced equipment performance, and durability in demanding industrial applications.
  • March 2025 : FUCHS SE launched NYOGEL 760G, a synthetic hydrocarbon, NLGI Grade 2 grease designed to lubricate and protect electrical connectors and exposed terminals in automotive and heavy-duty trucking applications. The grease offered heat and water resistance, fretting-corrosion protection, and dielectric insulation.


Table of Contents

checkmarkExclusive indicates content/data unique to MarketsandMarkets and not available with any competitors.

TITLE
PAGE NO
1
INTRODUCTION


25
2
EXECUTIVE SUMMARY


30
3
PREMIUM INSIGHTS


35
4
MARKET OVERVIEW
Automation and e-commerce drive industrial growth amid polyurea grease and electric vehicle challenges.


38
 
4.1
INTRODUCTION


4.2
MARKET DYNAMICS


4.2.1
DRIVERS


4.2.1.1
RISE IN AUTOMATION IN VARIOUS INDUSTRIES


ACCELERATING WIND ENERGY DEPLOYMENT AND SPECIALIZED TURBINE


4.2.1.3
EXPANDING GLOBAL INDUSTRIAL MANUFACTURING AND MECHANIZATION


4.2.2
RESTRAINTS


ACCELERATING ELECTRIFICATION OF VEHICLE FLEET DISPLACING CONVENTIONAL


LITHIUM THICKENER SUPPLY CONSTRAINTS DISRUPTING GREASE


4.2.3
OPPORTUNITIES


4.2.3.1
LEVERAGING E-COMMERCE INDUSTRY TO INCREASE CUSTOMER REACH


4.2.3.2
RISING TREND OF POLYUREA GREASE OVER LITHIUM GREASE


4.2.4
CHALLENGES


4.2.4.1
REFORMULATION COMPLEXITY FOR ELECTRIC VEHICLE DRIVETRAIN APPLICATIONS


4.2.4.2
BASE OIL AND RAW MATERIAL PRICE VOLATILITY


4.3
INTERCONNECTED MARKETS AND CROSS-SECTOR OPPORTUNITIES


4.3.1
INTERCONNECTED MARKETS


4.3.2
CROSS-SECTOR OPPORTUNITIES


4.4
STRATEGIC MOVES BY TIER-1/2/3 PLAYERS


4.4.1
KEY MOVES AND STRATEGIC FOCUS


5
PORTER'S FIVE FORCES ANALYSIS
Uncover strategic leverage points amid evolving competitive pressures and global economic shifts.


45
 
5.1
INTRODUCTION


5.1.1
THREAT OF NEW ENTRANTS


5.1.2
THREAT OF SUBSTITUTES


5.1.3
BARGAINING POWER OF SUPPLIERS


5.1.4
BARGAINING POWER OF BUYERS


5.1.5
INTENSITY OF COMPETITIVE RIVALRY


5.2
MACROECONOMIC INDICATORS


5.2.1
INTRODUCTION


5.2.2
GDP TRENDS AND FORECAST FOR MAJOR ECONOMIES


5.2.3
TRENDS IN GLOBAL AUTOMOTIVE INDUSTRY


5.2.4
TRENDS IN GLOBAL HEAVY INDUSTRY AND STEEL PRODUCTION


5.3
SUPPLY CHAIN ANALYSIS


5.4
ECOSYSTEM ANALYSIS


5.5
PRICING ANALYSIS


AVERAGE SELLING PRICE OF GREASE OFFERED BY KEY PLAYERS,


5.5.2
AVERAGE SELLING PRICE TREND OF GREASE, BY REGION


5.6
TRADE ANALYSIS


5.6.1
IMPORT SCENARIO (HS CODE 340399)


5.6.2
EXPORT SCENARIO (HS CODE 340399)


5.7
KEY CONFERENCES & EVENTS IN 2026–2027


5.8
TRENDS/DISRUPTIONS IMPACTING CUSTOMERS' BUSINESSES


5.9
INVESTMENT AND FUNDING SCENARIO


5.10
CASE STUDY ANALYSIS


REDUCING GREASE LEAKAGE AT A MAJOR PORT FACILITY WITH


5.10.2
IMPROVING STEEL MILL BEARING PERFORMANCE WITH RENOLIT CXS AM 1


5.11
IMPACT OF 2025 US TARIFF – GREASE MARKET


5.11.1
INTRODUCTION


5.11.2
KEY TARIFF RATES


5.11.3
PRICE IMPACT ANALYSIS


5.11.4
IMPACT ON COUNTRIES/REGIONS


5.11.4.1
US


5.11.4.2
EUROPE


5.11.4.3
ASIA PACIFIC


5.11.5
IMPACT ON END-USE INDUSTRIES:


TECHNOLOGICAL ADVANCEMENTS, AI-DRIVEN IMPACT, PATENTS,


6.1
KEY EMERGING TECHNOLOGIES


6.1.1
LOW-SULFUR GREASE


6.1.2
BIODEGRADABLE GREASE


6.2
COMPLEMENTARY TECHNOLOGIES


6.2.1
NANOTECHNOLOGY IN GREASE PRODUCTION


6.2.2
SMART GREASE MONITORING SYSTEMS


6.2.3
ADDITIVE MANUFACTURING (3D PRINTING) FOR GREASE COMPONENTS


6.3
TECHNOLOGY/PRODUCT ROADMAP


SHORT-TERM (2025-2027) | FORMULATION OPTIMIZATION


MID-TERM (2027-2030) | PERFORMANCE ENHANCEMENT


LONG-TERM (2030-2035+) | SUSTAINABILITY, SMART LUBRICATION


6.4
PATENT ANALYSIS


6.4.1
APPROACH


6.4.2
DOCUMENT TYPES


6.4.3
TOP APPLICANTS


6.4.4
JURISDICTION ANALYSIS


6.5
IMPACT OF AI/GEN AI ON GREASE MARKET


6.5.1
TOP USE CASES AND MARKET POTENTIAL


6.5.2
BEST PRACTICES IN GREASE PROCESSING


6.5.3
CASE STUDIES OF AI IMPLEMENTATION IN GREASE MARKET


6.5.4
INTERCONNECTED ADJACENT ECOSYSTEM AND IMPACT ON MARKET PLAYERS


6.5.5
CLIENTS' READINESS TO ADOPT GENERATIVE AI IN GREASE MARKET


7
SUSTAINABILITY AND REGULATORY LANDSCAPE
Navigate complex global regulations to drive sustainable development and compliance in the grease market.


78
 
7.1
REGIONAL REGULATIONS AND COMPLIANCE


7.1.1
REGULATORY BODIES, GOVERNMENT AGENCIES, AND OTHER ORGANIZATIONS


7.1.2
INDUSTRY STANDARDS


7.2
SUSTAINABILITY IMPACT AND REGULATORY POLICY INITIATIVES


7.2.1
SAFETY PROTOCOLS


7.2.2
SUSTAINABLE DEVELOPMENT


7.2.3
STANDARDIZATION


7.3
CERTIFICATIONS, LABELING, AND ECO-STANDARDS


8
CUSTOMER LANDSCAPE & BUYER BEHAVIOR
Discover unmet needs and stakeholder influences shaping buyer decisions across industries.


83
 
8.1
DECISION-MAKING PROCESS


8.2
KEY STAKEHOLDERS AND BUYING CRITERIA


8.2.1
KEY STAKEHOLDERS IN BUYING PROCESS


8.2.2
`BUYING CRITERIA


8.3
ADOPTION BARRIERS & INTERNAL CHALLENGES


8.4
UNMET NEEDS IN VARIOUS END-USE INDUSTRIES


9
GREASE MARKET, BY BASE OIL
Market Size & Growth Rate Forecast Analysis to 2031 in USD Million and Kilotons | 16 Data Tables


88
 
9.1
INTRODUCTION


9.2
MINERAL OIL


9.2.1
LOW COST AND EASY AVAILABILITY TO DRIVE MARKET GROWTH


9.3
SYNTHETIC OIL


9.3.1
DEMAND FOR HIGH-PERFORMANCE PRODUCTS TO PROPEL MARKET


9.4
BIO-BASED OIL


9.4.1
DEMAND FOR ENVIRONMENTALLY FRIENDLY GREASE TO BOOST MARKET


10
GREASE MARKET, BY THICKENER TYPE
Market Size & Growth Rate Forecast Analysis to 2031 in USD Million and Kilotons | 20 Data Tables


96
 
10.1
INTRODUCTION


10.2
METALLIC SOAP THICKENER


DEMAND FOR RELIABLE AND HIGH-PERFORMANCE LUBRICATION


10.2.2
LITHIUM


10.2.3
CALCIUM


10.2.4
ALUMINUM


10.2.5
SODIUM


10.2.6
OTHER METALLIC SOAP THICKENERS


10.3
NON-SOAP THICKENER


10.3.1
RISING ADOPTION OF POLYUREA TO SUPPORT MARKET GROWTH


10.4
INORGANIC THICKENER


10.4.1
SUPERIOR THERMAL STABILITY AND WATER RESISTANCE TO DRIVE MARKET


10.5
OTHER THICKENER TYPES


11
GREASE MARKET, BY END-USE INDUSTRY
Market Size & Growth Rate Forecast Analysis to 2031 in USD Million and Kilotons | 36 Data Tables


108
 
11.1
INTRODUCTION


11.2
AUTOMOTIVE


11.2.1
INCREASE IN DEMAND FROM ASIA PACIFIC TO DRIVE MARKET


11.3
CONSTRUCTION


11.3.1
DEMAND FOR HIGH-PERFORMANCE GREASE TO BOOST MARKET


11.4
GENERAL MANUFACTURING


11.4.1
GROWTH OF MANUFACTURING SECTOR IN ASIA PACIFIC TO DRIVE MARKET


11.5
METAL PRODUCTION


11.5.1
DEMAND FOR HIGH LOAD BEARABLE GREASE TO DRIVE MARKET


11.6
MINING


11.6.1
EXPANDING MINING ACTIVITIES TO STRENGTHEN DEMAND


11.7
POWER GENERATION


11.7.1
GROWING POWER GENERATION EQUIPMENT BASE TO SUPPORT DEMAND


11.8
AGRICULTURE


11.8.1
ADVANCING AGRICULTURAL EQUIPMENT USE TO BOOST MARKET GROWTH


11.9
OTHER END-USE INDUSTRIES


12
GREASE MARKET, BY REGION
Comprehensive coverage of 8 Regions with country-level deep-dive of 20 Countries | 168 Data Tables.


125
 
12.1
INTRODUCTION


12.2
ASIA PACIFIC


12.2.1
CHINA


12.2.1.1
RAPID INDUSTRIALIZATION TO DRIVE DEMAND FOR GREASE


12.2.2
JAPAN


12.2.2.1
STRONG AUTOMOTIVE INDUSTRY TO DRIVE DEMAND FOR GREASE


12.2.3
INDIA


12.2.3.1
GROWING INDUSTRIALIZATION TO POSITIVELY INFLUENCE MARKET GROWTH


12.2.4
AUSTRALIA


12.2.4.1
EXPANSION OF MINING ACTIVITIES FUELING MARKET GROWTH


12.2.5
SOUTH KOREA


12.2.5.1
SMART FACTORY EXPANSION BOOSTING INDUSTRIAL GREASE APPLICATIONS


12.2.6
THAILAND


12.2.6.1
PUBLIC INFRASTRUCTURE INVESTMENT SUPPORTING GREASE CONSUMPTION


12.3
NORTH AMERICA


12.3.1
US


12.3.1.1
STRONG OIL & GAS INFRASTRUCTURE CREATING OPPORTUNITIES FOR SPECIALTY GREASES


12.3.2
CANADA


12.3.2.1
MINING AND RESOURCE DEVELOPMENT TO DRIVE DEMAND


12.3.3
MEXICO


12.3.3.1
INFRASTRUCTURE DEVELOPMENT PROPELLING MARKET GROWTH


12.4
EUROPE


12.4.1
GERMANY


12.4.1.1
STRONG AUTOMOTIVE EXPORT BASE TO DRIVE DEMAND


12.4.2
UK


RESURGENCE IN MACHINERY PRODUCTION BOOSTING INDUSTRIAL


12.4.3
FRANCE


STRONG AEROSPACE MANUFACTURING BASE CREATING OPPORTUNITIES


12.4.4
RUSSIA


12.4.4.1
STRONG ENERGY SECTOR SUSTAINING DEMAND FOR INDUSTRIAL GREASES


12.4.5
ITALY


12.4.5.1
EXPANSION OF RAIL NETWORK STRENGTHENING GREASE APPLICATIONS


12.5
MIDDLE EAST & AFRICA


12.5.1
GCC


12.5.1.1
SAUDI ARABIA


12.5.1.1.1
GROWING OIL & GAS SECTOR TO DRIVE MARKET


12.5.2
IRAN


12.5.2.1
AUTOMOTIVE MANUFACTURING EXPANSION RESHAPING MARKET


12.5.3
SOUTH AFRICA


12.5.3.1
MINING-INTENSIVE OPERATIONS CREATING REQUIREMENTS FOR SPECIALTY GREASES


12.5.4
EGYPT


12.5.4.1
LARGE-SCALE INFRASTRUCTURE PROJECTS FUELING MARKET GROWTH


12.5.5
TURKEY


INCREASING FOCUS ON EQUIPMENT MAINTENANCE AND LONGER LUBRICANT


12.6
SOUTH AMERICA


12.6.1
BRAZIL


12.6.1.1
EXPANSION OF RENEWABLE POWER GENERATION TO DRIVE DEMAND


12.6.2
ARGENTINA


12.6.2.1
AUTOMOTIVE PRODUCTION ACCELERATING GREASE CONSUMPTION IN ARGENTINA


13
COMPETITIVE LANDSCAPE
Discover how emerging leaders are reshaping market dynamics to challenge established giants.


202
 
13.1
INTRODUCTION


13.2
KEY PLAYERS' STRATEGIES/RIGHT TO WIN, 2021–2026


13.3
MARKET SHARE ANALYSIS, 2025


13.4
REVENUE ANALYSIS, 2021–2025


13.5
COMPANY EVALUATION MATRIX: KEY PLAYERS, 2025


13.5.1
STARS


13.5.2
EMERGING LEADERS


13.5.3
PERVASIVE PLAYERS


13.5.4
PARTICIPANTS


13.5.5
COMPANY FOOTPRINT: KEY PLAYERS, 2025


13.5.5.1
COMPANY FOOTPRINT


13.5.5.2
REGION FOOTPRINT


13.5.5.3
BASE OIL FOOTPRINT


13.5.5.4
THICKENER TYPE FOOTPRINT


13.5.5.5
END-USE INDUSTRY FOOTPRINT


13.6
COMPANY EVALUATION MATRIX: STARTUPS/SMES, 2025


13.6.1
PROGRESSIVE COMPANIES


13.6.2
RESPONSIVE COMPANIES


13.6.3
DYNAMIC COMPANIES


13.6.4
STARTING BLOCKS


13.6.5
COMPETITIVE BENCHMARKING: STARTUPS/SMES, 2025


13.6.5.1
DETAILED LIST OF KEY STARTUPS/SMES


13.6.5.2
COMPETITIVE BENCHMARKING OF KEY STARTUPS/SMES


13.7
BRAND/PRODUCT COMPARISON


13.8
COMPANY VALUATION AND FINANCIAL METRICS


13.9
COMPETITIVE SCENARIO


13.9.1
PRODUCT LAUNCHES


13.9.2
DEALS


13.9.3
EXPANSIONS


14
COMPANY PROFILES
In-depth Company Profiles of Leading Market Players with detailed Business Overview, Product and Service Portfolio, Recent Developments, and Unique Analyst Perspective (MnM View)


223
 
14.1
KEY PLAYERS


14.1.1
SHELL PLC


14.1.1.1
BUSINESS OVERVIEW


14.1.1.2
PRODUCTS/SOLUTIONS/SERVICES OFFERED


14.1.1.3
RECENT DEVELOPMENTS


14.1.1.3.1
SHELL PLC: DEALS


14.1.1.3.2
SHELL PLC: EXPANSIONS


14.1.1.4
STRATEGIC INTELLIGENCE


14.1.1.4.1
POSITION IN MARKET


14.1.1.4.2
FINANCIAL STRATEGY


14.1.1.4.3
OPERATIONAL STRATEGY


14.1.1.4.4
MARKET EXPANSION STRATEGY


14.1.1.4.5
PRODUCT USP


14.1.1.5
MNM VIEW


14.1.1.5.1
KEY STRENGTHS


14.1.1.5.2
STRATEGIC CHOICES


14.1.1.5.3
WEAKNESSES AND COMPETITIVE THREATS


14.1.2
EXXON MOBIL CORPORATION


14.1.3
BP P.L.C.


14.1.4
CHEVRON CORPORATION


14.1.5
TOTALENERGIES SE


14.1.6
IDEMITSU KOSAN CO., LTD.


14.1.7
CHINA PETROLEUM & CHEMICAL CORPORATION


14.1.8
FUCHS SE


14.1.9
ENEOS HOLDINGS, INC.


14.1.10
PETROLIAM NASIONAL BERHAD (PETRONAS)


14.2
OTHER PLAYERS


14.2.1
AXEL AMERICAS LLC


14.2.2
BALMER LAWRIE & CO. LTD.


14.2.3
PJSC “LUKOIL”


14.2.4
MARATHON PETROLEUM CORPORATION


14.2.5
CALUMET, INC.


14.2.6
SCHAEFFER MANUFACTURING CO.


14.2.7
WHITMORE MANUFACTURING LLC


14.2.8
HARRISON MANUFACTURING CO PTY LTD.


14.2.9
PHILLIPS 66


14.2.10
INDIAN OIL CORPORATION LIMITED (IOCL)


14.2.11
HEXOL INTERNATIONAL LTD.


14.2.12
LUBRI-LAB BC


14.2.13
PENRITE OIL


14.2.14
PT PERTAMINA LUBRICANTS


14.2.15
SAUDI ARABIAN OIL COMPANY


15
RESEARCH METHODOLOGY


286
 
15.1
RESEARCH DATA


15.1.1
SECONDARY DATA


15.1.1.1
KEY DATA FROM SECONDARY SOURCES


15.1.2
PRIMARY DATA


15.1.2.1
KEY DATA FROM PRIMARY SOURCES


15.1.2.2
PRIMARY INTERVIEW PARTICIPANTS


15.1.2.3
BREAKDOWN OF PRIMARY INTERVIEWS


15.1.2.4
KEY INDUSTRY INSIGHTS


15.2
MARKET SIZE ESTIMATION


15.2.1
BOTTOM-UP APPROACH


15.2.2
TOP-DOWN APPROACH


15.3
GROWTH FORECAST


15.3.1
SUPPLY SIDE


15.3.2
DEMAND SIDE


15.4
DATA TRIANGULATION


15.5
FACTOR ANALYSIS


15.6
RESEARCH ASSUMPTIONS


15.7
RESEARCH LIMITATIONS


15.8
RISK ASSESSMENT


16
APPENDIX


297
 
16.1
DISCUSSION GUIDE


16.2
KNOWLEDGESTORE: MARKETSANDMARKETS' SUBSCRIPTION PORTAL


16.3
CUSTOMIZATION OPTIONS


16.4
RELATED REPORTS


16.5
AUTHOR DETAILS


LIST OF TABLES


TABLE 1
GREASE MARKET: PORTER'S FIVE FORCES ANALYSIS


TABLE 2
GDP TRENDS AND FORECAST OF MAJOR ECONOMIES, 2022–2031 (USD BILLION)


TABLE 3
GLOBAL VEHICLE PRODUCTION TRENDS, 2021–2025


TABLE 4
GLOBAL STEEL PRODUCTION TRENDS, JUNE 2026


TABLE 5
GREASE MARKET: ROLE OF COMPANIES IN ECOSYSTEM


TABLE 6
AVERAGE SELLING PRICE OF GREASE OFFERED BY KEY PLAYERS, BY END-USE INDUSTRIES, 2025 (USD/KG)


TABLE 7
AVERAGE SELLING PRICE OF GREASE, BY REGION, 2023–2031 (USD/KG)


TABLE 8
IMPORT DATA FOR HS CODE 340399-COMPLIANT PRODUCTS, 2021–2025 (USD MILLION)


TABLE 9
EXPORT DATA FOR HS CODE 340399-COMPLIANT PRODUCTS, 2021–2025 (USD MILLION)


TABLE 10
GREASE MARKET: DETAILED LIST OF CONFERENCES & EVENTS, 2026–2027


TABLE 11
GREASE MARKET: FUNDING/INVESTMENT SCENARIO


TABLE 12
US ADJUSTED RECIPROCAL TARIFF RATES


TABLE 13
PATENT STATUS: PATENT APPLICATIONS, LIMITED PATENTS, AND GRANTED PATENTS


TABLE 14
LIST OF MAJOR PATENTS RELATED TO GREASE, 2015–2025


TABLE 15
TOP USE CASES AND MARKET POTENTIAL


TABLE 16
BEST PRACTICES: COMPANIES IMPLEMENTING USE CASES


TABLE 17
GREASE MARKET: CASE STUDIES RELATED TO GEN AI IMPLEMENTATION


TABLE 18
INTERCONNECTED ADJACENT ECOSYSTEM AND IMPACT ON MARKET PLAYERS


TABLE 19
NORTH AMERICA: REGULATORY BODIES, GOVERNMENT AGENCIES, AND OTHER ORGANIZATIONS


TABLE 20
EUROPE: REGULATORY BODIES, GOVERNMENT AGENCIES, AND OTHER ORGANIZATIONS


TABLE 21
ASIA PACIFIC: REGULATORY BODIES, GOVERNMENT AGENCIES, AND OTHER ORGANIZATIONS


TABLE 22
MIDDLE EAST & AFRICA: REGULATORY BODIES, GOVERNMENT AGENCIES, AND OTHER ORGANIZATIONS


TABLE 23
SOUTH AMERICA: REGULATORY BODIES, GOVERNMENT AGENCIES, AND OTHER ORGANIZATIONS


TABLE 24
GLOBAL STANDARDS IN GREASE MARKET


TABLE 25
CERTIFICATIONS, LABELING, AND ECO-STANDARDS IN GREASE MARKET


TABLE 26
INFLUENCE OF STAKEHOLDERS ON BUYING PROCESS, BY END-USE INDUSTRIES (%)


TABLE 27
KEY BUYING CRITERIA FOR TOP THREE END-USE INDUSTRIES


TABLE 28
GREASE MARKET: UNMET NEEDS IN KEY END-USE INDUSTRIES


TABLE 29
GREASE MARKET, BY BASE OIL, 2023–2025 (USD MILLION)


TABLE 30
GREASE MARKET, BY BASE OIL, 2026–2031 (USD MILLION)


TABLE 31
GREASE MARKET, BY BASE OIL, 2023–2025 (KILOTON)


TABLE 32
GREASE MARKET, BY BASE OIL, 2026–2031 (KILOTON)


TABLE 33
MINERAL OIL: GREASE MARKET, BY REGION, 2023–2025 (USD MILLION)


TABLE 34
MINERAL OIL: GREASE MARKET, BY REGION, 2026–2031 (USD MILLION)


TABLE 35
MINERAL OIL: GREASE MARKET, BY REGION, 2023–2025 (KILOTON)


TABLE 36
MINERAL OIL: GREASE MARKET, BY REGION, 2026–2031 (KILOTON)


TABLE 37
SYNTHETIC OIL: GREASE MARKET, BY REGION, 2023–2025 (USD MILLION)


TABLE 38
SYNTHETIC OIL: GREASE MARKET, BY REGION, 2026–2031 (USD MILLION)


TABLE 39
SYNTHETIC OIL: GREASE MARKET, BY REGION, 2023–2025 (KILOTON)


TABLE 40
SYNTHETIC OIL: GREASE MARKET, BY REGION, 2026–2031 (KILOTON)


TABLE 41
BIO-BASED OIL: GREASE MARKET, BY REGION, 2023–2025 (USD MILLION)


TABLE 42
BIO-BASED OIL: GREASE MARKET, BY REGION, 2026–2031 (USD MILLION)


TABLE 43
BIO-BASED OIL: GREASE MARKET, BY REGION, 2023–2025 (KILOTON)


TABLE 44
BIO-BASED OIL: GREASE MARKET, BY REGION, 2026–2031 (KILOTON)


TABLE 45
GREASE MARKET, BY THICKENER TYPE, 2023–2025 (USD MILLION)


TABLE 46
GREASE MARKET, BY THICKENER TYPE, 2026–2031 (USD MILLION)


TABLE 47
GREASE MARKET, BY THICKENER TYPE, 2023–2025 (KILOTON)


TABLE 48
GREASE MARKET, BY THICKENER TYPE, 2026–2031 (KILOTON)


TABLE 49
METALLIC SOAP THICKENER: GREASE MARKET, BY REGION, 2023–2025 (USD MILLION)


TABLE 50
METALLIC SOAP THICKENER: GREASE MARKET, BY REGION, 2026–2031 (USD MILLION)


TABLE 51
METALLIC SOAP THICKENER: GREASE MARKET, BY REGION, 2023–2025 (KILOTON)


TABLE 52
METALLIC SOAP THICKENER: GREASE MARKET, BY REGION, 2026–2031 (KILOTON)


TABLE 53
NON-SOAP THICKENER: GREASE MARKET, BY REGION, 2023–2025 (USD MILLION)


TABLE 54
NON-SOAP THICKENER: GREASE MARKET, BY REGION, 2026–2031 (USD MILLION)


TABLE 55
NON-SOAP THICKENER: GREASE MARKET, BY REGION, 2023–2025 (KILOTON)


TABLE 56
NON-SOAP THICKENER: GREASE MARKET, BY REGION, 2026–2031 (KILOTON)


TABLE 57
INORGANIC THICKENER: GREASE MARKET, BY REGION, 2023–2025 (USD MILLION)


TABLE 58
INORGANIC THICKENER: GREASE MARKET, BY REGION, 2026–2031 (USD MILLION)


TABLE 59
INORGANIC THICKENER: GREASE MARKET, BY REGION, 2023–2025 (KILOTON)


TABLE 60
INORGANIC THICKENER: GREASE MARKET, BY REGION, 2026–2031 (KILOTON)


TABLE 61
OTHER THICKENER TYPES: GREASE MARKET, BY REGION, 2023–2025 (USD MILLION)


TABLE 62
OTHER THICKENER TYPES: GREASE MARKET, BY REGION, 2026–2031 (USD MILLION)


TABLE 63
OTHER THICKENER TYPES: GREASE MARKET, BY REGION, 2023–2025 (KILOTON)


TABLE 64
OTHER THICKENER TYPES: GREASE MARKET, BY REGION, 2026–2031 (KILOTON)


TABLE 65
GREASE MARKET, BY END-USE INDUSTRY, 2023–2025 (USD MILLION)


TABLE 66
GREASE MARKET, BY END-USE INDUSTRY, 2026–2031 (USD MILLION)


TABLE 67
GREASE MARKET, BY END-USE INDUSTRY, 2023–2025 (KILOTON)


TABLE 68
GREASE MARKET, BY END-USE INDUSTRY, 2026–2031 (KILOTON)


TABLE 69
AUTOMOTIVE: GREASE MARKET, BY REGION, 2023–2025 (USD MILLION)


TABLE 70
AUTOMOTIVE: GREASE MARKET, BY REGION, 2026–2031 (USD MILLION)


TABLE 71
AUTOMOTIVE: GREASE MARKET, BY REGION, 2023–2025 (KILOTON)


TABLE 72
AUTOMOTIVE: GREASE MARKET, BY REGION, 2026–2031 (KILOTON)


TABLE 73
CONSTRUCTION: GREASE MARKET, BY REGION, 2023–2025 (USD MILLION)


TABLE 74
CONSTRUCTION: GREASE MARKET, BY REGION, 2026–2031 (USD MILLION)


TABLE 75
CONSTRUCTION: GREASE MARKET, BY REGION, 2023–2025 (KILOTON)


TABLE 76
CONSTRUCTION: GREASE MARKET, BY REGION, 2026–2031 (KILOTON)


TABLE 77
GENERAL MANUFACTURING: GREASE MARKET, BY REGION, 2023–2025 (USD MILLION)


TABLE 78
GENERAL MANUFACTURING: GREASE MARKET, BY REGION, 2026–2031 (USD MILLION)


TABLE 79
GENERAL MANUFACTURING: GREASE MARKET, BY REGION, 2023–2025 (KILOTON)


TABLE 80
GENERAL MANUFACTURING: GREASE MARKET, BY REGION, 2026–2031 (KILOTON)


TABLE 81
METAL PRODUCTION: GREASE MARKET, BY REGION, 2023–2025 (USD MILLION)


TABLE 82
METAL PRODUCTION: GREASE MARKET, BY REGION, 2026–2031 (USD MILLION)


TABLE 83
METAL PRODUCTION: GREASE MARKET, BY REGION, 2023–2025 (KILOTON)


TABLE 84
METAL PRODUCTION: GREASE MARKET, BY REGION, 2026–2031 (KILOTON)


TABLE 85
MINING: GREASE MARKET, BY REGION, 2023–2025 (USD MILLION)


TABLE 86
MINING: GREASE MARKET, BY REGION, 2026–2031 (USD MILLION)


TABLE 87
MINING: GREASE MARKET, BY REGION, 2023–2025 (KILOTON)


TABLE 88
MINING: GREASE MARKET, BY REGION, 2026–2031 (KILOTON)


TABLE 89
POWER GENERATION: GREASE MARKET, BY REGION, 2023–2025 (USD MILLION)


TABLE 90
POWER GENERATION: GREASE MARKET, BY REGION, 2026–2031 (USD MILLION)


TABLE 91
POWER GENERATION: GREASE MARKET, BY REGION, 2023–2025 (KILOTON)


TABLE 92
POWER GENERATION: GREASE MARKET, BY REGION, 2026–2031 (KILOTON)


TABLE 93
AGRICULTURE: GREASE MARKET, BY REGION, 2023–2025 (USD MILLION)


TABLE 94
AGRICULTURE: GREASE MARKET, BY REGION, 2026–2031 (USD MILLION)


TABLE 95
AGRICULTURE: GREASE MARKET, BY REGION, 2023–2025 (KILOTON)


TABLE 96
AGRICULTURE: GREASE MARKET, BY REGION, 2026–2031 (KILOTON)


TABLE 97
OTHER END-USE INDUSTRIES: GREASE MARKET, BY REGION, 2023–2025 (USD MILLION)


TABLE 98
OTHER END-USE INDUSTRIES: GREASE MARKET, BY REGION, 2026–2031 (USD MILLION)


TABLE 99
OTHER END-USE INDUSTRIES: GREASE MARKET, BY REGION, 2023–2025 (KILOTON)


TABLE 100
OTHER END-USE INDUSTRIES: GREASE MARKET, BY REGION, 2026–2031 (KILOTON)


TABLE 101
GREASE MARKET, BY REGION, 2023–2025 (USD MILLION)


TABLE 102
GREASE MARKET, BY REGION, 2026–2031 (USD MILLION)


TABLE 103
GREASE MARKET, BY REGION, 2023–2025 (KILOTON)


TABLE 104
GREASE MARKET, BY REGION, 2026–2031 (KILOTON)


TABLE 105
ASIA PACIFIC: GREASE MARKET, BY THICKENER TYPE, 2023–2025 (USD MILLION)


TABLE 106
ASIA PACIFIC: GREASE MARKET, BY THICKENER TYPE, 2026–2031 (USD MILLION)


TABLE 107
ASIA PACIFIC: GREASE MARKET, BY THICKENER TYPE, 2023–2025 (KILOTON)


TABLE 108
ASIA PACIFIC: GREASE MARKET, BY THICKENER TYPE, 2026–2031 (KILOTON)


TABLE 109
ASIA PACIFIC: GREASE MARKET, BY BASE OIL, 2023–2025 (USD MILLION)


TABLE 110
ASIA PACIFIC: GREASE MARKET, BY BASE OIL, 2026–2031 (USD MILLION)


TABLE 111
ASIA PACIFIC: GREASE MARKET, BY BASE OIL, 2023–2025 (KILOTON)


TABLE 112
ASIA PACIFIC: GREASE MARKET, BY BASE OIL, 2026–2031 (KILOTON)


TABLE 113
ASIA PACIFIC: GREASE MARKET, BY END-USE INDUSTRY, 2023–2025 (USD MILLION)


TABLE 114
ASIA PACIFIC: GREASE MARKET, BY END-USE INDUSTRY, 2026–2031 (USD MILLION)


TABLE 115
ASIA PACIFIC: GREASE MARKET, BY END-USE INDUSTRY, 2023–2025 (KILOTON)


TABLE 116
ASIA PACIFIC: GREASE MARKET, BY END-USE INDUSTRY, 2026–2031 (KILOTON)


TABLE 117
ASIA PACIFIC: GREASE MARKET, BY COUNTRY, 2023–2025 (USD MILLION)


TABLE 118
ASIA PACIFIC: GREASE MARKET, BY COUNTRY, 2026–2031 (USD MILLION)


TABLE 119
ASIA PACIFIC: GREASE MARKET, BY COUNTRY, 2023–2025 (KILOTON)


TABLE 120
ASIA PACIFIC: GREASE MARKET, BY COUNTRY, 2026–2031 (KILOTON)


TABLE 121
CHINA: GREASE MARKET, BY END-USE INDUSTRY, 2023–2025 (USD MILLION)


TABLE 122
CHINA: GREASE MARKET, BY END-USE INDUSTRY, 2026–2031 (USD MILLION)


TABLE 123
CHINA: GREASE MARKET, BY END-USE INDUSTRY, 2023–2025 (KILOTON)


TABLE 124
CHINA: GREASE MARKET, BY END-USE INDUSTRY, 2026–2031 (KILOTON)


TABLE 125
JAPAN: GREASE MARKET, BY END-USE INDUSTRY, 2023–2025 (USD MILLION)


TABLE 126
JAPAN: GREASE MARKET, BY END-USE INDUSTRY, 2026–2031 (USD MILLION)


TABLE 127
JAPAN: GREASE MARKET, BY END-USE INDUSTRY, 2023–2025 (KILOTON)


TABLE 128
JAPAN: GREASE MARKET, BY END-USE INDUSTRY, 2026–2031 (KILOTON)


TABLE 129
INDIA: GREASE MARKET, BY END-USE INDUSTRY, 2023–2025 (USD MILLION)


TABLE 130
INDIA: GREASE MARKET, BY END-USE INDUSTRY, 2026–2031 (USD MILLION)


TABLE 131
INDIA: GREASE MARKET, BY END-USE INDUSTRY, 2023–2025 (KILOTON)


TABLE 132
INDIA: GREASE MARKET, BY END-USE INDUSTRY, 2026–2031 (KILOTON)


TABLE 133
AUSTRALIA: GREASE MARKET, BY END-USE INDUSTRY, 2023–2025 (USD MILLION)


TABLE 134
AUSTRALIA: GREASE MARKET, BY END-USE INDUSTRY, 2026–2031 (USD MILLION)


TABLE 135
AUSTRALIA: GREASE MARKET, BY END-USE INDUSTRY, 2023–2025 (KILOTON)


TABLE 136
AUSTRALIA: GREASE MARKET, BY END-USE INDUSTRY, 2026–2031 (KILOTON)


TABLE 137
SOUTH KOREA: GREASE MARKET, BY END-USE INDUSTRY, 2023–2025 (USD MILLION)


TABLE 138
SOUTH KOREA: GREASE MARKET, BY END-USE INDUSTRY, 2026–2031 (USD MILLION)


TABLE 139
SOUTH KOREA: GREASE MARKET, BY END-USE INDUSTRY, 2023–2025 (KILOTON)


TABLE 140
SOUTH KOREA: GREASE MARKET, BY END-USE INDUSTRY, 2026–2031 (KILOTON)


TABLE 141
THAILAND: GREASE MARKET, BY END-USE INDUSTRY, 2023–2025 (USD MILLION)


TABLE 142
THAILAND: GREASE MARKET, BY END-USE INDUSTRY, 2026–2031 (USD MILLION)


TABLE 143
THAILAND: GREASE MARKET, BY END-USE INDUSTRY, 2023–2025 (KILOTON)


TABLE 144
THAILAND: GREASE MARKET, BY END-USE INDUSTRY, 2026–2031 (KILOTON)


TABLE 145
NORTH AMERICA: GREASE MARKET, BY THICKENER TYPE, 2023–2025 (USD MILLION)


TABLE 146
NORTH AMERICA: GREASE MARKET, BY THICKENER TYPE, 2026–2031 (USD MILLION)


TABLE 147
NORTH AMERICA: GREASE MARKET, BY THICKENER TYPE, 2023–2025 (KILOTON)


TABLE 148
NORTH AMERICA: GREASE MARKET, BY THICKENER TYPE, 2026–2031 (KILOTON)


TABLE 149
NORTH AMERICA: GREASE MARKET, BY BASE OIL, 2023–2025 (USD MILLION)


TABLE 150
NORTH AMERICA: GREASE MARKET, BY BASE OIL, 2026–2031 (USD MILLION)


TABLE 151
NORTH AMERICA: GREASE MARKET, BY BASE OIL, 2023–2025 (KILOTON)


TABLE 152
NORTH AMERICA: GREASE MARKET, BY BASE OIL, 2026–2031 (KILOTON)


TABLE 153
NORTH AMERICA: GREASE MARKET, BY END-USE INDUSTRY, 2023–2025 (USD MILLION)


TABLE 154
NORTH AMERICA: GREASE MARKET, BY END-USE INDUSTRY, 2026–2031 (USD MILLION)


TABLE 155
NORTH AMERICA: GREASE MARKET, BY END-USE INDUSTRY, 2023–2025 (KILOTON)


TABLE 156
NORTH AMERICA: GREASE MARKET, BY END-USE INDUSTRY, 2026–2031 (KILOTON)


TABLE 157
NORTH AMERICA: GREASE MARKET, BY COUNTRY, 2023–2025 (USD MILLION)


TABLE 158
NORTH AMERICA: GREASE MARKET, BY COUNTRY, 2026–2031 (USD MILLION)


TABLE 159
NORTH AMERICA: GREASE MARKET, BY COUNTRY, 2023–2025 (KILOTON)


TABLE 160
NORTH AMERICA: GREASE MARKET, BY COUNTRY, 2026–2031 (KILOTON)


TABLE 161
US: GREASE MARKET, BY END-USE INDUSTRY, 2023–2025 (USD MILLION)


TABLE 162
US: GREASE MARKET, BY END-USE INDUSTRY, 2026–2031 (USD MILLION)


TABLE 163
US: GREASE MARKET, BY END-USE INDUSTRY, 2023–2025 (KILOTON)


TABLE 164
US: GREASE MARKET, BY END-USE INDUSTRY, 2026–2031 (KILOTON)


TABLE 165
CANADA: GREASE MARKET, BY END-USE INDUSTRY, 2023–2025 (USD MILLION)


TABLE 166
CANADA: GREASE MARKET, BY END-USE INDUSTRY, 2026–2031 (USD MILLION)


TABLE 167
CANADA: GREASE MARKET, BY END-USE INDUSTRY, 2023–2025 (KILOTON)


TABLE 168
CANADA: GREASE MARKET, BY END-USE INDUSTRY, 2026–2031 (KILOTON)


TABLE 169
MEXICO: GREASE MARKET, BY END-USE INDUSTRY, 2023–2025 (USD MILLION)


TABLE 170
MEXICO: GREASE MARKET, BY END-USE INDUSTRY, 2026–2031 (USD MILLION)


TABLE 171
MEXICO: GREASE MARKET, BY END-USE INDUSTRY, 2023–2025 (KILOTON)


TABLE 172
MEXICO: GREASE MARKET, BY END-USE INDUSTRY, 2026–2031 (KILOTON)


TABLE 173
EUROPE: GREASE MARKET, BY THICKENER TYPE, 2023–2025 (USD MILLION)


TABLE 174
EUROPE: GREASE MARKET, BY THICKENER TYPE, 2026–2031 (USD MILLION)


TABLE 175
EUROPE: GREASE MARKET, BY THICKENER TYPE, 2023–2025 (KILOTON)


TABLE 176
EUROPE: GREASE MARKET, BY THICKENER TYPE, 2026–2031 (KILOTON)


TABLE 177
EUROPE: GREASE MARKET, BY BASE OIL, 2023–2025 (USD MILLION)


TABLE 178
EUROPE: GREASE MARKET, BY BASE OIL, 2026–2031 (USD MILLION)


TABLE 179
EUROPE: GREASE MARKET, BY BASE OIL, 2023–2025 (KILOTON)


TABLE 180
EUROPE: GREASE MARKET, BY BASE OIL, 2026–2031 (KILOTON)


TABLE 181
EUROPE: GREASE MARKET, BY END-USE INDUSTRY, 2023–2025 (USD MILLION)


TABLE 182
EUROPE: GREASE MARKET, BY END-USE INDUSTRY, 2026–2031 (USD MILLION)


TABLE 183
EUROPE: GREASE MARKET, BY END-USE INDUSTRY, 2023–2025 (KILOTON)


TABLE 184
EUROPE: GREASE MARKET, BY END-USE INDUSTRY, 2026–2031 (KILOTON)


TABLE 185
EUROPE: GREASE MARKET, BY COUNTRY, 2023–2025 (USD MILLION)


TABLE 186
EUROPE: GREASE MARKET, BY COUNTRY, 2026–2031 (USD MILLION)


TABLE 187
EUROPE: GREASE MARKET, BY COUNTRY, 2023–2025 (KILOTON)


TABLE 188
EUROPE: GREASE MARKET, BY COUNTRY, 2026–2031 (KILOTON)


TABLE 189
GERMANY: GREASE MARKET, BY END-USE INDUSTRY, 2023–2025 (USD MILLION)


TABLE 190
GERMANY: GREASE MARKET, BY END-USE INDUSTRY, 2026–2031 (USD MILLION)


TABLE 191
GERMANY: GREASE MARKET, BY END-USE INDUSTRY, 2023–2025 (KILOTON)


TABLE 192
GERMANY: GREASE MARKET, BY END-USE INDUSTRY, 2026–2031 (KILOTON)


TABLE 193
UK: GREASE MARKET, BY END-USE INDUSTRY, 2023–2025 (USD MILLION)


TABLE 194
UK: GREASE MARKET, BY END-USE INDUSTRY, 2026–2031 (USD MILLION)


TABLE 195
UK: GREASE MARKET, BY END-USE INDUSTRY, 2023–2025 (KILOTON)


TABLE 196
UK: GREASE MARKET, BY END-USE INDUSTRY, 2026–2031 (KILOTON)


TABLE 197
FRANCE: GREASE MARKET, BY END-USE INDUSTRY, 2023–2025 (USD MILLION)


TABLE 198
FRANCE: GREASE MARKET, BY END-USE INDUSTRY, 2026–2031 (USD MILLION)


TABLE 199
FRANCE: GREASE MARKET, BY END-USE INDUSTRY, 2023–2025 (KILOTON)


TABLE 200
FRANCE: GREASE MARKET, BY END-USE INDUSTRY, 2026–2031 (KILOTON)


TABLE 201
RUSSIA: GREASE MARKET, BY END-USE INDUSTRY, 2023–2025 (USD MILLION)


TABLE 202
RUSSIA: GREASE MARKET, BY END-USE INDUSTRY, 2026–2031 (USD MILLION)


TABLE 203
RUSSIA: GREASE MARKET, BY END-USE INDUSTRY, 2023–2025 (KILOTON)


TABLE 204
RUSSIA: GREASE MARKET, BY END-USE INDUSTRY, 2026–2031 (KILOTON)


TABLE 205
ITALY: GREASE MARKET, BY END-USE INDUSTRY, 2023–2025 (USD MILLION)


TABLE 206
ITALY: GREASE MARKET, BY END-USE INDUSTRY, 2026–2031 (USD MILLION)


TABLE 207
ITALY: GREASE MARKET, BY END-USE INDUSTRY, 2023–2025 (KILOTON)


TABLE 208
ITALY: GREASE MARKET, BY END-USE INDUSTRY, 2026–2031 (KILOTON)


TABLE 209
MIDDLE EAST & AFRICA: GREASE MARKET, BY THICKENER TYPE, 2023–2025 (USD MILLION)


TABLE 210
MIDDLE EAST & AFRICA: GREASE MARKET, BY THICKENER TYPE, 2026–2031 (USD MILLION)


TABLE 211
MIDDLE EAST & AFRICA: GREASE MARKET, BY THICKENER TYPE, 2023–2025 (KILOTON)


TABLE 212
MIDDLE EAST & AFRICA: GREASE MARKET, BY THICKENER TYPE, 2026–2031 (KILOTON)


TABLE 213
MIDDLE EAST & AFRICA: GREASE MARKET, BY BASE OIL, 2023–2025 (USD MILLION)


TABLE 214
MIDDLE EAST & AFRICA: GREASE MARKET, BY BASE OIL, 2026–2031 (USD MILLION)


TABLE 215
MIDDLE EAST & AFRICA: GREASE MARKET, BY BASE OIL, 2023–2025 (KILOTON)


TABLE 216
MIDDLE EAST & AFRICA: GREASE MARKET, BY BASE OIL, 2026–2031 (KILOTON)


TABLE 217
MIDDLE EAST & AFRICA: GREASE MARKET, BY END-USE INDUSTRY, 2023–2025 (USD MILLION)


TABLE 218
MIDDLE EAST & AFRICA: GREASE MARKET, BY END-USE INDUSTRY, 2026–2031 (USD MILLION)


TABLE 219
MIDDLE EAST & AFRICA: GREASE MARKET, BY END-USE INDUSTRY, 2023–2025 (KILOTON)


TABLE 220
MIDDLE EAST & AFRICA: GREASE MARKET, BY END-USE INDUSTRY, 2026–2031 (KILOTON)


TABLE 221
MIDDLE EAST & AFRICA: GREASE MARKET, BY COUNTRY, 2023–2025 (USD MILLION)


TABLE 222
MIDDLE EAST & AFRICA: GREASE MARKET, BY COUNTRY, 2026–2031 (USD MILLION)


TABLE 223
MIDDLE EAST & AFRICA: GREASE MARKET, BY COUNTRY, 2023–2025 (KILOTON)


TABLE 224
MIDDLE EAST & AFRICA: GREASE MARKET, BY COUNTRY, 2026–2031 (KILOTON)


TABLE 225
SAUDI ARABIA: GREASE MARKET, BY END-USE INDUSTRY, 2023–2025 (USD MILLION)


TABLE 226
SAUDI ARABIA: GREASE MARKET, BY END-USE INDUSTRY, 2026–2031 (USD MILLION)


TABLE 227
SAUDI ARABIA: GREASE MARKET, BY END-USE INDUSTRY, 2023–2025 (KILOTON)


TABLE 228
SAUDI ARABIA: GREASE MARKET, BY END-USE INDUSTRY, 2026–2031 (KILOTON)


TABLE 229
IRAN: GREASE MARKET, BY END-USE INDUSTRY, 2023–2025 (USD MILLION)


TABLE 230
IRAN: GREASE MARKET, BY END-USE INDUSTRY, 2026–2031 (USD MILLION)


TABLE 231
IRAN: GREASE MARKET, BY END-USE INDUSTRY, 2023–2025 (KILOTON)


TABLE 232
IRAN: GREASE MARKET, BY END-USE INDUSTRY, 2026–2031 (KILOTON)


TABLE 233
SOUTH AFRICA: GREASE MARKET, BY END-USE INDUSTRY, 2023–2025 (USD MILLION)


TABLE 234
SOUTH AFRICA: GREASE MARKET, BY END-USE INDUSTRY, 2026–2031 (USD MILLION)


TABLE 235
SOUTH AFRICA: GREASE MARKET, BY END-USE INDUSTRY, 2023–2025 (KILOTON)


TABLE 236
SOUTH AFRICA: GREASE MARKET, BY END-USE INDUSTRY, 2026–2031 (KILOTON)


TABLE 237
EGYPT: GREASE MARKET, BY END-USE INDUSTRY, 2023–2025 (USD MILLION)


TABLE 238
EGYPT: GREASE MARKET, BY END-USE INDUSTRY, 2026–2031 (USD MILLION)


TABLE 239
EGYPT: GREASE MARKET, BY END-USE INDUSTRY, 2023–2025 (KILOTON)


TABLE 240
EGYPT: GREASE MARKET, BY END-USE INDUSTRY, 2026–2031 (KILOTON)


TABLE 241
TURKEY: GREASE MARKET, BY END-USE INDUSTRY, 2023–2025 (USD MILLION)


TABLE 242
TURKEY: GREASE MARKET, BY END-USE INDUSTRY, 2026–2031 (USD MILLION)


TABLE 243
TURKEY: GREASE MARKET, BY END-USE INDUSTRY, 2023–2025 (KILOTON)


TABLE 244
TURKEY: GREASE MARKET, BY END-USE INDUSTRY, 2026–2031 (KILOTON)


TABLE 245
SOUTH AMERICA: GREASE MARKET, BY THICKENER TYPE, 2023–2025 (USD MILLION)


TABLE 246
SOUTH AMERICA: GREASE MARKET, BY THICKENER TYPE, 2026–2031 (USD MILLION)


TABLE 247
SOUTH AMERICA: GREASE MARKET, BY THICKENER TYPE, 2023–2025 (KILOTON)


TABLE 248
SOUTH AMERICA: GREASE MARKET, BY THICKENER TYPE, 2026–2031 (KILOTON)


TABLE 249
SOUTH AMERICA: GREASE MARKET, BY BASE OIL, 2023–2025 (USD MILLION)


TABLE 250
SOUTH AMERICA: GREASE MARKET, BY BASE OIL, 2026–2031 (USD MILLION)


TABLE 251
SOUTH AMERICA: GREASE MARKET, BY BASE OIL, 2023–2025 (KILOTON)


TABLE 252
SOUTH AMERICA: GREASE MARKET, BY BASE OIL, 2026–2031 (KILOTON)


TABLE 253
SOUTH AMERICA: GREASE MARKET, BY END-USE INDUSTRY, 2023–2025 (USD MILLION)


TABLE 254
SOUTH AMERICA: GREASE MARKET, BY END-USE INDUSTRY, 2026–2031 (USD MILLION)


TABLE 255
SOUTH AMERICA: GREASE MARKET, BY END-USE INDUSTRY, 2023–2025 (KILOTON)


TABLE 256
SOUTH AMERICA: GREASE MARKET, BY END-USE INDUSTRY, 2026–2031 (KILOTON)


TABLE 257
SOUTH AMERICA: GREASE MARKET, BY COUNTRY, 2023–2025 (USD MILLION)


TABLE 258
SOUTH AMERICA: GREASE MARKET, BY COUNTRY, 2026–2031 (USD MILLION)


TABLE 259
SOUTH AMERICA: GREASE MARKET, BY COUNTRY, 2023–2025 (KILOTON)


TABLE 260
SOUTH AMERICA: GREASE MARKET, BY COUNTRY, 2026–2031 (KILOTON)


TABLE 261
BRAZIL: GREASE MARKET, BY END-USE INDUSTRY, 2023–2025 (USD MILLION)


TABLE 262
BRAZIL: GREASE MARKET, BY END-USE INDUSTRY, 2026–2031 (USD MILLION)


TABLE 263
BRAZIL: GREASE MARKET, BY END-USE INDUSTRY, 2023–2025 (KILOTON)


TABLE 264
BRAZIL: GREASE MARKET, BY END-USE INDUSTRY, 2026–2031 (KILOTON)


TABLE 265
ARGENTINA: GREASE MARKET, BY END-USE INDUSTRY, 2023–2025 (USD MILLION)


TABLE 266
ARGENTINA: GREASE MARKET, BY END-USE INDUSTRY, 2026–2031 (USD MILLION)


TABLE 267
ARGENTINA: GREASE MARKET, BY END-USE INDUSTRY, 2023–2025 (KILOTON)


TABLE 268
ARGENTINA: GREASE MARKET, BY END-USE INDUSTRY, 2026–2031 (KILOTON)


TABLE 269
KEY PLAYERS' STRATEGIES/RIGHT TO WIN, 2021–2026


TABLE 270
GREASE MARKET: DEGREE OF COMPETITION, 2025


TABLE 271
GREASE MARKET: REGION FOOTPRINT


TABLE 272
GREASE MARKET: BASE OIL FOOTPRINT


TABLE 273
GREASE MARKET: THICKENER TYPE FOOTPRINT


TABLE 274
GREASE MARKET: END-USE INDUSTRY FOOTPRINT


TABLE 275
GREASE MARKET: DETAILED LIST OF KEY STARTUPS/SMES


TABLE 276
GREASE MARKET: COMPETITIVE BENCHMARKING OF KEY STARTUPS/SMES


TABLE 277
GREASE MARKET: PRODUCT LAUNCHES, JANUARY 2020–SEPTEMBER 2026


TABLE 278
GREASE MARKET: DEALS, JANUARY 2020–SEPTEMBER 2026


TABLE 279
GREASE MARKET: EXPANSIONS, JANUARY 2020–SEPTEMBER 2026


TABLE 280
SHELL PLC: COMPANY OVERVIEW


TABLE 281
SHELL PLC: PRODUCTS/SOLUTIONS/SERVICES OFFERED


TABLE 282
SHELL PLC: DEALS


TABLE 283
SHELL PLC: EXPANSIONS


TABLE 284
EXXON MOBIL CORPORATION: COMPANY OVERVIEW


TABLE 285
EXXON MOBIL CORPORATION: PRODUCTS/SOLUTIONS/SERVICES OFFERED


TABLE 286
EXXON MOBIL CORPORATION: DEALS


TABLE 287
EXXON MOBIL CORPORATION: EXPANSIONS


TABLE 288
BP P.L.C.: COMPANY OVERVIEW


TABLE 289
BP P.L.C.: PRODUCTS/SOLUTIONS/SERVICES OFFERED


TABLE 290
BP P.L.C.: EXPANSIONS


TABLE 291
CHEVRON CORPORATION: COMPANY OVERVIEW


TABLE 292
CHEVRON CORPORATION: PRODUCTS/SOLUTIONS/SERVICES OFFERED


TABLE 293
CHEVRON CORPORATION: PRODUCT LAUNCHES


TABLE 294
CHEVRON CORPORATION: DEALS


TABLE 295
CHEVRON CORPORATION: EXPANSIONS


TABLE 296
TOTALENERGIES SE: COMPANY OVERVIEW


TABLE 297
TOTALENERGIES SE: PRODUCTS/SOLUTIONS/SERVICES OFFERED


TABLE 298
TOTALENERGIES SE: DEALS


TABLE 299
TOTALENERGIES SE: EXPANSIONS


TABLE 300
IDEMITSU KOSAN CO., LTD.: COMPANY OVERVIEW


TABLE 301
IDEMITSU KOSAN CO., LTD: PRODUCTS/SOLUTIONS/SERVICES OFFERED


TABLE 302
IDEMITSU KOSAN CO., LTD.: EXPANSIONS


TABLE 303
CHINA PETROLEUM & CHEMICAL CORPORATION: COMPANY OVERVIEW


TABLE 304
CHINA PETROLEUM & CHEMICAL CORPORATION: PRODUCTS/SOLUTIONS/ SERVICES OFFERED


TABLE 305
CHINA PETROLEUM & CHEMICAL CORPORATION: DEALS


TABLE 306
FUCHS SE: COMPANY OVERVIEW


TABLE 307
FUCHS SE: PRODUCTS/SOLUTIONS/SERVICES OFFERED


TABLE 308
FUCHS SE: PRODUCT LAUNCHES


TABLE 309
FUCHS SE: DEALS


TABLE 310
FUCHS SE: EXPANSIONS


TABLE 311
ENEOS HOLDINGS, INC.: COMPANY OVERVIEW


TABLE 312
ENEOS HOLDINGS, INC.: PRODUCTS/SOLUTIONS/SERVICES OFFERED


TABLE 313
ENEOS HOLDINGS, INC.: DEALS


TABLE 314
PETROLIAM NASIONAL BERHAD (PETRONAS): COMPANY OVERVIEW


TABLE 315
PETROLIAM NASIONAL BERHAD (PETRONAS): PRODUCTS/SOLUTIONS/SERVICES OFFERED


TABLE 316
PETROLIAM NASIONAL BERHAD (PETRONAS): PRODUCT LAUNCHES


TABLE 317
PETROLIAM NASIONAL BERHAD (PETRONAS): DEALS


TABLE 318
PETROLIAM NASIONAL BERHAD (PETRONAS): EXPANSIONS


TABLE 319
AXEL AMERICAS LLC: COMPANY OVERVIEW


TABLE 320
BALMER LAWRIE & CO. LTD.: COMPANY OVERVIEW


TABLE 321
PJSC “LUKOIL”: COMPANY OVERVIEW


TABLE 322
MARATHON PETROLEUM CORPORATION: COMPANY OVERVIEW


TABLE 323
CALUMET, INC.: COMPANY OVERVIEW


TABLE 324
SCHAEFFER MANUFACTURING CO.: COMPANY OVERVIEW


TABLE 325
WHITMORE MANUFACTURING LLC: COMPANY OVERVIEW


TABLE 326
HARRISON MANUFACTURING CO PTY LTD: COMPANY OVERVIEW


TABLE 327
PHILLIPS 66: COMPANY OVERVIEW


TABLE 328
INDIAN OIL CORPORATION LIMITED (IOCL): COMPANY OVERVIEW


TABLE 329
HEXOL INTERNATIONAL LTD.: COMPANY OVERVIEW


TABLE 330
LUBRI-LAB BC: COMPANY OVERVIEW


TABLE 331
PENRITE OIL: COMPANY OVERVIEW


TABLE 332
PT PERTAMINA LUBRICANTS: COMPANY OVERVIEW


TABLE 333
SAUDI ARABIAN OIL COMPANY: COMPANY OVERVIEW


LIST OF FIGURES


FIGURE 1
GREASE MARKET SEGMENTATION AND REGIONAL SCOPE


FIGURE 2
KEY INSIGHTS AND MARKET HIGHLIGHTS


FIGURE 3
GLOBAL GREASE MARKET, 2026–2031


FIGURE 4
MAJOR STRATEGIES ADOPTED BY KEY PLAYERS IN GREASE MARKET (2021–2026)


FIGURE 5
DISRUPTIVE TRENDS IMPACTING GROWTH OF GREASE MARKET


FIGURE 6
HIGH-GROWTH SEGMENTS AND EMERGING FRONTIERS IN GREASE MARKET, 2025


FIGURE 7
ASIA PACIFIC TO REGISTER HIGHEST GROWTH DURING FORECAST PERIOD


FIGURE 8
RISING INDUSTRIAL DEMAND TO OFFER LUCRATIVE GROWTH OPPORTUNITIES FOR MARKET PLAYERS DURING FORECAST PERIOD


FIGURE 9
AUTOMOTIVE ACCOUNTED FOR LARGEST MARKET SHARE IN 2025


FIGURE 10
MINERAL OIL SEGMENT DOMINATED GREASE MARKET IN 2025


FIGURE 11
METALLIC SOAP THICKENER DOMINATED GREASE MARKET IN 2025


FIGURE 12
INDIA TO REGISTER HIGHEST CAGR DURING FORECAST PERIOD


FIGURE 13
GREASE MARKET: DRIVERS, RESTRAINTS, OPPORTUNITIES, AND CHALLENGES


FIGURE 14
GREASE MARKET: PORTER'S FIVE FORCES ANALYSIS


FIGURE 15
GREASE MARKET: SUPPLY CHAIN ANALYSIS


FIGURE 16
GREASE MARKET: KEY PARTICIPANTS IN ECOSYSTEM


FIGURE 17
GREASE MARKET: ECOSYSTEM ANALYSIS


FIGURE 18
AVERAGE SELLING PRICE OF GREASE OFFERED BY KEY PLAYERS, BY END-USE INDUSTRY, 2025


FIGURE 19
AVERAGE SELLING PRICE TREND OF GREASE, BY REGION, 2023–2031


FIGURE 20
IMPORT SCENARIO FOR HS CODE 340399-COMPLIANT PRODUCTS, BY KEY COUNTRIES, 2021–2025


FIGURE 21
EXPORT SCENARIO FOR HS CODE 340399-COMPLIANT PRODUCTS, BY KEY COUNTRIES, 2021–2025


FIGURE 22
TREND/DISRUPTIONS IMPACTING CUSTOMERS' BUSINESSES


FIGURE 23
PATENTS REGISTERED FOR GREASE, 2015–2025


FIGURE 24
MAJOR PATENTS RELATED TO GREASE, 2015–2025


FIGURE 25
LEGAL STATUS OF PATENTS FILED RELATED TO GREASE, 2015–2025


FIGURE 26
MAXIMUM PATENTS FILED IN JURISDICTION OF US, 2015–2025


FIGURE 27
IMPACT OF AI/GEN AI ON GREASE MARKET


FIGURE 28
GREASE MARKET: DECISION-MAKING FACTORS


FIGURE 29
INFLUENCE OF STAKEHOLDERS ON BUYING PROCESS, BY END-USE INDUSTRIES


FIGURE 30
KEY BUYING CRITERIA FOR TOP THREE END-USE INDUSTRIES


FIGURE 31
ADOPTION BARRIERS & INTERNAL CHALLENGES


FIGURE 32
MINERAL BASE OIL TO DOMINATE GREASE MARKET DURING FORECAST PERIOD


FIGURE 33
METALLIC SOAP THICKENER TO BE LARGEST SEGMENT DURING FORECAST PERIOD


FIGURE 34
AUTOMOTIVE INDUSTRY TO DOMINATE GREASE MARKET DURING FORECAST PERIOD


FIGURE 35
ASIA PACIFIC TO LEAD GREASE MARKET BETWEEN 2026 AND 2031


FIGURE 36
ASIA PACIFIC: GREASE MARKET SNAPSHOT


FIGURE 37
NORTH AMERICA: GREASE MARKET SNAPSHOT


FIGURE 38
EUROPE: GREASE MARKET SNAPSHOT


FIGURE 39
MARKET SHARE ANALYSIS OF KEY PLAYERS, 2025


FIGURE 40
REVENUE ANALYSIS OF TOP FIVE PLAYERS, 2022–2025


FIGURE 41
GREASE MARKET: COMPANY EVALUATION MATRIX (KEY PLAYERS), 2025


FIGURE 42
GREASE MARKET: COMPANY FOOTPRINT


FIGURE 43
GREASE MARKET: COMPANY EVALUATION MATRIX (STARTUPS/SMES), 2025


FIGURE 44
BRAND/PRODUCT COMPARISON


FIGURE 45
FINANCIAL METRICS (EV/EBITDA)


FIGURE 46
COMPANY VALUATION (USD BILLION)


FIGURE 47
SHELL PLC: COMPANY SNAPSHOT


FIGURE 48
EXXON MOBIL CORPORATION: COMPANY SNAPSHOT


FIGURE 49
BP P.L.C.: COMPANY SNAPSHOT


FIGURE 50
CHEVRON CORPORATION: COMPANY SNAPSHOT


FIGURE 51
TOTALENERGIES SE: COMPANY SNAPSHOT


FIGURE 52
IDEMITSU KOSAN CO., LTD.: COMPANY SNAPSHOT


FIGURE 53
CHINA PETROLEUM & CHEMICAL CORPORATION: COMPANY SNAPSHOT


FIGURE 54
FUCHS SE: COMPANY SNAPSHOT


FIGURE 55
ENEOS HOLDINGS, INC.: COMPANY SNAPSHOT


FIGURE 56
PETROLIAM NASIONAL BERHAD (PETRONAS): COMPANY SNAPSHOT


FIGURE 57
GREASE MARKET: RESEARCH DESIGN


FIGURE 58
MARKET SIZE ESTIMATION METHODOLOGY: APPROACH 1 (SUPPLY SIDE) - COLLECTIVE MARKET SHARE OF KEY PLAYERS


FIGURE 59
MARKET SIZE ESTIMATION METHODOLOGY: APPROACH 2 (SUPPLY SIDE) - COLLECTIVE REVENUE OF ALL PRODUCTS


FIGURE 60
MARKET SIZE ESTIMATION METHODOLOGY: APPROACH 3 (DEMAND SIDE)


FIGURE 61
TOP-DOWN APPROACH


FIGURE 62
CAGR PROJECTIONS FROM SUPPLY SIDE


FIGURE 63
GROWTH PROJECTIONS FROM DEMAND-SIDE DRIVERS


FIGURE 64
GREASE MARKET: DATA TRIANGULATION


Methodology

The study involved four major activities in estimating the market size for grease. Exhaustive secondary research was done to collect information on the market, the peer market, and the parent market. The next step was to validate these findings, assumptions, and sizing with industry experts across the value chain through primary research. Both top-down and bottom-up approaches were employed to estimate the complete market size. After that, the market breakdown and data triangulation procedures were used to estimate the market size of the segments and subsegments.

Secondary Research

Secondary sources used in this study included annual reports, press releases, and investor presentations of companies; white papers; certified publications; articles from recognized authors; and gold-standard and silver-standard websites, such as Factiva, ICIS, Bloomberg, and others. The findings of this study were verified through primary research, which involved conducting extensive interviews with key officials, including CEOs, VPs, directors, and other executives.

Primary Research

The grease market comprises several stakeholders, such as raw material suppliers, end-product manufacturers, and regulatory organizations in the supply chain. Various primary sources from both the supply and demand sides of the market were interviewed to obtain qualitative and quantitative information.

Breakdown of a Primary Interview
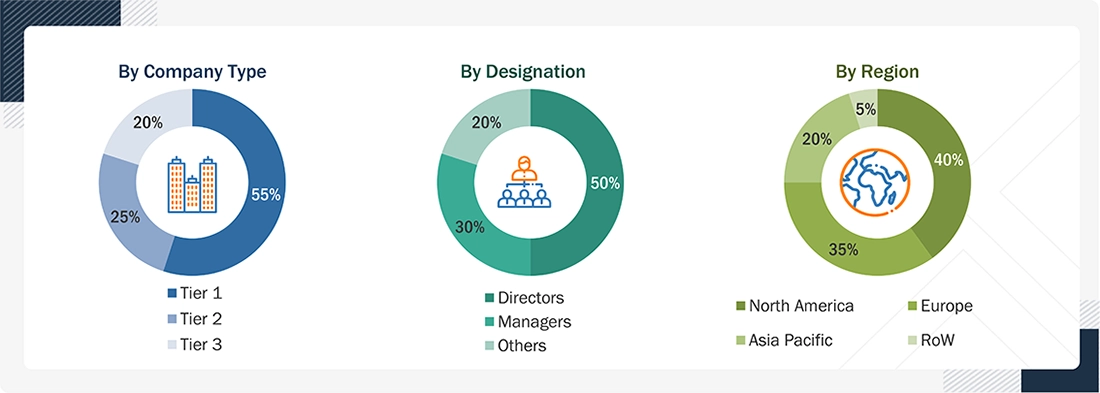
Grease Market Size, and Share

Notes: Tier 1, Tier 2, and Tier 3 companies are classified based on their market revenue in 2024/2025, available in the public domain, product portfolios, and geographical presence.
Other designations include consultants, marketing, and procurement managers.

COMPANY NAME

DESIGNATION

Shell plc

Senior Manager

FUCHS SE

Innovation Manager

BP p.l.c.

Vice-President

Exxon Mobil Corporation

Production Supervisor

TotalEnergies SE

Sales Manager

To know about the assumptions considered for the study, download the pdf brochure

Market Size Estimation

Both top-down and bottom-up approaches were used to estimate and validate the total size of the grease market. These methods were also used extensively to estimate the size of various subsegments in the market. The research methodology used to estimate the market size includes the following:

  • The key players in the industry have been identified through extensive secondary research.
  • The supply chain of the industry has been determined through primary and secondary research.
  • All percentage shares, splits, and breakdowns have been determined using secondary sources and verified through primary sources.
  • All possible parameters that affect the markets covered in this research study have been accounted for, viewed in extensive detail, verified through primary research, and analyzed to obtain the final quantitative and qualitative data.

Grease Market : Top-Down and Bottom-Up Approach
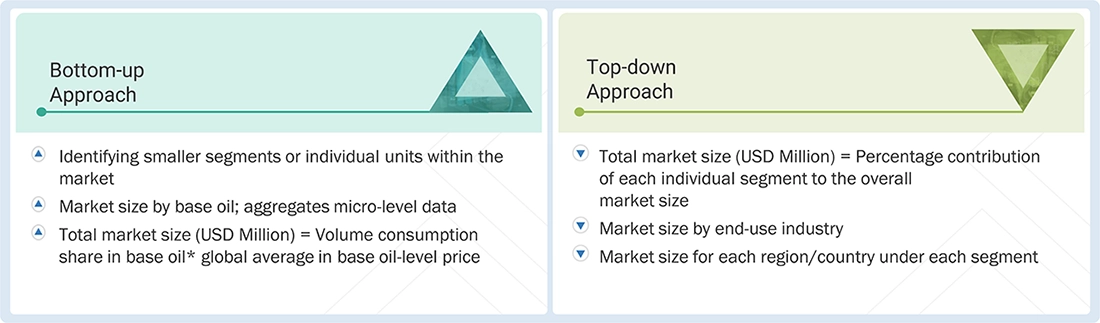
Grease Market Top Down and Bottom Up Approach

Data Triangulation

After determining the overall market size using the market size estimation processes explained above, the market was divided into several segments and subsegments. To complete the overall market engineering process and determine the exact statistics for each market segment and subsegment, data triangulation and market breakdown procedures were employed, as applicable. The data was triangulated by studying various factors and trends from both the demand and supply sides in the grease industry.

Market Definition

According to the American Society for Testing Materials (ASTM), grease is defined as “A semisolid or solid combination of a petroleum product and a soap or a mixture of soaps, with or without fillers, suitable for certain types of lubrication.”

Grease possesses high viscosity, which, on the application of shear drops, gives the effect of an oil-lubricated bearing. It consists of oil or other lubricant that is mixed with a thickener. It is used in places where lubricating oil would not stay in position. It also acts as a sealant to prevent the ingress of water and incompressible material. The end-use industries of grease include automotive, general manufacturing, mining, and steel, among others.

Key Stakeholders

  • Grease Manufacturers
  • Grease Distributors
  • Raw Material Suppliers
  • Service Providers
  • Industry Associations
  • Government and Research Organizations

Report Objectives

  • To analyze and forecast the size of the global grease market in terms of value and volume
  • To provide detailed information about the major drivers, restraints, challenges, and opportunities influencing market growth
  • To define, describe, and segment the market based on thickener type, base oil, and end-use industry
  • To forecast the size of the market segments based on regions such as North America, Europe, Asia Pacific, the Middle East & Africa, and South America
  • To strategically analyze micromarkets1 with respect to individual growth trends, prospects, and their contribution to the overall market
  • To strategically analyze the segmented markets with respect to individual growth trends, prospects, and contributions to the overall market
  • To identify and analyze opportunities for stakeholders in the market
  • To analyze competitive developments such as expansions, partnerships, collaborations, mergers & acquisitions, agreements, and product launches in the market
  • To strategically profile the key companies and comprehensively analyze their core competencies

Available customizations:

Along with the given market data, MarketsandMarkets offers customizations according to the company’s specific needs. The following customization options are available for the report:

Regional Analysis

  • Further breakdown of a region with respect to a particular country or additional end-use industry

Company Information

  • Detailed analysis and profiles of additional market players (up to five)

 

Personalize This Research

  • Triangulate with your Own Data
  • Get Data as per your Format and Definition
  • Gain a Deeper Dive on a Specific Application, Geography, Customer or Competitor
  • Any level of Personalization
Request A Free Customisation

Let Us Help You

  • What are the Known and Unknown Adjacencies Impacting the Grease Market
  • What will your New Revenue Sources be?
  • Who will be your Top Customer; what will make them switch?
  • Defend your Market Share or Win Competitors
  • Get a Scorecard for Target Partners
Customized Workshop Request

Custom Market Research Services

We Will Customise The Research For You, In Case The Report Listed Above Does Not Meet With Your Requirements

Get 10% Free Customisation

TESTIMONIALS

Growth opportunities and latent adjacency in Grease Market

DMCA.com Protection Status
popup img