Self-Driving Cars Market

Self-Driving Cars Market by Level of Autonomy (L1, L2, L3, L4, L5), Mobility (Personal & Shared), Component (LIDAR, Radar, Camera, GNSS & IMU, SOC), Vehicle Class (A&B, C&D, E&F), Autonomous Driving System (Perception & Sensing, Compute & AI, Localization & Mapping, Planning & Decision Making, Vehicle Control, Safety & Redundancy), EV (BEV, PHEV, FCEV), and Region - Global Forecast to 2035




OVERVIEW
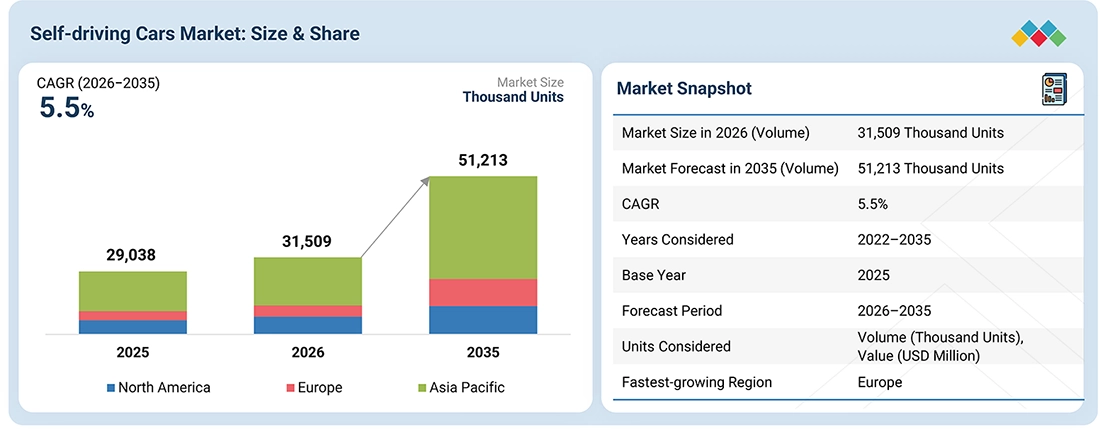
Source: Secondary Research, Interviews with Experts, MarketsandMarkets Analysis
The global self-driving cars market is projected to grow from 31,509 thousand units in 2026 to 51,213 thousand units by 2035, at a CAGR of 5.5%. Growth will increasingly depend on automakers’ ability to scale automated driving features across high-volume vehicle platforms while meeting stricter safety and regulatory requirements. Euro NCAP’s 2026 assessment protocols place greater emphasis on driver monitoring, real-world crash avoidance, and system usability, increasing the importance of proven safety performance rather than feature availability alone. In October 2026, Stellantis and Wayve demonstrated AI-driven autonomous driving technology in the Fiat 500e, with plans to integrate Wayve’s software into Stellantis’ STLA AutoDrive platform for a planned North American launch in 2028. Meanwhile, the proposed UNECE global regulation for automated driving systems signals progress toward harmonized approval of driverless vehicles. The key market differentiator will be the ability to deliver cost-effective, validated driving systems that satisfy regional regulations and scale beyond premium vehicles.
KEY TAKEAWAYS
-
By RegionThe Asia Pacific self-driving cars market dominates with a share of 64.1% in 2026.
-
By Level of AutonomyBy level of autonomy, the L3 segment is expected to register the highest CAGR of 29.0%.
-
By ComponentBy component, the LiDAR segment is projected to grow at the fastest rate from 2026 to 2035.
-
By Mobility TypeBy mobility type, the personal mobility segment is expected to dominate the market.
-
By Vehicle ClassBy vehicle class, the E&F segment is projected to grow at the fastest rate during the forecast period.
-
COMPETITIVE LANDSCAPE (KEY PLAYERS)Leading self driving car manufacturers, including Toyota Motor Corporation (Japan), Volkswagen Group (Germany), BYD Company Limited (China), Stellantis N.V. (Netherlands), and Hyundai Motor Group (South Korea), are advancing automated driving capabilities across passenger vehicle portfolios, focusing on AI-driven perception, centralized computing, sensor integration, and scalable Level 1 to Level 4 driving technologies.
-
COMPETITIVE LANDSCAPE (STARTUPS/SMES)The market also includes emerging autonomous driving technology companies such as Wayve (UK), Momenta (China), Pony.ai (China), WeRide (China), and May Mobility (US), which provide AI-based driving software, autonomous vehicle platforms, perception algorithms, and Level 4 autonomous driving solutions supporting OEM partnerships and commercial robotaxi deployment.
The self-driving cars market is moving from standalone driver assistance features toward integrated AI-driven driving systems, particularly across Level 2, Level 3, and Level 4 applications where perception, computing, safety validation, and software integration are increasingly interconnected. Automakers are prioritizing scalable driving platforms that can support multiple vehicle models, reduce system costs, and enable software upgrades throughout the vehicle lifecycle. Meanwhile, autonomous mobility providers are expanding robotaxi programs, creating demand for purpose-built vehicles, redundant sensing systems, high-performance computing, and fleet management software. Market growth will depend on the ability to translate technological progress into production-ready systems that meet regional regulations, achieve strong safety performance, and deliver commercially viable operating economics. Wider adoption of advanced driver assistance across mass-market vehicles is expected to drive near-term volumes, while higher automation levels will depend on regulatory approvals, infrastructure readiness, and reliable operation under diverse driving conditions. Ultimately, the commercial viability of self-driving cars will be shaped by the balance between automation capability, vehicle affordability, safety requirements, software scalability, and the total cost of ownership.
TRENDS & DISRUPTIONS IMPACTING CUSTOMERS' CUSTOMERS
The self-driving cars market is shifting from hardware-led L2 ADAS deployment toward software-driven autonomy and fleet-based mobility models. Current revenues are concentrated in sensors, computing systems, and driver assistance software, while future opportunities lie in L3 commercialization, L4 autonomous fleets, robotaxis, and recurring mobility services. Key industry priorities include reducing system costs, accelerating safety validation, and scaling deployments within defined operating domains. Competitive advantage will increasingly depend on AI capabilities, regulatory readiness, and commercially viable autonomous driving solutions.
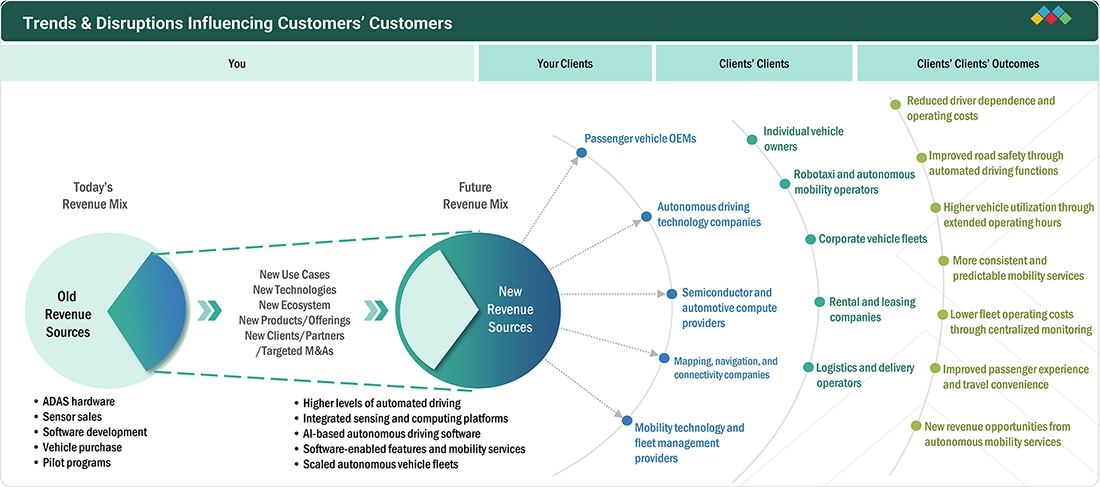
Source: Secondary Research, Interviews with Experts, MarketsandMarkets Analysis
MARKET DYNAMICS

Level
-
Shift toward software-defined vehicle architectures and centralized compute

-
Expansion of sensor-fusion and AI-based perception from ADAS toward higher automation levels


Level
-
High validation burden and edge-case complexity for higher-level autonomy


Level
-
Expansion of autonomous ride-hailing services and driverless passenger car fleets

-
Domain-specific Level 4 autonomy beyond private passenger cars


Level
-
Level 3 to Level 4 validation and ODD

Source: Secondary Research, Interviews with Experts, MarketsandMarkets Analysis
Driver: Expansion of sensor-fusion and AI-based perception from ADAS toward higher automation levels
Mandatory safety features, including automatic emergency braking, lane-keeping assistance, and driver monitoring, are accelerating ADAS adoption. Regulatory requirements and evolving safety standards are driving OEM investment in AI-based perception, sensor fusion, and advanced computing, supporting the expansion of Level 2 and Level 3 driving automation.
Restraint: High validation burden and edge-case complexity for higher-level autonomy
Higher-level autonomous driving requires extensive simulation and road testing to validate rare scenarios, adverse weather, and unpredictable road-user behavior. The resulting safety validation costs, computing requirements, and certification timelines increase development expenditure and delay commercialization, particularly for Level 3 and higher automation systems.
Opportunity: Domain-specific Level 4 autonomy beyond private passenger cars
Level 4 autonomy in controlled environments, such as mining sites, industrial facilities, ports, and logistics hubs, offers near-term deployment opportunities. Predictable operating routes and dedicated infrastructure simplify validation, enabling fleet operators to improve productivity, reduce labor dependency, and scale autonomous operations with lower complexity than unrestricted public-road driving.
Challenge: Level 3 to Level 4 validation and ODD
Transitioning from Level 3 to Level 4 autonomy requires rigorous validation across a wider range of operating design domains (ODDs), including weather, road conditions, and traffic scenarios. Ensuring safe operation and fallback capability increases testing complexity, system development costs, and deployment timelines, particularly for large-scale commercial adoption.
SELF-DRIVING CARS MARKET: COMMERCIAL USE CASES ACROSS INDUSTRIES
| COMPANY | USE CASE DESCRIPTION | BENEFITS |
|---|---|---|
 |
Integration of Level 2 and Level 3 advanced driver assistance and automated driving technologies across passenger vehicles, supported by sensor fusion, automated control systems, and software-based vehicle functions. | Improves driving safety and convenience, reduces driver workload, and supports the gradual adoption of automated driving features. Software and system integration capabilities can also enable future upgrades across vehicle platforms. |
 |
Deployment of advanced driver assistance systems, including adaptive cruise control, lane-keeping assistance, automated parking, and highway driving assistance, across selected vehicle models. | Enhances driver assistance, improves comfort in highway and congested traffic conditions, and supports the standardization of software-enabled driving functions across vehicle platforms. |
 |
Integration of intelligent driving assistance, sensor-based perception, and automated parking functions into electric passenger vehicles, supported by vehicle electronics and software integration. | Improves driving convenience, strengthens safety assistance, and expands access to intelligent driving features across electric vehicle segments. Greater integration of hardware and software supports scalable feature deployment. |
 |
Implementation of Level 2 advanced driver assistance and selected hands-free driving capabilities, including highway assistance, adaptive cruise control, and lane-centering functions across eligible vehicle models. | Reduces driver workload during long-distance travel, improves driving comfort, and enables differentiated technology offerings across vehicle brands. Software integration supports the expansion of driver assistance capabilities across multiple vehicle platforms. |
 |
Deployment of Highway Driving Assist, adaptive cruise control, lane-following assistance, and remote smart parking functions across selected passenger vehicles, with continued development of higher-level automated driving technologies. | Improves driver convenience and highway safety assistance, simplifies parking in constrained spaces, and supports broader adoption of automated driving technologies across vehicle categories. |
Logos and trademarks shown above are the property of their respective owners. Their use here is for informational and illustrative purposes only.
MARKET ECOSYSTEM
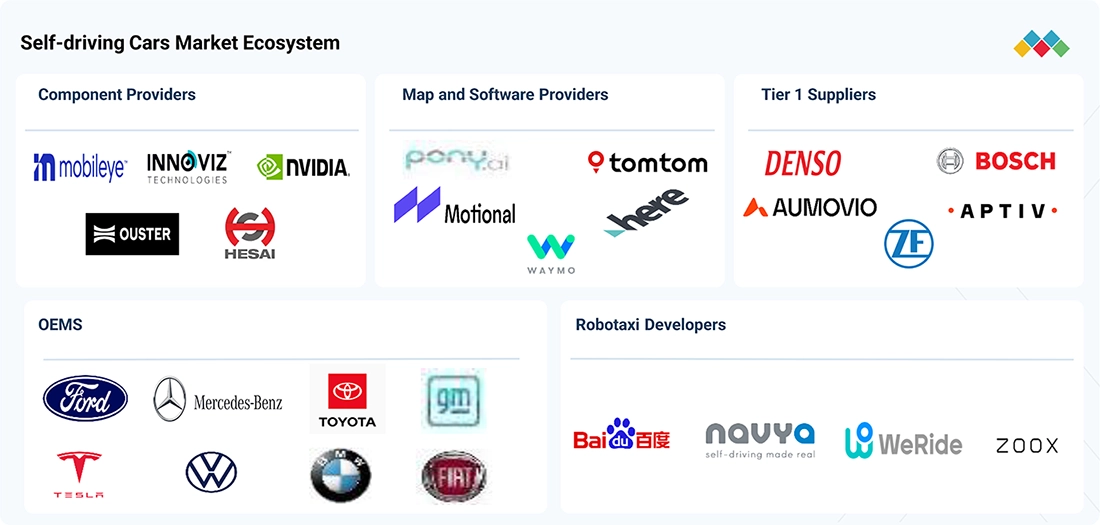
The self-driving cars market ecosystem comprises component and semiconductor providers (NVIDIA, Mobileye, Hesai) supplying sensing, AI computing, and perception technologies; Tier 1 suppliers (Bosch, ZF, Aptiv) integrating autonomous driving systems; and OEMs (Tesla, Toyota, BYD) deploying these capabilities across passenger vehicles. Software and mapping providers (HERE, TomTom) support localization and navigation, while robotaxi developers (Waymo, Baidu Apollo, Zoox) advance driverless mobility through fleet testing and commercial deployments. Collaboration across these stakeholders accelerates technology integration, improves system reliability, and supports the transition toward scalable autonomous driving solutions.
Logos and trademarks shown above are the property of their respective owners. Their use here is for informational and illustrative purposes only.
MARKET SEGMENTS
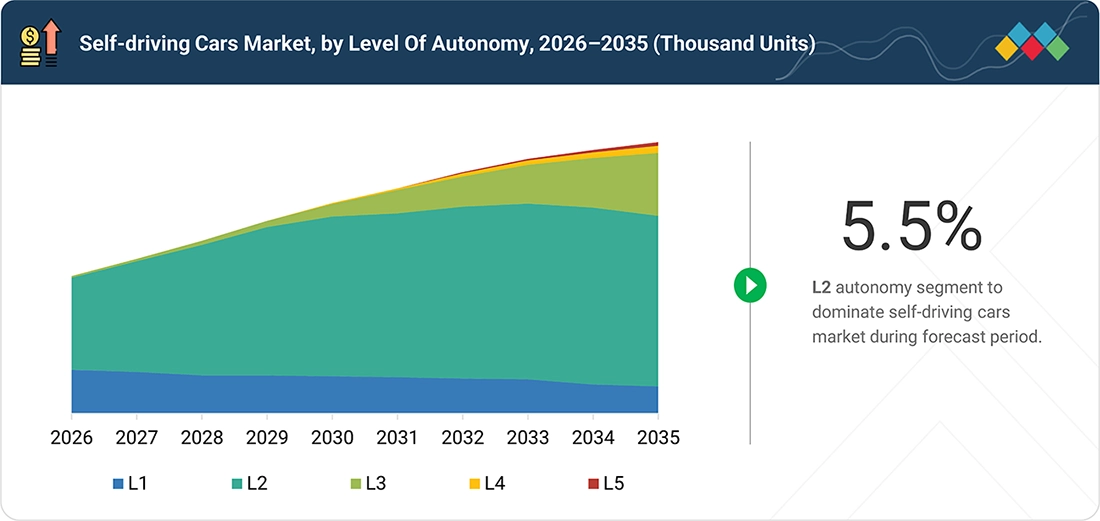
Source: Secondary Research, Interviews with Experts, MarketsandMarkets Analysis
Self-Driving Cars Market, By Level of Autonomy
L3 is expected to gain traction in the self-driving cars market as automakers move from advanced driver assistance toward conditional automated driving, supported by improving AI-based driving systems and clearer regulatory pathways. In July 2026, Volkswagen’s CARIZON and Horizon Robotics expanded their partnership in China to develop advanced driving solutions, including L3 systems, with L3-equipped Volkswagen models planned for the Chinese market from the second half of 2027. The partnership combines Volkswagen’s vehicle development capabilities with Horizon Robotics’ autonomous driving computing and software technologies. AI-based driving software, high-performance computing platforms, and regulatory frameworks are expected to support L3 adoption in self-driving cars.
Self-Driving Cars Market, By Component Type
Radar is expected to have a significant share during the forecast period, driven by its essential role in enhancing vehicle safety and supporting ADAS. The integration of radar into cost-optimized sensing architectures is also expanding its use across mass-market passenger cars. In 2026, NXP Semiconductors introduced its SAF8444 automotive radar SoC, designed to support L2 and L2+ ADAS applications by integrating key radar functions into a single chip, helping reduce system complexity and component requirements. NXP Semiconductors ' SAF8444 automotive radar SoC. Such developments are expected to support wider radar adoption by improving sensing capabilities while enabling more compact and cost-efficient radar architectures.
Self-Driving Cars Market, By Vehicle Class
C&D cars are expected to hold a significant share of the self-driving cars market, supported by the integration of Level 2 automated driving functions across mid-size passenger cars and SUVs. OEMs are expanding advanced driver assistance features in high-volume C&D models to increase the availability of automated driving technology in mainstream passenger vehicles. In October 2026, BMW Group introduced the new BMW 3 Series, with all variants equipped with SAE Level 2 driver assistance systems and active safety functions. The vehicle also features the BMW Motorway Assistant, enabling hands-free driving at speeds of up to 130 km/h on suitable roads, along with automated lane changes. The expansion of Level 2 capabilities across mainstream C&D models is expected to support the growth of this segment.
Self-Driving Cars Market, By Mobility Type
Shared mobility is expected to witness significant growth in the self-driving cars market during the forecast period, supported by the increasing deployment of Level 4 autonomous passenger cars for robotaxi and autonomous ride-hailing services. The expansion of autonomous ride-hailing services is supporting the transition toward shared mobility. In September 2026, Waymo opened fully autonomous public rides in Las Vegas, further expanding its commercial robotaxi operations in the US. The growing use of higher levels of automation in commercial passenger transportation, while Level 4 and Level 5 vehicles are expected to support the expansion of shared mobility through robotaxis and autonomous ride-hailing services.
Self-Driving Cars Market, By EV Type
BEVs are expected to hold a significant share of the self-driving cars market during the forecast period, driven by the increasing integration of centralized computing and advanced automated driving systems in electric vehicle platforms. In January 2026, Mercedes-Benz introduced MB.DRIVE ASSIST PRO on the all-electric CLA, providing SAE Level 2 automated point-to-point driving. The system integrates around 30 sensors, including cameras, radar, and ultrasonic sensors, with centralized computing delivering up to 508 TOPS, strengthening the integration of advanced automated driving capabilities in BEVs. These developments are supporting the adoption of BEVs in the self-driving cars market by integrating advanced automated driving, sensing, and computing capabilities into electric vehicle platforms.
REGION
Asia Pacific to hold largest share in global self-driving cars market during forecast period
In 2026, Asia Pacific remains a key growth region for the self-driving cars market, led by China’s rapid deployment of intelligent driving systems and robotaxis. China’s new mandatory safety standards for L3 and L4 systems, scheduled for 2027, are strengthening the focus on validation and regulatory compliance. Japan and South Korea are advancing autonomous mobility initiatives, while India offers growth potential through expanding ADAS adoption. Regional growth will depend on scalable AI-driven driving systems, cost-efficient vehicle computing, safety validation, and regulatory readiness.
SELF-DRIVING CARS MARKET: COMPANY EVALUATION MATRIX
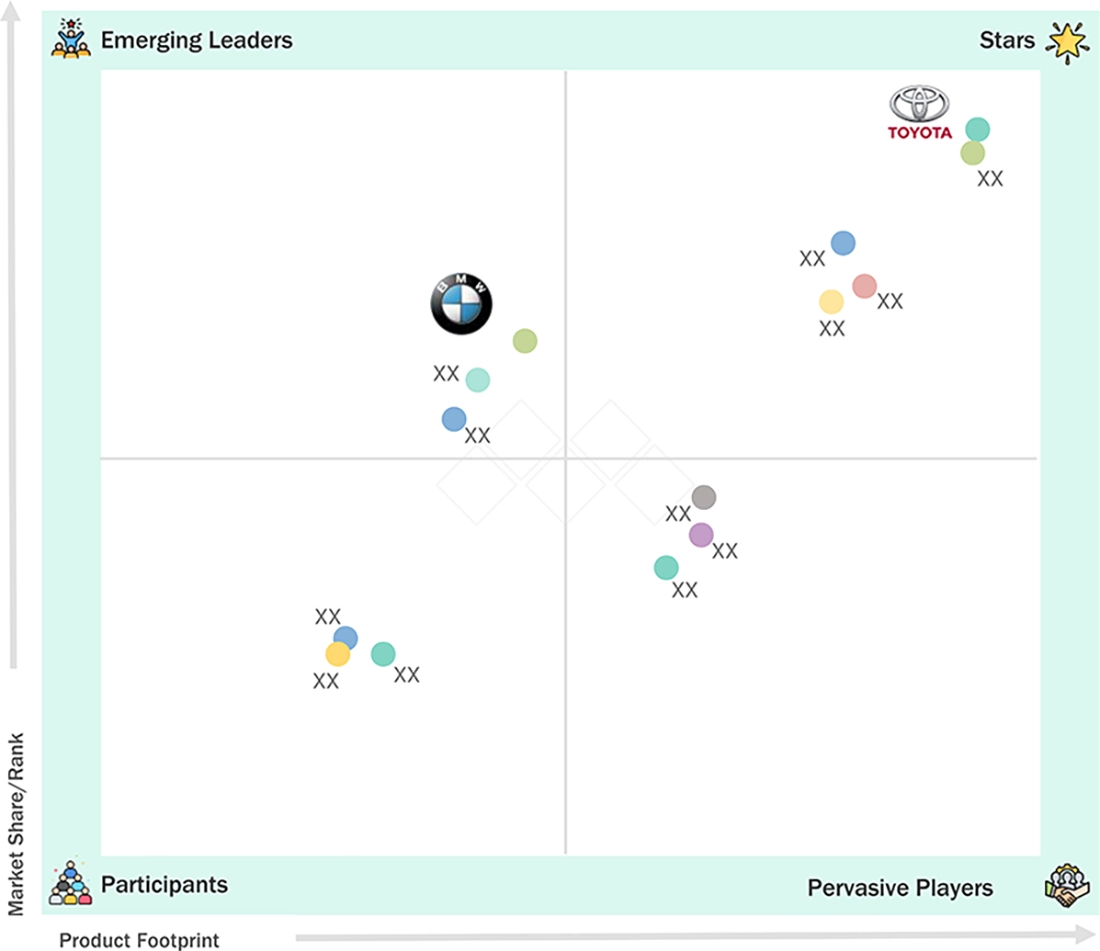
In the self-driving cars market, Toyota Motor Corporation (Star) leads with a strong market share and a broad product footprint, driven by its steady rollout of advanced automated driving features across various passenger car models. BMW Group (Emerging Leader) is gaining visibility with focused progress in autonomous driving software, sensor fusion, and platform-level integration, strengthening its position through rapid development cycles and targeted technology investments. While Toyota dominates through scale and a wide technology portfolio, BMW shows significant potential to move toward the leaders quadrant as demand for higher autonomy levels continues to rise.
Source: Secondary Research, Interviews with Experts, MarketsandMarkets Analysis
KEY MARKET PLAYERS
- Toyota Motor Corporation (Japan)
- Volkswagen Group (Germany)
- BYD Company (China)
- Stellantis N.V. (Netherlands)
- Hyundai Motor Group (South Korea)
- BMW Group (Germany)
- Nissan Motor Co. (Japan)
- Tesla (US)
- Honda Motor Co. (Japan)
- Mercedes Benz Group AG (Germany)
- Ford Motor Company (US)
- Renault Group (France)
- Motional, Inc. (US)
- Zoox, Inc. (US)
- NAVYA (France)
MARKET SCOPE
| REPORT METRIC | DETAILS |
|---|---|
| Market Size in 2026 (Volume) | 31,509 Thousand Units |
| Market Forecast in 2035 (Volume) | 51,213 Thousand Units |
| Growth Rate | CAGR of 5.5% from 2026-2035 |
| Years Considered | 2022-2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Units Considered | Value (USD Million), Volume (Thousand Units) |
| Report Coverage | Revenue forecast, company ranking, competitive landscape, growth factors, and trends |
| Segments Covered |
|
| Regions Covered | North America, Asia Pacific, Europe |
WHAT IS IN IT FOR YOU: SELF-DRIVING CARS MARKET REPORT CONTENT GUIDE
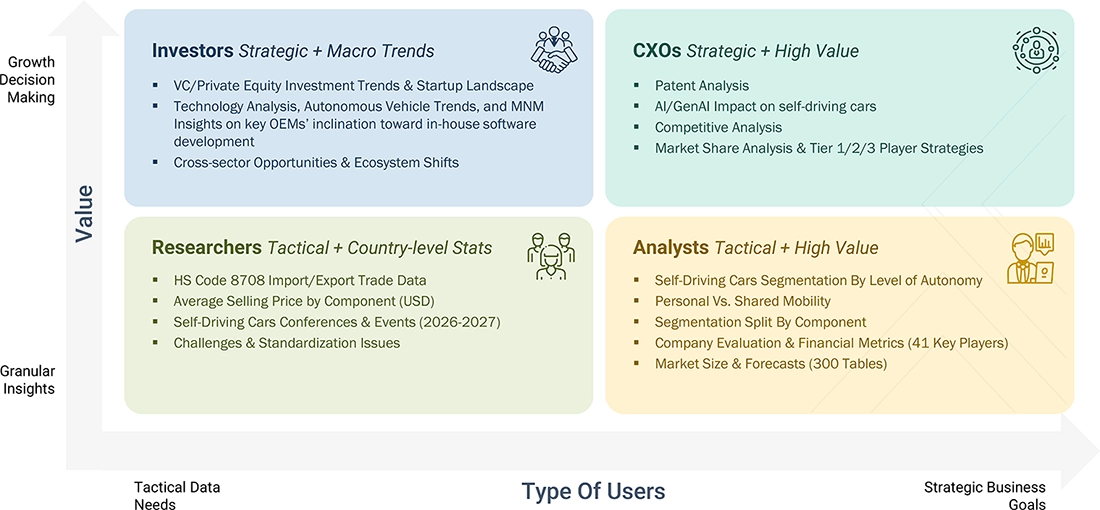
DELIVERED CUSTOMIZATIONS
We have successfully delivered the following deep-dive customizations:
| CLIENT REQUEST | CUSTOMIZATION DELIVERED | VALUE ADDS |
|---|---|---|
| OEM |
|
|
| Component Manufacturer |
|
|
| Map/Software Provider |
|
|
| Tier-1 Supplier |
|
|
| Mobility Service Provider |
|
|
| Government Agencies |
|
|
| Investment Firms |
|
|
| Testing & Validation Companies |
|
|
RECENT DEVELOPMENTS
- July 2026 : Qualcomm made an agreement with BMW to supply Snapdragon Digital Chassis solutions for BMW’s future vehicle platforms. The agreement covers cockpit processors, automated driving chips, and AI accelerators for BMW’s next generation digital and advanced driver assistance systems.
- July 2026 : Volkswagen launched the MOIA robotaxi service in Hamburg, using autonomous ID. Buzz vehicles. The initial service operated with five vehicles and allowed pre-registered passengers to book shared autonomous rides through the MOIA app.
- May 2026 : BYD introduced an upgraded God's Eye system with XUANJI Architecture 2.0, a satellite sensor architecture, an upgraded physical AI model, and a self-evolving data system.
- April 2026 : Tesla launched FSD Supervised v14.3, which is an updated version of FSD Supervised. The update added improvements to reinforcement learning, visual perception in low-visibility conditions, AI model development, and inference latency. Tesla stated that these developments support its longer-term objective of unsupervised autonomy for Robotaxi vehicles and customer-owned vehicles.
- January 2026 : Pony.ai partnered with Toyota to develop and deploy mass-produced robotaxis. The partnership combines Pony.ai’s autonomous driving technology with Toyota’s vehicle manufacturing capabilities to support commercial robotaxi deployment in China.
Table of Contents
 Exclusive indicates content/data unique to MarketsandMarkets and not available with any competitors.
Methodology
The research study used extensive secondary sources, such as company annual reports/presentations, industry association publications, magazine articles, directories, technical handbooks, World Economic Outlook, trade websites, technical articles, and databases, to identify and collect information on the self-driving cars market. Primary sources, including experts from related industries, OEMs, and suppliers, were interviewed to obtain and verify critical information and assess growth prospects and market estimates.
Secondary Research
Secondary sources for this research study included corporate filings, such as annual reports, investor presentations, and financial statements; trade, business, and professional associations; whitepapers and self-driving car and ADAS-related journals; certified publications; articles by recognized authors; directories; and databases. Secondary data was collected and analyzed to determine the overall market size, further validated by primary research.
Primary Research
After understanding the self-driving cars market scenario through secondary research, extensive primary research was conducted. Primary interviews were conducted with market experts from both demand and supply sides across North America, Europe, and Asia Pacific. Approximately 35% of interviews were conducted from the demand side, while 65% of primary interviews were conducted from the supply side. Primary data were collected through questionnaires, emails, and telephone interviews.
In the canvassing of primary data, various departments within organizations, such as sales and operations, were covered to provide a holistic viewpoint in this report. Primary sources from the supply side included various industry experts, such as CXOs, vice presidents, directors from business development, marketing, product development/innovation teams, and related key executives from various key companies. Various system integrators, industry associations, independent consultants’/industry veterans, and key opinion leaders were also interviewed.
Breakdown of Primary Interviews
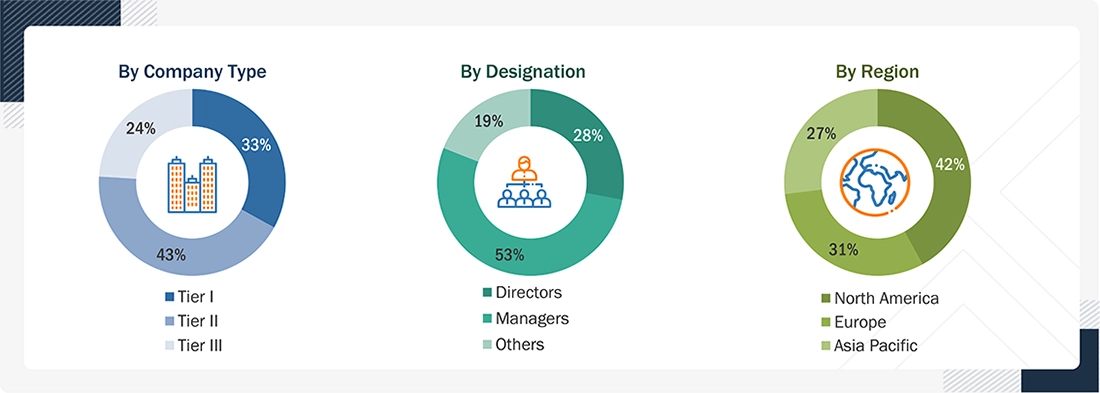
Note: Others include purchase and sales managers, marketing managers, and product managers.
Company tiers are based on the value chain; the company's revenue is not considered.
To know about the assumptions considered for the study, download the pdf brochure
Market Size Estimation
Bottom-up approach
The bottom-up approach was used to estimate and validate the size of the self-driving cars market. In this approach, vehicle sales statistics for each vehicle class were considered at the country and regional levels. The penetration of the level of autonomy for each passenger car at the country level was identified through model mapping to determine the market size of self-driving cars in terms of volume. Then, the penetration of each level of autonomy in passenger cars for all countries was applied to obtain the volume of the self-driving cars market.
Extensive secondary and primary research was conducted to understand the global market scenario for ADAS features with respect to the level of autonomy used in the automotive industry. Several primary interviews were conducted with key opinion leaders related to self-driving car development, including OEMs, Tier 1 suppliers, and applications. Qualitative aspects such as drivers, restraints, opportunities, and challenges were considered while calculating and forecasting the market size.
Top-down approach
The top-down approach was used to determine the size of the self-driving cars market for the component segment. Although the total market size in value (USD million) was derived using the bottom-up approach, the component segment was derived using the top-down approach. For instance, the self-driving cars market for the component segment was derived using the top-down approach to estimate the subsegments. Mapping was done at the regional level to understand the contribution by component. The market size was derived at the regional level in terms of value. The total value of the self-driving cars market was multiplied by the cost breakdown percentage of each component at the regional level.
Self-Driving Cars Market: Top-Down and Bottom-Up Approach

Data Triangulation
After arriving at the overall market size of the global market through the methodology mentioned above, this market was split into several segments and subsegments. The data triangulation and market breakdown procedures were employed to complete the overall market engineering process and arrive at the exact market value data for the key segments and sub-segments, wherever applicable. The extrapolated market data was triangulated by studying various macro indicators and regional trends from both the demand and supply-side participants.
Market Definition
Self-driving cars are technologies capable of performing dynamic driving tasks, with or without human supervision. The California DMV defines autonomous mode as when the technology manages driving operations independently. At the same time, SAE Level 5 autonomy represents vehicles capable of moving under all conditions without human intervention, even with a user in the driver's seat.
Key Stakeholders
- ADAS Integrators
- ADAS Solution Suppliers
- Associations, Forums, and Alliances related to Autonomous Vehicles
- Automotive Component Manufacturers
- Automotive Industry Associations, Government Authorities, and Research Organizations
- Automotive OEMs
- Automotive Sensor Manufacturers
- Automotive SoC and ECU Manufacturers
- Automotive Software and Platform Providers
- Autonomous Driving Platform Providers
- Autonomous Vehicle Manufacturers
- Country-specific Automotive Associations
- European Automobile Manufacturers Association (ACEA)
- Government and Research Organizations
- National Highway Traffic Safety Administration (NHTSA)
- Transport Authorities
- Vehicle Safety Regulatory Bodies
Report Objectives
- To analyze and forecast the self-driving cars market in terms of volume (thousand units) and value (USD million) from 2026 to 2035
-
To segment the market by level of autonomy, component type, mobility type, vehicle class, region, EV type, and autonomous driving system
- To segment and forecast the market by level of autonomy (semi-autonomous (L1, L2, and L3), and autonomous (L4 and L5))
- To segment and forecast the market by component type (camera, LiDAR, radar, ultrasonic sensors, infrared sensors, GNSS & IMU, SOC, and others)
- To segment and forecast the market by mobility type (personal mobility and shared mobility)
- To segment and forecast the market by vehicle class (A&B, C&D, and E&F)
- To forecast the market by region [North America, Europe, and Asia Pacific]
- To segment and forecast the market by autonomous driving system (perception & sensing, compute & AI, localization & mapping, planning & decision making, vehicle control, safety & redundancy)
- To segment and forecast the market by EV type (BEV, PHEV, and FCEV)
- To identify and analyze key drivers, challenges, restraints, and opportunities influencing market growth
- To strategically analyze the market for individual growth trends, prospects, and contributions to the total market
-
To study the following with respect to the market
- Pricing Analysis
- Investment and Funding Scenario
- Value Chain Analysis
- Ecosystem Analysis
- Technology Analysis
- Trade Analysis
- Case Study Analysis
- Patent Analysis
- Regulatory Landscape
- Key Stakeholders and Buying Criteria
- Key Conferences and Events
- To strategically profile the key players and comprehensively analyze their market share and core competencies
- To analyze the impact of AI on the market
- To track and analyze competitive developments such as deals, product launches/developments, expansions, and other activities undertaken by the key industry participants
Available customizations:
Along with the market data, MarketsandMarkets offers customizations in accordance with a company’s specific needs.
- self-driving cars Market, by Level of Autonomy, at country level
- self-driving cars Market, by EV type, at country level
Company Information
-
Profiling of additional market players (up to five)


Personalize This Research
- Triangulate with your Own Data
- Get Data as per your Format and Definition
- Gain a Deeper Dive on a Specific Application, Geography, Customer or Competitor
- Any level of Personalization
Let Us Help You
- What are the Known and Unknown Adjacencies Impacting the Self-Driving Cars Market
- What will your New Revenue Sources be?
- Who will be your Top Customer; what will make them switch?
- Defend your Market Share or Win Competitors
- Get a Scorecard for Target Partners

Custom Market Research Services
We Will Customise The Research For You, In Case The Report Listed Above Does Not Meet With Your Requirements
Get 10% Free CustomisationTESTIMONIALS
JIM NAAS
PRODUCT DIRECTOR, WEASLER
Weasler Engineering, a CentroMotion organization
Global Provider of Industrial Actuation & Control Solutionswww.weasler.com
Our organization was interested in learning more about the attractiveness of a particular market space. We contacted MarketsandMarkets to help us based on previous positive experiences we had with them. The results did not disappoint! We discussed our objectives with them, and the team at MarketsandMarkets developed and executed a proposal that met our needs precisely. We were very impressed by their level of expertise, the quality of the analysis and their insightful recommendations. We would not hesitate in working with them again in the future.

Matt Kardel,
Vice President
Aptiv,
A global technology company that develops safer, greener and more connected solutions.www.aptiv.com
We contracted with
MarketsandMarkets to evaluate the value chain and potential go-to-market partners related to our
interest in the Fleet Management space. The team successfully completed the work on time and at the
pricing agreed. MarketsandMarkets listened and understood our objectives and collaborated well with
us to help us get the visibility we needed to make an investment.
We have subsequently used
MarketsandMarkets again related to Smart Cities to good results.
- China Self-driving Cars Market
- India Self-driving Cars Market
- Japan Self-driving Cars Market
- South Korea Self-driving Cars Market
- Germany Self-driving Cars Market
- France Self-driving Cars Market
- Italy Self-driving Cars Market
- UK Self-driving Cars Market
- Spain Self-driving Cars Market
- Canada Self-driving Cars Market
- US Self-driving Cars Market




Growth opportunities and latent adjacency in Self-Driving Cars Market