Pilot Operated Gas Regulators Market by Pressure (Low, Medium, High), Installation Type (New Installation, Retrofit), Installation Location (Offshore, Onshore), End-use Industry, and Region - Global Forecast to 2031

icon1
USD 0.52 BN
MARKET SIZE, 2031
icon2
CAGR 5.6%
(2026-2031)
icon3
310
REPORT PAGES
icon4
150
MARKET TABLES

OVERVIEW

pilot-operated-gas-regulators-market Overview

Source: Secondary Research, Interviews with Experts, MarketsandMarkets Analysis

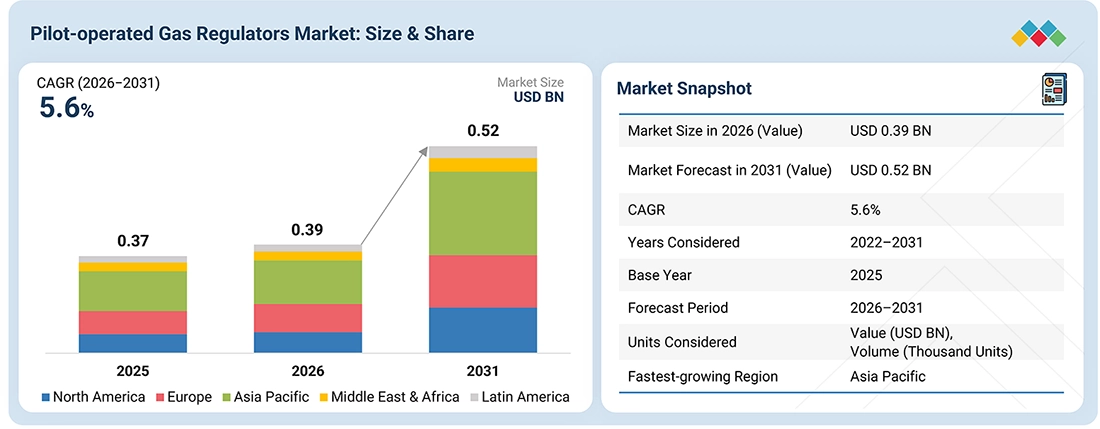
The pilot-operated gas regulators market is projected to grow from USD 0.39 billion in 2026 to USD 0.52 billion by 2031, at a CAGR of 5.6%, supported by the continued expansion and modernization of natural gas transmission and distribution infrastructure, rising investments in LNG and gas-processing facilities, and increasing demand for reliable pressure control solutions across industrial and energy applications. Growth is primarily driven by new gas infrastructure projects, replacement of aging regulators, and retrofit activities aimed at improving system reliability, safety, and pressure stability. Furthermore, increasing gas utilization across power generation, manufacturing industries, gas utilities, and oil & gas facilities is sustaining demand for POGRs. Advancements in pressure control technologies, improved pilot systems, enhanced monitoring capabilities, and more reliable high-pressure regulation are further expanding the application scope of POGRs, particularly across gas transmission networks, city-gate stations, LNG terminals, gas processing facilities, and offshore oil & gas installations.

MARKET SCOPE

REPORT METRIC DETAILS
Market Size in 2025 (Value) USD 0.37 Billion
Market Size in 2026 (Value) USD 0.39 Billion
Market Forecast in 2031 (Value) USD 0.52 Billion
Growth Rate CAGR of 5.6% from 2026-2031
Years Considered 2022–2031
Base Year 2025
Forecast Period 2026–2031
Units Considered Value (USD Billion), Volume (Thousand Units)
Report Coverage Market size and forecast, company profiling, competitive landscape, market dynamics (drivers, restraints, opportunities, and challenges), technology trends, ecosystem analysis, commercial use cases, and regional analysis
Segments Covered
  • By Pressure:
    • Low
    • Medium
    • High
  • By Installation Type:
    • New Installation
    • Retrofit
  • By Installation Location:
    • Offshore
    • Onshore
  • By End-use Industry:
    • Oil & Gas
    • Gas Utilities
    • Power Generation
    • Industrial Manufacturing
    • Other End-use Industries
Regions Covered North America, South America, Europe , Asia Pacific, and Middle East & Africa


KEY TAKEAWAYS

  • BY REGION
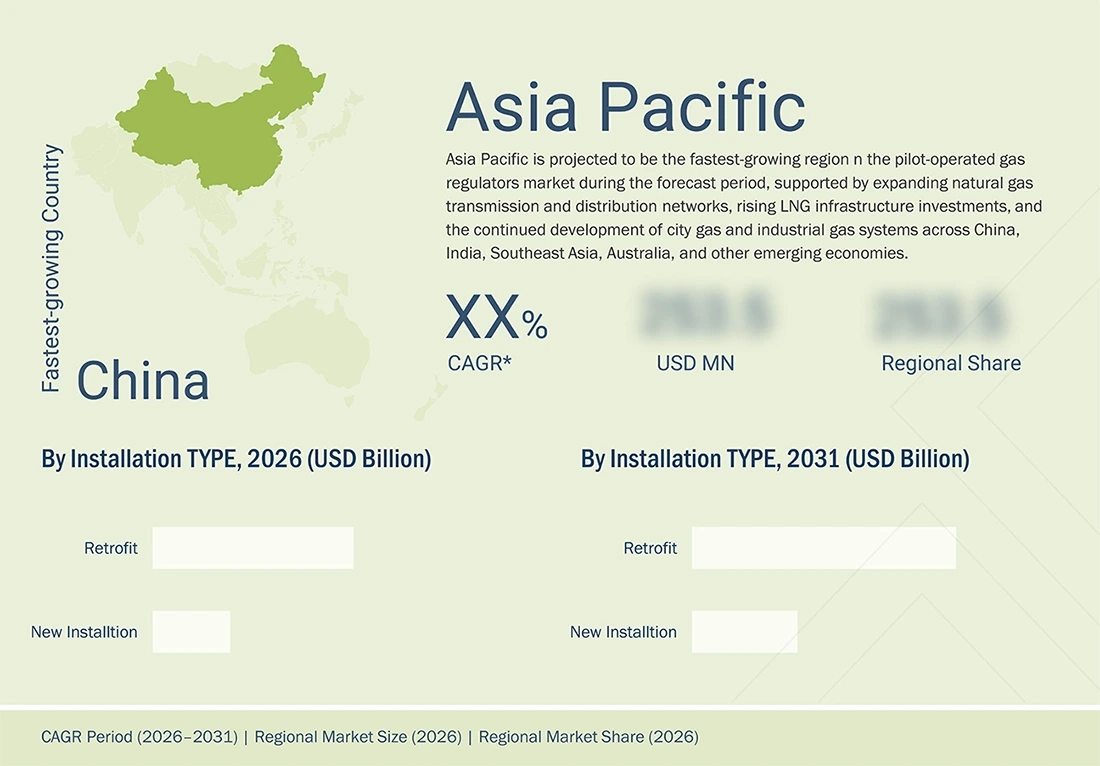
    Asia Pacific is expected to register the highest CAGR of 6.6% in the pilot-operated gas regulators market during the forecast period.
  • BY PRESSURE
    High-pressure pilot-operated gas regulators are likely to hold the largest market share, by pressure, throughout the forecast period.
  • BY INSTALLATION TYPE
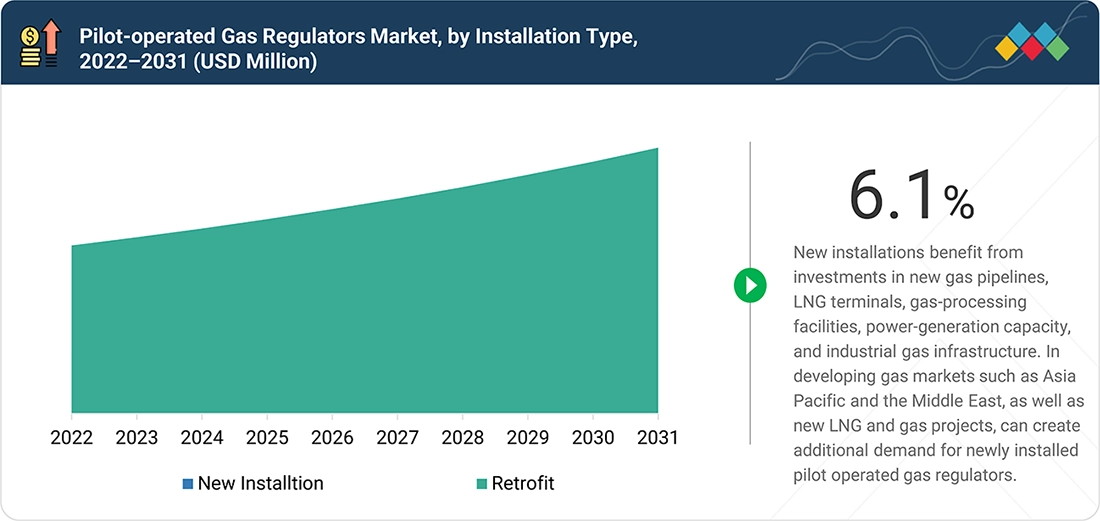
    By installation type, the new installation segment is expected to register a higher CAGR of 6.1% during the forecast period.
  • BY INSTALLATION LOCATION
    By installation location, the onshore segment is expected to register a higher CAGR of 5.7% during the forecast period.
  • BY END-USE INDUSTRY
    By end-use industry, the gas utilities segment is likely to hold the largest market share during the forecast period.
  • COMPETITIVE LANDSCAPE - KEY PLAYERS
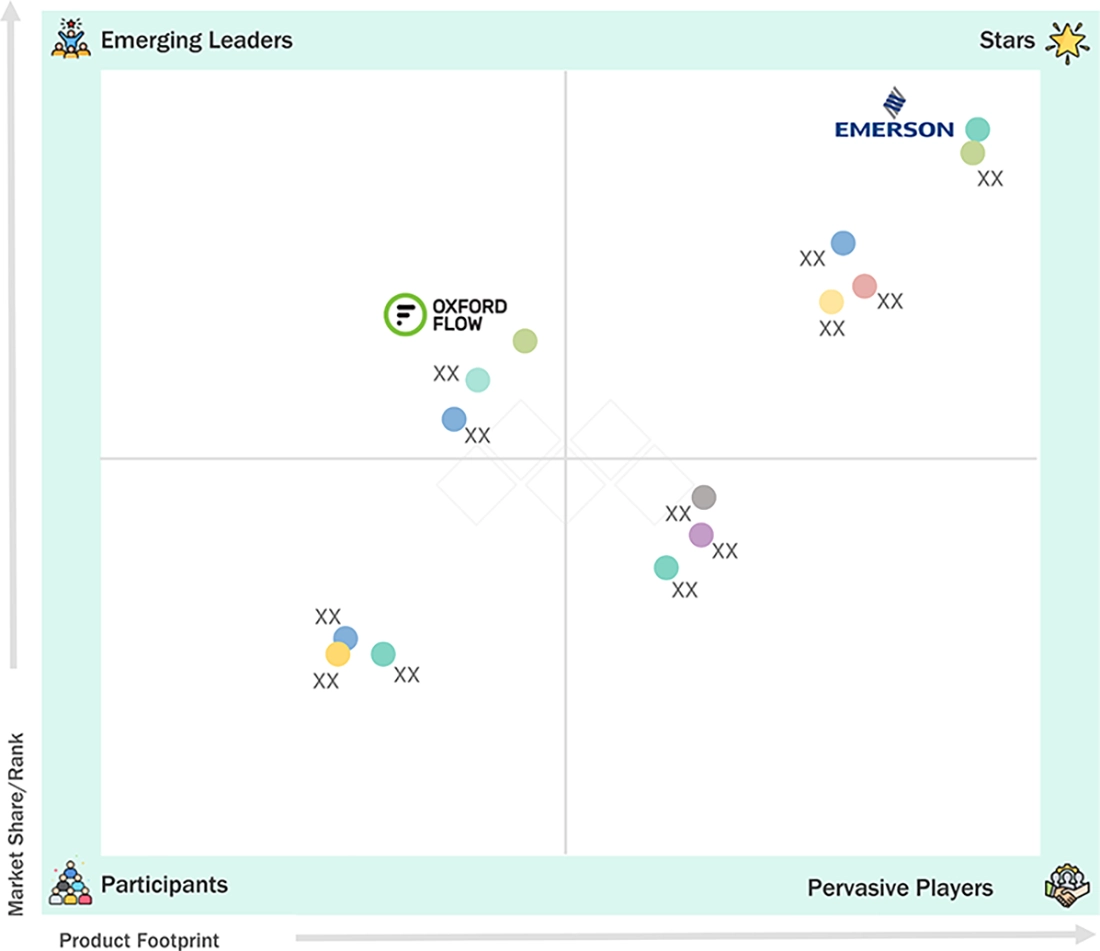
    Emerson (US) and Honeywell International Inc. (US) have been identified as leading players in the global pilot-operated gas regulator market. These companies are strengthening their market positions through advanced pressure-regulation technologies, broad product portfolios, and solutions designed to deliver reliable gas flow control, pressure stability, and operational safety. Their market presence is further supported by continuous product development, expansion of gas-regulation solutions for gas utilities, oil & gas, LNG, power generation, and industrial applications, and established manufacturing, sales, and distribution networks across major regional markets.
  • COMPETITIVE LANDSCAPE - STARUP/SME PLAYERS
    Oxford Flow (UK), Flow Metering Technology (India), and Pinxin Intelligent Control (China) have distinguished themselves among startups and SMEs by securing strong footholds in specialized niche areas, underscoring their potential as emerging market leaders in the pilot-operated gas regulators market.

The pilot-operated gas regulators market is projected to grow steadily during 2026–2031, driven by the continued expansion and modernization of natural gas transmission and distribution infrastructure, rising investments in LNG and gas-processing facilities, and increasing demand for reliable gas pressure control solutions across energy and industrial applications. The market is also supported by the replacement and retrofit of aging gas-regulation equipment, as operators seek to improve system reliability, safety, pressure stability, and operational efficiency. Furthermore, growing natural gas utilization in power generation, manufacturing industries, gas utilities, and oil & gas facilities is creating additional demand for pilot-operated gas regulators. Advancements in pilot-control mechanisms, high-pressure regulation, remote monitoring, and smart pressure management technologies are further improving regulator performance and expanding their application across gas transmission networks, city-gate stations, LNG terminals, gas processing facilities, and offshore oil & gas infrastructure.

TRENDS & DISRUPTIONS IMPACTING CUSTOMERS' CUSTOMERS

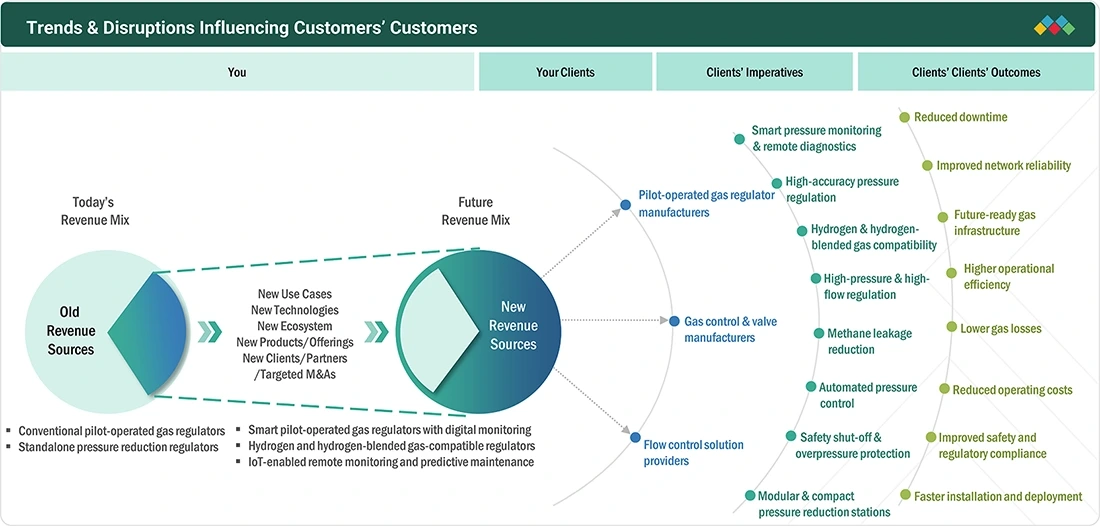
The impact on customers’ businesses is driven by the growing demand for safe, reliable, and precise gas pressure control, expanding natural gas transmission and distribution networks, increasing adoption of city gas distribution (CGD) systems, and the development of gas-intensive industrial and power generation facilities. Continuous advancements in smart pressure regulation, digital monitoring, remote diagnostics, high-performance pilot systems, and low-emission gas infrastructure are improving operational reliability while reducing pressure fluctuations, gas losses, maintenance requirements, and unplanned downtime. Supportive government policies promoting natural gas adoption, investments in pipeline and gas distribution infrastructure, stricter safety standards, and the transition toward cleaner fuels are further accelerating the deployment of advanced pilot-operated gas regulators. The revenue mix is expected to shift over the next 4–5 years from conventional pilot-operated gas regulators and standalone pressure reduction regulators toward smart, digitally enabled, and hydrogen-compatible solutions. This shift will be driven by the evolving requirements of pilot-operated gas regulator manufacturers, gas control and valve manufacturers, and flow control solution providers, which are increasingly prioritizing smart pressure monitoring, remote diagnostics, high-accuracy and automated pressure regulation, methane leakage reduction, hydrogen and hydrogen-blended gas compatibility, safety shut-off and overpressure protection, and modular pressure reduction systems. These capabilities are expected to generate customer outcomes including reduced downtime and gas losses, improved network reliability, operational efficiency, safety and regulatory compliance, future-ready gas infrastructure, and faster installation and deployment. End users such as natural gas transmission and distribution companies, city gas distribution operators, oil & gas companies, power generation facilities, industrial manufacturers, commercial complexes, LNG and gas processing facilities, and gas storage operators represent the primary customers for pilot-operated gas regulator manufacturers, driving demand for reliable, high-capacity, energy-efficient, and safety-compliant pressure regulation solutions.

pilot-operated-gas-regulators-market Disruptions

Source: Secondary Research, Interviews with Experts, MarketsandMarkets Analysis

MARKET DYNAMICS

Drivers
Impact
Level
  • Rising global demand for natural gas as a reliable, low-emission fuel source
  • Increasing investments in natural gas infrastructure, city gas distribution networks, and LNG terminals
RESTRAINTS
Impact
Level
  • Economic volatility affecting capital expenditure in utilities and industrial sectors
OPPORTUNITIES
Impact
Level
  • Growing focus on hydrogen-ready regulator technologies and decarbonization projects
  • Rapid expansion of city gas distribution and industrial gas networks in emerging markets
CHALLENGES
Impact
Level
  • Regulatory shifts and potential trade barriers impacting imports

Source: Secondary Research, Interviews with Experts, MarketsandMarkets Analysis

Rising global demand for natural gas as a reliable, low-emission fuel source

Natural gas power generation remains an important component of the global energy mix due to its flexibility, lower emissions intensity than coal and oil, and ability to provide reliable energy alongside variable renewable generation. Its continued use across power generation, industrial processes, heating, and commercial applications is supporting investments across the gas value chain, including production, transmission, storage, LNG infrastructure, and city gas distribution, thereby sustaining demand for pilot-operated gas regulators. According to the IEA, global natural gas demand increased by 2.7% in 2024, reaching a record level, with more than three-quarters of the growth coming from emerging market and developing economies. Gas demand for power generation also increased by approximately 2.8%, reinforcing the need for reliable gas pressure regulation in gas-fired power plants.

Economic volatility affecting capital expenditure in utilities and industrial sectors

Economic volatility can directly influence capital expenditure across utilities, oil & gas, power generation, and industrial sectors, affecting demand for pilot-operated gas regulators. Changes in economic growth, interest rates, inflation, commodity prices, exchange rates, and energy demand can lead companies to postpone infrastructure projects, reduce capital budgets, or prioritize maintenance over new installations. Higher financing costs may further delay large-scale investments in gas transmission, distribution, LNG, and pressure-reduction infrastructure. Similarly, industrial companies may defer capacity expansions and modernization projects during periods of uncertainty, reducing demand for high-capacity regulators used in new gas systems.

Growing focus on hydrogen-ready regulator technologies and decarbonization projects

The growing focus on hydrogen as a low-carbon energy carrier is creating opportunities for the pilot-operated gas regulator market. Investments in hydrogen production, transportation, storage, blending, and end-use applications are increasing demand for regulators capable of safely handling hydrogen and hydrogen-natural gas blends across pipelines, distribution networks, industrial facilities, power plants, and refueling infrastructure. Because hydrogen has different properties from natural gas, including lower molecular weight and higher diffusivity, regulators may require compatible materials, improved sealing, optimized pilot assemblies, and application-specific validation to ensure stable pressure control and minimize leakage.

Regulatory shifts and potential trade barriers impacting imports

Regulatory changes and evolving trade policies are increasingly influencing the global pilot-operated gas regulator market. As safety-critical components, gas regulators are subject to stringent requirements for materials, pressure ratings, performance, testing, documentation, and certification. Changes in national standards, import regulations, and customs procedures can increase compliance costs and extend product-approval timelines. Differences in regional requirements may also require additional testing, certification, labeling, and documentation, creating barriers for manufacturers entering international markets. For example, evolving ISO and CSA requirements covering performance, pressure ratings, temperature limits, overpressure protection, and testing can increase the time and cost associated with introducing regulator products across regions.

PILOT-OPERATED GAS REGULATORS MARKET: COMMERCIAL USE CASES ACROSS INDUSTRIES

COMPANY USE CASE DESCRIPTION BENEFITS
company logo
Emerson supplied Tartarini FL pilot-operated regulators for high-pressure transmission, city-gate, large-capacity distribution, and power-plant gas-feed applications. The FL Series is designed for accurate pressure control, smooth operation, tight shutoff, and long service life. Emerson also offers an integrated noise-attenuation option and designs that reduce bleed gas emissions. Enables stable downstream gas pressure across high-flow applications and improves reliability at city-gate and transmission stations. The low-emission design can reduce gas venting, while noise attenuation improves operating conditions. The solution is also suitable for power-plant fuel-gas applications where maintaining consistent pressure is critical.
company logo
Pietro Fiorentini supplies ASX 176/FO pilot-operated regulators for high-pressure transmission systems and medium-pressure natural gas distribution networks. The regulator supports inlet pressures up to 100 bar and downstream pressures up to 74 bar, depending on the pilot configuration. Provides accurate and reliable pressure reduction across transmission and distribution networks while accommodating high-pressure operating conditions. Its broad pressure and size range enables deployment across different gas-network configurations. Pietro Fiorentini also offers pilot-operated solutions such as Dixi for medium- and low-pressure distribution networks.

Logos and trademarks shown above are the property of their respective owners. Their use here is for informational and illustrative purposes only.

MARKET ECOSYSTEM

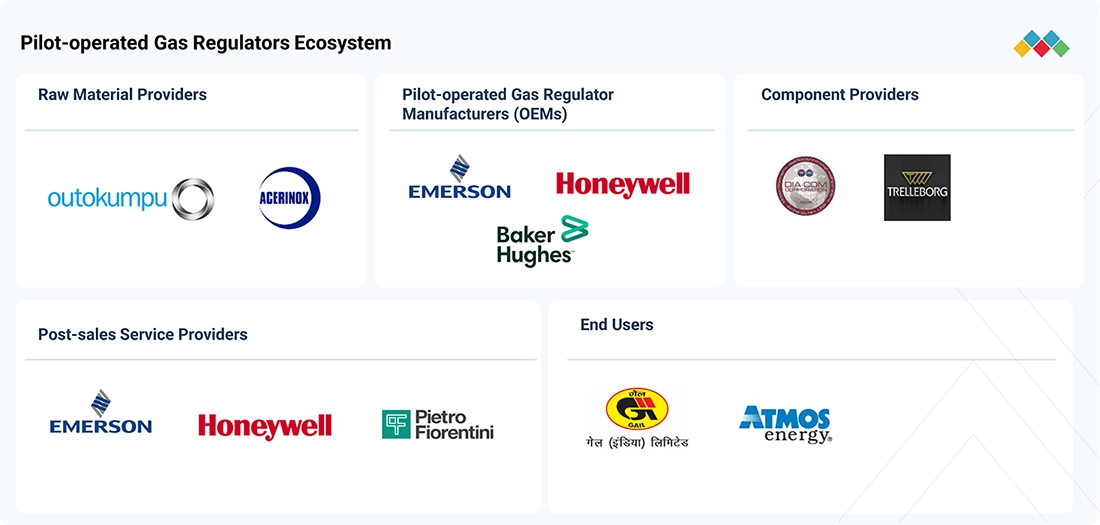
The pilot-operated gas regulators ecosystem spans five interconnected tiers. Raw material providers such as Outokumpu and Acerinox supply the stainless steel and specialty alloys required for pressure-bearing bodies and trim. These feed into pilot-operated gas regulator OEMs—including Emerson, Honeywell, and Baker Hughes—which design, assemble, and certify complete regulator systems. Component providers such as Trelleborg contribute sealing systems, diaphragms, and elastomers that determine reliability under variable pressure conditions. Downstream, post-sales service providers including Emerson, Honeywell, and Pietro Fiorentini deliver installation, calibration, maintenance, and retrofit services across the asset lifecycle. End users — gas transmission and distribution utilities such as GAIL (India) and Atmos Energy—operate these regulators across city-gate stations, industrial feeds, and residential distribution networks. Value is concentrated at the OEM and post-sales tiers, where certification requirements, safety standards, and lon service relationships create durable competitive advantage.

pilot-operated-gas-regulators-market Ecosystem

Logos and trademarks shown above are the property of their respective owners. Their use here is for informational and illustrative purposes only.

MARKET SEGMENTS

pilot-operated-gas-regulators-market Segments

Source: Secondary Research, Interviews with Experts, MarketsandMarkets Analysis

By Pressure

High-pressure pilot-operated gas regulators account for the largest market share, primarily due to their extensive deployment in natural gas transmission pipelines, city-gate and transfer stations, power plants, and large industrial facilities. These applications involve high inlet pressures and substantial gas flow rates, requiring regulators capable of providing high flow capacity, accurate downstream pressure control, and reliable operation under varying demand conditions. The continued expansion and upgrading of high-pressure gas transmission and distribution infrastructure, therefore, supports sustained demand for pilot-operated regulators in this pressure range.

By Installation Type

In the pilot-operated gas regulator (POGR) market, the new installation segment is expected to register the highest CAGR during the forecast period. The growth of this segment is driven by the development of new gas transmission and distribution networks, LNG facilities, gas processing plants, power generation facilities, and industrial infrastructure. Retrofit installations involve replacing or upgrading existing regulators to improve pressure control, operational reliability, safety, and system efficiency. The retrofit segment is supported by the large installed base of aging gas infrastructure, regulatory requirements, and the need for modernization, while new installations remain closely linked to ongoing investments in gas infrastructure and energy projects.

By Installation Location

Onshore installations are projected to register a higher CAGR, supported by the expansion and modernization of natural gas transmission and distribution networks, increasing gas consumption across industrial and power-generation applications, and the development of infrastructure connecting LNG import terminals and production facilities with inland demand centers. The broader application base and recurring replacement requirements of onshore gas infrastructure are expected to generate sustained demand for pilot-operated gas regulators.

By End-use Industry

Gas utilities account for the largest share, primarily due to their extensive transmission and distribution networks, which require pressure regulation across city-gate stations, district regulating stations, pressure-reducing facilities, and customer connections. The progressive reduction of gas pressure from high-pressure transmission pipelines to levels suitable for residential, commercial, industrial, and CNG applications creates multiple points of demand for pilot-operated regulators. Continued expansion and modernization of gas distribution infrastructure, coupled with replacement requirements across existing networks, further supports demand from gas utilities.

REGION

Asia Pacific is expected to account for the largest market share during the forecast period

Asia Pacific is projected to remain the fastest-growing regional market for pilot-operated gas regulators during the forecast period, supported by continued expansion of natural gas transmission and distribution networks, LNG infrastructure, city gas networks, and gas-fired power generation across China, India, Southeast Asia, Japan, South Korea, and Australia. Continued development of LNG import and regasification facilities, expansion of city gas distribution, increasing gas use in industrial and power-generation applications, and modernization of existing gas networks are expected to sustain demand for pilot-operated gas regulators across Asia Pacific.

pilot-operated-gas-regulators-market Region

PILOT-OPERATED GAS REGULATORS MARKET: COMPANY EVALUATION MATRIX

The pilot-operated gas regulators market is competitive. Emerson emerged as the star player, supported by broad technology coverage and significant international presence. Oxfordflow is an emerging leader benefiting from an established product portfolio and regional presence.

pilot-operated-gas-regulators-market Evaluation Metrics

Source: Secondary Research, Interviews with Experts, MarketsandMarkets Analysis

KEY MARKET PLAYERS

WHAT IS IN IT FOR YOU: PILOT-OPERATED GAS REGULATORS MARKET REPORT CONTENT GUIDE

pilot-operated-gas-regulators-market Content Guide

DELIVERED CUSTOMIZATIONS

We have successfully delivered the following deep-dive customizations:

CLIENT REQUEST CUSTOMIZATION DELIVERED VALUE ADDS
Gas Regulator/Pressure Control Equipment Manufacturer
  • Mapping pilot-operated gas regulator deployments across gas transmission, distribution networks, city gate & district regulating stations, industrial process, power generation, and commercial & residential applications
  • Benchmarking self-operated vs. pilot-operated and single-stage vs. two-stage pressure control architectures
  • Assessment of regulator specifications including inlet/outlet pressure ranges, capacity (Cv), accuracy class, lock-up performance, and materials of construction
  • Identify high-growth application segments
  • Strengthen product positioning
  • Support long-term product development and go-to-market planning
Component & Materials Supplier
  • Competitive mapping of pilots, diaphragms, elastomers, springs, valve bodies, trim, orifices, and internal relief assemblies
  • Benchmarking component performance parameters such as pressure rating, temperature range, hydrogen and sour-gas compatibility, cycle life, and leakage class
  • Tracking product innovations and material technology trends
  • Identify white-space opportunities
  • Prioritize OEM and EPC engagements
  • Support technology and product roadmap planning
Gas Utility /Transmission & Distribution Operator
  • Assessment of regulator selection criteria, by application, including city gate stations, district regulating stations, farm taps, industrial meter sets, and overpressure protection & relief
  • Benchmarking integration with telemetry, smart metering, and remote pressure-monitoring systems
  • Mapping network modernization and hydrogen-blending readiness strategies
  • Strengthen network reliability and safety compliance
  • Identify high-value pressure control use cases
  • Enable readiness for hydrogen blending and grid modernization
Oil & Gas, Petrochemical & Industrial Enterprise
  • Mapping procurement strategies and supplier landscape, by region
  • Evaluation of vendor capabilities, accuracy and droop performance, turndown, capacity, certification coverage (ANSI, EN, API), aftermarket service, and lead times across leading suppliers such as Emerson (Fisher), Honeywell, Pietro Fiorentini, Cavagna Group, Itron, and Flowserve
  • Support informed procurement decisions
  • Enhance operational efficiency and process safety
  • Improve equipment reliability and predictive maintenance
Private Equity / Investment Firm
  • Financial and competitive benchmarking of leading pilot-operated gas regulator manufacturers across North America, Europe, Asia Pacific, and RoW
  • M&A landscape mapping across regulator, valve, metering, pressure-control station, and aftermarket service providers
  • Growth trend analysis, by product type, pressure range, material, end-use industry, and region
  • Prioritize investment targets
  • Validate market sizing and growth opportunities
  • Identify attractive product segments and mitigate sector-entry risk

RECENT DEVELOPMENTS

  • July 2026 : Baker Hughes announced a significant order booked in the second quarter from Venture Global LNG to provide a comprehensive liquefaction solution for the CP2 LNG expansion project in Louisiana.
  • September 2025 : Honeywell collaborated with Energy Assets on a UK gas-meter upgrade, supplying smart communication modules and batteries for 67,000 gas meters.
  • January 2024 : Emerson introduced the Fisher 63EGLP-16 Pilot Operated Relief Valve for installation on pressurized bullet tanks used to store liquid propane and anhydrous ammonia. This type of pressure-relief valve (PRV) is typically installed on tanks fabricated by original equipment manufacturers (OEMs), which provide them to end users, engineering firms, or contractor customers.
  • January 2023 : Pietro Fiorentini continued its long-standing partnership with Chilean gas distributor Gasvalpo through a hydrogen-blending project using special Reflux 819 pilot-operated regulators.


Table of Contents

checkmarkExclusive indicates content/data unique to MarketsandMarkets and not available with any competitors.

TITLE
PAGE NO
1
INTRODUCTION


28
2
EXECUTIVE SUMMARY


34
3
PREMIUM INSIGHTS


39
4
MARKET OVERVIEW
Seize growth by investing in hydrogen-ready technologies and expanding gas networks in emerging markets.


44
 
4.1
INTRODUCTION


4.2
MARKET DYNAMICS


4.2.1
DRIVERS


GROWING NATURAL GAS CONSUMPTION ACROSS POWER


4.2.1.2
INCREASING INVESTMENTS IN NATURAL GAS INFRASTRUCTURE, CITY GAS DISTRIBUTION NETWORKS, AND LNG TERMINALS


4.2.1.3
ELEVATING ADOPTION OF HYBRID AND DISTRIBUTED POWER SYSTEMS


4.2.2
RESTRAINTS


4.2.2.1
ECONOMIC VOLATILITY AND HIGHER FINANCING COSTS


4.2.3
OPPORTUNITIES


4.2.3.1
GROWING ADOPTION OF HYDROGEN-READY REGULATOR TECHNOLOGIES


4.2.3.2
EXPANDING CGD AND INDUSTRIAL GAS NETWORKS IN EMERGING MARKETS


4.2.4
CHALLENGES


4.2.4.1
REGULATORY SHIFTS AND TRADE BARRIERS


4.3
UNMET NEEDS AND WHITE SPACES


4.4
INTERCONNECTED MARKETS AND CROSS-SECTOR OPPORTUNITIES


4.5
STRATEGIC MOVES BY TIER 1/2/3 PLAYERS


5
INDUSTRY TRENDS
Navigate competitive forces and macroeconomic shifts to leverage emerging opportunities in the gas industry.


53
 
5.1
PORTER’S FIVE FORCES ANALYSIS


5.1.1
THREAT OF NEW ENTRANTS


5.1.2
THREAT OF SUBSTITUTES


5.1.3
BARGAINING POWER OF SUPPLIERS


5.1.4
BARGAINING POWER OF BUYERS


5.1.5
INTENSITY OF COMPETITIVE RIVALRY


5.2
MACROECONOMIC OUTLOOK


5.2.1
INTRODUCTION


5.2.2
GDP TRENDS AND FORECAST


5.2.3
TRENDS IN GLOBAL OIL & GAS INDUSTRY


5.2.4
TRENDS IN GLOBAL GAS UTILITIES


5.3
VALUE CHAIN ANALYSIS


5.4
ECOSYSTEM ANALYSIS


5.5
PRICING ANALYSIS


AVERAGE SELLING PRICE TREND OF PILOT-OPERATED GAS REGULATORS,


AVERAGE SELLING PRICE TREND OF PILOT-OPERATED GAS REGULATORS,


5.6
TRADE ANALYSIS


5.6.1
IMPORT SCENARIO (HS CODE 848110)


5.6.2
EXPORT SCENARIO (HS CODE 848110)


5.7
KEY CONFERENCES AND EVENTS, 2026–2027


5.8
TRENDS/DISRUPTIONS IMPACTING CUSTOMER BUSINESS


5.9
INVESTMENT AND FUNDING SCENARIO


5.10
CASE STUDY ANALYSIS


5.10.1
NATURAL GAS UTILITY DEPLOYS EMERSON PILOT-OPERATED REGULATORS TO OPTIMIZE LOW-PRESSURE DISTRIBUTION NETWORKS


5.10.2
NATURAL GAS DISTRIBUTOR DEPLOYS MOONEY PILOT-OPERATED REGULATORS TO UPGRADE OVER-PRESSURE PROTECTION


5.11
IMPACT OF US TARIFFS – PILOT-OPERATED GAS REGULATORS MARKET


5.11.1
INTRODUCTION


5.11.2
KEY TARIFF RATES


5.11.3
PRICE IMPACT ANALYSIS


5.11.4
IMPACT ON COUNTRIES/REGIONS


5.11.4.1
US


5.11.4.2
EUROPE


5.11.4.3
ASIA PACIFIC


5.11.5
IMPACT ON END USERS


6
TECHNOLOGICAL ADVANCEMENTS, AI-DRIVEN IMPACT, PATENTS, INNOVATIONS, AND FUTURE APPLICATIONS
AI-driven innovations revolutionize gas regulators with predictive maintenance and smart city integration.


76
 
6.1
KEY TECHNOLOGIES


6.1.1
ELECTRO-PNEUMATIC AND DIGITAL PLOTS


6.1.2
SMART PRESSURE REGULATION & DIGITAL CONTROL


6.2
COMPLEMENTARY TECHNOLOGIES


6.2.1
PREDICTIVE MAINTENANCE & CONDITION MONITORING


6.2.2
SAFETY & PROTECTION TECHNOLOGIES


6.3
TECHNOLOGY/PRODUCT ROADMAP


6.3.1
SHORT-TERM (2025–2027) | FOUNDATION & EARLY COMMERCIALIZATION


6.3.2
MID-TERM (2027–2030) | EXPANSION & STANDARDIZATION


6.3.3
LONG-TERM (2030+) | MASS COMMERCIALIZATION & DISRUPTION


6.4
PATENT ANALYSIS


6.5
FUTURE APPLICATIONS


6.6
IMPACT OF AI/GEN AI ON PILOT-OPERATED GAS REGULATORS MARKET


6.6.1
TOP USE CASES AND MARKET POTENTIAL


6.6.2
BEST PRACTICES FOLLOWED BY OEMS IN PILOT OPERTAED GAS REGULATORS MARKET


6.6.3
CASE STUDIES RELATED TO AI/GEN AI IMPLEMENTATION IN PILOT OPERTAED GAS REGULATORS MARKET


6.6.4
INTERCONNECTED ECOSYSTEM AND IMPACT ON MARKET PLAYERS


6.6.5
CLIENTS’ READINESS TO ADOPT AI/GEN AI-INTEGRATED PILOT-OPERATED GAS REGULATORS


6.7
SUCCESS STORIES AND REAL-WORLD APPLICATIONS


7
REGULATORY LANDSCAPE AND SUSTAINABILITY INITIATIVES
Navigate complex regulations to align sustainability efforts with global compliance and eco-standards.


89
 
7.1
REGIONAL REGULATIONS AND COMPLIANCE


7.1.1
REGULATORY BODIES, GOVERNMENT AGENCIES, AND OTHER ORGANIZATIONS


7.1.2
INDUSTRY STANDARDS


7.2
SUSTAINABILITY INITIATIVES


GAS EMISSION AND EFFICIENT GAS INFRASTRUCTURE


7.3
IMPACT OF REGULATORY POLICIES ON SUSTAINABILITY INITIATIVES


7.4
CERTIFICATIONS, LABELING, AND ECO-STANDARDS


8
CUSTOMER LANDSCAPE AND BUYER BEHAVIOR
Unlock revenue potential by understanding key stakeholders' influence and unmet needs across end users.


96
 
8.1
DECISION-MAKING PROCESS


8.2
KEY STAKEHOLDERS INVOLVED IN BUYING PROCESS AND THEIR EVALUATION CRITERIA


8.2.1
KEY STAKEHOLDERS IN BUYING PROCESS


8.2.2
BUYING CRITERIA


8.3
ADOPTION BARRIERS AND INTERNAL CHALLENGES


8.4
UNMET NEEDS FROM VARIOUS END USERS


8.5
MARKET PROFITABILITY


8.5.1
REVENUE POTENTIAL


8.5.2
COST DYNAMICS


8.5.3
MARGIN OPPORTUNITIES BY END USER


9
PILOT-OPERATED GAS REGULATORS MARKET, BY PRESSURE
Market Size & Growth Rate Forecast Analysis to 2031 in USD Million | 8 Data Tables


103
 
9.1
INTRODUCTION


9.2
LOW


EXPANSION OF GAS DISTRIBUTION NETWORKS TO SUPPORT


9.3
MEDIUM


GROWING INDUSTRIAL CONSUMPTION OF NATURAL GAS


9.4
HIGH


9.4.1
DEVELOPMENT OF LNG REGASIFICATION TERMINALS AND HIGH-PRESSURE GAS PIPELINES TO CONTRIBUTE TO SEGMENTAL GROWTH


10
PILOT-OPERATED GAS REGULATORS MARKET, BY INSTALLATION TYPE
Market Size & Growth Rate Forecast Analysis to 2031 in USD Million | 6 Data Tables


109
 
10.1
INTRODUCTION


10.2
NEW INSTALLATION


10.2.1
EMERGING HYDROGEN-READY PIPELINE NETWORKS TO CREATE LUCRATIVE GROWTH OPPORTUNITIES


10.3
RETROFIT


10.3.1
PRESSING NEED TO MODERNIZE AGING GAS PIPELINES AND PRESSURE-REGULATION STATIONS TO ACCELERATE DEMAND


11
PILOT-OPERATED GAS REGULATORS MARKET, BY INSTALLATION LOCATION
Market Size & Growth Rate Forecast Analysis to 2031 in USD Million | 6 Data Tables


114
 
11.1
INTRODUCTION


11.2
ONSHORE


11.2.1
EXPANDING NATURAL GAS INFRASTRUCTURE AND CITY GAS DISTRIBUTION NETWORKS TO FUEL SEGMENTAL GROWTH


11.3
OFFSHORE


11.3.1
RISING ADOPTION OF REMOTE MONITORING AND PREDICTIVE MAINTENANCE TECHNOLOGIES TO DRIVE MARKET


12
PILOT-OPERATED GAS REGULATORS MARKET, BY END USER
Market Size & Growth Rate Forecast Analysis to 2031 in USD Million | 18 Data Tables


120
 
12.1
INTRODUCTION


12.2
OIL & GAS COMPANIES


12.2.1
SUBSEA


12.2.1.1
DEVELOPMENT OF DEEPWATER AND ULTRA-DEEPWATER RESERVES TO SPUR DEMAND


12.2.2
TOPSIDES


12.2.2.1
INCREASING MODERNIZATION OF AGING OFFSHORE PLATFORMS TO STRENGTHEN DEMAND


12.2.3
GAS PROCESSING


12.2.3.1
RISING NATURAL GAS PRODUCTION AND PROCESSING CAPACITY EXPANSION TO STRENGTHEN GAS PROCESSING DEMAND


12.2.4
LNG TERMINALS


12.2.4.1
INCREASING LNG TRADE AND EXPANSION OF REGASIFICATION CAPACITY TO BOOST PILOT-OPERATED GAS REGULATOR ADOPTION


12.2.5
REFINERIES & PETROCHEMICAL PLANTS


12.2.5.1
REFINERY EXPANSION AND PETROCHEMICAL CAPACITY ADDITIONS TO ENHANCE PILOT-OPERATED GAS REGULATOR REQUIREMENT


12.3
GAS UTILITIES


12.3.1
TRANSMISSION


12.3.1.1
EXPANSION OF LONG-DISTANCE GAS PIPELINES AND INCREASING NATURAL GAS PRODUCTION TO FACILITATE MARKET GROWTH


12.3.2
DISTRIBUTION


12.3.2.1
EXPANDING CITY GAS DISTRIBUTION NETWORKS AND RISING DOWNSTREAM GAS CONSUMPTION TO CONTRIBUTE TO PROMOTING DEPLOYMENT


12.3.3
CITY GATE STATIONS


12.3.3.1
INCREASING NATURAL GAS CONNECTIONS, URBANIZATION, AND GROWING USE OF PIPED NATURAL GAS ACROSS EMERGING MARKETS TO SPIKE DEMAND


12.4
POWER GENERATION PLANTS


12.4.1
RISING ELECTRICITY CONSUMPTION AND CONTINUED INVESTMENTS IN GAS INFRASTRUCTURE TO SUPPORT MARKET GROWTH


12.5
INDUSTRIAL MANUFACTURING PLANTS


12.5.1
CHEMICAL


12.5.1.1
INCREASING INVESTMENTS IN SPECIALTY CHEMICALS, FERTILIZERS, AND PETROCHEMICALS TO AUGMENT MARKET GROWTH


12.5.2
FOOD & BEVERAGE


12.5.2.1
RISING FOCUS ON MODIFYING OLDER GAS INFRASTRUCTURE TO IMPROVE ENERGY EFFICIENCY AND OPERATIONAL SAFETY TO STIMULATE DEMAND


12.5.3
METAL & MINING


12.5.3.1
NEED TO REGULATE NATURAL GAS AND OTHER COMBUSTIBLE GASES SUPPLIED TO PROCESS EQUIPMENT TO PROPEL MARKET


12.5.4
PULP & PAPER


12.5.4.1
GROWING EFFORTS TO REDUCE EMISSIONS FROM ENERGY-INTENSIVE PAPER PRODUCTION TO ACCELERATE DEMAND


12.5.5
OTHER INDUSTRIAL MANUFACTURING APPLICATIONS


12.6
OTHER END USERS


13
PILOT-OPERATED GAS REGULATORS MARKET, BY REGION
Comprehensive coverage of 8 Regions with country-level deep-dive of 20 Countries | 136 Data Tables.


136
 
13.1
INTRODUCTION


13.2
NORTH AMERICA


13.2.1
US


13.2.1.1
EXPANDING PIPELINE INFRASTRUCTURE AND NETWORK MODERNIZATION EFFORTS TO BOOST PILOT-OPERATED GAS REGULATOR ADOPTION


13.2.2
CANADA


13.2.2.1
INCREASING INVESTMENTS IN NATURAL GAS PRODUCTION AND LNG INFRASTRUCTURE DEVELOPMENT TO SUPPORT MARKET GROWTH


13.2.3
MEXICO


13.2.3.1
GOVERNMENT-LED INVESTMENTS IN PIPELINE NETWORK EXPANSION TO BOOST DEMAND FOR PILOT-OPERATED GAS REGULATORS


13.3
EUROPE


13.3.1
GERMANY


13.3.1.1
GROWING LNG IMPORT CAPACITY TO ACCELERATE DEMAND


13.3.2
UK


13.3.2.1
CONTINUED SPENDING ON GAS NETWORK SAFETY AND LNG SUPPLY SECURITY TO CONTRIBUTE TO MARKET GROWTH


13.3.3
FRANCE


13.3.3.1
NEED FOR RELIABLE GAS SUPPLY FOR PROCESS HEATING AND MANUFACTURING OPERATIONS TO SPIKE ADOPTION


13.3.4
ITALY


13.3.4.1
SIGNIFICANT INVESTMENTS IN GAS SUPPLY DIVERSIFICATION TO FOSTER MARKET GROWTH


13.3.5
SPAIN


13.3.5.1
EFFORTS TOWARD EXPANSION AND MODERNIZATION OF CITY GAS DISTRIBUTION NETWORKS TO FUEL MARKET EXPANSION


13.3.6
REST OF EUROPE


13.4
ASIA PACIFIC


13.4.1
CHINA


13.4.1.1
SHIFT TOWARD NATURAL GAS FOR POWER GENERATION, INDUSTRIAL HEATING, AND RESIDENTIAL CONSUMPTION TO FACILITATE MARKET GROWTH


13.4.2
INDIA


13.4.2.1
EXPANSION OF CITY GAS DISTRIBUTION INFRASTRUCTURE TO ACCELERATE PILOT-OPERATED GAS REGULATOR ADOPTION


13.4.3
JAPAN


13.4.3.1
HIGH DEPENDENCE ON EXTENSIVE LNG TERMINAL NETWORK AND ASSOCIATED GAS INFRASTRUCTURE TO SPUR DEMAND


13.4.4
SOUTH KOREA


13.4.4.1
ESTABLISHED NATURAL GAS TRANSMISSION AND DISTRIBUTION NETWORKS AND HIGHLY INDUSTRIALIZED ECONOMY TO REINFORCE MARKET GROWTH


13.4.5
AUSTRALIA


13.4.5.1
EXPANSION AND MODERNIZATION OF EXISTING PIPELINE AND GAS-PROCESSING INFRASTRUCTURE TO CREATE GROWTH OPPORTUNITIES


13.4.6
REST OF ASIA PACIFIC


13.5
SOUTH AMERICA


13.5.1
BRAZIL


13.5.1.1
THRIVING PETROCHEMICALS, POWER GENERATION, STEEL, AND CHEMICALS INDUSTRIES TO CREATE GROWTH OPPORTUNITIES


13.5.2
ARGENTINA


13.5.2.1
VACA MUERTA EXPANSION PROJECT AND GAS INFRASTRUCTURE MODERNIZATION EFFORTS TO EXPEDITE MARKET GROWTH


13.5.3
REST OF SOUTH AMERICA


13.6
MIDDLE EAST & AFRICA


13.6.1
GCC


13.6.1.1
SAUDI ARABIA


13.6.1.1.1
LARGE-SCALE GAS PRODUCTION AND PIPELINE EXPANSION PROJECTS TO STRENGTHEN MARKET GROWTH


13.6.1.2
UAE


13.6.1.2.1
ADNOC GAS’ RICH GAS DEVELOPMENT (RGD) PROGRAM TO ACCELERATE MARKET GROWTH


13.6.1.3
QATAR


13.6.1.3.1
QATARENERGY’S NORTH FIELD EXPANSION PROGRAM TO CREATE GROWTH OPPORTUNITIES


13.6.1.4
REST OF GCC


13.6.2
SOUTH AFRICA


13.6.2.1
GROWING FOCUS ON GAS INFRASTRUCTURE MODERNIZATION AND LNG DEVELOPMENT TO SPUR DEMAND


13.6.3
EGYPT


13.6.3.1
RISING DOMESTIC GAS PRODUCTION AND LNG ACTIVITY TO FUEL MARKET GROWTH


13.6.4
REST OF MIDDLE EAST & AFRICA


14
COMPETITIVE LANDSCAPE
Discover winning strategies and market positions of key players and startups in the competitive landscape.


199
 
14.1
OVERVIEW


14.2
KEY PLAYER COMPETITIVE STRATEGIES/RIGHT TO WIN, 2023–2026


14.3
MARKET SHARE ANALYSIS, 2025


14.4
REVENUE ANALYSIS, 2021–2025


14.5
BRAND COMPARISON


14.5.1
EMERSON (US)


14.5.2
HONEYWELL INTERNATIONAL, INC. (US)


14.5.3
PIETRO FIORENTINI S.P.A. (ITALY)


14.5.4
BAKER HUGHES COMPANY (US)


14.5.5
DRESSER UTILITY SOLUTIONS (US)


14.6
COMPANY EVALUATION MATRIX: KEY PLAYERS, 2025


14.6.1
STARS


14.6.2
EMERGING LEADERS


14.6.3
PERVASIVE PLAYERS


14.6.4
PARTICIPANTS


14.6.5
COMPANY FOOTPRINT: KEY PLAYERS, 2025


14.6.5.1
COMPANY FOOTPRINT


14.6.5.2
REGION FOOTPRINT


14.6.5.3
INSTALLATION TYPE FOOTPRINT


14.6.5.4
PRESSURE FOOTPRINT


14.6.5.5
END USER FOOTPRINT


14.7
COMPANY EVALUATION MATRIX: STARTUPS/SMES, 2025


14.7.1
PROGRESSIVE COMPANIES


14.7.2
RESPONSIVE COMPANIES


14.7.3
DYNAMIC COMPANIES


14.7.4
STARTING BLOCKS


14.7.5
COMPETITIVE BENCHMARKING: STARTUPS/SMES, 2025


14.7.5.1
DETAILED LIST OF KEY STARTUPS/SMES


14.7.5.2
COMPETITIVE BENCHMARKING OF KEY STARTUPS/SMES


14.8
COMPANY VALUATION AND FINANCIAL METRICS


14.9
COMPETITIVE SCENARIO


14.9.1
PRODUCT LAUNCHES


14.9.2
DEALS


14.9.3
EXPANSIONS


14.9.4
OTHER DEVELOPMENTS


15
COMPANY PROFILES
In-depth Company Profiles of Leading Market Players with detailed Business Overview, Product and Service Portfolio, Recent Developments, and Unique Analyst Perspective (MnM View)


220
 
15.1
KEY PLAYERS


15.1.1
EMERSON


15.1.1.1
BUSINESS OVERVIEW


15.1.1.2
PRODUCTS/SOLUTIONS/SERVICES OFFERED


15.1.1.3
RECENT DEVELOPMENTS


15.1.1.3.1
PRODUCT LAUNCHES


15.1.1.3.2
DEALS


15.1.1.4
MNM VIEW


15.1.1.4.1
KEY STRENGTHS/RIGHT TO WIN


15.1.1.4.2
STRATEGIC CHOICES


15.1.1.4.3
WEAKNESSES/COMPETITIVE THREATS


15.1.2
HONEYWELL INTERNATIONAL INC.


15.1.3
PIETRO FIORENTINI S.P.A.


15.1.4
BAKER HUGHES COMPANY


15.1.5
DRESSER UTILITY SOLUTIONS


15.1.6
NIRMAL INDUSTRIAL CONTROLS PVT. LTD.


15.1.7
CAVAGNA GROUP S.P.A.


15.1.8
VALVITALIA


15.1.9
AXIS SOLUTIONS LIMITED


15.1.10
GASCAT IND. E COM. LTDA


15.1.11
CASHCO


15.1.12
OXFORD FLOW


15.1.13
FLOW METERING TECHNOLOGY


15.1.14
SPECS VALVE


15.1.15
GASTEH


15.2
OTHER PLAYERS


15.2.1
SAMSON CONTROLS PVT. LTD.


15.2.2
RICHARDS INDUSTRIALS


15.2.3
MAXITROL


15.2.4
ARMSTRONG INTERNATIONAL INC.


15.2.5
HYPERR VALVES PVT. LTD.


15.2.6
HEAT GROUP


15.2.7
BELGAS


15.2.8
MEDENUS


15.2.9
PINXIN INTELLIGENT CONTROL


15.2.10
VANAZ ENGINEERS LIMITED


16
RESEARCH METHODOLOGY


267
 
16.1
RESEARCH DATA


16.2
SECONDARY AND PRIMARY RESEARCH


16.2.1
SECONDARY DATA


16.2.1.1
LIST OF KEY SECONDARY SOURCES


16.2.1.2
KEY DATA FROM SECONDARY SOURCES


16.2.2
PRIMARY DATA


16.2.2.1
LIST OF PRIMARY INTERVIEW PARTICIPANTS


16.2.2.2
KEY INDUSTRY INSIGHTS


16.2.2.3
BREAKDOWN OF PRIMARIES


16.2.2.4
KEY DATA FROM PRIMARY SOURCES


16.3
MARKET SIZE ESTIMATION


16.3.1
BOTTOM-UP APPROACH


16.3.2
TOP-DOWN APPROACH


16.4
MARKET FORECAST APPROACH


16.4.1
DEMAND-SIDE


16.4.1.1
DEMAND-SIDE ASSUMPTIONS


16.4.1.2
DEMAND-SIDE CALCULATIONS


16.4.2
SUPPLY-SIDE


16.4.2.1
SUPPLY-SIDE ASSUMPTIONS


16.4.2.2
SUPPLY-SIDE CALCULATIONS


16.5
DATA TRIANGULATION


16.6
RESEARCH LIMITATIONS


17
APPENDIX


280
 
17.1
DISCUSSION GUIDE


17.2
KNOWLEDGESTORE: MARKETSANDMARKETS’ SUBSCRIPTION PORTAL


17.3
CUSTOMIZATION OPTIONS


17.4
RELATED REPORTS


17.5
AUTHOR DETAILS


LIST OF TABLES


TABLE 1
PILOT-OPERATED GAS REGULATORS MARKET: INCLUSIONS AND EXCLUSIONS BY PRESSURE


TABLE 2
PILOT-OPERATED GAS REGULATORS MARKET: INCLUSIONS AND EXCLUSIONS BY INSTALLATION TYPE


TABLE 3
PILOT-OPERATED GAS REGULATORS MARKET: INCLUSIONS AND EXCLUSIONS BY INSTALLATION LOCATION


TABLE 4
PILOT-OPERATED GAS REGULATORS MARKET: INCLUSIONS AND EXCLUSIONS BY END USER


TABLE 5
INTERCONNECTED MARKETS


TABLE 6
STRATEGIC FOCUS OF TIER 1/2/3 PLAYERS


TABLE 7
IMPACT OF PORTER’S FIVE FORCES


TABLE 8
GDP PERCENTAGE CHANGE, BY KEY COUNTRY, 2021–2029


TABLE 9
ROLES OF COMPANIES IN PILOT-OPERATED GAS REGULATOR ECOSYSTEM


TABLE 10
AVERAGE SELLING PRICE TREND OF PILOT-OPERATED GAS REGULATORS, BY PRESSURE, 2022–2025 (USD/UNIT)


TABLE 11
AVERAGE SELLING PRICE TREND OF PILOT-OPERATED GAS REGULATORS, BY REGION, 2022–2025 (USD/UNIT)


TABLE 12
IMPORT DATA FOR HS CODE 848110-COMPLIANT PRODUCTS, BY COUNTRY, 2021–2025 (USD MILLION)


TABLE 13
EXPORT DATA FOR HS CODE 848110-COMPLIANT PRODUCTS, BY COUNTRY, 2021–2025 (USD MILLION)


TABLE 14
LIST OF KEY CONFERENCES AND EVENTS, 2026–2027


TABLE 15
EMERSON PILOT-OPERATED REGULATORS REDUCE OPERATING COSTS IN EUROPEAN NATURAL GAS GRID


TABLE 16
BAKER HUGHES’ MOONEY SLAM SHUT REGULATORS IMPROVE SAFETY IN US PIPELINE DISTRIBUTION


TABLE 17
US-ADJUSTED RECIPROCAL TARIFF RATES


TABLE 18
EXPECTED CHANGE IN PRICES AND IMPACT ON END USERS DUE TO TARIFFS


TABLE 19
LIST OF KEY PATENTS, 2015–2025


TABLE 20
SMART CITY GAS DISTRIBUTION NETWORKS


TABLE 21
DIGITAL PRESSURE-REDUCTION STATIONS


TABLE 22
METHANE EMISSION MONITORING AND REDUCTION


TABLE 23
HYDROGEN AND HYDROGEN-BLENDED GAS NETWORKS


TABLE 24
INDUSTRIAL GAS AUTOMATION


TABLE 25
USE CASES AND PILOT-OPERATED GAS REGULATORS MARKET POTENTIAL


TABLE 26
BEST PRACTICES: USE CASES OF PILOT OPERTAED GAS REGULATORS, BY COMPANY


TABLE 27
CASE STUDIES RELATED TO AI/GEN AI IMPLEMENTATION


TABLE 28
INTERCONNECTED ECOSYSTEM AND IMPACT ON PILOT-OPERATED GAS REGULATORS MARKET PLAYERS


TABLE 29
NORTH AMERICA: REGULATORY BODIES, GOVERNMENT AGENCIES, AND OTHER ORGANIZATIONS


TABLE 30
EUROPE: LIST OF REGULATORY BODIES, GOVERNMENT AGENCIES, AND OTHER ORGANIZATIONS


TABLE 31
ASIA PACIFIC: LIST OF REGULATORY BODIES, GOVERNMENT AGENCIES, AND OTHER ORGANIZATIONS


TABLE 32
SOUTH AMERICA: LIST OF REGULATORY BODIES, GOVERNMENT AGENCIES, AND OTHER ORGANIZATIONS


TABLE 33
MIDDLE EAST & AFRICA: LIST OF REGULATORY BODIES, GOVERNMENT AGENCIES, AND OTHER ORGANIZATIONS


TABLE 34
GLOBAL INDUSTRY STANDARDS


TABLE 35
LABELING AND ECO-STANDARDS


TABLE 36
INFLUENCE OF STAKEHOLDERS ON BUYING PROCESS, BY END USER (%)


TABLE 37
BUYING CRITERIA, BY END USER


TABLE 38
UNMET NEEDS IN THE PILOT-OPERATED GAS REGULATORS MARKET BY END USER


TABLE 39
PILOT-OPERATED GAS REGULATORS MARKET, BY PRESSURE, 2022–2025 (USD MILLION)


TABLE 40
PILOT-OPERATED GAS REGULATORS MARKET, BY PRESSURE, 2026–2031 (USD MILLION)


TABLE 41
LOW: PILOT-OPERATED GAS REGULATORS MARKET, BY REGION, 2022–2025 (USD MILLION)


TABLE 42
LOW: PILOT-OPERATED GAS REGULATORS MARKET, BY REGION, 2026–2031 (USD MILLION)


TABLE 43
MEDIUM: PILOT-OPERATED GAS REGULATORS MARKET, BY REGION, 2022–2025 (USD MILLION)


TABLE 44
MEDIUM: PILOT-OPERATED GAS REGULATORS MARKET, BY REGION, 2026–2031 (USD MILLION)


TABLE 45
HIGH: PILOT-OPERATED GAS REGULATORS MARKET, BY REGION, 2022–2025 (USD MILLION)


TABLE 46
HIGH: PILOT-OPERATED GAS REGULATORS MARKET, BY REGION, 2026–2031 (USD MILLION)


TABLE 47
PILOT-OPERATED GAS REGULATORS MARKET, BY INSTALLATION TYPE, 2022–2025 (USD MILLION)


TABLE 48
PILOT-OPERATED GAS REGULATORS MARKET, BY INSTALLATION TYPE, 2026–2031 (USD MILLION)


TABLE 49
NEW INSTALLATION: PILOT-OPERATED GAS REGULATORS MARKET, BY REGION, 2022–2025 (USD MILLION)


TABLE 50
NEW INSTALLATION: PILOT-OPERATED GAS REGULATORS MARKET, BY REGION, 2026–2031 (USD MILLION)


TABLE 51
RETROFIT: PILOT-OPERATED GAS REGULATORS MARKET, BY REGION, 2022–2025 (USD MILLION)


TABLE 52
RETROFIT: PILOT-OPERATED GAS REGULATORS MARKET, BY REGION, 2026–2031 (USD MILLION)


TABLE 53
PILOT-OPERATED GAS REGULATORS MARKET, BY INSTALLATION LOCATION, 2022–2025 (USD MILLION)


TABLE 54
PILOT-OPERATED GAS REGULATORS MARKET, BY INSTALLATION LOCATION, 2026–2031 (USD MILLION)


TABLE 55
ONSHORE: PILOT-OPERATED GAS REGULATORS MARKET, BY REGION, 2022–2025 (USD MILLION)


TABLE 56
ONSHORE: PILOT-OPERATED GAS REGULATORS MARKET, BY REGION, 2026–2031 (USD MILLION)


TABLE 57
OFFSHORE: PILOT-OPERATED GAS REGULATORS MARKET, BY REGION, 2022–2025 (USD MILLION)


TABLE 58
OFFSHORE: PILOT-OPERATED GAS REGULATORS MARKET, BY REGION, 2026–2031 (USD MILLION)


TABLE 59
PILOT-OPERATED GAS REGULATORS MARKET, BY END USER, 2022–2025 (USD MILLION)


TABLE 60
PILOT-OPERATED GAS REGULATORS MARKET, BY END USER, 2026–2031 (USD MILLION)


TABLE 61
OIL & GAS COMPANIES: PILOT-OPERATED GAS REGULATORS MARKET, BY APPLICATION, 2022–2025 (USD MILLION)


TABLE 62
OIL & GAS COMPANIES: PILOT-OPERATED GAS REGULATORS MARKET, BY APPLICATION, 2026–2031 (USD MILLION)


TABLE 63
GAS UTILITIES: PILOT-OPERATED GAS REGULATORS MARKET, BY APPLICATION, 2022–2025 (USD MILLION)


TABLE 64
GAS UTILITIES: PILOT-OPERATED GAS REGULATORS MARKET, BY APPLICATION, 2026–2031 (USD MILLION)


TABLE 65
INDUSTRIAL MANUFACTURING PLANTS: PILOT-OPERATED GAS REGULATORS MARKET, BY APPLICATION, 2022–2025 (USD MILLION)


TABLE 66
INDUSTRIAL MANUFACTURING PLANTS: PILOT-OPERATED GAS REGULATORS MARKET, BY APPLICATION, 2026–2031 (USD MILLION)


TABLE 67
OIL & GAS COMPANIES: PILOT-OPERATED GAS REGULATORS MARKET, BY REGION, 2022–2025 (USD MILLION)


TABLE 68
OIL & GAS COMPANIES: PILOT-OPERATED GAS REGULATORS MARKET, BY REGION, 2026–2031 (USD MILLION)


TABLE 69
GAS UTILITIES: PILOT-OPERATED GAS REGULATORS MARKET, BY REGION, 2022–2025 (USD MILLION)


TABLE 70
GAS UTILITIES: PILOT-OPERATED GAS REGULATORS MARKET, BY REGION, 2026–2031 (USD MILLION)


TABLE 71
POWER GENERATION PLANTS: PILOT-OPERATED GAS REGULATORS MARKET, BY REGION, 2022–2025 (USD MILLION)


TABLE 72
POWER GENERATION PLANTS: PILOT-OPERATED GAS REGULATORS MARKET, BY REGION, 2026–2031 (USD MILLION)


TABLE 73
INDUSTRIAL MANUFACTURING PLANTS: PILOT-OPERATED GAS REGULATORS MARKET, BY REGION, 2022–2025 (USD MILLION)


TABLE 74
INDUSTRIAL MANUFACTURING PLANTS: PILOT-OPERATED GAS REGULATORS MARKET, BY REGION, 2026–2031 (USD MILLION)


TABLE 75
OTHER END USERS: PILOT-OPERATED GAS REGULATORS MARKET, BY REGION, 2022–2025 (USD MILLION)


TABLE 76
OTHER END USERS: PILOT-OPERATED GAS REGULATORS MARKET, BY REGION, 2026–2031 (USD MILLION)


TABLE 77
PILOT-OPERATED GAS REGULATORS MARKET, BY REGION, 2022–2025 (USD MILLION)


TABLE 78
PILOT-OPERATED GAS REGULATORS MARKET, BY REGION, 2026–2031 (USD MILLION)


TABLE 79
PILOT-OPERATED GAS REGULATORS MARKET, BY REGION, 2022–2025 (UNITS)


TABLE 80
PILOT-OPERATED GAS REGULATORS MARKET, BY REGION, 2026–2031 (UNITS)


TABLE 81
NORTH AMERICA: PILOT-OPERATED GAS REGULATORS MARKET, BY PRESSURE, 2022–2025 (USD MILLION)


TABLE 82
NORTH AMERICA: PILOT-OPERATED GAS REGULATORS MARKET, BY PRESSURE, 2026–2031 (USD MILLION)


TABLE 83
NORTH AMERICA: PILOT-OPERATED GAS REGULATORS MARKET, BY INSTALLATION TYPE, 2022–2025 (USD MILLION)


TABLE 84
NORTH AMERICA: PILOT-OPERATED GAS REGULATORS MARKET, BY INSTALLATION TYPE, 2026–2031 (USD MILLION)


TABLE 85
NORTH AMERICA: PILOT-OPERATED GAS REGULATORS MARKET, BY INSTALLATION LOCATION, 2022–2025 (USD MILLION)


TABLE 86
NORTH AMERICA: PILOT-OPERATED GAS REGULATORS MARKET, BY INSTALLATION LOCATION, 2026–2031 (USD MILLION)


TABLE 87
NORTH AMERICA: PILOT-OPERATED GAS REGULATORS MARKET, BY END USER, 2022–2025 (USD MILLION)


TABLE 88
NORTH AMERICA: PILOT-OPERATED GAS REGULATORS MARKET, BY END USER, 2026–2031 (USD MILLION)


TABLE 89
NORTH AMERICA: PILOT-OPERATED GAS REGULATORS MARKET FOR OIL & GAS COMPANIES, BY APPLICATION, 2022–2025 (USD MILLION)


TABLE 90
NORTH AMERICA: PILOT-OPERATED GAS REGULATORS MARKET FOR OIL & GAS COMPANIES, BY APPLICATION, 2026–2031 (USD MILLION)


TABLE 91
NORTH AMERICA: PILOT-OPERATED GAS REGULATORS MARKET FOR GAS UTILITIES, BY APPLICATION, 2022–2025 (USD MILLION)


TABLE 92
NORTH AMERICA: PILOT-OPERATED GAS REGULATORS MARKET FOR GAS UTILITIES, BY APPLICATION, 2026–2031 (USD MILLION)


TABLE 93
NORTH AMERICA: PILOT-OPERATED GAS REGULATORS MARKET FOR INDUSTRIAL MANUFACTURING PLANTS, BY APPLICATION, 2022–2025 (USD MILLION)


TABLE 94
NORTH AMERICA: PILOT-OPERATED GAS REGULATORS MARKET FOR INDUSTRIAL MANUFACTURING PLANTS, BY APPLICATION, 2026–2031 (USD MILLION)


TABLE 95
NORTH AMERICA: PILOT-OPERATED GAS REGULATORS MARKET, BY COUNTRY, 2022–2025 (USD MILLION)


TABLE 96
NORTH AMERICA: PILOT-OPERATED GAS REGULATORS MARKET, BY COUNTRY, 2026–2031 (USD MILLION)


TABLE 97
US: PILOT-OPERATED GAS REGULATORS MARKET, BY END USER, 2022–2025 (USD MILLION)


TABLE 98
US: PILOT-OPERATED GAS REGULATORS MARKET, BY END USER, 2026–2031 (USD MILLION)


TABLE 99
CANADA: PILOT-OPERATED GAS REGULATORS MARKET, BY END USER, 2022–2025 (USD MILLION)


TABLE 100
CANADA: PILOT-OPERATED GAS REGULATORS MARKET, BY END USER, 2026–2031 (USD MILLION)


TABLE 101
MEXICO: PILOT-OPERATED GAS REGULATORS MARKET, BY END USER, 2022–2025 (USD MILLION)


TABLE 102
MEXICO: PILOT-OPERATED GAS REGULATORS MARKET, BY END USER, 2026–2031 (USD MILLION)


TABLE 103
EUROPE: PILOT-OPERATED GAS REGULATORS MARKET, BY PRESSURE, 2022–2025 (USD MILLION)


TABLE 104
EUROPE: PILOT-OPERATED GAS REGULATORS MARKET, BY PRESSURE, 2026–2031 (USD MILLION)


TABLE 105
EUROPE: PILOT-OPERATED GAS REGULATORS MARKET, BY INSTALLATION TYPE, 2022–2025 (USD MILLION)


TABLE 106
EUROPE: PILOT-OPERATED GAS REGULATORS MARKET, BY INSTALLATION TYPE, 2026–2031 (USD MILLION)


TABLE 107
EUROPE: PILOT-OPERATED GAS REGULATORS MARKET, BY INSTALLATION LOCATION, 2022–2025 (USD MILLION)


TABLE 108
EUROPE: PILOT-OPERATED GAS REGULATORS MARKET, BY INSTALLATION LOCATION, 2026–2031 (USD MILLION)


TABLE 109
EUROPE: PILOT-OPERATED GAS REGULATORS MARKET, BY END USER, 2022–2025 (USD MILLION)


TABLE 110
EUROPE: PILOT-OPERATED GAS REGULATORS MARKET, BY END USER, 2026–2031 (USD MILLION)


TABLE 111
EUROPE: PILOT-OPERATED GAS REGULATORS MARKET FOR OIL & GAS COMPANIES, BY APPLICATION, 2022–2025 (USD MILLION)


TABLE 112
EUROPE: PILOT-OPERATED GAS REGULATORS MARKET FOR OIL & GAS COMPANIES, BY APPLICATION, 2026–2031 (USD MILLION)


TABLE 113
EUROPE: PILOT-OPERATED GAS REGULATORS MARKET FOR GAS UTILITIES, BY APPLICATION, 2022–2025 (USD MILLION)


TABLE 114
EUROPE: PILOT-OPERATED GAS REGULATORS MARKET FOR GAS UTILITIES, BY APPLICATION, 2026–2031 (USD MILLION)


TABLE 115
EUROPE: PILOT-OPERATED GAS REGULATORS MARKET FOR INDUSTRIAL MANUFACTURING PLANTS, BY APPLICATION, 2022–2025 (USD MILLION)


TABLE 116
EUROPE: PILOT-OPERATED GAS REGULATORS MARKET FOR INDUSTRIAL MANUFACTURING PLANTS, BY APPLICATION, 2026–2031 (USD MILLION)


TABLE 117
EUROPE: PILOT-OPERATED GAS REGULATORS MARKET, BY COUNTRY, 2022–2025 (USD MILLION)


TABLE 118
EUROPE: PILOT-OPERATED GAS REGULATORS MARKET, BY COUNTRY, 2026–2031 (USD MILLION)


TABLE 119
GERMANY: PILOT-OPERATED GAS REGULATORS MARKET, BY END USER, 2022–2025 (USD MILLION)


TABLE 120
GERMANY: PILOT-OPERATED GAS REGULATORS MARKET, BY END USER, 2026–2031 (USD MILLION)


TABLE 121
UK: PILOT-OPERATED GAS REGULATORS MARKET, BY END USER, 2022–2025 (USD MILLION)


TABLE 122
UK: PILOT-OPERATED GAS REGULATORS MARKET, BY END USER, 2026–2031 (USD MILLION)


TABLE 123
FRANCE: PILOT-OPERATED GAS REGULATORS MARKET, BY END USER, 2022–2025 (USD MILLION)


TABLE 124
FRANCE: PILOT-OPERATED GAS REGULATORS MARKET, BY END USER, 2026–2031 (USD MILLION)


TABLE 125
ITALY: PILOT-OPERATED GAS REGULATORS MARKET, BY END USER, 2022–2025 (USD MILLION)


TABLE 126
ITALY: PILOT-OPERATED GAS REGULATORS MARKET, BY END USER, 2026–2031 (USD MILLION)


TABLE 127
SPAIN: PILOT-OPERATED GAS REGULATORS MARKET, BY END USER, 2022–2025 (USD MILLION)


TABLE 128
SPAIN: PILOT-OPERATED GAS REGULATORS MARKET, BY END USER, 2026–2031 (USD MILLION)


TABLE 129
REST OF EUROPE: PILOT-OPERATED GAS REGULATORS MARKET, BY END USER, 2022–2025 (USD MILLION)


TABLE 130
REST OF EUROPE: PILOT-OPERATED GAS REGULATORS MARKET, BY END USER, 2026–2031 (USD MILLION)


TABLE 131
ASIA PACIFIC: PILOT-OPERATED GAS REGULATORS MARKET, BY PRESSURE, 2022–2025 (USD MILLION)


TABLE 132
ASIA PACIFIC: PILOT-OPERATED GAS REGULATORS MARKET, BY PRESSURE, 2026–2031 (USD MILLION)


TABLE 133
ASIA PACIFIC: PILOT-OPERATED GAS REGULATORS MARKET, BY INSTALLATION TYPE, 2022–2025 (USD MILLION)


TABLE 134
ASIA PACIFIC: PILOT-OPERATED GAS REGULATORS MARKET, BY INSTALLATION TYPE, 2026–2031 (USD MILLION)


TABLE 135
ASIA PACIFIC: PILOT-OPERATED GAS REGULATORS MARKET, BY INSTALLATION LOCATION, 2022–2025 (USD MILLION)


TABLE 136
ASIA PACIFIC: PILOT-OPERATED GAS REGULATORS MARKET, BY INSTALLATION LOCATION, 2026–2031 (USD MILLION)


TABLE 137
ASIA PACIFIC: PILOT-OPERATED GAS REGULATORS MARKET, BY END USER, 2022–2025 (USD MILLION)


TABLE 138
ASIA PACIFIC: PILOT-OPERATED GAS REGULATORS MARKET, BY END USER, 2026–2031 (USD MILLION)


TABLE 139
ASIA PACIFIC: PILOT-OPERATED GAS REGULATORS MARKET FOR OIL & GAS COMPANIES, BY APPLICATION, 2022–2025 (USD MILLION)


TABLE 140
ASIA PACIFIC: PILOT-OPERATED GAS REGULATORS MARKET FOR OIL & GAS COMPANIES, BY APPLICATION, 2026–2031 (USD MILLION)


TABLE 141
ASIA PACIFIC: PILOT-OPERATED GAS REGULATORS MARKET FOR GAS UTILITIES, BY APPLICATION, 2022–2025 (USD MILLION)


TABLE 142
ASIA PACIFIC: PILOT-OPERATED GAS REGULATORS MARKET FOR GAS UTILITIES, BY APPLICATION, 2026–2031 (USD MILLION)


TABLE 143
ASIA PACIFIC: PILOT-OPERATED GAS REGULATORS MARKET FOR INDUSTRIAL MANUFACTURING PLANTS, BY APPLICATION, 2022–2025 (USD MILLION)


TABLE 144
ASIA PACIFIC: PILOT-OPERATED GAS REGULATORS MARKET FOR INDUSTRIAL MANUFACTURING PLANTS, BY APPLICATION, 2026–2031 (USD MILLION)


TABLE 145
ASIA PACIFIC: PILOT-OPERATED GAS REGULATORS MARKET, BY COUNTRY, 2022–2025 (USD MILLION)


TABLE 146
ASIA PACIFIC: PILOT-OPERATED GAS REGULATORS MARKET, BY COUNTRY, 2026–2031 (USD MILLION)


TABLE 147
CHINA: PILOT-OPERATED GAS REGULATORS MARKET, BY END USER, 2022–2025 (USD MILLION)


TABLE 148
CHINA: PILOT-OPERATED GAS REGULATORS MARKET, BY END USER, 2026–2031 (USD MILLION)


TABLE 149
INDIA: PILOT-OPERATED GAS REGULATORS MARKET, BY END USER, 2022–2025 (USD MILLION)


TABLE 150
INDIA: PILOT-OPERATED GAS REGULATORS MARKET, BY END USER, 2026–2031 (USD MILLION)


TABLE 151
JAPAN: PILOT-OPERATED GAS REGULATORS MARKET, BY END USER, 2022–2025 (USD MILLION)


TABLE 152
JAPAN: PILOT-OPERATED GAS REGULATORS MARKET, BY END USER, 2026–2031 (USD MILLION)


TABLE 153
SOUTH KOREA: PILOT-OPERATED GAS REGULATORS MARKET, BY END USER, 2022–2025 (USD MILLION)


TABLE 154
SOUTH KOREA: PILOT-OPERATED GAS REGULATORS MARKET, BY END USER, 2026–2031 (USD MILLION)


TABLE 155
AUSTRALIA: PILOT-OPERATED GAS REGULATORS MARKET, BY END USER, 2022–2025 (USD MILLION)


TABLE 156
AUSTRALIA: PILOT-OPERATED GAS REGULATORS MARKET, BY END USER, 2026–2031 (USD MILLION)


TABLE 157
REST OF ASIA PACIFIC: PILOT-OPERATED GAS REGULATORS MARKET, BY END USER, 2022–2025 (USD MILLION)


TABLE 158
REST OF ASIA PACIFIC: PILOT-OPERATED GAS REGULATORS MARKET, BY END USER, 2026–2031 (USD MILLION)


TABLE 159
SOUTH AMERICA: PILOT-OPERATED GAS REGULATORS MARKET, BY PRESSURE, 2022–2025 (USD MILLION)


TABLE 160
SOUTH AMERICA: PILOT-OPERATED GAS REGULATORS MARKET, BY PRESSURE, 2026–2031 (USD MILLION)


TABLE 161
SOUTH AMERICA: PILOT-OPERATED GAS REGULATORS MARKET, BY INSTALLATION TYPE, 2022–2025 (USD MILLION)


TABLE 162
SOUTH AMERICA: PILOT-OPERATED GAS REGULATORS MARKET, BY INSTALLATION TYPE, 2026–2031 (USD MILLION)


TABLE 163
SOUTH AMERICA: PILOT-OPERATED GAS REGULATORS MARKET, BY INSTALLATION LOCATION, 2022–2025 (USD MILLION)


TABLE 164
SOUTH AMERICA: PILOT-OPERATED GAS REGULATORS MARKET, BY INSTALLATION LOCATION, 2026–2031 (USD MILLION)


TABLE 165
SOUTH AMERICA: PILOT-OPERATED GAS REGULATORS MARKET, BY END USER, 2022–2025 (USD MILLION)


TABLE 166
SOUTH AMERICA: PILOT-OPERATED GAS REGULATORS MARKET, BY END USER, 2026–2031 (USD MILLION)


TABLE 167
SOUTH AMERICA: PILOT-OPERATED GAS REGULATORS MARKET FOR OIL & GAS COMPANIES, BY APPLICATION, 2022–2025 (USD MILLION)


TABLE 168
SOUTH AMERICA: PILOT-OPERATED GAS REGULATORS MARKET FOR OIL & GAS COMPANIES, BY APPLICATION, 2026–2031 (USD MILLION)


TABLE 169
SOUTH AMERICA: PILOT-OPERATED GAS REGULATORS MARKET FOR GAS UTILITIES, BY APPLICATION, 2022–2025 (USD MILLION)


TABLE 170
SOUTH AMERICA: PILOT-OPERATED GAS REGULATORS MARKET FOR GAS UTILITIES, BY APPLICATION, 2026–2031 (USD MILLION)


TABLE 171
SOUTH AMERICA: PILOT-OPERATED GAS REGULATORS MARKET FOR INDUSTRIAL MANUFACTURING PLANTS, BY APPLICATION, 2022–2025 (USD MILLION)


TABLE 172
SOUTH AMERICA: PILOT-OPERATED GAS REGULATORS MARKET FOR INDUSTRIAL MANUFACTURING PLANTS, BY APPLICATION, 2026–2031 (USD MILLION)


TABLE 173
SOUTH AMERICA: PILOT-OPERATED GAS REGULATORS MARKET, BY COUNTRY, 2022–2025 (USD MILLION)


TABLE 174
SOUTH AMERICA: PILOT-OPERATED GAS REGULATORS MARKET, BY COUNTRY, 2026–2031 (USD MILLION)


TABLE 175
BRAZIL: PILOT-OPERATED GAS REGULATORS MARKET, BY END USER, 2022–2025 (USD MILLION)


TABLE 176
BRAZIL: PILOT-OPERATED GAS REGULATORS MARKET, BY END USER, 2026–2031 (USD MILLION)


TABLE 177
ARGENTINA: PILOT-OPERATED GAS REGULATORS MARKET, BY END USER, 2022–2025 (USD MILLION)


TABLE 178
ARGENTINA: PILOT-OPERATED GAS REGULATORS MARKET, BY END USER, 2026–2031 (USD MILLION)


TABLE 179
REST OF SOUTH AMERICA: PILOT-OPERATED GAS REGULATORS MARKET, BY END USER, 2022–2025 (USD MILLION)


TABLE 180
REST OF SOUTH AMERICA: PILOT-OPERATED GAS REGULATORS MARKET, BY END USER, 2026–2031 (USD MILLION)


TABLE 181
MIDDLE EAST & AFRICA: PILOT-OPERATED GAS REGULATORS MARKET, BY PRESSURE, 2022–2025 (USD MILLION)


TABLE 182
MIDDLE EAST & AFRICA: PILOT-OPERATED GAS REGULATORS MARKET, BY PRESSURE, 2026–2031 (USD MILLION)


TABLE 183
MIDDLE EAST & AFRICA: PILOT-OPERATED GAS REGULATORS MARKET, BY INSTALLATION TYPE, 2022–2025 (USD MILLION)


TABLE 184
MIDDLE EAST & AFRICA: PILOT-OPERATED GAS REGULATORS MARKET, BY INSTALLATION TYPE, 2026–2031 (USD MILLION)


TABLE 185
MIDDLE EAST & AFRICA: PILOT-OPERATED GAS REGULATORS MARKET, BY INSTALLATION LOCATION, 2022–2025 (USD MILLION)


TABLE 186
MIDDLE EAST & AFRICA: PILOT-OPERATED GAS REGULATORS MARKET, BY INSTALLATION LOCATION, 2026–2031 (USD MILLION)


TABLE 187
MIDDLE EAST & AFRICA: PILOT-OPERATED GAS REGULATORS MARKET, BY END USER, 2022–2025 (USD MILLION)


TABLE 188
MIDDLE EAST & AFRICA: PILOT-OPERATED GAS REGULATORS MARKET, BY END USER, 2026–2031 (USD MILLION)


TABLE 189
MIDDLE EAST & AFRICA: PILOT-OPERATED GAS REGULATORS MARKET FOR OIL & GAS COMPANIES, BY APPLICATION, 2022–2025 (USD MILLION)


TABLE 190
MIDDLE EAST & AFRICA: PILOT-OPERATED GAS REGULATORS MARKET FOR OIL & GAS COMPANIES, BY APPLICATION, 2026–2031 (USD MILLION)


TABLE 191
MIDDLE EAST & AFRICA: PILOT-OPERATED GAS REGULATORS MARKET FOR GAS UTILITIES, BY APPLICATION, 2022–2025 (USD MILLION)


TABLE 192
MIDDLE EAST & AFRICA: PILOT-OPERATED GAS REGULATORS MARKET FOR GAS UTILITIES, BY APPLICATION, 2026–2031 (USD MILLION)


TABLE 193
MIDDLE EAST & AFRICA: PILOT-OPERATED GAS REGULATORS MARKET FOR INDUSTRIAL MANUFACTURING PLANTS, BY APPLICATION, 2022–2025 (USD MILLION)


TABLE 194
MIDDLE EAST & AFRICA: PILOT-OPERATED GAS REGULATORS MARKET FOR INDUSTRIAL MANUFACTURING PLANTS, BY APPLICATION, 2026–2031 (USD MILLION)


TABLE 195
MIDDLE EAST & AFRICA: PILOT-OPERATED GAS REGULATORS MARKET, BY COUNTRY, 2022–2025 (USD MILLION)


TABLE 196
MIDDLE EAST & AFRICA: PILOT-OPERATED GAS REGULATORS MARKET, BY COUNTRY, 2026–2031 (USD MILLION)


TABLE 197
GCC: PILOT-OPERATED GAS REGULATORS MARKET, BY COUNTRY, 2022–2025 (USD MILLION)


TABLE 198
GCC: PILOT-OPERATED GAS REGULATORS MARKET, BY COUNTRY, 2026–2031 (USD MILLION)


TABLE 199
SAUDI ARABIA: PILOT-OPERATED GAS REGULATORS MARKET, BY END USER, 2022–2025 (USD MILLION)


TABLE 200
SAUDI ARABIA: PILOT-OPERATED GAS REGULATORS MARKET, BY END USER, 2026–2031 (USD MILLION)


TABLE 201
UAE: PILOT-OPERATED GAS REGULATORS MARKET, BY END USER, 2022–2025 (USD MILLION)


TABLE 202
UAE: PILOT-OPERATED GAS REGULATORS MARKET, BY END USER, 2026–2031 (USD MILLION)


TABLE 203
QATAR: PILOT-OPERATED GAS REGULATORS MARKET, BY END USER, 2022–2025 (USD MILLION)


TABLE 204
QATAR: PILOT-OPERATED GAS REGULATORS MARKET, BY END USER, 2026–2031 (USD MILLION)


TABLE 205
REST OF GCC: PILOT-OPERATED GAS REGULATORS MARKET, BY END USER, 2022–2025 (USD MILLION)


TABLE 206
REST OF GCC: PILOT-OPERATED GAS REGULATORS MARKET, BY END USER, 2026–2031 (USD MILLION)


TABLE 207
SOUTH AFRICA: PILOT-OPERATED GAS REGULATORS MARKET, BY END USER, 2022–2025 (USD MILLION)


TABLE 208
SOUTH AFRICA: PILOT-OPERATED GAS REGULATORS MARKET, BY END USER, 2026–2031 (USD MILLION)


TABLE 209
EGYPT: PILOT-OPERATED GAS REGULATORS MARKET, BY END USER, 2022–2025 (USD MILLION)


TABLE 210
EGYPT: PILOT-OPERATED GAS REGULATORS MARKET, BY END USER, 2026–2031 (USD MILLION)


TABLE 211
REST OF MIDDLE EAST & AFRICA: PILOT-OPERATED GAS REGULATORS MARKET, BY END USER, 2022–2025 (USD MILLION)


TABLE 212
REST OF MIDDLE EAST & AFRICA: PILOT-OPERATED GAS REGULATORS MARKET, BY END USER, 2026–2031 (USD MILLION)


TABLE 213
PILOT-OPERATED GAS REGULATORS MARKET: OVERVIEW OF STRATEGIES ADOPTED BY KEY PLAYERS, JANUARY 2023–JULY 2026


TABLE 214
PILOT-OPERATED GAS REGULATORS MARKET: DEGREE OF COMPETITION, 2025


TABLE 215
PILOT-OPERATED GAS REGULATORS MARKET: REGION FOOTPRINT


TABLE 216
PILOT-OPERATED GAS REGULATORS MARKET: INSTALLATION TYPE FOOTPRINT


TABLE 217
PILOT-OPERATED GAS REGULATORS MARKET: PRESSURE FOOTPRINT


TABLE 218
PILOT-OPERATED GAS REGULATORS MARKET: END USER FOOTPRINT


TABLE 219
PILOT-OPERATED GAS REGULATORS MARKET: DETAILED LIST OF KEY STARTUPS/SMES


TABLE 220
PILOT-OPERATED GAS REGULATORS MARKET: COMPETITIVE BENCHMARKING OF KEY STARTUPS/SMES


TABLE 221
PILOT-OPERATED GAS REGULATORS MARKET: PRODUCT LAUNCHES, JANUARY 2023–JULY 2026


TABLE 222
PILOT-OPERATED GAS REGULATORS MARKET: DEALS, JANUARY 2023–JULY 2026


TABLE 223
PILOT-OPERATED GAS REGULATORS MARKET: EXPANSIONS, JANUARY 2023–JULY 2026


TABLE 224
PILOT-OPERATED GAS REGULATORS MARKET: OTHER DEVELOPMENTS, JANUARY 2023–JULY 2026


TABLE 225
EMERSON: COMPANY OVERVIEW


TABLE 226
EMERSON: PRODUCTS/SOLUTIONS/SERVICES OFFERED


TABLE 227
EMERSON: PRODUCT LAUNCHES


TABLE 228
EMERSON: DEALS


TABLE 229
HONEYWELL INTERNATIONAL INC.: COMPANY OVERVIEW


TABLE 230
HONEYWELL INTERNATIONAL INC.: PRODUCTS/SOLUTIONS/SERVICES OFFERED


TABLE 231
HONEYWELL INTERNATIONAL INC.: DEALS


TABLE 232
PIETRO FIORENTINI S.P.A.: COMPANY OVERVIEW


TABLE 233
PIETRO FIORENTINI S.P.A: PRODUCTS/SOLUTIONS/SERVICES OFFERED


TABLE 234
PIETRO FIORENTINI S.P.A.: DEALS


TABLE 235
BAKER HUGHES COMPANY: COMPANY OVERVIEW


TABLE 236
BAKER HUGHES COMPANY: PRODUCTS/SOLUTIONS/SERVICES OFFERED


TABLE 237
BAKER HUGHES COMPANY: DEALS


TABLE 238
BAKER HUGHES COMPANY: OTHER DEVELOPMENTS


TABLE 239
DRESSER UTILITY SOLUTIONS: COMPANY OVERVIEW


TABLE 240
DRESSER UTILITY SOLUTIONS: PRODUCTS/SOLUTIONS/SERVICES OFFERED


TABLE 241
NIRMAL INDUSTRIAL CONTROLS PVT. LTD.: COMPANY OVERVIEW


TABLE 242
NIRMAL INDUSTRIAL CONTROLS PVT. LTD.: PRODUCTS/SOLUTIONS/SERVICES OFFERED


TABLE 243
CAVAGNA GROUP S.P.A: COMPANY OVERVIEW


TABLE 244
CAVAGNA GROUP S.P.A.: PRODUCTS/SOLUTIONS/SERVICES OFFERED


TABLE 245
CAVAGNA GROUP S.P.A.: DEALS


TABLE 246
CAVAGNA GROUP S.P.A.: EXPANSIONS


TABLE 247
VALVITALIA: COMPANY OVERVIEW


TABLE 248
VALVITALIA: PRODUCTS/SOLUTIONS/SERVICES OFFERED


TABLE 249
VALVITALIA: DEALS


TABLE 250
VALVITALIA: OTHER DEVELOPMENTS


TABLE 251
AXIS SOLUTIONS LIMITED: COMPANY OVERVIEW


TABLE 252
AXIS SOLUTIONS LIMITED: PRODUCTS/SOLUTIONS/SERVICES OFFERED


TABLE 253
GASCAT IND. E COM. LTDA: COMPANY OVERVIEW


TABLE 254
GASCAT IND. E COM. LTDA: PRODUCTS/SOLUTIONS/SERVICES OFFERED


TABLE 255
GASCAT IND. E COM. LTDA: PRODUCT LAUNCHES


TABLE 256
CASHCO: COMPANY OVERVIEW


TABLE 257
CASHCO: PRODUCTS/SOLUTIONS/SERVICES OFFERED


TABLE 258
OXFORD FLOW: COMPANY OVERVIEW


TABLE 259
OXFORD FLOW: PRODUCTS/SOLUTIONS/SERVICES OFFERED


TABLE 260
FLOW METERING TECHNOLOGY: COMPANY OVERVIEW


TABLE 261
FLOW METERING TECHNOLOGY: PRODUCTS/SOLUTIONS/SERVICES OFFERED


TABLE 262
SPECS VALVE: COMPANY OVERVIEW


TABLE 263
SPECS VALVE: PRODUCTS/SOLUTIONS/SERVICES OFFERED


TABLE 264
GASTEH: COMPANY OVERVIEW


TABLE 265
GASTEH: PRODUCTS/SOLUTIONS/SERVICES OFFERED


TABLE 266
SAMSON CONTROLS PVT. LTD.: COMPANY OVERVIEW


TABLE 267
RICHARDS INDUSTRIALS: COMPANY OVERVIEW


TABLE 268
MAXITROL: COMPANY OVERVIEW


TABLE 269
ARMSTRONG INTERNATIONAL INC.: COMPANY OVERVIEW


TABLE 270
HYPERR VALVES PVT. LTD.: COMPANY OVERVIEW


TABLE 271
HEAT GROUP: COMPANY OVERVIEW


TABLE 272
BELGAS: COMPANY OVERVIEW


TABLE 273
MEDENUS: COMPANY OVERVIEW


TABLE 274
PINXIN INTELLIGENT CONTROL: COMPANY OVERVIEW


TABLE 275
VANAZ ENGINEERS LIMITED: COMPANY OVERVIEW


TABLE 276
KEY SECONDARY SOURCES


TABLE 277
PRIMARY INTERVIEW PARTICIPANTS


TABLE 278
DATA CAPTURED FROM PRIMARY SOURCES


LIST OF FIGURES


FIGURE 1
MARKETS COVERED AND REGIONAL SCOPE


FIGURE 2
PILOT-OPERATED GAS REGULATORS MARKET: DURATION CONSIDERED


FIGURE 3
PILOT-OPERATED GAS REGULATORS MARKET SCENARIO


FIGURE 4
GLOBAL PILOT-OPERATED GAS REGULATORS MARKET SIZE, 2022–2031


FIGURE 5
MAJOR STRATEGIES ADOPTED BY KEY PLAYERS IN PILOT-OPERATED GAS REGULATORS MARKET, 2023–2026


FIGURE 6
DISRUPTIONS INFLUENCING GROWTH OF PILOT-OPERATED GAS REGULATORS MARKET


FIGURE 7
HIGH-GROWTH SEGMENTS IN PILOT-OPERATED GAS REGULATORS MARKET, 2026–2031


FIGURE 8
ASIA PACIFIC TO REGISTER HIGHEST CAGR DURING FORECAST PERIOD


FIGURE 9
INCREASING INVESTMENTS IN GAS TRANSMISSION NETWORKS AND LNG INFRASTRUCTURE TO DRIVE MARKET


FIGURE 10
NEW INSTALLATION SEGMENT AND ASIA PACIFIC ACCOUNTED FOR LARGEST MARKET SHARE IN 2025


NEW INSTALLATION SEGMENT TO EXHIBIT HIGHER CAGR BETWEEN


2026
AND 2031


41
FIGURE 12
HIGH SEGMENT TO EXHIBIT HIGHEST CAGR BETWEEN 2026 AND 2031


FIGURE 13
OFFSHORE SEGMENT TO EXHIBIT HIGHER CAGR BETWEEN 2026 AND 2031


FIGURE 14
INDUSTRIAL MANUFACTURING PLANTS SEGMENT TO EXHIBIT HIGHEST CAGR BETWEEN 2026 AND 2031


FIGURE 15
INDIA TO REGISTER HIGHEST CAGR IN GLOBAL PILOT-OPERATED GAS REGULATORS MARKET DURING FORECAST PERIOD


FIGURE 16
PILOT-OPERATED GAS REGULATORS MARKET: DRIVERS, RESTRAINTS, OPPORTUNITIES, AND CHALLENGES


FIGURE 17
GLOBAL NATURAL GAS DEMAND, BY REGION, 2000–2024


FIGURE 18
GLOBAL CLEAN ENERGY INVESTMENTS, 2018–2025


FIGURE 19
GLOBAL CO2 EMISSIONS, BY REGION, 2015–2024


FIGURE 20
PORTER’S FIVE FORCES ANALYSIS


FIGURE 21
PILOT-OPERATED GAS REGULATORS VALUE CHAIN ANALYSIS


FIGURE 22
KEY PARTICIPANTS IN PILOT-OPERATED GAS REGULATOR ECOSYSTEM


FIGURE 23
PILOT-OPERATED GAS REGULATOR ECOSYSTEM ANALYSIS


FIGURE 24
AVERAGE SELLING PRICE TREND OF PILOT-OPERATED GAS REGULATORS WITH DIFFERENT PRESSURE CAPABILITIES, 2022–2025


FIGURE 25
REGION-WISE AVERAGE SELLING PRICE TREND OF PILOT-OPERATED GAS REGULATORS, 2022–2025


FIGURE 26
IMPORT SCENARIO FOR HS CODE 848110-COMPLIANT PRODUCTS IN TOP 5 COUNTRIES, 2021–2025


FIGURE 27
EXPORT SCENARIO FOR HS CODE 848110-COMPLIANT PRODUCTS IN TOP 5 COUNTRIES, 2021–2025


FIGURE 28
TRENDS/DISRUPTIONS INFLUENCING CUSTOMER BUSINESS


FIGURE 29
INVESTMENT AND FUNDING SCENARIO, 2025


FIGURE 30
PATENTS APPLIED AND GRANTED, 2015–2025


FIGURE 31
FUTURE APPLICATIONS OF PILOT-OPERATED GAS REGULATORS


FIGURE 32
REAL-WORLD APPLICATIONS


FIGURE 33
DECISION-MAKING FACTORS IN PILOT OPERTAED GAS REGULATORS MARKET


FIGURE 34
INFLUENCE OF STAKEHOLDERS ON BUYING PROCESS, BY END USER


FIGURE 35
KEY BUYING CRITERIA, BY END USER


FIGURE 36
PILOT-OPERATED GAS REGULATORS ADOPTION BARRIERS AND INTERNAL CHALLENGES


FIGURE 37
PILOT-OPERATED GAS REGULATORS MARKET SHARE, BY PRESSURE, 2025


FIGURE 38
PILOT-OPERATED GAS REGULATORS MARKET SHARE, BY INSTALLATION TYPE, 2025


FIGURE 39
PILOT-OPERATED GAS REGULATORS MARKET SHARE, BY INSTALLATION LOCATION, 2025


FIGURE 40
PILOT-OPERATED GAS REGULATORS MARKET SHARE, BY END USER, 2025


FIGURE 41
INDIA TO REGISTER HIGHEST CAGR IN GLOBAL PILOT-OPERATED GAS REGULATORS MARKET DURING FORECAST PERIOD


FIGURE 42
ASIA PACIFIC HELD LARGEST MARKET SHARE, IN TERMS OF VALUE, IN 2025


FIGURE 43
NORTH AMERICA: PILOT-OPERATED GAS REGULATORS MARKET SNAPSHOT


FIGURE 44
ASIA PACIFIC: PILOT-OPERATED GAS REGULATORS MARKET SNAPSHOT


FIGURE 45
MARKET SHARE ANALYSIS OF COMPANIES PROVIDING PILOT-OPERATED GAS REGULATORS, 2025


FIGURE 46
PILOT-OPERATED GAS REGULATORS MARKET: REVENUE ANALYSIS OF TOP 3 PLAYERS, 2021–2025


FIGURE 47
BRAND COMPARISON


FIGURE 48
PILOT-OPERATED GAS REGULATORS MARKET: COMPANY EVALUATION MATRIX (KEY PLAYERS), 2025


FIGURE 49
PILOT-OPERATED GAS REGULATORS MARKET: COMPANY FOOTPRINT


FIGURE 50
PILOT-OPERATED GAS REGULATORS MARKET: COMPANY EVALUATION MATRIX (STARTUPS/SMES), 2025


FIGURE 51
COMPANY VALUATION


FIGURE 52
FINANCIAL METRICS (EV/EBITDA)


FIGURE 53
EMERSON: COMPANY SNAPSHOT


FIGURE 54
HONEYWELL INTERNATIONAL INC.: COMPANY SNAPSHOT


FIGURE 55
BAKER HUGHES COMPANY: COMPANY SNAPSHOT


FIGURE 56
AXIS SOLUTIONS LIMITED: COMPANY SNAPSHOT


FIGURE 57
PILOT-OPERATED GAS REGULATORS MARKET: RESEARCH DESIGN


FIGURE 58
DATA CAPTURED FROM SECONDARY SOURCES


FIGURE 59
CORE FINDINGS FROM INDUSTRY EXPERTS


FIGURE 60
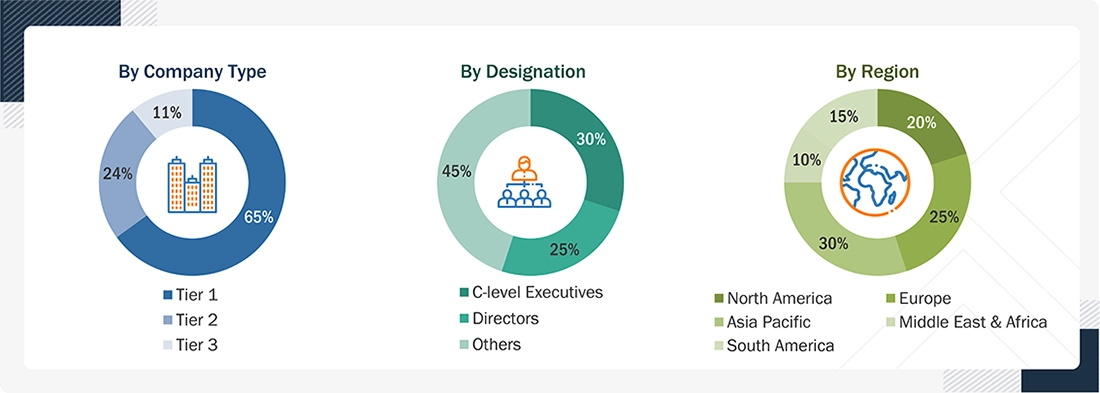
BREAKDOWN OF PRIMARY INTERVIEWS: BY COMPANY TYPE, DESIGNATION, AND REGION


FIGURE 61
PILOT-OPERATED GAS REGULATORS MARKET: BOTTOM-UP APPROACH


FIGURE 62
PILOT-OPERATED GAS REGULATORS MARKET: TOP-DOWN APPROACH


FIGURE 63
KEY METRICS CONSIDERED TO ANALYZE DEMAND FOR PILOT-OPERATED GAS REGULATORS


FIGURE 64
KEY METRICS CONSIDERED TO ASSESS SUPPLY OF PILOT-OPERATED GAS REGULATORS


FIGURE 65
PILOT-OPERATED GAS REGULATORS MARKET: SUPPLY-SIDE ANALYSIS


FIGURE 66
INDUSTRY CONCENTRATION, 2025


FIGURE 67
PILOT-OPERATED GAS REGULATORS MARKET: DATA TRIANGULATION


FIGURE 68
PILOT-OPERATED GAS REGULATORS MARKET: RESEARCH LIMITATIONS


Methodology

The research process for this technical, market-oriented, and commercial study of the pilot-operated gas regulators market involved systematic collection, validation, and analysis of information related to gas pressure regulation technologies, regulator designs, installation types, end-use industries, gas infrastructure development, safety requirements, and digital pressure control systems. Extensive secondary research was conducted using annual reports, investor presentations, product catalogs, technical datasheets, regulatory publications, industry databases, company websites, financial reports, pipeline and gas infrastructure project announcements, and technical publications to identify key market participants, technology trends, market developments, product portfolios, and competitive strategies. The study also analyzed the deployment of pilot-operated gas regulators across gas utilities, oil & gas, power generation, industrial manufacturing, and other end-use industries, with particular emphasis on natural gas transmission and distribution networks, city gas distribution systems, pressure reduction stations, gas processing facilities, and industrial gas infrastructure.

Secondary Research

In the secondary research process, various sources were referred to for identifying and collecting information relevant to the pilot-operated gas regulators market. Secondary sources included annual reports, investor presentations, press releases, company websites, product catalogs and technical datasheets, industry journals, technical papers, regulatory publications, pipeline and gas infrastructure reports, and recognized market databases. Publications and datasets from organizations such as the US Energy Information Administration (EIA), International Energy Agency (IEA), Pipeline and Hazardous Materials Safety Administration (PHMSA), US Department of Transportation (DOT), European Commission, European Union Agency for the Cooperation of Energy Regulators (ACER), International Gas Union (IGU), and International Organization for Standardization (ISO) were reviewed to understand natural gas infrastructure development, pipeline modernization, gas distribution networks, pressure control requirements, safety standards, and emerging hydrogen infrastructure.

Primary Research

During the primary research phase, pilot-operated gas regulator manufacturers, gas utilities, pipeline operators, oil & gas companies, distributors, system integrators, engineering, procurement, and construction (EPC) contractors, maintenance service providers, and industry experts were interviewed to obtain qualitative and quantitative insights into the pilot-operated gas regulators market. Interviews were conducted to validate market estimates, technology adoption, product pricing, installation and replacement trends, regional demand, competitive positioning, supplier selection criteria, and customer purchasing behavior. Discussions with industry participants also helped assess the demand for regulators across gas transmission, gas distribution, city gas distribution, gas processing, power generation, and industrial applications.

A combination of top-down and bottom-up approaches, supported by data triangulation, was used to estimate and forecast the market across all segments and subsegments. Primary interviews helped evaluate the relative contribution of new installations and retrofit projects, as well as the demand for onshore and offshore applications. Respondents also provided insights into key purchasing factors such as pressure accuracy, flow capacity, safety performance, reliability, lifecycle cost, maintenance requirements, certifications, delivery time, and availability of local technical support. Primary research further assessed the impact of pipeline modernization, expansion of natural gas distribution networks, replacement of aging pressure control equipment, digitalization of gas infrastructure, and methane emission reduction requirements on market growth. Interviews also examined the adoption of smart regulators, remote monitoring, SCADA integration, predictive maintenance, low-emission designs, and technologies capable of handling hydrogen-blended gases.

Pilot-Operated Gas Regulators Market Size, and Share

Note: Other designations include sales managers, engineers, and regional managers.
Tier 1 Company Revenue: > USD 5 billion, Tier 2 Company Revenue: between USD 1 and USD 5 billion, and Tier 3 Company Revenue: < USD 1 billion.

To know about the assumptions considered for the study, download the pdf brochure

Market Size Estimation

Both top-down and bottom-up approaches were used to estimate and validate the size of the pilot-operated gas regulators market and its dependent submarkets. The key players in the market were identified through secondary research, and their market shares in the respective regions were obtained through both primary and secondary research. The research methodology includes the study of the annual and financial reports of the top market players and interviews with industry experts, such as chief executive officers, vice presidents, directors, sales managers, and marketing executives, for key quantitative and qualitative insights related to the pilot-operated gas regulators market.

Bottom-up Approach

  • Estimating the pilot-operated gas regulators market size across pressure, installation type, installation location, and end-use industry segments by analyzing revenue generated from pilot-operated gas regulators and consolidating segment-level estimates to derive the overall market size
  • Mapping leading market participants, including Emerson, Honeywell International Inc., Pietro Fiorentini S.P.A, Baker Hughes, Dresser Utility Solutions, Nirmal Industrial Controls Pvt Ltd., Cavagna Group S.P.A, Valvitalia, and other regional and specialized manufacturers
  • Collecting segment-wise revenue and product portfolio information from annual reports, investor presentations, company websites, product catalogs, press releases, regulatory filings, and other publicly available disclosures
  • Estimating demand across major end-use industries, including Gas utilities, oil & gas, power generation, and industrial manufacturing, with further assessment of demand from gas transmission and distribution networks, city gas distribution systems, pressure reduction stations, gas processing facilities, and industrial gas applications based on pipeline additions, infrastructure modernization, regulator installations, replacement cycles, and gas consumption trends
  • Estimating market demand across major installation types and locations, including new installation and retrofit, as well as onshore and offshore locations, using manufacturer product portfolios, regulator deployment data, pipeline and gas infrastructure projects, replacement requirements, utility investment plans, and regional adoption trends
  • Incorporating qualitative factors, including natural gas infrastructure expansion, pipeline modernization, gas utility investments, pressure and safety regulations, methane emission reduction requirements, aging infrastructure, digitalization of gas networks, SCADA integration, smart pressure control technologies, hydrogen and hydrogen-blended gas adoption, technology advancements, and maintenance requirements into the market forecasting model

Top-down Approach

  • Estimating the overall global pilot-operated gas regulators market by analyzing natural gas infrastructure investments, gas transmission and distribution network expansion, city gas distribution development, regulator installations, replacement of aging pressure control equipment, and demand for reliable pressure management across gas infrastructure
  • Allocating the market across installation type (new installation and retrofit), installation location (onshore and offshore), and end-use industry (gas utilities, oil & gas, power generation, industrial manufacturing, and other end-use industries) using regional infrastructure development, regulator deployment trends, manufacturer product portfolios, pipeline projects, replacement cycles, and industry data
  • Distributing market estimates across North America, Europe, Asia Pacific, South America, and the Middle East & Africa based on natural gas pipeline length and expansion, gas distribution infrastructure investments, city gas distribution projects, LNG and gas processing developments, installed regulator base, replacement demand, and regional adoption of advanced pressure control technologies
  • Validating the final market estimates through primary interviews with pilot-operated gas regulator manufacturers, gas utilities, pipeline operators, distributors, EPC contractors, system integrators, and industry experts. Primary discussions are used to validate regional sales trends, installation and retrofit activity, pricing, product preferences, technology adoption, replacement cycles, and customer purchasing criteria, followed by data triangulation across company disclosures, industry databases, government statistics, infrastructure project data, and secondary research to ensure consistency and accuracy. 

Pilot-Operated Gas Regulators Market : Top-Down and Bottom-Up Approach
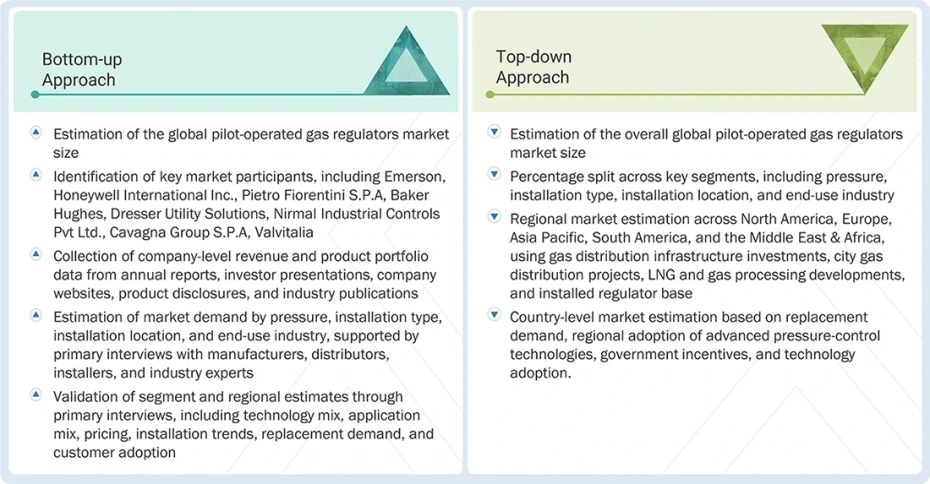
Pilot-Operated Gas Regulators Market Top Down and Bottom Up Approach

Data Triangulation

The process of determining the overall market size involved the methodologies described earlier, followed by segmenting the market into multiple segments and subsegments. To finalize the comprehensive market analysis and obtain precise statistics for each market segment and subsegment, data triangulation and market breakdown procedures were applied, wherever appropriate. Data triangulation was accomplished by examining factors and trends from both the demand and supply sides of the pilot-operated gas regulator ecosystem, including regulator sales and installations, pipeline and gas distribution infrastructure investments, manufacturer revenues and product portfolios, replacement of aging pressure-control equipment, new gas infrastructure projects, gas utility investments, technology adoption, and regional market dynamics.

Market Definition

Pilot-operated gas regulators are pressure control devices designed to regulate and maintain the downstream pressure of natural gas and other compatible gaseous fuels across transmission, distribution, industrial, and commercial applications. Unlike direct-acting regulators, pilot-operated regulators use a separate pilot mechanism to control the main valve, enabling precise pressure regulation and high flow capacity across varying inlet pressures and demand conditions. Pilot-operated regulators considered in this study typically consist of a main regulator valve, pilot valve, sensing line, diaphragm or actuator assembly, spring mechanism, and associated control and safety components. These regulators are widely used in gas transmission and distribution networks, city gate stations, industrial gas supply systems, power generation facilities, LNG infrastructure, and other applications requiring stable and reliable gas pressure.  

Key Stakeholders

  • Government and research organizations
  • Institutional investors and investment banks
  • Investors/shareholders
  • Environmental research institutes
  • Consulting companies (energy & power sector)
  • Pilot-operated gas regulator raw materials and component manufacturers
  • Pilot-operated gas regulator manufacturers, dealers, and suppliers
  • Manufacturing industry players
  • Energy-efficiency consultancies
  • Gas utilities and distribution network operators

Report Objectives

  • To describe and forecast the pilot-operated gas regulator market, by pressure, installation type, installation location, and end use industry, in terms of value
  • To forecast the market size for five key regions: North America, Europe, Asia Pacific, the Middle East & Africa, and South America, along with their key countries, in terms of value
  • To describe and forecast the pilot-operated gas regulator market, by region, in terms of volume
  • To provide detailed information about the key factors, such as drivers, restraints, opportunities, and challenges, influencing market growth
  • To strategically analyze the subsegments with respect to individual growth trends, prospects, and contributions of each segment to the overall market size
  • To study the complete supply chain and allied industry segments, and perform a supply chain analysis of the pilot-operated gas regulator market landscape
  • To provide a detailed overview of the unmet needs and white spaces, interconnected markets and cross-sector opportunities, strategic moves by tier 1/2/3 players, pilot-operated gas regulator value chain analysis, ecosystem analysis, key conferences and events, key stakeholders and buying criteria, patent analysis, trends/disruptions impacting customer business, trade analysis, tariff analysis, investment and funding scenario, technology analysis, technology/product roadmap, case study analysis, regulations, future applications, macroeconomic outlook, pricing analysis, Porter’s five forces analysis, sustainability initiatives, adoption barriers and internal challenges, market profitability, impact of regulatory policies on sustainability initiatives, certifications, labeling and eco-standards, decision-making process, the impact of AI/Gen AI, and the impact of US tariffs   
  • To analyze competitive developments such as acquisitions, product launches, collaborations, partnerships, announcements, expansions, and agreements in the market

Available customizations:

With the given market data, MarketsandMarkets offers customizations based on the company’s specific needs. The following customization options are available for the report:

Product Analysis

  • Product Matrix, which provides a detailed comparison of the product portfolio of each company

Company Information

  • Detailed analyses and profiling of additional market players (up to 5)


Personalize This Research

  • Triangulate with your Own Data
  • Get Data as per your Format and Definition
  • Gain a Deeper Dive on a Specific Application, Geography, Customer or Competitor
  • Any level of Personalization
Request A Free Customisation

Let Us Help You

  • What are the Known and Unknown Adjacencies Impacting the Pilot Operated Gas Regulators Market
  • What will your New Revenue Sources be?
  • Who will be your Top Customer; what will make them switch?
  • Defend your Market Share or Win Competitors
  • Get a Scorecard for Target Partners
Customized Workshop Request

Custom Market Research Services

We Will Customise The Research For You, In Case The Report Listed Above Does Not Meet With Your Requirements

Get 10% Free Customisation

TESTIMONIALS

Growth opportunities and latent adjacency in Pilot Operated Gas Regulators Market

DMCA.com Protection Status
popup img