Recreational Boat Market by Boat Type (Yacht & Cruiser, Sailboat, Personal Watercraft, Fishing, Pontoon, Others), Boat Size, Engine Location, Propulsion, Material, Hull Design, Electric, Power Output, Distribution Channel, Region - Global Forecast to 2033

icon1
USD 48.06 BN
MARKET SIZE, 2033
icon2
CAGR 6.3%
(2026-2033)
icon3
350
REPORT PAGES
icon4
230
MARKET TABLES

OVERVIEW

recreational-boats-market Overview

Source: Secondary Research, Interviews with Experts, MarketsandMarkets Analysis

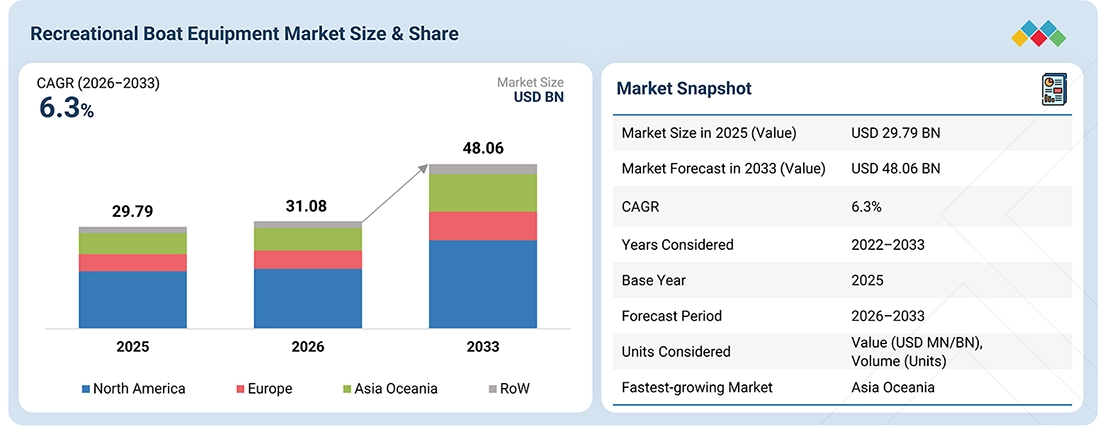
The recreational boat market is projected to grow from USD 31.38 billion in 2026 to USD 48.06 billion by 2033, at a CAGR of 6.3%, The market is driven by consumer spending on leisure activities, recreational fishing, watersports, coastal tourism, and boating experiences, with demand spanning fishing boats, pontoons, personal watercraft, bowriders, cruisers, sailboats, and luxury yachts. Growth opportunities for manufacturers lie in offering fuel-efficient outboard-powered boats, improved onboard connectivity and navigation, advanced safety features, hybrid and electric propulsion, and customizable designs that enhance convenience and the ownership experience.

KEY TAKEAWAYS

  • BY REGION
    By region, North America is estimated to account for >50% of the global recreational boat market in 2026.
  • BY BOAT TYPE
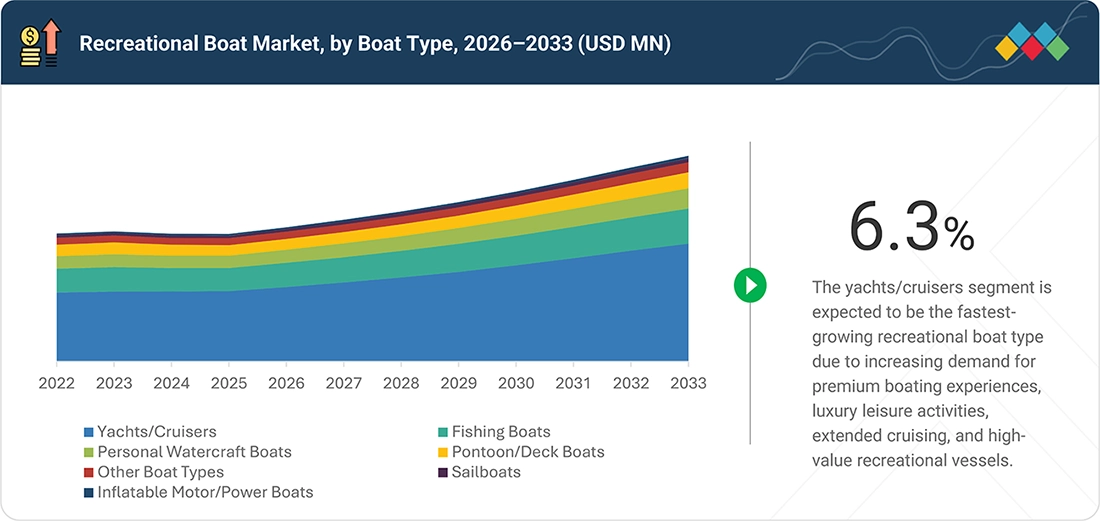
    By boat type, the yachts/cruisers segment is projected to grow at a CAGR of >5% during the forecast period, as they support high-speed recreational activities and watersports through compact, easy-to-operate designs, with growing demand for jet skis, sit-down and stand-up watercraft, and rental-based leisure experiences driving adoption across coastal, lake, and inland-water destinations.
  • BY HULL DESIGN
    By hull design, the planning hulls segment is likely to hold a 75% market share in 2026. Their dominance is supported by widespread use in powerboats, personal watercraft, and other recreational vessels, where high speed, maneuverability, and suitability for short-distance leisure activities are important purchase factors.
  • BY BOAT SIZE
    By boat size, the 30–50 feet segment is anticipated to exhibit a CAGR of >7% between 2026 and 2033, driven by rising demand for luxury yachts, premium onboard amenities, extended cruising experiences, and customized recreational vessels
  • BY MATERIAL TYPE
    By material type, the fiberglass holds the largest market share due to its high strength-to-weight ratio, corrosion resistance, design flexibility, and relatively low maintenance requirements.
  • BY ENGINE LOCATION
    By engine location, the outboard engine boats segment accounts for a major market share due to the fuel efficiency, easy maintenance, lower installation complexity, and space-saving design.
  • BY ENGINE TYPE
    By engine type, the electric segment is projected to grow at a CAGR of >5% during the forecast period, driven by stricter emission regulations, rising demand for sustainable boating, and lower operating and maintenance costs.
  • BY POWER RANGE
    By power range, the 100–200 kW segment holds the largest market share as it strikes the ideal balance between performance, fuel/operational efficiency, and versatility for mid-sized vessels.
  • BY DISTRIBUTION CHANNEL
    By distribution channel, the online boat sales segment is likely to record a CAGR of >6% during the forecast period, as manufacturers and buyers bypass traditional large-scale dealership networks and store maintenance costs, which significantly reduces intermediate markups and increases affordability.
  • COMPETITIVE LANDSCAPE - KEY PLAYERS
    Key players such as Brunswick Corporation (US), Yamaha Motor (Japan), Groupe Beneteau (France), Ferretti Group (Italy), and Azimut Benetti Group (Italy) are focusing on electric and hybrid propulsion, autonomous docking, advanced joystick controls, and connected vessel-management technologies. Brunswick is advancing Avator electrification and autonomous navigation, while Yamaha is expanding its Helm Master EX platform. Groupe Beneteau is developing electric and hybrid boats, whereas Ferretti Group and Azimut Benetti are strengthening their positions through hybrid propulsion, sustainable yacht designs, and integrated onboard automation. These initiatives highlight the industry's focus on improving vessel efficiency, performance, safety, and onboard experience.
  • COMPETITIVE LANDSCAPE - STARTUP/SMES
    Smoker Craft Inc. and Ocean Alexander, among other specialized recreational boat manufacturers, have established positions in fishing, family-oriented boating and premium luxury yacht applications, highlighting their potential as emerging market participants in the recreational boat market.

There is a key strategic shift in the recreational boat market from conventional gasoline and diesel powered vessels toward electrified, hybrid, digitally connected, and software-enabled boats. Internal-combustion propulsion remains crucial due to established refueling infrastructure, long range, and suitability for offshore and towing applications. However, emission regulations, noise reduction, lower operating costs, and demand for smarter onboard experiences are boosting the adoption of electric outboards, hybrid sailboats, electric pontoons, and connected vessel technologies. OEMs are integrating battery management, digital displays, remote diagnostics, predictive maintenance, and assisted navigation to improve safety, utilization, and ownership experience. The key opportunity is to combine boatbuilding, electrification, connectivity, and aftermarket services to reduce total cost of ownership. High upfront costs, limited charging infrastructure, restricted range, battery weight, and performance requirements in offshore and adverse conditions remain major adoption challenges.

TRENDS & DISRUPTIONS IMPACTING CUSTOMERS' CUSTOMERS

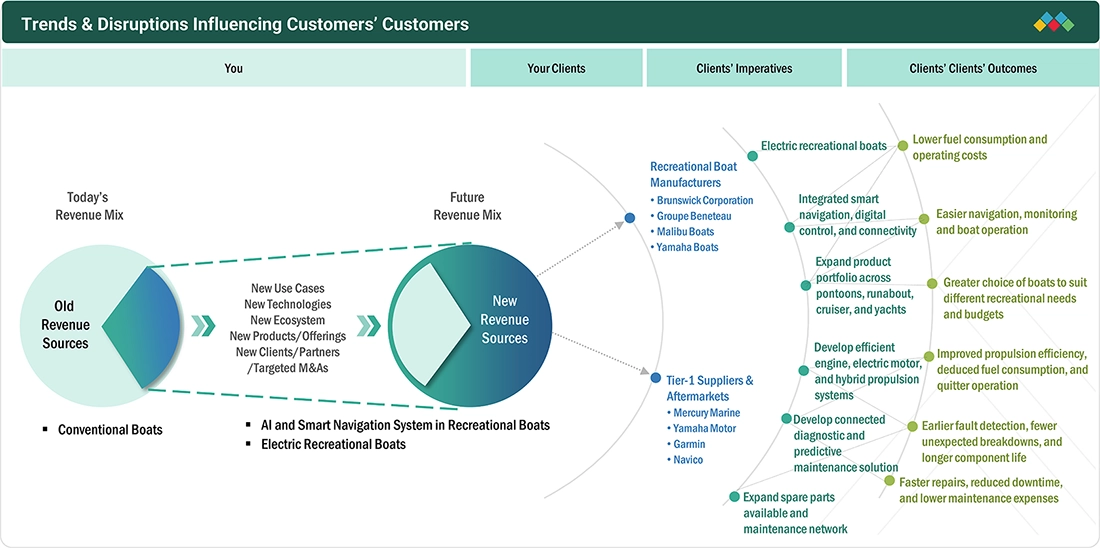
Changes in recreational boating preferences, propulsion technologies, and marine operating requirements are directly influencing recreational boat manufacturers and Tier-1 suppliers. The growing adoption of electric and hybrid propulsion, connected marine electronics, advanced navigation systems, digital helm controls, and energy-efficient hull designs is increasing demand for high-performance, fuel-efficient, and technologically advanced boats that improve onboard comfort, safety, maneuverability, and ownership economics. These shifts are cascading across the value chain, from engine, battery, marine electronics, and component suppliers to boat manufacturers and end users, while creating opportunities for electric pontoons, premium cruisers, sport boats, yachts, integrated navigation systems, and connected boating solutions. At the same time, the integration of boats with digital monitoring platforms, assisted docking, onboard diagnostics, and remote connectivity is encouraging manufacturers to move beyond conventional vessel sales toward integrated propulsion, technology, customization, and lifecycle-service offerings. However, high upfront costs, limited charging infrastructure, battery range constraints, maintenance requirements, and varying boating regulations continue to influence technology adoption, creating a market in which conventional gasoline-powered boats coexist with increasingly electrified, connected, and digitally enabled recreational vessels.

recreational-boats-market Disruptions

Source: Secondary Research, Interviews with Experts, MarketsandMarkets Analysis

MARKET DYNAMICS

Drivers
Impact
Level
  • Convergence of smart vessel architecture, versatile hull designs, and advanced onboard systems
  • Advancements in high-horsepower outboards and integrated propulsion systems
RESTRAINTS
Impact
Level
  • High ownership and lifecycle costs reinforced by regulatory and design constraints
OPPORTUNITIES
Impact
Level
  • Affordable and entry-level and EV & hybrid recreational boat development 
  • Integrated smart boat systems and advanced propulsion package challenges
CHALLENGES
Impact
Level
  • Powertrain electrification without compromising range, payload, and performance
  • Managing product complexity, regulatory compliance, and long-term reliability

Source: Secondary Research, Interviews with Experts, MarketsandMarkets Analysis

Driver: Convergence of smart vessel architecture, versatile hull designs, and advanced onboard systems

The convergence of smart vessel architecture, versatile hull designs, and advanced onboard systems is driving the recreational boats market by improving vessel stability, fuel efficiency, maneuverability, and passenger comfort. The integration of digital helm controls, connected navigation, onboard monitoring, and modular layouts is enabling manufacturers to deliver safer, more adaptable, and technologically advanced boats that meet evolving recreational and premium boating preferences.

Restraint: High ownership and lifecycle costs reinforced by regulatory and design constraints

High upfront purchase prices, fuel expenses, insurance, maintenance, storage, and servicing costs constrain recreational boat ownership and limit adoption among price-sensitive buyers. These lifecycle costs are further reinforced by stringent marine emission and safety regulations, design limitations, and the high cost of integrating advanced propulsion and onboard technologies, increasing manufacturing expenses and making ownership less accessible to a broader customer base.

Opportunity: Affordable and entry-level and EV & hybrid recreational boat development 

The development of affordable, entry-level electric and hybrid recreational boats presents an opportunity for manufacturers to expand their customer base and tap into emerging demand for accessible and sustainable boating. OEMs can particularly target compact personal watercraft (PWC), entry-level fishing boats, aluminum fishing boats, small pontoon boats, and recreational tenders, which cater to first-time buyers. Cost-optimized hull designs, lightweight materials, modular battery systems, and efficient electric propulsion can reduce upfront ownership and operating costs, particularly for short-distance recreational activities. These offerings would enable manufacturers to penetrate price-sensitive customer segments, increase electric boating adoption, diversify their product portfolios, and unlock additional growth opportunities.

Challenge: Managing product complexity, regulatory compliance, and long-term reliability

Managing product complexity, regulatory compliance, and long-term reliability remains a key challenge in the recreational boat market. Manufacturers must integrate advanced propulsion systems, marine electronics, safety features, and onboard technologies while meeting varying environmental and maritime regulations across regions. Ensuring durability in harsh marine conditions, minimizing maintenance requirements, and maintaining consistent product quality increase engineering costs and development timelines, putting pressure on manufacturers to balance innovation, compliance, reliability, and affordability.

RECREATIONAL BOAT MARKET: COMMERCIAL USE CASES ACROSS INDUSTRIES

COMPANY USE CASE DESCRIPTION BENEFITS
company logo
In October 2025, Brunswick introduced the Simrad AutoCaptain autonomous boating system, integrating Mercury Marine propulsion, cameras, and marine electronics to automate docking, undocking, and short-distance maneuvering. Reduces the complexity of close-quarters maneuvering | Improves situational awareness | Helps less-experienced boaters dock with greater confidence
company logo
In September 2026, BENETEAU unveiled the Swift Trawler 43 and Gran Turismo 40 Open, expanding its motorboat portfolio with models designed for cruising and recreational use. Broadens customer choice across cruising and leisure boating, supporting different onboard comfort, performance, and recreational requirements
company logo
In February 2025, Yamaha introduced the Helm Master EX Wireless Control System, enabling joystick control, autopilot functions, and man-overboard safety features from different positions around the vessel. Improves maneuverability and operational convenience | Enables easier close-quarters handling | Strengthens onboard safety
company logo
In September 2025, Ferretti Group showcased its sustainable propulsion technologies, including the Riva El-Iseo fully electric powerboat and hybrid propulsion solutions developed in collaboration with Rolls-Royce Power Systems for future yachts. Reduces propulsion-related emissions | Supports quieter and more efficient cruising | Expands sustainable luxury boating options | Strengthens the Group's position in electric and hybrid yacht technologies.

Logos and trademarks shown above are the property of their respective owners. Their use here is for informational and illustrative purposes only.

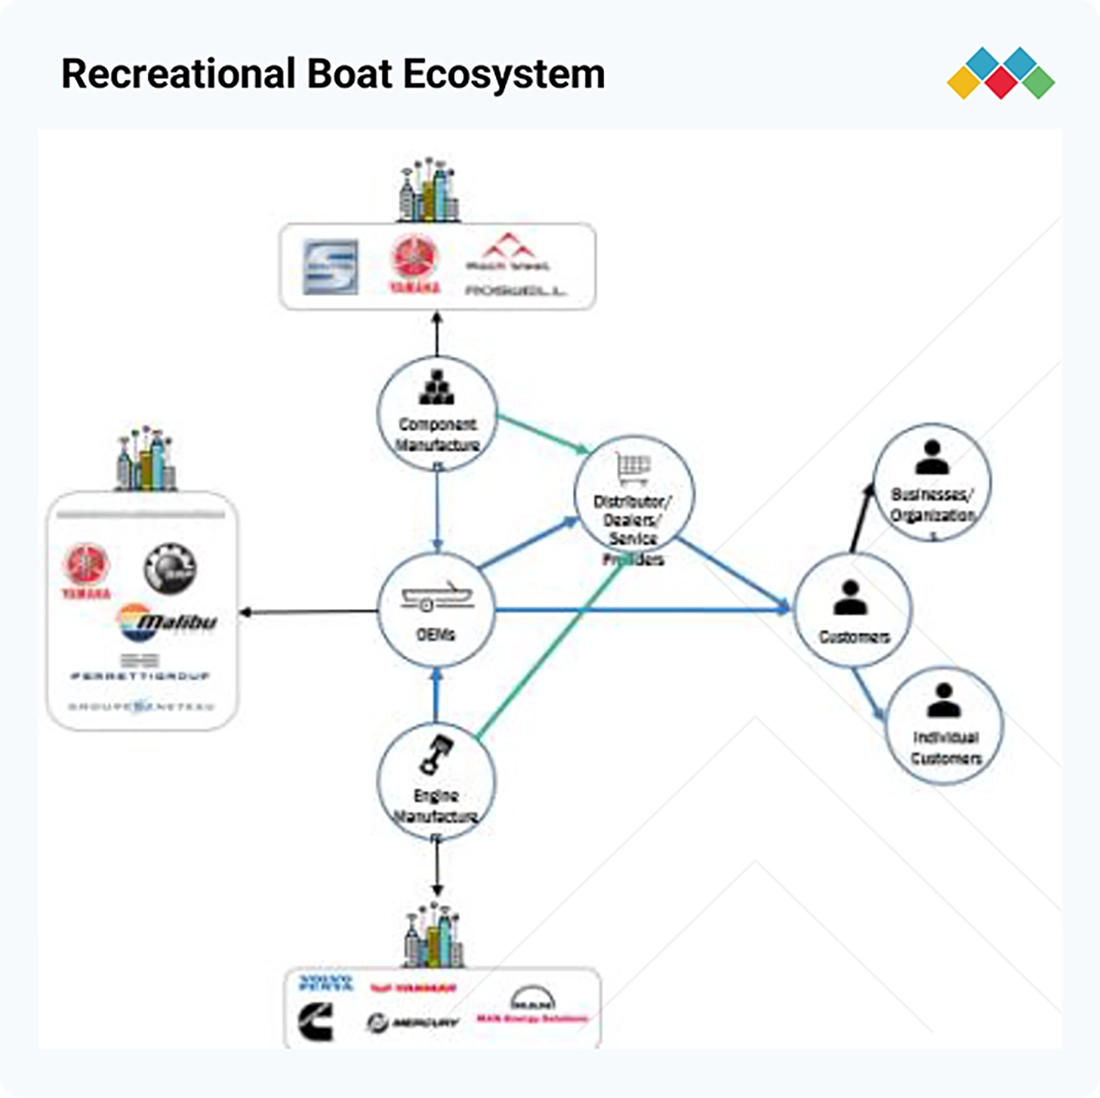
MARKET ECOSYSTEM

The recreational boat ecosystem comprises raw material and component suppliers, propulsion and marine technology providers, boat manufacturers (OEMs), sales and distribution channels, end users, and aftermarket service providers. Key players such as Brunswick Corporation (US), Yamaha Motor (Japan), Groupe Beneteau (France), Ferretti Group (Italy), and Azimut Benetti Group (Italy) offer recreational boats spanning motorboats, sailing boats, fishing boats, pontoon boats, cruisers, personal watercraft, and luxury yachts. Raw material and component suppliers provide fiberglass, composites, aluminum, resins, marine engines, propulsion systems, batteries, steering systems, navigation equipment, and onboard electronics, while technology providers support electric propulsion, connected vessels, digital navigation, safety systems, and onboard automation. Private boat owners, recreational anglers, watersports enthusiasts, yacht owners, and charter and rental operators drive demand based on leisure activities, boating tourism, vessel performance, comfort, and ownership costs. Authorized dealers, distributors, boat brokers, marinas, and aftermarket service providers support boat sales, financing, maintenance, repairs, spare parts, refits, and upgrades throughout the vessel lifecycle. Continuous feedback on customer preferences, vessel performance, operating costs, sustainability requirements, and emerging marine technologies encourages OEMs and suppliers to improve fuel efficiency, safety, onboard comfort, propulsion performance, and ownership economics across the market.

recreational-boats-market Ecosystem

Logos and trademarks shown above are the property of their respective owners. Their use here is for informational and illustrative purposes only.

MARKET SEGMENTS

recreational-boats-market Segments

Source: Secondary Research, Interviews with Experts, MarketsandMarkets Analysis

Recreational Boat Market, By Boat Type

Demand for yachts and cruisers is supported by growing interest in luxury cruising, coastal tourism, extended leisure voyages, family recreation, and premium onboard experiences. Manufacturers are expanding their product portfolios across motor yachts, sailing yachts, sport cruisers, express cruisers, and flybridge yachts to address varying consumer preferences, vessel-size requirements, onboard comfort, performance expectations, and spending capacity

Recreational Boat Market, By Hull Design

Monohull boats benefit from broad adoption across fishing, cruising, and general recreational boating due to their versatile design and established manufacturing base, while multihull boats attract buyers seeking greater stability, spacious layouts, and comfort. Demand for different hull configurations is influenced by vessel size, intended use, handling characteristics, fuel efficiency, and offshore performance requirements.

Recreational Boat Market, By Boat Size

Boats below 30 feet benefit from relatively affordable purchase prices, easier storage, and suitability for fishing and day trips, while 30–50-foot boats appeal to consumers seeking greater onboard comfort and extended recreational use. Boats above 50 feet serve the premium segment through spacious accommodation, luxury amenities, and long-range cruising capabilities, supported by demand from affluent buyers and charter operators.

Recreational Boat Market, By Material Type

Fiberglass remains widely adopted in recreational boat manufacturing due to its design flexibility, corrosion resistance, durability, and ability to support complex hull shapes, while aluminum is preferred in selected fishing and utility-oriented applications due to its lightweight construction and recyclability. Manufacturers are also exploring advanced composites and improved material designs to reduce vessel weight, improve performance, and lower lifecycle maintenance requirements.

Recreational Boat Market, By Engine Location

Outboard engines benefit from broad adoption due to easier maintenance, convenient replacement, and improved usable space within the boat, supporting demand across fishing boats, pontoons, and smaller recreational motorboats. Inboard and sterndrive configurations remain relevant for larger cruisers, watersports boats, and applications requiring specific performance, handling, or onboard layout characteristics

Recreational Boat Market, By Engine Type

Internal combustion (IC) engines continue to support recreational boating through established refueling infrastructure, extended range, and proven performance across multiple vessel categories. Electric and hybrid propulsion are gaining attention for reduced operating noise, lower direct emissions, and improved efficiency in suitable applications, encouraging manufacturers to develop electrified boats, battery systems, and compatible charging solutions while addressing range, charging access, and upfront cost constraints.

Recreational Boat Market, By Power Range

Recreational boats with lower power output are widely used for fishing, leisure cruising, and small-vessel applications, benefiting from lower acquisition costs, fuel consumption, and maintenance requirements. Higher-power boats support larger vessels, watersports, offshore activities, and premium cruising, with demand driven by requirements for greater speed, load capacity, acceleration, and long-distance performance.

Recreational Boat Market, By Distribution Channel

Authorized dealerships remain an important distribution channel for recreational boats by providing product demonstrations, financing assistance, customization, warranty support, and after-sales services. Online platforms, direct manufacturer sales, and independent brokers are expanding customer access and purchase flexibility, while established dealer networks continue to influence buying decisions through local availability, servicing capabilities, and customer relationships.

REGION

Asia Oceania to grow at fastest rate in recreational boat market during forecast period

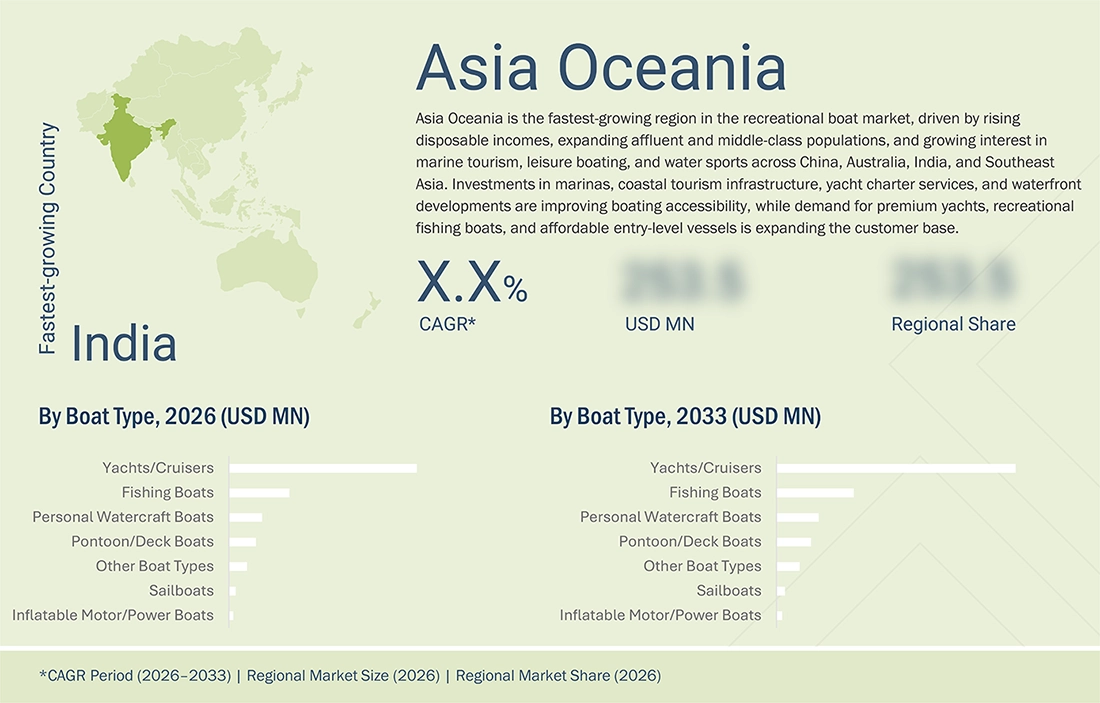
Asia Oceania is the fastest-growing region in the recreational boat market, driven by rising disposable incomes, expanding affluent and middle-class populations, and growing interest in marine tourism, leisure boating, and water sports across China, Australia, India, and Southeast Asia. Investments in marinas, coastal tourism infrastructure, yacht charter services, and waterfront developments are improving boating accessibility, while demand for premium yachts, recreational fishing boats, and affordable entry-level vessels is expanding the customer base. Government initiatives to promote tourism and marine infrastructure, particularly in emerging markets, are further supporting regional growth, creating opportunities for boat manufacturers to expand their presence and introduce products tailored to diverse consumer budgets and recreational preferences.

recreational-boats-market Region

RECREATIONAL BOAT MARKET: COMPANY EVALUATION MATRIX

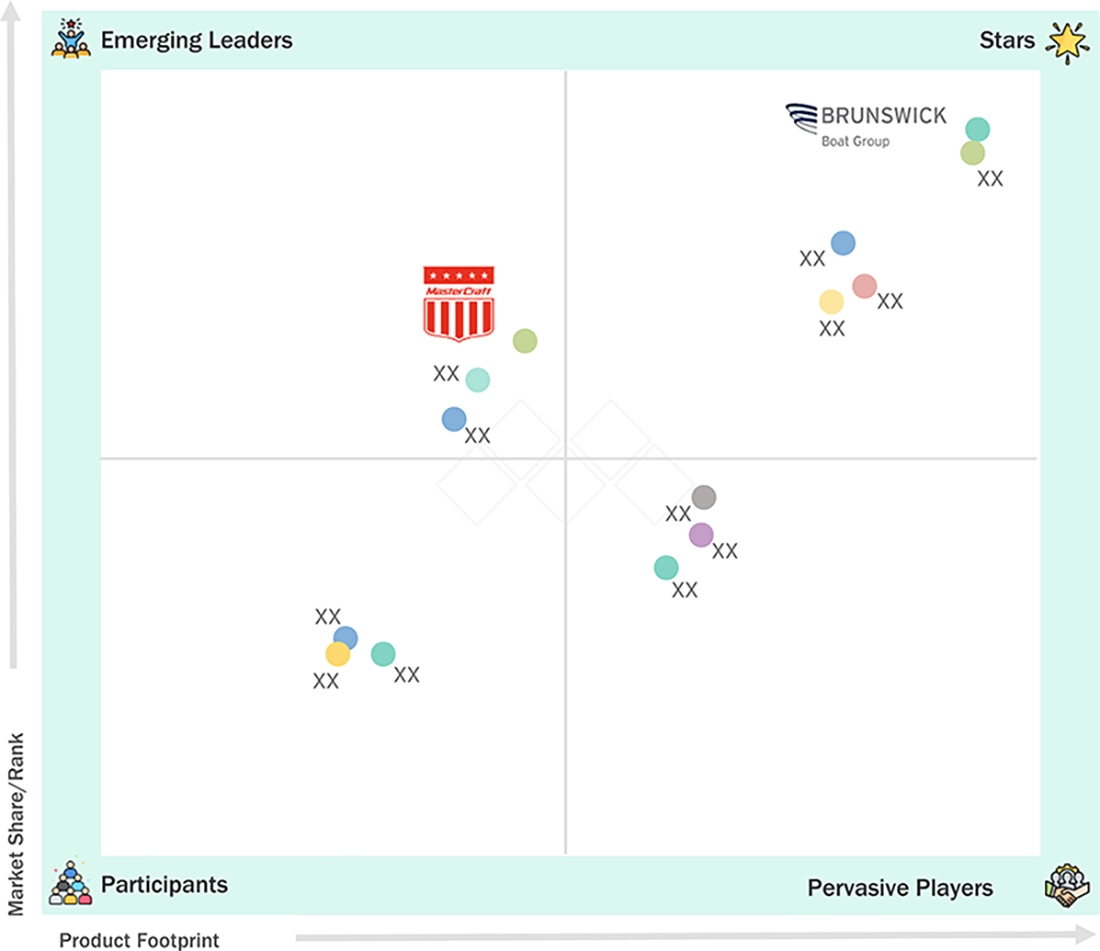
In the recreational boats market matrix, Brunswick Corporation (US) (Star Player) leads through its diversified portfolio of recreational boat brands, marine propulsion systems, and integrated marine technologies, supported by a strong global distribution network and extensive aftermarket services. MasterCraft Boat Holdings (US) (Emerging Player) is strengthening its market position through its specialized portfolio of premium performance, wakeboarding, and watersports boats, supported by innovations in wake-shaping technologies, onboard digital controls, and customizable boating experiences that enhance product differentiation and address demand for premium recreational activities.

recreational-boats-market Evaluation Metrics

Source: Secondary Research, Interviews with Experts, MarketsandMarkets Analysis

MARKET SCOPE

REPORT METRIC DETAILS
Market Size in 2025 (Value) USD 29.79 Billion
Market Size in 2026 (Value) USD 31.38 Billion
Market Forecast in 2033 (Value) USD 48.06 Billion
Growth Rate CAGR of 6.3% from 2026-2033
Years Considered 2022-2033
Base Year 2025
Forecast Period 2026-2033
Units Considered Value (USD Million/Billion), Volume (Units)
Report Coverage Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments Covered
  • By boat type (yachts/cruisers, sailboats, personal watercraft boats, inflatable motor boats/power boats, pontoon/ deck boats, fishing boats, and other boat types)
  • By boat size (<30 feet boats, 30-50 feet boats, and >50 feet boats)
  • By material type (aluminum, steel boats, fiberglass boats, and other material types)
  • By engine location (outboard engine boats, inboard engine boats, and other engine locations)
  • By engine type (ICE and electric)
  • By power range (below 100 kW, 100-200 kW, and above 200 kW)
  • By distribution channel (boat dealership, boat shows, and online boat sales)
  • By hull design (planning hulls, displacement hulls, and semi-displacement hulls)
Regions Covered North America, Asia Oceania, Europe, and RoW

WHAT IS IN IT FOR YOU: RECREATIONAL BOAT MARKET REPORT CONTENT GUIDE

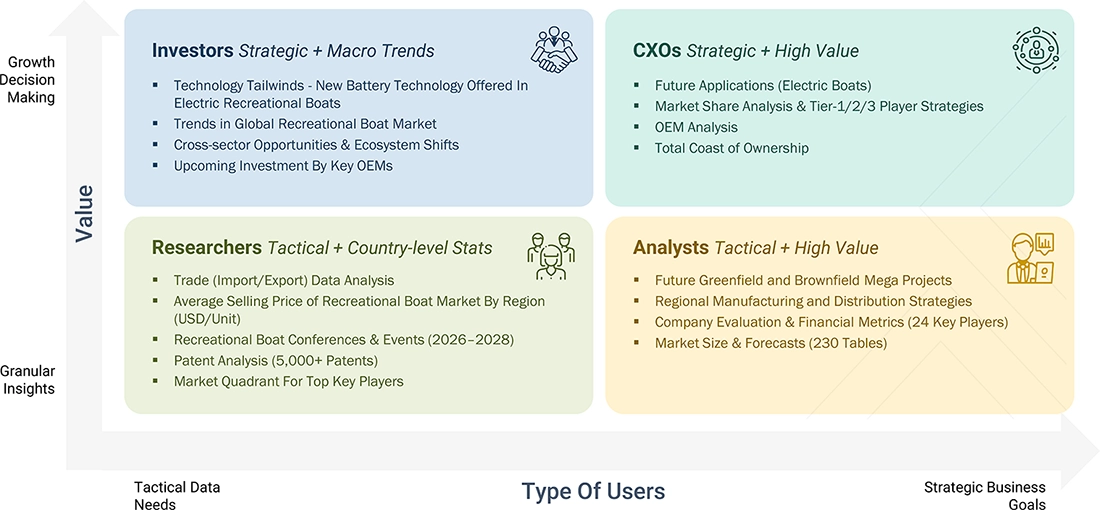
recreational-boats-market Content Guide

DELIVERED CUSTOMIZATIONS

We have successfully delivered the following deep-dive customizations:

CLIENT REQUEST CUSTOMIZATION DELIVERED VALUE ADDS
Country- and region-wise recreational boats market outlook Developed country- and regional-level market sizing and forecasts, covering recreational boats by boat type, hull design, boat size, engine location, engine type, and propulsion system. Enabled the client to identify high-growth markets and prioritize regional expansion, distribution development, manufacturing capacity, and investment opportunities
Competitive benchmarking of leading recreational boat manufacturers Created a competitive benchmarking matrix covering Brunswick Corporation, Groupe Beneteau, Yamaha Motor Company, MasterCraft Boat Holdings, Malibu Boats, and other key manufacturers based on product portfolio, propulsion technologies, innovation, brand positioning, and geographic presence. Provided insights into competitor positioning, portfolio strengths, technological differentiation, and regional capabilities to identify competitive gaps and opportunities for market expansion
Identification of future customer segments and OEM sourcing opportunities Assessed demand across individual boat owners, premium leisure consumers, yacht owners, watersports enthusiasts, and charter and rental operators, alongside dealer networks, marina partnerships, and marine component suppliers. Helped identify high-potential customer segments, distribution partnerships, supplier opportunities, and product categories for portfolio expansion and revenue diversification.
Assessment of advanced recreational boat technologies and electrification opportunities Evaluated conventional, electric, and hybrid propulsion systems, battery technologies, connected marine electronics, advanced hull designs, digital helm controls, and onboard energy-management solutions. Enabled the client to assess emerging technology opportunities, prioritize product development, and identify pathways to improve fuel efficiency, reduce emissions, and differentiate its offerings.
Evaluation of smart boating, digitalization, and next-generation onboard systems Analyzed connected navigation, GPS and sonar integration, digital monitoring, assisted docking, onboard diagnostics, and advanced safety technologies across recreational boat categories. Helped the client identify opportunities to enhance boating safety, convenience, vessel performance, and customer experience while expanding connected services and aftermarket revenue streams.

RECENT DEVELOPMENTS

  • September 2026 : Brunswick Corporation, through its NAVAN Boats brand, launched the C38 exploration boat, featuring its T-Step Hull design and a modular aft section configurable for fishing, cruising, and cooking.
  • September 2026 : Yamaha introduced an upgraded version of its 33-foot flagship fishing boat with premium interior trim, dedicated seating, integrated Helm Master EX and bow-thruster controls, an optional Wireless Station, and Wave Assist for adjusting outboard output when crossing waves.
  • September 2026 : Groupe Beneteau, through BENETEAU, announced the First 36 Spirit, a new addition to its performance-sailing range for the 2026–2027 season.
  • August 2026 : Yamaha unveiled four new 20-foot sport boats for the 2027 model year. The lineup combines marine engines and jet propulsion with a compact design for towing and storage. The 205XD targets wake sports, and the lineup introduces single-engine DRiVE control. Availability was announced for Q1 2027.
  • March 2026 : Malibu Boats, Inc. acquired Saxdor Yachts for approximately USD 175 million. The acquisition adds Saxdor’s premium adventure dayboats to Malibu’s recreational powerboat portfolio and establishes a broader European manufacturing and distribution platform. Saxdor operates manufacturing facilities in Finland and Poland and distributes through more than 100 dealer locations across over 50 countries. The acquisition supports Malibu’s strategy to expand internationally and diversify beyond its established performance-sport boat segments.
  • March 2026 : Malibu Boats, Inc. acquired Saxdor Yachts for approximately USD 175 million. The acquisition adds Saxdor’s premium adventure dayboats to Malibu’s recreational powerboat portfolio and establishes a broader European manufacturing and distribution platform. Saxdor operates manufacturing facilities in Finland and Poland and distributes through more than 100 dealer locations across over 50 countries. The acquisition supports Malibu’s strategy to expand internationally and diversify beyond its established performance-sport boat segments.


Table of Contents

checkmarkExclusive indicates content/data unique to MarketsandMarkets and not available with any competitors.

TITLE
PAGE NO
1
INTRODUCTION


15
2
EXECUTIVE SUMMARY


3
PREMIUM INSIGHTS


4
MARKET OVERVIEW
This section summarizes market dynamics, key shifts, and high-impact trends shaping demand outlook.


4.1
INTRODUCTION


4.2
MARKET DYNAMICS


4.2.1
DRIVERS


4.2.1.1
CONVERGENCE OF SMART VESSEL ARCHITECTURE, VERSATILE HULL DESIGNS, AND ADVANCED ONBOARD SYSTEMS


4.2.1.2
ADVANCEMENTS IN HIGH-HORSEPOWER OUTBOARDS AND INTEGRATED PROPULSION SYSTEMS


4.2.2
RESTRAINTS


4.2.2.1
HIGH OWNERSHIP AND LIFECYCLE COSTS REINFORCED BY REGULATORY AND DESIGN CONSTRAINTS


4.2.3
OPPORTUNITIES


4.2.3.1
AFFORDABLE AND ENTRY-LEVEL RECREATIONAL BOAT WITH EV AND HYBRID BOAT DEVELOPMENT


4.2.3.2
INTEGRATED SMART BOAT SYSTEMS AND ADVANCED PROPULSION PACKAGE CHALLENGES


4.2.4
CHALLENGES


4.2.4.1
POWERTRAIN ELECTRIFICATION WITHOUT COMPROMISING RANGE, PAYLOAD, AND PERFORMANCE


4.2.4.2
MANAGING PRODUCT COMPLEXITY, REGULATORY COMPLIANCE, AND LONG-TERM RELIABILITY
 
 
4.3
UNMET NEEDS AND WHITE SPACES


4.4
INTERCONNECTED MARKETS AND CROSS-SECTOR OPPORTUNITIES


4.5
STRATEGIC MOVES BY TIER-1/2/3 PLAYERS


5
INDUSTRY TRENDS
Presents a concise view of industry direction, strategic priorities, and key indicators influencing market momentum.


5.1
MACROECONOMIC OUTLOOK


5.1.1
INTRODUCTION


5.1.2
GDP TRENDS AND FORECAST


5.1.3
TRENDS IN GLOBAL RECREATIONAL BOAT INDUSTRY


5.2
SUPPLY CHAIN ANALYSIS


5.3
ECOSYSTEM ANALYSIS


5.4
EVOLUTION OF PROPULSION TECHNOLOGIES AND IMPACT ON BOAT DESIGN


5.5
TOTAL COST OF OWNERSHIP


5.3
PRICING ANALYSIS


5.3.1
AVERAGE SELLING PRICE TREND OF KEY PLAYERS, BY BOAT TYPE, 2022–2025


5.3.2
AVERAGE SELLING PRICE, BY ENGINE TYPE, 2022–2025


5.3.3
AVERAGE SELLING PRICE, BY REGION, 2022–2025


5.4
TRADE ANALYSIS


5.5.1
IMPORT SCENARIO (HS CODE 89039100)


5.5.2
EXPORT SCENARIO (HS CODE 89039100)


5.5
KEY CONFERENCES AND EVENTS, 2026–2027


5.6
TRENDS/DISRUPTIONS IMPACTING CUSTOMER BUSINESS


5.7
INVESTMENT AND FUNDING SCENARIO


5.8
CASE STUDY ANALYSIS


5.9
OEM ANALYSIS AND EXPANSION STRATEGIES


5.5.3
OEM’S EV PRODUCT PORTFOLIO BENCHMARKING


5.5.4
EXPANSION STRATEGIES


5.9.1.1
REGIONAL MANUFACTURING AND DISTRIBUTION STRATEGIES


5.9.1.2
EMERGING BOATING MARKETS, LOCALIZATION, EXPORT OPPORTUNITIES, AND AFTERMARKET/SERVICE-NETWORK EXPANSION
 
 
5.10
RECREATIONAL BOAT OEM STRATEGIES AND PORTFOLIO REALIGNMENT


5.10.1
EXPANSION INTO HIGH-GROWTH BOAT CATEGORIES


5.10.2
PREMIUMIZATION WITHIN EXISTING PORTFOLIOS


5.10.3
PLATFORM SHARING, ACQUISITIONS, AND PORTFOLIO GAPS ACROSS FISHING BOATS, PONTOONS, CRUISERS, AND YACHTS


5.11
TOTAL COST OF OWNERSHIP OF EV RECREATIONAL BOAT


6
TECHNOLOGICAL ADVANCEMENTS, AI-DRIVEN IMPACT, PATENTS, INNOVATIONS, AND FUTURE STRATEGIC APPLICATIONS


6.8
TECHNOLOGY ANALYSIS


6.8.1
KEY TECHNOLOGIES


6.8.1.1
ELECTRIC AND HYBRID PROPULSION


6.8.1.2
AUTONOMOUS AND ASSISTED NAVIGATION


6.8.1.3
ADVANCED HULL DESIGN AND LIGHTWEIGHT MATERIALS


6.8.1.4
FOILING AND HYDROFOILS


6.8.1.5
SMART AND CONNECTED BOATS


6.8.2
COMPLEMENTARY TECHNOLOGIES


6.8.2.1
MARINE NAVIGATION AND COMMUNICATION


6.8.2.2
CHARGING INFRASTRUCTURE


6.8.2.3
MARINE CYBERSECURITY


6.8.2.4
TELEMATICS AND DIAGNOSTICS


6.8.3
ADJACENT TECHNOLOGIES


6.8.3.1
BOAT-SHARING AND SUBSCRIPTION PLATFORMS


6.8.3.2
AI-BASED FLEET AND RENTAL MANAGEMENT


6.8.3.3
DRONE-ASSISTED MARINE SERVICES
 
 
6.9
PATENT ANALYSIS


6.10
FUTURE TECHNOLOGIES AUTONOMOUS


6.10.1
RECREATIONAL BOATS


6.10.2
HYBRID MARINE PROPULSION


6.11
IMPACT OF AI/GEN AI ON RECREATIONAL BOAT MARKET


8.1.1.1
TOP USE CASES AND MARKET POTENTIAL


8.1.1.2
BEST PRACTICES FOLLOWED BY MANUFACTURERS IN RECREATIONAL BOAT MARKET


8.1.1.3
CASE STUDIES RELATED TO AI/GEN AI IMPLEMENTATION IN RECREATIONAL BOAT MARKET


8.1.1.4
INTERCONNECTED ECOSYSTEM AND IMPACT ON MARKET PLAYERS


8.1.1.5
CLIENT’S READINESS TO ADOPT AI/GEN AI-INTEGRATED RECREATIONAL BOATS
 
 
6.12
IMPACT OF EU-FTA TRADE DEAL ON RECREATIONAL BOAT MARKET


6.13
IMPACT OF US–ISRAEL IRAN WAR ON RECREATIONAL BOAT MARKET


6.14
RECREATIONAL BOAT PROPULSION TECHNOLOGY EVOLUTION


6.15
MARINE ELECTRIFICATION ARCHITECTURE


7
REGULATORY LANDSCAPE


7.1
REGIONAL REGULATIONS AND COMPLIANCE


7.8.1
REGULATORY BODIES, GOVERNMENT AGENCIES, AND OTHER ORGANIZATIONS


8.1.1.6
NORTH AMERICA


8.1.1.7
EUROPE


8.1.1.8
ASIA PACIFIC
 
8
CUSTOMER LANDSCAPE AND BUYER BEHAVIOR


8.2
DECISION-MAKING PROCESS


8.3
KEY STAKEHOLDERS INVOLVED IN BUYING PROCESS AND THEIR EVALUATION CRITERIA


7.8.2
KEY STAKEHOLDERS IN BUYING PROCESS


7.8.3
BUYING CRITERIA


8.4
ADOPTION BARRIERS AND INTERNAL CHALLENGES


8.5
UNMET NEEDS OF VARIOUS END-USE INDUSTRIES


8.6
MARKET PROFITABILITY


9
RECREATIONAL BOAT MARKET, BY BOAT TYPE (MARKET SIZE & FORECAST TO 2032 – IN VALUE, USD MILLION & VOLUME, UNITS)


9.1
INTRODUCTION


9.2
YACHTS/CRUISERS


9.3
SAILBOATS


9.4
PERSONAL WATERCRAFT BOATS


9.5
INFLATABLE MOTOR BOATS/POWER BOATS


9.6
PONTOON/DECK BOATS


9.7
FISHING BOATS


9.8
OTHER BOAT TYPES


9.9
KEY PRIMARY INSIGHTS


10
RECREATIONAL BOAT MARKET, BY HULL DESIGN (MARKET SIZE & FORECAST TO 2032 – IN VALUE, USD MILLION & VOLUME, UNITS)


10.1
INTRODUCTION


10.2
PLANING HULLS


10.3
DISPLACEMENT HULLS


10.4
SEMI-DISPLACEMENT HULLS


10.5
KEY PRIMARY INSIGHTS


11
RECREATIONAL BOAT MARKET, BY BOAT SIZE (MARKET SIZE & FORECAST TO 2032 – IN VALUE, USD MILLION & VOLUME, UNITS)


11.1
INTRODUCTION


11.2
<30 FEET BOATS


11.3
30–50 FEET BOATS


11.4
>50 FEET BOATS


11.5
KEY PRIMARY INSIGHTS


12
RECREATIONAL BOAT MARKET, BY MATERIAL TYPE (MARKET SIZE & FORECAST TO 2032 – IN VALUE, USD MILLION & VOLUME, UNITS)


12.1
INTRODUCTION


12.2
ALUMINUM


12.3
STEEL BOATS


12.4
FIBERGLASS BOATS


12.5
OTHER MATERIAL TYPES


12.6
KEY PRIMARY INSIGHTS


13
RECREATIONAL BOAT MARKET, BY ENGINE LOCATION (MARKET SIZE & FORECAST TO 2032 – IN VALUE, USD MILLION & VOLUME, UNITS)


13.1
INTRODUCTION


13.2
OUTBOARD ENGINE BOATS


13.3
INBOARD ENGINE BOATS


13.4
OTHER ENGINE LOCATIONS


13.5
KEY PRIMARY INSIGHTS


14
RECREATIONAL BOAT MARKET, BY ENGINE TYPE (MARKET SIZE & FORECAST TO 2032 – IN VALUE, USD MILLION & VOLUME, UNITS)


14.1
INTRODUCTION


14.2
ICE


14.4
ELECTRIC


14.5
KEY PRIMARY INSIGHTS


15
RECREATIONAL BOAT MARKET, BY POWER RANGE (MARKET SIZE & FORECAST TO 2032 – IN VALUE, USD MILLION & VOLUME, UNITS)


15.1
INTRODUCTION


15.2
BELOW 100 KW


15.3
100–200 KW


15.4
ABOVE 200 KW


15.5
KEY PRIMARY INSIGHTS


16
RECREATIONAL BOAT MARKET, BY DISTRIBUTION CHANNEL (MARKET SIZE & FORECAST TO 2032 – IN VALUE, USD MILLION & VOLUME, UNITS)


16.1
INTRODUCTION


16.2
BOAT DEALERSHIP


16.3
BOAT SHOWS


16.4
ONLINE BOAT SALES


16.5
KEY PRIMARY INSIGHTS


17
RECREATIONAL BOAT MARKET, BY REGION (MARKET SIZE & FORECAST TO 2033 – IN VALUE, USD MILLION & VOLUME, UNITS)


17.1
INTRODUCTION


17.2
NORTH AMERICA


17.2.1
US


17.2.2
CANADA


17.2.3
MEXICO


17.3
EUROPE


17.3.1
GERMANY


17.3.2
FRANCE


17.3.3
SPAIN


17.3.4
UK


17.3.5
ITALY


17.4
ASIA OCEANIA


17.4.1
INDIA


17.4.2
JAPAN


17.4.3
CHINA


17.4.4
SOUTH KOREA


17.4.5
AUSTRALIA


17.4.6
NEW ZEALAND


17.5
ROW


17.5.1
BRAZIL


17.5.2
RUSSIA
 
 
18
COMPETITIVE LANDSCAPE


18.1
OVERVIEW


18.2
KEY PLAYER COMPETITIVE STRATEGIES, RIGHT TO WIN, 2023–2026


18.3
MARKET SHARE ANALYSIS,


18.4
REVENUE ANALYSIS, 2021–2025


18.5
COMPANY VALUATION AND FINANCIAL METRICS


18.6
BRAND COMPARISON


18.7
COMPETITIVE SCENARIO


18.7.1
PRODUCT LAUNCHES


18.7.2
DEALS


18.7.3
EXPANSIONS


18.7.4
OTHER DEVELOPMENTS


5.6
COMPANY EVALUATION MATRIX: RECREATIONAL BOAT MANUFACTURERS,


18.7.5
STARS


18.7.6
EMERGING LEADERS


18.7.7
PERVASIVE PLAYERS


18.7.8
PARTICIPANTS


18.7.9
COMPANY FOOTPRINT: KEY PLAYERS,


18.7.9.1
COMPANY FOOTPRINT


18.7.9.2
REGION FOOTPRINT


18.7.9.3
POWER RANGE FOOTPRINT


18.7.9.4
BOAT TYPE FOOTPRINT
 
 
18.8
COMPANY EVALUATION MATRIX: STARTUPS/SMES,


18.8.1
PROGRESSIVE COMPANIES


18.8.2
RESPONSIVE COMPANIES


18.8.3
DYNAMIC COMPANIES


18.8.4
STARTING BLOCKS


18.8.5
COMPETITIVE BENCHMARKING


18.8.5.1
DETAILED LIST OF KEY STARTUPS/SMES


18.8.5.2
COMPETITIVE BENCHMARKING OF KEY STARTUPS/SMES
 
 
18.9
COMPETITIVE PRODUCT MIX


19
COMPANY PROFILES


20.1
KEY PLAYERS


20.1.1
BRUNSWICK CORPORATION


20.1.2
YAMAHA MOTOR COMPANY


20.1.3
GROUPE BENETEAU


20.1.4
MALIBU BOATS


20.1.5
FERRETTI GROUP


20.1.6
POLARIS INC.


20.1.7
MASTERCRAFT BOAT COMPANY


20.1.8
BOMBARDIER RECREATIONAL PRODUCTS


20.1.9
MARINE PRODUCTS CORPORATION


20.1.10
AZIMUT BENETTI GROUP


20.1.11
SUNSEEKER INTERNATIONAL


20.1.12
BASS PRO GROUP


20.1.13
BRYTON MARINE GROUP


20.2
OTHER PLAYERS


20.2.1
MAHINDRA AND MAHINDRA


20.2.2
CATALINA YACHTS


20.2.3
ZODIAC MARINE (ZODIAC NAUTIC)


20.2.4
ISLAND PACKET YACHTS


20.2.5
HALLBERG-RASSY


20.2.6
OYSTER YACHTS


20.2.7
WINNEBAGO INDUSTRIES


20.2.8
MONTEREY BOATS


20.2.9
S2 YACHTS


20.2.10
SMOKER CRAFT


20.1.11
OCEAN ALEXANDER
 
 
21
RESEARCH METHODOLOGY


21.1
RESEARCH DATA


21.1.1
SECONDARY DATA


19.1.1.1
LIST OF KEY SECONDARY SOURCES


19.1.1.2
KEY DATA FROM SECONDARY SOURCES


21.1.2
PRIMARY DATA


19.1.1.3
LIST OF PRIMARY INTERVIEW PARTICIPANTS


19.1.1.4
KEY DATA FROM PRIMARY SOURCES


19.1.1.5
KEY INDUSTRY INSIGHTS


19.1.1.6
BREAKDOWN OF PRIMARY INTERVIEWS
 
 
21.2
MARKET SIZE ESTIMATION


21.2.1
BOTTOM-UP APPROACH


19.1.1.7
APPROACH TO ARRIVE AT MARKET SHARE USING BOTTOM-UP ANALYSIS


21.2.2
TOP-DOWN APPROACH


19.1.1.8
APPROACH TO ARRIVE AT MARKET SHARE USING TOP-DOWN ANALYSIS
 
 
21.3
DATA TRIANGULATION


21.4
RESEARCH ASSUMPTIONS


21.5
RESEARCH LIMITATIONS


21.6
RISK ANALYSIS


22
APPENDIX


22.1
INSIGHTS FROM INDUSTRY EXPERTS


22.2
DISCUSSION GUIDE


22.3
KNOWLEDGESTORE: MARKETSANDMARKETS’ SUBSCRIPTION PORTAL


22.4
CUSTOMIZATION OPTIONS


22.5
RELATED REPORTS


22.6
AUTHOR DETAILS


Methodology

The study encompassed four primary tasks to determine the present and future scope of the recreational boat market. Initially, extensive secondary research was conducted to gather data on the market, its related sectors, and overarching industries. Subsequently, primary research involving industry experts across the supply chain corroborated and validated these findings and assumptions. The complete market size was estimated by using the bottom-up and top-down methodologies. Following this, a market breakdown and data triangulation approach were utilized to determine the size of specific segments and subsegments within the market.

Secondary Research

In the secondary research process, various sources, including company annual reports and presentations, press releases, industry association publications, publications by automobile OEMs, recreational boating publications, and reports from recreational boating associations [such as the National Marine Manufacturers Association (NMMA), European Boating Association (EBA), National Association of State Boating Law Administrators, and International Council of Marine Industry Associations (ICOMIA)], country-level boating associations, recreational boating magazines, articles, directories, technical handbooks, the World Economic Outlook, trade websites, technical articles, and databases, were used to identify and collect information for an extensive commercial study of the global recreational boat market.

Primary Research

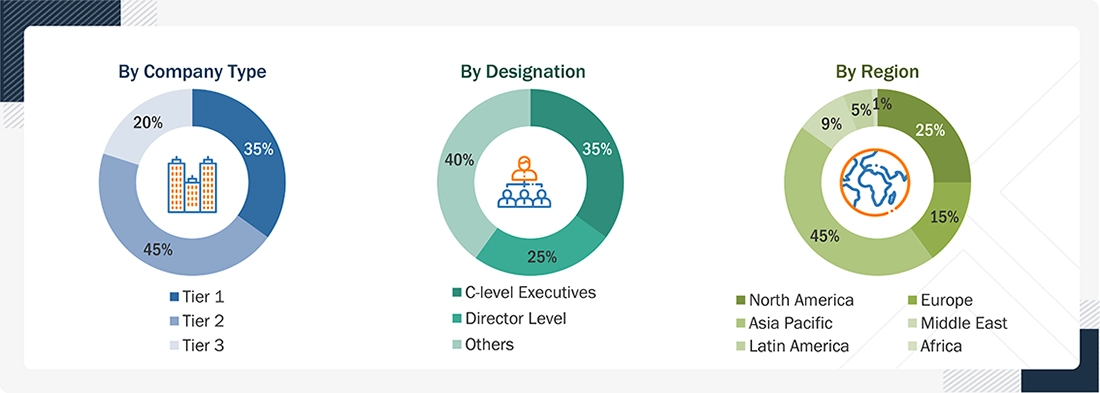
Extensive primary research was conducted after acquiring an understanding of the recreational boat market scenarios through secondary research. Several primary interviews were conducted with market experts from both the demand (country-level government associations, trade associations, and institutes) and supply (boat manufacturers and part manufacturers) sides across four major regions, namely, North America, Europe, Asia Oceania, and RoW. 30% of the experts involved in primary interviews were from the demand side, and 70% were from the supply side of the industry. Primary data was collected through questionnaires, emails, and telephonic interviews. Several primary interviews were conducted with various departments within organizations, such as sales, operations, and administration, to provide a holistic viewpoint in the report.

After interacting with industry participants, some brief sessions were conducted with experienced independent consultants to reinforce the findings from the primaries. This, along with the in-house subject matter experts’ opinions, has led to the findings delineated in the rest of this report. The following is the breakdown of primary respondents

Breakdown of Primaries

Recreational Boat Market Size, and Share

  • Note: Tiers of companies are based on engine/parts/systems/manufacturers and technology providers of the recreational boat market; revenues of companies were not considered. Tier 1 companies are engine/parts/systems/manufacturers and technology providers for the market. 
  • * Others include production managers, R&D, manufacturing managers, and engineers

To know about the assumptions considered for the study, download the pdf brochure

Market Size Estimation

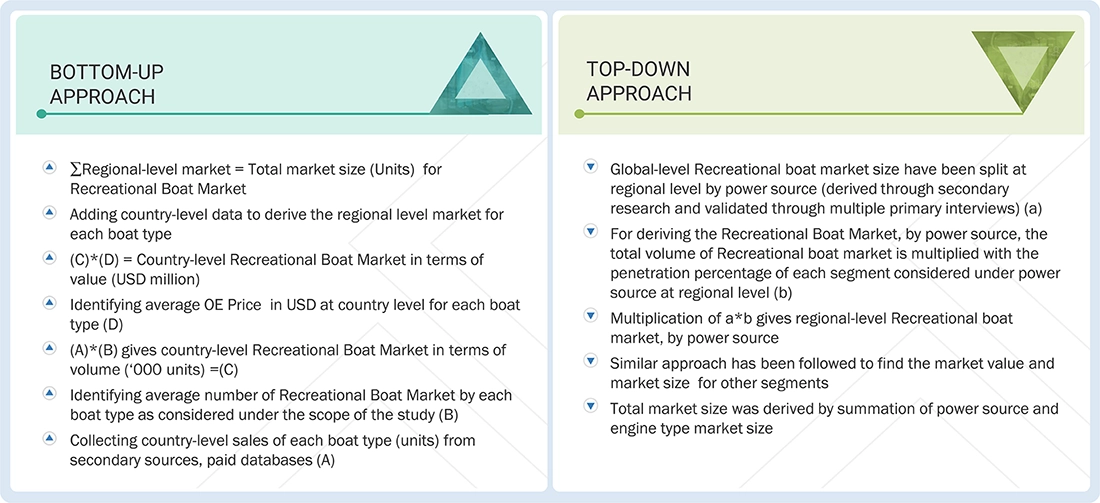
The bottom-up & top-down approaches were used to estimate and validate the total size of the recreational boat market. These methods were also used extensively to estimate the size of various subsegments, such as in the Boat Type segment. The research methodology used to estimate the market size includes the following:

  • The key players in the industry and markets have been identified through extensive secondary research.
  • The industry’s future supply chain and market size, in terms of volume, have been determined through primary and secondary research processes.
  • All percentage shares, splits, and breakdowns have been determined using secondary sources and verified through primary sources.

Bottom-up Approach

  • The bottom-up approach has been used to estimate and validate the market size of the recreational boat market. Historical unit recreational boats, by type—motorboats, yachts/cruisers, sailboats, personal watercraft (PWC), inflatable boats, pontoon/deck boats, and others—were tracked at the country level using OEM annual reports, manufacturer shipment disclosures, industry association data, boat registration records, dealer inputs, government statistics, import-export data, and industry databases. Where direct sales data was unavailable, estimates were developed using new boat registrations, historical shipment trends, import volumes, manufacturer delivery announcements, and dealer-level market information.
  • Country-level unit sales, by type, were forecast through 2033 based on historical demand patterns, boat replacement cycles, growth in recreational boating participation, tourism activity, marina & boating infrastructure development, and water sports and other leisure activities. Forecasting assumptions accounted for boat lifespan, ownership trends, economic conditions, seasonal demand, and tourism expenditure. Replacement demand was assessed separately from incremental boat purchases to avoid double counting.
  • Average selling prices (ASPs) were estimated for each boat type (motorboats, yachts/cruisers, sailboats, personal watercraft boats, inflatable boats, pontoon and deck boats, and cruisers), country, and relevant size or configuration class using OEM product prices, dealer quotations, public procurement data, import-export values, and available transaction information. These estimates were validated through primary interviews, considering differences in boat type. Forecast ASPs incorporated assumptions regarding price inflation, raw-material and component costs, exchange-rate movements, import duties, local manufacturing, technological upgrades, electrification, and changes in boat size and product mix.
  • Finally, country-level unit sales were multiplied by the corresponding ASPs to calculate market values for country-level recreational boats, by type. The resulting volumes and values were aggregated across countries and regions to derive the global market size in terms of volume and value.

Top-down Approach

  • The recreational boat market volume (units), by region, was derived from regional recreational boat sales across major engine types: gasoline, diesel, and electric/hybrid.
  • The penetration of engine type was estimated at the regional level leveraging secondary sources, including OEM product portfolios, industry association statistics, boat registration data, and manufacturer disclosures, and validated through primary interviews with industry experts.
  • Forecast regional penetration was based on expected changes in consumer boating preferences, boat type, tourism activity, and fuel efficiency requirements. The engine type penetration rates were multiplied by regional recreational boat volume to derive market volume (units) for gasoline, diesel, and electric/hybrid.
  • The average selling price (ASP) of recreational boats (USD) was derived from secondary sources and validated through primary interviews, considering differences in engine type (Gasoline, diesel, and Electric/hybrid).
  • The volume of recreational boats by engine type was multiplied by the corresponding ASP and converted into USD million to derive market value.
  • Finally, regional estimates were aggregated to determine the global market by engine type (gasoline, diesel, and electric/hybrid), in terms of value (USD million) and volume (units).
  • The same approach was used for hull design, boat size, material type, power range, and distribution channel.

Recreational Boat Market: Top-Down and Bottom-Up Approach

Recreational Boat Market Top Down and Bottom Up Approach

Data Triangulation

After arriving at the overall market size of recreational boats using the market size estimation processes as explained above, the market was split into several segments and subsegments. To complete the overall market engineering process and arrive at the exact statistics of each market segment and subsegment, data triangulation and market breakdown procedures were employed, wherever applicable. The data were triangulated by studying various factors and trends from both the demand and supply sides.

Market Definition

The recreational boat market refers to the design, manufacturing, sale, and use of boats intended for leisure and personal enjoyment activities such as cruising, fishing, water sports, and sailing. These boats include motorboats, sailboats, yachts, and personal watercraft, equipped with modern propulsion, navigation, and infotainment systems. The market integrates technologies such as GPS-based telematics, electric propulsion, and connected onboard systems to enhance safety, performance, and user convenience. Increasing adoption of digital monitoring, smart displays, and energy-efficient powertrains supports predictive maintenance and sustainability. Overall, the market aims to deliver high-performance, user-friendly, and environmentally responsible boating experiences while maximizing operational reliability and consumer value.

Key Stakeholders

  • Recreational boat manufacturers
  • Dealers and distributors
  • Marine engine manufacturers
  • Marine parts manufacturers
  • Recreational boating associations
  • Individual marine experts and consultants
  • International unions
  • Boat owners
  • Boat maintenance and repair service providers
  • Boating shows and event organizers
  • Insurance companies
  • Financing institutions
  • Government regulatory agencies

Report Objectives

  • To segment and forecast the recreational boat market, in terms of volume (units) and value (USD million):
    • By boat type (yachts/cruisers, inflatable motorboats/powerboats, personal watercraft boats, sailboats, cruisers, pontoon/deck boats, fishing boats, and others)
    • By boat size (<30 feet, 30–50 feet, >50 feet)
    • By engine placement (outboards and inboards)
    • By engine type (ICE and electric/hybrid)
    • By power range (below 100 kW, 100–200 kW, above 200 KW)
    • By material type (aluminum, fiberglass, and steel)
    • By hull design (planning hulls and displacement hulls)
    • By distribution channel (boat dealerships, boat shows, and online sales)
    • By regions (North America, Europe, Asia Oceania, and RoW)
  • To provide detailed information about the major factors influencing market growth (drivers, challenges, restraints, and opportunities)
  • To track and analyze competitive developments, such as product launches, deals, and other activities by key industry participants
  • To strategically analyze the market with supply chain analysis, revenue analysis, and regulatory analysis in the market
  • To examine the opportunities in the market for stakeholders and provide details of the competitive landscape for market leaders

Available customizations:

With the given market data, MarketsandMarkets offers customizations in line with company-specific needs.

  • Recreational boat market, by engine location at the country level (for countries covered in the report)
  • Recreational boat market, by yacht type, additional countries (small, medium, and large)
  • Recreational boat market, by region, additional countries (up to 3)


Key Questions Addressed by the Report

What is the current market size of the Recreational Boat Market?

The global Recreational Boat Market is valued at USD 15.96 billion in 2025 and is projected to reach USD 24.64 billion by 2032, growing at a CAGR of 6.4%.

What are the key factors driving the growth of the Recreational Boat Market?

The market is driven by increasing demand for leisure boating activities, advances in onboard technologies, the adoption of hybrid-electric propulsion systems, flexible ownership models such as boat subscriptions and fractional ownership, and rising investments in marina infrastructure.

Which propulsion type is expected to hold the largest share of the Recreational Boat Market?

Engine-powered boats are expected to account for the largest market share during the forecast period due to their high performance, suitability for cruising, fishing, and watersports, and well-established fueling and marina infrastructure.

Which activity segment is expected to witness the fastest growth in the Recreational Boat Market?

The Cruising & Watersports segment is expected to register the fastest growth, driven by increasing leisure tourism, growing demand for premium outdoor experiences, and the expansion of boat rental and charter services.

Which region is expected to lead the Recreational Boat Market?

North America is expected to lead the Recreational Boat Market during the forecast period, supported by a strong boating culture, extensive marina infrastructure, high participation in recreational boating activities, and the presence of leading boat manufacturers.

Personalize This Research

  • Triangulate with your Own Data
  • Get Data as per your Format and Definition
  • Gain a Deeper Dive on a Specific Application, Geography, Customer or Competitor
  • Any level of Personalization
Request A Free Customisation

Let Us Help You

  • What are the Known and Unknown Adjacencies Impacting the Recreational Boat Market
  • What will your New Revenue Sources be?
  • Who will be your Top Customer; what will make them switch?
  • Defend your Market Share or Win Competitors
  • Get a Scorecard for Target Partners
Customized Workshop Request

Custom Market Research Services

We Will Customise The Research For You, In Case The Report Listed Above Does Not Meet With Your Requirements

Get 10% Free Customisation

TESTIMONIALS

Growth opportunities and latent adjacency in Recreational Boat Market

THIS REPORT TELLS YOU

How big the Recreational Boat market is, and who leads it.

GROWTHIQ TELLS YOU NEW

Where your company should play next, and who is taking your share.

Get your company's view of this market. Free snapshot.

DMCA.com Protection Status
popup img