North America AI Data Center Liquid Cooling Market (2026-2032)

The North America AI Data Center Liquid Cooling Market was valued at $1640.4 Million in 2026 and projected to reach to $9849.8 Million by 2032, representing a compound annual growth rate of 34.8%. North America's AI data center liquid cooling market is positioned for transformative growth, expanding from $1,640.4 million in 2026 to $9,849.8 million by 2032.


| Market Size in | USD 26.32 MN |
| Market Forecast in | |
| CAGR | |
| Forecast Period | |
| Units Considered | Value (USD MN) |
North America AI Data Center Liquid Cooling Market Trends and Insights
- The region is experiencing unprecedented growth driven by massive investments in AI infrastructure and the urgent need for efficient thermal management solutions across hyperscale data centers.
- North America's market is projected to expand to $9,849.8 million by 2032, reflecting a compound annual growth rate of 34.8%, significantly outpacing global trends. The acceleration in North America is fueled by the concentration of leading cloud service providers, semiconductor manufacturers, and AI companies headquartered in the region.
- North America's data center operators are increasingly adopting liquid cooling technologies to manage the extreme heat generated by advanced GPU clusters and AI processors.
- This regional momentum is supported by robust capital expenditure cycles, technological innovation, and regulatory pressures to reduce energy consumption and carbon footprints in data center operations..
Key Market Statistics
- CAGR (2026-2032) 34.8% CAGR
- Market Size, 2026 ~USD 1640.4 Million
- Forecast, 2032 ~USD 9849.8 Million
- Geography North America
North America AI Data Center Liquid Cooling Market Overview
Market Dominance :
North America commands the largest share of the global AI data center liquid cooling market, driven by concentrated hyperscale data center operations and aggressive AI infrastructure investments from major tech giants.
Explosive Growth Trajectory :
The region's 34.8% CAGR significantly outpaces the global average of 34%, reflecting North America's accelerated adoption of advanced thermal management solutions to support AI workloads.
US Market Leadership :
The United States represents $8,627.4 million of the regional market by 2032, accounting for approximately 88% of North America's total liquid cooling demand for AI data centers.
Thermal Management Urgency :
Rising power densities in AI chips and the need for energy-efficient cooling solutions are driving rapid adoption of liquid cooling technologies across North American hyperscale facilities.
North America AI Data Center Liquid Cooling Market Dynamics
- This exceptional trajectory reflects the region's leadership in AI infrastructure development and the critical need for advanced thermal management solutions to support increasingly power-intensive AI workloads.
- Major cloud providers and semiconductor manufacturers are prioritizing liquid cooling investments to enhance operational efficiency and reduce energy consumption. The market outlook is bolstered by substantial capital expenditures in data center expansion, regulatory pressure for energy efficiency, and technological advancements in cooling systems.
- North America's mature technology ecosystem, coupled with strong venture capital support and government initiatives promoting AI development, creates a favorable environment for liquid cooling solution providers.
- Competition will intensify as new entrants and established players vie for market share in this high-growth segment..
Market Ecosystem
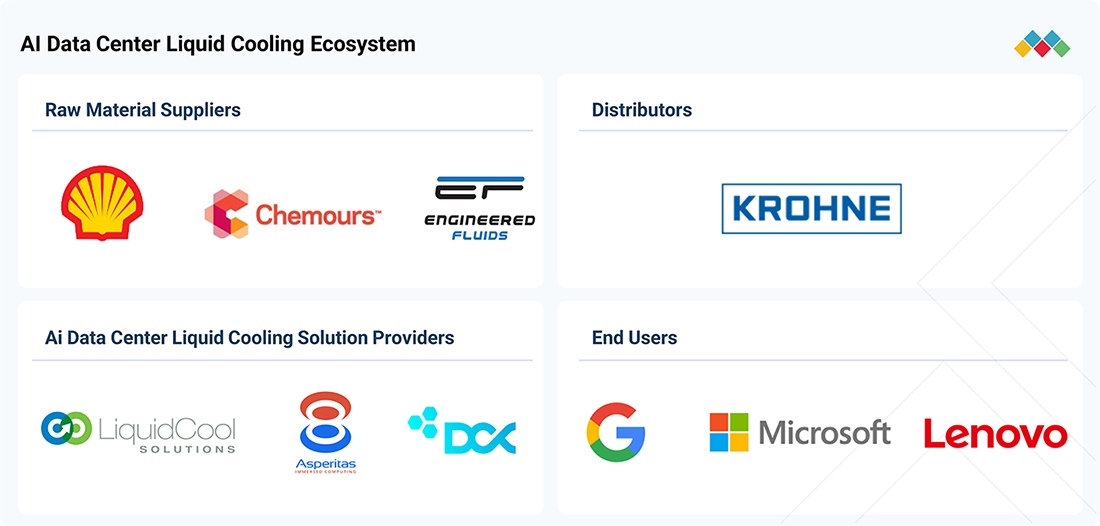
AI DATA CENTER LIQUID COOLING MARKET: COMMERCIAL USE CASES ACROSS INDUSTRIES
| COMPANY | USE CASE DESCRIPTION | BENEFITS |
|---|---|---|
 |
Vertiv provides liquid cooling infrastructure for AI and high-density data centers through CoolChip CDUs, CoolPhase CDUs, fluid networks, and rear-door heat exchangers. Its solutions support direct-to-chip cooling of high-power CPUs/GPUs and hybrid cooling configurations across hyperscale, colocation, and enterprise facilities. | Its solutions support high-density AI racks. |
 |
Schneider Electric provides end-to-end liquid cooling solutions for AI data centers, including direct-to-chip cooling, CDUs, rear-door heat exchangers, and heat-rejection systems. Its solutions are used in both new and existing facilities to accommodate high-density GPU infrastructure and retrofit air-cooled data centers for AI workloads. | Its solutions enable higher rack densities. |
 |
Super Micro Computer integrates direct liquid cooling (DLC) into GPU-optimized AI server and rack-scale platforms, including NVIDIA HGX and GB200 NVL72 systems. Its liquid-cooled architectures incorporate cold plates, CDUs, and coolant distribution manifolds to provide rack-level thermal management for dense AI/LLM deployments. | Its solutions support high-density GPU deployment. |
 |
DCX Liquid Cooling Systems develops facility, in-rack, and equipment-level liquid cooling systems for AI, HPC, hyperscale, colocation, and enterprise data centers. Its portfolio includes ECDU, FDU, and InRack CDU platforms, with facility-level systems designed to provide multi-megawatt cooling capacity for high-density AI data halls. | Its solutions support large-scale AI and HPC deployments. |
 |
CoolIT Systems provides scalable direct liquid cooling systems for AI and high-performance computing, including cold plates, CDUs, manifolds, and rack-level cooling architectures. Its solutions are designed to remove heat directly from high-power processors and support increasingly dense AI compute clusters. | Its solutions enable high-density AI computing. |
Logos and trademarks shown above are the property of their respective owners. Their use here is for informational and illustrative purposes only.
Related Ecosystem
Key Takeaways
- North America's AI data center liquid cooling market will grow from $1,640.4M (2026) to $9,849.8M (2032) at a 34.8% CAGR, driven by hyperscale AI infrastructure expansion.
- North America leads global adoption due to concentration of major cloud providers, tech giants, and semiconductor manufacturers investing heavily in advanced cooling solutions.
- Energy efficiency mandates and sustainability regulations in North America are accelerating the transition from air cooling to liquid cooling technologies in data centers.
- North America's market growth is supported by continuous innovation in immersion cooling, direct-to-chip cooling, and closed-loop liquid systems for next-generation AI processors.
AI Data Center Liquid Cooling Market Report Scope
| Report Metric | Details |
|---|---|
| Base Year | 2026 |
| Fastest Growing Segment | 120 KW & ABOVE (Rack Density) |
| Forecast Period | 2026-2030 |
| Growth Rate | CAGR of 34% from 2026 to 2030 |
| Largest Segment | DIRECT-TO-CHIP (Cooling Type) |
| Market Size Base Year (Billions) | ~USD 3.52 (2026) |
| Revenue Forecast (Billions) | ~USD 11.36 (2030) |
| Segments Covered | Component, Cooling Type, Data Center Type, Rack Density |
North America AI Data Center Liquid Cooling Market Report Segmentation
4 segment dimensions are covered across the global market.
By Component
- Services
- Solutions
By Cooling Type
- Direct-To-Chip
- Immersion
By Data Center Type
- Colocation
- Enterprise
- Hyperscale
By Rack Density
- 120 Kw & Above
- 30 Kw - 40 Kw
- 40 Kw - 60 Kw
- 60 Kw - 120 Kw
Target Audience
- Data Center Operators & Hyperscalers : Need detailed market intelligence to optimize cooling infrastructure investments, evaluate technology solutions, and benchmark operational efficiency against North American competitors managing massive AI workloads.
- Liquid Cooling Solution Providers : Require granular market data to identify growth opportunities, assess competitive positioning, develop regional sales strategies, and allocate R&D resources for North American market penetration.
- Technology & Infrastructure Investors : Seek comprehensive market analysis to evaluate investment opportunities in North American cooling technology companies, identify acquisition targets, and assess portfolio company growth potential.
- Enterprise IT & Procurement Teams : Need market insights to evaluate cooling solution vendors, understand technology trends, benchmark pricing, and make strategic purchasing decisions for data center thermal management systems.
- Strategic Consultants & Advisors : Require detailed regional market data to support client advisory engagements, develop business strategies, conduct competitive analysis, and identify emerging opportunities in North America's AI infrastructure sector.
Countries within North America - compare and drill down
| Country | 2025 size (native) |
|---|---|
| US | USD 8627.4 Million |
| Canada | USD 1096.2 Million |
| Mexico | USD 126.3 Million |
Country market size visualization
Reasons to Buy this Report
- Regional Market Dominance Insights : Gain comprehensive understanding of North America's 88% market concentration and identify which sub-regions and countries offer the highest growth opportunities for liquid cooling solutions.
- Competitive Landscape Analysis : Access detailed competitive intelligence specific to North American players, including market share distribution, technology differentiation, and strategic positioning among hyperscale data center operators.
- Investment Decision Support : Leverage precise market sizing and forecasting data to make informed capital allocation decisions, facility expansion plans, and technology adoption strategies tailored to North American market dynamics.
- Customer Segmentation Strategy : Identify and prioritize high-value customer segments within North America, including cloud providers, semiconductor manufacturers, and enterprise data center operators with specific cooling requirements.
- Growth Acceleration Roadmap : Develop targeted go-to-market strategies leveraging North America's 34.8% CAGR advantage over global averages, with actionable insights on market drivers, adoption barriers, and expansion opportunities.
Frequently asked questions
What is the projected market size for AI data center liquid cooling in North America by 2032?
North America's AI data center liquid cooling market is projected to reach $9,849.8 million by 2032, growing from $1,640.4 million in 2026 at a CAGR of 34.8%.
Why is North America experiencing faster growth than the global average in liquid cooling adoption?
North America's accelerated growth is driven by the region's concentration of hyperscale cloud providers, AI companies, and semiconductor manufacturers, combined with stringent energy efficiency regulations and massive capital investments in AI infrastructure.
What types of liquid cooling solutions are being deployed in North America data centers?
North America data centers are increasingly adopting immersion cooling, direct-to-chip liquid cooling, and closed-loop systems designed to handle the thermal demands of advanced GPU clusters and AI processors.
How do sustainability regulations impact North America's liquid cooling market growth?
Environmental regulations and corporate sustainability commitments in North America are pushing data center operators to replace traditional air cooling with more energy-efficient liquid cooling technologies to reduce power consumption and carbon emissions.
Which industries in North America are driving demand for liquid cooling solutions?
North America's demand is primarily driven by cloud computing providers, artificial intelligence companies, semiconductor manufacturers, and financial institutions operating large-scale data centers requiring advanced thermal management.
RESEARCH METHODOLOGY
The study involved four major activities in estimating the current size of the AI data center liquid cooling market. Exhaustive secondary research was done to collect information on the market, peer markets, and parent market. The next step was to validate these findings, assumptions, and sizing with industry experts across the AI data center liquid cooling value chain through primary research. Both top-down and bottom-up approaches were employed to estimate the complete market size. Thereafter, market breakdown and data triangulation were used to estimate the market size of segments and subsegments.
Secondary Research
Secondary sources for this research study include annual reports, press releases, and investor presentations of companies; white papers; certified publications; and articles by recognized authors; gold- and silver-standard websites; AI data center liquid cooling manufacturing companies, regulatory bodies, trade directories, and databases. The secondary research was mainly used to obtain key information about the industry’s supply chain, the total pool of key players, market classification, and segmentation according to industry trends to the bottom-most level and regional markets. It has also been used to obtain information about key developments from a market-oriented perspective.
Primary Research
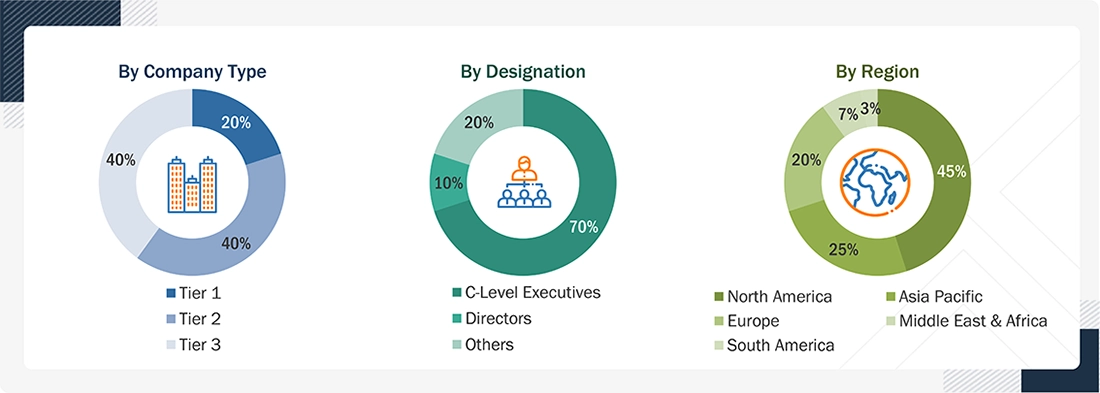
The AI data center liquid cooling market comprises several stakeholders, such as raw material suppliers, technology support providers, data center cooling equipment manufacturers, and regulatory organizations in the supply chain. Various primary sources from both the supply and demand sides of the market were interviewed to obtain qualitative and quantitative information. Primary sources from the supply side included industry experts such as chief executive officers (CEOs), vice presidents, marketing directors, technology and innovation directors, and related key executives from various key companies and organizations operating in the AI data center liquid cooling market. Primary sources from the demand side included directors, marketing heads, and purchase managers from various sourcing industries. The following is the breakdown of the primary respondents:
Breakdown of Primary Profiles
To know about the assumptions considered for the study, download the pdf brochure
Market Size Estimation
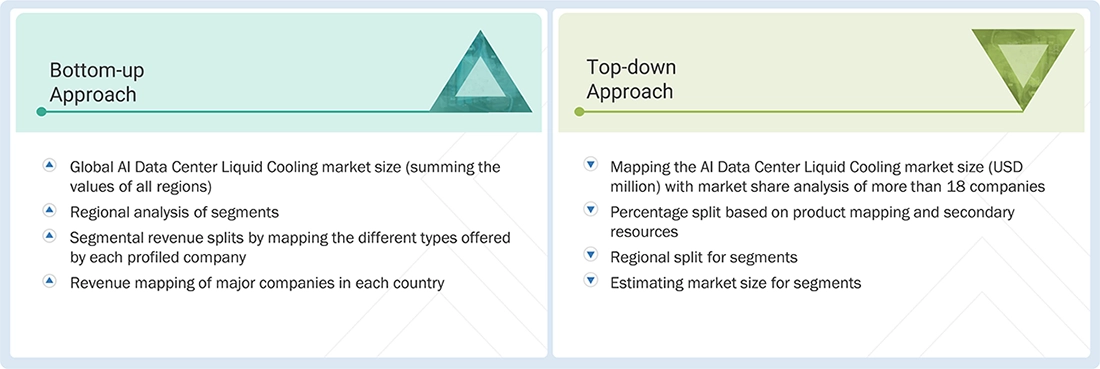
The top-down and bottom-up approaches have been employed to estimate and validate the total size of the AI data center liquid cooling market. These approaches have also been used extensively to estimate the size of various dependent market subsegments. The research methodology used to estimate the market size included the following:
The following segments provide details about the overall market size estimation process employed in this study:
- Extensive primary and secondary research was done to identify the key players.
- The value chain and market size of the AI data center liquid cooling market, in terms of value, were determined through primary and secondary research.
- All percentage shares, splits, and breakdowns were collected through secondary sources and verified through primary sources.
- All possible parameters that affect the market were covered in this research study and are viewed in extensive detail, verified through primary research, and analyzed to obtain the final quantitative and qualitative data.
- The study of reports, reviews, and newsletters of top market players, along with extensive interviews for opinions from key leaders, such as CEOs, directors, and marketing executives, is included in this research.
Global AI data center liquid cooling Market Size: Bottom-up & Top-down Approach
Data Triangulation
After arriving at the overall market size using the market size estimation processes as explained above, the market was split into several segments and subsegments. To complete the overall market engineering process and arrive at the exact statistics of each market segment and subsegment, the data triangulation and market breakdown procedures were employed, wherever applicable. The data was triangulated by studying various factors and trends from both the demand and supply sides.
Market Definition
AI data center liquid cooling refers to a range of cooling solutions designed to manage the heat generated by increasingly powerful AI processors and computing systems. These solutions provide targeted thermal management for high-density infrastructure and can be integrated into new or existing data center environments. Market growth is being supported by the rapid deployment of AI and accelerated computing, increasing computational workloads, higher equipment density, and the need for dependable cooling infrastructure. The expansion of hyperscale, colocation, and enterprise data centers is expected to create further opportunities for liquid cooling technologies.
Key Stakeholders
- AI data center liquid cooling manufacturers, processors, and recycling technology providers
- Research institutions, standards organizations, and regulatory agencies such as ASTM, ISO, and others
- NGOs, governments, investment banks, venture capitalists, and private equity firms
Report Objectives
- To define, describe, and forecast the market size of AI data center liquid cooling in terms of value
- To provide detailed information regarding the key factors, such as drivers, restraints, opportunities, and industry-specific challenges, influencing the growth of the AI data center liquid cooling market
- To analyze and forecast the global AI data center liquid cooling market on the basis of cooling type, rack density, component, data center type, and region
- To analyze the opportunities in the market for stakeholders and provide details of a competitive landscape for market leaders
- To forecast the size of various market segments based on four major regions: North America, Asia Pacific, Europe, and Rest of the World, along with their respective key countries
- To track and analyze the competitive developments, such as product launches, expansions, and others, in the market
- To strategically profile the key players and comprehensively analyze their market shares and core competencies
Available customizations:
With the given market data, MarketsandMarkets offers customizations according to the client-specific needs.
The following customization options are available for the report:
- Additional country-level analysis of the AI data center liquid cooling market
- Profiling of additional market players (up to five)
Product Analysis
- Product matrix, which provides a detailed comparison of each company's product portfolio
Get the Full AI Data Center Liquid Cooling Market Report
Full forecast, segment splits, and company analysis for all AI Data Center Liquid Cooling Market.
- US AI Data Center Liquid Cooling Market
- Canada AI Data Center Liquid Cooling Market
- Mexico AI Data Center Liquid Cooling Market
- UK AI Data Center Liquid Cooling Market
- Germany AI Data Center Liquid Cooling Market
- France AI Data Center Liquid Cooling Market
- China AI Data Center Liquid Cooling Market
- Japan AI Data Center Liquid Cooling Market
- South Korea AI Data Center Liquid Cooling Market
- India AI Data Center Liquid Cooling Market
- Singapore AI Data Center Liquid Cooling Market
- Malaysia AI Data Center Liquid Cooling Market
- Australia AI Data Center Liquid Cooling Market
- Brazil AI Data Center Liquid Cooling Market
- South Africa AI Data Center Liquid Cooling Market
- Rest Of Europe AI Data Center Liquid Cooling Market
- Rest Of Asia Pacific AI Data Center Liquid Cooling Market
- GCC Countries AI Data Center Liquid Cooling Market
- -Rest Of GCC Countries AI Data Center Liquid Cooling Market
- Rest Of South America AI Data Center Liquid Cooling Market
Need a Tailored Report?
Customize this report to your needs
Get 10% FREE Customization
Customize This Report
