US Artificial Intelligence (AI) in Networks Market (2024-2029)
The US Artificial Intelligence (AI) in Networks Market was valued at $3489.5 Million in 2024 and projected to reach to $14487.3 Million by 2029, representing a compound annual growth rate of 32.9%. The US Artificial Intelligence in Networks market is positioned for sustained high-growth trajectory through 2029, driven by enterprise demand for intelligent network automation and real-time optimization capabilities.

| Market Size in | USD 26.32 MN |
| Market Forecast in | |
| CAGR | |
| Forecast Period | |
| Units Considered | Value (USD MN) |
US Artificial Intelligence (AI) in Networks Market Trends and Insights
- This represents a compound annual growth rate (CAGR) of 32.9%, driven by increasing adoption of AI-powered network optimization, automation, and intelligent traffic management across US enterprises.
- The US market benefits from strong technological infrastructure, significant R&D investment, and early adoption of advanced networking solutions among leading technology companies and telecommunications providers. US organizations are increasingly deploying AI-driven network solutions to enhance operational efficiency, reduce latency, and improve security posture.
- Between 2024 and 2029, the US market will witness substantial growth as enterprises integrate machine learning algorithms into network management platforms, edge computing architectures, and 5G infrastructure.
- The competitive landscape in the US is characterized by major semiconductor and networking vendors investing heavily in AI capabilities, positioning the country as a global leader in AI-enabled network innovation and deployment..
Key Market Statistics
- CAGR (2024-2029) 32.9% CAGR
- Market Size, 2024 ~USD 3489.5 Million
- Forecast, 2029 ~USD 14487.3 Million
- Country US
US Artificial Intelligence (AI) in Networks Market Overview
Explosive US Market Growth :
The US AI in Networks market is projected to grow from $3,489.5 million in 2024 to $14,487.3 million by 2029, representing a robust 32.9% CAGR, outpacing many other technology sectors.
Enterprise AI Adoption Leadership :
US enterprises are leading global adoption of AI-powered network optimization and automation, driven by competitive pressures and digital transformation initiatives across Fortune 500 companies.
Intelligent Traffic Management Innovation :
American tech companies are pioneering advanced AI-driven intelligent traffic management solutions, reducing network congestion and improving operational efficiency for mission-critical infrastructure.
Strong Technology Infrastructure :
The US benefits from robust cloud infrastructure, 5G deployment, and a mature semiconductor ecosystem, creating ideal conditions for AI network solutions integration and scaling.
US Artificial Intelligence (AI) in Networks Market Dynamics
- Major US technology companies and telecommunications providers are investing heavily in AI-powered solutions to enhance network reliability, reduce operational costs, and enable emerging applications like edge computing and IoT connectivity. Key growth catalysts include accelerating 5G rollout, increasing cybersecurity threats requiring AI-driven threat detection, and regulatory pressures for network efficiency.
- US data centers and cloud providers are prioritizing AI network technologies to maintain competitive advantages, while mid-market enterprises increasingly adopt these solutions for digital transformation initiatives..
Market Ecosystem
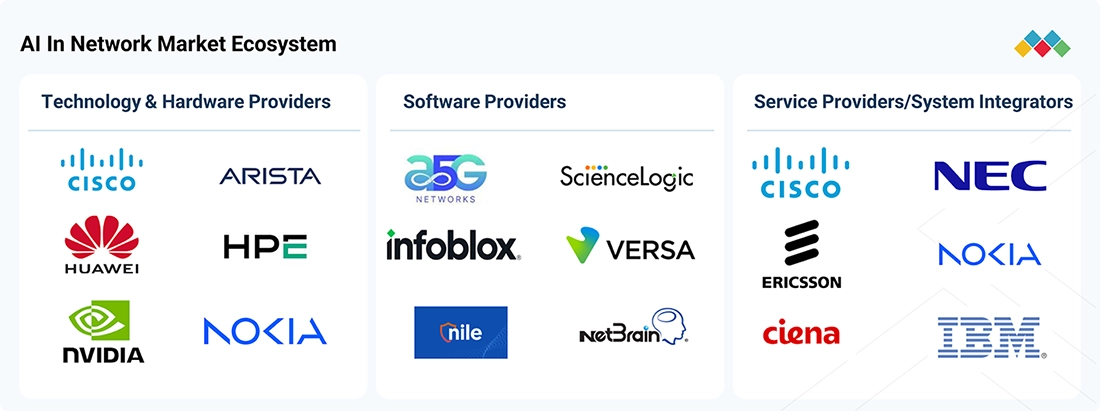
AI IN NETWORK MARKET : COMMERCIAL USE CASES ACROSS INDUSTRIES
| COMPANY | USE CASE DESCRIPTION | BENEFITS |
|---|---|---|
 |
Cisco integrates AI, network telemetry, predictive analytics, and agentic operations across data center, campus, and WAN environments | Enterprises use these capabilities to monitor network performance, detect anomalies, optimize traffic paths, automate troubleshooting, and enable autonomous network assurance. | Real-time network visibility and assurance | Predictive issue detection and remediation | Optimized traffic routing and application performance | Reduced downtime and troubleshooting effort | Improved operational efficiency. |
 |
Ericsson integrates AI across RAN, core, and OSS/BSS to enable intent-driven and autonomous network operations | Telecom operators use AI to monitor network conditions, optimize resources, automate provisioning and fault resolution, and implement closed-loop service assurance across multi-domain networks. | Improved network reliability and service quality | Automated fault resolution and assurance | Reduced operating costs and mean time to resolution | Optimized resource and energy utilization | Scalable autonomous operations. |
 |
Huawei integrates AI, generative AI, digital twins, and intelligent network management through its Autonomous Driving Network solutions | Telecom operators use these capabilities for predictive fault management, traffic optimization, energy saving, network planning, and closed-loop service provisioning and assurance. | Proactive fault detection and faster troubleshooting | Optimized network resource utilization | Improved service quality and SLA assurance | Reduced manual O&M effort and costs | Enhanced energy efficiency and network reliability. |
Logos and trademarks shown above are the property of their respective owners. Their use here is for informational and illustrative purposes only.
Related Ecosystem
Electrical System And Components
- Natural Language Processing (NLP)
- Sensors
- Machine Learning
- Temperature Sensors
- Actuators
- ABB India Limited
- Siemens ag
- SCHNEIDER ELECTRIC SE
- Eaton Corporation plc
- Lenovo
Analytics
- Natural Language Processing (NLP)
- Machine Learning
- Supply Chain Management
- Predictive Analytics
- Image Sensors
- International Business Machines Corporation
- MICROSOFT CORPORATION
- Oracle Corporation
- SAP SE
Cloud Computing
- Software as A Service (SaaS)
- Natural Language Processing (NLP)
- Platform as A Service (PaaS)
- Machine Learning
- Supply Chain Management
- International Business Machines Corporation
- MICROSOFT CORPORATION
- Oracle Corporation
- Amazon.com, Inc.
Key Takeaways
- The US AI in Networks Market is valued at $3,489.5 million in 2024 and will grow to $14,487.3 million by 2029, representing a 32.9% CAGR.
- US enterprises are rapidly adopting AI-powered network optimization and automation solutions to improve operational efficiency and reduce infrastructure costs.
- The US market is driven by strong technological infrastructure, significant venture capital investment, and early adoption by major technology and telecommunications companies.
- By 2029, the US will solidify its position as a global leader in AI-enabled networking, with widespread deployment across 5G, edge computing, and enterprise network management.
Artificial Intelligence (AI) in Networks Market Report Scope
| Report Metric | Details |
|---|---|
| Base Year | 2024 |
| Fastest Growing Segment | GENERATIVE AI (Technology) |
| Forecast Period | 2024-2029 |
| Growth Rate | CAGR of 33.8% from 2024 to 2029 |
| Largest Segment | CLOUD (Deployment Mode) |
| Market Size Base Year (Billions) | ~USD 10.91 (2024) |
| Revenue Forecast (Billions) | ~USD 46.8 (2029) |
| Segments Covered | Offering, Deployment Mode, Network Function, Technology, End User |
US Artificial Intelligence (AI) in Networks Market Report Segmentation
5 segment dimensions are covered across the global market.
By Offering
- AI Networking Platforms
- Routers And Ethernet Switches
- Services
- Software
By Deployment Mode
- Cloud
- On-Premises
By Network Function
- Cybersecurity
- Optimization
- Predictive Maintenance
- Troubleshooting
By Technology
- Deep Learning
- Generative AI
- Machine Learning
- Natural Language Processing
- Other Technologies
By End User
- Data Centers
- Enterprises
- Government
- Telecom Service Providers
Target Audience
- US Technology & Telecom Executives : C-suite leaders and strategic planners need US market intelligence to guide product development, M&A decisions, and go-to-market strategies for AI network solutions.
- Enterprise IT Decision Makers : CIOs and network infrastructure managers require detailed US market insights to evaluate AI network vendors, benchmark solutions, and justify technology investments to stakeholders.
- Investment & Private Equity Firms : US-focused investors need comprehensive market data to identify acquisition targets, assess portfolio company growth potential, and evaluate emerging AI networking startups.
- Semiconductor & Hardware Manufacturers : US chip designers and equipment makers require market forecasts to align product roadmaps, R&D investments, and supply chain strategies with AI network infrastructure demand.
- Management Consultants & Analysts : Strategy consultants and research firms need authoritative US market data to support client advisory engagements, competitive analyses, and industry benchmarking studies.
Reasons to Buy this Report
- US Market-Specific Sizing & Forecasts : Access precise valuation data for the US market segment with detailed 2024-2029 projections, enabling accurate budget allocation and investment planning specific to American market conditions.
- Competitive Landscape Intelligence : Identify leading US-based AI network solution providers, emerging startups, and technology partnerships shaping the American market, with detailed competitive positioning analysis.
- Enterprise Adoption Trends : Understand how US enterprises across industries are implementing AI network solutions, including adoption rates by company size, sector, and geographic region within the United States.
- Regulatory & Infrastructure Insights : Gain clarity on US-specific regulatory frameworks, 5G deployment status, data residency requirements, and infrastructure investments impacting AI network technology adoption.
- Strategic Growth Opportunities : Identify high-potential market segments, emerging use cases, and geographic hotspots within the US where AI network solutions are experiencing accelerated adoption and investment.
Frequently asked questions
What is the current size of the US AI in Networks Market?
The US AI in Networks Market was valued at $3,489.5 million in 2024 and is expected to reach $14,487.3 million by 2029.
What is the growth rate of the US AI in Networks Market?
The US AI in Networks Market is growing at a compound annual growth rate (CAGR) of 32.9% from 2024 to 2029.
What are the primary drivers of growth in the US market?
Key drivers include increasing enterprise demand for network automation, AI-powered security solutions, 5G infrastructure deployment, and the need for intelligent traffic management across US organizations.
Which industries in the US are leading AI in Networks adoption?
Telecommunications, cloud computing, financial services, healthcare, and technology companies are among the leading sectors driving AI in Networks adoption in the US.
What challenges does the US AI in Networks Market face?
Challenges include high implementation costs, skills shortage in AI and network engineering, data privacy concerns, and the complexity of integrating AI solutions with legacy network infrastructure.
RESEARCH METHODOLOGY
The research study involved four major activities to estimate the AI in network market size. We conducted exhaustive secondary research to collect key information on the market and peer markets. Next, we validated these findings and assumptions and sized the market with the help of primary research with industry experts across the value chain. We used both top-down and bottom-up approaches to estimate market size. Afterward, we used market breakdowns and data triangulation to estimate segment and sub-segment market sizes.
Secondary Research
We determined the market size of companies offering AI in network solutions and services for various subscribers based on secondary data from paid and unpaid sources, and by analyzing the offerings (solutions and services) of major companies in the ecosystem and rating them based on performance and quality. In the secondary research process, various sources were used to identify and collect information for this study. The secondary sources included annual reports, press releases and investor presentations of companies, white papers, journals, and certified publications and articles from recognized authors, directories, and databases.
Secondary research was mainly used to obtain key information about the industry’s supply chain, the total pool of key players, market classification, and segmentation according to industry trends to the bottom-most level, regional markets, and key developments from both market- and technology-oriented perspectives, all of which were further validated by primary sources.
Primary Research
In the primary research process, we interviewed primary sources from both the supply and demand sides to obtain qualitative and quantitative information for the report. Primary sources on the supply side include industry experts such as Chief Executive Officers (CEOs), Vice Presidents (VPs), marketing directors, technology and innovation directors, and other key executives from companies and organizations providing AI in network solutions. Primary demand-side sources include end users such as Chief Information Officers (CIOs), consultants, service professionals, technicians and technologists, and managers at public and investor-owned utilities.
In the market engineering process, we used top-down and bottom-up approaches, along with several data triangulation methods, to estimate and forecast the overall market segments and subsegments listed in the report. We performed extensive qualitative and quantitative analyses across the entire market engineering process to identify key information/insights throughout the report.
After completing the market engineering (including calculations for market statistics, market breakup, market size estimations, market forecasting, and data triangulation), we conducted extensive primary research to gather information. Primary research identified segmentation, industry trends, key players, the competitive landscape, and key market dynamics such as drivers, restraints, opportunities, challenges, and key strategies.
breakdown of primaries
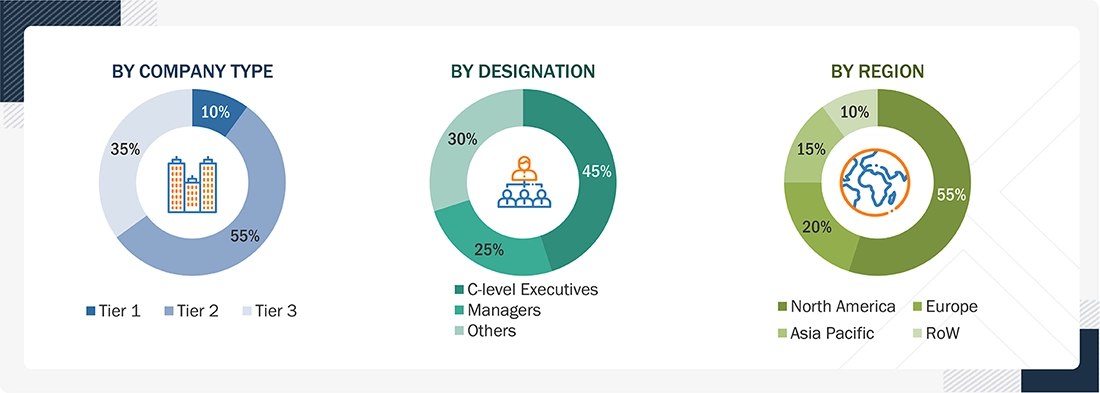
Note 1: Tier 1 companies have revenues of more than USD 10 billion; tier 2 companies’ revenue ranges from USD 1 billion to USD 10 billion; and tier 3 companies’ revenue ranges from USD 500 million to USD 1 billion
Source: Secondary Literature, Expert Interviews, and MarketsandMarkets Analysis
To know about the assumptions considered for the study, download the pdf brochure
Market Size Estimation
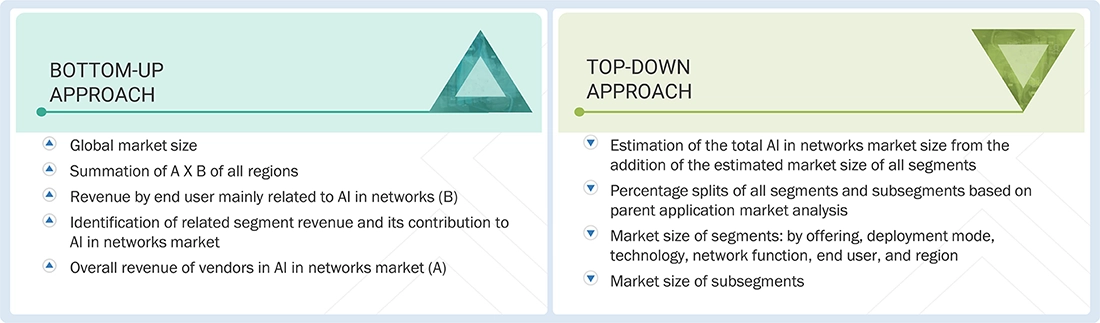
In the market engineering process, the top-down and bottom-up approaches were used, along with multiple data triangulation methods, to estimate and validate the size of the AI in network market and other dependent submarkets. The research methodology used to estimate the market sizes includes the following:
- Initially, MarketsandMarkets focuses on top-line investments and spending in the ecosystems. It also considers significant developments in the critical market area.
- Tracking the recent and upcoming developments in the AI in network market that include investments, R&D activities, product launches, collaborations, mergers and acquisitions, and partnerships, as well as forecasting the market size based on these developments and other critical parameters.
- Conduct multiple discussions with key opinion leaders to learn about the diverse types of authentications and brand protection offerings used and the applications for which they are used to analyze the breakdown of the scope of work carried out by major companies.
- Segmenting the market based on technology types concerning applications wherein the types are to be used and deriving the size of the global AI in network market.
- Segmenting the overall market into various market segments
- Validating the estimates at every level through discussions with key opinion leaders, such as chief executives (CXOs), directors, and operations managers, and finally with the domain experts at MarketsandMarkets
AI in Network Market : Top-Down and Bottom-Up Approach
Data Triangulation
After arriving at the overall market size from the above estimation process, the AI in network market has been split into several segments and sub-segments. To complete the overall market engineering process and arrive at exact statistics for all segments and sub-segments, we used data triangulation and market breakdown procedures, where applicable. The data has been triangulated by studying various factors and trends from both the demand and supply sides.
We validated the AI in network market size using top-down and bottom-up approaches.
Market Definition
AI in network refers to applying artificial intelligence technologies across network infrastructure and operations to enhance visibility, decision-making, performance, security, and automation. It includes machine learning, generative AI, predictive analytics, and intelligent automation for network monitoring, observability, DDI, optimization, threat detection, configuration, orchestration, and planning. AI in Network solutions analyze telemetry, traffic, topology, configuration, and operational data to identify anomalies, predict network conditions, optimize resources, automate remediation, and support increasingly autonomous network operations across data center, cloud, wireless, SD-WAN, campus, and other network environments.
Key Stakeholders
- AI in Network Solution Vendors
- Network Equipment and Infrastructure Providers
- Network Monitoring & Observability Solution Providers
- Network Automation & Orchestration Solution Providers
- DDI and DNS Management Solution Providers
- Network Security Solution Providers
- AI/ML Technology and Platform Providers
- Cloud Service Providers and Hyperscalers
- System Integrators (SIs) and Technology Consulting Firms
- Managed Network Service Providers (MNSPs) and Managed Service Providers (MSPs)
- Value-added Resellers (VARs), Distributors, and Channel Partners
- Telecommunication Operators and Communication Service Providers (CSPs)
- Data Center and Colocation Service Providers
- Enterprise Network Operators/Large Enterprises
Report Objectives
- To determine, segment, and forecast the AI in network market based on offerings (solutions and services), end users, and regions in terms of value
- To forecast the size of the market segments across five main regions: North America, Europe, Asia Pacific, Middle East & Africa, and Latin America
- To provide detailed information about the major factors (drivers, restraints, opportunities, and challenges) influencing the growth of the market
- To study the complete value chain and related industry segments and perform a value chain analysis of the market landscape
- To strategically analyze the macro and micromarkets with respect to individual growth trends, prospects, and contributions to the total market
- To analyze the industry trends, pricing data, patents, and innovations related to the market
- To analyze opportunities for stakeholders by identifying high-growth market segments
- To profile the key players in the market and comprehensively analyze their market share/ranking and core competencies
- To track and analyze competitive developments, such as mergers & acquisitions, product launches & developments, partnerships, agreements, collaborations, business expansions, and R&D activities
Available customizations:
With the given market data, MarketsandMarkets offers customizations per the company’s specific needs. The following customization options are available for the report:
Geographic Analysis
- Further break-up of the Asia Pacific market into countries contributing 75% to the regional market size
- Further break-up of the North American market into countries contributing 75% to the regional market size
- Further break-up of the Latin American market into countries contributing 75% to the regional market size
- Further break-up of the Middle East & African market into countries contributing 75% to the regional market size
- Further break-up of the European market into countries contributing 75% to the regional market size
Company Information
- Detailed analysis and profiling of additional market players (up to 5)
Get the Full Artificial Intelligence (AI) in Networks Market Report
Full forecast, segment splits, and company analysis for all Artificial Intelligence (AI) in Networks Market.
- Canada Artificial Intelligence (AI) in Networks Market
- Mexico Artificial Intelligence (AI) in Networks Market
- Germany Artificial Intelligence (AI) in Networks Market
- UK Artificial Intelligence (AI) in Networks Market
- France Artificial Intelligence (AI) in Networks Market
- Italy Artificial Intelligence (AI) in Networks Market
- Rest Of Europe Artificial Intelligence (AI) in Networks Market
- China Artificial Intelligence (AI) in Networks Market
- Japan Artificial Intelligence (AI) in Networks Market
- South Korea Artificial Intelligence (AI) in Networks Market
- Rest Of Asia Pacific Artificial Intelligence (AI) in Networks Market
Need a Tailored Report?
Customize this report to your needs
Get 10% FREE Customization
Customize This Report