Asia Pacific Automotive Conformal Coatings Market (2024-2029)

The Asia Pacific Automotive Conformal Coatings Market was valued at $1282.5 Million in 2024 and projected to reach to $2299.2 Million by 2029, representing a compound annual growth rate of 10.2%. Asia Pacific's automotive conformal coatings market is positioned for exceptional growth through 2029, driven by the region's dominance in vehicle manufacturing and accelerating EV adoption.


| Market Size in | USD 26.32 MN |
| Market Forecast in | |
| CAGR | |
| Forecast Period | |
| Units Considered | Value (USD MN) |
Asia Pacific Automotive Conformal Coatings Market Trends and Insights
- Asia Pacific's rapid automotive electrification, increasing vehicle production volumes, and stringent environmental regulations are driving demand for advanced protective coatings across the region.
- The market in Asia Pacific is benefiting from rising adoption of electric vehicles and hybrid technologies, which require enhanced circuit board protection and reliability in harsh operating conditions. Asia Pacific's conformal coatings market growth is underpinned by expanding manufacturing capabilities and supply chain consolidation across China, India, Japan, and Southeast Asia.
- Between 2024 and 2029, Asia Pacific is expected to capture significant market share as automotive OEMs and Tier-1 suppliers invest in coating technologies to meet durability and performance standards.
- The region's competitive cost structure and technological innovation position Asia Pacific as a critical hub for conformal coating adoption in the global automotive sector..
Key Market Statistics
- CAGR (2024-2029) 10.2% CAGR
- Market Size, 2024 ~USD 1282.5 Million
- Forecast, 2029 ~USD 2299.2 Million
- Geography Asia Pacific
Asia Pacific Automotive Conformal Coatings Market Overview
Rapid Electrification Drive :
Asia Pacific's automotive electrification surge is accelerating demand for conformal coatings to protect advanced electronic components in EVs and hybrid vehicles, particularly in China, Japan, and India.
Production Volume Leadership :
The region accounts for over 50% of global vehicle production, with major manufacturing hubs in China, Japan, and India driving substantial coating requirements across OEM and aftermarket segments.
Stringent Environmental Standards :
Increasingly strict environmental regulations across Asia Pacific nations are mandating advanced protective coatings to meet durability and sustainability requirements, boosting market adoption.
High Growth Trajectory :
Asia Pacific's 10.2% CAGR (2024-2029) outpaces the global 10% rate, with market expansion from USD 1,282.5 million to USD 2,299.2 million, reflecting region-specific growth momentum.
Asia Pacific Automotive Conformal Coatings Market Dynamics
- China's leadership in electric vehicle production, combined with Japan's advanced automotive technology sector and India's emerging manufacturing capabilities, creates a dynamic market landscape.
- Stringent environmental regulations and increasing consumer demand for vehicle longevity are propelling manufacturers to invest in superior protective coating solutions. The market's expansion is further supported by rising disposable incomes, growing automotive aftermarket services, and substantial OEM investments in next-generation vehicle platforms.
- Strategic partnerships between coating manufacturers and automotive suppliers, coupled with technological innovations in nanotechnology and eco-friendly formulations, will continue to drive market penetration across Asia Pacific's diverse automotive ecosystem..
Market Ecosystem


OVERVIEW
Source: Secondary Research, Interviews with Experts, MarketsandMarkets Analysis
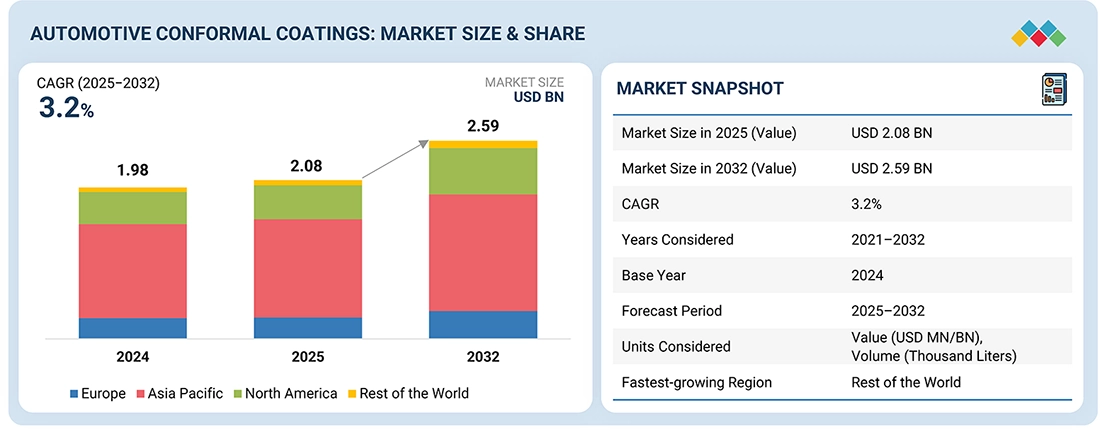
The automotive conformal coatings market is projected to reach USD 2.59 billion by 2032 from USD 2.08 billion in 2025, at a CAGR of 3.2%. The automotive conformal coatings market is increasingly driven by architecture-level changes in vehicle electronics, where higher power density, tighter PCB layouts, and centralized ECUs demand enhanced protection against thermal, electrical, and environmental stress. The shift toward electrified powertrains and high-voltage systems is driving the need for coatings with enhanced dielectric strength and thermal stability to ensure reliability in inverters, onboard chargers, and battery management units. Automakers are also standardizing conformal coatings across ECUs and sensors to support ADAS, connectivity, and software-defined vehicle functions, without requiring redesign of the hardware. In Europe, stringent functional safety and durability regulations are accelerating the adoption of high-performance and precision-applied coatings, while North America’s growth is supported by compute-heavy ECUs, high-load EV electronics, and long warranty expectations. Asia-Pacific expansion is fueled by high-volume electronics manufacturing, harsh operating environments, and cost-optimized coating integration, making conformal coatings a critical enabler of reliable, scalable automotive electronics across regions.
KEY TAKEAWAYS
-
BY COMPONENTBy Component, PCBs are expected to register the highest CAGR of 3.9%.
-
BY VEHICLE TYPEBy vehicle type, the heavy commercial vehicles segment is expected to grow at the fastest rate from 2025 to 2032.
-
BY MATERIALThe acrylic segment is expected to dominate the market.
-
By EV TypeBy EV type, the BEV segment is expected to lead the market during the forecast period.
-
BY REGIONAsia Pacific is expected to lead the market, with a 61% share in 2025.
-
COMPETITIVE LANDSCAPE: KEY PLAYERSKey players such as Dow, Henkel AG & CO. KGAA, H.B. Fuller, and Shin-etsu Chemical Co. Ltd are advancing high-performance acrylic, silicone, and specialty conformal coating chemistries, along with precision selective-coating and vapor-deposition technologies, to enhance the reliability, thermal stability, and durability of automotive electronics. Their innovation efforts focus on protecting ECUs, PCBs, power electronics, sensors, and LED systems used in electric, connected, and autonomous vehicles, enabling higher electronics density, longer service life, and improved functional safety across modern automotive platforms.
-
COMPETITIVE LANDSCAPE: STARTUPSSA (Switzerland), Peters Group (Germany), CSL Silicones Inc. (Canada), and emerging US players are focused on high-reliability silicone and specialty conformal coatings optimized for automotive ECUs, PCBs, sensors, and power electronics. Their developments emphasize high-temperature resistance, chemical durability, precise selective coating, and low-stress curing, supporting higher electronic density and long-life performance in EV, ADAS, and connected vehicle applications.
The growth of this market is primarily driven by the increasing use of automotive electronics in vehicles and various technological advancements in the application methods of conformal coatings.
TRENDS & DISRUPTIONS IMPACTING CUSTOMERS' CUSTOMERS
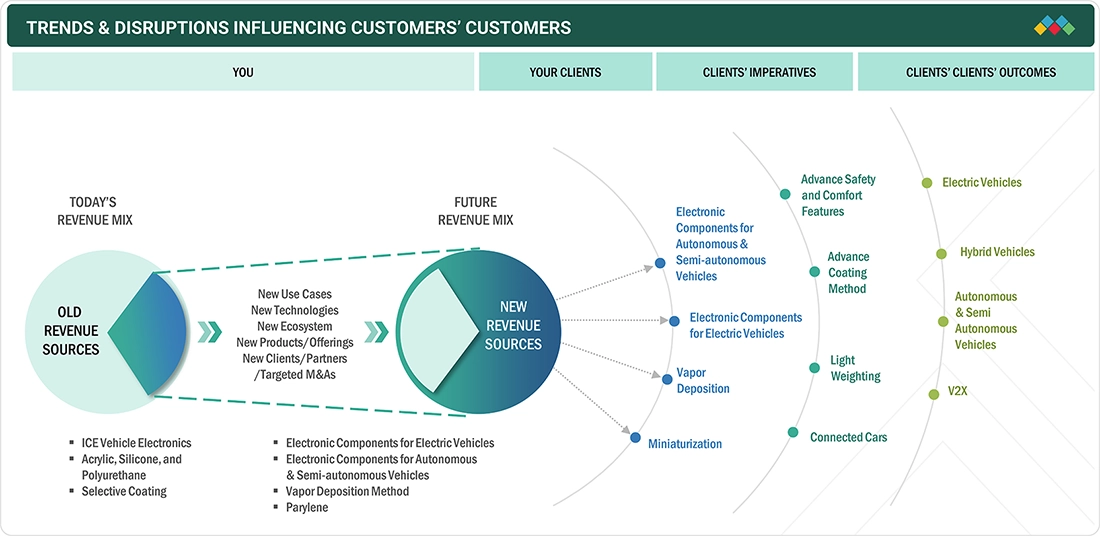
Changes in demand and emerging technology shifts in the automotive conformal coatings market are pushing OEMs and Tier-I suppliers toward more advanced protection solutions for high-density, software-driven vehicle electronics. The transition from ICE electronics to electric, hybrid, connected, and autonomous vehicle platforms is accelerating the use of compact, high-voltage, and high-frequency electronic architectures, increasing exposure to thermal stress, moisture ingress, and signal-integrity risks. This shift is driving adoption of selective coating, vapor deposition, and parylene-based solutions, alongside materials optimized for miniaturization, lightweighting, and automated application. As advanced safety systems, V2X connectivity, and OTA-enabled ECUs become standard, coating performance is no longer a passive requirement but a critical enabler of electronics reliability and lifecycle durability. These evolving requirements are reshaping material selection, application methods, and process automation across the value chain, unlocking new revenue opportunities for suppliers offering high-performance, EV-ready, and precision-applied conformal coating technologies.
Source: Secondary Research, Interviews with Experts, MarketsandMarkets Analysis
MARKET DYNAMICS

Level
-
Increasing adoption of electronics in vehicles

-
Growing popularity of electric vehicles


Level
-
Size reduction and consolidation of component

-
Costly removal and repair of conformal coatings


Level
-
Innovations in autonomous and connected mobility

-
Technological advancements in conformal coatings


Level
-
Lack of technical knowledge

-
Stringent government regulations

Source: Secondary Research, Interviews with Experts, MarketsandMarkets Analysis
Driver: Increasing adoption of electronics in vehicles
The rising penetration of safety, comfort, and emission-control features is sharply increasing the electronic content per vehicle, with sensor counts surpassing 200 per car. These sensors and control modules operate in thermally stressed, contamination-prone environments, making conformal coatings essential to maintaining signal accuracy and long-term reliability. At the same time, ECUs are evolving from single-function controllers to high-performance units that manage braking, powertrain, thermal systems, and vehicle security. In EVs, where ECU density, voltage exposure, and replacement costs are significantly higher than in ICE vehicles, conformal coatings play a critical role in protecting high-value electronics, reducing failure risk, and supporting extended warranty requirements—directly accelerating market adoption.
Restraint: Size reduction and consolidation of the component
Rapid miniaturization of automotive electronics is structurally reducing the amount of conformal coating per vehicle. The shift toward HDI PCBs places components closer together, enabling smaller boards with lower coating surface area despite rising electronic complexity. In parallel, OEMs and Tier-1 suppliers are consolidating multiple ECUs into centralized, high-compute domain or zonal controllers. This architecture replaces several mid-density boards with a single high-power PCB, improving packaging efficiency while reducing total coating volume. As a result, while electronic content per vehicle continues to rise, coating demand is increasingly decoupled from unit growth, acting as a moderating restraint on overall market expansion.
Opportunity: Innovation in autonomous and connected mobility
Automotive electronics are transitioning from a support function to a core cost driver, with their share of vehicle value projected to approach half by 2030. The rapid penetration of connected-car features, including sensor fusion, V2X communication, real-time diagnostics, and cloud-linked control systems, is sharply increasing the density and criticality of onboard electronics. As OEMs move toward Level 2+ and Level 3 autonomy, the reliability of ECUs, sensors, and communication modules becomes non-negotiable, particularly under thermal, moisture, and vibration stress. This creates a structural opportunity for conformal coatings as an enabling technology that safeguards high-value electronics as the industry shifts from connectivity-led vehicles to fully autonomous platforms.
Challenge: Lack of technical knowledge
Conformal coatings are critical for protecting automotive electronics from moisture, heat, corrosion, chemicals, and electrical failure, but their effectiveness depends on material selection and application quality. Silicone coatings are preferred over acrylic in vehicles due to higher thermal stability and superior moisture resistance. Challenges arise from improper surface preparation, insufficient coverage, trapped air bubbles, or uneven thickness, all of which can compromise protection and lead to PCB failure, highlighting the need for precise process control.
AUTOMOTIVE CONFORMAL COATINGS MARKET: COMMERCIAL USE CASES ACROSS INDUSTRIES
| COMPANY | USE CASE DESCRIPTION | BENEFITS |
|---|---|---|
 |
Specification and validation of conformal coatings for ECUs, PCBs, sensors, battery packs, power electronics, lighting modules, and infotainment systems across ICE, HEV, and BEV platforms | Improves electronic reliability under thermal, moisture, and vibration stress | Reduces field failures and recalls | Supports higher electronics density required for ADAS, electrification, and software-defined vehicles |
 |
Application of acrylic, silicone, epoxy, or parylene coatings on high-density PCBs and miniaturized electronic assemblies used in ADAS, body electronics, and EV power management systems | Enables miniaturization, improves insulation and corrosion resistance | Supports high-voltage and high-frequency electronics | Increases yield in harsh automotive environments |
 |
Integration of selective, spray, or vapor-phase conformal coating processes within ECU, sensor, and power-module assembly lines to meet OEM durability and lifetime performance requirements | Enhances product robustness and extends component lifecycle | Ensures compliance with OEM quality standards | Lowers warranty exposure for safety-critical electronics |
 |
Development of application-specific coating chemistries optimized for under-hood temperatures, high-voltage EV systems, LED optics, and automated selective-coating equipment | Creates differentiation through high-performance materials | Secures long-term supply agreements with OEMs and Tier-1s | Captures EV-driven demand growth | Strengthens positioning in premium and safety-critical automotive electronics |
Logos and trademarks shown above are the property of their respective owners. Their use here is for informational and illustrative purposes only.
MARKET ECOSYSTEM
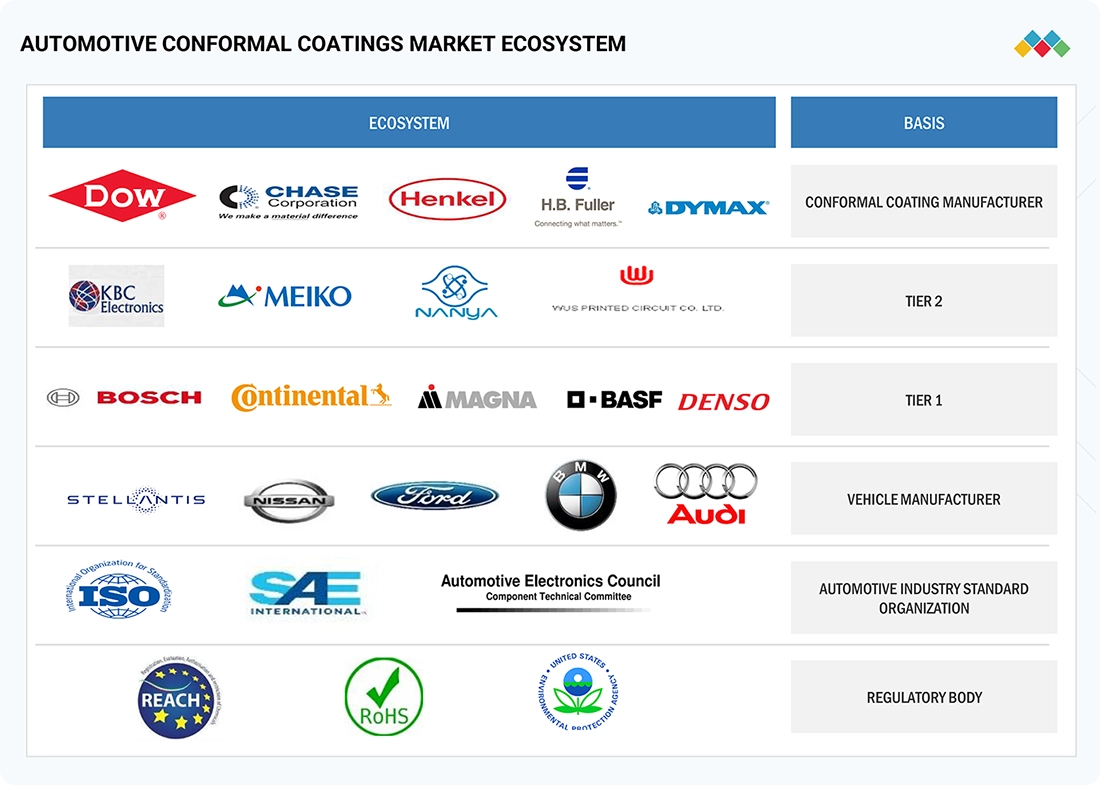
The automotive conformal coatings market features the latest technologies, diversified portfolios, and strong global distribution networks. The major players in the global automotive conformal coatings market include Dow (US), Henkel AG & CO. KGAA (Germany), H.B. Fuller (US), and Shin-Etsu Chemical Co. Ltd. (Japan).
Logos and trademarks shown above are the property of their respective owners. Their use here is for informational and illustrative purposes only.
MARKET SEGMENTS
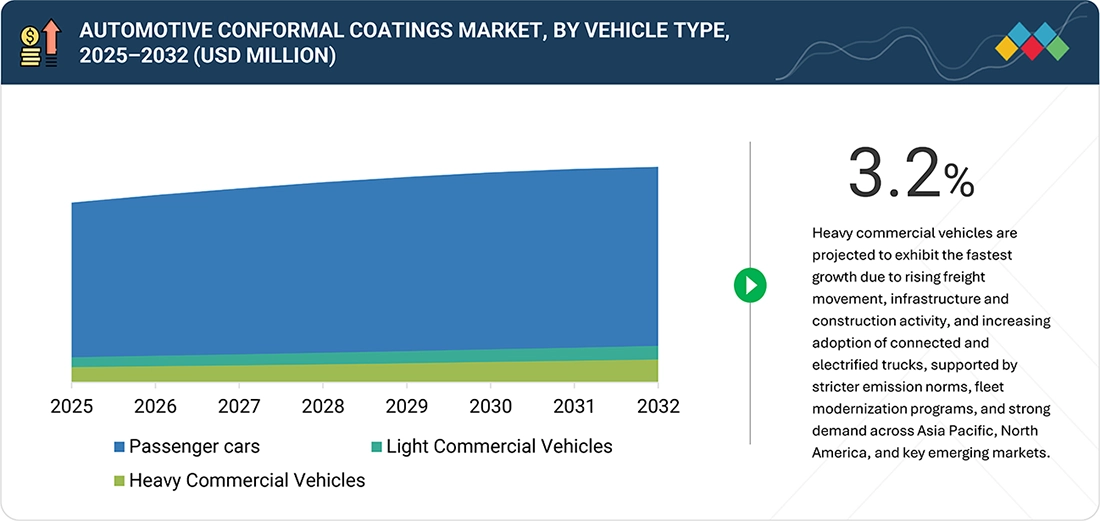
Source: Secondary Research, Interviews with Experts, MarketsandMarkets Analysis
Automotive Conformal Coatings Market, By Component
ECUs represent the dominant segment in the automotive conformal coatings market due to their rapid proliferation, rising compute density, and harsh operating environments. Modern vehicles integrate centralized and domain ECUs for powertrain control, ADAS, thermal management, and body electronics, many of which are mounted in engine bays or near high-voltage systems, exposing them to sustained heat, vibration, and moisture. The shift toward EV and software-defined vehicle architectures further increases ECU value and failure risk, as battery management, inverter control, and vehicle-domain controllers rely on uninterrupted electronic performance. As ECU consolidation raises functional criticality per unit, OEMs increasingly mandate conformal coatings to ensure thermal stability, long-term reliability, and functional safety compliance, reinforcing ECU dominance in conformal coating demand.
Automotive Conformal Coatings Market, By Material Type
Silicone conformal coatings hold a critical position in the automotive conformal coatings market due to their exceptional thermal stability and environmental resilience, making them the preferred choice for under-the-hood electronics, power electronics, and LED modules. Their ability to maintain electrical insulation and mechanical integrity across extreme temperature cycles supports reliable operation in EV inverters, battery control units, and high-heat PCBs. Silicone’s resistance to moisture, chemicals, and corrosion further strengthens its adoption in harsh automotive environments. However, difficult reworkability and the need for thicker coating layers limit its use in ultra-miniaturized electronics such as MEMS and dense IoT-grade assemblies, confining its dominance to high-stress automotive applications rather than compact modules.
Automotive Conformal Coatings Market, by Vehicle Type
Passenger cars dominate the automotive conformal coatings market, primarily due to their high production volumes and the deepest penetration of electronics per vehicle. Unlike commercial vehicles, passenger cars increasingly integrate multiple ECUs, high-density PCBs, ADAS sensors, infotainment modules, digital instrument clusters, LED lighting, and body-control electronics across even mid-priced models, significantly expanding the coated surface area per unit. The rapid shift toward electrified and software-defined passenger platforms further amplifies coating demand, as battery management systems, power electronics, and centralized compute units require robust protection against moisture, thermal cycling, and voltage stress. In addition, passenger cars are exposed to diverse operating environments urban humidity, dust, temperature extremes, and vibration, necessitating conformal coatings to ensure long-term electronic reliability and warranty compliance. OEM focuses on lifecycle durability, reduced field failures, and regulatory safety validation, making conformal coating a standardized, non-negotiable process in passenger car electronics manufacturing, reinforcing this segment’s dominance by vehicle type.
Automotive Conformal Coatings Market, By Application
Selective coating dominates the automotive conformal coatings market by application because it aligns most effectively with the high-density, mixed-technology electronics used in modern vehicles. Automotive PCBs increasingly combine sensitive connectors, test points, sensors, and heat-dissipating components that must remain uncoated, making full-coverage methods such as dipping or vapor deposition impractical. Selective coating enables precise, programmable deposition only where protection is required, ensuring consistent film thickness while avoiding masking-related rework and yield losses common in spray and brush processes. As OEMs transition to centralized ECUs, HDI boards, and automated electronics assembly, selective coating integrates seamlessly with inline manufacturing, enabling higher throughput, reduced material waste, and improved process repeatability. Compared to dipping and spray coating, it reduces contamination risk and improves reliability in harsh automotive environments, making it the preferred method for large-scale production of passenger vehicle and EV electronics.
REGION
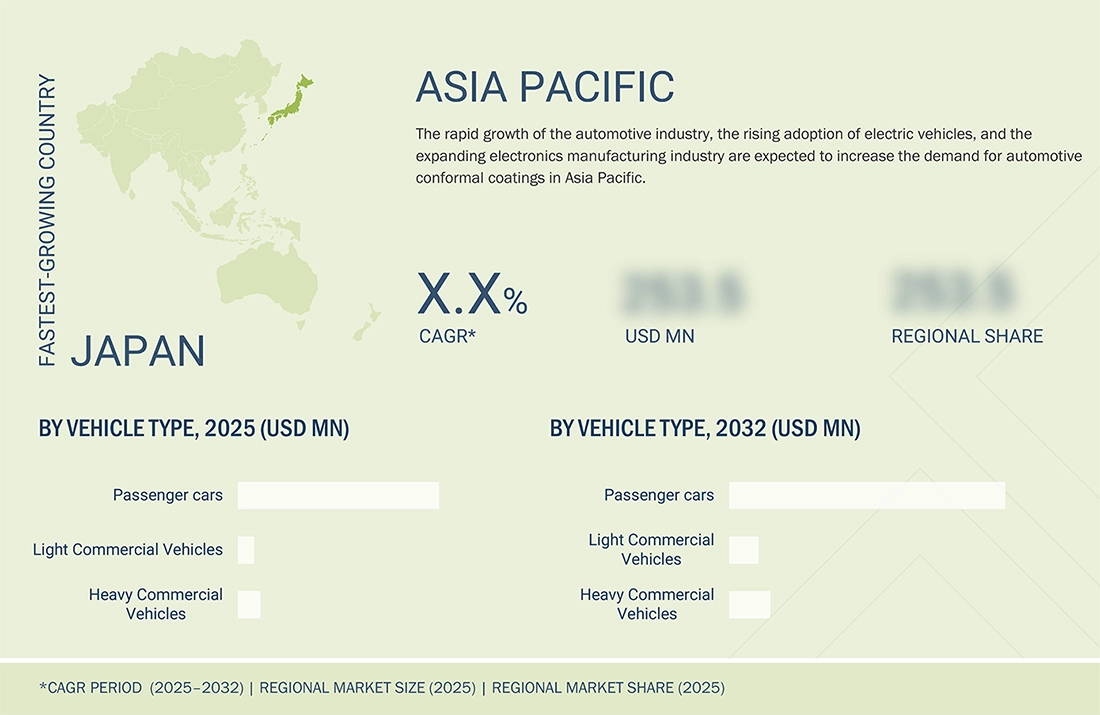
Asia Pacific is expected to be the largest region in the global automotive conformal coatings market during the forecast period.
Asia Pacific remains the largest automotive conformal coatings market, driven by its dominance in passenger car and EV production, particularly in China, Japan, South Korea, and increasingly India. The region is driving the global deployment of electronics-intensive vehicles, in which compact and mid-size passenger cars feature high ECU counts for powertrain control, ADAS, body electronics, and infotainment, directly increasing coating demand per vehicle. China anchors regional demand through large-scale BEV manufacturing by OEMs such as BYD, SAIC, Geely, and Tesla, where battery management systems, inverters, and high-density PCBs require selective and high-reliability conformal coatings. Japan and South Korea contribute through advanced electronics architectures adopted by Toyota, Honda, Hyundai, and Kia, emphasizing durability, long vehicle lifecycles, and high under-the-hood reliability standards. India is emerging as a volume-driven growth market as safety regulations and feature penetration push conformal coatings into mid-priced passenger cars. The presence of global OEM manufacturing hubs alongside strong regional electronics and materials suppliers ensures sustained investment in localized coating capacity, reinforcing Asia Pacific’s leadership through 2032.
AUTOMOTIVE CONFORMAL COATINGS MARKET: COMPANY EVALUATION MATRIX
In the automotive conformal coatings market matrix, Henkel AG & Co. KGaA (Star) leads with a strong global manufacturing footprint, broad acrylic and silicone coating portfolios, and deep integration with Tier-I automotive electronic suppliers across ECUs, PCBs, sensors, and power electronics. Its early alignment with EV and ADAS reliability standards and automated selective-coating processes reinforces its leadership across major automotive regions. Dymax (Emerging Leader) is rapidly gaining share by scaling high-performance silicone and specialty coatings optimized for high-temperature EV and under-hood electronics, supported by strong relationships with Japanese and Korean OEMs and expanding penetration into Europe and North America through EV-focused electronics programs.
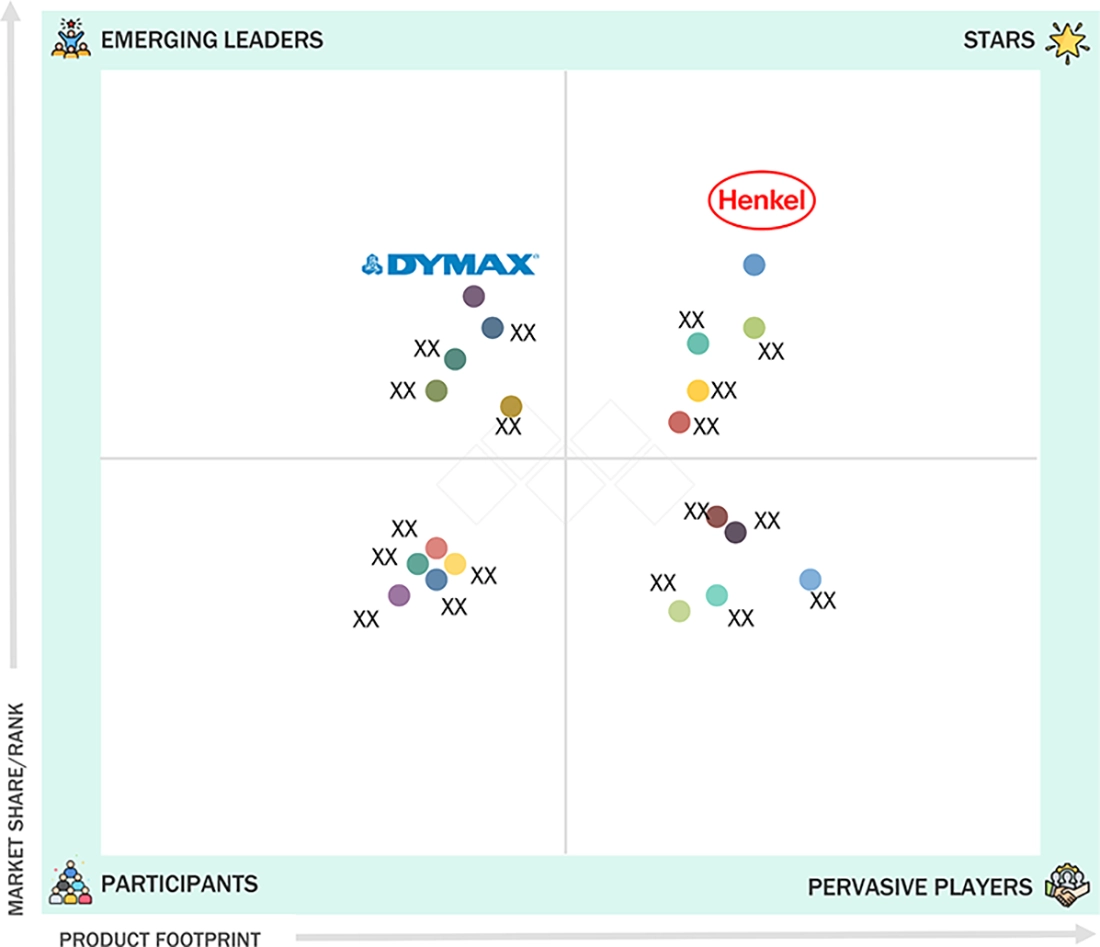
Source: Secondary Research, Interviews with Experts, MarketsandMarkets Analysis
KEY MARKET PLAYERS
- Dow
- Henkel AG & CO. KGAA
- Chase Corporation
- H.B. Fuller
- Shin-etsu Chemical Co., Ltd.
- ALTANA AG
- Electrolube
- Dymax
- CHT Group
MARKET SCOPE
| REPORT METRIC | DETAILS |
|---|---|
| Market Size in 2025 (Value) | USD 2.08 BN |
| Market Size in 2032 (Value) | USD 2.59 BN |
| Growth Rate | CAGR of 3.2% from 2025 to 2032 |
| Years Considered | 2021–2032 |
| Base Year | 2024 |
| Forecast Period | 2025–2032 |
| Units Considered | Value (USD MN/BN), Volume (Thousand Units) |
| Report Coverage | Revenue forecast, company ranking, competitive landscape, growth factors, and trends |
| Segments Covered |
|
| Regional Scope | Asia Pacific, Europe, North America, Rest of the world |
WHAT IS IN IT FOR YOU: AUTOMOTIVE CONFORMAL COATINGS MARKET REPORT CONTENT GUIDE
DELIVERED CUSTOMIZATIONS
We have successfully delivered the following deep-dive customizations:
| CLIENT REQUEST | CUSTOMIZATION DELIVERED | VALUE ADDS |
|---|---|---|
| OEMs and Tier-I suppliers are evaluating next-generation electronic architectures for ICE, HEV, and BEV platforms with higher ECU density and compact PCBs | Component-level assessment of conformal coating requirements for ECUs, HDI PCBs, sensors, and LED modules across under-hood, chassis, and cabin zones | Component-level assessment of conformal coating requirements for ECUs, HDI PCBs, sensors, and LED modules across under-hood, chassis, and cabin zones |
RECENT DEVELOPMENTS
- December 2025 : Henkel introduced the Bergquist TGF-10000, a new high-performance thermal gap filler engineered for ultra-demanding electronics applications that require exceptional heat dissipation and mechanical compliance. The material delivers very high thermal conductivity and robust performance under thermal cycling and stress, making it suitable for advanced power electronics used in electric vehicles, renewable energy inverters, and industrial systems.
- October 2025 : Dymax announced the release of its new 9773 ruggedized adhesive, formulated to meet the NASA/ASTM E595 low-outgassing standard, making it suitable for demanding environments where volatile emissions must be minimized. The material delivers robust adhesion and environmental resistance, making it suitable for applications in electronics, aerospace, and other high-performance industries that require reliable bonding with stringent outgassing specifications.
- August 2025 : ALTANA announced that its specialty chemicals division BYK has established a new company, “BYK do Brasil,” headquartered in São Paulo, to strengthen its presence and customer proximity in the South American market. This strategic move reflects BYK’s focus on tapping into the economic growth dynamics of key industries such as paints/coatings, plastics, and cosmetics in the region, enabling faster response times, closer cooperation with partners and customers, and deeper market development.
- July 2025 : Henkel completed the acquisition of Nordbak, a South African manufacturer of industrial adhesives, sealants, and coating solutions, to strengthen its Adhesive Technologies footprint in Africa. The transaction enhances Henkel’s local production capabilities, broadens its product portfolio for regional customers, and supports tailored solutions across automotive, construction, packaging, and industrial applications.
- May 2025 : H.B. Fuller is expanding its manufacturing capabilities across the IMEA region (India, the Middle East, and Africa), emphasizing localized production, technical service, and application expertise to better serve regional customers. It outlines how investments in plants, labs, and supply-chain infrastructure enable faster delivery, customized adhesive solutions, and stronger support for industries such as automotive, construction, electronics, hygiene, and packaging across high-growth IMEA markets.
- May 2025 : CHT showcased its latest sustainable, high-performance products and solutions at the European Coatings Show 2025 in Nuremberg, highlighting innovations across coatings, paints, inks, and specialty applications. The company presented advanced solutions focused on sustainability, performance enhancement, and regulatory compliance, reinforcing CHT’s position as a technology partner for the global coatings and materials industry.
Related Ecosystem
Automotive Materials
- Light Commercial Vehicles (LCVs)
- Battery Electric Vehicle (BEV)
- Hybrid Electric Vehicle (HEV)
- Fuel Cell Electric Vehicle (FCEV)
- Agricultural Tractors
- AISIN CORPORATION
- GORKOVSKY AVTOMOBILNY ZAVOD
- Continental ag
- Basf se
- BOSCH LIMITED
Key Takeaways
- Asia Pacific's automotive conformal coatings market will grow from USD 1,282.5 million in 2024 to USD 2,299.2 million by 2029, representing a 10.2% CAGR.
- Asia Pacific's electric vehicle boom and advanced driver-assistance systems (ADAS) adoption are primary catalysts for conformal coating demand in the region.
- Asia Pacific manufacturers benefit from cost advantages and proximity to major automotive production hubs, strengthening regional market competitiveness.
- Asia Pacific's regulatory environment and OEM quality standards are accelerating adoption of high-performance conformal coating solutions across the automotive supply chain.
Automotive Conformal Coatings Market Report Scope
| Report Metric | Details |
|---|---|
| Base Year | 2024 |
| Fastest Growing Segment | BEV (Ev Type) |
| Forecast Period | 2024-2029 |
| Growth Rate | CAGR of 10% from 2024 to 2029 |
| Largest Segment | SELECTIVE COATING (Application Method) |
| Market Size Base Year (Billions) | ~USD 1.98 (2024) |
| Revenue Forecast (Billions) | ~USD 3.18 (2029) |
| Segments Covered | Material, Component, Vehicle Type, Ev Type, Application Method |
Asia Pacific Automotive Conformal Coatings Market Report Segmentation
5 segment dimensions are covered across the global market.
By Material
- Acrylic
- Epoxy
- Parylene
- Polyurethane
- Silicone
By Component
- Battery Casing
- Ecu
- Infotainment System
- Led
- Pcb
- Sensor
By Vehicle Type
- Heavy Commercial Vehicle
- Light Commercial Vehicle
- Passenger Car
By Ev Type
- Bev
- Hev/Phev
By Application Method
- Brush Coating
- Dipping
- Selective Coating
- Spray Coating
- Vapor Deposition
Target Audience
- Coating Manufacturers & Suppliers : Need Asia Pacific market data to develop region-specific product portfolios, optimize manufacturing capacity, and identify high-growth segments within China, Japan, and India.
- Automotive OEMs & Tier-1 Suppliers : Require detailed market intelligence on coating demand trends, regulatory requirements, and competitive offerings to inform sourcing decisions and supply chain strategies in Asia Pacific.
- Investment & Private Equity Firms : Seek comprehensive market sizing and growth forecasts for Asia Pacific to evaluate M&A opportunities, portfolio company valuations, and capital allocation in the automotive coatings sector.
- Market Entry & Expansion Strategists : Need country-level market analysis and competitive insights for Asia Pacific to assess market viability, identify entry barriers, and develop localized go-to-market strategies.
- Industry Consultants & Research Firms : Require granular Asia Pacific data and forecasts to support client advisory services, competitive analysis, and strategic recommendations in the automotive conformal coatings space.
Countries within Asia Pacific - compare and drill down
| Country | 2025 size (native) |
|---|---|
| China | USD 25572 Million |
| Japan | USD 6470 Million |
| India | USD 4435 Million |
Country market size visualization
Reasons to Buy this Report
- Regional Market Sizing & Forecasts : Obtain precise market valuations for Asia Pacific (USD 1,282.5M in 2024) with country-level breakdowns for China, Japan, and India to inform regional expansion strategies.
- EV & Electrification Insights : Understand how rapid automotive electrification across Asia Pacific is reshaping conformal coating demand, material specifications, and competitive positioning in the EV supply chain.
- Regulatory & Compliance Framework : Access detailed analysis of stringent environmental regulations driving coating adoption across Asia Pacific nations, enabling compliant product development and market entry strategies.
- Competitive Landscape Analysis : Identify key market players, manufacturing hubs, and distribution channels specific to Asia Pacific's automotive conformal coating ecosystem for competitive benchmarking.
- Growth Opportunity Identification : Leverage 10.2% CAGR projections and country-specific growth drivers to prioritize investment decisions and partnership opportunities across Asia Pacific's high-growth automotive markets.
Frequently asked questions
What is the market size of automotive conformal coatings in Asia Pacific?
Asia Pacific's automotive conformal coatings market was valued at USD 1,282.5 million in 2024 and is forecast to reach USD 2,299.2 million by 2029.
What is the CAGR for Asia Pacific's automotive conformal coatings market?
Asia Pacific's automotive conformal coatings market is projected to grow at a compound annual growth rate (CAGR) of 10.2% from 2024 to 2029.
Which countries drive growth in Asia Pacific's conformal coatings market?
China, Japan, India, and South Korea are the primary growth drivers in Asia Pacific, supported by large-scale automotive manufacturing and EV adoption initiatives.
Why is Asia Pacific's conformal coatings market growing faster than other regions?
Asia Pacific's market growth is accelerated by rapid EV adoption, increasing vehicle electrification, cost-competitive manufacturing, and stringent automotive quality standards across the region.
What applications drive conformal coating demand in Asia Pacific's automotive sector?
Key applications in Asia Pacific include PCB protection in engine control units, battery management systems, ADAS modules, and infotainment systems in electric and hybrid vehicles.
RESEARCH METHODOLOGY
Get the Full Automotive Conformal Coatings Market Report
Full forecast, segment splits, and company analysis for all Automotive Conformal Coatings Market.
Need a Tailored Report?
Customize this report to your needs
Get 10% FREE Customization
Customize This Report
