Canada Automotive Test Equipment Market (2025-2030)

The Canada Automotive Test Equipment Market was valued at $91.8 Million in 2025 and projected to reach to $122.2 Million by 2030, representing a compound annual growth rate of 4.2%. Canada's automotive test equipment market is poised for steady expansion through 2030, supported by the country's established manufacturing ecosystem and growing investment in EV production facilities.


| Market Size in | USD 26.32 MN |
| Market Forecast in | |
| CAGR | |
| Forecast Period | |
| Units Considered | Value (USD MN) |
Canada Automotive Test Equipment Market Trends and Insights
- This growth trajectory reflects Canada's strengthening automotive manufacturing sector and increasing demand for advanced diagnostic and testing solutions.
- Canada's position as a major automotive hub in North America drives sustained investment in test equipment infrastructure to meet regulatory compliance and quality assurance standards. The Canadian market benefits from the country's established vehicle production facilities and the rising complexity of modern vehicle systems requiring sophisticated testing capabilities.
- Between 2025 and 2030, Canada is expected to see accelerated adoption of electric vehicle testing equipment and emissions compliance solutions.
- Canada's commitment to automotive innovation and manufacturing excellence positions the market for steady expansion, supported by both domestic OEM requirements and cross-border supply chain integration with the broader North American automotive ecosystem..
Key Market Statistics
- CAGR (2025-2030) 4.2% CAGR
- Market Size, 2025 ~USD 91.8 Million
- Forecast, 2030 ~USD 122.2 Million
- Country Canada
Canada Automotive Test Equipment Market Overview
Market Valuation :
Canada's automotive test equipment market is valued at $91.8 million in 2025, with projected growth to $122.2 million by 2030, driven by robust manufacturing infrastructure and technological advancement.
Strong CAGR Performance :
The Canadian market demonstrates a 4.2% CAGR from 2025-2030, outpacing the global average of 3.9%, indicating accelerated adoption of advanced diagnostic and testing solutions in the region.
North American Manufacturing Hub :
Canada's strategic position as a major automotive manufacturing center in North America, with significant OEM and Tier-1 supplier presence, drives sustained demand for sophisticated test equipment solutions.
Technology Integration Trends :
Increasing adoption of electric vehicle testing, autonomous vehicle diagnostics, and Industry 4.0 compliance requirements are reshaping Canada's automotive test equipment landscape and creating new market opportunities.
Canada Automotive Test Equipment Market Dynamics
- Major automotive manufacturers and suppliers operating in Canada are increasingly prioritizing advanced diagnostic capabilities to meet stringent quality standards and regulatory requirements.
- The shift toward electrification and autonomous vehicle development is accelerating demand for specialized testing solutions, particularly in battery diagnostics, powertrain validation, and safety systems verification.
- Government incentives for clean vehicle manufacturing and R&D investments further strengthen market fundamentals. The competitive landscape in Canada is characterized by a mix of global equipment providers and regional specialists adapting to local manufacturing needs.
- Integration of AI-powered diagnostics, real-time data analytics, and cloud-based testing platforms represents a significant growth vector.
- Supply chain resilience initiatives and nearshoring trends are expected to bolster domestic automotive production, creating sustained demand for test equipment upgrades and modernization across manufacturing facilities throughout the forecast period..
Market Ecosystem
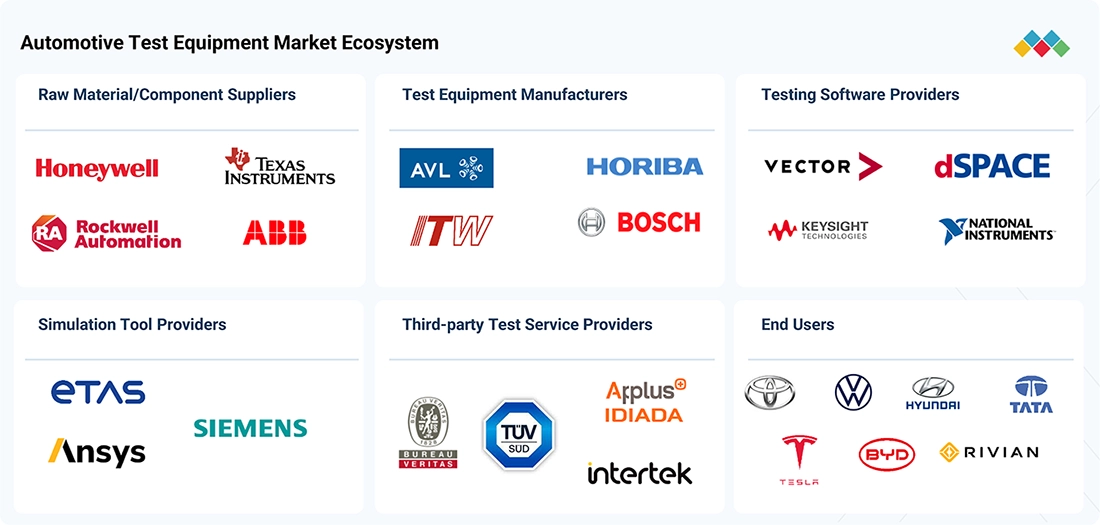
AUTOMOTIVE TEST EQUIPMENT MARKET SIZE, SHARE & ANALYSIS: COMMERCIAL USE CASES ACROSS INDUSTRIES
| COMPANY | USE CASE DESCRIPTION | BENEFITS |
|---|---|---|
 |
Provides battery, e-motor, inverter, powertrain, and vehicle test systems for EV development, calibration, durability, and validation. | Higher test coverage, reduced prototype dependency, and faster EV powertrain development. |
 |
Deploys battery cyclers, e-motor test benches, chassis dynamometers, and powertrain test systems across electrification and vehicle testing programs. | Higher testing throughput, precise performance characterization, and improved laboratory utilization. |
 |
Uses modular PXI-based instrumentation, data acquisition, real-time control, and HIL systems for battery, power electronics, ECU, and vehicle testing. | Flexible test configurations, automated testing, faster data acquisition, and reduced test cycle time. |
 |
Provides automated end-of-line testing and production testing solutions for vehicle and battery manufacturing, including testing of electrical and mechanical systems. | Higher production throughput, automated quality control, reduced assembly defects, and consistent end-of-line validation. |
 |
Uses advanced test systems across powertrain, electronics, battery, ADAS, and component development to validate automotive systems under controlled operating conditions. | Faster component qualification, improved reliability, earlier fault detection, and reduced development risk. |
Logos and trademarks shown above are the property of their respective owners. Their use here is for informational and illustrative purposes only.
Related Ecosystem
Driving Support Security
- Battery Electric Vehicle (BEV)
- Hybrid Electric Vehicle (HEV)
- Light Commercial Vehicles (LCVs)
- Fuel Cell Electric Vehicle (FCEV)
- Blind Spot Detection (BSD)
- BOSCH LIMITED
- Continental ag
- DENSO Corporation
- Magna International Inc.
- ZF FRIEDRICHSHAFEN AG
Key Takeaways
- Canada's automotive test equipment market is valued at $91.8 million in 2025 and will reach $122.2 million by 2030, growing at 4.2% CAGR.
- Canada's established manufacturing base and OEM presence drive consistent demand for advanced testing and diagnostic equipment.
- Electric vehicle testing and emissions compliance solutions are key growth drivers in Canada between 2025 and 2030.
- Canada's integration within the North American automotive supply chain supports sustained market expansion and cross-border equipment adoption.
Automotive Test Equipment Market Report Scope
| Report Metric | Details |
|---|---|
| Base Year | 2025 |
| Fastest Growing Segment | EV DRIVETRAIN TESTING (Equipment) |
| Forecast Period | 2025-2030 |
| Growth Rate | CAGR of 3.9% from 2025 to 2030 |
| Largest Segment | ICE (Propulsion) |
| Market Size Base Year (Billions) | ~USD 3.66 (2025) |
| Revenue Forecast (Billions) | ~USD 4.44 (2030) |
| Segments Covered | Equipment, Application, Vehicle Type, Propulsion, End Market |
Canada Automotive Test Equipment Market Report Segmentation
5 segment dimensions are covered across the global market.
By Equipment
- Battery Test Equipment
- Chassis Dynamometer
- E-Axle Testing
- E-Motor Test Equipment
- Engine Dynamometer
- EV Drivetrain Testing
- Fuel Injection Pump Tester
- Hardware-In-The-Loop (Hil) Test Benches
- Transmission Dynamometer
- Vehicle Charging & High Voltage Test System
- Vehicle Emission Test System
- Wheel Alignment Tester
By Application
- Mobile/Tablet-Based Equipment
- Pc/Laptop-Based Equipment
By Vehicle Type
- Commercial Vehicle
- Passenger Car
By Propulsion
- EV
- ICE
By End Market
- Authorized Service Center
- OEM Assembly Plant
- R&D/Technical Center
Target Audience
- Automotive OEMs & Manufacturers : Canadian and multinational automotive manufacturers require detailed market intelligence to optimize test equipment procurement, upgrade legacy systems, and ensure compliance with evolving quality and regulatory standards.
- Tier-1 & Tier-2 Suppliers : Component suppliers and subsystem manufacturers need Canada-specific market data to benchmark testing capabilities, identify technology gaps, and make informed capital investment decisions for diagnostic equipment.
- Test Equipment Vendors & Distributors : Equipment manufacturers and regional distributors require market sizing, growth forecasts, and competitive analysis specific to Canada to develop go-to-market strategies and optimize sales resource allocation.
- Private Equity & Investment Firms : Investors evaluating acquisition targets or portfolio companies in the Canadian automotive sector need market validation, growth trajectory analysis, and competitive positioning data for due diligence and valuation.
- Consulting & Engineering Firms : Management consultants and engineering service providers advising automotive clients require Canada-specific market intelligence to support strategic planning, technology roadmaps, and operational efficiency initiatives.
Reasons to Buy this Report
- Market-Specific Growth Insights : Gain detailed understanding of Canada's 4.2% CAGR trajectory and the unique drivers differentiating it from global trends, enabling precise investment and expansion decisions in the region.
- Competitive Landscape Analysis : Identify key players, market consolidation patterns, and competitive positioning specific to Canada's automotive test equipment sector to inform strategic partnerships and market entry strategies.
- Regulatory & Compliance Framework : Understand Canada-specific regulatory requirements, emission standards, and safety certifications driving test equipment demand among OEMs and Tier-1 suppliers operating in the region.
- Technology Adoption Trends : Analyze EV testing, autonomous vehicle diagnostics, and Industry 4.0 integration patterns unique to Canadian manufacturers to align product development and marketing strategies accordingly.
- Investment & Expansion Opportunities : Identify high-growth segments, underserved customer categories, and geographic hotspots within Canada to prioritize capital allocation and establish competitive advantages in this strategic North American market.
Frequently asked questions
What is the current size of Canada's automotive test equipment market?
Canada's automotive test equipment market is valued at $91.8 million in 2025 and is expected to grow to $122.2 million by 2030.
What is the growth rate for Canada's automotive test equipment market?
Canada's automotive test equipment market is projected to grow at a compound annual growth rate (CAGR) of 4.2% from 2025 to 2030.
What factors are driving growth in Canada's automotive test equipment market?
Growth in Canada is driven by the country's strong manufacturing base, increasing vehicle complexity, rising EV adoption, emissions compliance requirements, and integration with North American supply chains.
Which segments are growing fastest in Canada's automotive test equipment market?
Electric vehicle testing equipment and emissions compliance solutions are among the fastest-growing segments in Canada's market between 2025 and 2030.
How does Canada's market compare to the global automotive test equipment market?
Canada's market growth rate of 4.2% CAGR slightly exceeds the global average of 3.9%, reflecting the country's strong automotive manufacturing sector and technological advancement.
RESEARCH METHODOLOGY
Various secondary sources, directories, and databases have been used to identify and collect information for an extensive study of the automotive test equipment market. The study involved four main activities in estimating the current size of the automotive test equipment market: secondary research, validation through primary research, assumptions, and market analysis. The research study involved various secondary sources, such as company annual reports/presentations, industry association publications, automotive wiring harness magazine articles, directories, technical handbooks, World Economic Outlook, trade websites, technical articles, and databases, which were used to identify and collect information for an extensive study of the automotive test equipment market. Primary sources experts from automotive OEMs, Tier 1 suppliers and test equipment manufacturers were interviewed to obtain and verify critical information, assess prospects and develop market estimates.
Secondary Research
Secondary sources used in this research study included automotive test equipment industry organizations; corporate filings such as annual reports, investor presentations, and financial statements; trade and business whitepapers and databases; and articles from recognized associations and government publications. The secondary data was collected and analyzed to determine the overall market size, which was further validated through primary research.
Primary Research
Extensive primary research has been conducted following an understanding of the market scenario gained through secondary research. Several primary interviews have been conducted with market experts from the demand- and supply-side OEMs (in terms of component supply, country-level government associations, and trade associations) and component manufacturers across four major regions, namely, Asia Pacific (40%), Europe (25%), North America (20%), and the Rest of the World (15%). Approximately 60% and 40% of primary interviews have been conducted from the demand and supply side, respectively. Primary data has been collected through questionnaires, emails, LinkedIn, and telephonic interviews. In canvassing primaries, we have striven to cover various departments within organizations, such as sales, operations, and administration, to provide a holistic viewpoint in our report.
Brief sessions with highly experienced independent consultants were conducted to reinforce findings from primaries after interacting with industry experts. This, along with the opinions of in-house subject matter experts, led to the findings described in the remainder of this report.
In the primary research process, various primary sources from the supply and demand sides were interviewed to obtain qualitative and quantitative information for the report. The primary sources from the supply side included industry experts, such as Vice Presidents (VPs), marketing directors, technology and innovation directors, and related key executives from various key companies and organizations. The primary sources from the demand side included end users, such as Chief Information Officers (CIOs), consultants, service professionals, technicians and technologists, and managers at public and investor-owned utilities.
Breakdown of Primaries
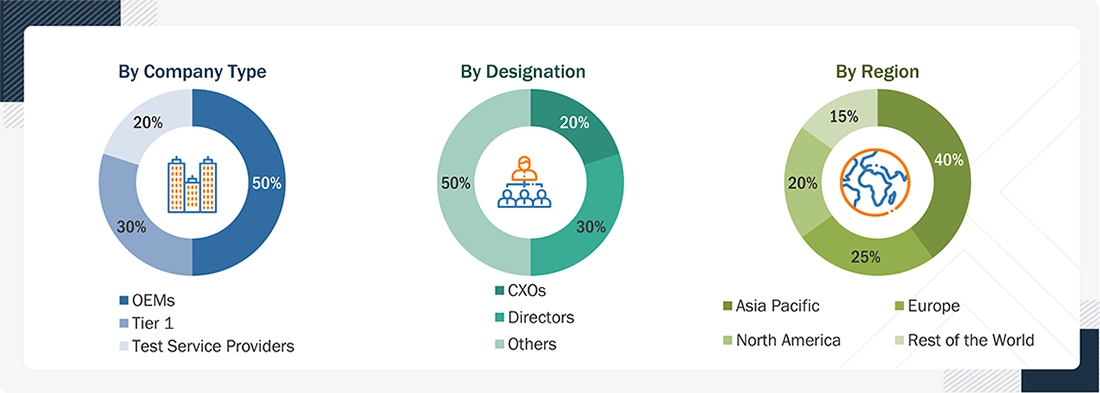
Note: Tier 1 suppliers include automotive system and component suppliers using test equipment for component and system validation.
To know about the assumptions considered for the study, download the pdf brochure
Market Size Estimation
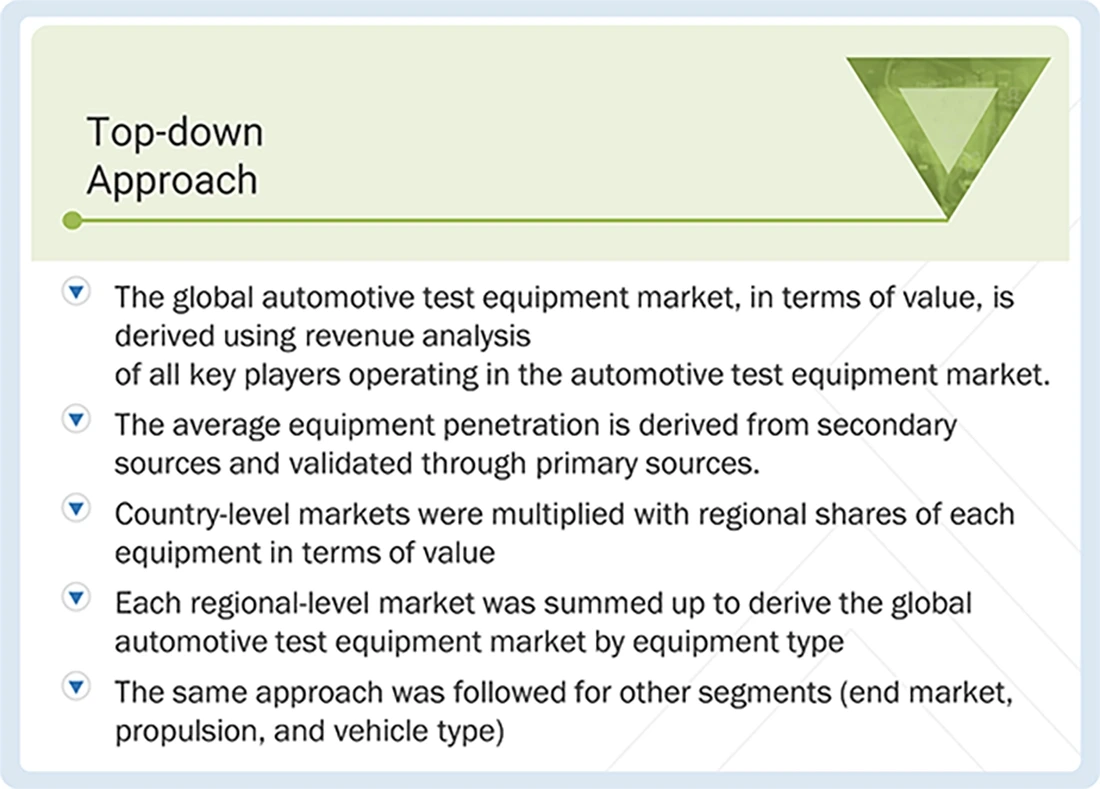
The top-down approach has been used to estimate and validate the size of the automotive test equipment market by equipment type. This approach identifies key types of automotive test equipment at the regional level. The market share of each equipment type is determined for each region. The market share of equipment types is then multiplied by the value of the global automotive test equipment market. The market value for each equipment type is derived by multiplying the regional market size by the percentage share of each equipment type. All regional data is then aggregated to derive the global automotive test equipment market by equipment type. The same approach has been applied to other segments, including vehicle type, end market, propulsion, and application type, to obtain a consistent view of the overall market.
Automotive Test Equipment Market : Top-Down Approach
Data Triangulation
After arriving at the overall market size using the market size estimation processes as explained above, the market was split into several segments and subsegments. To complete the overall market engineering process and obtain precise statistics for each market segment and subsegment, data triangulation and market breakdown procedures were employed where applicable. The data was triangulated by studying various factors and trends from both the demand and supply sides.
Market Definition
Automotive test equipment refers to specialized tools and systems used to evaluate, verify, and validate the performance, safety, and compliance of automotive components, subsystems, and complete vehicles throughout their development, production, and maintenance lifecycles.
This equipment includes a wide range of devices such as chassis dynamometers, engine dynamometers, transmission dynamometers, vehicle emission test systems, wheel alignment testers, fuel injection pump testers, hardware-in-the-loop (HIL) test benches, battery test equipment, E-motor test equipment, E-axle testing, vehicle charging and high-voltage test systems, EV drivetrain testing, brake test equipment, NVH test equipment, ADAS test equipment, durability test equipment, and EMC and environmental test equipment.
This range of equipment covers everything from traditional ICE testing devices to state-of-the-art EV test platforms.
Key Stakeholders
- Automotive OEMs
- Tier 1 Automotive Component and System Suppliers
- Automotive Test Equipment Manufacturers
- Automotive Testing, Inspection, and Certification Companies
- Independent Testing and Validation Service Providers
- Automotive R&D and Engineering Centers
- Battery Cell and Battery Pack Manufacturers
- Electric Motor and Power Electronics Manufacturers
- ECU, Semiconductor, and Automotive Electronics Suppliers
- ADAS and Autonomous Driving Technology Developers
- Automotive Manufacturing and Assembly Plants
- End-of-Line Testing and Production Quality Providers
- Automotive Software, Simulation, and HIL/SIL Providers
- Calibration and Measurement Service Providers
- Vehicle Inspection and Certification Centers
- Automotive Aftermarket Service and Diagnostic Providers
- Government and Automotive Regulatory Authorities
- Automotive Standards and Certification Organizations
- Technical Universities and Research Institutes
- Battery and EV Testing Laboratories
- Chassis Dynamometer and Powertrain Test Facility Operators
- Test Automation and Data Analytics Providers
- Cloud and High-Performance Computing Providers
- Automotive Engineering and Consulting Firms
- Leasing and Equipment Financing Providers
Report Objectives
-
To segment and forecast the automotive test equipment market in terms of value (USD million)
- By application (mobile/tablet-based equipment and PC/laptop-based equipment)
- By propulsion (ICE and EVs)
- By vehicle type (passenger cars and commercial vehicles)
- By end market (OEM assembly plants, R&D/Technical centers, and authorized service centers)
- By equipment (chassis dynamometer, engine dynamometer, transmission dynamometer, vehicle emission test system, wheel alignment tester, fuel injection pump tester, Hardware-in-the-Loop (HIL) test benches, battery test equipment, E-motor test equipment, E-axle testing, vehicle charging & high voltage test systems, EV drivetrain testing, brake test equipment, NVH test equipment, ADAS test equipment, durability test equipment, EMC & environmental test equipment, and others)
- Region (Asia Pacific, Europe, North America, and the Rest of the World)
-
To segment and forecast the automotive test equipment market qualitatively
- By advanced technology (sensor testing, perception system testing, ECU testing, ADAS testing, simulation testing, edge computing, and V2X testing)
- To analyze regional markets for growth trends, prospects, and their contribution to the overall market
- To define, describe, and forecast the size of the automotive test equipment market for automotives with respect to growth trends and prospects, and determine the contribution of the segments to the total market
- To provide detailed information regarding the major factors (drivers, challenges, restraints, and opportunities) influencing market growth
- To strategically analyze markets with respect to individual growth trends, prospects, and contributions to the total market
- To analyze opportunities for stakeholders and the competitive landscape for market leaders
-
To study the following with respect to the market:
- Supply chain analysis
- Ecosystem analysis
- Pricing analysis
- Technology analysis
- HS code
- Case study analysis
- Patent analysis
- Impact of AI
- Impact of 2025 India-EU trade deal
- Regulatory landscape
- Key stakeholders & buying criteria
- Key conferences & events
- To strategically profile key players and comprehensively analyze their market share and core competencies
- To track and analyze competitive developments such as deals (mergers & acquisitions, partnerships, collaborations), product developments, and other activities carried out by key industry participants
Available customizations:
With the given market data, MarketsandMarkets offers customizations tailored to company-specific needs.
- Automotive test equipment market, by propulsion, at the country level
- Additional country mapping (up to three in the report)
Company Information
- Profiling of additional market players (up to 5)
Get the Full Automotive Test Equipment Market Report
Full forecast, segment splits, and company analysis for all Automotive Test Equipment Market.
- China Automotive Test Equipment Market
- India Automotive Test Equipment Market
- Japan Automotive Test Equipment Market
- South Korea Automotive Test Equipment Market
- France Automotive Test Equipment Market
- Germany Automotive Test Equipment Market
- Italy Automotive Test Equipment Market
- Spain Automotive Test Equipment Market
- UK Automotive Test Equipment Market
- Mexico Automotive Test Equipment Market
- US Automotive Test Equipment Market
- Brazil Automotive Test Equipment Market
- Russia Automotive Test Equipment Market
- Rest Of Europe Automotive Test Equipment Market
- Rest Of Asia Pacific Automotive Test Equipment Market
Need a Tailored Report?
Customize this report to your needs
Get 10% FREE Customization
Customize This Report
