Asia Pacific Automotive Transmission Market (2023-2028)
The Asia Pacific Automotive Transmission Market was valued at $32394.2 Million in 2023 and projected to reach to $43699.9 Million by 2028, representing a compound annual growth rate of 6.2%. Asia Pacific's automotive transmission market is poised for robust expansion through 2028, fueled by rapid industrialization, urbanization, and rising disposable incomes across emerging economies.

| Market Size in | USD 26.32 MN |
| Market Forecast in | |
| CAGR | |
| Forecast Period | |
| Units Considered | Value (USD MN) |
Asia Pacific Automotive Transmission Market Trends and Insights
- The region is projected to expand significantly, reaching $43,699.9 million by 2028, driven by rapid industrialization, rising vehicle production, and increasing consumer demand across emerging economies.
- Asia Pacific's transmission market benefits from the presence of major automotive manufacturers and a growing shift toward advanced transmission technologies including automatic and continuously variable transmissions. The Asia Pacific automotive transmission market is experiencing robust growth fueled by expanding middle-class populations and rising disposable incomes across key markets such as China, India, and Southeast Asia.
- Between 2023 and 2028, Asia Pacific is expected to maintain steady momentum as electric vehicle adoption accelerates and OEMs invest in next-generation transmission systems.
- The region's competitive landscape features both established global players and regional manufacturers adapting to local preferences and regulatory requirements. Asia Pacific's transmission market reflects broader automotive industry trends, including electrification and efficiency improvements.
- The forecast period through 2028 positions Asia Pacific as a critical growth engine, with infrastructure development and government incentives supporting vehicle sales and transmission technology upgrades across the region..
Key Market Statistics
- CAGR (2023-2028) 6.2% CAGR
- Market Size, 2023 ~USD 32394.2 Million
- Forecast, 2028 ~USD 43699.9 Million
- Geography Asia Pacific
Asia Pacific Automotive Transmission Market Overview
Market Dominance :
Asia Pacific commands the largest share of the global automotive transmission market, accounting for $32,394.2 million in 2023, driven by massive vehicle production volumes and rapid motorization across the region.
China's Leadership :
China leads Asia Pacific with $31,083.02 million in market size, representing the world's largest automotive transmission market due to its position as the global manufacturing hub and largest vehicle consumer.
Strong Growth Trajectory :
The region is projected to grow at a 6.2% CAGR, expanding from $32,394.2 million in 2023 to $43,699.9 million by 2028, reflecting sustained demand from emerging economies and industrial expansion.
Emerging Market Opportunities :
India, Thailand, and South Korea present significant growth opportunities with combined market sizes exceeding $13.4 billion, supported by rising middle-class populations and increasing vehicle ownership rates.
Asia Pacific Automotive Transmission Market Dynamics
- China's continued dominance as a manufacturing powerhouse, coupled with India's accelerating vehicle production and Thailand's automotive hub status, will drive regional growth.
- The shift toward electric vehicles and advanced transmission technologies presents both challenges and opportunities for market participants. Key growth drivers include increasing vehicle production capacity, government infrastructure investments, and growing consumer demand for personal mobility.
- The region's transmission market will benefit from technological advancements in automatic and CVT transmissions, as well as the integration of hybrid and electric powertrains.
- Strategic partnerships between global OEMs and regional suppliers will further accelerate market penetration and innovation across Asia Pacific..
Market Ecosystem
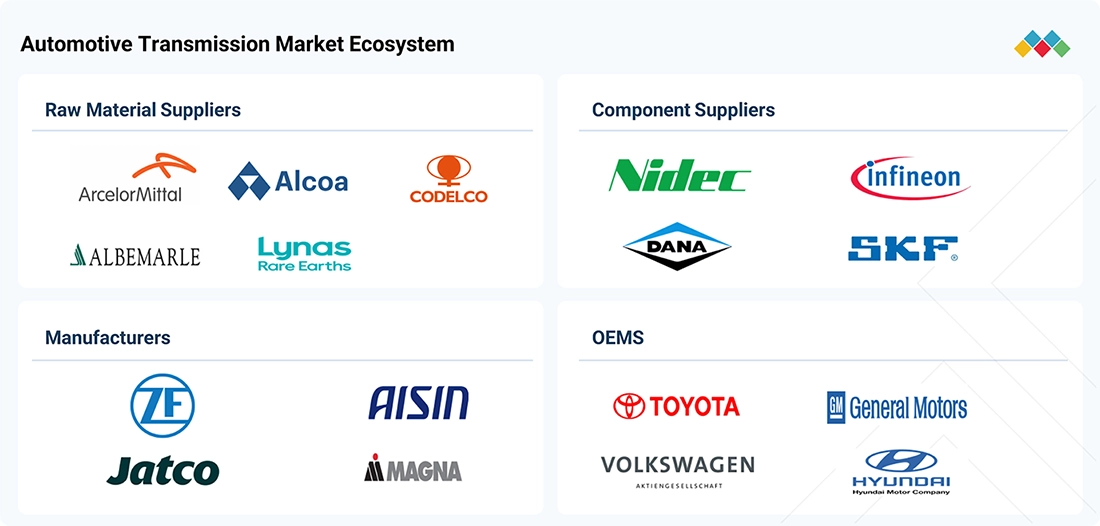
AUTOMOTIVE TRANSMISSION MARKET: COMMERCIAL USE CASES ACROSS INDUSTRIES
| COMPANY | USE CASE DESCRIPTION | BENEFITS |
|---|---|---|
 |
In August 2026, AISIN and its partners introduced a two-motor hybrid drive module selected for the new Jeep Cherokee, combining a high-torque transaxle with coordinated motor and boost-converter control. The system manages engine and electric-motor output across hybrid driving conditions. | Improves fuel efficiency and acceleration by coordinating motor output and increasing system voltage. Integrated torque management supports responsive power delivery across hybrid driving modes. The architecture can optimize motor operating points during launch and regenerative braking. |
 |
In June 2025, ZF developed its fourth-generation 8HP eight-speed automatic transmission platform for conventional, mild hybrid, and plug-in hybrid vehicles. Its modular design accommodates different levels of electrification within a shared transmission architecture. | Improves transmission efficiency, supports higher electrical performance, and enables automakers to adapt existing vehicle platforms for hybridization while reducing the need for major powertrain redesigns. |
 |
In July 2026, Magna secured an 800 V, 250 kW two-speed eDrive programme with Chery, with production planned at its Wuhu facility in China. The system combines two-speed gearing with a high-voltage electric drive for the vehicle programme. | Combines high power output with two-speed gearing to support acceleration and high-speed efficiency. The additional ratio helps maintain motor efficiency across a wider vehicle-speed range. The 800 V architecture supports high-power operation with lower current for a given power level. |
 |
In 2025, Hyundai Transys advanced its next-generation e²AT hybrid transmission for Hyundai Motor Group hybrid platforms, integrating a P1+P2 motor configuration with a six-speed automatic transmission. The arrangement coordinates engine and motor output within a single hybrid drive system. | Improves fuel efficiency and acceleration compared with the previous hybrid transmission, while integrating key components to reduce packaging requirements and improve power delivery. P1+P2 motor placement enables engine starting, torque assist, and regenerative energy recovery. Coordinated motor control also supports smoother transitions between operating modes. |
 |
In October 2025, BorgWarner secured a programme to supply a 7-in-1 integrated drive module for a Chinese OEM’s hybrid SUV, with production planned for 2026. The module consolidates electric-drive and power-management functions into one assembly. | Reduces packaging requirements and simplifies vehicle integration by consolidating multiple components. The integrated architecture supports scalable hybrid powertrain design and efficient power delivery. Consolidating power electronics and drive components can shorten high-voltage interconnections and simplify thermal-management integration. |
Logos and trademarks shown above are the property of their respective owners. Their use here is for informational and illustrative purposes only.
Related Ecosystem
Automotive Systems
- Light Commercial Vehicles (LCVs)
- Battery Electric Vehicle (BEV)
- Hybrid Electric Vehicle (HEV)
- Agricultural Tractors
- Fuel Cell Electric Vehicle (FCEV)
- BOSCH LIMITED
- DENSO Corporation
- Continental ag
- ZF FRIEDRICHSHAFEN AG
- TENNECO
Key Takeaways
- Asia Pacific automotive transmission market valued at $32.4 billion in 2023, expanding to $43.7 billion by 2028 at 6.2% CAGR
- Rising vehicle production and electrification trends in Asia Pacific drive demand for advanced automatic and CVT transmission systems
- China, India, and Southeast Asia emerge as primary growth markets within Asia Pacific due to expanding middle-class populations and infrastructure development
- Asia Pacific manufacturers increasingly compete on transmission efficiency and EV compatibility to meet regional regulatory standards and consumer preferences
Automotive Transmission Market Report Scope
| Report Metric | Details |
|---|---|
| Base Year | 2023 |
| Fastest Growing Segment | AUTOMATED MANUAL TRANSMISSION (Transmission Type) |
| Forecast Period | 2023-2028 |
| Growth Rate | CAGR of 6.2% from 2023 to 2028 |
| Largest Segment | GASOLINE (Fuel Type) |
| Market Size Base Year (Billions) | ~USD 62.33 (2023) |
| Revenue Forecast (Billions) | ~USD 84.2 (2028) |
| Segments Covered | Transmission Type, Vehicle Type, Fuel Type, Number Of Forward Gears, Type |
Asia Pacific Automotive Transmission Market Report Segmentation
5 segment dimensions are covered across the global market.
By Transmission Type
- Automated Manual Transmission
- Automatic Transmission
- Continuously Variable Transmission
- Dual Clutch Transmission
- Manual Transmission
By Vehicle Type
- Buses
- Lcvs
- Passenger Cars
- Trucks
By Fuel Type
- Alternate Fuel
- Diesel
- Gasoline
By Number Of Forward Gears
- 6 To 8
- 9 To 10
- Above 10
- Cvt
- Up To 5
By Type
- Automatic Transmission
- Manual Transmission
Target Audience
- Automotive OEMs & Tier-1 Suppliers : Manufacturers and suppliers need Asia Pacific market data to optimize production capacity, plan regional expansions, and align transmission technology strategies with local market demands and regulatory requirements.
- Investment & Private Equity Firms : Investors require detailed Asia Pacific market sizing and growth forecasts to identify acquisition targets, evaluate transmission technology companies, and assess regional expansion opportunities in high-growth markets.
- Market Entry & Strategy Consultants : Consulting firms use Asia Pacific transmission market intelligence to advise clients on market entry strategies, competitive positioning, and localization approaches for the region's diverse automotive markets.
- Transmission Technology Developers : Companies developing advanced transmission technologies need Asia Pacific adoption trends and market forecasts to prioritize R&D investments and commercialization strategies for the world's largest automotive market.
- Government & Trade Organizations : Policy makers and trade bodies require Asia Pacific market data to develop automotive industry policies, trade agreements, and technology standards aligned with regional market growth and sustainability goals.
Countries within Asia Pacific - compare and drill down
| Country | 2025 size (native) |
|---|---|
| China | USD 31083.02 Million |
| India | USD 7287.9 Million |
| Japan | USD 8135.1 Million |
| South Korea | USD 3925.5 Million |
| Thailand | USD 2193.2 Million |
| Rest Of Asia Pacific | USD 2999.6 Million |
Country market size visualization
Reasons to Buy this Report
- Regional Market Dominance Insights : Gain comprehensive understanding of Asia Pacific's 35%+ share of the global transmission market, with detailed analysis of China's $31.1B market and emerging opportunities in India and Southeast Asia.
- Country-Level Intelligence : Access granular market data for six key Asia Pacific markets including China, India, Japan, South Korea, Thailand, and Rest of Asia Pacific to identify high-growth segments and investment opportunities.
- Growth Forecasting Through 2028 : Leverage 5-year projections showing 35% market expansion to $43.7B, enabling strategic planning for capacity investments, supply chain optimization, and market entry strategies in the fastest-growing automotive region.
- Competitive Landscape Analysis : Understand the competitive dynamics specific to Asia Pacific, including OEM preferences, supplier consolidation trends, and technology adoption patterns across the region's diverse automotive ecosystems.
- Technology & Trend Identification : Identify region-specific transmission technology trends including automatic transmission adoption, CVT penetration, and electric vehicle transmission integration across Asia Pacific's heterogeneous markets.
Frequently asked questions
What is the current size of the Asia Pacific automotive transmission market?
The Asia Pacific automotive transmission market was valued at $32,394.2 million in 2023 and is projected to reach $43,699.9 million by 2028.
What is the expected growth rate for Asia Pacific's transmission market through 2028?
Asia Pacific's automotive transmission market is expected to grow at a compound annual growth rate (CAGR) of 6.2% from 2023 to 2028.
Which countries drive the largest share of Asia Pacific's transmission market?
China, India, and Southeast Asian nations are the primary growth drivers in Asia Pacific, supported by rising vehicle production, industrialization, and expanding consumer purchasing power.
What transmission technologies are gaining traction in Asia Pacific?
Automatic transmissions, continuously variable transmissions (CVTs), and electric vehicle-compatible transmission systems are increasingly adopted across Asia Pacific as manufacturers prioritize efficiency and performance.
How does electrification impact Asia Pacific's transmission market?
Electrification drives innovation in transmission design within Asia Pacific, with manufacturers developing specialized systems for hybrid and electric vehicles to meet regional emission standards and consumer demand.
RESEARCH METHODOLOGY
The research study involved extensive use of secondary sources, such as company annual reports/presentations, industry association publications, automotive magazine articles, directories, technical handbooks, the World Economic Outlook, trade websites, technical articles, and databases, to identify and collect information on the automotive transmission market. Primary interviews have been conducted to obtain and verify critical qualitative and quantitative information as well as assess the prospects of the industry. Primary sources include experts from core and related industries, suppliers, manufacturers, distributors, service providers, technology developers, and organizations related to various segments of the automotive transmission market value chain. Detailed interviews have been conducted with various primary respondents, including key industry participants, Subject Matter Experts (SMEs), C-level executives of key market players, and industry consultants.
Secondary Research
Secondary sources referred to for this research study include automotive industry organizations such as the International Organization of Motor Vehicle Manufacturers (OICA), United Nations Economic Commission for Europe (UNECE), European Automobile Manufacturers' Association (ACEA), China Association of Automobile Manufacturers (CAAM), National Highway Traffic Safety Administration (NHTSA), Society of Indian Automobile Manufacturers (SIAM), among others; corporate filings such as annual reports, investor presentations, and financial statements; and trade, business, and automotive associations. Secondary data has been collected and analyzed to arrive at the overall market size, which is further validated by primary research.
Primary Research
Extensive primary research was conducted after acquiring an understanding of the automotive transmission market scenario through secondary research. Several primary interviews were conducted with market experts from the automotive OEMs and automotive transmission providers across four major regions, namely, Asia Pacific, Europe, North America, and Middle East & Africa. Approximately 70% and 30% of the primary interviews were conducted with the automotive transmission manufacturers and OEMs, respectively. Primary data was collected through questionnaires, emails, and telephonic interviews. Various departments within organisations, including sales, operations, and administration, were contacted to provide a holistic viewpoint in reports while canvassing primary data. After interacting with industry participants, some brief sessions were conducted with experienced independent consultants to reinforce the findings from the primary interviews. This, along with the opinions of in-house subject matter experts, led to the findings delineated in the rest of this report.
Primary interviews have been conducted to gather insights, including automotive transmission market sizing estimation and forecast, future trends, and upcoming technologies in the automotive transmission market. Data triangulation of all these points was done using the information gathered from secondary research and model mapping. Stakeholders from the demand and supply sides have been interviewed to understand their views on the aforementioned points.
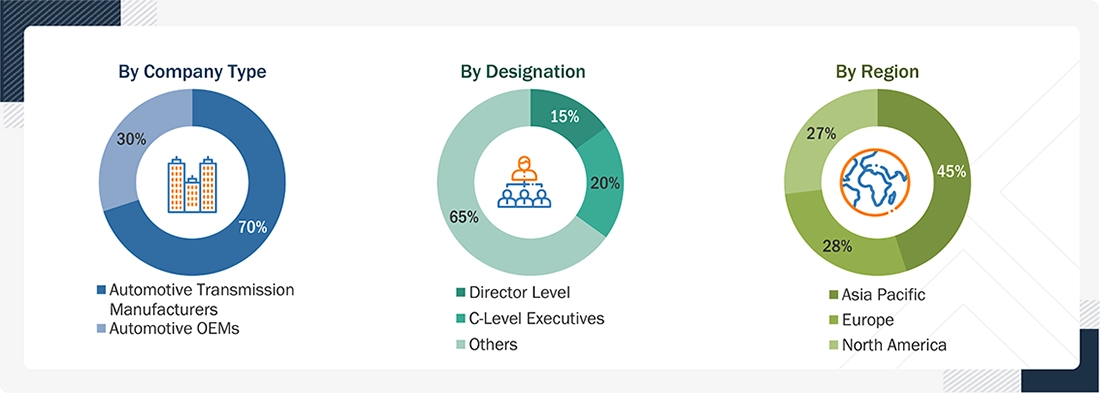
Note: Others include sales, marketing, and product managers.
Company tiers are based on the value chain; revenue of the company is not considered.
To know about the assumptions considered for the study, download the pdf brochure
Market Size Estimation
A detailed market estimation approach was followed to estimate and validate the value and volume of the automotive transmission market and other dependent submarkets, as mentioned below:
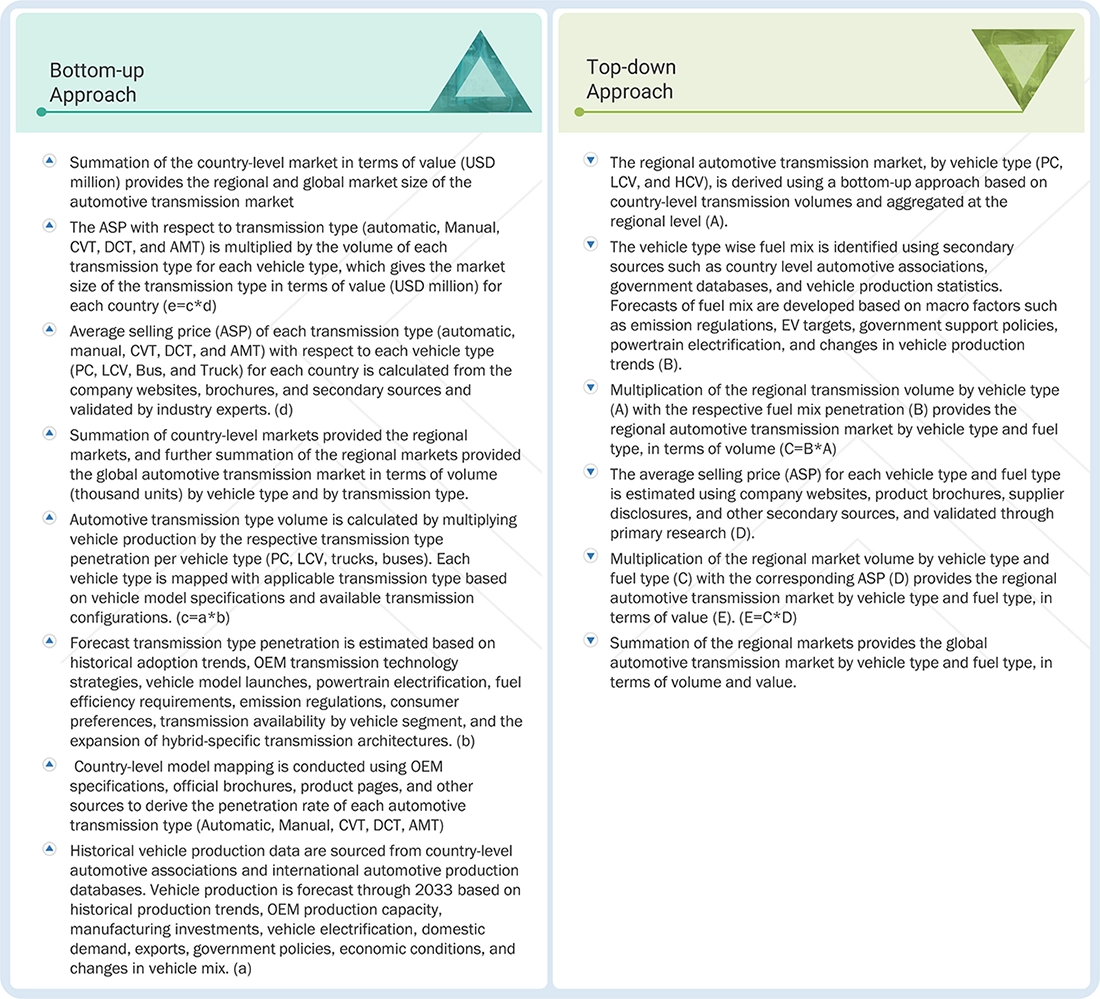
- The bottom-up and top-down approaches have been used to estimate and validate the size of the automotive transmission market. The automotive transmission market, by transmission type, in terms of value and volume, is derived by identifying the country-level production numbers of each vehicle type (PC, LCV, Trucks, and buses). Forecasts are based on the expected penetration of transmission type across vehicle segments, considering OEM adoption plans, vehicle electrification, premiumization, safety and fuel-efficiency requirements, and increasing integration of advanced transmission systems.
- The market size was derived using parameters such as production of vehicle types (passenger cars, LCVs, heavy trucks, and buses) and corresponding penetration of the transmission type considered under the scope. Forecasts are based on expected vehicle production by country and vehicle type, considering OEM production plans, regional demand trends, economic conditions, electrification, and capacity expansion or rationalization.
- Transmission volume is calculated by multiplying vehicle production by the penetration of each transmission type, including automatic, manual, CVT, DCT, and AMT, across the respective vehicle segments. Transmission penetration is derived through country-level vehicle model mapping using OEM specifications, official product pages, brochures, and available transmission configurations.
- The market value for each transmission type is calculated by multiplying the corresponding transmission volume by its average selling price (ASP). ASPs are estimated for each transmission type and vehicle segment at the country level using supplier websites, product brochures, company disclosures, secondary sources, and industry expert validation.
- Country-level vehicle production and transmission penetration are forecast through 2033, considering historical production trends, OEM manufacturing plans, capacity expansions, vehicle electrification, domestic demand, export trends, economic conditions, government policies, and changes in vehicle mix. Country-level market estimates are aggregated to derive regional and global market sizes in terms of value and volume.
- Key players in the automotive transmission market were identified through secondary research, and their global market rankings were determined through primary and secondary research.
- The research methodology included the study of annual and quarterly financial reports, regulatory filings of major market players, and interviews with industry experts to gain detailed market insights.
- All major penetration rates, percentage shares, splits, and breakdowns for the automotive transmission market were determined through secondary sources and verified through primary sources.
- All key macro indicators affecting the revenue growth of the market segments and subsegments have been accounted for, viewed in extensive detail, verified through primary research, and analyzed to obtain validated and verified quantitative & qualitative data.
- The market data gathered was consolidated and added with detailed inputs, analyzed, and presented in this report.
Automotive Transmission Market: Top-Down and Bottom-Up Approach
Data Triangulation
All percentage shares, splits, and breakdowns were determined using secondary sources and verified by primary sources. All parameters that are said to affect the markets covered in this research study were accounted for, viewed in extensive detail, and analyzed to obtain the final quantitative and qualitative data.
Market Definition
- Manual Transmission (MT): A manual transmission uses a driver-operated clutch and gear lever to select fixed gear ratios. The driver controls gear changes according to vehicle speed, engine load, and driving conditions, while the mechanically simple architecture offers lower manufacturing and maintenance costs.
- Automated Manual Transmission (AMT): An AMT automates clutch operation and gear selection in a conventional manual gearbox using electronic control units and electromechanical or hydraulic actuators. It reduces driver effort while retaining much of the manual transmission's hardware, making it suitable for cost-sensitive passenger cars and commercial vehicles.
- Automatic Transmission (AT): An automatic transmission changes gear ratios without requiring driver-operated clutch control. Conventional ATs typically use planetary gearsets, a torque converter and electronically controlled hydraulic clutches to transfer engine torque across different driving conditions. Multiple gear ratios support smooth acceleration, high torque delivery and lower engine speeds during cruising, making ATs suitable for SUVs, passenger cars and heavy-duty vehicles.
- Dual Clutch Transmission (DCT): A DCT uses two independently controlled clutches to manage odd and even gear sets, allowing the next gear to be preselected before the current gear disengages. This enables rapid gear changes with minimal torque interruption, although clutch temperature management, low-speed smoothness and system cost influence adoption.
- Continuously Variable Transmission (CVT): A CVT varies the transmission ratio continuously, commonly through a belt or chain operating between variable-diameter pulleys. By adjusting the ratio to keep the engine within an efficient operating range, it supports smooth acceleration and fuel efficiency, particularly in small and mid-size passenger cars.
Key Stakeholders
- Automotive Transmission Manufacturers
- Automotive Original Equipment Manufacturers
- Automotive Transmission Component and Raw Material Suppliers
- Automotive Powertrain and Electric Drive System Suppliers
- Automotive Transmission Control Systems and Electronics Suppliers
- Automotive Transmission Testing, Certification, and Standards Organizations
- Regional Transmission Manufacturer Associations and Automobile Associations
- Traders, Distributors, and Suppliers of Automotive Transmission Systems
- Automotive Regulatory Bodies and Government Agencies
Report Objectives
-
To segment and forecast the size of the automotive transmission market by volume (million units) and value (USD billion/million) from 2026 to 2033.
- By transmission type (manual transmission, automatic transmission, continuously variable transmission (CVT), dual clutch transmission (DCT), automated manual transmission (AMT), at the regional level
- By vehicle type (passenger cars, light commercial vehicles, Trucks and Buses,), at the regional level
- By fuel type (diesel, gasoline, CNG/Alternate fuel), at the regional level
- By number of forward gears (up to 5, 6 to 8, 9 to 10, above 10 and CVT), at the regional level
- EV transmission, by transmission type (single-speed transmission and multi-speed transmission) at the regional level
- EV transmission, by integration level (reducer, e-transmission, integrated e-drive, e-axle) at the regional level
- Hybrid transmission market, by motor configuration (1 Motor Hybrid, 2 Motor Hybrid, 3 Motor Hybrid) at the regional level
- By region (Asia Pacific, Europe, North America, Latin America and Middle East & Africa)
- To comprehensively evaluate the key market dynamics, including growth drivers, restraints, opportunities, and challenges, shaping the evolution of the Automotive Transmission Market
- To strategically assess market segments based on their growth potential, emerging trends, future opportunities, and contribution to overall market revenue
- To analyze the competitive leadership mapping of the global automotive transmission manufacturers in the market and understand their market position with the help of a company evaluation matrix
- To track and analyze competitive developments, such as joint ventures, collaborations, partnerships, mergers & acquisitions, new product developments, and expansions, in the automotive transmission market
-
To study the following with respect to the market:
- Supply Chain Analysis
- Ecosystem Analysis
- Technology Analysis
- Trade Analysis
- Case Study Analysis
- Patent Analysis
- Regulatory Landscape
- Pricing Analysis
- Investment Scenario
- Key Stakeholders and Buying Criteria
- To analyze opportunities for stakeholders and the competitive landscape for market leaders
Available customizations:
MarketsandMarkets offers the following customisations for this market report:
Get the Full Automotive Transmission Market Report
Full forecast, segment splits, and company analysis for all Automotive Transmission Market.
- China Automotive Transmission Market
- India Automotive Transmission Market
- Japan Automotive Transmission Market
- South Korea Automotive Transmission Market
- Thailand Automotive Transmission Market
- Germany Automotive Transmission Market
- France Automotive Transmission Market
- Italy Automotive Transmission Market
- Russia Automotive Transmission Market
- UK Automotive Transmission Market
- Spain Automotive Transmission Market
- Canada Automotive Transmission Market
- Mexico Automotive Transmission Market
- US Automotive Transmission Market
- Brazil Automotive Transmission Market
- Argentina Automotive Transmission Market
- Iran Automotive Transmission Market
- South Africa Automotive Transmission Market
- Rest Of Europe Automotive Transmission Market
- Turkey Automotive Transmission Market
- Rest Of Asia Pacific Automotive Transmission Market
- Rest Of Latin America Automotive Transmission Market
Need a Tailored Report?
Customize this report to your needs
Get 10% FREE Customization
Customize This Report