Germany Biosurgery Market (2025-2030)
The Germany Biosurgery Market was valued at $796.3 Million in 2025 and projected to reach to $1025.5 Million by 2030, representing a compound annual growth rate of 5.2%. Germany's biosurgery market is poised for sustained growth through 2030, supported by increasing surgical procedures, aging demographics, and rising demand for advanced hemostatic solutions.

| Market Size in | USD 26.32 MN |
| Market Forecast in | |
| CAGR | |
| Forecast Period | |
| Units Considered | Value (USD MN) |
Germany Biosurgery Market Trends and Insights
- Germany maintains a strong position in the European biosurgery sector, driven by advanced healthcare infrastructure, high surgical volumes, and robust reimbursement frameworks that support adoption of innovative hemostatic and tissue sealing products.
- The German market benefits from significant investment in surgical innovation and a well-established network of hospitals and surgical centers that prioritize cutting-edge biosurgical solutions. Germany's biosurgery expansion is underpinned by increasing demand for minimally invasive surgical procedures and growing awareness of advanced wound management techniques among healthcare providers.
- Germany's aging population and rising prevalence of chronic conditions requiring surgical intervention further support market growth through 2030.
- The country's regulatory environment and emphasis on clinical evidence create favorable conditions for biosurgery product launches and market penetration across multiple surgical specialties..
Key Market Statistics
- CAGR (2025-2030) 5.2% CAGR
- Market Size, 2025 ~USD 796.3 Million
- Forecast, 2030 ~USD 1025.5 Million
- Country Germany
Germany Biosurgery Market Overview
Market Valuation :
Germany's biosurgery market is valued at $796.3 million in 2025, with projected growth to $1,025.5 million by 2030, reflecting steady expansion in the European healthcare sector.
Advanced Healthcare Infrastructure :
Germany's well-established medical device ecosystem, stringent quality standards, and high surgical volumes create an ideal environment for biosurgery product adoption and innovation.
Robust Reimbursement Framework :
Strong reimbursement policies from German statutory health insurance systems support widespread adoption of hemostatic agents and tissue sealants across surgical specialties.
Regional Leadership :
Germany maintains a dominant position in the European biosurgery market, driven by leading medical device manufacturers, research institutions, and surgeon expertise in minimally invasive techniques.
Germany Biosurgery Market Dynamics
- The 5.2% CAGR reflects steady adoption of innovative tissue sealants and hemostatic agents across orthopedic, cardiovascular, and general surgery applications.
- Germany's stringent regulatory environment and emphasis on clinical evidence ensure only high-quality products reach the market, maintaining premium pricing and profitability for established players.
- Continued investment in surgical training and minimally invasive techniques will further drive biosurgery product utilization across German hospitals and surgical centers..
Market Ecosystem
Biosurgery Market: COMMERCIAL USE CASES ACROSS INDUSTRIES
| COMPANY | USE CASE DESCRIPTION | BENEFITS |
|---|---|---|
 |
Bone-graft substitutes, surgical sealants & adhesives, adhesion barriers, staple-line reinforcement, soft-tissue attachments, and hemostatic agents for hemostasis, tissue sealing, adhesion prevention, and tissue repair in surgical procedures. | Advanced hemostasis, minimized risk of leaks and bleeding, improved tissue handling, and effective adhesion prevention. Ethicon’s powered stapling and energy devices deliver enhanced sealing, less tissue slippage, and optimized surgical recovery. |
 |
Biosurgery portfolio includes hemostats and sealants, adhesion barrier for preventing adhesions; and suture line reinforcement and sealing in cardiovascular and general surgery. | Rapid surgical hemostasis, effective adhesion reduction, strong, consistent tissue sealing, broad multi-specialty versatility, and clinically proven reduction in postoperative complications and optimized surgical workflow. |
 |
Polymeric sealants, biological adhesives, skin and tissue closure products, and staple-line reinforcement agents for wound closure, spinal, cranial, and complex general surgery. | Enables rapid, needle-free wound closure, strong adhesion even in high-tension and moist environments, reduced CSF and other fluid leaks, and lower risk of infection. Enables sutureless procedures and improved cosmetic outcomes with robust tissue support. |
 |
Synthetic and allograft bone grafts, staple-line reinforcement, soft-tissue attachments, dural sealants, and topical adhesives for craniofacial, spine, orthopaedic, and trauma applications. | Excellent osteointegration, reliable watertight dural sealing (99% CSF leak prevention), absorbable biomaterials for long-term regeneration, and reduced need for autograft harvesting all supporting faster healing and complication risk reduction. |
 |
Biosurgery portfolio includes hemostatic agents, surgical sealants, absorbable sponges, and soft-tissue reinforcement for bleeding control and tissue closure used in open and minimally invasive surgeries. | Accelerates natural clotting, delivers rapid, reliable hemostasis, reduces surgical air leaks, is easy to use even in complex fields, and offers thrombin-free, 100% plant-based and collagen-based options proven safe and effective in a wide range of specialties |
Logos and trademarks shown above are the property of their respective owners. Their use here is for informational and illustrative purposes only.
Related Ecosystem
Medical Devices
- Polymerase Chain Reaction (PCR)
- Magnetic Resonance Imaging (MRI)
- Disposable Autoinjectors
- Pulse Oximeters
- Blood Pressure Monitors
- Medtronic plc
- Abbott Laboratories
- Stryker Corporation
- Becton, Dickinson and Company
- JOHNSON & JOHNSON
Key Takeaways
- Germany's biosurgery market is projected to grow from $796.3 million in 2025 to $1,025.5 million by 2030 at a 5.2% CAGR.
- Germany's advanced healthcare infrastructure and high surgical volumes position it as a key European biosurgery market.
- Minimally invasive surgical procedures and aging demographics drive biosurgery demand across Germany.
- Germany's robust reimbursement framework and regulatory environment support continued biosurgery product adoption and innovation.
Biosurgery Market Report Scope
| Report Metric | Details |
|---|---|
| Base Year | 2025 |
| Fastest Growing Segment | BONE MORPHOGENETIC PROTEINS (Type) |
| Forecast Period | 2025-2030 |
| Growth Rate | CAGR of 6.4% from 2025 to 2030 |
| Largest Segment | HOSPITALS (End User) |
| Market Size Base Year (Billions) | ~USD 15.83 (2025) |
| Revenue Forecast (Billions) | ~USD 21.59 (2030) |
| Segments Covered | Type, Origin, Application, End User, Product |
Germany Biosurgery Market Report Segmentation
5 segment dimensions are covered across the global market.
By Type
- Albumin-Based Sealants & Adhesives
- Allografts
- Biological Meshes
- Bone Morphogenetic Proteins
- Collagen & Protein Adhesion Barriers
- Collagen-Based Sealants & Adhesives
- Combination Hemostatic Agents
- Cyanoacrylate-Based Sealants & Adhesives
- Demineralized Bone Matrix
- Fibrin-Based Adhesion Barriers
- Fibrin-Based Sealants & Adhesives
- Gelatin-Based Sealants & Adhesives
- Hyaluronic Acid-Based Adhesion Barriers
- Natural Adhesion Barriers
- Natural/Biological Sealants & Adhesives
- Natural/Biological Surgical Sealants & Adhesives
- Other Bone-Graft Substitutes
- Other Natural/Biological Surgical Sealants & Adhesives
- Other Synthetic & Semi-Synthetic Surgical Sealants & Adhesives
- Other Synthetic Adhesion Barriers
- Oxidized Regenerated Cellulose-Based Hemostatic Agents
- Peg Hydrogel-Based Sealants & Adhesives
- Peg-Based Adhesion Barriers
- Regenerated Cellulose-Based Adhesion Barriers
- Synthetic & Semi-Synthetic Surgical Sealants & Adhesives
- Synthetic Adhesion Barriers
- Synthetic Bone Grafts
- Synthetic Meshes
- Thrombin-Based Hemostatic Agents
- Urethane-Based Sealants & Adhesives
- Xenografts
By Origin
- Animal-Based Sealants & Adhesives
- Human Blood-Based Sealants & Adhesives
By Application
- Cardiovascular Surgery
- General Surgery
- Gynecological Surgery
- Neurological Surgery
- Orthopedic Surgery
- Other Applications
- Reconstructive Surgery
- Thoracic Surgery
- Urological Surgery
By End User
- Ambulatory Surgical Centers
- Clinics
- Hospitals
- Other End Users
By Product
- Adhesion Barriers
- Bone-Graft Substitutes
- Hemostatic Agents
- Soft-Tissue Attachments
- Staple-Line Reinforcement Agents
- Surgical Sealants & Adhesives
GERMANY: BIOSURGERY MARKET, BY END USER, 2023–2030
| Segment | 2023 | 2024 | 2025 | 2026 | 2027 | 2028 | 2029 | 2030 | CAGR (%) |
|---|---|---|---|---|---|---|---|---|---|
| AMBULATORY SURGICAL CENTERS | 93 | 97.8 | 104 | 110.7 | 118 | 126 | 134.8 | 144.5 | 6.8 |
| CLINICS | 124.3 | 129.7 | 136.7 | 144.3 | 152.6 | 161.6 | 171.4 | 182.2 | 5.9 |
| HOSPITALS | 468.3 | 483.5 | 504.4 | 526.9 | 551.3 | 577.7 | 606.5 | 637.6 | 4.8 |
| OTHER END USERS | 48.5 | 49.5 | 51.1 | 52.8 | 54.7 | 56.7 | 58.9 | 61.2 | 3.7 |
| TOTAL | 734.1 | 760.5 | 796.3 | 834.7 | 876.6 | 922 | 971.6 | 1025.5 | 5.2 |
Target Audience
- Medical Device Manufacturers : Biosurgery companies need Germany-specific market data to assess market size, competitive positioning, and growth opportunities for hemostatic and tissue sealant product launches.
- Healthcare Investors & PE Firms : Investment professionals require detailed German market analysis to evaluate acquisition targets, portfolio company performance, and return potential in the European biosurgery sector.
- Hospital & Surgical Center Administrators : Healthcare facility leaders need market insights to benchmark biosurgery adoption rates, optimize procurement strategies, and evaluate emerging hemostatic technologies for their surgical programs.
- Market Research & Strategy Consultants : Consulting firms require Germany-specific biosurgery data to support client strategy development, competitive analysis, and market entry recommendations for healthcare clients.
- Regulatory & Compliance Professionals : Regulatory specialists need German market intelligence to understand local approval pathways, reimbursement requirements, and compliance standards for biosurgery product commercialization.
Reasons to Buy this Report
- Country-Specific Market Sizing : Obtain precise valuation data for Germany's biosurgery market with verified 2025 baseline ($796.3M) and 2030 forecast ($1,025.5M), enabling accurate financial planning and investment decisions.
- Competitive Landscape Intelligence : Understand Germany's unique competitive dynamics, including leading manufacturers, market share distribution, and regional product preferences specific to German surgical practices.
- Reimbursement & Regulatory Insights : Access detailed analysis of German reimbursement frameworks, regulatory pathways, and healthcare policies that directly impact biosurgery product adoption and pricing strategies.
- Growth Opportunity Identification : Identify high-growth surgical segments and therapeutic areas within Germany where biosurgery adoption is accelerating, supporting targeted market entry and expansion strategies.
- Strategic Market Entry Planning : Leverage Germany-specific data on healthcare infrastructure, surgeon preferences, and distribution channels to develop effective market entry and commercialization strategies.
Frequently asked questions
What is the current size of Germany's biosurgery market?
Germany's biosurgery market is valued at $796.3 million in 2025 and is expected to reach $1,025.5 million by 2030.
What is the growth rate of Germany's biosurgery market?
Germany's biosurgery market is growing at a compound annual growth rate (CAGR) of 5.2% from 2025 to 2030.
What factors drive biosurgery market growth in Germany?
Key growth drivers in Germany include advanced healthcare infrastructure, increasing demand for minimally invasive procedures, an aging population, robust reimbursement frameworks, and strong clinical evidence requirements supporting product adoption.
How does Germany's biosurgery market compare to Europe?
Germany maintains a strong position within the European biosurgery sector due to its advanced healthcare system, high surgical volumes, and favorable regulatory environment that supports innovation and product launches.
What biosurgery products are most in demand in Germany?
Germany shows strong demand for hemostatic agents, tissue sealants, and advanced wound management products, particularly in minimally invasive surgical applications across multiple specialties.
RESEARCH METHODOLOGY
The study involved major activities in estimating the current market size for the biosurgery market. Exhaustive secondary research was done to collect information on the biosurgery industry. The next step was to validate these findings, assumptions, and sizing with industry experts across the value chain using primary research. Different approaches, such as top-down and bottom-up, were employed to estimate the total market size. After that, the market breakup and data triangulation procedures were used to estimate the market size of the segments and subsegments of the Biosurgery market.
Secondary Research
The secondary research process involves the widespread use of secondary sources, directories, databases (such as Bloomberg Businessweek, Factiva, and D&B Hoovers), white papers, annual reports, investor presentations, SEC filings of companies and publications from government sources [such as National Institutes of Health (NIH), US FDA, US Census Bureau, World Health Organization (WHO), International Trade Administration (ITA), Global Burden of Disease Study, and Centers for Medicare and Medicaid Services (CMS) were referred to identify and collect information for the global biosurgery market study. It was also used to obtain important information about the key players and market classification & segmentation according to industry trends to the bottom-most level and key developments related to market and technology perspectives. A database of the key industry leaders was also prepared using secondary research.
Primary Research
In the primary research process, various supply and demand sources were interviewed to obtain qualitative and quantitative information for this report. The primary sources from the supply side include industry experts such as CEOs, vice presidents, marketing and sales directors, technology & innovation directors, and related key executives from various key companies and organizations in the biosurgery market. The primary sources from the demand side include ambulatory surgical centers, hospitals, Clinics, and other end users. Primary research was conducted to validate the market segmentation, identify key players, and gather insights on key industry trends & key market dynamics.
A breakdown of the primary respondents is provided below:
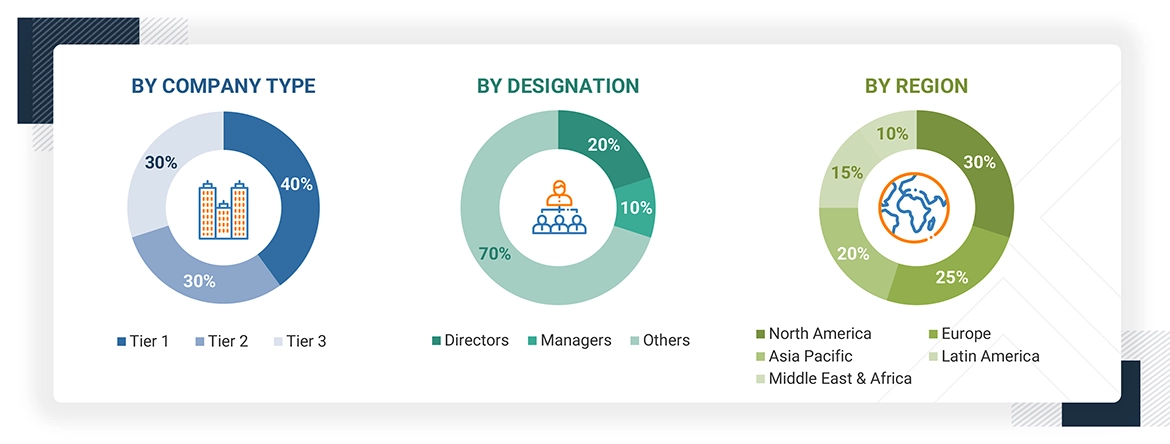
*C-level primaries include CEOs, CFOs, COOs, and VPs.
*Others include sales managers, marketing managers, business development managers, product managers, distributors, and suppliers.
Note: Companies are classified into tiers based on their total revenue. As of 2024, Tier 1 = >USD 10.00 billion, Tier 2 = USD 1.00 billion to USD 10.00 billion, and Tier 3 = < USD 1.00 billion.
Source: MarketsandMarkets Analysis
To know about the assumptions considered for the study, download the pdf brochure
Market Size Estimation
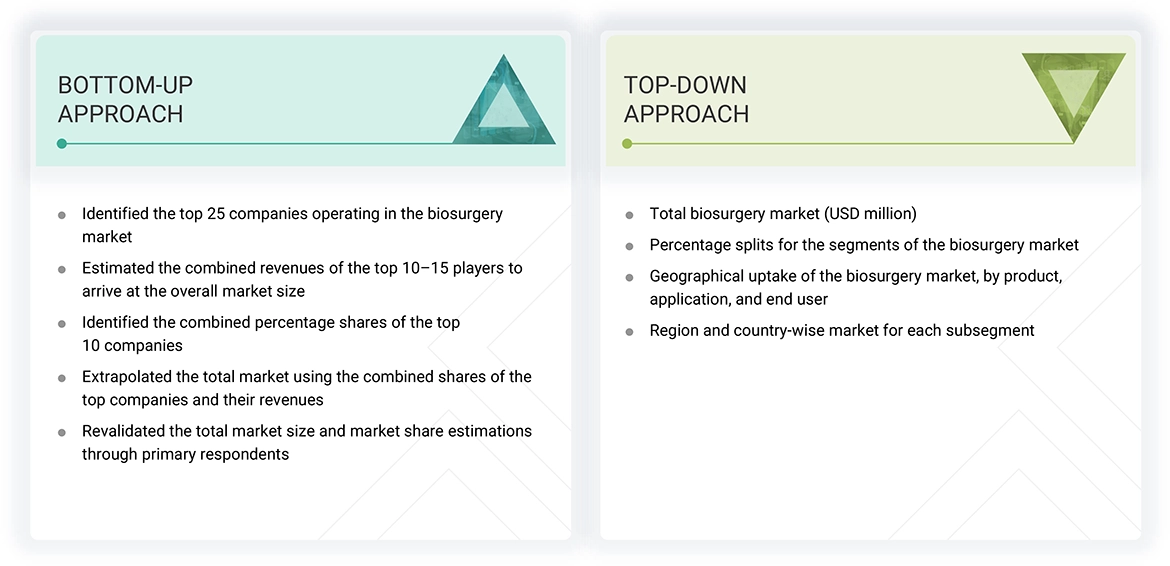
For the global market value, annual revenues were calculated based on the revenue mapping of major product manufacturers and OEMs active in the global biosurgery market. All the major product manufacturers were identified at the global and/or country/regional level. Revenue mapping for the respective business segments/sub-segments was done for the major players. Also, the global biosurgery market was split into various segments and sub-segments based on:
- List of major players operating in the products market at the regional and/or country level
- Product mapping of various biosurgery manufacturers at the regional and/or country level
- Mapping of annual revenue generated by listed major players from biosurgery (or the nearest reported business unit/product category)
- Extrapolation of the revenue mapping of the listed major players to derive the global market value of the respective segments/subsegments
- Summation of the market value of all segments/subsegments to arrive at the global biosurgery market
The above-mentioned data was consolidated and added with detailed inputs and analysis from MarketsandMarkets and presented in this report.
Market Size Estimation (Bottom-up Approach and Top-down Approach)
Data Triangulation
After arriving at the global biosurgery market's overall size through the methodology mentioned above, this market was split into several segments and subsegments. Where applicable, the data triangulation and market breakdown procedures were employed to complete the overall market engineering process and arrive at the exact market value data for the key segments and subsegments. The extrapolated market data was triangulated by studying various macro indicators and regional trends from both demand- and supply-side participants.
Market Definition
Biosurgery products are essential in surgical procedures, aiding in the repair of damaged tissues and bones. Surgeons utilize these products to stabilize skin, internal organs, and blood vessels, ensuring hemostasis and tissue integrity after injury or surgery. Key types include surgical sealants, hemostatic agents, adhesion barriers, soft-tissue attachments, bone-graft substitutes, and staple-line reinforcement agents, all designed to enhance healing and prevent complications.
Stakeholders
- Transfection products manufacturing companies
- Pharmaceutical & Biopharmaceutical Companies
- Chemical Companies
- Biopharmaceutical Companies
- Contract Research Organizations (CROs)
- Contract Development and Manufacturing Organizations (CDMOs)
- Research Institutes and Universities
- Venture Capitalists & Investors
- Government Associations
Report Objectives
- To define, describe, segment, and forecast the transfection technologies market by product type, method, application, end user, and region
- To provide detailed information about the major factors (such as drivers, restraints, opportunities, and challenges) influencing the market growth
- To strategically analyze micromarkets1 with respect to individual growth trends, prospects, and contributions to the overall market
- To analyze market opportunities for stakeholders and provide details of the competitive landscape for key players
- To forecast the size of the transfection technologies market in five main regions: North America, Europe, Asia Pacific, Latin America, and the Middle East & Africa, along with their respective key countries
- To profile the key players in the transfection technologies market and comprehensively analyze their core competencies2 and market shares
- To track and analyze competitive developments, such as product launches, acquisitions, expansions, collaborations, agreements, and partnerships of the leading players in the transfection technologies market
- To benchmark players within the transfection technologies market using the ‘Competitive Leadership Mapping’ framework, which analyzes market players based on various parameters, including product portfolio, geographic reach, and market share/rank
Get the Full Biosurgery Market Report
Full forecast, segment splits, and company analysis for all Biosurgery Market.
- Canada Biosurgery Market
- US Biosurgery Market
- UK Biosurgery Market
- France Biosurgery Market
- Italy Biosurgery Market
- Spain Biosurgery Market
- China Biosurgery Market
- India Biosurgery Market
- Japan Biosurgery Market
- South Korea Biosurgery Market
- Australia Biosurgery Market
- Brazil Biosurgery Market
- Mexico Biosurgery Market
- Rest Of Europe Biosurgery Market
- Rest Of Asia Pacific Biosurgery Market
- Rest Of Latin America Biosurgery Market
Need a Tailored Report?
Customize this report to your needs
Get 10% FREE Customization
Customize This Report