North America Carbon Capture, Utilization, and Storage Market (2025-2030)
The North America Carbon Capture, Utilization, and Storage Market was valued at $2804.6 Million in 2025 and projected to reach to $7196.5 Million by 2030, representing a compound annual growth rate of 20.7%. North America's CCUS market is positioned for accelerated growth driven by stringent environmental regulations, substantial government incentives, and corporate net-zero commitments.

| Market Size in | USD 26.32 MN |
| Market Forecast in | |
| CAGR | |
| Forecast Period | |
| Units Considered | Value (USD MN) |
North America Carbon Capture, Utilization, and Storage Market Trends and Insights
- This 20.7% compound annual growth rate reflects North America's leadership in climate technology innovation and regulatory support for carbon reduction initiatives.
- North America benefits from established infrastructure, significant government incentives, and strong private sector investment driving CCUS adoption across industrial, energy, and chemical sectors. The North America CCUS market is propelled by stringent environmental regulations, corporate net-zero commitments, and technological advancements in capture efficiency.
- North America's diverse industrial base—including oil and gas, cement, and power generation—creates substantial demand for carbon capture solutions.
- Between 2025 and 2030, North America is expected to consolidate its position as a global CCUS hub, with increasing deployment of direct air capture (DAC) facilities and enhanced utilization pathways for captured carbon..
Key Market Statistics
- CAGR (2025-2030) 20.7% CAGR
- Market Size, 2025 ~USD 2804.6 Million
- Forecast, 2030 ~USD 7196.5 Million
- Geography North America
North America Carbon Capture, Utilization, and Storage Market Overview
Market Valuation & Growth :
North America's CCUS market is valued at $2,804.6 million in 2025, with a robust 20.7% CAGR projected through 2030, reaching $7,196.5 million. This growth trajectory underscores the region's commitment to carbon reduction and climate technology advancement.
Regulatory & Policy Support :
North America benefits from strong governmental incentives including the US 45Q tax credit, Canadian carbon pricing mechanisms, and Mexico's climate commitments. These policies create favorable conditions for CCUS technology deployment and investment across the region.
Infrastructure & Technology Leadership :
The region possesses established CO2 pipeline networks, storage facilities, and advanced capture technologies. North America leads in innovation with major investments from energy companies, tech firms, and startups driving commercialization of CCUS solutions.
Industrial & Energy Sector Adoption :
Key sectors including oil & gas, chemicals, cement, and power generation are increasingly adopting CCUS technologies. Industrial emitters in North America are integrating carbon capture into operations to meet regulatory requirements and sustainability targets.
North America Carbon Capture, Utilization, and Storage Market Dynamics
- The US 45Q tax credit expansion and Canadian carbon pricing frameworks are catalyzing investment in both point-source capture and direct air capture technologies.
- Industrial sectors are rapidly adopting CCUS to achieve emissions reduction targets while maintaining operational efficiency. The forecast period through 2030 will witness significant infrastructure development, including expanded CO2 pipeline networks and permanent storage facilities.
- Strategic partnerships between energy majors, technology providers, and government agencies will accelerate commercialization.
- North America's technological expertise and capital availability position it as a global CCUS hub, attracting international investment and enabling the region to lead in carbon management innovation..
Market Ecosystem
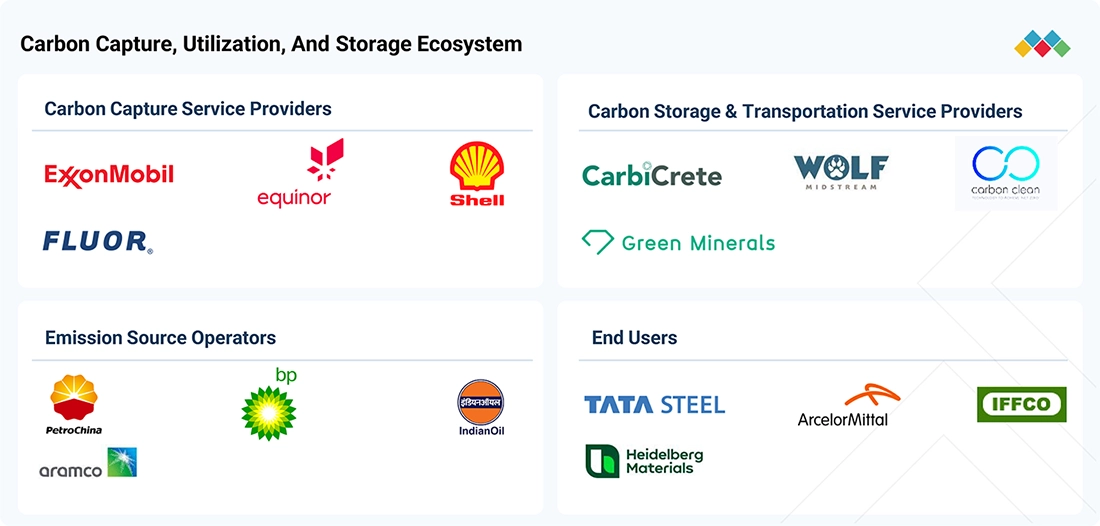
CARBON CAPTURE, UTILIZATION, AND STORAGE MARKET: COMMERCIAL USE CASES ACROSS INDUSTRIES
| COMPANY | USE CASE DESCRIPTION | BENEFITS |
|---|---|---|
 |
Carbon capture and storage across Gulf Coast heavy industrial facilities, including steel production, fertilizer plants, and power generation assets | Emissions reduction, regulatory compliance, asset preservation, scale efficiency |
 |
Carbon capture integration at cement manufacturing plants for industrial flue gas decarbonization and underground storage | Industrial decarbonization, green product differentiation, regulatory alignment, risk mitigation |
 |
Cross-border CO2 transport and offshore subsea geological storage (Northern Lights) for third-party industrial emitters. | Infrastructure access, scalable storage, regulatory compliance, shared Capex model |
 |
Direct Air Capture (STRATOS) for atmospheric CO2 removal and utilization in Enhanced Oil Recovery (EOR) and permanent sequestration | High-integrity removals, carbon credit generation, EOR efficiency, net-zero alignment |
Logos and trademarks shown above are the property of their respective owners. Their use here is for informational and illustrative purposes only.
Related Ecosystem
Green Bio Chemicals
- Animal-Based Sealants
- Bacterial Fermentation
- Corrosion Inhibitors
- Hydrogen Peroxide
- Nitrile Butadiene Rubber (NBR)
- Basf se
- Evonik industries ag
- Solvay sa
- AZELIS HOLDINGS SA
- CARGILL, INCORPORATED
Key Takeaways
- North America's CCUS market will grow from $2,804.6M (2025) to $7,196.5M (2030), representing a 20.7% CAGR.
- North America leads globally in CCUS infrastructure investment, driven by federal tax credits and state-level climate policies.
- North America's industrial sectors—oil & gas, cement, chemicals—are primary adopters of carbon capture technologies.
- North America is accelerating direct air capture (DAC) deployment and carbon utilization pathways for enhanced market growth.
Carbon Capture, Utilization, and Storage Market Report Scope
| Report Metric | Details |
|---|---|
| Base Year | 2025 |
| Fastest Growing Segment | POST-COMBUSTION (Technology) |
| Forecast Period | 2025–2030 |
| Growth Rate | CAGR of 25% from 2025 to 2030 |
| Largest Segment | CAPTURE (Service) |
| Market Size Base Year (Billions) | ~USD 5.82 (2025) |
| Revenue Forecast (Billions) | ~USD 17.75 (2030) |
| Segments Covered | Service, Technology, End-Use Industry |
North America Carbon Capture, Utilization, and Storage Market Report Segmentation
3 segment dimensions are covered across the global market.
By Service
- Capture
- Storage
- Transportation
- Utilization
By Technology
- Beccs
- Chemical Looping
- Dac
- Deep Ocean Storage
- Geological Storage
- Membranes
- Other Carbon Capture Technologies
- Other Technologies
- Oxy-Fuel
- Post-Combustion
- Pre-Combustion
- Solvents & Sorbents
By End-Use Industry
- Cement
- Chemical & Petrochemical
- Iron & Steel
- Oil & Gas
- Other End-Use Industries
- Power Generation
Target Audience
- Energy & Oil & Gas Companies : Evaluate CCUS integration opportunities, assess regulatory compliance pathways, and identify carbon management investments to support net-zero transitions and enhance operational sustainability in North America.
- Industrial Manufacturers : Understand CCUS adoption requirements for chemicals, cement, and steel production. Access market data to evaluate technology investments, cost-benefit analyses, and emissions reduction strategies specific to North American operations.
- Technology & Equipment Providers : Identify market demand drivers, competitive landscapes, and growth opportunities for CCUS solutions. Understand regional customer needs, regulatory requirements, and commercialization pathways in North America.
- Government & Policy Makers : Assess CCUS market development, evaluate policy effectiveness, and benchmark North American initiatives against global standards. Use data to inform climate strategy, incentive programs, and infrastructure investment decisions.
- Investors & Financial Institutions : Evaluate CCUS market growth potential, identify high-return investment opportunities, and assess risk profiles across North American segments. Support portfolio decisions and capital allocation strategies in climate technology.
Key Companies in the North America Carbon Capture, Utilization, and Storage Market
| Company | HQ | Ownership | Strongest segments |
|---|---|---|---|
| BAKER HUGHES COMPANY | United States | Public Company | Drilling, Completions & Intervention Services,Pressure Pumping, Wireline & Well Production,Subsea, Flexible Pipe & Surface Pressure Control, |
| PETROBRAS | Brazil | Public Company | Exploration and Production (crude oil, NGLs, natural gas),Refining, Transportation & Marketing (oil products, petrochemicals, fertilizers),Gas & Low Carbon Energies (natural gas, LNG, power, renewables, biodiesel), |
| HOLCIM LTD | Switzerland | Public Company | Cement, clinker, and other cementitious materials,Ready-mix concrete and digital concrete services,Aggregates (crushed stone, gravel, sand), |
| FLUOR CORPORATION | United States | Public Company | Energy Solutions (oil, gas, chemicals, power, energy transition),Urban Solutions (advanced manufacturing, life sciences, mining, infrastructure, staffing, maintenance),Mission Solutions (government, nuclear remediation, security, logistics, O&M), |
| EXXON MOBIL CORPORATION | United States | Public Company | Upstream (crude oil and natural gas),Energy Products (fuels, aromatics, catalysts, licensing),Chemical Products (olefins, polyolefins, intermediates), |
| SHELL PLC | United Kingdom | Public Company | Integrated Gas (incl. LNG and GTL),Upstream (oil, gas, NGLs),Marketing (mobility, lubricants, commercial fuels), |
| EQUINOR ASA | Norway | Public Company | Exploration & Production Norway,Exploration & Production International & USA,Marketing, Midstream & Processing, |
| TOTALENERGIES SE | France | Public Company | Upstream oil and gas production,Refining, fuels marketing, and biofuels,LNG, pipeline gas, and biogas, |
| LINDE PLC | United Kingdom | Public Company | Atmospheric gases (oxygen, nitrogen, argon, rare gases),Process gases (hydrogen, CO2, CO, helium, acetylene, specialty and electronic gases),Engineering & turnkey process plants, |
| MITSUBISHI HEAVY INDUSTRIES, LTD. | Japan | Public Company | Thermal power generation systems (gas turbine combined cycle and steam),Nuclear power systems and post-operational services,Wind power generators and renewable/low-carbon solutions, |
| JGC HOLDINGS CORPORATION | Japan | Public Company | Petroleum and Refining EPC,Petrochemicals and Gas Processing EPC,LNG EPC, |
| SCHLUMBERGER LIMITED | United States | Public Company | Digital & Integration,Reservoir Performance,Well Construction, |
| AKER SOLUTIONS | Norway | Public Company | Field Development (subsea, topsides, facilities),Life Cycle (maintenance, modifications, decommissioning),Renewables & Low-Carbon Solutions (offshore wind, CCUS, hydropower, electrification), |
| HONEYWELL INTERNATIONAL | United States | Public Company | Industrial Automation,Building Automation,Energy and Sustainability Solutions (UOP and related), |
| HITACHI, LTD. | Japan | Public Company | Digital Systems & Services,Green Energy & Mobility,Connective Industries, |
| SIEMENS AG | Germany | Public Company | Digital Industries (automation, control, industrial software),Smart Infrastructure (electrification, buildings, grid solutions),Mobility (rail systems, automation, services), |
| GE VERNOVA | United States | Public Company | Power (gas, nuclear, hydro, steam),Wind (onshore and offshore),Electrification (grid, power conversion, solar and storage, software), |
| HALLIBURTON | United States | Public Company | Completion and Production,Drilling and Evaluation, |
BAKER HUGHES COMPANY
Baker Hughes Company is a U.S.-based public company founded in 2016 with 53,000 employees. The company operates in the energy sector, providing equipment and services to the oil and gas industry.
PETROBRAS
Petrobras is a Brazilian public company founded in 1953 with 43,199 employees. It is a major integrated energy company engaged in exploration, production, refining, and distribution of oil and natural gas.
HOLCIM LTD
Holcim Ltd is a Swiss public company founded in 1833 with 45,595 employees. The company is a leading global manufacturer and distributor of cement, aggregates, and ready-mix concrete.
FLUOR CORPORATION
Fluor Corporation is a U.S.-based public company founded in 1912 with 22,995 employees. The company provides engineering, procurement, and construction services to the energy, chemical, and industrial sectors.
EXXON MOBIL CORPORATION
Exxon Mobil Corporation is a U.S.-based public company founded in 1870 with 57,900 employees. It is one of the world's largest integrated energy companies, engaged in exploration, production, refining, and marketing of oil and natural gas.
SHELL PLC
Shell PLC is a United Kingdom-based public company founded in 1897 with 84,000 employees. It is a major global energy company involved in oil and gas exploration, production, refining, and renewable energy.
EQUINOR ASA
Equinor ASA is a Norwegian public company founded in 1972 with 23,843 employees. The company is an integrated energy company focused on oil and gas exploration, production, and renewable energy development.
TOTALENERGIES SE
TotalEnergies SE is a French public company founded in 1924 with 94,847 employees. It is a major integrated energy company engaged in oil and gas production, refining, and renewable energy projects worldwide.
LINDE PLC
Linde PLC is a United Kingdom-based public company founded in 1879 with 65,034 employees. The company is a leading global supplier of industrial gases and engineering services to various industries.
MITSUBISHI HEAVY INDUSTRIES, LTD.
Mitsubishi Heavy Industries, Ltd. is a Japanese public company founded in 1884 with 78,793 employees. The company operates across multiple sectors including energy, infrastructure, industrial machinery, and aerospace.
JGC HOLDINGS CORPORATION
JGC Holdings Corporation is a Japanese public company founded in 1928 with 8,154 employees. The company provides engineering, procurement, and construction services primarily for the energy and chemical industries.
SCHLUMBERGER LIMITED
Schlumberger Limited is a U.S.-based public company founded in 1926 with 109,000 employees. It is the world's largest oilfield services company, providing technology and services to the oil and gas industry.
AKER SOLUTIONS
Aker Solutions is a Norwegian public company founded in 1841 with 11,731 employees. The company provides engineering, design, and construction services to the oil, gas, and renewable energy sectors.
HONEYWELL INTERNATIONAL
Honeywell International is a U.S.-based public company founded in 1885 with 101,000 employees. The company is a diversified technology and manufacturing conglomerate serving aerospace, building, performance materials, and safety sectors.
HITACHI, LTD.
Hitachi, Ltd. is a Japanese public company founded in 1910 with 287,901 employees. It is a major diversified conglomerate operating across infrastructure, industrial systems, information technology, and other sectors.
SIEMENS AG
Siemens AG is a German public company founded in 1847 with 310,312 employees. It is a global technology conglomerate providing solutions in electrification, automation, and digitalization across multiple industries.
GE VERNOVA
GE Vernova is a U.S.-based public company founded in 2023 with 78,000 employees. The company focuses on energy transition solutions including power generation, grid services, and energy storage technologies.
HALLIBURTON
Halliburton is a U.S.-based public company founded in 1919 with 46,000 employees. The company provides a wide range of services and products to the oil and gas industry, including drilling, completion, and production services.
Countries within North America - compare and drill down
| Country | 2025 size (native) |
|---|---|
| US | USD 63809 Million |
| Canada | USD 23124.7 Million |
| Mexico | USD 7949.7 Million |
Country market size visualization
Reasons to Buy this Report
- Regional Market Sizing & Forecasts : Obtain precise market valuations for North America's CCUS sector with country-level breakdowns for the US, Canada, and Mexico. Access detailed 2025-2030 forecasts to inform strategic planning and investment decisions.
- Regulatory & Policy Landscape Analysis : Understand the impact of the US 45Q tax credit, Canadian carbon pricing, and Mexican climate policies on market dynamics. Identify compliance requirements and incentive structures driving CCUS adoption across North America.
- Competitive & Technology Insights : Analyze leading CCUS technology providers, infrastructure developers, and industrial adopters in North America. Benchmark competitive positioning and identify emerging technologies reshaping the regional market.
- Sector-Specific Opportunities : Discover high-growth segments including point-source capture in chemicals and cement, direct air capture expansion, and utilization applications. Identify which industries offer the strongest ROI potential in North America.
- Investment & Partnership Strategy : Leverage market intelligence to identify strategic investment targets, joint venture opportunities, and partnership potential with technology leaders, energy majors, and infrastructure developers across North America.
Frequently asked questions
What is the projected market size of CCUS in North America by 2030?
North America's CCUS market is projected to reach $7,196.5 million by 2030, up from $2,804.6 million in 2025, representing a 20.7% CAGR.
What are the primary drivers of CCUS market growth in North America?
North America's CCUS growth is driven by federal tax incentives (45Q credits), corporate net-zero commitments, stringent environmental regulations, and technological advancements in carbon capture efficiency.
Which industries in North America are leading CCUS adoption?
North America's oil and gas, cement, chemical manufacturing, and power generation sectors are the primary adopters of CCUS technologies due to their high carbon emissions and regulatory pressures.
How does North America's CCUS market compare to global growth rates?
North America's CCUS market CAGR of 20.7% is slightly below the global average of 25%, reflecting North America's mature market position and established infrastructure base.
What role does direct air capture (DAC) play in North America's CCUS market?
North America is rapidly expanding DAC deployment as a key growth segment, with increasing investment in permanent carbon removal solutions and utilization pathways for captured CO2.
RESEARCH METHODOLOGY
This study consisted of two main tasks to determine the current size of the carbon capture, utilization, and storage market. The first task involved conducting extensive secondary research to gather information on the carbon capture, utilization, and storage market, related markets, and parent markets. The results, assumptions, and market sizing were further verified through primary research with industry players. Market size was estimated using both top-down and bottom-up approaches. Further market segmentation and data triangulation techniques were used to obtain the market size of segments and subsegments.
Secondary Research
Sources used for secondary research for this study include annual reports, financial documents, product portfolios, technical sheets, certificates, company websites, industry magazines, and industry associations. Secondary research was conducted to gain insights into the value chain of carbon capture, utilization, and storage service providers, major market players, market segmentation, and classification by service, technology, end-use industry, and geography. The data gathered through this process was further analyzed to estimate the size of the global carbon capture, utilization, and storage market and its segments and subsegments.
Primary Research
Extensive primary research was conducted after obtaining information regarding the market scenario through secondary research. We conducted several primary interviews with market experts on both the demand and supply sides across major countries. We collected primary data through questionnaires, emails, and telephonic interviews. The primary sources from the supply side included various industry experts, such as chief experience officers (CXOs), vice presidents (VPs), business development/marketing directors, product development/innovation teams, related key executives from the carbon capture, utilization, and storage service industry, system integrators, technology suppliers, EPC contractors, component providers, distributors, and key opinion leaders. Primary interviews were conducted to gather insights such as market statistics, revenue data from products and services, market breakdowns, market size estimates, market forecasts, and data triangulation. Primary research helped in understanding various trends related to service, technology, end-use industry, and region. Stakeholders from the demand side, such as CIOs, CTOs, CSOs, and installation teams of the customers/end users who are seeking carbon capture, utilization, and storage services, were interviewed to understand the buyer’s perspective on product/service providers, as well as their current usage of carbon capture, utilization, and storage products/services and future outlook of their business, which will affect the overall market.
Breakup of Primary Research:
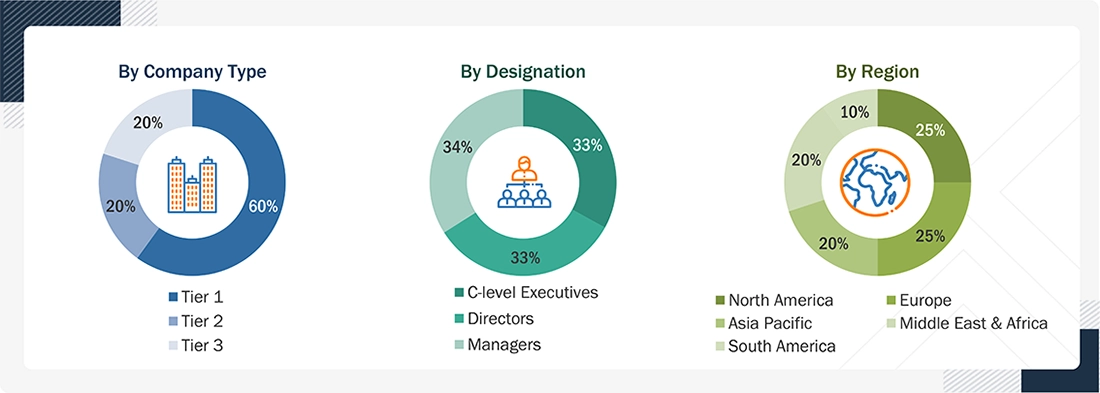
To know about the assumptions considered for the study, download the pdf brochure
Market Size Estimation
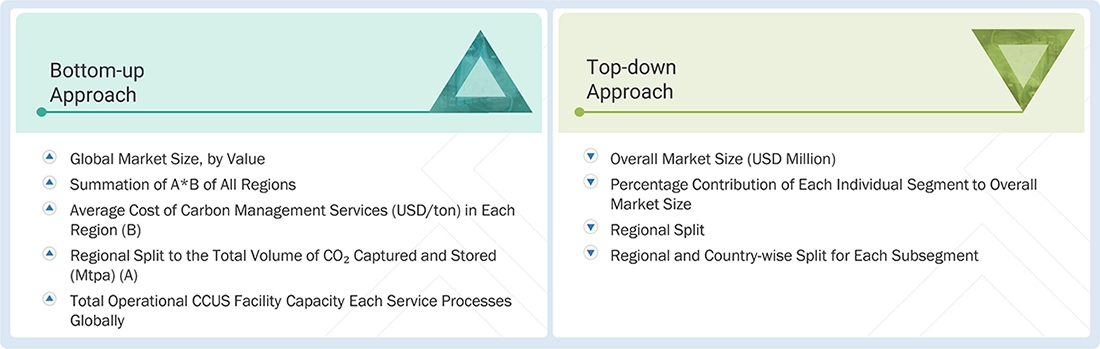
The research methodology used to estimate the size of the carbon capture, utilization, and storage market includes the following details. The market size was estimated from the demand side. The market was expanded based on global demand for carbon capture, utilization, and storage products/services across different industries. These procurements provide demand-side information for each end-use industry in the carbon capture, utilization, and storage market. For each end-use industry, all possible segments of the carbon capture, utilization, and storage market were integrated and mapped.
Data Triangulation
After determining the overall size through the market size estimation process explained above, the total market was split into several segments and subsegments. The data triangulation and market breakdown procedures explained below were implemented, wherever applicable, to complete the overall market engineering process and arrive at the exact statistics for various market segments and subsegments. The data were triangulated by studying factors and trends from both the demand and supply sides. In addition, the market size was validated using both the top-down and bottom-up approaches.
Market Definition
The carbon capture, utilization, and storage market comprises technologies, solutions, and associated services across the CO2 management value chain, including the capture of CO2 from industrial facilities, power generation plants, and the atmosphere; its conditioning, compression, and transportation; and its subsequent utilization or permanent geological storage. The market encompasses solutions/services for CO2 capture, transport, utilization, and storage, as well as integrated systems that connect these stages to enable carbon management and emission reduction across industrial and energy applications.
Key Stakeholders
- CCUS service providers
- Universities, governments, and research organizations
- Associations and industrial bodies
- Environmental support agencies
- Investment banks and private equity firms
- Fire safety testing and certification organizations
- R&D institutes and research organizations
- Raw material suppliers
- Government and regulatory authorities
Report Objectives
- To define, describe, and forecast the carbon capture, utilization, and storage market in terms of volume and value
- To provide detailed information regarding the key factors, such as drivers, restraints, opportunities, and challenges influencing market growth
- To analyze and project the market size by service, technology, end-use industry, and region
- To forecast the global carbon capture, utilization, and storage market size, along with regional and country-level data, and analyze key country-specific trends
- To strategically analyze micromarkets, including individual growth trends, prospects, and submarket contributions to the overall market
- To analyze the market opportunities and the competitive landscape for stakeholders and market leaders
- To assess recent market developments and competitive strategies, such as agreements, contracts, acquisitions, and product developments/product launches, to map the competitive landscape
- To strategically profile the key market players and comprehensively analyze their core competencies
Available customizations:
MarketsandMarkets offers the following customizations for this market report:
- Additional country-level analysis of the carbon capture, utilization, and storage market
Product Analysis
- Product matrix, which provides a detailed comparison of the product portfolio of each company in the market
Get the Full Carbon Capture, Utilization, and Storage Market Report
Full forecast, segment splits, and company analysis for all Carbon Capture, Utilization, and Storage Market.
- US Carbon Capture, Utilization, and Storage Market
- Canada Carbon Capture, Utilization, and Storage Market
- Mexico Carbon Capture, Utilization, and Storage Market
- UK Carbon Capture, Utilization, and Storage Market
- France Carbon Capture, Utilization, and Storage Market
- Netherlands Carbon Capture, Utilization, and Storage Market
- Italy Carbon Capture, Utilization, and Storage Market
- Norway Carbon Capture, Utilization, and Storage Market
- China Carbon Capture, Utilization, and Storage Market
- Japan Carbon Capture, Utilization, and Storage Market
- India Carbon Capture, Utilization, and Storage Market
- Australia Carbon Capture, Utilization, and Storage Market
- Brazil Carbon Capture, Utilization, and Storage Market
- Argentina Carbon Capture, Utilization, and Storage Market
- Rest Of Europe Carbon Capture, Utilization, and Storage Market
- Rest Of Asia Pacific Carbon Capture, Utilization, and Storage Market
Need a Tailored Report?
Customize this report to your needs
Get 10% FREE Customization
Customize This Report