Canada Cloud Services Brokerage Market (2024-2029)

The Canada Cloud Services Brokerage Market was valued at $462.1 Million in 2024 and projected to reach to $1110.6 Million by 2029, representing a compound annual growth rate of 19.2%. Canada's cloud services brokerage market is positioned for sustained growth as enterprises continue their digital transformation journeys and embrace hybrid and multi-cloud architectures.


| Market Size in | USD 26.32 MN |
| Market Forecast in | |
| CAGR | |
| Forecast Period | |
| Units Considered | Value (USD MN) |
Canada Cloud Services Brokerage Market Trends and Insights
- This represents a compound annual growth rate of 19.2%, significantly outpacing global trends as Canadian enterprises increasingly adopt multi-cloud strategies and seek specialized brokerage solutions to optimize cloud spending and vendor management.
- Canada's market growth is driven by rising cloud adoption across financial services, healthcare, and technology sectors, where organizations require sophisticated tools to navigate complex cloud ecosystems and reduce operational costs. The Canadian market benefits from strong digital infrastructure, regulatory frameworks supporting cloud innovation, and a mature IT services sector.
- Between 2024 and 2029, Canada is expected to capture growing demand from mid-market and enterprise organizations seeking to consolidate cloud vendors, improve governance, and enhance cost visibility.
- The 19.2% CAGR reflects Canada's position as a leading North American hub for cloud transformation, with increasing investment in cloud management platforms and brokerage services to address vendor lock-in concerns and optimize cloud resource allocation..
Key Market Statistics
- CAGR (2024-2029) 19.2% CAGR
- Market Size, 2024 ~USD 462.1 Million
- Forecast, 2029 ~USD 1110.6 Million
- Country Canada
Canada Cloud Services Brokerage Market Overview
Rapid Market Expansion :
Canada's cloud services brokerage market is growing at 19.2% CAGR, outpacing the global rate of 18%, driven by enterprises' shift toward multi-cloud environments and cost optimization strategies.
Significant Market Growth :
The market is projected to more than double from $462.1 million in 2024 to $1,110.6 million by 2029, reflecting strong demand for cloud management solutions across Canadian organizations.
Multi-Cloud Adoption :
Canadian enterprises are increasingly implementing multi-cloud strategies, creating heightened demand for specialized brokerage solutions to manage vendor relationships and optimize cloud spending across platforms.
Cost Optimization Focus :
Organizations across Canada are prioritizing cloud cost management and vendor optimization, positioning cloud services brokers as critical partners for budget control and operational efficiency.
Canada Cloud Services Brokerage Market Dynamics
- The 19.2% CAGR through 2029 reflects strong organizational investment in cloud optimization tools and services, particularly among mid-market and enterprise-level companies seeking to maximize ROI on cloud infrastructure investments. The Canadian market benefits from a mature IT landscape, regulatory compliance requirements, and a competitive business environment that drives adoption of advanced cloud management solutions.
- As organizations navigate complex vendor ecosystems and cost pressures, cloud services brokers will play an increasingly vital role in helping Canadian enterprises achieve operational excellence and financial efficiency in their cloud deployments..
Market Ecosystem


OVERVIEW
Source: Secondary Research, Interviews with Experts, MarketsandMarkets Analysis
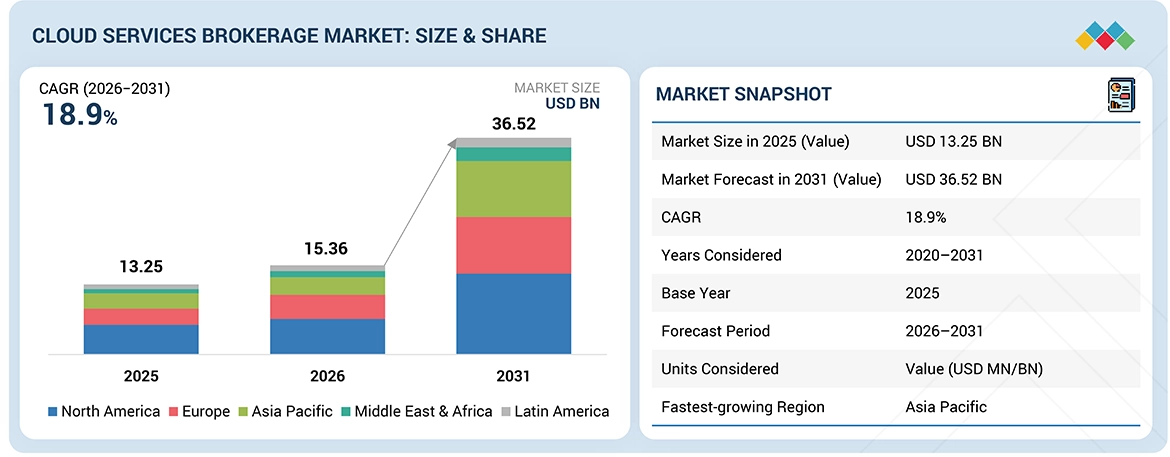
The cloud services brokerage market is expected to reach USD 36.52 billion by 2031, from USD 15.36 billion in 2026, with a CAGR of 18.9%. This growth is mainly driven by rapid multicloud adoption. Enterprises using multiple cloud providers face fragmented billing, security, and governance systems. Brokerage platforms address this complexity by enabling centralized cost optimization, workload orchestration, compliance management, and unified cross-cloud visibility.
KEY TAKEAWAYS
-
By RegionAsia Pacific is the fastest-growing region, with a CAGR of 23.8%.
-
By Service TypeService intermediation is expected to record a CAGR of 20.2% during the forecast period.
-
By Cloud Service ModelPlatform-as-a-Service is expected to grow at the highest CAGR of 22.2% from 2026 to 2031.
-
By Organization SizeSmall enterprises are the fastest-growing segment among all organization sizes.
-
By VerticalThe retail & consumer goods segment is expected to grow at the fastest rate during the forecast period.
-
Competitive Landscape – Large ProvidersIBM, Accenture, and Broadcom lead with strong multicloud integration and enterprise-scale automation capabilities.
-
Competitive Landscape – Emerging ProvidersOpenText, InContinuum, and Compunnel gain traction through flexible and cost-efficient cloud brokerage solutions.
The cloud services brokerage market is driven by increasing enterprise demand for easier workload portability, standardized cloud purchasing, and greater vendor transparency. As more organizations work with multiple vendors, there is a rising need for centralized service catalogs, consolidated billing, and performance tracking. Brokerage platforms will be vital for streamlining procurement processes, enabling cross-cloud comparisons, and enhancing operational accountability in distributed cloud setups.
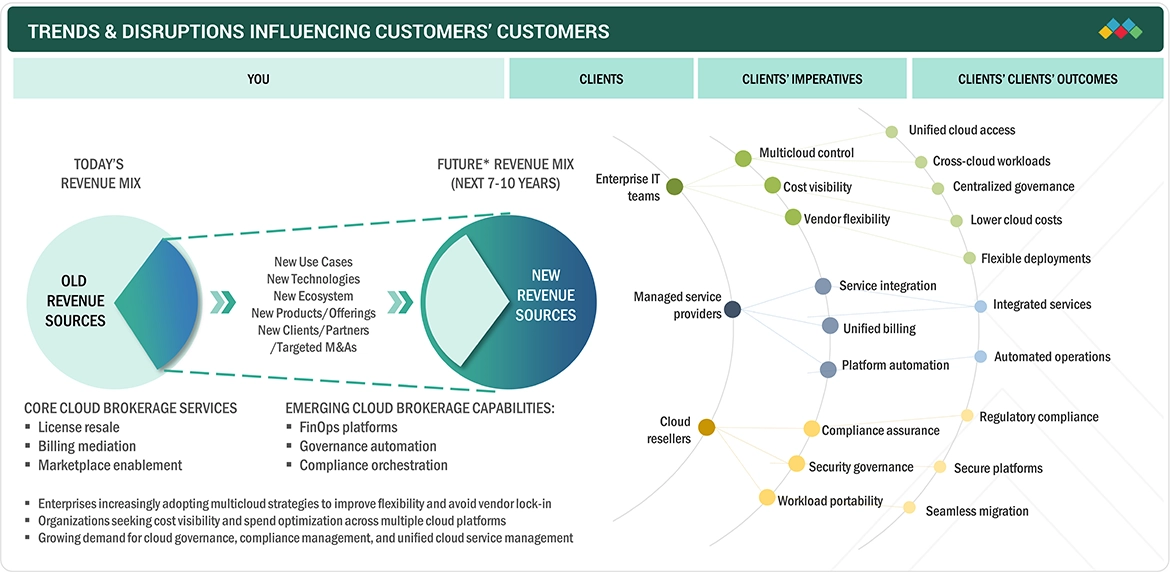
TRENDS & DISRUPTIONS IMPACTING CUSTOMERS' CUSTOMERS
The cloud services brokerage market is expanding as enterprises adopt multicloud strategies to avoid vendor lock-in and improve resilience, which increases operational and cost complexity. To address this, organizations are deploying brokerage platforms for centralized cost monitoring, automated workload placement, SLA tracking, and unified governance across AWS, Azure, and private clouds. Providers are embedding AI for predictive cost and performance optimization. Future growth will be shaped by sovereign cloud controls, API-led integration, and tighter security-policy orchestration.
Source: Secondary Research, Interviews with Experts, MarketsandMarkets Analysis
MARKET DYNAMICS

Level
-
Accelerated enterprise shift toward multicloud strategies requiring centralized governance, cost visibility, and workload orchestration across AWS, Azure, and private environments

-
Rising enterprise focus on minimizing downtime and ensuring business continuity


Level
-
Enterprise concerns over control, accountability, and integration dependency

-
Integration complexity across diverse billing models, IAM frameworks, and legacy systems creating implementation friction


Level
-
Increasing regulatory scrutiny and FinOps accountability mandates

-
Growing adoption of AI-driven orchestration and predictive optimization tools embedded within brokerage platforms


Level
-
Complexity of delivering consistent orchestration across heterogeneous cloud environments

-
Ensuring consistent performance, SLA enforcement, and latency optimization across global multicloud deployments

Source: Secondary Research, Interviews with Experts, MarketsandMarkets Analysis
Driver: Rising enterprise focus on minimizing downtime and ensuring business continuity
Enterprises are redesigning IT architectures around multicloud resilience, vendor diversification, and workload portability. However, fragmented billing, inconsistent policy enforcement, and limited cross-cloud visibility are driving up costs and operational risks. This structural complexity is increasing the need for brokerage platforms that centralize governance, optimize spending, and coordinate workloads across providers.
Restraint: Enterprise concerns over control, accountability, and integration dependency
Organizations are taking a cautious approach to introducing an intermediary governance layer between themselves and the hyperscalers due to concerns about data sovereignty, API dependencies, reduced contractual leverage, and the potential for architectural lock-in. These issues are creating barriers to large-scale implementation. Enterprises want transparency, validation for interoperability, and clear accountability models before deploying with brokers.
Opportunity: Increasing regulatory scrutiny and FinOps accountability mandates
The increasing regulatory scrutiny and the ongoing rise in cloud spending are pushing enterprise cloud strategies to require greater governance and financial accountability. As companies must demonstrate auditable controls, ensure transparent cost allocation, and enforce consistent policies across multicloud environments, this ecosystem will further promote the adoption of brokerage platforms. These platforms enable centralized visibility, compliance monitoring, and structured cost governance over dispersed cloud estates.
Challenge: Complexity of delivering consistent orchestration across heterogeneous cloud environments
Cloud providers have different APIs, pricing models, identity frameworks, and performance setups. Making sure security policies, SLA compliance, and latency are consistent across global deployments needs advanced automation and strong cross-platform integration. Achieving scalable interoperability remains a key challenge.
CLOUD SERVICES BROKERAGE MARKET OVERVIEW AND FUTURE OUTLOOK: COMMERCIAL USE CASES ACROSS INDUSTRIES
| COMPANY | USE CASE DESCRIPTION | BENEFITS |
|---|---|---|
 |
Implemented ArrowSphere multicloud delivery and management platform in the Nordic SME telecommunications industry to manage IaaS, PaaS, and SaaS. | Improved cloud service scalability, enabled new AI and IoT revenue streams, increased regional subscriptions, and delivered cost-effective cloud distribution to resellers and customers. |
 |
Implemented Cloudmore to automate billing processes and self-service capabilities for Microsoft´s cloud solutions provider services and improve customer relationship management. | Increased accuracy in billing and profitability tracking with improved customer self-service experiences, reduced manual work, and increased efficiency for operations and retention of customers. |
 |
Utilized NTT DATA´s cloud management services to optimize AWS spending with increased controls around financial governance and better management of hyperscale cloud complexity. | Delivered cost optimization recommendations, improved financial visibility, enhanced long-term cloud utilization strategy, and enabled scalable, flexible cloud management operations. |
Logos and trademarks shown above are the property of their respective owners. Their use here is for informational and illustrative purposes only.
MARKET ECOSYSTEM
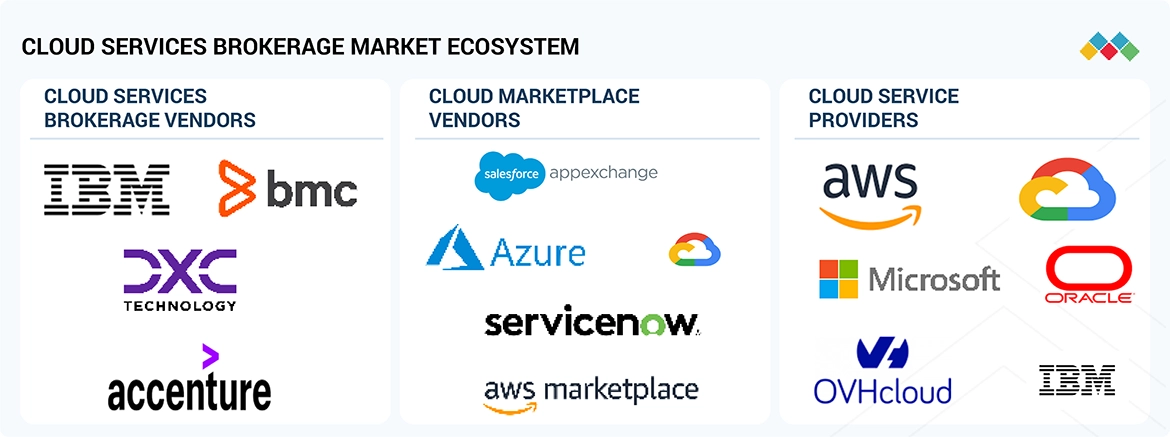
The cloud services brokerage ecosystem includes three main types of providers: cloud service brokerages (CSBs), cloud marketplaces (CMs), and cloud service providers (CSPs). As intermediaries, CSBs enable the integration, governance, and billing management across multiple clouds, offering support services for managing multicloud environments. CMs equip users with tools to discover and purchase cloud services, while CSPs deliver essential infrastructure or platform services for running businesses in the cloud.
Logos and trademarks shown above are the property of their respective owners. Their use here is for informational and illustrative purposes only.
MARKET SEGMENTS
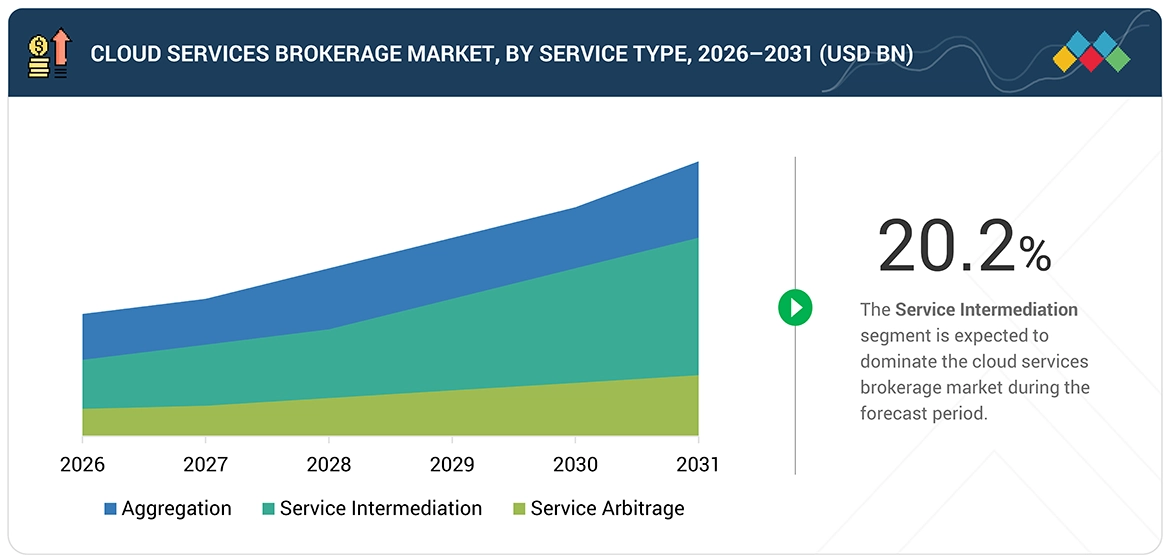
Source: Secondary Research, Interviews with Experts, MarketsandMarkets Analysis
By Service Type
Aggregation is key as enterprises increasingly operate across multiple cloud providers, leading to fragmented billing, governance, and performance visibility. The need to unify cost management, enforce standardized policies, and simplify vendor oversight makes aggregation essential. Providers should focus on integrated dashboards, FinOps tools, and API integrations to enhance value delivery.
By Cloud Service Model
SaaS leads because of quicker deployment, lower initial costs, and subscription-based scalability that fits with enterprise cloud adoption models. Organizations prefer SaaS brokerage platforms for automated updates and centralized governance without the burden of infrastructure. Vendors should improve AI-driven analytics and seamless integration to maintain a competitive edge.
By Organization Size
Large enterprises represent the largest portion as they manage complex, multi-region cloud setups with strict compliance and performance standards. Their size increases cost exposure and governance risks. Brokerage providers should focus on advanced orchestration, compliance automation, and executive-level cost reporting to meet enterprise needs.
By Vertical
BFSI continues to lead due to strict regulations, high transaction volumes, and the expectation of zero downtime. To meet compliance standards, financial institutions need centralized tracking of compliance, enforcement of SLAs, and transparency in costs across their cloud infrastructures. As a result, they focus on audit-ready reporting, robust security integration, and resilient orchestration across multicloud environments.
REGION
Asia Pacific to be fastest-growing region during forecast period
Asia Pacific is expected to witness the fastest growth in the cloud services brokerage market as China, India, Japan, South Korea, and Southeast Asian nations rapidly adopt cloud technology. Digital transformation initiatives are currently strong, with global cloud service providers investing heavily, and significant growth in Fintech, Telecom, and other verticals fueling demand for integrated multicloud management solutions and cost optimization platforms in the region. Recent implementation of stricter data governance regulations in these countries has also increased demand for cloud service brokerage solutions across Asia Pacific.
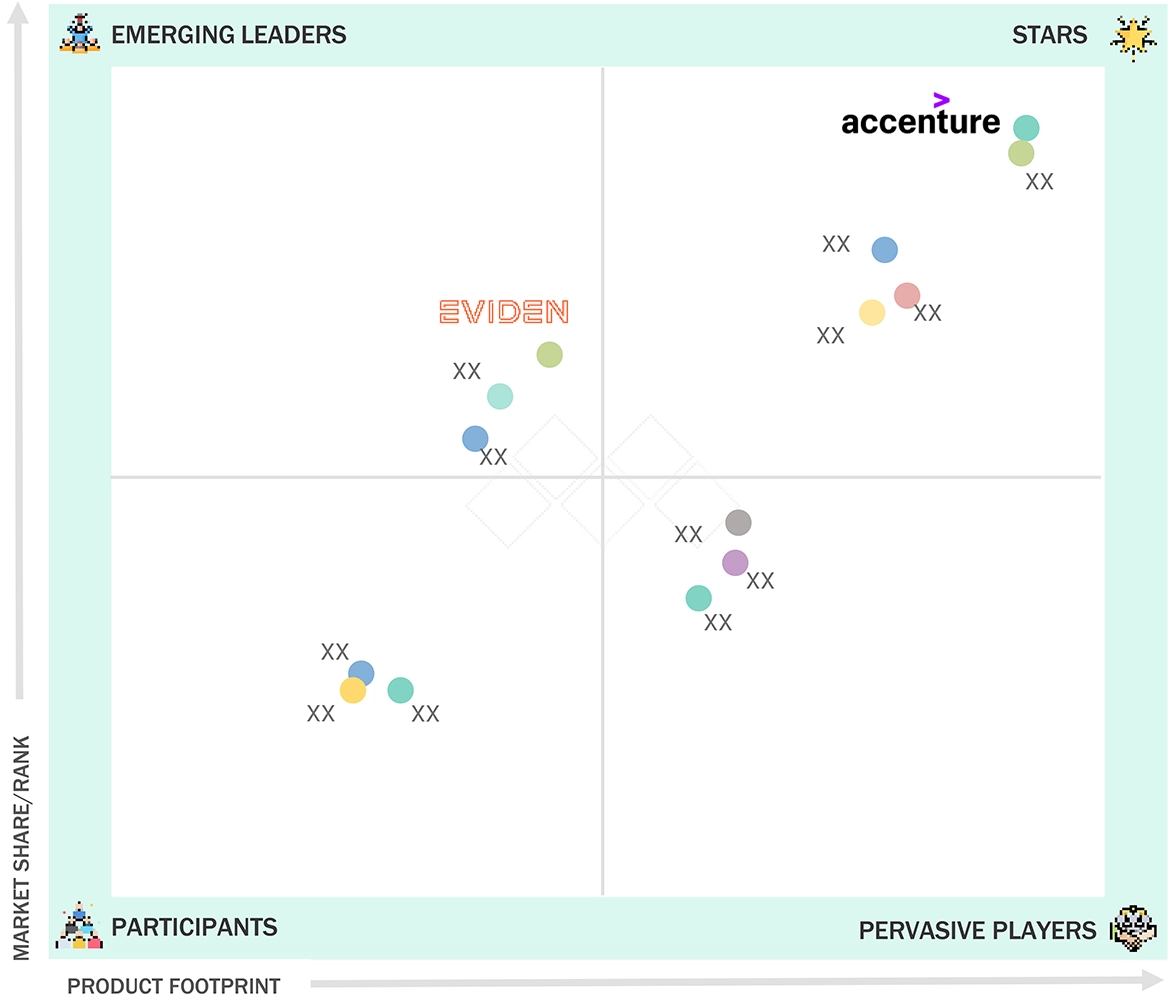
CLOUD SERVICES BROKERAGE MARKET OVERVIEW AND FUTURE OUTLOOK: COMPANY EVALUATION MATRIX
Accenture is positioned in the Stars quadrant due to its strong global service strategy and presence. It has received high scores for the capabilities of its vendor services and products. Meanwhile, Eviden is still expanding as it develops new capabilities and is therefore ranked as an Emerging Leader in the evaluation matrix.
Source: Secondary Research, Interviews with Experts, MarketsandMarkets Analysis
KEY MARKET PLAYERS
- Accenture (Ireland)
- IBM (US)
- Broadcom (US)
- Arrow Electronics (US)
- Fujitsu (Japan)
- DXC Technology (US)
- Wipro (India)
- Eviden (France)
- AWS (US)
- Infosys (India)
- NTT Data (Japan)
- TCS (India)
- Tech Mahindra (India)
- BMC Software (US)
- Flexera (US)
- Jamcracker (US)
- Cloudmore (Finland)
- ESHGro (US)
- OpenText (Canada)
- InContinuum (Netherlands)
- CompuNet (US)
- Shivami (India)
- Bittium (Finland)
- Capgemini (France)
- Oracle (US)
- CIGNEX (US)
- ActivePlatform (Belarus)
- CloudFX (US)
- CloudBolt (US)
- Cloudsme (Netherlands)
- AppDirect (US)
- Morpheus Data (US)
- Interworks Cloud (Greece)
- RackNap (US)
- Spot (US)
- CloudBroker (Switzerland)
MARKET SCOPE
| REPORT METRIC | DETAILS |
|---|---|
| Market Size in 2025 (Value) | USD 13.25 BN |
| Market Forecast in 2031 (Value) | USD 36.52 BN |
| Growth Rate | CAGR of 18.9% from 2026 to 2031 |
| Years Considered | 2020–2031 |
| Base Year | 2025 |
| Forecast Period | 2026–2031 |
| Units Considered | Value (USD MN/BN) |
| Report Coverage | Revenue forecast, company ranking, competitive landscape, growth factors, and trends |
| Segments Covered |
|
| Regions Covered | North America, Europe, Asia Pacific, Middle East & Africa, Latin America |
WHAT IS IN IT FOR YOU: CLOUD SERVICES BROKERAGE MARKET OVERVIEW AND FUTURE OUTLOOK REPORT CONTENT GUIDE
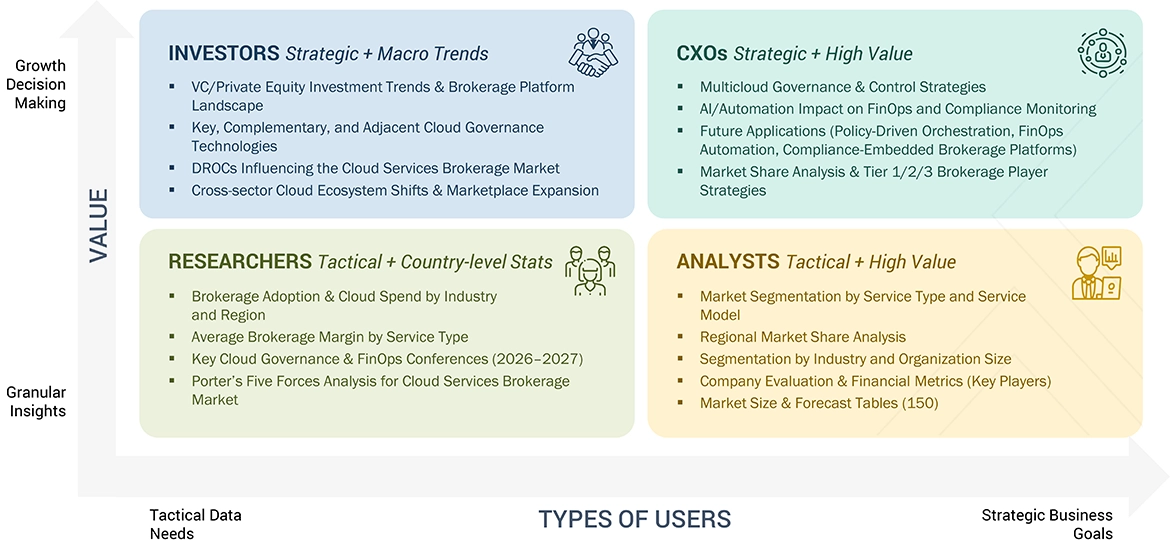
DELIVERED CUSTOMIZATIONS
We have successfully delivered the following deep-dive customizations:
| CLIENT REQUEST | CUSTOMIZATION DELIVERED | VALUE ADDS |
|---|---|---|
| Enterprise (BFSI) | Competitive benchmarking of cloud services brokerage vendors, pricing comparison, service capability analysis, and adoption trends specific to BFSI cloud environments. | Support strategic vendor selection and strengthen multicloud governance and cost optimization strategy. |
| Telecom Operator | Vendor landscape analysis focused on telecom-grade brokerage capabilities, workload orchestration, and deployment models. | Enable structured investment decisions for network cloud and edge orchestration. |
| Cloud Service Provider | Market sizing, segment analysis, and demand outlook for cloud services brokerage solutions across hybrid and multicloud environments. | Identify growth opportunities and refine platform positioning strategy. |
RECENT DEVELOPMENTS
- December 2025 : IBM agreed to acquire Confluent for USD 11 billion in order to enhance hybrid-cloud integration and real-time data streaming capabilities for enterprise AI. This will also improve data connectivity, governance, and automation across multicloud environments in support of brokerage-driven integration, orchestration, and cross-platform service delivery.
- December 2025 : AWS and Google Cloud have launched a private multicloud networking service that combines AWS Interconnect and Google Cross-Cloud Interconnect. It allows for fast, secure, and low-latency connections between different clouds, offering greater multicloud workload portability and improved data transfer between clouds, thereby assisting cloud brokers in supporting multi-provider architectures that have been developed.
- November 2025 : The acquisition of Cloud4C by Capgemini was completed to offer an expanded suite of automation-driven managed services. This acquisition will provide hyper-automation and AI-ops capabilities that enhance cloud management, migration, and continuity, as well as increase compliance services in alignment with existing core Cloud Services Brokerage functions.
Related Ecosystem
Cloud Computing
Software And Services
Communication And Connectivity Technology
Key Takeaways
- Canada's cloud services brokerage market is valued at $462.1 million in 2024 and is projected to grow to $1,110.6 million by 2029, representing a 19.2% CAGR.
- Canada's growth rate of 19.2% exceeds the global average of 18%, positioning the country as a high-growth market within the cloud services brokerage sector.
- Canadian enterprises across financial services, healthcare, and technology are driving demand for cloud brokerage solutions to optimize multi-cloud environments and reduce vendor costs.
- The forecast period (2024–2029) will see Canada's market more than double in size, reflecting accelerating digital transformation and cloud governance priorities among Canadian organizations.
Cloud Services Brokerage Market Report Scope
| Report Metric | Details |
|---|---|
| Base Year | 2024 |
| Fastest Growing Segment | EXTERNAL ENABLEMENT (Platform) |
| Forecast Period | 2024–2029 |
| Growth Rate | CAGR of 18% from 2024 to 2029 |
| Largest Segment | PUBLIC CLOUD (Deployment Model) |
| Market Size Base Year (Billions) | ~USD 11.45 (2024) |
| Revenue Forecast (Billions) | ~USD 26.2 (2029) |
| Segments Covered | Service Type, Cloud Service Model, Organization Size, Vertical, Service Model, Deployment Model, Platform, Application |
Canada Cloud Services Brokerage Market Report Segmentation
8 segment dimensions are covered across the global market.
By Service Type
- Aggregation
- Cloud Automation
- Data Security And Risk Management
- Migration And Integration
- Monitoring And Access Management
- Reporting And Analytics
- Service Arbitrage
- Service Intermediation
- Support And Maintenance
- Training And Consulting
By Cloud Service Model
- IaaS
- PaaS
- SaaS
By Organization Size
- Large Enterprises
- Medium Enterprises
- Small Enterprises
- Smes
By Vertical
- Bfsi
- Energy & Utilities
- Government & Public Sector
- Government And Public Sector
- Healthcare & Life Sciences
- Healthcare And Life Sciences
- It & Ites
- Manufacturing
- Media & Entertainment
- Media And Entertainment
- Other Verticals
- Retail & Consumer Goods
- Retail And Consumer Goods
- Telecommunications
- Telecommunications And Ites
- Travel And Hospitality
By Service Model
- IaaS
- PaaS
- SaaS
By Deployment Model
- Hybrid Cloud
- Private Cloud
- Public Cloud
By Platform
- External Enablement
- Internal Enablement
By Application
- Compliance Management
- Identity And Policy Management
- Infrastructure And Resource Management
- Lifecycle Management
- Metering And Billing
- Provisioning
Target Audience
- Cloud Services Brokers & Resellers : Evaluate market opportunity in Canada, understand growth potential, and develop localized strategies to capture share in this rapidly expanding $1.1B market by 2029.
- Enterprise IT & Cloud Leaders : Benchmark cloud spending strategies against market trends, validate multi-cloud adoption decisions, and identify best practices for vendor management and cost optimization specific to Canadian enterprises.
- Technology Solution Providers : Assess market demand for cloud management tools and services in Canada, identify partnership opportunities with brokers, and develop complementary offerings aligned with regional growth drivers.
- Investment & Private Equity Firms : Evaluate acquisition targets and investment opportunities in Canada's high-growth cloud services brokerage sector, with detailed market sizing and competitive landscape analysis through 2029.
- Management Consultants & Advisors : Support client engagements with authoritative Canadian market data, growth forecasts, and industry insights to guide cloud strategy, vendor selection, and digital transformation initiatives.
Key Companies in the Canada Cloud Services Brokerage Market
| Company | HQ | Ownership | Strongest segments |
|---|---|---|---|
| SIFY TECHNOLOGIES LIMITED | India | Public Company | Network-centric services,Data center services,Digital services, |
| DIMENSION DATA | United Kingdom | Private Company | Managed & outsourcing services (incl. data centers, networking, security),Cloud & ITaaS (incl. OneCloud, Microsoft cloud, contact center-as-a-service),Systems integration, consulting & professional services, |
| HOYA CORPORATION | Japan | Public Company | Eyeglasses and ophthalmic lenses,Contact lenses and Eyecity retail,Intraocular lenses and surgical ophthalmology, |
| PERSISTENT SYSTEMS | India | Public Company | BFSI services and platforms,Healthcare & Life Sciences solutions,Technology Companies & Software/Hi-Tech, |
| AVAYA INC | United States | Private Company | Contact Center platforms and OneCloud CCaaS,Unified Communications and OneCloud UCaaS,Services (support, managed, professional), |
| F5 NETWORKS | United States | Public Company | BIG-IP Systems & Packaged Software,NGINX (Plus, One Console, Ingress, WAF for NGINX),Distributed Cloud & SaaS Security Services, |
| HCL TECHNOLOGIES LIMITED | India | Public Company | IT and Business Services,Engineering and R&D Services,HCL Software and IP-led Offerings, |
| SHAW COMMUNICATIONS INC | Canada | Private Company | Consumer Internet and WiFi,Video (cable and satellite),Wireless (Freedom Mobile and Shaw Mobile), |
| SYNTEL | United States | Private Company | Application & Infrastructure Management,Legacy Modernization & Cloud Migration,Digital Engineering, Microservices & DevOps, |
| TELIA COMPANY | Sweden | Public Company | Consumer mobile services,Fixed broadband & TV (consumer),Enterprise networking, cloud & security, |
| NEW RELIC, INC. | United States | Private Company | Application Performance Monitoring (APM),Infrastructure & Kubernetes Monitoring,Log Management & Telemetry Analytics, |
| SAGE SOFTWARE | United States | Private Company | Sage Intacct (cloud financial management),Sage Business Cloud Accounting (SMB cloud accounting),Sage Business Cloud X3 and mid-market ERP, |
| GETRONICS | Netherlands | Private Company | Digital workplace and service desk (incl. field/onsite),Cloud services and multicloud strategy,Cybersecurity and managed security services, |
| ACCENTURE | Ireland | Public Company | Strategy & Consulting / Industry X / Song,Technology (cloud, data, AI, software engineering, security),Operations & BPO (including platform trust and safety), |
| IBM | United States | Public Company | Software (Hybrid Cloud and AI Platforms),Consulting (Strategy, Technology, and Managed Services),Infrastructure (Servers, Storage, Hybrid Cloud Infrastructure Services), |
| BROADCOM | United States | Public Company | Networking connectivity (Ethernet switching, routing, NICs, PHYs, optics),Wireless device connectivity (RF, connectivity ICs, touch controllers, charging ASICs),Servers and storage (PCIe switches, SAS/RAID, Fibre Channel, HDD/SSD solutions), |
| ARROW ELECTRONICS | United States | Public Company | Semiconductor products and related services,Interconnect, passive, and electromechanical (IP&E) products,Computing and memory products, |
| FUJITSU | Japan | Public Company | Service Solutions (consulting, cloud, SI, BPO, managed services),Hardware Solutions (computer platforms, network equipment),Ubiquitous Solutions (devices and edge-centric offerings), |
| DXC TECHNOLOGY | United States | Public Company | Global Infrastructure Services,Consulting & Engineering Services,Insurance Software & Services, |
| WIPRO | India | Public Company | Application Services & Digital Engineering,Cloud & Infrastructure Services,Business Process Services (BPS), |
| INFOSYS | India | Public Company | Digital & Cloud (Infosys Cobalt, experience, digital workplace, commerce),AI, Analytics & Automation (Infosys Topaz, applied & generative AI, automation),Core Application Services (ADM, modernization, agile DevOps, integration), |
| NTT DATA | Japan | Private Company | Application and Cloud Services,IT Modernization and Managed Services,Consulting and Industry Solutions, |
| TCS | India | Public Company | BFSI platforms and services (TCS BaNCS, TCS BFSI Platforms, Quartz, BFSI consulting),Enterprise transformation and cloud (TCS ERP on Cloud, enterprise solutions, consulting, network services),AI, data, analytics, and cognitive automation (AI services, ignio, MasterCraft, AI WisdomNext, Customer Intelligence & Insights), |
| TECH MAHINDRA | India | Public Company | Application, Cloud, and Digital Enterprise Services,Engineering, Network, and Testing Services,AI, Automation, and Analytics Platforms, |
| BMC SOFTWARE | United States | Private Company | Enterprise Service Management (ITSM/ITOM/ITAM),Mainframe Service Management (MSM),Control-M Workload Automation, |
SIFY TECHNOLOGIES LIMITED
Sify Technologies Limited is an Indian public company founded in 1995 with 1,047 employees, providing technology and IT services.
DIMENSION DATA
Dimension Data is a private technology services company established in 1983 in the United Kingdom, employing 11,032 people.
HOYA CORPORATION
Hoya Corporation is a Japanese public company founded in 1941 with 37,752 employees, operating across multiple technology and manufacturing sectors.
PERSISTENT SYSTEMS
Persistent Systems is an Indian public company founded in 1990 with 22,205 employees, providing IT and software services.
AVAYA INC
Avaya Inc is a private technology company based in the United States, founded in 2007 with 7,090 employees.
F5 NETWORKS
F5 Networks is a United States-based public company founded in 1996 with 6,545 employees, specializing in application delivery and security solutions.
HCL TECHNOLOGIES LIMITED
HCL Technologies Limited is an Indian public company founded in 1976, providing IT services and solutions globally.
SHAW COMMUNICATIONS INC
Shaw Communications Inc is a Canadian private company founded in 1966 with 9,300 employees, operating in the communications sector.
SYNTEL
Syntel is a private technology services company based in the United States, founded in 1980 with 22,114 employees.
TELIA COMPANY
Telia Company is a Swedish public company founded in 1853 with 14,552 employees, operating in the telecommunications industry.
NEW RELIC, INC.
New Relic, Inc is a private software company based in the United States, founded in 2007 with 2,383 employees.
SAGE SOFTWARE
Sage Software is a private software company based in the United States, founded in 1982 with 500 employees.
GETRONICS
Getronics is a private technology services company based in the Netherlands, founded in 1887 with 23,915 employees.
ACCENTURE
Accenture is an Irish public company founded in 1951 with 799,000 employees, providing global consulting, technology, and outsourcing services.
IBM
IBM is a United States-based public company founded in 1911 with 264,300 employees, operating as a global technology and consulting leader.
BROADCOM
Broadcom is a United States-based public company founded in 1961 with 33,000 employees, specializing in semiconductor and infrastructure software solutions.
ARROW ELECTRONICS
Arrow Electronics is a United States-based public company founded in 1935 with 22,230 employees, operating as a distributor of electronic components and services.
FUJITSU
Fujitsu is a Japanese public company founded in 1935 with 99,203 employees, providing IT services, solutions, and products globally.
DXC TECHNOLOGY
DXC Technology is a United States-based public company founded in 1959 with 115,000 employees, offering IT services and digital transformation solutions.
WIPRO
Wipro is an Indian public company founded in 1945 with 240,000 employees, providing IT services, consulting, and business process outsourcing.
INFOSYS
Infosys is an Indian public company founded in 1981 with 328,594 employees, providing IT services, consulting, and business solutions globally.
NTT DATA
NTT Data is a Japanese private company founded in 1988 with 197,777 employees, offering IT services and digital solutions worldwide.
TCS
TCS is an Indian public company founded in 1968 with 584,519 employees, providing IT services, consulting, and business solutions on a global scale.
TECH MAHINDRA
Tech Mahindra is an Indian public company founded in 1986 with 119,337 employees, delivering IT services and digital transformation solutions.
BMC SOFTWARE
BMC Software is a private software company based in the United States, founded in 1980 with 6,700 employees.
Reasons to Buy this Report
- Market Size & Growth Validation : Confirm the substantial $462.1M market size in 2024 and validate investment decisions with precise forecasts showing 140% growth to $1,110.6M by 2029, supporting strategic planning for Canadian operations.
- Competitive Positioning Intelligence : Understand Canada's 19.2% CAGR advantage over global trends to identify market opportunities, assess competitive dynamics, and benchmark performance against regional growth patterns specific to Canadian enterprises.
- Multi-Cloud Adoption Insights : Gain detailed understanding of Canadian organizations' multi-cloud strategy adoption patterns, vendor management priorities, and cloud spending optimization needs to tailor solutions and messaging for this market.
- Investment & Expansion Planning : Make informed decisions about market entry, resource allocation, and product development for Canada by leveraging comprehensive market data, growth projections, and regional demand drivers through 2029.
- Customer Segmentation & Targeting : Identify high-value customer segments within Canada's enterprise landscape seeking cloud cost optimization and vendor management solutions, enabling precise go-to-market strategies and sales prioritization.
Frequently asked questions
What is the current size of Canada's cloud services brokerage market?
Canada's cloud services brokerage market was valued at $462.1 million in 2024 and is expected to reach $1,110.6 million by 2029.
What is the projected growth rate for Canada's cloud services brokerage market?
Canada's cloud services brokerage market is projected to grow at a compound annual growth rate (CAGR) of 19.2% from 2024 to 2029.
How does Canada's market growth compare to global trends?
Canada's 19.2% CAGR exceeds the global average of 18%, indicating that Canada is a faster-growing market for cloud services brokerage solutions.
Which industries in Canada are driving cloud services brokerage adoption?
Financial services, healthcare, and technology sectors in Canada are primary drivers of cloud services brokerage adoption, seeking to optimize multi-cloud environments and manage vendor relationships.
What factors are contributing to Canada's cloud services brokerage market growth?
Key factors include rising multi-cloud adoption, increasing need for cost optimization, regulatory compliance requirements, strong digital infrastructure, and growing demand for cloud governance solutions among Canadian enterprises.
RESEARCH METHODOLOGY
Get the Full Cloud Services Brokerage Market Report
Full forecast, segment splits, and company analysis for all Cloud Services Brokerage Market.
- US Cloud Services Brokerage Market
- UK Cloud Services Brokerage Market
- Germany Cloud Services Brokerage Market
- France Cloud Services Brokerage Market
- Italy Cloud Services Brokerage Market
- China Cloud Services Brokerage Market
- Japan Cloud Services Brokerage Market
- India Cloud Services Brokerage Market
- Brazil Cloud Services Brokerage Market
- Mexico Cloud Services Brokerage Market
- South Africa Cloud Services Brokerage Market
- Rest Of Europe Cloud Services Brokerage Market
- Rest Of Asia Pacific Cloud Services Brokerage Market
Need a Tailored Report?
Customize this report to your needs
Get 10% FREE Customization
Customize This Report
