France Data Center Power Market (2025-2030)

The France Data Center Power Market was valued at $911.4 Million in 2025 and projected to reach to $1210 Million by 2030, representing a compound annual growth rate of 5.8%. France's data center power market is poised for steady expansion through 2030, driven by digital transformation initiatives and the proliferation of cloud-native applications across public and private sectors.


| Market Size in | USD 26.32 MN |
| Market Forecast in | |
| CAGR | |
| Forecast Period | |
| Units Considered | Value (USD MN) |
France Data Center Power Market Trends and Insights
- This growth trajectory reflects France's strategic position as a digital hub in Europe, driven by increasing cloud adoption, AI infrastructure expansion, and regulatory emphasis on energy efficiency.
- France's data center sector benefits from competitive electricity costs and a commitment to renewable energy integration, positioning the country as an attractive destination for hyperscale and enterprise data center investments. The French market's moderate growth rate compared to global averages underscores the maturity of France's data center infrastructure and the country's focus on sustainable power solutions.
- Between 2025 and 2030, France is expected to see heightened demand for advanced cooling technologies, backup power systems, and grid modernization to support next-generation workloads.
- France's regulatory framework, including the EU's Digital Decade initiative and carbon neutrality targets, continues to shape investment priorities in efficient power distribution and renewable energy integration within data centers..
Key Market Statistics
- CAGR (2025-2030) 5.8% CAGR
- Market Size, 2025 ~USD 911.4 Million
- Forecast, 2030 ~USD 1210 Million
- Country France
France Data Center Power Market Overview
Market Size & Growth :
France's data center power market is valued at USD 911.4 million in 2025, with projected growth to USD 1,210.0 million by 2030, representing a steady 5.8% CAGR, outpacing broader European averages in infrastructure modernization.
Cloud & AI Expansion :
Accelerating cloud adoption and AI infrastructure investments across French enterprises are driving demand for reliable, scalable power solutions in data centers, positioning France as a critical digital hub for European operations.
Energy Efficiency Regulations :
France's stringent regulatory framework emphasizing sustainable energy practices and carbon reduction mandates is reshaping data center power requirements, favoring efficient cooling systems and renewable energy integration.
Strategic European Position :
As a leading digital economy in Europe, France attracts multinational tech companies and hyperscalers seeking reliable power infrastructure, creating sustained demand for advanced data center power management solutions.
France Data Center Power Market Dynamics
- The country's commitment to energy efficiency standards and renewable energy adoption will shape infrastructure investments, with enterprises prioritizing sustainable power solutions.
- Hyperscaler expansion and edge computing deployments will further accelerate demand for specialized power systems.
- However, growth remains moderate compared to global markets, reflecting France's mature digital infrastructure and competitive landscape.
- Strategic investments in grid modernization and power redundancy will be critical for supporting France's ambitions as a European tech leader..
Market Ecosystem
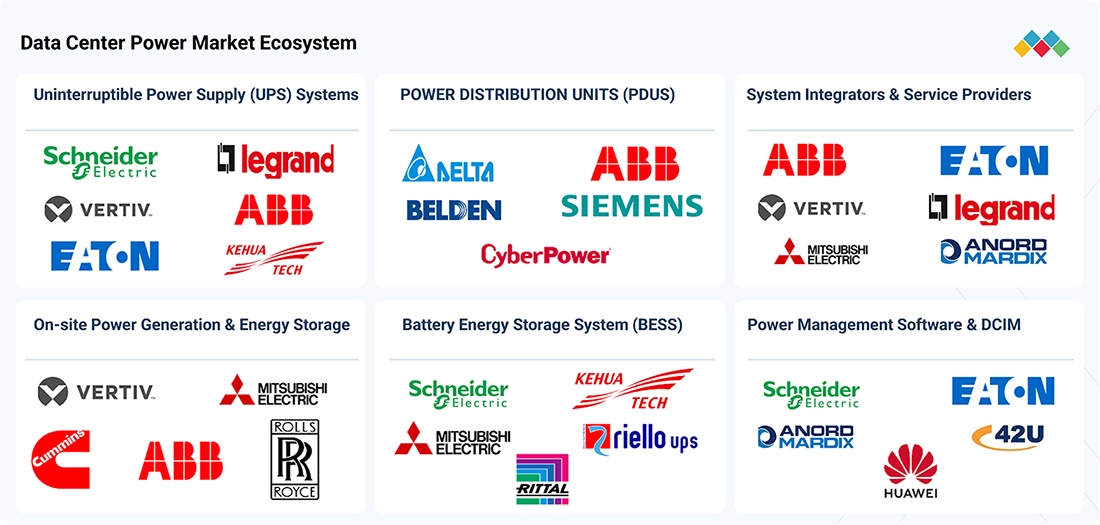
DATA CENTER POWER MARKET: COMMERCIAL USE CASES ACROSS INDUSTRIES
| COMPANY | USE CASE DESCRIPTION | BENEFITS |
|---|---|---|
 |
Ficolo, a Finnish colocation provider, deployed ABB's DPA UPS system at its underground data center in Ulvila, Finland. The facility needed a scalable, reliable power backup solution to meet rising electricity demand while maintaining operational continuity. ABB provided a modular UPS system featuring double-conversion technology and hot-swappable modules to support capacity expansion and simplify maintenance. | Enabled seamless expansion to accommodate increasing power requirements. Improved energy efficiency and reduced operational costs. Hot-swappable modules minimized downtime and kept data center operations uninterrupted. |
 |
Converge ICT Solutions, a Philippine broadband and telecommunications provider, deployed Huawei's SmartLi UPS solution to support its expansion into the internet data center market. Limited power distribution space and the need for 2N redundancy presented infrastructure challenges. Huawei provided a modular UPS system integrated with lithium-ion batteries to deliver reliable backup power within a compact footprint. | Reduced the power infrastructure's physical footprint by 70%. Lithium-ion batteries offered a longer operating lifespan and reduced replacement requirements. Modular architecture enabled hot-swapping and online capacity expansion, simplifying maintenance and reducing capital expenditure. |
 |
LCL Data Centers, a Belgian data center operator, deployed a 13.5 MVA standby power generation system powered entirely by hydrotreated vegetable oil (HVO100). The company required a reliable backup power solution that aligned with its carbon neutrality commitments while maintaining generator performance and responsiveness. Caterpillar's dealer, Eneria, supplied the HVO100-powered standby system to provide reliable backup power and reduce lifecycle greenhouse gas emissions. | Enabled standby power generation using 100% renewable HVO100 fuel. Reduced lifecycle greenhouse gas emissions by up to 40% compared with conventional diesel. Maintained reliable generator performance and responsiveness. Supported LCL's objective of achieving carbon neutrality by 2030. |
 |
NGN's Star of Bosphorus data center in Istanbul, Türkiye, needed a reliable, space-efficient power distribution infrastructure to meet tier III availability requirements. Hitachi Energy supplied its System pro E power main distribution switchboard, Emax 2 and Tmax XT circuit breakers, ArTu L enclosures, and control products. The integrated solution enabled rapid installation while meeting space constraints and operational reliability requirements. | Supported tier III reliability and maintenance without disrupting IT operations. Optimized available facility space through compact power distribution infrastructure. Enabled installation and completion of the power infrastructure within four months. Provided technical support for system design, product selection, and implementation. |
Logos and trademarks shown above are the property of their respective owners. Their use here is for informational and illustrative purposes only.
Related Ecosystem
Data Centre And Networking
- Software-Defined Networking (SDN)
- Mid-Sized Data Centers
- Small Data Centers
- Remote Monitoring
- Smart Healthcare
- Cisco Systems, Inc.
- HUAWEI TECHNOLOGIES CO LTD
- Hewlett Packard Enterprise Company
- MITSUBISHI ELECTRIC INFORMATION SYSTEMS CORPORATION
- MITSUBISHI ELECTRIC INFORMATION NETWORK CORPORATION
Key Takeaways
- France's data center power market will grow from USD 911.4M (2025) to USD 1,210.0M (2030) at a 5.8% CAGR.
- France's mature infrastructure and renewable energy focus differentiate it from faster-growing European markets.
- Regulatory compliance with EU carbon neutrality targets is driving France's investment in efficient power technologies.
- France's competitive electricity pricing and grid stability make it a preferred location for European data center operators.
Data Center Power Market Report Scope
| Report Metric | Details |
|---|---|
| Base Year | 2025 |
| Fastest Growing Segment | PORTABLE SKID-MOUNTED SYSTEMS (Type) |
| Forecast Period | 2025–2030 |
| Growth Rate | CAGR of 7.5% from 2025 to 2030 |
| Largest Segment | ELECTRICAL SOLUTIONS (Component) |
| Market Size Base Year (Billions) | ~USD 35.18 (2025) |
| Revenue Forecast (Billions) | ~USD 50.51 (2030) |
| Segments Covered | Component, Electrical Solution, Service, Tier Type, Data Center Size, Data Center Type, Enterprise Vertical, Type |
France Data Center Power Market Report Segmentation
8 segment dimensions are covered across the global market.
By Component
- Electrical Solutions
- Infrastructure
- Services
- Software
- Solutions
By Electrical Solution
- On-Site Power Generation & Energy Storage
- Other Electrical Solutions
- Power Distribution Unit
- Power Distribution Unit (Pdu)
- Power Management Software & Dcim
- Uninterrupted Power Supply (Ups)
- Uninterruptible Power Supply (Ups) Systems
By Service
- Design And Consulting
- Integration And Deployment
- Support And Maintenance
By Tier Type
- Tier I & Ii
- Tier Iii
- Tier Iv
By Data Center Size
- Large Data Center (5 Mw To 10 Mw)
- Large Data Centers
- Large Data Centers (5 Mw To 10 Mw)
- Massive Data Center (Over 100 Mw)
- Massive Data Centers (Over 100 Mw)
- Medium Data Centers
- Mega-Sized Data Center (10 Mw To 100 Mw)
- Mega-Sized Data Centers (10 Mw To 100 Mw)
- Mid-Sized Data Center (1 Mw To 5 Mw)
- Mid-Sized Data Centers (1 Mw To 5 Mw)
- Small Data Centers
- Small-Sized Data Center (Less Than 1 Mw)
- Small-Sized Data Centers (Less Than 1 Mw)
By Data Center Type
- Cloud/Hyperscale Data Centers
- Colocation Data Centers
- Enterprises
By Enterprise Vertical
- Bfsi
- Government & Public Sector
- Healthcare & Life Sciences
- Manufacturing
- Other Enterprise Verticals
- Other Verticals
- Retail & E-Commerce
- Technology & Software
- Telecommunications
By Type
- Fixed Skid-Mounted Systems
- Portable Skid-Mounted Systems
Target Audience
- Data Center Operators & Facility Managers : Need France-specific power market data to optimize infrastructure investments, plan capacity expansions, and align operations with evolving energy efficiency regulations and sustainability mandates.
- Power Solutions & Equipment Vendors : Require detailed market insights on France's demand for UPS systems, cooling solutions, and power distribution equipment to develop localized product strategies and identify key customer segments.
- Cloud & Hyperscaler Companies : Seek France market intelligence to guide data center site selection, power infrastructure planning, and investment decisions aligned with regional growth trends and regulatory requirements.
- Energy & Sustainability Consultants : Need comprehensive France market data to advise clients on renewable energy integration, power efficiency optimization, and compliance with French environmental regulations in data center operations.
- Investment & Private Equity Firms : Require France-specific market forecasts and opportunity analysis to evaluate investment potential in data center infrastructure, power solutions, and related technology companies in this growing market.
Key Companies in the France Data Center Power Market
| Company | HQ | Ownership | Strongest segments |
|---|---|---|---|
| SIFY TECHNOLOGIES LIMITED | India | Public Company | UPS,Power Distribution Unit (PDU),Generators & Energy Storage, |
| BHARTI AIRTEL LIMITED | India | Public Company | UPS,Power Distribution Unit,Generators & Energy Storage, |
| TELIA COMPANY | Sweden | ||
| PENTAIR PLC | United Kingdom | Public Company | Flow segment – data center cooling and process pumps,Water Solutions – treatment, filtration, and reuse for facilities,Pool segment – repurposed circulation and filtration technologies, |
| LENOVO | China | Public Company | UPS,Power Distribution Unit (PDU),Generators & Energy Storage, |
| ZENSAR TECHNOLOGIES LTD | India | Public Company | Cloud Infrastructure and Hybrid DC Services (including power-aware design and operations),Application Modernization and Digital Platforms impacting DC footprint,Security and Enterprise System Management for DC estates, |
| NUTANIX INC | United States | Public Company | Nutanix Cloud Infrastructure (AOS, AHV, data services),Nutanix Cloud Manager, Prism, and DC operations tooling,Unified Storage (Files, Objects, Volumes), |
| TELECOM EGYPT | Egypt | Public Company | UPS,Power Distribution Unit,Generators & Energy Storage, |
| SCHNEIDER ELECTRIC | Canada | Public Company | UPS,Power Distribution Units,Generators & Energy Storage, |
| ABB | Switzerland | Public Company | UPS,Power Distribution Units and Switchgear,Generators & Energy Storage Integration, |
| EATON | Ireland | Public Company | UPS,Power Distribution Unit,Generators & Energy Storage, |
| DELTA ELECTRONICS | Taiwan | Public Company | UPS,Power Distribution Units (PDU),Generators & Energy Storage, |
| VERTIV | United States | Public Company | UPS,Power Distribution Units,Generators & Energy Storage, |
| LEGRAND | France | Public Company | UPS,Power Distribution Unit (PDU),Generators & Energy Storage, |
| TOSHIBA | Japan | Private Company | UPS,Power Distribution Units (including switchgear and distribution systems),Generators & Energy Storage, |
| SIEMENS | Germany | Public Company | UPS,Power Distribution Unit,Generators & Energy Storage, |
| MITSUBISHI ELECTRIC | Japan | Public Company | UPS,Power Distribution Unit,Generators & Energy Storage, |
| CYBER POWER SYSTEM | Taiwan | Public Company | UPS,Power Distribution Units,Generators & Energy Storage, |
SIFY TECHNOLOGIES LIMITED
SIFY TECHNOLOGIES LIMITED is a public company established in India in 1995 with 1,047 employees.
BHARTI AIRTEL LIMITED
BHARTI AIRTEL LIMITED is a public telecommunications company established in India in 1995 with 28,730 employees.
TELIA COMPANY
TELIA COMPANY is a telecommunications company based in Sweden.
PENTAIR PLC
PENTAIR PLC is a public company founded in 1966 in the United Kingdom with 9,000 employees.
LENOVO
LENOVO is a public technology company founded in 1984 in China.
ZENSAR TECHNOLOGIES LTD
ZENSAR TECHNOLOGIES LTD is a public Indian IT services company founded in 1963 with 10,066 employees.
NUTANIX INC
NUTANIX INC is a public cloud computing company founded in 2009 in the United States with 7,800 employees.
TELECOM EGYPT
TELECOM EGYPT is a public telecommunications company founded in 1854 in Egypt.
SCHNEIDER ELECTRIC
SCHNEIDER ELECTRIC is a public industrial automation and energy management company founded in 1836 in Canada with 158,122 employees.
ABB
ABB is a public multinational technology company founded in 1883 in Switzerland with 111,900 employees.
EATON
EATON is a public diversified industrial company founded in 1911 in Ireland with 97,303 employees.
DELTA ELECTRONICS
DELTA ELECTRONICS is a public electronics manufacturer founded in 1971 in Taiwan with 85,684 employees.
VERTIV
VERTIV is a public infrastructure technology company headquartered in the United States with 34,000 employees.
LEGRAND
LEGRAND is a public electrical and digital building infrastructure company founded in 1865 in France with 35,410 employees.
TOSHIBA
TOSHIBA is a private Japanese conglomerate founded in 1875 with 106,648 employees.
SIEMENS
SIEMENS is a public German multinational conglomerate founded in 1847 with 310,312 employees.
MITSUBISHI ELECTRIC
MITSUBISHI ELECTRIC is a public Japanese electronics and electrical equipment manufacturer founded in 1921 with 150,386 employees.
CYBER POWER SYSTEM
CYBER POWER SYSTEM is a public Taiwanese company founded in 1997 with 1,760 employees.
Reasons to Buy this Report
- Localized Market Intelligence : Gain France-specific insights on market size, growth trajectories, and competitive dynamics unavailable in global reports, enabling precise strategic planning for French market entry or expansion.
- Regulatory & Compliance Guidance : Understand France's unique energy efficiency mandates and sustainability requirements shaping data center power procurement, ensuring compliance and competitive advantage in infrastructure investments.
- Investment Decision Support : Access detailed forecasts and market segmentation for France to identify high-growth opportunities in power solutions, cooling systems, and renewable energy integration for data centers.
- Competitive Positioning : Benchmark your offerings against France's market landscape, identify key customer segments, and develop targeted go-to-market strategies for data center power solutions in this strategic European market.
- Risk Mitigation & Opportunity Mapping : Evaluate France-specific market risks, regulatory changes, and emerging opportunities in AI infrastructure and hyperscaler expansion to optimize resource allocation and minimize investment risk.
Frequently asked questions
What is the current size of France's data center power market?
France's data center power market is valued at USD 911.4 million in 2025, with expectations to reach USD 1,210.0 million by 2030.
What is the projected growth rate for France's data center power market?
France's data center power market is expected to grow at a compound annual growth rate (CAGR) of 5.8% between 2025 and 2030.
What factors are driving growth in France's data center power market?
Key drivers include increased cloud adoption, AI infrastructure expansion, EU regulatory requirements for energy efficiency, and France's commitment to renewable energy integration in data centers.
How does France's data center power market compare to global trends?
France's 5.8% CAGR is lower than the global average of 7.5%, reflecting the maturity of France's infrastructure and its focus on sustainable, regulated growth aligned with EU directives.
What role does renewable energy play in France's data center power market?
France's abundant hydroelectric and nuclear power resources, combined with EU carbon neutrality targets, position renewable energy as a critical competitive advantage and investment driver for data center operators.
RESEARCH METHODOLOGY
This research study used extensive secondary sources, directories, and databases, such as D&B Hoovers, Bloomberg Businessweek, and Factiva, to identify and collect information for a technical, market-oriented, and commercial study of the global data center power market. A few other market-related reports and analyses published by various industry associations, such as the National Security Agency (NSA) and SC Magazine, were considered while doing the extensive secondary research. Primary sources were mainly industry experts from core and related industries, as well as preferred suppliers, manufacturers, distributors, service providers, technology developers, and technologists from companies and organizations across all segments of this industry's value chain.
In-depth interviews were conducted with primary respondents, including key industry participants, subject-matter experts, C-level executives of key market players, and industry consultants to obtain and verify critical qualitative and quantitative information and assess the prospects. The market size was estimated by analyzing driving factors such as improving organizational compliance requirements, enhancing operational efficiency, and simplifying workflows to eliminate bottlenecks.
Secondary Research
The market size of companies offering data center power was derived based on secondary data available through paid and unpaid sources, analyzing the product portfolios of major companies in the ecosystem, and rating the companies based on their product capabilities and business strategies.
The secondary research process referenced various sources to identify and collect information for the study. These sources included annual reports, press releases, investor presentations, product data sheets, white papers, journals, certified publications, and articles from recognized authors, government websites, directories, and databases.
Secondary research was mainly used to obtain key information about the industry’s supply chain, the total pool of key players, market classification and segmentation according to industry trends to the bottom-most level, regional markets, and key developments from market- and technology-oriented perspectives, all of which were further validated by primary sources.
Primary Research
In the primary research process, various sources from the supply and demand sides were interviewed to obtain qualitative and quantitative information for this report. Primary sources on the supply side included industry experts such as chief executive officers (CEOs), vice presidents (VPs), marketing directors, technology and innovation directors, and other key executives from various companies and organizations operating in the data center power market.
Primary interviews were conducted to gather insights, such as market statistics, the latest trends disrupting the market, new use cases implemented, data on revenue collected from products and services, market breakdowns, market size estimations, market forecasts, and data triangulation. Primary research also helped understand various technology-related trends, segmentation types, industry trends, and regions.
Demand-side stakeholders, such as Chief Information Officers (CIOs), Chief Technology Officers (CTOs), Chief Security Officers (CSOs), installation teams of governments and end users who utilize data center power, and digital initiatives project teams, were interviewed to understand the buyers’ perspectives on suppliers, products, service providers, and their current use of services, which would influence the overall data center power market.
Breakdown of Primary Profiles
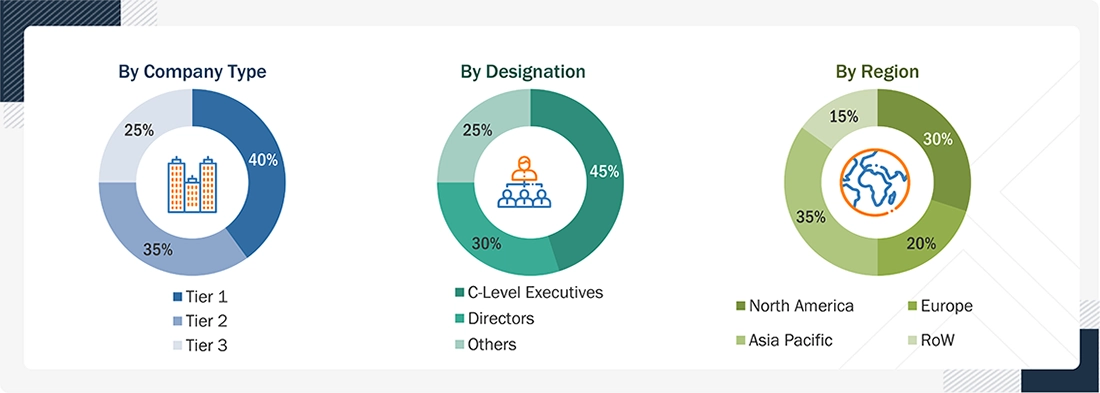
Note 1: Tier 1 companies have revenues greater than USD 10 billion; Tier 2 companies’ revenues range between USD 1 and 10 billion; and Tier 3 companies’ revenues range between USD 500 million and 1 billion.
Note 2: Others include sales, marketing, and product managers.
To know about the assumptions considered for the study, download the pdf brochure
Market Size Estimation
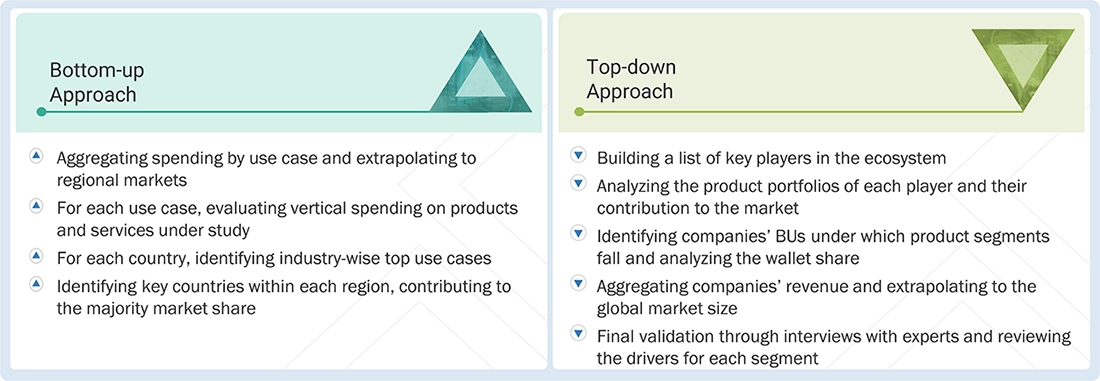
Multiple approaches were adopted to estimate and forecast the data center power market. The first approach estimated market size by summing companies’ revenue generated through services sales.
The research methodology used to estimate the market size included the following:
- Primary and secondary research was conducted to assess the revenue contributions of major market participants in each country, with secondary research identifying these participants.
- Critical insights were obtained by conducting in-depth interviews with industry professionals, including directors, CEOs, VPs, and marketing executives, and by reading the annual and financial reports of the top firms in the market.
- Primary sources were used to verify all percentage splits and breakdowns, which we calculated using secondary sources.
Data Center Power Market: Top-Down and Bottom-Up Approach
Data Triangulation
Once the overall market size was determined, we divided the market into segments and subsegments using the previously described market size estimation procedures. When required, market breakdown and data triangulation procedures were employed to complete the market engineering process and specify the exact figures for every market segment and subsegment. The data was triangulated by examining several variables and patterns from the government entities’ supply and demand sides.
Market Definition
According to MarketsandMarkets, “Data center power refers to the electrical infrastructure that supplies, distributes, and manages electricity within a data center to ensure the continuous operation of servers, networking, and cooling systems. It includes components such as UPS, PDUs, generators, transformers, and backup systems designed for reliability and redundancy. Modern data center power solutions also focus on efficiency, scalability, and integration of renewable energy to support growing workloads and sustainability goals.”
Key Stakeholders
- UPS system providers (modular, monolithic, lithium-ion, lead-acid)
- Generator manufacturers (diesel, gas, hybrid)
- PDU and switchgear suppliers
- Battery Energy Storage System (BESS) providers
- Data Center Infrastructure Management (DCIM) vendors
- Power monitoring and optimization software providers
- Smart grid and energy management solution developers
- Hyperscale cloud providers
- Colocation providers
- Enterprise data center operators
- Grid electricity suppliers
- Renewable energy providers (solar, wind, hydro integration for data centers)
Report Objectives
- To define, describe, and forecast the data center power market based on component, tier type, data center size, data center type, enterprise vertical, and region
- To forecast the market size of five major regional segments: North America, Europe, Asia Pacific, the Middle East & Africa, and Latin America
- To strategically analyze the market subsegments with respect to individual growth trends, prospects, and contributions to the total market
- To provide detailed information related to the major factors influencing the growth of the market (drivers, restraints, opportunities, and challenges)
- To strategically analyze macro and micromarkets with respect to growth trends, prospects, and their contributions to the overall market
- To analyze industry trends, patents, innovations, and pricing data related to the market
- To analyze the opportunities in the market for stakeholders and provide details of the competitive landscape for major players
- To analyze the impact of AI/generative AI on the market
- To profile key players in the market and comprehensively analyze their market share/ranking and core competencies
- To track and analyze competitive developments such as mergers & acquisitions, product launches, and partnerships & collaborations in the market
Available customizations:
MarketsandMarkets provides customizations based on the company’s unique requirements using market data. The following customization options are available for the report.
Product Analysis
- The product matrix provides a detailed comparison of each company’s portfolio.
Geographic Analysis
- Further breakdown of the data center power market
Company Information
- Detailed analysis and profiling of five additional market players
Get the Full Data Center Power Market Report
Full forecast, segment splits, and company analysis for all Data Center Power Market.
- Canada Data Center Power Market
- US Data Center Power Market
- UK Data Center Power Market
- Germany Data Center Power Market
- Italy Data Center Power Market
- China Data Center Power Market
- Japan Data Center Power Market
- India Data Center Power Market
- Saudi Arabia Data Center Power Market
- UAE Data Center Power Market
- South Africa Data Center Power Market
- Brazil Data Center Power Market
- Mexico Data Center Power Market
- Rest Of Europe Data Center Power Market
- Rest Of Asia Pacific Data Center Power Market
- Rest Of Latin America Data Center Power Market
- GCC Data Center Power Market
- Rest Of Mea Data Center Power Market
- Rest Of GCC Data Center Power Market
Need a Tailored Report?
Customize this report to your needs
Get 10% FREE Customization
Customize This Report
