Europe Digital Education Market (2025-2030)
The Europe Digital Education Market was valued at $6501.7 Million in 2025 and projected to reach to $17504.8 Million by 2030, representing a compound annual growth rate of 21.9%. Europe's digital education market is poised for substantial expansion through 2030, driven by regulatory support for digital literacy, increased government funding for educational technology infrastructure, and widespread adoption of hybrid learning models.

| Market Size in | USD 26.32 MN |
| Market Forecast in | |
| CAGR | |
| Forecast Period | |
| Units Considered | Value (USD MN) |
Europe Digital Education Market Trends and Insights
- This significant growth trajectory reflects Europe's commitment to digital transformation in educational institutions across primary, secondary, and higher education sectors.
- Europe is leveraging advanced technologies including artificial intelligence, cloud-based learning platforms, and interactive digital content to modernize educational delivery and enhance student engagement. The European digital education landscape is characterized by strong regulatory support, substantial public and private investment, and a mature technology infrastructure that facilitates rapid adoption.
- Europe's emphasis on digital literacy, remote learning capabilities, and personalized education solutions is driving market expansion across diverse demographic segments.
- By 2030, Europe is expected to solidify its position as a leading regional market, with digital education becoming integral to institutional strategies and student learning outcomes throughout the continent..
Key Market Statistics
- CAGR (2025-2030) 21.9% CAGR
- Market Size, 2025 ~USD 6501.7 Million
- Forecast, 2030 ~USD 17504.8 Million
- Geography Europe
Europe Digital Education Market Overview
Strong Market Valuation :
Europe's digital education market is valued at $6,501.7 million in 2025, with Germany and France leading as the largest markets at $3,995.7 million and $3,531.3 million respectively, demonstrating significant regional investment in educational technology.
Accelerated Growth Trajectory :
The European market is projected to nearly triple to $17,504.8 million by 2030, driven by a robust 21.9% CAGR, reflecting sustained institutional adoption of digital learning platforms across primary, secondary, and higher education sectors.
Digital Transformation Leadership :
Europe is leveraging advanced technologies including AI-powered learning systems, cloud-based educational platforms, and interactive digital content to modernize classrooms and enhance student engagement across diverse educational institutions.
Diverse Market Composition :
The UK ($3,694.5M), Italy ($1,754M), and Rest of Europe ($4,529.3M) contribute significantly to the regional market, creating a well-distributed ecosystem with opportunities across multiple European nations and educational segments.
Europe Digital Education Market Dynamics
- The region's commitment to digital transformation, combined with strong investment from both public and private sectors, positions Europe as a key growth driver in the global digital education landscape. Key growth catalysts include the European Union's digital education initiatives, rising demand for upskilling and reskilling programs, and the integration of emerging technologies such as artificial intelligence and virtual reality in educational settings.
- With major markets like Germany and France leading innovation, Europe is expected to maintain its competitive advantage while expanding digital education accessibility across all socioeconomic segments..
Market Ecosystem
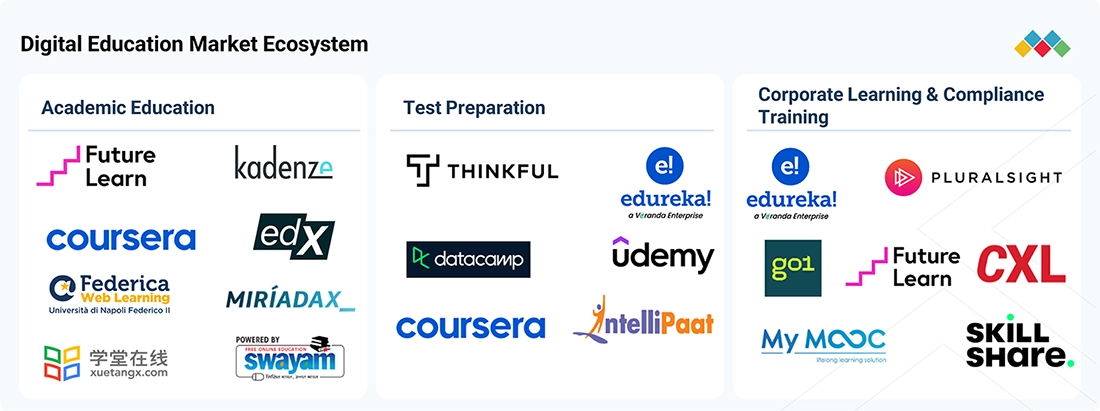
DIGITAL EDUCATION MARKET : COMMERCIAL USE CASES ACROSS INDUSTRIES
| COMPANY | USE CASE DESCRIPTION | BENEFITS |
|---|---|---|
 |
Maxis, a leading telecommunications company operating in an industry marked by high fixed costs, low margins, and constant technological change, sought to drive data and AI upskilling to boost employee productivity and enhance customer experience. By partnering with Coursera, Maxis accessed a comprehensive platform offering a balanced mix of business and digital skill courses tailored to its workforce needs. | Through the partnership, Maxis drove strong learner engagement across the organization, with employees completing over 16,000 courses and 700 certifications, strengthening the company's data and AI capabilities and supporting its broader learning and development strategy. |
 |
Sage, a global software organization, needed to simplify its notoriously complex tech stack and better secure its operations as it scaled its cloud offerings. Sage adopted Pluralsight Skills, leveraging its content libraries and Skill IQ capabilities to deliver tailored, data-driven learning experiences aligned to each employee's proficiency and the company's highest-risk products. | Over 1,300 Sage engineering employees now learn new skills weekly and stay accountable to quarterly upskilling goals, with 60% of team members completing more than the recommended courses. The company has seen measurable increases in time spent on security learning and stronger receptiveness to security initiatives. |
 |
Siemens sought to fuel future-ready skills across its ASEAN operations amid rapid technological change. The company partnered with LinkedIn Learning to launch its 'SkillUp! Learning Challenge,' aimed at building 'NextSkills' across its regional workforce through structured, career-aligned learning content. | The initiative strengthened a culture of continuous learning across Siemens' ASEAN workforce, supporting employee skill development aligned to evolving business and technology needs, and reinforcing Siemens' broader workforce transformation goals in the region. |
Logos and trademarks shown above are the property of their respective owners. Their use here is for informational and illustrative purposes only.
Related Ecosystem
Digitalization And Iot
- Sensors
- Remote Monitoring
- Supply Chain Management
- Passenger Information System (PIS)
- Platform as A Service (PaaS)
- International Business Machines Corporation
- Cisco Systems, Inc.
- MICROSOFT CORPORATION
- Oracle Corporation
- HUAWEI TECHNOLOGIES CO LTD
Software And Services
- Natural Language Processing (NLP)
- Machine Learning
- Supply Chain Management
- Predictive Analytics
- Image Sensors
- International Business Machines Corporation
- MICROSOFT CORPORATION
- Oracle Corporation
- SAP SE
- Amazon.com, Inc.
Key Takeaways
- Europe's digital education market will nearly triple from $6,501.7M (2025) to $17,504.8M (2030) at a 21.9% CAGR
- Europe is prioritizing AI-driven personalized learning and cloud-based platforms to enhance educational outcomes
- Strong regulatory frameworks and public investment in Europe support sustained digital education adoption
- Europe's mature tech infrastructure positions the region as a leader in implementing advanced educational technologies
Digital Education Market Report Scope
| Report Metric | Details |
|---|---|
| Base Year | 2025 |
| Fastest Growing Segment | BLENDED LEARNING (Learning Model) |
| Forecast Period | 2025–2030 |
| Growth Rate | CAGR of 24.2% from 2025 to 2030 |
| Largest Segment | ASYNCHRONOUS LEARNING (Learning Type) |
| Market Size Base Year (Billions) | ~USD 32.38 (2025) |
| Revenue Forecast (Billions) | ~USD 95.7 (2030) |
| Segments Covered | Learning Model, Delivery Mode, Course Type, End User, Offering, Learning Type |
Europe Digital Education Market Report Segmentation
6 segment dimensions are covered across the global market.
By Learning Model
- Adaptive Learning
- Blended Learning
- Instructor-Led
- Microlearning
- Mobile Learning
- Self-Paced Learning
By Delivery Mode
- Asynchronous Learning
- Blended Learning
- Distance Learning
- Hybrid Learning
- Instructor-Led Training
- Synchronous Learning
By Course Type
- Academic Education
- Corporate Learning & Compliance Training
- Professional Certification & Skill Development
- Test Preparation
- Vocational Training
By End User
- Academic Institutions
- Corporate & Enterprise Organizations
- Government & Public Sector
By Offering
- Hardware
- Services
- Solutions
By Learning Type
- Asynchronous Learning
- Synchronous Learning
EUROPE: DIGITAL EDUCATION MARKET, BY END USER, 2025–2030
| Segment | 2025 | 2026 | 2027 | 2028 | 2029 | 2030 | CAGR (%) |
|---|---|---|---|---|---|---|---|
| ACADEMIC INSTITUTIONS | 3191.8 | 3942.6 | 4831.1 | 5844 | 7051.6 | 8322.4 | 21.1 |
| CORPORATE & ENTERPRISE ORGANIZATIONS | 1939 | 2428 | 3016.4 | 3699.7 | 4526.9 | 5418 | 22.8 |
| GOVERNMENT & PUBLIC SECTOR | 1370.9 | 1710.7 | 2117.9 | 2588.6 | 3156.2 | 3764.4 | 22.4 |
| TOTAL | 6501.7 | 8081.4 | 9965.5 | 12132.4 | 14734.7 | 17504.8 | 21.9 |
Target Audience
- EdTech Companies & Startups : European and international edtech firms need detailed regional market data to identify expansion opportunities, benchmark against competitors, and develop localized solutions aligned with European educational standards and digital transformation initiatives.
- Educational Institutions : Universities, schools, and training centers across Europe require market insights to make informed technology investments, understand peer adoption trends, and align digital infrastructure spending with regional growth patterns and best practices.
- Investment & Venture Capital Firms : Investors targeting Europe's digital education sector need comprehensive market sizing, growth forecasts, and regional opportunity analysis to identify promising portfolio companies, assess market maturity, and optimize capital deployment across European markets.
- Government & Policy Makers : European government agencies and educational policy bodies utilize market data to inform digital education funding decisions, regulatory frameworks, and strategic initiatives that support the region's digital transformation and competitive positioning.
- Technology & Software Providers : Enterprise software vendors, cloud service providers, and technology solution companies need Europe-specific market intelligence to develop region-appropriate offerings, understand adoption barriers, and prioritize feature development for European educational customers.
Key Companies in the Europe Digital Education Market
| Company | HQ | Ownership | Strongest segments |
|---|---|---|---|
| COURSERA | United States | Public Company | Consumer (Coursera.org & Coursera Plus),Enterprise (Business, Campus, Government),Online Degrees & MasterTrack/Postgraduate Diplomas, |
| UDEMY | United States | Private Company | Consumer marketplace courses,Udemy Business seat-based subscriptions (team, enterprise, leadership academy, Business Pro),Professional services and learning architecture / AI transformation packages, |
| PLURALSIGHT | United States | Private Company | Pluralsight Skills (individual and enterprise subscriptions),Pluralsight Flow (engineering analytics),Other services and partnerships (including Elice and ancillary offerings), |
| VERANDA LEARNING | India | Public Company | Exam preparation (civil services, banking, government, law, commerce qualifications),Higher education and professional courses (management, technology, leadership, marketing),K-12 and undergraduate academic support, |
| LINKEDIN LEARNING | United States | Private Company | Enterprise & Government Subscriptions,Academic (Higher Ed & K-12) Licensing,Individual Premium Subscriptions, |
COURSERA
Coursera is a public educational technology company founded in 2011 in the United States with 1,307 employees. The company provides online learning courses and degree programs through partnerships with universities and organizations worldwide.
UDEMY
Udemy is a private online learning platform founded in 2010 in the United States with 1,380 employees. The company offers a marketplace of courses across various subjects taught by independent instructors to millions of learners globally.
PLURALSIGHT
Pluralsight is a private technology skills training company founded in 2004 in the United States with 1,700 employees. The company offers online courses and learning paths focused on software development, IT operations, and creative skills.
VERANDA LEARNING
Veranda Learning is a public educational company founded in 2018 in India. The company provides online and offline learning solutions and skill development programs.
LINKEDIN LEARNING
LinkedIn Learning is a private online education platform founded in 1995 in the United States with 3 employees. The company provides professional development courses and training content to help individuals advance their careers.
Countries within Europe - compare and drill down
| Country | 2025 size (native) |
|---|---|
| UK | USD 3694.5 Million |
| Germany | USD 3995.7 Million |
| France | USD 3531.3 Million |
| Italy | USD 1754 Million |
| Rest Of Europe | USD 4529.3 Million |
Country market size visualization
Reasons to Buy this Report
- Regional Market Segmentation : Gain detailed insights into Europe's digital education market broken down by major countries including Germany, France, UK, and Italy, enabling targeted market entry and expansion strategies specific to high-growth European nations.
- Growth Forecasting & Projections : Access comprehensive 5-year forecasts projecting the European market's expansion from $6.5B to $17.5B, providing critical data for investment decisions, product development timelines, and competitive positioning in the region.
- Competitive Landscape Analysis : Understand Europe's unique digital education ecosystem, including regulatory frameworks, institutional adoption patterns, and technology preferences that differentiate the region from global markets and inform localization strategies.
- Investment & Partnership Opportunities : Identify high-potential markets and segments within Europe's 21.9% CAGR growth trajectory, enabling strategic partnerships, M&A opportunities, and venture capital allocation across the continent's thriving edtech sector.
- Strategic Decision Support : Leverage Europe-specific market intelligence to support executive decision-making, resource allocation, and go-to-market strategies tailored to regional educational priorities, funding mechanisms, and technology adoption rates.
Frequently asked questions
What is the projected size of Europe's digital education market by 2030?
Europe's digital education market is projected to reach $17,504.8 million by 2030, growing from $6,501.7 million in 2025.
What is the CAGR for Europe's digital education market?
Europe's digital education market is expected to grow at a compound annual growth rate of 21.9% between 2025 and 2030.
What technologies are driving growth in Europe's digital education sector?
Europe's digital education growth is driven by artificial intelligence, cloud-based learning platforms, interactive digital content, and personalized learning solutions.
Which educational segments are experiencing the most growth in Europe?
Europe's digital education expansion spans primary, secondary, and higher education sectors, with particular emphasis on institutional digital transformation and remote learning capabilities.
What factors support Europe's digital education market expansion?
Europe's market growth is supported by strong regulatory frameworks, substantial public and private investment, mature technology infrastructure, and institutional commitment to digital literacy.
RESEARCH METHODOLOGY
This research study used extensive secondary sources, directories, and databases, such as D&B Hoovers, Bloomberg Businessweek, and Factiva, to identify and collect information for a technical, market-oriented, and commercial study of the global digital education market. We also considered other market-related reports and analyses published by various industry associations and consortiums, such as the National Security Agency (NSA) and SC Magazine, during the extensive secondary research. Primary sources were mainly industry experts from the core and related industries, including preferred suppliers, manufacturers, distributors, service providers, technology developers, and technologists from companies and organizations across all segments of this industry’s value chain. We conducted in-depth interviews with primary respondents, including key industry participants, subject-matter experts, C-level executives of key market players, and industry consultants, to gather and validate critical qualitative and quantitative information and assess prospects. The market has been estimated by analyzing driving factors such as the need to improve compliance within an organization, enhance operational efficiency, and simplify workflows to eliminate bottlenecks.
Secondary Research
The market size of companies offering digital education solutions was determined using secondary data from paid and unpaid sources, analyzing the product portfolios of major companies in the ecosystem, and rating companies based on their product capabilities and business strategies.
In the secondary research process, we referred to various sources to identify and collect information for the study. Secondary sources included annual reports, press releases, investor presentations, product data sheets, white papers, journals, certified publications, and articles from recognized authors, government websites, directories, and databases.
Secondary research was mainly used to obtain key information about the industry’s supply chain, the total pool of key players, market classification and segmentation according to industry trends to the bottom-most level, regional markets, and key developments from both market- and technology-oriented perspectives, all of which were further validated by primary sources.
Primary Research
In the primary research process, we interviewed various primary sources from the supply and demand sides to obtain qualitative and quantitative information for this report. Supply-side primary sources included industry experts such as chief executive officers (CEOs), vice presidents (VPs), marketing directors, technology and innovation directors, and other key executives from companies and organizations operating in the digital education market.
We conducted primary interviews to gather insights, including market statistics, the latest market-disrupting trends, new use cases, revenue data for products and services, market breakdowns, market size estimates, market forecasts, and data triangulation. Primary research also helped us understand technology trends, segmentation types, industry trends, and regions. Demand-side stakeholders, such as chief information officers (CIOs), chief technology officers (CTOs), chief security officers (CSOs), the installation teams of governments/end users using digital education platforms, and digital initiatives project teams, were interviewed to understand the buyer’s perspective on suppliers, products, service providers, and their current use of services, which would affect the overall digital education market.
Breakdown of Primary Profiles
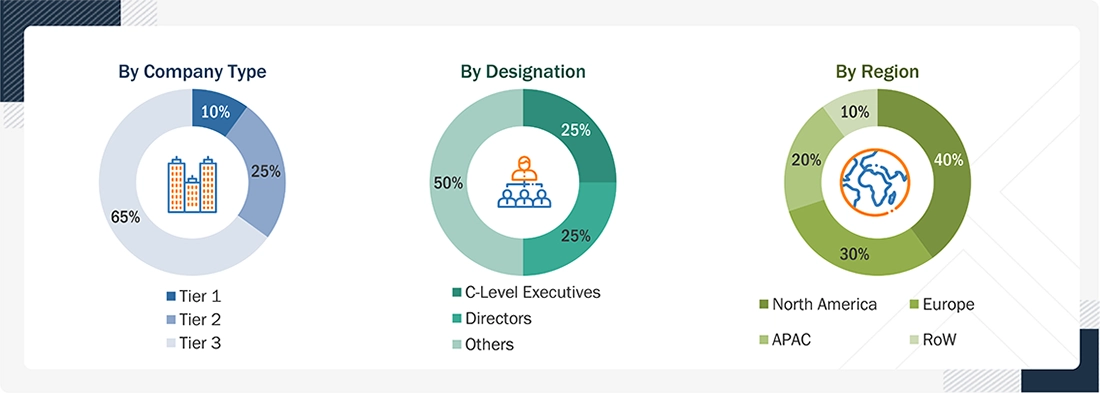
Note 1: Tier 1 companies have revenues greater than USD 10 billion; tier 2 companies’ revenues range between USD 1 and 10 billion; and tier 3 companies’ revenues range between USD 500 million and 1 billion.
Note 2: Others include sales, marketing, and product managers.
Source: Secondary Literature, Interviews with Experts, and MarketsandMarkets Analysis
To know about the assumptions considered for the study, download the pdf brochure
Market Size Estimation
Multiple approaches were adopted to estimate and forecast the digital education market. The first approach estimated market size by summing the companies’ revenue generated through service sales.
Top-down and Bottom-up Approach of Digital Education Market
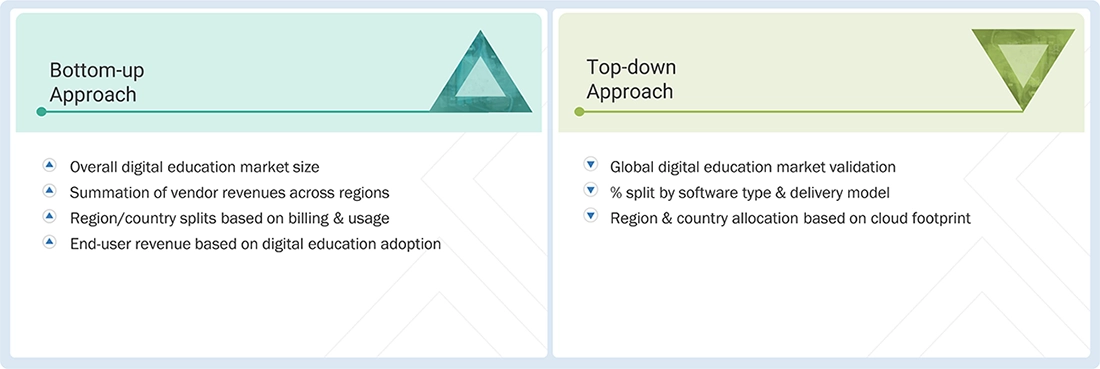
Source: Annual Reports, SEC Filings, Secondary Research, Interviews with Experts, and MarketsandMarkets Analysis
The research methodology used to estimate the market size included the following:
- Primary and secondary research was conducted to assess the revenue contributions of major market participants in each country, with secondary research identifying these participants.
- Critical insights were obtained by conducting in-depth interviews with industry professionals, including directors, CEOs, VPs, and marketing executives, and by reading the annual and financial reports of the top firms in the market.
- Primary sources were used to verify all percentage splits and breakups, which we calculated using secondary sources.
Data Triangulation
Once we determined the overall market size, we divided the market into segments and subsegments using the previously described market size estimation procedures. When needed, we used market breakdown and data triangulation procedures to complete the market engineering process and specify exact figures for each market segment and subsegment. The data was triangulated by examining several variables and patterns from the government entities’ supply and demand sides.
Market Definition
Considering the views of various sources and associations, MarketsandMarkets defines digital education as “the use of digital technologies and tools to facilitate teaching and learning. It encompasses online learning platforms, virtual classrooms, digital content, and interactive resources that enhance access to education beyond traditional settings. Digital education enables personalized learning, supports flexible study environments, and fosters collaboration through technology. It includes a broad spectrum of formats such as e-learning, blended learning, and mobile learning. With advancements in artificial intelligence and cloud computing, digital education plays a crucial role in equipping learners with essential digital skills and promoting inclusive, lifelong learning opportunities across various age groups and educational contexts.”
Key Stakeholders
- Students
- Teachers & Educators
- Educational Institutions
- EdTech Companies
- Governments & Regulatory Bodies
- Parents & Guardians
- Content Providers & Publishers
- Technology Providers
- Investors & Venture Capitalists
- NGOs & Foundations
- Telecommunication Companies
- Assessment & Accreditation Bodies
Report Objectives
- To define, describe, and forecast the global digital education market based on learning model (self-paced online learning, instructor-led online learning, blended learning, microlearning, adaptive learning, and mobile learning), delivery mode (synchronous learning, asynchronous, and hybrid classrooms), course type (academic education, test preparation, professional certifications & skill development, vocational training, and corporate learning & compliance training), end user (academic institutions, corporates & enterprises, government & public sector, and edtech companies), and region
- To forecast the market size of the five major regional segments: North America, Europe, Asia Pacific, the Middle East & Africa, and Latin America
- To strategically analyze the market subsegments with respect to individual growth trends, prospects, and contributions to the total market
- To provide detailed information related to the major factors influencing the growth of the market (drivers, restraints, opportunities, and challenges)
- To strategically analyze macro and micromarkets with respect to growth trends, prospects, and their contributions to the overall market
- To analyze industry trends, patents and innovations, and pricing data related to the digital education market
- To analyze the opportunities in the market for stakeholders and provide details of the competitive landscape for major players
- To analyze the impact of AI/GenAI on the global digital education market
- To profile key players in the market and comprehensively analyze their market share/ranking and core competencies
- To track and analyze competitive developments, such as mergers & acquisitions, product developments, and partnerships & collaborations in the market
Available customizations:
MarketsandMarkets provides customizations based on the company’s unique requirements using market data. The following customization options are available for the report.
Product analysis
- The product matrix provides a detailed comparison of each company’s portfolio.
Geographic analysis
- Further breakdown of the digital education market
Company information
- Detailed analysis and profiling of five additional market players
Get the Full Digital Education Market Report
Full forecast, segment splits, and company analysis for all Digital Education Market.
- US Digital Education Market
- Canada Digital Education Market
- UK Digital Education Market
- Germany Digital Education Market
- France Digital Education Market
- Italy Digital Education Market
- China Digital Education Market
- Japan Digital Education Market
- India Digital Education Market
- UAE Digital Education Market
- South Africa Digital Education Market
- Brazil Digital Education Market
- Mexico Digital Education Market
- Rest Of Europe Digital Education Market
- Rest Of Asia Pacific Digital Education Market
- Rest Of Latin America Digital Education Market
- GCC Digital Education Market
- Ksa Digital Education Market
- Rest Of GCC Digital Education Market
Need a Tailored Report?
Customize this report to your needs
Get 10% FREE Customization
Customize This Report