Germany Digital Substation Market (2025-2030)
The Germany Digital Substation Market was valued at $803.9 Million in 2025 and projected to reach to $1132.9 Million by 2030, representing a compound annual growth rate of 7.1%. Germany's digital substation market is poised for sustained growth through 2030, driven by the country's commitment to grid modernization and renewable energy integration.

| Market Size in | USD 26.32 MN |
| Market Forecast in | |
| CAGR | |
| Forecast Period | |
| Units Considered | Value (USD MN) |
Germany Digital Substation Market Trends and Insights
- Germany's commitment to grid modernization and renewable energy integration is driving adoption of advanced digital substation technologies across the country.
- The market in Germany is benefiting from stringent regulatory frameworks and substantial investments in smart grid infrastructure that position the nation as a leader in digital substation deployment across Europe. Germany's digital substation market growth is underpinned by the country's Energiewende (energy transition) initiative, which necessitates upgraded electrical infrastructure to accommodate distributed renewable sources.
- Germany's utilities and grid operators are increasingly deploying digital substations to enhance operational efficiency, reduce downtime, and improve grid stability.
- By 2030, Germany is expected to see widespread adoption of IoT-enabled monitoring systems and AI-driven analytics within substation environments, reflecting the country's technological advancement and regulatory push toward decarbonization..
Key Market Statistics
- CAGR (2025-2030) 7.1% CAGR
- Market Size, 2025 ~USD 803.9 Million
- Forecast, 2030 ~USD 1132.9 Million
- Country Germany
Germany Digital Substation Market Overview
Market Valuation Growth :
Germany's digital substation market is valued at $803.9 million in 2025, with a projected CAGR of 7.1% through 2030, reaching $1,132.9 million. This outpaces the global CAGR of 6.5%, reflecting Germany's accelerated digital transformation in energy infrastructure.
Renewable Energy Integration :
Germany's Energiewende (energy transition) policy drives substantial investment in digital substations to manage distributed renewable energy sources. Advanced grid management technologies are critical for integrating wind and solar capacity across the country's decentralized energy network.
Regulatory Framework Support :
Stringent EU and German regulatory requirements for grid modernization, cybersecurity, and operational efficiency create a favorable environment for digital substation adoption. Compliance mandates accelerate technology deployment across utilities and grid operators.
Industrial Leadership Position :
Germany's strong manufacturing base and engineering expertise position the country as a hub for digital substation innovation. Local technology providers and utilities drive competitive market dynamics and technological advancement in the sector.
Germany Digital Substation Market Dynamics
- The transition to Industry 4.0 and smart grid technologies creates significant opportunities for advanced digital solutions that enhance operational efficiency and grid stability.
- Utilities across Germany are increasingly investing in automation, real-time monitoring, and predictive maintenance capabilities to support the growing share of renewable energy sources. The regulatory landscape, including EU directives on grid resilience and cybersecurity, will continue to propel market expansion.
- Germany's position as Europe's largest economy and energy consumer ensures substantial capital investment in digital infrastructure.
- Strategic partnerships between utilities, technology providers, and government agencies will accelerate innovation and deployment of next-generation digital substation solutions throughout the forecast period..
Market Ecosystem
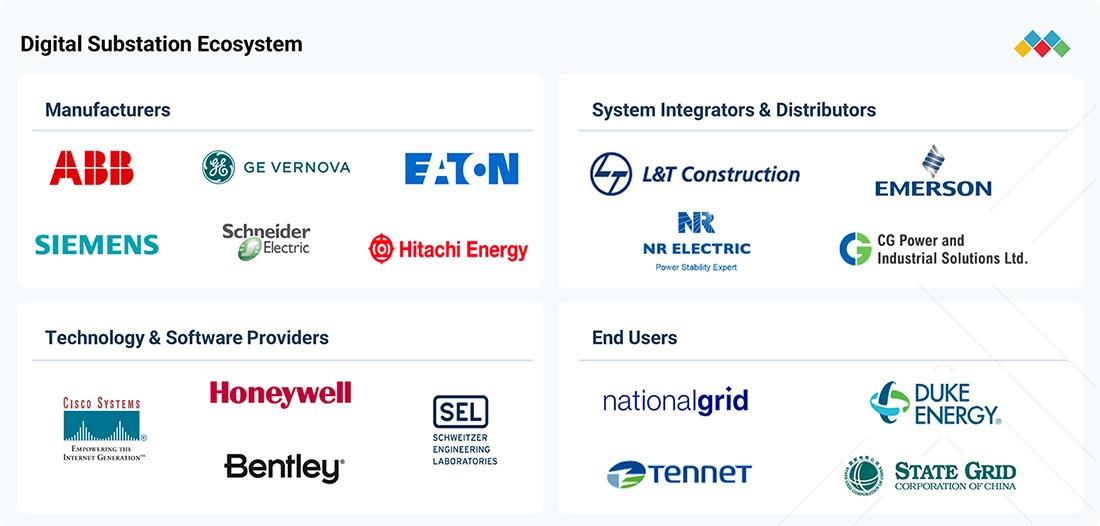
DIGITAL SUBSTATION MARKET: COMMERCIAL USE CASES ACROSS INDUSTRIES
| COMPANY | USE CASE DESCRIPTION | BENEFITS |
|---|---|---|
 |
TEPCO Power Grid uses sensing and digital technologies across substations and grid infrastructure to monitor equipment condition, operating status, and abnormal conditions. Its advanced substation initiatives combine sensors, remote monitoring, AI, and other digital technologies to assess equipment status and support automated and remote maintenance. | Enables real-time equipment monitoring | Supports remote and predictive maintenance | Reduces inspection requirements and downtime | Improves grid reliability and operational efficiency |
 |
KEPCO integrates sensor-based monitoring, digital substations, and predictive diagnostics across transmission and distribution infrastructure. Its systems use real-time sensor data to monitor transformers, GIS, underground cables, and other power assets, while smart distribution systems enable real-time monitoring and control of grid equipment. | Enables early fault detection | Supports predictive maintenance | Improves equipment reliability and grid stability | Enables automated and remote grid operations |
 |
National Grid deploys sensor-based grid monitoring technologies, including dynamic line rating sensors and AI-enabled infrastructure monitoring. Its DLR deployment uses non-contact sensors and analytics to identify available capacity on overhead lines, while digital monitoring supports asset inspection and network management. | Enables real-time line and asset monitoring | Increases utilization of existing grid infrastructure | Supports integration of renewable power | Improves network reliability and maintenance planning |
 |
Statnett uses sensors across its transmission network to monitor asset condition and operating parameters. Its sensor deployments include transformer and substation monitoring as well as Dynamic Line Rating sensors on transmission lines, enabling more accurate assessment of line capacity and asset health. | Enables accurate asset-condition monitoring | Supports predictive maintenance | Increases transmission-line capacity | Improves grid utilization and reliability |
 |
Duke Energy uses electronic sensors, switches, smart grid devices, and monitoring systems to track grid conditions and equipment status. Its smart-grid initiatives include instrumented distribution equipment such as reclosers, smart meters, sensors, and PMUs, enabling remote monitoring and control of grid assets. | Enables real-time grid monitoring | Supports automated fault detection and control | Improves outage response and grid reliability | Enables efficient management of distributed energy resources |
Logos and trademarks shown above are the property of their respective owners. Their use here is for informational and illustrative purposes only.
Related Ecosystem
Smart Grid
- Meter Data Management (MDM)
- Sensors
- Workforce Management
- Cellular Network
- Customer Analytics
- SCHNEIDER ELECTRIC SE
- Siemens ag
- ABB India Limited
- Eaton Corporation plc
- Hitachi Energy India Limited
Electronics System And Components
- Sensors
- Temperature Sensors
- Pressure Sensors
- Actuators
- Image Sensors
- Lenovo
- Samsung
- Texas Instruments Incorporated
- HONEYWELL INTERNATIONAL INC.
- Teledyne Technologies Incorporated
Industrial Iot
- Sensors
- Pressure Sensors
- Flow Sensors
- Gas Sensors
- Image Sensors
- Siemens ag
- ABB India Limited
- HONEYWELL INTERNATIONAL INC.
- Emerson Electric Co.
- SCHNEIDER ELECTRIC SE
Key Takeaways
- Germany's digital substation market will grow from $803.9M (2025) to $1,132.9M (2030), representing a 7.1% CAGR.
- Germany's Energiewende initiative is the primary catalyst driving digital substation investments and grid modernization efforts.
- Germany leads Europe in digital substation adoption due to strong regulatory support and renewable energy integration requirements.
- By 2030, Germany's market will be characterized by widespread IoT and AI-driven analytics deployment in substation operations.
Digital Substation Market Report Scope
| Report Metric | Details |
|---|---|
| Base Year | 2025 |
| Fastest Growing Segment | SCADA SYSTEMS (Module) |
| Forecast Period | 2025–2030 |
| Growth Rate | CAGR of 6.5% from 2025 to 2030 |
| Largest Segment | HARDWARE (Module) |
| Market Size Base Year (Billions) | ~USD 14.44 (2025) |
| Revenue Forecast (Billions) | ~USD 19.78 (2030) |
| Segments Covered | Type, Installation Type, Industry, Module, Voltage, Hardware Type, Utility Type, Protection Devices Type |
Germany Digital Substation Market Report Segmentation
8 segment dimensions are covered across the global market.
By Type
- Bus Bars
- Circuit Breakers
- Distribution
- Distribution Substations
- Interfacing Units
- Other Hardware Types
- Protection Devices
- Protection Relays
- Switch Gears
- Transformers
- Transmission
- Transmission Substations
By Installation Type
- New Installations
- Retrofit
By Industry
- Heavy Industries
- Other Industries
- Transportation
- Utilities
By Module
- Fiber-Optic Communication Networks
- Hardware
- Scada Systems
By Voltage
- 220–550 Kv
- 220–550Kv
- Above 550 Kv
- Above 550Kv
- Up To 220 Kv
- Up To 220Kv
By Hardware Type
- Bus Bars
- Interfacing Units
- Other Hardware Type
- Other Hardware Types
- Protection Devices
- Transformers
By Utility Type
- Non-Renewable
- Non-Renewables
- Renewable
- Renewables
By Protection Devices Type
- Circuit Breakers
- Protection Relays
- Switch Gears
GERMANY: DIGITAL SUBSTATION MARKET, BY INDUSTRY, 2025–2030
| Segment | 2025 | 2026 | 2027 | 2028 | 2029 | 2030 | CAGR (%) |
|---|---|---|---|---|---|---|---|
| HEAVY INDUSTRIES | 127.3 | 134.5 | 141.8 | 149.2 | 156.7 | 164.3 | 5.2 |
| OTHER INDUSTRIES | 70.4 | 73.2 | 75.7 | 78 | 80 | 81.6 | 3 |
| TRANSPORTATION | 88.2 | 94.4 | 100.7 | 107.3 | 114.2 | 121.2 | 6.6 |
| UTILITIES | 517.9 | 562.1 | 609 | 658.5 | 710.8 | 765.8 | 8.1 |
| TOTAL | 803.9 | 864.2 | 927.2 | 993 | 1061.6 | 1132.9 | 7.1 |
Target Audience
- Utility Companies & Grid Operators : German utilities and transmission system operators need market intelligence to guide capital investment decisions in digital substation infrastructure, understand competitive offerings, and align technology roadmaps with regulatory requirements and renewable energy integration goals.
- Technology & Equipment Manufacturers : Suppliers of digital substation components, automation systems, and software solutions require Germany-specific market data to identify growth opportunities, assess competitive positioning, and develop localized product strategies for Europe's largest industrial market.
- Energy Consultants & System Integrators : Consulting firms and system integrators advising German utilities need detailed market insights to support client recommendations, validate business cases for digital transformation projects, and benchmark solutions against market standards and best practices.
- Investment & Financial Institutions : Private equity, venture capital, and infrastructure investors evaluating opportunities in Germany's energy sector require comprehensive market analysis to assess growth potential, identify acquisition targets, and structure investment theses in digital grid modernization.
- Government & Policy Makers : German federal and state energy agencies, regulatory bodies, and policy development teams use market research to inform energy transition strategies, assess infrastructure investment needs, and evaluate the effectiveness of grid modernization initiatives.
Key Companies in the Germany Digital Substation Market
| Company | HQ | Ownership | Strongest segments |
|---|---|---|---|
| KONGSBERG GRUPPEN | Norway | Public Company | Air defence, combat systems, and C2,Missiles (naval strike and air-to-surface),Remote weapon stations and land systems, |
| AT&S | Canada | Public Company | Turnkey automated manufacturing and assembly systems,Lifecycle and post-automation services,Software and digital solutions, |
| TECH MAHINDRA LIMITED | India | Public Company | Application services and digital enterprise platforms (SAP, Oracle, Salesforce, ServiceNow, digital process solutions),Engineering, network, and testing services,Cloud and infrastructure services (CLOUDNXT.NOW, data center, FLEX digital workplace, enterprise mainframe), |
| KEC INTERNATIONAL LIMITED | India | Public Company | Transmission & Distribution EPC (including GIS and substations),Railway EPC and Urban Transport,Civil Infrastructure (transport, industrial, residential/defense, data centers, water), |
| ABB | Switzerland | Public Company | Electrification,Motion,Automation, |
| GE VERNOVA | United States | Public Company | Power (gas, nuclear, hydro, steam),Wind (onshore and offshore),Electrification (grid, power conversion, software, solar and storage), |
| MITSUBISHI ELECTRIC CORPORATION | Japan | Public Company | Infrastructure, Energy, Defense & Space Systems,Factory Automation & Industrial Systems,Automotive Equipment, |
| EATON | Ireland | Public Company | Electrical Americas (power distribution, power quality, residential, utility),Electrical Global (hazardous duty, emergency lighting, structural support),Aerospace (hydraulics, fuel systems, thermal management, filtration), |
| HONEYWELL INTERNATIONAL INC. | United States | Public Company | Industrial Automation,Building Automation,Energy and Sustainability Solutions (UOP and related), |
| TOSHIBA CORPORATION | Japan | Private Company | Energy Systems & Solutions,Infrastructure Systems & Solutions,Building Solutions, |
| CISCO | United States | Public Company | Data Center and Campus Switching/Routing,Network Security and SASE,Collaboration and Webex Suite, |
| LANNER ELECTRONICS | Taiwan | Public Company | x86 Network Appliances (rackmount & desktop, SD-WAN/security),Rugged & Industrial Edge Computers (DIN-rail, vehicle, rail, IEC61850-3),Edge AI Appliances & NVIDIA GPU-based Systems, |
| WELOTEC GMBH | Germany | Private Company | Industrial networking & routers,Industrial PCs & edge computing,Remote access & security solutions, |
KONGSBERG GRUPPEN
Kongsberg Gruppen is a Norwegian public company founded in 1814 with 7,586 employees. It operates as a diversified industrial group with operations across multiple sectors.
AT&S
AT&S is a Canadian public company founded in 1978 with 7,000 employees. It operates in the technology and industrial sectors.
TECH MAHINDRA LIMITED
Tech Mahindra Limited is an Indian public company founded in 1986 with 119,337 employees. It is a major information technology and business process management services provider.
KEC INTERNATIONAL LIMITED
KEC International Limited is an Indian public company founded in 1945 with 6,709 employees. It operates in the engineering and construction sectors.
ABB
ABB is a Swiss public company founded in 1883 with 111,900 employees. It is a leading provider of electrification, robotics, and industrial automation solutions.
GE VERNOVA
GE Vernova is a United States-based public company founded in 2023 with 78,000 employees. It operates in the energy and power generation sector.
MITSUBISHI ELECTRIC CORPORATION
Mitsubishi Electric Corporation is a Japanese public company founded in 1921 with 150,386 employees. It manufactures electrical and electronic equipment across industrial, consumer, and infrastructure sectors.
EATON
Eaton is an Ireland-based public company founded in 1911 with 97,303 employees. It provides power management solutions and diversified industrial products.
HONEYWELL INTERNATIONAL INC.
Honeywell International Inc. is a United States-based public company founded in 1885 with 101,000 employees. It operates in aerospace, building technologies, performance materials, and safety solutions.
TOSHIBA CORPORATION
Toshiba Corporation is a Japanese private company founded in 1875 with 106,648 employees. It operates across electronics, energy, infrastructure, and digital solutions sectors.
CISCO
Cisco is a United States-based public company founded in 1984 with 86,200 employees. It is a leading provider of networking and cybersecurity solutions.
LANNER ELECTRONICS
Lanner Electronics is a Taiwan-based public company founded in 1986. It operates in the electronics and computing sector.
WELOTEC GMBH
Welotec GmbH is a German private company founded in 1991. It operates in the industrial technology sector.
Reasons to Buy this Report
- Market-Specific Sizing & Forecasts : Access precise valuation data for Germany's digital substation market with detailed 2025-2030 projections. Understand market growth trajectories specific to German regulatory, economic, and energy transition contexts that differ from global averages.
- Competitive Landscape Intelligence : Identify key players, market share dynamics, and competitive positioning within Germany's digital substation ecosystem. Gain insights into local technology providers, utility partnerships, and emerging competitors shaping the German market.
- Regulatory & Policy Analysis : Understand how German and EU regulatory frameworks, including Energiewende policies and cybersecurity mandates, drive market opportunities. Assess compliance requirements and their impact on technology adoption and investment timelines.
- Investment & Expansion Strategy : Develop informed market entry or expansion strategies tailored to Germany's unique energy landscape. Identify high-growth segments, regional opportunities, and customer segments within the German digital substation market.
- Technology Trend Insights : Discover emerging technologies, innovation trends, and digital transformation priorities specific to German utilities and grid operators. Align product development and go-to-market strategies with Germany's advanced technology adoption patterns.
Frequently asked questions
What is the current size of Germany's digital substation market?
Germany's digital substation market was valued at $803.9 million in 2025 and is expected to reach $1,132.9 million by 2030.
What is driving growth in Germany's digital substation market?
Germany's digital substation market growth is primarily driven by the Energiewende energy transition initiative, renewable energy integration requirements, and regulatory mandates for grid modernization.
What is the projected CAGR for Germany's digital substation market?
Germany's digital substation market is projected to grow at a compound annual growth rate (CAGR) of 7.1% from 2025 to 2030.
Which technologies are being deployed in Germany's digital substations?
Germany's digital substations are increasingly incorporating IoT-enabled monitoring systems, AI-driven analytics, advanced sensors, and cloud-based management platforms to enhance grid efficiency and reliability.
How does Germany's market compare to other European countries?
Germany leads Europe in digital substation adoption due to its strong regulatory framework, substantial government investments in grid modernization, and aggressive renewable energy targets.
RESEARCH METHODOLOGY
The study involved four major activities in estimating the current size of the global digital substation market. Extensive secondary research was conducted to gather information on the digital substation ecosystem, including substation automation providers, protection and control equipment manufacturers, IED suppliers, communication technology providers, SCADA and software providers, system integrators, utilities, transmission and distribution operators, renewable energy companies, and industrial end users. This was followed by primary research with industry stakeholders across the value chain, including digital substation manufacturers, technology developers, protection and automation providers, communication equipment suppliers, system integrators, utilities, renewable energy developers, industrial companies, and end users, to validate assumptions and market sizing.
Both top-down and bottom-up approaches were used to estimate the overall market size. Market breakdowns and data triangulation techniques were then applied to determine the size of individual segments and subsegments by component, module, voltage level, installation, technology, application, end user, and region. Secondary and primary sources were jointly used to support a comprehensive technical, commercial, and competitive analysis of the global market. Digital-substation technologies considered include IEC 61850-based automation, protection and control, IEDs, process-bus systems, SCADA, communication networks, monitoring and diagnostics, and digital substation software.
Secondary Research
Various secondary sources were referred to during the secondary research process to identify and collect information relevant to the digital substation market. These sources included annual reports, company presentations, press releases, product catalogs, technical datasheets, patents, technical journals, industry publications, company websites, trade directories, utility publications, standards organizations, and government databases. Secondary research was conducted to obtain key insights into the market’s supply chain, value chain, competitive landscape, technology ecosystem, and segmentation by component, module, voltage level, installation, technology, application, end user, and region. It also helped assess industry trends, adoption of digital substations across transmission and distribution networks, renewable energy projects, industrial facilities, and smart-grid applications, as well as advancements in IEC 61850, digital protection and control, IEDs, process-bus communication, SCADA, cybersecurity, digital monitoring, and automation technologies. Company-level research included assessment of portfolios from leading providers such as Hitachi Energy, Siemens Energy, ABB, GE Vernova, and Schneider Electric. The collected information was further analyzed to estimate the overall market size and validate market assumptions, which were subsequently refined through primary research with industry experts and key stakeholders.
Primary Research
Extensive primary research was conducted after gaining knowledge about the current scenario of the digital substation market through secondary research. Several primary interviews were conducted with experts from the demand and supply sides across four major regions: North America, Europe, Asia Pacific, and RoW. This primary data was collected through questionnaires, emails, and telephonic interviews.
Breakdown of Primary Interviews
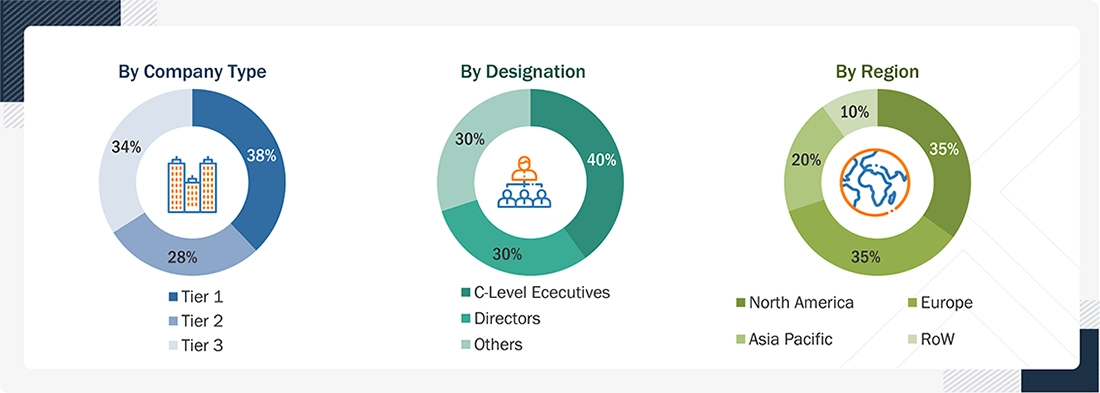
Note: The three tiers of the companies are defined based on their total revenue in 2025: Tier 1 - revenue greater than or equal to USD 1 billion; Tier 2 - revenue between USD 100 million and USD 1 billion; and Tier 3 revenue less than or equal to USD 100 million. Other designations include sales managers, marketing managers, and product managers.
To know about the assumptions considered for the study, download the pdf brochure
Market Size Estimation
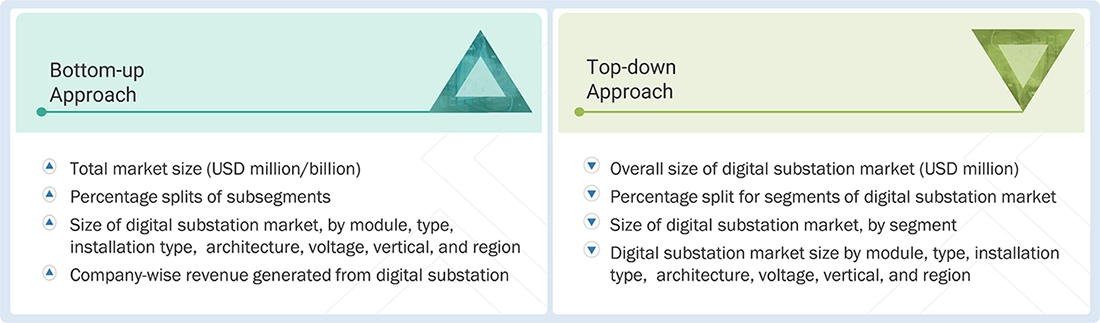
Both top-down and bottom-up approaches were used to estimate and validate the total size of the digital substation market. These methods have also been used extensively to estimate the size of various subsegments in the market. The following research methodology was used to estimate the market size:
- Major players in the digital substation market and related markets were identified through extensive secondary research.
- The industry’s value chain and market size in terms of value and volume were determined through primary and secondary research processes.
- All percentage shares, splits, and segment-level breakdowns were determined using secondary sources and verified through primary research and data triangulation.
Digital Substation Market: Top-Down and Bottom-Up Approach
Data Triangulation
After arriving at the overall size of the digital substation market through the market size estimation process, the total market was divided into relevant segments and subsegments. Data triangulation and market breakdown procedures were employed, where applicable, to complete the market engineering process and derive statistics for each segment and subsegment. The data were triangulated by evaluating factors and trends from the demand and supply sides, including grid modernization investments, digitalization of transmission and distribution networks, renewable energy integration, substation automation adoption, product deployments, technology developments, utility requirements, and regional trends. The analysis considered key digital substation technologies such as IEC 61850-based communication, intelligent electronic devices (IEDs), protection and control systems, process-bus technology, merging units, SCADA, digital monitoring, automation systems, and cybersecurity solutions. Digital substation applications across transmission, distribution, renewable energy, industrial, and infrastructure sectors were also considered. The market size was validated using top-down and bottom-up approaches to ensure consistency across the overall market and individual segments.
Market Definition
Digital substations refer to electrical substations that use digital communication, intelligent electronic devices, automated protection and control systems, and advanced monitoring technologies to acquire, transmit, process, and exchange electrical and operational data. Unlike conventional substations that rely extensively on point-to-point copper wiring, digital substations use Ethernet-based communication and IEC 61850 process-bus architectures to transmit measurements, status information, and control signals between field equipment and protection and control systems.
Digital substations play an important role in grid modernization, renewable-energy integration, distributed energy resources, and improving power-system reliability and operational efficiency. Process-bus architectures can replace extensive copper connections with standardized digital communication, while merging units convert current and voltage measurements into digital signals for use by protection and control IEDs. These capabilities support improved interoperability, reduced wiring requirements, remote diagnostics, condition-based maintenance, and more flexible substation configurations.
Key Stakeholders
- Primary equipment manufacturers (transformers, switchgear, circuit breakers, etc.)
- Intelligent electronic device (IED) manufacturers
- Supervisory control and data acquisition (SCADA) solution providers
- Communication network providers
- Engineering, procurement & construction (EPC) firms/system integrators
- Power utility companies
- Turnkey contractors
- Distributors and traders
- Research organizations
- Regulatory bodies & government energy agencies
- Forums, alliances, and associations
Report Objectives
- To define, analyze, and forecast the digital substation market size by module, type, installation type, voltage, architecture type, industry, and region, in terms of value
- To define, analyze, and forecast the market size, by hardware, in terms of volume
- To forecast the market size for various segments with respect to four main regions, namely North America, Europe, Asia Pacific, and RoW, in terms of value
- To provide detailed information regarding the major drivers, restraints, opportunities, and challenges influencing the market growth
- To study the complete supply chain and related industry segments for the market
- To strategically study the micro markets with respect to individual growth trends, prospects, and contributions to the total market
- To analyze the supply chain, market ecosystem, trends/disruptions impacting customers’ business, technology analysis, pricing analysis, Porter’s five forces model, key stakeholders & buying criteria, case study analysis, trade analysis, patent analysis, key conferences & events, regulations, and investment and funding scenario
- To understand opportunities in the market for various stakeholders by identifying the high-growth segments of the market
- To strategically profile the key players and comprehensively analyze their market position in terms of ranking, core competencies, company valuation and financial metrics, and product/brand comparison, along with detailing the competitive landscape for the market leaders
- To analyze competitive developments such as product launches, agreements, partnerships, collaborations, contracts, acquisitions, expansions, and research and development (R&D) activities carried out by players in the market
Available customizations:
With the given market data, MarketsandMarkets offers customizations according to the company’s specific needs. The following customization options are available for the report:
Company Information
-
Detailed analysis and profiling of additional market players (up to 5)
Get the Full Digital Substation Market Report
Full forecast, segment splits, and company analysis for all Digital Substation Market.
- Canada Digital Substation Market
- Mexico Digital Substation Market
- US Digital Substation Market
- UK Digital Substation Market
- France Digital Substation Market
- Italy Digital Substation Market
- Spain Digital Substation Market
- Poland Digital Substation Market
- China Digital Substation Market
- Japan Digital Substation Market
- South Korea Digital Substation Market
- India Digital Substation Market
- Australia Digital Substation Market
- Indonesia Digital Substation Market
- Malaysia Digital Substation Market
- Thailand Digital Substation Market
- Vietnam Digital Substation Market
- Nordics Digital Substation Market
- Rest Of Europe Digital Substation Market
- Rest Of Asia Pacific Digital Substation Market
- Bahrain Digital Substation Market
- Kuwait Digital Substation Market
- Oman Digital Substation Market
- Qatar Digital Substation Market
- Rest Of Middle East Digital Substation Market
- Saudi Arabia Digital Substation Market
- UAE Digital Substation Market
- Rest Of Africa Digital Substation Market
- South Africa Digital Substation Market
Need a Tailored Report?
Customize this report to your needs
Get 10% FREE Customization
Customize This Report