Asia Pacific Display Module Market (2026-2031)
The Asia Pacific Display Module Market was valued at $69500 Million in 2026 and projected to reach to $82840 Million by 2031, representing a compound annual growth rate of CAGR 3.0%. Asia Pacific's display module market is positioned for sustained growth through 2031, driven by escalating consumer electronics demand, smartphone proliferation, and the region's dominance in manufacturing infrastructure.

| Market Size in | USD 26.32 MN |
| Market Forecast in | |
| CAGR | |
| Forecast Period | |
| Units Considered | Value (USD MN) |
Asia Pacific Display Module Market Trends and Insights
- The region's market size is estimated at $69,500 million in 2026 and is forecast to grow to $82,840 million by 2031, representing a compound annual growth rate (CAGR) of 3.0%.
- This growth trajectory reflects Asia Pacific's position as a manufacturing and consumption hub for consumer electronics, automotive displays, and industrial applications. The Asia Pacific display module market is driven by rapid urbanization, increasing smartphone penetration, and rising adoption of advanced display technologies across the region.
- Asia Pacific's strong electronics manufacturing ecosystem, coupled with investments in next-generation display solutions, supports sustained market expansion through 2031.
- Key markets within Asia Pacific, including China, Japan, South Korea, and Southeast Asia, continue to innovate in OLED, LCD, and emerging display technologies, reinforcing the region's competitive advantage. Asia Pacific's growth outpaces the global average, underscoring the region's critical role in the display module supply chain and end-user demand.
- Strategic partnerships, technological advancements, and regional supply chain resilience position Asia Pacific as the primary growth engine for the global display module market between 2026 and 2031..
Key Market Statistics
- CAGR (2026-2031) CAGR 3.0%
- Market Size, 2026 ~USD 69500 Million
- Forecast, 2031 ~USD 82840 Million
- Geography Asia Pacific
Asia Pacific Display Module Market Overview
Market Dominance :
Asia Pacific commands the largest share of the global display module market, driven by China's manufacturing prowess and Japan's advanced technology leadership in semiconductor display solutions.
Robust Growth Trajectory :
The region is projected to grow from $69,500 million in 2026 to $82,840 million by 2031, with a 3.0% CAGR outpacing the global average of 2.6%, reflecting strong regional demand.
China's Market Leadership :
China alone represents $43,540 million of the Asia Pacific market in 2026, accounting for over 62% of regional demand and serving as the primary manufacturing and consumption hub.
Diversified Growth Engines :
Japan ($13,020M), South Korea ($9,440M), and India ($6,850M) provide complementary growth drivers, with emerging markets in Southeast Asia contributing additional expansion opportunities.
Asia Pacific Display Module Market Dynamics
- China's continued investment in display technology and production capacity, combined with Japan's innovation in advanced display solutions, creates a competitive advantage that attracts global investment and talent. The region benefits from established supply chains, cost-competitive manufacturing, and growing adoption of display modules in automotive, IoT, and industrial applications.
- India's emerging market potential and Southeast Asia's expanding middle class present untapped opportunities.
- Strategic partnerships between regional manufacturers and global technology leaders will further accelerate market penetration and technological advancement across Asia Pacific..
Market Ecosystem
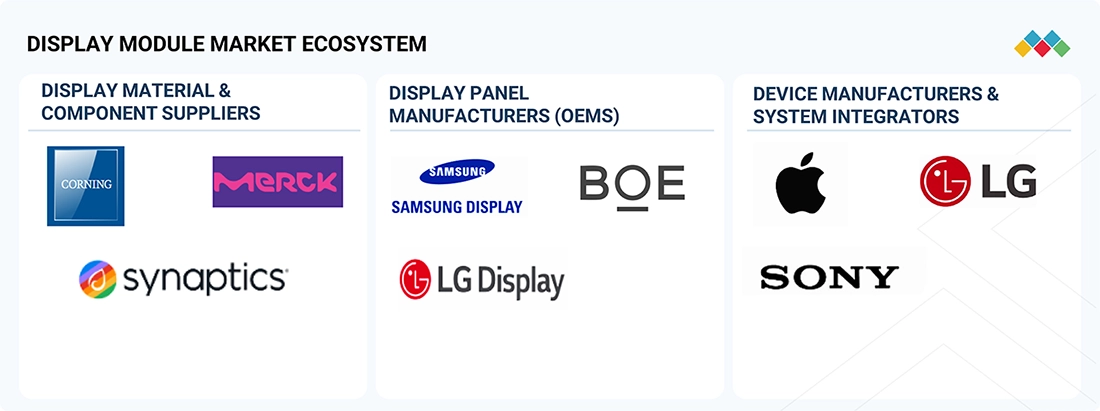
DISPLAY MODULE MARKET: COMMERCIAL USE CASES ACROSS INDUSTRIES
| COMPANY | USE CASE DESCRIPTION | BENEFITS |
|---|---|---|
 |
Expanding OLED, AMOLED, and foldable display modules for smartphones, automotive displays, IT devices, and XR applications, with a focus on thinner, energy-efficient, and high-performance modules | Enhanced display quality and power efficiency | Advanced flexible display solutions | Stronger premium product positioning |
 |
Increasing production of OLED, Mini-LED, and flexible display modules while expanding manufacturing capacity for consumer electronics, automotive, and industrial applications | Higher production scalability | Improved display module performance | Expanded customer reach |
 |
Developing OLED and large-format display modules for TVs, automotive, gaming, and commercial applications with enhanced brightness, durability, and energy efficiency | Superior visual performance | Improved energy efficiency | Broader adoption in premium and automotive applications |
Logos and trademarks shown above are the property of their respective owners. Their use here is for informational and illustrative purposes only.
Related Ecosystem
Display Technology
- Augmented Reality
- Liquid Crystal Display (LCD)
- Sensors
- Virtual Reality Devices
- Liquid Crystal on Silicon (LCOS)
- VIVITEK CORPORATION
- Samsung
- Lenovo
- Panasonic Holdings Corporation
- Lg corp
Key Takeaways
- Asia Pacific display module market valued at $69.5B in 2026, expanding to $82.8B by 2031 at 3.0% CAGR
- Asia Pacific's growth rate outpaces global average, driven by manufacturing dominance and consumer electronics demand
- China, Japan, South Korea, and Southeast Asia lead innovation in OLED, LCD, and emerging display technologies
- Asia Pacific's integrated supply chain and urbanization trends position it as the primary growth engine through 2031
Display Module Market Report Scope
| Report Metric | Details |
|---|---|
| Base Year | 2026 |
| Fastest Growing Segment | MICROLED (Display Technology) |
| Forecast Period | 2026-2031 |
| Growth Rate | CAGR of 2.6% from 2026 to 2031 |
| Largest Segment | ELECTRONIC (NON-OPTICAL) (Type) |
| Market Size Base Year (Billions) | ~USD 137 (2026) |
| Revenue Forecast (Billions) | ~USD 155.76 (2031) |
| Segments Covered | Type, Display Technology, Display Type, Product Type, Technology, Electronic Type, End Use, Display Size |
Asia Pacific Display Module Market Report Segmentation
8 segment dimensions are covered across the global market.
By Type
- Electronic (Non-Optical)
- Optical
- Other Non-Optical Module-Based Products
- Smartphones
- Tablets, Monitors & Laptops
By Display Technology
- Dlp
- E-Paper
- Laser Beam Scanning
- Laser-Beam Scanning
- Lcd
- Lcos
- Led
- Microled
- Oled
- Oledos
- Other Optical Display Technologies
- Tft Lcd
By Display Type
- Ar
- Vr & Mr
By Product Type
- Hmds
- Huds
- Other Non-Optical Module-Based Products
- Smartphones
- Tablets, Monitors & Laptops
By Technology
- Dlp
- Laser Beam Scanning
- Oled
By Electronic Type
- Other Non-Optical Module-Based Products
- Smartphones
- Tablets, Monitors & Laptops
- Tablets, Monitors, & Laptops
By End Use
- Aerospace & Defense
- Automotive
- Consumer Electronics
- Education
- Healthcare
- Industrial
- Other End Uses
- Retail, Hospitality & Bfsi
- Sports & Entertainment
- Transportation
By Display Size
- 0.5-1 Inch
- Less Than 0.5 Inch
- Microdisplays
- More Than 1 Inch
- More Than 9 Inches
- Up To 9 Inches
Target Audience
- Display Module Manufacturers : Manufacturers need Asia Pacific market data to optimize production capacity, identify growth markets, and develop region-specific product strategies for LCD, OLED, and emerging display technologies.
- Electronics OEMs : Original equipment manufacturers require detailed regional insights to source display modules competitively, manage supply chains across Asia Pacific, and forecast component costs.
- Investment & Private Equity Firms : Investors need comprehensive Asia Pacific market analysis to identify acquisition targets, evaluate growth potential, and assess competitive dynamics in the semiconductor display sector.
- Technology & Strategy Consultants : Consultants leverage regional market data to advise clients on market entry strategies, competitive positioning, and technology trends specific to Asia Pacific's display module ecosystem.
- Supply Chain & Procurement Teams : Procurement professionals use country-level market intelligence to negotiate supplier contracts, diversify sourcing across Asia Pacific, and optimize total cost of ownership.
Countries within Asia Pacific - compare and drill down
| Country | 2025 size (native) |
|---|---|
| China | USD 43540 Million |
| Japan | USD 13020 Million |
| South Korea | USD 9440 Million |
| Taiwan | USD 6270 Million |
| India | USD 6850 Million |
| Rest Of Asia Pacific | USD 3720 Million |
Country market size visualization
Reasons to Buy this Report
- Regional Market Sizing : Obtain precise market valuations for Asia Pacific and individual countries including China ($43.5B), Japan ($13.0B), and South Korea ($9.4B) to benchmark competitive positioning.
- Growth Opportunity Identification : Identify high-growth segments within Asia Pacific's 3.0% CAGR trajectory, with detailed insights into emerging markets like India and Southeast Asia for expansion strategies.
- Competitive Intelligence : Analyze regional manufacturing hubs, supply chain dynamics, and technology leadership across key markets to inform sourcing, partnership, and investment decisions.
- Demand Forecasting : Leverage 2026-2031 projections for Asia Pacific to optimize production planning, inventory management, and market entry timing across the region's diverse economies.
- Strategic Market Entry : Develop targeted go-to-market strategies for Asia Pacific by understanding country-specific market sizes, growth rates, and consumption patterns across the semiconductor display sector.
Frequently asked questions
What is the current size of the Asia Pacific display module market in 2026?
The Asia Pacific display module market is estimated at $69,500 million in 2026, representing a significant portion of global display module demand.
What is the projected market size for Asia Pacific display modules by 2031?
Asia Pacific's display module market is forecast to reach $82,840 million by 2031, reflecting a 3.0% CAGR over the forecast period.
How does Asia Pacific's growth rate compare to the global display module market?
Asia Pacific's 3.0% CAGR exceeds the global average of 2.6%, demonstrating the region's accelerated market expansion and strategic importance.
Which countries drive the Asia Pacific display module market?
China, Japan, South Korea, and Southeast Asian nations are primary drivers, leveraging advanced manufacturing capabilities and consumer demand for display technologies.
What factors support growth in the Asia Pacific display module market through 2031?
Key growth drivers include urbanization, smartphone penetration, automotive display adoption, industrial applications, and investments in next-generation display technologies like OLED.
RESEARCH METHODOLOGY
The study involved four major activities in estimating the current size of the display module market. Exhaustive secondary research was conducted to gather information on the market, adjacent markets, and the overall high-end refractometer landscape. These findings, along with assumptions and projections, were validated through primary research involving interviews with industry experts and key stakeholders across the value chain. Both top-down and bottom-up approaches were utilized to estimate the overall market size. Subsequently, market breakdown and data triangulation techniques were applied to determine the sizes of various segments and subsegments. Two key sources, secondary and primary, were leveraged to conduct a comprehensive technical and commercial assessment of the display module market.
Secondary Research
The secondary research process referred to various secondary sources to identify and collect necessary information for this study. The secondary sources included annual reports, press releases, and investor presentations of companies; white papers; journals and certified publications; and articles from recognized authors, websites, directories, and databases. Secondary research was conducted to obtain key information about the industry’s supply chain, the market’s value chain, the total pool of key players, market segmentation according to the industry trends (to the bottom-most level), regional markets, and key developments from market- and technology-oriented perspectives. The secondary data was collected and analyzed to determine the overall market size, which is further validated through primary research.
Primary Research
Extensive primary research was conducted after gaining knowledge about the current scenario of the display module market through secondary research. Several primary interviews were conducted with experts from the demand and supply sides across five major regions—North America, Europe, Asia Pacific, and the RoW. This primary data was collected through questionnaires, emails, and telephonic interviews.
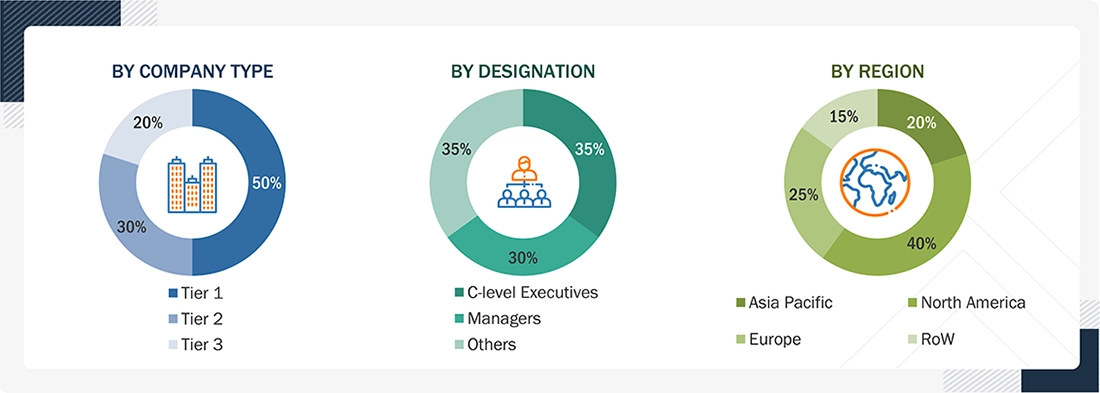
Notes: The three tiers of companies have been defined based on their total revenue as of 2025. The categorization given below has been applied:
To know about the assumptions considered for the study, download the pdf brochure
Market Size Estimation
In the complete market engineering process, top-down and bottom-up approaches and several data triangulation methods were used to estimate and forecast the overall market segments and subsegments listed in this report. Key players in the market were identified through secondary research, and their market shares in the respective regions were determined through primary and secondary research. This entire procedure included the study of annual and financial reports of the top market players and extensive interviews for key insights (quantitative and qualitative) with industry experts (CEOs, VPs, directors, and marketing executives).
All percentage shares, splits, and breakdowns were determined using secondary sources and verified through primary sources. All the parameters affecting the markets covered in this research study were accounted for, viewed in detail, verified through primary research, and analyzed to obtain the final quantitative and qualitative data. This data was consolidated and supplemented with detailed inputs and analysis from MarketsandMarkets and presented in this report.
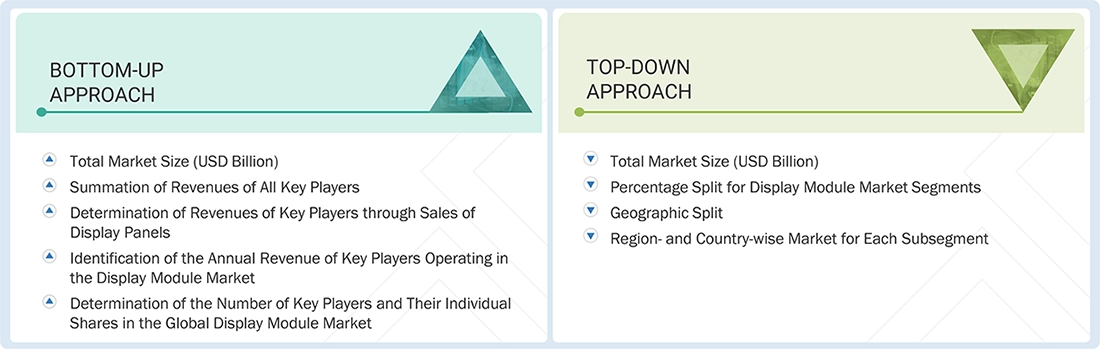
- Approach to arrive at market size using bottom-up analysis (demand side)
- Companies offering display panels were identified, and their offerings were mapped based on technology and panel size footprint.
- The global display module market size was derived through the data sanity method. The revenues of display panel providers were analyzed through annual reports and press releases and summed up to derive the overall market size.
- For each company, a percentage was assigned to the overall revenue to derive the revenues from display panels.
- Each company’s percentage was assigned after analyzing various factors, including its product offerings, geographic presence, R&D expenditures and initiatives, and recent developments/strategies adopted for growth in the display module market.
- For the CAGR, the market trend analysis of display panels was carried out by understanding the industry penetration rate and the demand and supply of display panels to different verticals.
- Estimates at every level were verified and cross-checked by discussing them with key opinion leaders, including sales heads, directors, operations managers, and market domain experts of MarketsandMarkets.
- Various paid and unpaid information sources, such as annual reports, press releases, white papers, and databases, were studied.
The top-down approach was used to estimate and validate the total size of the display module market.
- Focusing initially on the top-line investments and expenditures being made in the ecosystem of displays, further splitting into display technology, product type, display size, end-use industry, and display resolution, and listing key developments in key market areas
- Identifying all major players in the display module market and their product portfolio for various verticals through secondary research, as well as verifying with a brief discussion with industry experts
- Analyzing revenues, product mix, geographic presence, and key verticals for which all identified players serve, display products/technologies to estimate and arrive at the percentage splits for all key segments
- Discussing these splits with the industry experts to validate the information and identify key growth pockets across all key segments
- Breaking down the total market based on verified splits and key growth pockets across all segments
The market size was arrived at using the following approaches:
Data Triangulation
After estimating the overall market size, the label identification market was classified into subsegments. The overall market engineering process was finalized through data triangulation and market segmentation, yielding accurate statistics for all segments and subsegments. This triangulation involved analyzing various trends and factors on both the demand and supply sides. Furthermore, label identification market data were verified and validated using both top-down and bottom-up approaches.
Market Definition
The label identification market comprises technologies, instruments, software, and consumables used to accurately identify, authenticate, and track biological, chemical, and material samples in laboratory environments. These technologies include barcode and RFID systems, laboratory information management systems (LIMS), sample labeling and tracking solutions, molecular identification technologies, microbial identification systems, and automated data management platforms. Label identification is widely used across pharmaceutical and biotechnology companies, clinical and diagnostic laboratories, academic and research institutes, food and beverage testing, environmental testing, and forensic laboratories to improve sample traceability, workflow efficiency, regulatory compliance, data integrity, and the accuracy of analytical and diagnostic results.
Key Stakeholders
- Research & Development Directors
- Analytical Laboratory Managers
- Scientists
- Quality Control (QC) Managers
- Quality Assurance (QA) Directors
- Procurement Managers
- Supply Chain Managers
- Bioprocessing Managers
- Manufacturing Operations Directors
- Clinical Research Managers
- Product Development Scientists
- Regulatory Affairs Managers
- Laboratory Directors
- Sales & Marketing Directors
- CRO/CDMO Operations Managers
Report Objectives
- To define, describe, and forecast the size of the label identification market based on product type, technology, application, and region
- To provide detailed information regarding the factors influencing the growth potential of the global label identification market (drivers, restraints, opportunities, challenges, and trends)
- To analyze micromarkets with respect to individual growth trends, prospects, and contributions to the global label identification market
- To analyze key growth opportunities in the global label identification market for key stakeholders and provide details of the competitive landscape for market leaders
- To forecast the size of market segments and/or subsegments concerning five regions, namely, North America (US and Canada), Europe (Germany, France, the UK, Spain, Italy, and the Rest of Europe), Asia Pacific (Japan, China, India, Australia, South Korea, and the Rest of Asia Pacific), Latin America (Brazil, Mexico, and the Rest of Latin America), and the Middle East & Africa (GCC Countries and the Rest of Middle East & Africa)
- To profile the key players in the label identification market and comprehensively analyze their market shares and core competencies
- To track and analyze the competitive developments undertaken in the global label identification market, such as product launches/approvals, agreements, expansions, collaborations, and acquisitions.
Available customizations:
With the market data given, MarketsandMarkets offers customizations according to the company’s specific needs. The following customization options are available for the report:
Company Information:
- Detailed analysis and profiling of additional market players (up to five)
Get the Full Display Module Market Report
Full forecast, segment splits, and company analysis for all Display Module Market.
- US Display Module Market
- Canada Display Module Market
- Mexico Display Module Market
- Germany Display Module Market
- UK Display Module Market
- France Display Module Market
- Italy Display Module Market
- China Display Module Market
- Japan Display Module Market
- South Korea Display Module Market
- Taiwan Display Module Market
- India Display Module Market
- Rest Of Europe Display Module Market
- Rest Of Asia Pacific Display Module Market
- GCC Countries Display Module Market
Need a Tailored Report?
Customize this report to your needs
Get 10% FREE Customization
Customize This Report