North America Enterprise Imaging IT Market (2025-2030)
The North America Enterprise Imaging IT Market was valued at $881.4 Million in 2025 and projected to reach to $1552.6 Million by 2030, representing a compound annual growth rate of 12.0%. North America's Enterprise Imaging IT market is poised for sustained expansion through 2030, driven by healthcare systems' urgent need to modernize legacy imaging infrastructure and adopt integrated, cloud-enabled solutions.

| Market Size in | USD 26.32 MN |
| Market Forecast in | |
| CAGR | |
| Forecast Period | |
| Units Considered | Value (USD MN) |
North America Enterprise Imaging IT Market Trends and Insights
- North America's healthcare sector is increasingly adopting advanced imaging IT solutions to enhance diagnostic accuracy, streamline workflows, and improve patient outcomes.
- This growth trajectory reflects North America's strong investment in digital health infrastructure and the region's commitment to modernizing medical imaging capabilities across hospitals, diagnostic centers, and specialty clinics. Driving North America's market expansion are regulatory compliance requirements, the shift toward value-based care models, and integration of artificial intelligence in imaging workflows.
- North America's mature healthcare market and high technology adoption rates position the region as a leader in enterprise imaging innovation.
- Between 2025 and 2030, North America will continue to see significant capital allocation toward cloud-based imaging platforms, interoperability solutions, and advanced analytics tools that support clinical decision-making and operational efficiency..
Key Market Statistics
- CAGR (2025-2030) 12.0% CAGR
- Market Size, 2025 ~USD 881.4 Million
- Forecast, 2030 ~USD 1552.6 Million
- Geography North America
North America Enterprise Imaging IT Market Overview
Market Leadership :
North America commands the largest share of the global Enterprise Imaging IT market, driven by advanced healthcare infrastructure, high adoption of digital solutions, and significant investment in medical imaging technologies across the US and Canada.
Robust Growth Trajectory :
The region is experiencing 12.0% CAGR from 2025 to 2030, outpacing many global peers. This growth is fueled by increasing demand for integrated imaging platforms, AI-powered diagnostic tools, and cloud-based imaging solutions in North American healthcare systems.
US Market Dominance :
The United States represents $1,407.7 million of the North American market, accounting for approximately 90% of regional revenue. Strong healthcare spending, regulatory support, and technological innovation drive sustained expansion in US enterprise imaging IT adoption.
Regulatory & Innovation Environment :
North America benefits from favorable regulatory frameworks, FDA approvals for advanced imaging solutions, and substantial R&D investments. Healthcare providers prioritize interoperability, data security, and workflow optimization, accelerating enterprise imaging IT implementation.
North America Enterprise Imaging IT Market Dynamics
- Major US healthcare networks and Canadian provincial health systems are increasingly investing in AI-powered diagnostic platforms, enterprise-wide PACS systems, and mobile imaging access to enhance clinical efficiency and patient care quality. The region's growth will be supported by rising healthcare expenditures, aging population demographics requiring advanced diagnostic capabilities, and regulatory incentives for digital health transformation.
- Consolidation among healthcare providers and increased partnerships between imaging IT vendors and healthcare systems will further accelerate market penetration, positioning North America as the global leader in enterprise imaging IT innovation and adoption through 2030..
Market Ecosystem
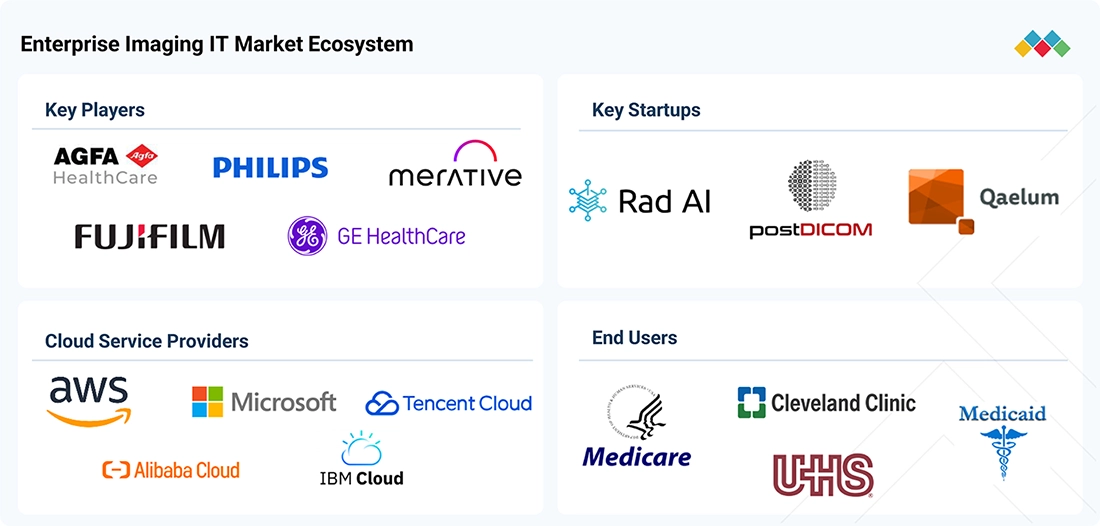
ENTERPRISE IMAGING IT MARKET: COMMERCIAL USE CASES ACROSS INDUSTRIES
| COMPANY | USE CASE DESCRIPTION | BENEFITS |
|---|---|---|
 |
Deploy Centricity/VNA + Universal Viewer to unify radiology, cardiology and clinical images into a single patient timeline used for tumor boards and perioperative planning | Single patient timeline; faster MDT decisions; fewer repeat scans |
 |
Replace multiple PACS with Synapse Enterprise Imaging + Synapse 3D to give radiology and surgical teams one workflow for advanced visualization (oncology, vascular, neuro) | Streamlined pre-op planning; consistent 3D tools across sites; faster clinician adoption |
 |
Implement Sectra VNA and secure exchange to enable referral networks, second opinions and centralized reading | Secure sharing; faster referrals; reduced duplicate imaging |
 |
Consolidate imaging and apply Vitrea analytics (CT/MR quantification) for disease tracking (cardio/oncology) across the enterprise | Quantified follow-up metrics; consistent measurements; faster clinical decisions |
 |
IntelliSpace Enterprise Imaging consolidates studies across hospital networks and embeds analytics/quantification into the reading workflow | Standardized workflows; faster KPI tracking; embedded decision support |
Logos and trademarks shown above are the property of their respective owners. Their use here is for informational and illustrative purposes only.
Related Ecosystem
Diagnostic Imaging
- Magnetic Resonance Imaging (MRI)
- Computed Tomography (CT)
- CT Scanners
- Nuclear Imaging
- Positron Emission Tomography
- Siemens healthineers
- PHILIPS HEALTHCARE
- CANON INC.
- FUJIFILM Holdings Corporation
- UNITED IMAGING HEALTHCARE CO., LTD.
Healthcare It
- Computed Tomography (CT)
- Machine Learning
- Magnetic Resonance Imaging (MRI)
- Natural Language Processing (NLP)
- Predictive Analytics
- CERNER CORPORATION
- PHILIPS HEALTHCARE
- Oracle Corporation
- GE HealthCare Technologies Inc.
- Siemens healthineers
Medical Devices
- Polymerase Chain Reaction (PCR)
- Magnetic Resonance Imaging (MRI)
- Disposable Autoinjectors
- Pulse Oximeters
- Blood Pressure Monitors
- Medtronic plc
- Abbott Laboratories
- Stryker Corporation
- Becton, Dickinson and Company
- JOHNSON & JOHNSON
Key Takeaways
- North America's Enterprise Imaging IT Market will grow from $881.4M (2025) to $1,552.6M (2030) at a 12.0% CAGR.
- North America leads in AI-driven imaging solutions and cloud-based platform adoption within the healthcare sector.
- Regulatory compliance and value-based care models are primary growth catalysts for North America's imaging IT investments.
- North America's mature healthcare infrastructure and high technology adoption rates support sustained market expansion through 2030.
Enterprise Imaging IT Market Report Scope
| Report Metric | Details |
|---|---|
| Base Year | 2025 |
| Fastest Growing Segment | COMPUTED TOMOGRAPHY (CT) (Modality) |
| Forecast Period | 2025–2030 |
| Growth Rate | CAGR of 12.2% from 2025 to 2030 |
| Largest Segment | SOFTWARE (Offering) |
| Market Size Base Year (Billions) | ~USD 2.32 (2025) |
| Revenue Forecast (Billions) | ~USD 4.12 (2030) |
| Segments Covered | Function, Application, Modality, Type, Offering, Deployment Mode, Therapeutic Area, End User |
North America Enterprise Imaging IT Market Report Segmentation
8 segment dimensions are covered across the global market.
By Function
- Analytics
- Image Exchange
- Other Functions
- Picture Archiving And Communication Systems (Pacs)
- Universal Viewers
- Vendor Neutral Archives (Vna)
- Workflow Orchestration
By Application
- Clinical Research
- Diagnostics
- Therapeutics
By Modality
- Computed Tomography (Ct)
- Echocardiography
- Endoscopy
- Fluoroscopy
- Magnetic Resonance Imaging (Mri)
- Mammography
- Nuclear Imaging
- Other Modalities
- Ultrasound
- X-Ray
By Type
- Pet
- Pet (Positron Emission Tomography)
- Spect
- Spect (Single-Photon Emission Computed Tomography)
By Offering
- Services
- Software
By Deployment Mode
- Cloud-Based Solutions
- Hybrid Solutions
- On-Premise Solutions
By Therapeutic Area
- Cardiology
- Neurology
- Oncology
- Orthopedics
- Other Therapeutic Areas
By End User
- Clinics & Outpatient Settings
- Diagnostic Centers
- Hospitals
- Medtech Companies
- Other End Users
- Pharmaceutical & Biotechnology Companies
- Research & Academic Institutes
Target Audience
- Healthcare IT Vendors : Enterprise imaging IT solution providers need North America market intelligence to refine product roadmaps, prioritize feature development, and allocate sales resources across the US and Canadian markets where demand is highest.
- Healthcare System Executives : Hospital networks and integrated delivery systems require market data to justify imaging IT investments, benchmark against peer institutions, and make informed procurement decisions aligned with regional growth trends.
- Investment & Private Equity Firms : Investors evaluating healthcare IT opportunities need North America market sizing and growth forecasts to assess portfolio companies, identify acquisition targets, and evaluate return potential in enterprise imaging IT.
- Technology Consultants : Healthcare IT consultants advising on digital transformation initiatives require regional market insights to recommend appropriate imaging solutions, assess vendor viability, and align technology strategies with North American market dynamics.
- Medical Device & Imaging Equipment Manufacturers : Imaging hardware and software manufacturers need North America market data to understand IT infrastructure requirements, identify integration opportunities, and develop complementary solutions for healthcare providers.
Key Companies in the North America Enterprise Imaging IT Market
| Company | HQ | Ownership | Strongest segments |
|---|---|---|---|
| AGFA-GEVAERT GROUP | Belgium | Public Company | Healthcare enterprise imaging platform and software,Diagnostic imaging hardware, X-ray film, and hardcopy,Sign, display, and packaging printers, inks, and software, |
| FUJIFILM HOLDINGS CORPORATION | Japan | Public Company | Healthcare (medical systems, CDMO, pharma, regenerative medicine, cosmetics/supplements),Electronics (display, semiconductor and image sensor materials, storage, industrial equipment, fine chemicals),Business Innovation (office equipment, document solutions, graphic communications, inkjet), |
| GE HEALTHCARE | United States | Public Company | Imaging,Advanced Visualization Solutions (AVS),Patient Care Solutions (PCS), |
| KONINKLIJKE PHILIPS N.V. | Netherlands | Public Company | Diagnostic Imaging (MRI, CT, Diagnostic X-ray, Ultrasound),Image Guided Therapy (Systems and Devices),Connected Care (Monitoring, Enterprise Informatics, Sleep & Respiratory Care), |
| SIEMENS HEALTHINEERS AG | Germany | Public Company | Imaging,Diagnostics,Varian (Oncology), |
| SECTRA AB | Sweden | Public Company | Imaging IT Solutions,Secure Communications,Business Innovation, |
| PRO MEDICUS, LTD. | Australia | Public Company | Visage 7 Enterprise Imaging Platform (incl. PACS/digital imaging),Visage RIS and practice management services,Mobile viewers (Visage Ease, Visage Ease Pro) and e-health platform (Promedicus.net), |
| HYLAND SOFTWARE, INC. | United States | Private Company | OnBase platform (content, process, case management),Healthcare imaging and interoperability (Hyland Healthcare, Acuo, NilRead, PACSgear, OnBase Mackinac),Intelligent capture, search, and developer toolkits (Brainware, Enterprise Search, Document Filters), |
| INFINITT HEALTHCARE CO., LTD. | South Korea | Public Company | Core Imaging IT (PACS, VNA, Enterprise Viewer, Unified Worklist),Advanced Visualization & AI (Xelis Fusion, Advanced Visualization and AI, Lunit INSIGHT integrations),Clinical Workflow & Reporting (INFINITT Results, Exam Quality Reporting, DoseM, CDS, portals), |
| MACH7 TECHNOLOGIES | United States | Public Company | Vendor-neutral archive (VNA) and data management,eUnity enterprise diagnostic viewer,Workflow applications and universal worklist, |
AGFA-GEVAERT GROUP
AGFA-GEVAERT GROUP is a Belgian public company founded in 1867 with 4,211 employees. The company operates as a multinational corporation with a long-established history in imaging and healthcare technology.
FUJIFILM HOLDINGS CORPORATION
FUJIFILM HOLDINGS CORPORATION is a Japanese public company founded in 1934 with 73,526 employees. The company is a major multinational corporation operating across multiple business segments including imaging and healthcare solutions.
GE HEALTHCARE
GE HEALTHCARE is a United States-based public company founded in 2022 with 54,000 employees. The company operates as a significant player in the healthcare technology and medical equipment sector.
KONINKLIJKE PHILIPS N.V.
KONINKLIJKE PHILIPS N.V. is a Dutch public company founded in 1891 with 63,670 employees. The multinational corporation is a major provider of healthcare technology, consumer electronics, and lighting solutions.
SIEMENS HEALTHINEERS AG
SIEMENS HEALTHINEERS AG is a German public company founded in 1896 with 72,369 employees. The company is a leading multinational provider of medical imaging, diagnostics, and healthcare IT solutions.
SECTRA AB
SECTRA AB is a Swedish public company founded in 1957 with 1,365 employees. The company specializes in medical imaging and IT solutions for the healthcare industry.
PRO MEDICUS, LTD.
PRO MEDICUS, LTD. is an Australian public company founded in 1983 with 132 employees. The company provides medical imaging software and healthcare IT solutions.
HYLAND SOFTWARE, INC.
HYLAND SOFTWARE, INC. is a United States-based private company founded in 1991 with 336 employees. The company provides content management and healthcare information solutions.
INFINITT HEALTHCARE CO., LTD.
INFINITT HEALTHCARE CO., LTD. is a South Korean public company founded in 2002 with 246 employees. The company develops and provides healthcare IT and medical imaging solutions.
MACH7 TECHNOLOGIES
MACH7 TECHNOLOGIES is a United States-based public company founded in 2007 with an undisclosed employee count. The company provides medical imaging and healthcare IT solutions.
Countries within North America - compare and drill down
| Country | 2025 size (native) |
|---|---|
| US | USD 1407.7 Million |
| Canada | USD 144.9 Million |
Country market size visualization
Reasons to Buy this Report
- Market Size & Valuation Data : Access precise market sizing for North America ($881.4M in 2025) and country-level breakdowns for the US and Canada, enabling accurate financial forecasting and investment decisions for enterprise imaging IT solutions.
- Regional Growth Insights : Understand the 12.0% CAGR trajectory specific to North America and identify key drivers of growth in US and Canadian healthcare systems, including regulatory changes, technology adoption rates, and competitive dynamics.
- Competitive Landscape Analysis : Benchmark your enterprise imaging IT offerings against regional competitors and identify market gaps, customer pain points, and opportunities for differentiation in the North American healthcare sector.
- Strategic Market Positioning : Develop targeted go-to-market strategies for the US and Canadian markets with data-driven insights on healthcare provider priorities, budget allocation trends, and technology preferences specific to North America.
- Investment & Partnership Opportunities : Identify high-growth segments, emerging vendors, and acquisition targets within North America's enterprise imaging IT ecosystem to guide M&A strategy and partnership development.
Frequently asked questions
What is the current size of the Enterprise Imaging IT Market in North America?
The North America Enterprise Imaging IT Market is valued at $881.4 million in 2025 and is expected to reach $1,552.6 million by 2030.
What is the projected growth rate for North America's Enterprise Imaging IT Market?
North America's Enterprise Imaging IT Market is projected to grow at a compound annual growth rate (CAGR) of 12.0% from 2025 to 2030.
What are the main drivers of growth in North America's Enterprise Imaging IT Market?
Key growth drivers in North America include regulatory compliance requirements, the transition to value-based care models, AI integration in imaging workflows, and increased adoption of cloud-based imaging platforms.
Which segments are leading North America's Enterprise Imaging IT Market growth?
North America's market growth is led by cloud-based imaging solutions, AI-powered diagnostic tools, interoperability platforms, and advanced analytics systems that enhance clinical workflows and operational efficiency.
How does North America's Enterprise Imaging IT Market compare to global trends?
North America's 12.0% CAGR aligns closely with the global market CAGR of 12.2%, reflecting the region's strong position as a leader in healthcare IT innovation and digital imaging adoption.
RESEARCH METHODOLOGY
This research study involved the extensive use of both primary and secondary sources. It analyzed various factors affecting the industry to identify segmentation types, industry trends, key players, the competitive landscape of market players, and key market dynamics such as drivers, opportunities, challenges, restraints, and key player strategies.
Secondary Research
This research study extensively used secondary sources, including directories, databases such as Dun & Bradstreet, Bloomberg Businessweek, and Factiva, as well as white papers, annual reports, and companies' house documents. The secondary research aimed to gather and analyze information for a comprehensive, commercially focused study of the enterprise imaging IT market, covering technical aspects and market dynamics. It also helped identify key players, market classifications, industry trends, geographic markets, and significant market developments. Additionally, a database of prominent industry leaders was compiled through secondary research.
Primary Research
In the primary research process, various supply-side and demand-side sources were interviewed to gather qualitative and quantitative information for this report. Primary sources from the supply side included industry experts such as CEOs, vice presidents, marketing and sales directors, technology and innovation directors, engineers, and other key executives from companies and organizations operating in the enterprise imaging IT market. Primary sources from the demand side included personnel from hospitals, diagnostic centers, clinics, and outpatient settings (ASCs, ACCs, etc.).
A breakdown of the primary respondents is provided below:
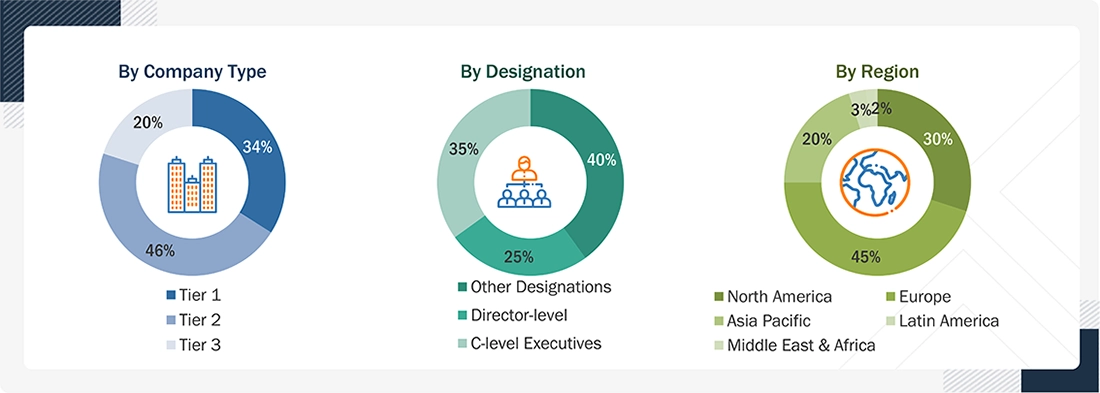
*Others include sales managers, marketing managers, and product managers.
Note: Tiers are defined based on a company’s total revenue, as of 2025: Tier 1 = >USD 1 billion, Tier 2 = USD 500 million to USD 1 billion, and Tier 3 = <USD 500 million.
To know about the assumptions considered for the study, download the pdf brochure
Market Size Estimation
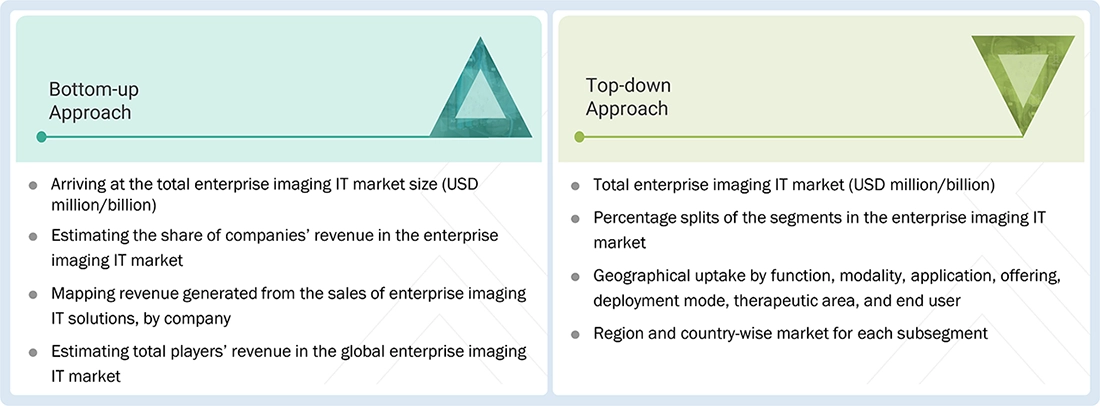
The total size of the enterprise imaging IT market was determined after data triangulation using the two approaches outlined below. After each approach was completed, the results were combined into a weighted average based on the level of assumptions used in each approach.
Enterprise Imaging IT Market: Top-Down and Bottom-Up Approach
Data Triangulation
The size of the enterprise imaging IT market was estimated through segmental extrapolation using the bottom-up approach. The methodology is outlined below.
- Revenue of individual companies was gathered from public sources and databases.
- Shares of leading players in the enterprise imaging IT market were obtained from secondary sources to the extent available. In certain cases, shares of enterprise imaging IT businesses have been ascertained after a detailed analysis of various parameters, including product portfolios, market positioning, selling price, and geographic reach and strength.
- Individual share or revenue estimates were validated through interviews with experts.
- The total revenue in the enterprise imaging IT market was determined by extrapolating the market share data of major companies.
Market Definition
The enterprise imaging IT market comprises software and IT infrastructure solutions that enable seamless management, integration, and sharing of medical images across departments and care settings. It supports unified imaging workflows, enhances clinical collaboration, and improves diagnostic efficiency. This market serves hospitals, diagnostic centers, and integrated delivery networks, with the goal of optimizing image-driven decision-making.
Key Stakeholders
- Vendor neutral archive (VNA) & PACS vendors
- Government bodies
- Healthcare service providers
- Clinical/Physician centers
- Healthcare professionals
- Health IT service providers
- Healthcare associations/institutes
- Ambulatory care centers
- Venture capitalists
- Distributors and resellers
- Maintenance and support service providers
- Integration service providers
- Advocacy groups
- Data security and privacy experts
- Investors and financial institutions
- Industry associations and trade groups
Report Objectives
- To define, describe, and forecast the enterprise imaging IT market by function, modality, application, offering, deployment mode, therapeutic area, end user, and region.
- To provide detailed information regarding the major drivers, restraints, opportunities, and challenges influencing market growth
- To strategically analyze micromarkets1 with respect to individual growth trends, prospects, and contributions to the overall enterprise imaging IT solutions market
- To analyze market opportunities for stakeholders and provide details of the competitive landscape for key players.
- To forecast the size of the enterprise imaging IT solutions market in five main regions (and their respective countries): North America, Europe, Asia Pacific, the Middle East & Africa, and Latin America
- To provide key industry insights, such as supply chain, regulatory, patent, and the Impact of the 2025 US tariff.
- To profile the key players in the market and comprehensively analyze their core competencies2
- To analyze competitive developments, such as solution launches, enhancements, & upgrades, collaborations, partnerships, acquisitions, agreements, and expansions of the leading players in the market
- To benchmark players within the market using the company evaluation matrix, which analyzes market players on various parameters within the broad categories of business strategy, market share, and product offerings.
Available customizations:
With the given market data, MarketsandMarkets offers customizations as per your company’s specific needs. The following customization options are available for the report:
- Company information
- Detailed analysis and profiling of additional market players (up to 5)
Geographic Analysis
- Further breakdown of the Rest of Asia Pacific enterprise imaging IT market into Taiwan, New Zealand, Thailand, Singapore, Malaysia, and other countries
- Further breakdown of the Rest of Europe enterprise imaging IT market into Russia, Austria, Finland, Sweden, Turkey, Norway, Poland, Portugal, Romania, Denmark, and other countries
Get the Full Enterprise Imaging IT Market Report
Full forecast, segment splits, and company analysis for all Enterprise Imaging IT Market.
- Rest Of Asia Pacific Enterprise Imaging IT Market
- Rest Of Latin America Enterprise Imaging IT Market
- Canada Enterprise Imaging IT Market
- US Enterprise Imaging IT Market
- Germany Enterprise Imaging IT Market
- UK Enterprise Imaging IT Market
- France Enterprise Imaging IT Market
- Italy Enterprise Imaging IT Market
- Spain Enterprise Imaging IT Market
- China Enterprise Imaging IT Market
- Japan Enterprise Imaging IT Market
- India Enterprise Imaging IT Market
- Brazil Enterprise Imaging IT Market
- Mexico Enterprise Imaging IT Market
- Rest Of Europe Enterprise Imaging IT Market
Need a Tailored Report?
Customize this report to your needs
Get 10% FREE Customization
Customize This Report