US Hybrid Bonding Market (2025-2030)

The US Hybrid Bonding Market was valued at $31.4 Million in 2025 and projected to reach to $113.1 Million by 2030, representing a compound annual growth rate of 20.1%. The US hybrid bonding market is poised for significant expansion as semiconductor manufacturers prioritize advanced packaging technologies to meet performance demands of next-generation computing architectures.


| Market Size in | USD 26.32 MN |
| Market Forecast in | |
| CAGR | |
| Forecast Period | |
| Units Considered | Value (USD MN) |
US Hybrid Bonding Market Trends and Insights
- The US semiconductor industry is increasingly adopting hybrid bonding technology to enhance chiplet integration and advanced packaging capabilities.
- This growth trajectory reflects the US's leadership in semiconductor innovation and the rising demand for high-performance computing solutions across data centers, AI applications, and consumer electronics. Driving this expansion, the US benefits from a concentration of leading semiconductor manufacturers, research institutions, and technology companies investing heavily in next-generation bonding techniques.
- The US market's 20.1% compound annual growth rate significantly outpaces traditional packaging methods, as US-based firms prioritize hybrid bonding to achieve superior electrical performance and thermal management.
- By 2030, the US is expected to solidify its position as a critical hub for hybrid bonding adoption, supporting the nation's broader semiconductor competitiveness and advanced manufacturing capabilities..
Key Market Statistics
- CAGR (2025-2030) 20.1% CAGR
- Market Size, 2025 ~USD 31.4 Million
- Forecast, 2030 ~USD 113.1 Million
- Country US
US Hybrid Bonding Market Overview
Market Valuation Growth :
The US hybrid bonding market is valued at $31.4 million in 2025 and is projected to reach $113.1 million by 2030, representing a robust 20.1% CAGR over the forecast period.
Chiplet Integration Leadership :
US semiconductor manufacturers are rapidly adopting hybrid bonding technology to enable advanced chiplet integration, positioning the country as a global leader in next-generation packaging solutions.
Advanced Packaging Demand :
Rising demand for high-performance computing, AI processors, and data center applications is driving US adoption of hybrid bonding for superior interconnect density and thermal management.
Innovation Ecosystem :
The US semiconductor industry's strong R&D infrastructure and presence of major chipmakers accelerates hybrid bonding technology development and commercialization across multiple application segments.
US Hybrid Bonding Market Dynamics
- Key drivers include the proliferation of AI and machine learning applications, increased chiplet adoption for modular design, and the need for enhanced thermal and electrical performance in high-density interconnects.
- US-based semiconductor companies and equipment suppliers are investing heavily in hybrid bonding capabilities to maintain competitive advantage and support domestic chip manufacturing initiatives.
- The market's 20.1% CAGR reflects sustained momentum through 2030, supported by government incentives for semiconductor manufacturing and growing demand from cloud computing and automotive sectors..
Market Ecosystem
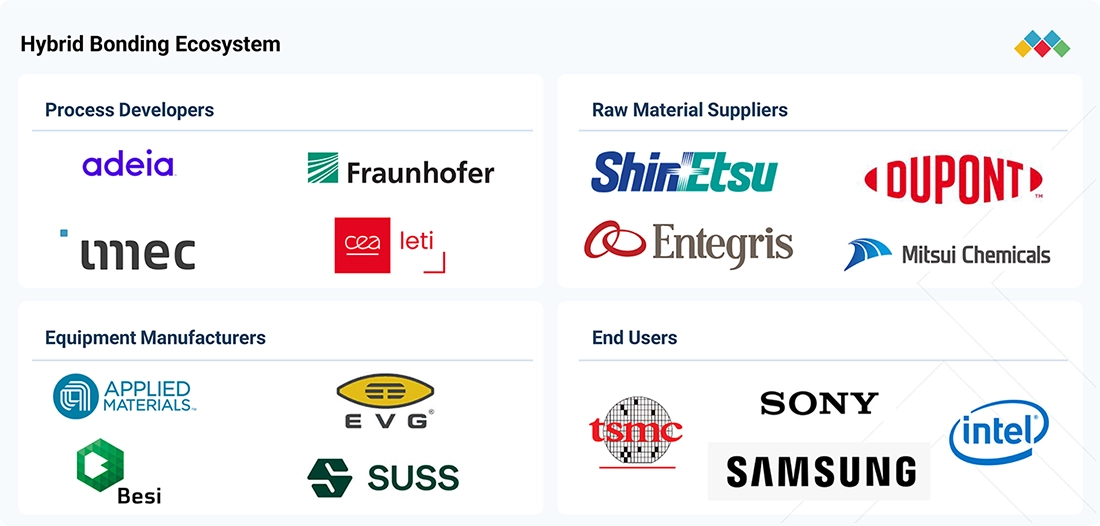
HYBRID BONDING MARKET: COMMERCIAL USE CASES ACROSS INDUSTRIES
| COMPANY | USE CASE DESCRIPTION | BENEFITS |
|---|---|---|
 |
EVG provides wafer-to-wafer and die-to-wafer hybrid bonding solutions for advanced 3D device integration. Its technology enables simultaneous dielectric and copper bonding and supports applications such as 3D SoCs, memory, CMOS image sensors, chiplets, and heterogeneous integration. EVG systems support very fine interconnect pitches and high-accuracy alignment. | Enables high-density 3D integration | Supports sub-micron interconnect pitches | Improves wafer/die alignment accuracy | Supports chiplet and heterogeneous integration |
 |
SUSS MicroTec offers hybrid bonding platforms including the XBC300 Gen2 D2W/W2W, supporting wafer-to-wafer, collective die-to-wafer, and sequential die-to-wafer bonding. The platform is designed for 3D stacked memory, SoC, and advanced semiconductor integration, with integrated metrology and sub-100 nm W2W alignment capability. | Enables flexible W2W and D2W bonding | Supports high-density chip stacking | Improves alignment precision | Facilitates transition from R&D to high-volume manufacturing |
 |
Applied Materials provides process technologies for hybrid bonding, including dielectric and metal deposition, electroplating, CMP, etch, surface preparation, and integrated die-to-wafer bonding. Its hybrid bonding solutions target logic, HBM, memory, chiplets, and heterogeneous integration, enabling direct copper-to-copper connections. | Increases I/O density | Reduces interconnect length and power consumption | Supports HBM and AI/HPC applications | Enables advanced heterogeneous integration |
 |
BESI's Datacon 8800 CHAMEO ultra plus AC hybrid bonding platform is designed for high-accuracy and high-throughput advanced packaging. Its hybrid bonding technology uses optical alignment and cleanliness control to enable high-density interconnects and 3D integration, particularly for high-end semiconductor packages. | Enables high-accuracy die placement | Supports high-density interconnects | Improves production throughput | Facilitates 3D semiconductor integration |
 |
K&S is developing hybrid bonding solutions around its APTURA platform and Fluxless Thermo-Compression technology. Its CuFirst hybrid bonding approach supports chip-to-wafer bonding by forming the copper interconnect first and subsequently creating the dielectric connection. The technology targets advanced logic, memory, and chiplet-based packaging. | Supports chip-to-wafer hybrid bonding | Targets higher yield and lower infrastructure costs | Supports copper-to-copper interconnection | Enables advanced logic and memory packaging |
Logos and trademarks shown above are the property of their respective owners. Their use here is for informational and illustrative purposes only.
Related Ecosystem
Semiconductor Materials And Components
- Sensors
- Gallium Nitride (GaN)
- Digital Signal Processor (DSP)
- Natural Language Processing (NLP)
- Silicon Carbide
- Texas Instruments Incorporated
- Samsung
- APPLIED MATERIALS, INC.
- Stmicroelectronics
- Lenovo
Key Takeaways
- The US hybrid bonding market is valued at $31.4 million in 2025 and is forecast to reach $113.1 million by 2030, representing a 20.1% CAGR.
- The US semiconductor industry is rapidly adopting hybrid bonding for advanced chiplet integration and high-performance packaging applications.
- US-based technology leaders are investing significantly in hybrid bonding R&D to maintain competitive advantage in AI and data center markets.
- The US market's growth is driven by demand for superior electrical performance, thermal management, and miniaturization in next-generation semiconductors.
Hybrid Bonding Market Report Scope
| Report Metric | Details |
|---|---|
| Base Year | 2025 |
| Fastest Growing Segment | DIE-TO-DIE (D2D) (Packaging Architecture) |
| Forecast Period | 2025–2030 |
| Growth Rate | CAGR of 21.2% from 2025 to 2030 |
| Largest Segment | BACK-END (Process Flow) |
| Market Size Base Year (Billions) | ~USD 0.17 (2025) |
| Revenue Forecast (Billions) | ~USD 0.43 (2030) |
| Segments Covered | Bonding Type, Packaging Architecture, Integration Level, Process Flow, Equipment Type, Application, Type, Vertical |
US Hybrid Bonding Market Report Segmentation
8 segment dimensions are covered across the global market.
By Bonding Type
- Copper-To-Copper (Cu-Cu)
- Copper-To-Pad /Metal-To-Pad
- Other Bonding Types
By Packaging Architecture
- Die-To-Die (D2D)
- Die-To-Wafer (D2W)
- Wafer-To-Wafer (W2W)
By Integration Level
- 2.5D Packaging
- 3D Stacked Ics
- Heterogeneous Integration
By Process Flow
- Back-End
- Front-End
By Equipment Type
- Cleaning & Cmp Systems
- Inspection & Metrology Tools
- Surface Prep Tools
- Wafer Bonders
By Application
- Computing & Logic
- Connectivity & Communications
- Memory & Storage
- Other Applications
- Sensing & Interface
By Type
- 3D Nand & Stacked Dram
- 5G Devices
- Cmos Image Sensors (Cis)
- Heterogeneous Socs & Chiplet Integration
- High-Bandwidth Memory (Hbm)
- High-Performance Computing & AI Accelerators
- MEMS & Other Sensors
- Micro-Led Displays
- Photonics & Optical Interconnects
- Rf Front-End Modules (Fem)
By Vertical
- Aerospace & Defense
- Automotive
- Consumer Electronics
- Healthcare & Medical
- Industrial Automation
- It & Telecommunications
- Other Verticals
Target Audience
- Semiconductor Manufacturers : US chipmakers need detailed market insights to evaluate hybrid bonding technology adoption, assess competitive positioning, and plan capital investments in advanced packaging capabilities.
- Equipment & Materials Suppliers : Vendors serving the US semiconductor industry require market data to identify growth opportunities, forecast demand for hybrid bonding equipment, and develop targeted sales strategies.
- Investment & Private Equity Firms : Investors evaluating opportunities in US semiconductor packaging need validated market sizing, growth projections, and trend analysis to assess investment returns and portfolio company potential.
- Technology Consultants & Analysts : Consulting firms and research organizations need comprehensive US market data to support client advisory services, competitive analysis, and strategic recommendations in semiconductor packaging.
- Government & Policy Makers : US government agencies and policy organizations require market intelligence to inform semiconductor manufacturing incentives, R&D funding decisions, and domestic supply chain development initiatives.
Key Companies in the US Hybrid Bonding Market
| Company | HQ | Ownership | Strongest segments |
|---|---|---|---|
| APPLIED MATERIALS, INC. | United States | Public Company | Wafer Bonder,Surface Prep Tool,Inspection & Metrology Tool, |
| SUSS MICROTEC SE | Germany | Public Company | Wafer Bonder (including hybrid-capable W2W/D2W tools),Surface Prep Tool,Inspection & Metrology Tool, |
| BESI | Netherlands | Public Company | Wafer Bonder (Hybrid-Capable),Die-to-Wafer (D2W) Hybrid Die Bonders,Die-to-Die (D2D) and Advanced Die Attach, |
| EV GROUP (EVG) | Canada | ||
| KULICKE AND SOFFA INDUSTRIES, INC. | Singapore | Public Company | Die-to-Wafer (D2W) Hybrid Bonding Tools,Die-to-Die (D2D) Hybrid Bonding Tools,Wafer-to-Wafer (W2W) Hybrid Bonders, |
| TOKYO ELECTRON LIMITED | Japan | Public Company | Wafer-to-Wafer (W2W),Die-to-Wafer (D2W),Die-to-Die (D2D), |
| LAM RESEARCH CORPORATION | United States | Public Company | Surface Prep Tool,Cleaning & CMP System,Surface-Related Etch (Dielectric/TSV), |
| SHIBAURA MECHATRONICS CORPORATION | Japan | Public Company | Cleaning & CMP System,Surface Prep Tool,Wafer Bonder, |
| ASMPT | Singapore | Public Company | Die-to-Wafer (D2W) Hybrid Bonders,Die-to-Die (D2D) Hybrid Bonders,Wafer-to-Wafer (W2W) Hybrid Bonders, |
| HANMI SEMICONDUCTOR | South Korea | Public Company | Wafer Bonder (Hybrid-capable W2W and D2W),Die-to-Die and Die-to-Wafer Placement / Pick-and-Place,Inspection & Metrology Tools, |
| ONTO INNOVATION | United States | Public Company | Inspection & Metrology Tool,Surface Prep Tool,Cleaning & CMP System (Metrology/Control), |
| DISCO CORPORATION | United States | Private Company | Surface Prep Tool,Cleaning & CMP System,Inspection & Metrology Tool, |
| KLA CORPORATION | United States | Public Company | Inspection & Metrology Tool,Surface Prep Tool,Cleaning & CMP System, |
| BEIJING U-PRECISION TECH CO., LTD | China | Private Company | Precision motion stages for wafer bonder and D2W/D2D handling,Electrostatic chucks for wafer handling and bonding,Ultra-precision measurement, inspection, and metrology subsystems, |
APPLIED MATERIALS, INC.
Applied Materials, Inc. is a United States-based public company founded in 1967 with 36,500 employees. The company is a leading provider of manufacturing equipment and services for the semiconductor and display industries.
SUSS MICROTEC SE
SUSS MicroTec SE is a German public company established in 1949 with 1,484 employees. The company specializes in manufacturing equipment for microstructuring and nanotechnology applications.
BESI
BESI is a Netherlands-based public company founded in 1995 with 1,856 employees. The company provides assembly equipment and solutions for the semiconductor and electronics packaging industries.
EV GROUP (EVG)
EV Group (EVG) is a company based in Canada. Specific operational details are not provided.
KULICKE AND SOFFA INDUSTRIES, INC.
Kulicke and Soffa Industries, Inc. is a Singapore-based public company founded in 1951 with 2,551 employees. The company manufactures semiconductor assembly and packaging equipment.
TOKYO ELECTRON LIMITED
Tokyo Electron Limited is a Japanese public company established in 1951 with 20,236 employees. The company is a major provider of semiconductor production equipment and services.
LAM RESEARCH CORPORATION
Lam Research Corporation is a United States-based public company founded in 1980 with 20,600 employees. The company designs and manufactures semiconductor processing equipment for the global chip manufacturing industry.
SHIBAURA MECHATRONICS CORPORATION
Shibaura Mechatronics Corporation is a Japanese public company founded in 1939 with 1,269 employees. The company manufactures precision machinery and equipment for various industrial applications.
ASMPT
ASMPT is a Singapore-based public company established in 1975 with 9,000 employees. The company provides assembly and packaging solutions for the semiconductor and electronics industries.
HANMI SEMICONDUCTOR
Hanmi Semiconductor is a South Korea-based private company founded in 1980 with 698 employees. The company operates in the semiconductor industry.
ONTO INNOVATION
Onto Innovation is a United States-based public company founded in 1940 with 1,615 employees. The company provides process technology solutions for the semiconductor and advanced packaging industries.
DISCO CORPORATION
Disco Corporation is a United States-based private company founded in 1960 with 21,000 employees. The company manufactures precision cutting, grinding, and polishing equipment for semiconductor and electronics applications.
KLA CORPORATION
KLA Corporation is a United States-based public company founded in 2012 with 2,333 employees. The company provides process control and yield management solutions for the semiconductor industry.
BEIJING U-PRECISION TECH CO., LTD
Beijing U-Precision Tech Co., Ltd. is a China-based private company founded in 2012. Specific employee and operational details are unavailable.
Reasons to Buy this Report
- Market Size & Growth Validation : Obtain precise US market valuation ($31.4M in 2025) and verified forecast data ($113.1M by 2030) to support investment decisions, business planning, and competitive positioning in the hybrid bonding sector.
- Regional Trend Analysis : Understand US-specific adoption drivers including chiplet integration strategies, advanced packaging requirements, and technology preferences unique to American semiconductor manufacturers and their supply chains.
- Competitive Intelligence : Identify key US market players, their market share, technology capabilities, and strategic initiatives to benchmark performance and identify partnership or acquisition opportunities in the hybrid bonding ecosystem.
- Application & Segment Insights : Access detailed breakdown of US hybrid bonding applications across high-performance computing, AI processors, data centers, and automotive sectors to target the most lucrative market segments.
- Strategic Planning & Forecasting : Leverage 5-year forecast data and growth trajectory analysis to develop informed go-to-market strategies, resource allocation plans, and long-term business roadmaps aligned with US market dynamics.
Frequently asked questions
What is the current size of the US hybrid bonding market?
The US hybrid bonding market is estimated at $31.4 million in 2025 and is projected to grow to $113.1 million by 2030.
What is the growth rate of the US hybrid bonding market?
The US hybrid bonding market is expected to grow at a compound annual growth rate (CAGR) of 20.1% from 2025 to 2030.
Which industries in the US are driving hybrid bonding adoption?
The US data center, artificial intelligence, high-performance computing, and advanced consumer electronics sectors are primary drivers of hybrid bonding adoption.
Why is the US a key market for hybrid bonding technology?
The US hosts leading semiconductor manufacturers, research institutions, and technology companies that are investing heavily in hybrid bonding to achieve superior performance and maintain global competitiveness.
What advantages does hybrid bonding offer in the US market?
Hybrid bonding enables US semiconductor manufacturers to achieve superior electrical performance, enhanced thermal management, improved chiplet integration, and greater miniaturization compared to traditional packaging methods.
RESEARCH METHODOLOGY
The study involved four major activities in estimating the current size of the global hybrid bonding market. Extensive secondary research was conducted to gather information on the semiconductor advanced packaging ecosystem, including hybrid bonding equipment manufacturers, semiconductor manufacturers, foundries, integrated device manufacturers (IDMs), OSATs, materials suppliers, technology providers, and research organizations. This was followed by primary research with industry stakeholders across the value chain, including hybrid bonding equipment manufacturers, semiconductor companies, foundries, IDMs, OSATs, advanced packaging companies, materials suppliers, and technology developers. These discussions were conducted to validate market assumptions and pricing, technology adoption, application trends, and market dynamics.
Both top-down and bottom-up approaches were used to estimate the overall market size. Market breakdowns and data triangulation techniques were applied to determine the size of individual segments and subsegments by bonding type, process flow, packaging architecture, integration level, application, vertical, and region. Secondary and primary sources were jointly used to support a comprehensive technical, commercial, and competitive analysis of the global hybrid bonding market. Hybrid bonding applications considered include 3D ICs, HBM and advanced memory, chiplets, heterogeneous integration, and advanced logic devices.
Secondary Research
Various secondary sources were referred to during the secondary research process to identify and collect information relevant to the hybrid bonding market. These sources included annual reports, company presentations, press releases, product announcements, technical publications, patents, industry publications, company websites, trade directories, and government databases. Secondary research was conducted to obtain key insights into the market’s supply chain, value chain, competitive landscape, and segmentation by bonding type, process, application, end user, and region.
Secondary research also helped assess industry trends, adoption of hybrid bonding across advanced semiconductor packaging, 3D ICs, HBM, chiplets, heterogeneous integration, and advanced logic and memory applications, as well as developments in wafer-to-wafer (W2W) and die-to-wafer (D2W) bonding technologies. Direct copper-to-copper interconnection, fine-pitch bonding, alignment accuracy, process integration, and high-volume manufacturing capabilities were also evaluated. The collected information was further analyzed to estimate the overall market size and validate market assumptions, which were subsequently refined through primary research with industry experts and key stakeholders.
Primary Research
Extensive primary research was conducted after gaining knowledge about the current scenario of the hybrid bonding market through secondary research. Several primary interviews were conducted with experts from the demand and supply sides across four major regions: North America, Europe, Asia Pacific, and RoW. This primary data was collected through questionnaires, emails, and telephonic interviews.
Breakdown of Primary Interviews
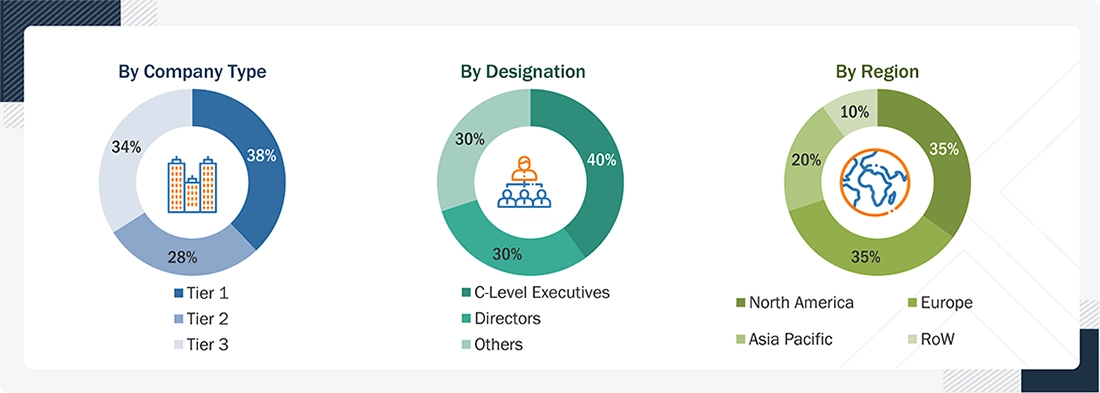
Note: The three tiers of the companies are defined based on their total revenue in 2025: Tier 1 - revenue greater than or equal to USD 1 billion; Tier 2 - revenue between USD 100 million and USD 1 billion; and Tier 3 revenue less than or equal to USD 100 million.
Other designations include sales managers, marketing managers, and product managers.
To know about the assumptions considered for the study, download the pdf brochure
Market Size Estimation
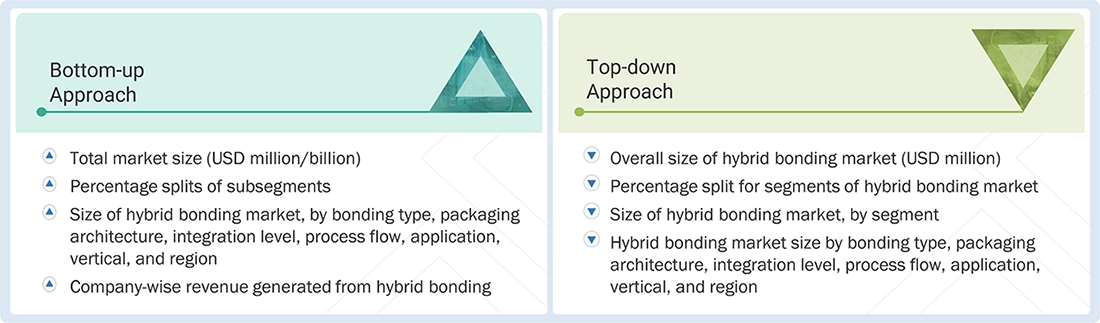
Both top-down and bottom-up approaches were used to estimate and validate the total size of the hybrid bonding market. These methods have also been used extensively to estimate the size of various subsegments in the market. The following research methodology was used to estimate the market size:
- Major players in the market and related markets were identified through extensive secondary research.
- The industry’s value chain and market size in terms of value and volume were determined through primary and secondary research processes.
- All percentage shares, splits, and segment-level breakdowns were determined using secondary sources and verified through primary research and data triangulation.
Hybrid Bonding Market: Top-Down and Bottom-Up Approach
Data Triangulation
After arriving at the overall size of the hybrid bonding market through the market size estimation process, the total market was divided into relevant segments and subsegments. Data triangulation and market breakdown procedures were employed, wherever applicable, to complete the market engineering process and derive the statistics for each segment and subsegment. The data were triangulated by evaluating factors and trends from the demand and supply sides, including technology adoption, equipment capabilities, semiconductor manufacturing developments, advanced packaging requirements, HBM and memory demand, chiplet integration, and regional trends. The analysis considered key hybrid bonding technologies such as wafer-to-wafer (W2W), die-to-wafer (D2W), collective D2W, and sequential D2W, along with applications including 3D ICs, HBM and advanced memory, chiplets, CMOS image sensors, and advanced logic. W2W and D2W are established process configurations across current hybrid bonding platforms, while applications such as HBM, 3D ICs, and chiplet-based architectures are being targeted for advanced integration. Along with this, the market size was validated using top-down and bottom-up approaches to ensure consistency across the overall market and individual segments.
Market Definition
Hybrid bonding refers to advanced semiconductor packaging and 3D integration technology that directly bonds semiconductor wafers or dies through simultaneous dielectric-to-dielectric and copper-to-copper connections, eliminating or reducing the need for conventional solder-based microbumps. The technology enables extremely fine-pitch interconnections and high-density vertical integration between chips or wafers. Hybrid bonding can be implemented through wafer-to-wafer (W2W), collective die-to-wafer (D2W), and sequential die-to-wafer (D2W) approaches.
Hybrid bonding plays a crucial role in advanced semiconductor packaging, 3D ICs, high-bandwidth memory (HBM), 3D NAND, chiplets, CMOS image sensors, and heterogeneous integration. By creating shorter and denser electrical connections between dies, the technology can increase interconnect density, improve bandwidth, reduce power consumption, and support higher levels of device integration. It is particularly relevant to AI, high-performance computing, advanced memory, and next-generation logic applications where conventional 2D scaling and microbump-based interconnects face increasing limitations. A typical hybrid bonding process involves surface preparation and activation, dielectric and copper formation, planarization, cleaning, precision alignment, bonding, and thermal treatment to establish the dielectric and copper interfaces. The process requires highly uniform and particle-free surfaces, precise copper recess control, and extremely accurate alignment to achieve high bonding yield and reliability. Depending on the bonding approach, the process can involve bonding two complete wafers or selectively placing individual dies onto a target wafer.
Key Stakeholders
- Original device manufacturers (ODMs)
- System integrators
- Component/raw material suppliers
- Equipment providers
- End users
- Technical universities
- Government/Private research institutes
- Market research and consulting firms
Report Objectives
- To define, describe, segment, and forecast the hybrid bonding market, in terms of value, based on packaging architecture, process flow, integration level, bonding type, application, vertical, and region
- To forecast the market, in terms of volume, based on packaging architecture
- To forecast the size of the market and its segments with respect to four main regions, namely North America, Europe, Asia Pacific, and RoW, along with their key countries
- To strategically analyze micromarkets with respect to individual growth trends, prospects, and contributions to the total market
- To provide detailed information regarding the key factors influencing market growth, such as drivers, restraints, opportunities, and challenges
- To provide a detailed analysis of the hybrid bonding value chain, porter’s five forces, regulatory landscape, key stakeholders and buying criteria, trade analysis, patent analysis, and key conferences and events
- To provide a detailed analysis of the impact of AI/Gen AI and the US tariffs on the market
- To analyze the opportunities in the market for stakeholders and provide a detailed competitive landscape of the market leaders
- To strategically profile the key players and comprehensively analyze their market ranking and core competencies
- To analyze the key growth strategies, such as expansions, mergers, joint ventures, acquisitions, product launches/developments, and R&D activities, undertaken by players operating in the market
Available customizations:
With the given market data, MarketsandMarkets offers customizations according to the company’s specific needs. The following customization options are available for the report:
Company Information
-
Detailed analysis and profiling of additional market players (up to 5)
Get the Full Hybrid Bonding Market Report
Full forecast, segment splits, and company analysis for all Hybrid Bonding Market.
- Canada Hybrid Bonding Market
- Mexico Hybrid Bonding Market
- Germany Hybrid Bonding Market
- UK Hybrid Bonding Market
- France Hybrid Bonding Market
- Italy Hybrid Bonding Market
- Spain Hybrid Bonding Market
- Nordics Hybrid Bonding Market
- Poland Hybrid Bonding Market
- Rest Of Europe Hybrid Bonding Market
- China Hybrid Bonding Market
- Japan Hybrid Bonding Market
- South Korea Hybrid Bonding Market
- Taiwan Hybrid Bonding Market
- India Hybrid Bonding Market
- Rest Of Asia Pacific Hybrid Bonding Market
Need a Tailored Report?
Customize this report to your needs
Get 10% FREE Customization
Customize This Report
