Latin America LEO Satellite Market (2025-2030)

The Latin America LEO Satellite Market was valued at $97.4 Million in 2025 and projected to reach to $121.9 Million by 2030, representing a compound annual growth rate of 4.6%. Latin America's LEO satellite market is positioned for steady expansion as regional governments and private enterprises recognize the strategic value of satellite connectivity and Earth observation capabilities.


| Market Size in | USD 26.32 MN |
| Market Forecast in | |
| CAGR | |
| Forecast Period | |
| Units Considered | Value (USD MN) |
Latin America LEO Satellite Market Trends and Insights
- Latin America's LEO satellite sector is experiencing steady expansion driven by increasing demand for broadband connectivity, Earth observation capabilities, and government investment in space infrastructure.
- The region's growth trajectory reflects Latin America's strategic focus on bridging the digital divide and enhancing telecommunications coverage across remote and underserved areas. Latin America's LEO satellite market benefits from rising adoption of satellite-based services for agriculture, disaster management, and IoT applications.
- The forecast period through 2030 indicates that Latin America will continue to attract investment from both international satellite operators and regional stakeholders seeking to leverage LEO constellations for commercial and public-sector applications.
- Latin America's regulatory environment and partnerships with global space agencies are expected to support sustained market development during this period..
Key Market Statistics
- CAGR (2025-2030) 4.6% CAGR
- Market Size, 2025 ~USD 97.4 Million
- Forecast, 2030 ~USD 121.9 Million
- Geography Latin America
Latin America LEO Satellite Market Overview
Steady Regional Growth :
Latin America's LEO satellite market is projected to grow from USD 97.4 million in 2025 to USD 121.9 million by 2030, with a CAGR of 4.6%, reflecting consistent demand for satellite-based solutions across the region.
Broadband Connectivity Expansion :
Increasing demand for high-speed internet connectivity in underserved rural and remote areas of Latin America is driving LEO satellite adoption, bridging the digital divide across the region.
Government Space Infrastructure Investment :
Latin American governments are actively investing in space infrastructure and satellite capabilities, supporting the development of indigenous space programs and fostering regional technological advancement.
Earth Observation Applications :
Growing utilization of LEO satellites for Earth observation, environmental monitoring, agriculture, and disaster management is creating new revenue streams and operational efficiencies across Latin American industries.
Latin America LEO Satellite Market Dynamics
- The region's geographic diversity and infrastructure gaps create significant opportunities for LEO satellite operators to deliver broadband services to underserved populations.
- Investment in space infrastructure and increasing partnerships with global satellite operators are expected to accelerate market penetration. The forecast period through 2030 will likely see enhanced adoption across telecommunications, agriculture, and disaster management sectors.
- While Latin America's 4.6% CAGR trails the global 11.9% rate, the region's unique connectivity challenges and growing digital economy present substantial long-term growth potential.
- Strategic government initiatives and private sector innovation will be critical drivers of market expansion..
Market Ecosystem
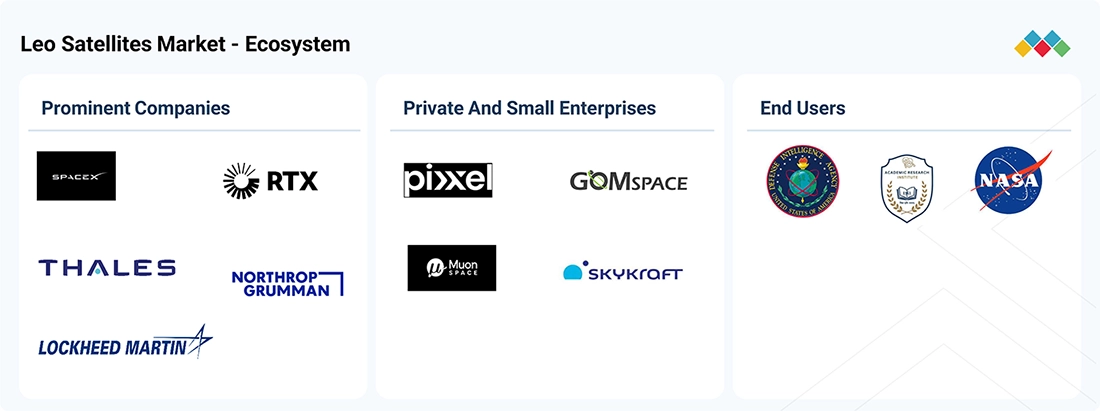
LEO SATELLITE MARKET SIZE, SHARE & TRENDS: COMMERCIAL USE CASES ACROSS INDUSTRIES
| COMPANY | USE CASE DESCRIPTION | BENEFITS |
|---|---|---|
 |
LEO Satellite Broadband Connectivity – Starlink uses a large constellation of LEO satellites to provide broadband connectivity to residential, enterprise, government, aviation, maritime, and remote users. The satellites operate closer to Earth than traditional geostationary satellites, supporting lower-latency communication and wider coverage across areas with limited terrestrial infrastructure. | High-Speed, Low-Latency Connectivity – Provides broadband access in remote and underserved locations where terrestrial networks are limited. The LEO architecture supports lower communication latency and enables connectivity for fixed users, mobile platforms, emergency response, and government operations. |
 |
LEO Earth Observation & Monitoring – Planet operates LEO Earth observation satellites that collect frequent imagery of the Earth's surface for applications including mapping, agriculture, environmental monitoring, infrastructure assessment, and government intelligence. Its satellite fleet supports repeated observation of geographic areas to identify and monitor changes over time. | Frequent Earth Observation & Change Detection – Enables organizations to monitor large areas regularly and compare imagery across different time periods. This supports faster identification of changes in infrastructure, agriculture, environmental conditions, and areas of government or defense interest. |
 |
LEO Weather, Maritime & Aviation Data Collection – Spire operates LEO satellites carrying radio-frequency sensing payloads that collect weather, maritime AIS, and aviation ADS-B data. The satellites support global monitoring of atmospheric conditions, ship movements, and aircraft activity, including regions where terrestrial monitoring infrastructure is limited. | Global Monitoring & Data Coverage – Extends weather, maritime, and aviation data collection across oceans and remote regions. Frequent LEO satellite passes support updated information for weather forecasting, vessel tracking, aircraft monitoring, logistics, and government operations. |
Logos and trademarks shown above are the property of their respective owners. Their use here is for informational and illustrative purposes only.
Related Ecosystem
Space
- C-Band
- Small Satellite
- Antennas
- Ka-Band
- Microsatellite
- AIRBUS
- L3Harris Technologies, Inc.
- Thales group
- Northrop Grumman Corporation
- LOCKHEED MARTIN CORPORATION
Key Takeaways
- Latin America's LEO satellite market is valued at USD 97.4 million in 2025 and is expected to reach USD 121.9 million by 2030, with a CAGR of 4.6%.
- Latin America is leveraging LEO satellite technology to address connectivity gaps and support digital transformation across rural and remote regions.
- Latin America's market growth is driven by increasing demand for Earth observation, agricultural monitoring, and disaster management applications.
- Latin America's regulatory frameworks and international partnerships are positioning the region as an emerging hub for LEO satellite services and infrastructure development.
LEO Satellite Market Report Scope
| Report Metric | Details |
|---|---|
| Base Year | 2025 |
| Fastest Growing Segment | LASER/OPTICAL (Frequency) |
| Forecast Period | 2025–2030 |
| Growth Rate | CAGR of 11.9% from 2025 to 2030 |
| Largest Segment | COMMERCIAL (End Use) |
| Market Size Base Year (Billions) | ~USD 11.79 (2025) |
| Revenue Forecast (Billions) | ~USD 20.69 (2030) |
| Segments Covered | Satellite Mass, Type, Subsystem, Propulsion, Payload, Application, End Use, Frequency |
Latin America LEO Satellite Market Report Segmentation
8 segment dimensions are covered across the global market.
By Satellite Mass
- Cubesats
- Large Satellites
- Medium Satellites
- Small Satellites
By Type
- Academic & Research Institutions
- Attitude & Orbital Control Systems
- Command & Data Handling Systems
- Communication Payloads/Transponders
- Departments Of Defense & Intelligence Agencies
- Electrical Power Systems
- Energy Industry
- Hyperspectral And Multispectral Imagers
- Media & Entertainment
- Micro Satellites (11–100 Kg)
- Mini Satellites (101–500 Kg)
- Nano Satellites (1–10 Kg)
- National Mapping & Topographic Agencies
- National Space Agencies
- Optical And Infrared
- Others (Ais)
- Propulsion
- Radar Payloads
- Satellite Operators/Owners
- Scientific Research & Development
- Search & Rescue Entities
- Smallsats (501–1,000 Kg)
- Structures
- Telemetry, Tracking, & Command (Tt&C)
- Thermal Systems
By Subsystem
- Payloads
- Satellite Antennas
- Satellite Buses
- Solar Panels
By Propulsion
- Chemical Propulsion
- Electric Propulsion
- Hybrid Propulsion
By Payload
- Software-Defined Payloads
- Traditional Payloads
By Application
- Communication
- Earth Observation & Remote Sensing
- Scientific Research
- Technology
By End Use
- Commercial
- Dual Use
- Government & Military
By Frequency
- C-Band
- Hf/Vhf/Uhf-Band
- Ka-Band
- Ku-Band
- L-Band
- Laser/Optical
- Q/V-Band
- S-Band
- X-Band
Target Audience
- Satellite Operators & Constellation Developers : Need regional market sizing, growth forecasts, and connectivity demand data to prioritize Latin American coverage expansion and optimize constellation deployment strategies.
- Telecommunications & ISP Providers : Require insights into broadband connectivity gaps, rural market opportunities, and competitive positioning to develop satellite-based service offerings across Latin America.
- Government & Space Agencies : Seek market intelligence on regional space infrastructure investments, policy trends, and technology adoption to inform national space programs and regulatory frameworks.
- Investment & Private Equity Firms : Need market valuation, growth projections, and sector dynamics to evaluate investment opportunities in Latin American satellite ventures and space technology companies.
- Enterprise & Agricultural Operators : Require data on Earth observation capabilities, disaster management applications, and service availability to assess LEO satellite solutions for operational efficiency and risk mitigation.
Key Companies in the Latin America LEO Satellite Market
| Company | HQ | Ownership | Strongest segments |
|---|---|---|---|
| EUTELSAT COMMUNICATIONS S.A. | France | ||
| SATELLOGIC | United States | Public Company | Optical payload data & analytics,Satellite bus & space systems (sales and support),Constellation-as-a-service & sovereign constellations, |
| TERRAN ORBITAL CORPORATION | United States | Private Company | Satellite Bus – Command & Data Handling,Satellite Bus – Electric Power System,Payload – Optical / Infrared / Radar, |
| SPIRE GLOBAL INC. | United States | Public Company | Space Reconnaissance (defense, intelligence, national security),Aviation (satellite-based aircraft tracking),Weather and Climate (data and predictive analytics), |
| RAYTHEON TECHNOLOGIES CORPORATION | United States | Public Company | Payload – Radar,Payload – Infrared,Payload – Optical, |
| PLANET LABS, INC | United States | Public Company | Optical payload data (SuperDove, SkySat, Pelican),Hyperspectral payload data (Tanager),Earth Observation platform and analytics (APIs, browser apps), |
| SPACE EXPLORATION TECHNOLOGIES CORP. | United States | Public Company | Satellite Bus (Command & Data Handling, Electric Power System),Payload (Optical, Infrared, Radar),Solar Panel, |
| SPACEX | United States | Public Company | Satellite Bus (Command & Data Handling, Electric Power System),Payload (Broadband-focused RF payloads, including phased arrays),Solar Panels, |
| LOCKHEED MARTIN CORPORATION | United States | Public Company | Satellite Bus – Command & Data Handling,Satellite Bus – Electric Power System,Payload – Optical / Infrared / Radar, |
| NORTHROP GRUMMAN | United States | Public Company | Satellite Bus (Command & Data Handling, Electric Power System),Payload (Optical, Infrared, Radar),Solar Panel, |
| L3HARRIS TECHNOLOGIES, INC. | United States | Public Company | Satellite Bus – Command & Data Handling,Satellite Bus – Electric Power System,Payload – Optical, |
| PLANET LABS PBC | United States | Public Company | Optical payload data subscriptions (Dove/SuperDove),High-resolution tasked imagery (SkySat),Value-added analytics and monitoring services, |
| MAXAR TECHNOLOGIES | United States | Private Company | Payload-derived data (optical, radar) and analytics platforms,Mission software, C2, and digital twin solutions,Satellite bus, solar panel, and antenna-related activities, |
| GOMSPACE | Denmark | Public Company | Satellite Bus (Command & Data Handling, Electric Power System, AOCS, structures),Payloads (mission payloads across optical, RF, and specialized sensors),Power, Communication Systems, Solar Panels, and Antennas, |
| MITSUBISHI ELECTRIC CORPORATION | Japan | Public Company | Satellite Bus – Command & Data Handling,Satellite Bus – Electric Power System,Payload – Optical, |
| CHINA AEROSPACE SCIENCE AND TECHNOLOGY CORPORATION | China | Private Company | Satellite Bus – Command & Data Handling,Satellite Bus – Electric Power System,Payload – Optical, |
EUTELSAT COMMUNICATIONS S.A.
Eutelsat Communications S.A. is a French satellite operator providing telecommunications and broadcasting services through a fleet of geostationary satellites.
SATELLOGIC
Satellogic is a United States-based public company founded in 2010 with 154 employees that operates in the satellite imagery and Earth observation sector.
TERRAN ORBITAL CORPORATION
Terran Orbital Corporation is a United States-based private company founded in 2013 with 660 employees specializing in satellite manufacturing and space systems.
SPIRE GLOBAL INC.
Spire Global Inc. is a United States-based public company founded in 2012 with 375 employees providing satellite-based data and analytics for maritime, aviation, and weather applications.
RAYTHEON TECHNOLOGIES CORPORATION
Raytheon Technologies Corporation is a United States-based public company founded in 1934 with 180,000 employees providing aerospace and defense technologies and services.
PLANET LABS, INC
Planet Labs, Inc. is a United States-based public company founded in 2010 with 973 employees operating a constellation of Earth imaging satellites for global monitoring and analysis.
SPACE EXPLORATION TECHNOLOGIES CORP.
Space Exploration Technologies Corp. is a United States-based public company founded in 2002 with 21,000 employees developing rockets and spacecraft for commercial and government missions.
SPACEX
SpaceX is a United States-based public company founded in 2002 with 22,000 employees designing and manufacturing rockets and spacecraft for commercial and government space missions.
LOCKHEED MARTIN CORPORATION
Lockheed Martin Corporation is a United States-based public company founded in 1912 with 123,000 employees providing aerospace, defense, and security solutions.
NORTHROP GRUMMAN
Northrop Grumman is a United States-based public company founded in 1939 with 95,000 employees providing aerospace, defense, and security technologies and services.
L3HARRIS TECHNOLOGIES, INC.
L3Harris Technologies, Inc. is a United States-based public company founded in 1895 with 45,000 employees specializing in aerospace, defense, and security solutions.
PLANET LABS PBC
Planet Labs PBC is a United States-based public company founded in 2010 operating Earth imaging satellites for global monitoring and geospatial intelligence.
MAXAR TECHNOLOGIES
Maxar Technologies is a United States-based private company founded in 1957 with 4,600 employees specializing in satellite imagery, geospatial intelligence, and space infrastructure.
GOMSPACE
GOMSPACE is a Denmark-based public company founded in 2007 with 208 employees manufacturing small satellites and spacecraft subsystems.
MITSUBISHI ELECTRIC CORPORATION
Mitsubishi Electric Corporation is a Japan-based public company founded in 1921 with 150,386 employees providing electrical equipment, electronics, and space systems.
CHINA AEROSPACE SCIENCE AND TECHNOLOGY CORPORATION
China Aerospace Science and Technology Corporation is a China-based private company founded in 1956 engaged in aerospace and space technology development and manufacturing.
Countries within Latin America - compare and drill down
| Country | 2025 size (native) |
|---|---|
| Mexico | USD 21.7 Million |
| Argentina | USD 96.4 Million |
Country market size visualization
Reasons to Buy this Report
- Country-Level Market Breakdown : Access detailed market sizing for Mexico (USD 21.7M) and Argentina (USD 96.4M), enabling targeted investment and expansion strategies in key Latin American markets.
- Growth Trajectory Analysis : Understand the 4.6% CAGR trajectory and USD 24.5 million market expansion opportunity from 2025-2030, supporting long-term business planning and resource allocation decisions.
- Regional Connectivity Insights : Gain competitive intelligence on broadband connectivity demand drivers, rural market penetration opportunities, and infrastructure gaps unique to Latin America's diverse geography.
- Government Investment Landscape : Identify government space infrastructure initiatives, policy frameworks, and funding mechanisms across Latin American nations to inform partnership and licensing strategies.
- Sector-Specific Applications : Discover high-potential use cases in agriculture, disaster management, and environmental monitoring tailored to Latin American economic priorities and operational needs.
Frequently asked questions
What is the current size of the LEO satellite market in Latin America?
The LEO satellite market in Latin America is estimated at USD 97.4 million in 2025 and is projected to grow to USD 121.9 million by 2030.
What is the expected growth rate for Latin America's LEO satellite market?
Latin America's LEO satellite market is expected to grow at a compound annual growth rate (CAGR) of 4.6% from 2025 to 2030.
What are the primary drivers of LEO satellite market growth in Latin America?
Latin America's LEO satellite market growth is driven by increasing demand for broadband connectivity, Earth observation services, agricultural monitoring, disaster management, and government investment in space infrastructure.
How is Latin America using LEO satellite technology?
Latin America is using LEO satellite technology to bridge the digital divide, enhance telecommunications coverage in remote areas, support precision agriculture, enable disaster response, and facilitate IoT applications across the region.
What role do international partnerships play in Latin America's LEO satellite market?
International partnerships and regulatory frameworks in Latin America are attracting investment from global satellite operators and enabling regional stakeholders to develop LEO-based services, positioning Latin America as an emerging market for satellite infrastructure and applications.
RESEARCH METHODOLOGY
The LEO satellites market is estimated at USD 12.82 billion in 2026 and is projected to reach USD 43.37 billion by 2031 at a CAGR of 27.6%. This research study involves the use of secondary sources, company publications, government databases, procurement records, technical papers, and industry associations to collect information related to the LEO satellites market. Primary research includes discussions with satellite manufacturers, satellite operators, launch service providers, payload and subsystem manufacturers, communication service providers, system integrators, and end users. Interviews with industry experts, company executives, and other market participants are used to validate information on market size, segment trends, technology adoption, competitive developments, and future market developments. Both qualitative and quantitative inputs are considered to assess the market and its segments.
Secondary Research
In the secondary research process, various sources are referred to for identifying and collecting information related to the LEO satellites market. These sources include company annual reports, press releases, investor presentations, product documents, government and space agency publications, procurement databases, technical papers, patents, industry associations, and recognized news sources. Secondary research is used to gather information on the market supply chain, competitive landscape, market segmentation, regional presence, satellite technologies, contracts, partnerships, product developments, constellation deployments, and launch activities. Information on satellite platforms, payloads, subsystems, communication technologies, Earth observation, navigation, and related technologies is also reviewed to understand changes in the market. The collected information is analyzed to estimate the overall market and individual segments using bottom-up and top-down approaches. The findings from secondary research are further checked and validated through primary research with relevant industry participants along with subject matter experts.
Primary Research
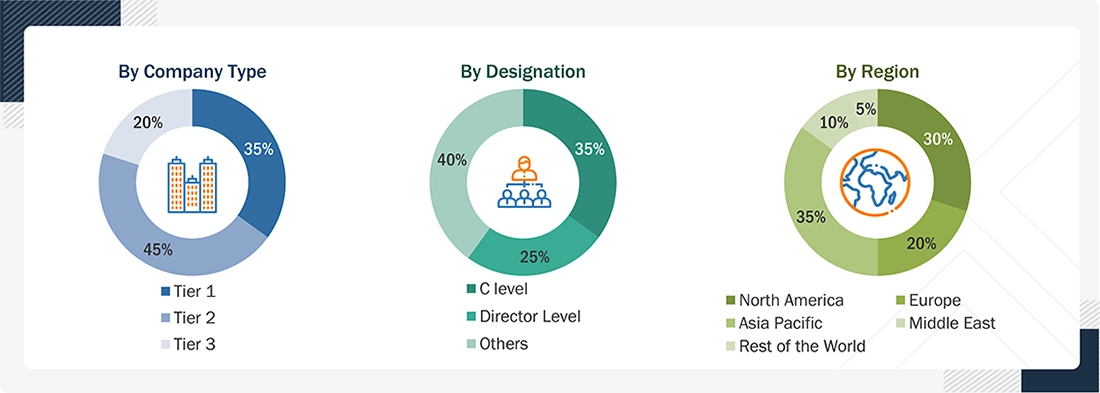
Extensive primary research was conducted after acquiring information on the LEO satellites market through secondary research. Several primary interviews were conducted with market experts from the demand and supply sides across major countries of North America, Europe, the Asia Pacific, the Middle East, and the Rest of the World. Primary data was collected through questionnaires, emails, and telephonic interviews.
Following is the breakdown of primary respondents:
To know about the assumptions considered for the study, download the pdf brochure
Market Size Estimation
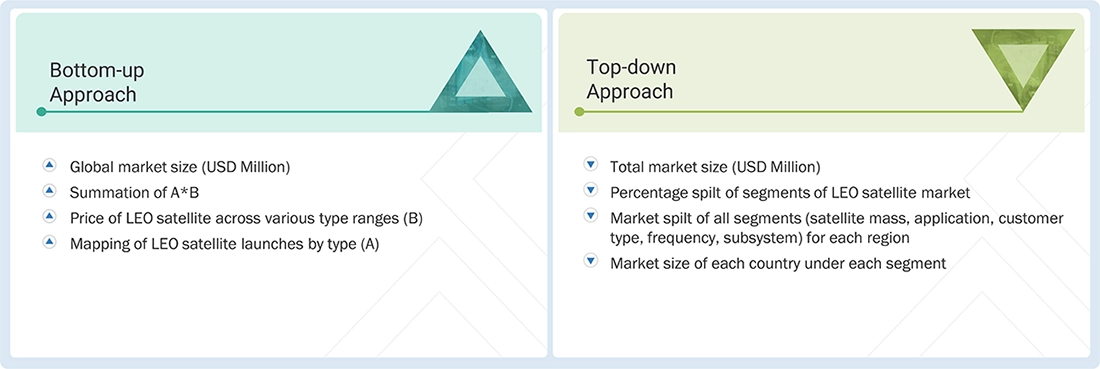
Top-down and bottom-up approaches were used to estimate and validate the size of the LEO satellites market. The research methodology used to estimate the size of the market included the following details:
- Key players in the LEO satellites market were identified through secondary research, and their market shares were determined through a combination of primary and secondary research. This included a study of the annual and financial reports of the top market players, as well as extensive interviews with leaders, including directors, engineers, marketing executives, and other key stakeholders of leading companies operating in the market.
- All percentage shares, splits, and breakdowns were determined using secondary sources and verified through primary sources.
- All possible parameters that affect the markets covered in this research study were accounted for, viewed in extensive detail, verified through primary research, and analyzed to obtain the final quantitative and qualitative data on the LEO satellites market. This data was consolidated, enhanced with detailed input, analyzed by MarketsandMarkets, and presented in this report.
Data Triangulation
After determining the overall market size, the total market was classified into several segments and subsegments. The data triangulation and market breakdown procedures explained below were implemented, wherever applicable, to complete the overall market engineering process and arrive at the estimated market numbers for the market segments and subsegments. The data were triangulated by examining various factors and trends on both the demand and supply sides. Additionally, the market size was validated using top-down and bottom-up approaches.
Market Definition
Low Earth orbit (LEO) satellites are used for commercial, communication, and space research purposes. According to NASA, a low Earth orbit is an Earth-centered orbit with an altitude of 2,000 km (1,200 miles) or less. For the purposes of the commercial use policy, a low Earth orbit is considered the area in Earth orbit near enough to Earth for convenient transportation, communication, observation, and resupply. Unlike satellites in GEO, which must orbit along the Earth’s equator, LEO satellites do not have to follow a fixed path around Earth; their orbital plane can be tilted. This means there are more available routes for satellites in LEO, which is one of the reasons why LEO is a very commonly used orbit.
LEO satellites are used for Earth observation & remote sensing, communication, mapping & navigation, surveillance & security, meteorology, scientific research & exploration, space observation, and various other applications by the defense, civil, commercial, and government verticals.
Key Stakeholders
- Satellite Component Manufacturers
- Satellite Manufacturers
- Satellite Integrators
- Launch Service Providers
- Government and Civil Organizations
- Small Satellite Companies
- Payload Suppliers
- Scientific Institutions
- Meteorological Organizations
Report Objectives
- To define, describe, segment, and forecast the size of the LEO satellites market based on satellite mass, application, customer type, frequency, subsystem, and region
- To forecast the sizes of various segments of the market with respect to these major regions: North America, Europe, Asia Pacific, the Middle East, and the Rest of the World, along with major countries in each of these regions
- To identify and analyze the drivers, restraints, opportunities, and challenges influencing the growth of the market
- To identify industry trends, market trends, and technology trends currently prevailing in the market
- To analyze micromarkets with respect to growth trends, prospects, and their contribution to the overall market
- To analyze opportunities in the market for stakeholders by identifying key market trends
- To profile key market players and comprehensively analyze their market share and core competencies
- To evaluate the degree of competition in the market by analyzing recent developments, such as contracts, agreements, and acquisitions adopted by leading market players
- To identify detailed financial positions, key products, and unique selling points of leading companies in the market
- To provide a detailed competitive landscape of the market, along with market share analysis and revenue analysis of key players
Customization Options
MarketsandMarkets offers the following customizations for this market report:
- Additional country-level analysis of the LEO satellites market
- Profiling of other market players (up to five)
Product Analysis
- Product matrix, which provides a detailed comparison of the product portfolios of each company in the LEO satellites market
Get the Full LEO Satellite Market Report
Full forecast, segment splits, and company analysis for all LEO Satellite Market.
- US LEO Satellite Market
- Canada LEO Satellite Market
- UK LEO Satellite Market
- Germany LEO Satellite Market
- France LEO Satellite Market
- Italy LEO Satellite Market
- Russia LEO Satellite Market
- China LEO Satellite Market
- India LEO Satellite Market
- Japan LEO Satellite Market
- South Korea LEO Satellite Market
- Australia LEO Satellite Market
- Mexico LEO Satellite Market
- Argentina LEO Satellite Market
- Israel LEO Satellite Market
- Rest Of Europe LEO Satellite Market
- Rest Of Asia Pacific LEO Satellite Market
- Rest Of Latin America LEO Satellite Market
- GCC LEO Satellite Market
Need a Tailored Report?
Customize this report to your needs
Get 10% FREE Customization
Customize This Report
