Asia Pacific Smart Hospital Market (2026-2031)
The Asia Pacific Smart Hospital Market was valued at $35759.2 Million in 2026 and projected to reach to $79562 Million by 2031, representing a compound annual growth rate of 14.3%. Asia Pacific is emerging as the fastest-growing region for smart hospital solutions, driven by substantial investments in healthcare infrastructure modernization and digital transformation initiatives.

| Market Size in | USD 26.32 MN |
| Market Forecast in | |
| CAGR | |
| Forecast Period | |
| Units Considered | Value (USD MN) |
Asia Pacific Smart Hospital Market Trends and Insights
- The region is experiencing rapid digital transformation across healthcare infrastructure, driven by increasing investments in IoT, AI, and cloud-based hospital management systems.
- Asia Pacific's smart hospital market is projected to expand significantly to $79,562.0 million by 2031, reflecting a compound annual growth rate of 14.3%. The acceleration in Asia Pacific reflects strong demand from emerging economies modernizing their healthcare facilities and developed markets enhancing operational efficiency.
- Asia Pacific's adoption of smart hospital technologies is outpacing the global average, supported by government initiatives, rising healthcare expenditure, and growing patient populations.
- By 2031, Asia Pacific is expected to capture a substantial share of the global smart hospital market, positioning the region as a critical hub for semiconductor and electronics innovation in healthcare delivery..
Key Market Statistics
- CAGR (2026-2031) 14.3% CAGR
- Market Size, 2026 ~USD 35759.2 Million
- Forecast, 2031 ~USD 79562 Million
- Geography Asia Pacific
Asia Pacific Smart Hospital Market Overview
Rapid Digital Transformation :
Asia Pacific is undergoing accelerated digital transformation in healthcare, with hospitals increasingly adopting IoT, AI, and cloud-based management systems to enhance operational efficiency and patient care delivery.
Strong Investment Growth :
Significant capital investments in smart hospital infrastructure across Asia Pacific are driving market expansion, supported by government healthcare modernization initiatives and private sector funding in key economies.
High CAGR Performance :
The Asia Pacific smart hospital market is projected to grow at 14.3% CAGR from 2026 to 2031, outpacing the global average of 10.6%, reflecting the region's strategic focus on healthcare innovation.
Market Scale Expansion :
The region's market size is expected to more than double from $35,759.2 million in 2026 to $79,562 million by 2031, driven by population growth, rising healthcare demand, and technological adoption.
Asia Pacific Smart Hospital Market Dynamics
- Countries like China, India, and Japan are leading adoption of advanced technologies including AI-powered diagnostics, IoT-enabled patient monitoring, and integrated hospital management systems.
- Government support for healthcare digitalization, combined with increasing healthcare expenditure and a growing patient population, creates a robust market environment. The region's competitive landscape is intensifying as both established healthcare IT vendors and emerging local players expand their presence.
- Rising awareness of operational efficiency benefits, coupled with declining technology costs, is accelerating smart hospital adoption across urban and emerging healthcare facilities.
- By 2031, Asia Pacific is positioned to capture a significant share of global smart hospital investments, with particular growth opportunities in emerging markets seeking cost-effective digital healthcare solutions..
Market Ecosystem
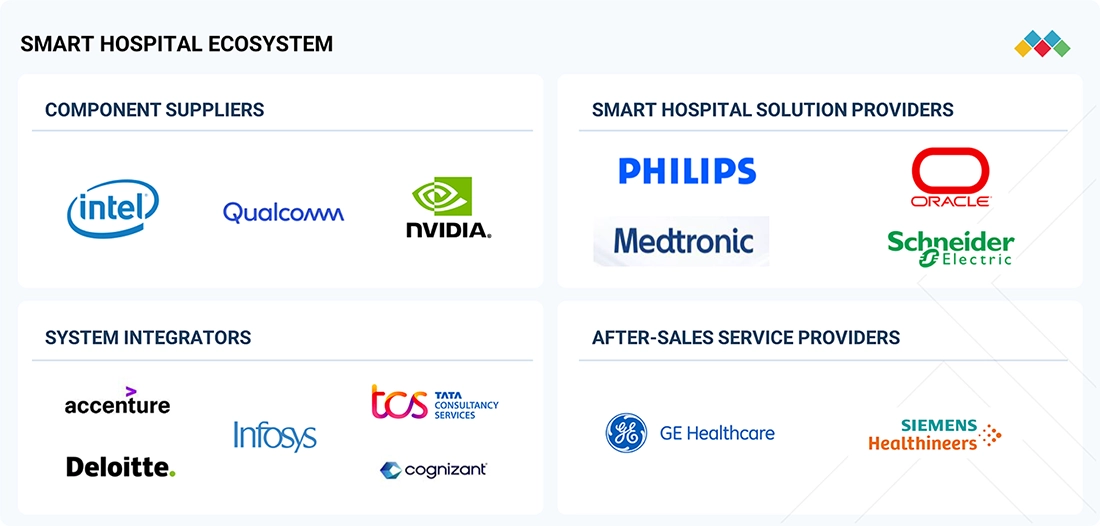
SMART HOSPITAL MARKET: COMMERCIAL USE CASES ACROSS INDUSTRIES
| COMPANY | USE CASE DESCRIPTION | BENEFITS |
|---|---|---|
 |
Siemens Healthineers is applying AI and digital simulation to hospital operations. In November 2025, it introduced AI-enabled radiology services and the ActExcell Operational Twin to support imaging workflows and simulate complex hospital scenarios. | Optimizes hospital workflows | Supports capacity and resource planning | Improves imaging productivity | Enables data-driven operational decisions |
 |
In February 2025, Philips and Mass General Brigham announced a collaboration to integrate live medical-device data with clinical information and AI, creating a near-real-time data and insights environment. | Improves clinical data visibility | Supports earlier intervention | Reduces fragmented information | Enhances patient safety and operational efficiency |
 |
In October 2025, GE HealthCare collaborated with Queen’s Health Systems and Duke Health to develop AI-driven hospital operations software using predictive analytics for patient flow and resource optimization. | Improves patient flow | Supports resource optimization | Enables predictive operational insights | Helps care teams improve hospital efficiency |
 |
Oracle is developing cloud-based, AI-enabled hospital information infrastructure through Oracle Health EHR. In November 2025, its next-generation EHR received ONC certification, supporting AI-assisted clinical and administrative workflows. | Reduces administrative workload | Supports scalable digital infrastructure | Improves access to patient information | Enables AI-assisted clinical workflows |
 |
Epic is embedding AI across clinical, patient, and operational workflows. In February 2026, Epic released AI Charting, while its Curiosity models use the Cosmos dataset to support prediction and management of patient outcomes. | Reduces clinician documentation burden | Supports clinical decision-making | Improves patient and clinician workflows | Enables data-driven healthcare delivery |
Logos and trademarks shown above are the property of their respective owners. Their use here is for informational and illustrative purposes only.
Related Ecosystem
Internet Of Things And M2M
- Sensors
- Cellular Network
- Digital Signal Processor (DSP)
- Global Positioning System (GPS)
- Near Field Communication (NFC)
- MITSUI ELECTRONICS INC
- INTEL CORPORATION
- MICROSOFT CORPORATION
- Amazon.com, Inc.
- Cisco Systems, Inc.
Key Takeaways
- Asia Pacific's smart hospital market is valued at $35,759.2 million in 2026 and is forecast to reach $79,562.0 million by 2031, representing a 14.3% CAGR.
- Asia Pacific's growth rate significantly exceeds the global CAGR of 10.6%, indicating accelerated regional adoption of smart hospital technologies.
- Asia Pacific's market expansion is driven by government healthcare modernization initiatives, rising healthcare spending, and increasing IoT and AI integration across hospitals.
- Asia Pacific is positioned to become a dominant region in the global smart hospital market by 2031, driven by both emerging and developed economies.
Smart Hospital Market Report Scope
| Report Metric | Details |
|---|---|
| Base Year | 2026 |
| Fastest Growing Segment | CLOUD-BASED (Deployment Mode) |
| Forecast Period | 2026-2031 |
| Growth Rate | CAGR of 10.6% from 2026 to 2031 |
| Largest Segment | HOSPITALS (End User) |
| Market Size Base Year (Billions) | ~USD 134.49 (2026) |
| Revenue Forecast (Billions) | ~USD 222.58 (2031) |
| Segments Covered | Offering, Type, Deployment Mode, Connectivity Technology, Technology, Application, End User |
Asia Pacific Smart Hospital Market Report Segmentation
7 segment dimensions are covered across the global market.
By Offering
- Hardware
- Services
- Smart Beds
- Software
By Type
- AI Analytics Platforms
- Asset Management Software
- Clinical Decision Support Systems
- Consulting & Advisory Services
- Cybersecurity Software
- Deployment & System Integration Services
- Electronic Health Records
- Hospital Information Systems
- Laboratory Information Systems
- Managed & Support/Maintenance Services
- Medical Imaging Systems
- Networking & Communication Infrastructure
- Other Hardware
- Other Software
- Patient Monitoring Devices
- Radiology Information Systems
- Rfid & Rtls Hardware
- Robots
- Smart Beds
- Smart Therapeutic & Life Support Devices
- Training & Education Services
- Wearable Medical Devices
- Workforce Management Software
By Deployment Mode
- Cloud-Based
- Hybrid
- On-Premises
By Connectivity Technology
- Bluetooth/Ble
- Cellular (4G/5G)
- Ethernet/Lan
- Lorawan/Lpwan
- Near Field Communication
- Rfid
- Wi-Fi
- Zigbee
By Technology
- Artificial Intelligence & Machine Learning
- Big Data Analytics
- Cloud Computing
- Cybersecurity
- Digital Twin
- Edge Computing
- Internet Of Medical Things (Iomt)
- Robotics
By Application
- Asset Tracking
- Building & Energy Management
- Clinical Workflow Optimization
- Diagnostic Imaging
- Hospital Workflow Management
- Medication Management
- Patient Care Management
- Remote Patient Monitoring
- Security & Surveillance
- Telemedicine
By End User
- Academic Medical Centers
- Ambulatory Surgical Centers
- Diagnostic & Imaging Centers
- Hospitals
- Specialty & Outpatient Clinics
Target Audience
- Healthcare IT Vendors : Identify market opportunities and growth potential in Asia Pacific for smart hospital solutions, understand regional adoption rates, and develop localized go-to-market strategies.
- Hospital Operators & Administrators : Benchmark digital transformation initiatives against regional peers, understand technology investment trends, and evaluate smart hospital solutions relevant to Asia Pacific healthcare standards.
- Investment & Private Equity Firms : Assess market size, growth trajectory, and investment opportunities in Asia Pacific smart hospital sector, supporting portfolio decisions and healthcare IT company valuations.
- Government & Healthcare Policy Makers : Understand regional smart hospital adoption trends, technology gaps, and infrastructure investment needs to inform healthcare digitalization policies and funding priorities.
- Technology & IoT Solution Providers : Evaluate Asia Pacific demand for IoT, AI, and cloud technologies in healthcare settings, identify key verticals and use cases, and prioritize regional product development.
Countries within Asia Pacific - compare and drill down
| Country | 2025 size (native) |
|---|---|
| China | USD 22277.4 Million |
| Japan | USD 11934.3 Million |
| India | USD 14321.2 Million |
| South Korea | USD 6365 Million |
| Singapore | USD 2546 Million |
| Australia | USD 5489.8 Million |
| Southeast Asia | USD 9547.4 Million |
| Rest Of Asia Pacific | USD 7081 Million |
Country market size visualization
Reasons to Buy this Report
- Regional Growth Opportunity : Capture insights into the fastest-growing smart hospital market globally, with 14.3% CAGR outpacing global average, enabling strategic market entry and expansion planning across Asia Pacific.
- Country-Level Intelligence : Access detailed market sizing and forecasts for major Asia Pacific economies including China, India, Japan, and Southeast Asia, supporting targeted investment and partnership decisions.
- Technology Adoption Trends : Understand IoT, AI, and cloud adoption patterns specific to Asia Pacific healthcare systems, identifying key technology segments and implementation priorities driving regional market growth.
- Competitive Landscape Analysis : Gain competitive intelligence on regional and global players entering Asia Pacific smart hospital market, including market positioning, partnerships, and growth strategies.
- Investment & Forecast Data : Leverage comprehensive market projections through 2031 with detailed breakdowns by country and technology segment, supporting financial planning and resource allocation decisions.
Frequently asked questions
What is the current size of the smart hospital market in Asia Pacific?
Asia Pacific's smart hospital market is estimated at $35,759.2 million in 2026, making it a significant regional market within the global semiconductor and electronics industry.
What is the projected market size for Asia Pacific smart hospitals by 2031?
Asia Pacific's smart hospital market is forecast to reach $79,562.0 million by 2031, more than doubling from 2026 levels.
What is the CAGR for Asia Pacific's smart hospital market?
Asia Pacific's smart hospital market is growing at a compound annual growth rate of 14.3% from 2026 to 2031, outpacing the global average of 10.6%.
What factors are driving growth in Asia Pacific's smart hospital market?
Key drivers include government healthcare modernization programs, increased healthcare expenditure, rising adoption of IoT and AI technologies, and growing patient populations across the region.
How does Asia Pacific's smart hospital market compare to global growth?
Asia Pacific's 14.3% CAGR significantly exceeds the global CAGR of 10.6%, indicating that the region is experiencing faster adoption and investment in smart hospital technologies than the global average.
RESEARCH METHODOLOGY
The study involved four major activities in estimating the current size of the smart hospital market. Extensive secondary research was conducted to gather information on the market, adjacent healthcare technology markets, and the broader digital health and hospital automation ecosystem. This was followed by primary research with industry stakeholders across the value chain, including smart hospital technology providers, medical device manufacturers, healthcare IT companies, system integrators, consultants, hospital administrators, and end users, to validate assumptions and market sizing. Both top-down and bottom-up approaches were used to estimate the overall market size. Market breakdowns and data triangulation techniques were then applied to derive the size of individual segments and subsegments, including offering, deployment mode, connectivity technology, technology, and regional markets. Secondary and primary sources were jointly used to support a comprehensive technical and commercial analysis of the smart hospital market, covering technologies such as AI, IoMT, cloud computing, robotics, digital twins, analytics, and cybersecurity.
Secondary Research
Various secondary sources were referred to during the secondary research process to identify and collect information relevant to the smart hospital market. These sources included annual reports, investor presentations, company websites, press releases, product literature, white papers, technical journals, healthcare publications, industry associations, government databases, and digital health reports. Secondary research was conducted to obtain key insights into the market's value chain, competitive landscape, technology ecosystem, and segmentation across offering, deployment mode, connectivity technology, technology, and region. It also helped analyze trends in hospital digitalization, AI adoption, IoMT deployment, cloud computing, healthcare automation, connected medical devices, cybersecurity, and smart hospital infrastructure. Publicly available sources from organizations such as AHRQ and healthcare industry bodies were also reviewed to understand digital healthcare adoption, interoperability, clinical workflows, and technology implementation. The data collected was further analyzed to estimate the overall market size and validate market trends, which were subsequently refined through primary research with industry experts, technology providers, healthcare organizations, and other key stakeholders.
Primary Research
Extensive primary research was conducted after gaining knowledge about the current scenario of the smart hospital market through secondary research. Several primary interviews were conducted with experts from the demand and supply sides across four major regions: North America, Europe, Asia Pacific, and RoW. This primary data was collected through questionnaires, emails, and telephonic interviews.
Breakdown of Primary Interviews
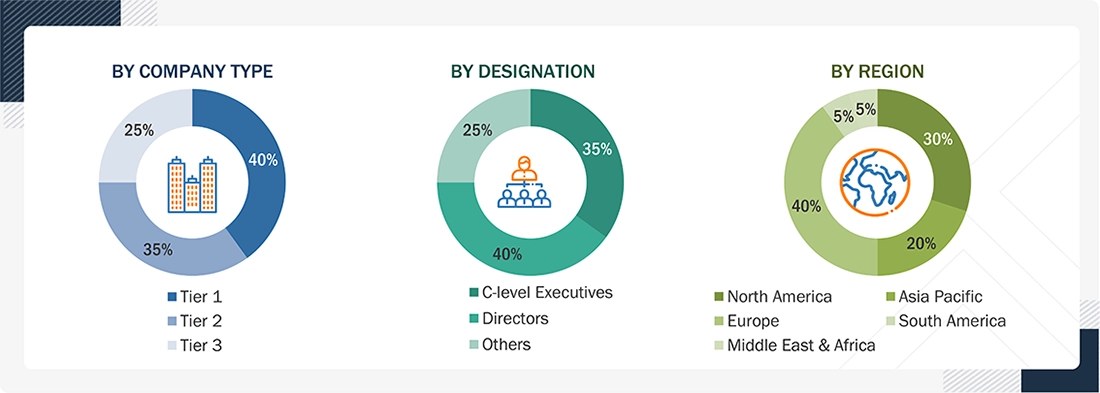
Note: The three tiers of the companies are defined based on their total revenue in 2025: Tier 1 - revenue greater than or equal to USD 1 billion; Tier 2 - revenue between USD 100 million and USD 1 billion; and Tier 3 revenue less than or equal to USD 100 million. Other designations include sales managers, marketing managers, and product managers.
To know about the assumptions considered for the study, download the pdf brochure
Market Size Estimation
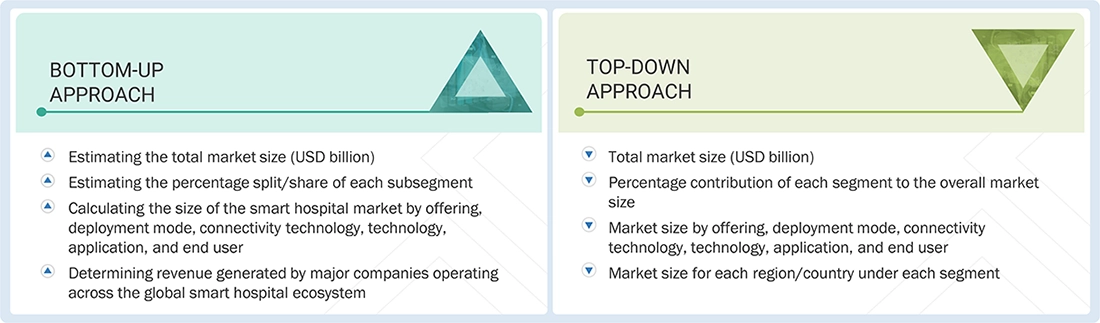
Both top-down and bottom-up approaches were used to estimate and validate the total size of the smart hospital market. These methods have also been used extensively to estimate the size of various subsegments in the market. The following research methodology was used to estimate the market size:
- Approach to arrive at market size using bottom-up analysis(demand side)
- Companies offering smart hospital solutions were identified, and their offerings were mapped based on technology, application, and end-user footprint.
- The global smart hospital market size was derived through the data sanity method. Revenues of key smart hospital technology providers were analyzed through annual reports, investor presentations, company websites, and press releases to estimate the overall market size.
- For each company, a percentage was assigned to the overall revenue to derive revenues attributable to smart hospital-related offerings.
- Each company's percentage contribution was assigned after analyzing factors including its technology portfolio, geographic presence, healthcare customer base, R&D investments, strategic initiatives, and recent developments in the smart hospital market.
- For the CAGR, market trend analysis was carried out by assessing technology adoption, healthcare digitalization, hospital infrastructure investments, and demand for AI, IoMT, cloud computing, robotics, and connected healthcare solutions.
- Estimates at every level were verified and cross-checked through discussions with key opinion leaders, including healthcare technology executives, hospital administrators, technology specialists, and market domain experts.
- Various paid and unpaid information sources, such as annual reports, company websites, press releases, white papers, healthcare publications, and industry databases, were studied.
The top-down approach was used to estimate and validate the total size of the smart hospital market.
- Focusing initially on healthcare technology investments and hospital digitalization expenditure, further splitting the market into offering, deployment mode, connectivity technology, technology, and region, while identifying key developments across major markets.
- Identifying all major players in the smart hospital market and their technology portfolios across healthcare organizations through secondary research, as well as verifying findings through discussions with industry experts.
- Analyzing revenues, technology mix, geographic presence, and key healthcare applications served by identified players to estimate and arrive at percentage splits for all key segments.
- Discussing these splits with industry experts to validate the information and identify key growth pockets across all major segments.
- Breaking down the total market based on verified percentage splits and key growth pockets across all segments and subsegments.
- Breaking down the total market based on verified splits and key growth pockets across all segments.
Smart Hospital Market : Top-Down and Bottom-Up Approach
Data Triangulation
After arriving at the overall size of the smart hospital market through the market size estimation process, the total market was divided into key segments and subsegments. Data triangulation and market breakdown procedures were applied, wherever applicable, to complete the market engineering process and derive statistics for all segments and subsegments. The data was triangulated by analyzing various factors and trends from both the demand and supply sides. Market estimates were validated using information from smart hospital technology providers, healthcare organizations, medical device manufacturers, healthcare IT companies, system integrators, and other industry stakeholders. In addition, the market size was validated using both top-down and bottom-up approaches. The triangulation process also considered technology adoption, hospital digitalization, healthcare IT investments, connected medical devices, AI deployment, and regional smart hospital development.
Market Definition
A smart hospital is a healthcare facility that integrates connected digital technologies, intelligent infrastructure, and data-driven systems to improve patient care, operational efficiency, resource utilization, and hospital management. It incorporates technologies such as artificial intelligence and machine learning, the Internet of Medical Things (IoMT), cloud and edge computing, big data analytics, robotics, digital twins, advanced connectivity, and cybersecurity. Smart hospitals enable connected patient monitoring, digital clinical workflows, automated hospital operations, real-time information exchange, remote care, and data-driven decision-making. They integrate hardware, software, connectivity infrastructure, and services across clinical and non-clinical environments, including patient monitoring, medical imaging, electronic health records, hospital information systems, asset management, workforce management, and facility operations.
Smart hospital technologies play an important role across general hospitals, specialty hospitals, academic medical centers, private hospital networks, and government healthcare facilities. They help address rising patient volumes, workforce constraints, increasing healthcare costs, and the need for more efficient and coordinated care delivery. The market encompasses solutions deployed across hardware, software, and services, with applications spanning clinical care, diagnostics, patient engagement, hospital administration, asset management, and facility management. During the forecast period, increasing integration of AI, IoMT, cloud computing, robotics, advanced connectivity, and cybersecurity is expected to support the transition from conventional digital hospitals toward more connected, intelligent, automated, and data-driven healthcare environments.
Key Stakeholders
- Smart hospital technology vendors
- Medical device manufacturers
- Healthcare IT and software providers
- Cloud and data platform providers
- AI and analytics solution providers
- IoT and connectivity technology providers
- Semiconductor and component suppliers
- RFID and RTLS solution providers
- Cybersecurity solution providers
- System integrators and consulting firms
- Hospital infrastructure and building automation providers
- Hospitals and health systems
- Academic medical centers
- Specialty and outpatient care providers
- Diagnostic and imaging centers
- Healthcare professionals and clinical staff
- Government healthcare authorities
- Regulatory and certification bodies
- Insurance companies and healthcare payers
- Distributors and channel partners
- After-sales, maintenance, and lifecycle service providers
- Research institutions and technology partners
Report Objectives
- To define, describe, and forecast the smart hospital market by offering, deployment mode, connectivity technology, technology, end user, application, and region, in terms of value
- To forecast the market size by region—North America, Europe, Asia Pacific, South America, and Middle East & Africa, in terms of value
- To provide qualitative information about smart hospital applications, digital healthcare trends, technology adoption, and advancements in connected hospital infrastructure
- To provide detailed information regarding the major factors influencing market growth, namely, drivers (increasing adoption of connected medical devices, AI-enabled healthcare, and hospital automation), restraints (high implementation costs, interoperability challenges, and cybersecurity concerns), opportunities (expansion of cloud-based healthcare, remote patient monitoring, and AI-enabled clinical applications), and challenges (data privacy, legacy-system integration, regulatory compliance, and workforce readiness)
- To estimate the market size in terms of value for hardware, including patient monitoring devices, smart beds, medical imaging systems, smart therapeutic & life-support devices, networking & communication infrastructure, RFID & RTLS hardware, wearable medical devices, robots, and other hardware
- To estimate the market size in terms of value for software, including EHR, HIS, CDSS, LIS, RIS, asset management software, AI analytics platforms, workforce management software, cybersecurity software, and other software
- To estimate the market size in terms of value for services, including consulting & advisory services, deployment & system integration services, managed & support/maintenance services, and training & education services
- To strategically analyze micromarkets with respect to individual growth trends, prospects, and contributions to the overall smart hospital market
- To study the complete smart hospital value chain, including technology providers, medical device manufacturers, healthcare IT companies, system integrators, service providers, healthcare organizations, and end users
- To analyze opportunities in the market for stakeholders by identifying high-growth segments such as AI & ML, IoMT, cloud computing, edge computing, robotics, digital twins, cybersecurity, remote monitoring, and connected medical infrastructure
- To strategically profile key players and comprehensively analyze their core competencies, along with detailing the competitive landscape for market leaders
- To analyze competitive developments such as product launches, partnerships, collaborations, acquisitions, expansions, and technology integrations in the smart hospital market
- To benchmark market players using company evaluation frameworks based on various parameters within business strategies, technology capabilities, product portfolios, geographic presence, and smart hospital solutions
- To provide a macroeconomic outlook for all regions covered in this report, considering healthcare expenditure, hospital modernization, digital health initiatives, AI adoption, healthcare infrastructure development, and technology investments
- To provide information on ecosystem analysis, case study analysis, technology trends, emerging applications, interconnected markets, and cross-sector opportunities, along with the impact of evolving healthcare regulations, interoperability requirements, cybersecurity standards, and digitalization trends on the smart hospital market
Available customizations:
With the market data given, MarketsandMarkets offers customizations according to the company’s specific needs. The following customization options are available for the report:
Company Information
-
Detailed analysis and profiling of additional market players (up to 5)
Get the Full Smart Hospital Market Report
Full forecast, segment splits, and company analysis for all Smart Hospital Market.
- US Smart Hospital Market
- Canada Smart Hospital Market
- Mexico Smart Hospital Market
- UK Smart Hospital Market
- Germany Smart Hospital Market
- France Smart Hospital Market
- Italy Smart Hospital Market
- Spain Smart Hospital Market
- Netherlands Smart Hospital Market
- China Smart Hospital Market
- Japan Smart Hospital Market
- South Korea Smart Hospital Market
- India Smart Hospital Market
- Singapore Smart Hospital Market
- Australia Smart Hospital Market
- Brazil Smart Hospital Market
- Argentina Smart Hospital Market
- South Africa Smart Hospital Market
- Nordics Smart Hospital Market
- Rest Of Europe Smart Hospital Market
- Rest Of Asia Pacific Smart Hospital Market
- Southeast Asia Smart Hospital Market
- GCC Countries Smart Hospital Market
- Rest Of South America Smart Hospital Market
Need a Tailored Report?
Customize this report to your needs
Get 10% FREE Customization
Customize This Report