Europe Student Information System (SIS) Market (2026-2031)

The Europe Student Information System (SIS) Market was valued at $2224.2 Million in 2026 and projected to reach to $3946.8 Million by 2031, representing a compound annual growth rate of 12.2%. Europe's Student Information System market is positioned for sustained expansion through 2031, supported by institutional investments in digital infrastructure and regulatory mandates.


| Market Size in | USD 26.32 MN |
| Market Forecast in | |
| CAGR | |
| Forecast Period | |
| Units Considered | Value (USD MN) |
Europe Student Information System (SIS) Market Trends and Insights
- This 12.2% compound annual growth rate reflects Europe's increasing investment in digital transformation across educational institutions, driven by regulatory compliance requirements, modernization of legacy systems, and the shift toward cloud-based solutions.
- Europe's diverse regulatory landscape and emphasis on data protection standards are shaping SIS adoption patterns across the region. The European SIS market benefits from strong government initiatives promoting digital education infrastructure and institutional funding for technology upgrades.
- Europe's educational institutions are prioritizing integrated platforms that streamline student lifecycle management, from enrollment through graduation.
- The forecast period (2026-2031) will see Europe consolidating its position as a mature yet expanding market, with particular growth in Northern and Western Europe driven by advanced IT infrastructure and higher education spending..
Key Market Statistics
- CAGR (2026-2031) 12.2% CAGR
- Market Size, 2026 ~USD 2224.2 Million
- Forecast, 2031 ~USD 3946.8 Million
- Geography Europe
Europe Student Information System (SIS) Market Overview
Strong Regional Growth Trajectory :
Europe's SIS market is expanding at 12.2% CAGR, growing from $2,224.2 million in 2026 to $3,946.8 million by 2031, driven by digital transformation initiatives across educational institutions.
Regulatory Compliance Momentum :
European educational institutions are increasingly adopting SIS solutions to meet stringent GDPR, data protection, and accessibility compliance requirements, creating sustained demand for compliant platforms.
Legacy System Modernization Wave :
Schools and universities across Europe are prioritizing replacement of outdated administrative systems with cloud-based, integrated SIS platforms to improve operational efficiency and student outcomes.
Digital-First Education Shift :
Post-pandemic acceleration of digital learning infrastructure investments in Europe is fueling adoption of comprehensive student information systems that support hybrid and remote education models.
Europe Student Information System (SIS) Market Dynamics
- Educational institutions across the region are prioritizing system modernization to enhance administrative efficiency, improve student engagement, and ensure compliance with evolving data protection standards.
- The shift toward integrated, cloud-based solutions reflects Europe's commitment to educational excellence and digital transformation. Key growth drivers include increasing government funding for educational technology, rising adoption of analytics-driven decision-making in schools and universities, and the need for interoperable systems that support cross-border student mobility.
- European vendors and international players are expanding offerings tailored to regional requirements, while partnerships between EdTech providers and educational institutions are accelerating market penetration across primary, secondary, and higher education segments..
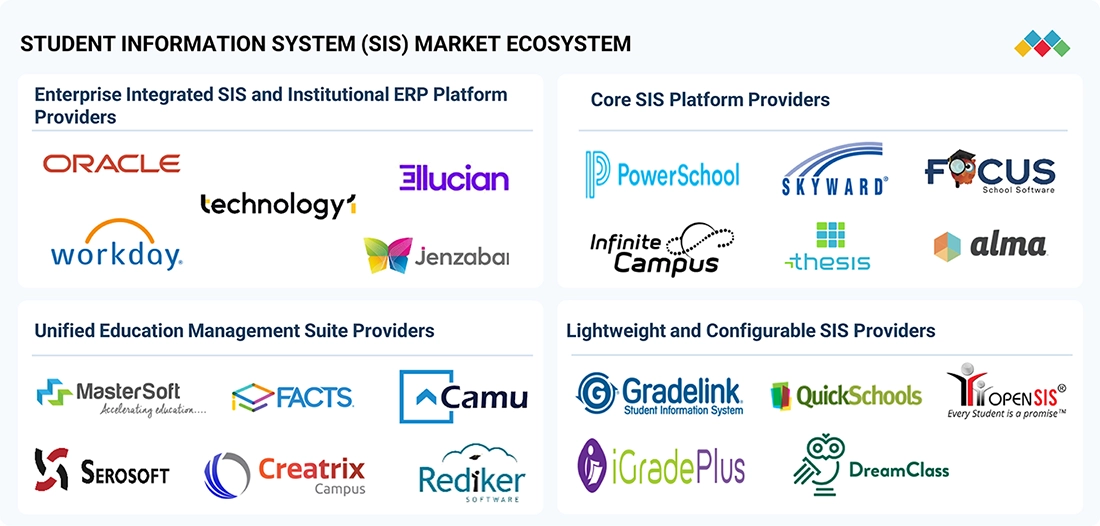
Market Ecosystem
STUDENT INFORMATION SYSTEM MARKET: COMMERCIAL USE CASES ACROSS INDUSTRIES
| COMPANY | USE CASE DESCRIPTION | BENEFITS |
|---|---|---|
 |
Florida Polytechnic University modernizes student operations with Ellucian to create a unified digital campus experience | Achieved 92% student satisfaction across integrated platforms | Increased student mobile usage by 70% | Reduced login barriers by 85% | Cut infrastructure and licensing costs by 40% | Generated more than 60% soft cost savings through reclaimed staff time | Retired more than 100 legacy customizations | Reduced system integrations by 55% | Reduced custom reports by 44% |
 |
Northpointe Christian Schools builds an integrated and secure education ecosystem with PowerSchool | Improved student data accuracy by eliminating repetitive manual data entry | Strengthened data security through centralized, cloud-hosted system management | Created seamless data flow across enrollment, SIS, and LMS environments | Simplified enrollment and re-enrollment processes for families and administrative staff | Achieved earlier re-enrollment completion from more families than previously recorded | Reduced duplicate spreadsheets, disconnected records, and outdated information silos |
 |
Ambrose University strengthens institutional agility and student experience with Jenzabar one | Reduced operational bottlenecks through streamlined and automated processes | Improved staff efficiency across connected institutional workflows | Integrated previously fragmented tools within a unified platform environment | Centralized critical information for faster institutional access | Strengthened organizational agility through improved process coordination |
 |
Calvert Hall College high school unifies the student lifecycle and school operations with Blackbaud | Established a single, consistent student and family data environment | Eliminated departmental silos across academic and administrative functions | Enabled real-time student information updates across connected departments | Improved cross-functional collaboration by creating a unified schoolwide platform | Provided families with one access point for grades, schedules, assignments, communications, activities, and bills | Strengthened parent engagement through comprehensive visibility into student information |
 |
Redlands Sydney advances toward unified school operations with Veracross and Accucom | Advanced the implementation four weeks ahead of schedule during the early project stage |Targeted SIS launch within six months of the reported implementation phase | Created a pathway to reduce data silos across school systems | Established shared information access across enrollment, student support, teaching, and alumni teams | Improved prospects for faster access to timely institutional information |
Logos and trademarks shown above are the property of their respective owners. Their use here is for informational and illustrative purposes only.
Related Ecosystem
Cloud Computing
- Software as A Service (SaaS)
- Natural Language Processing (NLP)
- Platform as A Service (PaaS)
- Machine Learning
- Supply Chain Management
- International Business Machines Corporation
- MICROSOFT CORPORATION
- Oracle Corporation
- Amazon.com, Inc.
Software And Services
- Natural Language Processing (NLP)
- Machine Learning
- Supply Chain Management
- Predictive Analytics
- Image Sensors
- International Business Machines Corporation
- MICROSOFT CORPORATION
- Oracle Corporation
- SAP SE
- Amazon.com, Inc.
Information System And Analytics
- Machine Learning
- Natural Language Processing (NLP)
- Sensors
- Software as A Service (SaaS)
- Data Loss Prevention (DLP)
- International Business Machines Corporation
- MICROSOFT CORPORATION
- Amazon.com, Inc.
- Oracle Corporation
Key Takeaways
- Europe's SIS market will grow from $2,224.2M (2026) to $3,946.8M (2031), representing a 12.2% CAGR driven by digital transformation and regulatory compliance.
- Europe's emphasis on GDPR and data protection standards is accelerating adoption of secure, compliant SIS solutions across educational institutions.
- Cloud-based and integrated SIS platforms are gaining traction in Europe as institutions seek scalability and reduced IT infrastructure costs.
- Northern and Western Europe lead market growth, supported by higher education funding and advanced digital infrastructure maturity.
Student Information System (SIS) Market Report Scope
| Report Metric | Details |
|---|---|
| Base Year | 2026 |
| Fastest Growing Segment | AI-ENABLED SIS (Technology) |
| Forecast Period | 2026-2031 |
| Growth Rate | CAGR of 12.9% from 2026 to 2031 |
| Largest Segment | STUDENT INFORMATION SYSTEM (SIS) SOFTWARE (Offering) |
| Market Size Base Year (Billions) | ~USD 8.37 (2026) |
| Revenue Forecast (Billions) | ~USD 15.36 (2031) |
| Segments Covered | Offering, Service, Professional Service, Platform Module, Technology, Deployment Mode, End User |
Europe Student Information System (SIS) Market Report Segmentation
7 segment dimensions are covered across the global market.
By Offering
- Services
- Student Information System (Sis) Software
By Service
- Managed Services
- Professional Services
By Professional Service
- Consulting & Strategy
- Implementation & Integration
- Training & Support
By Platform Module
- Academia Management
- Admission & Recruitment
- Analytics & Compliance
- Communication & Engagement
- Core Student Administration
- Financial Management
- Other Platform Modules
By Technology
- AI-Enabled Sis
- Conventional/Rule-Based Sis
By Deployment Mode
- Cloud-Based
- On-Premises
By End User
- Higher Education Institutions
- K-12/Schools
- Vocational, Skills & Professional Training Institutions
- Vocational, Skills & Professionaltraining Institutions
Target Audience
- EdTech Solution Providers : SIS vendors and EdTech companies need Europe-specific market intelligence to refine product offerings, identify high-growth segments, and develop localized strategies for compliance and regional requirements.
- Educational Institution Leaders : School administrators, university IT directors, and education procurement teams require market insights to benchmark SIS investments, evaluate vendor options, and justify digital transformation budgets.
- Investment & Private Equity Firms : Investors targeting the European EdTech sector need detailed market sizing, growth forecasts, and competitive analysis to identify acquisition targets and assess portfolio company performance.
- System Integrators & Consultants : IT consulting firms and system integrators serving European educational institutions need market data to support client advisory services, solution design, and implementation roadmaps.
- Government & Policy Makers : Education ministries and policy organizations across Europe require market intelligence to inform digital education strategies, funding allocation, and regulatory frameworks for institutional technology adoption.
Countries within Europe - compare and drill down
| Country | 2025 size (native) |
|---|---|
| UK | USD 1022.2 Million |
| Germany | USD 1049.9 Million |
| France | USD 817 Million |
| Italy | USD 568.3 Million |
| Rest Of Europe | USD 489.4 Million |
Country market size visualization
Reasons to Buy this Report
- Regional Market Sizing & Forecasts : Access precise market valuations for Europe's SIS sector with country-level breakdowns for UK, Germany, France, Italy, and Rest of Europe, enabling targeted investment and expansion strategies.
- Competitive Landscape Intelligence : Understand market dynamics, vendor positioning, and competitive strategies specific to European educational institutions, helping identify partnership and acquisition opportunities.
- Regulatory & Compliance Insights : Gain detailed analysis of GDPR, data protection, and accessibility compliance requirements driving SIS adoption across Europe, critical for product development and market entry planning.
- Growth Driver Analysis : Identify key factors accelerating 12.2% CAGR growth including digital transformation budgets, legacy system replacement cycles, and government education funding trends across European markets.
- Strategic Decision Support : Leverage comprehensive market data to inform go-to-market strategies, pricing models, and feature prioritization for European educational institutions and regional EdTech vendors.
Frequently asked questions
What is the current size of Europe's Student Information System market?
Europe's SIS market was valued at $2,224.2 million in 2026 and is forecast to reach $3,946.8 million by 2031.
What is the expected growth rate for Europe's SIS market?
Europe's SIS market is expected to grow at a compound annual growth rate (CAGR) of 12.2% between 2026 and 2031.
What are the primary drivers of SIS adoption in Europe?
Key drivers include digital transformation initiatives, GDPR and data protection compliance requirements, modernization of legacy systems, and the shift toward cloud-based educational technology solutions.
Which regions within Europe are experiencing the fastest SIS market growth?
Northern and Western Europe are leading the market, driven by advanced IT infrastructure, higher education funding, and institutional investment in digital transformation.
How is Europe's regulatory environment influencing SIS market development?
Europe's strict data protection standards, particularly GDPR, are driving demand for SIS solutions with robust security, compliance, and privacy features, shaping vendor offerings and institutional procurement decisions.
RESEARCH METHODOLOGY
This research study on the student information system (SIS) market involved extensive secondary sources, including directories, IEEE Communication-Efficient: Algorithms and Systems, and the International Journal of Innovation and Technology Management, as well as paid databases. Primary sources were mainly industry experts from core and related industries, preferred student information system software providers, third-party service providers, consulting service providers, end users, and other commercial enterprises. In-depth interviews with primary respondents, including key industry participants and subject matter experts, were conducted to gather and verify critical qualitative and quantitative information, as well as to assess the market’s prospects.
Secondary Research
In the secondary research process, various sources were referred to to identify and collect information for this study. Secondary sources included annual reports, press releases, and investor presentations of companies; white papers, journals, and certified publications; and articles from recognized authors, directories, and databases. The data was also collected from other secondary sources, such as journals, government websites, blogs, and vendors’ websites. Additionally, the SIS spending of various countries was extracted from the respective sources.
Primary Research
In the primary research process, various sources from the supply and demand sides were interviewed to obtain qualitative and quantitative information on the market. The primary sources from the supply side included various industry experts, such as chief experience officers (CXOs), vice presidents (VPs), and directors specializing in business development, marketing, and student information system services. It also included key executives from SIS vendors, system integrators, professional service providers, industry associations, and other key opinion leaders.

Note: Tier 1 companies’ revenues are more than USD 10 billion; tier 2 companies’ revenues range between USD 1 and 10 billion; and tier 3 companies’ revenues range between USD 500 million and USD 1 billion. Other designations include sales, marketing, and product managers.
Source: Industry Experts
To know about the assumptions considered for the study, download the pdf brochure
Market Size Estimation
Multiple approaches were adopted to estimate and forecast the student information system (SIS) market. The first approach involved estimating the market size based on companies’ revenue from the sale of SIS products.
Market Size Estimation Methodology: Top-down Approach
The top-down approach prepared an exhaustive list of all the vendors offering products in the student information system (SIS) market. The revenue contribution of the market vendors was estimated through annual reports, press releases, funding, investor presentations, paid databases, and primary interviews. Each vendor’s offerings were evaluated based on offering, platform module, technology, deployment mode, end user, and region. The markets were triangulated through primary and secondary research. The primary procedure included extensive interviews for key insights from industry leaders, such as CIOs, CEOs, VPs, directors, and marketing executives. The market numbers were further triangulated with the existing MarketsandMarkets’ repository for validation.
Market Size Estimation Methodology: Bottom-up Approach
The bottom-up approach identified the adoption rate of student information system (SIS) products across different verticals in key countries, considering the regions that contribute the most to the market share. For cross-validation, the adoption of SIS products among enterprises and other use cases for their regions was identified and extrapolated. Use cases identified in different areas were weighed for the market size calculation.
Based on the market numbers, the regional split was determined by primary and secondary sources. The procedure included an analysis of the SIS market’s regional penetration. Based on secondary research, the regional spending on Information and Communications Technology (ICT), socioeconomic analysis of each country, strategic vendor analysis of major student information system service providers, and organic and inorganic business development activities of regional and global players were estimated.
Student Information System (SIS) Market : Top-Down and Bottom-Up Approach

Data Triangulation
After arriving at the overall market size—using the market size estimation processes—the market was split into several segments and subsegments. To complete the overall market engineering process and arrive at the exact statistics of each market segment and sub-segment, the data triangulation and market breakdown procedures were employed, wherever applicable. The data was triangulated by studying various factors and trends from both the demand and supply sides in the AI in drug discovery market. After determining the overall market size using the market size estimation processes as explained above, the market was split into several segments and subsegments. Data triangulation and market breakup procedures were employed, wherever applicable, to complete the overall market engineering process and arrive at the exact statistics of each market segment and subsegment. The overall market size was then used in the top-down approach to estimate the size of other individual markets by applying percentage splits to the market segmentation.
Market Definition
The student information system (SIS) market comprises software platforms and associated services that enable educational institutions to manage, automate, and optimize student lifecycle operations from enrollment and admissions through academics, attendance, assessments, financial management, graduation, and alumni records. These platforms serve as the central repository for student, faculty, academic, and administrative data while facilitating workflow automation, regulatory compliance, reporting, and integration with learning management systems, enterprise resource planning solutions, financial systems, and other campus applications. The market includes cloud-based and on-premises deployments, along with implementation, integration, consulting, training, support, and managed services, serving K–12 schools, higher education institutions, and vocational and professional training providers.
Key Stakeholders
-
- Student Information System (SIS) Software Providers
- Cloud-based Student Information System Solution Providers
- Student Lifecycle Management Platform Providers
- Student Enrollment and Admissions Management Solution Providers
- Academic Records and Registrar Management Software Providers
- Student Financial Management and Billing Solution Providers
- Learning Management System (LMS) Integration Providers
- Enterprise Resource Planning (ERP) Software Providers for Education
- Education Data Analytics and Business Intelligence Solution Providers
- Artificial Intelligence and Automation Technology Providers for Education
- Identity and Access Management (IAM) Solution Providers
- Cloud Infrastructure Providers and Hyperscalers
- System Integrators and SIS Implementation Partners
- Education Technology (EdTech) Consulting Service Providers
- Managed SIS Service Providers
Report Objectives
- To define and describe the student information system (SIS) market based on offering (student information system software and services), platform module (core student administration, academia management, financial management, admission & recruitment, communication & engagement, analytics & compliance, other platform modules), technology (conventional/rule-based SIS and AI-enabled SIS), deployment mode (on-premises and cloud-based), and end user
- To provide detailed information on major factors influencing market growth (drivers, restraints, opportunities, and challenges) across student information systems, finances planning, student profile management, and aftermarket transformation
- To strategically analyze micro markets with respect to individual growth trends, adoption patterns, and their contribution to the overall market
- To analyze market opportunities for stakeholders and present a comprehensive competitive landscape of leading student information system vendors, OEM aftermarket players, and service providers
- To project the market size and its submarkets in terms of value (USD million) across five key regions (North America, Europe, Asia Pacific, Middle East & Africa, Latin America), along with an analysis of their respective major countries
- To strategically profile leading companies and provide an in-depth evaluation of their core competencies, product portfolios, technology capabilities, and market positioning
- To examine competitive developments, including product launches, software upgrades, partnerships, integrations, strategic expansions, and mergers & acquisitions across the SIS ecosystem
Customizations Options:
With the given market data, MarketsandMarkets offers customizations as per the company’s specific needs. The following customization options are available for the report:
Product Analysis
- The product matrix provides a detailed comparison of the product portfolio of each company.
Geographic Analysis based on Feasibility
- Further breakup of the North America student information system market
- Further breakup of the Europe student information system market
- Further breakup of the Asia Pacific student information system market
- Further breakup of the Middle East & Africa student information system market
- Further breakup of the Latin America student information system market
Company Information
- Detailed analysis and profiling of additional market players (up to five)
Get the Full Student Information System (SIS) Market Report
Full forecast, segment splits, and company analysis for all Student Information System (SIS) Market.
- US Student Information System (SIS) Market
- Canada Student Information System (SIS) Market
- UK Student Information System (SIS) Market
- Germany Student Information System (SIS) Market
- France Student Information System (SIS) Market
- Italy Student Information System (SIS) Market
- China Student Information System (SIS) Market
- India Student Information System (SIS) Market
- Japan Student Information System (SIS) Market
- South Korea Student Information System (SIS) Market
- Saudi Arabia Student Information System (SIS) Market
- UAE Student Information System (SIS) Market
- South Africa Student Information System (SIS) Market
- Brazil Student Information System (SIS) Market
- Mexico Student Information System (SIS) Market
- Rest Of Europe Student Information System (SIS) Market
- Rest Of Asia Pacific Student Information System (SIS) Market
- Rest Of Latin America Student Information System (SIS) Market
- GCC Student Information System (SIS) Market
- Rest Of Mea Student Information System (SIS) Market
- Rest Of GCC Student Information System (SIS) Market
Need a Tailored Report?
Customize this report to your needs
Get 10% FREE Customization
Customize This Report
