UK Train Battery Market (2026-2031)

The UK Train Battery Market was valued at $1450 Million in 2026 and projected to reach to $1685 Million by 2031, representing a compound annual growth rate of 2.2%. The UK train battery market is positioned for steady growth driven by government electrification mandates and sustainability commitments.


| Market Size in | USD 26.32 MN |
| Market Forecast in | |
| CAGR | |
| Forecast Period | |
| Units Considered | Value (USD MN) |
UK Train Battery Market Trends and Insights
- The UK's rail electrification initiatives and investment in sustainable transportation infrastructure are driving moderate but steady demand for advanced battery technologies in the train sector.
- The UK's commitment to decarbonizing rail transport and modernizing aging rolling stock continues to support market expansion through the forecast period. The UK train battery market reflects the nation's broader transition toward zero-emission rail operations.
- By 2031, the UK is expected to see increased adoption of battery-electric and hybrid train systems, particularly on regional and commuter routes where full electrification remains economically challenging.
- The UK's regulatory framework and government funding mechanisms are facilitating gradual market penetration, though growth remains constrained by high capital costs and infrastructure limitations compared to global peers..
Key Market Statistics
- CAGR (2026-2031) 2.2% CAGR
- Market Size, 2026 ~USD 1450 Million
- Forecast, 2031 ~USD 1685 Million
- Country UK
UK Train Battery Market Overview
UK Rail Electrification Push :
The UK government's commitment to electrifying rail networks across England, Scotland, and Wales is accelerating battery technology adoption. Major projects like the Midland Main Line and Great Western Railway upgrades are creating sustained demand for advanced train battery solutions.
Moderate Growth Trajectory :
The UK train battery market is projected to grow from £1,450 million in 2026 to £1,685 million by 2031 at a 2.2% CAGR, reflecting steady but conservative expansion compared to the global 5.3% growth rate, indicating a maturing market with established infrastructure.
Decarbonization Regulatory Framework :
UK transport decarbonization targets and Net Zero commitments are driving investment in battery-electric and hydrogen-hybrid train technologies. Network Rail and train operators are prioritizing sustainable alternatives to diesel-powered services across regional and commuter routes.
Regional Infrastructure Investment :
Significant capital allocation from the Department for Transport and local transport authorities is supporting battery technology integration. The Levelling Up agenda includes rail modernization funding that directly benefits battery system procurement and deployment across underserved UK regions.
UK Train Battery Market Dynamics
- While growth rates lag behind global averages, the UK's mature rail infrastructure and regulatory environment create predictable, long-term demand for battery technologies.
- Investment in regional rail networks and the transition away from diesel services will sustain market expansion through 2031. Key opportunities exist in retrofitting existing rolling stock and developing next-generation battery systems for longer-range regional services.
- However, market maturity and established supplier relationships may limit rapid expansion.
- Strategic partnerships with Network Rail and train operating companies will be essential for capturing growth in this regulated, infrastructure-dependent sector..
Market Ecosystem
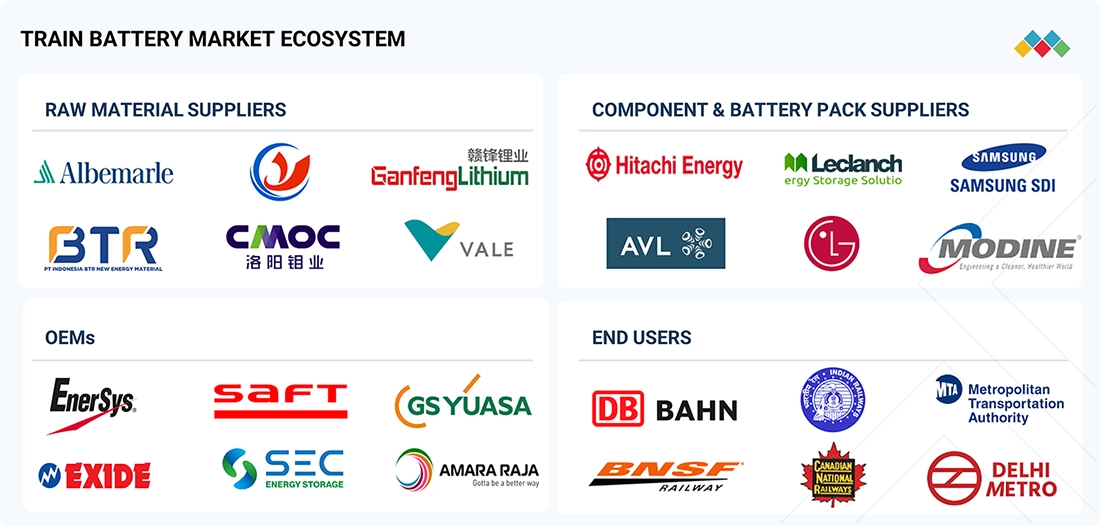
TRAIN BATTERY MARKET SIZE, SHARE & ANALYSIS: COMMERCIAL USE CASES ACROSS INDUSTRIES
| COMPANY | USE CASE DESCRIPTION | BENEFITS |
|---|---|---|
 |
Expanding its NexSys iON lithium-ion battery platform, advanced Thin Plate Pure Lead (TPPL) batteries, and intelligent Battery Management Systems (BMS) for transportation and industrial applications | Enables EnerSys to address growing demand for maintenance-free, longer-life, and digitally connected battery systems in modern rail fleets |
 |
Investing in Intensium lithium-ion battery systems, rail-certified LFP (Lithium Iron Phosphate) and NMC-based energy storage solutions, and modular traction battery platforms for battery-electric and hybrid trains | Strengthens its position in battery-electric rolling stock, hybrid train projects, and railway decarbonization initiatives |
 |
Focusing on industrial lithium-ion batteries, high-capacity LIM series lithium-ion systems, energy storage systems (ESS), and next-generation high-cycle-life battery technologies | Supports demand for reliable, long-life batteries in metros, passenger trains, and railway backup power applications while expanding into future traction battery opportunities |
 |
Investing in LFP lithium-ion cell manufacturing, battery pack assembly, Battery Management Systems (BMS), and gigafactory development through its advanced energy business | Positions the company to benefit from India's railway electrification, metro expansion, and increasing localization of lithium-ion battery sourcing |
Logos and trademarks shown above are the property of their respective owners. Their use here is for informational and illustrative purposes only.
Related Ecosystem
Automotive Materials
- Light Commercial Vehicles (LCVs)
- Battery Electric Vehicle (BEV)
- Hybrid Electric Vehicle (HEV)
- Fuel Cell Electric Vehicle (FCEV)
- Agricultural Tractors
- AISIN CORPORATION
- GORKOVSKY AVTOMOBILNY ZAVOD
- Basf se
- BOSCH LIMITED
- Continental ag
Locomotives And Rolling Stock
- Sensors
- Passenger Information System (PIS)
- Cartesian Robots
- Flow Sensors
- Gas Sensors
- Alstom s.a.
- Siemens ag
- Hitachi, Ltd.
- SYSTRA LTD.
- Knorr-bremse ag
Logistics And Transportation
- Internal Combustion Engine (ICE)
- Crawler Excavator
- Fuel Cell
- Light Commercial Vehicles (LCVs)
- Sensors
- Siemens ag
- Alstom s.a.
- Hitachi, Ltd.
- Godrej Industries Limited
- Toshiba Corporation
Key Takeaways
- The UK train battery market will grow from £1,450M (2026) to £1,685M (2031) at a 2.2% CAGR.
- The UK's rail decarbonization agenda and government support are primary drivers of battery adoption in trains.
- The UK market faces constraints from high infrastructure costs and limited electrification on regional routes.
- By 2031, the UK will see expanded deployment of battery-electric and hybrid train systems on non-electrified lines.
Train Battery Market Report Scope
| Report Metric | Details |
|---|---|
| Base Year | 2026 |
| Fastest Growing Segment | FULLY BATTERY-OPERATED TRAINS (Advanced Train Type) |
| Forecast Period | 2026-2031 |
| Growth Rate | CAGR of 5.3% from 2026 to 2031 |
| Largest Segment | VALVE-REGULATED LEAD-ACID (VRLA) BATTERIES (Battery Technology) |
| Market Size Base Year (Billions) | ~USD 0.38 (2026) |
| Revenue Forecast (Billions) | ~USD 0.5 (2031) |
| Segments Covered | Battery Type, Battery Technology, Application & Battery Type, Engine/Head, Application, Advanced Train Type, Rolling Stock |
UK Train Battery Market Report Segmentation
7 segment dimensions are covered across the global market.
By Battery Type
- Lead-Acid Batteries
- Lithium-Ion Batteries
- Nickel-Cadmium Batteries
By Battery Technology
- Conventional Lead-Acid Batteries
- Fiber/Pne Nickel-Cadmium Batteries
- Gel Tubular Lead-Acid Batteries
- Lithium Iron Phosphate (Lfp)
- Lithium Titanate Oxide (Lto)
- Pocket Plate Nickel-Cadmium Batteries
- Sinter/Pne Nickel-Cadmium Batteries
- Valve-Regulated Lead-Acid (Vrla) Batteries
By Application & Battery Type
- Auxiliary Batteries
- Starter Batteries
By Engine/Head
- Diesel Locomotives
- Diesel Multiple Units (Dmus)
- Electric Locomotives
- Electric Multiple Units (Emus)
By Application
- Auxiliary Batteries
- High-Speed Trains
- Light Rails/Trams/ Monorails
- Light Rails/Trams/Monorails
- Metros
- Passenger Coaches
- Starter Batteries
By Advanced Train Type
- Fully Battery-Operated Trains
- Hybrid Trains
By Rolling Stock
- Locomotives
- Multiple Units
- Passenger Coaches
Target Audience
- Train Operating Companies (TOCs) : UK rail operators need market intelligence to evaluate battery technology investments, plan fleet modernization, and align procurement strategies with electrification timelines and regulatory requirements.
- Battery & Energy Technology Suppliers : Manufacturers and suppliers require UK-specific market data to assess demand, identify customer segments, develop localized product offerings, and establish partnerships with rail infrastructure stakeholders.
- Network Rail & Infrastructure Planners : Rail infrastructure managers need forecasts and market insights to guide capital investment decisions, technology selection, and long-term planning for electrification projects across UK rail networks.
- Government & Policy Makers : UK transport authorities and policymakers require market analysis to evaluate decarbonization progress, allocate funding effectively, and assess the viability of rail electrification targets and sustainability goals.
- Investment & Financial Analysts : Investors and financial institutions need UK market data to evaluate opportunities in rail modernization, assess portfolio companies in the transport sector, and understand growth potential in sustainable rail technologies.
Reasons to Buy this Report
- Regulatory Compliance Intelligence : Understand UK-specific rail electrification standards, Net Zero requirements, and Department for Transport mandates that directly impact battery procurement decisions and technology specifications for train operators.
- Market Sizing & Forecasting : Access precise UK market valuations (£1,450M-£1,685M) and regional growth projections to inform investment decisions, capacity planning, and competitive positioning within the constrained UK rail battery sector.
- Regional Opportunity Mapping : Identify high-priority electrification corridors and regional rail projects across England, Scotland, and Wales where battery technology deployment is accelerating, enabling targeted sales and partnership strategies.
- Competitive Landscape Analysis : Benchmark against established UK and European battery suppliers, understand supplier concentration, and identify gaps in the market for innovative battery solutions tailored to British rail infrastructure requirements.
- Strategic Investment Guidance : Make informed decisions on R&D investment, market entry timing, and partnership development with Network Rail, train operators, and transport authorities based on data-driven UK market dynamics and growth trajectories.
Frequently asked questions
What is the current size of the UK train battery market?
The UK train battery market is valued at £1,450 million in 2026 and is expected to reach £1,685 million by 2031.
What is the growth rate of the UK train battery market?
The UK train battery market is projected to grow at a compound annual growth rate (CAGR) of 2.2% from 2026 to 2031.
What factors are driving growth in the UK train battery market?
The UK's rail decarbonization initiatives, government funding for sustainable transport, and modernization of rolling stock are key drivers of market growth.
Which train types are most likely to adopt batteries in the UK?
Regional and commuter trains on non-electrified lines are the primary candidates for battery-electric and hybrid systems in the UK market.
What challenges does the UK train battery market face?
High capital costs, limited infrastructure for full electrification, and the need for significant investment in charging systems are major challenges for the UK market.
RESEARCH METHODOLOGY
This research study relied on extensive secondary sources, including company annual reports and presentations, industry association publications, industry magazine articles, directories, technical handbooks, the World Economic Outlook, technical articles, and databases, to identify and collect information on the train battery market. In-depth interviews were conducted with primary respondents, including key industry participants, subject-matter experts, C-level executives of key market players (train battery manufacturers, battery component manufacturers), and industry consultants, among other experts, to obtain and verify critical qualitative and quantitative information and to assess market prospects.
Secondary Research
Secondary sources for this research study included train battery associations and organizations, corporate filings (such as annual reports, investor presentations, and financial statements), and trade, business, and industry associations. Secondary data were collected and analyzed to determine the overall market size, which was further validated by primary research.
Primary Research
Extensive primary research was conducted after understanding the train battery market through secondary research. Several primary interviews were conducted with market experts from the demand side (OEMs) across major regions, namely, North America, Europe, and Asia Pacific. Approximately 80% of primary interviews were conducted with the demand side, and 20% with train battery component manufacturers. Primary data was collected through questionnaires, emails, and telephonic interviews.
The canvassing of primary sources covered various departments within organizations, such as sales, operations, and marketing, to provide a holistic view in the report. After interacting with industry experts, brief sessions were held with highly experienced independent consultants to reinforce the findings from primary sources. These sessions, along with the opinions of in-house subject matter experts, led to the conclusions described in the remainder of this report.
Breakdown of Primaries
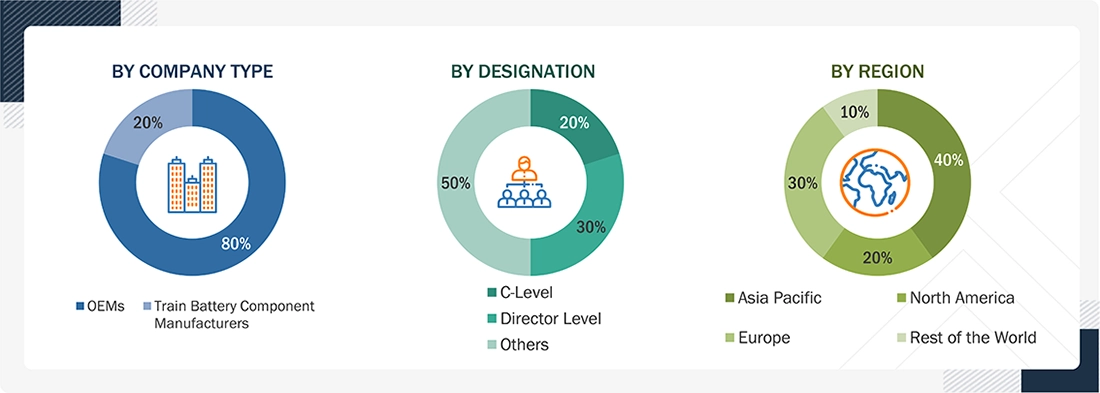
Note: Others include sales managers, marketing managers, product managers, etc.
To know about the assumptions considered for the study, download the pdf brochure
Market Size Estimation
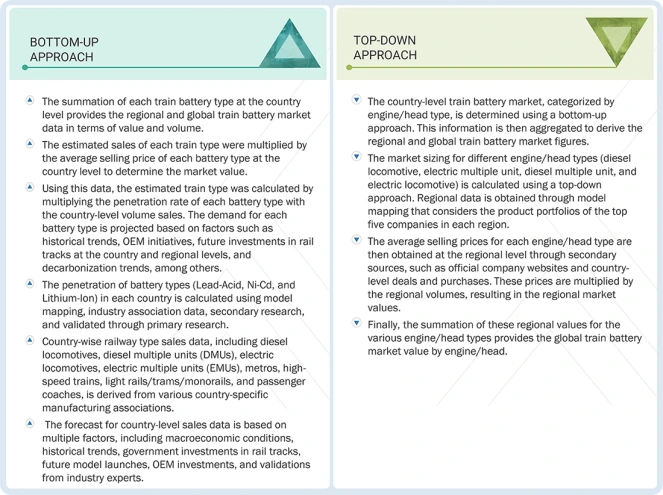
Bottom-up Approach
The bottom-up approach was used to estimate and validate the size of the train battery market by battery type. In this approach, country-wise sales data for different railway types (diesel locomotives, diesel multiple units (DMUs), electric locomotives, electric multiple units (EMUs), metros, high-speed trains, light rails/trams/monorails, and passenger coaches) were obtained from secondary sources, and sales statistics from industry associations and organizations were compiled. Following this, secondary research was used to determine the percentage penetration of battery types (Lead-acid Batteries, Ni-Cd Batteries, and Lithium-ion Batteries) by railway type per country. Then the Average Selling Price (ASP) was multiplied by each battery type for all train types to arrive at the country-wise value of the train and battery types. These numbers, when collated, represent the regional and global market size and forecast (volume as well as value) for train and battery types. The forecasting was based on factors such as GDP, economic stability, war conditions in the Middle East and Europe, regulations, investments and deals for battery technology by the key players, and investments by governing bodies for new railway tracks, etc.
Country-level tractor sales were multiplied by the battery-type penetration at the country level to determine the market size of the train battery market for each battery type in terms of volume. The forecast was based on factors such as war conditions, GDP growth rate, government investments, and others. In terms of volume, the country-level railway-type market size for each train-type category was summed to derive the regional market. All the regional markets were summed to derive the global market's power output by battery type.
The country-wise forecast for train types is based on multiple factors, including OEM investments in the country for train battery manufacturing plants, emissions regulations, the technological landscape, economic conditions, increasing demand for electric trains, and future train battery model launches.
The country-level train battery market was then multiplied by the country-level average selling price of train batteries, which resulted in the country-level market size.
The train battery ASP by battery type for each country was derived from secondary sources and model mapping, and validated through primary sources. The addition of the respective countries provides the regional-level market. Then, the summation of regional-level markets provides the global market by battery type in terms of value. A similar approach was used to derive the train aftermarket by battery type. However, these submarkets were analyzed at the regional level.
Top-down Approach
The top-down approach estimated and validated the market by engine/head (diesel locomotive, electric multiple units, diesel multiple units, and electric locomotive) in terms of volume and value. The train battery market value (USD million) and volume (units) by region were derived from the global market. The penetration of each engine/head type at the regional level was derived from secondary sources and model mapping, and validated through interviews with experts. The model mapping provided information such as the dominant drive type (head (diesel locomotive, electric multiple units, diesel multiple units, and electric locomotive)) and model with drive type offerings by key OEMs. The penetration of each drive type was multiplied by the regional train type market to obtain the market for engine/head by value and volume by drive type for each region. All region-wise markets were summed to derive the total train market value and volume by engine/head type. The top-down approach was followed by train type, by passenger coaches, advanced train type, by application, aftermarket by battery type, and aftermarket by application segments.
Train Battery Market : Top-Down and Bottom-Up Approach
Data Triangulation
After determining the overall market size, the market was segmented into several segments and subsegments using the market size estimation processes explained above. Data triangulation and market breakdown procedures were employed to complete the overall market engineering process and arrive at the exact statistics for each market segment and subsegment, wherever applicable. The data was triangulated by analyzing various factors and trends from both the demand and supply sides.
Market Definition
According to Saft, rail batteries are an important component of energy storage systems used for end-use applications such as starters, lighting, air conditioning, access mechanisms, water-filling systems, isolators, connectors, and battery management control (BMC) systems.
According to Exide Industries, the train battery is securely housed within a battery enclosure located beneath the coach. In railway applications, the battery operates in a dusty environment, experiences moderate to high levels of vibration, encounters fluctuating temperatures, has limited windows for inspection and maintenance, and operates continuously in a charge-discharge cycle. This represents the most rigorous evaluation of a battery's performance and longevity, emphasizing the critical importance of reliability.
Key Stakeholders
- Battery Manufacturers
- Battery Material & Component Suppliers
- Battery Management System (BMS) Providers
- Rolling Stock Manufacturers
- Locomotive Manufacturers
- Railway Operators
- Metro & Urban Transit Authorities
- High-Speed Rail Operators
- Rail Leasing Companies
- Maintenance, Repair & Overhaul (MRO) Service Providers
- Rail Infrastructure Developers
- Signaling & Electrification Solution Providers
- Charging & Energy Storage Solution Providers
- Engineering, Procurement & Construction (EPC) Contractors
- Government & Transport Authorities
- Rail Safety & Regulatory Bodies
- Industry Associations & Standardization Organizations
- Technology & Automation Providers
- Research Institutes & Testing Organizations
Report Objectives
- To define, segment, analyze, and forecast (2023–2030) the train battery market size, in terms of volume (units) and value (USD million) based on:
- OE By Battery Type (Lead-Acid, Nickel-Cadmium, and Lithium-ion)
- OE By Battery Technology (Conventional Lead-Acid, Valve Regulated Lead-Acid, Gel Tubular Lead-Acid, Sinter/PNE Ni-Cd Battery, Pocket Plate Ni-Cd Battery, Fiber/PNE Ni-Cd Battery, Lithium Iron Phosphate, Titanate Oxide, and Others)
- OE By Application (Starter and Auxiliary)
- OE By Engine/Head (Diesel Locomotive, Diesel Multiple Units (DMUs), Electric Locomotive, and Electric Multiple Units (EMUs))
- OE By Application (Metro, High-Speed Trains, Light Rail/ Trams/Monorail, Passenger Coaches)
- OE By Advanced Train Type (Fully Battery-Powered Train, and Hybrid Train)
- Aftermarket By Battery Type (Lead-Acid, Nickel-Cadmium)
- Aftermarket By Application (Starter, and Auxiliary)
- Aftermarket By Rolling Stock (Locomotives, Multiple Units, and Passenger Coaches)
- Aftermarket By Region (Asia Pacific, Europe, and North America)
- OE By Region (North America, Europe, Asia Pacific, and the Rest of the World (RoW))
- To understand the market dynamics (drivers, restraints, opportunities, and challenges) of the train battery market
- To analyze the impact of the Israel-Iran war on the market
- To strategically analyze markets concerning individual growth trends, prospects, and contributions to the total market
- To analyze opportunities for stakeholders and details of the competitive landscape for market leaders
- To analyze the market share of the key players in the market
- To analyze competitive developments such as deals (joint ventures, mergers & acquisitions, partnerships, collaborations), new product developments, and other activities carried out by key industry participant.
-
To study the following concerning the market:
- Supply Chain Analysis
- Ecosystem Analysis
- Technology Analysis
- Trade Analysis
- Case Study Analysis
- Patent Analysis
- Regulatory Landscape
- Conferences and Events
- Average Selling Price Analysis
- Buying Criteria
- OEM Analysis
- OEM Strategies: Future Investments by the key players
- Total Cost of Ownership: Train Battery
Available customizations:
With the given market data, MarketsandMarkets offers customizations based on the company’s needs.
Get the Full Train Battery Market Report
Full forecast, segment splits, and company analysis for all Train Battery Market.
- China Train Battery Market
- India Train Battery Market
- Japan Train Battery Market
- South Korea Train Battery Market
- Germany Train Battery Market
- France Train Battery Market
- Italy Train Battery Market
- Spain Train Battery Market
- Switzerland Train Battery Market
- Poland Train Battery Market
- Sweden Train Battery Market
- Canada Train Battery Market
- Mexico Train Battery Market
- Brazil Train Battery Market
- Russia Train Battery Market
- US Train Battery Market
Need a Tailored Report?
Customize this report to your needs
Get 10% FREE Customization
Customize This Report
