GCC Countries Ventilators Market (2024-2029)

The GCC Countries Ventilators Market was valued at $44.5 Million in 2024 and projected to reach to $56.3 Million by 2029, representing a compound annual growth rate of 4.8%. The GCC Countries ventilators market is poised for sustained expansion through 2029, driven by continuous healthcare infrastructure development and rising respiratory disease burden across the region.


| Market Size in | USD 26.32 MN |
| Market Forecast in | |
| CAGR | |
| Forecast Period | |
| Units Considered | Value (USD MN) |
GCC Countries Ventilators Market Trends and Insights
- GCC Countries' healthcare infrastructure investments and rising respiratory disease prevalence are driving demand for advanced ventilation technologies.
- By 2029, the GCC Countries ventilators market is forecast to expand to $56.3 million, reflecting a compound annual growth rate of 4.8% throughout the forecast period. GCC Countries' strategic focus on healthcare modernization and critical care capacity enhancement supports market expansion.
- The region's increasing adoption of ICU-grade ventilators and portable respiratory devices positions GCC Countries as a growing hub for ventilator deployment.
- Enhanced government healthcare spending and private sector participation in GCC Countries continue to accelerate market penetration and accessibility across the region..
Key Market Statistics
- CAGR (2024-2029) 4.8% CAGR
- Market Size, 2024 ~USD 44.5 Million
- Forecast, 2029 ~USD 56.3 Million
- Country GCC Countries
GCC Countries Ventilators Market Overview
Market Size & Growth :
GCC Countries ventilators market valued at $44.5 million in 2024, projected to reach $56.3 million by 2029, representing a steady 4.8% CAGR aligned with global growth trends.
Healthcare Infrastructure Investment :
GCC nations are significantly investing in advanced medical infrastructure and hospital modernization, creating strong demand for sophisticated ventilation technologies across ICU and emergency care units.
Rising Respiratory Disease Prevalence :
Increasing incidence of respiratory conditions, including COPD and asthma, combined with post-pandemic awareness, is driving healthcare facilities to upgrade ventilator capacity and technology.
Regional Market Dynamics :
GCC Countries' high healthcare spending per capita and emphasis on advanced medical equipment adoption position the region as a premium market for next-generation ventilation solutions.
GCC Countries Ventilators Market Dynamics
- Government initiatives to enhance hospital capabilities and the region's focus on medical technology adoption are creating favorable conditions for ventilator manufacturers.
- The market's 4.8% CAGR reflects steady demand from both public and private healthcare sectors seeking advanced respiratory support solutions. Key growth catalysts include increasing ICU bed capacity expansion, aging population demographics, and heightened awareness of respiratory health post-pandemic.
- GCC nations' strong purchasing power and preference for premium medical equipment position them as attractive markets for innovative ventilation technologies.
- Strategic partnerships between regional healthcare providers and international manufacturers are expected to accelerate market penetration and product availability..
Market Ecosystem
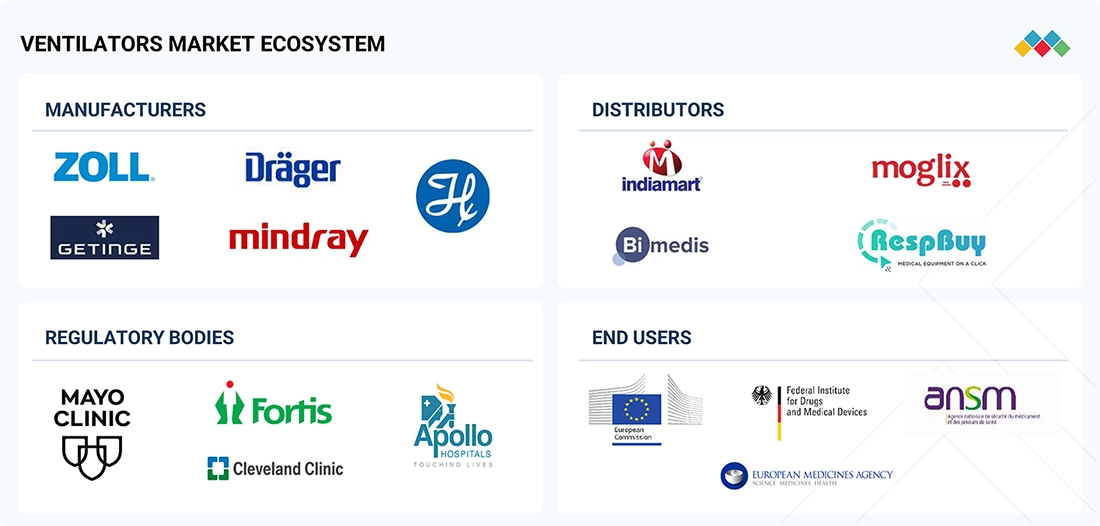
VENTILATORS MARKET: COMMERCIAL USE CASES ACROSS INDUSTRIES
| COMPANY | USE CASE DESCRIPTION | BENEFITS |
|---|---|---|
 |
Deploys ICU and neonatal ventilators within connected acute-care environments, integrating ventilation data with patient monitoring and clinical workflow systems | Supports standardized critical-care workflows | Remote visibility | Lung-protective ventilation | Long-term fleet serviceability |
 |
Provides Servo ventilators for adult, pediatric, and neonatal care, with advanced synchrony, monitoring, and automated support across high-acuity settings | Improves patient-ventilator interaction | Enables one-platform use across patient groups | Supports efficient ICU standardization |
 |
Combines ventilators with patient monitors, infusion systems, anesthesia equipment, and digital ICU solutions for hospital-wide critical-care deployments | Enables bundled procurement | Competitive lifecycle economics | Integrated data and alarm management across care areas |
 |
Offers ventilation-focused platforms for ICU, neonatal, MRI, emergency, and transport settings with automated modes and compact mobility options | Reduces clinician workload | Supports consistent therapy during transport | Enables fleet continuity from prehospital to ICU care |
 |
Provides a broad respiratory portfolio spanning critical-care, transport, neonatal, and high-frequency ventilation following the acquisition of selected Vyaire product lines | Maintains continuity for legacy fleets | Expands patient-range coverage | Supports hospitals and EMS providers with multiple ventilation technologies |
Logos and trademarks shown above are the property of their respective owners. Their use here is for informational and illustrative purposes only.
Related Ecosystem
Medical Devices
- Polymerase Chain Reaction (PCR)
- Magnetic Resonance Imaging (MRI)
- Disposable Autoinjectors
- Pulse Oximeters
- Blood Pressure Monitors
- Medtronic plc
- Abbott Laboratories
- Stryker Corporation
- Becton, Dickinson and Company
- JOHNSON & JOHNSON
Key Takeaways
- GCC Countries ventilators market valued at $44.5 million in 2024, expanding to $56.3 million by 2029
- GCC Countries demonstrates a 4.8% CAGR, driven by healthcare infrastructure modernization and critical care investments
- Rising respiratory disease prevalence in GCC Countries fuels demand for advanced ventilation technologies
- Government healthcare spending and private sector participation accelerate ventilator market accessibility across GCC Countries
Ventilators Market Report Scope
| Report Metric | Details |
|---|---|
| Base Year | 2024 |
| Fastest Growing Segment | HOME CARE SETTINGS (Care Setting) |
| Forecast Period | 2024–2029 |
| Growth Rate | CAGR of 4.7% from 2024 to 2029 |
| Largest Segment | ADULT & PEDIATRIC VENTILATORS (Age Group) |
| Market Size Base Year (Billions) | ~USD 3.7 (2024) |
| Revenue Forecast (Billions) | ~USD 4.66 (2029) |
| Segments Covered | Type, Age Group, Interface, Mode, Care Setting |
GCC Countries Ventilators Market Report Segmentation
5 segment dimensions are covered across the global market.
By Type
- Basic Icu Ventilators
- High-End Icu Ventilators
- Intensive Care Ventilators
- Mid-End Icu Ventilators
- Portable/ Transportable Ventilators
- Portable/Transportable Ventilators
By Age Group
- Adult & Pediatric Ventilators
- Neonatal/Infant Ventilators
By Interface
- Hybrid Ventilation
- Invasive Ventilation
- Non-Invasive Ventilation
By Mode
- Combined-Mode Ventilators
- Other Ventilators
- Pressure-Mode Ventilators
- Volume-Mode Ventilators
By Care Setting
- Ambulatory Care Centers
- Emergency Medical Services
- Home Care Settings
- Hospitals & Clinics
Target Audience
- Medical Device Manufacturers : Ventilator and respiratory equipment producers need GCC-specific market data to assess regional demand, plan product launches, and develop localized strategies for Gulf healthcare facilities.
- Healthcare Facility Administrators : Hospital and clinic decision-makers require market insights to justify equipment investments, benchmark procurement decisions, and align ventilator acquisitions with regional growth trends.
- Healthcare Investors & PE Firms : Investment professionals evaluating GCC healthcare opportunities need regional market sizing and growth forecasts to assess portfolio companies and identify attractive acquisition targets in respiratory care.
- Medical Equipment Distributors : Regional distributors and importers require GCC-specific market data to optimize inventory planning, negotiate supplier agreements, and identify emerging demand segments across Gulf nations.
- Healthcare Consultants & Analysts : Strategy consultants and research firms need detailed GCC ventilators market intelligence to support client advisory work, competitive analysis, and healthcare sector recommendations.
Key Companies in the GCC Countries Ventilators Market
| Company | HQ | Ownership | Strongest segments |
|---|---|---|---|
| KINDRED HEALTHCARE INC. | United States | Private Company | Intensive Care Ventilators,Transportable Ventilators,Adult & Pediatric Ventilators, |
| TEIJIN LIMITED | Japan | Public Company | Intensive Care Ventilators,Transportable Ventilators,Adult & Pediatric Ventilators, |
| TELEFLEX INCORPORATED | United States | Public Company | Intensive Care Ventilator–linked disposables,Transportable Ventilator–linked disposables,Adult & Pediatric ventilation interfaces and accessories, |
| ZOLL MEDICAL CORPORATION | United States | Private Company | Intensive Care Ventilators,Transportable Ventilators,Adult & Pediatric Ventilators, |
| GODREJ GROUP | India | Private Company | Intensive Care Ventilators,Transportable Ventilators,Adult & Pediatric Ventilators, |
| UPONOR CORPORATION | Finland | Private Company | Hospital hydronic heating and cooling infrastructure,Potable and hot-water systems for hospitals and clinics,Noise-reducing wastewater and drainage in healthcare, |
| RESMED | United States | Public Company | Intensive Care Ventilators,Transportable Ventilators,Adult & Pediatric Ventilators, |
| GETINGE AB | Sweden | Public Company | Intensive Care Ventilators – Adult & Pediatric, Hybrid Interface, Combined Modes,Transportable Ventilators – Adult & Pediatric, Hybrid Interface, Combined Modes, |
| KONINKLIJKE PHILIPS N.V. | Netherlands | Public Company | Intensive Care Ventilators (Adult & Pediatric),Transportable Ventilators (Adult & Pediatric),Software, Connectivity & Service around Ventilators, |
| DRäGERWERK AG & CO. KGAA | Germany | Public Company | Intensive Care Ventilators – Adult & Pediatric, Hybrid/Combined Modes,Transportable Ventilators – Hospital & Emergency Use,Neonatal & Perinatal Ventilation within ICU Settings, |
| ICU MEDICAL INC. | United States | Public Company | Intensive Care Ventilators,Transportable Ventilators,Adult & Pediatric Ventilators, |
| ASAHI KASEI CORPORATION | Japan | Public Company | Intensive Care Ventilators (Adult & Pediatric, Combined Mode, Hybrid Interface),Transportable Ventilators (Adult & Pediatric),Ventilation-Linked Data & Integration (Hybrid/Combined Mode Workflows in Hospitals & Clinics), |
| AIR LIQUIDE | France | Public Company | Intensive Care Ventilators,Transportable Ventilators,Adult & Pediatric Ventilators, |
| NIHON KOHDEN CORPORATION | Japan | Public Company | Intensive Care Ventilators,Transportable Ventilators,Adult & Pediatric Ventilators, |
| SHENZHEN MINDRAY BIO-MEDICAL ELECTRONICS CO., LTD. | China | Public Company | Intensive Care Ventilators,Transportable Ventilators,Adult & Pediatric Ventilators (cross-setting), |
| GE HEALTHCARE | United States | Public Company | Intensive Care Ventilators,Transportable Ventilators,Adult & Pediatric Ventilators, |
| BAXTER | United States | Public Company | Intensive Care Ventilators,Transportable Ventilators,Adult & Pediatric Ventilators, |
| SKANRAY TECHNOLOGIES, LTD. | India | Private Company | Intensive Care Ventilators – Adult & Pediatric, Hospitals & Clinics,Transportable Ventilators – Adult & Pediatric, Hospitals & Clinics,Other Ventilator-Linked Solutions (bundled software, accessories, service), |
KINDRED HEALTHCARE INC.
Kindred Healthcare Inc. is a United States-based private healthcare company founded in 1985, operating with a workforce of 64,200 employees.
TEIJIN LIMITED
Teijin Limited is a Japanese public company established in 1918 with 15,689 employees, operating across diversified industrial and healthcare sectors.
TELEFLEX INCORPORATED
Teleflex Incorporated is a United States-based public company founded in 1943 with 15,500 employees, specializing in medical devices and healthcare solutions.
ZOLL MEDICAL CORPORATION
ZOLL Medical Corporation is a United States-based private company established in 1980 with 1,908 employees, specializing in emergency medical devices and software.
GODREJ GROUP
Godrej Group is an Indian private conglomerate established in 1897 with 13,316 employees, operating across multiple sectors including healthcare and consumer goods.
UPONOR CORPORATION
Uponor Corporation is a Finnish private company founded in 1918 with 3,527 employees, specializing in building solutions and infrastructure systems.
RESMED
ResMed is a United States-based public company founded in 1989 with 10,600 employees, specializing in cloud-connected medical devices and software solutions.
GETINGE AB
Getinge AB is a Swedish public company established in 1904 with 11,754 employees, providing medical technology and healthcare solutions.
KONINKLIJKE PHILIPS N.V.
Koninklijke Philips N.V. is a Dutch multinational public company founded in 1891 with 63,670 employees, operating in healthcare, lighting, and consumer electronics.
DRäGERWERK AG & CO. KGAA
Drägerwerk AG & Co. KGaA is a German public company established in 1889 with 16,033 employees, specializing in medical and safety technology.
ICU MEDICAL INC.
ICU Medical Inc. is a United States-based public company founded in 1984 with 13,000 employees, manufacturing infusion therapy and critical care products.
ASAHI KASEI CORPORATION
Asahi Kasei Corporation is a Japanese public company established in 1922 with 47,895 employees, operating in chemicals, materials, and healthcare sectors.
AIR LIQUIDE
Air Liquide is a French multinational public company founded in 1902 with 65,000 employees, specializing in industrial gases and healthcare solutions.
NIHON KOHDEN CORPORATION
Nihon Kohden Corporation is a Japanese public company established in 1951 with 6,116 employees, specializing in medical electronic equipment and monitoring systems.
SHENZHEN MINDRAY BIO-MEDICAL ELECTRONICS CO., LTD.
Shenzhen Mindray Bio-Medical Electronics Co., Ltd. is a Chinese public company founded in 1991 with 21,288 employees, manufacturing medical devices and equipment.
GE HEALTHCARE
GE Healthcare is a United States-based public company established in 2022 with 54,000 employees, providing medical imaging, diagnostics, and healthcare IT solutions.
BAXTER
Baxter is a United States-based public company founded in 1931 with 37,500 employees, specializing in renal care, medication delivery, and hospital products.
SKANRAY TECHNOLOGIES, LTD.
Skanray Technologies, Ltd. is an Indian private company founded in 2007 with 500 employees, manufacturing medical imaging and diagnostic equipment.
Reasons to Buy this Report
- Market-Specific Sizing & Forecasts : Access precise market valuation ($44.5M in 2024) and 5-year projections ($56.3M by 2029) exclusive to GCC Countries, enabling accurate budget allocation and revenue forecasting for regional operations.
- Regional Growth Drivers Analysis : Understand GCC-specific factors including healthcare infrastructure investments, respiratory disease prevalence trends, and government health initiatives that directly impact ventilator demand and market opportunities.
- Competitive Landscape Intelligence : Gain insights into regional market dynamics, key players operating in GCC Countries, and competitive positioning strategies tailored to the Gulf region's unique healthcare procurement environment.
- Strategic Market Entry Planning : Leverage GCC-focused data to develop targeted market entry strategies, identify high-potential segments, and optimize product positioning for healthcare facilities across Gulf Cooperation Council nations.
- Investment & Partnership Opportunities : Identify growth hotspots and partnership opportunities within GCC Countries' healthcare sector, supported by regional market trends and infrastructure development initiatives through 2029.
Frequently asked questions
What is the current market size of ventilators in GCC Countries?
The ventilators market in GCC Countries was valued at $44.5 million in 2024 and is projected to grow to $56.3 million by 2029.
What is the growth rate for ventilators in GCC Countries?
GCC Countries' ventilators market is growing at a compound annual growth rate (CAGR) of 4.8% from 2024 to 2029.
What factors are driving ventilator demand in GCC Countries?
Key drivers in GCC Countries include healthcare infrastructure modernization, rising respiratory disease prevalence, increased ICU capacity investments, and enhanced government healthcare spending.
How much will the ventilators market in GCC Countries grow by 2029?
The ventilators market in GCC Countries is forecast to reach $56.3 million by 2029, representing growth of approximately $11.8 million from the 2024 baseline.
What types of ventilators are most in demand in GCC Countries?
GCC Countries shows increasing adoption of ICU-grade ventilators and portable respiratory devices, reflecting the region's focus on critical care capacity and accessibility.
RESEARCH METHODOLOGY
This research study involved the extensive use of both primary and secondary sources. It examined various factors affecting the industry to identify segmentation types, industry trends, key players, the competitive landscape of market players, and key market dynamics such as drivers, opportunities, challenges, restraints, and key player strategies.
Secondary Research
This research study involved the wide use of secondary sources, directories, databases such as Dun & Bradstreet, Bloomberg Businessweek, and Factiva, white papers, and companies’ in-house documents. Secondary research was undertaken to identify and collect information for this extensive, technical, market-oriented, and commercial study of the ventilators market. It was also used to obtain important information about the top players, market classification, and segmentation according to industry trends to the bottom-most level, geographic markets, and key developments related to the market. A database of the key industry leaders was also prepared using secondary research.
Primary Research
In the primary research process, various supply-side and demand-side sources were interviewed to obtain qualitative and quantitative information for this report. Primary sources from the supply side included industry experts such as CEOs, vice presidents, marketing and sales directors, technology & innovation directors, engineers, and related key executives from various companies and organizations operating in the ventilators market. Primary sources from the demand side included hospitals, clinics, researchers, lab technicians, purchase managers, and stakeholders in corporate & government bodies.
The following is a breakdown of the primary respondents:
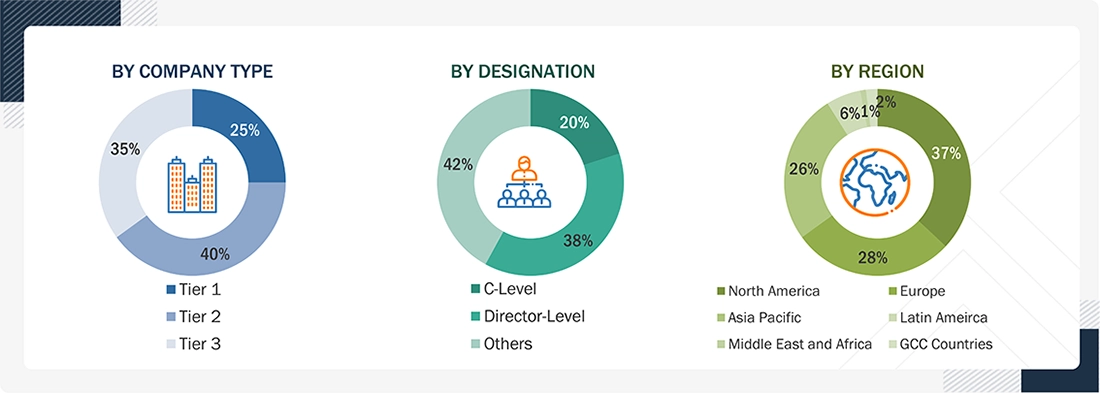
Note 1: Companies are classified into tiers based on their total revenue. As of 2025: Tier 1 = >USD 1 billion, Tier 2 = USD 500 million to USD 1 billion, and Tier 3 = <USD 500 million.
Note 2: C-level executives include CEOs, COOs, CTOs, and VPs.
Note 3: Other primaries include sales managers, marketing managers, and product managers.
To know about the assumptions considered for the study, download the pdf brochure
Market Size Estimation
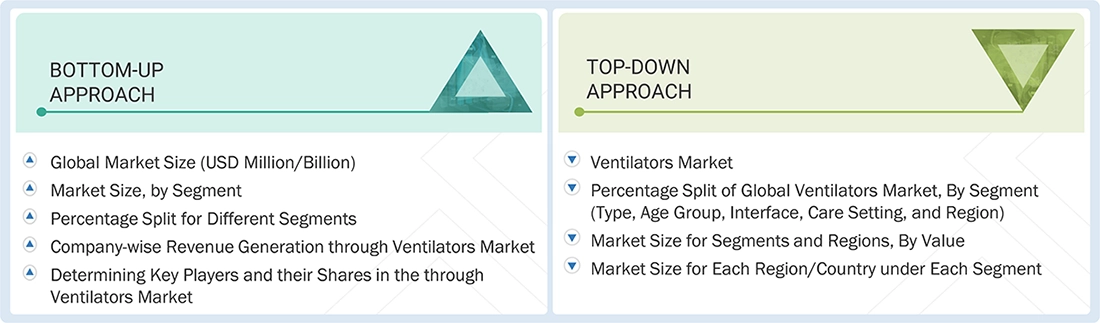
Both top-down and bottom-up approaches were used to estimate and validate the total size of the ventilators market. These methods were also used extensively to estimate the size of various subsegments in the market. The research methodology used to estimate the market size includes the following:
Ventilators Market: Top-Down and Bottom-Up Approach
Data Triangulation
The entire market was split up into five segments when the market size was determined. Data triangulation and market breakdown processes were used, wherever necessary, to complete the entire market engineering process and arrive at the precise statistics for all segments.
Approach to derive the market size and estimate market growth.
Using secondary data from both paid and unpaid sources, the market rankings for the major players were determined following a thorough analysis of their sales of ventilators. Due to data restrictions, the revenue share in certain cases was determined after a thorough analysis of the product portfolio of big corporations and their individual sales performance. This information was verified at each stage by in-depth interviews with professionals in the field.
Market Definition
Ventilators are medical devices that assist or replace spontaneous breathing in patients with respiratory failure by mechanically delivering air and oxygen to the lungs. They can operate invasively—via intubation—or non-invasively using masks, and are essential in settings like intensive care units, emergency departments, and home care for improving patient oxygenation and respiratory support.
Key Stakeholders
- Manufacturers of ventilators
- Original equipment manufacturing companies
- Suppliers and distributors of ventilators
- Healthcare service providers
- Teaching hospitals and academic medical centers
- Health insurance players
- Government bodies/Municipal corporations
- Regulatory bodies
- Business research and consulting service providers
- Authorities framing reimbursement policies for ventilators
- Venture capitalists
- Market research and consulting firms
Report Objectives
- To define, describe, and forecast the ventilators market based on mobility, type, age group, interface, mode, care setting, and region
- To provide detailed information about the major factors influencing the market growth (such as drivers, restraints, challenges, and opportunities)
- To strategically analyze micromarkets with respect to individual growth trends, prospects, and contributions to the overall ventilators market
- To analyze market opportunities for stakeholders and provide details of the competitive landscape for key players
- To forecast the size of the ventilator market in North America, Europe, the Asia Pacific, Latin America, Middle East & Africa, and GCC countries
- To profile the key players and comprehensively analyze their market shares and core competencies in the ventilators market
- To track and analyze competitive developments such as partnerships, expansions, acquisitions, collaborations, product launches, agreements, and other developments in the ventilators market
- To benchmark players within the ventilators market using the Company Evaluation Quadrant framework, which analyzes market players on various parameters within the broad categories of business strategy, market share, and product offerings
Available customizations:
With the given market data, MarketsandMarkets offers customizations as per your company’s specific needs. The following customization options are available for the report:
Company Information
- Detailed analysis and profiling of additional market players (up to 5)
Geographic Analysis
-
Further breakdown of the Rest of Europe ventilators market into Denmark, Norway, and others
-
Further breakdown of the Rest of Asia Pacific ventilators market into Vietnam and others
Get the Full Ventilators Market Report
Full forecast, segment splits, and company analysis for all Ventilators Market.
- Italy Ventilators Market
- Spain Ventilators Market
- Netherlands Ventilators Market
- China Ventilators Market
- Japan Ventilators Market
- India Ventilators Market
- Australia Ventilators Market
- Brazil Ventilators Market
- Mexico Ventilators Market
- Argentina Ventilators Market
- Rest Of Europe Ventilators Market
- Rest Of Asia Pacific Ventilators Market
- Rest Of Latin America Ventilators Market
- Canada Ventilators Market
- US Ventilators Market
- Germany Ventilators Market
- France Ventilators Market
- UK Ventilators Market
Need a Tailored Report?
Customize this report to your needs
Get 10% FREE Customization
Customize This Report
