Transformer Oil Market by Oil Type [Mineral (Naphthenic, Paraffinic), Silicone, Bio-based], Application (Transformer, Switchgear, Reactor), End User (Transmission & Distribution, Power Generation, Railways & Metros), Region - Global Forecast to 2031

icon1
USD 2.87 BN
MARKET SIZE, 2031
icon2
CAGR 5.6%
(2026-2031)
icon3
260
REPORT PAGES
icon4
160
MARKET TABLES

OVERVIEW

The transformer oil market is projected to grow from USD 2.18 billion in 2026 to USD 2.87 billion by 2031, at a 5.6% CAGR. The market is driven by rising electricity demand, expansion and modernization of power transmission and distribution infrastructure, and growing investments in renewable energy projects. Growing deployment of transformers across utilities, industrial, commercial, and renewable power applications is supporting demand for transformer oils. Furthermore, advancements in high-performance mineral oils, natural and synthetic ester fluids, enhanced thermal stability, and fire-resistant insulating fluids are expanding application opportunities, enabling improved transformer efficiency, longer equipment life, and greater reliability across power networks.
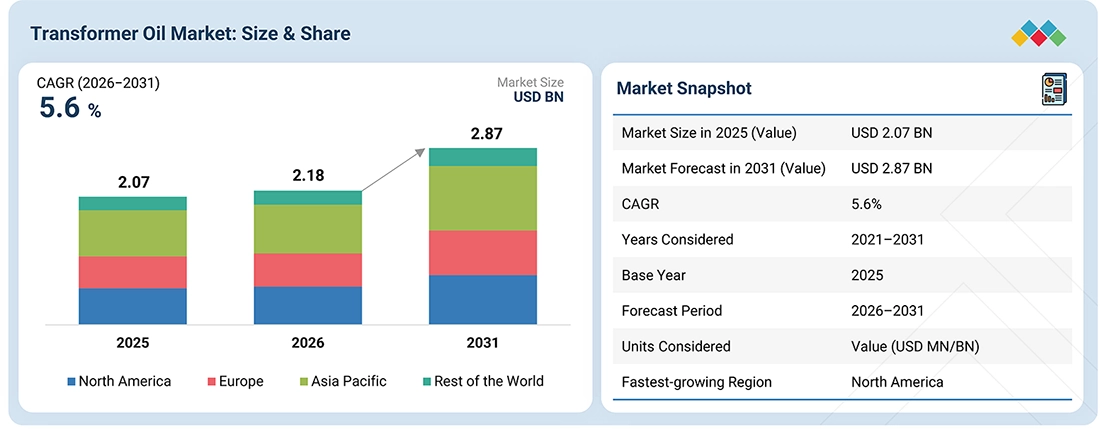
transformer-oil-market Overview

Source: Secondary Research, Interviews with Experts, MarketsandMarkets Analysis

Transformer Oil Market Size and Forecast:

  • Market Size (2025): USD 2.07 Billion
  • Market Size (2026): USD 2.18 Billion
  • Market Forecast (2031): USD 2.87 Billion
  • Growth Rate: CAGR of 5.6% from 2026 to 2031
  • Base Year: 2025
  • Forecast Period: 2026–2031

Key growth drivers

  • Rising electricity demand
  • Expansion and modernization of power transmission and distribution infrastructure
  • Growing investments in renewable energy generation
  • Replacement of aging transformer fleets
  • Shift toward bio-based and ester transformer fluids

KEY TAKEAWAYS

  • BY REGION
    By region, the North American market is expected to register the highest CAGR of 5.2% during the forecast period.
  • BY TYPE
    By type, the bio-based oil segment is expected to register the highest CAGR of 4.3% during the forecast period.
  • BY APPLICATION
    By application, the transformers segment registers the highest CAGR during the forecast period.
  • BY END USER
    By end user, the transmission & distribution segment registers the highest CAGR during the forecast period.
  • COMPETITIVE LANDSCAPE - KEY PLAYERS
    Nynas AB (Sweden), APAR Industries (India), Ergon (US), Calumet Specialty Products Partners (US), Cargill (US), Dow (US), Exxon Mobil Corporation(US), Shell (UK), Repsol (Spain), and PetroChina Company Limited (China) have been identified as leading players in the global transformer oil market. These companies are strengthening their market positions through high-performance insulating oils, bio-based and ester fluids, enhanced thermal stability, product innovation, expanded refining capacities, and strategic distribution networks across key regional markets.
  • COMPETITIVE LANDSCAPE - STARTUPS/SMES
    NYCO (France), Prolec Energy (US), and Insulect (Australia) are emerging players in the transformer oil market, driven by the development and deployment of next-generation synthetic and natural ester dielectric fluids for power, distribution, traction, and renewable-energy transformers.

The transformer oil market is projected to grow significantly during 2026–2031, driven by expanding power transmission and distribution infrastructure, rising electricity demand, and increasing investments in renewable energy generation. Growing transformer deployment across utility, industrial, commercial, and renewable energy applications is supporting demand for insulating fluids. Furthermore, advances in high-performance mineral oils, natural and synthetic ester fluids, enhanced thermal stability, and fire-resistant transformer oils are expanding application opportunities, enabling improved transformer efficiency, longer equipment life, reduced maintenance requirements, and greater power-network reliability.

TRENDS & DISRUPTIONS IMPACTING CUSTOMERS' CUSTOMERS

The transformer oil market is estimated to register a CAGR of 5.6% during the forecast period, with Nynas AB, APAR Industries, Cargill, Calumet Specialty Products Partners, L.P., Exxon Mobil Corporation, Shell, Repsol, and PetroChina Company Limited strengthening portfolios across utility, industrial, renewable energy, and commercial applications. Nynas AB, APAR Industries, and Cargill are similarly strengthening transformer-oil portfolios through bio-based ester fluids, high-performance insulating oils, product development, localized production, and strategic expansion, intensifying competition across power transmission, distribution, and industrial applications.
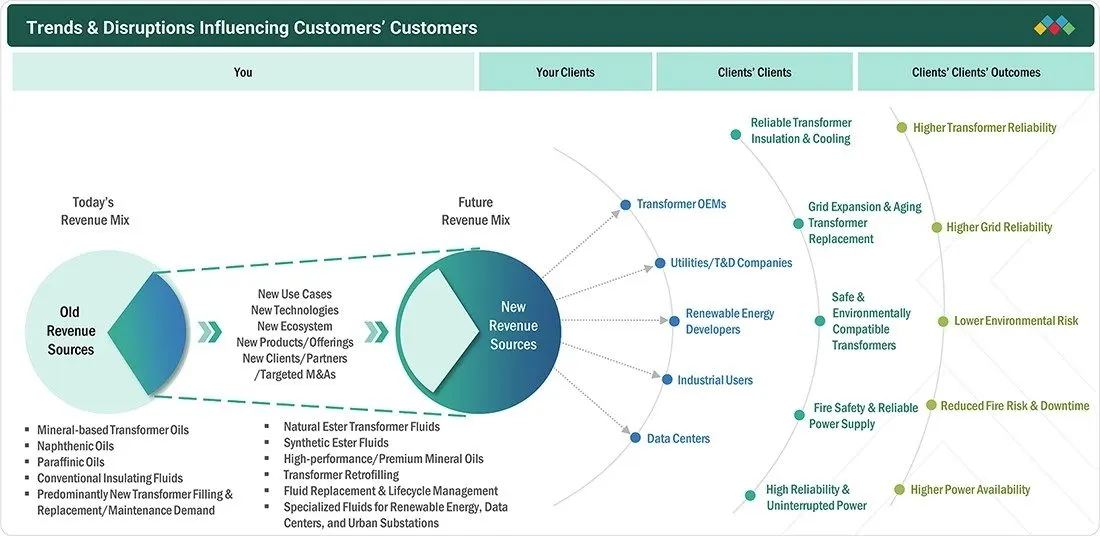
transformer-oil-market Disruptions

Source: Secondary Research, Interviews with Experts, MarketsandMarkets Analysis

MARKET DYNAMICS

Drivers
Impact
Level
  • Expansion and modernization of transmission & distribution infrastructure
  • Replacement of aging transformer fleets
RESTRAINTS
Impact
Level
  • Higher cost of ester-based transformer fluids
  • Availability and volatility of specialty feedstocks
OPPORTUNITIES
Impact
Level
  • Shift toward bio-based and ester transformer fluids
  • Retrofilling of existing mineral-oil transformers
CHALLENGES
Impact
Level
  • Competition from established mineral-based oils
  • Technical compatibility with existing transformer fleets

Source: Secondary Research, Interviews with Experts, MarketsandMarkets Analysis

Driver: Expansion and modernization of transmission & distribution infrastructure

The expansion and modernization of electricity transmission and distribution infrastructure are major drivers of the transformer oil market. Rising electricity consumption, grid expansion, urbanization, and the integration of renewable power are encouraging utilities to install new substations, transformers, and grid equipment. Transformers require insulating and cooling fluids to maintain electrical insulation and dissipate heat during operation, directly supporting demand for transformer oil. In parallel, utilities in developed markets are replacing aging transformer fleets to improve grid reliability and reduce failure-related outages. Emerging economies are also investing in new transmission networks to expand electricity access and accommodate growing industrial and commercial loads. These developments generate demand not only for oil used in newly manufactured transformers but also for replacement oil during maintenance, servicing, and refurbishment. Consequently, continued investment in transmission and distribution infrastructure is expected to sustain transformer oil consumption across utility, industrial, renewable-energy, and commercial applications.

Restraint: Higher cost of ester-based transformer fluids

The relatively high cost of ester-based transformer fluids is a key restraint for the transformer oil market. Natural and synthetic ester fluids provide advantages such as higher fire safety, biodegradability, and improved environmental performance compared with conventional mineral oil. However, these benefits generally come with a higher purchase price. For utilities and industrial users managing large transformer fleets, the initial cost difference can become significant when fluids are required for numerous transformers or large-capacity units. Mineral oil also benefits from established manufacturing infrastructure, mature supply chains, widespread availability, and extensive historical use, making it a cost-effective option for many applications. As a result, customers that prioritize upfront procurement costs may continue using conventional mineral oils rather than shifting to ester fluids. Although lifecycle benefits can partly offset the initial premium in specific applications, the higher upfront investment remains a barrier, particularly in price-sensitive developing markets and standard transformer installations where advanced fire-safety or environmental characteristics are not mandatory.

Opportunity: Shift toward bio-based and ester transformer fluids

Growing adoption of bio-based and ester transformer fluids represents a significant opportunity for market participants. Growing emphasis on environmental sustainability, fire safety, and reduced ecological risk is encouraging utilities, transformer manufacturers, and industrial users to consider alternatives to conventional mineral oil. Natural ester fluids, particularly those derived from renewable, plant-based feedstocks, offer biodegradability and a higher fire point, making them attractive for applications where environmental or fire-safety considerations matter. Potential demand is particularly strong in urban substations, renewable-energy installations, indoor facilities, and other locations where minimizing fire and environmental risks is a priority. Retrofitting existing transformers with ester fluids also creates an opportunity because customers can potentially improve the environmental and safety profile of installed assets without replacing the entire transformer. As awareness of lifecycle costs and sustainability increases, manufacturers can expand premium-fluid portfolios and develop application-specific solutions. This shift gives transformer oil suppliers opportunities to diversify beyond traditional mineral-based products and capture higher-value applications.

Challenge: Competition from established mineral-based oils

The continued dominance of conventional mineral oil presents a major challenge to transformer oil manufacturers seeking to expand alternative-fluid adoption. Mineral oil has been used extensively in power and distribution transformers for decades and benefits from established production capacity, global availability, well-developed supply chains, and extensive operating experience. Transformer OEMs and utilities are familiar with its performance characteristics, maintenance requirements, and compatibility with existing transformer designs. This established ecosystem creates switching barriers for customers considering natural or synthetic ester alternatives. In addition, mineral oil generally offers a lower upfront cost, which remains important for large-scale utility procurement and standard transformer applications. Alternative fluids may therefore need additional technical validation, compatibility assessment, and customer approval before adoption. Manufacturers of ester-based fluids must demonstrate sufficient performance, reliability, economic value, and compatibility to overcome customer hesitation. Consequently, although sustainability and fire-safety considerations support gradual diversification, the large installed base and cost advantages of mineral oil will continue to make market penetration of alternative transformer fluids challenging.

TRANSFORMER OIL MARKET SIZE, SHARE, INDUSTRY ANALYSIS: COMMERCIAL USE CASES ACROSS INDUSTRIES

COMPANY USE CASE DESCRIPTION BENEFITS
company logo
Cargill – FR3™ Natural Ester Dielectric Fluid: FR3™ is a natural ester transformer fluid derived from renewable vegetable oil and is used in distribution and power-generation transformers across voltage classes | It is also suitable for applications such as renewable-energy projects, data centers, switchgear, and transformer retrofilling | Its higher thermal capability allows transformers to handle increased loading, while its moisture-management properties help protect insulation | The fluid is particularly relevant where fire safety and environmental performance are priorities, including densely populated areas and renewable-energy installations. FR3™ provides multiple operational and sustainability benefits | Its high flash and fire points significantly improve transformer fire safety compared with mineral oil | The fluid can enable up to 20% higher loading capacity and can help extend transformer insulation life by reducing moisture-related degradation | Its renewable, readily biodegradable formulation also reduces environmental risks from leaks or spills | These characteristics can support improved grid resilience, longer asset life, lower maintenance requirements, and potentially lower total cost of ownership | Cargill also positions FR3™ for retrofitting existing transformers, allowing utilities to improve performance without replacing the entire asset.
company logo
Nynas – NYTRO® Transformer Oils: Nynas supplies NYTRO® transformer fluids for insulating and cooling power, distribution, and industrial transformers | Its portfolio includes conventional naphthenic oils as well as sustainable solutions such as NYTRO® RR 900X, a re-refined circular transformer fluid, and NYTRO® BIO 300X, a renewable and biodegradable transformer fluid | These products are designed for different transformer designs, climates, and operating conditions, with applications extending to renewable-energy infrastructure such as wind and solar projects. NYTRO® fluids provide reliable insulation, heat transfer, oxidation stability, and long service life | NYTRO® RR 900X enables circular use of end-of-life transformer oil while maintaining performance comparable to virgin mineral oil and requiring no transformer design modifications | NYTRO® BIO 300X provides ultra-low viscosity and enhanced cooling, helping reduce winding temperatures and improve transformer operating flexibility | The portfolio therefore supports transformer reliability, reduced maintenance, improved thermal performance, and sustainability objectives | Nynas reports that RR 900X can reduce greenhouse-gas emissions by at least 70% over its lifetime compared with virgin transformer oil, strengthening its value for circularity-focused utilities and OEMs.

Logos and trademarks shown above are the property of their respective owners. Their use here is for informational and illustrative purposes only.

MARKET ECOSYSTEM

The transformer oil ecosystem includes base oil and chemical suppliers, transformer oil manufacturers, transformer OEMs, distributors, testing/service providers, utilities, and industrial users. Upstream companies supply mineral oils, silicone fluids, bio-based esters, and additives, while oil manufacturers formulate and distribute dielectric fluids. Transformer OEMs and service providers use these fluids for insulation, cooling, testing, purification, and regeneration. Downstream demand is led by transmission & distribution, power generation, railways and metros, renewable energy, and industrial applications. Regulations and standards increasingly influence product quality, fire safety, and environmental performance.
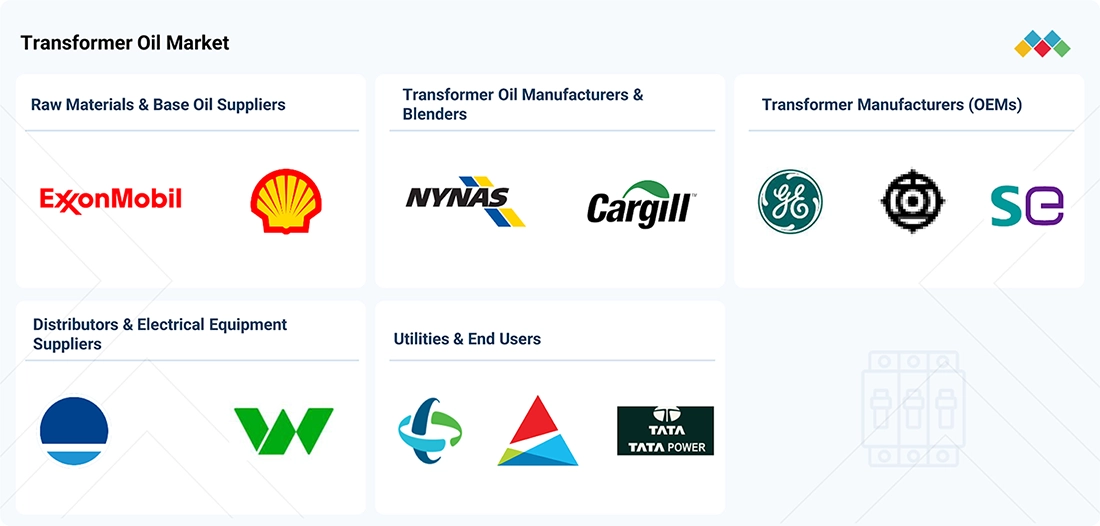
transformer-oil-market Ecosystem

Logos and trademarks shown above are the property of their respective owners. Their use here is for informational and illustrative purposes only.

MARKET SEGMENTS
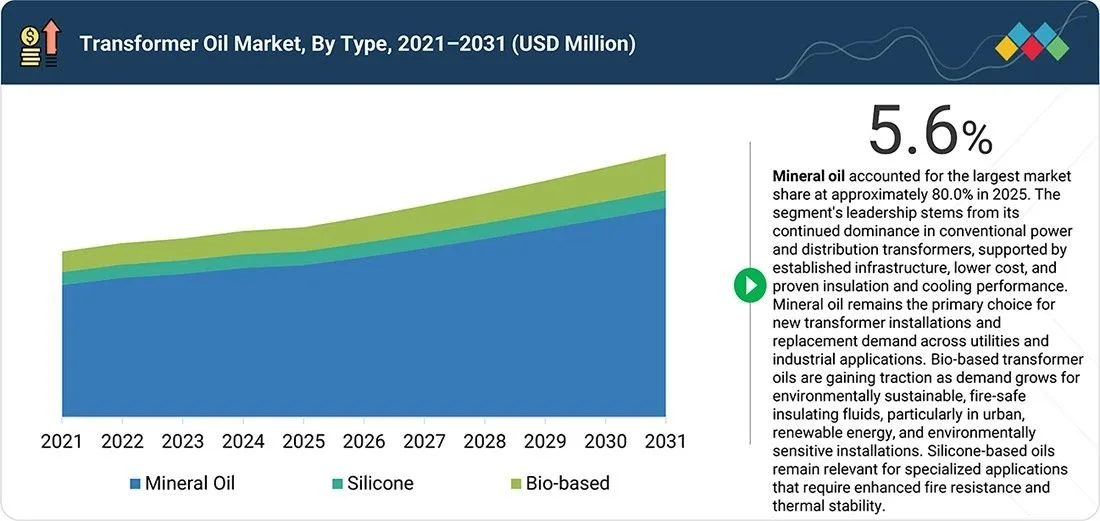
transformer-oil-market Segments

Source: Secondary Research, Interviews with Experts, MarketsandMarkets Analysis

By Type — Mineral oil is projected to register the highest CAGR during the forecast period

Mineral oil dominates the transformer oil market because it is widely used in conventional power and distribution transformers and is the industry-standard insulating fluid. The segment benefits from strong dielectric properties, effective heat dissipation, chemical stability, and cost advantages compared with silicone and bio-based alternatives. Mineral oil is also supported by well-established global supply chains, technical standards, maintenance practices, and compatibility with the large installed base of oil-filled transformers. Utilities and transformer manufacturers continue to prefer mineral oil for high-volume applications because of its proven operational performance and availability. Growing investments in transmission and distribution infrastructure, replacement of aging transformers, and expansion of electricity networks further support demand.

By Application — Transformers are projected to register the highest CAGR during the forecast period

The largest application segment is transformers, since transformer oil is mainly used to provide electrical insulation and cooling in oil-filled transformers. It aids in heat dissipation during transformer operation, maintains the transformer's dielectric strength, and prevents internal components from breaking down and deteriorating due to electrical stress. Power and distribution transformers can consume a great deal of insulating fluid compared with switchgear and reactors. Demand is also being fueled by the ongoing growth of electricity transmission and distribution networks, the integration of more renewable energy and the replacement of the aging transformer fleet. Transformers are also used in renewable energy projects to step up the voltage of electrical generation and to link generation resources to electrical transmission networks, thus increasing transformer oil consumption.

By End User — Transmission & distribution is expected to register the highest CAGR during the forecast period

Mineral oil dominates the transformer oil market because it is widely used in traditional and distribution transformers and is the industry-standard insulating liquid. The segment benefits from superior dielectric properties, good heat resistance, chemical stability, and a cost advantage over silicone and bio-based alternatives. Mineral oil's popularity is supported by well-established global supply chains, technical standards, maintenance practices, and compatibility with the large installed base of oil-filled transformers. Utilities and transformer manufacturers still view mineral oil as the first choice for mass-market applications because it has delivered strong business performance and customer satisfaction. The increasing investment in transmission and distribution infrastructure, the replacement of old transformers, and the growth of electricity networks further drive demand.

REGION

North America to account for fastest growing region during forecast period

North America is a significant, mature transformer oil market, supported by grid modernization, replacement of aging transformer fleets, renewable-energy integration, and rising electricity demand from data centers and industrial electrification. The US remains the primary demand center, while Canada contributes through transmission upgrades and renewable power projects. Demand continues to favor mineral oils, although natural and synthetic ester fluids are gaining traction where fire safety, biodegradability, and environmental performance are priorities. North America's position as the fastest-growing region, even as Asia Pacific remains the largest market by overall market size.
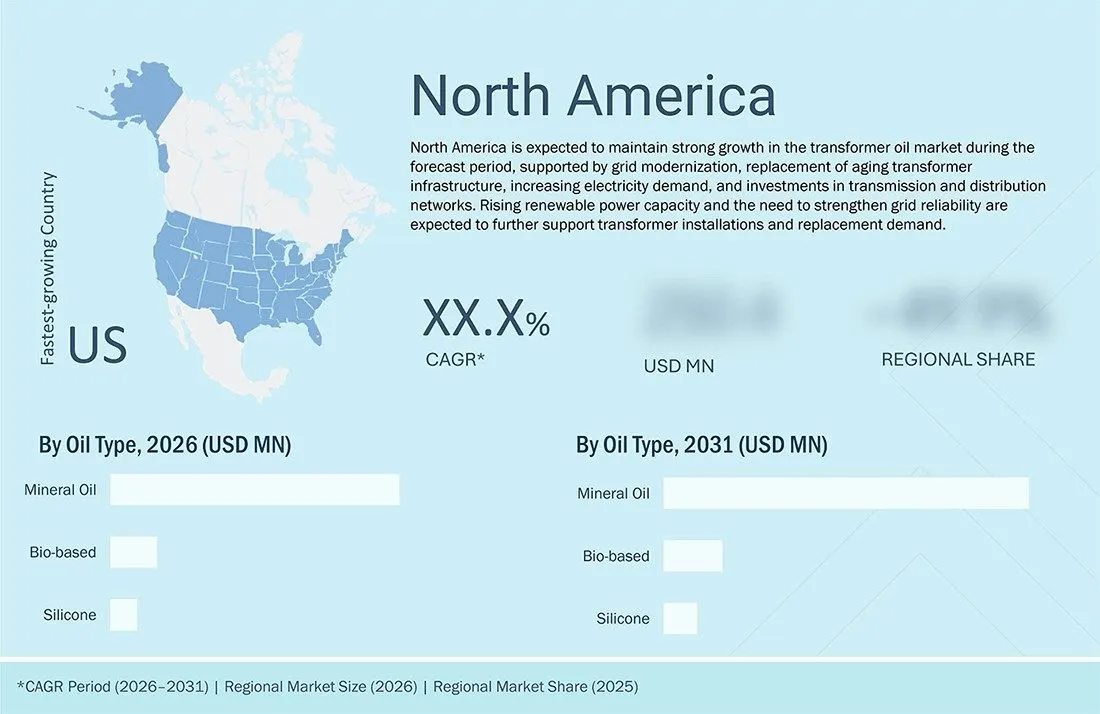
transformer-oil-market Region

TRANSFORMER OIL MARKET SIZE, SHARE, INDUSTRY ANALYSIS: COMPANY EVALUATION MATRIX

The transformer oil market is moderately consolidated, with established players competing through broad product portfolios, technical expertise, global distribution networks, and long-standing utility relationships. Shell, Nynas AB, PetroChina Company Limited, Cargill Incorporated, and APAR Industries are among the prominent participants. Competition is increasingly influenced by the shift toward bio-based and ester fluids, alongside continued demand for conventional mineral oils. Leading companies are expanding production capacity, strengthening regional supply capabilities, developing higher-performance fluids, and pursuing partnerships and acquisitions. Regional players such as APAR and Savita remain competitive through cost-effective offerings and a strong presence in Asia, while global companies leverage diversified portfolios and international reach.
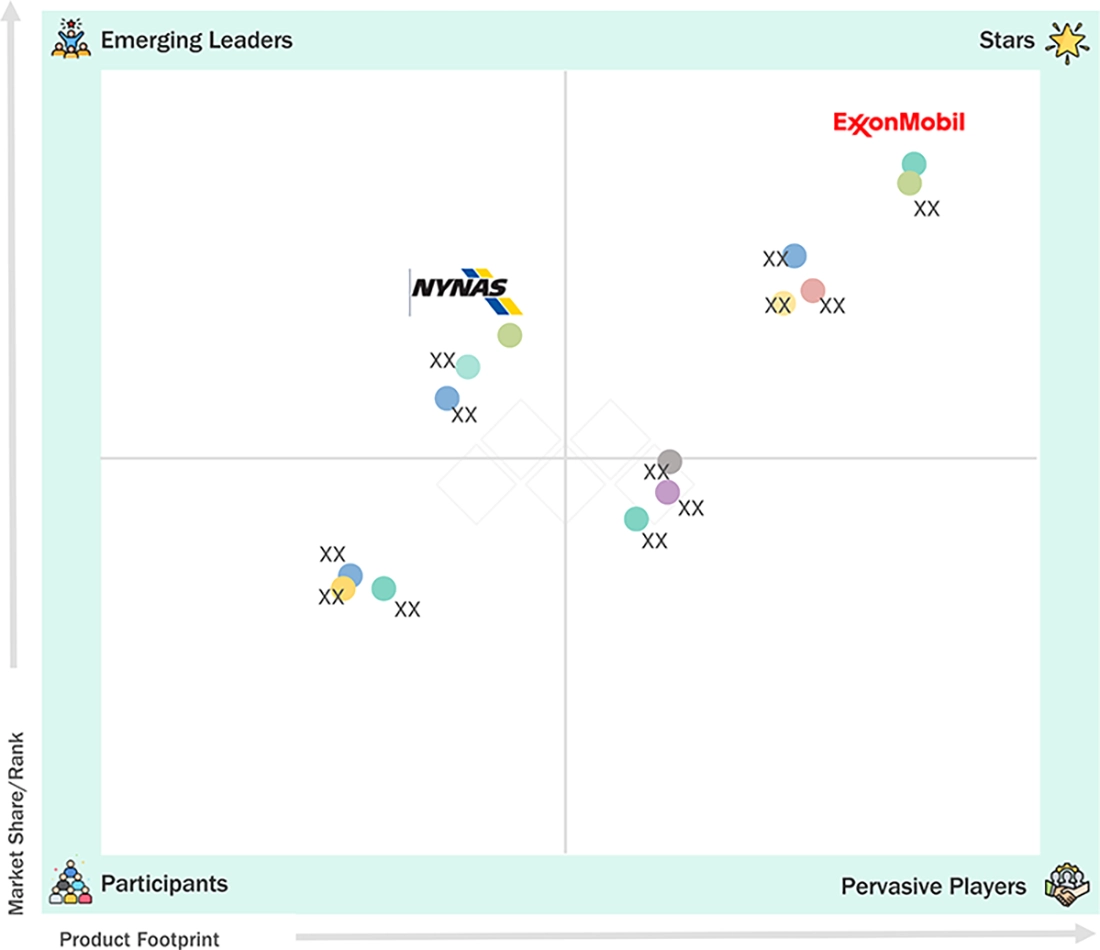
transformer-oil-market Evaluation Metrics

Source: Secondary Research, Interviews with Experts, MarketsandMarkets Analysis

KEY MARKET PLAYERS

MARKET SCOPE

REPORT METRIC DETAILS
Market Size in 2025 (Value) USD 2.07 Billion
Market Forecast in 2026 (Value) USD 2.18 Billion
Market Forecast in 2031 (Value) USD 2.87 Billion
Growth Rate CAGR of 5.6% from 2026–2031
Years Considered 2021–2031
Base Year 2025
Forecast Period 2026–2031
Units Considered Value (USD Million/Billion)
Report Coverage Market Size and Forecast, Company Profiling, Competitive Landscape, Market Dynamics (Drivers, Restraints, Opportunities, and Challenges), Technology Trends, Ecosystem Analysis, Commercial Use Cases, and Regional Analysis
Segments Covered
  • By Type:
    • Mineral Oil
    • Silicone
    • Bio-based
  • By Application:
    • Transformers
    • Switchgears
    • Reactors
  • By End User:
    • Transmission & Distribution
    • Power Generation
    • Railways & Metros
    • Other End Users
Regions Covered North America, Europe, Asia Pacific, Rest of the World

WHAT IS IN IT FOR YOU: TRANSFORMER OIL MARKET SIZE, SHARE, INDUSTRY ANALYSIS REPORT CONTENT GUIDE
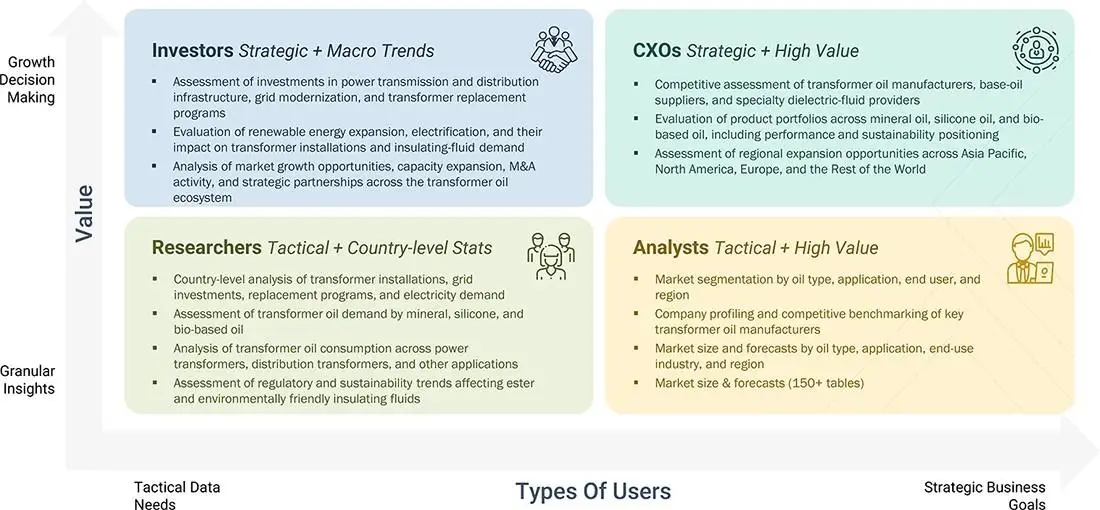
transformer-oil-market Content Guide

DELIVERED CUSTOMIZATIONS

We have successfully delivered the following deep-dive customizations:

CLIENT REQUEST CUSTOMIZATION DELIVERED VALUE ADDS
European Transformer Oil
  • European transformer oil market analysis covering market size and forecast by oil type, application, end user, and key European countries
  • The analysis includes key market drivers, trends, regulatory developments, competitive landscape, company profiles, recent developments, and opportunities across mineral, bio-based, and silicone transformer oils.
Provides a focused view of the European market, enabling assessment of country-level growth opportunities, demand from transmission & distribution, power generation, and railways & metros, as well as the shift toward bio-based and ester transformer fluids driven by fire-safety and environmental requirements.

RECENT DEVELOPMENTS

  • August 2026 : Cargill doubled production capacity for its FR3™ natural ester dielectric fluid at its Dilovasi, Türkiye facility. The expansion adds a new production line to meet increasing demand from transformer manufacturers and critical infrastructure applications, including data centers, renewable energy, battery storage, and electrification. FR3 contains more than 99% bio-based content and has a high fire point, positioning the expansion as a safer, more sustainable alternative to conventional mineral transformer oil. The investment also strengthens Türkiye's role as a regional manufacturing and supply hub for advanced transformer fluids.
  • March 2026 : Cargill opened a new FR3™ natural ester dielectric fluid production plant in Gouda, Netherlands, investing approximately USD 30 million and tripling its European production capacity. The facility is intended to improve regional supply availability and logistics as demand increases from grid expansion, renewable energy, battery storage, and data centers. The development strengthens Cargill's position in bio-based transformer fluids and supports customers seeking high-performance insulating fluids with improved fire safety, biodegradability, and grid-resilience characteristics.
  • March 2026 : Nynas and Hitachi Energy advanced the adoption of circular transformer fluids through the first retrofit of NYTRO® RR 900X in a critical 117 MVA transformer at Hitachi Energy's Córdoba, Spain, facility. Electrical and thermal testing confirmed performance comparable to virgin mineral oil. The fully re-refined fluid is produced from used transformer oils and complies with IEC 60296:2020. The development demonstrates the commercial potential of circular transformer oil solutions, supports lower-carbon transformer manufacturing, and reduces dependence on virgin feedstocks.
  • April 2025 : Shell launched the Shell MIDEL brand worldwide as part of its expanded portfolio of transformer liquids. The addition brings natural and synthetic ester insulating liquids alongside Shell Diala products, broadening Shell's offering beyond conventional transformer oils. Shell positioned the expanded portfolio for power and distribution transformers as well as renewable energy, rail, mining, and industrial applications. The development strengthens Shell's presence in higher-value transformer fluid applications where fire safety, environmental performance, reliability, and energy-transition requirements increasingly influence fluid selection.


Table of Contents

checkmarkExclusive indicates content/data unique to MarketsandMarkets and not available with any competitors.

TITLE
PAGE NO
1
INTRODUCTION


29
2
EXECUTIVE SUMMARY


34
3
PREMIUM INSIGHTS


39
4
MARKET OVERVIEW
Power grid evolution drives demand for sustainable transformers amid electrification and infrastructure expansion.


43
 
4.1
INTRODUCTION


4.2
MARKET DYNAMICS


4.2.1
DRIVERS


4.2.1.1
GRID INVESTMENTS TO MEET INCREASING POWER DEMAND


4.2.1.2
REQUIREMENT FOR REPLACEMENT AND UPGRADES OF AGING GRID ASSETS


4.2.1.3
RISE IN ELECTRICITY-INTENSIVE LOADS AND ELECTRIFICATION


4.2.2
RESTRAINTS


4.2.2.1
ENVIRONMENTAL AND FIRE-SAFETY CONCERNS


4.2.2.2
GROWING DRY-TYPE TRANSFORMER ADOPTION


4.2.2.3
AVAILABILITY OF ALTERNATIVE INSULATING LIQUIDS


4.2.3
OPPORTUNITIES


4.2.3.1
GROWING DEMAND FOR ESTER-BASED INSULATING LIQUIDS AMID SUSTAINABILITY REQUIREMENTS


4.2.3.2
TRANSFORMER INFRASTRUCTURE EXPANSION TO SUPPORT CROSS-BORDER POWER TRANSMISSION


4.2.3.3
DEMAND FOR HIGH-VOLTAGE TRANSFORMERS DUE TO HVDC EXPANSION


4.2.3.4
AFTERMARKET OPPORTUNITIES FOR TRANSFORMER FLEET MAINTENANCE AND RETROFILLING


4.2.4
CHALLENGES


4.2.4.1
FEEDSTOCK PRICE VOLATILITY PRESSURES TRANSFORMER OIL MANUFACTURERS


4.2.4.2
TRANSFORMER SUPPLY CONSTRAINTS


4.3
INTERCONNECTED MARKETS AND CROSS-SECTOR OPPORTUNITIES


4.3.1
CROSS SECTOR OPPORTUNITIES


4.3.2
MARKET MAP


5
INDUSTRY TRENDS
Navigate competitive landscapes and seize opportunities in the evolving transformer oil market.


53
 
5.1
PORTER’S FIVE FORCES ANALYSIS


5.1.1
THREAT OF NEW ENTRANTS


5.1.2
BARGAINING POWER OF SUPPLIERS


5.1.3
BARGAINING POWER OF BUYERS


5.1.4
THREAT OF SUBSTITUTES


5.1.5
INTENSITY OF COMPETITIVE RIVALRY


5.2
VALUE CHAIN ANALYSIS


5.2.1
RAW MATERIAL SUPPLIERS


5.2.2
TRANSFORMER OIL PRODUCERS


5.2.3
EQUIPMENT MANUFACTURERS


5.2.4
DISTRIBUTORS


5.2.5
END USERS


5.3
PRICING ANALYSIS


5.3.1
AVERAGE SELLING PRICE ANALYSIS, BY OIL TYPE


5.4
TRENDS/DISRUPTIONS IMPACTING CUSTOMER BUSINESS


5.5
CASE STUDY ANALYSIS


5.5.1
TATA POWER INSTALLS DISTRIBUTION TRANSFORMERS IN MUMBAI TO ADDRESS SPACE- AND SAFETY-RELATED CONCERNS AND REDUCE COST AND ENVIRONMENTAL IMPACT


5.6
IMPACT OF DEVELOPMENTS IN RENEWABLE ENERGY & TRANSITION TOWARD CLEAN ENERGY ON TRANSFORMER OIL MARKET


5.7
IMPACT OF EV ADOPTION & EV INFRASTRUCTURE DEVELOPMENTS ON TRANSFORMER OIL MARKET


5.8
TECHNOLOGY ANALYSIS


5.9
REGULATIONS


6
TRANSFORMER OIL MARKET, BY OIL TYPE
Market Size & Growth Rate Forecast Analysis to 2031 in USD Million and Liters | 38 Data Tables


62
 
6.1
INTRODUCTION


6.2
MINERAL OIL


6.2.1
ESTABLISHED INFRASTRUCTURE AND COST COMPETITIVENESS TO SUSTAIN DEMAND FOR MINERAL TRANSFORMER OIL


6.2.2
NAPHTHENIC OIL


6.2.2.1
NAPHTHENIC OIL, BY INHIBITION TYPE


6.2.2.1.1
INHIBITED NAPHTHENIC OIL


6.2.2.1.2
UNINHIBITED NAPHTHENIC OIL


6.2.3
PARAFFINIC OIL


6.2.3.1
PARAFFINIC OIL, BY INHIBITION TYPE


6.2.3.1.1
INHIBITED PARAFFINIC OIL


6.2.3.1.2
UNINHIBITED PARAFFINIC OIL
 
 
6.3
BIO-BASED OIL


6.3.1
RISING ENVIRONMENTAL CONCERNS TO DRIVE DEMAND FOR BIO-BASED OIL


6.4
SILICONE OIL


6.4.1
NON-REACTIVE AND NON-TOXIC PROPERTIES TO FUEL NEED FOR SILICONE TRANSFORMER OIL


7
TRANSFORMER OIL MARKET, BY END USER
Market Size & Growth Rate Forecast Analysis to 2031 in USD Million and Liters | 12 Data Tables


78
 
7.1
INTRODUCTION


7.2
TRANSMISSION & DISTRIBUTION UTILITIES


7.2.1
RISING FOCUS ON UPGRADING AGING T&D INFRASTRUCTURE TO FUEL MARKET GROWTH


7.3
RAILWAYS & METROS


7.3.1
GROWING INVESTMENTS IN RAILWAYS & METROS TO PROPEL DEMAND FOR TRANSFORMER OIL


7.4
POWER GENERATION UTILITIES


7.4.1
INCREASING NEED FOR POWER GENERATION TO DRIVE MARKET


7.5
OTHERS


8
TRANSFORMER OIL MARKET, BY APPLICATION
Market Size & Growth Rate Forecast Analysis to 2031 in USD Million and Liters | 18 Data Tables


86
 
8.1
INTRODUCTION


8.2
TRANSFORMER


8.2.1
INCREASING INVESTMENTS IN T&D SECTOR TO CREATE DEMAND FOR TRANSFORMERS


8.2.2
POWER TRANSFORMER


8.2.3
DISTRIBUTION TRANSFORMER


8.3
REACTOR


8.3.1
LONG-TERM INDUSTRIAL GROWTH AND INCREASED DEMAND FOR ENERGY TO BOOST SEGMENTAL GROWTH


8.4
SWITCHGEAR


8.4.1
INVESTMENTS IN T&D NETWORK EXPANSION TO PROPEL DEMAND FOR OIL-FILLED SWITCHGEAR


9
TRANSFORMER OIL MARKET, BY REGION
Comprehensive coverage of 8 Regions with country-level deep-dive of 12 Countries | 254 Data Tables.


95
 
9.1
INTRODUCTION


9.2
ASIA PACIFIC


9.2.1
BY OIL TYPE


9.2.1.1
MINERAL OIL - BY SUB-OIL TYPE


9.2.1.2
MINERAL OIL - BY INHIBITION TYPE


9.2.1.2.1
NAPHTHENIC MINERAL OIL - BY INHIBITION TYPE


9.2.1.2.2
PARAFFINIC MINERAL OIL - BY INHIBITION TYPE


9.2.2
BY APPLICATION


9.2.2.1
TRANSFORMER - BY SUB-APPLICATION


9.2.3
BY END USER


9.2.4
BY COUNTRY


9.2.4.1
CHINA


9.2.4.1.1
INCREASING INVESTMENTS IN T&D SECTOR TO FAVOR MARKET GROWTH


9.2.4.2
INDIA


9.2.4.2.1
INCREASING POWER GENERATION ACTIVITIES TO GENERATE DEMAND FOR TRANSFORMER OIL


9.2.4.3
JAPAN


9.2.4.3.1
RENOVATION OF GRID INFRASTRUCTURE TO DRIVE MARKET


9.2.4.4
AUSTRALIA


9.2.4.4.1
RISING ENERGY INFRASTRUCTURE AND RENEWABLE INVESTMENTS TO SUPPORT TRANSFORMER OIL DEMAND


9.2.4.5
SOUTH KOREA


9.2.4.5.1
GOVERNMENT INITIATIVES TO BOOST RENEWABLE POWER GENERATION TO FACILITATE SEGMENTAL GROWTH


9.2.4.6
REST OF ASIA PACIFIC


9.3
NORTH AMERICA


9.3.1
BY OIL TYPE


9.3.1.1
MINERAL OIL - BY SUB-OIL TYPE


9.3.1.2
MINERAL OIL - BY INHIBITION TYPE


9.3.1.2.1
NAPHTHENIC MINERAL OIL - BY INHIBITION TYPE


9.3.1.2.2
PARAFFINIC MINERAL OIL - BY INHIBITION TYPE


9.3.2
BY APPLICATION


9.3.2.1
TRANSFORMER - BY SUB-APPLICATION


9.3.3
BY END USER


9.3.4
BY COUNTRY


9.3.4.1
US


9.3.4.1.1
UPGRADES TO EXISTING POWER INFRASTRUCTURE TO DRIVE MARKET


9.3.4.2
CANADA


9.3.4.2.1
RAPID EXPANSION OF TRANSMISSION NETWORKS TO DRIVE MARKET


9.3.4.3
MEXICO


9.3.4.3.1
GROWTH OF INDUSTRIAL SECTOR AND SURGING ENERGY REQUIREMENTS TO BOOST MARKET
 
 
9.4
EUROPE


9.4.1
BY OIL TYPE


9.4.2
MINERAL OIL – BY SUB-OIL TYPE


9.4.3
MINERAL OIL – BY INHIBITION TYPE


9.4.3.1
NAPHTHENIC MINERAL OIL – BY INHIBITION TYPE


9.4.3.2
PARAFFINIC MINERAL OIL – BY INHIBITION TYPE


9.4.4
BY APPLICATION


9.4.4.1
BY TRANSFORMER – SUB-APPLICATION


9.4.5
BY END USER


9.4.6
BY COUNTRY


9.5
UK


9.5.1
RISING GRID INVESTMENT AND RENEWABLE INTEGRATION TO FOSTER MARKET GROWTH


9.5.2
BY OIL TYPE


9.5.3
MINERAL OIL – BY SUB-OIL TYPE


9.5.4
BY APPLICATION


9.5.4.1
BY TRANSFORMER – SUB-APPLICATION


9.5.5
BY END USER


9.6
GERMANY


9.6.1
ENERGY TRANSITION AND RENEWABLE ENERGY ADOPTION TO EXPEDITE MARKET GROWTH


9.6.2
BY OIL TYPE


9.6.3
MINERAL OIL – BY SUB-OIL TYPE


9.6.4
BY APPLICATION


9.6.4.1
BY TRANSFORMER – SUB-APPLICATION


9.6.5
BY END USER


9.7
RUSSIA


9.7.1
GRID MODERNIZATION AND TRANSFORMER CAPACITY EXPANSION TO BOLSTER MARKET GROWTH


9.7.2
BY OIL TYPE


9.7.3
MINERAL OIL – BY SUB-OIL TYPE


9.7.4
BY APPLICATION


9.7.4.1
BY TRANSFORMER – SUB-APPLICATION


9.7.5
BY END USER


9.8
FRANCE


9.8.1
GRID REINFORCEMENT AND ELECTRIFICATION TO ACCELERATE MARKET GROWTH


9.8.2
BY OIL TYPE


9.8.3
MINERAL OIL – BY SUB-OIL TYPE


9.8.4
BY APPLICATION


9.8.4.1
BY TRANSFORMER – SUB-APPLICATION


9.8.5
BY END USER


9.9
REST OF EUROPE


9.9.1
BY OIL TYPE


9.9.2
MINERAL OIL – BY SUB-OIL TYPE


9.9.3
BY APPLICATION


9.9.3.1
BY TRANSFORMER – SUB-APPLICATION


9.9.4
BY END USER


9.10
ROW


9.10.1
BY OIL TYPE


9.10.1.1
MINERAL OIL - BY SUB-OIL TYPE


9.10.1.2
MINERAL OIL - BY INHIBITION TYPE


9.10.1.2.1
NAPHTHENIC MINERAL OIL - BY INHIBITION TYPE


9.10.1.2.2
PARAFFINIC MINERAL OIL - BY INHIBITION TYPE


9.10.2
BY APPLICATION


9.10.2.1
TRANSFORMER - BY SUB-APPLICATION


9.10.3
BY END USER


9.10.4
BY REGION


9.10.4.1
MIDDLE EAST


9.10.4.1.1
HIGH INVESTMENTS IN OIL & GAS INDUSTRY AND INFRASTRUCTURAL DEVELOPMENTS TO AUGMENT MARKET GROWTH


9.10.4.2
AFRICA


9.10.4.2.1
STRONG FOCUS ON REDUCING BLACKOUTS AND POWER OUTAGES TO FUEL MARKET GROWTH


9.10.4.3
SOUTH AMERICA


9.10.4.3.1
INCREASING INVESTMENTS IN POWER GENERATION TO BOLSTER MARKET GROWTH
 
10
COMPETITIVE LANDSCAPE
Uncover key strategies and market positions of top transformer oil players shaping global competition.


182
 
10.1
OVERVIEW


10.2
KEY PLAYER COMPETITIVE STRATEGIES/RIGHT TO WIN, JANUARY 2023–AUGUST 2026


10.3
REVENUE ANALYSIS, 2021–2025


10.4
MARKET SHARE ANALYSIS, 2025


10.5
BRAND COMPARISON


10.5.1
NYNAS AB (SWEDEN)


10.5.2
PETROCHINA COMPANY LIMITED (CHINA)


10.5.3
APAR INDUSTRIES (INDIA)


10.5.4
SHELL (UK)


10.5.5
ERGON, INC. (US)


10.6
COMPANY EVALUATION MATRIX: KEY PLAYERS, 2025


10.6.1
STARS


10.6.2
EMERGING LEADERS


10.6.3
PERVASIVE PLAYERS


10.6.4
PARTICIPANTS


10.7
COMPETITIVE SCENARIOS


10.7.1
PRODUCT LAUNCHES


10.7.2
DEALS


10.7.3
EXPANSIONS


11
COMPANY PROFILES
In-depth Company Profiles of Leading Market Players with detailed Business Overview, Product and Service Portfolio, Recent Developments, and Unique Analyst Perspective (MnM View)


195
 
11.1
KEY PLAYERS


11.1.1
NYNAS AB


11.1.1.1
BUSINESS OVERVIEW


11.1.1.2
PRODUCTS OFFERED


11.1.1.3
RECENT DEVELOPMENTS


11.1.1.3.1
PRODUCT LAUNCHES


11.1.1.3.2
DEALS


11.1.1.3.3
OTHER DEVELOPMENTS


11.1.1.4
MNM VIEW


11.1.1.4.1
KEY STRENGTHS/RIGHT TO WIN


11.1.1.4.2
STRATEGIC CHOICES


11.1.1.4.3
WEAKNESSES/COMPETITIVE THREATS


11.1.2
ERGON, INC.


11.1.3
PETROCHINA COMPANY LIMITED


11.1.4
APAR INDUSTRIES LIMITED


11.1.5
SHELL


11.1.6
CALUMET SPECIALTY PRODUCTS PARTNERS, L.P.


11.1.7
SINOPEC LUBRICANT COMPANY


11.1.8
CARGILL, INCORPORATED.


11.1.9
EXXON MOBIL CORPORATION


11.1.10
GULF OIL INTERNATIONAL LTD


11.1.11
PHILLIPS 66 COMPANY


11.1.12
DOW


11.1.13
REPSOL


11.1.14
CHEVRON CORPORATION


11.1.15
SAVITA


11.2
OTHER PLAYERS


11.2.1
GANDHAR OIL REFINERY (INDIA) LIMITED


11.2.2
HYDRODEC GROUP PLC


11.2.3
ENGEN PETROLEUM LIMITED


11.2.4
LUBRITA


11.2.5
PETRO-CANADA


12
RESEARCH METHODOLOGY


241
 
12.1
RESEARCH DATA


12.2
DATA TRIANGULATION


12.2.1
SECONDARY DATA


12.2.1.1
KEY DATA FROM SECONDARY SOURCES


12.2.2
PRIMARY DATA


12.2.2.1
KEY INDUSTRY INSIGHTS


12.2.2.2
BREAKDOWN OF PRIMARY INTERVIEWS


12.3
MARKET SIZE ESTIMATION


12.3.1
BOTTOM-UP APPROACH


12.3.2
TOP-DOWN APPROACH


12.3.3
DEMAND-SIDE ANALYSIS


12.3.3.1
DEMAND-SIDE CALCULATIONS


12.3.3.2
DEMAND-SIDE ASSUMPTIONS


12.3.4
SUPPLY-SIDE ANALYSIS


12.3.4.1
SUPPLY-SIDE CALCULATIONS


12.3.4.2
SUPPLY-SIDE ASSUMPTIONS


12.3.5
FORECAST


13
APPENDIX


251
 
13.1
INSIGHTS FROM INDUSTRY EXPERTS


13.2
DISCUSSION GUIDE


13.3
KNOWLEDGESTORE: MARKETSANDMARKETS’ SUBSCRIPTION PORTAL


13.4
CUSTOMIZATION OPTIONS


13.5
RELATED REPORTS


13.6
AUTHOR DETAILS


LIST OF TABLES


TABLE 1
TRANSFORMER OIL MARKET: INCLUSIONS AND EXCLUSIONS


TABLE 2
INTERCONNECTED MARKETS


TABLE 3
IMPACT OF PORTER’S FIVE FORCES


TABLE 4
TRANSFORMER OIL MARKET: VALUE CHAIN ANALYSIS


TABLE 5
TRANSFORMER OIL MARKET: PRICING ANALYSIS


TABLE 6
TRANSFORMER OIL MARKET: REGULATIONS


TABLE 7
TRANSFORMER OIL MARKET, BY OIL TYPE, 2021–2025 (USD MILLION)


TABLE 8
TRANSFORMER OIL MARKET, BY OIL TYPE, 2026–2031 (USD MILLION)


TABLE 9
TRANSFORMER OIL MARKET, BY OIL TYPE, 2021–2025 (MILLION LITERS)


TABLE 10
TRANSFORMER OIL MARKET, BY OIL TYPE, 2026–2031 (MILLION LITERS)


TABLE 11
MINERAL OIL: TRANSFORMER OIL MARKET, BY SUB-OIL TYPE, 2021–2025 (USD MILLION)


TABLE 12
MINERAL OIL: TRANSFORMER OIL MARKET, BY SUB-OIL TYPE, 2026–2031 (USD MILLION)


TABLE 13
MINERAL OIL: TRANSFORMER OIL MARKET, BY SUB-OIL TYPE, 2021–2025 (MILLION LITERS)


TABLE 14
MINERAL OIL: TRANSFORMER OIL MARKET, BY SUB-OIL TYPE, 2026–2031 (MILLION LITERS)


TABLE 15
MINERAL OIL: TRANSFORMER OIL MARKET, BY INHIBITION TYPE, 2021–2025 (USD MILLION)


TABLE 16
MINERAL OIL: TRANSFORMER OIL MARKET, BY INHIBITION TYPE, 2026–2031 (USD MILLION)


TABLE 17
MINERAL OIL: TRANSFORMER OIL MARKET, BY INHIBITION TYPE, 2021–2025 (MILLION LITERS)


TABLE 18
MINERAL OIL: TRANSFORMER OIL MARKET, BY INHIBITION TYPE, 2026–2031 (MILLION LITERS)


TABLE 19
MINERAL OIL: TRANSFORMER OIL MARKET, BY REGION, 2021–2025 (USD MILLION)


TABLE 20
MINERAL OIL: TRANSFORMER OIL MARKET, BY REGION, 2026–2031 (USD MILLION)


TABLE 21
NAPHTHENIC OIL: TRANSFORMER OIL MARKET, BY REGION, 2021–2025 (USD MILLION)


TABLE 22
NAPHTHENIC OIL: TRANSFORMER OIL MARKET, BY REGION, 2026–2031 (USD MILLION)


TABLE 23
NAPHTHENIC OIL: TRANSFORMER OIL MARKET, BY INHIBITION TYPE, 2021–2025 (USD MILLION)


TABLE 24
NAPHTHENIC OIL: TRANSFORMER OIL MARKET, BY INHIBITION TYPE, 2026–2031 (USD MILLION)


TABLE 25
NAPHTHENIC OIL: TRANSFORMER OIL MARKET, BY INHIBITION TYPE, 2021–2025 (MILLION LITERS)


TABLE 26
NAPHTHENIC OIL: TRANSFORMER OIL MARKET, BY INHIBITION TYPE, 2026–2031 (MILLION LITERS)


TABLE 27
INHIBITED NAPHTHENIC OIL: TRANSFORMER OIL MARKET, BY REGION, 2021–2025 (USD MILLION)


TABLE 28
INHIBITED NAPHTHENIC OIL: TRANSFORMER OIL MARKET, BY REGION, 2026–2031 (USD MILLION)


TABLE 29
UNINHIBITED NAPHTHENIC OIL: TRANSFORMER OIL MARKET, BY REGION, 2021–2025 (USD MILLION)


TABLE 30
UNINHIBITED NAPHTHENIC OIL: TRANSFORMER OIL MARKET, BY REGION, 2026–2031 (USD MILLION)


TABLE 31
PARAFFINIC OIL: TRANSFORMER OIL MARKET, BY REGION, 2021–2025 (USD MILLION)


TABLE 32
PARAFFINIC OIL: TRANSFORMER OIL MARKET, BY REGION, 2026–2031 (USD MILLION)


TABLE 33
PARAFFINIC OIL: TRANSFORMER OIL MARKET, BY INHIBITION TYPE, 2021–2025 (USD MILLION)


TABLE 34
PARAFFINIC OIL: TRANSFORMER OIL MARKET, BY INHIBITION TYPE, 2026–2031 (USD MILLION)


TABLE 35
PARAFFINIC OIL: TRANSFORMER OIL MARKET, BY INHIBITION TYPE, 2021–2025 (MILLION LITERS)


TABLE 36
PARAFFINIC OIL: TRANSFORMER OIL MARKET, BY INHIBITION TYPE, 2026–2031 (MILLION LITERS)


TABLE 37
INHIBITED PARAFFINIC OIL: TRANSFORMER OIL MARKET, BY REGION, 2021–2025 (USD MILLION)


TABLE 38
INHIBITED PARAFFINIC OIL: TRANSFORMER OIL MARKET, BY REGION, 2026–2031 (USD MILLION)


TABLE 39
UNINHIBITED PARAFFINIC OIL: TRANSFORMER OIL MARKET, BY REGION, 2021–2025 (USD MILLION)


TABLE 40
UNINHIBITED PARAFFINIC OIL: TRANSFORMER OIL MARKET, BY REGION, 2026–2031 (USD MILLION)


TABLE 41
BIO-BASED OIL: TRANSFORMER OIL MARKET, BY REGION, 2021–2025 (USD MILLION)


TABLE 42
BIO-BASED OIL: TRANSFORMER OIL MARKET, BY REGION, 2026–2031 (USD MILLION)


TABLE 43
SILICONE OIL: TRANSFORMER OIL MARKET, BY REGION, 2021–2025 (USD MILLION)


TABLE 44
SILICONE OIL: TRANSFORMER OIL MARKET, BY REGION, 2026–2031 (USD MILLION)


TABLE 45
TRANSFORMER OIL MARKET, BY END USER, 2021–2025 (USD MILLION)


TABLE 46
TRANSFORMER OIL MARKET, BY END USER, 2026–2031 (USD MILLION)


TABLE 47
TRANSFORMER OIL MARKET, BY END USER, 2021–2025 (MILLION LITERS)


TABLE 48
TRANSFORMER OIL MARKET, BY END USER, 2026–2031 (MILLION LITERS)


TABLE 49
TRANSMISSION & DISTRIBUTION UTILITIES: TRANSFORMER OIL MARKET, BY REGION, 2021–2025 (USD MILLION)


TABLE 50
TRANSMISSION & DISTRIBUTION UTILITIES: TRANSFORMER OIL MARKET, BY REGION, 2026–2031 (USD MILLION)


TABLE 51
RAILWAYS & METROS: TRANSFORMER OIL MARKET, BY REGION, 2021–2025 (USD MILLION)


TABLE 52
RAILWAYS & METROS: TRANSFORMER OIL MARKET, BY REGION, 2026–2031 (USD MILLION)


TABLE 53
POWER GENERATION UTILITIES: TRANSFORMER OIL MARKET, BY REGION, 2021–2025 (USD MILLION)


TABLE 54
POWER GENERATION UTILITIES: TRANSFORMER OIL MARKET, BY REGION, 2026–2031 (USD MILLION)


TABLE 55
OTHERS: TRANSFORMER OIL MARKET, BY REGION, 2021–2025 (USD MILLION)


TABLE 56
OTHERS: TRANSFORMER OIL MARKET, BY REGION, 2026–2031 (USD MILLION)


TABLE 57
TRANSFORMER OIL MARKET, BY APPLICATION, 2021–2025 (USD MILLION)


TABLE 58
TRANSFORMER OIL MARKET, BY APPLICATION, 2026–2031 (USD MILLION)


TABLE 59
TRANSFORMER OIL MARKET, BY APPLICATION, 2021–2025 (MILLION LITERS)


TABLE 60
TRANSFORMER OIL MARKET, BY APPLICATION, 2026–2031 (MILLION LITERS)


TABLE 61
TRANSFORMER: TRANSFORMER OIL MARKET, BY SUB-APPLICATION, 2021–2025 (USD MILLION)


TABLE 62
TRANSFORMER: TRANSFORMER OIL MARKET, BY SUB-APPLICATION, 2026–2031 (USD MILLION)


TABLE 63
TRANSFORMER: TRANSFORMER OIL MARKET, BY SUB-APPLICATION, 2021–2025 (MILLION LITERS)


TABLE 64
TRANSFORMER: TRANSFORMER OIL MARKET, BY SUB-APPLICATION, 2026–2031 (MILLION LITERS)


TABLE 65
TRANSFORMER: TRANSFORMER OIL MARKET, BY REGION, 2021–2025 (USD MILLION)


TABLE 66
TRANSFORMER: TRANSFORMER OIL MARKET, BY REGION, 2026–2031 (USD MILLION)


TABLE 67
POWER TRANSFORMER: TRANSFORMER OIL MARKET, BY REGION, 2021–2025 (USD MILLION)


TABLE 68
POWER TRANSFORMER: TRANSFORMER OIL MARKET, BY REGION, 2026–2031 (USD MILLION)


TABLE 69
DISTRIBUTION TRANSFORMER: TRANSFORMER OIL MARKET, BY REGION, 2021–2025 (USD MILLION)


TABLE 70
DISTRIBUTION TRANSFORMER: TRANSFORMER OIL MARKET, BY REGION, 2026–2031 (USD MILLION)


TABLE 71
REACTOR: TRANSFORMER OIL MARKET, BY REGION, 2021–2025 (USD MILLION)


TABLE 72
REACTOR: TRANSFORMER OIL MARKET, BY REGION, 2026–2031 (USD MILLION)


TABLE 73
SWITCHGEAR: TRANSFORMER OIL MARKET, BY REGION, 2021–2025 (USD MILLION)


TABLE 74
SWITCHGEAR: TRANSFORMER OIL MARKET, BY REGION, 2026–2031 (USD MILLION)


TABLE 75
TRANSFORMER OIL MARKET, BY REGION, 2021–2025 (USD MILLION)


TABLE 76
TRANSFORMER OIL MARKET, BY REGION, 2026–2031 (USD MILLION)


TABLE 77
TRANSFORMER OIL MARKET, BY REGION, 2021–2025 (MILLION LITERS)


TABLE 78
TRANSFORMER OIL MARKET, BY REGION, 2026–2031 (MILLION LITERS)


TABLE 79
ASIA PACIFIC: TRANSFORMER OIL MARKET, BY OIL TYPE, 2021–2025 (USD MILLION)


TABLE 80
ASIA PACIFIC: TRANSFORMER OIL MARKET, BY OIL TYPE, 2026–2031 (USD MILLION)


TABLE 81
ASIA PACIFIC: TRANSFORMER OIL MARKET, BY SUB-OIL TYPE (MINERAL OIL), 2021–2025 (USD MILLION)


TABLE 82
ASIA PACIFIC: TRANSFORMER OIL MARKET, BY SUB-OIL TYPE (MINERAL OIL), 2026–2031 (USD MILLION)


TABLE 83
ASIA PACIFIC: TRANSFORMER OIL MARKET, BY INHIBITION TYPE (MINERAL OIL), 2021–2025 (USD MILLION)


TABLE 84
ASIA PACIFIC: TRANSFORMER OIL MARKET, BY INHIBITION TYPE (MINERAL OIL), 2026–2031 (USD MILLION)


TABLE 85
ASIA PACIFIC: TRANSFORMER OIL MARKET, BY INHIBITION TYPE (NAPHTHENIC MINERAL OIL), 2021–2025 (USD MILLION)


TABLE 86
ASIA PACIFIC: TRANSFORMER OIL MARKET, BY INHIBITION TYPE (NAPHTHENIC MINERAL OIL), 2026–2031 (USD MILLION)


TABLE 87
ASIA PACIFIC: TRANSFORMER OIL MARKET, BY INHIBITION TYPE (PARAFFINIC MINERAL OIL), 2021–2025 (USD MILLION)


TABLE 88
ASIA PACIFIC: TRANSFORMER OIL MARKET, BY INHIBITION TYPE (PARAFFINIC MINERAL OIL), 2026–2031 (USD MILLION)


TABLE 89
ASIA PACIFIC: TRANSFORMER OIL MARKET, BY APPLICATION, 2021–2025 (USD MILLION)


TABLE 90
ASIA PACIFIC: TRANSFORMER OIL MARKET, BY APPLICATION, 2026–2031 (USD MILLION)


TABLE 91
ASIA PACIFIC: TRANSFORMER OIL MARKET, BY SUB-APPLICATION (TRANSFORMER), 2021–2025 (USD MILLION)


TABLE 92
ASIA PACIFIC: TRANSFORMER OIL MARKET, BY SUB-APPLICATION (TRANSFORMER), 2026–2031 (USD MILLION)


TABLE 93
ASIA PACIFIC: TRANSFORMER OIL MARKET, BY END USER, 2021–2025 (USD MILLION)


TABLE 94
ASIA PACIFIC: TRANSFORMER OIL MARKET, BY END USER, 2026–2031 (USD MILLION)


TABLE 95
ASIA PACIFIC: TRANSFORMER OIL MARKET, BY COUNTRY, 2021–2025 (USD MILLION)


TABLE 96
ASIA PACIFIC: TRANSFORMER OIL MARKET, BY COUNTRY, 2026–2031 (USD MILLION)


TABLE 97
ASIA PACIFIC: TRANSFORMER OIL MARKET, BY COUNTRY, 2021–2025 (MILLION LITERS)


TABLE 98
ASIA PACIFIC: TRANSFORMER OIL MARKET, BY COUNTRY, 2026–2031 (MILLION LITERS)


TABLE 99
CHINA: TRANSFORMER OIL MARKET, BY OIL TYPE, 2021–2025 (USD MILLION)


TABLE 100
CHINA: TRANSFORMER OIL MARKET, BY OIL TYPE, 2026–2031 (USD MILLION)


TABLE 101
CHINA: TRANSFORMER OIL MARKET, BY SUB-OIL TYPE (MINERAL OIL), 2021–2025 (USD MILLION)


TABLE 102
CHINA: TRANSFORMER OIL MARKET, BY SUB-OIL TYPE (MINERAL OIL), 2026–2031 (USD MILLION)


TABLE 103
CHINA: TRANSFORMER OIL MARKET, BY APPLICATION, 2021–2025 (USD MILLION)


TABLE 104
CHINA: TRANSFORMER OIL MARKET, BY APPLICATION, 2026–2031 (USD MILLION)


TABLE 105
CHINA: TRANSFORMER OIL MARKET, BY SUB-APPLICATION (TRANSFORMER), 2021–2025 (USD MILLION)


TABLE 106
CHINA: TRANSFORMER OIL MARKET, BY SUB-APPLICATION (TRANSFORMER), 2026–2031 (USD MILLION)


TABLE 107
CHINA: TRANSFORMER OIL MARKET, BY END USER, 2021–2025 (USD MILLION)


TABLE 108
CHINA: TRANSFORMER OIL MARKET, BY END USER, 2026–2031 (USD MILLION)


TABLE 109
INDIA: TRANSFORMER OIL MARKET, BY OIL TYPE, 2021–2025 (USD MILLION)


TABLE 110
INDIA: TRANSFORMER OIL MARKET, BY OIL TYPE, 2026–2031 (USD MILLION)


TABLE 111
INDIA: TRANSFORMER OIL MARKET, BY SUB-OIL TYPE (MINERAL OIL), 2021–2025 (USD MILLION)


TABLE 112
INDIA: TRANSFORMER OIL MARKET, BY SUB-OIL TYPE (MINERAL OIL), 2026–2031 (USD MILLION)


TABLE 113
INDIA: TRANSFORMER OIL MARKET, BY APPLICATION, 2021–2025 (USD MILLION)


TABLE 114
INDIA: TRANSFORMER OIL MARKET, BY APPLICATION, 2026–2031 (USD MILLION)


TABLE 115
INDIA: TRANSFORMER OIL MARKET, BY SUB-APPLICATION (TRANSFORMER), 2021–2025 (USD MILLION)


TABLE 116
INDIA: TRANSFORMER OIL MARKET, BY SUB-APPLICATION (TRANSFORMER), 2026–2031 (USD MILLION)


TABLE 117
INDIA: TRANSFORMER OIL MARKET, BY END USER, 2021–2025 (USD MILLION)


TABLE 118
INDIA: TRANSFORMER OIL MARKET, BY END USER, 2026–2031 (USD MILLION)


TABLE 119
JAPAN: TRANSFORMER OIL MARKET, BY OIL TYPE, 2021–2025 (USD MILLION)


TABLE 120
JAPAN: TRANSFORMER OIL MARKET, BY OIL TYPE, 2026–2031 (USD MILLION)


TABLE 121
JAPAN: TRANSFORMER OIL MARKET, BY SUB-OIL TYPE (MINERAL OIL), 2021–2025 (USD MILLION)


TABLE 122
JAPAN: TRANSFORMER OIL MARKET, BY SUB-OIL TYPE (MINERAL OIL), 2026–2031 (USD MILLION)


TABLE 123
JAPAN: TRANSFORMER OIL MARKET, BY APPLICATION, 2021–2025 (USD MILLION)


TABLE 124
JAPAN: TRANSFORMER OIL MARKET, BY APPLICATION, 2026–2031 (USD MILLION)


TABLE 125
JAPAN: TRANSFORMER OIL MARKET, BY SUB-APPLICATION (TRANSFORMER), 2021–2025 (USD MILLION)


TABLE 126
JAPAN: TRANSFORMER OIL MARKET, BY SUB-APPLICATION (TRANSFORMER), 2026–2031 (USD MILLION)


TABLE 127
JAPAN: TRANSFORMER OIL MARKET, BY END USER, 2021–2025 (USD MILLION)


TABLE 128
JAPAN: TRANSFORMER OIL MARKET, BY END USER, 2026–2031 (USD MILLION)


TABLE 129
AUSTRALIA: TRANSFORMER OIL MARKET, BY OIL TYPE, 2021–2025 (USD MILLION)


TABLE 130
AUSTRALIA: TRANSFORMER OIL MARKET, BY OIL TYPE, 2026–2031 (USD MILLION)


TABLE 131
AUSTRALIA: TRANSFORMER OIL MARKET, BY SUB-OIL TYPE (MINERAL OIL), 2021–2025 (USD MILLION)


TABLE 132
AUSTRALIA: TRANSFORMER OIL MARKET, BY SUB-OIL TYPE (MINERAL OIL), 2026–2031 (USD MILLION)


TABLE 133
AUSTRALIA: TRANSFORMER OIL MARKET, BY APPLICATION, 2021–2025 (USD MILLION)


TABLE 134
AUSTRALIA: TRANSFORMER OIL MARKET, BY APPLICATION, 2026–2031 (USD MILLION)


TABLE 135
AUSTRALIA: TRANSFORMER OIL MARKET, BY SUB-APPLICATION (TRANSFORMER), 2021–2025 (USD MILLION)


TABLE 136
AUSTRALIA: TRANSFORMER OIL MARKET, BY SUB-APPLICATION (TRANSFORMER), 2026–2031 (USD MILLION)


TABLE 137
AUSTRALIA: TRANSFORMER OIL MARKET, BY END USER, 2021–2025 (USD MILLION)


TABLE 138
AUSTRALIA: TRANSFORMER OIL MARKET, BY END USER, 2026–2031 (USD MILLION)


TABLE 139
SOUTH KOREA: TRANSFORMER OIL MARKET, BY OIL TYPE, 2021–2025 (USD MILLION)


TABLE 140
SOUTH KOREA: TRANSFORMER OIL MARKET, BY OIL TYPE, 2026–2031 (USD MILLION)


TABLE 141
SOUTH KOREA: TRANSFORMER OIL MARKET, BY SUB-OIL TYPE (MINERAL OIL), 2021–2025 (USD MILLION)


TABLE 142
SOUTH KOREA: TRANSFORMER OIL MARKET, BY SUB-OIL TYPE (MINERAL OIL), 2026–2031 (USD MILLION)


TABLE 143
SOUTH KOREA: TRANSFORMER OIL MARKET, BY APPLICATION, 2021–2025 (USD MILLION)


TABLE 144
SOUTH KOREA: TRANSFORMER OIL MARKET, BY APPLICATION, 2026–2031 (USD MILLION)


TABLE 145
SOUTH KOREA: TRANSFORMER OIL MARKET, BY SUB-APPLICATION (TRANSFORMER), 2021–2025 (USD MILLION)


TABLE 146
SOUTH KOREA: TRANSFORMER OIL MARKET, BY SUB-APPLICATION (TRANSFORMER), 2026–2031 (USD MILLION)


TABLE 147
SOUTH KOREA: TRANSFORMER OIL MARKET, BY END USER, 2021–2025 (USD MILLION)


TABLE 148
SOUTH KOREA: TRANSFORMER OIL MARKET, BY END USER, 2026–2031 (USD MILLION)


TABLE 149
REST OF ASIA PACIFIC: TRANSFORMER OIL MARKET, BY OIL TYPE, 2021–2025 (USD MILLION)


TABLE 150
REST OF ASIA PACIFIC: TRANSFORMER OIL MARKET, BY OIL TYPE, 2026–2031 (USD MILLION)


TABLE 151
REST OF ASIA PACIFIC: TRANSFORMER OIL MARKET, BY SUB-OIL TYPE (MINERAL OIL), 2021–2025 (USD MILLION)


TABLE 152
REST OF ASIA PACIFIC: TRANSFORMER OIL MARKET, BY SUB-OIL TYPE (MINERAL OIL), 2026–2031 (USD MILLION)


TABLE 153
REST OF ASIA PACIFIC: TRANSFORMER OIL MARKET, BY APPLICATION, 2021–2025 (USD MILLION)


TABLE 154
REST OF ASIA PACIFIC: TRANSFORMER OIL MARKET, BY APPLICATION, 2026–2031 (USD MILLION)


TABLE 155
REST OF ASIA PACIFIC: TRANSFORMER OIL MARKET, BY SUB-APPLICATION (TRANSFORMER), 2021–2025 (USD MILLION)


TABLE 156
REST OF ASIA PACIFIC: TRANSFORMER OIL MARKET, BY SUB-APPLICATION (TRANSFORMER), 2026–2031 (USD MILLION)


TABLE 157
REST OF ASIA PACIFIC: TRANSFORMER OIL MARKET, BY END USER, 2021–2025 (USD MILLION)


TABLE 158
REST OF ASIA PACIFIC: TRANSFORMER OIL MARKET, BY END USER, 2026–2031 (USD MILLION)


TABLE 159
NORTH AMERICA: TRANSFORMER OIL MARKET, BY OIL TYPE, 2021–2025 (USD MILLION)


TABLE 160
NORTH AMERICA: TRANSFORMER OIL MARKET, BY OIL TYPE, 2026–2031 (USD MILLION)


TABLE 161
NORTH AMERICA: TRANSFORMER OIL MARKET, BY SUB-OIL TYPE (MINERAL OIL), 2021–2025 (USD MILLION)


TABLE 162
NORTH AMERICA: TRANSFORMER OIL MARKET, BY SUB-OIL TYPE (MINERAL OIL), 2026–2031 (USD MILLION)


TABLE 163
NORTH AMERICA: TRANSFORMER OIL MARKET, BY INHIBITION TYPE (MINERAL OIL), 2021–2025 (USD MILLION)


TABLE 164
NORTH AMERICA: TRANSFORMER OIL MARKET, BY INHIBITION TYPE (MINERAL OIL), 2026–2031 (USD MILLION)


TABLE 165
NORTH AMERICA: TRANSFORMER OIL MARKET, BY INHIBITION TYPE (NAPHTHENIC MINERAL OIL), 2021–2025 (USD MILLION)


TABLE 166
NORTH AMERICA: TRANSFORMER OIL MARKET, BY INHIBITION TYPE (NAPHTHENIC MINERAL OIL), 2026–2031 (USD MILLION)


TABLE 167
NORTH AMERICA: TRANSFORMER OIL MARKET, BY INHIBITION TYPE (PARAFFINIC MINERAL OIL), 2021–2025 (USD MILLION)


TABLE 168
NORTH AMERICA: TRANSFORMER OIL MARKET, BY INHIBITION TYPE (PARAFFINIC MINERAL OIL), 2026–2031 (USD MILLION)


TABLE 169
NORTH AMERICA: TRANSFORMER OIL MARKET, BY APPLICATION, 2021–2025 (USD MILLION)


TABLE 170
NORTH AMERICA: TRANSFORMER OIL MARKET, BY APPLICATION, 2026–2031 (USD MILLION)


TABLE 171
NORTH AMERICA: TRANSFORMER OIL MARKET, BY SUB-APPLICATION (TRANSFORMER), 2021–2025 (USD MILLION)


TABLE 172
NORTH AMERICA: TRANSFORMER OIL MARKET, BY SUB-APPLICATION (TRANSFORMER), 2026–2031 (USD MILLION)


TABLE 173
NORTH AMERICA: TRANSFORMER OIL MARKET, BY END USER, 2021–2025 (USD MILLION)


TABLE 174
NORTH AMERICA: TRANSFORMER OIL MARKET, BY END USER, 2026–2031 (USD MILLION)


TABLE 175
NORTH AMERICA: TRANSFORMER OIL MARKET, BY COUNTRY, 2021–2025 (USD MILLION)


TABLE 176
NORTH AMERICA: TRANSFORMER OIL MARKET, BY COUNTRY, 2026–2031 (USD MILLION)


TABLE 177
NORTH AMERICA: TRANSFORMER OIL MARKET, BY COUNTRY, 2021–2025 (MILLION LITERS)


TABLE 178
NORTH AMERICA: TRANSFORMER OIL MARKET, BY COUNTRY, 2026–2031 (MILLION LITERS)


TABLE 179
US: TRANSFORMER OIL MARKET, BY OIL TYPE, 2021–2025 (USD MILLION)


TABLE 180
US: TRANSFORMER OIL MARKET, BY OIL TYPE, 2026–2031 (USD MILLION)


TABLE 181
US: TRANSFORMER OIL MARKET, BY SUB-OIL TYPE (MINERAL OIL), 2021–2025 (USD MILLION)


TABLE 182
US: TRANSFORMER OIL MARKET, BY SUB-OIL TYPE (MINERAL OIL), 2026–2031 (USD MILLION)


TABLE 183
US: TRANSFORMER OIL MARKET, BY APPLICATION, 2021–2025 (USD MILLION)


TABLE 184
US: TRANSFORMER OIL MARKET, BY APPLICATION, 2026–2031 (USD MILLION)


TABLE 185
US: TRANSFORMER OIL MARKET, BY SUB-APPLICATION (TRANSFORMER), 2021–2025 (USD MILLION)


TABLE 186
US: TRANSFORMER OIL MARKET, BY SUB-APPLICATION (TRANSFORMER), 2026–2031 (USD MILLION)


TABLE 187
US: TRANSFORMER OIL MARKET, BY END USER, 2021–2025 (USD MILLION)


TABLE 188
US: TRANSFORMER OIL MARKET, BY END USER, 2026–2031 (USD MILLION)


TABLE 189
CANADA: TRANSFORMER OIL MARKET, BY OIL TYPE, 2021–2025 (USD MILLION)


TABLE 190
CANADA: TRANSFORMER OIL MARKET, BY OIL TYPE, 2026–2031 (USD MILLION)


TABLE 191
CANADA: TRANSFORMER OIL MARKET, BY SUB-OIL TYPE (MINERAL OIL), 2021–2025 (USD MILLION)


TABLE 192
CANADA: TRANSFORMER OIL MARKET, BY SUB-OIL TYPE (MINERAL OIL), 2026–2031 (USD MILLION)


TABLE 193
CANADA: TRANSFORMER OIL MARKET, BY APPLICATION, 2021–2025 (USD MILLION)


TABLE 194
CANADA: TRANSFORMER OIL MARKET, BY APPLICATION, 2026–2031 (USD MILLION)


TABLE 195
CANADA: TRANSFORMER OIL MARKET, BY SUB-APPLICATION (TRANSFORMER), 2021–2025 (USD MILLION)


TABLE 196
CANADA: TRANSFORMER OIL MARKET, BY SUB-APPLICATION (TRANSFORMER), 2026–2031 (USD MILLION)


TABLE 197
CANADA: TRANSFORMER OIL MARKET, BY END USER, 2021–2025 (USD MILLION)


TABLE 198
CANADA: TRANSFORMER OIL MARKET, BY END USER, 2026–2031 (USD MILLION)


TABLE 199
MEXICO: TRANSFORMER OIL MARKET, BY OIL TYPE, 2021–2025 (USD MILLION)


TABLE 200
MEXICO: TRANSFORMER OIL MARKET, BY OIL TYPE, 2026–2031 (USD MILLION)


TABLE 201
MEXICO: TRANSFORMER OIL MARKET, BY SUB-OIL TYPE (MINERAL OIL), 2021–2025 (USD MILLION)


TABLE 202
MEXICO: TRANSFORMER OIL MARKET, BY SUB-OIL TYPE (MINERAL OIL), 2026–2031 (USD MILLION)


TABLE 203
MEXICO: TRANSFORMER OIL MARKET, BY APPLICATION, 2021–2025 (USD MILLION)


TABLE 204
MEXICO: TRANSFORMER OIL MARKET, BY APPLICATION, 2026–2031 (USD MILLION)


TABLE 205
MEXICO: TRANSFORMER OIL MARKET, BY SUB-APPLICATION (TRANSFORMER), 2021–2025 (USD MILLION)


TABLE 206
MEXICO: TRANSFORMER OIL MARKET, BY SUB-APPLICATION (TRANSFORMER), 2026–2031 (USD MILLION)


TABLE 207
MEXICO: TRANSFORMER OIL MARKET, BY END USER, 2021–2025 (USD MILLION)


TABLE 208
MEXICO: TRANSFORMER OIL MARKET, BY END USER, 2026–2031 (USD MILLION)


TABLE 209
EUROPE: TRANSFORMER OIL MARKET, BY OIL TYPE, 2021–2025 (USD MILLION)


TABLE 210
EUROPE: TRANSFORMER OIL MARKET, BY OIL TYPE, 2026–2031 (USD MILLION)


TABLE 211
MINERAL OIL: EUROPEAN TRANSFORMER OIL MARKET, BY SUB-OIL TYPE, 2021–2025 (USD MILLION)


TABLE 212
MINERAL OIL: EUROPEAN TRANSFORMER OIL MARKET, BY SUB-OIL TYPE, 2026–2031 (USD MILLION)


TABLE 213
MINERAL OIL: EUROPEAN TRANSFORMER OIL MARKET, BY INHIBITION TYPE, 2021–2025 (USD MILLION)


TABLE 214
MINERAL OIL: EUROPEAN TRANSFORMER OIL MARKET, BY INHIBITION TYPE, 2026–2031 (USD MILLION)


TABLE 215
NAPHTHENIC MINERAL OIL: EUROPEAN TRANSFORMER OIL MARKET, BY INHIBITION TYPE, 2021–2025 (USD MILLION)


TABLE 216
NAPHTHENIC MINERAL OIL: EUROPEAN TRANSFORMER OIL MARKET, BY INHIBITION TYPE, 2026–2031 (USD MILLION)


TABLE 217
PARAFFINIC MINERAL OIL: EUROPEAN TRANSFORMER OIL MARKET, BY INHIBITION TYPE, 2021–2025 (USD MILLION)


TABLE 218
PARAFFINIC MINERAL OIL: EUROPEAN TRANSFORMER OIL MARKET, BY INHIBITION TYPE, 2026–2031 (USD MILLION)


TABLE 219
EUROPE: TRANSFORMER OIL MARKET, BY APPLICATION, 2021–2025 (USD MILLION)


TABLE 220
EUROPE: TRANSFORMER OIL MARKET, BY APPLICATION, 2026–2031 (USD MILLION)


TABLE 221
TRANSFORMER: EUROPEAN TRANSFORMER OIL MARKET, BY APPLICATION, 2021–2025 (USD MILLION)


TABLE 222
TRANSFORMER: EUROPEAN TRANSFORMER OIL MARKET, BY APPLICATION, 2026–2031 (USD MILLION)


TABLE 223
EUROPE: TRANSFORMER OIL MARKET, BY END USER, 2021–2025 (USD MILLION)


TABLE 224
EUROPE: TRANSFORMER OIL MARKET, BY END USER, 2026–2031 (USD MILLION)


TABLE 225
EUROPE: TRANSFORMER OIL MARKET, BY COUNTRY, 2021–2025 (USD MILLION)


TABLE 226
EUROPE: TRANSFORMER OIL MARKET, BY COUNTRY, 2026–2031 (USD MILLION)


TABLE 227
EUROPE: TRANSFORMER OIL MARKET, BY COUNTRY, 2021–2025 (MILLION LITERS)


TABLE 228
EUROPE: TRANSFORMER OIL MARKET, BY COUNTRY, 2026–2031 (MILLION LITERS)


TABLE 229
UK: TRANSFORMER OIL MARKET, BY OIL TYPE, 2021–2025 (USD MILLION)


TABLE 230
UK: TRANSFORMER OIL MARKET, BY OIL TYPE, 2026–2031 (USD MILLION)


TABLE 231
MINERAL OIL: TRANSFORMER OIL MARKET IN UK, BY SUB-OIL TYPE, 2021–2025 (USD MILLION)


TABLE 232
MINERAL OIL: TRANSFORMER OIL MARKET IN UK, BY SUB-OIL TYPE, 2026–2031 (USD MILLION)


TABLE 233
UK: TRANSFORMER OIL MARKET, BY APPLICATION, 2021–2025 (USD MILLION)


TABLE 234
UK: TRANSFORMER OIL MARKET, BY APPLICATION, 2026–2031 (USD MILLION)


TABLE 235
TRANSFORMER: TRANSFORMER OIL MARKET IN UK, BY APPLICATION, 2021–2025 (USD MILLION)


TABLE 236
TRANSFORMER: TRANSFORMER OIL MARKET IN UK, BY APPLICATION, 2026–2031 (USD MILLION)


TABLE 237
UK: TRANSFORMER OIL MARKET, BY END USER, 2021–2025 (USD MILLION)


TABLE 238
UK: TRANSFORMER OIL MARKET, BY END USER, 2026–2031 (USD MILLION)


TABLE 239
GERMANY: TRANSFORMER OIL MARKET, BY OIL TYPE, 2021–2025 (USD MILLION)


TABLE 240
GERMANY: TRANSFORMER OIL MARKET, BY OIL TYPE, 2026–2031 (USD MILLION)


TABLE 241
MINERAL OIL: TRANSFORMER OIL MARKET IN GERMANY, BY SUB-OIL TYPE, 2021–2025 (USD MILLION)


TABLE 242
MINERAL OIL: TRANSFORMER OIL MARKET IN GERMANY, BY SUB-OIL TYPE, 2026–2031 (USD MILLION)


TABLE 243
GERMANY: TRANSFORMER OIL MARKET, BY APPLICATION, 2021–2025 (USD MILLION)


TABLE 244
GERMANY: TRANSFORMER OIL MARKET, BY APPLICATION, 2026–2031 (USD MILLION)


TABLE 245
TRANSFORMER: TRANSFORMER OIL MARKET IN GERMANY, BY APPLICATION, 2021–2025 (USD MILLION)


TABLE 246
TRANSFORMER: TRANSFORMER OIL MARKET IN GERMANY, BY APPLICATION, 2026–2031 (USD MILLION)


TABLE 247
GERMANY: TRANSFORMER OIL MARKET, BY END USER, 2021–2025 (USD MILLION)


TABLE 248
GERMANY: TRANSFORMER OIL MARKET, BY END USER, 2026–2031 (USD MILLION)


TABLE 249
RUSSIA: TRANSFORMER OIL MARKET, BY OIL TYPE, 2021–2025 (USD MILLION)


TABLE 250
RUSSIA: TRANSFORMER OIL MARKET, BY OIL TYPE, 2026–2031 (USD MILLION)


TABLE 251
MINERAL OIL: TRANSFORMER OIL MARKET IN RUSSIA, BY SUB-OIL TYPE, 2021–2025 (USD MILLION)


TABLE 252
MINERAL OIL: TRANSFORMER OIL MARKET IN RUSSIA, BY SUB-OIL TYPE, 2026–2031 (USD MILLION)


TABLE 253
RUSSIA: TRANSFORMER OIL MARKET, BY APPLICATION, 2021–2025 (USD MILLION)


TABLE 254
RUSSIA: TRANSFORMER OIL MARKET, BY APPLICATION, 2026–2031 (USD MILLION)


TABLE 255
TRANSFORMER: TRANSFORMER OIL MARKET IN RUSSIA, BY APPLICATION, 2021–2025 (USD MILLION)


TABLE 256
TRANSFORMER: TRANSFORMER OIL MARKET IN RUSSIA, BY APPLICATION, 2026–2031 (USD MILLION)


TABLE 257
RUSSIA: TRANSFORMER OIL MARKET, BY END USER, 2021–2025 (USD MILLION)


TABLE 258
RUSSIA: TRANSFORMER OIL MARKET, BY END USER, 2026–2031 (USD MILLION)


TABLE 259
FRANCE: TRANSFORMER OIL MARKET, BY OIL TYPE, 2021–2025 (USD MILLION)


TABLE 260
FRANCE: TRANSFORMER OIL MARKET, BY OIL TYPE, 2026–2031 (USD MILLION)


TABLE 261
MINERAL OIL: TRANSFORMER OIL MARKET IN FRANCE, BY SUB-OIL TYPE, 2021–2025 (USD MILLION)


TABLE 262
MINERAL OIL: TRANSFORMER OIL MARKET IN FRANCE, BY SUB-OIL TYPE, 2026–2031 (USD MILLION)


TABLE 263
FRANCE: TRANSFORMER OIL MARKET, BY APPLICATION, 2021–2025 (USD MILLION)


TABLE 264
FRANCE: TRANSFORMER OIL MARKET, BY APPLICATION, 2026–2031 (USD MILLION)


TABLE 265
TRANSFORMER: TRANSFORMER OIL MARKET IN FRANCE, BY APPLICATION, 2021–2025 (USD MILLION)


TABLE 266
TRANSFORMER: TRANSFORMER OIL MARKET IN FRANCE, BY APPLICATION, 2026–2031 (USD MILLION)


TABLE 267
FRANCE: TRANSFORMER OIL MARKET, BY END USER, 2021–2025 (USD MILLION)


TABLE 268
FRANCE: TRANSFORMER OIL MARKET, BY END USER, 2026–2031 (USD MILLION)


TABLE 269
REST OF EUROPE: TRANSFORMER OIL MARKET, BY OIL TYPE, 2021–2025 (USD MILLION)


TABLE 270
REST OF EUROPE: TRANSFORMER OIL MARKET, BY OIL TYPE, 2026–2031 (USD MILLION)


TABLE 271
MINERAL OIL: TRANSFORMER OIL MARKET IN REST OF EUROPE, BY SUB-OIL TYPE, 2021–2025 (USD MILLION)


TABLE 272
MINERAL OIL: TRANSFORMER OIL MARKET IN REST OF EUROPE, BY SUB-OIL TYPE, 2026–2031 (USD MILLION)


TABLE 273
REST OF EUROPE: TRANSFORMER OIL MARKET, BY APPLICATION, 2021–2025 (USD MILLION)


TABLE 274
REST OF EUROPE: TRANSFORMER OIL MARKET, BY APPLICATION, 2026–2031 (USD MILLION)


TABLE 275
TRANSFORMER: TRANSFORMER OIL MARKET IN REST OF EUROPE, BY APPLICATION, 2021–2025 (USD MILLION)


TABLE 276
TRANSFORMER: TRANSFORMER OIL MARKET IN REST OF EUROPE, BY APPLICATION, 2026–2031 (USD MILLION)


TABLE 277
REST OF EUROPE: TRANSFORMER OIL MARKET, BY END USER, 2021–2025 (USD MILLION)


TABLE 278
REST OF EUROPE: TRANSFORMER OIL MARKET, BY END USER, 2026–2031 (USD MILLION)


TABLE 279
ROW: TRANSFORMER OIL MARKET, BY OIL TYPE, 2021–2025 (USD MILLION)


TABLE 280
ROW: TRANSFORMER OIL MARKET, BY OIL TYPE, 2026–2031 (USD MILLION)


TABLE 281
ROW: TRANSFORMER OIL MARKET, BY SUB-OIL TYPE (MINERAL OIL), 2021–2025 (USD MILLION)


TABLE 282
ROW: TRANSFORMER OIL MARKET, BY SUB-OIL TYPE (MINERAL OIL), 2026–2031 (USD MILLION)


TABLE 283
ROW: TRANSFORMER OIL MARKET, BY INHIBITION TYPE (MINERAL OIL), 2021–2025 (USD MILLION)


TABLE 284
ROW: TRANSFORMER OIL MARKET, BY INHIBITION TYPE (MINERAL OIL), 2026–2031 (USD MILLION)


TABLE 285
ROW: TRANSFORMER OIL MARKET, BY INHIBITION TYPE (NAPHTHENIC MINERAL OIL), 2021–2025 (USD MILLION)


TABLE 286
ROW: TRANSFORMER OIL MARKET, BY INHIBITION TYPE (NAPHTHENIC MINERAL OIL), 2026–2031 (USD MILLION)


TABLE 287
ROW: TRANSFORMER OIL MARKET, BY INHIBITION TYPE (PARAFFINIC MINERAL OIL), 2021–2025 (USD MILLION)


TABLE 288
ROW: TRANSFORMER OIL MARKET, BY INHIBITION TYPE (PARAFFINIC MINERAL OIL), 2026–2031 (USD MILLION)


TABLE 289
ROW: TRANSFORMER OIL MARKET, BY APPLICATION, 2021–2025 (USD MILLION)


TABLE 290
ROW: TRANSFORMER OIL MARKET, BY APPLICATION, 2026–2031 (USD MILLION)


TABLE 291
ROW: TRANSFORMER OIL MARKET, BY SUB-APPLICATION (TRANSFORMER), 2021–2025 (USD MILLION)


TABLE 292
ROW: TRANSFORMER OIL MARKET, BY SUB-APPLICATION (TRANSFORMER), 2026–2031 (USD MILLION)


TABLE 293
ROW: TRANSFORMER OIL MARKET, BY END USER, 2021–2025 (USD MILLION)


TABLE 294
ROW: TRANSFORMER OIL MARKET, BY END USER, 2026–2031 (USD MILLION)


TABLE 295
ROW: TRANSFORMER OIL MARKET, BY REGION, 2021–2025 (USD MILLION)


TABLE 296
ROW: TRANSFORMER OIL MARKET, BY REGION, 2026–2031 (USD MILLION)


TABLE 297
ROW: TRANSFORMER OIL MARKET, BY REGION, 2021–2025 (MILLION LITERS)


TABLE 298
ROW: TRANSFORMER OIL MARKET, BY REGION, 2026–2031 (MILLION LITERS)


TABLE 299
MIDDLE EAST: TRANSFORMER OIL MARKET, BY OIL TYPE, 2021–2025 (USD MILLION)


TABLE 300
MIDDLE EAST: TRANSFORMER OIL MARKET, BY OIL TYPE, 2026–2031 (USD MILLION)


TABLE 301
MIDDLE EAST: TRANSFORMER OIL MARKET, BY SUB-OIL TYPE (MINERAL OIL), 2021–2025 (USD MILLION)


TABLE 302
MIDDLE EAST: TRANSFORMER OIL MARKET, BY SUB-OIL TYPE (MINERAL OIL), 2026–2031 (USD MILLION)


TABLE 303
MIDDLE EAST: TRANSFORMER OIL MARKET, BY APPLICATION, 2021–2025 (USD MILLION)


TABLE 304
MIDDLE EAST: TRANSFORMER OIL MARKET, BY APPLICATION, 2026–2031 (USD MILLION)


TABLE 305
MIDDLE EAST: TRANSFORMER OIL MARKET, BY SUB-APPLICATION (TRANSFORMER), 2021–2025 (USD MILLION)


TABLE 306
MIDDLE EAST: TRANSFORMER OIL MARKET, BY SUB-APPLICATION (TRANSFORMER), 2026–2031 (USD MILLION)


TABLE 307
MIDDLE EAST: TRANSFORMER OIL MARKET, BY END USER, 2021–2025 (USD MILLION)


TABLE 308
MIDDLE EAST: TRANSFORMER OIL MARKET, BY END USER, 2026–2031 (USD MILLION)


TABLE 309
AFRICA: TRANSFORMER OIL MARKET, BY OIL TYPE, 2021–2025 (USD MILLION)


TABLE 310
AFRICA: TRANSFORMER OIL MARKET, BY OIL TYPE, 2026–2031 (USD MILLION)


TABLE 311
AFRICA: TRANSFORMER OIL MARKET, BY SUB-OIL TYPE (MINERAL OIL), 2021–2025 (USD MILLION)


TABLE 312
AFRICA: TRANSFORMER OIL MARKET, BY SUB-OIL TYPE (MINERAL OIL), 2026–2031 (USD MILLION)


TABLE 313
AFRICA: TRANSFORMER OIL MARKET, BY APPLICATION, 2021–2025 (USD MILLION)


TABLE 314
AFRICA: TRANSFORMER OIL MARKET, BY APPLICATION, 2026–2031 (USD MILLION)


TABLE 315
AFRICA: TRANSFORMER OIL MARKET, BY SUB-APPLICATION (TRANSFORMER), 2021–2025 (USD MILLION)


TABLE 316
AFRICA: TRANSFORMER OIL MARKET, BY SUB-APPLICATION (TRANSFORMER), 2026–2031 (USD MILLION)


TABLE 317
AFRICA: TRANSFORMER OIL MARKET, BY END USER, 2021–2025 (USD MILLION)


TABLE 318
AFRICA: TRANSFORMER OIL MARKET, BY END USER, 2026–2031 (USD MILLION)


TABLE 319
SOUTH AMERICA: TRANSFORMER OIL MARKET, BY OIL TYPE, 2021–2025 (USD MILLION)


TABLE 320
SOUTH AMERICA: TRANSFORMER OIL MARKET, BY OIL TYPE, 2026–2031 (USD MILLION)


TABLE 321
SOUTH AMERICA: TRANSFORMER OIL MARKET, BY SUB-OIL TYPE (MINERAL OIL), 2021–2025 (USD MILLION)


TABLE 322
SOUTH AMERICA: TRANSFORMER OIL MARKET, BY SUB-OIL TYPE (MINERAL OIL), 2026–2031 (USD MILLION)


TABLE 323
SOUTH AMERICA: TRANSFORMER OIL MARKET, BY APPLICATION, 2021–2025(USD MILLION)


TABLE 324
SOUTH AMERICA: TRANSFORMER OIL MARKET, BY APPLICATION, 2026–2031 (USD MILLION)


TABLE 325
SOUTH AMERICA: TRANSFORMER OIL MARKET, BY SUB-APPLICATION (TRANSFORMER), 2021–2025 (USD MILLION)


TABLE 326
SOUTH AMERICA: TRANSFORMER OIL MARKET, BY SUB-APPLICATION (TRANSFORMER), 2026–2031 (USD MILLION)


TABLE 327
SOUTH AMERICA: TRANSFORMER OIL MARKET, BY END USER, 2021–2025 (USD MILLION)


TABLE 328
SOUTH AMERICA: TRANSFORMER OIL MARKET, BY END USER, 2026–2031 (USD MILLION)


TABLE 329
TRANSFORMER OIL MARKET: OVERVIEW OF STRATEGIES ADOPTED BY KEY PLAYERS, JANUARY 2023–AUGUST 2026


TABLE 330
TRANSFORMER OIL MARKET: DEGREE OF COMPETITION, 2025


TABLE 331
TRANSFORMER OIL MARKET: OIL TYPE FOOTPRINT


TABLE 332
TRANSFORMER OIL MARKET: REGION FOOTPRINT


TABLE 333
TRANSFORMER OIL MARKET: PRODUCT LAUNCHES, JANUARY 2023–AUGUST 2026


TABLE 334
TRANSFORMER OIL MARKET: DEALS, JANUARY 2023–AUGUST 2026


TABLE 335
TRANSFORMER OIL MARKET: EXPANSIONS, JANUARY 2023–AUGUST 2026


TABLE 336
NYNAS AB: COMPANY OVERVIEW


TABLE 337
NYNAS AB: PRODUCT LAUNCHES


TABLE 338
NYNAS AB: DEALS


TABLE 339
NYNAS AB: OTHER DEVELOPMENTS


TABLE 340
ERGON, INC.: COMPANY OVERVIEW


TABLE 341
ERGON, INC.: PRODUCT LAUNCHES


TABLE 342
ERGON, INC.: DEALS


TABLE 343
ERGON, INC.: OTHER DEVELOPMENTS


TABLE 344
PETROCHINA COMPANY LIMITED: COMPANY OVERVIEW


TABLE 345
PETROCHINA COMPANY LIMITED: DEVELOPMENTS


TABLE 346
APAR INDUSTRIES LIMITED: COMPANY OVERVIEW


TABLE 347
APAR INDUSTRIES LIMITED: PRODUCT LAUNCHES


TABLE 348
APAR INDUSTRIES LIMITED: EXPANSIONS


TABLE 349
APAR INDUSTRIES LIMITED: OTHER DEVELOPMENTS


TABLE 350
SHELL: COMPANY OVERVIEW


TABLE 351
SHELL: PRODUCT LAUNCHES


TABLE 352
SHELL: DEALS


TABLE 353
SHELL: OTHER DEVELOPMENTS


TABLE 354
CALUMET SPECIALTY PRODUCTS PARTNERS, L.P.: COMPANY OVERVIEW


TABLE 355
CALUMET SPECIALTY PRODUCTS PARTNERS, L.P.: PRODUCT LAUNCHES


TABLE 356
SINOPEC LUBRICANT COMPANY: COMPANY OVERVIEW


TABLE 357
CARGILL, INCORPORATED: COMPANY OVERVIEW


TABLE 358
EXXON MOBIL CORPORATION: COMPANY OVERVIEW


TABLE 359
EXXON MOBIL CORPORATION: PRODUCT LAUNCHES


TABLE 360
EXXON MOBIL CORPORATION: EXPANSIONS


TABLE 361
GULF OIL INTERNATIONAL LTD: COMPANY OVERVIEW


TABLE 362
GULF OIL INTERNATIONAL LTD: EXPANSIONS


TABLE 363
PHILLIPS 66 COMPANY: COMPANY OVERVIEW


TABLE 364
DOW: COMPANY OVERVIEW


TABLE 365
REPSOL: COMPANY OVERVIEW


TABLE 366
REPSOL: PRODUCT LAUNCHES


TABLE 367
REPSOL: DEALS


TABLE 368
REPSOL: EXPANSIONS


TABLE 369
REPSOL: OTHER DEVELOPMENTS


TABLE 370
CHEVRON CORPORATION: COMPANY OVERVIEW


TABLE 371
CHEVRON CORPORATION: DEALS


TABLE 372
CHEVRON CORPORATION: EXPANSIONS


TABLE 373
CHEVRON CORPORATION: OTHER DEVELOPMENTS


TABLE 374
SAVITA: COMPANY OVERVIEW


LIST OF FIGURES


FIGURE 1
TRANSFORMER OIL MARKET SEGMENTATION AND REGIONAL SCOPE


FIGURE 2
TRANSFORMER OIL MARKET SCENARIO


FIGURE 3
GLOBAL TRANSFORMER OIL MARKET SIZE, 2022–2031


FIGURE 4
MAJOR STRATEGIES ADOPTED BY KEY PLAYERS IN TRANSFORMER OIL MARKET, 2023–2026


FIGURE 5
DISRUPTIONS INFLUENCING GROWTH OF TRANSFORMER OIL MARKET


FIGURE 6
HIGH-GROWTH SEGMENTS IN TRANSFORMER OIL MARKET, 2026–2031


FIGURE 7
ASIA PACIFIC TO REGISTER HIGHEST CAGR DURING FORECAST PERIOD


FIGURE 8
RAPID EXPANSION AND MODERNIZATION OF TRANSMISSION AND DISTRIBUTION NETWORKS TO DRIVE MARKET


FIGURE 9
MINERAL OIL SEGMENT AND ASIA PACIFIC ACCOUNTED FOR LARGEST MARKET SHARE IN 2025


FIGURE 10
MINERAL OIL SEGMENT TO DOMINATE TRANSFORMER OIL MARKET FROM 2026 TO 2031


FIGURE 11
TRANSFORMER SEGMENT TO CAPTURE LARGEST MARKET SHARE IN 2026 AND 2031


FIGURE 12
RAILWAYS & METROS SEGMENT TO EXHIBIT HIGHEST CAGR BETWEEN 2026 AND 2031


FIGURE 13
ASIA PACIFIC TO EXHIBIT HIGHEST CAGR IN GLOBAL TRANSFORMER OIL MARKET DURING FORECAST PERIOD


FIGURE 14
DRIVERS, RESTRAINTS, OPPORTUNITIES, AND CHALLENGES


FIGURE 15
GLOBAL T&D INVESTMENT PROJECTION, 2020–2040


FIGURE 16
WEST TEXAS INTERMEDIATE (WTI) CRUDE OIL PRICES, JANUARY 2018–MARCH 2025


FIGURE 17
TRANSFORMER OIL MARKET MAP


FIGURE 18
PORTER’S FIVE FORCES ANALYSIS


FIGURE 19
TRANSFORMER OIL VALUE CHAIN ANALYSIS


FIGURE 20
TRENDS/DISRUPTIONS INFLUENCING CUSTOMER BUSINESS


FIGURE 21
MINERAL OIL SEGMENT HELD MAJORITY OF TRANSFORMER OIL MARKET SHARE IN 2025


FIGURE 22
TRANSMISSION & DISTRIBUTION UTILITIES SEGMENT HELD LARGEST MARKET SHARE IN 2025


FIGURE 23
TRANSFORMER SEGMENT CAPTURED MAJORITY OF MARKET SHARE IN 2025


FIGURE 24
ASIA PACIFIC TO GROW AT HIGHEST CAGR DURING FORECAST PERIOD


FIGURE 25
ASIA PACIFIC HELD LARGEST SHARE OF TRANSFORMER OIL MARKET IN 2025


FIGURE 26
ASIA PACIFIC: TRANSFORMER OIL MARKET SNAPSHOT


FIGURE 27
EUROPE: TRANSFORMER OIL MARKET SNAPSHOT


FIGURE 28
TRANSFORMER OIL MARKET: REVENUE ANALYSIS OF TOP FOUR PLAYERS, 2021–2025


FIGURE 29
MARKET SHARE ANALYSIS OF COMPANIES OFFERING TRANSFORMER OILS, 2025


FIGURE 30
BRAND COMPARATIVE ANALYSIS


FIGURE 31
TRANSFORMER OIL MARKET: COMPANY EVALUATION MATRIX (KEY PLAYERS), 2025


FIGURE 32
NYNAS AB: COMPANY SNAPSHOT


FIGURE 33
PETROCHINA COMPANY LIMITED: COMPANY SNAPSHOT


FIGURE 34
APAR INDUSTRIES LIMITED: COMPANY SNAPSHOT


FIGURE 35
SHELL: COMPANY SNAPSHOT


FIGURE 36
EXXON MOBIL CORPORATION: COMPANY SNAPSHOT


FIGURE 37
PHILLIPS 66 COMPANY: COMPANY SNAPSHOT


FIGURE 38
DOW: COMPANY SNAPSHOT


FIGURE 39
REPSOL: COMPANY SNAPSHOT


FIGURE 40
CHEVRON CORPORATION: COMPANY SNAPSHOT


FIGURE 41
SAVITA: COMPANY SNAPSHOT


FIGURE 42
TRANSFORMER OIL MARKET: RESEARCH DESIGN


FIGURE 43
DATA TRIANGULATION METHODOLOGY


FIGURE 44
BREAKDOWN OF PRIMARY INTERVIEWS: BY COMPANY TYPE, DESIGNATION, & REGION


FIGURE 45
MARKET SIZE ESTIMATION METHODOLOGY: BOTTOM-UP APPROACH


FIGURE 46
MARKET SIZE ESTIMATION METHODOLOGY: TOP-DOWN APPROACH


FIGURE 47
MAIN METRICS CONSIDERED WHILE CONSTRUCTING AND ASSESSING DEMAND FOR TRANSFORMER OIL


FIGURE 48
KEY STEPS CONSIDERED FOR ASSESSING SUPPLY OF TRANSFORMER OIL


FIGURE 49
TRANSFORMER OIL MARKET: SUPPLY-SIDE ANALYSIS, 2025


FIGURE 50
INDUSTRY CONCENTRATION, 2025


FIGURE 51
TRANSFORMER OIL MARKET: INSIGHTS FROM INDUSTRY EXPERTS


Methodology

The research process for this technical, market-oriented, and commercial study of the transformer oil market involved systematically collecting, validating, and analyzing information on transformer oil technologies, oil types, applications, end users, transformer installations, grid infrastructure, and industry developments. We conducted extensive secondary research using annual reports, investor presentations, technical papers, regulatory publications, industry databases, company websites, and financial reports to identify key market participants, technology trends, market developments, and competitive strategies. The team further validated the findings through primary interviews with executives from transformer oil manufacturers, transformer OEMs, utilities, distributors, electrical equipment manufacturers, and industry experts to assess market estimates, product adoption, pricing trends, customer requirements, and competitive positioning. The team established key market players and their market positions through a combination of secondary and primary research involving senior executives, business development managers, product specialists, and technical experts across the transformer oil ecosystem.

Secondary Research

In the secondary research process, we referred to various sources to identify and collect information relevant to the study. Secondary sources included annual reports, investor presentations, press releases, company websites, technical papers, industry journals, regulatory publications, and recognized market databases. Publications and datasets from organizations such as the International Energy Agency (IEA), International Electrotechnical Commission (IEC), IEEE, CIGRE, and national energy and electricity regulatory authorities were reviewed to understand developments in power transmission and distribution, transformer installations, grid modernization, renewable energy integration, and transformer oil standards and regulations. Secondary research primarily focused on the transformer oil value chain, key market participants, product developments, oil-type trends, application trends, end-user demand, production capacities, distribution networks, and regional market dynamics. The study also assessed mineral, silicone, and bio-based transformer oils, along with developments in natural and synthetic ester fluids, to understand evolving product preferences and technology adoption.

Primary Research

During the primary research phase, we interviewed transformer oil manufacturers, transformer OEMs, utilities, electrical equipment manufacturers, distributors, and industry experts to gather qualitative and quantitative insights into the transformer oil market. Interviews validated market estimates, product adoption, pricing trends, regional demand, competitive positioning, customer requirements, and technology developments. Primary interviews also helped assess transformer installation and replacement trends, demand for mineral versus bio-based and silicone oils, adoption of ester-based fluids, transformer maintenance requirements, utility procurement practices, and emerging opportunities across transmission & distribution, power generation, and railways & metros. The findings were validated against company disclosures, industry statistics, regulatory publications, and technical sources to refine market estimates, segment shares, regional forecasts, and competitive assessments.
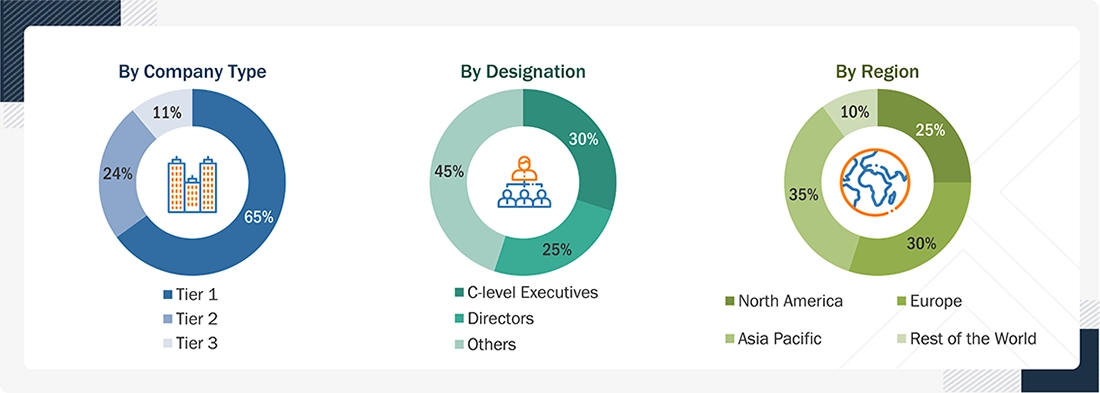
Transformer Oil Market 
 Size, and Share

Note 1: Others include sales managers, engineers, and regional managers.
Note 2: Tier 1 Company Revenue: >USD 5 billion, Tier 2 Company Revenue: Between USD 1 and USD 5 billion, and Tier 3 Company Revenue: <USD 1 billion.

To know about the assumptions considered for the study, download the pdf brochure

Market Size Estimation

We used both top-down and bottom-up approaches to estimate and validate the size of the transformer oil market and its dependent submarkets. The key players in the market were identified through secondary research, and their market shares in the respective regions were obtained through both primary and secondary research. The research methodology includes reviewing the annual and financial reports of the top market players and interviewing industry experts, such as chief executive officers, vice presidents, directors, sales managers, and marketing executives, to gather key quantitative and qualitative insights on the transformer oil market.

Bottom-up Approach

  • Market size is estimated based on the total demand for oil-filled transformers, switchgears, and reactors across individual countries.
  • The number of relevant transformers, switchgears, and reactors/substations is identified for each country using secondary research and industry data.
  • The number of units is multiplied by the average transformer oil capacity per unit/application to estimate total oil demand in liters.
  • Estimated oil consumption is then multiplied by the average cost of transformer oil in the respective country/region to derive the market value.
  • The country-level estimates are aggregated to determine regional and global transformer oil market size.
  • Key assumptions, including average oil capacity and oil pricing, are validated through primary interviews with transformer manufacturers, oil suppliers, utilities, and industry experts.
  • The resulting market size is further cross-checked and validated through secondary research and data triangulation.

Top-down Approach

  • Estimating the overall global transformer oil market by analyzing transformer installations, electricity transmission and distribution investments, power generation capacity additions, grid expansion, and transformer replacement demand.
  • Allocating the market across oil type, application, and end user based on adoption patterns, transformer oil consumption, product preferences, industry trends, and company-level data.
  • Distributing market estimates across North America, Europe, Asia Pacific, and the Rest of the World based on transformer deployment, power infrastructure investments, electricity demand, renewable energy capacity additions, and regional market dynamics.
  • Further splitting regional markets into country-level markets based on transformer installations, grid infrastructure development, power generation capacity, railway electrification, and market penetration of different transformer oil types.
  • Validating the final market estimates through primary interviews with transformer oil manufacturers, transformer OEMs, utilities, distributors, and industry experts to validate regional demand trends, product adoption, pricing, and end-user requirements, followed by data triangulation to ensure consistency and accuracy.

Global Transformer Oil Market Size: Bottom-up Approach and Top-down Approach
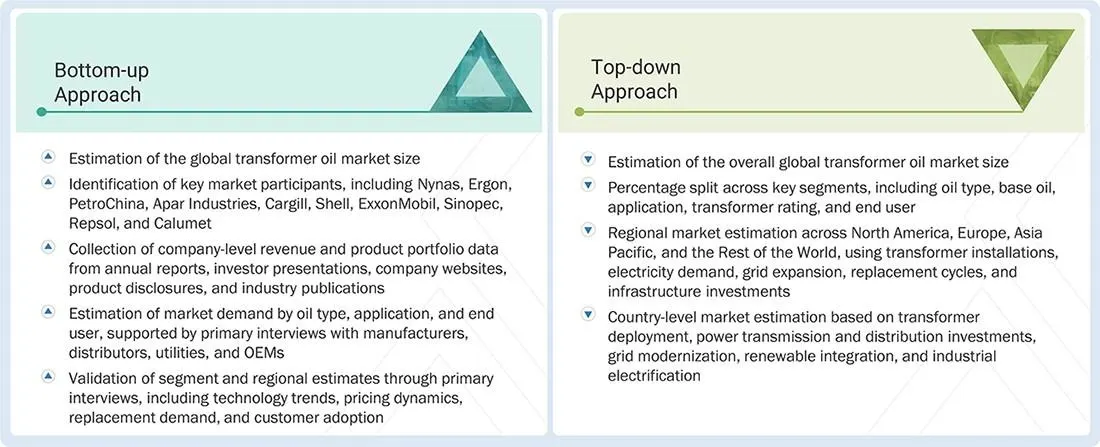
Transformer Oil Market Top Down and Bottom Up Approach

Data Triangulation

The process of determining the overall market size involved the methodologies described earlier, followed by segmenting the market into multiple segments and subsegments. To finalize the comprehensive market analysis and obtain precise statistics for each market segment and subsegment, we applied data triangulation and market breakdown procedures where appropriate. Data triangulation was accomplished by examining factors and trends from both the demand and supply sides of the transformer oil ecosystem, including transformer installations, transformer oil sales and consumption, power transmission and distribution investments, power generation capacity additions, transformer replacement and maintenance demand, product adoption, pricing trends, and regional market dynamics.

Market Definition

Transformer oil is a specialized insulating fluid used in oil-filled electrical equipment, primarily to provide electrical insulation and heat dissipation. It circulates within transformers to transfer heat generated by the core and windings while maintaining dielectric strength between energized components. Transformer oils are primarily classified as mineral oils, silicone oils, and bio-based oils, with mineral oils further categorized as naphthenic and paraffinic.

The transformer oil market encompasses total global revenue from transformer oil sales across various oil types, including mineral (naphthenic and paraffinic), silicone, and bio-based oils. The market covers applications such as transformers, switchgears, and reactors, serving end users, including transmission & distribution, power generation, and railways & metros. The study covers transformer oils used in power, distribution, and traction transformers, as well as other oil-filled electrical equipment, across North America, Europe, Asia Pacific, and the Rest of the World.

Key Stakeholders

  • Transformer oil manufacturers
  • Technicians and repair personnel
  • T&D utilities
  • Companies in the railways & metro industry
  • Industrial sector end users
  • Commercial sector end users
  • Power generation plants
  • Power and energy associations
  • Government and research organizations
  • State and national regulatory authorities
  • Switchgear component manufacturers

Report Objectives

  • To define and describe the transformer oil market, based on oil type, application, end user, and region, in terms of value
  • To describe and forecast the market for five key regions: North America, Europe, Asia Pacific, South America, and the Middle East & Africa, along with their country-level market sizes, in terms of value and volume
  • To provide detailed information regarding key drivers, restraints, opportunities, and challenges influencing the growth of the transformer oil market
  • To provide the supply chain analysis, trends/disruptions impacting customer business, ecosystem analysis, regulatory landscape, patent analysis, case study analysis, technology analysis, key conferences & events, the impact of AI/Gen AI, macroeconomic outlook, pricing analysis, Porter’s Five Forces analysis, regulatory analysis, and the impact of the 2025 US tariffs on the market
  • To analyze opportunities for stakeholders in the transformer oil market and draw a competitive landscape of the market
  • To benchmark market players using the company evaluation matrix, which analyzes market players on broad categories of business and product strategies adopted by them
  • To compare key market players for market shares, product specifications, and applications
  • To strategically profile key players and comprehensively analyze their market ranking and core competencies.
  • To analyze competitive developments, such as contracts, agreements, partnerships, and expansions in the transformer oil market

Available customizations:

With the given market data, MarketsandMarkets offers customizations based on the company’s specific needs. The following customization options are available for the report:

PRODUCT ANALYSIS

  • Product Matrix, which provides a detailed comparison of the product portfolio of each company

COMPANY INFORMATION

  • Detailed analyses and profiling of additional market players (up to 5)
 

Personalize This Research

  • Triangulate with your Own Data
  • Get Data as per your Format and Definition
  • Gain a Deeper Dive on a Specific Application, Geography, Customer or Competitor
  • Any level of Personalization
Request A Free Customisation

Let Us Help You

  • What are the Known and Unknown Adjacencies Impacting the Transformer Oil Market
  • What will your New Revenue Sources be?
  • Who will be your Top Customer; what will make them switch?
  • Defend your Market Share or Win Competitors
  • Get a Scorecard for Target Partners
Customized Workshop Request

Custom Market Research Services

We Will Customise The Research For You, In Case The Report Listed Above Does Not Meet With Your Requirements

Get 10% Free Customisation

TESTIMONIALS

Growth opportunities and latent adjacency in Transformer Oil Market

DMCA.com Protection Status
popup img