


Biopesticides Market
Report Code
AGI 2716
Published in
Oct, 2026, By MarketsandMarkets™
Biopesticides Market by Type (Bioinsecticides, Biofungicides, Bionematicides), Crop Type (Cereals & Grains, Oilseeds & Pulses), Formulation (Liquid, Dry), Source (Microbials, Biochemicals), Mode of Application, and Region - Global Forecast To 2031

USD 20.32 Billion
MARKET SIZE, 2031

CAGR 14.5%
(2026-2031)

300+
REPORT PAGES

280+
MARKET TABLES
OVERVIEW
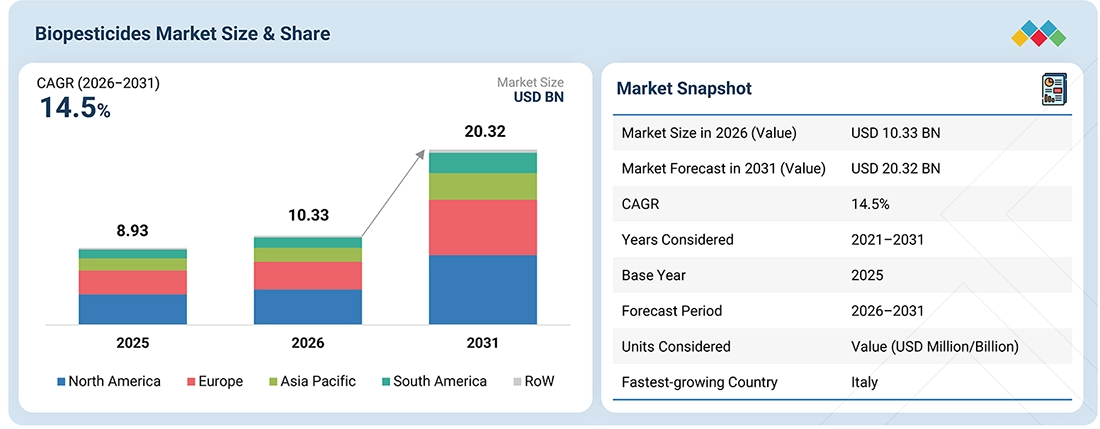
Source: Secondary Research, Interviews with Experts, MarketsandMarkets Analysis
The global biopesticides market is estimated at USD 10.33 billion in 2026 and is projected to reach USD 20.32 billion by 2031, at a CAGR of 14.5%. The global biopesticides market is experiencing strong growth because people want sustainable crop protection solutions that do not leave any chemical residues behind. Market growth momentum also benefits from evolving regulatory requirements, which are encouraging the adoption of integrated pest management (IPM) systems, while scientists continue to create better microbial and biochemical products. Biopesticides have become a crucial growth driver for the global biological crop protection market because their use has expanded into specialty crops, fruit and vegetable farming, and row crop farming.
KEY TAKEAWAYS
-
BY REGIONEurope is projected to register a CAGR of 14.9% in the global biopesticides market during the forecast period.
-
BY TYPEBy type, the bionematicides segment is expected to register the highest CAGR of 15.7% between 2026 and 2031.
-
BY MODE OF APPLICATIONBy mode of application, the seed treatment segment is expected to register the highest CAGR.
-
BY FORMULATIONBy formulation type, the liquid segment is projected to grow at the fastest CAGR of 14.7% from 2026 to 2031.
-
BY CROP TYPEBy crop type, the fruits & vegetables segment is expected to dominate the market.
-
BY SOURCEBy source, the microbial segment is projected to grow at the fastest rate from 2026 to 2031.
-
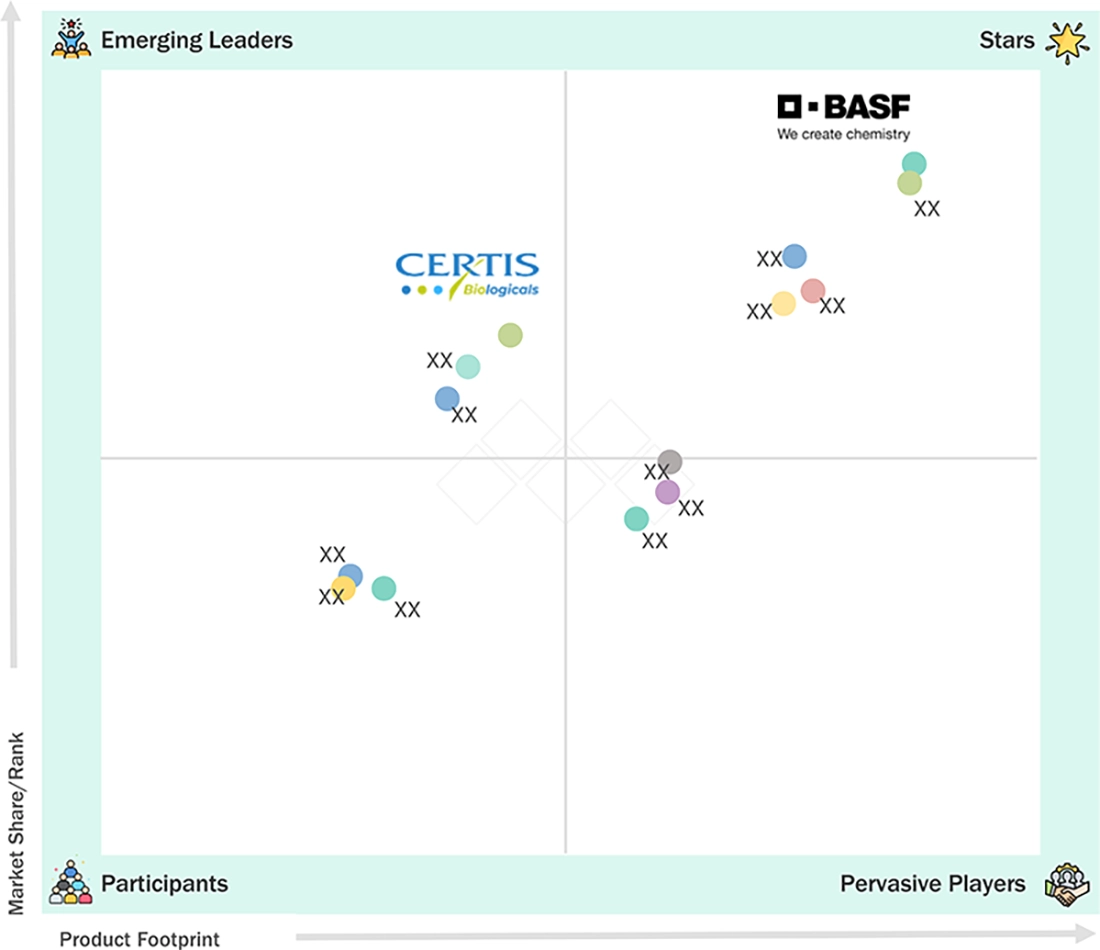
COMPETITIVE LANDSCAPE - KEY PLAYERSCompanies such as Corteva Agriscience, Valent BioSciences, BASF, and Bayer CropScience were identified as some of the star players in the global biopesticides market, given their strong market share and product footprint.
-
COMPETITIVE LANDSCAPE - STARTUPS/SMESCompanies such as BioWorks Inc., Lallemand Plant Care, and AgBiome, among others, have distinguished themselves among startups and SMEs by securing strong footholds in specialized niche areas, underscoring their potential as emerging market leaders.
The global biopesticides market is estimated at USD 10.33 billion in 2026 and is projected to reach USD 20.32 billion by 2031, at a CAGR of 14.5%. The global biopesticides market experiences growth because farmers demand environmentally friendly methods for protecting their crops. The market shows faster expansion because new microbial and biochemical products enter the market and existing integrated pest management (IPM) systems gain wider acceptance from farmers. The agricultural industry identifies biopesticides as a highly promising growth sector because farmers now use biological products in their crop protection programs across all major crop categories, which include fruits, vegetables, and row crops.
TRENDS & DISRUPTIONS IMPACTING CUSTOMERS' CUSTOMERS
A primary trend in the global biopesticides market is the shift toward sustainable crop protection methods that produce minimal chemical residues. The combination of stricter pesticide regulations and growing consumer demand for safe, green products is driving both manufacturers and growers to select biological solutions as their preferred choice. Innovations in microbial and biochemical technologies enable the development of sustainable agricultural systems that increase system resilience when used with precision agriculture and integrated pest management (IPM) solutions.
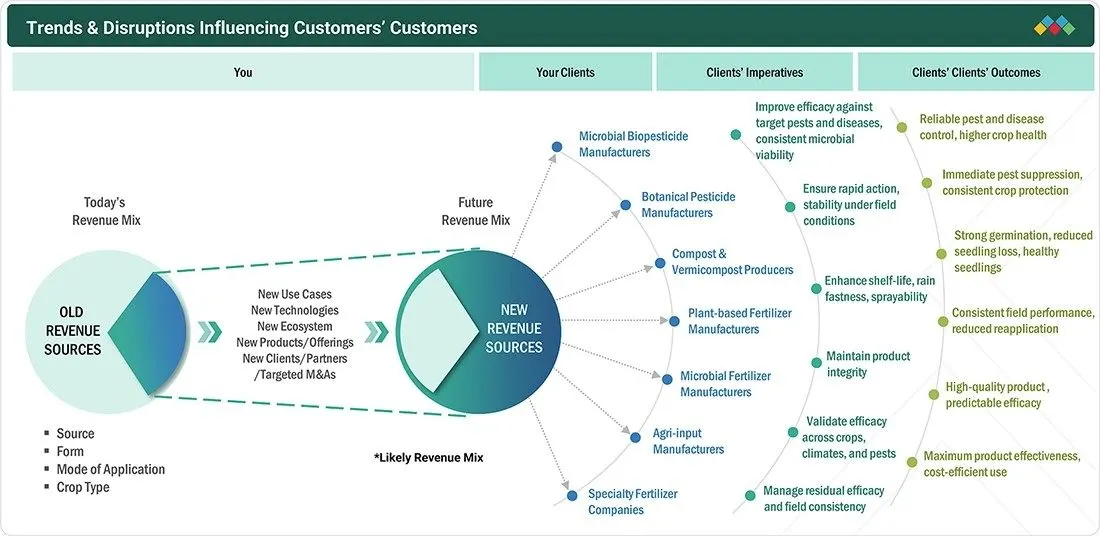
Source: Secondary Research, Interviews with Experts, MarketsandMarkets Analysis
MARKET DYNAMICS

Drivers
Impact
Level
Level
-
Stricter pesticide residue limits and sustainability-driven agricultural policies

-
Rising consumer demand for organic and chemical-free food


RESTRAINTS
Impact
Level
Level
-
Higher costs compared to conventional synthetic crop protection products

-
Variable efficacy under diverse climatic and pest conditions


OPPORTUNITIES
Impact
Level
Level
-
Expansion of organic farming and integrated pest management programs

-
Advancements in microbial formulations and precision application technologies


CHALLENGES
Impact
Level
Level
-
Fragmented regulatory standards across regions delaying product approvals

-
Limited farmer awareness and technical adoption capabilities

Source: Secondary Research, Interviews with Experts, MarketsandMarkets Analysis
Driver: Stricter pesticide residue limits and sustainability-driven agricultural policies
A key driver for the global biopesticides market is the growing emphasis on sustainable and low-residue crop protection solutions. With increasing regulation of synthetic chemicals and consumers demanding safer, eco-friendly food, both producers and growers are looking toward biological alternatives. Advances in microbial and biochemical technologies, as well as their incorporation into precision agriculture and integrated pest management systems, will further drive this trend. All of these converging trends will eventually lead to more resilient and eco-friendly farming practices worldwide.
Restraint: Higher costs compared to conventional synthetic crop protection products
A key restraint in the global biopesticides market is the cost gap between biopesticides and chemical pesticides, which is one of the most significant factors hindering market growth. Biopesticides require expert processing, fermentation, and cold chain distribution, leading to incrementally higher processing costs. Due to such cost variations, small and medium-scale farmers find it difficult to adopt these solutions, particularly in cost-conscious regions that demand an instant effect on pest control.
Opportunity: Expansion of organic farming and integrated pest management programs
A major opportunity for the global biopesticides market lies in the greater acceptance of organic farming and the growing implementation of integrated pest management (IPM) programs across regions. Governments, as well as certification bodies, are pushing for reduced chemical use. This drives further demand for biological products that comply with organic standards and residue limits, rather than synthetic products. As operations worldwide gear toward sustainable production systems, biopesticides will find their way into different components of IPM strategies, providing high long-term growth potential for microbial and biochemical products across key crop categories.
Challenge: Fragmented regulatory standards across regions delaying product approvals
A lack of consistency among the regulatory structures of various countries emerges as an issue for most biopesticide producers. Every country has its own registration processes and safety standards for biological crop protection agents. If consistency is not developed across regions, it will create hurdles for producers seeking to pursue large-scale opportunities in the global market. Addressing such issues will play an important role in the adoption of biopesticides worldwide.
BIOPESTICIDES MARKET: COMMERCIAL USE CASES ACROSS INDUSTRIES
| COMPANY | USE CASE DESCRIPTION | BENEFITS |
|---|---|---|
 |
Application of microbial bioinsecticides in corn and soybean farming | Enhances targeted pest control, minimizes residues, and supports sustainable row-crop systems |
 |
Use of Bacillus-based biofungicides in fruits and vegetables | Strengthens disease management, improves crop quality, and meets residue-free requirements |
 |
Integration of botanical and microbial biopesticides in specialty crops | Provides broad-spectrum protection and supports IPM while reducing synthetic pesticide use |
 |
Use of biofungicides and seed-applied biologicals in cereals and grains | Improves early-stage protection, enhances plant vigor, and promotes sustainable crop production |
Logos and trademarks shown above are the property of their respective owners. Their use here is for informational and illustrative purposes only.
MARKET ECOSYSTEM
Some of the prominent companies in this market include well-established and financially sound manufacturers of biopesticide products. These companies have been operational in the market for over a decade and have diversified portfolios, the latest technologies, and excellent global sales and marketing networks. The global biopesticides ecosystem comprises manufacturers, regulatory bodies, and end users. Key manufacturers such as Corteva Agriscience, Valent BioSciences, Certis Biologicals, and BASF develop microbial, botanical, and biochemical solutions.
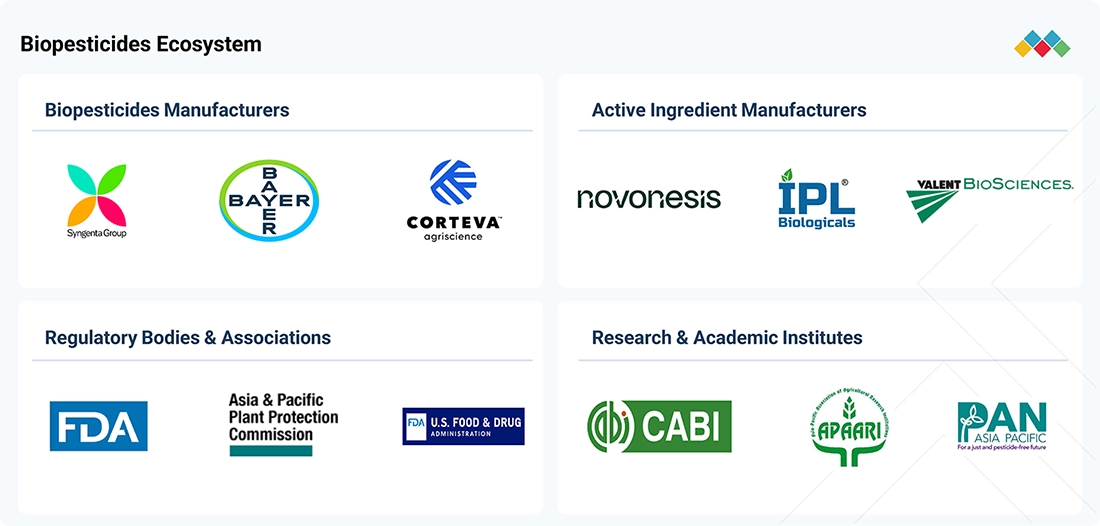
Logos and trademarks shown above are the property of their respective owners. Their use here is for informational and illustrative purposes only.
MARKET SEGMENTS
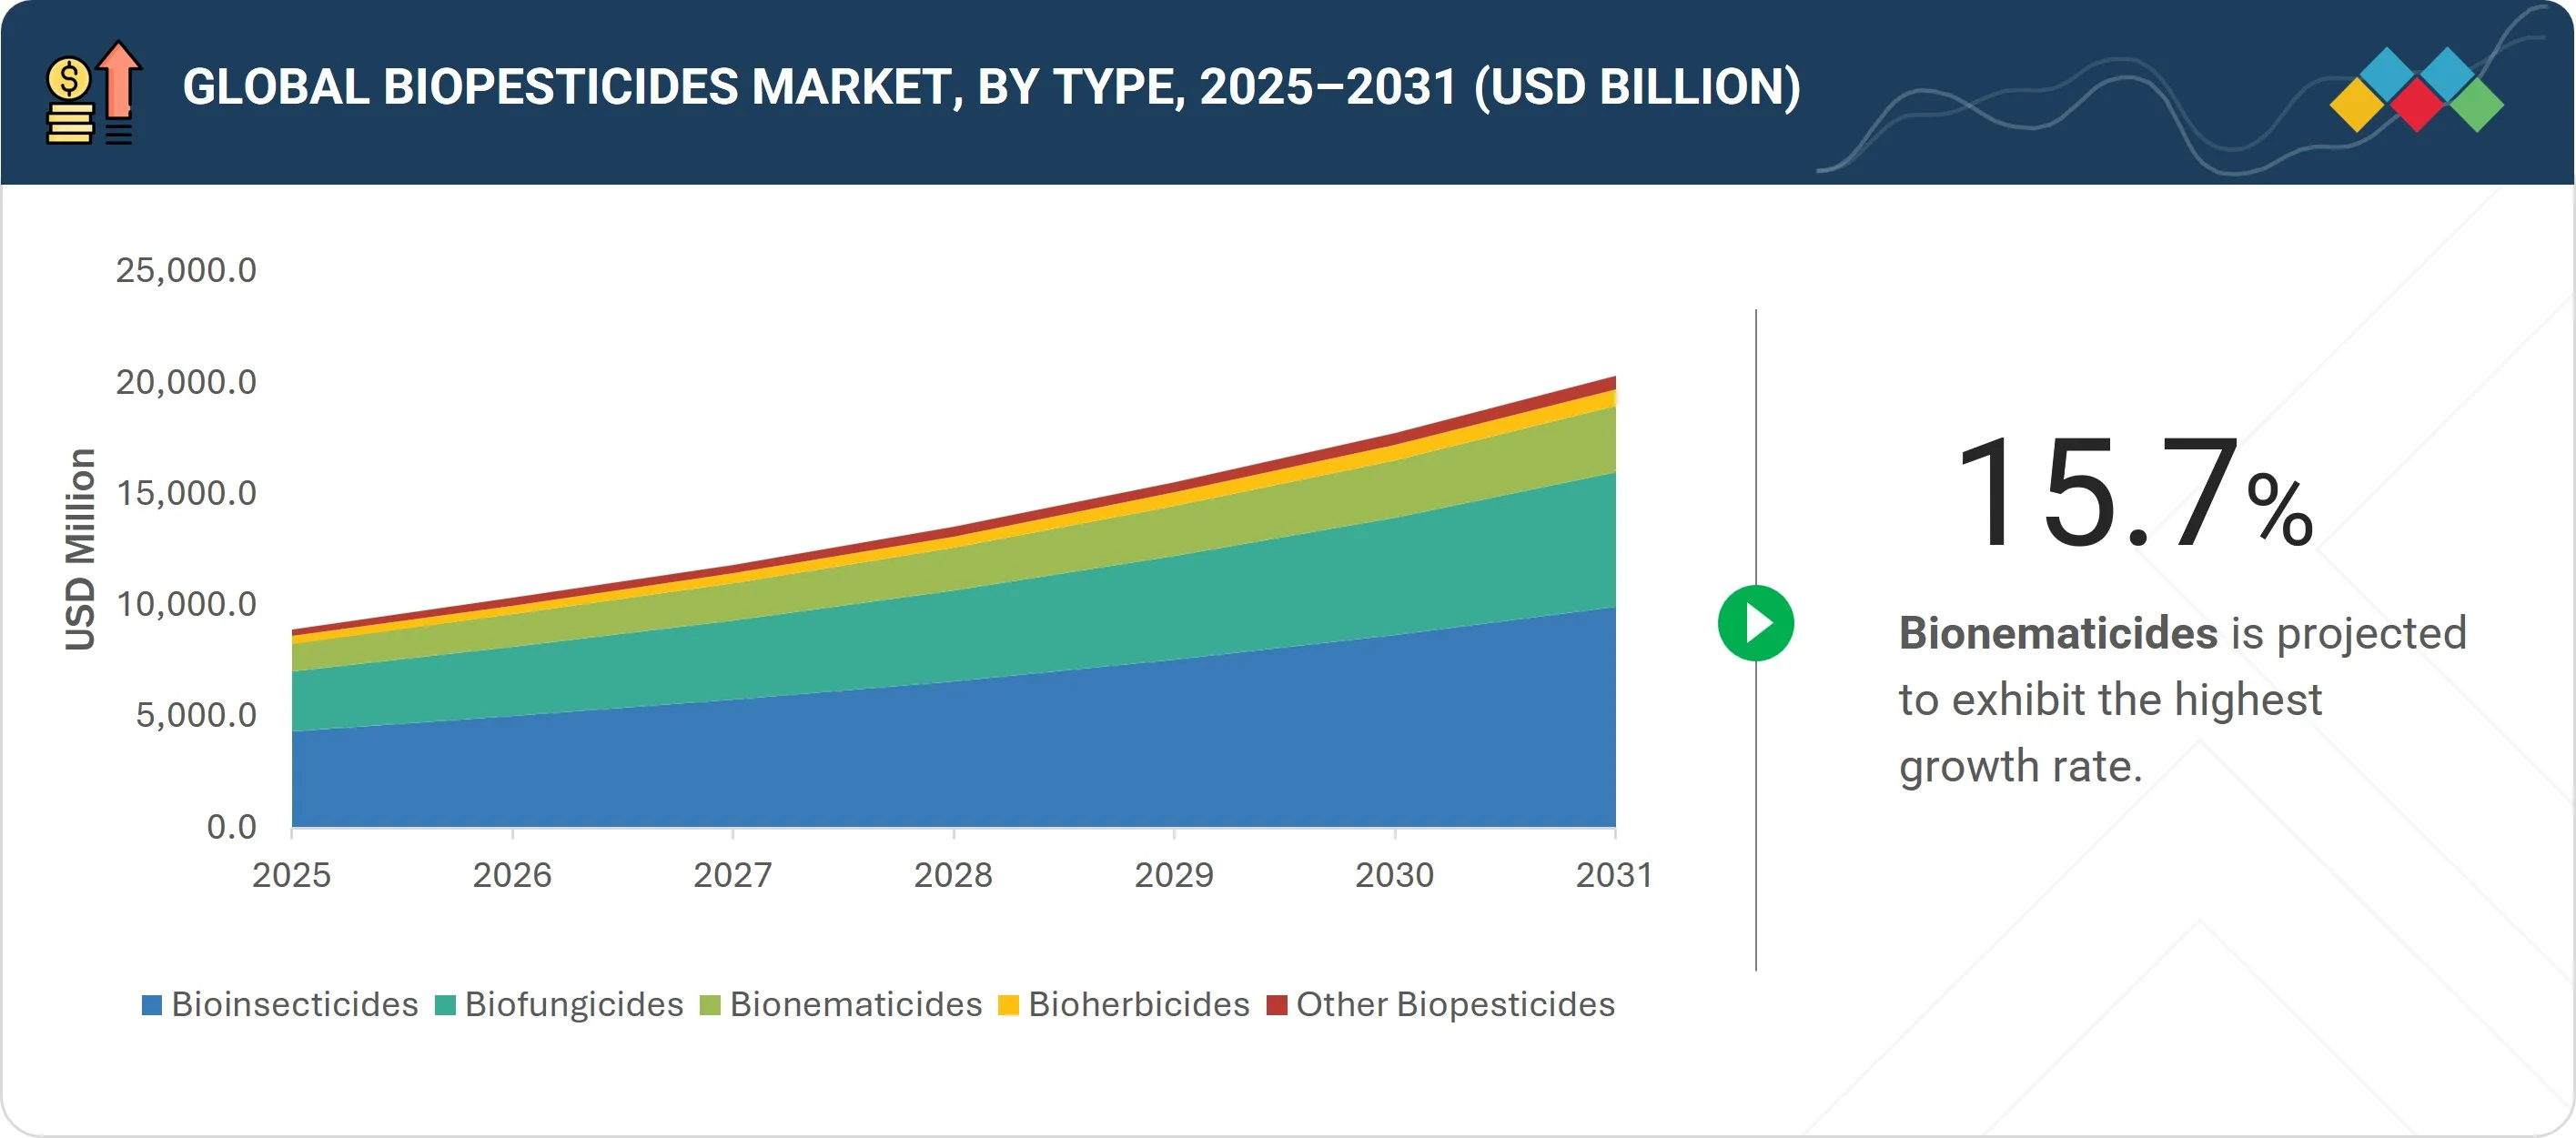
Source: Secondary Research, Interviews with Experts, MarketsandMarkets Analysis
Global Biopesticides Market, By Type
In the global biopesticides market, bioinsecticides hold the largest market share. They are being driven by a growing need for environmentally friendly substitutes for chemical insecticides, especially for fruits, vegetables, and high-value row crops. Bioinsecticides offer targeted insect pest management, lower pesticide residues in treated products, and compatibility with integrated pest management. Advances in microbial and biochemical formulation technology have also increased awareness of their advantages, enabling mass usage and securing their leadership in the type segment.
Global Biopesticides Market, By Mode of Application
In the global biopesticides market, seed treatment commands the largest share of the mode of application segment. The efficacy of seed-applied biopesticides in controlling pests, diseases, and nematodes during early crop growth stages remains uncontested. Seed treatment applications, therefore, help minimize dependency on chemical sprays, increase nutrient utilization, and fit well into various integrated pest management programs. Continuous developments in formulation stability, coating technologies, and microbial viability are promoting the adoption of biopesticides, with seed treatment as the preferred and most efficient mode of application.
Global Biopesticides Market, By Formulation
In the global biopesticides market, the liquid formulation segment holds the largest share. Factors favoring this segment include ease of application, uniform crop coverage, and compatibility with existing spraying equipment and integrated pest management programs. Liquid formulations of biopesticides provide greater stability, exhibiting higher efficacy and application flexibility across a large array of crops, including row crops, fruits, and vegetables. Continued developments in microbial and biochemical formulation technologies will further enhance product performance and drive wider acceptance, strengthening the dominance of liquid formulations in the marketplace.
Global Biopesticides Market, By Source
In the global biopesticides market, microbials represent the largest segment within the source category. Their high efficacy, specificity, and environmentally sustainable profile make them a preferred choice for managing pests, diseases, and nematodes. Widely applied across row crops, fruits, and vegetables, microbial biopesticides are compatible with integrated pest management programs and have minimal impact on non-target organisms. Ongoing advancements in strain development, formulation technologies, and delivery methods are further enhancing performance and adoption, reinforcing microbials as the dominant source in the global biopesticides market.
Global Biopesticides Market, By Crop Type
In the global biopesticides market, fruits and vegetables are the largest segment in this category due to the high economic value of these crops, strict regulations regarding pesticide residues, and increasing consumer preference for organically and sustainably grown foods. Growers are increasingly turning to microbial, biochemical, and botanical biopesticides for pest and disease management while ensuring crop quality and compliance with standards. Research advances in formulation technologies, seed treatments, and foliar applications, as well as integration into precision agriculture and integrated pest management programs, are further enhancing adoption, reinforcing fruits and vegetables as the dominant crop type segment in the global biopesticides market.
REGION
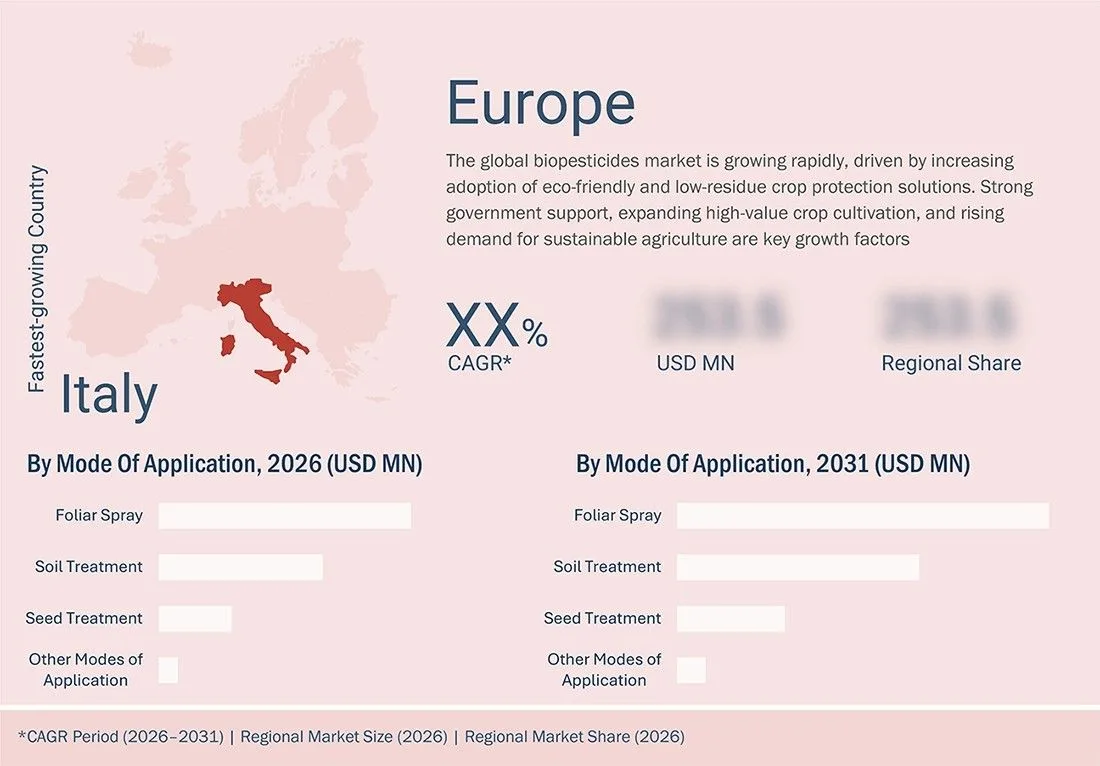
Europe to be the fastest-growing region in the global biopesticides market during the forecast period
Europe is emerging as the fastest-growing market for biopesticides globally, driven by strong government backing for sustainable farming and stricter rules on chemical pesticide use. Farmers growing fruits, vegetables, and specialty crops are increasingly turning to biological solutions to meet both safety standards and market demands. Local companies are ramping up production, investing in research, and making these products more accessible, while awareness among growers continues to grow. Together, these trends are positioning Europe as a key driver of biopesticide market growth.
BIOPESTICIDES MARKET: COMPANY EVALUATION MATRIX
Star companies such as Corteva Agriscience, along with leading regional biopesticide manufacturers, possess broad and diversified portfolios, strong brand visibility, and significant market influence. Emerging Leaders such as AgBiome are expanding rapidly through innovative, eco-friendly biopesticides and integrated pest management solutions. Participants maintain steady operations, while Pervasive Players hold a moderate but growing market presence.
Source: Secondary Research, Interviews with Experts, MarketsandMarkets Analysis
KEY MARKET PLAYERS
- Corteva Agriscience (US)
- Valent BioSciences (US)
- BASF (Germany)
- Bayer CropScience (Germany)
- Syngenta Group (Switzerland)
- FMC Corporation (US)
- UPL (India)
- Marrone Bio Innovations (US)
- Certis Biologicals (US)
- Koppert Biological Systems (Netherlands)
- AgBiome (US)
- Novonesis (Denmark)
- Andermatt Group AG (Switzerland)
- Lallemand Plant Care (Canada)
- BioWorks Inc. (US)
MARKET SCOPE
| REPORT METRIC | DETAILS |
|---|---|
| Market Size in 2026 (Value) | USD 10.33 Billion |
| Market Forecast in 2031 (Value) | USD 20.32 Billion |
| Growth Rate | CAGR of 14.5% during 2026-2031 |
| Years Considered | 2021-2031 |
| Base Year | 2025 |
| Forecast Period | 2026-2031 |
| Units Considered | Value (USD Million/Billion) |
| Report Coverage | Revenue forecast, company ranking, competitive landscape, growth factors, and trends |
| Segments Covered |
|
| Region Covered | North America, South America, Europe, Asia Pacific, Rest of the World |
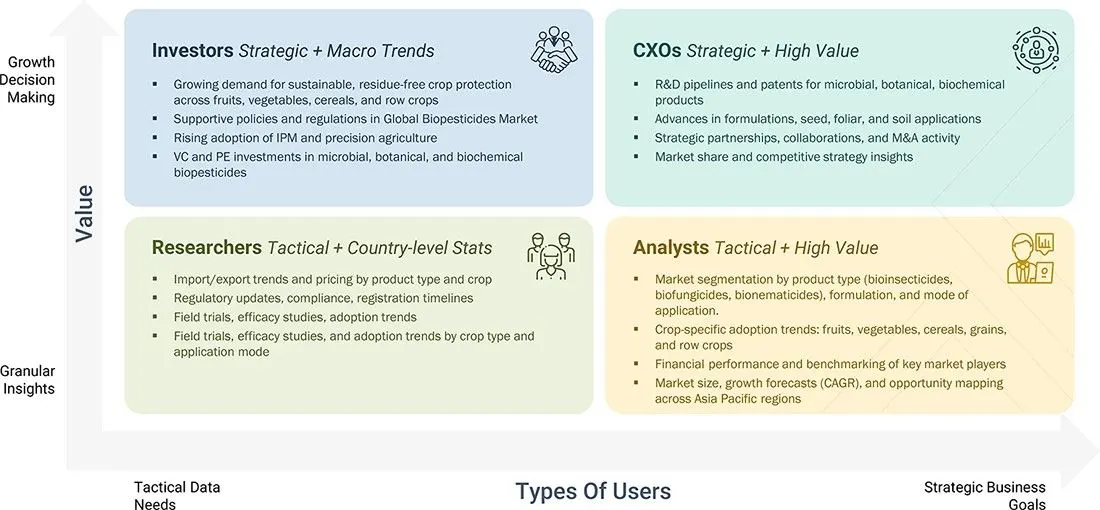
WHAT IS IN IT FOR YOU: BIOPESTICIDES MARKET REPORT CONTENT GUIDE
DELIVERED CUSTOMIZATIONS
We have successfully delivered the following deep-dive customizations:
| CLIENT REQUEST | CUSTOMIZATION DELIVERED | VALUE ADDS |
|---|---|---|
| Global Biopesticides Manufacturer |
|
|
| Globally focused Distributor |
|
|
| Global Agri-Biologicals Company |
|
|
| Investor/Private Equity Firm |
|
|
RECENT DEVELOPMENTS
- February 2025 : UPL launched Thiopron, a sulfur-based biofungicide aimed at sustainable powdery mildew control in specialty crops.
- January 2025 : Syngenta Group advanced its biologicals platform with the rollout of new nature-inspired microbial and biochemical solutions supported by expanded manufacturing capacity.
- January 2025 : Valent BioSciences entered a strategic partnership to commercialize Sweetsei and other Seipasa biostimulants in the US market.
- December 2024 : AgBiome transferred its biological fungicides Howler and Theia to Certis Biologicals, enabling expanded commercialization of these microbial solutions globally.
Table of Contents
 Exclusive indicates content/data unique to MarketsandMarkets and not available with any competitors.
TITLE
PAGE NO
1
INTRODUCTION
15
2
EXECUTIVE SUMMARY
3
PREMIUM INSIGHTS
4
MARKET OVERVIEW
Highlights the market structure, growth drivers, restraints, and near-term inflection points influencing performance.
4.1
INTRODUCTION
4.2
MACROECONOMIC INDICATORS
4.3
MARKET DYNAMICS
4.3.1
DRIVERS
4.3.1.1
STRICTER PESTICIDE RESIDUE LIMITS AND SUSTAINABILITY-DRIVEN AGRICULTURAL POLICIES
4.3.1.2
RISING CONSUMER DEMAND FOR ORGANIC AND CHEMICAL-FREE FOOD
4.3.2
RESTRAINTS
4.3.2.1
HIGHER COSTS COMPARED TO CONVENTIONAL SYNTHETIC CROP PROTECTION PRODUCTS
4.3.2.2
VARIABLE EFFICACY UNDER DIVERSE CLIMATIC AND PEST CONDITIONS
4.3.3
OPPORTUNITIES
4.3.3.1
EXPANSION OF ORGANIC FARMING AND INTEGRATED PEST MANAGEMENT PROGRAMS
4.3.3.2
ADVANCEMENTS IN MICROBIAL FORMULATIONS AND PRECISION APPLICATION TECHNOLOGIES
4.3.4
CHALLENGES
4.3.4.1
FRAGMENTED REGULATORY STANDARDS ACROSS REGIONS DELAYING PRODUCT APPROVALS
4.3.4.2
LIMITED FARMER AWARENESS AND TECHNICAL ADOPTION CAPABILITIES
4.4
UNMET NEEDS AND WHITE SPACES
4.5
INTERCONNECTED MARKETS AND CROSS-SECTOR OPPORTUNITIES
4.6
STRATEGIC MOVES BY TIER-1/2/3 PLAYERS
5
INDUSTRY TRENDS
Captures industry movement, adoption patterns, and strategic signals across key end-use segments and regions.
5.1
PORTER’S FIVE FORCES ANALYSIS
5.2
VALUE CHAIN ANALYSIS
5.3
ECOSYSTEM ANALYSIS
5.4
PRICING ANALYSIS
5.4.1
AVERAGE SELLING PRICE TREND OF KEY PLAYERS, BY TYPE, 2021–2025
5.4.2
AVERAGE SELLING PRICE TREND, BY REGION, 2021–2025
5.5
TRADE ANALYSIS
5.5.1
IMPORT SCENARIO (HS CODE 3808)
5.5.2
EXPORT SCENARIO (HS CODE 3808)
5.6
KEY CONFERENCES AND EVENTS, 2025–2026
5.7
TRENDS/DISRUPTIONS IMPACTING CUSTOMERS’ BUSINESSES
5.8
INVESTMENT AND FUNDING SCENARIO
5.9
CASE STUDY ANALYSIS
5.10
IMPACT OF 2025 US TARIFFS – GLOBAL BIOPESTICIDES MARKET
5.10.1
INTRODUCTION
5.10.2
KEY TARIFF RATES
5.10.3
PRICE IMPACT ANALYSIS
5.10.4
IMPACT ON COUNTRIES/REGIONS
5.10.5
IMPACT ON END-USE INDUSTRIES
6
STRATEGIC DISRUPTIONS THROUGH TECHNOLOGY, PATENTS, DIGITAL, AND AI ADOPTION
6.1
KEY EMERGING TECHNOLOGIES
6.1.1
SMART IOT-ENABLED BIOPEST MONITORING
6.1.2
AUTOMATED AND SENSOR-TRIGGERED BAIT STATIONS
6.2
COMPLEMENTARY TECHNOLOGIES
6.3
TECHNOLOGY/PRODUCT ROADMAP
6.4
PATENT ANALYSIS
6.5
FUTURE APPLICATIONS
6.6
IMPACT OF AI/GEN AI ON THE GLOBAL BIOPESTICIDES MARKET
6.6.1
TOP USE CASES AND MARKET POTENTIAL
6.6.2
BEST PRACTICES IN THE GLOBAL BIOPESTICIDES MARKET
6.6.3
CASE STUDIES OF AI IMPLEMENTATION IN THE GLOBAL BIOPESTICIDES MARKET
6.6.4
INTERCONNECTED ADJACENT ECOSYSTEM AND IMPACT ON MARKET PLAYERS
6.6.5
CLIENTS’ READINESS TO ADOPT GENERATIVE AI IN THE GLOBAL BIOPESTICIDES MARKET
6.7
SUCCESS STORIES AND REAL-WORLD APPLICATIONS
7
REGULATORY LANDSCAPE
7.1
REGIONAL REGULATIONS AND COMPLIANCE
7.1.1
REGULATORY BODIES, GOVERNMENT AGENCIES, AND OTHER ORGANIZATIONS
7.1.2
INDUSTRY STANDARDS
8
CUSTOMER LANDSCAPE & BUYER BEHAVIOR
8.1
DECISION-MAKING PROCESS
8.2
BUYER STAKEHOLDERS AND BUYING EVALUATION CRITERIA
8.3
ADOPTION BARRIERS & INTERNAL CHALLENGES
8.4
UNMET NEEDS FROM VARIOUS END-USE INDUSTRIES
8.5
MARKET PROFITABILITY
9
BIOPESTICIDES MARKET, BY TYPE
Market Size, Volume & Forecast – USD Million
9.1
INTRODUCTION
9.2
BIOINSECTICIDES
9.2.1
RISING PEST RESISTANCE DRIVES STRONG DEMAND FOR BIOINSECTICIDE ADOPTION
9.2.1.1
BACILLUS THURINGIENSIS
9.2.1.2
BEAUVERIA BASSIANA
9.2.1.3
METARHIZIUM ANISOPLIAE
9.2.1.4
VERTICILLIUM LECANII
9.2.1.5
BACULOVIRUS
9.2.1.6
OTHER BIOINSECTICIDES
9.3
BIOFUNGICIDES
9.3.1
GROWING DISEASE PRESSURE ACCELERATES SHIFT TOWARD BIOFUNGICIDE SOLUTIONS
9.3.1.1
TRICHODERMA
9.3.1.2
BACILLUS
9.3.1.3
PSEUDOMONAS
9.3.1.4
STREPTOMYCES
9.3.1.5
OTHER BIOFUNGICIDES
9.4
BIONEMATICIDES
9.4.1
SOIL HEALTH CONCERNS PROPEL UPTAKE OF MICROBIAL BIONEMATICIDE TECHNOLOGIES
9.4.1.1
PAECILOMYCES LILACINUS
9.4.1.2
BACILLUS FIRMUS
9.4.1.3
PASTEURIA SPP.
9.4.1.4
OTHER BIONEMATICIDES
9.5
BIOHERBICIDES
9.5.1
NEED FOR ECO-SAFE WEED CONTROL CATALYZES INTEREST IN BIOHERBICIDE ALTERNATIVES
9.6
OTHER BIOPESTICIDES
10
BIOPESTICIDES MARKET, BY FORMULATION
Market Size, Volume & Forecast – USD Million
10.1
INTRODUCTION
10.2
DRY
10.2.1
LONGER SHELF LIFE AND STORAGE STABILITY DRIVE DEMAND FOR DRY BIOPESTICIDES
10.3
LIQUID
10.3.1
EASE OF APPLICATION AND COMPATIBILITY BOOST ADOPTION OF LIQUID BIOPESTICIDES
11
BIOPESTICIDES MARKET, BY MODE OF APPLICATION
Market Size, Volume & Forecast – USD Million
11.1
INTRODUCTION
11.2
SEED TREATMENT
11.2.1
EARLY-STAGE CROP PROTECTION DEMAND ACCELERATES ADOPTION OF BIOPESTICIDE SEED TREATMENTS
11.3
SOIL TREATMENT
11.3.1
FOCUS ON SOIL HEALTH AND ROOT-ZONE PROTECTION DRIVES GROWTH IN BIOPESTICIDE SOIL TREATMENTS
11.4
FOLIAR SPRAY
11.4.1
RAPID ACTION AND BROAD CROP COVERAGE STRENGTHEN USE OF BIOPESTICIDE FOLIAR SPRAYS
11.5
OTHER MODES OF APPLICATION
12
BIOPESTICIDES MARKET, BY SOURCE
Market Size, Volume & Forecast – USD Million
12.1
INTRODUCTION
12.2
MICROBIAL
12.2.1
ADVANCEMENTS IN MICROBIAL TECHNOLOGIES ACCELERATE ADOPTION OF MICROBIAL BIOPESTICIDES
12.2.1.1
BACTERIA
12.2.1.2
FUNGI
12.2.1.3
VIRUSES
12.2.1.4
PROTOZOA
12.3
BIOCHEMICALS
12.3.1
DEMAND FOR NATURAL, RESIDUE-FREE INPUTS BOOSTS GROWTH OF BIOCHEMICAL BIOPESTICIDES
12.3.1.1
SEMIOCHEMICALS
12.3.1.2
PLANT EXTRACTS
12.3.1.3
ORGANIC ACIDS
12.4
BENEFICIAL INSECTS
12.4.1
INTEGRATED PEST MANAGEMENT STRATEGIES FUEL EXPANSION OF BENEFICIAL INSECT USE
12.4.1.1
PREDATORS
12.4.1.2
PARASITOIDS
13
BIOPESTICIDES MARKET, BY CROP TYPE
Market Size, Volume & Forecast – USD Million
13.1
INTRODUCTION
13.2
CEREALS & GRAINS
13.2.1
RISING RESISTANCE ISSUES STRENGTHEN BIOPESTICIDE ADOPTION IN CEREALS AND GRAINS
13.2.1.1
CORN
13.2.1.2
WHEAT
13.2.1.3
RICE
13.2.1.4
OTHER CEREALS & GRAINS
13.3
OILSEEDS & PULSES
13.3.1
NEED FOR SOIL HEALTH IMPROVEMENT DRIVES BIOPESTICIDE USE IN OILSEEDS AND PULSES
13.3.1.1
SOYBEAN
13.3.1.2
SUNFLOWER
13.3.1.3
OTHER OILSEEDS & PULSES
13.4
FRUITS & VEGETABLES
13.4.1
HIGH DEMAND FOR RESIDUE-FREE PRODUCE ACCELERATES BIOPESTICIDE UPTAKE IN FRUITS AND VEGETABLES
13.4.1.1
POME FRUITS
13.4.1.2
CITRUS FRUITS
13.4.1.3
LEAFY VEGETABLES
13.4.1.4
BERRIES
13.4.1.5
ROOT & TUBER VEGETABLES
13.4.1.6
OTHER FRUITS & VEGETABLES
13.5
OTHER CROP TYPES
14
BIOPESTICIDES MARKET, BY REGION
Market Size, Volume & Forecast – USD Million
14.1
INTRODUCTION
14.2
NORTH AMERICA
14.2.1
US
14.2.1.1
ACCELERATE BIOPESTICIDE ADOPTION THROUGH STRICT RESIDUE AND SUSTAINABILITY REGULATIONS
14.2.2
CANADA
14.2.2.1
PROMOTE BIOPESTICIDES VIA ORGANIC FARMING EXPANSION AND CLIMATE-RESILIENT PRACTICES
14.2.3
MEXICO
14.2.3.1
DRIVE BIOPESTICIDE DEMAND THROUGH EXPORT COMPLIANCE AND HORTICULTURE GROWTH
14.3
EUROPE
14.3.1
GERMANY
14.3.1.1
ENFORCE CHEMICAL PESTICIDE RESTRICTIONS TO ACCELERATE BIOPESTICIDE SUBSTITUTION
14.3.2
FRANCE
14.3.2.1
EXPAND AGROECOLOGY AND RESIDUE-FREE FARMING TO BOOST BIOPESTICIDE USAGE
14.3.3
ITALY
14.3.3.1
SUPPORT BIOPESTICIDES THROUGH HIGH-VALUE FRUIT AND VEGETABLE CULTIVATION
14.3.4
SPAIN
14.3.4.1
INCREASE BIOPESTICIDE DEMAND VIA EXPORT-DRIVEN HORTICULTURE AND IPM ADOPTION
14.3.5
UK
14.3.5.1
PROMOTE SUSTAINABLE CROP PROTECTION THROUGH POST-BREXIT REGULATORY REFORMS
14.3.6
REST OF EUROPE
14.4
ASIA PACIFIC
14.4.1
CHINA
14.4.1.1
ACCELERATE ADOPTION THROUGH REGULATORY SUPPORT AND HIGH-VALUE CROP INTEGRATION
14.4.2
INDIA
14.4.2.1
DRIVE MARKET EXPANSION VIA FARMER AWARENESS AND SUSTAINABLE AGRICULTURE PROGRAMS
14.4.3
JAPAN
14.4.3.1
PROMOTE ECO-FRIENDLY SOLUTIONS IN SPECIALTY CROPS AND PROTECTED CULTIVATION
14.4.4
AUSTRALIA
14.4.4.1
LEVERAGE GOVERNMENT INCENTIVES AND PRECISION AGRICULTURE FOR BIOPESTICIDE UPTAKE
14.5
SOUTH AMERICA
14.5.1
BRAZIL
14.5.1.1
SCALE BIOPESTICIDE ADOPTION THROUGH SOYBEAN, SUGARCANE, AND HORTICULTURE EXPANSION
14.5.2
ARGENTINA
14.5.2.1
BOOST BIOPESTICIDE DEMAND VIA EXPORT COMPLIANCE AND IPM INTEGRATION
14.5.3
REST OF SOUTH AMERICA
14.6
REST OF THE WORLD
14.6.1
AFRICA
14.6.1.1
EXPAND BIOPESTICIDE USE THROUGH HORTICULTURE GROWTH AND FOOD SAFETY INITIATIVES
14.6.2
MIDDLE EAST
14.6.2.1
ADOPT BIOPESTICIDES TO SUPPORT SUSTAINABLE AGRICULTURE AND WATER-EFFICIENT FARMING
15
COMPETITIVE LANDSCAPE
15.1
OVERVIEW
15.2
KEY PLAYER STRATEGIES/RIGHT TO WIN
15.2.1
COMPETITIVE STRATEGIES INITIATIVES
15.3
REVENUE ANALYSIS
15.4
MARKET SHARE ANALYSIS
15.5
BRAND COMPARISON
15.5.1
CORTEVA AGRISCIENCE
15.5.2
VALENT BIOSCIENCES
15.5.3
BASF
15.5.4
BAYER CROPSCIENCE
15.6
COMPANY EVALUATION MATRIX: KEY PLAYERS,
15.6.1
STARS
15.6.2
EMERGING LEADERS
15.6.3
PERVASIVE PLAYERS
15.6.4
PARTICIPANTS
15.6.5
COMPANY FOOTPRINT: KEY PLAYERS,
15.6.5.1
COMPANY FOOTPRINT
15.6.5.2
TYPE FOOTPRINT
15.6.5.3
APPLICATION FOOTPRINT
15.6.5.4
OFFERING FOOTPRINT
15.6.5.5
REGION FOOTPRINT
15.7
COMPANY EVALUATION MATRIX: STARTUPS/SMES,
15.7.1
PROGRESSIVE COMPANIES
15.7.2
RESPONSIVE COMPANIES
15.7.3
DYNAMIC COMPANIES
15.7.4
STARTING BLOCKS
15.7.5
COMPETITIVE BENCHMARKING: STARTUPS/SMES,
15.7.5.1
DETAILED LIST OF KEY STARTUPS/SMES
15.7.5.2
COMPETITIVE BENCHMARKING OF KEY STARTUPS/SMES
15.8
COMPANY VALUATION AND FINANCIAL METRICS
15.9
COMPETITIVE SCENARIO
15.9.1
PRODUCT LAUNCHES
15.9.2
DEALS
15.9.3
EXPANSIONS
16
COMPANY PROFILES
16.1
KEY PLAYERS
16.1.1
CORTEVA AGRISCIENCE
16.1.1.1
BUSINESS OVERVIEW
16.1.1.2
PRODUCTS/SOLUTIONS/SERVICES OFFERED
16.1.1.3
MNM VIEW
16.1.1.3.1
KEY STRENGTHS/RIGHT TO WIN
16.1.1.3.2
STRATEGIC CHOICES
16.1.1.3.3
WEAKNESSES/COMPETITIVE THREATS
16.1.2
VALENT BIOSCIENCES
16.1.2.1
BUSINESS OVERVIEW
16.1.2.2
PRODUCTS/SOLUTIONS/SERVICES OFFERED
16.1.2.3
MNM VIEW
16.1.2.3.1
KEY STRENGTHS/RIGHT TO WIN
16.1.2.3.2
STRATEGIC CHOICES
16.1.2.3.3
WEAKNESSES/COMPETITIVE THREATS
16.1.3
BASF
16.1.3.1
BUSINESS OVERVIEW
16.1.3.2
PRODUCTS/SOLUTIONS/SERVICES OFFERED
16.1.3.3
MNM VIEW
16.1.3.3.1
KEY STRENGTHS/RIGHT TO WIN
16.1.3.3.2
STRATEGIC CHOICES
16.1.3.3.3
WEAKNESSES/COMPETITIVE THREATS
16.1.4
BAYER CROPSCIENCE
16.1.4.1
BUSINESS OVERVIEW
16.1.4.2
PRODUCTS/SOLUTIONS/SERVICES OFFERED
16.1.4.3
MNM VIEW
16.1.4.3.1
KEY STRENGTHS/RIGHT TO WIN
16.1.4.3.2
STRATEGIC CHOICES
16.1.4.3.3
WEAKNESSES/COMPETITIVE THREATS
16.1.5
SYNGENTA GROUP
16.1.5.1
BUSINESS OVERVIEW
16.1.5.2
PRODUCTS/SOLUTIONS/SERVICES OFFERED
16.1.5.3
MNM VIEW
16.1.5.3.1
KEY STRENGTHS/RIGHT TO WIN
16.1.5.3.2
STRATEGIC CHOICES
16.1.5.3.3
WEAKNESSES/COMPETITIVE THREATS
16.1.6
FMC CORPORATION
16.1.6.1
BUSINESS OVERVIEW
16.1.6.2
PRODUCTS/SOLUTIONS/SERVICES OFFERED
16.1.6.3
MNM VIEW
16.1.6.3.1
KEY STRENGTHS/RIGHT TO WIN
16.1.6.3.2
STRATEGIC CHOICES
16.1.6.3.3
WEAKNESSES/COMPETITIVE THREATS
16.1.7
UPL
16.1.7.1
BUSINESS OVERVIEW
16.1.7.2
PRODUCTS/SOLUTIONS/SERVICES OFFERED
16.1.7.3
MNM VIEW
16.1.7.3.1
KEY STRENGTHS/RIGHT TO WIN
16.1.7.3.2
STRATEGIC CHOICES
16.1.7.3.3
WEAKNESSES/COMPETITIVE THREATS
16.1.8
MARRONE BIO INNOVATIONS
16.1.8.1
BUSINESS OVERVIEW
16.1.8.2
PRODUCTS/SOLUTIONS/SERVICES OFFERED
16.1.8.3
MNM VIEW
16.1.8.3.1
KEY STRENGTHS/RIGHT TO WIN
16.1.8.3.2
STRATEGIC CHOICES
16.1.8.3.3
WEAKNESSES/COMPETITIVE THREATS
16.1.9
CERTIS BIOLOGICALS
16.1.9.1
BUSINESS OVERVIEW
16.1.9.2
PRODUCTS/SOLUTIONS/SERVICES OFFERED
16.1.9.3
MNM VIEW
16.1.9.3.1
KEY STRENGTHS/RIGHT TO WIN
16.1.9.3.2
STRATEGIC CHOICES
16.1.9.3.3
WEAKNESSES/COMPETITIVE THREATS
16.1.10
KOPPERT BIOLOGICAL SYSTEMS
16.1.10.1
BUSINESS OVERVIEW
16.1.10.2
PRODUCTS/SOLUTIONS/SERVICES OFFERED
16.1.10.3
MNM VIEW
16.1.10.3.1
KEY STRENGTHS/RIGHT TO WIN
16.1.10.3.2
STRATEGIC CHOICES
16.1.10.3.3
WEAKNESSES/COMPETITIVE THREATS
16.1.11
AGBIOME
16.1.11.1
BUSINESS OVERVIEW
16.1.11.2
PRODUCTS/SOLUTIONS/SERVICES OFFERED
16.1.11.3
MNM VIEW
16.1.11.3.1
KEY STRENGTHS/RIGHT TO WIN
16.1.11.3.2
STRATEGIC CHOICES
16.1.11.3.3
WEAKNESSES/COMPETITIVE THREATS
16.1.12
NOVOZYMES
16.1.12.1
BUSINESS OVERVIEW
16.1.12.2
PRODUCTS/SOLUTIONS/SERVICES OFFERED
16.1.12.3
MNM VIEW
16.1.12.3.1
KEY STRENGTHS/RIGHT TO WIN
16.1.12.3.2
STRATEGIC CHOICES
16.1.12.3.3
WEAKNESSES/COMPETITIVE THREATS
16.1.13
CHR. HANSEN
16.1.13.1
BUSINESS OVERVIEW
16.1.13.2
PRODUCTS/SOLUTIONS/SERVICES OFFERED
16.1.13.3
MNM VIEW
16.1.13.3.1
KEY STRENGTHS/RIGHT TO WIN
16.1.13.3.2
STRATEGIC CHOICES
16.1.13.3.3
WEAKNESSES/COMPETITIVE THREATS
16.1.14
LALLEMAND PLANT CARE
16.1.14.1
BUSINESS OVERVIEW
16.1.14.2
PRODUCTS/SOLUTIONS/SERVICES OFFERED
16.1.14.3
MNM VIEW
16.1.14.3.1
KEY STRENGTHS/RIGHT TO WIN
16.1.14.3.2
STRATEGIC CHOICES
16.1.14.3.3
WEAKNESSES/COMPETITIVE THREATS
16.1.15
BIOWORKS INC.
16.1.15.1
BUSINESS OVERVIEW
16.1.15.2
PRODUCTS/SOLUTIONS/SERVICES OFFERED
16.1.15.3
MNM VIEW
16.1.15.3.1
KEY STRENGTHS/RIGHT TO WIN
16.1.15.3.2
STRATEGIC CHOICES
16.1.15.3.3
WEAKNESSES/COMPETITIVE THREATS
NOTE: THE KEY COMPANY PROFILES INCLUDE BUSINESS OVERVIEW, RECENT FINANCIALS, PRODUCT OFFERINGS, AND KEY STRATEGIES. RECENT FINANCIALS CAN BE PROVIDED BASED ON DATA/INFORMATION AVAILABILITY IN THE PUBLIC DOMAIN. THE LIST OF COMPANIES MENTIONED ABOVE CAN BE
17
RESEARCH METHODOLOGY
17.1
RESEARCH DATA
17.1.1
SECONDARY DATA
17.1.1.1
KEY DATA FROM SECONDARY SOURCES
17.1.2
PRIMARY DATA
17.1.2.1
KEY DATA FROM PRIMARY SOURCES
17.1.2.2
KEY PRIMARY PARTICIPANTS
17.1.2.3
BREAKDOWN OF PRIMARY INTERVIEWS
17.1.2.4
KEY INDUSTRY INSIGHTS
17.2
MARKET SIZE ESTIMATION
17.2.1
BOTTOM-UP APPROACH
17.2.2
TOP-DOWN APPROACH
17.2.3
BASE NUMBER CALCULATION
17.3
MARKET FORECAST APPROACH
17.3.1
SUPPLY SIDE
17.3.2
DEMAND SIDE
17.4
DATA TRIANGULATION
17.5
FACTOR ANALYSIS
17.6
RESEARCH ASSUMPTIONS
17.7
RESEARCH LIMITATIONS AND RISK ASSESSMENT
18
APPENDIX
18.1
DISCUSSION GUIDE
18.2
KNOWLEDGESTORE: MARKETSANDMARKETS’ SUBSCRIPTION PORTAL
18.3
CUSTOMIZATION OPTIONS
18.4
RELATED REPORTS
18.5
AUTHOR DETAILS
Methodology
The study involved four major activities in estimating the current size of the biopesticides market. Exhaustive secondary research was done to collect information on the market, peer market, and parent market. The next step was to validate these findings, assumptions, and sizing with industry experts across the value chain through primary research. Both top-down and bottom-up approaches were employed to estimate the complete market size. After that, market breakdown and data triangulation were used to estimate the market size of segments and subsegments.
Secondary Research
This research study involved the extensive use of secondary sources—directories and databases such as Bloomberg Businessweek and Factiva—to identify and collect information useful for a technical, market-oriented, and commercial study of the biopesticides market.
In the secondary research process, various sources such as annual reports, press releases & investor presentations of companies, white papers, certified publications, articles from recognized authors, gold & silver standard websites, directories, and databases were referred to identify and collect information. This research study involved the extensive use of secondary sources—directories and databases such as Bloomberg Businessweek and Factiva—to identify and collect information useful for a technical, market-oriented, and commercial study of the biopesticides market.
Secondary research was mainly used to obtain key information about the industry’s supply chain, the total pool of key players, and market classification and segmentation as per the industry trends to the bottom-most level, regional markets, and key developments from both market- and technology-oriented perspectives.
Primary Research
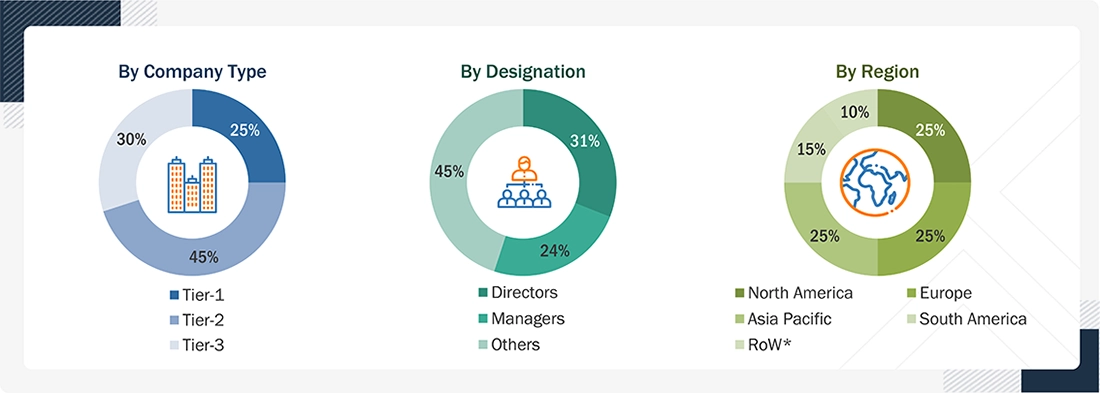
Extensive primary research was conducted after obtaining information regarding the global biopesticides market scenario through secondary research. Several primary interviews were conducted with market experts from both the demand and supply sides across major countries of North America, Europe, Asia Pacific, South America, and RoW. Primary data was collected through questionnaires, emails, and telephonic interviews. The primary sources from the supply side included various industry experts, such as Chief X Officers (CXOs), Vice Presidents (VPs), Directors from business development, marketing, research, and development teams, and key opinion leaders. Primary interviews were conducted to gather insights such as market statistics, data on revenue collected from the products and services, market breakdowns, market size estimations, market forecasting, and data triangulation. Primary research also helped in understanding the various trends related to global biopesticides core material, shell material, method, technology, and application. Stakeholders from the demand side, such as research institutions and universities, and third-party vendors, were interviewed to understand the buyer’s perspective on the service, and their current usage of encapsulation and the outlook of their business, which will affect the overall market.
To know about the assumptions considered for the study, download the pdf brochure
Note: The three tiers of the companies are defined based on their total revenues in 2023 or 2024, as per the availability of financial data: Tier 1: Revenue > USD 1 billion; Tier 2: USD 100 million ≤ Revenue ≤ USD 1 billion; Tier 3: Revenue < USD 100 million.
|
COMPANY NAME |
DESIGNATION |
|
Corteva Agriscience (US) |
R&D Expert |
|
BASF SE (Germany) |
Sales Manager |
|
Bayer CropSciences (Germany) |
Manager |
|
Syngenta Group (Switzerland) |
Sales Manager |
|
FMC Corporation (US) |
Marketing Manager |
Market Size Estimation
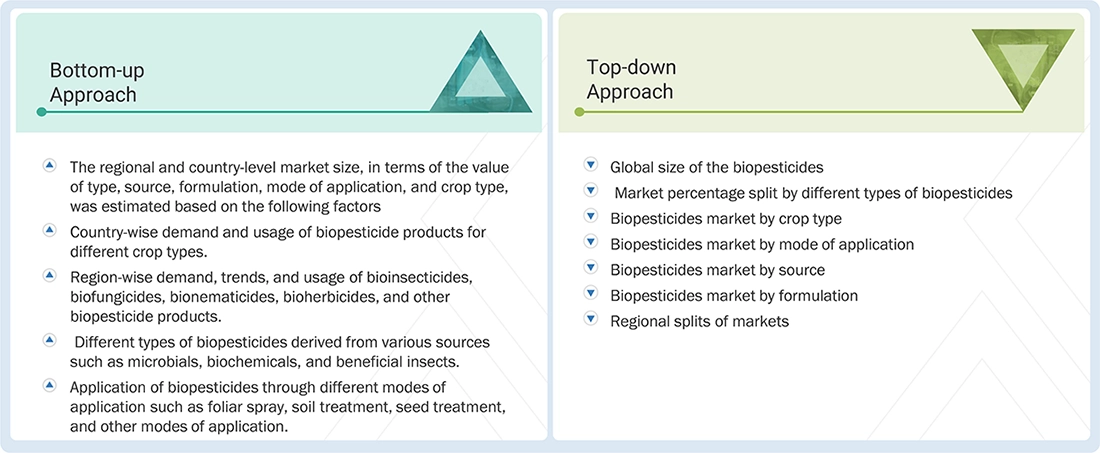
Both the top-down and bottom-up approaches were used to estimate and validate the total size of the biopesticides market. These approaches were also used extensively to determine the size of various subsegments in the market. The research methodology used to estimate the market size includes the following details:
- The key players in the industry and the overall markets were identified through extensive secondary research.
- All shares, splits, and breakdowns were determined using secondary sources and verified through primary sources.
- All possible parameters that affect the market covered in this research study were accounted for, viewed in extensive detail, verified through primary research, and analyzed to obtain final quantitative and qualitative data.
- The research included the study of reports, reviews, and newsletters of top market players, along with extensive interviews for opinions from leaders, such as CEOs, directors, and marketing executives.
Biopesticides Market : Top-Down and Bottom-Up Approach
Data Triangulation
After arriving at the overall market size from the estimation process explained above, the total market was split into several segments and subsegments. Data triangulation and market breakdown procedures were employed, wherever applicable, to estimate the overall biopesticides market and arrive at the exact statistics for all segments and subsegments. The data was triangulated by studying various factors and trends from the demand and supply sides. Along with this, the market size was validated using both the top-down and bottom-up approaches.
Market Definition
Biopesticides have pesticide properties originating from natural living organisms, including microorganisms, plants, and animals. Biopesticides are gaining prominence due to their safer and eco-friendly
ature.The Environmental Protection Agency has defined biopesticides as follows:
“Biopesticides include naturally occurring substances that control pests (biochemical pesticides), microorganisms that control pests (microbial pesticides), and pesticidal substances produced by plants containing added genetic material (plant-incorporated protectants) or PIPs.”
Key Stakeholders
- Agriculture pesticide manufacturers & suppliers
- Associations and industry bodies
- Biopesticide manufacturers & suppliers
- Biopesticide traders, retailers, and distributors
- Commercial research & development (R&D) institutions
- Venture capitalists and investors
- Government, regulatory bodies, and research organizations
- Technology providers to biopesticide & microbial companies
- Public hygiene organizations, government regulatory institutions, and food safety agencies
-
Associations and industry bodies:
- Food and Agriculture Organization (FAO)
- European Food Safety Authority (EFSA)
- British Pest Control Association (BPCA)
- National Pest Management Association (NPMA)
- National Pest Technicians Association
- Confederation of European Pest Management Association (CEPA)
- International associations and industry bodies such as Biopesticide Industry Alliance (BPIA) and the International Biocontrol Manufacturers Association (IBMA)
- Organisation for Economic Co-operation and Development (OECD)
Report Objectives
- Determining and projecting the size of the biopesticides market with respect to type, crop type, mode of application, source, formulation, and region
- Identifying the attractive opportunities in the market by determining the largest and fastest-growing segments
- Providing detailed information about the key factors influencing the market growth (drivers, restraints, opportunities, and industry-specific challenges)
- Providing the regulatory framework and market entry process related to the biopesticides market
- Analyzing the micro markets with respect to individual growth trends, prospects, and their contribution to the total market
Customization Options
With the given market data, MarketsandMarkets offers customizations according to company-specific scientific needs.
The following customization options are available for the report:
- Additional country-level analysis of the space sensors and actuators market
- Profiling of other market players (up to five)
Product Analysis
- Products Matrix, which gives a detailed comparison of the service portfolio of each company
Geographic Analysis
With the given market data, MarketsandMarkets offers customizations according to company-specific scientific needs
- Further breakdown of the Rest of Europe global biopesticides market into key countries
- Further breakdown of the Rest of Asia Pacific global biopesticides market into key countries
- Further breakdown of the Rest of South America global biopesticides market into key countries
Company Information
- Detailed analyses and profiling of additional market players (up to five)
Key Questions Addressed by the Report
What is the projected size of the biopesticides market by 2030?
The global biopesticides market is projected to grow from USD 8.94 billion in 2025 to USD 17.68 billion by 2030, registering a CAGR of 14.6% during the forecast period.
What factors are driving the growth of the biopesticides market?
The growth of the biopesticides market is driven by increasing demand for organic food products, stricter regulations on chemical pesticide residues, and the rising adoption of sustainable farming methods. Farmers are also increasingly implementing integrated pest management (IPM) and precision agriculture practices, which support the use of microbial and biochemical pest control solutions.
Why are farmers adopting biopesticides in modern agriculture?
Farmers are adopting biopesticides because they provide effective pest control without leaving harmful chemical residues. These products are considered safer for the environment, human health, and beneficial organisms. They also fit well into sustainable agriculture systems and help farmers meet regulatory requirements related to pesticide residues.
Which region holds a significant share in the global biopesticides market?
Europe holds a substantial share of the global biopesticides market. The region’s growth is supported by strict regulations on chemical pesticides, strong government support for sustainable agriculture, and increasing demand for environmentally friendly crop protection products.
Who are the key players in the global biopesticides market?
Key companies operating in the biopesticides market include Corteva Agriscience (US), Valent BioSciences (US), BASF (Germany), Bayer CropScience (Germany), Syngenta Group (Switzerland), FMC Corporation (US), UPL (India), Marrone Bio Innovations (US), Certis Biologicals (US), Koppert Biological Systems (Netherlands), AgBiome (US), Novonesis (Denmark), Lallemand Plant Care (Canada), BioWorks Inc. (US), and Andermatt Group AG (Switzerland).
Fact checked
Personalize This Research
- Triangulate with your Own Data
- Get Data as per your Format and Definition
- Gain a Deeper Dive on a Specific Application, Geography, Customer or Competitor
- Any level of Personalization
Let Us Help You
- What are the Known and Unknown Adjacencies Impacting the Biopesticides Market
- What will your New Revenue Sources be?
- Who will be your Top Customer; what will make them switch?
- Defend your Market Share or Win Competitors
- Get a Scorecard for Target Partners

Custom Market Research Services
We Will Customise The Research For You, In Case The Report Listed Above Does Not Meet With Your Requirements
Get 10% Free CustomisationTESTIMONIALS

Business Innovation Director
US Based Leading Agribusiness,
Food and Ingredients ManufacturerI highly appreciate the team's efficiency for a well conducted study that helped us clarify some blind spots in food and agricultural niche markets. Although compiling information for B2B markets is very difficult, the MnM team pulled out the task successfully. The quality of research, level of insights, and responsiveness of team were commendable.
- US Biopesticides Market
- Canada Biopesticides Market
- Mexico Biopesticides Market
- France Biopesticides Market
- Germany Biopesticides Market
- Spain Biopesticides Market
- Italy Biopesticides Market
- UK Biopesticides Market
- Netherlands Biopesticides Market
- Russia Biopesticides Market
- China Biopesticides Market
- India Biopesticides Market
- Japan Biopesticides Market
- Australia Biopesticides Market
- Thailand Biopesticides Market
- Indonesia Biopesticides Market
- Brazil Biopesticides Market
- Argentina Biopesticides Market
- Chile Biopesticides Market
Growth opportunities and latent adjacency in Biopesticides Market


KORANGI
Jul, 2019
Looking for global biopesticides market and African share in consumption of biopesticides..
Giacomo
May, 2019
Want to develop an understanding regarding the global trend of Biopesticide - especially bacteria and microbials..
HyeGin
Aug, 2018
In addition to the sample report, I would like to know if you can provide the integrated table showing the market size of Beauveria Bassiana by soil treatment to berries in US..
User
Nov, 2019
Interested in the global biopesticide market.
Maitrayee
Jun, 2018
Want to know a detailed information about bio-insecticide..
Ricardo
Jun, 2019
By 2013/2014 Brazilian crop season a great amount of Dipel biospesticide was used against Helicoverpa armigera outbreaks. This represents a significant increase in Bacillus thuringiensis based biopesticides worldwide. I would like to know how important was this event to the whole biopesticide market..
David
Jan, 2019
Need information on the availability, mode of action and application of biopesticides in the UK..
David
Jan, 2019
Need information on the availability, mode of action and application of biopesticides in the UK..
Nguya
Feb, 2019
I would like to know the market outlook of microbial-based pesticides. .
MUJEEB
Nov, 2019
Looking for information regarding growth of global biopesticides market. .
Chen
Nov, 2019
Interested in the global biopesticide market.
Md
Oct, 2016
Looking for the bio pesticides (Bio-herbicides, Bio-insecticides, Bio-fungicides and others) details falong with bio pesticides list, explaining the active ingredient, doses, targeted crop, and targeted pest, mode of action, using methodology and price. .
Taufik
Sep, 2019
Interested in knowing the market potential for bio-oil from tobacco stem as biopesticide. .
Riley
Jul, 2026
Which regions are witnessing strong growth in the biopesticides market?.
Nicole
Jul, 2026
What future trends are shaping the biopesticides industry?.
Paisley
Jul, 2026
Biopesticides may not always act as quickly as chemical pesticides, but their environmental benefits are becoming increasingly important..
Emerson
Jul, 2026
Why are farmers increasingly adopting biopesticides despite slower action?.
Domenico
Jun, 2020
Very useful and interesting information. Thank you for your effort!.