Concrete Fiber Market by Type (Steel, Glass, Synthetic, Natural, Basalt), Form, Application (Slabs & Floors, Precast, Shotcrete, Pavement), End-use Industry (Building & Construction, Transport Infrastructure, Mining), and Region - Global Forecast To 2031

icon1
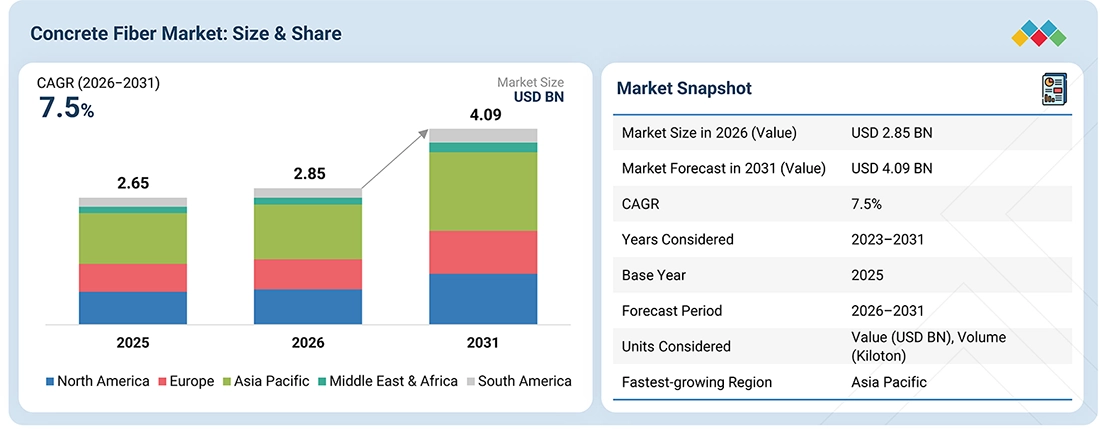
USD 4.09 BN
MARKET SIZE, 2031
icon2
CAGR 7.5%
(2026-2031)
icon3
236
REPORT PAGES
icon4
248
MARKET TABLES

OVERVIEW

concrete-fibers-market Overview

Source: Secondary Research, Interviews with Experts, MarketsandMarkets Analysis

The concrete fiber market is projected to reach USD 4.09 billion by 2031 up from USD 2.85 billion in 2026, at a CAGR of 7.5%. The market for concrete fibers is growing due to the rising demand for lasting construction materials as a result of the growing of infrastructure and urban areas all over the world. Road construction, as well as industrial buildings, tunnels, bridges, airports, and precast structures, is creating demand in the market for fibers. Rising worries about cracking, longevity, and shock resistance are pushing up the demand for concrete fiber in a big way. At the same time, labor shortages in skilled trades, the need to finish projects faster, and improvements in fiber and concrete methods are also fueling the market growth.

KEY TAKEAWAYS

  • By Region
    Asia Pacific accounted for a share of 43.6% of the concrete fiber market in 2025.
  • By Type
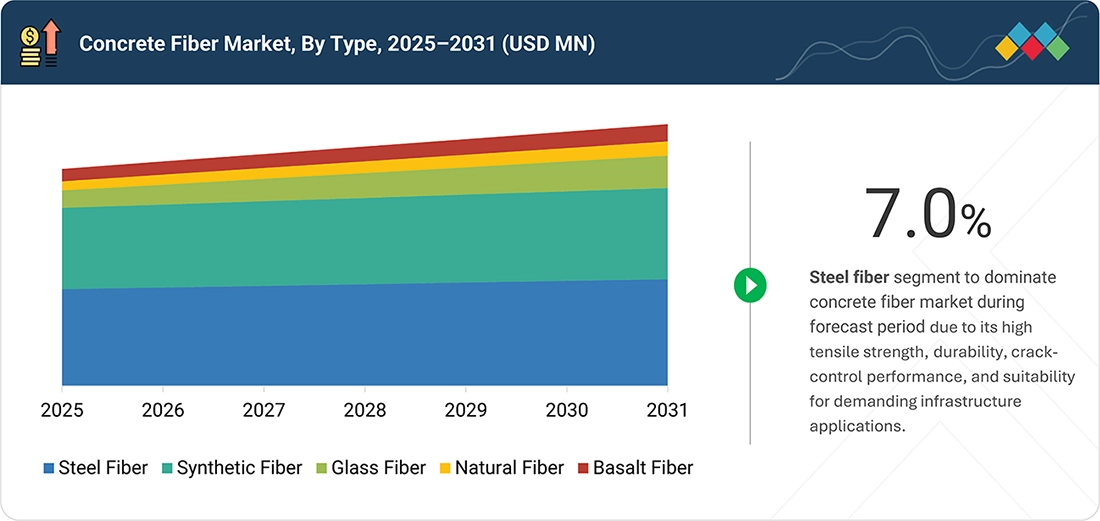
    Steel fiber held the largest share of 44.5% of the concrete fiber market, by type, in 2025.
  • By Form
    Concrete fibers in chopped form are likely to record the highest CAGR of 6.5% during the forecast period.
  • By Application
    Slabs & floors captured the largest share of the concrete fiber market, by application, in 2025.
  • By End-use Industry
    The industrial flooring industry is likely to be the fastest growing end-use industry between 2026 and 2031.
  • Competitive Landscape - Key Players
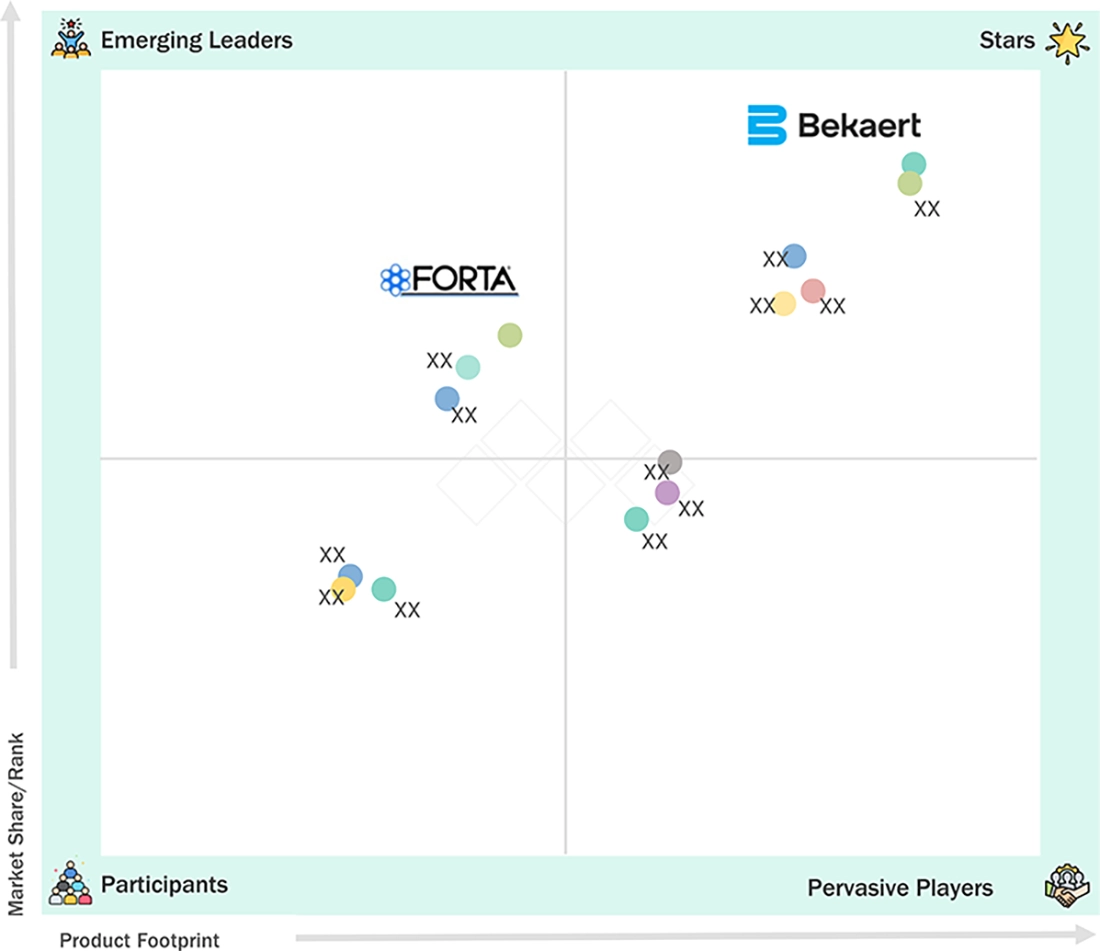
    Bekaert, Sika, and ArcelorMittal were identified as some of the star players in the concrete fiber market (global), given their strong market share and product footprint.
  • Competitive Landscape - Startups
    KrampeHarex GmbH & Co. KG; Nippon Seisen Co., Ltd.; and SPAJIC DOO have distinguished themselves among startups and SMEs by securing strong footholds in specialized niche areas.

The market for concrete fiber is experiencing significant growth, driven by the increasing demand for durable, crack-resistant, and high-performance concrete in infrastructure and construction applications. The advantages of concrete fiber include the potential for reduced reliance on conventional reinforcement, enhanced load-bearing capacity, and simplified installation processes, all of which contribute to its growing acceptance in the industry. Concurrently, the expansion of infrastructure spending, persistent labor shortages, and advancements in both synthetic and steel fiber technologies are accelerating market expansion.

TRENDS & DISRUPTIONS IMPACTING CUSTOMERS' CUSTOMERS

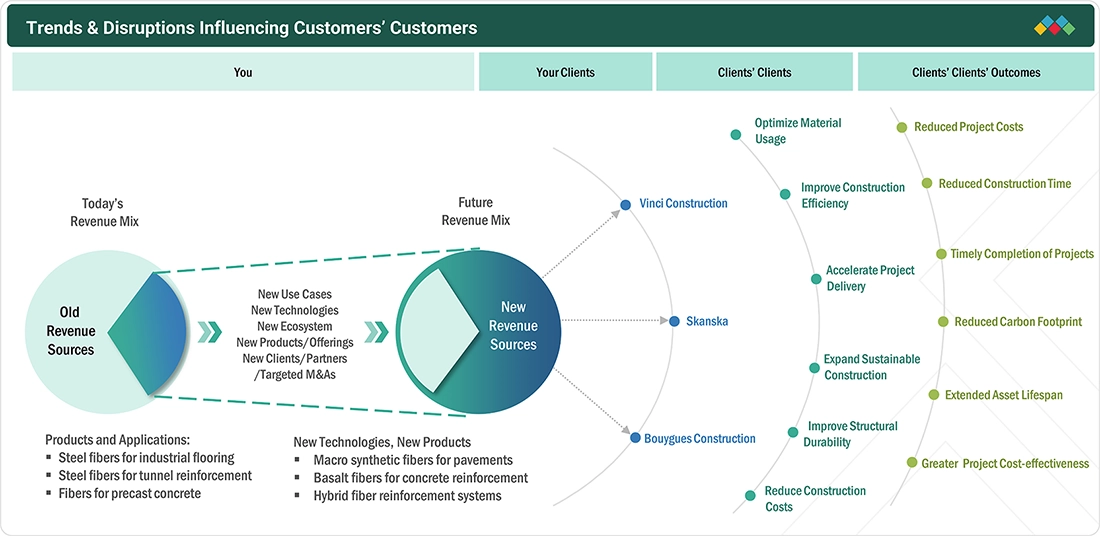
The concrete fiber market is influencing the business of major contractors such as Vinci Construction, Skanska, and Bouygues Construction. By optimizing the use of materials and increasing the efficiency of the construction process, the main contractors achieve lower project costs and shorter construction times. Furthermore, expanded sustainable construction practices and higher structural durability allow for timely completion of buildings while at the same time reducing a carbon footprint, prolonging an asset life, and maximizing project economy.

concrete-fibers-market Disruptions

Source: Secondary Research, Interviews with Experts, MarketsandMarkets Analysis

MARKET DYNAMICS

Drivers
Impact
Level
  • Increasing infrastructure development
  • Rising demand for durable and high-performance concrete
RESTRAINTS
Impact
Level
  • Volatile raw material prices
  • Higher initial cost than conventional reinforcement
OPPORTUNITIES
Impact
Level
  • Expansion of tunnel and underground construction
  • Development of sustainable and bio-based fibers
CHALLENGES
Impact
Level
  • Achieving uniform fiber dispersion
  • Meeting project-specific performance requirements

Source: Secondary Research, Interviews with Experts, MarketsandMarkets Analysis

Driver: Increasing infrastructure development

Increasing infrastructure development is driving factor in the concrete fiber market, since both government and private developers are putting money into roads, bridges, tunnels, airports, railways, and also a bunch of other projects. Concrete fibers help with crack control, they add toughness, boost impact resistance, and improve durability, so they work well for harsh structural uses. Because they can elevate concrete performance, cut down on maintenance needs, and prolong the service life, engineers and contractors are more and more willing to go with fiber-reinforced concrete for new infrastructure projects.

Restraint: Volatile raw material prices

Price volatility for steel, polymer, and other raw materials can constrain the concrete fiber market by increasing manufacturing costs and creating uncertainty around product pricing. Steel fibers are particularly exposed to fluctuations in steel prices, while synthetic fibers are influenced by changes in polymer and petrochemical feedstock costs. Persistent raw material price fluctuations can pressure manufacturers’ profit margins and increase the cost of fiber-reinforced concrete. As a result, contractors may be more hesitant to adopt fiber reinforcement in cost-sensitive projects because unpredictable material costs make project budgeting and cost management more challenging.

Opportunity: Expansion of tunnel and underground construction

Expansion of tunnel and underground construction presents a significant opportunity for the concrete fiber market, supported by rising investments in metro systems, railway tunnels, highways, and mining infrastructure worldwide. Concrete fibers are increasingly used in shotcrete and tunnel linings because they improve crack control, enhance toughness, and provide reliable post-cracking performance. As underground infrastructure development accelerates, particularly across emerging economies, demand for fiber-reinforced concrete is expected to increase as project developers seek durable and cost-efficient construction solutions.

Challenge: Achieving uniform fiber dispersion

Achieving uniform fiber dispersion remains a key challenge in the concrete fiber market because inadequate mixing can result in fiber balling, uneven distribution, and inconsistent reinforcement throughout the concrete matrix. The risk increases at higher fiber dosages and when fibers differ in length, shape, or surface characteristics. Consequently, manufacturers, ready-mix producers, and contractors must adopt appropriate mixing procedures, suitable equipment, and rigorous quality-control measures to ensure consistent fiber distribution and achieve the desired mechanical performance of fiber-reinforced concrete.

CONCRETE FIBER MARKET: COMMERCIAL USE CASES ACROSS INDUSTRIES

COMPANY USE CASE DESCRIPTION BENEFITS
company logo
Supplies Dramix steel fibers for industrial floors, precast concrete, pavements, shotcrete, tunneling, and other structural applications Improves crack control, toughness, durability, and post-cracking performance | Reduces conventional reinforcement requirements
company logo
Offers SikaFiber and Fibermesh fibers for slabs, floors, pavements, precast concrete, shotcrete, transportation infrastructure, and underground applications Controls shrinkage cracking | Improves impact and abrasion resistance | enhances durability | Reduces or replaces conventional reinforcement
company logo
Manufactures steel fibers for flooring, tunneling, shotcrete, precast, housing, and structural concrete applications Enhances ductility, crack control, toughness, and durability | Enables faster construction | Reduces conventional reinforcement requirements
company logo
Supplies Cem-FIL AR-glass fibers for concrete and cementitious applications, including GRC, precast concrete, mortars, and specialized applications Provides crack control, toughness, flexural strength, and three-dimensional reinforcement | Offers corrosion-free reinforcement and efficient dispersion

Logos and trademarks shown above are the property of their respective owners. Their use here is for informational and illustrative purposes only.

MARKET ECOSYSTEM

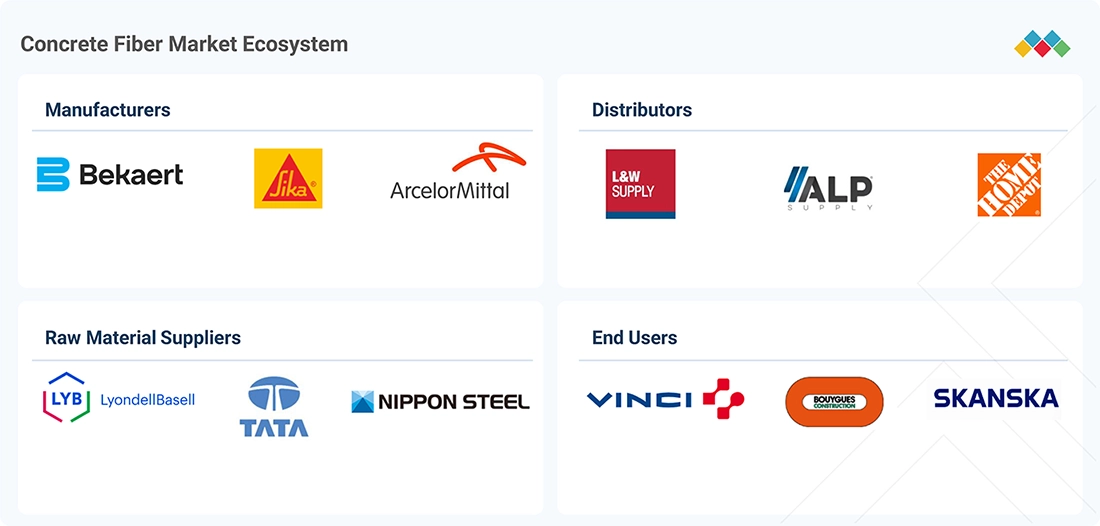
The concrete fiber ecosystem comprises raw material suppliers, manufacturers, distributors, and end users. Raw material suppliers, including Tata Steel, Nippon Steel, and LyondellBasell, provide key inputs such as steel, polypropylene, glass, and other synthetic materials. Manufacturers, including Bekaert, Sika, and ArcelorMittal, process these materials into concrete fiber products. Distributors, such as L&W Supply, ALP Supply, and The Home Depot, facilitate product availability across regional markets. End users, including construction companies, contractors, precast manufacturers, and infrastructure developers such as VINCI Construction, Skanska, and Bouygues Construction, use concrete fibers in applications including buildings, roads, bridges, tunnels, and industrial floors.

concrete-fibers-market Ecosystem

Logos and trademarks shown above are the property of their respective owners. Their use here is for informational and illustrative purposes only.

MARKET SEGMENTS

concrete-fibers-market Segments

Source: Secondary Research, Interviews with Experts, MarketsandMarkets Analysis

Concrete Fiber Market, By Type

Steel fiber holds the largest share of the concrete fiber market by type, primarily because of its high tensile strength, durability, and ability to improve concrete performance after cracking. Steel fibers are widely used in industrial flooring, tunnels, mining applications, precast components, bridges, and other heavy-duty infrastructure projects where structural performance and crack control are critical. In certain applications, steel fibers can partially or fully replace conventional reinforcement, reducing installation time and labor requirements. Their established performance in structural and infrastructure applications, broad availability from major manufacturers, and growing infrastructure development further support their adoption. In addition, increasing demand for durable and resilient construction materials is expected to sustain the growth of steel fiber applications worldwide.

Concrete Fiber Market, by Form

Chopped fibers represent the fastest-growing form in the concrete fiber market, supported by their versatility, ease of handling, and suitability for a wide range of concrete applications. Their short, discrete structure facilitates more uniform dispersion throughout the concrete matrix, improving crack control and enhancing toughness. Chopped fibers can be readily incorporated into ready-mix concrete, precast components, shotcrete, and other concrete systems without requiring complex installation processes. Their compatibility with automated batching and mixing systems also helps streamline construction and reduce labor requirements. In addition, growing adoption of chopped synthetic, steel, glass, and other fiber types across infrastructure, commercial, and residential projects is expanding their application scope. Ongoing product development focused on improving fiber–concrete bonding, durability, and reinforcement performance is further supporting market growth.

Concrete Fiber Market, by Application

Slabs and floors hold the largest share of the concrete fiber market, by application, primarily because fiber reinforcement provides effective crack control, improves toughness, and extends the service life of large concrete surfaces. Industrial warehouses, logistics centers, manufacturing facilities, parking areas, commercial buildings, and residential floors increasingly use concrete fibers to reduce reliance on conventional reinforcement systems. Fibers can also simplify installation by reducing the need for welded wire mesh and, in certain engineered applications, partially or fully replacing conventional reinforcement, thereby lowering labor and installation requirements. Continued construction of industrial and commercial facilities, particularly projects involving large floor areas exposed to heavy loads and traffic, further supports demand. In addition, fiber-reinforced slabs offer improved impact and abrasion resistance, making them well suited for demanding flooring applications and reinforcing their leading position in the market.

Concrete Fiber Market, by End-use Industry

Industrial flooring is expected to be the fastest-growing end-use industry in the concrete fiber market, driven by the expansion of warehouses, manufacturing facilities, distribution centers, logistics hubs, and industrial plants worldwide. These facilities require durable flooring systems capable of withstanding heavy loads, frequent vehicle traffic, impact, abrasion, and demanding operating conditions. Concrete fibers provide effective crack control while improving toughness, durability, and load-bearing performance, making them well suited for industrial flooring applications. The rapid growth of e-commerce and organized logistics is further increasing demand for large warehouse and distribution facilities, supporting greater adoption of fiber-reinforced concrete. In addition, fibers can simplify reinforcement installation, reduce construction time and labor requirements, and improve overall project efficiency, further strengthening their appeal for large-scale industrial flooring projects.

REGION

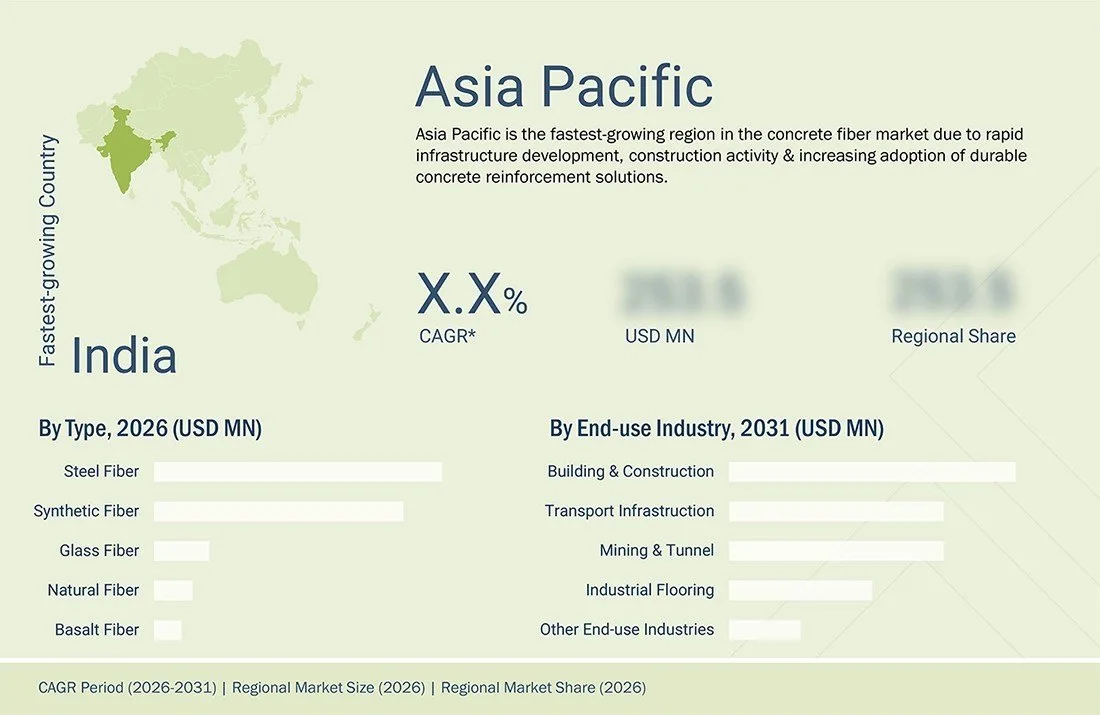
Asia Pacific to be fastest-growing region in global concrete fiber market during forecast period

Asia Pacific is expected to be the fastest-growing region in the concrete fiber market, driven by rapid urbanization, expanding infrastructure investment, and increasing construction activity across emerging economies. Rising investments in roads, bridges, tunnels, railways, airports, industrial facilities, commercial buildings, and residential projects are strengthening demand for high-performance concrete reinforcement. Countries such as India, China, Indonesia, and Vietnam are advancing transportation and industrial infrastructure, creating broader opportunities for concrete fiber adoption. In addition, the expansion of warehouses, manufacturing facilities, and residential construction is widening the application base. Growing awareness of fiber-reinforced concrete, increasing demand for durable construction materials, labor availability constraints, and improvements in local production of steel and synthetic fibers are further supporting regional market growth.

concrete-fibers-market Region

CONCRETE FIBER MARKET: COMPANY EVALUATION MATRIX

Bekaert is a leading player in the concrete fiber market, supported by its strong position in steel fiber reinforcement, established Dramix brand, broad product portfolio, technological expertise, and extensive application coverage. FORTA is an emerging leader, driven by its focus on synthetic fiber reinforcement and growing adoption of macro synthetic fibers across applications such as slabs, pavements, precast components, and shotcrete. Its market position is further supported by increasing demand for lightweight, corrosion-resistant, durable, and labor-efficient reinforcement solutions.

concrete-fibers-market Evaluation Metrics

Source: Secondary Research, Interviews with Experts, MarketsandMarkets Analysis

KEY MARKET PLAYERS

MARKET SCOPE

REPORT METRIC DETAILS
Market Size in 2025 (Value) USD 2.65 Billion
Market Size in 2026 (Value) USD 2.85 Billion
Market Forecast in 2031 (Value) USD 4.09 Billion
Growth Rate CAGR of 7.5% from 2026–2031
Years Considered 2023–2031
Base Year 2025
Forecast Period 2026–2031
Units Considered Value (USD Billion), Volume (Kiloton)
Report Coverage Revenue Forecast, Company Ranking, Competitive Landscape, Growth Factors, and Trends
Segments Covered
  • By Type:
    • Steel Fiber
    • Synthetic Fiber
    • Glass Fiber
    • Natural Fiber
    • Basalt Fiber
  • By Form:
    • Monofilament
    • Multifilament
    • Fibrillated
    • Chopped
    • Other Forms
  • By Application:
    • Slabs & Floors
    • Precast Concrete
    • Shotcrete
    • Pavements
    • Other Applications
  • By End-use industry:
    • Transport Infrastructure
    • Building & Construction
    • Mining & Tunnel
    • Industrial Flooring
    • Other End-Use Industries
Regions Covered North America, Asia Pacific, Europe, South America, and Middle East & Africa

WHAT IS IN IT FOR YOU: CONCRETE FIBER MARKET REPORT CONTENT GUIDE

concrete-fibers-market Content Guide

DELIVERED CUSTOMIZATIONS

We have successfully delivered the following deep-dive customizations:

CLIENT REQUEST CUSTOMIZATION DELIVERED VALUE ADDS
Concrete Fiber Manufacturers Competitive benchmarking of concrete fiber grades, production capacities, product portfolios, technology adoption, pricing trends, & regional demand across applications Support product portfolio optimization, identify growth opportunities, strengthen competitive positioning, & improve strategic planning
Distributors & Channel Partners Regional demand analysis, supplier comparison, inventory planning, & end-user purchasing trends by fiber type, application, & geography Optimize product sourcing, improve inventory management, expand customer reach, & increase sales opportunities
Raw Material Suppliers Assessment of raw material demand by fiber type, customer requirements, manufacturing trends, & regional consumption patterns Identify growth segments, strengthen partnerships, & optimize production
Contractors & Engineering Firms Fiber selection analysis based on applications, specifications, & project requirements Improve fiber selection, reduce costs, & enhance project performance
Infrastructure, Mining & Industrial Flooring Companies Comparison of fiber solutions based on durability, performance, installation, & lifecycle costs Improve durability, reduce maintenance, & enhance operational efficiency

RECENT DEVELOPMENTS

  • January 2026 : Bekaert launched Dramix Loop, a sustainable steel fiber made from high-grade steel recovered from end-of-life tire cords. With this launch, Bekaert strengthened its position in circular concrete reinforcement, expanding the circular product line and also responding to the rising demand for low-carbon building solutions. In the end, it helped the company to differentiate its Dramix range, support customers' ESG ambitions, and focus on applications that are looking for reduced-carbon reinforcement materials.
  • November 2025 : Bekaert partnered with EMSTEEL, a UAE-based steel and building materials manufacturer, to develop high-performance, sustainable construction products using locally produced steel. As part of the partnership, Bekaert planned to manufacture Dramix steel fiber-reinforced concrete solutions using UAE-produced steel, reducing reliance on imported materials. The collaboration strengthened Bekaert’s presence across the GCC, expanded its portfolio of lower-carbon construction solutions, and addressed growing demand for locally sourced and more sustainable building materials.
  • May 2023 : Sika expanded its concrete fiber production capacity at its Chattanooga, Tennessee, facility by adding a new packaging and extrusion line. The expansion increased production capacity to up to 4 million pounds, enabling Sika to meet growing customer demand while improving manufacturing efficiency. The new extrusion line is approximately 30% more energy-efficient than existing lines, helping reduce energy consumption and the facility’s carbon footprint.

Table of Contents

checkmarkExclusive indicates content/data unique to MarketsandMarkets and not available with any competitors.

TITLE
PAGE NO
1
INTRODUCTION


27
2
EXECUTIVE SUMMARY


30
3
PREMIUM INSIGHTS


35
4
MARKET OVERVIEW
Rising infrastructure investment and sustainable fibers drive high-performance concrete demand amidst cost challenges.


38
 
4.1
INTRODUCTION


4.2
MARKET DYNAMICS


4.2.1
DRIVERS


4.2.1.1
RISING INVESTMENT IN INFRASTRUCTURE AND CONSTRUCTION


4.2.1.2
GROWING DEMAND FOR HIGH-PERFORMANCE CONCRETE


4.2.1.3
INCREASING ADOPTION IN INDUSTRIAL FLOORS AND SLABS


4.2.2
RESTRAINTS


4.2.2.1
VOLATILITY IN RAW MATERIAL PRICES


4.2.2.2
HIGH INITIAL MATERIAL COST


4.2.3
OPPORTUNITIES


4.2.3.1
EXPANSION OF TUNNEL AND UNDERGROUND CONSTRUCTION


4.2.3.2
DEVELOPMENT OF SUSTAINABLE AND BIO-BASED FIBERS


4.2.4
CHALLENGES


4.2.4.1
ACHIEVING UNIFORM FIBER DISPERSION


4.2.4.2
MEETING PROJECT-SPECIFIC PERFORMANCE REQUIREMENTS


4.3
UNMET NEEDS AND WHITE SPACES


4.3.1
UNMET NEEDS IN CONCRETE FIBER MARKET


4.3.2
WHITE SPACE OPPORTUNITIES


4.4
INTERCONNECTED MARKETS AND CROSS-SECTOR OPPORTUNITIES


4.4.1
INTERCONNECTED MARKETS


4.4.2
CROSS-SECTOR OPPORTUNITIES


4.5
EMERGING BUSINESS MODELS AND ECOSYSTEM SHIFTS


4.5.1
EMERGING BUSINESS MODELS


4.5.2
ECOSYSTEM SHIFTS


4.6
STRATEGIC MOVES BY TIER 1/2/3 PLAYERS


4.6.1
KEY MOVES AND STRATEGIC FOCUS


4.7
PORTER’S FIVE FORCES ANALYSIS


4.7.1
THREAT OF NEW ENTRANTS


4.7.2
THREAT OF SUBSTITUTES


4.7.3
BARGAINING POWER OF SUPPLIERS


4.7.4
BARGAINING POWER OF BUYERS


4.7.5
INTENSITY OF COMPETITIVE RIVALRY


4.8
VALUE CHAIN ANALYSIS


4.8.1
RAW MATERIAL SUPPLIERS


4.8.2
MANUFACTURERS


4.8.3
DISTRIBUTORS


4.8.4
END USERS


4.9
ECOSYSTEM ANALYSIS


4.10
PRICING ANALYSIS


4.10.1
AVERAGE SELLING PRICE, BY REGION


4.10.2
AVERAGE SELLING PRICE, BY KEY PLAYERS


4.10.3
AVERAGE SELLING PRICE, BY TYPE


4.11
MACROECONOMIC INDICATORS


4.11.1
GLOBAL GDP TRENDS


4.12
IMPACT OF 2025 US TARIFFS ON CONCRETE FIBER MARKET


4.12.1
INTRODUCTION


4.12.2
KEY TARIFF RATES


4.12.3
PRICE IMPACT ANALYSIS


4.12.4
IMPACT ON COUNTRIES/REGIONS


4.12.4.1
NORTH AMERICA


4.12.4.2
EUROPE


4.12.4.3
ASIA PACIFIC


4.12.5
IMPACT ON END-USE INDUSTRIES


4.13
TRADE ANALYSIS


4.13.1
IMPORT SCENARIO (HS CODE 732690)


4.13.2
EXPORT SCENARIO (HS CODE 732690)


4.14
TRENDS/DISRUPTIONS IMPACTING CUSTOMER BUSINESS


4.15
INVESTMENT AND FUNDING SCENARIO


4.16
CASE STUDY ANALYSIS


4.16.1
SIKAFIBER PP-940/50 FOR INDUSTRIAL FLOORING AT ASPROKAT S.A.


4.16.2
BASALT FIBER REINFORCEMENT FOR AIRPORT RUNWAY PAVEMENT


4.17
KEY CONFERENCES & EVENTS


5
TECHNOLOGICAL ADVANCEMENTS, AI-DRIVEN IMPACT, PATENTS, INNOVATIONS, AND FUTURE APPLICATIONS
AI-driven advancements revolutionize concrete fiber technology, unlocking sustainable, automated, and high-performance construction solutions.


65
 
5.1
TECHNOLOGY ANALYSIS


5.1.1
KEY TECHNOLOGIES


5.1.1.1
ADVANCED FIBER ENGINEERING


5.1.1.2
HYBRID FIBER REINFORCEMENT


5.1.2
COMPLEMENTARY TECHNOLOGIES


5.1.2.1
AUTOMATED FIBER DOSING


5.1.2.2
CONCRETE RHEOLOGY CONTROL


5.1.3
ADJACENT TECHNOLOGIES


5.1.3.1
3D CONCRETE PRINTING


5.1.3.2
ROBOTIC SHOTCRETE SYSTEMS


5.2
TECHNOLOGY/PRODUCT ROADMAP


5.2.1
SHORT-TERM (2026–2027) | FOUNDATION & EARLY COMMERCIALIZATION


5.2.2
MID-TERM (2027–2030) | EXPANSION & STANDARDIZATION


5.2.3
LONG-TERM (2030–2035+) | MASS COMMERCIALIZATION & DISRUPTION


5.3
PATENT ANALYSIS


5.3.1
LEGAL STATUS OF PATENTS


5.3.2
JURISDICTION ANALYSIS


5.4
FUTURE APPLICATIONS


5.4.1
3D-PRINTED CONCRETE BUILDING STRUCTURES


5.4.2
SMART REINFORCED INFRASTRUCTURE SYSTEMS


5.4.3
LOW-CARBON CONCRETE CONSTRUCTION PROJECTS


5.4.4
ROBOTIC SHOTCRETE CONSTRUCTION APPLICATIONS


5.4.5
HIGH-PERFORMANCE PRECAST CONCRETE COMPONENTS


5.5
IMPACT OF AI/GENERATIVE AI ON CONCRETE FIBER MARKET


5.5.1
TOP USE CASES AND MARKET POTENTIAL


5.5.2
BEST PRACTICES IN CONCRETE FIBER PROCESSING


5.5.3
CASE STUDIES OF AI IMPLEMENTATION IN CONCRETE FIBER MARKET


5.5.4
INTERCONNECTED ADJACENT ECOSYSTEM AND IMPACT ON MARKET PLAYERS


5.5.5
CLIENTS’ READINESS TO ADOPT GENERATIVE AI IN CONCRETE FIBER MARKET


6
REGULATORY LANDSCAPE AND SUSTAINABILITY INITIATIVES
Navigate complex regulations and eco-standards to harness sustainability in concrete fiber markets.


78
 
6.1
REGIONAL REGULATIONS AND COMPLIANCE


6.1.1
REGULATORY BODIES, GOVERNMENT AGENCIES, AND OTHER ORGANIZATIONS


6.1.2
INDUSTRY STANDARDS


6.2
SUSTAINABILITY INITIATIVES


6.3
IMPACT OF REGULATORY POLICIES AND SUSTAINABILITY INITIATIVES


6.4
CERTIFICATIONS, LABELING, AND ECO-STANDARDS


7
CUSTOMER LANDSCAPE & BUYER BEHAVIOR
Unlock market profitability by addressing unmet needs and optimizing stakeholder influence in buying processes.


87
 
7.1
INTRODUCTION


7.2
DECISION-MAKING PROCESS


7.3
KEY STAKEHOLDERS AND BUYING CRITERIA


7.3.1
KEY STAKEHOLDERS IN BUYING PROCESS


7.3.2
BUYING CRITERIA


7.4
ADOPTION BARRIERS & INTERNAL CHALLENGES


7.5
UNMET NEEDS IN VARIOUS END-USE INDUSTRIES


7.6
MARKET PROFITABILITY


7.6.1
REVENUE POTENTIAL


7.6.2
COST DYNAMICS


7.6.3
MARGIN OPPORTUNITIES IN KEY END-USE SECTORS


8
CONCRETE FIBER MARKET, BY FORM
Market Size & Growth Rate Forecast Analysis to 2031 in USD Million and Kilotons | 4 Data Tables


93
 
8.1
INTRODUCTION


8.2
MONOFILAMENT


8.2.1
SUPPORTS CRACK CONTROL, DURABILITY, AND CORROSION-FREE REINFORCEMENT IN CONCRETE APPLICATIONS


8.3
MULTIFILAMENT


8.3.1
ENABLES WIDESPREAD MICRO-REINFORCEMENT AND IMPROVES CONCRETE COHESIVENESS DURING CURING


8.4
FIBRILLATED


8.4.1
ENHANCES MECHANICAL INTERLOCKING AND MAINTAINS REINFORCEMENT DISTRIBUTION WITHIN CONCRETE


8.5
CHOPPED


8.5.1
PROVIDES CONVENIENT, STANDARDIZED, AND APPLICATION-SPECIFIC DISTRIBUTED REINFORCEMENT


8.6
OTHER FORMS


9
CONCRETE FIBER MARKET, BY TYPE
Market Size & Growth Rate Forecast Analysis to 2031 in USD Million and Kilotons | 4 Data Tables


99
 
9.1
INTRODUCTION


9.2
STEEL FIBER


9.2.1
EXTENSIVE ADOPTION IN INDUSTRIAL FLOORS, TUNNELS, AND PAVEMENTS TO DRIVE MARKET


9.3
SYNTHETIC FIBER


9.3.1
LIGHTWEIGHT, CORROSION-RESISTANT, EASY TO HANDLE, AND EXCELLENT CRACK-CONTROL PROPERTIES TO DRIVE MARKET


9.4
GLASS FIBER


9.4.1
DEMAND FOR LIGHTWEIGHT AND ARCHITECTURAL CONCRETE TO FUEL MARKET GROWTH


9.5
NATURAL FIBER


9.5.1
GROWING DEMAND FOR LOW-IMPACT CONSTRUCTION MATERIALS TO SUPPORT MARKET


9.6
BASALT FIBER


9.6.1
ADOPTION IN CORROSION-PRONE INFRASTRUCTURE TO DRIVE DEMAND


10
CONCRETE FIBER MARKET, BY APPLICATION
Market Size & Growth Rate Forecast Analysis to 2031 in USD Million and Kilotons | 4 Data Tables


106
 
10.1
INTRODUCTION


10.2
SLABS & FLOORS


10.2.1
STRENGTHENS LARGE-AREA CONCRETE SURFACES AGAINST CRACKING, HEAVY LOADS & REPEATED TRAFFIC


10.3
PRECAST CONCRETE


10.3.1
STREAMLINES FACTORY PRODUCTION THROUGH CONSISTENT REINFORCEMENT, FASTER DEMOLDING & EASIER HANDLING


10.4
SHOTCRETE


10.4.1
PROVIDES RAPID, DISTRIBUTED REINFORCEMENT FOR TUNNELING, MINING & UNDERGROUND STRUCTURAL SUPPORT


10.5
PAVEMENTS


10.5.1
IMPROVES PAVEMENT TOUGHNESS, CRACK RESISTANCE & DURABILITY UNDER REPEATED LOADING AND ENVIRONMENTAL EXPOSURE


10.6
OTHER APPLICATIONS


11
CONCRETE FIBER MARKET, BY END-USE INDUSTRY
Market Size & Growth Rate Forecast Analysis to 2031 in USD Million and Kilotons | 4 Data Tables


112
 
11.1
INTRODUCTION


11.2
TRANSPORT INFRASTRUCTURE


11.2.1
IMPROVES CONCRETE DURABILITY UNDER REPEATED TRAFFIC, LOADING & ENVIRONMENTAL EXPOSURE


11.3
BUILDING & CONSTRUCTION


11.3.1
ENHANCES CRACK CONTROL, DURABILITY & CONSTRUCTION EFFICIENCY ACROSS DIVERSE STRUCTURES


11.4
MINING & TUNNEL


11.4.1
PROVIDES HIGH-TOUGHNESS REINFORCEMENT FOR DEMANDING UNDERGROUND CONSTRUCTION & STABILIZATION


11.5
INDUSTRIAL FLOORING


11.5.1
DELIVERS DURABLE FLOORS FOR CONTINUOUS TRAFFIC, EQUIPMENT MOVEMENT & MECHANICAL STRESSES


11.6
OTHER END-USE INDUSTRIES


12
CONCRETE FIBER MARKET, BY REGION
Comprehensive coverage of 8 Regions with country-level deep-dive of 17 Countries | 192 Data Tables.


118
 
12.1
INTRODUCTION


12.2
ASIA PACIFIC


12.2.1
CHINA


12.2.1.1
SHIELD TUNNELING & PRECAST PRODUCTION DRIVE HIGH-VOLUME FIBER CONSUMPTION


12.2.2
INDIA


12.2.2.1
EXPRESSWAY DEVELOPMENT & EXPANDING NATIONAL HIGHWAY NETWORK ACCELERATING FIBER ADOPTION


12.2.3
JAPAN


12.2.3.1
DEMAND FOR ULTRA-HIGH-PERFORMANCE CONCRETE & STRUCTURAL REHABILITATION TO DRIVE MARKET


12.2.4
SOUTH KOREA


12.2.4.1
RISING DEMAND FOR TUNNEL ENGINEERING & PERFORMANCE TESTING TO DRIVE MARKET


12.2.5
REST OF ASIA PACIFIC


12.3
EUROPE


12.3.1
GERMANY


12.3.1.1
INFRASTRUCTURE RENEWAL FUND ACCELERATING FIBER ADOPTION IN BRIDGES & RAIL ASSETS


12.3.2
UK


12.3.2.1
RISING FOCUS ON STRUCTURAL EFFICIENCY, RESOURCE OPTIMIZATION, AND LOW-CARBON CONSTRUCTION TO DRIVE MARKET


12.3.3
FRANCE


12.3.3.1
UHPFRC EXPERTISE DRIVING HIGH-PERFORMANCE FIBER APPLICATIONS IN STRUCTURAL REHABILITATION


12.3.4
ITALY


12.3.4.1
TUNNEL & SEISMIC INFRASTRUCTURE DEVELOPMENT CREATING DEMAND FOR HIGH-TOUGHNESS FIBER SYSTEMS


12.3.5
SPAIN


12.3.5.1
DEVELOPMENT OF HIGH-SPEED RAIL, TRANSPORT INFRASTRUCTURE, AND PRECAST CONSTRUCTION TO DRIVE MARKET


12.3.6
REST OF EUROPE


12.4
NORTH AMERICA


12.4.1
US


12.4.1.1
RISING FEDERAL INFRASTRUCTURE INVESTMENT FUELING DEMAND


12.4.2
CANADA


12.4.2.1
DEMAND IN LONG-LIFE TRANSPORTATION ASSETS TO DRIVE MARKET GROWTH


12.4.3
MEXICO


12.4.3.1
EXPANSION OF UNDERGROUND MINING & TUNNEL CONSTRUCTION FUELING DEMAND FOR FIBER-REINFORCED SHOTCRETE


12.5
MIDDLE EAST & AFRICA


12.5.1
GCC COUNTRIES


12.5.1.1
SAUDI ARABIA


12.5.1.1.1
VISION 2030 MEGA-PROJECTS EXPANDING FIBER DEMAND ACROSS LARGE-SCALE CONCRETE INFRASTRUCTURE


12.5.1.2
UAE


12.5.1.2.1
METRO, HIGH-RISE & BRIDGE CONSTRUCTION FUELING FIBER APPLICATIONS


12.5.1.3
REST OF GCC COUNTRIES


12.5.2
SOUTH AFRICA


12.5.2.1
ROAD REHABILITATION & UNDERGROUND MINING CREATING DEMAND FOR STRUCTURAL & SHOTCRETE FIBERS


12.5.3
REST OF MIDDLE EAST & AFRICA


12.6
SOUTH AMERICA


12.6.1
BRAZIL


12.6.1.1
DEMAND ACROSS URBAN MOBILITY, SANITATION & NATIONWIDE INFRASTRUCTURE PROJECTS TO DRIVE MARKET


12.6.2
ARGENTINA


12.6.2.1
GRID EXPANSION & VACA MUERTA DEVELOPMENT OPENING MARKET OPPORTUNITIES IN HEAVY-DUTY INDUSTRIAL CONSTRUCTION


12.6.3
REST OF SOUTH AMERICA


13
COMPETITIVE LANDSCAPE
Explore strategic moves and market dominance of key players shaping industry dynamics.


197
 
13.1
INTRODUCTION


13.2
KEY PLAYERS’ STRATEGIES/RIGHT TO WIN, 2023–2026


13.3
REVENUE ANALYSIS, 2023–2025


13.4
MARKET SHARE ANALYSIS, 2025


13.4.1
BEKAERT


13.4.2
ARCELORMITTAL


13.4.3
SIKA


13.4.4
OWENS CORNING


13.4.5
CEMEX S.A.B. DE C.V.


13.5
COMPANY VALUATION AND FINANCIAL METRICS


13.6
BRAND/PRODUCT COMPARISON


13.7
COMPANY EVALUATION MATRIX: KEY PLAYERS, 2025


13.7.1
STARS


13.7.2
EMERGING LEADERS


13.7.3
PERVASIVE PLAYERS


13.7.4
PARTICIPANTS


13.7.5
COMPANY FOOTPRINT: KEY PLAYERS, 2025


13.7.5.1
COMPANY FOOTPRINT


13.7.5.2
REGION FOOTPRINT


13.7.5.3
TYPE FOOTPRINT


13.7.5.4
FORM FOOTPRINT


13.7.5.5
APPLICATION FOOTPRINT


13.7.5.6
END-USE INDUSTRY FOOTPRINT


13.8
COMPANY EVALUATION MATRIX: STARTUPS/SMES, 2025


13.8.1
PROGRESSIVE COMPANIES


13.8.2
RESPONSIVE COMPANIES


13.8.3
DYNAMIC COMPANIES


13.8.4
STARTING BLOCKS


13.8.5
COMPETITIVE BENCHMARKING: STARTUPS/SMES, 2025


13.8.5.1
DETAILED LIST OF KEY STARTUPS/SMES


13.8.5.2
COMPETITIVE BENCHMARKING OF KEY STARTUPS/SMES


13.9
COMPETITIVE SCENARIO


13.9.1
PRODUCT LAUNCHES


13.9.2
DEALS


13.9.3
EXPANSIONS


14
COMPANY PROFILES
In-depth Company Profiles of Leading Market Players with detailed Business Overview, Product and Service Portfolio, Recent Developments, and Unique Analyst Perspective (MnM View)


219
 
14.1
KEY PLAYERS


14.1.1
BEKAERT


14.1.1.1
BUSINESS OVERVIEW


14.1.1.2
PRODUCTS/SOLUTIONS/SERVICES OFFERED


14.1.1.3
RECENT DEVELOPMENTS


14.1.1.3.1
PRODUCT LAUNCHES


14.1.1.3.2
DEALS


14.1.1.3.3
EXPANSIONS


14.1.1.4
MNM VIEW


14.1.1.4.1
RIGHT TO WIN


14.1.1.4.2
STRATEGIC CHOICES


14.1.1.4.3
WEAKNESSES AND COMPETITIVE THREATS


14.1.2
SIKA


14.1.3
OWENS CORNING


14.1.4
CEMEX, S.A.B. DE C.V.


14.1.5
ABC POLYMER INDUSTRIES, LLC


14.1.6
FORTA


14.1.7
THE EUCLID CHEMICAL COMPANY


14.1.8
BARCHIP PTY LTD.


14.1.9
NYCON


14.1.10
FIBERCON INTERNATIONAL INC.


14.1.11
ARCELORMITTAL


14.1.12
CHRYSO


14.2
OTHER PLAYERS


14.2.1
KRAMPEHAREX GMBH & CO. KG


14.2.2
MASTER BUILDERS SOLUTIONS


14.2.3
NIPPON SEISEN CO., LTD.


14.2.4
SPAJIC DOO


14.2.5
CREAFILL


14.2.6
MINIFIBERS, INC.


14.2.7
HUNAN SUNSHINE STEEL FIBER CO., LTD.


14.2.8
KOSTEEL CO., LTD.


14.2.9
GANZHOU DAYE METAL FIBER CO., LTD.


14.2.10
TENGZHOU STAR SMITH METAL PRODUCTS CO., LTD.


14.2.11
BILSTEIN STEEL FIBER GMBH


14.2.12
KALYANI


14.2.13
NUOVAFIL INFOTECK PVT LTD.


15
RESEARCH METHODOLOGY


287
 
15.1
RESEARCH DATA


15.1.1
SECONDARY DATA


15.1.1.1
LIST OF SECONDARY SOURCES


15.1.1.2
KEY DATA FROM SECONDARY SOURCES


15.1.2
PRIMARY DATA


15.1.2.1
LIST OF PRIMARY INTERVIEW PARTICIPANTS—DEMAND AND SUPPLY SIDES


15.1.2.2
KEY DATA FROM PRIMARY SOURCES


15.1.2.3
BREAKDOWN OF PRIMARY INTERVIEWS


15.1.2.4
INSIGHTS FROM INDUSTRY EXPERTS


15.2
MARKET SIZE ESTIMATION


15.2.1
BOTTOM-UP APPROACH


15.2.2
TOP-DOWN APPROACH


15.3
FORECAST NUMBER CALCULATION


15.4
DATA TRIANGULATION


15.5
FACTOR ANALYSIS


15.6
RESEARCH ASSUMPTIONS


15.7
RESEARCH LIMITATIONS AND RISK ASSESSMENT


16
APPENDIX


296
 
16.1
DISCUSSION GUIDE


16.2
KNOWLEDGESTORE: MARKETSANDMARKETS’ SUBSCRIPTION PORTAL


16.3
CUSTOMIZATION OPTIONS


16.4
RELATED REPORTS


16.5
AUTHOR DETAILS


LIST OF TABLES


TABLE 1
CONCRETE FIBER MARKET: IMPACT OF PORTER’S FIVE FORCES


TABLE 2
CONCRETE FIBER MARKET: ROLE OF COMPANIES IN ECOSYSTEM


TABLE 3
AVERAGE SELLING PRICE TREND OF CONCRETE FIBER, BY REGION, 2023–2025 (USD/KG)


TABLE 4
AVERAGE SELLING PRICE RANGE OF CONCRETE FIBER IN MAJOR END-USE INDUSTRY, BY KEY PLAYERS, 2025 (USD/KG)


TABLE 5
AVERAGE SELLING PRICE TREND OF CONCRETE FIBER, BY TYPE, 2023–2025 (USD/KG)


TABLE 6
PROJECTED REAL GDP GROWTH (ANNUAL PERCENT CHANGE) OF KEY COUNTRIES, 2021–2030


TABLE 7
US-ADJUSTED RECIPROCAL TARIFF RATES


TABLE 8
IMPORT SCENARIO FOR HS CODE 732690-COMPLIANT PRODUCTS, BY COUNTRY, 2021–2025 (USD MILLION)


TABLE 9
EXPORT SCENARIO FOR HS CODE 732690-COMPLIANT PRODUCTS, BY COUNTRY, 2021–2025 (USD MILLION)


TABLE 10
CONCRETE FIBER MARKET: CONFERENCES & EVENTS, 2026–2027


TABLE 11
TOP USE CASES AND MARKET POTENTIAL


TABLE 12
BEST PRACTICES: NOTABLE INDUSTRY PRACTICES BY LEADING COMPANIES


TABLE 13
CONCRETE FIBER MARKET: CASE STUDIES RELATED TO AI IMPLEMENTATION


TABLE 14
INTERCONNECTED ADJACENT ECOSYSTEM AND IMPACT ON MARKET PLAYERS


TABLE 15
NORTH AMERICA: LIST OF REGULATORY BODIES, GOVERNMENT AGENCIES, AND OTHER ORGANIZATIONS


TABLE 16
ASIA PACIFIC: LIST OF REGULATORY BODIES, GOVERNMENT AGENCIES, AND OTHER ORGANIZATIONS


TABLE 17
EUROPE: LIST OF REGULATORY BODIES, GOVERNMENT AGENCIES, AND OTHER ORGANIZATIONS


TABLE 18
MIDDLE EAST & AFRICA: LIST OF REGULATORY BODIES, GOVERNMENT AGENCIES, AND OTHER ORGANIZATIONS


TABLE 19
SOUTH AMERICA: LIST OF REGULATORY BODIES, GOVERNMENT AGENCIES, AND OTHER ORGANIZATIONS


TABLE 20
GLOBAL STANDARDS IN CONCRETE FIBER MARKET


TABLE 21
CERTIFICATIONS, LABELING, AND ECO-STANDARDS IN CONCRETE FIBER MARKET


TABLE 22
INFLUENCE OF STAKEHOLDERS ON BUYING PROCESS FOR KEY APPLICATIONS (%)


TABLE 23
KEY BUYING CRITERIA FOR KEY APPLICATIONS


TABLE 24
CONCRETE FIBER MARKET: UNMET NEEDS IN KEY END-USE SECTORS


TABLE 25
CONCRETE FIBER MARKET, BY FORM, 2023–2025 (USD MILLION)


TABLE 26
CONCRETE FIBER MARKET, BY FORM, 2026–2031 (USD MILLION)


TABLE 27
CONCRETE FIBER MARKET, BY FORM, 2023–2025 (KILOTON)


TABLE 28
CONCRETE FIBER MARKET, BY FORM, 2026–2031 (KILOTON)


TABLE 29
CONCRETE FIBER MARKET, BY TYPE, 2023–2025 (USD MILLION)


TABLE 30
CONCRETE FIBER MARKET, BY TYPE, 2026–2031 (USD MILLION)


TABLE 31
CONCRETE FIBER MARKET, BY TYPE, 2023–2025 (KILOTON)


TABLE 32
CONCRETE FIBER MARKET, BY TYPE, 2026–2031 (KILOTON)


TABLE 33
CONCRETE FIBER MARKET, BY APPLICATION, 2023–2025 (USD MILLION)


TABLE 34
CONCRETE FIBER MARKET, BY APPLICATION, 2026–2031 (USD MILLION)


TABLE 35
CONCRETE FIBER MARKET, BY APPLICATION, 2023–2025 (KILOTON)


TABLE 36
CONCRETE FIBER MARKET, BY APPLICATION, 2026–2031 (KILOTON)


TABLE 37
CONCRETE FIBER MARKET, BY END-USE INDUSTRY, 2023–2025 (USD MILLION)


TABLE 38
CONCRETE FIBER MARKET, BY END-USE INDUSTRY, 2026–2031 (USD MILLION)


TABLE 39
CONCRETE FIBER MARKET, BY END-USE INDUSTRY, 2023–2025 (KILOTON)


TABLE 40
CONCRETE FIBER MARKET, BY END-USE INDUSTRY, 2026–2031 (KILOTON)


TABLE 41
CONCRETE FIBER MARKET SIZE, BY REGION, 2023–2025 (USD MILLION)


TABLE 42
CONCRETE FIBER MARKET SIZE, BY REGION, 2026–2031 (USD MILLION)


TABLE 43
CONCRETE FIBER MARKET SIZE, BY REGION, 2023–2025 (KILOTON)


TABLE 44
CONCRETE FIBER MARKET SIZE, BY REGION, 2026–2031 (KILOTON)


TABLE 45
ASIA PACIFIC: CONCRETE FIBER MARKET SIZE, BY COUNTRY, 2023–2025 (USD MILLION)


TABLE 46
ASIA PACIFIC: CONCRETE FIBER MARKET SIZE, BY COUNTRY, 2026–2031 (USD MILLION)


TABLE 47
ASIA PACIFIC: CONCRETE FIBER MARKET SIZE, BY COUNTRY, 2023–2025 (KILOTON)


TABLE 48
ASIA PACIFIC: CONCRETE FIBER MARKET SIZE, BY COUNTRY, 2026–2031 (KILOTON)


TABLE 49
ASIA PACIFIC: CONCRETE FIBER MARKET SIZE, BY TYPE, 2023–2025 (USD MILLION)


TABLE 50
ASIA PACIFIC: CONCRETE FIBER MARKET SIZE, BY TYPE, 2026–2031 (USD MILLION)


TABLE 51
ASIA PACIFIC: CONCRETE FIBER MARKET SIZE, BY TYPE, 2023–2025 (KILOTON)


TABLE 52
ASIA PACIFIC: CONCRETE FIBER MARKET SIZE, BY TYPE, 2026–2031 (KILOTON)


TABLE 53
ASIA PACIFIC: CONCRETE FIBER MARKET SIZE, BY FORM, 2023–2025 (USD MILLION)


TABLE 54
ASIA PACIFIC: CONCRETE FIBER MARKET SIZE, BY FORM, 2026–2031 (USD MILLION)


TABLE 55
ASIA PACIFIC: CONCRETE FIBER MARKET SIZE, BY FORM, 2023–2025 (KILOTON)


TABLE 56
ASIA PACIFIC: CONCRETE FIBER MARKET SIZE, BY FORM, 2026–2031 (KILOTON)


TABLE 57
ASIA PACIFIC: CONCRETE FIBER MARKET SIZE, BY APPLICATION, 2023–2025 (USD MILLION)


TABLE 58
ASIA PACIFIC: CONCRETE FIBER MARKET SIZE, BY APPLICATION, 2026–2031 (USD MILLION)


TABLE 59
ASIA PACIFIC: CONCRETE FIBER MARKET SIZE, BY APPLICATION, 2023–2025 (KILOTON)


TABLE 60
ASIA PACIFIC: CONCRETE FIBER MARKET SIZE, BY APPLICATION, 2026–2031 (KILOTON)


TABLE 61
ASIA PACIFIC: CONCRETE FIBER MARKET SIZE, BY END-USE INDUSTRY, 2023–2025 (USD MILLION)


TABLE 62
ASIA PACIFIC: CONCRETE FIBER MARKET SIZE, BY END-USE INDUSTRY, 2026–2031 (USD MILLION)


TABLE 63
ASIA PACIFIC: CONCRETE FIBER MARKET SIZE, BY END-USE INDUSTRY, 2023–2025 (KILOTON)


TABLE 64
ASIA PACIFIC: CONCRETE FIBER MARKET SIZE, BY END-USE INDUSTRY, 2026–2031 (KILOTON)


TABLE 65
CHINA: CONCRETE FIBER MARKET SIZE, BY END-USE INDUSTRY, 2023–2025 (USD MILLION)


TABLE 66
CHINA: CONCRETE FIBER MARKET SIZE, BY END-USE INDUSTRY, 2026–2031 (USD MILLION)


TABLE 67
CHINA: CONCRETE FIBER MARKET SIZE, BY END-USE INDUSTRY, 2023–2025 (KILOTON)


TABLE 68
CHINA: CONCRETE FIBER MARKET SIZE, BY END-USE INDUSTRY, 2026–2031 (KILOTON)


TABLE 69
INDIA: CONCRETE FIBER MARKET SIZE, BY END-USE INDUSTRY, 2023–2025 (USD MILLION)


TABLE 70
INDIA: CONCRETE FIBER MARKET SIZE, BY END-USE INDUSTRY, 2026–2031 (USD MILLION)


TABLE 71
INDIA: CONCRETE FIBER MARKET SIZE, BY END-USE INDUSTRY, 2023–2025 (KILOTON)


TABLE 72
INDIA: CONCRETE FIBER MARKET SIZE, BY END-USE INDUSTRY, 2026–2031 (KILOTON)


TABLE 73
JAPAN: CONCRETE FIBER MARKET SIZE, BY END-USE INDUSTRY, 2023–2025 (USD MILLION)


TABLE 74
JAPAN: CONCRETE FIBER MARKET SIZE, BY END-USE INDUSTRY, 2026–2031 (USD MILLION)


TABLE 75
JAPAN: CONCRETE FIBER MARKET SIZE, BY END-USE INDUSTRY, 2023–2025 (KILOTON)


TABLE 76
JAPAN: CONCRETE FIBER MARKET SIZE, BY END-USE INDUSTRY, 2026–2031 (KILOTON)


TABLE 77
SOUTH KOREA: CONCRETE FIBER MARKET SIZE, BY END-USE INDUSTRY, 2023–2025 (USD MILLION)


TABLE 78
SOUTH KOREA: CONCRETE FIBER MARKET SIZE, BY END-USE INDUSTRY, 2026–2031 (USD MILLION)


TABLE 79
SOUTH KOREA: CONCRETE FIBER MARKET SIZE, BY END-USE INDUSTRY, 2023–2025 (KILOTON)


TABLE 80
SOUTH KOREA: CONCRETE FIBER MARKET SIZE, BY END-USE INDUSTRY, 2026–2031 (KILOTON)


TABLE 81
REST OF ASIA PACIFIC: CONCRETE FIBER MARKET SIZE, BY END-USE INDUSTRY, 2023–2025 (USD MILLION)


TABLE 82
REST OF ASIA PACIFIC: CONCRETE FIBER MARKET SIZE, BY END-USE INDUSTRY, 2026–2031 (USD MILLION)


TABLE 83
REST OF ASIA PACIFIC: CONCRETE FIBER MARKET SIZE, BY END-USE INDUSTRY, 2023–2025 (KILOTON)


TABLE 84
REST OF ASIA PACIFIC: CONCRETE FIBER MARKET SIZE, BY END-USE INDUSTRY, 2026–2031 (KILOTON)


TABLE 85
EUROPE: CONCRETE FIBER MARKET SIZE, BY COUNTRY, 2023–2025 (USD MILLION)


TABLE 86
EUROPE: CONCRETE FIBER MARKET SIZE, BY COUNTRY, 2026–2031 (USD MILLION)


TABLE 87
EUROPE: CONCRETE FIBER MARKET SIZE, BY COUNTRY, 2023–2025 (KILOTON)


TABLE 88
EUROPE: CONCRETE FIBER MARKET SIZE, BY COUNTRY, 2026–2031 (KILOTON)


TABLE 89
EUROPE: CONCRETE FIBER MARKET SIZE, BY TYPE, 2023–2025 (USD MILLION)


TABLE 90
EUROPE: CONCRETE FIBER MARKET SIZE, BY TYPE, 2026–2031 (USD MILLION)


TABLE 91
EUROPE: CONCRETE FIBER MARKET SIZE, BY TYPE, 2023–2025 (KILOTON)


TABLE 92
EUROPE: CONCRETE FIBER MARKET SIZE, BY TYPE, 2026–2031 (KILOTON)


TABLE 93
EUROPE: CONCRETE FIBER MARKET SIZE, BY FORM, 2023–2025 (USD MILLION)


TABLE 94
EUROPE: CONCRETE FIBER MARKET SIZE, BY FORM, 2026–2031 (USD MILLION)


TABLE 95
EUROPE: CONCRETE FIBER MARKET SIZE, BY FORM, 2023–2025 (KILOTON)


TABLE 96
EUROPE: CONCRETE FIBER MARKET SIZE, BY FORM, 2026–2031 (KILOTON)


TABLE 97
EUROPE: CONCRETE FIBER MARKET SIZE, BY APPLICATION, 2023–2025 (USD MILLION)


TABLE 98
EUROPE: CONCRETE FIBER MARKET SIZE, BY APPLICATION, 2026–2031 (USD MILLION)


TABLE 99
EUROPE: CONCRETE FIBER MARKET SIZE, BY APPLICATION, 2023–2025 (KILOTON)


TABLE 100
EUROPE: CONCRETE FIBER MARKET SIZE, BY APPLICATION, 2026–2031 (KILOTON)


TABLE 101
EUROPE: CONCRETE FIBER MARKET SIZE, BY END-USE INDUSTRY, 2023–2025 (USD MILLION)


TABLE 102
EUROPE: CONCRETE FIBER MARKET SIZE, BY END-USE INDUSTRY, 2026–2031 (USD MILLION)


TABLE 103
EUROPE: CONCRETE FIBER MARKET SIZE, BY END-USE INDUSTRY, 2023–2025 (KILOTON)


TABLE 104
EUROPE: CONCRETE FIBER MARKET SIZE, BY END-USE INDUSTRY, 2026–2031 (KILOTON)


TABLE 105
GERMANY: CONCRETE FIBER MARKET SIZE, BY END-USE INDUSTRY, 2023–2025 (USD MILLION)


TABLE 106
GERMANY: CONCRETE FIBER MARKET SIZE, BY END-USE INDUSTRY, 2026–2031 (USD MILLION)


TABLE 107
GERMANY: CONCRETE FIBER MARKET SIZE, BY END-USE INDUSTRY, 2023–2025 (KILOTON)


TABLE 108
GERMANY: CONCRETE FIBER MARKET SIZE, BY END-USE INDUSTRY, 2026–2031 (KILOTON)


TABLE 109
UK: CONCRETE FIBER MARKET SIZE, BY END-USE INDUSTRY, 2023–2025 (USD MILLION)


TABLE 110
UK: CONCRETE FIBER MARKET SIZE, BY END-USE INDUSTRY, 2026–2031 (USD MILLION)


TABLE 111
UK: CONCRETE FIBER MARKET SIZE, BY END-USE INDUSTRY, 2023–2025 (KILOTON)


TABLE 112
UK: CONCRETE FIBER MARKET SIZE, BY END-USE INDUSTRY, 2026–2031 (KILOTON)


TABLE 113
FRANCE: CONCRETE FIBER MARKET SIZE, BY END-USE INDUSTRY, 2023–2025 (USD MILLION)


TABLE 114
FRANCE: CONCRETE FIBER MARKET SIZE, BY END-USE INDUSTRY, 2026–2031 (USD MILLION)


TABLE 115
FRANCE: CONCRETE FIBER MARKET SIZE, BY END-USE INDUSTRY, 2023–2025 (KILOTON)


TABLE 116
FRANCE: CONCRETE FIBER MARKET SIZE, BY END-USE INDUSTRY, 2026–2031 (KILOTON)


TABLE 117
ITALY: CONCRETE FIBER MARKET SIZE, BY END-USE INDUSTRY, 2023–2025 (USD MILLION)


TABLE 118
ITALY: CONCRETE FIBER MARKET SIZE, BY END-USE INDUSTRY, 2026–2031 (USD MILLION)


TABLE 119
ITALY: CONCRETE FIBER MARKET SIZE, BY END-USE INDUSTRY, 2023–2025 (KILOTON)


TABLE 120
ITALY: CONCRETE FIBER MARKET SIZE, BY END-USE INDUSTRY, 2026–2031 (KILOTON)


TABLE 121
SPAIN: CONCRETE FIBER MARKET SIZE, BY END-USE INDUSTRY, 2023–2025 (USD MILLION)


TABLE 122
SPAIN: CONCRETE FIBER MARKET SIZE, BY END-USE INDUSTRY, 2026–2031 (USD MILLION)


TABLE 123
SPAIN: CONCRETE FIBER MARKET SIZE, BY END-USE INDUSTRY, 2023–2025 (KILOTON)


TABLE 124
SPAIN: CONCRETE FIBER MARKET SIZE, BY END-USE INDUSTRY, 2026–2031 (KILOTON)


TABLE 125
REST OF EUROPE: CONCRETE FIBER MARKET SIZE, BY END-USE INDUSTRY, 2023–2025 (USD MILLION)


TABLE 126
REST OF EUROPE: CONCRETE FIBER MARKET SIZE, BY END-USE INDUSTRY, 2026–2031 (USD MILLION)


TABLE 127
REST OF EUROPE: CONCRETE FIBER MARKET SIZE, BY END-USE INDUSTRY, 2023–2025 (KILOTON)


TABLE 128
REST OF EUROPE: CONCRETE FIBER MARKET SIZE, BY END-USE INDUSTRY, 2026–2031 (KILOTON)


TABLE 129
NORTH AMERICA: CONCRETE FIBER MARKET SIZE, BY COUNTRY, 2023–2025 (USD MILLION)


TABLE 130
NORTH AMERICA: CONCRETE FIBER MARKET SIZE, BY COUNTRY, 2026–2031 (USD MILLION)


TABLE 131
NORTH AMERICA: CONCRETE FIBER MARKET SIZE, BY COUNTRY, 2023–2025 (KILOTON)


TABLE 132
NORTH AMERICA: CONCRETE FIBER MARKET SIZE, BY COUNTRY, 2026–2031 (KILOTON)


TABLE 133
NORTH AMERICA: CONCRETE FIBER MARKET SIZE, BY TYPE, 2023–2025 (USD MILLION)


TABLE 134
NORTH AMERICA: CONCRETE FIBER MARKET SIZE, BY TYPE, 2026–2031 (USD MILLION)


TABLE 135
NORTH AMERICA: CONCRETE FIBER MARKET SIZE, BY TYPE, 2023–2025 (KILOTON)


TABLE 136
NORTH AMERICA: CONCRETE FIBER MARKET SIZE, BY TYPE, 2026–2031 (KILOTON)


TABLE 137
NORTH AMERICA: CONCRETE FIBER MARKET SIZE, BY FORM, 2023–2025 (USD MILLION)


TABLE 138
NORTH AMERICA: CONCRETE FIBER MARKET SIZE, BY FORM, 2026–2031 (USD MILLION)


TABLE 139
NORTH AMERICA: CONCRETE FIBER MARKET SIZE, BY FORM, 2023–2025 (KILOTON)


TABLE 140
NORTH AMERICA: CONCRETE FIBER MARKET SIZE, BY FORM, 2026–2031 (KILOTON)


TABLE 141
NORTH AMERICA: CONCRETE FIBER MARKET SIZE, BY APPLICATION, 2023–2025 (USD MILLION)


TABLE 142
NORTH AMERICA: CONCRETE FIBER MARKET SIZE, BY APPLICATION, 2026–2031 (USD MILLION)


TABLE 143
NORTH AMERICA: CONCRETE FIBER MARKET SIZE, BY APPLICATION, 2023–2025 (KILOTON)


TABLE 144
NORTH AMERICA: CONCRETE FIBER MARKET SIZE, BY APPLICATION, 2026–2031 (KILOTON)


TABLE 145
NORTH AMERICA: CONCRETE FIBER MARKET SIZE, BY END-USE INDUSTRY, 2023–2025 (USD MILLION)


TABLE 146
NORTH AMERICA: CONCRETE FIBER MARKET SIZE, BY END-USE INDUSTRY, 2026–2031 (USD MILLION)


TABLE 147
NORTH AMERICA: CONCRETE FIBER MARKET SIZE, BY END-USE INDUSTRY, 2023–2025 (KILOTON)


TABLE 148
NORTH AMERICA: CONCRETE FIBER MARKET SIZE, BY END-USE INDUSTRY, 2026–2031 (KILOTON)


TABLE 149
US: CONCRETE FIBER MARKET SIZE, BY END-USE INDUSTRY, 2023–2025 (USD MILLION)


TABLE 150
US: CONCRETE FIBER MARKET SIZE, BY END-USE INDUSTRY, 2026–2031 (USD MILLION)


TABLE 151
US: CONCRETE FIBER MARKET SIZE, BY END-USE INDUSTRY, 2023–2025 (KILOTON)


TABLE 152
US: CONCRETE FIBER MARKET SIZE, BY END-USE INDUSTRY, 2026–2031 (KILOTON)


TABLE 153
CANADA: CONCRETE FIBER MARKET SIZE, BY END-USE INDUSTRY, 2023–2025 (USD MILLION)


TABLE 154
CANADA: CONCRETE FIBER MARKET SIZE, BY END-USE INDUSTRY, 2026–2031 (USD MILLION)


TABLE 155
CANADA: CONCRETE FIBER MARKET SIZE, BY END-USE INDUSTRY, 2023–2025 (KILOTON)


TABLE 156
CANADA: CONCRETE FIBER MARKET SIZE, BY END-USE INDUSTRY, 2026–2031 (KILOTON)


TABLE 157
MEXICO: CONCRETE FIBER MARKET SIZE, BY END-USE INDUSTRY, 2023–2025 (USD MILLION)


TABLE 158
MEXICO: CONCRETE FIBER MARKET SIZE, BY END-USE INDUSTRY, 2026–2031 (USD MILLION)


TABLE 159
MEXICO: CONCRETE FIBER MARKET SIZE, BY END-USE INDUSTRY, 2023–2025 (KILOTON)


TABLE 160
MEXICO: CONCRETE FIBER MARKET SIZE, BY END-USE INDUSTRY, 2026–2031 (KILOTON)


TABLE 161
MIDDLE EAST & AFRICA: CONCRETE FIBER MARKET SIZE, BY COUNTRY, 2023–2025 (USD MILLION)


TABLE 162
MIDDLE EAST & AFRICA: CONCRETE FIBER MARKET SIZE, BY COUNTRY, 2026–2031 (USD MILLION)


TABLE 163
MIDDLE EAST & AFRICA: CONCRETE FIBER MARKET SIZE, BY COUNTRY, 2023–2025 (KILOTON)


TABLE 164
MIDDLE EAST & AFRICA: CONCRETE FIBER MARKET SIZE, BY COUNTRY, 2026–2031 (KILOTON)


TABLE 165
MIDDLE EAST & AFRICA: CONCRETE FIBER MARKET SIZE, BY TYPE, 2023–2025 (USD MILLION)


TABLE 166
MIDDLE EAST & AFRICA: CONCRETE FIBER MARKET SIZE, BY TYPE, 2026–2031 (USD MILLION)


TABLE 167
MIDDLE EAST & AFRICA: CONCRETE FIBER MARKET SIZE, BY TYPE, 2023–2025 (KILOTON)


TABLE 168
MIDDLE EAST & AFRICA: CONCRETE FIBER MARKET SIZE, BY TYPE, 2026–2031 (KILOTON)


TABLE 169
MIDDLE EAST & AFRICA: CONCRETE FIBER MARKET SIZE, BY FORM, 2023–2025 (USD MILLION)


TABLE 170
MIDDLE EAST & AFRICA: CONCRETE FIBER MARKET SIZE, BY FORM, 2026–2031 (USD MILLION)


TABLE 171
MIDDLE EAST & AFRICA: CONCRETE FIBER MARKET SIZE, BY FORM, 2023–2025 (KILOTON)


TABLE 172
MIDDLE EAST & AFRICA: CONCRETE FIBER MARKET SIZE, BY FORM, 2026–2031 (KILOTON)


TABLE 173
MIDDLE EAST & AFRICA: CONCRETE FIBER MARKET SIZE, BY APPLICATION, 2023–2025 (USD MILLION)


TABLE 174
MIDDLE EAST & AFRICA: CONCRETE FIBER MARKET SIZE, BY APPLICATION, 2026–2031 (USD MILLION)


TABLE 175
MIDDLE EAST & AFRICA: CONCRETE FIBER MARKET SIZE, BY APPLICATION, 2023–2025 (KILOTON)


TABLE 176
MIDDLE EAST & AFRICA: CONCRETE FIBER MARKET SIZE, BY APPLICATION, 2026–2031 (KILOTON)


TABLE 177
MIDDLE EAST & AFRICA: CONCRETE FIBER MARKET SIZE, BY END-USE INDUSTRY, 2023–2025 (USD MILLION)


TABLE 178
MIDDLE EAST & AFRICA: CONCRETE FIBER MARKET SIZE, BY END-USE INDUSTRY, 2026–2031 (USD MILLION)


TABLE 179
MIDDLE EAST & AFRICA: CONCRETE FIBER MARKET SIZE, BY END-USE INDUSTRY, 2023–2025 (KILOTON)


TABLE 180
MIDDLE EAST & AFRICA: CONCRETE FIBER MARKET SIZE, BY END-USE INDUSTRY, 2026–2031 (KILOTON)


TABLE 181
SAUDI ARABIA: CONCRETE FIBER MARKET SIZE, BY END-USE INDUSTRY, 2023–2025 (USD MILLION)


TABLE 182
SAUDI ARABIA: CONCRETE FIBER MARKET SIZE, BY END-USE INDUSTRY, 2026–2031 (USD MILLION)


TABLE 183
SAUDI ARABIA: CONCRETE FIBER MARKET SIZE, BY END-USE INDUSTRY, 2023–2025 (KILOTON)


TABLE 184
SAUDI ARABIA: CONCRETE FIBER MARKET SIZE, BY END-USE INDUSTRY, 2026–2031 (KILOTON)


TABLE 185
UAE: CONCRETE FIBER MARKET SIZE, BY END-USE INDUSTRY, 2023–2025 (USD MILLION)


TABLE 186
UAE: CONCRETE FIBER MARKET SIZE, BY END-USE INDUSTRY, 2026–2031 (USD MILLION)


TABLE 187
UAE: CONCRETE FIBER MARKET SIZE, BY END-USE INDUSTRY, 2023–2025 (KILOTON)


TABLE 188
UAE: CONCRETE FIBER MARKET SIZE, BY END-USE INDUSTRY, 2026–2031 (KILOTON)


TABLE 189
REST OF GCC COUNTRIES: CONCRETE FIBER MARKET SIZE, BY END-USE INDUSTRY, 2023–2025 (USD MILLION)


TABLE 190
REST OF GCC COUNTRIES: CONCRETE FIBER MARKET SIZE, BY END-USE INDUSTRY, 2026–2031 (USD MILLION)


TABLE 191
REST OF GCC COUNTRIES: CONCRETE FIBER MARKET SIZE, BY END-USE INDUSTRY, 2023–2025 (KILOTON)


TABLE 192
REST OF GCC COUNTRIES: CONCRETE FIBER MARKET SIZE, BY END-USE INDUSTRY, 2026–2031 (KILOTON)


TABLE 193
SOUTH AFRICA: CONCRETE FIBER MARKET SIZE, BY END-USE INDUSTRY, 2023–2025 (USD MILLION)


TABLE 194
SOUTH AFRICA: CONCRETE FIBER MARKET SIZE, BY END-USE INDUSTRY, 2026–2031 (USD MILLION)


TABLE 195
SOUTH AFRICA: CONCRETE FIBER MARKET SIZE, BY END-USE INDUSTRY, 2023–2025 (KILOTON)


TABLE 196
SOUTH AFRICA: CONCRETE FIBER MARKET SIZE, BY END-USE INDUSTRY, 2026–2031 (KILOTON)


TABLE 197
REST OF MIDDLE EAST & AFRICA: CONCRETE FIBER MARKET SIZE, BY END-USE INDUSTRY, 2023–2025 (USD MILLION)


TABLE 198
REST OF MIDDLE EAST & AFRICA: CONCRETE FIBER MARKET SIZE, BY END-USE INDUSTRY, 2026–2031 (USD MILLION)


TABLE 199
REST OF MIDDLE EAST & AFRICA: CONCRETE FIBER MARKET SIZE, BY END-USE INDUSTRY, 2023–2025 (KILOTON)


TABLE 200
REST OF MIDDLE EAST & AFRICA: CONCRETE FIBER MARKET SIZE, BY END-USE INDUSTRY, 2026–2031 (KILOTON)


TABLE 201
SOUTH AMERICA: CONCRETE FIBER MARKET SIZE, BY COUNTRY, 2023–2025 (USD MILLION)


TABLE 202
SOUTH AMERICA: CONCRETE FIBER MARKET SIZE, BY COUNTRY, 2026–2031 (USD MILLION)


TABLE 203
SOUTH AMERICA: CONCRETE FIBER MARKET SIZE, BY COUNTRY, 2023–2025 (KILOTON)


TABLE 204
SOUTH AMERICA: CONCRETE FIBER MARKET SIZE, BY COUNTRY, 2026–2031 (KILOTON)


TABLE 205
SOUTH AMERICA: CONCRETE FIBER MARKET SIZE, BY TYPE, 2023–2025 (USD MILLION)


TABLE 206
SOUTH AMERICA: CONCRETE FIBER MARKET SIZE, BY TYPE, 2026–2031 (USD MILLION)


TABLE 207
SOUTH AMERICA: CONCRETE FIBER MARKET SIZE, BY TYPE, 2023–2025 (KILOTON)


TABLE 208
SOUTH AMERICA: CONCRETE FIBER MARKET SIZE, BY TYPE, 2026–2031 (KILOTON)


TABLE 209
SOUTH AMERICA: CONCRETE FIBER MARKET SIZE, BY FORM, 2023–2025 (USD MILLION)


TABLE 210
SOUTH AMERICA: CONCRETE FIBER MARKET SIZE, BY FORM, 2026–2031 (USD MILLION)


TABLE 211
SOUTH AMERICA: CONCRETE FIBER MARKET SIZE, BY FORM, 2023–2025 (KILOTON)


TABLE 212
SOUTH AMERICA: CONCRETE FIBER MARKET SIZE, BY FORM, 2026–2031 (KILOTON)


TABLE 213
SOUTH AMERICA: CONCRETE FIBER MARKET SIZE, BY APPLICATION, 2023–2025 (USD MILLION)


TABLE 214
SOUTH AMERICA: CONCRETE FIBER MARKET SIZE, BY APPLICATION, 2026–2031 (USD MILLION)


TABLE 215
SOUTH AMERICA: CONCRETE FIBER MARKET SIZE, BY APPLICATION, 2023–2025 (KILOTON)


TABLE 216
SOUTH AMERICA: CONCRETE FIBER MARKET SIZE, BY APPLICATION, 2026–2031 (KILOTON)


TABLE 217
SOUTH AMERICA: CONCRETE FIBER MARKET SIZE, BY END-USE INDUSTRY, 2023–2025 (USD MILLION)


TABLE 218
SOUTH AMERICA: CONCRETE FIBER MARKET SIZE, BY END-USE INDUSTRY, 2026–2031 (USD MILLION)


TABLE 219
SOUTH AMERICA: CONCRETE FIBER MARKET SIZE, BY END-USE INDUSTRY, 2023–2025 (KILOTON)


TABLE 220
SOUTH AMERICA: CONCRETE FIBER MARKET SIZE, BY END-USE INDUSTRY, 2026–2031 (KILOTON)


TABLE 221
BRAZIL: CONCRETE FIBER MARKET SIZE, BY END-USE INDUSTRY, 2023–2025 (USD MILLION)


TABLE 222
BRAZIL: CONCRETE FIBER MARKET SIZE, BY END-USE INDUSTRY, 2026–2031 (USD MILLION)


TABLE 223
BRAZIL: CONCRETE FIBER MARKET SIZE, BY END-USE INDUSTRY, 2023–2025 (KILOTON)


TABLE 224
BRAZIL: CONCRETE FIBER MARKET SIZE, BY END-USE INDUSTRY, 2026–2031 (KILOTON)


TABLE 225
ARGENTINA: CONCRETE FIBER MARKET SIZE, BY END-USE INDUSTRY, 2023–2025 (USD MILLION)


TABLE 226
ARGENTINA: CONCRETE FIBER MARKET SIZE, BY END-USE INDUSTRY, 2026–2031 (USD MILLION)


TABLE 227
ARGENTINA: CONCRETE FIBER MARKET SIZE, BY END-USE INDUSTRY, 2023–2025 (KILOTON)


TABLE 228
ARGENTINA: CONCRETE FIBER MARKET SIZE, BY END-USE INDUSTRY, 2026–2031 (KILOTON)


TABLE 229
REST OF SOUTH AMERICA: CONCRETE FIBER MARKET SIZE, BY END-USE INDUSTRY, 2023–2025 (USD MILLION)


TABLE 230
REST OF SOUTH AMERICA: CONCRETE FIBER MARKET SIZE, BY END-USE INDUSTRY, 2026–2031 (USD MILLION)


TABLE 231
REST OF SOUTH AMERICA: CONCRETE FIBER MARKET SIZE, BY END-USE INDUSTRY, 2023–2025 (KILOTON)


TABLE 232
REST OF SOUTH AMERICA: CONCRETE FIBER MARKET SIZE, BY END-USE INDUSTRY, 2026–2031 (KILOTON)


TABLE 233
KEY PLAYERS’ STRATEGIES/RIGHT TO WIN, 2023–2026


TABLE 234
CONCRETE FIBER MARKET: DEGREE OF COMPETITION


TABLE 235
CONCRETE FIBER MARKET: REGION FOOTPRINT


TABLE 236
CONCRETE FIBER MARKET: TYPE FOOTPRINT


TABLE 237
CONCRETE FIBER MARKET: FORM FOOTPRINT


TABLE 238
CONCRETE FIBER MARKET: APPLICATION FOOTPRINT


TABLE 239
CONCRETE FIBER MARKET: END-USE INDUSTRY FOOTPRINT


TABLE 240
CONCRETE FIBER MARKET: DETAILED LIST OF KEY STARTUPS/SMES


TABLE 241
CONCRETE FIBER MARKET: COMPETITIVE BENCHMARKING OF KEY STARTUPS/SMES (1/2)


TABLE 242
CONCRETE FIBER MARKET: COMPETITIVE BENCHMARKING OF KEY STARTUPS/SMES (2/2)


TABLE 243
CONCRETE FIBER MARKET: PRODUCT LAUNCHES, JANUARY 2023– JULY 2026


TABLE 244
CONCRETE FIBER MARKET: DEALS, JANUARY 2023–JULY 2026


TABLE 245
CONCRETE FIBER MARKET: EXPANSIONS, JANUARY 2023–JULY 2026


TABLE 246
BEKAERT: COMPANY OVERVIEW


TABLE 247
BEKAERT: PRODUCTS/SOLUTIONS/SERVICES OFFERED


TABLE 248
BEKAERT: PRODUCT LAUNCHES, JANUARY 2023–JULY 2026


TABLE 249
BEKAERT: DEALS, JANUARY 2023–JULY 2026


TABLE 250
BEKAERT: EXPANSIONS, JANUARY 2023–JULY 2026


TABLE 251
SIKA: COMPANY OVERVIEW


TABLE 252
SIKA: PRODUCTS/SOLUTIONS/SERVICES OFFERED


TABLE 253
SIKA: EXPANSIONS, JANUARY 2023–JULY 2026


TABLE 254
OWENS CORNING: COMPANY OVERVIEW


TABLE 255
OWENS CORNING: PRODUCTS/SOLUTIONS/SERVICES OFFERED


TABLE 256
CEMEX S.A.B. DE C.V.: COMPANY OVERVIEW


TABLE 257
CEMEX S.A.B. DE C.V.: PRODUCTS/SOLUTIONS/SERVICES OFFERED


TABLE 258
ABC POLYMER INDUSTRIES, LLC: COMPANY OVERVIEW


TABLE 259
ABC POLYMER INDUSTRIES, LLC: PRODUCTS/SOLUTIONS/SERVICES OFFERED


TABLE 260
FORTA: COMPANY OVERVIEW


TABLE 261
FORTA: PRODUCTS/SOLUTIONS/SERVICES OFFERED


TABLE 262
FORTA: DEALS, JANUARY 2023–JULY 2026


TABLE 263
FORTA: EXPANSIONS, JANUARY 2023–JULY 2026


TABLE 264
THE EUCLID CHEMICAL COMPANY: COMPANY OVERVIEW


TABLE 265
THE EUCLID CHEMICAL COMPANY: PRODUCTS/SOLUTIONS/SERVICES OFFERED


TABLE 266
BARCHIP PTY LTD.: COMPANY OVERVIEW


TABLE 267
BARCHIP PTY LTD.: PRODUCTS/SOLUTIONS/SERVICES OFFERED


TABLE 268
NYCON: COMPANY OVERVIEW


TABLE 269
NYCON: PRODUCTS/SOLUTIONS/SERVICES OFFERED


TABLE 270
FIBERCON INTERNATIONAL INC.: COMPANY OVERVIEW


TABLE 271
FIBERCON INTERNATIONAL INC.: PRODUCTS/SOLUTIONS/SERVICES OFFERED


TABLE 272
ARCELORMITTAL: COMPANY OVERVIEW


TABLE 273
ARCELORMITTAL: PRODUCTS/SOLUTIONS/SERVICES OFFERED


TABLE 274
CHRYSO: COMPANY OVERVIEW


TABLE 275
CHRYSO: PRODUCTS/SOLUTIONS/SERVICES OFFERED


TABLE 276
CHRYSO: DEALS, JANUARY 2023–JULY 2026


TABLE 277
KRAMPEHAREX GMBH & CO. KG: COMPANY OVERVIEW


TABLE 278
MASTER BUILDERS SOLUTIONS: COMPANY OVERVIEW


TABLE 279
NIPPON SEISEN CO., LTD.: COMPANY OVERVIEW


TABLE 280
SPAJIC DOO: COMPANY OVERVIEW


TABLE 281
CREAFILL: COMPANY OVERVIEW


TABLE 282
MINIFIBERS, INC.: COMPANY OVERVIEW


TABLE 283
HUNAN SUNSHINE STEEL FIBER CO., LTD.: COMPANY OVERVIEW


TABLE 284
KOSTEEL CO., LTD.: COMPANY OVERVIEW


TABLE 285
GANZHOU DAYE METAL FIBER CO., LTD.: COMPANY OVERVIEW


TABLE 286
TENGZHOU STAR SMITH METAL PRODUCTS CO., LTD.: COMPANY OVERVIEW


TABLE 287
BILSTEIN STEEL FIBER GMBH: COMPANY OVERVIEW


TABLE 288
KALYANI: COMPANY OVERVIEW


TABLE 289
NUOVAFIL INFOTECK PVT LTD.: COMPANY OVERVIEW


LIST OF FIGURES


FIGURE 1
CONCRETE FIBER MARKET SEGMENTATION


FIGURE 2
KEY INSIGHTS AND MARKET HIGHLIGHTS


FIGURE 3
CONCRETE FIBER MARKET, 2026–2031


FIGURE 4
MAJOR STRATEGIES ADOPTED BY KEY PLAYERS IN CONCRETE FIBER MARKET, 2022–2026


FIGURE 5
DISRUPTIONS INFLUENCING GROWTH OF CONCRETE FIBER MARKET


FIGURE 6
HIGH-GROWTH SEGMENTS IN CONCRETE FIBER MARKET, 2026–2031


FIGURE 7
ASIA PACIFIC TO REGISTER HIGHEST CAGR IN CONCRETE FIBER MARKET DURING FORECAST PERIOD


FIGURE 8
ASIA PACIFIC TO OFFER ATTRACTIVE OPPORTUNITIES FOR MARKET PLAYERS DURING FORECAST PERIOD


FIGURE 9
STEEL SEGMENT TO LEAD CONCRETE FIBER MARKET DURING FORECAST PERIOD


FIGURE 10
MONOFILAMENT SEGMENT TO ACCOUNT FOR LARGEST MARKET SHARE DURING FORECAST PERIOD


FIGURE 11
SLABS & FLOORS SEGMENT TO ACCOUNT FOR LARGEST MARKET SHARE DURING FORECAST PERIOD


FIGURE 12
BUILDING & CONSTRUCTION SEGMENT TO LEAD MARKET DURING FORECAST PERIOD


FIGURE 13
INDIA TO WITNESS HIGHEST CAGR DURING FORECAST PERIOD


FIGURE 14
DRIVERS, RESTRAINTS, OPPORTUNITIES, AND CHALLENGES IN CONCRETE FIBER MARKET


FIGURE 15
CONCRETE FIBER MARKET: PORTER’S FIVE FORCES ANALYSIS


FIGURE 16
CONCRETE FIBER MARKET: VALUE CHAIN ANALYSIS


FIGURE 17
CONCRETE FIBER MARKET: ECOSYSTEM ANALYSIS


FIGURE 18
AVERAGE SELLING PRICE TREND, BY REGION, 2023–2025


FIGURE 19
AVERAGE SELLING PRICE TREND, BY TYPE, 2023–2025


FIGURE 20
IMPORT SCENARIO FOR HS CODE 732690-COMPLIANT PRODUCTS, BY COUNTRY, 2021–2025


FIGURE 21
EXPORT SCENARIO FOR HS CODE 732690-COMPLIANT PRODUCTS, BY COUNTRY, 2021–2025


FIGURE 22
TRENDS/DISRUPTIONS IMPACTING CUSTOMER BUSINESS


FIGURE 23
CONCRETE FIBER MARKET: INVESTMENT AND FUNDING SCENARIO, 2021–2024


FIGURE 24
PATENTS APPLIED AND GRANTED, 2016–2025


FIGURE 25
PATENT ANALYSIS, BY LEGAL STATUS


FIGURE 26
TOP JURISDICTION, BY DOCUMENT


FIGURE 27
CONCRETE FIBER MARKET: DECISION-MAKING FACTORS


FIGURE 28
INFLUENCE OF STAKEHOLDERS ON BUYING PROCESS FOR KEY APPLICATIONS


FIGURE 29
KEY BUYING CRITERIA FOR TOP THREE APPLICATIONS


FIGURE 30
ADOPTION BARRIERS & INTERNAL CHALLENGES


FIGURE 31
MONOFILAMENT TO ACCOUNT FOR LARGEST SHARE OF CONCRETE FIBER MARKET DURING FORECAST PERIOD


FIGURE 32
STEEL FIBER TO ACCOUNT FOR LARGEST SHARE OF CONCRETE FIBER MARKET DURING FORECAST PERIOD


FIGURE 33
SLABS & FLOORS TO ACCOUNT FOR LARGEST SHARE OF CONCRETE FIBER MARKET DURING FORECAST PERIOD


FIGURE 34
TRANSPORT INFRASTRUCTURE TO ACCOUNT FOR LARGEST SHARE OF CONCRETE FIBER MARKET DURING FORECAST PERIOD


FIGURE 35
INDIA TO REGISTER HIGHEST GROWTH IN CONCRETE FIBER MARKET DURING FORECAST PERIOD


FIGURE 36
ASIA PACIFIC: CONCRETE FIBER MARKET SNAPSHOT


FIGURE 37
EUROPE: CONCRETE FIBER MARKET SNAPSHOT


FIGURE 38
NORTH AMERICA: CONCRETE FIBER MARKET SNAPSHOT


FIGURE 39
REVENUE ANALYSIS OF TOP LISTED/PUBLIC PLAYERS, 2023–2025


FIGURE 40
MARKET SHARE ANALYSIS OF KEY PLAYERS, 2025


FIGURE 41
COMPANY VALUATION (USD BILLION)


FIGURE 42
FINANCIAL METRICS (EV/EBITDA)


FIGURE 43
BRAND/PRODUCT COMPARISON


FIGURE 44
CONCRETE FIBER MARKET: COMPANY EVALUATION MATRIX (KEY PLAYERS), 2025


FIGURE 45
CONCRETE FIBER MARKET: COMPANY FOOTPRINT


FIGURE 46
CONCRETE FIBER MARKET: COMPANY EVALUATION MATRIX (STARTUPS/SMES), 2025


FIGURE 47
BEKAERT: COMPANY SNAPSHOT


FIGURE 48
SIKA: COMPANY SNAPSHOT


FIGURE 49
OWENS CORNING: COMPANY SNAPSHOT


FIGURE 50
CEMEX S.A.B. DE C.V.: COMPANY SNAPSHOT


FIGURE 51
ARCELORMITTAL: COMPANY SNAPSHOT


FIGURE 52
CONCRETE FIBER MARKET: RESEARCH DESIGN


FIGURE 53
CONCRETE FIBER MARKET: BOTTOM-UP APPROACH


FIGURE 54
CONCRETE FIBER MARKET: TOP-DOWN APPROACH


FIGURE 55
MARKET SIZE ESTIMATION NOTES


FIGURE 56
DEMAND-SIDE FORECAST PROJECTIONS


FIGURE 57
CONCRETE FIBER MARKET: DATA TRIANGULATION


Methodology

The study involved four major activities to estimate the current size of the global concrete fiber market. Exhaustive secondary research was conducted to collect information on the concrete fiber market, the peer product market, and the parent product group market. The next step was to validate these findings, assumptions, and sizes with industry experts across the concrete fiber value chain through primary research. Both the top-down and bottom-up approaches were employed to estimate the overall size of the concrete fiber market. After that, market breakdown and data triangulation were used to determine the sizes of different market segments and subsegments.

Secondary Research

For the secondary research, sources such as D&B Hoovers, Factiva, Bloomberg BusinessWeek, and Dun & Bradstreet were used to identify and collect information for this study of the concrete fiber market. These sources included annual reports, press releases, and investor presentations from companies; white papers; certified publications; databases; articles by recognized authors; regulatory bodies; and trade directories.

Primary Research

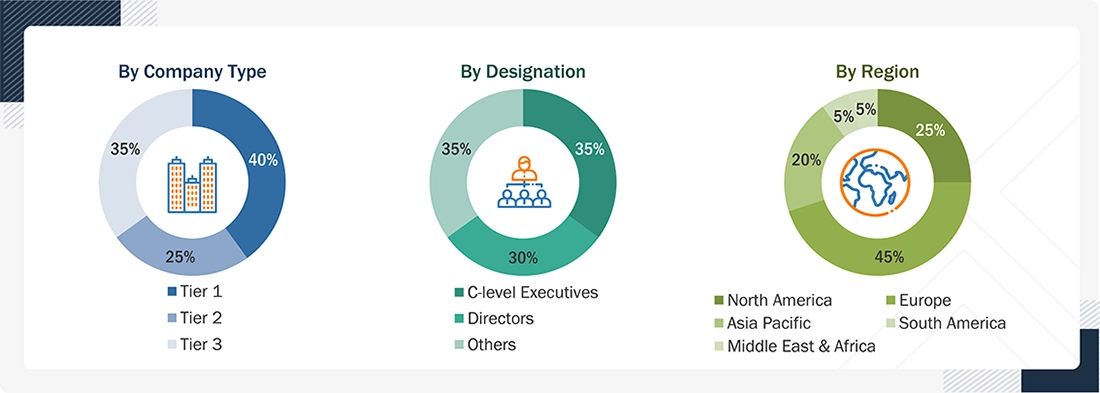
The concrete fiber market involves various stakeholders along the supply chain, such as raw material suppliers, distributors, end-product manufacturers, buyers, and regulatory bodies. Both qualitative and quantitative data have been collected through interviews with primary sources from both the supply and demand sides. On the demand side, key participants include opinion leaders, company executives, vice presidents, and CEOs in the market. On the supply side, primary sources consist of associations, institutions, influential opinion leaders, and processing companies involved in the market.

Concrete Fiber Market
 Size, and Share

To know about the assumptions considered for the study, download the pdf brochure

Market Size Estimation

The bottom-up and top-down approaches were used to estimate the concrete fiber market by type, form, application, end-use industry, and region. The research methodology used to calculate the market size includes the following steps:

  • The key players in the industry and markets were identified through extensive secondary research.
  • In terms of value, the industry’s supply chain and market size were determined through primary and secondary research processes.
  • All percentage shares, splits, and breakdowns were determined using secondary sources and verified through primary sources.
  • All parameters that affect the markets covered in this research study were accounted for, examined in detail, verified through primary research, and analyzed to obtain the final quantitative and qualitative data.
  • The research included reviewing reports, reviews, and newsletters from top market players, as well as extensive interviews with leaders, such as directors and marketing executives, to gather opinions.

The following figure illustrates the overall market size estimation process employed for this study.
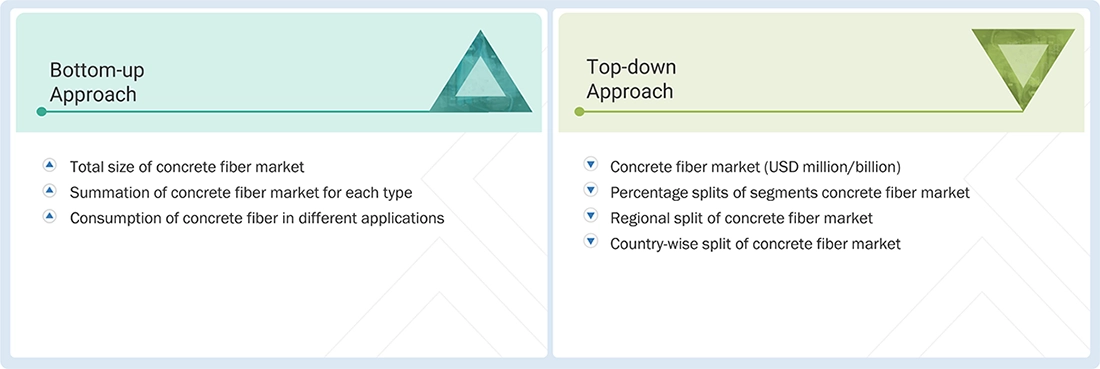
Concrete Fiber Market Top Down and Bottom Up Approach

Data Triangulation

After estimating the total size of the concrete fiber market, the market was divided into multiple segments and subsegments. Data triangulation and breakdown methods were used, where relevant, to refine the overall market analysis and determine precise statistics for all segments. The data was cross-checked by examining factors and trends from both demand and supply perspectives. Additionally, market size validation was performed using top-down and bottom-up approaches.

Market Definition

Concrete fibers are short, discrete reinforcing fibers put right into concrete or mortar to boost its mechanical properties, overall durability, and resistance to cracking. They are made from steel, synthetic polymers, glass, basalt, and also natural fiber sources, and they are available in different forms such as monofilament, multifilament, fibrillated, or chopped fibers, depending on the goal. If they are spread evenly inside the concrete matrix, these fibers help to control plastic shrinkage and drying shrinkage-type cracks while also raising tensile and flexural performance. Beyond that, they add toughness, better impact resistance, and more steady fatigue behavior. In practice, concrete fibers show up a lot in slabs & floors, precast work, shotcrete, pavements, tunnels, mining contexts, and other structural parts for stronger structural performance.

Key Stakeholders

  • Concrete fiber manufacturers
  • Raw material suppliers
  • Regulatory bodies and government agencies
  • Distributors and suppliers
  • End-use industries
  • Associations and industrial bodies
  • Market research and consulting firms

Report Objectives

  • To define, describe, and forecast the size of the concrete fiber market in terms of value and volume
  • To provide detailed information regarding the key factors influencing the growth of the market (drivers, restraints, opportunities, and challenges)
  • To forecast the market size based on type, form, application, end-use industry, and region
  • To study the market qualitatively based on manufacturing process
  • To forecast the market size for the five main regions—North America, Europe, Asia Pacific, South America, and Middle East & Africa—along with their key countries
  • To strategically analyze micromarkets with respect to individual growth trends, prospects, and contributions to the total market
  • To analyze opportunities in the market for stakeholders and provide details of the competitive landscape for market leaders
  • To strategically profile leading players and comprehensively analyze their key developments, such as product launches, expansions, and deals in the concrete fiber market
  • To comprehensively analyze the market share and core competencies of key players
  • To study the impact of AI/gen AI on the market under study, along with the macroeconomic outlook

Available customizations:

With the given market data, MarketsandMarkets offers customizations per the specific needs of companies.

The following customization options are available for the report:

PRODUCT ANALYSIS

  • Product matrix, which provides a detailed comparison of the market for different sources of concrete fiber

REGIONAL ANALYSIS

  • Further breakdown of a country with respect to the concrete fiber market

COMPANY INFORMATION

  • Detailed analysis and profiling of additional market players

 

Personalize This Research

  • Triangulate with your Own Data
  • Get Data as per your Format and Definition
  • Gain a Deeper Dive on a Specific Application, Geography, Customer or Competitor
  • Any level of Personalization
Request A Free Customisation

Let Us Help You

  • What are the Known and Unknown Adjacencies Impacting the Concrete Fiber Market
  • What will your New Revenue Sources be?
  • Who will be your Top Customer; what will make them switch?
  • Defend your Market Share or Win Competitors
  • Get a Scorecard for Target Partners
Customized Workshop Request

Custom Market Research Services

We Will Customise The Research For You, In Case The Report Listed Above Does Not Meet With Your Requirements

Get 10% Free Customisation

TESTIMONIALS

Growth opportunities and latent adjacency in Concrete Fiber Market

avtar

Tom

Sep, 2015

Data on market size and share by region of Macro Synthetic Fibres, Micro Synthetic Fibres..

avtar

Tom

Sep, 2015

specific information on macro synthetic fibres and micro synthetic fibres and the size of the market in the different regions.

avtar

Mahdi

May, 2019

To conduct market research on hemp.

avtar

Pinar

Nov, 2016

Need information on polypropylene macro synthetic fibers for concrete reinforcement and steel fibers. .

avtar

Ziya

Mar, 2019

synthetic macro fiber market.

DMCA.com Protection Status
popup img