China Automotive Suspension Market (2025-2030)
The China Automotive Suspension Market was valued at $125986 Million in 2025 and projected to reach to $116753 Million by 2030, representing a compound annual growth rate of -1.1%. China's automotive suspension market faces headwinds as the industry transitions toward electric and autonomous vehicle platforms that require fundamentally different suspension architectures.

| Market Size in | USD 26.32 MN |
| Market Forecast in | |
| CAGR | |
| Forecast Period | |
| Units Considered | Value (USD MN) |
China Automotive Suspension Market Trends and Insights
- This downturn in China reflects structural shifts in the automotive sector, including increased competition from electric vehicle manufacturers prioritizing alternative suspension technologies and changing consumer preferences toward lighter, more efficient systems.
- China's market dynamics are shaped by overcapacity in traditional suspension component manufacturing and the transition toward integrated mobility solutions that reduce reliance on conventional suspension architectures. Despite the overall decline, China remains a critical hub for automotive suspension innovation and production.
- The market contraction signals China's automotive industry is undergoing significant transformation, with original equipment manufacturers (OEMs) in China investing heavily in next-generation suspension systems for electric and autonomous vehicles.
- China's suspension market challenges present opportunities for suppliers willing to pivot toward advanced materials, smart suspension technologies, and integrated chassis systems that align with the country's electrification and autonomous driving roadmap through 2030..
Key Market Statistics
- CAGR (2025-2030) -1.1%
- Market Size, 2025 ~USD 125986 Million
- Forecast, 2030 ~USD 116753 Million
- Country China
China Automotive Suspension Market Overview
Market Contraction :
China's automotive suspension market is declining at -1.1% CAGR, contracting from USD 125,986 million in 2025 to USD 116,753 million by 2030, reflecting significant structural challenges in the domestic automotive sector.
EV Technology Shift :
Rising adoption of electric vehicles in China is driving manufacturers toward alternative suspension technologies, reducing demand for traditional suspension systems and accelerating market consolidation among legacy suppliers.
Competitive Pressure :
Intensified competition from EV-focused manufacturers and new market entrants is eroding margins for conventional suspension component suppliers, forcing consolidation and strategic repositioning across the Chinese supply chain.
Market Size Decline :
The Chinese market will lose approximately USD 9,233 million in value over the 2025-2030 forecast period, representing a significant contraction compared to the global market's modest 0.9% growth trajectory.
China Automotive Suspension Market Dynamics
- Traditional hydraulic and mechanical suspension suppliers are experiencing declining volumes as EV manufacturers prioritize lightweight, integrated suspension systems optimized for electric drivetrains.
- This structural shift is expected to persist through 2030, with market contraction accelerating as legacy vehicle production declines. Despite the overall negative outlook, opportunities exist for suppliers who can innovate in adaptive suspension systems, air suspension technologies, and integrated chassis solutions for EVs.
- Companies investing in R&D for next-generation suspension technologies and establishing partnerships with EV manufacturers will be better positioned to navigate China's evolving automotive landscape and capture emerging segments within the declining market..
Market Ecosystem
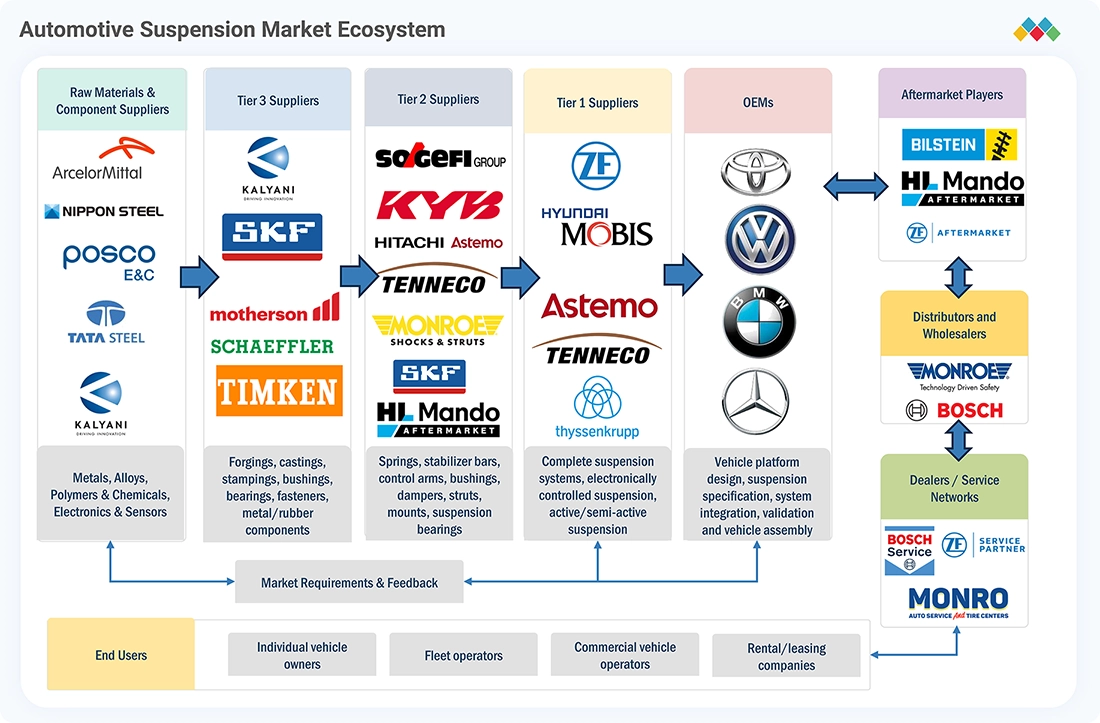
AUTOMOTIVE SUSPENSION MARKET SIZE, SHARE & ANALYSIS: COMMERCIAL USE CASES ACROSS INDUSTRIES
| COMPANY | USE CASE DESCRIPTION | BENEFITS |
|---|---|---|
 |
ZF applies electronically controlled suspension technologies, including Continuous Damping Control (CDC), sMOTION, and its cubiX chassis-control software, across passenger cars, EVs, SUVs, and commercial vehicles. These systems use vehicle and road-condition data to continuously adjust damping and coordinate chassis functions. ZF is also developing AI-enabled suspension control through AI Road Sense, which can anticipate road conditions and adapt chassis behavior. | Improved ride comfort and handling; enhanced vehicle stability; predictive suspension response; better control of heavier EVs; reduced body movement; and opportunities for software-enabled chassis functions and OTA feature upgrades. |
 |
Hyundai Mobis is developing e-Corner and integrated wheel-end technologies that combine steering, braking, driving, and suspension functions at individual wheels. The technology is particularly suited to next-generation EVs, where independent wheel control can support new vehicle architectures, flexible packaging, and advanced maneuverability. | Greater vehicle maneuverability; improved low-speed turning and parking; flexible EV packaging; enhanced wheel-level control; reduced mechanical interdependencies; and greater freedom in future vehicle design. |
 |
Tenneco applies Monroe Intelligent Suspension technologies, including CVSAe and CVSA2 electronically controlled dampers, to continuously adjust suspension response based on vehicle inputs and road conditions. Its newer CVSA2 steel-tube variant and DCx passive damper valve expand the technology across EVs, SUVs, premium vehicles, and higher-volume applications. | Adaptive ride comfort; improved handling and body control; optimized suspension response across different driving conditions; lower NVH; broader vehicle application coverage; and improved balance between performance and system cost. |
 |
thyssenkrupp develops lightweight springs, stabilizer bars, tubular/split stabilizers, and active-roll-control components for passenger vehicles and EVs. Its VarioShape technology optimizes stabilizer geometry to reduce mass, while split stabilizer bars can be integrated with active roll-control systems. | Lower suspension weight; improved roll stability; better handling and ride comfort; reduced material consumption; improved energy efficiency for EVs; and enhanced chassis performance without significant weight increase. |
Logos and trademarks shown above are the property of their respective owners. Their use here is for informational and illustrative purposes only.
Related Ecosystem
Body Exterior Interior
- Battery Electric Vehicle (BEV)
- Fuel Cell Electric Vehicle (FCEV)
- Light Commercial Vehicles (LCVs)
- Hybrid Electric Vehicle (HEV)
- Agricultural Tractors
- AISIN CORPORATION
- Magna International Inc.
- GORKOVSKY AVTOMOBILNY ZAVOD
- BOCAR
- Continental ag
Driving Support Security
- Battery Electric Vehicle (BEV)
- Hybrid Electric Vehicle (HEV)
- Light Commercial Vehicles (LCVs)
- Fuel Cell Electric Vehicle (FCEV)
- Blind Spot Detection (BSD)
- BOSCH LIMITED
- Continental ag
- DENSO Corporation
- Magna International Inc.
- ZF FRIEDRICHSHAFEN AG
Electric Hybrid Vehicles
- Battery Electric Vehicle (BEV)
- Fuel Cell Electric Vehicle (FCEV)
- Light Commercial Vehicles (LCVs)
- Hybrid Electric Vehicle (HEV)
- Agricultural Tractors
- Visteon Corporation
- Byd company ltd.
- BOSCH LIMITED
- Tesla, Inc.
- FORD MOTOR COMPANY
Key Takeaways
- China's automotive suspension market will contract from USD 125,986M (2025) to USD 116,753M (2030) at a -1.1% CAGR, reflecting industry-wide electrification pressures.
- China's EV manufacturers are adopting alternative suspension architectures that reduce demand for traditional suspension components, accelerating market decline.
- China's overcapacity in conventional suspension manufacturing is driving consolidation and forcing suppliers to innovate in smart and adaptive suspension technologies.
- China's transition toward autonomous and electric vehicles creates opportunities for suppliers developing integrated chassis and advanced suspension systems aligned with future mobility.
Automotive Suspension Market Report Scope
| Report Metric | Details |
|---|---|
| Base Year | 2025 |
| Fastest Growing Segment | ELECTRONICALLY ACTUATED (Actuation) |
| Forecast Period | 2025–2030 |
| Growth Rate | CAGR of 0.9% from 2025 to 2030 |
| Largest Segment | PASSIVE (System) |
| Market Size Base Year (Billions) | ~USD 39.85 (2025) |
| Revenue Forecast (Billions) | ~USD 41.68 (2030) |
| Segments Covered | Actuation, Component, Architecture, System, Vehicle Type |
China Automotive Suspension Market Report Segmentation
5 segment dimensions are covered across the global market.
By Actuation
- Electronically Actuated
- Hydraulically Actuated
By Component
- Air Springs
- Ball Joints
- Coil Springs
- Control Arms
- Leaf Springs
- Link Stabilizer/ Sway Bars
- Link Stabilizer/Sway Bars
- Rubber Bushings
- Shock Absorbers
- Struts
By Architecture
- Air Suspension
- Double Wishbone
- Leaf Spring
- Macpherson Strut
- Multilink
- Twist Beam/ Torsion Beam
- Twist Beam/Torsion Beam
By System
- Active
- Passive
- Semi-Active
By Vehicle Type
- Buses
- Lcvs
- Passenger Cars
- Trucks
Target Audience
- Automotive OEM Executives : Need China-specific suspension market data to inform manufacturing strategy, supplier consolidation decisions, and technology investments as the market transitions from traditional to EV-optimized suspension systems.
- Suspension Component Suppliers : Require detailed market contraction analysis and competitive landscape insights to identify survival strategies, technology differentiation opportunities, and potential acquisition or partnership targets in China's declining market.
- Investment & Private Equity Firms : Seek China market intelligence to evaluate investment opportunities in automotive suspension companies, assess portfolio company exposure to market contraction, and identify consolidation targets with EV-focused capabilities.
- Market Entry & Expansion Teams : Need comprehensive China market analysis to assess viability of market entry, identify niche opportunities in EV suspension technologies, and understand competitive barriers in a contracting market environment.
- Strategic Consultants & Analysts : Require authoritative China suspension market data and forecasts to support client advisory work, competitive benchmarking, and strategic recommendations for automotive suppliers navigating the EV transition.
Key Companies in the China Automotive Suspension Market
| Company | HQ | Ownership | Strongest segments |
|---|---|---|---|
| GAZ | Russia | Public Company | Gas business (upstream, midstream, sales),Oil and refined products,Electric power and heat, |
| ALTEN | France | Public Company | Engineering and R&D services,Digital and IT services,Quality, testing, and QA services, |
| AISIN SEIKI CO LTD | Japan | Public Company | Automatic, CVT, and manual transmissions,eAxle and electrified driveline,Brakes, steering, and chassis systems, |
| METALSA | Mexico | Private Company | Light vehicle chassis structures and side rails,Heavy vehicle and commercial chassis structures,Fuel tanks and related structural systems, |
| WABCO HOLDINGS INC | Switzerland | Private Company | Electronic braking and stability systems (ABS, EBS, ESC, brake controls),Air management and conventional braking hardware (compressors, valves, actuators, air disc brakes),Transmission automation and driveline control, |
| RHEINMETALL AG | Germany | Public Company | Vehicle Systems (combat, logistics, support, special vehicles),Weapon and Ammunition (weapons, ammo, protection, propellants, services),Electronic Solutions (sensors, C2, networking, training & simulation), |
| FEDERAL-MOGUL CORPORATION | United States | Private Company | Engine and powertrain components,Sealing systems and gaskets,Friction and braking solutions, |
| ZF FRIEDRICHSHAFEN AG | Germany | Private Company | Passenger car driveline, chassis, and safety systems,Commercial vehicle and fleet systems (truck, bus, LCV, trailers),Industrial applications (construction, agriculture, marine, wind, rail, material handling), |
| HYUNDAI MOBIS | South Korea | Public Company | Auto modules (chassis, cockpit, front-end, bumpers),Electrification (power conversion, drive, battery, 48V),Autonomous driving and safety (ADAS, airbags, ECUs, in-cabin sensing), |
| TENNECO INC. | United States | Private Company | Clean air / emissions-control systems,Powertrain / engine components,Ride performance / suspension and damping, |
| THYSSENKRUPP AG | Germany | Public Company | Materials Services,Steel Europe,Automotive Technology, |
| DANA LIMITED | United States | Public Company | Biotechnology (bioprocessing and therapeutic manufacturing solutions),Life Sciences (research tools and genomic medicines),Diagnostics (clinical instruments, consumables, software, services), |
| MAGNA INTERNATIONAL INC. | Canada | Public Company | Body Exteriors & Structures,Power & Vision (incl. ADAS and control modules),Seating Systems and Interior/Exterior Mechatronics, |
| CONTINENTAL AG | Germany | Public Company | Passenger and light truck tires,Truck, bus, and fleet tires,Two-wheel and specialist vehicle tires, |
| KYB CORPORATION | Japan | Public Company | Restaurant Leasing and Subleasing Business,Food Retail Business (Restaurant Operations and Consultancy), |
| HL MANDO CORPORATION | South Korea | Public Company | Braking systems (electronic and foundation),Steering systems (EPS and mechanical),Suspension and EV suspension, |
| MERITOR, INC. | United States | Private Company | Axles, drivelines, and suspension systems,Brakes and related safety systems,Engines and power systems (on/off-highway), |
| SOGEFI | Italy | Public Company | Suspensions (coil, leaf, precision springs, stabilizer bars),Air & Cooling (intake manifolds, air induction, charged air ducts),EV Thermal (battery cooling plates, coolant pumps and modules), |
GAZ
GAZ is a Russian public company founded in 1993, employing 468,000 people and operating as a major industrial enterprise.
ALTEN
ALTEN is a French public company founded in 1988 with 56,376 employees, specializing in engineering and technology services.
AISIN SEIKI CO LTD
AISIN SEIKI CO LTD is a Japanese public company founded in 1943 with 113,292 employees, operating as a major automotive components manufacturer.
METALSA
METALSA is a Mexican private company founded in 1956 with 13,000 employees, operating in the automotive components industry.
WABCO HOLDINGS INC
WABCO HOLDINGS INC is a Swiss private company founded in 1869 with 13,911 employees, providing advanced technologies and services for commercial vehicles.
RHEINMETALL AG
RHEINMETALL AG is a German public company founded in 1889 with 28,815 employees, operating in automotive and defense technology sectors.
FEDERAL-MOGUL CORPORATION
FEDERAL-MOGUL CORPORATION is a United States-based private company founded in 1899 with 44,275 employees, specializing in automotive components and powertrain solutions.
ZF FRIEDRICHSHAFEN AG
ZF FRIEDRICHSHAFEN AG is a German private company founded in 1915 with 145,909 employees, a leading global supplier of driveline and chassis technology.
HYUNDAI MOBIS
HYUNDAI MOBIS is a South Korean public company founded in 1977, serving as a major automotive parts supplier and mobility solutions provider.
TENNECO INC.
TENNECO INC. is a United States-based private company founded in 1930 with 71,000 employees, specializing in automotive emission control and ride performance products.
THYSSENKRUPP AG
THYSSENKRUPP AG is a German public company founded in 1811 with 90,916 employees, operating across industrial engineering, materials, and automotive sectors.
DANA LIMITED
DANA LIMITED is a United States-based public company founded in 1969 with 59,000 employees, providing power transmission and sealing solutions for vehicles.
MAGNA INTERNATIONAL INC.
MAGNA INTERNATIONAL INC. is a Canadian public company founded in 1957 with 156,000 employees, a leading global automotive supplier and mobility solutions provider.
CONTINENTAL AG
CONTINENTAL AG is a German public company founded in 1871 with 22,076 employees, specializing in automotive technology and industrial solutions.
KYB CORPORATION
KYB CORPORATION is a Japanese public company founded in 2019, specializing in hydraulic and automotive suspension components.
HL MANDO CORPORATION
HL MANDO CORPORATION is a South Korean public company founded in 1962 with 3,585 employees, providing automotive braking and steering systems.
MERITOR, INC.
MERITOR, INC. is a United States-based private company founded in 1909 with 9,600 employees, specializing in drivetrain and mobility solutions for commercial vehicles.
SOGEFI
SOGEFI is an Italian public company founded in 1980 with 3,243 employees, specializing in automotive filtration and engine components.
Reasons to Buy this Report
- Identify Market Contraction Drivers : Understand the specific factors causing China's -1.1% CAGR decline, including EV adoption rates, manufacturer shifts, and competitive dynamics, enabling strategic planning for market entry or exit decisions.
- Competitive Intelligence : Gain insights into how Chinese and international suspension suppliers are adapting to market contraction, including consolidation strategies, technology pivots, and partnership opportunities in the EV transition.
- Technology Investment Guidance : Determine which suspension technologies (adaptive systems, air suspension, integrated chassis) are gaining traction in China's EV market to prioritize R&D investments and product development roadmaps.
- Supply Chain Optimization : Identify emerging gaps and opportunities in China's automotive suspension supply chain as traditional suppliers exit or consolidate, enabling strategic sourcing and partnership decisions.
- Market Sizing & Forecasting : Access precise market valuations (USD 125.9B in 2025, USD 116.8B in 2030) and segment-level forecasts specific to China to support financial modeling, investment decisions, and business case development.
Frequently asked questions
Why is China's automotive suspension market declining?
China's suspension market is contracting due to electrification of the automotive sector, where EV manufacturers prioritize lightweight and integrated suspension designs that differ from traditional architectures, combined with manufacturing overcapacity and shifting consumer preferences toward efficient mobility solutions.
What is the market size of automotive suspension in China in 2025?
China's automotive suspension market is valued at USD 125,986 million in 2025, making it a significant but declining segment within the broader Asia Pacific automotive supply chain.
What will China's suspension market size be in 2030?
China's automotive suspension market is forecast to reach USD 116,753 million by 2030, representing a decline of approximately USD 9,233 million from 2025 levels.
How are China's OEMs responding to suspension market contraction?
China's original equipment manufacturers are investing in next-generation suspension technologies including smart dampers, adaptive systems, and integrated chassis solutions designed for electric and autonomous vehicles to maintain competitiveness.
What opportunities exist in China's declining suspension market?
China's market contraction creates opportunities for suppliers specializing in advanced materials, lightweight composites, smart suspension systems, and integrated mobility solutions that align with the country's electrification and autonomous driving initiatives through 2030.
RESEARCH METHODOLOGY
The research study relied heavily on secondary sources, including company annual reports/presentations, industry association publications, magazines, directories, technical handbooks, the World Economic Outlook, trade websites, technical articles, and databases, to identify and collect information on the automotive suspension market. In-depth interviews were conducted with primary-source experts from related industry players, automotive suspension suppliers, and automotive OEMs to obtain and verify critical information and assess growth prospects and market estimates.
Secondary Research
In the secondary research process, various secondary sources were used to identify and collect information on the automotive suspension market for this study. The sources included automotive industry organizations such as Organisation Internationale des Constructeurs d'Automobiles (OICA), CAAM, JAMA, ACEA, etc., OE and aftermarket suspension manufacturers and suppliers, automotive component and aftermarket associations such as CLEPA, MEMA Aftermarket Suppliers, Auto Care Association, and AASA, suspension-specific technical and product publications, regulatory bodies, corporate filings such as annual reports, investor presentations, and financial statements, and trade, business, and automotive associations. Secondary data has been collected and analyzed to arrive at the overall market size, which has been further validated through primary research.
Primary Research
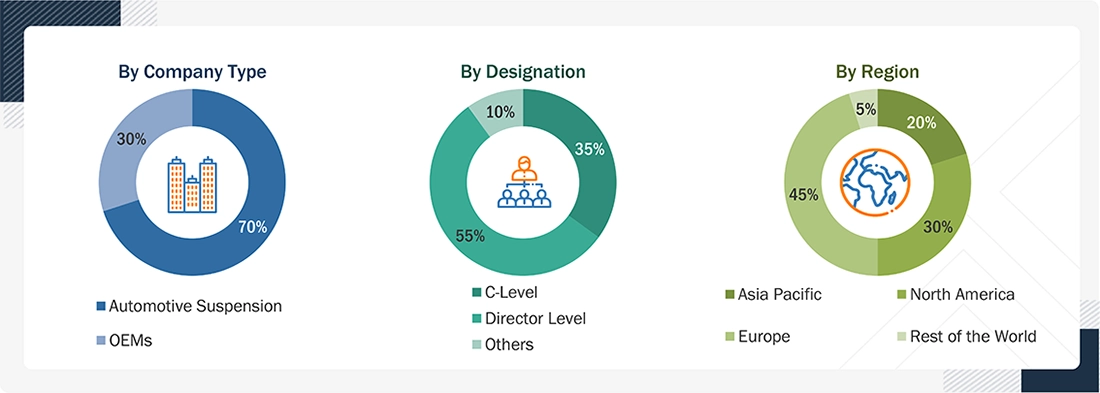
Extensive primary research was conducted after gaining an understanding of the automotive suspension market scenario through secondary research. Several primary interviews have been conducted with market experts from both the demand side (automotive OEMs) and the supply side (automotive suspension manufacturers and distributors), and players across 4 major regions, namely, North America, Europe, Asia Pacific, and the Rest of the World. Approximately 30% of primary interviews from the demand side and 70% from the supply side have been conducted. Primary data has been collected through questionnaires, emails, and telephonic interviews.
In our canvassing of primary interviews, we have strived to cover various departments within organizations, such as sales, operations, and administration, to provide a holistic viewpoint in our reports. After interacting with industry participants, we have also conducted brief sessions with highly experienced independent consultants to reinforce the findings from our primary interviews. This, along with the in-house subject-matter experts’ opinions, has led us to the findings as described in the remainder of this report.
To know about the assumptions considered for the study, download the pdf brochure
Market Size Estimation
A detailed market estimation approach was followed to estimate and validate the size of the automotive suspension market and other dependent submarkets, as mentioned below:
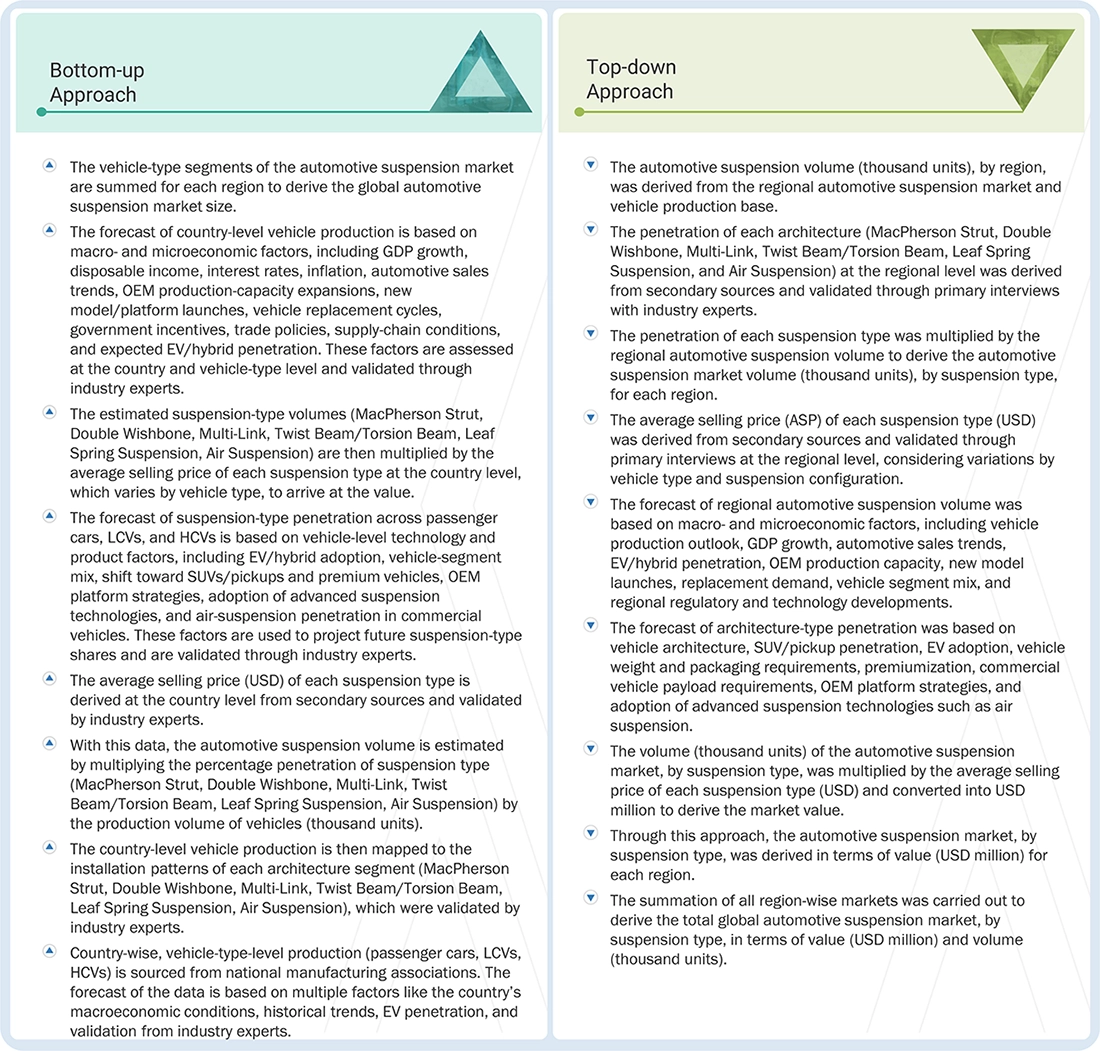
Bottom-up Approach
- Key players in the automotive suspension market were identified through secondary research, and their global market share was determined through primary and secondary research.
- The study identified the percentage penetration of major suspension types—MacPherson Strut, Double Wishbone, Multi-Link, Twist/Torsion Beam, Leaf Spring, Air Suspension, and other advanced systems—across passenger cars, LCVs, HCVs, buses, and EVs. Model-level mapping of OEM vehicles was used to determine the suspension configuration by country, vehicle type, model/variant, and powertrain.
- The suspension penetration rates for each vehicle type and country were multiplied by the corresponding vehicle production volume to calculate suspension demand in million units. These calculations were performed at the country level and aggregated to regional and global market volumes.
- All major penetration rates, vehicle-type splits, suspension-type shares, model mappings, and volume estimates were derived through secondary research and subsequently validated and refined through primary interviews with OEMs, Tier-1 suppliers, suspension manufacturers, and industry experts.
- Country-level average selling prices (ASPs) were established for each suspension type based on vehicle category, technology content, system configuration, and regional pricing. ASPs for MacPherson Strut, Double Wishbone, Multi-Link, Twist/Torsion Beam, Leaf Spring, Air Suspension, and advanced suspension systems were benchmarked through secondary research and validated through primary interviews.
- The value market was derived by multiplying the validated number of suspension units (thousand units) by the corresponding country-level ASP for each suspension type and vehicle category, followed by aggregation across countries and regions to determine the global market value.
- The summation of all country-level data for volume and value gave the global market for automotive suspension.
-
Top-down Approach
- The top-down approach was used to estimate and validate the regional size of the automotive suspension market, by suspension type (MacPherson Strut, Double Wishbone, Multi-Link, Twist Beam/Torsion Beam, Leaf Spring Suspension, and Air Suspension), in terms of volume and value.
- The global automotive suspension market was broken down into regional markets across North America, Europe, Asia Pacific, Latin America, and Middle East & Africa, based on regional vehicle production, suspension technology adoption, and market penetration.
- The market share/penetration of each suspension type was estimated at the regional level using historical installation patterns, vehicle mix, OEM fitment data, technology adoption trends, and secondary research. It was validated through primary interviews with industry experts.
- The penetration of each suspension type was multiplied by the regional vehicle production volume to estimate the automotive suspension market volume by suspension type and region.
- The average selling price (ASP) of each suspension type was derived from secondary sources, supplier/OEM pricing references, industry databases, and primary interviews, with variations considered by vehicle type and region.
- The volume of each suspension type was multiplied by its respective regional ASP to estimate the market value in USD million.
- Forecasts of the regional automotive suspension market were based on macro- and microeconomic factors, including vehicle production growth, GDP and automotive demand trends, EV/hybrid penetration, OEM production capacity, vehicle segment mix, new model launches, adoption of advanced suspension technologies, and regional regulatory and technology developments.
- The suspension-type mix forecast considered vehicle architecture changes, increasing SUV/pickup penetration, EV weight and packaging requirements, premium vehicle adoption, commercial vehicle payload requirements, and OEM adoption of air and other advanced suspension systems, supported by industry expert validation.
- The summation of region-wise markets was carried out to derive the total global automotive suspension market, by suspension type, in terms of value (USD million) and volume (thousand units).
Data Triangulation
After arriving at the overall market size of the global market through the above-mentioned methodology, this market was split into several segments and subsegments. The data triangulation and market breakdown procedures were employed, wherever applicable, to complete the overall market engineering process and arrive at the exact data for the market by value for the key segments and subsegments. The extrapolated market data was triangulated by studying various macro indicators and regional trends from both the demand and supply participants.
Market Definition
A suspension is the arrangement of shock absorbers, springs, tires, and linkages that connect a vehicle to its wheels and allow movement between the wheel and suspension components. The suspension system minimizes shocks transmitted to the vehicle body while moving over a surface. It makes the ride comfortable and keeps the tires in constant contact with the surface, regardless of contours. A suspension needs to keep the wheel in contact with the road surface to maintain the driver’s control of the vehicle.
Key Stakeholders
- Automotive suspension manufacturers
- Automotive raw material suppliers
- Automotive OEMs
- Research & Development (R&D) Centers
- Associations, forums, and alliances related to automobiles
- Automobile organizations/associations
- EV component manufacturers
- EV manufacturers
- Government agencies and policymakers
- Traders and distributors of automotive suspension
Report Objectives
- To segment and forecast the size of the automotive suspension market in terms of volume (Million Units) & value (USD million) from 2022 to 2033
- To define, describe, and forecast the automotive suspension market in terms of volume & value (USD million)
- To define, describe, and forecast the global automotive suspension market based on system, vehicle type, architecture, OE component, EV type, off-highway vehicles, ATV, and region.
- To segment and forecast the market size of the automotive suspension market by architecture (MacPherson Strut, Double Wishbone, Multilink, Twist Beam/Torsion Beam, and Air Suspension).
- To segment and forecast the market size of the automotive suspension market by vehicle type (ICE) (Passenger Car, Light Commercial Vehicle, and Heavy Commercial Vehicle)
- To segment and forecast the market size of the Electric & Hybrid Passenger Cars Suspension Market by Architecture (MacPherson Strut, Double Wishbone, Multilink, Twist Beam/Torsion Beam, and Air Suspension)
- To segment and forecast the market size of the Electric & Hybrid HCVs Suspension Market, by Vehicle Type (Trucks and Buses)
- To segment and forecast the market size of the Off-highway Vehicles Suspension Market, by Application (Construction Equipment and Agricultural Tractors)
- To segment and forecast the market size of the ATV Suspension Market by Region (Asia Pacific, Europe, and North America)
- To forecast market size by key regions, namely Asia Pacific, Europe, North America, and the Rest of the World.
- To provide detailed information regarding the major factors influencing market growth (drivers, challenges, restraints, and opportunities)
- To strategically analyze markets with respect to individual growth trends, prospects, and contributions to the total market
- To strategically profile key players and comprehensively analyze their market share and core competencies
- To study the following with respect to the market:
- Supply Chain Analysis
- Ecosystem Analysis
- Technology Analysis
- HS Code Analysis
- Case Study Analysis
- Patent Analysis
- Regulatory Landscape
- Conferences and Events
- Key Stakeholders and Buying Criteria
- Investment and Funding Scenario
- Unmet Needs and White Spaces
- Strategic Moves by Tier 1/2/3 Players
- Interconnected Markets and Cross-sector Opportunities
- Market Profitability
- To analyze opportunities for stakeholders and the competitive landscape for market leaders
- To track and analyze competitive developments such as product developments, deals, and others undertaken by the key industry participants
Available customizations:
With the given market data, MarketsandMarkets offers customizations to meet the company’s specific needs.
- Front Suspension, by architecture and vehicle type — Passenger Cars, LCVs, HCVs; MacPherson Strut, Double Wishbone, Multi-link, Torsion Beam, Leaf Spring, and Other Architectures — Country/Regional Level
- Rear Suspension, by architecture and vehicle type — Passenger Cars, LCVs, HCVs; Multi-link, Torsion Beam, Leaf Spring, Double Wishbone, MacPherson Strut, and Other Architectures — Country/Regional Level
- Passive, Semi-active, and Active Suspension, by architecture and vehicle type — Passenger Cars, LCVs, HCVs; Country/Regional Level
- Electric and Hybrid Vehicles, by vehicle type — Passenger Cars, LCVs, HCVs — Regional Level
- Off-highway Vehicles, by vehicle type and region — Construction, Agriculture, Mining, and Other Off-highway Vehicles — Regional Level
Get the Full Automotive Suspension Market Report
Full forecast, segment splits, and company analysis for all Automotive Suspension Market.
- India Automotive Suspension Market
- Japan Automotive Suspension Market
- South Korea Automotive Suspension Market
- US Automotive Suspension Market
- Mexico Automotive Suspension Market
- Canada Automotive Suspension Market
- Germany Automotive Suspension Market
- UK Automotive Suspension Market
- France Automotive Suspension Market
- Spain Automotive Suspension Market
- Italy Automotive Suspension Market
- Russia Automotive Suspension Market
- Brazil Automotive Suspension Market
- South Africa Automotive Suspension Market
- Iran Automotive Suspension Market
Need a Tailored Report?
Customize this report to your needs
Get 10% FREE Customization
Customize This Report