UK Cancer Diagnostics Market (2021-2026)
The UK Cancer Diagnostics Market was valued at $450 Million in 2021 and projected to reach to $860.6 Million by 2026, representing a compound annual growth rate of 13.8%. The UK cancer diagnostics market is poised for substantial growth through 2026, supported by the NHS's commitment to early cancer detection and the integration of advanced diagnostic technologies.

| Market Size in | USD 26.32 MN |
| Market Forecast in | |
| CAGR | |
| Forecast Period | |
| Units Considered | Value (USD MN) |
UK Cancer Diagnostics Market Trends and Insights
- The UK's advanced healthcare infrastructure, coupled with rising cancer incidence rates and increased investment in early detection technologies, is driving robust market expansion.
- The UK's National Health Service (NHS) commitment to cancer screening and diagnostic innovation has positioned the country as a leader in precision oncology diagnostics across Europe. The UK cancer diagnostics market is experiencing accelerated adoption of molecular and genomic testing platforms, driven by growing demand for personalized treatment approaches.
- Between 2021 and 2026, the UK is expected to see significant growth in liquid biopsy, immunohistochemistry, and next-generation sequencing (NGS) technologies.
- The UK's regulatory environment and reimbursement policies continue to support the integration of advanced diagnostic solutions into clinical practice, making the market increasingly attractive for both established and emerging diagnostic providers..
Key Market Statistics
- CAGR (2021-2026) 13.8% CAGR
- Market Size, 2021 ~USD 450 Million
- Forecast, 2026 ~USD 860.6 Million
- Country UK
UK Cancer Diagnostics Market Overview
Strong Market Growth :
The UK cancer diagnostics market is experiencing robust expansion with a CAGR of 13.8%, significantly outpacing the global average of 11.5%, driven by NHS investment and technological advancement.
NHS Infrastructure Advantage :
The UK's National Health Service provides a centralized healthcare system with standardized diagnostic protocols, enabling rapid adoption of innovative cancer detection technologies across all regions.
Rising Cancer Incidence :
Increasing cancer prevalence in the UK population is creating sustained demand for advanced diagnostic solutions, with early detection initiatives becoming a priority across NHS trusts.
Market Valuation Trajectory :
The market is projected to nearly double from £450.0 million in 2021 to £860.6 million by 2026, reflecting strong investment in precision medicine and diagnostic innovation.
UK Cancer Diagnostics Market Dynamics
- Government funding initiatives and partnerships between healthcare providers and diagnostic companies are accelerating the adoption of innovative testing methodologies, including liquid biopsies and AI-powered imaging solutions.
- The market's outperformance relative to global trends reflects the UK's mature healthcare infrastructure and regulatory environment that facilitates rapid technology deployment.
- Continued investment in cancer research and diagnostic capabilities will sustain this growth trajectory, positioning the UK as a leader in European cancer diagnostics innovation..
Market Ecosystem
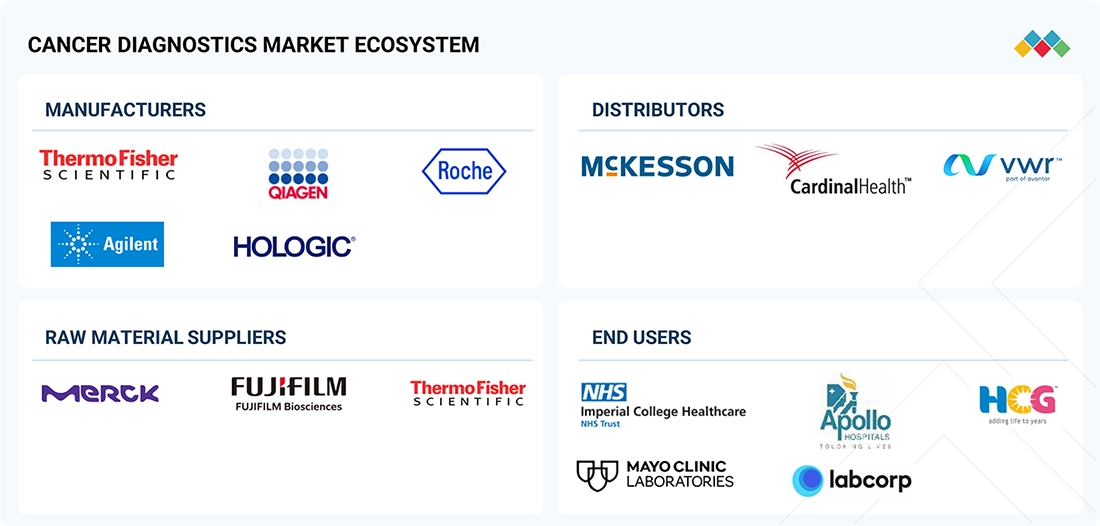
CANCER DIAGNOSTICS MARKET: COMMERCIAL USE CASES ACROSS INDUSTRIES
| COMPANY | USE CASE DESCRIPTION | BENEFITS |
|---|---|---|
 |
Develops molecular and tissue-based cancer diagnostic solutions, including companion diagnostics, PCR-based assays, next-generation sequencing (NGS), immunohistochemistry (IHC), and digital pathology for oncology applications. | Enables early and accurate cancer detection, supports personalized treatment selection, improves diagnostic confidence, and enhances patient outcomes through precision medicine. |
 |
Develops advanced cancer diagnostic solutions, including molecular diagnostics, HPV testing, cervical cytology, breast imaging (3D mammography/tomosynthesis), biopsy systems, and digital pathology technologies for early cancer detection, diagnosis, and treatment guidance. | Enables early and accurate cancer detection, improves screening and diagnostic accuracy, supports personalized treatment decisions, enhances workflow efficiency, and improves patient outcomes through comprehensive oncology diagnostics. |
 |
Provides molecular oncology testing, digital pathology, tissue diagnostics, flow cytometry, and NGS solutions for detecting cancer biomarkers, monitoring disease progression, and guiding targeted therapies. | Delivers rapid and precise cancer diagnosis, improves laboratory efficiency, supports personalized oncology care, and enables informed treatment decisions. |
 |
Provides advanced imaging technologies, laboratory diagnostics, molecular testing, and AI-enabled solutions for cancer screening, diagnosis, staging, and therapy monitoring. | Enhances early cancer detection, improves diagnostic precision, supports treatment planning, and streamlines oncology workflows. |
 |
Develops molecular diagnostic kits, sample preparation technologies, companion diagnostics, and NGS workflows for identifying cancer-related genetic mutations and biomarkers. | Enables accurate biomarker detection, supports precision oncology, accelerates molecular testing, and improves patient stratification for targeted therapies. |
Logos and trademarks shown above are the property of their respective owners. Their use here is for informational and illustrative purposes only.
Related Ecosystem
In Vitro Diagnostics
- Polymerase Chain Reaction (PCR)
- Enzyme-Linked Immunosorbent Assay (ELISA)
- Dna Microarrays
- Assay Kits
- Microarrays
- ROCHE HOLDINGS AG
- Thermo Fisher Scientific Inc.
- Danaher Corporation
- Abbott Laboratories
- Biomerieux s.a.
Medical Devices
- Polymerase Chain Reaction (PCR)
- Magnetic Resonance Imaging (MRI)
- Disposable Autoinjectors
- Pulse Oximeters
- Blood Pressure Monitors
- Medtronic plc
- Abbott Laboratories
- Stryker Corporation
- Becton, Dickinson and Company
- CONMED Corporation
Key Takeaways
- The UK cancer diagnostics market is projected to nearly double from £450.0M (2021) to £860.6M (2026) at a 13.8% CAGR.
- The UK's NHS-backed cancer screening programs and precision medicine initiatives are key drivers of market growth.
- Molecular and genomic testing technologies are experiencing the fastest adoption rates across UK diagnostic centers.
- The UK's favorable regulatory framework and reimbursement landscape support sustained investment in advanced cancer diagnostic solutions.
Cancer Diagnostics Market Report Scope
| Report Metric | Details |
|---|---|
| Base Year | 2021 |
| Fastest Growing Segment | BREAST CANCER (Application) |
| Forecast Period | 2021-2026 |
| Growth Rate | CAGR of 11.5% from 2021 to 2026 |
| Largest Segment | HOSPITALS (End User) |
| Market Size Base Year (Billions) | ~USD 15.44 (2021) |
| Revenue Forecast (Billions) | ~USD 26.6 (2026) |
| Segments Covered | Product, Type, Technology, Application, End User |
UK Cancer Diagnostics Market Report Segmentation
5 segment dimensions are covered across the global market.
By Product
- Consumables
- Instruments
By Type
- Antibodies
- Biopsy Instruments
- Cell Processors
- Ct
- Ct Systems
- Flow Cytometry
- Ihc
- Imaging Instruments
- Immunoassay
- Ish
- Kits & Reagents
- Mammography
- Mammography Systems
- Microarray
- Microarrays
- Microarrays Instruments
- Mri
- Mri Systems
- Ngs
- Ngs Instruments
- Nuclear Imaging
- Nuclear Imaging Systems
- Other Consumables
- Other Ivd Technologies
- Other Pathology-Based Instruments
- Pathology-Based Instruments
- Pcr
- Pcr Instruments
- Probes
- Slide Staining Systems
- Tissue Processing Systems
- Ultrasound
- Ultrasound Systems
By Technology
- Biopsies
- Imaging Technologies
- Ivd Testing
By Application
- Breast Cancer
- Colorectal Cancer
- Lung Cancer
- Melanoma
- Other Cancers
By End User
- Diagnostic Laboratories
- Hospitals
Target Audience
- Diagnostic Device Manufacturers : Need UK-specific market data to develop go-to-market strategies, identify NHS partnership opportunities, and understand competitive positioning for cancer diagnostic products.
- Healthcare Investors & PE Firms : Require detailed market sizing and growth projections to evaluate investment opportunities in UK cancer diagnostics companies and assess portfolio company expansion potential.
- NHS Trust Procurement Teams : Seek market intelligence on available diagnostic solutions, pricing benchmarks, and technology trends to optimize procurement decisions and improve cancer detection capabilities.
- Pharmaceutical & Biotech Companies : Need companion diagnostic insights and market trends to support oncology drug development strategies and identify partnership opportunities with UK diagnostic providers.
- Healthcare Consultants & Analysts : Require comprehensive UK market data and forecasts to support client advisory work, strategic planning, and competitive analysis in the cancer diagnostics sector.
Reasons to Buy this Report
- NHS Market Penetration Strategy : Understand how to navigate NHS procurement processes and identify opportunities for diagnostic solutions across England, Scotland, Wales, and Northern Ireland with region-specific insights.
- Competitive Landscape Intelligence : Gain detailed analysis of UK-based and international diagnostic companies operating in the market, including their market share, product portfolios, and strategic positioning.
- Regulatory & Reimbursement Pathways : Access comprehensive guidance on NICE approval processes, MHRA regulations, and NHS reimbursement mechanisms specific to cancer diagnostic technologies in the UK.
- Growth Opportunity Identification : Identify high-growth segments within UK cancer diagnostics, including emerging technologies, underserved regions, and partnership opportunities with NHS trusts and private providers.
- Investment & Expansion Planning : Leverage market forecasts and trend analysis to make informed decisions about market entry, product launches, and capital allocation in the UK cancer diagnostics sector.
Frequently asked questions
What is the current size of the UK cancer diagnostics market?
The UK cancer diagnostics market was valued at £450.0 million in 2021 and is expected to reach £860.6 million by 2026.
What is the projected growth rate for the UK cancer diagnostics market?
The UK cancer diagnostics market is expected to grow at a compound annual growth rate (CAGR) of 13.8% between 2021 and 2026.
Which diagnostic technologies are driving growth in the UK market?
Molecular and genomic testing, liquid biopsy, immunohistochemistry, and next-generation sequencing (NGS) are the primary technologies driving UK market expansion.
How is the UK NHS influencing the cancer diagnostics market?
The UK NHS's commitment to cancer screening programs and precision medicine initiatives is significantly accelerating adoption of advanced diagnostic solutions across the country.
What factors support investment in UK cancer diagnostics?
The UK's favorable regulatory environment, robust reimbursement policies, advanced healthcare infrastructure, and rising cancer incidence rates create a compelling investment landscape.
RESEARCH METHODOLOGY
The study involved major activities in estimating the current market size for the Cancer Diagnostics market. Exhaustive secondary research was done to collect information on the Cancer Diagnostics market. The next step was to validate these findings, assumptions, and sizing with industry experts across the value chain using primary research. Different approaches, such as top-down and bottom-up, were employed to estimate the total market size. After that, the market breakup and data triangulation procedures were used to estimate the market size of the segments and subsegments of the Cancer Diagnostics market.
Secondary Research
This research study involved the wide use of secondary sources, directories, databases such as Dun & Bradstreet, Bloomberg Businessweek, Factiva, whitepapers, and companies’ house documents. Secondary research was undertaken to identify and collect information for this extensive, technical, market-oriented, and commercial study of the Cancer Diagnostics market. It was also used to obtain important information about the top players, market classification, and segmentation according to industry trends to the bottom-most level, geographic markets, and key developments related to the market. A database of the key industry leaders was also prepared using secondary research.
Primary Research
In the primary research process, various supply- and demand-side sources were interviewed to obtain qualitative and quantitative information for this report. Primary sources from the supply side included industry experts such as CEOs, VPs/Managing Directors, Marketing Heads/Directors and Sales Directors, Marketing/Sales Managers, Regional/Area Sales Managers, Export/Import Heads/Managers, and Other Cancer Diagnostics Market Related Personnel from various companies and organizations operating in the Cancer Diagnostics market. Primary sources from the demand side included Law Enforcement Agencies Vice Presidents,C-level Executives, Department Heads, Enterprises, Individuals, Supply Management Team of Hospitals, Clinic Personnel, and Laboratory Technicians.
Breakdown of Primary Interviews
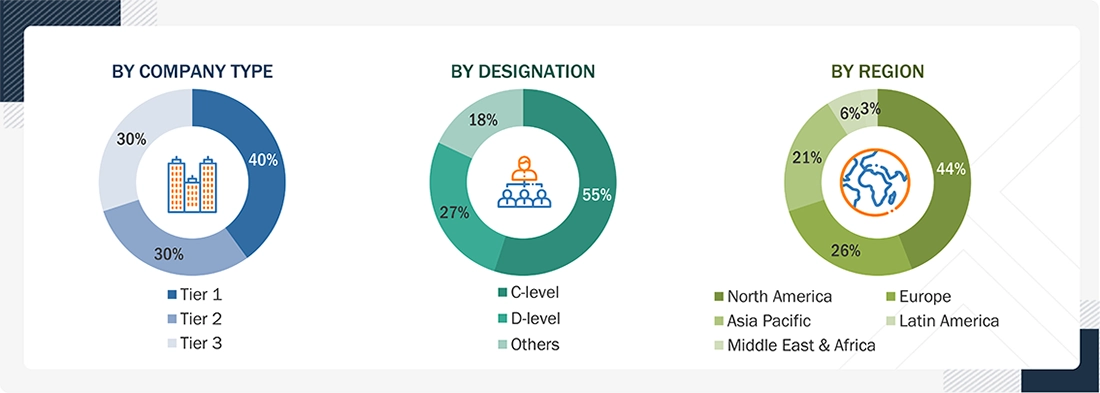
Note 1: C-level primaries include CEOs, COOs, CTOs, and VPs.
Note 2: Other primaries include sales, marketing, and product managers.
Note 3: Companies are classified into tiers based on their total revenue. As of 2025: Tier 1 = >USD 1 billion, Tier 2 = USD 500 million to USD 1 billion, and Tier 3 = <USD 500 million.
To know about the assumptions considered for the study, download the pdf brochure
Market Size Estimation
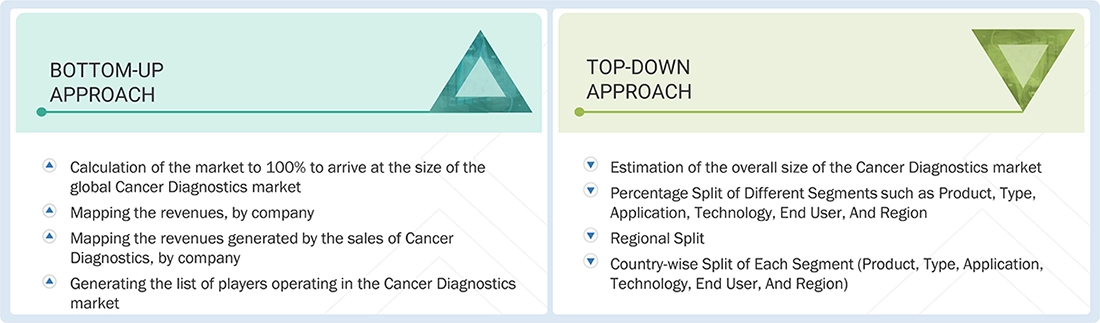
Both top-down and bottom-up approaches were used to estimate and validate the total size of the Cancer Diagnostics market. These methods were also used extensively to estimate the size of various subsegments in the market. The research methodology used to estimate the market size includes the following:
Cancer Diagnostics Market : Top-Down and Bottom-Up Approach
Data Triangulation
The entire market was split into two segments when the market size was determined. Data triangulation and market breakdown processes were used where necessary to complete the entire market engineering process and arrive at precise statistics for all segments.
Approach to derive the market size and estimate market growth.
Using secondary data from paid and unpaid sources, the market rankings for the major players were determined following a thorough analysis of their sales of Cancer Diagnostics . Due to data restrictions, the revenue share in certain cases was determined after a thorough analysis of the product portfolio of big corporations and their individual sales performance. This information was verified at each stage by in-depth interviews with professionals in the field.
Market Definition
Cancer diagnostics refers to the tests, technologies, and procedures used to detect, diagnose, characterize, and monitor cancer, enabling early detection, accurate diagnosis, treatment selection, and disease monitoring. The market includes imaging, molecular diagnostics, biopsy-based testing, immunohistochemistry (IHC), next-generation sequencing (NGS), liquid biopsy, and companion diagnostics, serving hospitals, diagnostic laboratories, cancer centers, and research institutes.
Key Stakeholders
- Diagnostic test and kit manufacturers
- Medical device and imaging equipment manufacturers
- Molecular diagnostics and genomics companies
- Hospitals and healthcare systems
- Diagnostic laboratories (clinical and reference laboratories)
- Cancer centers and oncology clinics
- Physicians (oncologists, pathologists, radiologists, and primary care physicians)
- Academic and research institutes
- Pharmaceutical and biotechnology companies (companion diagnostics and precision medicine)
- Contract research organizations (CROs)
- Government and public health agencies
- Regulatory authorities
- Health insurance providers and payers
- Patients and patient advocacy organizations
- Distributors and healthcare suppliers
Report Objectives
- To describe, analyze, and forecast the Cancer Diagnostics market, by product, type, application, technology, end user, and region.
- To describe and forecast the Cancer Diagnostics market for key regions, namely, North America, Europe, the Asia Pacific, Latin America and Middle East and Africa
- To provide detailed information regarding drivers, restraints, opportunities, and challenges influencing the growth of the Cancer Diagnostics market
- To strategically analyze the ecosystem, regulations, patenting trend, value chain, Porter’s five forces, and prices pertaining to the market under study
- To strategically analyze micromarkets1 with respect to individual growth trends, prospects, and contributions to the overall market
- To analyze market opportunities for stakeholders and provide details of the competitive landscape for market players
- To profile key players and comprehensively analyze their market shares and core competencies2 in the Cancer Diagnostics market
- To analyze competitive developments such as collaborations, acquisitions, product launches, expansions, and R&D activities in the Cancer Diagnostics market
Available customizations:
With the given market data, MarketsandMarkets offers customizations as per your company’s specific needs. The following customization options are available for the report:
Company Information
- Detailed analysis and profiling of additional market players (up to 5)
Product Analysis
- Product matrix, which gives a detailed comparison of the product portfolios of each company
Geographic Analysis
- Further breakdown of the Rest of Asia Pacific Cancer Diagnostics market into Vietnam, New Zealand, and others.
- Further breakdown of the Rest of Latin America Cancer Diagnostics market into Columbia, Chile, Ecuador, and others.
- Further breakdown of the Rest of Europe Cancer Diagnostics market into Belgium, Russia, Netherlands, Switzerland, and others.
Get the Full Cancer Diagnostics Market Report
Full forecast, segment splits, and company analysis for all Cancer Diagnostics Market.
- US Cancer Diagnostics Market
- Canada Cancer Diagnostics Market
- Germany Cancer Diagnostics Market
- France Cancer Diagnostics Market
- Italy Cancer Diagnostics Market
- Spain Cancer Diagnostics Market
- China Cancer Diagnostics Market
- Japan Cancer Diagnostics Market
- India Cancer Diagnostics Market
- Rest Of Europe Cancer Diagnostics Market
- Roapac Cancer Diagnostics Market
Need a Tailored Report?
Customize this report to your needs
Get 10% FREE Customization
Customize This Report