UK Dental Equipment Market (2026-2031)
The UK Dental Equipment Market was valued at $30.2 Million in 2026 and projected to reach to $33.6 Million by 2031, representing a compound annual growth rate of 3.5%. The UK dental equipment market is experiencing steady growth driven by demographic shifts and healthcare modernization.

| Market Size in | USD 26.32 MN |
| Market Forecast in | |
| CAGR | |
| Forecast Period | |
| Units Considered | Value (USD MN) |
UK Dental Equipment Market Trends and Insights
- The UK market reflects steady but moderate expansion, driven by aging demographics, increased dental awareness, and NHS modernization initiatives.
- The UK's mature healthcare infrastructure and regulatory environment support consistent demand for advanced diagnostic and treatment equipment. Growth in the UK dental equipment sector is underpinned by rising cosmetic dentistry adoption, digital transformation in dental practices, and investment in preventive care.
- The UK market benefits from strong private dental practice expansion alongside public sector upgrades.
- Between 2026 and 2031, the UK is expected to see incremental adoption of CAD/CAM systems, intraoral scanners, and imaging technologies, though growth remains conservative compared to emerging markets. The UK's competitive landscape features both established multinational suppliers and specialized regional manufacturers.
- Regulatory compliance with UK dental standards and NHS procurement requirements shapes market dynamics.
- The UK market's trajectory reflects a balance between innovation adoption and cost-conscious healthcare spending..
Key Market Statistics
- CAGR (2026-2031) 3.5% CAGR
- Market Size, 2026 ~USD 30.2 Million
- Forecast, 2031 ~USD 33.6 Million
- Country UK
UK Dental Equipment Market Overview
Market Valuation :
The UK dental equipment market is valued at $30.2 million in 2026 and is projected to reach $33.6 million by 2031, with a steady CAGR of 3.5%.
NHS Modernization Impact :
NHS modernization initiatives and increased investment in dental infrastructure are driving equipment upgrades across public and private dental practices throughout the UK.
Aging Demographics :
The UK's aging population is increasing demand for advanced dental treatments and equipment, particularly for restorative and cosmetic dental procedures.
Regulatory Environment :
The UK's mature healthcare infrastructure and stringent regulatory standards ensure consistent demand for compliant, high-quality dental equipment from established manufacturers.
UK Dental Equipment Market Dynamics
- Aging populations are increasing demand for advanced dental treatments, while NHS investment in practice upgrades supports equipment procurement.
- The market benefits from a mature regulatory framework and strong emphasis on dental health awareness among UK consumers. Future growth will be supported by technological advancements in digital dentistry, increased private practice expansion, and continued NHS funding for equipment modernization.
- However, growth remains moderate compared to global markets, reflecting the UK's mature market status and established competitive landscape.
- Strategic focus on innovation and compliance will be essential for market participants..
Market Ecosystem
DENTAL EQUIPMENT MARKET: COMMERCIAL USE CASES ACROSS INDUSTRIES
| COMPANY | USE CASE DESCRIPTION | BENEFITS |
|---|---|---|
 |
Dentsply Sirona's Primeprint is a high-precision dental 3D printing system for in-office and laboratory use. It enables rapid production of dental restorations, including surgical guides, crowns, bridges, and splints, through an automated, fully integrated digital workflow. Primeprint can be seamlessly integrated with intraoral scanners and CAD/CAM software, enabling efficient chairside and lab-based fabrication. | Primeprint improves workflow efficiency by reducing turnaround times and minimizing reliance on external laboratories. Its high accuracy ensures consistent restoration quality, while automation reduces manual errors and labor costs. The system supports same-day dentistry, enhances patient satisfaction, and enables dental practices to expand their digital services. |
 |
CBCT systems are part of Planmeca's 3D imaging solutions, used for advanced diagnostics and treatment planning in implantology, orthodontics, endodontics, and maxillofacial surgery. Such systems provide a three-dimensional visualization of dental and craniofacial structures in great detail, supporting very precise clinical decision-making. | Planmeca’s 3D imaging improves diagnostic accuracy and treatment predictability while enhancing patient safety through optimized radiation dosing. High-quality imaging enables precise planning of complex procedures, reduces procedural risks, and improves clinical outcomes, making it a critical tool for modern dental practices. |
 |
The Align Technology intraoral scanner captures highly accurate digital impressions for orthodontic, restorative, and cosmetic dental procedures. These eliminate the use of conventional impression materials and integrate directly into digital treatment planning and aligner manufacturing workflows. | Intraoral scanners enhance patient comfort by eliminating messy impressions and reducing chair time. They improve impression accuracy, enable faster case submission, and support seamless digital workflows. This leads to improved treatment efficiency, better clinical outcomes, and higher patient satisfaction. |
 |
Envista's dental curing lights are used to polymerize light-cured dental materials, such as composites, adhesives, and sealants, in restorative dentistry. These devices are widely used in routine restorative and cosmetic procedures in dental clinics. | Envista's curing lights provide a steady, powerful light output, ensuring the material is thoroughly cured and the restoration lasts. Their comfortable design makes the clinician's work easier, while fast curing times reduce procedure time, thereby enhancing practice efficiency and patient throughput. |
 |
Carestream Dental's dental chairs support various procedures by positioning patients securely while providing ergonomic access for clinicians. These chairs are utilized in general dentistry, orthodontics, and surgical applications within dental clinics and hospitals. | Carestream’s dental chairs are designed to prioritize patient comfort and safety during procedures while simultaneously enhancing clinician ergonomics and workflow efficiency. Features such as advanced positioning and integrated delivery systems help operators avoid fatigue, ensure smooth procedures, and create a clinical environment that is both productive and welcoming for patients. |
Logos and trademarks shown above are the property of their respective owners. Their use here is for informational and illustrative purposes only.
Related Ecosystem
Key Takeaways
- The UK dental equipment market is valued at $30.2M in 2026 and will reach $33.6M by 2031 at a 3.5% CAGR.
- The UK market is driven by NHS modernization, private practice expansion, and increased adoption of digital dental technologies.
- The UK's mature regulatory environment and aging population support steady, predictable demand for dental equipment.
- The UK market shows conservative growth compared to global trends, reflecting cost-conscious healthcare spending and market maturity.
Dental Equipment Market Report Scope
| Report Metric | Details |
|---|---|
| Base Year | 2026 |
| Fastest Growing Segment | DIAGNOSTIC DENTAL EQUIPMENT (End User) |
| Forecast Period | 2026–2031 |
| Growth Rate | CAGR of 7.2% from 2026 to 2031 |
| Largest Segment | THERAPEUTIC DENTAL EQUIPMENT (End User) |
| Market Size Base Year (Billions) | ~USD 8.72 (2026) |
| Revenue Forecast (Billions) | ~USD 12.34 (2031) |
| Segments Covered | Type, Product, End User, Type 2022–2029 |
UK Dental Equipment Market Report Segmentation
4 segment dimensions are covered across the global market.
By Type
- 3D Cbct Systems
- 3D Printing Equipment
- All-Tissue Lasers
- Cad/Cam Systems
- Carbon-Dioxide Lasers
- Casting Machines
- Ceramic Furnaces
- Dental Chairs
- Dental Handpieces
- Dental Imaging Software
- Dental Laboratory Equipment
- Dental Lasers
- Dental Light-Curing Equipment
- Dental Operatory & Treatment Center Equipment
- Dental Units
- Diode Lasers
- Electrosurgical Systems
- Er,Cr:Ysgg Lasers
- Er:Yag Lasers
- Extraoral Imaging Systems
- Instrument Delivery Systems
- Intraoral Cameras
- Intraoral Imaging Systems
- Intraoral Photostimulable Phosphor Systems
- Intraoral Sensors
- Intraoral X-Ray Systems
- Milling Equipment
- Nd:Yag Lasers
- Other Dental Laboratory Equipment
- Other Dental Operatory & Treatment Center Equipment
- Panoramic & Cephalometric Systems
- Panoramic Systems
- Soft-Tissue Lasers
By Product
- Diagnostic Dental Equipment
- Therapeutic Dental Equipment
By End User
- Academic & Research Institutes
- Hospitals & Clinics
- Other End Users
By Type 2022–2029
- Carbon-Dioxide Lasers
- Diode Lasers
- Nd:Yag Lasers
UK: DENTAL EQUIPMENT MARKET, BY END USER, 2024–2031
| Segment | 2024 | 2025 | 2026 | 2027 | 2028 | 2029 | 2030 | 2031 | CAGR (%) |
|---|---|---|---|---|---|---|---|---|---|
| ACADEMIC & RESEARCH INSTITUTES | 50.6 | 52.8 | 55.2 | 57.8 | 60.6 | 63.7 | 67 | 70.7 | 5.1 |
| HOSPITALS & CLINICS | 288.6 | 305.7 | 324.5 | 345 | 367.5 | 392.2 | 419.3 | 449 | 6.7 |
| OTHER END USERS | 78.2 | 82.2 | 86.6 | 91.4 | 96.6 | 102.3 | 108.5 | 115.3 | 5.9 |
| TOTAL | 417.4 | 440.8 | 466.3 | 494.2 | 524.7 | 558.1 | 594.8 | 635 | 6.4 |
Target Audience
- Dental Equipment Manufacturers : Manufacturers need UK-specific market data to develop localized product strategies, understand NHS procurement requirements, and identify distribution opportunities in British dental practices.
- Healthcare Investors & PE Firms : Investment firms require detailed UK market analysis to evaluate acquisition targets, assess growth potential in British dental equipment companies, and make informed capital allocation decisions.
- Dental Practice Operators : Practice owners and managers need market insights to benchmark equipment investments, understand technology trends, and optimize capital expenditure planning for UK dental clinics.
- Medical Device Distributors : UK-based and international distributors require market forecasts and competitive intelligence to develop distribution strategies and identify growth segments in British dental equipment sales.
- Healthcare Consultants & Advisors : Consultants advising NHS trusts, private equity firms, and dental organizations need authoritative UK market data to support strategic recommendations and business case development.
Key Companies in the UK Dental Equipment Market
| Company | HQ | Ownership | Strongest segments |
|---|---|---|---|
| CARL ZEISS AG | Germany | Public Company | Ophthalmology – Diagnostics (slit lamps, OCT, fundus, perimetry, tonometers),Ophthalmology – Surgical (microscopes, phaco, vitrectomy, IOLs, laser vision systems),Microsurgery (surgical visualization, intraoperative radiotherapy/pathology, instruments, ZEISS Tumor Workflow), |
| TRUMPF GROUP | Germany | Private Company | Machine tools for sheet and pipe machining,Industrial lasers and laser systems,Software, services, and financing, |
| HENRY SCHEIN | United States | Public Company | Global Distribution and Value-Added Services,Global Specialty Products,Global Technology, |
| PATTERSON COMPANIES, INC | United States | Private Company | Dental consumables and equipment,Dental software and practice optimization solutions,Animal health products (biologicals, pharmaceuticals, vaccines, diets), |
| DENTSPLY SIRONA | United States | Public Company | Connected Technology Solutions (imaging, CEREC, CAD/CAM, digital equipment),Essential Dental Solutions (endodontics, restorative, preventive consumables),Orthodontic and Implant Solutions (SureSmile, implants, digital dentures), |
| SOLVENTUM | United States | Public Company | Medsurg,Dental Solutions,Health Information Systems, |
| ENVISTA HOLDINGS CORPORATION | United States | Public Company | Equipment & Consumables,Specialty Products & Technologies – Implants & Biomaterials,Specialty Products & Technologies – Orthodontics & Clear Aligners, |
| ALIGN TECHNOLOGY INC. | United States | Public Company | Invisalign comprehensive (adult and teen),Invisalign First and pediatric solutions,Invisalign lite/moderate/Go and express offerings, |
| A-DEC | Switzerland | Public Company | Flexible placement (temporary and contract staffing),Permanent placement and talent advisory,Outsourcing, RPO, MSP, and engineering consulting, |
| GC CORPORATION | Thailand | Public Company | Polyolefin and imported commodity plastics,Engineering plastics,Additives and intermediates, |
| BIOLASE, INC. | United States | Public Company | Waterlase (all-tissue) systems,Diode (soft-tissue) laser systems,Consumables, fibers, and handpieces, |
CARL ZEISS AG
CARL ZEISS AG is a German public company established in 1846 with 5,798 employees, specializing in optical systems and precision instruments.
TRUMPF GROUP
TRUMPF GROUP is a German private company founded in 1923 with 18,303 employees, operating in industrial manufacturing and laser technology.
HENRY SCHEIN
HENRY SCHEIN is a United States-based public company founded in 1932 with 25,000 employees, serving as a distributor of healthcare products and services.
PATTERSON COMPANIES, INC
PATTERSON COMPANIES, INC is a United States-based private company founded in 1877 with 7,600 employees, operating as a distributor of dental and animal health products.
DENTSPLY SIRONA
DENTSPLY SIRONA is a United States-based public company founded in 1877 with 14,000 employees, operating as a manufacturer of dental products and technologies.
SOLVENTUM
SOLVENTUM is a United States-based public company founded in 2023 with 20,584 employees, operating in healthcare and industrial solutions.
ENVISTA HOLDINGS CORPORATION
ENVISTA HOLDINGS CORPORATION is a United States-based public company founded in 2018 with 12,000 employees, operating as a dental products and services provider.
ALIGN TECHNOLOGY INC.
ALIGN TECHNOLOGY INC. is a United States-based public company founded in 1997 with 20,275 employees, specializing in clear aligner technology and digital dentistry solutions.
A-DEC
A-DEC is a Swiss public company founded in 1957 with 33,569 employees, manufacturing dental equipment and practice solutions.
GC CORPORATION
GC CORPORATION is a Thailand-based public company founded in 1994 with 91 employees, operating in the dental materials and products sector.
BIOLASE, INC.
BIOLASE, INC. is a United States-based public company founded in 1984 with 157 employees, manufacturing dental laser technology and equipment.
Reasons to Buy this Report
- UK-Specific Market Sizing : Accurate valuation data for the UK market ($30.2M in 2026) enables precise budget allocation and investment decisions tailored to the British dental equipment sector.
- NHS Procurement Insights : Understand NHS modernization initiatives and public sector procurement patterns to identify opportunities in government-funded dental practice upgrades across the UK.
- Competitive Landscape Analysis : Gain intelligence on UK-based and international competitors operating in the British market, including market share distribution and strategic positioning.
- Regulatory & Compliance Guidance : Navigate UK healthcare regulations, MHRA standards, and compliance requirements specific to dental equipment distribution and sales in British markets.
- Growth Opportunity Identification : Identify high-potential segments within the UK market driven by aging demographics, private practice expansion, and digital dentistry adoption trends.
Frequently asked questions
What is the current size of the UK dental equipment market?
The UK dental equipment market is valued at $30.2 million in 2026 according to verified market data.
What is the projected size of the UK dental equipment market by 2031?
The UK dental equipment market is forecast to reach $33.6 million by 2031, growing at a 3.5% CAGR.
What factors are driving growth in the UK dental equipment market?
Key drivers include NHS modernization, private dental practice expansion, digital transformation, aging demographics, and increased cosmetic dentistry demand in the UK.
How does the UK dental equipment market compare to global growth rates?
The UK market grows at 3.5% CAGR, below the global average of 7.2%, reflecting market maturity and cost-conscious healthcare spending in the UK.
What types of dental equipment are most in demand in the UK?
The UK shows increasing demand for digital technologies including CAD/CAM systems, intraoral scanners, advanced imaging equipment, and diagnostic devices.
RESEARCH METHODOLOGY
This research study relied heavily on both primary and secondary sources. It involved studying various factors affecting the industry to identify segmentation types, industry trends, key players, the competitive landscape, and key market dynamics, including drivers, opportunities, challenges, restraints, and key player strategies.
Secondary Research
This research study involved the wide use of secondary sources, directories, databases such as Dun & Bradstreet, Bloomberg Businessweek, and Factiva, white papers, and companies’ house documents. Secondary research was undertaken to identify and collect information for this extensive, technical, market-oriented, and commercial study of the dental equipment market. It was also used to obtain important information on the top players, market classification, segmentation by industry trends, bottom-level geographic markets, and key developments in the market. A database of the key industry leaders was also prepared using secondary research.
Primary Research
In the primary research process, various supply-side and demand-side sources were interviewed to obtain qualitative and quantitative information for this report. Primary sources from the supply side included industry experts such as CEOs, vice presidents, marketing & sales directors, technology & innovation directors, engineers, and related key executives from various companies and organizations operating in the dental equipment market. Primary sources from the demand side included hospitals, clinics, researchers, lab technicians, purchase managers, and stakeholders in corporate & government bodies.
A breakdown of the primary respondents for the dental equipment market is provided below:
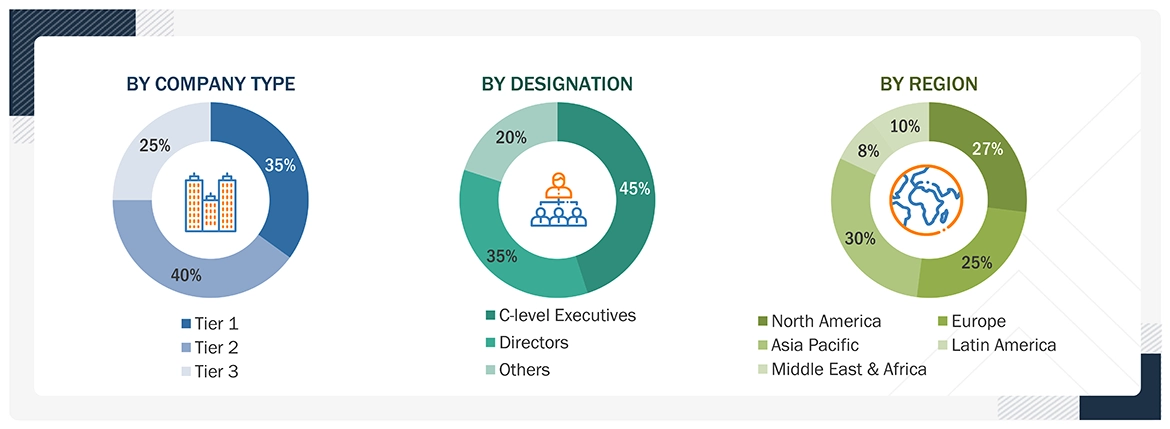
Note 1: C-level executives include CEOs, COOs, CTOs, and VPs.
Note 2: Others include sales, marketing, and product managers.
Note 3: Companies are classified into tiers based on their total revenue. As of 2025: Tier 1 = >USD 1 billion, Tier 2 = USD 500 million to USD 1 billion, and Tier 3 = <USD 500 million.
Note: Tier 1 companies’ revenue is more than USD 10 billion; Tier 2 companies’ revenue ranges between USD 1 and 10 billion; and Tier 3 companies’ revenue ranges between USD 500 million and USD 1 billion
To know about the assumptions considered for the study, download the pdf brochure
Market Size Estimation
The research methodology used to estimate the size of the dental equipment market includes the following details. The market sizing was conducted on a global basis.
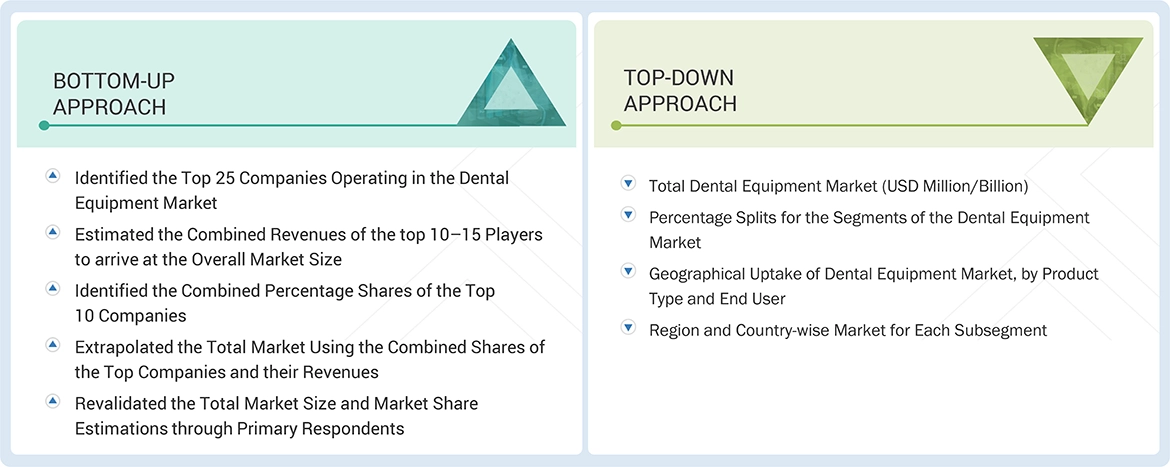
Country-level Analysis: The size of the dental equipment market was obtained from the annual presentations of leading players and secondary data available in the public domain. The share of products in the overall dental equipment market was obtained from secondary data and validated by primary participants to arrive at the total dental equipment market. Primary participants further validated the numbers.
Geographic Market Assessment (By Region and Country): The geographic assessment was done using the following approaches:
Approach 1: Geographic revenue contributions/splits of leading players in the market (wherever available) and respective growth trends.
Approach 2: Geographic adoption trends for individual product segments by end users and growth prospects for each of the segments (assumptions and indicative estimates validated from primary interviews).
At each point, the assumptions and approaches were validated by industry experts contacted during the primary research. Considering the limitations of data available from secondary research, revenue estimates for individual companies (for the overall dental equipment market and geographic market assessment) were ascertained based on a detailed analysis of their respective product offerings, geographic reach/strength (direct or through distributors or suppliers), and the shares of the leading players in a particular region or country.
Global Dental Equipment Market Size: Bottom-up Approach & Top-down Approach
Data Triangulation
The market was divided into several segments when determining market size. Data triangulation and market breakdown processes were used as needed to complete the market engineering process and obtain precise statistics for all segments.
Approach to derive the market size and estimate market growth:
Using secondary data from both paid and unpaid sources, the market rankings for the major players were determined following a thorough analysis of their dental equipment sales. Due to data restrictions, the revenue share in certain cases was determined after a thorough analysis of the product portfolio of big corporations and their individual sales performance. This information was verified at each stage by in-depth interviews with professionals in the field.
Market Definition
Dental equipment encompasses the tools and instruments used to diagnose and treat a range of dental diseases and disorders. These supplies are utilized by dentists, dental hygienists, and dental laboratories. The category includes a variety of dental equipment, such as diagnostic tools and therapeutic instruments.
Key Stakeholders
- Manufacturers and distributors of medical devices
- Dental equipment manufacturers
- Contract manufacturers of dental equipment
- Distributors of dental equipment
- Research and consulting firms
- Raw material suppliers of dental equipment
- Dental hospitals & clinics
- Dental laboratories and associations
- Dental practitioners
- Dental laboratory technicians
- Healthcare institutions
- Diagnostic laboratories
- Academic institutions
- Research institutions
- Government associations
- Market research & consulting firms
- Venture capitalists & investors
Report Objectives
- To define, describe, and forecast the dental equipment market based on product type, end user, and region
- To provide detailed information about the major factors influencing the market growth (such as drivers, restraints, challenges, and opportunities)
- To strategically analyze micromarkets with respect to individual growth trends, prospects, and contributions to the overall dental equipment market
- To analyze market opportunities for stakeholders and provide details of the competitive landscape for key players
- To forecast the size of the dental equipment market in North America, Europe, the Asia Pacific, Latin America, the Middle East & Africa, and GCC Countries
- To profile the key players and comprehensively analyze their market shares and core competencies in the dental equipment market
- To track and analyze competitive developments such as partnerships, expansions, acquisitions, collaborations, product launches, agreements, and other developments in the dental equipment market
- To benchmark players within the dental equipment market using the Company Evaluation Quadrant framework, which analyzes market players on various parameters within the broad categories of business strategy, market share, and product offerings
Available customizations:
Based on the given market data, MarketsandMarkets offers customizations tailored to your company’s specific needs. The following customization options are available for the report:
Company Information
- Detailed analysis and profiling of additional market players (up to 5)
Geographic Analysis
- Further breakdown of the Rest of Europe dental equipment market into Switzerland, Austria, Belgium, and others
- Further breakdown of the Rest of Asia Pacific dental equipment market into Singapore, Malaysia, and others
Company Information
- Detailed analysis and profiling of additional market players
Get the Full Dental Equipment Market Report
Full forecast, segment splits, and company analysis for all Dental Equipment Market.
- Spain Dental Equipment Market
- Canada Dental Equipment Market
- US Dental Equipment Market
- China Dental Equipment Market
- Japan Dental Equipment Market
- India Dental Equipment Market
- Australia Dental Equipment Market
- South Korea Dental Equipment Market
- Brazil Dental Equipment Market
- Mexico Dental Equipment Market
- Argentina Dental Equipment Market
- Germany Dental Equipment Market
- France Dental Equipment Market
- Italy Dental Equipment Market
Need a Tailored Report?
Customize this report to your needs
Get 10% FREE Customization
Customize This Report