UK Fire Resistant Glass Market (2024-2029)
The UK Fire Resistant Glass Market was valued at $267.5 Million in 2024 and projected to reach to $395 Million by 2029, representing a compound annual growth rate of 8.1%. The UK fire resistant glass market is positioned for sustained growth through 2029, driven by evolving building regulations and heightened fire safety consciousness among architects, developers, and facility managers.

| Market Size in | USD 26.32 MN |
| Market Forecast in | |
| CAGR | |
| Forecast Period | |
| Units Considered | Value (USD MN) |
UK Fire Resistant Glass Market Trends and Insights
- The UK market is driven by stringent building safety regulations, increased investment in commercial infrastructure, and heightened awareness of fire safety standards across residential and industrial sectors.
- The UK's adoption of advanced fire-resistant technologies reflects broader European compliance requirements and the nation's commitment to reducing fire-related risks in high-rise buildings and public facilities. Growth in the UK fire resistant glass market is supported by post-Grenfell Tower regulatory reforms, which have intensified demand for certified fire-safety materials in construction projects.
- The UK market benefits from a mature construction industry, strong enforcement of building codes, and significant renovation activity in aging commercial properties.
- Between 2024 and 2029, the UK is expected to see accelerated adoption of fire-resistant glazing solutions in both new builds and retrofitting applications, driven by insurance requirements and architectural specifications..
Key Market Statistics
- CAGR (2024-2029) 8.1% CAGR
- Market Size, 2024 ~USD 267.5 Million
- Forecast, 2029 ~USD 395 Million
- Country UK
UK Fire Resistant Glass Market Overview
Market Valuation :
The UK fire resistant glass market reached £267.5 million in 2024, with projections to reach £395.0 million by 2029, demonstrating robust growth potential in the domestic market.
Regulatory Compliance Drivers :
Stringent UK building safety regulations, including the Building Safety Act and enhanced fire safety standards post-Grenfell, are compelling commercial and residential developers to adopt fire resistant glass solutions.
Infrastructure Investment :
Increased investment in UK commercial infrastructure, office modernization, and hospitality sector recovery are accelerating demand for fire resistant glass in high-rise buildings and public spaces.
Sector Awareness Growth :
Rising awareness of fire safety standards across UK residential, industrial, and institutional sectors is driving adoption of fire resistant glass as a critical safety component in building design.
UK Fire Resistant Glass Market Dynamics
- The 8.1% CAGR reflects strong demand from both new construction projects and retrofitting initiatives across commercial, residential, and industrial properties.
- Government mandates on fire safety compliance and insurance incentives for upgraded fire protection systems are expected to further accelerate market expansion.
- Investment in smart buildings and sustainable construction practices will create additional opportunities for innovative fire resistant glass solutions tailored to UK specifications and standards..
Market Ecosystem
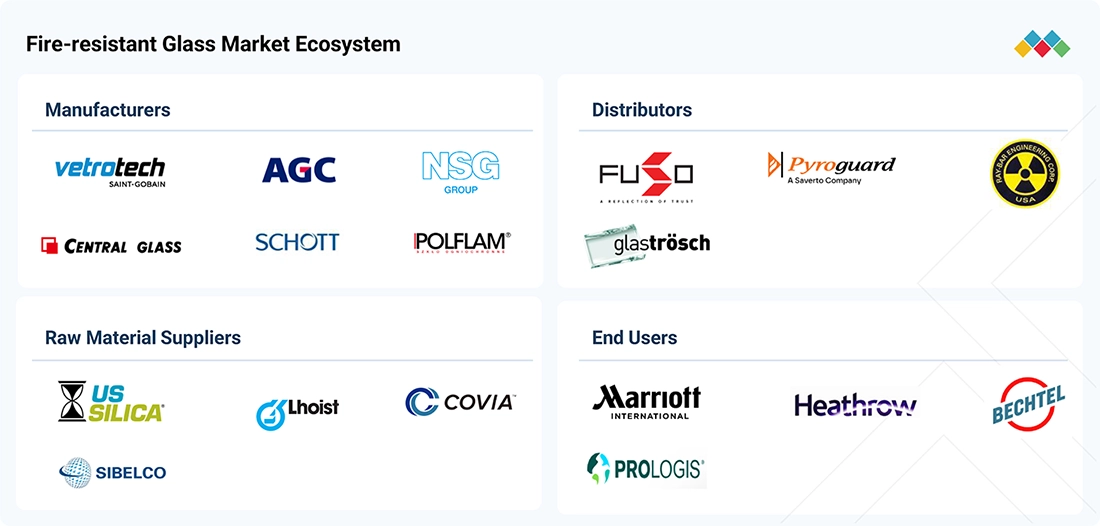
FIRE RESISTANT GLASS MARKET: COMMERCIAL USE CASES ACROSS INDUSTRIES
| COMPANY | USE CASE DESCRIPTION | BENEFITS |
|---|---|---|
 |
Fire-resistant glass in hotel fire-rated doors, partitions, corridors, stairwells, and façade glazing | Fire protection, code compliance, occupant safety, design flexibility |
 |
Fire-resistant glass in commercial, industrial, and infrastructure projects, including fire-rated doors, windows, and internal partitions | Enhanced fire safety, regulatory compliance, thermal protection |
 |
Fire-resistant glass in airport terminals, passenger areas, fire-rated partitions, doors, and façade systems | Improved passenger safety, fire containment, visibility, and code compliance |
 |
Fire-resistant glass in logistics warehouses, distribution centers, offices, and industrial facilities | Fire protection, compartmentation, durability, and improved building safety |
Logos and trademarks shown above are the property of their respective owners. Their use here is for informational and illustrative purposes only.
Related Ecosystem
Ceramics And Glass
- Zirconia
- Alumina Ceramics
- Silicon Carbide
- Silicon Nitride
- Titanate Ceramics
- Saint-gobain
- 3M COMPANY
- Kyocera Corporation
- CERAMTEC GMBH
- COORSTEK INCORPORATED
Building And Construction
- HVAC System
- Acoustic Insulation
- Alkyd Resins
- Fiberglass
- Thermal Insulation
- Snc-lavalin group inc.
- Saint-gobain
- LHOIST S.A
- USG CORPORATION
- Basf se
Infrastructure Material
- Alumina Ceramics
- Ceramic Coatings
- Monolithic Ceramics
- Polyphenylene Sulfide (PPS)
- Titanate Ceramics
- Saint-gobain
- Simpson Manufacturing Co., Inc.
- Basf se
- Sika ag
- DOW CHEMICAL COMPANY
Key Takeaways
- The UK fire resistant glass market is valued at £267.5 million in 2024 and will reach £395.0 million by 2029, growing at 8.1% CAGR.
- Regulatory reforms following the Grenfell Tower incident have significantly increased demand for certified fire-resistant materials across UK construction projects.
- The UK market is supported by strict building safety codes, mature construction infrastructure, and widespread retrofitting of commercial and residential properties.
- Between 2024 and 2029, the UK will experience accelerated adoption of fire-resistant glazing driven by insurance mandates and architectural compliance requirements.
Fire Resistant Glass Market Report Scope
| Report Metric | Details |
|---|---|
| Base Year | 2024 |
| Fastest Growing Segment | CERAMIC (Type) |
| Forecast Period | 2024–2029 |
| Growth Rate | CAGR of 9% from 2024 to 2029 |
| Largest Segment | BUILDING & CONSTRUCTION (Application) |
| Market Size Base Year (Billions) | ~USD 10.46 (2024) |
| Revenue Forecast (Billions) | ~USD 16.1 (2029) |
| Segments Covered | Type, Sub-Type, Interlayer, Application, Subsegment |
UK Fire Resistant Glass Market Report Segmentation
5 segment dimensions are covered across the global market.
By Type
- Ceramic
- Laminated
- Tempered
- Wired
By Sub-Type
- Cuttable
- Non-Cuttable
By Interlayer
- Eva
- Gel
- Pvb
By Application
- Building & Construction
- Building And Construction
- Marine
- Other Applications
By Subsegment
- Commercial
- Residential
UK: FIRE-RESISTANT GLASS MARKET, BY APPLICATION, 2024–2029
| Segment | 2024 | 2025 | 2026 | 2027 | 2028 | 2029 | CAGR (%) |
|---|---|---|---|---|---|---|---|
| BUILDING & CONSTRUCTION | 223 | 241.8 | 262.3 | 284.5 | 308.6 | 334.8 | 8.5 |
| MARINE | 9.5 | 10.2 | 11 | 11.8 | 12.6 | 13.6 | 7.4 |
| OTHER APPLICATIONS | 35 | 37.1 | 39.3 | 41.6 | 44.1 | 46.7 | 5.9 |
| TOTAL | 267.5 | 289.1 | 312.5 | 337.9 | 365.3 | 395 | 8.1 |
Target Audience
- Building Developers & Contractors : UK developers need market intelligence on fire resistant glass specifications, compliance requirements, and cost implications to meet building safety regulations and deliver compliant projects on time and budget.
- Architects & Design Firms : UK architects require detailed market data on fire resistant glass options, performance standards, and aesthetic solutions to specify appropriate materials that satisfy both safety codes and design objectives.
- Glass Manufacturers & Suppliers : UK glass producers need market sizing, growth forecasts, and competitive analysis to optimize production capacity, develop new products, and capture market share in the expanding fire resistant glass segment.
- Insurance & Risk Management Professionals : UK insurance companies and risk managers need market insights on fire resistant glass adoption rates and effectiveness to inform underwriting policies, premium structures, and risk mitigation recommendations.
- Government & Policy Bodies : UK regulatory agencies and policy makers require market data to assess the effectiveness of fire safety regulations, identify compliance gaps, and develop evidence-based building safety standards and guidelines.
Key Companies in the UK Fire Resistant Glass Market
| Company | HQ | Ownership | Strongest segments |
|---|---|---|---|
| CORNING, INC. | United States | Public Company | Optical Communications (fiber, cable, connectivity hardware),Display Technologies (LCD and OLED glass substrates),Specialty Materials (mobile, semiconductor, optics, radiation shielding, sunglasses), |
| SCHOTT AG | Germany | Public Company | Glass syringes (syriQ portfolio),Polymer syringes and containers (SCHOTT TOPPAC),Glass vials (adaptiQ, EVERIC family), |
| AGC INC. | United States | Public Company | High-horsepower and utility tractors,Compact tractors and implements,Combines and harvesting equipment, |
| NIPPON SHEET GLASS CO., LTD. | Japan | Public Company | Architectural (commercial and residential flat glass, solar),Automotive (OEM and replacement glazing),Technical Glass and MICROGLAS functional products, |
| ETEX GROUP | Belgium | Public Company | Building Performance (gypsum boards, ceilings, metal profiles, passive fire protection),Exteriors (fibre cement façades, roofing, water tanks, agricultural sheeting),Insulation (glass mineral wool, XPS, high-performance panels), |
| CENTRAL GLASS CO., LTD. | Japan | Public Company | Glassware and automotive glass,Electronic materials and semiconductor-related products,Fluorine products and specialty chemicals, |
CORNING, INC.
Corning, Inc. is a publicly traded American glass and materials science company founded in 1851. With 67,200 employees, Corning is a global leader in specialty glass, ceramics, and related materials for various industries including telecommunications, display technologies, and environmental applications.
SCHOTT AG
Schott AG is a German public company founded in 1884 that specializes in glass and glass-ceramic products. With 4,839 employees, the company serves diverse industries including pharmaceuticals, electronics, and laboratory equipment.
AGC INC.
AGC Inc. is a publicly traded American glass manufacturer founded in 1990. The company employs 22,000 people and produces a wide range of glass products for automotive, construction, and industrial applications.
NIPPON SHEET GLASS CO., LTD.
Nippon Sheet Glass Co., Ltd. is a Japanese public company established in 1918 with 25,406 employees. The company is a major global manufacturer of flat glass, specialty glass, and glass-related products for construction and automotive markets.
ETEX GROUP
Etex Group is a Belgian public company founded in 1905 that manufactures building materials and glass products. With 12,475 employees, the company serves construction and industrial markets across multiple regions.
CENTRAL GLASS CO., LTD.
Central Glass Co., Ltd. is a Japanese public company founded in 1936 with 3,194 employees. The company manufactures flat glass, automotive glass, and specialty glass products for global markets.
Reasons to Buy this Report
- Regulatory Compliance Intelligence : Understand how UK-specific building safety regulations and fire codes impact market demand, enabling informed product development and market entry strategies aligned with British Standards and Building Regulations.
- Competitive Market Positioning : Gain insights into the UK competitive landscape, key players, and market share distribution to identify growth opportunities and develop differentiated strategies for the domestic market.
- Investment Decision Support : Access detailed market sizing and growth forecasts specific to the UK to support capital allocation decisions, expansion planning, and ROI projections for fire resistant glass ventures.
- Sector-Specific Demand Analysis : Identify high-growth segments within UK residential, commercial, and industrial sectors to prioritize sales efforts and tailor product offerings to sector-specific fire safety requirements.
- Strategic Planning Data : Leverage UK market trends, growth drivers, and future outlook to develop long-term business strategies, supply chain planning, and partnership opportunities in the fire resistant glass sector.
Frequently asked questions
What is the current size of the UK fire resistant glass market?
The UK fire resistant glass market was valued at £267.5 million in 2024 and is expected to grow to £395.0 million by 2029.
What is the growth rate of the UK fire resistant glass market?
The UK fire resistant glass market is projected to grow at a compound annual growth rate (CAGR) of 8.1% from 2024 to 2029.
What are the main drivers of growth in the UK market?
Key drivers include post-Grenfell Tower regulatory reforms, stringent building safety codes, increased commercial infrastructure investment, and widespread property retrofitting initiatives across the UK.
Which sectors are driving demand for fire resistant glass in the UK?
The UK market is driven by demand from high-rise residential buildings, commercial offices, public facilities, and industrial properties requiring certified fire-safety materials.
How do UK regulations impact the fire resistant glass market?
The UK's strict building safety regulations, particularly those implemented after the Grenfell Tower incident, mandate the use of fire-resistant materials in construction, directly increasing market demand.
RESEARCH METHODOLOGY
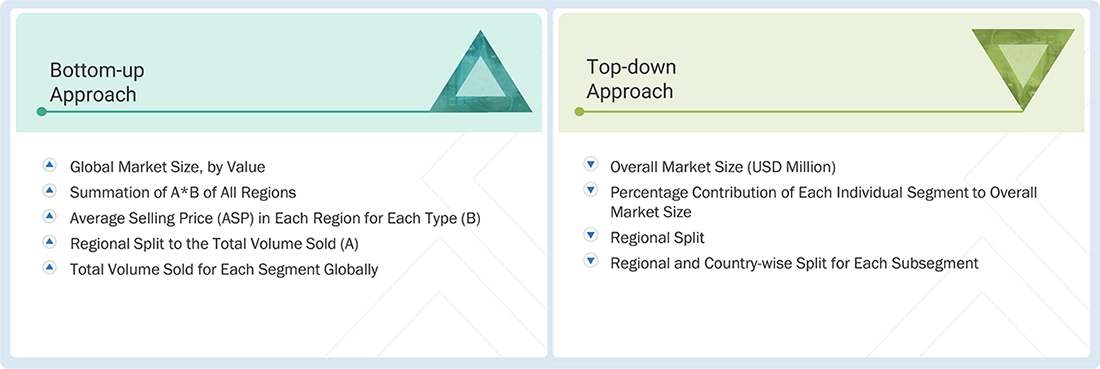
This study consisted of two main tasks to determine the current size of the fire-resistant glass market. The first task entailed conducting exhaustive secondary research aimed at obtaining information about the market for fire-resistant glass, other markets, and the parent markets. The results, assumptions, and market sizing were further verified through primary research with industry players. Market size was estimated using both top-down and bottom-up approaches. Further market segmentation and data triangulation techniques were used to obtain the market size of segments and subsegments.
Secondary Research
Sources used for secondary research for this study include annual reports, financial documents, product portfolios, technical sheets, certificates, company websites, industry magazines, and glass, construction, and fire safety industry associations. Secondary research was conducted to gain insights into the value chain of fire-resistant glass, major market players, market segmentation, and classification by glass type, application, and geography. The data gathered through this process was further analyzed to estimate the size of the global fire-resistant glass market and its segments and sub-segments.
Primary Research
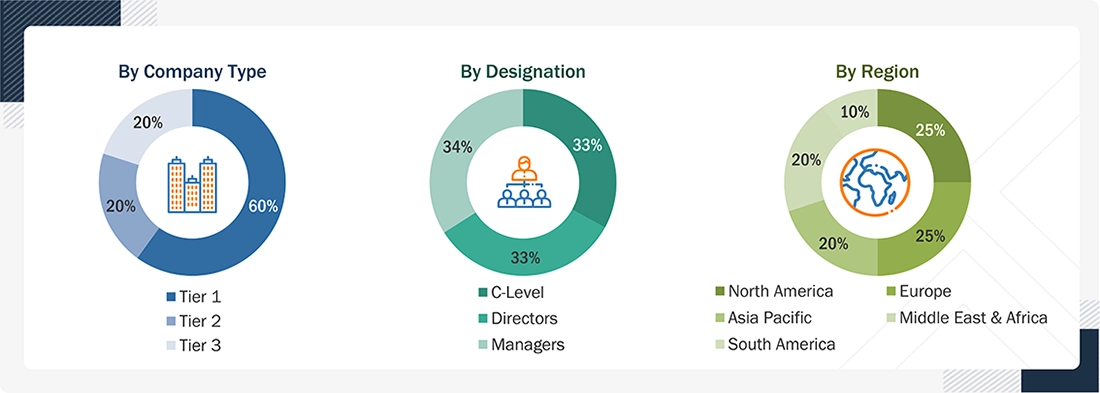
Extensive primary research was conducted after obtaining information regarding the market scenario of the fire-resistant market through secondary research. We conducted several primary interviews with market experts on both the demand and supply sides across major countries. We collected primary data through questionnaires, emails, and telephonic interviews. The primary sources from the supply side included various industry experts, such as chief experience officers (CXOs), vice presidents (VPs), business development/marketing directors, product development/innovation teams, related key executives from the fire-resistant glass industry, system integrators, component providers, distributors, and key opinion leaders. Primary interviews were conducted to gather insights such as market statistics, revenue data from products and services, market breakdowns, market size estimates, market forecasts, and data triangulation. Primary research helped in understanding the various trends related to type, application, and region. Stakeholders from the demand side, such as CIOs, CTOs, CSOs, and installation teams of the customers/end users who are seeking fire-resistant glass services, were interviewed to understand the buyer’s perspective on the suppliers, products, component providers, and their current usage of fire-resistant glass and future outlook of their business, which will affect the overall market.
To know about the assumptions considered for the study, download the pdf brochure
Market Size Estimation
The research methodology used to estimate the size of the fire-resistant glass market includes the following details. The market size was estimated from the demand side. The market was expanded based on global demand for fire-resistant glass across different applications. These procurements provide demand-side information for each application in the fire-resistant glass industry. For each application, all possible segments of the fire-resistant glass market were integrated and mapped.
Data Triangulation
After determining the overall size through the market size estimation process explained above, the total market was split into several segments and subsegments. The data triangulation and market breakdown procedures explained below were implemented, wherever applicable, to complete the overall market engineering process and arrive at the exact statistics for various market segments and subsegments. The data were triangulated by studying factors and trends from both the demand and supply sides. In addition, the market size was validated using both the top-down and bottom-up approaches.
Market Definition
Fire-resistant glass controls the spread of fire, smoke, hot gases, and heat transfer. Fire resistivity is determined by prevention levels classified as integrity (E), insulation (I), and radiant heat control (EW). This glass is used in buildings, marine vessels, and oil refineries and comes with various fire ratings, ranging between 20 and 180 minutes. The use of fire-resistant glass depends on the area and size limitations under the applicable building code and/or the authority having jurisdiction. Fire-resistant glass is manufactured by sheet glass processing. Raw materials include silica sand, soda ash, limestone, dolomite, alumina, fire-retardant intumescent interlayers, ceramics, and wires.
Key Stakeholders
- Fire-resistant glass Manufacturers
- Fire-resistant glass Distributors and Suppliers
- Glass Processors, Fabricators, and Glazing Contractors
- Building Developers, Architects, and Construction Companies
- Building Code Organizations and Standards Development Bodies
- Fire Safety Testing and Certification Organizations
- R&D Institutes and Research Organizations
- Raw Material and Interlayer Suppliers
- Government and Regulatory Authorities
- Investment Banks and Private Equity Firms
Report Objectives
- To define, describe, and forecast the fire-resistant glass market size in terms of volume and value.
- To provide detailed information regarding the key factors, such as drivers, restraints, opportunities, and challenges influencing market growth.
- To analyze and project the market by type, application, and region.
- To forecast the global fire-resistant glass market size, along with regional and country-level data, and analyze key country-specific trends.
- To strategically analyze micromarkets, including individual growth trends, prospects, and submarket contributions to the overall market.
- To analyze the market opportunities and the competitive landscape for stakeholders and market leaders.
- To assess recent market developments and competitive strategies, such as agreements, contracts, acquisitions, and product developments/product launches, to map the competitive landscape.
- To strategically profile the key market players and comprehensively analyze their core competencies.
Available customizations:
MarketsandMarkets offers the following customizations for this market report:
- Additional country-level analysis of the fire-resistant glass market
Product Analysis
- Product matrix, which provides a detailed comparison of the product portfolio of each company in the market
Get the Full Fire Resistant Glass Market Report
Full forecast, segment splits, and company analysis for all Fire Resistant Glass Market.
- US Fire Resistant Glass Market
- Canada Fire Resistant Glass Market
- Mexico Fire Resistant Glass Market
- Germany Fire Resistant Glass Market
- France Fire Resistant Glass Market
- Spain Fire Resistant Glass Market
- Italy Fire Resistant Glass Market
- Russia Fire Resistant Glass Market
- China Fire Resistant Glass Market
- Japan Fire Resistant Glass Market
- India Fire Resistant Glass Market
- South Korea Fire Resistant Glass Market
- UAE Fire Resistant Glass Market
- Saudi Arabia Fire Resistant Glass Market
- South Africa Fire Resistant Glass Market
- Brazil Fire Resistant Glass Market
- Argentina Fire Resistant Glass Market
- South America Fire Resistant Glass Market
Need a Tailored Report?
Customize this report to your needs
Get 10% FREE Customization
Customize This Report