Spain Forklift Market (2025-2030)
The Spain Forklift Market was valued at $40915 Million in 2025 and projected to reach to $56319 Million by 2030, representing a compound annual growth rate of 4.7%. Spain's forklift market is positioned for steady growth through 2030, supported by continued e-commerce expansion and supply chain digitalization.

| Market Size in | USD 26.32 MN |
| Market Forecast in | |
| CAGR | |
| Forecast Period | |
| Units Considered | Value (USD MN) |
Spain Forklift Market Trends and Insights
- This steady expansion reflects Spain's robust logistics and warehousing sectors, driven by e-commerce growth and supply chain modernization across the Iberian Peninsula.
- Spain's strategic position as a European distribution hub continues to fuel demand for material handling equipment. The Spanish forklift market benefits from increased automation investments in manufacturing and retail sectors throughout 2025–2030.
- Spain's industrial base, particularly in automotive and consumer goods, relies heavily on efficient warehouse operations, supporting sustained demand for forklifts.
- Regional economic recovery and infrastructure development initiatives further strengthen market fundamentals, positioning Spain as a key growth market within Europe's broader material handling landscape..
Key Market Statistics
- CAGR (2025-2030) 4.7% CAGR
- Market Size, 2025 ~USD 40915 Million
- Forecast, 2030 ~USD 56319 Million
- Country Spain
Spain Forklift Market Overview
Market Size & Growth :
Spain's forklift market is valued at USD 40,915 million in 2025, with a projected CAGR of 4.7% through 2030, reaching USD 56,319 million. This growth outpaces broader European trends, driven by Spain's expanding logistics infrastructure.
E-Commerce & Logistics Boom :
Spain's thriving e-commerce sector and modernization of supply chain networks are primary growth catalysts. Major distribution hubs in Madrid, Barcelona, and Valencia are driving increased demand for material handling equipment across the country.
Strategic European Hub :
Spain's position as a key European distribution center for Mediterranean and North African markets strengthens demand for forklifts. The country's port infrastructure and cross-border logistics networks support sustained equipment investment.
Warehouse Automation Trends :
Spanish warehousing facilities are increasingly adopting automated and semi-automated material handling solutions. Investment in modern logistics centers is accelerating forklift adoption across manufacturing, retail, and third-party logistics sectors.
Spain Forklift Market Dynamics
- The country's role as a European distribution gateway ensures sustained demand from logistics operators and warehouse operators seeking to modernize operations.
- Investment in automated warehousing and last-mile delivery infrastructure will drive equipment replacement cycles and new purchases across major metropolitan areas. Regional economic recovery and increased cross-border trade within the EU will further bolster market expansion.
- Spanish manufacturers and logistics providers are prioritizing operational efficiency, creating opportunities for advanced forklift technologies including electric and autonomous solutions.
- Market growth will remain moderate but consistent, reflecting Spain's mature but dynamic logistics landscape..
Market Ecosystem
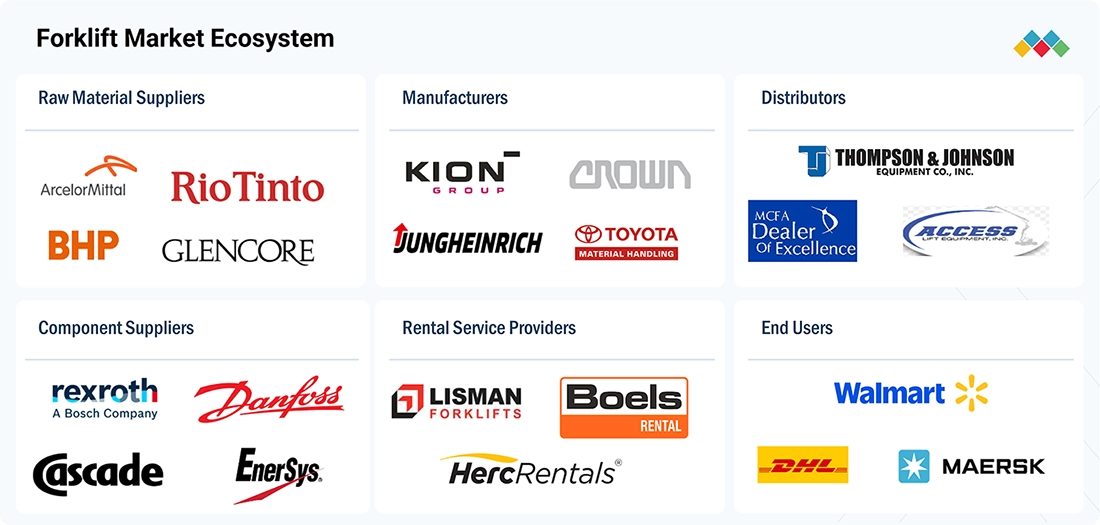
FORKLIFT MARKET: COMMERCIAL USE CASES ACROSS INDUSTRIES
| COMPANY | USE CASE DESCRIPTION | BENEFITS |
|---|---|---|
 |
Toyota Industries provides automated forklifts and warehouse trucks for repetitive pallet transport, storage, retrieval, and truck loading and unloading. Its automated warehouse portfolio includes low-lift trucks up to 2.5 tons, stacker trucks up to 1.6 tons, and reach trucks up to 2.5 tons, allowing automation across long-distance pallet movement, medium-level storage, and high-rack operations. | Enables warehouses to automate repetitive pallet handling while retaining the same basic truck architecture used in manual operations. Its automation approach can improve pallet handling accuracy, reduce manual travel, and support continuous operation in high-throughput facilities. |
 |
KION combines Linde forklift equipment with automation, AI, fleet control, and warehouse technologies. Its autonomous forklift solutions are designed for pallet transport and warehouse operations, with newer AI-based systems capable of independently executing complete transport orders and operating alongside employees and manually operated forklifts. | Enables operators to automate individual transport processes without requiring complete warehouse automation. AI-based perception and autonomous operation can improve task consistency, support mixed manual and automated fleets, and allow automation to be expanded as warehouse requirements increase. |
 |
Jungheinrich uses automated narrow-aisle forklifts, high-lift trucks, and automated guided equipment for high-density storage and repetitive pallet movement. Its automated solutions are particularly suitable for very narrow-aisle warehouses, where trucks can operate at storage heights of up to 10 meters and handle high-pallet throughput. | Increases storage density by allowing automated trucks to operate in narrow aisles and at high rack heights. Automation also reduces dependence on manual forklift operators for repetitive storage and retrieval tasks while supporting consistent throughput across multiple shifts. |
 |
Mitsubishi Logisnext provides automated guided forklifts for warehouses and factories, alongside reach stackers, automated warehouse systems, and forklift operation management systems. Its solutions are designed to connect automated equipment with broader logistics operations, including pallet movement and real-time monitoring of forklift activity. | Allows customers to combine automated forklifts with warehouse and fleet management technologies instead of deploying standalone equipment. This supports safer material movement, real-time visibility of equipment activity, and gradual automation of factories and warehouses. |
Logos and trademarks shown above are the property of their respective owners. Their use here is for informational and illustrative purposes only.
Related Ecosystem
Logistics And Transportation
- Internal Combustion Engine (ICE)
- Crawler Excavator
- Fuel Cell
- Light Commercial Vehicles (LCVs)
- Sensors
- Siemens ag
- Alstom s.a.
- Hitachi, Ltd.
- Godrej Industries Limited
- ABB India Limited
On Highway Off Highway Vehicles
- Internal Combustion Engine (ICE)
- Agricultural Tractors
- Crawler Excavator
- Battery Electric Vehicle (BEV)
- Excavators
- Visteon Corporation
- Deere & Company
- Honda Motor Co., Ltd.
- AB VOLVO PENTA
- Komatsu Ltd.
Key Takeaways
- Spain's forklift market is valued at USD 40,915 million in 2025 and will reach USD 56,319 million by 2030, growing at a 4.7% CAGR.
- E-commerce expansion and supply chain modernization are primary growth drivers for Spain's material handling equipment demand.
- Spain's role as a European logistics hub strengthens competitive positioning and supports sustained market expansion through 2030.
- Automation investments in Spanish manufacturing and retail sectors are accelerating forklift adoption and fleet modernization.
Forklift Market Report Scope
| Report Metric | Details |
|---|---|
| Base Year | 2025 |
| Fastest Growing Segment | LITHIUM-ION (Battery Type) |
| Forecast Period | 2025–2030 |
| Growth Rate | CAGR of 6.5% from 2025 to 2030 |
| Largest Segment | WAREHOUSE (Product Type) |
| Market Size Base Year (Billions) | ~USD 90.94 (2025) |
| Revenue Forecast (Billions) | ~USD 124.6 (2030) |
| Segments Covered | Propulsion, Tonnage Capacity, End-Use Industry, Class, Operation, Application, Battery Type, Lifting Capacity, Product Type, Tire Type |
Spain Forklift Market Report Segmentation
10 segment dimensions are covered across the global market.
By Propulsion
- Electric
- ICE
By Tonnage Capacity
- 11–36 Tons
- 5–10 Tons
- <5 Tons
- >36 Tons
By End-Use Industry
- Automotive
- Aviation
- Chemicals
- E-Commerce
- Food & Beverages
- Healthcare
- Metals & Heavy Machinery
- Pulp & Paper
- Semiconductors & Electronics
- Third-Party Logistics
By Class
- Class 1
- Class 2
- Class 3
- Class 4/5
By Operation
- Autonomous
- Manual
By Application
- Indoor
- Indoor & Outdoor
- Outdoor
By Battery Type
- Lead Acid
- Lithium-Ion
By Lifting Capacity
- 2–5 Tons
- <2 Tons
- >5 Tons
By Product Type
- Counterbalance
- Warehouse
By Tire Type
- Cushion
- Pneumatic
Target Audience
- Forklift Manufacturers & Distributors : Develop Spain-focused sales strategies and product portfolios. Understand regional demand patterns, customer segments, and competitive positioning to optimize market penetration and revenue growth in Spanish logistics markets.
- Logistics & Warehouse Operators : Make informed equipment investment decisions based on market trends and growth forecasts. Benchmark operational efficiency against industry standards and identify modernization opportunities aligned with Spain's supply chain evolution.
- Private Equity & Investment Firms : Evaluate investment opportunities in Spanish logistics infrastructure and material handling companies. Assess market growth potential, competitive dynamics, and exit opportunities within Spain's expanding forklift and warehousing sectors.
- Supply Chain & Operations Consultants : Provide clients with Spain-specific market data and logistics trends. Support strategic recommendations on warehouse automation, equipment modernization, and supply chain optimization tailored to Spanish market conditions.
- Government & Trade Organizations : Inform policy decisions and industry development initiatives related to logistics infrastructure and supply chain modernization. Support economic planning and trade promotion efforts targeting Spain's material handling and warehousing sectors.
Key Companies in the Spain Forklift Market
| Company | HQ | Ownership | Strongest segments |
|---|---|---|---|
| ENERSYS | United States | Public Company | Network & Infrastructure Solutions,Industrial Mobility Solutions,Precision Power Solutions, |
| TOYODA GOSEI CO., LTD | Japan | Public Company | Weatherstrips and body sealing,Interior and exterior plastic parts,Safety systems (airbags, steering wheels), |
| TENNECO | United States | Private Company | Emissions-control / clean air systems,Ride-performance systems (suspension, shocks, related components),Engine components / powertrain systems, |
| ZF FRIEDRICHSHAFEN AG | Germany | Private Company | Passenger car driveline, chassis, and safety systems,Commercial vehicle and bus systems,Industrial driveline and motion systems, |
| TOYOTA INDUSTRIES CORPORATION | Japan | Public Company | Materials handling equipment and warehouse solutions,Automobile-related components (engines, compressors, electronics, batteries),Automobiles and vehicles, |
| KION GROUP AG | Germany | Public Company | Industrial Trucks & Services – New Trucks (forklifts, warehouse trucks, narrow aisle, heavy trucks),Industrial Trucks & Services – Rental, Leasing, Maintenance, Repair, Fleet Management, Finance,Supply Chain Solutions – Automation Systems (AGVs, AS/RS, conveyors, sorters, palletizers), |
| JUNGHEINRICH AG | Germany | Public Company | Material handling equipment (new trucks: pallet, stackers, reach, VNA, forklifts, tow tractors),Automation systems and digital solutions (AGVs, shuttles, stacker cranes, software, mobile robots, PowerCube),Services, rental, and used equipment, |
| MITSUBISHI LOGISNEXT CO., LTD. | Japan | Private Company | Electric forklifts,Engine-powered forklifts,Container carriers and transfer cranes, |
| HYSTER-YALE MATERIALS HANDLING | United States | Public Company | Counterbalance lift trucks (IC and electric),Warehouse trucks and narrow-aisle equipment,Attachments, forks, masts, lift tables (Bolzoni, Auramo, Meyer), |
| CLARK MATERIAL HANDLING COMPANY | United States | Private Company | Forklifts, lift trucks, counterbalanced and reach machines,Parts, service supplies, planned maintenance products,Industrial and power batteries, load wheels, safety and accessories, |
| HYUNDAI CONSTRUCTION EQUIPMENT | South Korea | Public Company | Excavators,Wheel loaders,Backhoe, skid steer, and compact track loaders, |
| KOMATSU LTD. | Japan | Public Company | Construction Machinery and Vehicles,Mining Equipment,Industrial Machinery and Others, |
| BOBCAT COMPANY | South Korea | Public Company | Compact loaders and excavators,Attachments and utility products,Telehandlers, compact tractors, turf and grounds equipment, |
| KALMAR | Finland | Public Company | Container and cargo handling equipment (reach stackers, empty handlers, straddle carriers, spreaders),Forklift trucks and terminal tractors,Services and spare parts (on-call, contract maintenance, lifecycle, refurbishments, upgrades), |
| ANHUI HELI CO., LTD. | China | Public Company | Complete industrial vehicles (IC, electric, lithium, heavy forklifts, port and special vehicles),Spare parts and aftermarket (gearboxes, axles, brakes, hydraulics, attachments, batteries),Intelligent logistics and AGV solutions, |
| BYD COMPANY LTD. | China | Public Company | Automobiles and Related Products,Automobile Power Batteries and Lithium-ion Batteries,Mobile Handset Components, Assembly Service and Other Products, |
ENERSYS
EnerSys is a publicly traded United States company founded in 1991 that employs 9,682 people. The company specializes in energy storage and power conversion solutions.
TOYODA GOSEI CO., LTD
Toyoda Gosei Co., Ltd. is a Japanese public company established in 1949 with 41,304 employees. The company manufactures automotive components and industrial products.
TENNECO
Tenneco is a United States-based private company founded in 1930 with 71,000 employees. The company is a major manufacturer of automotive components and emission control systems.
ZF FRIEDRICHSHAFEN AG
ZF Friedrichshafen AG is a German private company established in 1915 with 145,909 employees. The company is a leading global supplier of driveline and chassis technology.
TOYOTA INDUSTRIES CORPORATION
Toyota Industries Corporation is a Japanese public company founded in 1926 with 81,808 employees. The company manufactures industrial equipment, vehicles, and textile machinery.
KION GROUP AG
KION Group AG is a German public company established in 2006 with 41,974 employees. The company is a leading supplier of industrial trucks and warehouse equipment.
JUNGHEINRICH AG
Jungheinrich AG is a German public company founded in 1953 with 21,438 employees. The company manufactures and distributes material handling equipment and warehouse solutions.
MITSUBISHI LOGISNEXT CO., LTD.
Mitsubishi Logisnext Co., Ltd. is a Japanese private company established in 1937 with 11,161 employees. The company manufactures forklifts and material handling equipment.
HYSTER-YALE MATERIALS HANDLING
Hyster-Yale Materials Handling is a publicly traded United States company founded in 1991 with 7,500 employees. The company manufactures forklifts and other material handling equipment.
CLARK MATERIAL HANDLING COMPANY
Clark Material Handling Company is a United States-based private company founded in 1903 with 249 employees. The company manufactures and distributes material handling equipment.
HYUNDAI CONSTRUCTION EQUIPMENT
Hyundai Construction Equipment is a South Korean public company founded in 1985 with 1,059 employees. The company manufactures construction and material handling equipment.
KOMATSU LTD.
Komatsu Ltd. is a Japanese public company established in 1884 with 67,279 employees. The company manufactures construction equipment, mining machinery, and industrial products.
BOBCAT COMPANY
Bobcat Company is a South Korean public company founded in 1947 with 142 employees. The company manufactures compact equipment and material handling solutions.
KALMAR
Kalmar is a Finnish public company founded in 2024 with 5,290 employees. The company provides cargo handling solutions and equipment.
ANHUI HELI CO., LTD.
Anhui Heli Co., Ltd. is a Chinese public company established in 1958 with 11,419 employees. The company manufactures forklifts and material handling equipment.
BYD COMPANY LTD.
BYD Company Ltd. is a Chinese public company founded in 1994 with 869,600 employees. The company is a major manufacturer of batteries, electric vehicles, and industrial equipment.
Reasons to Buy this Report
- Localized Market Intelligence : Gain Spain-specific insights on forklift demand drivers, regional logistics trends, and warehouse modernization initiatives. Understand how e-commerce growth and supply chain restructuring directly impact equipment purchasing decisions across Spanish markets.
- Competitive Positioning Data : Identify market opportunities and competitive dynamics specific to Spain's logistics sector. Benchmark your offerings against regional demand patterns and understand customer preferences in major distribution hubs like Madrid, Barcelona, and Valencia.
- Growth Forecasting & Planning : Leverage Spain's 4.7% CAGR projection through 2030 to inform strategic expansion plans. Make data-driven decisions on market entry, product development, and sales resource allocation tailored to Spanish market conditions.
- Supply Chain Insights : Understand Spain's role as a European distribution gateway and how cross-border logistics networks influence forklift demand. Identify emerging opportunities in automated warehousing and last-mile delivery infrastructure investments.
- Investment & Partnership Opportunities : Identify high-growth segments and regional partners within Spain's logistics ecosystem. Support M&A strategies, joint ventures, and distribution partnerships with data-backed market assessments specific to Spanish operations.
Frequently asked questions
What is the current size of Spain's forklift market in 2025?
Spain's forklift market is estimated at USD 40,915 million in 2025, reflecting strong demand from logistics, warehousing, and manufacturing sectors across the country.
What is the projected forklift market size for Spain by 2030?
Spain's forklift market is projected to reach USD 56,319 million by 2030, representing growth of approximately 37.6% over the five-year forecast period.
What is the CAGR for Spain's forklift market?
Spain's forklift market is expected to grow at a compound annual growth rate (CAGR) of 4.7% from 2025 to 2030.
What factors are driving growth in Spain's forklift market?
Key drivers include e-commerce expansion, supply chain modernization, automation investments in manufacturing and retail, and Spain's strategic position as a European distribution hub.
How does Spain's forklift market compare to other European markets?
Spain's 4.7% CAGR reflects steady, sustainable growth driven by regional logistics strength and industrial modernization, positioning it as a significant contributor to Europe's material handling equipment market.
RESEARCH METHODOLOGY
The research study involved extensive use of secondary sources, such as company annual reports/presentations, industry association publications, automotive magazine articles, directories, technical handbooks, the World Economic Outlook, trade websites, technical articles, and databases, to identify and collect information on the Forklift market. Primary interviews have been conducted to obtain and verify critical qualitative and quantitative information, as well as assess the prospects of the industry. Primary sources, experts from related industries, including forklift OEMs, battery and other component suppliers, were interviewed to obtain and verify critical information and assess the growth prospects and market estimations. Detailed interviews have been conducted with various primary respondents, including key industry participants, Subject-matter experts (SMEs), C-level executives of key market players, and industry consultants.
Secondary Research
Secondary sources for this research study included corporate filings (such as annual reports, investor presentations, and financial statements), white papers, certified publications, articles by recognized authors, directories, databases, and industry organizations such as the Industrial Truck Association (ITA), Material Handling Industry (MHI), and the International Warehouse Logistics Association (IWLA). The secondary data was collected and analyzed to determine the overall market size, which was further validated through primary research.
Primary Research
Primary interviews have been conducted with market experts from demand (OEM) and supply-side players across four major regions: North America, Europe, Asia Pacific, and Rest of the World. Approximately 20% of interviews have been conducted from the demand side (end-use industries such as warehouses, distribution centers, logistics hubs), while 80% of primary interviews have been conducted from the supply side (OEMs). The primary data was collected through questionnaires, e-mails, and telephone interviews. In the canvassing of primary interviews, various departments within organizations, such as sales and operations, have been covered to provide a holistic viewpoint in this report.
After interacting with industry experts, brief sessions with highly experienced independent consultants have been conducted to reinforce the findings from primary interviews. This, along with the opinions of the in-house SMEs, led to the findings described in the remainder of this report. Primary interviews have been conducted to gather insights, including forklift market estimation and forecast, future trends, and upcoming technologies in the forklift market. Data triangulation of all these points has been done using the information gathered from secondary research and model mapping. Stakeholders from the demand and supply sides have been interviewed to understand their views on the aforementioned points.
Following is the breakup of the primary study:
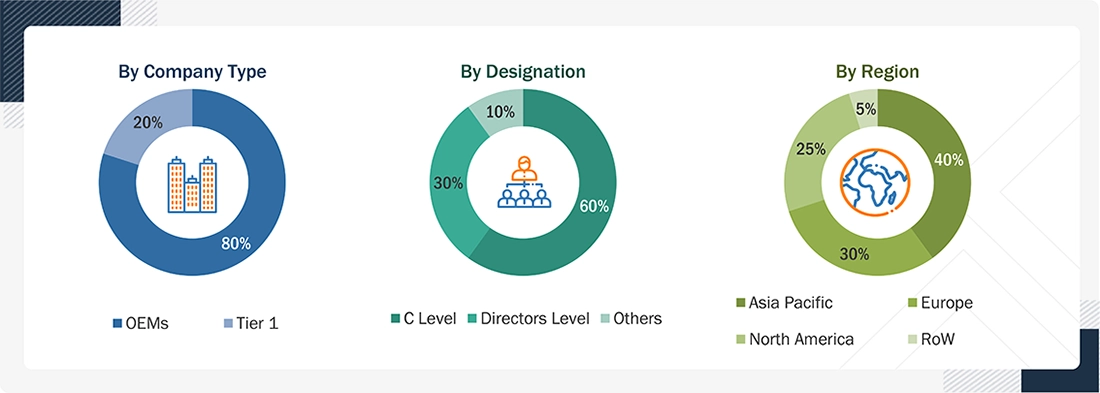
Note: Company types are based on the supply chain, and the value chain is not considered. Other company types include forklift suppliers (OEMs) and distributors. Other designations include sales, marketing, and product managers.
To know about the assumptions considered for the study, download the pdf brochure
Market Size Estimation
Bottom-Up Approach: Forklift MarketA detailed market estimation approach was followed to estimate and validate the value and volume of the Forklift market and other dependent submarkets, as mentioned below:
- Country-level forklift sales in units are derived from secondary sources, industry databases, OEM disclosures, trade associations, and validated through primary interviews.
- The forecast of forklift volumes is estimated leveraging several micro- and macroeconomic factors such as GDP and industrial production growth, warehouse and logistics activity, e-commerce growth, construction activity, fleet replacement cycles, electrification, automation, and technological advancements, among others.
- Country-level sales are segmented by forklift class, including Class 1, Class 2, Class 3 (Class 31 and Class 32), and Class 4/5, based on class-level penetration and available industry data. The derived market size and segment splits are cross-validated through OEM disclosures, industry associations, secondary databases, and primary interviews.
- Total country-level forklift sales are multiplied by the respective penetration of each forklift class to derive forklift market volume by class.
- Forklift volumes are further analyzed by powertrain, including electric and internal combustion engine (IC) forklifts, based on country-level adoption and sales data.
- Forklift demand is analyzed across major applications such as warehousing, manufacturing, logistics, construction, retail, and other material-handling operations, depending on data availability.
- These factors are used to estimate the forklift market volume in units by class, powertrain, and operation for each country.
- Country-level forklift volumes are summed to derive the regional forklift market (Units). Regional markets are further aggregated to derive the global forklift market in volume terms (units).
- Key players in the forklift market were identified through secondary research, and their global market rankings were determined through primary and secondary research.
- The research methodology included the study of annual and quarterly financial reports, regulatory filings of major market players, and interviews with industry experts to gain detailed market insights.
- All major penetration rates, percentage shares, splits, and breakdowns for the forklift market were determined through secondary sources and verified through primary sources.
- All key macro indicators affecting the revenue growth of the market segments and subsegments have been accounted for, viewed in extensive detail, verified through primary research, and analyzed to get the validated and verified quantitative & qualitative data.
- The market data gathered was consolidated and added with detailed inputs, analyzed, and presented in this report.
Top-Down Approach: Forklift Market
The top-down approach has been followed to determine the forklift market size by application, end-use industry, tire type, propulsion, and tonnage capacity in terms of volume and value. The region-wise forklift market volume and value (Asia Pacific, North America, Europe, and Rest of the World) have been derived from the global forklift market. The percentage share of forklifts by application, end-use industry, tire type, propulsion, and tonnage capacity has been derived from secondary sources and validated through primary interviews. It has been further multiplied by the region-wise forklift market volume and value. The forecast has been analyzed based on micro- and macro-economic factors such as countries' economic growth and GDP forecast trends, e-commerce industry growth, emission regulations, supply chain and logistics trends, and technological advancements. The market volume and value for forklifts by application, end-use industry, tire type, propulsion, and tonnage capacity have been derived through this. The summation of all region-wise markets has been done to obtain the total market for forklifts by application, end-use industry, tire type, operation, propulsion, and tonnage capacity in terms of volume (units) and value (USD million).
Forklift Market : Top-Down and Bottom-Up Approach
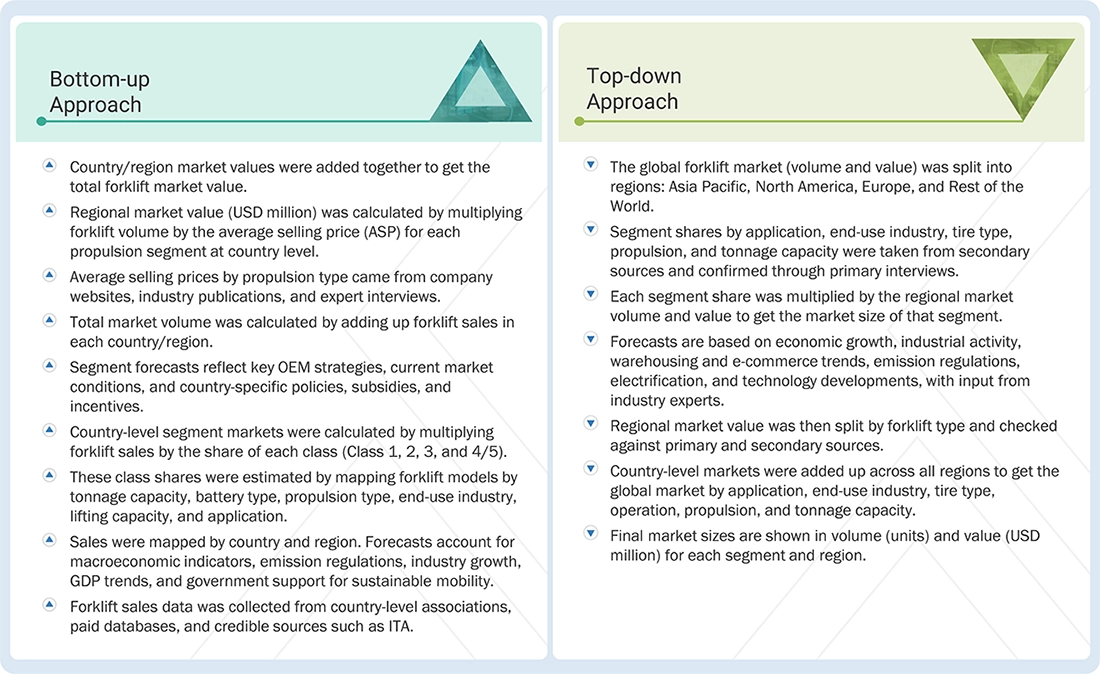
Source: MarketsandMarkets Analysis
Data Triangulation
All percentage shares, splits, and breakdowns have been determined using secondary sources and verified by primary sources. All parameters that affect the markets covered in this research study have been accounted for, viewed in extensive detail, and analyzed to obtain the final quantitative and qualitative data. This data has been consolidated and enhanced with detailed inputs and analysis from MarketsandMarkets and presented in the report. The following figure illustrates the overall market size estimation process employed for this study.
Market Definition
A forklift is an industrial vehicle with an attached, power-operated forked platform that can be raised and lowered to fit underneath cargo to lift or transfer it. Forklifts are used in many industries, including large storage facilities such as warehouses. Combustion engines and electric battery-powered forklifts are available in the market. This equipment is widely utilized throughout various sectors for transporting materials and goods.
Key Stakeholders
- Forklift system manufacturers
- Automation forklift solution & technology providers such as cameras, controllers, sensors, and other component suppliers
- Forklift rental fleet owners
- Forklift dealers and distributors
- Material handling associations, forums, and alliances
- Government agencies and policymakers
- Global industrial vehicle and container handler associations
Report Objectives
-
To define, describe, and forecast the forklift market in terms of value and volume based on the following segments:
- By tonnage capacity (<5 tons, 5–10 tons, 11–36 tons, and >36 tons)
- By application (indoor, outdoor, and indoor & outdoor)
- By class (class 1, class 2, class 3, and class 4/5)
- By end-use industry (third-party logistics (3PL), food & beverages, automotive, pulp & paper, metals and heavy machinery, e-commerce, aviation, semiconductors & electronics, chemicals, healthcare, and other end-use industries)
- By propulsion (electric, ICE, fuel cells)
- By operation (manual and autonomous)
- By type (warehouse and counterbalance)
- Electric forklift, by battery type (lithium-ion and lead-acid)
- Electric forklift market, by lifting capacity (<2 tons, 2–5 tons, and >5 tons)
- By tire type (cushion and pneumatic)
- Electric forklift by lifting capacity (<2 tons, 2–5 tons, and >5 tons)
- By region (Asia Pacific, Europe, North America, and Rest of the World)
- To provide detailed information about the major factors influencing market growth (drivers, challenges, restraints, and opportunities)
- To strategically analyze the market concerning individual growth trends, prospects, and contributions to the total market
- To strategically analyze the competitive landscape, prepare a company evaluation matrix for the players operating in the global market, evaluate the share/rankings based on product footprints of leading market players, and position them on the 2x2 quadrant. Also, analyze the competitive landscape of forklift manufacturers' startups/ SMEs, evaluate them based on product footprint, and position them on the 2x2 quadrant.
- To strategically analyze the market in terms of value chain, case study analysis, patent analysis, revenue analysis, OEM analysis, total cost of ownership, ecosystem analysis, trends/disruptions impacting buyers, pricing analysis, technology analysis, and regulatory analysis in the forklift market.
-
To study the following with respect to the market:
- Supply chain analysis
- Ecosystem analysis
- Technology analysis
- Case study analysis
- Patent analysis
- Regulatory landscape
- Pricing analysis
- Investment and funding scenario
- Key stakeholders and buying criteria
- OEM analysis
- To analyze competitive developments, such as product launches, deals, and other activities by key industry participants
- To examine the opportunities in the market for stakeholders and provide details of the competitive landscape for market leaders
Available Customizations:
With the given market data, MarketsandMarkets offers customizations according to the specific requirements of companies. The following customization options are available for the report:
Company Information
- Profiles of additional market players (up to 5)
Forklift Market by Tonnage Capacity at Country Level (For countries covered in the report)
- <5 Tons
- 5–10 Tons
- 11–36 Tons
- >36 Tons
Get the Full Forklift Market Report
Full forecast, segment splits, and company analysis for all Forklift Market.
Need a Tailored Report?
Customize this report to your needs
Get 10% FREE Customization
Customize This Report