Canada Genotyping Assay Market (2024-2029)
The Canada Genotyping Assay Market was valued at $807 Million in 2024 and projected to reach to $1436.7 Million by 2029, representing a compound annual growth rate of 12.2%. Canada's genotyping assay market is positioned for sustained growth through 2029, driven by increasing adoption of precision medicine across healthcare systems and growing patient demand for personalized treatment options.

| Market Size in | USD 26.32 MN |
| Market Forecast in | |
| CAGR | |
| Forecast Period | |
| Units Considered | Value (USD MN) |
Canada Genotyping Assay Market Trends and Insights
- This expansion in Canada reflects increasing adoption of precision medicine, rising demand for personalized healthcare solutions, and growing investment in genomic research infrastructure across Canadian healthcare institutions and diagnostic laboratories.
- Canada's strong regulatory framework and emphasis on advanced healthcare technologies are positioning the country as a key market for genotyping assay innovations. The Canadian market benefits from a well-established healthcare system, significant government funding for genomic research, and increasing collaboration between academic institutions and private sector players.
- Canada's commitment to precision medicine initiatives and the integration of genotyping assays into clinical practice are driving market penetration across oncology, pharmacogenomics, and infectious disease diagnostics.
- Between 2024 and 2029, Canada is expected to see accelerated adoption of next-generation sequencing and targeted genotyping platforms, supported by growing awareness among healthcare providers and patients regarding the benefits of genetic testing..
Key Market Statistics
- CAGR (2024-2029) 12.2% CAGR
- Market Size, 2024 ~USD 807 Million
- Forecast, 2029 ~USD 1436.7 Million
- Country Canada
Canada Genotyping Assay Market Overview
Market Valuation Growth :
Canada's genotyping assay market reached $807.0 million in 2024 and is projected to grow to $1,436.7 million by 2029, demonstrating strong market expansion driven by healthcare modernization and genomic adoption.
Precision Medicine Adoption :
Canadian healthcare institutions are increasingly integrating genotyping assays into clinical practice, supported by government funding for genomic research and personalized medicine initiatives across provinces.
Genomic Research Infrastructure :
Investment in Canadian genomic research centers and biotech hubs is accelerating, with major institutions leveraging genotyping assays for disease prevention, drug development, and population health studies.
Regulatory Support & Funding :
Canadian regulatory bodies and provincial health systems are actively supporting genomic testing adoption, with increased funding for precision healthcare programs and integration into standard clinical protocols.
Canada Genotyping Assay Market Dynamics
- Provincial health authorities are investing in genomic infrastructure, while Canadian biotech companies are expanding their genotyping capabilities to meet domestic and international demand. The 12.2% CAGR reflects strong momentum in clinical diagnostics, pharmacogenomics, and research applications.
- Key growth drivers include aging population demographics, rising prevalence of genetic disorders, and government initiatives supporting genomic medicine integration.
- Canadian healthcare providers are increasingly recognizing the clinical and economic value of genotyping assays in improving patient outcomes and reducing healthcare costs..
Market Ecosystem
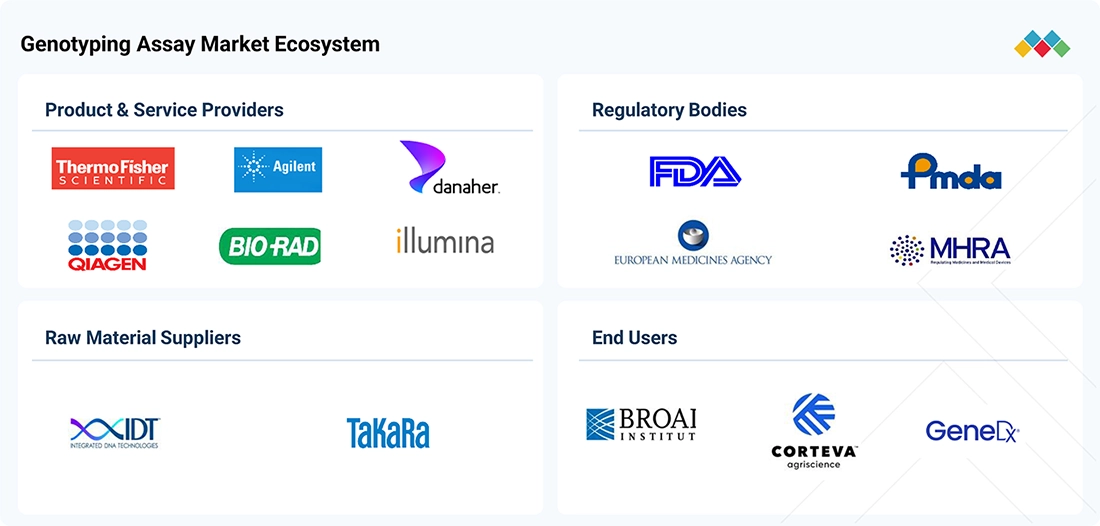
GENOTYPING ASSAY MARKET: COMMERCIAL USE CASES ACROSS INDUSTRIES
| COMPANY | USE CASE DESCRIPTION | BENEFITS |
|---|---|---|
 |
Provides genotyping technologies, including TaqMan SNP Genotyping Assays and Applied Biosystems real-time PCR platforms, for detecting genetic variations in research, pharmacogenomics, and clinical applications | Enables accurate detection of genetic variants, supports high-throughput genotyping workflows, and facilitates applications in drug discovery, genetic research, and personalized medicine |
 |
Provides microarray-based genotyping solutions, including Infinium arrays, and sequencing technologies for genome-wide association studies, population genomics, and genetic variation analysis | Supports high-throughput genetic analysis, enables large-scale population studies, and facilitates research into disease susceptibility, pharmacogenomics, and precision medicine |
Logos and trademarks shown above are the property of their respective owners. Their use here is for informational and illustrative purposes only.
Related Ecosystem
Advanced Genetic Sequencing
- Polymerase Chain Reaction (PCR)
- Reagents
- Assay Kits
- Bioinformatics
- Flow Cytometry
- Thermo Fisher Scientific Inc.
- Illumina, Inc.
- Qiagen N.V.
- Agilent Technologies, Inc.
- Danaher Corporation
Key Takeaways
- Canada's genotyping assay market is valued at $807.0 million in 2024 and is forecast to reach $1,436.7 million by 2029, growing at a 12.2% CAGR.
- Canada's strong healthcare infrastructure and government support for genomic research are key drivers of market expansion.
- Precision medicine adoption and integration of genotyping assays into clinical workflows are accelerating across Canadian healthcare systems.
- Canada's market growth is supported by increasing demand for personalized diagnostics in oncology, pharmacogenomics, and infectious disease management.
Genotyping Assay Market Report Scope
| Report Metric | Details |
|---|---|
| Base Year | 2024 |
| Fastest Growing Segment | PHARMACOGENOMICS (Application) |
| Forecast Period | 2024–2029 |
| Growth Rate | CAGR of 13.8% from 2024 to 2029 |
| Largest Segment | REAGENTS & KITS (Product & Service) |
| Market Size Base Year (Billions) | ~USD 19.44 (2024) |
| Revenue Forecast (Billions) | ~USD 37.1 (2029) |
| Segments Covered | Product & Service, Type, Technology, Application, End User |
Canada Genotyping Assay Market Report Segmentation
5 segment dimensions are covered across the global market.
By Product & Service
- Bioinformatics
- Genotyping Services
- Instruments
- Reagents & Kits
By Type
- Amplified Fragment Length Polymorphism
- Analyzers
- Digital Polymerase Chain Reaction
- Next-Generation Sequencing
- Pyrosequencing
- Real-Time Polymerase Chain Reaction
- Restriction Fragment Length Polymorphism
- Sanger Sequencing
- Sequencers & Amplifiers
- Services
- Single-Strand Confirmation Polymorphism
- Software
By Technology
- Capillary Electrophoresis
- Matrix-Assisted Laser Desorption/Ionization-Time Of Flight Mass Spectrometry
- Microarrays
- Other Technologies
- Polymerase Chain Reaction
- Sequencing
By Application
- Agricultural Biotechnology
- Animal Genetics
- Diagnostics & Personalized Medicines
- Other Applications
- Pharmacogenomics
By End User
- Academic & Research Institutes
- Diagnostic Laboratories
- Other End Users
- Pharmaceutical & Biopharmaceutical Companies
CANADA: GENOTYPING ASSAY MARKET, BY END USER, 2022–2029
| Segment | 2022 | 2023 | 2024 | 2025 | 2026 | 2027 | 2028 | 2029 | CAGR (%) |
|---|---|---|---|---|---|---|---|---|---|
| ACADEMIC & RESEARCH INSTITUTES | 133 | 183.2 | 200.9 | 221.5 | 245.7 | 274.1 | 307.5 | 346.8 | 11.5 |
| DIAGNOSTIC LABORATORIES | 162.6 | 178.4 | 197.1 | 218.9 | 244.6 | 274.7 | 310.4 | 352.6 | 12.3 |
| OTHER END USERS | 155.3 | 130.1 | 141.7 | 155.2 | 171 | 189.5 | 211.1 | 236.5 | 10.8 |
| PHARMACEUTICAL & BIOPHARMACEUTICAL COMPANIES | 216.2 | 239.6 | 267.3 | 299.8 | 338.1 | 383.3 | 436.9 | 500.7 | 13.4 |
| TOTAL | 667 | 731.3 | 807 | 895.5 | 999.4 | 1121.6 | 1265.9 | 1436.7 | 12.2 |
Target Audience
- Diagnostic Companies & IVD Manufacturers : Need Canada-specific market data to assess market size, growth potential, and competitive opportunities for genotyping assay product launches and expansion in Canadian healthcare systems.
- Pharmaceutical & Biotech Firms : Require insights into Canadian pharmacogenomics adoption and precision medicine trends to support drug development strategies and personalized medicine initiatives in the Canadian market.
- Healthcare Providers & Hospital Networks : Seek market intelligence on genotyping assay adoption trends, clinical applications, and ROI data to inform procurement decisions and integration of genomic testing into Canadian clinical workflows.
- Investment & Private Equity Firms : Need comprehensive Canada market analysis, growth forecasts, and competitive landscape data to evaluate investment opportunities in Canadian genomics and precision medicine companies.
- Government & Healthcare Policy Makers : Require market data and trend analysis to inform genomic medicine policy development, healthcare funding allocation, and strategic planning for precision medicine integration across Canadian provinces.
Key Companies in the Canada Genotyping Assay Market
| Company | HQ | Ownership | Strongest segments |
|---|---|---|---|
| SEQUENOM,INC. | United States | Private Company | MaterniT21 PLUS and VisibiliT NIPT,MaterniT21 GENOME and microarray (NextView),HerediT carrier screening (CF, Ashkenazi, SMA, fragile X), |
| DECODE GENETICS | Iceland | Private Company | Target discovery and validation for Amgen pipeline,Large-scale genome sequencing and analytics services,Data access, licensing, and collaborative research programs, |
| TRANSGENOMIC, INC. | United States | Public Company | Oncology and pharmacogenomics clinical trial services,Clinical oncology testing services (patient diagnostics and monitoring),Multiplexed ICE COLD-PCR reagents and technology licensing, |
| IMMUCOR, INC. | United States | Private Company | Transfusion serology reagents (manual and Capture),Automated serology instruments (NEO, Echo, Capture Workstation),Transplant & molecular assays (HEA/HPA typing, Array Imaging System, BASIS), |
| GENERAL ELECTRIC | United States | Public Company | Commercial Engines OE,Commercial Engines Services & MRO,Defense & Propulsion Technologies – Engines, |
| THERMO FISHER SCIENTIFIC INC. | United States | Public Company | Life Sciences Solutions,Analytical Instruments,Specialty Diagnostics, |
| ILLUMINA, INC. | United States | Public Company | Sequencing consumables (reagents, flow cells, library prep),Sequencing instruments,Array-based instruments and consumables, |
| DANAHER CORPORATION | United States | Public Company | Biotechnology,Life Sciences,Diagnostics, |
| QIAGEN | Netherlands | Public Company | Sample technology consumables and instruments,Molecular diagnostics assays (TB, oncology, sexual and reproductive health),PCR and enzymes (qPCR, dPCR, research PCR kits), |
| EUROFINS SCIENTIFIC | Luxembourg | Public Company | Food and Feed Testing,Environment Testing,Biopharma and Clinical Diagnostics, |
| AGILENT TECHNOLOGIES, INC. | United States | Public Company | Life Sciences and Diagnostics Markets,Agilent CrossLab,Applied Markets, |
| BIO-RAD LABORATORIES, INC. | United States | Public Company | Clinical Diagnostics,Life Science Research Tools,Other / Services and Software, |
| MERCK KGAA | Germany | Public Company | Life Science (lab reagents, consumables, bioprocessing, CDMO/testing),Healthcare (oncology, neurology, immunology, fertility, rare diseases),Electronics (semiconductor materials, specialty gases, display and OLED materials), |
| STANDARD BIOTOOLS | United States | Public Company | Proteomics platforms and consumables (SomaScan, CyTOF, Hyperion),Genomics and qPCR systems (Biomark X9 and related assays),Services, software, and other consumables, |
| REVVITY | United States | Public Company | Diagnostics instruments and automation (AutoDELFIA, GSP, EUROIMMUN, IDS-iSYS, EUROLabWorkstation),Diagnostics reagents, assays, and kits (prenatal, newborn, autoimmune, infectious disease, T-SPOT),Life science reagents and consumables (BioLegend, Dharmacon, NEXTFLEX, AlphaLISA portfolio), |
| PACBIO | United States | Public Company | Long-read instruments (Revio, Sequel, Vega),Long-read consumables (SMRT cells, library prep, binding and sequencing kits),Short-read instruments and consumables (Onso platform), |
| OXFORD NANOPORE TECHNOLOGIES PLC | United Kingdom | Public Company | PromethION platforms and consumables,MinION and portable platforms,GridION and mid-throughput systems, |
SEQUENOM,INC.
Sequenom, Inc. is a private molecular diagnostics company founded in 1994 in the United States with 434 employees. The company specializes in genetic testing and analysis.
DECODE GENETICS
Decode Genetics is a private genomics and biotechnology company founded in 1996 in Iceland with 331 employees. The company conducts genetic research and develops diagnostics based on genomic data.
TRANSGENOMIC, INC.
Transgenomic, Inc. is a public molecular diagnostics company founded in 1997 in the United States with 19 employees. The company develops genetic testing and analysis technologies.
IMMUCOR, INC.
Immucor, Inc. is a private blood bank and transfusion diagnostics company founded in 1982 in the United States with 1,125 employees. The company provides immunohematology and transfusion medicine solutions.
GENERAL ELECTRIC
General Electric is a public multinational conglomerate founded in 1892 in the United States with 57,000 employees. The company operates across diverse industries including healthcare, energy, and industrial sectors.
THERMO FISHER SCIENTIFIC INC.
Thermo Fisher Scientific Inc. is a public life sciences and diagnostics company founded in 1956 in the United States with 125,000 employees. The company provides laboratory equipment, reagents, and analytical instruments globally.
ILLUMINA, INC.
Illumina, Inc. is a public genomics and sequencing company founded in 1998 in the United States with 8,625 employees. The company develops DNA sequencing and genetic analysis technologies.
DANAHER CORPORATION
Danaher Corporation is a public diversified conglomerate founded in 1969 in the United States with 59,000 employees. The company operates across life sciences, diagnostics, and environmental solutions.
QIAGEN
Qiagen is a public molecular diagnostics and life sciences company founded in 1984 in the Netherlands with 5,500 employees. The company provides sample preparation, assay, and sequencing technologies.
EUROFINS SCIENTIFIC
Eurofins Scientific is a public laboratory services and diagnostics company founded in 1987 in Luxembourg with 65,694 employees. The company operates a global network of laboratories providing testing and analysis services.
AGILENT TECHNOLOGIES, INC.
Agilent Technologies, Inc. is a public life sciences and diagnostics company founded in 1999 in the United States with 18,000 employees. The company manufactures analytical instruments and laboratory equipment.
BIO-RAD LABORATORIES, INC.
Bio-Rad Laboratories, Inc. is a public life sciences and diagnostics company founded in 1952 in the United States with 7,450 employees. The company develops and manufactures clinical diagnostics and life science research products.
MERCK KGAA
Merck KGaA is a public pharmaceutical and life sciences company founded in 1668 in Germany with 59,077 employees. The company provides pharmaceuticals, chemicals, and laboratory solutions globally.
STANDARD BIOTOOLS
Standard Biotools is a public life sciences instrumentation company founded in 1999 in the United States with 387 employees. The company develops microfluidics and single-cell analysis technologies.
REVVITY
Revvity is a public life sciences and diagnostics company founded in 1937 in the United States with 11,000 employees. The company provides analytical instruments, reagents, and software solutions.
PACBIO
PacBio is a public genomics sequencing company founded in 2000 in the United States with 485 employees. The company develops long-read DNA sequencing technologies.
OXFORD NANOPORE TECHNOLOGIES PLC
Oxford Nanopore Technologies PLC is a public genomics sequencing company founded in 2005 in the United Kingdom with 1,316 employees. The company develops portable DNA and RNA sequencing technologies.
Reasons to Buy this Report
- Market Size & Growth Validation : Obtain precise market valuation data for Canada ($807M in 2024) with 5-year forecasts to validate investment decisions and competitive positioning in the Canadian genotyping assay sector.
- Regional Growth Drivers Analysis : Understand Canada-specific factors driving 12.2% CAGR, including precision medicine adoption, provincial healthcare policies, and genomic research funding to identify market opportunities.
- Competitive Landscape Intelligence : Benchmark against Canadian market dynamics and identify key players, market gaps, and expansion opportunities specific to Canada's healthcare and biotech ecosystem.
- Strategic Market Entry Planning : Develop informed go-to-market strategies for Canada with localized insights on regulatory requirements, healthcare system integration, and customer adoption patterns in the genotyping assay space.
- Investment & Partnership Decisions : Make data-driven decisions on Canadian market investments, partnerships, and acquisitions with comprehensive market forecasts and growth trajectory analysis through 2029.
Frequently asked questions
What is the current size of Canada's genotyping assay market?
Canada's genotyping assay market was valued at $807.0 million in 2024 and is expected to grow to $1,436.7 million by 2029.
What is the projected growth rate for Canada's genotyping assay market?
Canada's genotyping assay market is projected to grow at a compound annual growth rate (CAGR) of 12.2% from 2024 to 2029.
What factors are driving growth in Canada's genotyping assay market?
Key drivers include increasing adoption of precision medicine, government funding for genomic research, growing demand for personalized healthcare, and integration of genotyping assays into clinical practice across Canadian healthcare institutions.
Which applications are leading Canada's genotyping assay market growth?
Oncology, pharmacogenomics, and infectious disease diagnostics are among the leading applications driving genotyping assay adoption in Canada.
How does Canada's market compare to global genotyping assay market trends?
Canada's 12.2% CAGR is slightly below the global average of 13.8%, reflecting Canada's mature healthcare system and steady, sustainable market expansion driven by precision medicine initiatives.
RESEARCH METHODOLOGY
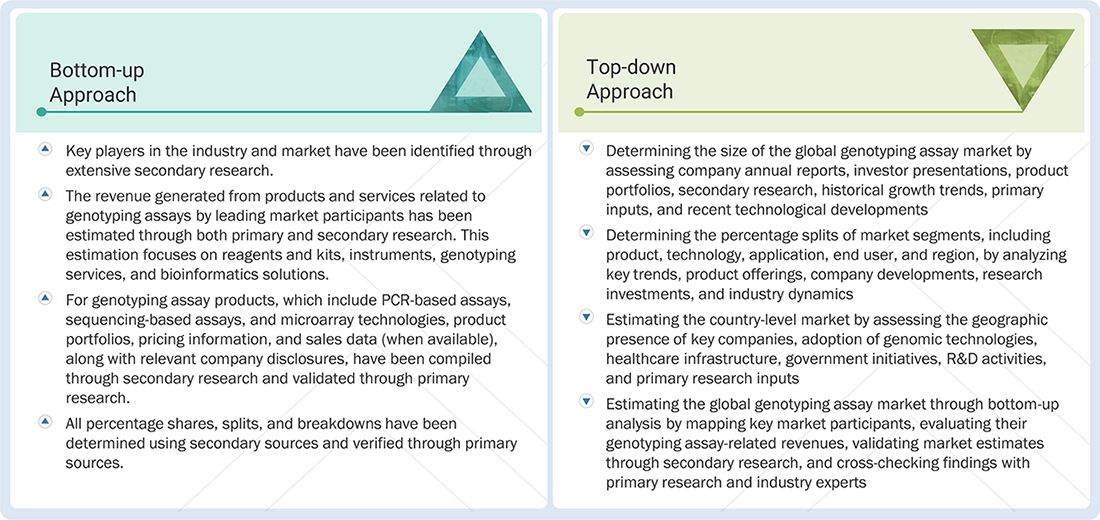
This study involved four major activities to estimate the current size of the genotyping assay market. Exhaustive secondary research was conducted to gather information on the market, its peer markets, and its parent market. These findings, assumptions, and sizing were then validated with industry experts across the value chain through primary research. Both top-down and bottom-up approaches were employed to estimate the total market size. Following this, data triangulation was used to estimate the market size of segments and subsegments.
Secondary Research
Secondary research was primarily used to identify and gather information for the extensive, technical, market-oriented, and commercial study. Secondary sources for this study included publications from government agencies, such as the National Center for Biotechnology Information (NCBI), National Institutes of Health (NIH), World Health Organization (WHO), Food and Drug Administration (FDA), European Medicines Agency (EMA), Pharmaceutical Research and Manufacturers of America (PhRMA), Global Cancer Observatory (GLOBOCAN), Centers for Disease Control and Prevention (CDC), and European Federation of Biotechnology. Secondary sources also included corporate and regulatory filings (such as annual reports, SEC filings, investor presentations, and financial statements); business magazines and research journals; press releases; and trade, business, and professional associations. These sources were used to obtain key information on major players, global product revenues, market classification, segmentation by industry trends and regional/country-level markets, market developments, and technology perspectives. Secondary data were collected and analyzed to determine the overall size of the global genotyping assay market, and the findings were validated through primary research.
Primary Research
In-depth interviews were conducted with primary respondents, including key industry participants, subject-matter experts (SMEs), C-level executives of key market players, and industry consultants, among others, to obtain and verify critical qualitative and quantitative information and to assess market prospects. Primary sources from both the supply and demand sides of the market were interviewed to gather qualitative and quantitative data. The following is a breakdown of the primary respondents:
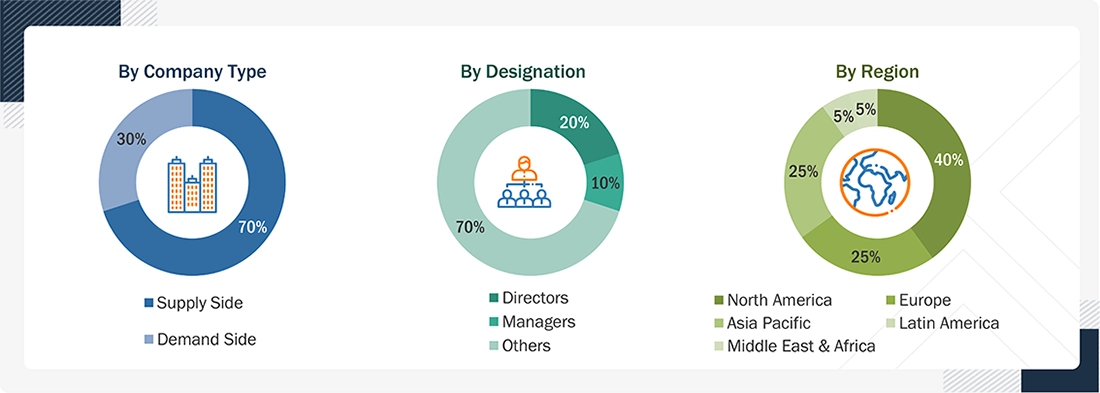
To know about the assumptions considered for the study, download the pdf brochure
Market Size Estimation
The global size of the genotyping assay market was estimated using multiple approaches. A detailed market estimation approach was used to estimate and validate the market value and other dependent submarkets. These methods were also used extensively to estimate the size of various subsegments in the market. The research methodology used to estimate the market size includes the following:
Genotyping Assay Market : Top-Down and Bottom-Up Approach
Data Triangulation
After estimating the overall market size through the market size estimation process, the total market was divided into several segments. To complete the overall market engineering process and arrive at the exact statistics for all segments, the data triangulation procedure was employed; it involved analyzing various factors and trends from both the demand and supply sides.
Market Definition
Genotyping assays are laboratory techniques that identify genetic variations in an individual's DNA. These assays detect single-nucleotide polymorphisms (SNPs), insertions, deletions, and other variants using technologies such as polymerase chain reaction (PCR), microarrays, and DNA sequencing. Genotyping assays are widely used in clinical diagnostics, personalized medicine, pharmacogenomics, drug discovery and development, and genetic research. They also have applications in agricultural biotechnology and animal genetics, supporting crop improvement, livestock breeding, and genetic trait identification. Increasing demand for precision medicine, advances in genomic technologies, and the growing use of genetic analysis in biomedical research are driving the adoption of genotyping assays across healthcare, pharmaceutical, biotechnology, and research industries.
Key Stakeholders
- Academic Research Institutes
- Raw Materials Manufacturers & Distributors
- Contract Research Organizations (CROs)
- Manufacturer Service Providers
- Market Research and Consulting Firms
- Pharmaceutical & Biotechnology Companies
- Regulatory Agencies
- Venture Capitalists
- Government organizations
- Private Research Firms
- Contract Development and Manufacturing Organizations (CDMOs)
Report Objectives
- To define, describe, and forecast the genotyping assays market by product & service, technology, application, end user, and region
- To provide detailed information regarding the major factors influencing market growth (such as drivers, restraints, opportunities, and challenges)
- To analyze the micromarkets with respect to individual growth trends, prospects, and contributions to the overall lipid nanoparticles market
- To analyze opportunities for stakeholders and provide details of the competitive landscape for market leaders
- To forecast the size of the market segments with respect to six regions: North America (US and Canada), Europe (Germany, France, the UK, Italy, Spain, and the Rest of Europe), Asia Pacific (China, Japan, India, and Rest of Asia Pacific), Latin America (Brazil, Mexico, and Rest of Latin America), Middle East and Africa
- To profile the key players and analyze their market share and core competencies
- To analyze competitive developments, such as product launches, partnerships, agreements, collaborations, and expansions
- To benchmark players within the market using the proprietary “Company Evaluation Matrix” framework, which analyzes market players on various parameters within the broad categories of business and product excellence strategy
Available customizations:
With the given market data, MarketsandMarkets offers customizations as per the company’s specific needs. The following customization options are available for the report:
Geographical Analysis
- Further breakdown of the Rest of genotyping assay market, by country
- Further breakdown of the Rest of Asia Pacific genotyping assay market, by country
Company Information
- Detailed analysis and profiling of additional market players (up to five)
Segment Analysis
-
Cross-segment analysis
Get the Full Genotyping Assay Market Report
Full forecast, segment splits, and company analysis for all Genotyping Assay Market.
- US Genotyping Assay Market
- Germany Genotyping Assay Market
- UK Genotyping Assay Market
- France Genotyping Assay Market
- Italy Genotyping Assay Market
- Spain Genotyping Assay Market
- China Genotyping Assay Market
- Japan Genotyping Assay Market
- India Genotyping Assay Market
- Brazil Genotyping Assay Market
- Mexico Genotyping Assay Market
Need a Tailored Report?
Customize this report to your needs
Get 10% FREE Customization
Customize This Report