US Genotyping Assay Market (2024-2029)

The US Genotyping Assay Market was valued at $3908.5 Million in 2024 and projected to reach to $8003.7 Million by 2029, representing a compound annual growth rate of 15.4%. The US genotyping assay market is positioned for exceptional growth through 2029, driven by accelerating adoption of precision medicine across clinical settings and increasing insurance coverage for genomic testing.


| Market Size in | USD 26.32 MN |
| Market Forecast in | |
| CAGR | |
| Forecast Period | |
| Units Considered | Value (USD MN) |
US Genotyping Assay Market Trends and Insights
- This growth trajectory reflects the US healthcare sector's increasing adoption of precision medicine and personalized genomic testing across clinical diagnostics, pharmacogenomics, and research applications.
- The US market is driven by rising demand for cost-effective genotyping solutions, expanding insurance coverage for genetic testing, and accelerating integration of genomic data into clinical workflows. Throughout the 2024–2029 forecast period, the US genotyping assay market will benefit from technological advances in high-throughput sequencing, growing prevalence of genetic disorders, and strengthened regulatory frameworks supporting genomic innovation.
- The US healthcare infrastructure's emphasis on preventive care and early disease detection continues to fuel investment in genotyping platforms.
- With a compound annual growth rate of 15.4%, the US market significantly outpaces global trends, positioning the country as a critical hub for genotyping assay development and commercialization..
Key Market Statistics
- CAGR (2024-2029) 15.4% CAGR
- Market Size, 2024 ~USD 3908.5 Million
- Forecast, 2029 ~USD 8003.7 Million
- Country US
US Genotyping Assay Market Overview
Market Valuation Growth :
The US genotyping assay market is valued at $3,908.5 million in 2024, with a projected CAGR of 15.4%, reaching $8,003.7 million by 2029, significantly outpacing the global growth rate of 13.8%.
Precision Medicine Adoption :
US healthcare providers are increasingly integrating genotyping assays into clinical diagnostics and personalized treatment protocols, driven by growing patient demand for precision medicine solutions and genomic-based healthcare decisions.
Pharmacogenomics Expansion :
Pharmacogenomic testing is accelerating across US hospitals and clinical laboratories, enabling providers to optimize drug selection and dosing based on individual genetic profiles, reducing adverse events and improving patient outcomes.
Research & Development Investment :
US academic institutions and biotech companies are substantially investing in genotyping research applications, supporting the development of advanced assay technologies and expanding the addressable market for genomic testing solutions.
US Genotyping Assay Market Dynamics
- Healthcare providers are integrating genotyping assays into routine diagnostic workflows, particularly in oncology, cardiology, and pharmacogenomics, supported by declining sequencing costs and improved accessibility.
- Regulatory clarity from the FDA and growing clinical evidence supporting genomic-guided treatment decisions are strengthening market confidence.
- The US market's growth trajectory reflects strong healthcare infrastructure investment, high patient awareness, and robust reimbursement frameworks that exceed global averages..
Market Ecosystem
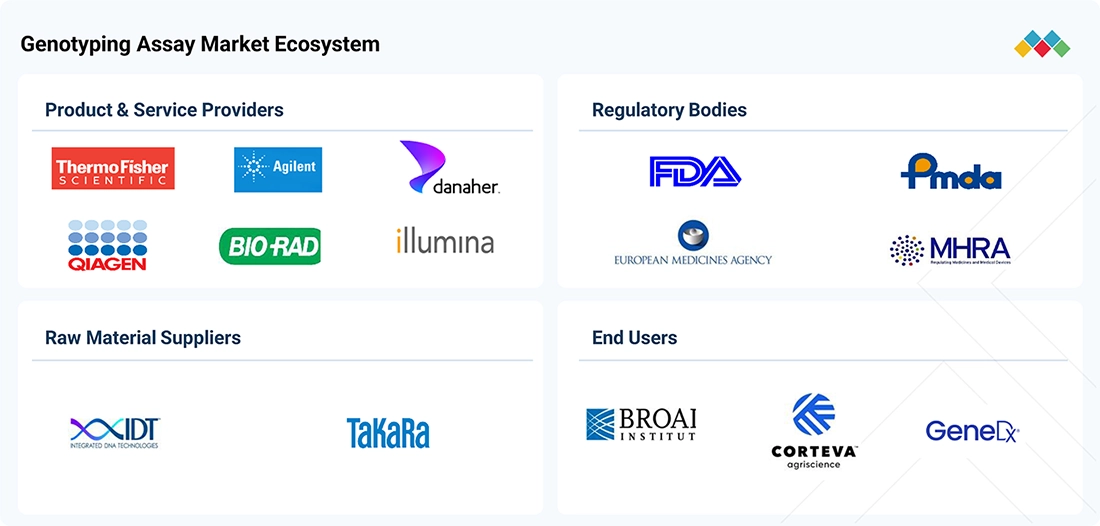
GENOTYPING ASSAY MARKET: COMMERCIAL USE CASES ACROSS INDUSTRIES
| COMPANY | USE CASE DESCRIPTION | BENEFITS |
|---|---|---|
 |
Provides genotyping technologies, including TaqMan SNP Genotyping Assays and Applied Biosystems real-time PCR platforms, for detecting genetic variations in research, pharmacogenomics, and clinical applications | Enables accurate detection of genetic variants, supports high-throughput genotyping workflows, and facilitates applications in drug discovery, genetic research, and personalized medicine |
 |
Provides microarray-based genotyping solutions, including Infinium arrays, and sequencing technologies for genome-wide association studies, population genomics, and genetic variation analysis | Supports high-throughput genetic analysis, enables large-scale population studies, and facilitates research into disease susceptibility, pharmacogenomics, and precision medicine |
Logos and trademarks shown above are the property of their respective owners. Their use here is for informational and illustrative purposes only.
Related Ecosystem
Advanced Genetic Sequencing
- Polymerase Chain Reaction (PCR)
- Reagents
- Assay Kits
- Bioinformatics
- Flow Cytometry
- Thermo Fisher Scientific Inc.
- Illumina, Inc.
- Qiagen N.V.
- Agilent Technologies, Inc.
- Danaher Corporation
Key Takeaways
- The US genotyping assay market will double in value from $3,908.5M (2024) to $8,003.7M (2029), driven by precision medicine adoption across US healthcare systems.
- The US market's 15.4% CAGR outperforms the global average of 13.8%, reflecting strong US demand for personalized genomic testing and pharmacogenomics.
- US regulatory support, insurance reimbursement expansion, and integration of genomic data into clinical workflows are accelerating market growth through 2029.
- The US genotyping assay market benefits from advanced sequencing infrastructure, high healthcare spending, and a robust biotech ecosystem supporting innovation.
Genotyping Assay Market Report Scope
| Report Metric | Details |
|---|---|
| Base Year | 2024 |
| Fastest Growing Segment | PHARMACOGENOMICS (Application) |
| Forecast Period | 2024–2029 |
| Growth Rate | CAGR of 13.8% from 2024 to 2029 |
| Largest Segment | REAGENTS & KITS (Product & Service) |
| Market Size Base Year (Billions) | ~USD 19.44 (2024) |
| Revenue Forecast (Billions) | ~USD 37.1 (2029) |
| Segments Covered | Product & Service, Type, Technology, Application, End User |
US Genotyping Assay Market Report Segmentation
5 segment dimensions are covered across the global market.
By Product & Service
- Bioinformatics
- Genotyping Services
- Instruments
- Reagents & Kits
By Type
- Amplified Fragment Length Polymorphism
- Analyzers
- Digital Polymerase Chain Reaction
- Next-Generation Sequencing
- Pyrosequencing
- Real-Time Polymerase Chain Reaction
- Restriction Fragment Length Polymorphism
- Sanger Sequencing
- Sequencers & Amplifiers
- Services
- Single-Strand Confirmation Polymorphism
- Software
By Technology
- Capillary Electrophoresis
- Matrix-Assisted Laser Desorption/Ionization-Time Of Flight Mass Spectrometry
- Microarrays
- Other Technologies
- Polymerase Chain Reaction
- Sequencing
By Application
- Agricultural Biotechnology
- Animal Genetics
- Diagnostics & Personalized Medicines
- Other Applications
- Pharmacogenomics
By End User
- Academic & Research Institutes
- Diagnostic Laboratories
- Other End Users
- Pharmaceutical & Biopharmaceutical Companies
US: GENOTYPING ASSAY MARKET, BY END USER, 2022–2029
| Segment | 2022 | 2023 | 2024 | 2025 | 2026 | 2027 | 2028 | 2029 | CAGR (%) |
|---|---|---|---|---|---|---|---|---|---|
| ACADEMIC & RESEARCH INSTITUTES | 1292.5 | 1830.4 | 2052.4 | 2314.4 | 2624.6 | 2993.1 | 3432.6 | 3958.5 | 14 |
| DIAGNOSTIC LABORATORIES | 1535.2 | 1723 | 1945.9 | 2210.1 | 2524.4 | 2899.4 | 3348.9 | 3889.5 | 14.9 |
| OTHER END USERS | 1520.3 | 1295 | 1442.5 | 1615.8 | 1820.2 | 2061.9 | 2348.9 | 2690.8 | 13.3 |
| PHARMACEUTICAL & BIOPHARMACEUTICAL COMPANIES | 1939 | 2200.4 | 2512.1 | 2883.4 | 3327.3 | 3860 | 4501.8 | 5278.2 | 16 |
| TOTAL | 6287 | 7048.8 | 7952.9 | 9023.7 | 10296.4 | 11814.5 | 13632.2 | 15816.9 | 14.7 |
Target Audience
- Diagnostic Laboratory Operators : US clinical laboratories and diagnostic centers need market intelligence to expand genotyping service offerings, optimize testing menus, and capitalize on growing demand for precision medicine and pharmacogenomic testing.
- Pharmaceutical & Biotech Companies : US-based pharma and biotech firms require market data to develop companion diagnostics, support precision medicine initiatives, and understand genotyping assay adoption rates among healthcare providers and patients.
- Healthcare System Administrators : Hospital networks and integrated healthcare systems need US market insights to evaluate genotyping assay integration, assess reimbursement potential, and plan genomic medicine program investments.
- Medical Device & Assay Manufacturers : Genotyping assay developers and manufacturers require US-specific market forecasts, competitive analysis, and adoption trends to guide product development, commercialization strategies, and market entry planning.
- Healthcare Investors & Consultants : Investment firms and management consultants need validated US market data, growth projections, and segment analysis to evaluate investment opportunities and advise clients on precision medicine and genomics sector positioning.
Key Companies in the US Genotyping Assay Market
| Company | HQ | Ownership | Strongest segments |
|---|---|---|---|
| SEQUENOM,INC. | United States | Private Company | MaterniT21 PLUS and VisibiliT NIPT,MaterniT21 GENOME and microarray (NextView),HerediT carrier screening (CF, Ashkenazi, SMA, fragile X), |
| DECODE GENETICS | Iceland | Private Company | Target discovery and validation for Amgen pipeline,Large-scale genome sequencing and analytics services,Data access, licensing, and collaborative research programs, |
| TRANSGENOMIC, INC. | United States | Public Company | Oncology and pharmacogenomics clinical trial services,Clinical oncology testing services (patient diagnostics and monitoring),Multiplexed ICE COLD-PCR reagents and technology licensing, |
| IMMUCOR, INC. | United States | Private Company | Transfusion serology reagents (manual and Capture),Automated serology instruments (NEO, Echo, Capture Workstation),Transplant & molecular assays (HEA/HPA typing, Array Imaging System, BASIS), |
| GENERAL ELECTRIC | United States | Public Company | Commercial Engines OE,Commercial Engines Services & MRO,Defense & Propulsion Technologies – Engines, |
| THERMO FISHER SCIENTIFIC INC. | United States | Public Company | Life Sciences Solutions,Analytical Instruments,Specialty Diagnostics, |
| ILLUMINA, INC. | United States | Public Company | Sequencing consumables (reagents, flow cells, library prep),Sequencing instruments,Array-based instruments and consumables, |
| DANAHER CORPORATION | United States | Public Company | Biotechnology,Life Sciences,Diagnostics, |
| QIAGEN | Netherlands | Public Company | Sample technology consumables and instruments,Molecular diagnostics assays (TB, oncology, sexual and reproductive health),PCR and enzymes (qPCR, dPCR, research PCR kits), |
| EUROFINS SCIENTIFIC | Luxembourg | Public Company | Food and Feed Testing,Environment Testing,Biopharma and Clinical Diagnostics, |
| AGILENT TECHNOLOGIES, INC. | United States | Public Company | Life Sciences and Diagnostics Markets,Agilent CrossLab,Applied Markets, |
| BIO-RAD LABORATORIES, INC. | United States | Public Company | Clinical Diagnostics,Life Science Research Tools,Other / Services and Software, |
| MERCK KGAA | Germany | Public Company | Life Science (lab reagents, consumables, bioprocessing, CDMO/testing),Healthcare (oncology, neurology, immunology, fertility, rare diseases),Electronics (semiconductor materials, specialty gases, display and OLED materials), |
| STANDARD BIOTOOLS | United States | Public Company | Proteomics platforms and consumables (SomaScan, CyTOF, Hyperion),Genomics and qPCR systems (Biomark X9 and related assays),Services, software, and other consumables, |
| REVVITY | United States | Public Company | Diagnostics instruments and automation (AutoDELFIA, GSP, EUROIMMUN, IDS-iSYS, EUROLabWorkstation),Diagnostics reagents, assays, and kits (prenatal, newborn, autoimmune, infectious disease, T-SPOT),Life science reagents and consumables (BioLegend, Dharmacon, NEXTFLEX, AlphaLISA portfolio), |
| PACBIO | United States | Public Company | Long-read instruments (Revio, Sequel, Vega),Long-read consumables (SMRT cells, library prep, binding and sequencing kits),Short-read instruments and consumables (Onso platform), |
| OXFORD NANOPORE TECHNOLOGIES PLC | United Kingdom | Public Company | PromethION platforms and consumables,MinION and portable platforms,GridION and mid-throughput systems, |
SEQUENOM,INC.
Sequenom, Inc. is a private molecular diagnostics company founded in 1994 in the United States with 434 employees. The company specializes in genetic testing and analysis.
DECODE GENETICS
Decode Genetics is a private genomics and biotechnology company founded in 1996 in Iceland with 331 employees. The company conducts genetic research and develops diagnostics based on genomic data.
TRANSGENOMIC, INC.
Transgenomic, Inc. is a public molecular diagnostics company founded in 1997 in the United States with 19 employees. The company develops genetic testing and analysis technologies.
IMMUCOR, INC.
Immucor, Inc. is a private blood bank and transfusion diagnostics company founded in 1982 in the United States with 1,125 employees. The company provides immunohematology and transfusion medicine solutions.
GENERAL ELECTRIC
General Electric is a public multinational conglomerate founded in 1892 in the United States with 57,000 employees. The company operates across diverse industries including healthcare, energy, and industrial sectors.
THERMO FISHER SCIENTIFIC INC.
Thermo Fisher Scientific Inc. is a public life sciences and diagnostics company founded in 1956 in the United States with 125,000 employees. The company provides laboratory equipment, reagents, and analytical instruments globally.
ILLUMINA, INC.
Illumina, Inc. is a public genomics and sequencing company founded in 1998 in the United States with 8,625 employees. The company develops DNA sequencing and genetic analysis technologies.
DANAHER CORPORATION
Danaher Corporation is a public diversified conglomerate founded in 1969 in the United States with 59,000 employees. The company operates across life sciences, diagnostics, and environmental solutions.
QIAGEN
Qiagen is a public molecular diagnostics and life sciences company founded in 1984 in the Netherlands with 5,500 employees. The company provides sample preparation, assay, and sequencing technologies.
EUROFINS SCIENTIFIC
Eurofins Scientific is a public laboratory services and diagnostics company founded in 1987 in Luxembourg with 65,694 employees. The company operates a global network of laboratories providing testing and analysis services.
AGILENT TECHNOLOGIES, INC.
Agilent Technologies, Inc. is a public life sciences and diagnostics company founded in 1999 in the United States with 18,000 employees. The company manufactures analytical instruments and laboratory equipment.
BIO-RAD LABORATORIES, INC.
Bio-Rad Laboratories, Inc. is a public life sciences and diagnostics company founded in 1952 in the United States with 7,450 employees. The company develops and manufactures clinical diagnostics and life science research products.
MERCK KGAA
Merck KGaA is a public pharmaceutical and life sciences company founded in 1668 in Germany with 59,077 employees. The company provides pharmaceuticals, chemicals, and laboratory solutions globally.
STANDARD BIOTOOLS
Standard Biotools is a public life sciences instrumentation company founded in 1999 in the United States with 387 employees. The company develops microfluidics and single-cell analysis technologies.
REVVITY
Revvity is a public life sciences and diagnostics company founded in 1937 in the United States with 11,000 employees. The company provides analytical instruments, reagents, and software solutions.
PACBIO
PacBio is a public genomics sequencing company founded in 2000 in the United States with 485 employees. The company develops long-read DNA sequencing technologies.
OXFORD NANOPORE TECHNOLOGIES PLC
Oxford Nanopore Technologies PLC is a public genomics sequencing company founded in 2005 in the United Kingdom with 1,316 employees. The company develops portable DNA and RNA sequencing technologies.
Reasons to Buy this Report
- Market Size & Growth Validation : Obtain precise US market valuation data ($3.9B in 2024) and verified 15.4% CAGR projections through 2029 to support strategic planning, investment decisions, and competitive positioning in the high-growth genotyping sector.
- US-Specific Adoption Insights : Access detailed analysis of precision medicine adoption patterns, clinical integration rates, and healthcare provider behavior specific to the US market, enabling targeted go-to-market strategies and customer segmentation.
- Reimbursement & Regulatory Landscape : Understand US-specific insurance coverage trends, FDA regulatory pathways, and reimbursement frameworks that directly impact market accessibility and revenue potential for genotyping assay providers and developers.
- Competitive Benchmarking : Benchmark your organization against US market competitors with region-specific performance metrics, market share analysis, and competitive positioning data to identify growth opportunities and differentiation strategies.
- Segment & Application Analysis : Gain insights into US demand drivers across clinical diagnostics, pharmacogenomics, and research applications with segment-level forecasts to prioritize product development and resource allocation decisions.
Frequently asked questions
What is the current size of the US genotyping assay market in 2024?
The US genotyping assay market is valued at $3,908.5 million in 2024, representing a significant segment of the global precision medicine landscape.
What is the projected size of the US genotyping assay market by 2029?
The US genotyping assay market is forecast to reach $8,003.7 million by 2029, reflecting a compound annual growth rate of 15.4%.
Why is the US genotyping assay market growing faster than the global average?
The US market grows at 15.4% CAGR versus the global 13.8% due to advanced healthcare infrastructure, high insurance reimbursement rates, strong biotech innovation, and widespread adoption of precision medicine in US clinical practice.
What are the primary drivers of growth in the US genotyping assay market?
Key drivers include increasing adoption of personalized medicine, expanding insurance coverage for genetic testing, technological advances in sequencing, growing prevalence of genetic disorders, and integration of genomic data into US clinical workflows.
Which applications dominate the US genotyping assay market?
The US market is led by clinical diagnostics, pharmacogenomics, oncology testing, and research applications, with strong demand across hospital systems, diagnostic laboratories, and academic medical centers.
RESEARCH METHODOLOGY
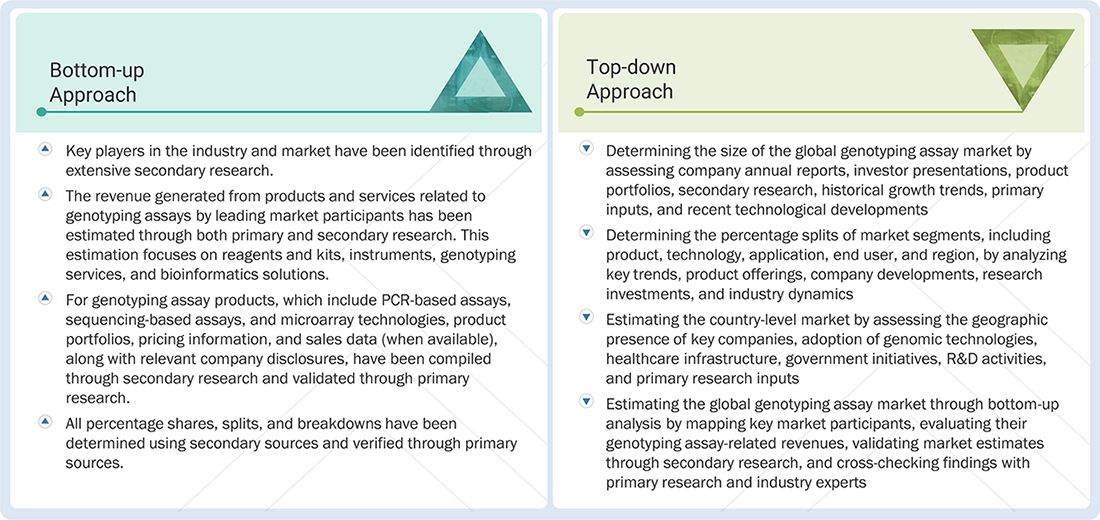
This study involved four major activities to estimate the current size of the genotyping assay market. Exhaustive secondary research was conducted to gather information on the market, its peer markets, and its parent market. These findings, assumptions, and sizing were then validated with industry experts across the value chain through primary research. Both top-down and bottom-up approaches were employed to estimate the total market size. Following this, data triangulation was used to estimate the market size of segments and subsegments.
Secondary Research
Secondary research was primarily used to identify and gather information for the extensive, technical, market-oriented, and commercial study. Secondary sources for this study included publications from government agencies, such as the National Center for Biotechnology Information (NCBI), National Institutes of Health (NIH), World Health Organization (WHO), Food and Drug Administration (FDA), European Medicines Agency (EMA), Pharmaceutical Research and Manufacturers of America (PhRMA), Global Cancer Observatory (GLOBOCAN), Centers for Disease Control and Prevention (CDC), and European Federation of Biotechnology. Secondary sources also included corporate and regulatory filings (such as annual reports, SEC filings, investor presentations, and financial statements); business magazines and research journals; press releases; and trade, business, and professional associations. These sources were used to obtain key information on major players, global product revenues, market classification, segmentation by industry trends and regional/country-level markets, market developments, and technology perspectives. Secondary data were collected and analyzed to determine the overall size of the global genotyping assay market, and the findings were validated through primary research.
Primary Research
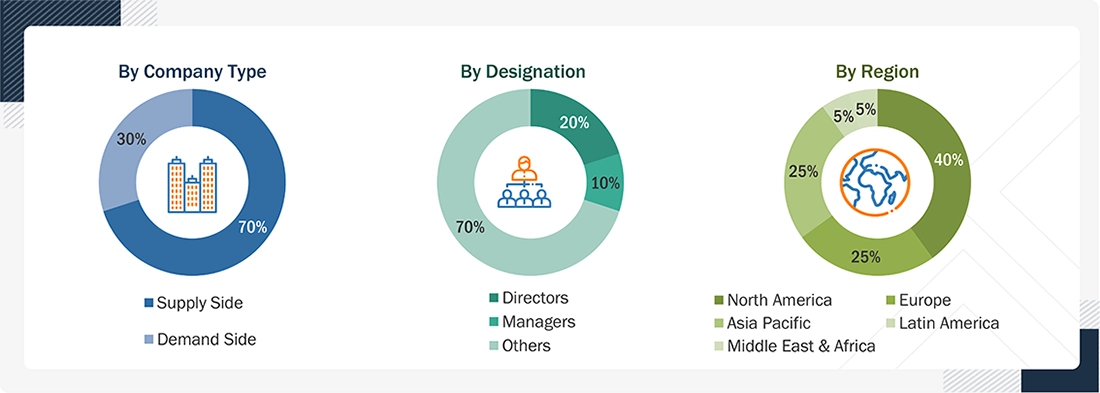
In-depth interviews were conducted with primary respondents, including key industry participants, subject-matter experts (SMEs), C-level executives of key market players, and industry consultants, among others, to obtain and verify critical qualitative and quantitative information and to assess market prospects. Primary sources from both the supply and demand sides of the market were interviewed to gather qualitative and quantitative data. The following is a breakdown of the primary respondents:
To know about the assumptions considered for the study, download the pdf brochure
Market Size Estimation
The global size of the genotyping assay market was estimated using multiple approaches. A detailed market estimation approach was used to estimate and validate the market value and other dependent submarkets. These methods were also used extensively to estimate the size of various subsegments in the market. The research methodology used to estimate the market size includes the following:
Genotyping Assay Market : Top-Down and Bottom-Up Approach
Data Triangulation
After estimating the overall market size through the market size estimation process, the total market was divided into several segments. To complete the overall market engineering process and arrive at the exact statistics for all segments, the data triangulation procedure was employed; it involved analyzing various factors and trends from both the demand and supply sides.
Market Definition
Genotyping assays are laboratory techniques that identify genetic variations in an individual's DNA. These assays detect single-nucleotide polymorphisms (SNPs), insertions, deletions, and other variants using technologies such as polymerase chain reaction (PCR), microarrays, and DNA sequencing. Genotyping assays are widely used in clinical diagnostics, personalized medicine, pharmacogenomics, drug discovery and development, and genetic research. They also have applications in agricultural biotechnology and animal genetics, supporting crop improvement, livestock breeding, and genetic trait identification. Increasing demand for precision medicine, advances in genomic technologies, and the growing use of genetic analysis in biomedical research are driving the adoption of genotyping assays across healthcare, pharmaceutical, biotechnology, and research industries.
Key Stakeholders
- Academic Research Institutes
- Raw Materials Manufacturers & Distributors
- Contract Research Organizations (CROs)
- Manufacturer Service Providers
- Market Research and Consulting Firms
- Pharmaceutical & Biotechnology Companies
- Regulatory Agencies
- Venture Capitalists
- Government organizations
- Private Research Firms
- Contract Development and Manufacturing Organizations (CDMOs)
Report Objectives
- To define, describe, and forecast the genotyping assays market by product & service, technology, application, end user, and region
- To provide detailed information regarding the major factors influencing market growth (such as drivers, restraints, opportunities, and challenges)
- To analyze the micromarkets with respect to individual growth trends, prospects, and contributions to the overall lipid nanoparticles market
- To analyze opportunities for stakeholders and provide details of the competitive landscape for market leaders
- To forecast the size of the market segments with respect to six regions: North America (US and Canada), Europe (Germany, France, the UK, Italy, Spain, and the Rest of Europe), Asia Pacific (China, Japan, India, and Rest of Asia Pacific), Latin America (Brazil, Mexico, and Rest of Latin America), Middle East and Africa
- To profile the key players and analyze their market share and core competencies
- To analyze competitive developments, such as product launches, partnerships, agreements, collaborations, and expansions
- To benchmark players within the market using the proprietary “Company Evaluation Matrix” framework, which analyzes market players on various parameters within the broad categories of business and product excellence strategy
Available customizations:
With the given market data, MarketsandMarkets offers customizations as per the company’s specific needs. The following customization options are available for the report:
Geographical Analysis
- Further breakdown of the Rest of genotyping assay market, by country
- Further breakdown of the Rest of Asia Pacific genotyping assay market, by country
Company Information
- Detailed analysis and profiling of additional market players (up to five)
Segment Analysis
-
Cross-segment analysis
Get the Full Genotyping Assay Market Report
Full forecast, segment splits, and company analysis for all Genotyping Assay Market.
- Canada Genotyping Assay Market
- Germany Genotyping Assay Market
- UK Genotyping Assay Market
- France Genotyping Assay Market
- Italy Genotyping Assay Market
- Spain Genotyping Assay Market
- China Genotyping Assay Market
- Japan Genotyping Assay Market
- India Genotyping Assay Market
- Brazil Genotyping Assay Market
- Mexico Genotyping Assay Market
Need a Tailored Report?
Customize this report to your needs
Get 10% FREE Customization
Customize This Report
