North America Heavy Construction Equipment Market (2025-2030)
The North America Heavy Construction Equipment Market was valued at $65261.8 Million in 2025 and projected to reach to $83265.2 Million by 2030, representing a compound annual growth rate of 5.0%. North America's heavy construction equipment market is positioned for steady growth, expanding from $65.3 billion in 2025 to $83.3 billion by 2030 at a 5% CAGR.

| Market Size in | USD 26.32 MN |
| Market Forecast in | |
| CAGR | |
| Forecast Period | |
| Units Considered | Value (USD MN) |
North America Heavy Construction Equipment Market Trends and Insights
- This steady expansion in North America reflects robust infrastructure investment, urbanization trends, and increased mining activity across the region.
- North America's market benefits from technological advancements in equipment efficiency and the region's strong construction and mining sectors driving demand for modern machinery. The North America heavy construction equipment market is supported by substantial capital expenditure in infrastructure projects, particularly in the United States and Canada.
- North America's forecast period through 2030 anticipates continued growth fueled by government stimulus programs, private sector construction initiatives, and the replacement cycle of aging equipment fleets.
- North America's competitive landscape features both established global manufacturers and regional players adapting to evolving customer demands for sustainability and automation in heavy equipment..
Key Market Statistics
- CAGR (2025-2030) 5.0% CAGR
- Market Size, 2025 ~USD 65261.8 Million
- Forecast, 2030 ~USD 83265.2 Million
- Geography North America
North America Heavy Construction Equipment Market Overview
Strong Infrastructure Investment :
North America's heavy construction equipment market is driven by substantial government infrastructure spending, including highway modernization, bridge rehabilitation, and urban transit projects across the US, Canada, and Mexico.
US Market Dominance :
The United States represents the largest market segment in North America at $62.6 billion, accounting for approximately 96% of the region's total heavy construction equipment demand.
Mining & Resource Extraction Growth :
Increased mining activity in Canada and the US, particularly in lithium, copper, and rare earth minerals, is fueling demand for specialized heavy construction and extraction equipment.
Technological Advancement Adoption :
North American manufacturers are rapidly adopting automation, IoT integration, and telematics in heavy equipment, enhancing operational efficiency and attracting investment from construction and mining operators.
North America Heavy Construction Equipment Market Dynamics
- This growth trajectory is supported by sustained infrastructure modernization initiatives, particularly in the United States, combined with increased capital expenditure in mining operations across Canada.
- The region benefits from technological innovation and digital transformation in equipment manufacturing, enabling operators to improve productivity and reduce operational costs. Key growth drivers include renewable energy infrastructure development, urban renewal projects, and supply chain resilience investments.
- Mexico's emerging construction sector and Canada's resource extraction expansion present additional growth opportunities.
- However, equipment manufacturers must navigate labor shortages, supply chain complexities, and the transition toward sustainable, emission-reducing technologies to maintain competitive advantage in this mature yet dynamic market..
Market Ecosystem

CONSTRUCTION EQUIPMENT MARKET: COMMERCIAL USE CASES ACROSS INDUSTRIES
| COMPANY | USE CASE DESCRIPTION | BENEFITS |
|---|---|---|
 |
Integration of telematics and autonomous haulage systems for real-time fleet monitoring and predictive maintenance | Improves equipment uptime, reduces unplanned downtime, and enhances productivity through data-driven fleet optimization |
 |
Deployment of Smart Construction solutions with IoT-enabled excavators and dozers for automated grading and jobsite visualization | Enables precision earthmoving, reduces rework, and enhances project efficiency with digital site coordination |
 |
Electrified and connected machines with remote diagnostics and energy-efficient operation for urban and quarry applications | Lowers fuel consumption and emissions while improving lifecycle cost and sustainability compliance |
 |
Integration of intelligent control systems and remote operation capabilities in excavators and cranes for high-risk environments | Enhances operator safety, enables remote jobsite control, and improves operational efficiency in complex terrains |
 |
Deployment of electric and autonomous mining equipment integrated with fleet management platforms | Reduces operating costs, supports zero-emission mining operations, and improves large-scale fleet coordination |
Logos and trademarks shown above are the property of their respective owners. Their use here is for informational and illustrative purposes only.
Related Ecosystem
Engine Engine System Exhaust
- Light Commercial Vehicles (LCVs)
- Agricultural Tractors
- Battery Electric Vehicle (BEV)
- Hybrid Electric Vehicle (HEV)
- Sensors
- TENNECO
- GORKOVSKY AVTOMOBILNY ZAVOD
- Titan Company Limited
- AISIN CORPORATION
- TI AUTOMOTIVE
Equipment Machine And Tooling
- Wastewater Treatment
- Air Cooled Heat Exchangers
- Diaphragm Pumps
- Fiberglass
- HVAC System
- Alfa Laval Corporate AB
- Veolia
- Johnson Controls International plc
- Daikin Industries,Ltd.
- Parker-Hannifin Corporation
Infrastructure Material
- Alumina Ceramics
- Ceramic Coatings
- Monolithic Ceramics
- Polyphenylene Sulfide (PPS)
- Titanate Ceramics
- Saint-gobain
- Simpson Manufacturing Co., Inc.
- DOW CHEMICAL COMPANY
- Basf se
- Sika ag
Key Takeaways
- North America's heavy construction equipment market will grow from $65.3B (2025) to $83.3B (2030) at a 5.0% CAGR.
- North America benefits from substantial infrastructure investment and government stimulus programs supporting equipment demand.
- North America's market is driven by urbanization, mining expansion, and the replacement cycle of aging equipment fleets.
- North America's competitive environment emphasizes technological innovation, sustainability, and automation in heavy equipment solutions.
Heavy Construction Equipment Market Report Scope
| Report Metric | Details |
|---|---|
| Base Year | 2025 |
| Fastest Growing Segment | ELECTRIC (Propulsion Type) |
| Forecast Period | 2025–2030 |
| Growth Rate | CAGR of 5% from 2025 to 2030 |
| Largest Segment | DIESEL (Propulsion Type) |
| Market Size Base Year (Billions) | ~USD 224.49 (2025) |
| Revenue Forecast (Billions) | ~USD 286.51 (2030) |
| Segments Covered | Machinery Type, Power Output, Propulsion Type, Engine Capacity, Application, End-Use Industry, Material |
North America Heavy Construction Equipment Market Report Segmentation
7 segment dimensions are covered across the global market.
By Machinery Type
- Cng/Lng/Rng
- Diesel
- Earthmoving Equipment
- Electric
- Heavy Construction Vehicles
- Material Handling Equipment
- Material-Handling Equipment
- Other Heavy Construction Equipment
- Other Machinery Types
By Power Output
- 101–200 Hp
- 201–400 Hp
- <100 Hp
- >400 Hp
By Propulsion Type
- Cng/Lng/Rng
- Diesel
- Electric
By Engine Capacity
- 5–10 L
- 5–1Ol
- <5 L
- <5L
- >10 L
- >10L
By Application
- Excavation & Demolition
- Heavy Lifting
- Material Handling
- Recycling & Waste Management
- Transportation
- Tunneling
By End-Use Industry
- Building & Construction
- Forestry & Agriculture
- Infrastructure
- Mining
- Other End-Use Industries
By Material
- 5–1Ol
- <5L
- >10L
Target Audience
- Equipment Manufacturers & OEMs : Manufacturers need North America-specific market data to optimize production capacity, identify regional demand shifts, and develop products aligned with US, Canadian, and Mexican regulatory standards.
- Construction & Mining Operators : Contractors and mining companies require market insights to forecast equipment costs, evaluate supplier options, and plan capital expenditure across North American operations.
- Private Equity & Investment Firms : Investors evaluating acquisition targets or portfolio companies in heavy equipment need regional market sizing, growth projections, and competitive dynamics to assess investment returns.
- Government & Infrastructure Agencies : Public sector planners and procurement officers use market data to understand equipment availability, pricing trends, and supplier capacity for infrastructure modernization projects.
- Distributors & Dealers : Equipment distributors require country-level demand forecasts and market trends to optimize inventory management, negotiate supplier agreements, and identify expansion opportunities.
Key Companies in the North America Heavy Construction Equipment Market
| Company | HQ | Ownership | Strongest segments |
|---|---|---|---|
| FLSMIDTH | Denmark | Public Company | Service,Products,Pumps, Cyclones & Valves (PC&V), |
| ACTUANT | United States | Public Company | High-force hydraulic tools (cylinders, pumps, valves),Torque and bolt tensioning tools,Heavy lifting technology and engineered systems, |
| ILLINOIS TOOL WORKS INC. | United States | Public Company | Automotive OEM,Food Equipment,Test & Measurement and Electronics, |
| SAMSUNG | South Korea | Public Company | Smartphones, tablets, wearables, and consumer IT,TVs, audio, and visual displays,Home appliances and smart home devices, |
| SNC-LAVALIN GROUP INC. | Canada | Public Company | Consultancy, Strategy, and Advisory,Engineering, Design, and Technical Services,Project and Program Management / Project Delivery, |
| CATERPILLAR | United States | Public Company | Construction Industries equipment and parts,Resource Industries mining equipment and services,Energy & Transportation engines, turbines, and rail, |
| VOLVO GROUP | Sweden | Public Company | Heavy-duty and light-duty trucks,Construction equipment,Buses and coaches, |
| KOMATSU | Japan | Public Company | Construction Machinery and Vehicles,Mining Equipment,Utility, Forestry, and Industrial Machinery, |
| HITACHI CONSTRUCTION MACHINERY CO., LTD. | Japan | Public Company | Hydraulic excavators (all sizes),Wheel loaders and compaction equipment,Rigid dump trucks and mining systems, |
| TEREX CORPORATION | United States | Public Company | Aerials (Genie and Terex-branded MEWPs/telehandlers),Materials Processing (crushers, screens, washing, recycling),Environmental & Utility Solutions (ES segment), |
| LIEBHERR AG | Switzerland | Private Company | Earthmoving & Mining Equipment,Cranes & Material Handling,Concrete Technology & Mixing, |
| SANY GROUP | China | Private Company | Excavators and earthmoving equipment,Concrete machinery,Cranes, port and material handling equipment, |
| HD HYUNDAI | South Korea | Public Company | Shipbuilding & Offshore (incl. engines, plants, renewables EPC),Oil Refining & Petroleum Products,Electrical & Electronics (transformers, switchgear, rotating machines), |
| XCMG GROUP | China | Private Company | Cranes and hoisting machinery,Excavators and earth-moving equipment,Loaders and shovel transportation, |
| CNH INDUSTRIAL N.V. | United Kingdom | Public Company | Agriculture equipment and precision solutions,Construction equipment,Financial Services, |
| WACKER NEUSON SE | Germany | Public Company | Compact Equipment (excavators, loaders, telehandlers, dumpers, backhoe loaders),Light Equipment (compaction, concrete, demolition, lighting, pumps, heaters, generators),Services and Solutions (repair, parts, rental, used, financing, telematics, e-business, digital), |
| SUMITOMO HEAVY INDUSTRIES, LTD. | Japan | Public Company | Mechatronics (gearmotors, gearboxes, motion control, cryogenics),Industrial Machinery (plastics, film forming, semiconductor, medical, defense),Logistics & Construction (excavators, cranes, logistics systems, parking), |
| MANITOU GROUP | France | Public Company | Rough-terrain telehandlers (fixed, rotating, heavy-duty),Access equipment (aerial work platforms, truck-mounted forklifts),Forklift trucks and warehousing equipment, |
| ESCORTS KUBOTA LIMITED | India | Public Company | Agricultural tractors,Farm implements & harvesters,Construction, earthmoving & material handling equipment, |
FLSMIDTH
FLSmidth is a Danish engineering company founded in 1882 with 5,340 employees and operates as a public company. The company specializes in providing equipment and services to the cement, minerals, and metals industries.
ACTUANT
Actuant is a United States public company founded in 1910 with 2,100 employees. The company designs, manufactures, and markets a range of industrial tools and equipment.
ILLINOIS TOOL WORKS INC.
Illinois Tool Works Inc. is a United States public company founded in 1912 with 43,000 employees. The company manufactures a diversified range of products including engineered fasteners, fluids, polymers, and specialty equipment.
SAMSUNG
Samsung is a South Korean public company founded in 1969 with 128,735 employees. The company operates across multiple sectors including electronics, semiconductors, and industrial equipment.
SNC-LAVALIN GROUP INC.
SNC-Lavalin Group Inc. is a Canada-based public company founded in 1911 with 40,246 employees. The company provides engineering, procurement, and construction services across multiple industries.
CATERPILLAR
Caterpillar is a United States public company founded in 1925 with 118,000 employees. The company designs, manufactures, and distributes construction and mining equipment, diesel engines, and related services.
VOLVO GROUP
Volvo Group is a Sweden-based public company founded in 1915 with 89,417 employees. The company manufactures trucks, buses, construction equipment, and engines for commercial and industrial applications.
KOMATSU
Komatsu is a Japan-based public company founded in 1884 with 67,279 employees. The company manufactures construction and mining equipment, industrial machinery, and related products.
HITACHI CONSTRUCTION MACHINERY CO., LTD.
Hitachi Construction Machinery Co., Ltd. is a Japan-based public company founded in 1951 with 25,304 employees. The company designs and manufactures construction and mining equipment including excavators and wheel loaders.
TEREX CORPORATION
Terex Corporation is a United States public company founded in 1933 with 10,700 employees. The company manufactures and distributes a range of equipment for construction, infrastructure, and industrial applications.
LIEBHERR AG
Liebherr AG is a Switzerland-based private company founded in 1949. The company manufactures construction machinery, mining equipment, and related industrial products.
SANY GROUP
Sany Group is a China-based private company founded in 1986 with 20,000 employees. The company manufactures construction machinery and heavy equipment for global markets.
HD HYUNDAI
HD Hyundai is a South Korea-based public company founded in 1972 with 42 employees. Limited information is available regarding the company's specific business operations.
XCMG GROUP
XCMG Group is a China-based private company founded in 1943. The company manufactures construction machinery and heavy equipment.
CNH INDUSTRIAL N.V.
CNH Industrial N.V. is a United Kingdom-based public company founded in 1842 with 34,197 employees. The company manufactures agricultural and construction equipment under multiple brand names.
WACKER NEUSON SE
Wacker Neuson SE is a Germany-based public company founded in 1848 with 5,830 employees. The company manufactures compact construction equipment and light equipment for construction and industrial applications.
SUMITOMO HEAVY INDUSTRIES, LTD.
Sumitomo Heavy Industries, Ltd. is a Japan-based public company founded in 1888 with 25,123 employees. The company manufactures industrial machinery, construction equipment, and provides engineering services.
MANITOU GROUP
Manitou Group is a France-based public company founded in 1954 with 6,028 employees. The company manufactures and distributes material handling and construction equipment.
ESCORTS KUBOTA LIMITED
Escorts Kubota Limited is an India-based public company founded in 1944 with 4,323 employees. The company manufactures tractors, construction equipment, and engines for agricultural and industrial markets.
Countries within North America - compare and drill down
| Country | 2025 size (native) |
|---|---|
| US | USD 62646.1 Million |
| Canada | USD 11808.8 Million |
| Mexico | USD 8810.3 Million |
Country market size visualization
Reasons to Buy this Report
- Market Size & Forecast Precision : Access detailed market valuations for North America ($65.3B in 2025) with country-level breakdowns for the US, Canada, and Mexico, enabling accurate budget allocation and investment planning.
- Regional Growth Drivers Analysis : Understand infrastructure spending patterns, mining expansion, and urbanization trends specific to North America that differentiate this region from global markets.
- Competitive Landscape Intelligence : Identify leading equipment manufacturers, market consolidation trends, and technology adoption rates across North American markets to benchmark competitive positioning.
- Country-Level Market Segmentation : Leverage granular data for the US ($62.6B), Canada ($11.8B), and Mexico ($8.8B) to develop targeted go-to-market strategies and localized business plans.
- Strategic Investment Opportunities : Discover high-growth segments within North America including renewable energy infrastructure, mining equipment, and automation technologies driving equipment modernization.
Frequently asked questions
What is the current size of North America's heavy construction equipment market?
North America's heavy construction equipment market is estimated at $65,261.8 million in 2025.
What is the projected market size for North America by 2030?
North America's heavy construction equipment market is forecasted to reach $83,265.2 million by 2030.
What is the CAGR for North America's heavy construction equipment market?
North America's heavy construction equipment market is expected to grow at a compound annual growth rate of 5.0% from 2025 to 2030.
What factors are driving growth in North America's heavy construction equipment market?
North America's market growth is driven by infrastructure investment, urbanization, mining activity expansion, government stimulus programs, and equipment fleet replacement cycles.
Which countries contribute most to North America's heavy construction equipment market?
The United States and Canada are the primary contributors to North America's heavy construction equipment market, supported by substantial capital expenditure in infrastructure and construction projects.
RESEARCH METHODOLOGY
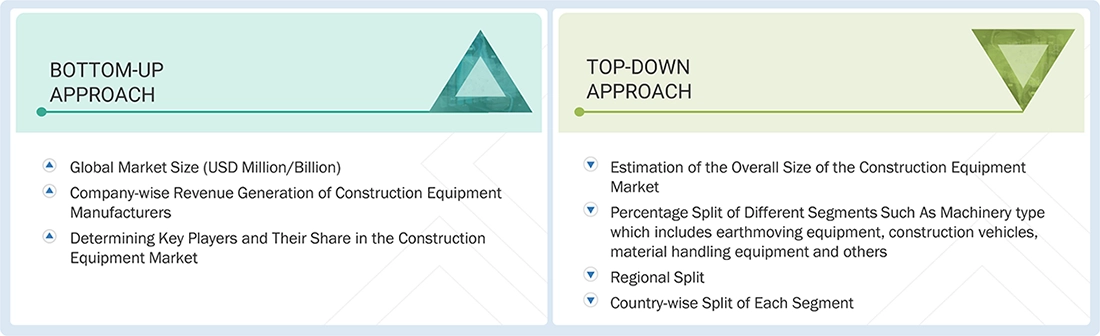
The study involves two major activities in estimating the current market size for the Construction equipment market. Exhaustive secondary research was done to collect information on the market, peer market, and parent market. The next step was to validate these findings, assumptions, and sizing with industry experts across the value chain through primary research. Both top-down and bottom-up approaches were employed to estimate the complete market size. After that, market breakdown and data triangulation were used to estimate the market size of segments and subsegments.
Secondary Research
Secondary sources referred to for this research study include financial statements of companies offering Construction equipment and information from various trade, business, and professional associations. Secondary research has been used to obtain critical information about the industry’s value chain, the total pool of key players, market classification, and segmentation according to industry trends to the bottom-most level and regional markets. The secondary data was collected and analyzed to arrive at the overall size of the Construction equipment market, which was validated by primary respondents.
Primary Research
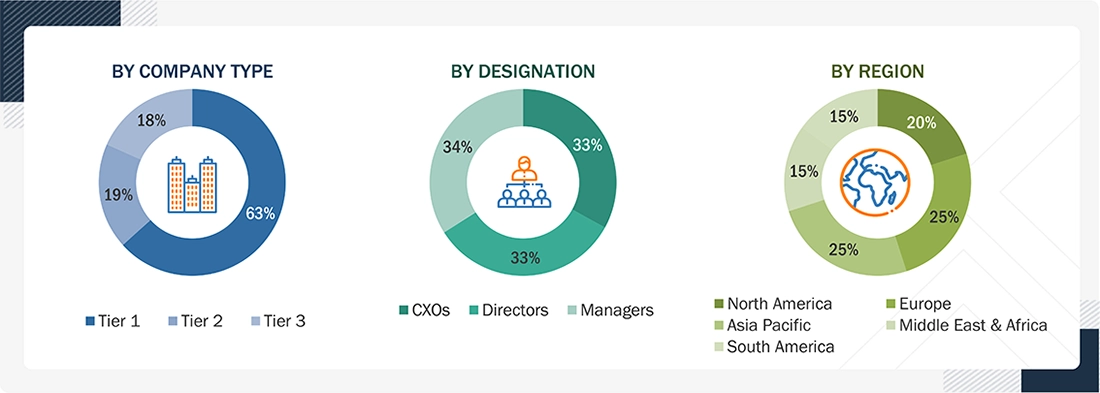
Extensive primary research was conducted after obtaining information regarding the Construction equipment market scenario through secondary research. Several primary interviews were conducted with market experts from both the demand and supply sides across major countries of North America, Europe, Asia Pacific, Middle East & Africa, and South America. Primary data was collected through questionnaires, emails, and telephonic interviews. The primary sources from the supply side included various industry experts, such as Chief X Officers (CXOs), Vice Presidents (VPs), Directors from business development, marketing, product development/innovation teams, and related key executives from Construction equipment industry vendors; system integrators; component providers; distributors; and key opinion leaders. Primary interviews were conducted to gather insights such as market statistics, data on revenue collected from the products and services, market breakdowns, market size estimations, market forecasting, and data triangulation. Primary research also helped in understanding the various trends related to resin type, fiber type, application, end-use industry, and region. Stakeholders from the demand side, such as CIOs, CTOs, CSOs, and installation teams of the customer/end users who are seeking Construction equipment services, were interviewed to understand the buyer’s perspective on the suppliers, products, component providers, and their current usage of Construction equipment and future outlook of their business which will affect the overall market.
To know about the assumptions considered for the study, download the pdf brochure
Market Size Estimation
The research methodology used to estimate the size of the Construction equipment market includes the following details. The market sizing of the market was undertaken from the demand side. The market was upsized based on the demand for Construction equipment in different applications at a regional level. Such procurements provide information on the demand aspects of the Construction equipment industry for each application. For each application, all possible segments of the Construction equipment market were integrated and mapped.
Data Triangulation
After arriving at the overall size from the market size estimation process explained above, the total market was split into several segments and subsegments. The data triangulation and market breakdown procedures explained below were implemented, wherever applicable, to complete the overall market engineering process and arrive at the exact statistics for various market segments and subsegments. The data was triangulated by studying various factors and trends from the demand and supply sides. Along with this, the market size was validated using both the top-down and bottom-up approaches.
Market Definition
Construction equipment is specialized machinery that weighs more than 12 metric tons and is utilized for certain construction or demolition jobs. The temporary, semi-permanent, or permanent equipment is primarily used for earthmoving, lifting containers or items, drilling holes in rock or dirt, and concrete and paving applications.
Key Stakeholders
- Equipment Manufacturers
- Distributors and Service Providers
- Universities, Governments, and Research Organizations
- Associations and Industrial Bodies
- R&D Institutes
- Investment Banks and Private Equity Firms
- Research and Consulting Firms
Report Objectives
- To define and segment the Construction equipment market based on machinery type, application, propulsion type, power output, engine capacity, end-use industry, and region
- To provide detailed information regarding the key factors, such as drivers, restraints, opportunities, and challenges influencing market growth
- To analyze market segments and forecast the market sizes based on machinery type, application, propulsion type, power output, engine capacity, end-use industry, and region
- To forecast the market size concerning five main regions (along with country-level data), namely, North America, Europe, Asia Pacific, Middle East & Africa, and South America, and analyze the significant region-specific trends
- To strategically analyze micromarkets with respect to individual growth trends, prospects, and contributions of the submarkets to the overall market
- To analyze the market opportunities and the competitive landscape for stakeholders and market leaders
- To assess recent market developments and competitive strategies, such as agreements, contracts, acquisitions, and new product developments/new product launches, to draw the competitive landscape
- To strategically profile the key market players and comprehensively analyze their core competencies
Available customizations:
MarketsandMarkets offers following customizations for this market report:
- Additional country-level analysis of the Construction equipment market
Product Analysis
- Product matrix, which provides a detailed comparison of the product portfolio of each company's market
Get the Full Heavy Construction Equipment Market Report
Full forecast, segment splits, and company analysis for all Heavy Construction Equipment Market.
- China Heavy Construction Equipment Market
- India Heavy Construction Equipment Market
- Japan Heavy Construction Equipment Market
- Australia Heavy Construction Equipment Market
- Germany Heavy Construction Equipment Market
- France Heavy Construction Equipment Market
- UK Heavy Construction Equipment Market
- Russia Heavy Construction Equipment Market
- Canada Heavy Construction Equipment Market
- US Heavy Construction Equipment Market
- Mexico Heavy Construction Equipment Market
- Brazil Heavy Construction Equipment Market
- Argentina Heavy Construction Equipment Market
- Chile Heavy Construction Equipment Market
- Peru Heavy Construction Equipment Market
- South Africa Heavy Construction Equipment Market
- Rest Of Europe Heavy Construction Equipment Market
- Rest Of Asia Pacific Heavy Construction Equipment Market
Need a Tailored Report?
Customize this report to your needs
Get 10% FREE Customization
Customize This Report