India Medical Image Analysis Software Market (2022-2027)
The India Medical Image Analysis Software Market was valued at $169.66 Million in 2022 and projected to reach to $271.84 Million by 2027, representing a compound annual growth rate of CAGR 9.9%. India's medical image analysis software market is poised for accelerated growth as healthcare institutions prioritize digital transformation and AI integration.

| Market Size in | USD 26.32 MN |
| Market Forecast in | |
| CAGR | |
| Forecast Period | |
| Units Considered | Value (USD MN) |
India Medical Image Analysis Software Market Trends and Insights
- This expansion reflects India's increasing adoption of AI-driven diagnostic tools and digital healthcare infrastructure modernization.
- India's healthcare sector is leveraging advanced imaging analytics to improve diagnostic accuracy and operational efficiency across hospitals and diagnostic centers. The 9.9% compound annual growth rate (CAGR) positions India as a high-growth market within the Asia Pacific region.
- India's growing patient population, rising healthcare expenditure, and government initiatives supporting digital health adoption are key catalysts driving demand for medical image analysis solutions.
- India's competitive advantage in software development and IT services further accelerates the localization and deployment of these technologies across the country's healthcare ecosystem..
Key Market Statistics
- CAGR (2022-2027) CAGR 9.9%
- Market Size, 2022 ~USD 169.66 Million
- Forecast, 2027 ~USD 271.84 Million
- Country India
India Medical Image Analysis Software Market Overview
Strong CAGR Growth :
India's medical image analysis software market is growing at 9.9% CAGR, outpacing the global rate of 7.8%, driven by rapid digital healthcare adoption and government initiatives like National Digital Health Mission.
Market Valuation Expansion :
The market is projected to grow from USD 169.66 million in 2022 to USD 271.84 million by 2027, representing a 60% increase over five years, reflecting strong investor confidence in India's healthcare digitalization.
AI-Driven Diagnostic Adoption :
Indian healthcare providers are increasingly implementing AI-powered imaging analytics to enhance diagnostic accuracy, reduce radiologist workload, and improve patient outcomes across urban and emerging tier-2 cities.
Infrastructure Modernization :
India's healthcare infrastructure is undergoing significant digital transformation with increased investments in cloud-based imaging solutions, telemedicine platforms, and integrated diagnostic centers supporting software adoption.
India Medical Image Analysis Software Market Dynamics
- The government's push toward universal digital health records and the rising prevalence of chronic diseases are driving demand for advanced diagnostic solutions.
- Private hospitals and diagnostic chains are leading adoption, while public healthcare systems are gradually integrating these technologies to improve accessibility and efficiency. The market will benefit from increasing smartphone penetration, growing medical tourism, and rising healthcare expenditure among India's expanding middle class.
- Partnerships between domestic software developers and international vendors are creating localized solutions tailored to India's unique healthcare challenges.
- By 2027, medical image analysis software will become integral to India's healthcare delivery ecosystem, supporting better clinical decision-making and operational efficiency across the country..
Market Ecosystem
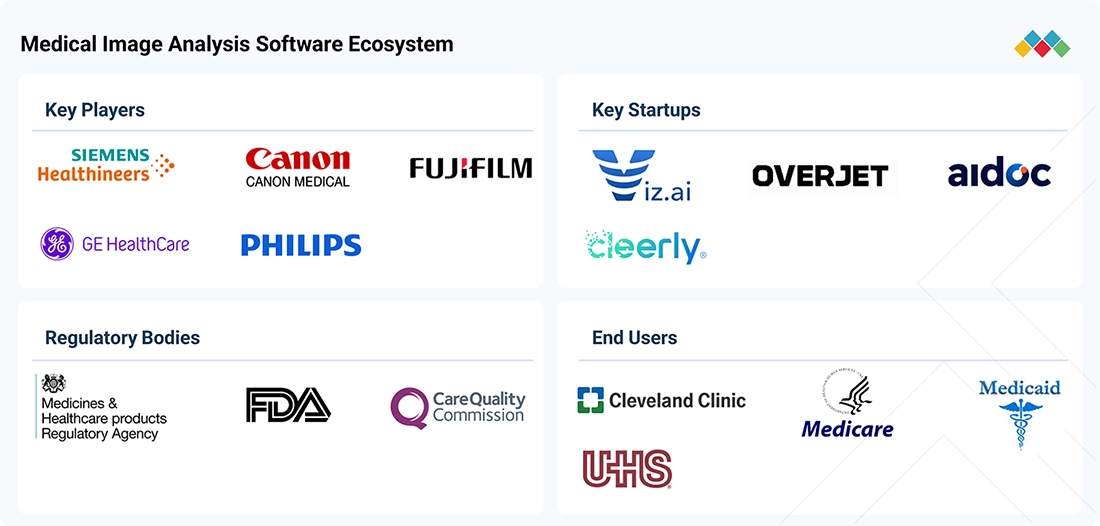
MEDICAL IMAGE ANALYSIS SOFTWARE MARKET: COMMERCIAL USE CASES ACROSS INDUSTRIES
| COMPANY | USE CASE DESCRIPTION | BENEFITS |
|---|---|---|
 |
Provides an AI-enabled radiology services suite covering scheduling, image acquisition, and automated reporting | Reduces reporting time and improves consistency of image interpretation |
 |
Combines its AI imaging portfolio with Intelerad's cloud and AI orchestration capabilities to deliver connected imaging software across care settings | Expands cloud-enabled imaging access and improves radiology workflow efficiency |
 |
Offers Philips Verida, the world's first detector-based Spectral CT fully powered by AI, and Philips Vue PACS, a web-based diagnostic viewer | Improves diagnostic image quality and enables remote study access without dedicated software |
 |
Provides Precise IQ Engine, an AI deep learning reconstruction technology under its Altivity AI brand for high-resolution CT imaging | Improves image resolution at lower radiation dose and standardizes imaging protocols |
 |
Offers REiLI, a vendor-neutral AI platform integrated into Synapse PACS that hosts both Fujifilm and third-party AI algorithms | Lets hospitals run multiple vendors' AI tools on one platform, speeding up reporting |
Logos and trademarks shown above are the property of their respective owners. Their use here is for informational and illustrative purposes only.
Related Ecosystem
Healthcare Analytics
- Machine Learning
- Natural Language Processing (NLP)
- Blood Pressure Monitors
- Computed Tomography (CT)
- Magnetic Resonance Imaging (MRI)
- Oracle Corporation
- PHILIPS HEALTHCARE
- Siemens healthineers
- Zensar Technologies Limited
- EPIC SYSTEMS CORPORATION
Healthcare It
- Computed Tomography (CT)
- Machine Learning
- Magnetic Resonance Imaging (MRI)
- Natural Language Processing (NLP)
- Predictive Analytics
- CERNER CORPORATION
- PHILIPS HEALTHCARE
- Oracle Corporation
- GE HealthCare Technologies Inc.
- Siemens healthineers
Medical Devices
- Polymerase Chain Reaction (PCR)
- Magnetic Resonance Imaging (MRI)
- Disposable Autoinjectors
- Pulse Oximeters
- Blood Pressure Monitors
- Medtronic plc
- Abbott Laboratories
- Stryker Corporation
- Becton, Dickinson and Company
- CONMED Corporation
Key Takeaways
- India's medical image analysis software market is valued at USD 169.66 million in 2022 and will reach USD 271.84 million by 2027, representing a 9.9% CAGR.
- India's large patient population and rising healthcare spending are driving adoption of AI-powered diagnostic imaging solutions across hospitals and clinics.
- India's strong IT and software development capabilities enable rapid localization and cost-effective deployment of medical imaging technologies.
- Government digital health initiatives and telemedicine expansion in India are accelerating demand for remote image analysis and cloud-based diagnostic platforms.
Medical Image Analysis Software Market Report Scope
| Report Metric | Details |
|---|---|
| Base Year | 2022 |
| Fastest Growing Segment | RADIOGRAPHIC IMAGING (Modality) |
| Forecast Period | 2022-2027 |
| Growth Rate | CAGR of 7.8% from 2022 to 2027 |
| Largest Segment | HOSPITALS (End User) |
| Market Size Base Year (Billions) | ~USD 3.09 (2022) |
| Revenue Forecast (Billions) | ~USD 4.5 (2027) |
| Segments Covered | Type, Image Type, Modality, Application, End User |
India Medical Image Analysis Software Market Report Segmentation
5 segment dimensions are covered across the global market.
By Type
- 2D Ultrasound Systems
- 3D And 4D Ultrasound Systems
- Closed Mri Systems
- Computed Tomography
- Doppler Imaging
- High-End Slice Ct
- Integrated Software
- Low-End Slice Ct
- Magnetic Resonance Imaging
- Mid-End Slice Ct
- Open Mri Systems
- Pet/Ct
- Pet/Mr
- Positron Emission Tomography
- Single-Photon Emission Computed Tomography
- Spect/Ct
- Standalone Software
By Image Type
- 2D Imaging
- 3D Imaging
- 4D Imaging
By Modality
- Combined Modalities
- Mammography
- Radiographic Imaging
- Tomography
- Ultrasound Imaging
By Application
- Cardiology
- Dental
- Mammography
- Neurology
- Obstetrics And Gynecology
- Oncology
- Orthopedics
- Respiratory
- Urology And Nephrology
- Vascular
By End User
- Diagnostic Imaging Centers
- Hospitals
- Other End Users
Target Audience
- Healthcare Technology Vendors : Software companies and medical device manufacturers need India market insights to develop localized solutions, identify distribution channels, and understand pricing strategies for competitive positioning.
- Hospital & Diagnostic Chains : Healthcare providers require market data to evaluate technology investments, benchmark against peers, and make procurement decisions for medical image analysis platforms and AI diagnostic tools.
- Private Equity & Investors : Investment firms and venture capitalists need comprehensive market analysis to identify high-potential startups, assess market growth trajectories, and evaluate acquisition opportunities in India's healthcare tech space.
- Government & Policy Makers : Healthcare administrators and policy officials require market intelligence to design digital health initiatives, allocate budgets for infrastructure modernization, and support healthcare digitalization programs.
- Consulting & Research Firms : Strategy consultants and research organizations need detailed market data to support client advisory services, competitive analysis, and strategic recommendations for healthcare technology implementations in India.
Reasons to Buy this Report
- Market Entry Strategy : Understand India's unique market dynamics, regulatory landscape, and competitive positioning to develop effective market entry strategies and localization approaches for medical imaging software solutions.
- Investment Decision Support : Access comprehensive data on market size, growth projections, and regional opportunities to make informed investment decisions in India's high-growth healthcare technology sector.
- Competitive Intelligence : Identify key players, emerging startups, and partnership opportunities in India's medical image analysis market to benchmark performance and develop competitive differentiation strategies.
- Revenue Forecasting : Leverage detailed market projections and segment analysis to forecast revenue potential, identify high-growth niches, and allocate resources effectively across India's healthcare regions.
- Strategic Planning : Develop informed go-to-market strategies, product roadmaps, and partnership frameworks based on India-specific market trends, customer needs, and adoption patterns in medical imaging technology.
Frequently asked questions
What is the current size of India's medical image analysis software market?
India's medical image analysis software market was valued at USD 169.66 million in 2022 and is expected to grow to USD 271.84 million by 2027.
What is the projected growth rate for India's medical image analysis software market?
India's medical image analysis software market is projected to grow at a compound annual growth rate (CAGR) of 9.9% from 2022 to 2027.
What factors are driving growth in India's medical image analysis software market?
Key growth drivers in India include increasing healthcare digitalization, rising patient volumes, government digital health initiatives, telemedicine expansion, and India's strong software development capabilities.
Which healthcare segments in India are adopting medical image analysis software?
India's hospitals, diagnostic imaging centers, radiology departments, and specialty clinics are increasingly adopting medical image analysis software to improve diagnostic accuracy and operational efficiency.
How does India's market compare to the global medical image analysis software market?
India's 9.9% CAGR outpaces the global market CAGR of 7.8%, positioning India as a high-growth market within the Asia Pacific region and globally.
RESEARCH METHODOLOGY
The study involved five major activities to estimate the current size of the medical image analysis software market. Exhaustive secondary research was done to collect information on the market and its different subsegments. The next step was to validate these findings, assumptions, and sizing with industry experts across the value chain through primary research. Both top-down and bottom-up approaches were employed to estimate the complete market size. Thereafter, market breakdown and data triangulation procedures were used to estimate the market size of the segments and subsegments.
Secondary Research
In the secondary research process, various secondary sources such as annual reports, press releases & investor presentations of companies, white papers, certified publications, articles by recognized authors, gold-standard & silver-standard websites, regulatory bodies, and databases (such as D&B Hoovers, Bloomberg Business, and Factiva) were referred to identify and collect information for the study of the medical image analysis software market. It was also used to obtain important information about the top players, market classification, and segmentation according to industry trends to the bottom-most level, geographic markets, and key developments related to the market. A database of the key industry leaders was also prepared using secondary research.
Primary Research
Extensive primary research was conducted after acquiring basic knowledge about the global medical image analysis software market scenario through secondary research. Several primary interviews were conducted with market experts from both the demand side (hospital directors, hospital vice presidents, department heads, and critical care specialists) and supply side (such as C-level and D-level executives, technology experts, product managers, marketing and sales managers, among others) across five major regions: North America, Europe, the Asia Pacific, Latin America, and the Middle East & Africa. This primary data was collected through questionnaires, e-mails, online surveys, personal interviews, and telephonic interviews.
Breakdown of Primary Interviews
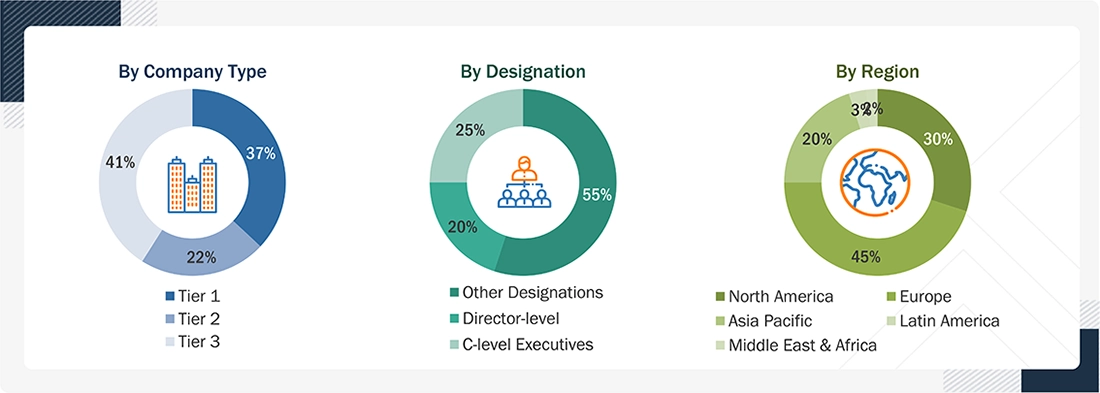
Note 1: Others include sales managers, marketing managers, and product managers.
Note 2: Tiers of companies are defined on the basis of their total revenues in 2025. Tier 1 = >USD 1 billion, Tier 2 = USD 500 million to USD 1 billion, and Tier 3 = <USD 500 million.
To know about the assumptions considered for the study, download the pdf brochure
Market Size Estimation
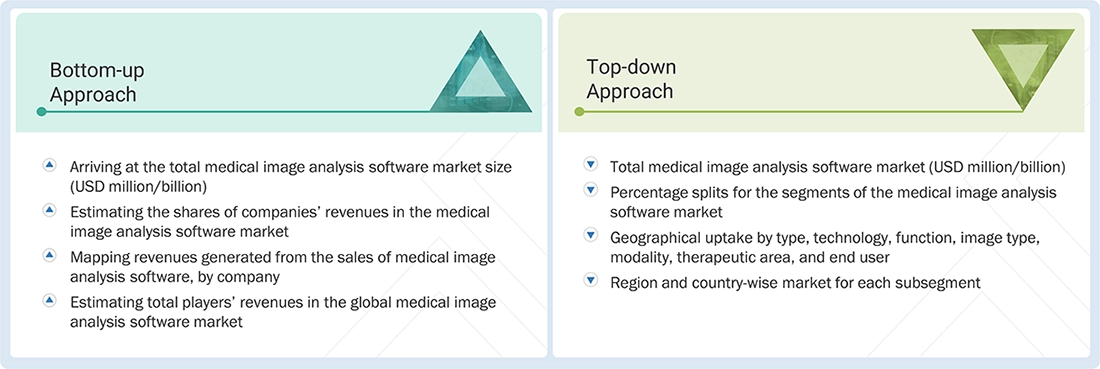
Both top-down and bottom-up approaches were used to estimate and validate the total size of the medical image analysis software market. These methods were also used extensively to estimate the size of various subsegments in the market.
Top-Down and Bottom-Up Approach
Data Triangulation
After arriving at the overall market size using the market size estimation processes, the market was split into several segments and subsegments. To complete the overall market engineering process and arrive at the exact statistics of each market segment and subsegment, data triangulation and market breakdown procedures were employed, wherever applicable. The data was triangulated by studying various factors and trends from both the demand and supply sides in the medical image analysis software market.
Market Definition
Medical image analysis software refers to computer-based tools that help clinicians detect, measure, and interpret findings from medical images such as CT, MRI, ultrasound, and X-ray scans. This software aims to reduce radiologists' manual workload while improving diagnostic accuracy and speed. By automating tasks such as abnormality detection and image reporting, hospitals and diagnostic centers can help radiologists focus on complex clinical decisions rather than routine image review.
Key Stakeholders
- Medical imaging equipment manufacturers
- AI software vendors/developers
- Hospitals and diagnostic imaging centers
- Radiologists and healthcare providers
- Academic and research institutions
- Regulatory bodies (e.g., FDA, EMA)
- Healthcare IT/PACS-RIS integration partners
- Cloud service providers
- Venture capitalists and private equity investors
- Business research and consulting service providers
Report Objectives
- To define, describe, and forecast the global medical image analysis software market based on type, technology, function, image type, modality, therapeutic area, end user, and region
- To provide detailed information regarding the major factors (such as drivers, restraints, opportunities, and challenges) influencing market growth
- To strategically analyze micro-markets with respect to individual growth trends, prospects, and contributions to the overall medical image analysis software market
- To analyze opportunities in the market for stakeholders and provide details of the competitive landscape for market leaders
- To strategically analyze the market structure profile of the key players of the medical image analysis software market and comprehensively analyze their core competencies
- To forecast the size of the market segments with respect to five regions: North America, Europe, Asia Pacific, Latin America, and the Middle East & Africa
- To track and analyze competitive developments such as product launches, investments, partnerships, collaborations, acquisitions, expansions, product approvals, and alliances in the medical image analysis software market during the forecast period
Available customizations:
With the given market data, MarketsandMarkets offers customizations as per the company’s specific needs.
The following customization options are available for the report:
- Product Analysis: Product matrix, which gives a detailed comparison of the product portfolios of each company.
- Geographic Analysis: Further breakdown of Latin America, Europe, and the Middle East & Africa medical image analysis software into specific countries.
Get the Full Medical Image Analysis Software Market Report
Full forecast, segment splits, and company analysis for all Medical Image Analysis Software Market.
- Canada Medical Image Analysis Software Market
- US Medical Image Analysis Software Market
- France Medical Image Analysis Software Market
- Germany Medical Image Analysis Software Market
- Italy Medical Image Analysis Software Market
- Spain Medical Image Analysis Software Market
- UK Medical Image Analysis Software Market
- China Medical Image Analysis Software Market
- Japan Medical Image Analysis Software Market
- Brazil Medical Image Analysis Software Market
- Mexico Medical Image Analysis Software Market
- Roe Medical Image Analysis Software Market
- Roapac Medical Image Analysis Software Market
Need a Tailored Report?
Customize this report to your needs
Get 10% FREE Customization
Customize This Report