Japan Medical Polymer Market (2025-2030)

The Japan Medical Polymer Market was valued at $2882.5 Million in 2025 and projected to reach to $3982.7 Million by 2030, representing a compound annual growth rate of 6.7%. Japan's medical polymer market is poised for steady growth through 2030, driven by the nation's aging population and advanced healthcare infrastructure.


| Market Size in | USD 26.32 MN |
| Market Forecast in | |
| CAGR | |
| Forecast Period | |
| Units Considered | Value (USD MN) |
Japan Medical Polymer Market Trends and Insights
- Japan's advanced healthcare infrastructure and aging population drive sustained demand for high-performance medical polymers used in diagnostic devices, surgical instruments, and implantable components.
- Japan's commitment to innovation in medical technology and stringent regulatory standards position the country as a key market within the Asia Pacific region. The growth trajectory in Japan reflects increasing adoption of minimally invasive procedures and rising healthcare expenditure.
- Japan's medical polymer market benefits from strong domestic manufacturing capabilities and partnerships with global medical device companies.
- Between 2025 and 2030, Japan is expected to maintain steady expansion driven by demographic shifts, technological advancement, and growing prevalence of chronic diseases requiring polymer-based medical solutions..
Key Market Statistics
- CAGR (2025-2030) 6.7% CAGR
- Market Size, 2025 ~USD 2882.5 Million
- Forecast, 2030 ~USD 3982.7 Million
- Country Japan
Japan Medical Polymer Market Overview
Aging Population Driving Demand :
Japan's rapidly aging demographic, with over 29% of the population aged 65+, creates sustained demand for medical polymers in diagnostic devices, surgical instruments, and implantable components tailored to geriatric healthcare needs.
Advanced Healthcare Infrastructure :
Japan's world-class healthcare system and high medical device adoption rates support premium medical polymer applications, positioning the country as a leader in innovative polymer-based medical solutions.
Strong Market Growth Trajectory :
With a CAGR of 6.7% from 2025 to 2030, Japan's medical polymer market is expanding from USD 2,882.5 million to USD 3,982.7 million, outpacing many developed markets despite slower global growth.
Domestic Manufacturing Excellence :
Japan's established polymer and medical device manufacturing sector, combined with stringent quality standards and regulatory expertise, positions local producers as key suppliers for both domestic and regional markets.
Japan Medical Polymer Market Dynamics
- The market's 6.7% CAGR reflects strong demand for high-performance polymers in diagnostic devices, surgical instruments, and implantable components.
- Japan's commitment to healthcare innovation and regulatory excellence ensures continued adoption of premium medical polymer solutions. The market will benefit from increasing investments in minimally invasive surgical technologies and personalized medicine.
- Domestic manufacturers' expertise in polymer processing and quality control positions Japan as a regional hub for medical polymer innovation.
- Strategic partnerships between material suppliers and medical device manufacturers will accelerate product development and market penetration across Asia-Pacific..
Market Ecosystem
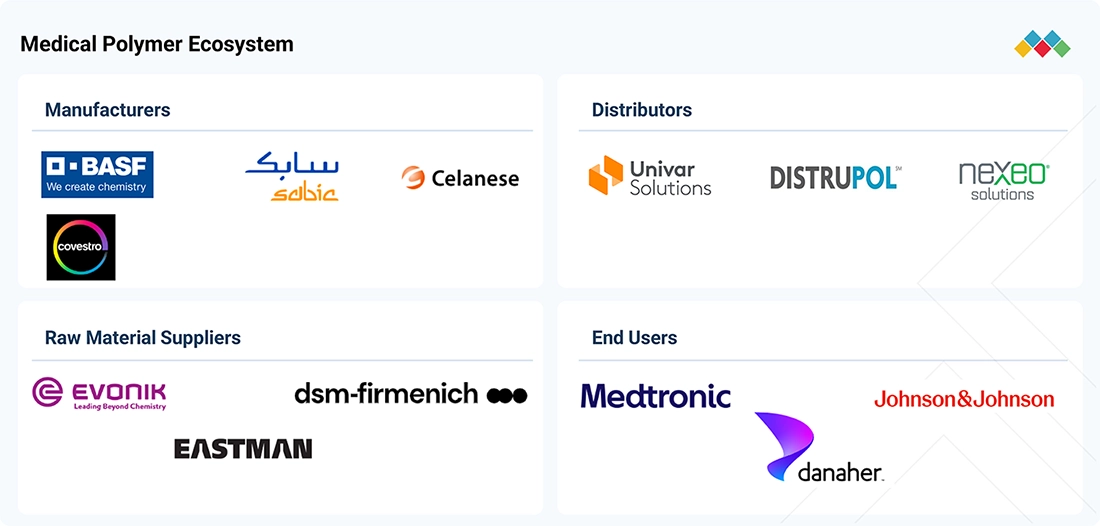
MEDICAL POLYMER MARKET: COMMERCIAL USE CASES ACROSS INDUSTRIES
| COMPANY | USE CASE DESCRIPTION | BENEFITS |
|---|---|---|
 |
BASF supplies Ultrason polyarylsulfone (PSU, PPSU, PESU) grades for healthcare applications, including respiratory devices, fluid collection containers, sterilization trays, diagnostic equipment, and orthopedic sizing components. It also offers custom-colored, USP Class V/VI and ISO 10993-compliant Ultrason grades, developed with partner Techmer PM, to remove the in-house color-blending step for device makers. | High-temperature resistance | Repeated steam/EtO sterilization tolerance | Custom-colorable, biocompatible grades reduce development cycles | Transparency retained after repeated sterilization | Chemical resistance exceeding polyamide/PC/POM/PBT |
 |
SABIC's LNP portfolio (ELCRES/ELCRIN CRX copolymers, EXL copolymers, LUBRILOY, SLX, ULTEM HU, SILTEM HU) serves device housings, insulin pumps, diagnostic imaging equipment, drug-delivery autoinjectors, surgical robot components, and medical tubing. The company backs this with a Healthcare Product Policy, management-of-change processes, and Centers of Excellence for OEM co-development. | High chemical resistance to aggressive disinfectants | Thin-wall, miniaturized device design enablement | Non-PFAS/non-fluorine compliant options | Biocompatible per ISO 10993 | Reduced carbon footprint on bio-based grades |
 |
Covestro provides Makrolon and Makroblend polycarbonate resins, Baymedix polyurethane adhesives/foams, Platilon TPU films, and Texin Rx TPU resins for drug-delivery devices, IV/luer components, on-body devices, wound care, and surgical instruments. It supports customers with design and material-selection guidance through final regulatory approval. | Biocompatibility per ISO 10993-1/USP Class IV | Gamma/e-Beam/ETO sterilization compatibility | High-flow grades for thin-wall, intricate designs | Chemical and oncology-drug resistance to prevent cracking | Renewable-content grades lower carbon footprint |
 |
Celanese supplies Hostaform/Celcon POM, Zytel nylon, GUR UHMW-PE, VitalDose EVA, and Vectra LCP for drug-delivery devices (inhalers, insulin pens, auto-injectors), orthopedic implants (hips/knees), and ventilator/respirator components. Its Hostaform MT SlideX grade is formulated specifically for low-friction mechanical drug-delivery devices. | Low friction/wear for patient comfort in wearables | Gold-standard biocompatibility for load-bearing implants | Vitamin E-stabilized grades resist implant oxidation | High impact and dimensional stability | Expanded portfolio via 2022 DuPont M&M acquisition |
Logos and trademarks shown above are the property of their respective owners. Their use here is for informational and illustrative purposes only.
Related Ecosystem
Resins And Polymers
- Polycarbonate
- Acrylonitrile Butadiene Styrene (ABS)
- Epoxy Resin
- Light Commercial Vehicles (LCVs)
- Polypropylene (PP)
- Basf se
- DOW CHEMICAL COMPANY
- Solvay sa
- Saudi arabia basic industries corporation (sabic)
- DuPont de Nemours, Inc.
Packaging
- Ampoules
- Gravure Process
- Rigid Packaging
- Aerosols
- Aseptic Filling and Sealing Equipment
- Amcor plc
- Essentra plc
- Berry Global Group, Inc.
- Mondi plc
- SEALED AIR CORPORATION
Key Takeaways
- Japan's medical polymer market is valued at USD 2,882.5 million in 2025 and will reach USD 3,982.7 million by 2030 at a 6.7% CAGR.
- Japan's aging population and advanced healthcare infrastructure create strong demand for medical polymers in implants and diagnostic devices.
- Japan's stringent regulatory environment and manufacturing excellence support premium positioning in the Asia Pacific medical polymer sector.
- Japan's market growth is driven by minimally invasive procedure adoption and chronic disease management innovations through 2030.
Medical Polymer Market Report Scope
| Report Metric | Details |
|---|---|
| Base Year | 2025 |
| Fastest Growing Segment | -PP (Type) |
| Forecast Period | 2025-2030 |
| Growth Rate | CAGR of 8.2% from 2025 to 2030 |
| Largest Segment | MEDICAL PLASTICS (Type) |
| Market Size Base Year (Billions) | ~USD 44.7 (2025) |
| Revenue Forecast (Billions) | ~USD 66.29 (2030) |
| Segments Covered | Type, Manufacturing Technology, Application |
Japan Medical Polymer Market Report Segmentation
3 segment dimensions are covered across the global market.
By Type
- Medical Elastomers
- Medical Plastics
- -Engineering & High-Performance Plastics
- -Other Medical Elastomers
- -Other Medical Plastics
- -Pe
- -Pp
- -Ps
- -Pvc
- -Silicone
- -Thermoplastic Elastomers
- --Abs
- --Other Engineering & High-Performance Plastics
- --Pa
- --Pc
- --Peek
- --Pmma
- --Ppsu
- --Psu
- --Tpc-Et
- --Tps
- --Tpu
- --Tpv
- ---Sbc, Tpo, & Other Tps
- ---Sbs
- ---Sebs
By Manufacturing Technology
- Compression Molding
- Extrusion Tubing
- Injection Molding
- Other Manufacturing Technologies
By Application
- Diagnostic Instruments & Tools
- Medical Disposables
- Medical Instruments & Devices
- Other Applications
- Prosthetics
- -Catheters
- -Dental Tools
- -Drug Delivery
- -Drug Delivery Instruments
- -Gloves
- -Implants
- -Limb Prosthetics
- -Medical Bags
- -Medical Tube
- -Medical Tubes
- -Other Diagnostic Instruments & Tools
- -Other Medical Disposables
- -Other Medical Instruments & Devices
- -Other Prosthetics
- -Surgical Instruments
- -Syringes
JAPAN: MEDICAL POLYMER MARKET, BY APPLICATION, 2025–2030
| Segment | 2025 | 2026 | 2027 | 2028 | 2029 | 2030 | CAGR (%) |
|---|---|---|---|---|---|---|---|
| DIAGNOSTIC INSTRUMENTS & TOOLS | 320.6 | 338 | 356.4 | 374.9 | 394.4 | 418.6 | 5.5 |
| MEDICAL DISPOSABLES | 876.8 | 939.2 | 1006 | 1074.8 | 1148.4 | 1237.6 | 7.1 |
| MEDICAL INSTRUMENTS & DEVICES | 1035.7 | 1110.5 | 1190.9 | 1274.1 | 1363.4 | 1471.8 | 7.3 |
| OTHER APPLICATIONS | 116.4 | 121.7 | 127.2 | 132.7 | 138.4 | 145.6 | 4.6 |
| PROSTHETICS | 532.9 | 563.9 | 596.9 | 630.2 | 665.6 | 709.1 | 5.9 |
| –CATHETERS | 327.6 | 351.6 | 377.4 | 404.1 | 432.9 | 467.7 | 7.4 |
| –DENTAL TOOLS | 120.6 | 125.8 | 131.2 | 136.5 | 141.9 | 148.9 | 4.3 |
| –DRUG DELIVERY | 127.6 | 135.2 | 143.2 | 151.3 | 160 | 170.6 | 6 |
| –GLOVES | 267.4 | 287 | 308.1 | 329.7 | 352.9 | 380.9 | 7.3 |
| –IMPLANTS | 252.2 | 268.6 | 286.2 | 304.2 | 323.3 | 346.6 | 6.6 |
| –LIMB PROSTHETICS | 185.6 | 195.5 | 206 | 216.4 | 227.5 | 241.2 | 5.4 |
| –MEDICAL BAGS | 192.5 | 204.1 | 216.5 | 229 | 242.3 | 258.5 | 6.1 |
| –MEDICAL TUBES | 428.2 | 465 | 504.8 | 546.5 | 591.6 | 645.7 | 8.6 |
| –OTHER DIAGNOSTIC INSTRUMENTS & TOOLS | 60.5 | 63.2 | 66.2 | 69.1 | 72.1 | 76 | 4.7 |
| –OTHER MEDICAL DISPOSABLES | 128.3 | 137.6 | 147.6 | 157.9 | 168.9 | 182.2 | 7.3 |
| –OTHER MEDICAL INSTRUMENTS & DEVICES | 152.3 | 158.8 | 165.5 | 172.1 | 179 | 187.8 | 4.3 |
| –OTHER PROSTHETICS | 95.1 | 99.8 | 104.7 | 109.6 | 114.8 | 121.3 | 5 |
| –SURGICAL INSTRUMENTS | 139.6 | 148.9 | 159 | 169.3 | 180.3 | 193.8 | 6.8 |
| –SYRINGES | 288.6 | 310.4 | 333.9 | 358.2 | 384.4 | 415.9 | 7.6 |
| TOTAL | 2882.5 | 3073.3 | 3277.5 | 3486.6 | 3710.3 | 3982.7 | 6.7 |
Target Audience
- Medical Device Manufacturers : Japanese and international device manufacturers need Japan-specific market data to identify polymer material opportunities, assess local supply chains, and develop products aligned with domestic healthcare regulations and aging population needs.
- Polymer Material Suppliers : Raw material and specialty polymer producers require detailed Japan market insights to optimize product portfolios, identify growth segments, and establish partnerships with local medical device OEMs and contract manufacturers.
- Healthcare Investment Firms : Private equity and venture capital investors targeting Japan's medical sector need comprehensive market analysis to evaluate investment opportunities, assess growth potential, and benchmark valuations against regional competitors.
- Government & Trade Organizations : Japanese government agencies, trade associations, and economic development organizations use market data to inform healthcare policy, support domestic industry competitiveness, and identify export opportunities in medical polymers.
- Strategic Consultants & Analysts : Management consulting firms and business analysts require Japan-specific market intelligence to advise clients on market entry strategies, competitive positioning, and long-term growth planning in the medical polymer sector.
Reasons to Buy this Report
- Japan-Specific Market Sizing : Access precise market valuations for Japan (USD 2,882.5M in 2025, USD 3,982.7M in 2030) with detailed segmentation by polymer type, application, and end-user, enabling accurate business planning and investment decisions.
- Demographic & Healthcare Insights : Understand how Japan's aging population and advanced healthcare infrastructure create unique demand drivers for medical polymers, with analysis of regional healthcare spending patterns and device adoption trends.
- Competitive Landscape Analysis : Identify key domestic and international players in Japan's medical polymer market, including market share data, manufacturing capabilities, and strategic positioning to inform competitive strategy.
- Regulatory & Quality Standards : Navigate Japan's stringent medical device regulations (PMDA approval pathways) and quality requirements with detailed compliance guidance specific to polymer materials and manufacturing standards.
- Growth Opportunity Mapping : Discover high-growth segments within Japan's medical polymer market, including emerging applications in minimally invasive surgery, personalized medicine, and next-generation implantable devices through 2030.
Frequently asked questions
What is the current size of Japan's medical polymer market?
Japan's medical polymer market is valued at USD 2,882.5 million in 2025.
What is the projected market size for Japan by 2030?
Japan's medical polymer market is projected to reach USD 3,982.7 million by 2030.
What is the CAGR for Japan's medical polymer market?
Japan's medical polymer market is expected to grow at a compound annual growth rate of 6.7% from 2025 to 2030.
What factors drive growth in Japan's medical polymer market?
Japan's market growth is driven by an aging population, advanced healthcare infrastructure, increasing adoption of minimally invasive procedures, and rising healthcare expenditure.
Why is Japan significant in the Asia Pacific medical polymer sector?
Japan is significant due to its stringent regulatory standards, strong domestic manufacturing capabilities, advanced healthcare technology, and strategic partnerships with global medical device companies.
RESEARCH METHODOLOGY
The study involved four major activities for estimating the current size of the global medical polymer market. Exhaustive secondary research was conducted to collect information on the market, the peer product market, and the parent product group market. The next step was to validate these findings, assumptions, and sizes with industry experts across the value chain of medical polymers through primary research. Both the top-down and bottom-up approaches were employed to estimate the overall size of the medical polymer market. After that, market breakdown and data triangulation procedures were used to determine the size of different segments and sub-segments of the market.
Secondary Research
In the secondary research process, various secondary sources such as Hoovers, Factiva, Bloomberg BusinessWeek, and Dun & Bradstreet were referred to identify and collect information for this study on the medical polymer market. These secondary sources included annual reports, press releases & investor presentations of companies; white papers; certified publications; articles by recognized authors; regulatory bodies, trade directories, and databases.
Primary Research
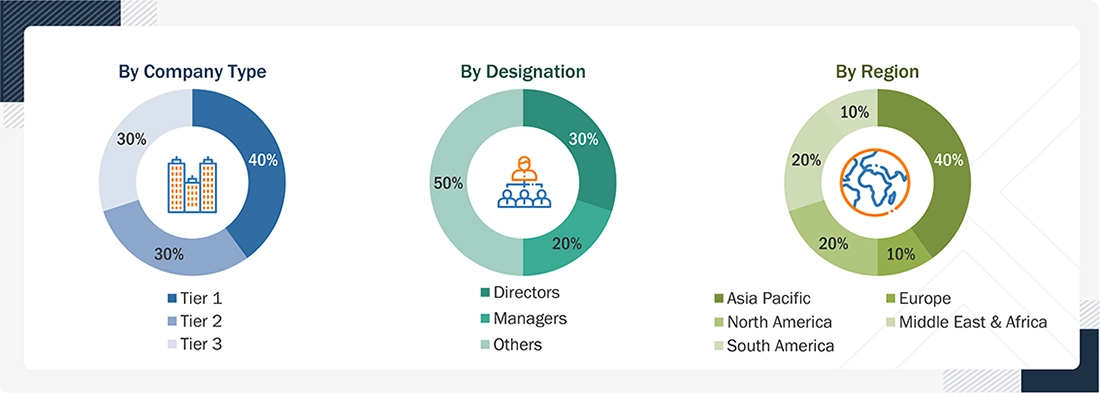
The medical polymer market comprises several stakeholders in the supply chain, which include raw material suppliers, distributors, end-product manufacturers, buyers, and regulatory organizations. Various primary sources from the supply and demand sides of the market have been interviewed to obtain qualitative and quantitative information. The primary participants from the demand side include key opinion leaders, executives, vice presidents, and CEOs of companies in the medical polymer market. Primary sources from the supply side include associations and institutions involved in the medical polymer market, key opinion leaders, and processing players.
To know about the assumptions considered for the study, download the pdf brochure
Market Size Estimation
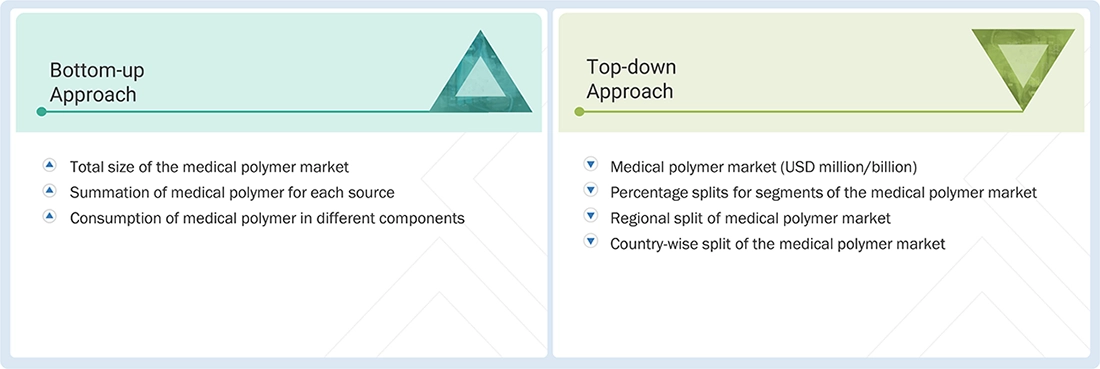
The bottom-up and top-down approaches have been used to estimate the medical polymer market by type, application, manufacturing technology, and region. The research methodology used to calculate the market size includes the following steps:
- The key players in the industry were identified through extensive secondary research.
- In terms of value, the industry’s supply chain and market size were determined through primary and secondary research processes.
- All percentage shares, splits, and breakdowns were determined using secondary sources and verified through primary sources.
- All possible parameters that affect the markets covered in this research study were accounted for, viewed in extensive detail, verified through primary research, and analyzed to obtain the final quantitative and qualitative data.
- The research included studying reports, reviews, and newsletters of top market players and extensive interviews with leaders such as directors and marketing executives to obtain opinions.
The following figure illustrates the overall market size estimation process employed for this study.
Data Triangulation
After arriving at the overall size of the medical polymer market from the estimation process explained above, the total market was split into several segments and sub-segments. The data triangulation and market breakdown procedures were employed, wherever applicable, to complete the overall market engineering process and arrive at the exact statistics for all segments and subsegments. The data was triangulated by studying various factors and trends from both the demand and supply sides. Along with this, the market size was validated using both the top-down and bottom-up approaches.
Market Definition
The medical polymer market represents the industry that develops and implements polymer materials intended for medical and healthcare purposes. In the medical sector, these polymers must adhere to strict specifications related to biocompatibility, durability, elasticity and sterilization or aseptic requirements. Various medical products, like surgical instruments, implants, diagnostic devices, drug delivery systems, and disposables, including syringes and gloves, use medical polymers. The market includes many different types of polymers, including medical plastics, elastomer polymers, and biodegradable polymers. The medical polymer market is an important institutional component in the advancement of modern health care through affordable, safe, efficient medical solutions.
Key Stakeholders
- Medical Polymer Manufacturers
- Raw Material Suppliers
- Regulatory Bodies and Government Agencies
- Distributors and Suppliers
- End-Use Industries
- Associations and Industrial Bodies
- Market Research and Consulting Firms
Report Objectives
- To define, describe, and forecast the size of the medical polymer market in terms of value and volume
- To provide detailed information regarding the key factors influencing the growth of the market (drivers, restraints, opportunities, and challenges)
- To forecast the market size based on type, application, manufacturing technology, and region
- To forecast the market size for the five main regions—North America, Europe, Asia Pacific (APAC), South America, and the Middle East & Africa (MEA)—along with their key countries
- To strategically analyze micro markets with respect to individual growth trends, prospects, and contributions to the total market
- To analyze the opportunities in the market for stakeholders and provide details of the competitive landscape for the market leaders
- To strategically profile leading players and comprehensively analyze their key developments such as new product launches, expansions, and deals in the medical polymer market
- To strategically profile key players and comprehensively analyze their market shares and core competencies
- To study the impact of AI/Gen AI on the market under study, along with the macroeconomic outlook
Available customizations:
With the given market data, MarketsandMarkets offers customizations per the specific needs of companies.
The following customization options are available for the report:
PRODUCT ANALYSIS
- Product matrix, which provides a detailed comparison of the market for different sources of medical polymer.
REGIONAL ANALYSIS
- Further breakdown of a country with respect to the medical polymer market.
COMPANY INFORMATION
- Detailed analysis and profiling of additional market players
Get the Full Medical Polymer Market Report
Full forecast, segment splits, and company analysis for all Medical Polymer Market.
- US Medical Polymer Market
- Canada Medical Polymer Market
- Mexico Medical Polymer Market
- Germany Medical Polymer Market
- France Medical Polymer Market
- UK Medical Polymer Market
- Italy Medical Polymer Market
- Spain Medical Polymer Market
- China Medical Polymer Market
- India Medical Polymer Market
- South Korea Medical Polymer Market
- Australia Medical Polymer Market
- South Africa Medical Polymer Market
- Brazil Medical Polymer Market
- Argentina Medical Polymer Market
- Rest Of Europe Medical Polymer Market
- Rest Of Asia Pacific Medical Polymer Market
- GCC Medical Polymer Market
- -Rest Of GCC Medical Polymer Market
- Rest Of South America Medical Polymer Market
Need a Tailored Report?
Customize this report to your needs
Get 10% FREE Customization
Customize This Report
