Canada mHealth Solutions Market (2023-2028)
The Canada mHealth Solutions Market was valued at $2098.1 Million in 2023 and projected to reach to $5971.1 Million by 2028, representing a compound annual growth rate of CAGR 23.3%. Canada's mHealth Solutions Market is positioned for sustained growth through 2028, driven by provincial healthcare initiatives, increasing smartphone penetration, and government support for digital health infrastructure.

| Market Size in | USD 26.32 MN |
| Market Forecast in | |
| CAGR | |
| Forecast Period | |
| Units Considered | Value (USD MN) |
Canada mHealth Solutions Market Trends and Insights
- This expansion reflects Canada's increasing adoption of digital health technologies, driven by healthcare system pressures and rising consumer demand for remote care solutions.
- Canada's market growth outpaces many developed nations, positioning the country as a key hub for mHealth innovation in North America. The Canadian mHealth sector is characterized by strong government support for digital health initiatives and substantial investment from both public and private sectors.
- Canada's aging population and geographic challenges, particularly in rural regions, create compelling use cases for mobile health applications.
- Between 2023 and 2028, Canada is expected to see accelerated deployment of telemedicine platforms, remote patient monitoring systems, and integrated health management applications across provincial healthcare networks. Canada's regulatory environment and emphasis on data privacy through frameworks like PIPEDA provide a stable foundation for mHealth solution providers.
- The market's trajectory demonstrates Canada's commitment to modernizing healthcare delivery and improving patient outcomes through technology-enabled care models..
Key Market Statistics
- CAGR (2023-2028) CAGR 23.3%
- Market Size, 2023 ~USD 2098.1 Million
- Forecast, 2028 ~USD 5971.1 Million
- Country Canada
Canada mHealth Solutions Market Overview
Market Valuation Growth :
Canada's mHealth Solutions Market reached $2,098.1 million in 2023 and is projected to grow to $5,971.1 million by 2028, demonstrating strong market expansion driven by digital health adoption across the nation.
Robust CAGR Performance :
With a compound annual growth rate of 23.3% from 2023 to 2028, Canada's mHealth market significantly outpaces many developed nations, reflecting accelerated digital transformation in healthcare delivery.
Healthcare System Pressures :
Canada's strained healthcare infrastructure and physician shortages are catalyzing rapid adoption of remote care solutions, telemedicine platforms, and digital health tools across provinces and territories.
Consumer Demand Surge :
Rising Canadian consumer preference for convenient, accessible healthcare services is fueling investment in mobile health applications, wearable devices, and patient engagement platforms across the country.
Canada mHealth Solutions Market Dynamics
- The market benefits from Canada's aging population, rising chronic disease prevalence, and healthcare professionals' adoption of digital tools to improve patient outcomes and operational efficiency. Key growth catalysts include expanded telemedicine reimbursement policies, integration of artificial intelligence in health applications, and partnerships between technology companies and healthcare providers.
- Investment in cybersecurity and data privacy compliance will remain critical as Canadian healthcare organizations prioritize patient information protection under federal and provincial regulations..
Market Ecosystem
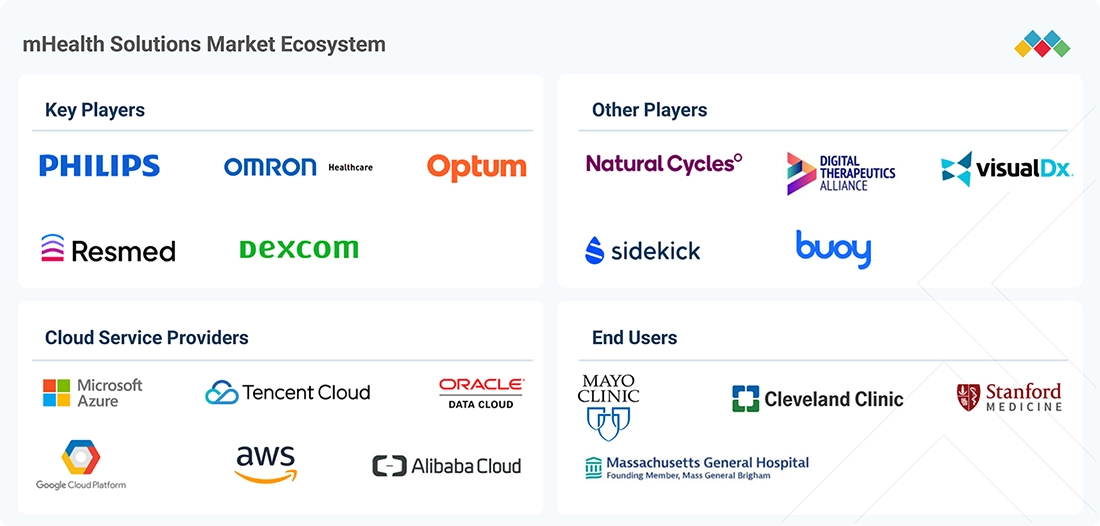
MHEALTH SOLUTIONS MARKET: COMMERCIAL USE CASES ACROSS INDUSTRIES
| COMPANY | USE CASE DESCRIPTION | BENEFITS |
|---|---|---|
 |
Connects patient-monitoring devices and digital platforms for remote and virtual care | Remote patient monitoring, virtual care, chronic disease management, home-based care, connected patient monitoring, telehealth |
 |
Uses smartphone-connected cardiac devices to transmit patient data to clinicians remotely | Remote cardiac monitoring, implantable device monitoring, arrhythmia monitoring, symptom tracking, patient-clinician connectivity |
 |
Connects FreeStyle Libre CGM sensors with mobile apps for real-time glucose monitoring | Diabetes management, continuous glucose monitoring, glucose trend analysis, food and lifestyle management, data sharing with caregivers and providers |
 |
Provides mobile applications integrated with CGM systems for continuous glucose monitoring | Diabetes management, continuous glucose monitoring, glucose alerts, trend tracking, caregiver monitoring, provider data sharing, connected digital health |
 |
Connects sleep and respiratory devices with digital platforms for remote therapy monitoring | Sleep apnea management, respiratory monitoring, therapy monitoring, treatment adherence, remote troubleshooting, patient engagement, personalized therapy support |
Logos and trademarks shown above are the property of their respective owners. Their use here is for informational and illustrative purposes only.
Related Ecosystem
Healthcare It
- Computed Tomography (CT)
- Machine Learning
- Magnetic Resonance Imaging (MRI)
- Natural Language Processing (NLP)
- Predictive Analytics
- CERNER CORPORATION
- PHILIPS HEALTHCARE
- Oracle Corporation
- GE HealthCare Technologies Inc.
- Siemens healthineers
Medical Devices
- Polymerase Chain Reaction (PCR)
- Magnetic Resonance Imaging (MRI)
- Disposable Autoinjectors
- Pulse Oximeters
- Blood Pressure Monitors
- Medtronic plc
- Abbott Laboratories
- Stryker Corporation
- Becton, Dickinson and Company
- CONMED Corporation
Healthcare Analytics
- Machine Learning
- Natural Language Processing (NLP)
- Blood Pressure Monitors
- Computed Tomography (CT)
- Magnetic Resonance Imaging (MRI)
- Oracle Corporation
- PHILIPS HEALTHCARE
- Siemens healthineers
- Zensar Technologies Limited
- EPIC SYSTEMS CORPORATION
Key Takeaways
- Canada's mHealth Solutions Market will nearly triple from $2,098.1M (2023) to $5,971.1M (2028) at a 23.3% CAGR.
- Canada's geographic and demographic factors-including rural populations and aging demographics-drive strong demand for remote health solutions.
- Canada's government-backed digital health initiatives and PIPEDA privacy framework create a favorable regulatory environment for mHealth providers.
- Canada's market growth rate of 23.3% significantly outpaces global average, establishing Canada as a North American mHealth leader.
mHealth Solutions Market Report Scope
| Report Metric | Details |
|---|---|
| Base Year | 2023 |
| Fastest Growing Segment | MHEALTH SERVICES (Product & Service) |
| Forecast Period | 2023-2028 |
| Growth Rate | CAGR of 27% from 2023 to 2028 |
| Largest Segment | MHEALTH APPS (Product & Service) |
| Market Size Base Year (Billions) | ~USD 119.56 (2023) |
| Revenue Forecast (Billions) | ~USD 395 (2028) |
| Segments Covered | Product & Service, Type, End User |
Canada mHealth Solutions Market Report Segmentation
3 segment dimensions are covered across the global market.
By Product & Service
- Connected Medical Devices
- Mhealth Apps
- Mhealth Services
By Type
- Blood Glucose Meters
- Blood Pressure & Ecg Monitoring Apps
- Blood Pressure Monitors
- Breastfeeding Apps
- Cancer Management Apps
- Chronic Care Management Apps
- Communication & Consulting Apps
- Continuing Medical Education Apps
- Diabetes Management Apps
- Diagnosis & Consultation Services
- Ecg/Heart Rate Monitors
- Fertility Apps
- Fetal Monitoring Devices
- Fitness & Nutrition Apps
- Fitness & Wellness Services
- General Health & Fitness Apps
- Health Tracking Apps
- Healthcare Apps
- Healthcare System Strengthening Services
- Medical Apps
- Medical Reference Apps
- Medication Management Apps
- Mental Health & Behavioral Disorder Management Apps
- Multiparameter Trackers
- Neurological Monitoring Devices
- Obesity & Weight Management Apps
- Other Chronic Care Management Apps
- Other Connected Medical Devices
- Other Healthcare Apps
- Other Women'S Health Apps
- Patient Management & Monitoring Apps
- Peak Flow Meters
- Personal Health Record Apps
- Pregnancy Apps
- Prevention Services
- Pulse Oximeters
- Remote Monitoring Services
- Sleep Apnea Monitors
- Treatment Services
- Vital Signs Monitoring Devices
- Women'S Health Apps
- Women'S Health Apps
By End User
- Other End Users
- Patient/ Consumers
- Patients/Consumers
- Payers
- Providers
Target Audience
- Healthcare Technology Investors : Investment firms and venture capitalists need Canada-specific market data to evaluate mHealth opportunities, assess portfolio companies' competitive positioning, and identify high-growth segments for capital deployment.
- Digital Health Solution Providers : mHealth companies and software developers require detailed Canadian market insights to refine product offerings, understand regulatory requirements, and develop localized go-to-market strategies for provincial healthcare systems.
- Healthcare Providers & Institutions : Canadian hospitals, clinics, and healthcare networks need market intelligence to evaluate mHealth vendor options, benchmark adoption rates, and make informed technology investment decisions aligned with patient care goals.
- Government & Policy Makers : Federal and provincial health authorities require market analysis to inform digital health policy development, funding allocation, and regulatory frameworks supporting mHealth innovation and equitable access across Canada.
- Pharmaceutical & Medical Device Companies : Pharma and medtech firms need Canadian mHealth market data to identify digital health integration opportunities, develop companion apps, and understand patient engagement trends in the Canadian healthcare market.
Reasons to Buy this Report
- Market Size & Growth Validation : Obtain precise valuation data for Canada's mHealth market with verified CAGR of 23.3%, enabling accurate financial forecasting and investment decision-making for market entry or expansion strategies.
- Competitive Landscape Intelligence : Understand Canada-specific market dynamics, key players, and competitive positioning to identify partnership opportunities, acquisition targets, and differentiation strategies within the growing digital health ecosystem.
- Regional Growth Drivers Analysis : Access detailed insights into Canadian healthcare pressures, regulatory environment, provincial adoption rates, and consumer behavior patterns that directly influence mHealth solution demand and market penetration.
- Investment & Funding Opportunities : Leverage comprehensive market data to identify high-growth segments, emerging technologies, and underserved regions within Canada to guide venture capital allocation and strategic business development initiatives.
- Strategic Planning & Forecasting : Utilize 5-year market projections and trend analysis specific to Canada to develop informed go-to-market strategies, product roadmaps, and resource allocation plans aligned with regional growth trajectories.
Frequently asked questions
What is the projected size of Canada's mHealth Solutions Market by 2028?
Canada's mHealth Solutions Market is projected to reach $5,971.1 million by 2028, growing from $2,098.1 million in 2023.
What is the CAGR for Canada's mHealth Solutions Market?
Canada's mHealth Solutions Market is expected to grow at a compound annual growth rate of 23.3% between 2023 and 2028.
What factors are driving growth in Canada's mHealth market?
Canada's mHealth market growth is driven by government digital health initiatives, geographic healthcare access challenges, aging population demographics, and increasing consumer adoption of remote care solutions.
How does Canada's mHealth market compare to global trends?
Canada's mHealth market CAGR of 23.3% exceeds the global average of 27%, reflecting strong regional adoption and favorable market conditions specific to Canada's healthcare landscape.
What regulatory considerations apply to mHealth solutions in Canada?
Canada's mHealth providers must comply with PIPEDA privacy regulations, provincial healthcare requirements, and federal health data protection standards, creating a robust but navigable regulatory framework.
RESEARCH METHODOLOGY
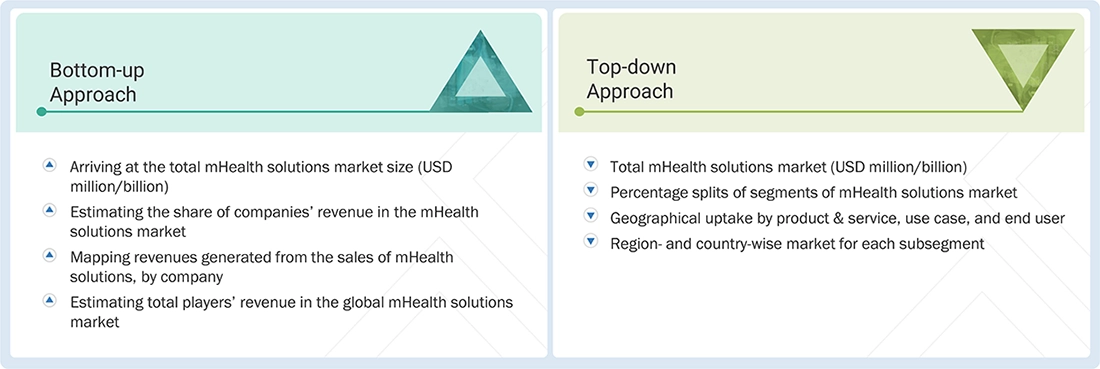
The study involved significant efforts to estimate the current size of the mHealth solutions market. Exhaustive secondary research was conducted to gather information on the mHealth solutions market. The next step was to validate these findings, assumptions, and sizing with industry experts across the value chain through primary research. Different approaches, such as top-down and bottom-up, were employed to estimate the total market size. After that, the market breakup and data triangulation procedures were used to estimate the market size of the segments and subsegments of the mHealth solutions market.
Secondary Research
This research study relied extensively on secondary sources, including directories and databases such as Dun & Bradstreet, Bloomberg Businessweek, and Factiva; white papers, annual reports, and companies’ house documents; investor presentations; and SEC filings of companies. The market for companies offering mHealth solutions was estimated using secondary data from paid and unpaid sources, analyzing the product portfolios of the major companies in the ecosystem, and rating the companies by their performance and quality. A wide range of sources was consulted during the secondary research process to identify and collect information for this study. These sources include annual reports, press releases, investor presentations of companies, white papers, journals, certified publications, and articles from recognized authors, as well as directories and databases.
Various secondary sources were consulted during the secondary research process to identify and collect information relevant to the study. These sources included annual reports, press releases, investor presentations from mHealth solutions vendors, forums, certified publications, and whitepapers. The secondary research was used to obtain critical information on the industry’s value chain, the total pool of key players, market classification, and segmentation from market- and technology-oriented perspectives.
Primary Research
In the primary research process, interviews were conducted with sources from both the supply and demand sides to gather qualitative and quantitative information for this report. Primary sources include industry experts from core and related industries, as well as preferred suppliers, manufacturers, distributors, technology developers, researchers, and organizations across all segments of this industry’s value chain. In-depth interviews were conducted with key industry participants, subject-matter experts (SMEs), C-level executives of key market players, and industry consultants, among other experts, to obtain and verify critical qualitative and quantitative information and to assess prospects.
Primary research was conducted to identify segmentation types; industry trends; key players; and key market dynamics such as drivers, restraints, opportunities, challenges, industry trends, and strategies adopted by key players.
After the complete market engineering (calculations for market statistics, market breakdown, market size estimates, market forecasting, and data triangulation), extensive primary research was conducted to gather information and verify and validate the critical numbers arrived at.
Throughout the complete market engineering process, the top-down and bottom-up approaches, along with several data triangulation methods, were extensively used to estimate and forecast the overall market segments and subsegments listed in this report. Extensive qualitative and quantitative analysis was conducted throughout the process to present key information and insights throughout the report.
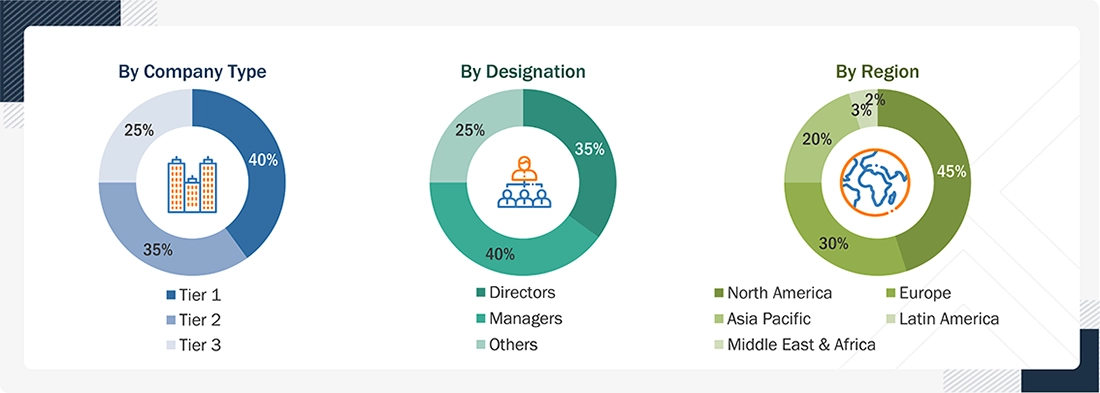
Note: Other designations include sales managers, marketing managers, and product managers.
Note: Tiers are defined based on a company’s total revenue as of 2025: Tier 1 = >USD 1 billion, Tier 2 = USD 500 million to USD 1 billion, and Tier 3 = <USD 500 million.
To know about the assumptions considered for the study, download the pdf brochure
Market Size Estimation
The market size estimates and forecasts provided in this study are derived from a mix of the bottom-up approach (revenue share analysis of leading players) and the top-down approach (assessment of utilization, adoption, and penetration trends by offering, use case, end user, and region).
Data Triangulation
After determining the overall market size using the market size estimation processes, the market was divided into several segments and subsegments. To complete the overall market engineering process and arrive at the exact statistics for each market segment and subsegment, data triangulation and market breakdown procedures were employed wherever applicable. The data was triangulated by analyzing various factors and trends from both the demand and supply sides in the mHealth solutions market.
Market Definition
The mHealth solutions market comprises mobile-enabled healthcare technologies and services that use smartphones, tablets, wearable devices, connected medical devices, wireless connectivity, and digital platforms to support the delivery, management, monitoring, and coordination of healthcare. The market includes mHealth applications, connected medical devices, and mHealth services for activities such as preventive care and wellness, diagnosis and screening, treatment and chronic disease management, patient monitoring, medication management and adherence, teleconsultation, and care coordination.
Key Stakeholders
- mHealth solutions vendors
- Independent software vendors (ISVs)
- Platform providers
- Technology providers
- System integrators
- Patients
- Healthcare payers
- Cloud service providers
- Healthcare IT service providers
- Hospitals & clinics
- Certified community behavioral health clinics
- Academic institutes and research centers
- Pharmaceutical companies
- Forums, alliances, and associations
- Government organizations
- Institutional investors and investment banks
- Investors/Shareholders
- Venture capitalists
Report Objectives
- To define, describe, and forecast the global MHealth solutions market based on offering, use case, end user, and region
- To provide detailed information regarding the factors influencing the growth of the market (such as the drivers, restraints, opportunities, and challenges)
- To strategically analyze micromarkets with respect to individual growth trends, prospects, and contributions to the overall mHealth solutions market
- To analyze market opportunities for stakeholders and provide details of the competitive landscape for market leaders
- To forecast the size of the mHealth solutions market in five main regions (along with their respective key countries): North America, Europe, Asia Pacific, Latin America, and Middle East & Africa
- To profile key players and comprehensively analyze their product portfolios, position, and core competencies in the market
- To analyze competitive developments such as offering launches; expansions; partnerships, agreements, and collaborations; and acquisitions in the mHealth solutions market
- To benchmark players within the mHealth solutions market using the Company Evaluation Matrix framework, which analyzes market players on various parameters within the broad categories of business strategy, market share, and product offering
Available customizations:
With the given market data, MarketsandMarkets offers customizations as per your company’s specific needs. The following customization options are available for the report:
Company Information
- Detailed analysis and profiling of additional market players (up to 5)
Geographic Analysis
- Further breakdown of the Rest of Europe’s mHealth solutions Market into Denmark, Norway, and others
- Further breakdown of the Rest of Asia Pacific mHealth solutions Market into Vietnam, New Zealand, and others
Get the Full mHealth Solutions Market Report
Full forecast, segment splits, and company analysis for all mHealth Solutions Market.
- US mHealth Solutions Market
- Germany mHealth Solutions Market
- UK mHealth Solutions Market
- France mHealth Solutions Market
- Italy mHealth Solutions Market
- Spain mHealth Solutions Market
- China mHealth Solutions Market
- Japan mHealth Solutions Market
- India mHealth Solutions Market
- Brazil mHealth Solutions Market
- Mexico mHealth Solutions Market
- Rest Of Europe mHealth Solutions Market
- Rest Of Asia Pacific mHealth Solutions Market
- Rest Of Latin America mHealth Solutions Market
Need a Tailored Report?
Customize this report to your needs
Get 10% FREE Customization
Customize This Report