–Rest Of GCC Paper and Paperboard Packaging Market (2024-2029)
The –Rest Of GCC Paper and Paperboard Packaging Market was valued at $371.1 Million in 2024 and projected to reach to $404.8 Million by 2029, representing a compound annual growth rate of 1.5%. Rest Of GCC's paper and paperboard packaging market demonstrates resilient growth potential, supported by expanding retail infrastructure and rising e-commerce penetration across smaller Gulf economies.

| Market Size in | USD 26.32 MN |
| Market Forecast in | |
| CAGR | |
| Forecast Period | |
| Units Considered | Value (USD MN) |
–Rest Of GCC Paper and Paperboard Packaging Market Trends and Insights
- –Rest Of GCC's packaging sector reflects moderate but steady demand driven by regional e-commerce growth, retail expansion, and increased focus on sustainable packaging solutions.
- The market in –Rest Of GCC demonstrates resilience despite economic headwinds, with local manufacturers and importers adapting to evolving consumer preferences for eco-friendly materials. –Rest Of GCC's paper and paperboard packaging landscape is characterized by a mix of multinational players and regional suppliers competing on cost-efficiency and sustainability credentials.
- Between 2024 and 2029, –Rest Of GCC is expected to benefit from infrastructure development and rising consumer awareness regarding environmental impact.
- The relatively modest 1.5% CAGR in –Rest Of GCC reflects the region's mature market dynamics, though opportunities exist in specialty packaging segments and value-added solutions tailored to local industries..
Key Market Statistics
- CAGR (2024-2029) 1.5% CAGR
- Market Size, 2024 ~USD 371.1 Million
- Forecast, 2029 ~USD 404.8 Million
- Country –Rest Of GCC
–Rest Of GCC Paper and Paperboard Packaging Market Overview
Steady Regional Growth :
Rest Of GCC's paper and paperboard packaging market is expanding at 1.5% CAGR, driven by moderate but consistent demand from emerging retail and e-commerce sectors across smaller GCC economies.
E-Commerce Acceleration :
Growing online retail adoption in Rest Of GCC countries is creating sustained demand for protective and corrugated packaging solutions, supporting market expansion beyond traditional retail channels.
Sustainability Focus :
Increasing regional emphasis on eco-friendly packaging materials is reshaping Rest Of GCC's market dynamics, with businesses adopting sustainable paperboard solutions to meet consumer and regulatory expectations.
Market Size Trajectory :
Rest Of GCC's market is valued at USD 371.1 million in 2024 and projected to reach USD 404.8 million by 2029, representing USD 33.7 million in incremental growth over the forecast period.
–Rest Of GCC Paper and Paperboard Packaging Market Dynamics
- The region's packaging sector is transitioning toward sustainable solutions, with businesses increasingly investing in recyclable and biodegradable paperboard alternatives to align with environmental regulations and consumer preferences.
- Regional supply chain development and local manufacturing initiatives are enhancing market accessibility and reducing import dependencies.
- The 1.5% CAGR reflects moderate but stable demand dynamics, positioning Rest Of GCC as a steady contributor to broader GCC packaging growth.
- Key growth drivers include retail modernization, food and beverage sector expansion, and heightened corporate sustainability commitments across the region..
Market Ecosystem
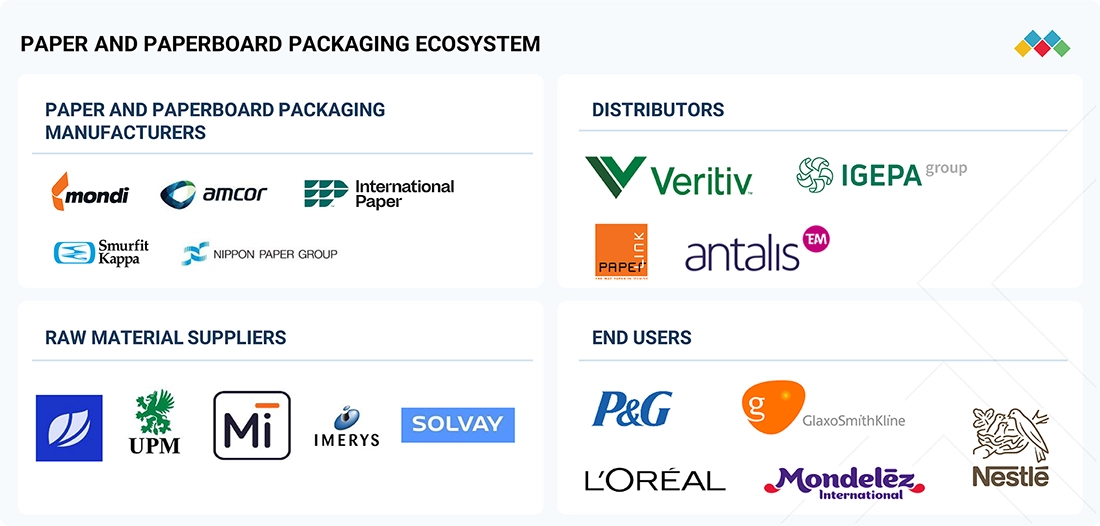
Paper and Paperboard Packaging Market: COMMERCIAL USE CASES ACROSS INDUSTRIES
| COMPANY | USE CASE DESCRIPTION | BENEFITS |
|---|---|---|
 |
Green Bay Packaging sought to digitize and optimize its recycling operations to eliminate inefficiencies associated with manual processes, improve inspection tracking, and enhance overall operational efficiency. | The company implemented Augmentir's Connected Worker solution to digitize processes for plant inspections, facility checks, safety checklists, and auditing procedures. This digital transformation eliminated manual data capture, provided enhanced documentation for OEM and warranty communications, and standardized inspections across multiple sites. The adoption of this technology led to improved accountability, streamlined operations, and a more efficient recycling process. |
 |
Priwatt, a German solar energy company, aimed to enhance its packaging to support increased production volumes and reduce damage rates during transportation. The existing packaging was not sufficiently robust, leading to product damages and inefficiencies in the supply chain | Smurfit Kappa partnered with Priwatt to develop an improved packaging solution tailored to the specific needs of solar panels. The new design focused on enhancing protection, reducing material usage, and optimizing the packaging process. As a result, Priwatt more than tripled its daily output and significantly reduced damage rates, leading to cost savings and improved customer satisfaction. |
 |
Metsä Board, a leading European producer of premium fresh fiber paperboards, sought to improve the functionality, recyclability, and brand impact of its customers' packaging solutions. The company aimed to maximize product performance while minimizing both, carbon footprint and costs | Metsä Board implemented the 3DEXPERIENCE platform to enhance its packaging design and development processes. This digital solution enabled the company to create innovative, sustainable packaging solutions that met customer demands for both performance and environmental responsibility. The platform facilitated collaboration across teams, streamlined workflows, and reduced time-to-market for new packaging designs. |
Logos and trademarks shown above are the property of their respective owners. Their use here is for informational and illustrative purposes only.
Related Ecosystem
Packaging
- Ampoules
- Gravure Process
- Rigid Packaging
- Aerosols
- Aseptic Filling and Sealing Equipment
- Amcor plc
- Essentra plc
- Berry Global Group, Inc.
- Mondi plc
- SEALED AIR CORPORATION
Key Takeaways
- –Rest Of GCC's paper and paperboard packaging market is valued at USD 371.1 million in 2024 and will reach USD 404.8 million by 2029.
- –Rest Of GCC exhibits a conservative 1.5% CAGR, indicating a mature but stable market with incremental growth opportunities.
- –Rest Of GCC's market is driven by e-commerce expansion, retail modernization, and growing demand for sustainable packaging alternatives.
- –Rest Of GCC's competitive landscape features both regional suppliers and multinational corporations focusing on cost and environmental differentiation.
Paper and Paperboard Packaging Market Report Scope
| Report Metric | Details |
|---|---|
| Base Year | 2024 |
| Fastest Growing Segment | PASTED VALVE (Product Type) |
| Forecast Period | 2024–2029 |
| Growth Rate | CAGR of 2.9% from 2024 to 2029 |
| Largest Segment | CORRUGATED BOX (Type) |
| Market Size Base Year (Billions) | ~USD 380.59 (2024) |
| Revenue Forecast (Billions) | ~USD 451.8 (2029) |
| Segments Covered | Grade, Type, Application, Product Type, Thickness, Material, End-Use, Printing Ink, Printing Technology, End-Use Industry |
–Rest Of GCC Paper and Paperboard Packaging Market Report Segmentation
10 segment dimensions are covered across the global market.
By Grade
- Coated Unbleached Kraft Paperboard (Cuk/Sus)
- Folding Boxboard (Fbb)
- Glassine & Greaseproof
- Label Paper
- Other Grades
- Solid Bleached Sulfate (Sbs)
- Solid Bleached Sulfates (Sbs)
- Solid Bleached Sulphates (Sbs)
- White Lined Chipboard (Wlc)
By Type
- Boxboard
- Corrugated Box
- Flexible Paper
- Folder Boxes
- Rigid Boxes
- Slotted Boxes
- Telescope Boxes
By Application
- Beverage
- Food
- Healthcare
- Other Applications
- Personal Care & Homecare
By Product Type
- Flat Bottom
- Pasted Open Mouth
- Pasted Valve
- Pinched Bottom Open Mouth
- Sewn Open Mouth
By Thickness
- 1 Ply
- 2 Ply
- 3 Ply
- Over 3 Ply
By Material
- Brown Kraft Paper
- Linerboard
- Medium
- Other Materials
- White Kraft Paper
By End-Use
- E-Commerce
- Food Service
- Industrial
- Other End-Uses
- Retail
By Printing Ink
- Hot-Melt-Based Ink
- Solvent-Based Ink
- Uv-Curable Ink
- Water-Based Ink
By Printing Technology
- Digital Printing
- Flexography Printing
- Lithography Printing
By End-Use Industry
- Chemicals
- Electronic Goods
- Food & Beverages
- Glassware & Ceramics
- Home & Personal Care
- Paper Products
- Textile
Target Audience
- Packaging Manufacturers : Regional and international packaging producers need Rest Of GCC-specific data to assess market entry viability, capacity planning, and localization strategies for paperboard products.
- Retail & E-Commerce Operators : Retailers and online merchants operating in Rest Of GCC require market insights to optimize packaging procurement, manage costs, and align sourcing with regional sustainability trends.
- Supply Chain & Logistics Providers : Logistics companies and distributors need Rest Of GCC market intelligence to forecast demand, optimize warehouse operations, and identify growth opportunities in regional packaging logistics.
- Investment & Private Equity Firms : Investors evaluating packaging sector opportunities in Rest Of GCC need detailed market analysis, growth projections, and competitive landscape data to inform investment decisions.
- Government & Trade Organizations : Regional economic development agencies and trade bodies require market data to support policy development, industry promotion, and strategic planning for Rest Of GCC's packaging sector.
Key Companies in the –Rest Of GCC Paper and Paperboard Packaging Market
| Company | HQ | Ownership | Strongest segments |
|---|---|---|---|
| ESSENTRA PLC | United Kingdom | Public Company | Corrugated box–linked components,Boxboard & carton–linked hardware,Flexible paper–adjacent masking and protection, |
| RANPAK CORP. | United States | ||
| KEMIRA OYJ | Finland | ||
| AGFA-GEVAERT N.V | Belgium | Public Company | Packaging inkjet printers and presses,Inkjet inks and fluids for packaging,Synthetic papers and films for labels and flexible packaging, |
| AHLSTROM-MUNKSJO | Finland | Private Company | Glassine & Greaseproof,Label Paper,Folding Boxboard and WLC, |
| VALMET CORPORATION | Finland | ||
| LG CHEM LTD. | South Korea | ||
| MONDI GROUP | United Kingdom | Public Company | Corrugated Box (incl. containerboard),Flexible Paper & Functional Paper,Boxboard (FBB, WLC, CUK, SBS-adjacent), |
| INTERNATIONAL PAPER | United States | Public Company | Corrugated Box (containerboard-based),Boxboard (SBS, CUK, FBB, WLC),Flexible Paper & Specialty Grades, |
| SMURFIT KAPPA | Ireland | Public Company | Corrugated Box (containerboard-based packaging),Boxboard / Consumer Packaging (SBS, FBB, WLC, CUK),Flexible Paper, Sacks, Label Paper, Glassine & Greaseproof, |
| NIPPON PAPER INDUSTRIES CO., LTD. | Japan | Public Company | Boxboard (SBS, FBB, WLC, CUK),Corrugated Box and Containerboard,Flexible Paper (Glassine, Greaseproof, Label, Functional), |
| OJI HOLDINGS CORPORATION | Japan | Public Company | Corrugated box and containerboard,Boxboard (SBS/FBB/WLC and special paperboard),Flexible paper and packaging paper, |
| ITC LIMITED | India | Public Company | Boxboard (SBS, FBB, WLC, CUK and specialty boards),Corrugated box and liner grades,Flexible paper and green / plastic-substitution packaging, |
| METSä GROUP | Finland | Private Company | Folding Boxboard (FBB) and Boxboard,White Kraftliner and Corrugated Box Grades,Tissue, Greaseproof, Glassine & Flexible Paper, |
| CLEARWATER PAPER CORPORATION | United States | Public Company | SBS for folding cartons,Foodservice paperboard (cups, plates, liquid packaging),Commercial printing and specialty SBS, |
| PACKAGING CORPORATION OF AMERICA | United States | Public Company | Corrugated Box,Boxboard,Flexible Paper, |
| KLABIN S.A. | Brazil | Public Company | Corrugated Box,Boxboard (SBS, CUK, FBB, WLC),Flexible Paper & Industrial Sacks, |
| SAPPI LTD | South Africa | Public Company | Specialty & Flexible Packaging Paper,Paperboard (SBS, FBB, WLC, CUK),Label Paper & Release Liner, |
ESSENTRA PLC
Essentra PLC is a United Kingdom-based public company founded in 2005 with 2,998 employees, specializing in essential components and solutions for various industries.
RANPAK CORP.
Ranpak Corp. is a United States-based company providing protective packaging solutions and paper-based packaging materials.
KEMIRA OYJ
Kemira Oyj is a Finnish company providing chemicals and services for water-intensive industries including pulp and paper, oil and gas, and municipal water treatment.
AGFA-GEVAERT N.V
Agfa-Gevaert N.V. is a Belgian public company founded in 1867 with 4,211 employees, operating in imaging technology, healthcare IT, and printing solutions.
AHLSTROM-MUNKSJO
Ahlstrom-Munksjo is a Finnish private company founded in 1851 with 6,883 employees, specializing in fiber-based materials and solutions.
VALMET CORPORATION
Valmet Corporation is a Finnish company providing technologies, automation, and services for the pulp, paper, and energy industries.
LG CHEM LTD.
LG Chem Ltd. is a South Korean company producing chemicals, advanced materials, and energy solutions for various industrial and consumer applications.
MONDI GROUP
Mondi Group is a United Kingdom-based public company founded in 2007 with 22,200 employees, producing packaging and paper products globally.
INTERNATIONAL PAPER
International Paper is a United States public company founded in 1898 with 62,602 employees, a leading producer of fiber-based packaging, pulp, and paper products.
SMURFIT KAPPA
Smurfit Kappa is an Ireland-based public company founded in 1934 with 97,000 employees, specializing in paper-based packaging solutions.
NIPPON PAPER INDUSTRIES CO., LTD.
Nippon Paper Industries Co., Ltd. is a Japanese public company founded in 1949 with 15,042 employees, producing paper, pulp, and packaging materials.
OJI HOLDINGS CORPORATION
Oji Holdings Corporation is a Japanese public company founded in 1873 with 38,757 employees, engaged in pulp, paper, packaging, and chemical production.
ITC LIMITED
ITC Limited is an Indian public company founded in 1910 with 22,493 employees, operating diversified businesses including agribusiness, hotels, and fast-moving consumer goods.
METSä GROUP
Metsa Group is a Finnish private company founded in 1947 with 8,767 employees, producing forest products, packaging, and energy solutions.
CLEARWATER PAPER CORPORATION
Clearwater Paper Corporation is a United States public company founded in 1926 with 1,900 employees, manufacturing tissue, paperboard, and packaging products.
PACKAGING CORPORATION OF AMERICA
Packaging Corporation of America is a United States public company founded in 1867 with 16,800 employees, producing containerboard, corrugated packaging, and uncoated paper.
KLABIN S.A.
Klabin S.A. is a Brazilian public company founded in 1899 with 18,153 employees, producing pulp, paper, and packaging materials.
SAPPI LTD
Sappi Ltd is a South African public company founded in 1936 with 12,329 employees, producing printing papers, packaging papers, and dissolving pulp.
Reasons to Buy this Report
- Region-Specific Market Sizing : Obtain precise market valuation data exclusive to Rest Of GCC, enabling accurate budget allocation and investment decisions tailored to this specific regional segment rather than broader GCC-wide estimates.
- Localized Growth Drivers : Understand unique demand catalysts in Rest Of GCC including e-commerce expansion, retail modernization, and sustainability initiatives that differentiate this market from major GCC economies.
- Competitive Positioning : Identify market gaps and competitive opportunities specific to Rest Of GCC's packaging landscape, enabling strategic market entry or expansion planning for regional and international players.
- Forecast-Based Planning : Leverage 5-year projections (2024-2029) to develop long-term supply chain, production, and distribution strategies aligned with Rest Of GCC's anticipated market growth trajectory.
- Sustainability Trend Insights : Gain actionable intelligence on eco-friendly packaging adoption rates and regulatory drivers in Rest Of GCC, informing product development and market positioning strategies.
Frequently asked questions
What is the current market size of paper and paperboard packaging in –Rest Of GCC?
–Rest Of GCC's paper and paperboard packaging market is estimated at USD 371.1 million in 2024.
What is the projected market size for –Rest Of GCC by 2029?
–Rest Of GCC's market is forecast to reach USD 404.8 million by 2029, representing growth of approximately USD 33.7 million over the five-year period.
What is the CAGR for –Rest Of GCC's paper and paperboard packaging market?
–Rest Of GCC's market is expected to grow at a CAGR of 1.5% from 2024 to 2029.
What factors are driving growth in –Rest Of GCC's packaging market?
–Rest Of GCC's market growth is driven by e-commerce expansion, retail sector development, sustainability initiatives, and increased demand for protective and eco-friendly packaging solutions.
Who are the main competitors in –Rest Of GCC's paper and paperboard packaging market?
–Rest Of GCC's market comprises a mix of multinational packaging corporations and regional manufacturers competing on pricing, sustainability credentials, and service quality.
RESEARCH METHODOLOGY
The study involved four major activities for estimating the current global size of the paper and paperboard packaging market. Exhaustive secondary research was conducted to gather information on the market, the peer market, and the parent market. The next step was to validate these findings, assumptions, and sizes with the industry experts across the value chain of paper and paperboard packaging through primary research. Both, the top-down and bottom-up approaches were employed to estimate the overall size of the paper and paperboard packaging market. After that, market breakdown and data triangulation procedures were used to determine the size of different segments and subsegments of the market.
Secondary Research
Various primary sources from both, the supply and demand sides of the paper and paperboard packaging market were interviewed to obtain qualitative and quantitative information. The primary sources from the supply side included industry experts, such as Chief Executive Officers (CEOs), vice presidents, marketing directors, sales professionals, and related key executives from various leading companies and organizations operating in the paper & paperboard packaging industry. The breakdown of the profiles of primary respondents is as follows:
Primary Research
Various primary sources from both, the supply and demand sides of the paper and paperboard packaging market were interviewed to obtain qualitative and quantitative information. The primary sources from the supply side included industry experts, such as Chief Executive Officers (CEOs), vice presidents, marketing directors, sales professionals, and related key executives from various leading companies and organizations operating in the paper & paperboard packaging industry. The breakdown of the profiles of primary respondents is as follows:
Breakdown of Primary Interviews
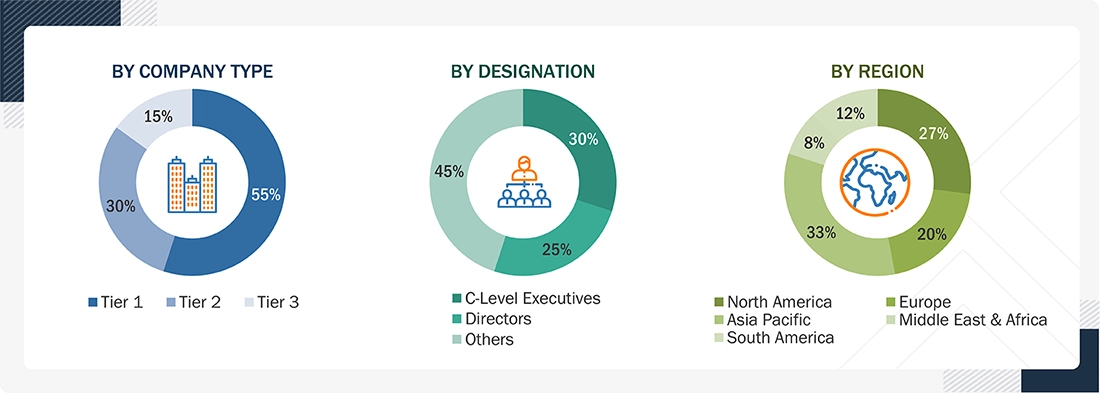
Note: Companies are classified based on their revenue–Tier 1 = >USD 7 billion, Tier 2 = USD 500 million to USD 7 billion, and Tier 3 = < USD 500 million.
Others include sales, marketing, and product managers.
To know about the assumptions considered for the study, download the pdf brochure
Market Size Estimation
Both, the top-down and bottom-up approaches were used to estimate and validate the global size of the paper and paperboard packaging market. These approaches were also used extensively to estimate the size of various dependent segments of the market. The research methodology used to estimate the market size included the following details:
- The key players were identified through extensive secondary research.
- The industry’s supply chain and market size, in terms of value, were determined through primary and secondary research processes.
- All percentage shares, splits, and breakdowns were determined using secondary sources and verified through primary sources.
- All possible parameters that affect the markets covered in this research study were accounted for, viewed in extensive detail, verified through primary research, and analyzed to obtain the final quantitative and qualitative data.
- The research includes the study of reports, reviews, and newsletters of key industry players, along with extensive interviews with key officials, such as directors and marketing executives.
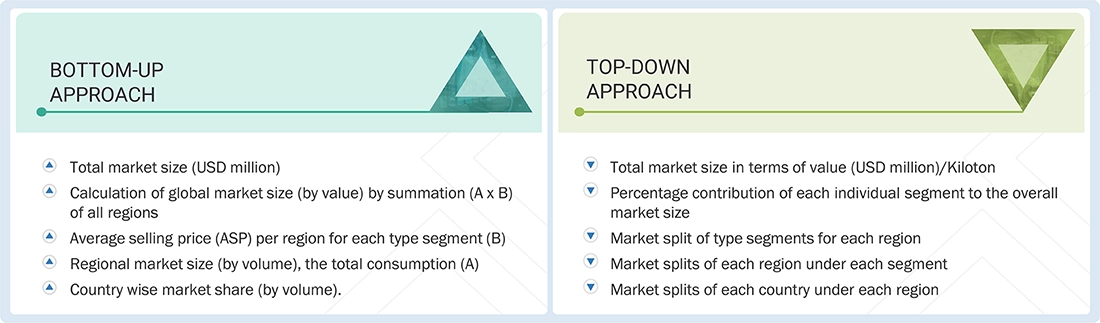
Data Triangulation
After arriving at the overall market size from the estimation process explained above, the total market was split into several segments and subsegments. The data triangulation and market breakdown procedures were employed, wherever applicable, to complete the overall market engineering process and arrive at the exact statistics for all segments and subsegments of the paper and paperboard packaging market. The data was triangulated by studying various factors and trends from both, the demand- and supply-sides.
In addition, the market size was validated by using both, the top-down and bottom-up approaches. Then, it was verified through interviews with experts. Hence, for every data segment, there are three sources—top-down approach, bottom-up approach, and interviews with experts. The data was assumed to be correct when the values arrived at from the three sources matched.
Market Definition
Paper & paperboard packaging refers to packaging materials made from cellulose fibers derived from wood, recycled paper, or agricultural residues. Paper is typically lightweight and flexible, while paperboard is thicker and more rigid, making it suitable for folding cartons, boxes, and trays. These materials are widely used across the food, beverages, personal care, and consumer goods industries due to their recyclability, biodegradability, and printability, offering an eco-friendly alternative to plastic and other non-renewable packaging formats.
Stakeholders
- Paper & paperboard packaging manufacturers
- Paper & paperboard packaging distributors
- Raw material suppliers
- Research & development entities
- Industry associations and regulatory bodies
- End users
Report Objectives
- To estimate and forecast the paper & paperboard packaging market, in terms of value and volume
- To provide detailed information about the major factors (drivers, restraints, opportunities, and challenges) influencing market growth
- To define, describe, and forecast the market size, based on grade, type, application, and region
- To forecast the market size along with segments and submarkets, in key regions: North America, Europe, Asia Pacific (APAC), Middle East & Africa (MEA), and South America, along with their key countries
- To strategically analyze micromarkets, for individual growth trends, prospects, and their contribution to the total market
- To analyze growth opportunities in the market for stakeholders and provide details on the competitive landscape for market leaders
- To strategically profile key players and comprehensively analyze their market shares and core competencies
- To analyze competitive developments, such as mergers & acquisitions, expansions & investments, and agreements in the paper and paperboard packaging market
Get the Full Paper and Paperboard Packaging Market Report
Full forecast, segment splits, and company analysis for all Paper and Paperboard Packaging Market.
- Canada Paper and Paperboard Packaging Market
- Mexico Paper and Paperboard Packaging Market
- Germany Paper and Paperboard Packaging Market
- UK Paper and Paperboard Packaging Market
- France Paper and Paperboard Packaging Market
- Italy Paper and Paperboard Packaging Market
- China Paper and Paperboard Packaging Market
- India Paper and Paperboard Packaging Market
- Japan Paper and Paperboard Packaging Market
- South Korea Paper and Paperboard Packaging Market
- Brazil Paper and Paperboard Packaging Market
- Argentina Paper and Paperboard Packaging Market
- South Africa Paper and Paperboard Packaging Market
- U.S. Paper and Paperboard Packaging Market
- Rest Of Europe Paper and Paperboard Packaging Market
- Rest Of Asia Pacific Paper and Paperboard Packaging Market
- GCC Countries Paper and Paperboard Packaging Market
- Rest Of Mea Paper and Paperboard Packaging Market
- Rest Of South America Paper and Paperboard Packaging Market
Need a Tailored Report?
Customize this report to your needs
Get 10% FREE Customization
Customize This Report