Rest Of Europe Polyols Market (2026-2031)
The Rest Of Europe Polyols Market was valued at $763.6 Million in 2026 and projected to reach to $885.3 Million by 2031, representing a compound annual growth rate of 3.0%. Rest Of Europe's polyols market is positioned for moderate but consistent growth through 2031, with a 3.0% CAGR reflecting the region's stable industrial demand and construction activity.

| Market Size in | USD 26.32 MN |
| Market Forecast in | |
| CAGR | |
| Forecast Period | |
| Units Considered | Value (USD MN) |
Rest Of Europe Polyols Market Trends and Insights
- Rest Of Europe encompasses a diverse industrial base with significant demand from foam, adhesives, coatings, and elastomer applications.
- The region's polyols market reflects steady expansion driven by construction activity, automotive production, and consumer goods manufacturing across smaller EU member states and non-EU European economies. Rest Of Europe's growth trajectory is more moderate compared to global benchmarks, reflecting mature market conditions and regulatory constraints specific to the region.
- Rest Of Europe's polyols sector benefits from established supply chains and technical expertise, though price competition and sustainability pressures shape market dynamics.
- Between 2026 and 2031, Rest Of Europe will experience incremental capacity additions and product innovation focused on bio-based and recycled polyol formulations to meet evolving environmental standards..
Key Market Statistics
- CAGR (2026-2031) 3.0% CAGR
- Market Size, 2026 ~USD 763.6 Million
- Forecast, 2031 ~USD 885.3 Million
- Country Rest Of Europe
Rest Of Europe Polyols Market Overview
Market Size & Growth :
Rest Of Europe's polyols market is valued at USD 763.6 million in 2026 and is projected to reach USD 885.3 million by 2031, growing at a steady CAGR of 3.0%.
Key Application Sectors :
The region demonstrates robust demand across foam manufacturing, adhesives, coatings, and elastomer applications, driven by diverse industrial requirements and construction activity.
Regional Industrial Base :
Rest Of Europe encompasses a varied industrial landscape with significant manufacturing capabilities, supporting consistent polyols consumption across multiple end-use industries.
Growth Drivers :
Steady expansion is fueled by construction sector growth, rising demand for sustainable foam solutions, and increasing adoption of polyols in automotive and furniture manufacturing.
Rest Of Europe Polyols Market Dynamics
- The diverse application base spanning foam, adhesives, coatings, and elastomers provides multiple growth vectors, though expansion remains measured compared to global rates.
- Key opportunities lie in sustainable polyol formulations and emerging applications in specialty chemicals.
- Regional regulatory frameworks and raw material availability will continue to shape market dynamics, while established manufacturing infrastructure supports steady market penetration across traditional and emerging end-use sectors..
Market Ecosystem
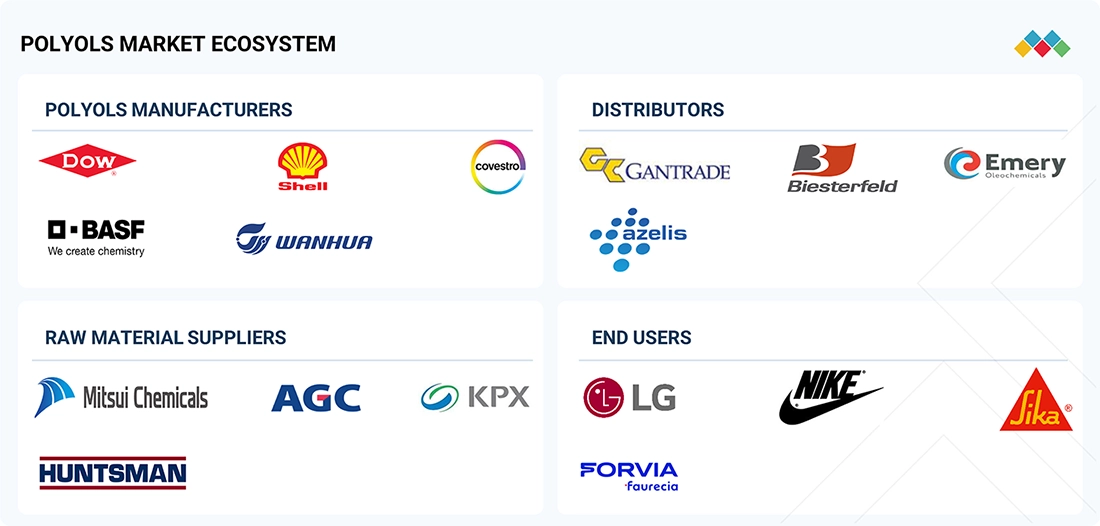
POLYOLS MARKET: COMMERCIAL USE CASES ACROSS INDUSTRIES
| COMPANY | USE CASE DESCRIPTION | BENEFITS |
|---|---|---|
 |
Covestro developed a sustainable cast polyurethane elastomer for offshore wind energy applications using Cardyon®, a CO2-based polyol. The solution was designed to deliver high durability, mechanical stability, and resistance to hydrolysis in harsh marine environments, while reducing dependence on fossil-based feedstocks and supporting environmental sustainability. | The CO2-based elastomer delivers excellent performance under dynamic loading, resists hydrolysis, and reduces the carbon footprint. It demonstrates the feasibility of using captured CO2 in demanding industrial applications, promoting circularity and sustainability across renewable energy sectors. |
 |
Huntsman produced TEROL® polyester polyols from recycled PET bottles to manufacture rigid polyurethane insulation foams. The goal was to divert plastic waste from landfills, improve building energy efficiency, and meet insulation performance and fire safety regulations for residential, commercial, and industrial applications. | TEROL® polyols improve compressive strength, thermal insulation, and flame-retardant performance while converting more than one billion PET bottles annually into valuable materials. This approach reduces plastic waste, lowers building energy consumption, and supports scalable, circular, and environmentally compliant construction solutions. |
 |
BASF engineered low-emission Lupranol® polyether polyols to reduce aldehyde emissions from polyurethane foams used in automotive interiors. The goal was to help OEMs meet strict VOC regulations while maintaining foam properties, including resilience, durability, and processability, for components such as headrests, seats, and insulation panels. | Low-emission polyols reduce formaldehyde and acetaldehyde by up to 20%, meeting VDA276 and BMW GS 97014-3 standards. The solution improves in-cabin air quality without affecting foam processing, supporting regulatory compliance and healthier environments for vehicle occupants. |
Logos and trademarks shown above are the property of their respective owners. Their use here is for informational and illustrative purposes only.
Related Ecosystem
Key Takeaways
- Rest Of Europe's polyols market is valued at USD 763.6 million in 2026 and will expand to USD 885.3 million by 2031 at a 3.0% CAGR.
- Rest Of Europe exhibits slower growth than global markets, reflecting mature industrial saturation and stringent EU environmental regulations.
- Rest Of Europe's demand is anchored in foam production, automotive components, and construction-related applications across diverse economies.
- Rest Of Europe's market will increasingly shift toward sustainable polyol solutions, including bio-based and recycled content formulations through 2031.
Polyols Market Report Scope
| Report Metric | Details |
|---|---|
| Base Year | 2026 |
| Fastest Growing Segment | BUILDING & CONSTRUCTION (End-Use Industry) |
| Forecast Period | 2026–2031 |
| Growth Rate | CAGR of 5.1% from 2026 to 2031 |
| Largest Segment | POLYETHER POLYOLS (Type) |
| Market Size Base Year (Billions) | ~USD 17.54 (2026) |
| Revenue Forecast (Billions) | ~USD 22.49 (2031) |
| Segments Covered | Type, Application, End-Use Industry |
Rest Of Europe Polyols Market Report Segmentation
3 segment dimensions are covered across the global market.
By Type
- Polyester Polyols
- Polyether Polyols
By Application
- Case
- Flexible Polyurethane Foam
- Rigid Polyurethane Foam
By End-Use Industry
- Automotive
- Building & Construction
- Electronics
- Furnishing
- Other End-Use Industries
- Packaging
Target Audience
- Polyols Manufacturers & Suppliers : Need regional market data to optimize production capacity, identify growth segments, and develop targeted sales strategies for Rest Of Europe's diverse industrial customer base.
- Foam & Adhesive Producers : Require insights into polyols demand trends and pricing dynamics in Rest Of Europe to secure reliable supply chains and forecast raw material requirements.
- Chemical Distributors & Traders : Depend on accurate market forecasts and application-specific demand data to optimize inventory management and identify high-growth opportunities in Rest Of Europe.
- Investment & Private Equity Firms : Seek comprehensive regional market analysis to evaluate acquisition targets, assess growth potential, and make informed investment decisions in Rest Of Europe's polyols sector.
- Strategic Business Planners : Need detailed regional forecasts and market dynamics to support expansion planning, competitive analysis, and long-term business strategy development in Rest Of Europe.
Key Companies in the Rest Of Europe Polyols Market
| Company | HQ | Ownership | Strongest segments |
|---|---|---|---|
| OLEON NV | Belgium | Private Company | Fatty acids and glycerine,Esters and specialty oleochemicals,Dimers, technical oils, and industrial grades, |
| HEXION INC | United States | Private Company | Engineered wood and industrial adhesives,Formaldehyde and derivative products,Melamine-based resins and specialty monomers, |
| MOL GROUP | Hungary | Public Company | Fuels (gasoline, diesel, heating oil, bunker, autogas, JET A-1),Petrochemicals and black products (bitumen, HFO, petrolcoke, residues),Retail convenience and mobility services (Fresh Corner, car/bike sharing, fleet), |
| PTT PUBLIC COMPANY LIMITED | Thailand | Public Company | Petroleum and refined products (including lube oil and retail fuels),Natural gas, LNG, and related infrastructure services,Petrochemicals, polymers, and chemical products, |
| DOW | United States | Public Company | Packaging & Specialty Plastics,Industrial Intermediates & Infrastructure,Performance Materials & Coatings, |
| COVESTRO AG | Germany | Public Company | Performance Materials – MDI/TDI and long-chain polyols,Performance Materials – Polycarbonate resins,Solutions & Specialties – TPU, elastomers, specialty films, |
| BASF SE | Germany | Public Company | Chemicals,Materials,Industrial Solutions, |
| HUNTSMAN INTERNATIONAL LLC | United States | Private Company | MDI and Polyurethanes (including polyols and TPU),Amines and Maleic Anhydride/Carbonates,Epoxy, Phenoxy, Acrylic, Polyurethane and Mercaptan Systems, |
| SHELL | United Kingdom | Public Company | Integrated Gas (LNG and GTL),Upstream (oil, gas, NGLs),Marketing (mobility, lubricants, commercial fuels), |
| STEPAN COMPANY | United States | Public Company | Surfactants,Polymers,Specialty Products, |
| WANHUA CHEMICAL GROUP | China | Public Company | Polyurethane (isocyanates, polyether polyols, systems),Petrochemicals (olefin derivatives, ethylene, chlorine chain),Fine Chemicals and New Materials, |
| REPSOL S.A. | Spain | Public Company | Industrial (refining, trading, wholesale, hydrogen, sustainable and synthetic fuels),Customer (mobility/gas stations, power and gas retail, lubricants, LPG, apps and services),Upstream (oil and gas exploration and production, low-carbon geological solutions), |
| PCC SE | Germany | Private Company | Polyols and polyurethane systems,Surfactants and derivatives,Chlorine, MCA, and chlorine derivatives, |
| LANXESS | Germany | Public Company | Specialty Additives,Advanced Intermediates,Consumer Protection, |
| SHANDONG LONGHUA NEW MATERIAL CO., LTD. | China | Public Company | Polymer polyols (POP) and general-purpose soft foam polyether,Polyether for CASE and amine-terminated polyether,Nylon 66 fiber-grade and engineering plastic resins, |
| MANALI PETROCHEMICALS LIMITED | India | Public Company | Propylene Glycol,Polyether Polyols and Polyurethane Systems,Solvents (Propylene Glycol Mono Methyl Ether and Related), |
OLEON NV
OLEON NV is a private chemical company based in Belgium, established in 1957.
HEXION INC
HEXION INC is a private specialty chemicals company founded in 1857 and employs 2,600 people in the United States.
MOL GROUP
MOL GROUP is a Hungarian public company founded in 1991 with 24,744 employees, operating in the energy and chemical sectors.
PTT PUBLIC COMPANY LIMITED
PTT PUBLIC COMPANY LIMITED is a Thai public company founded in 1978 with 10,630 employees, operating in the energy and petrochemical industries.
DOW
DOW is a major American public chemical company founded in 1897 with 34,600 employees, serving global markets.
COVESTRO AG
COVESTRO AG is a German public company founded in 1863 with 17,806 employees, specializing in high-performance polymers and chemicals.
BASF SE
BASF SE is a German public chemical company founded in 1865 with 94,910 employees, operating as one of the world's largest chemical producers.
HUNTSMAN INTERNATIONAL LLC
HUNTSMAN INTERNATIONAL LLC is a private specialty chemicals company founded in 1970 with 6,000 employees in the United States.
SHELL
SHELL is a British public energy and petrochemical company founded in 1897 with 84,000 employees, operating globally.
STEPAN COMPANY
STEPAN COMPANY is a public specialty chemical manufacturer founded in 1932 with 2,328 employees in the United States.
WANHUA CHEMICAL GROUP
WANHUA CHEMICAL GROUP is a Chinese public company founded in 1978 with 30,772 employees, specializing in polyurethane and chemical products.
REPSOL S.A.
REPSOL S.A. is a Spanish public energy and petrochemical company founded in 1927 with 24,523 employees.
PCC SE
PCC SE is a German private chemical company founded in 1993 with 3,115 employees.
LANXESS
LANXESS is a German public specialty chemicals company founded in 1863 with 11,630 employees.
SHANDONG LONGHUA NEW MATERIAL CO., LTD.
SHANDONG LONGHUA NEW MATERIAL CO., LTD. is a Chinese public company founded in 2011 with 615 employees, operating in new materials manufacturing.
MANALI PETROCHEMICALS LIMITED
MANALI PETROCHEMICALS LIMITED is an Indian public petrochemical company founded in 1986 with 321 employees.
Reasons to Buy this Report
- Precise Regional Forecasting : Access detailed market projections specific to Rest Of Europe, enabling accurate business planning and investment decisions tailored to regional growth trajectories through 2031.
- Application-Specific Insights : Understand demand patterns across foam, adhesives, coatings, and elastomer sectors unique to Rest Of Europe's industrial landscape and customer preferences.
- Competitive Positioning : Benchmark your polyols business against regional market dynamics, identify growth opportunities, and develop targeted strategies for Rest Of Europe's diverse industrial base.
- Investment & Expansion Strategy : Make informed decisions on market entry, capacity expansion, or product development in Rest Of Europe with data-driven insights on market size, growth rates, and sector opportunities.
- Supply Chain Optimization : Align procurement and distribution strategies with Rest Of Europe's specific demand patterns, regional industrial clusters, and projected market evolution through 2031.
Frequently asked questions
What is the market size of polyols in Rest Of Europe in 2026?
Rest Of Europe's polyols market is estimated at USD 763.6 million in 2026.
What is the projected market size for Rest Of Europe polyols by 2031?
Rest Of Europe's polyols market is forecast to reach USD 885.3 million by 2031.
What is the CAGR for Rest Of Europe's polyols market?
Rest Of Europe's polyols market is expected to grow at a CAGR of 3.0% from 2026 to 2031.
Which applications drive demand in Rest Of Europe's polyols market?
Rest Of Europe's polyols market is primarily driven by foam production, adhesives, coatings, elastomers, and automotive and construction applications.
What sustainability trends are shaping Rest Of Europe's polyols market?
Rest Of Europe's polyols market is increasingly focused on bio-based polyols, recycled content formulations, and compliance with EU environmental and circular economy regulations.
RESEARCH METHODOLOGY
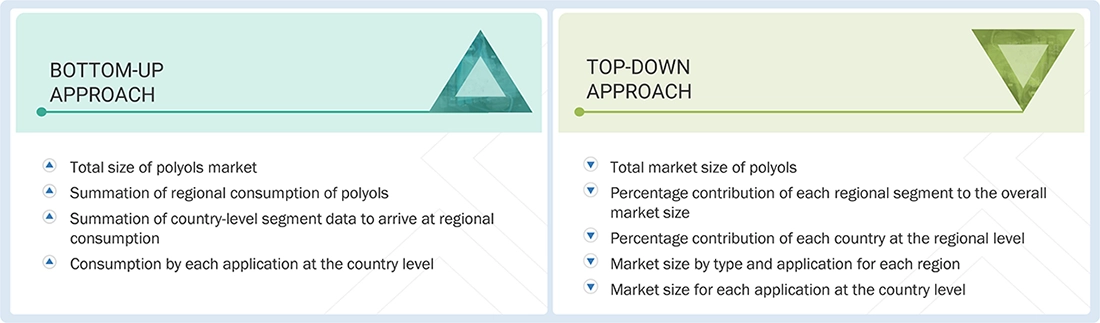
The study involved four major activities to estimate the current size of the global polyols market. Exhaustive secondary research was carried out to collect information on the market, the peer product market, and the parent product group market. The next step was to validate these findings, assumptions, and sizes with the industry experts across the value chain of polyols through primary research. The top-down and bottom-up approaches were employed to estimate the overall size of the polyols market. After that, market breakdown and data triangulation procedures were used to determine the size of different market segments.
Secondary Research
The market for companies offering polyols was arrived at through secondary data available through paid and unpaid sources, analyzing the product portfolios of major companies in the ecosystem, and rating the companies by their performance and quality. For this study, various secondary sources, such as Business Standard, Bloomberg, the World Bank, and Factiva, were referred to identify and collect information on the polyols market. In the secondary research process, various secondary sources were referred to identify and collect information related to the study. Secondary sources included annual reports, press releases, and investor presentations of polyols vendors, forums, certified publications, and whitepapers. Secondary research was used to obtain critical information on the industry’s value chain, the total pool of key players, market classification, and segmentation from market- and technology-oriented perspectives.
Primary Research
In the primary research process, various primary sources from the supply and demand sides were interviewed to obtain qualitative and quantitative information for this report. The primary sources from the supply side included industry experts, such as chief executive officers (CEOs), vice presidents (VPs), marketing directors, technology and innovation directors, and related key executives from several key companies and organizations operating in the polyols market. After the complete market engineering (calculations for market statistics, market breakdown, market size estimations, market forecasting, and data triangulation), extensive primary research was conducted to gather information and verify and validate the critical numbers arrived at.
Primary research was also conducted to identify the segmentation types, industry trends, competitive landscape of polyols offered by various market players, and key market dynamics, such as drivers, restraints, opportunities, challenges, trends, and key player strategies. In the complete market engineering process, the top-down and bottom-up approaches and several data triangulation methods were extensively used to perform the market estimation and market forecasting for the overall market segments and subsegments listed in this report. Extensive qualitative and quantitative analysis was performed throughout the market engineering process to list key information/insights throughout the report.
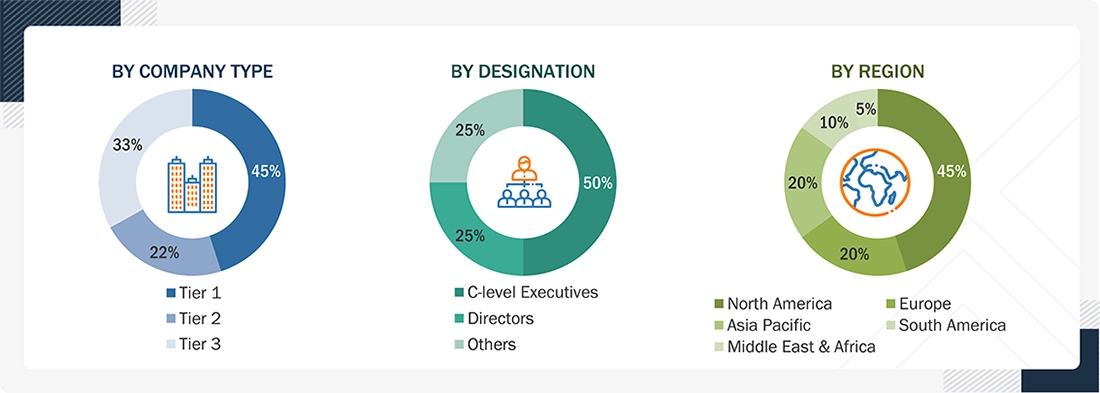
To know about the assumptions considered for the study, download the pdf brochure
Market Size Estimation
The top-down and bottom-up approaches were used to estimate and validate the size of the global polyols market. These approaches were also used extensively to estimate the size of various dependent market segments. The research methodology used to estimate the market size included the following:
Data Triangulation
After arriving at the overall market size using the market size estimation processes, the market was split into several segments and subsegments. The data triangulation and market breakup procedures were employed, wherever applicable, to complete the overall market engineering process and arrive at the exact statistics of each market segment and subsegment. The data was triangulated by studying various factors and trends from the demand and supply sides.
Market Definition
According to the Polyurethane Manufacturers Association (PMA), a polyol is a chemical compound containing more than one reactive hydroxyl (–OH) group per molecule. These hydroxyl groups are vital for the polyol’s role in polyurethane production because they chemically react with di- or poly-isocyanates to create urethane linkages. This reaction forms the core of polyurethane polymers, which are used in many applications, including flexible and rigid foams, coatings, adhesives, sealants, and elastomers. The number and arrangement of hydroxyl groups within a polyol molecule determine its reactivity and functionality, directly impacting the physical, mechanical, and thermal properties of the final polyurethane material.
Key Stakeholders
- Raw material suppliers
- Polyol manufacturers
- Retailers and distributors
- Research & development entities
- Industry associations and regulatory bodies
- End users
Report Objectives
- To define, describe, and forecast the size of the global polyols market, by type, application, and end-use industry, in terms of value and volume
- To forecast the market size of segments for North America, Europe, Asia Pacific, South America, and the Middle East & Africa, along with their respective countries, in terms of value and volume
- To provide detailed information on the significant drivers, restraints, opportunities, and challenges influencing the market
- To strategically analyze micromarkets concerning individual growth trends, prospects, and their contribution to the market
- To assess the growth opportunities in the market for stakeholders and provide details on the competitive landscape for market leaders
- To strategically profile key players and comprehensively analyze their market shares and core competencies
- To analyze competitive developments, such as acquisitions, product launches, investments, expansions, and agreements in the polyols market
- To provide the impact of AI/Gen AI on the market
- To provide the macroeconomic outlook for each region covered under the study, and the impact of the 2025 US tariff on the market
Available customizations:
With the given market data, MarketsandMarkets offers customizations according to client-specific needs.
The following customization options are available for the polyols report:
Product Analysis
- A product matrix that gives a detailed comparison of the product portfolio of each company
Regional Analysis
- A further breakdown of the polyols market for additional countries
Company Information
- Detailed analysis and profiling of additional market players (up to five)
Get the Full Polyols Market Report
Full forecast, segment splits, and company analysis for all Polyols Market.
- China Polyols Market
- India Polyols Market
- Japan Polyols Market
- South Korea Polyols Market
- Thailand Polyols Market
- Indonesia Polyols Market
- Germany Polyols Market
- UK Polyols Market
- France Polyols Market
- Italy Polyols Market
- Russia Polyols Market
- Turkey Polyols Market
- Canada Polyols Market
- Mexico Polyols Market
- US Polyols Market
- Saudi Arabia Polyols Market
- UAE Polyols Market
- South Africa Polyols Market
- Brazil Polyols Market
- Argentina Polyols Market
- GCC Countries Polyols Market
- –Rest Of The GCC Countries Polyols Market
- Rest Of South America Polyols Market
- South America Polyols Market
- Rest Of Asia Pacific Polyols Market
Need a Tailored Report?
Customize this report to your needs
Get 10% FREE Customization
Customize This Report