Rest Of Europe Smart Water Management Market (2026-2031)
The Rest Of Europe Smart Water Management Market was valued at $2237.2 Million in 2026 and projected to reach to $4532.6 Million by 2031, representing a compound annual growth rate of 12.5%. Rest Of Europe's smart water management market is positioned for exceptional growth through 2031, driven by critical infrastructure renewal needs and regulatory compliance requirements.

| Market Size in | USD 26.32 MN |
| Market Forecast in | |
| CAGR | |
| Forecast Period | |
| Units Considered | Value (USD MN) |
Rest Of Europe Smart Water Management Market Trends and Insights
- This represents a compound annual growth rate (CAGR) of 12.5%, significantly outpacing global trends.
- Rest Of Europe is increasingly adopting advanced water technologies driven by regulatory pressures, aging water infrastructure, and heightened environmental awareness across the region. The expansion of Rest Of Europe's smart water management sector reflects growing investments in digital transformation and sustainability initiatives.
- Rest Of Europe's utilities and municipalities are deploying IoT sensors, AI-powered analytics, and real-time monitoring systems to optimize water distribution and reduce non-revenue water losses.
- Between 2026 and 2031, Rest Of Europe is expected to see accelerated adoption of smart metering and leak detection technologies, positioning the region as a key growth market within Europe's broader digital water infrastructure landscape..
Key Market Statistics
- CAGR (2026-2031) 12.5% CAGR
- Market Size, 2026 ~USD 2237.2 Million
- Forecast, 2031 ~USD 4532.6 Million
- Country Rest Of Europe
Rest Of Europe Smart Water Management Market Overview
Strong Regional Growth Trajectory :
Rest Of Europe's smart water management market is expanding at 12.5% CAGR, significantly outpacing the global average of 10.4%, demonstrating accelerated regional adoption and investment momentum.
Infrastructure Modernization Imperative :
Aging water infrastructure across Rest Of Europe is driving urgent demand for smart technologies, with regulatory compliance and water scarcity concerns compelling municipalities and utilities to upgrade legacy systems.
Market Valuation Growth :
The market is projected to nearly double from USD 2,237.2 million in 2026 to USD 4,532.6 million by 2031, reflecting substantial investment opportunities and increasing technology penetration across the region.
Regulatory and Environmental Drivers :
Stringent EU water directives, sustainability mandates, and climate adaptation strategies are compelling Rest Of Europe's water utilities to adopt IoT, AI, and analytics-driven smart water solutions for efficiency and conservation.
Rest Of Europe Smart Water Management Market Dynamics
- The region's aging water systems, combined with increasing water scarcity and environmental pressures, are accelerating the adoption of intelligent monitoring, leak detection, and demand management technologies.
- Investment in digital transformation across municipal water authorities and private utilities is expected to intensify. The competitive landscape in Rest Of Europe is becoming increasingly dynamic, with both established technology providers and innovative startups capturing market share.
- Government funding initiatives, public-private partnerships, and EU sustainability programs are facilitating technology deployment.
- By 2031, smart water solutions will become standard infrastructure across the region, with advanced analytics and IoT integration driving operational efficiency and resource conservation..
Market Ecosystem
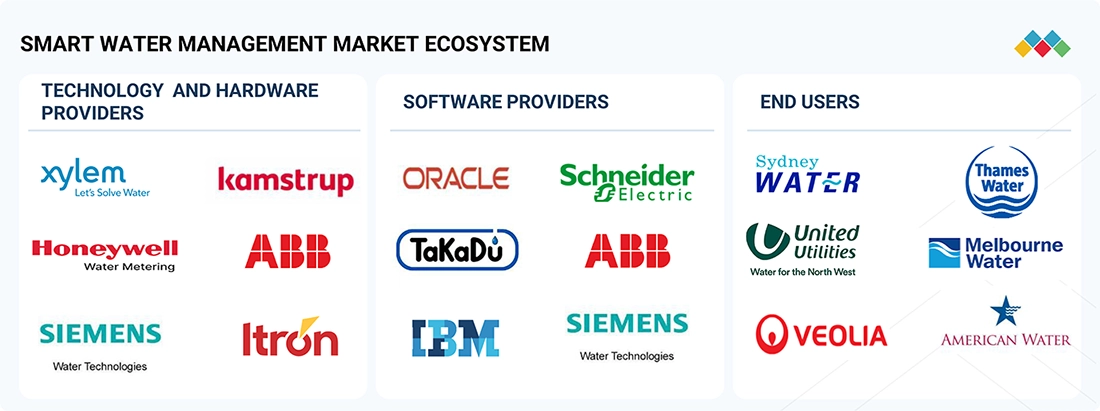
SMART WATER MANAGEMENT MARKET SIZE, SHARE, GROWTH, LATEST TRENDS: COMMERCIAL USE CASES ACROSS INDUSTRIES
| COMPANY | USE CASE DESCRIPTION | BENEFITS |
|---|---|---|
 |
Xylem provides integrated smart water management solutions combining smart meters, network monitoring sensors, advanced analytics, leak detection, digital twin technology, and asset performance management. Water utilities use the platform to monitor water distribution networks in real time, detect leaks, optimize pressure, improve water quality monitoring, reduce non-revenue water (NRW), and enhance operational efficiency through AI-driven insights and predictive maintenance. | Reduced non-revenue water (NRW) and leak losses | Real-time network visibility and water quality monitoring | Optimized asset performance and predictive maintenance | Lower energy and operating costs | Improved regulatory compliance and customer service |
 |
Siemens delivers digital water solutions through industrial automation, IoT connectivity, SCADA, AI-based analytics, digital twins, and intelligent control systems for water and wastewater facilities. Utilities and industrial operators use these solutions to automate treatment plants, optimize pumping operations, monitor critical infrastructure, improve energy efficiency, and ensure continuous compliance with environmental and water quality regulations. | Intelligent plant automation and process optimization | Reduced energy consumption and operational costs | Improved treatment efficiency and regulatory compliance | Predictive maintenance for critical assets | Increased operational resilience and sustainability |
 |
ABB provides smart water management solutions by integrating electrification, process automation, digital monitoring, industrial IoT, and advanced control technologies. Water utilities and industrial facilities use ABB's solutions to optimize pumping stations, monitor electrical assets, automate treatment processes, improve energy management, and enhance system reliability with predictive diagnostics and remote operations. | Optimized pump and process performance | Lower energy consumption through intelligent automation | Improved asset reliability and reduced downtime | Remote monitoring and predictive diagnostics | Enhanced operational efficiency and sustainable water management |
Logos and trademarks shown above are the property of their respective owners. Their use here is for informational and illustrative purposes only.
Related Ecosystem
Digitalization And Iot
- Sensors
- Remote Monitoring
- Supply Chain Management
- Passenger Information System (PIS)
- Platform as A Service (PaaS)
- International Business Machines Corporation
- Cisco Systems, Inc.
- MICROSOFT CORPORATION
- Oracle Corporation
- Siemens ag
Key Takeaways
- Rest Of Europe's smart water management market will grow from USD 2,237.2M (2026) to USD 4,532.6M (2031) at a 12.5% CAGR.
- Rest Of Europe is prioritizing digital water infrastructure to address aging systems and regulatory compliance requirements.
- Rest Of Europe's adoption of IoT, AI analytics, and real-time monitoring is accelerating across utilities and municipalities.
- Rest Of Europe represents a high-growth opportunity within the broader European smart water management landscape through 2031.
Smart Water Management Market Report Scope
| Report Metric | Details |
|---|---|
| Base Year | 2026 |
| Fastest Growing Segment | LEAK DETECTION & NON-REVENUE WATER (NRW) ANALYTICS SOFTWARE (Software) |
| Forecast Period | 2026-2031 |
| Growth Rate | CAGR of 10.4% from 2026 to 2031 |
| Largest Segment | HARDWARE (Offering) |
| Market Size Base Year (Billions) | ~USD 28.8 (2026) |
| Revenue Forecast (Billions) | ~USD 47.24 (2031) |
| Segments Covered | Offering, Hardware, Software, Service, Professional Service, End User, Industrial, Services |
Rest Of Europe Smart Water Management Market Report Segmentation
8 segment dimensions are covered across the global market.
By Offering
- Hardware
- Services
- Software
By Hardware
- Other Hardware
- Smart Valves & Controllers
- Smart Water Meters
By Software
- Asset Management Software
- Leak Detection & Non-Revenue Water (Nrw) Analytics Software
- Meter Data Management Software
- Network Monitoring & Management Software
- Other Software
- Pressure Management Software
- Smart Irrigation Software
- Supervisory Control & Data Acquisition (Scada) Software
- Water Quality Management Software
By Service
- Managed Services
- Professional Services
By Professional Service
- Consulting
- Support & Maintenance
- System Integration & Deployment
By End User
- Commercial
- Industrial
- Residential
By Industrial
- Agriculture
- Energy & Utilities
- Manufacturing
- Mining
- Other Industries
By Services
- Managed Services
- Professional Services
Target Audience
- Water Utility Operators : Municipal and regional water authorities in Rest Of Europe need market intelligence to justify smart technology investments, benchmark against peers, and optimize operational efficiency through data-driven decisions.
- Technology Solution Providers : Software, IoT, and hardware vendors targeting Rest Of Europe require detailed market analysis to identify growth segments, customer needs, and competitive positioning for product development and go-to-market strategies.
- Investment & Private Equity Firms : Investors evaluating opportunities in Rest Of Europe's water tech sector need comprehensive market sizing, growth forecasts, and competitive dynamics to assess portfolio companies and identify acquisition targets.
- Government & Policy Makers : EU and national government agencies developing water infrastructure policies and funding programs require market data to align investments with growth trends and regulatory objectives across Rest Of Europe.
- Consulting & Engineering Firms : Professional services firms advising water utilities and municipalities in Rest Of Europe need market insights to support client strategy development, feasibility studies, and technology implementation roadmaps.
Reasons to Buy this Report
- Regional Market Sizing & Forecasts : Obtain precise market valuations and growth projections specific to Rest Of Europe, enabling accurate budget allocation and investment planning for regional expansion strategies.
- Competitive Landscape Intelligence : Identify key players, market share distribution, and competitive positioning within Rest Of Europe's smart water sector to inform partnership and acquisition strategies.
- Regulatory & Policy Insights : Understand EU water directives, national regulations, and compliance requirements driving smart water adoption across Rest Of Europe, critical for product development and market entry.
- Growth Driver Analysis : Analyze infrastructure modernization needs, aging system challenges, and environmental pressures specific to Rest Of Europe to identify high-potential market segments and customer pain points.
- Investment Opportunity Assessment : Evaluate funding trends, government initiatives, and public-private partnership opportunities across Rest Of Europe to identify optimal entry points and revenue acceleration pathways.
Frequently asked questions
What is the market size of smart water management in Rest Of Europe in 2026?
Rest Of Europe's smart water management market is valued at USD 2,237.2 million in 2026.
What is the projected market size for Rest Of Europe by 2031?
Rest Of Europe's smart water management market is forecast to reach USD 4,532.6 million by 2031.
What is the CAGR for Rest Of Europe's smart water management market?
Rest Of Europe's smart water management market is expected to grow at a CAGR of 12.5% from 2026 to 2031.
What are the primary drivers of growth in Rest Of Europe's smart water management sector?
Rest Of Europe's growth is driven by regulatory compliance, aging water infrastructure, environmental sustainability initiatives, and digital transformation investments by utilities and municipalities.
Which technologies are being adopted in Rest Of Europe's smart water management market?
Rest Of Europe is adopting IoT sensors, AI-powered analytics, real-time monitoring systems, smart metering, and advanced leak detection technologies across water utilities.
RESEARCH METHODOLOGY
The research study involved four major activities in estimating the smart water management market size. Exhaustive secondary research has been done to collect important information about the market and peer markets. The next step has been to validate these findings and assumptions and size them with the help of primary research with industry experts across the value chain. Both top-down and bottom-up approaches have been used to estimate the market size. Post which, the market breakdown and data triangulation have been adopted to estimate the market sizes of segments and sub-segments.
Secondary Research
The market size of companies offering smart water management solutions and services for various subscribers is arrived at based on the secondary data available through paid and unpaid sources and by analyzing the different offerings (hardware, software and services) of major companies in the ecosystem and rating them based on their performance and quality. In the secondary research process, various sources were referred to for identifying and collecting information for this study. The secondary sources included annual reports, press releases and investor presentations of companies, white papers, journals, and certified publications and articles from recognized authors, directories, and databases.
Secondary research was mainly used to obtain key information about the industry’s supply chain, the total pool of key players, market classification, and segmentation according to the industry trends to the bottom most level, regional markets, and key developments from both market- and technology-oriented perspectives, all of which were further validated by primary sources.
Primary Research
In the primary research process, various primary sources from both the supply and demand sides were interviewed to obtain qualitative and quantitative information for the report. The primary sources from the supply side include industry experts, such as Chief Executive Officers (CEOs), Vice Presidents (VPs), marketing directors, technology and innovation directors, and related key executives from various key companies and organizations providing smart water management solutions. The primary sources from the demand side include end users, such as Chief Information Officers (CIOs), consultants, service professionals, technicians and technologists, and managers at public and investor-owned utilities.
In the market engineering process, top-down and bottom-up approaches have been extensively used, along with several data triangulation methods, to perform market estimation and market forecasting for the overall market segments and subsegments listed in the report. Extensive qualitative and quantitative analyses have been performed on the complete market engineering process to list key information/insights throughout the report.
After the complete market engineering process (including calculations for market statistics, market breakup, market size estimations, market forecasting, and data triangulation), extensive primary research has been conducted to gather information. Primary research has been conducted to identify the segmentation, industry trends, key players, competitive landscape, and key market dynamics, such as drivers, restraints, opportunities, challenges, industry trends, and key strategies.
BREAKDOWN OF PRIMARIES
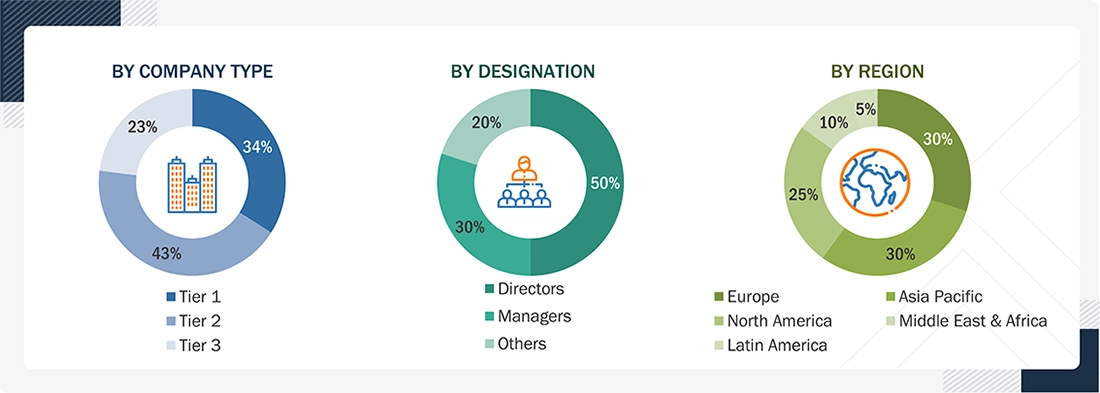
Note: Tier 1 companies have revenues of more than USD 10 billion; tier 2 companies’ revenue ranges from USD 1 billion to USD 10 billion; and tier 3 companies’ revenue ranges from USD 500 million to USD 1 billion.
To know about the assumptions considered for the study, download the pdf brochure
Market Size Estimation
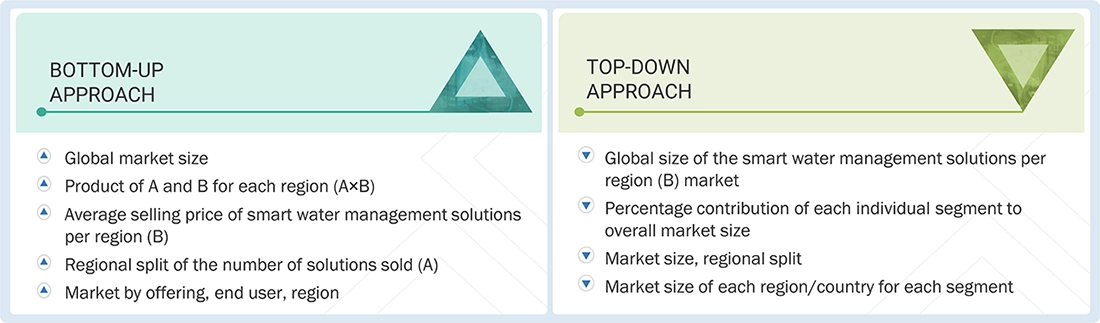
In the market engineering process, the top-down and bottom-up approaches were used along with multiple data triangulation methods to estimate and validate the size of the smart water management market, as well as other dependent submarkets. The research methodology used to estimate the market sizes includes the following:
- Initially, MarketsandMarkets focuses on top-line investments and spending in the ecosystems. Further, significant developments in the critical market area have been considered.
- Tracking the recent and upcoming developments in the smart water management market that include investments, R&D activities, product launches, collaborations, mergers & acquisitions, and partnerships, as well as forecasting the market size based on these developments and other critical parameters
- Conduct multiple discussions with key opinion leaders to learn about the diverse types of authentications and brand protection offerings used and the applications for which they are used to analyze the breakdown of the scope of work carried out by major companies
- Segmenting the market based on technology types concerning applications wherein the types are to be used and deriving the size of the global smart water management market
- Segmenting the overall market into various market segments
- Validating the estimates at every level through discussions with key opinion leaders, such as chief executives (CXOs), directors, and operations managers, and finally with the domain experts at MarketsandMarkets
Smart Water Management Market : Top-Down and Bottom-Up Approach
Data Triangulation
After arriving at the overall market size from the above estimation process, the smart water management market has been split into several segments and sub-segments. To complete the overall market engineering process and arrive at the exact statistics for all segments and sub-segments, data triangulation and market breakdown procedures have been used, wherever applicable. The data has been triangulated by studying various factors and trends from both the demand and supply sides.
The smart water management market size has been validated using top-down and bottom-up approaches.
Market Definition
Smart water management is an integration of smart meters, smart technology solutions, and services that use Information and Communication Technology (ICT) and real-time data and responses as a vital part of the solution for challenges. It brings transparency and improved control to the whole water supply chain, improves water distribution network efficiency, reduces energy costs in pumping water through the distribution network, streamlines water utility operations, and enhances asset management for water and wastewater utility infrastructure by continuously and remotely monitoring critical water infrastructure. It focuses on prioritizing the flow of data for informed decisions through enterprise asset management, analytics and data management, smart irrigation management, Advanced Pressure Management (APM), and network management.
Key Stakeholders
- SWM Vendors
- Network and System Integrators (SIs)
- SWM Infrastructure Providers
- SWM Support Service Providers
- Value-added Resellers (VARs) and Distributors
- Water and Wastewater Utilities
- Water Regulatory Authorities
- Water Meter Manufacturers
- Managed Service Providers
- Water Distribution Network Monitoring Solution Providers
- Advanced Pressure Management Solution Providers
- Smart Irrigation Management Solution Providers
Report Objectives
- To determine, segment, and forecast the smart water management market on the basis of offering (hardware, software, and services), end user, and region in terms of value
- To forecast the size of the market segments with respect to five main regions: North America, Europe, Asia Pacific, the Middle East & Africa, and Latin America
- To provide detailed information about the major factors (drivers, restraints, opportunities, and challenges) influencing the growth of the market
- To study the complete value chain and related industry segments and perform a value chain analysis of the market landscape
- To strategically analyze the macro and micromarkets with respect to individual growth trends, prospects, and contributions to the total market
- To analyze the industry trends, pricing data, patents, and innovations related to the market
- To analyze the opportunities for stakeholders by identifying the high-growth segments of the market
- To profile the key players in the market and comprehensively analyze their market share/ranking and core competencies
- To track and analyze competitive developments, such as mergers & acquisitions, product launches & developments, partnerships, agreements, collaborations, business expansions, and R&D activities
Available customizations:
With the given market data, MarketsandMarkets offers customizations as per the company’s specific needs. The following customization options are available for the report:
Geographic Analysis
- Further breakup of the Asia Pacific market into countries contributing 75% to the regional market size
- Further breakup of the North American market into countries contributing 75% to the regional market size
- Further breakup of the Latin American market into countries contributing 75% to the regional market size
- Further breakup of the Middle East African market into countries contributing 75% to the regional market size
- Further breakup of the European market into countries contributing 75% to the regional market size
Company Information
- Detailed analysis and profiling of additional market players (up to 5)
Get the Full Smart Water Management Market Report
Full forecast, segment splits, and company analysis for all Smart Water Management Market.
- Canada Smart Water Management Market
- US Smart Water Management Market
- UK Smart Water Management Market
- Germany Smart Water Management Market
- France Smart Water Management Market
- Italy Smart Water Management Market
- China Smart Water Management Market
- India Smart Water Management Market
- Japan Smart Water Management Market
- South Korea Smart Water Management Market
- Brazil Smart Water Management Market
- Mexico Smart Water Management Market
- UAE Smart Water Management Market
- South Africa Smart Water Management Market
- Rest Of Asia Pacific Smart Water Management Market
- Rest Of Latin America Smart Water Management Market
- Ksa Smart Water Management Market
Need a Tailored Report?
Customize this report to your needs
Get 10% FREE Customization
Customize This Report