North America Software Defined Radio (SDR) Market (2026-2031)
The North America Software Defined Radio (SDR) Market was valued at $5618 Million in 2026 and projected to reach to $9026.4 Million by 2031, representing a compound annual growth rate of 7.0%. North America's Software Defined Radio market is poised for sustained growth through 2031, driven by increasing defence modernization budgets and the critical need for interoperable communications systems across military branches.

| Market Size in | USD 26.32 MN |
| Market Forecast in | |
| CAGR | |
| Forecast Period | |
| Units Considered | Value (USD MN) |
North America Software Defined Radio (SDR) Market Trends and Insights
- This represents a compound annual growth rate (CAGR) of 7.0%, outpacing the global average and reflecting strong demand from North American aerospace and defence sectors.
- North America's leadership is driven by advanced military modernization programs, substantial defence budgets, and the region's technological expertise in radio communications systems. The North America SDR market benefits from increasing adoption of next-generation military platforms and the transition from legacy analog systems to software-defined architectures.
- North America's defence contractors and government agencies are investing heavily in interoperable, flexible communication solutions that SDR technology provides.
- Between 2026 and 2031, North America is expected to maintain its position as a primary growth engine, supported by ongoing procurement initiatives and R&D investments in advanced defence technologies..
Key Market Statistics
- CAGR (2026-2031) 7.0% CAGR
- Market Size, 2026 ~USD 5618 Million
- Forecast, 2031 ~USD 9026.4 Million
- Geography North America
North America Software Defined Radio (SDR) Market Overview
Market Leadership Position :
North America commands a significant share of the global Software Defined Radio market, valued at $5,618.0 million in 2026 and expanding to $9,026.4 million by 2031, demonstrating robust regional dominance in aerospace and defence SDR adoption.
Above-Average Growth Trajectory :
North America's 7.0% CAGR outpaces the global average of 6.6%, reflecting accelerated investment in advanced military communications, modernization programs, and next-generation defence technologies across the region.
US Market Dominance :
The United States represents the largest SDR market in North America at $8,532.5 million in 2026, driven by substantial defence budgets, military modernization initiatives, and leading aerospace and defence contractors concentrated in the region.
Strategic Defence Investments :
North American aerospace and defence sectors are prioritizing SDR technology for enhanced interoperability, spectrum efficiency, and tactical flexibility, supported by government funding and military procurement strategies focused on next-generation capabilities.
North America Software Defined Radio (SDR) Market Dynamics
- The region's advanced technological infrastructure, coupled with significant investments in next-generation aerospace platforms and tactical communications networks, creates a robust demand environment for SDR solutions. Canada and the United States are expected to lead regional expansion, supported by NATO interoperability requirements, joint defence initiatives, and the modernization of legacy communication systems.
- Ongoing geopolitical tensions and the emphasis on spectrum efficiency will further accelerate SDR adoption, positioning North America as a key growth engine for the global market through 2031..
Market Ecosystem
SOFTWARE DEFINED RADIO MARKET SIZE, SHARE GROWTH FORECAST: COMMERCIAL USE CASES ACROSS INDUSTRIES
| COMPANY | USE CASE DESCRIPTION | BENEFITS |
|---|---|---|
 |
Motorola Solutions’ APX NEXT radios and ASTRO 25 platform support police, fire, and emergency-response communications. The radios combine P25 mission-critical voice with LTE-based applications, broadband connectivity, and remote fleet management. | Improves communication reliability and interoperability among public-safety agencies; broadband fallback helps maintain connectivity beyond P25 coverage, while remote programming and software updates reduce radio downtime and simplify fleet management. |
 |
L3Harris supplies AN/PRC-158 and AN/PRC-163 software-defined radios to the US Army under the HMS program. These multichannel radios support resilient waveforms, multiple encryption levels, cross-banding, and connectivity between tactical ground and airborne networks. | Enables secure and resilient communications in contested electronic-warfare environments; software-defined waveforms and cross-banding improve interoperability across units and coalition forces, while allowing capabilities to be upgraded without replacing the complete radio hardware. |
 |
Thales is supplying more than 6,000 SquadNet and SYNAPS software-defined radios to the Irish Defense Forces. The radios will support secure communications across military branches and carry coalition waveforms, including the ESSOR broadband waveform. | Establishes a common tactical communication network across personnel, vehicles, and command units; it improves information sharing with allied forces, supports broadband voice and data exchange, and enables future waveform upgrades as operational requirements evolve. |
Logos and trademarks shown above are the property of their respective owners. Their use here is for informational and illustrative purposes only.
Related Ecosystem
Key Takeaways
- North America SDR market valued at $5,618.0 million in 2026, growing to $9,026.4 million by 2031 at 7.0% CAGR
- North America's growth rate of 7.0% exceeds the global CAGR of 6.6%, indicating regional market strength
- North America's defence modernization programs and military procurement drive sustained SDR adoption through 2031
- North America's technological leadership and interoperability requirements position it as a key growth market for SDR solutions
Software Defined Radio (SDR) Market Report Scope
| Report Metric | Details |
|---|---|
| Base Year | 2026 |
| Fastest Growing Segment | AUTONOMOUS MARITIME SYSTEMS (Application) |
| Forecast Period | 2026-2031 |
| Growth Rate | CAGR of 6.6% from 2026 to 2031 |
| Largest Segment | HF/VHF/UHF (Frequency Band) |
| Market Size Base Year (Billions) | ~USD 23.53 (2026) |
| Revenue Forecast (Billions) | ~USD 32.38 (2031) |
| Segments Covered | Technology, General-Purpose Sdr Systems, Tactical & Mission-Critical Sdr, Broadband & High-Bandwidth Sdr, Uav & Autonomous Systems Sdr, Cognitive & Ai-Enabled Sdr, Application, Defense Land Systems, Public Safety & Government Systems, Transportation & Smart Mobility, Industrial & Critical Infrastructure, Unmanned Aerial Systems, Commercial Drones, Enterprise & Industrial Drones, Military Drones, Government & Law Enforcement Drones, Naval Platforms, Commercial Maritime, Autonomous Maritime Systems, Frequency Band |
North America Software Defined Radio (SDR) Market Report Segmentation
20 segment dimensions are covered across the global market.
By Technology
- Broadband & High-Bandwidth Sdr
- Cognitive & AI-Enabled Sdr
- General-Purpose Sdr Systems
- Tactical & Mission-Critical Sdr
- Uav & Autonomous Systems Sdr
By General-Purpose Sdr Systems
- Embedded Sdr Systems
- Fixed Sdr Systems
- Portable & Mobile Sdr Systems
By Tactical & Mission-Critical Sdr
- Anti-Jam & Secure Sdr Systems
- Manet & Mesh Networking Sdr
- Tactical Communication Sdr
By Broadband & High-Bandwidth Sdr
- Isr & High-Speed Data Link Sdr
- Satcom Sdr Systems
- Wideband Sdr Systems
By Uav & Autonomous Systems Sdr
- Unmanned Aerial Vehicles
- Unmanned Aerial Vehicles (Uavs)
- Unmanned Ground Vehicles
- Unmanned Ground Vehicles (Ugvs)
- Unmanned Maritime Vehicles
- Unmanned Maritime Vehicles (Umvs)
By Cognitive & Ai-Enabled Sdr
- AI/ML-Enabled Sdr
- Cognitive Radio Sdr
- Dynamic Spectrum Access Sdr
By Application
- Autonomous Maritime Systems
- Business & General Aviation
- Commercial Aircraft
- Commercial Maritime
- Defense Land Systems
- Industrial & Critical Infrastructure
- Military Aircraft
- Naval Platforms
- Public Safety & Government Systems
- Satellites & Ground Stations
- Transportation & Smart Mobility
- Unmanned Aerial Systems
By Defense Land Systems
- Military Vehicle Communication
- Soldier Radios & Manet Systems
- Tactical Battlefield Communication
By Public Safety & Government Systems
- Disaster Response
- Emergency Services
- Police Communication
By Transportation & Smart Mobility
- Connected & Autonomous Mobility Infrastructure
- Intelligent Transportation Systems
- Railway Communication
By Industrial & Critical Infrastructure
- Mining Communication
- Oil & Gas Operations
- Utility Grid Communication
By Unmanned Aerial Systems
- Commercial Drones
- Enterprise & Industrial Drones
- Government & Law Enforcement Drones
- Military Drones
By Commercial Drones
- Agriculture Drones
- Delivery Drones
- Media & Photography Drones
By Enterprise & Industrial Drones
- Mining & Construction
- Oil & Gas Inspection
- Telecom Infrastructure Monitoring
By Military Drones
- Group 1
- Group 2
- Group 3
- Group 4
- Group 5
- Loitering Munitions
- Swarm Uavs
By Government & Law Enforcement Drones
- Border Surveillance
- Disaster Management
- Law Enforcement
By Naval Platforms
- Isr Communication Systems
- Naval Tactical Communication
By Commercial Maritime
- Commercial Shipping
- Offshore Platforms
- Port Communication Infrastructure
By Autonomous Maritime Systems
- Autonomous Underwater Systems
- Remote Maritime Monitoring
- Unmanned Surface Vehicles
By Frequency Band
- C, X, Ku & Ka Band
- Hf/Vhf/Uhf
- L & S Band
- Multi-Band & Wideband Sdr Systems
Target Audience
- Defence Contractors & Integrators : North American defence primes and systems integrators require detailed market intelligence to identify SDR opportunities, assess competitive positioning, and align product development with regional military modernization priorities and procurement cycles.
- SDR Technology Vendors : Software Defined Radio manufacturers and solution providers need North America-specific market data to prioritize sales efforts, forecast revenue potential, and develop localized strategies for the region's high-value aerospace and defence customers.
- Military & Government Agencies : US Department of Defence, Canadian Armed Forces, and related agencies utilize market research to inform procurement strategies, technology roadmaps, and budget planning for next-generation communications and spectrum management initiatives.
- Investment & Private Equity Firms : Investors evaluating aerospace and defence technology companies require North America market insights to assess growth potential, competitive positioning, and return on investment in the expanding SDR sector.
- Telecommunications & Spectrum Regulators : FCC, ISED Canada, and spectrum management authorities need market intelligence to understand SDR adoption trends, spectrum efficiency impacts, and regulatory implications for North American aerospace and defence communications.
Countries within North America - compare and drill down
| Country | 2025 size (native) |
|---|---|
| US | USD 8532.5 Million |
| Canada | USD 493.9 Million |
Country market size visualization
Reasons to Buy this Report
- Regional Market Sizing & Forecasts : Access precise market valuations for North America ($5.6B in 2026, $9.0B in 2031) with country-level breakdowns for the US and Canada, enabling accurate budget allocation and investment planning for regional operations.
- Competitive Landscape Intelligence : Understand the competitive dynamics specific to North American aerospace and defence sectors, including key players, market share distribution, and strategic positioning within the region's high-growth SDR ecosystem.
- Growth Driver Analysis : Identify region-specific growth catalysts including military modernization programs, NATO interoperability mandates, and defence procurement cycles that differentiate North American SDR demand from global markets.
- Strategic Market Entry Guidance : Leverage North America-focused insights to develop targeted go-to-market strategies, partnership opportunities with defence contractors, and customer acquisition approaches tailored to the region's unique regulatory and procurement environment.
- Investment & Risk Assessment : Evaluate investment opportunities and market risks specific to North America's aerospace and defence sectors, including government spending trends, technology adoption rates, and regulatory factors affecting SDR market expansion.
Frequently asked questions
What is the current size of the North America SDR market?
North America's Software Defined Radio market is valued at $5,618.0 million in 2026, representing a substantial portion of global aerospace and defence communications infrastructure.
What is the projected market size for North America SDR by 2031?
North America's SDR market is forecast to reach $9,026.4 million by 2031, reflecting a 7.0% compound annual growth rate over the five-year period.
How does North America's SDR growth compare to global trends?
North America's 7.0% CAGR outpaces the global average of 6.6%, demonstrating stronger regional demand driven by defence modernization and military procurement initiatives.
What factors are driving SDR adoption in North America?
North America's SDR growth is fueled by military modernization programs, substantial defence budgets, interoperability requirements, and the transition from legacy analog systems to software-defined architectures.
Which sectors in North America are primary SDR consumers?
North America's aerospace and defence sectors are the primary consumers of SDR technology, including military branches, defence contractors, and government agencies investing in next-generation communication platforms.
RESEARCH METHODOLOGY
The study used four main activities to estimate the current size of the software defined radio (SDR) market. First, detailed secondary research was conducted to collect information on SDR products, suppliers, applications, frequency bands, contracts, military communication programs, public-safety networks, and commercial wireless systems. The collected findings and assumptions were then checked through primary interviews with industry experts across the value chain. Demand-side analysis was used to estimate SDR spending by application and region. Finally, market breakdown and data triangulation were used to calculate the size of each segment and subsegment.
Secondary Research
Secondary research included information from government procurement portals, defense ministries, spectrum and communication authorities, company annual reports, regulatory filings, investor presentations, product documents, press releases, technical papers, journals, and recognized industry databases. Sources such as SIPRI were used to review relevant military transfers and procurement activity, while ITU publications were used to understand radio frequency allocation and spectrum regulations. Company filings and official product information were used to study SDR portfolios, revenues, contracts, technologies, applications and geographical presence as well.
Primary Research
Primary research was conducted after completing the secondary research. Interviews were carried out with SDR manufacturers, component suppliers, software and waveform developers, system integrators, distributors, defense communication specialists, public-safety users, telecom experts, and other industry participants. The interviews covered major countries across North America, Europe, Asia Pacific, the Middle East, and the Rest of the World. Primary information was collected through questionnaires, emails, and telephone interviews and was used to check market assumptions, pricing, demand patterns, segment shares, and growth estimates.
Breakdown of Primary Interviews
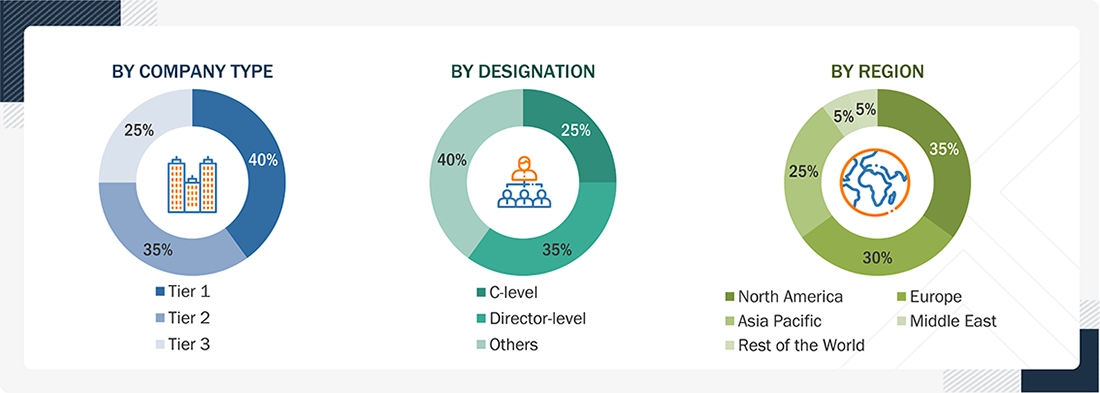
To know about the assumptions considered for the study, download the pdf brochure
Market Size Estimation
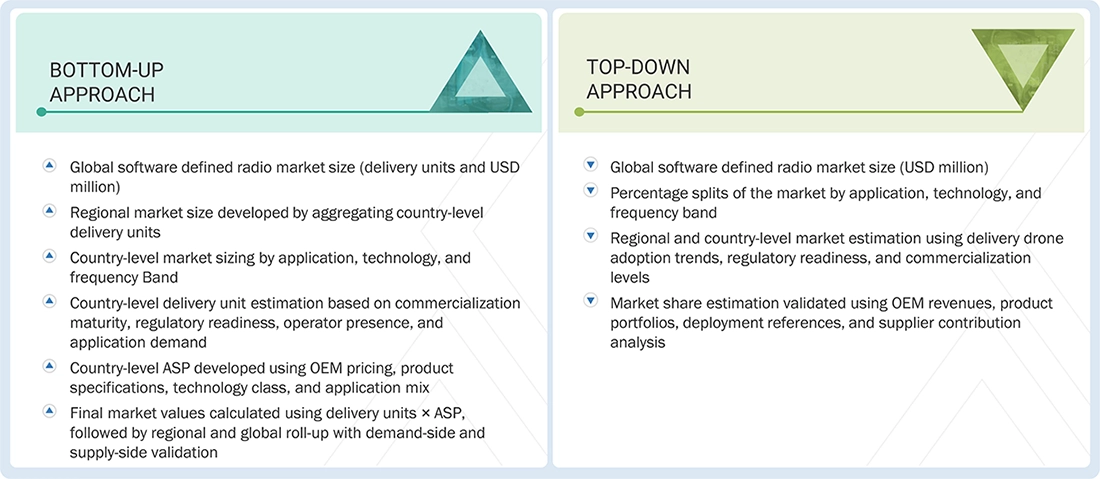
The top-down and bottom-up approaches were used to estimate and validate the size of the SDR market. The research methodology used to estimate the size of the market included the following details:
- Key SDR companies were identified through secondary research. Their market shares were estimated using company revenues, SDR product portfolios, contract activity, customer base, and application presence. Annual reports, financial filings, product documents, and interviews with company executives, engineers, sales professionals, distributors, and other industry participants were used for the analysis.
- Market shares, segment splits, regional shares, and growth rates were first estimated using secondary sources and then verified through primary interviews. The analysis covered SDR technology types, applications, frequency bands, regions, pricing, shipment volumes, and adoption levels.
- Demand from military communication, public safety, aviation, maritime, space, industrial, telecom, and autonomous-system applications was considered. Frequency allocation rules, waveform compatibility, system integration, cybersecurity, and software-upgrade requirements were also reviewed because they influence SDR adoption.
- The collected information was compared and combined through data triangulation. The final market values were calculated using company-level revenues, product-level pricing, shipment volumes, application demand, regional procurement patterns, and expert validation.
Software Defined Radio Market : Top-Down and Bottom-Up Approach
Data Triangulation
After determining the overall market size, the total market was divided into several segments and subsegments. The data triangulation and market breakdown procedures explained below were implemented, wherever applicable, to complete the overall market engineering process and arrive at the estimated market numbers for the market segments and subsegments. The data was triangulated by studying various factors and trends from the demand and supply sides. Additionally, the market size was validated using top-down and bottom-up approaches.
Market Definition
Software-defined radio (SDR) is a radio communication system where components that have been traditionally implemented by hardware, such as mixers, filters, amplifiers, modulators/demodulators, and detectors, are instead implemented by means of software to perform signal processing tasks. SDR can implement all these hardware functionalities using software so that the same hardware is used for multiple radio modes, resulting in an extremely flexible radio that can be quickly reconfigured to handle different signaling techniques.
Key Stakeholders
- Semiconductor & RF Component Suppliers
- SDR Platform Manufacturers (OEMs)
- Waveform & SDR Software Providers
- System Integrators & Solution Providers
- Network & Communication Service Providers
- Government, Regulatory & Standards Organizations
- Testing & Certification Organizations
- Research Institutions
Report Objectives
- To define, describe, segment, and forecast the size of the SDR market based on application, technology, and frequency band
- To forecast the size of market segments across five regions: North America, Europe, Asia Pacific, the Middle East, and the Rest of the World (RoW)
- To identify and analyze key drivers, restraints, opportunities, and challenges influencing the growth of the market
- To identify industry trends, market trends, and technology trends in the market
- To analyze micro markets with respect to individual technology trends, growth prospects, and their contribution to the overall market
- To strategically profile key market players and analyze their market position and core capabilities
- To provide a detailed competitive landscape of the market and analyze competitive strategies such as product launches, partnerships, agreements, and collaborations adopted by key players
- To assess the financial position of key players along with their key products, unique offerings, and recent developments
Available customizations:
MarketsandMarkets offers the following customizations for this market report:
- Additional country-level analysis of the SDR market
- Profiling of other market players (up to five)
Product Analysis
-
Product matrix, which provides a detailed comparison of the product portfolio of each company in the SDR market
Get the Full Software Defined Radio (SDR) Market Report
Full forecast, segment splits, and company analysis for all Software Defined Radio (SDR) Market.
- Canada Software Defined Radio (SDR) Market
- US Software Defined Radio (SDR) Market
- UK Software Defined Radio (SDR) Market
- Germany Software Defined Radio (SDR) Market
- France Software Defined Radio (SDR) Market
- Italy Software Defined Radio (SDR) Market
- Spain Software Defined Radio (SDR) Market
- Rest Of Europe Software Defined Radio (SDR) Market
Need a Tailored Report?
Customize this report to your needs
Get 10% FREE Customization
Customize This Report