Netherlands Underfloor Heating Market (2024-2029)
The Netherlands Underfloor Heating Market was valued at $168.9 Million in 2024 and projected to reach to $247.4 Million by 2029, representing a compound annual growth rate of 7.9%. The Netherlands underfloor heating market is positioned for sustained expansion through 2029, driven by stringent EU energy efficiency regulations and the country's ambitious sustainability targets.

| Market Size in | USD 26.32 MN |
| Market Forecast in | |
| CAGR | |
| Forecast Period | |
| Units Considered | Value (USD MN) |
Netherlands Underfloor Heating Market Trends and Insights
- This growth trajectory reflects Netherlands' commitment to energy-efficient building solutions and sustainable heating technologies across residential and commercial sectors.
- The 7.9% compound annual growth rate demonstrates strong market momentum driven by regulatory support for green building standards and increasing consumer demand for comfort-focused climate control in Netherlands. Netherlands' underfloor heating adoption is accelerated by the country's stringent energy performance regulations and the prevalence of modern construction practices.
- The market in Netherlands benefits from high disposable incomes, advanced infrastructure, and a growing preference for smart home integration.
- Between 2024 and 2029, Netherlands is expected to see increased penetration in both new construction and retrofit applications, supported by government incentives and the rising cost-consciousness of Dutch consumers regarding long-term heating efficiency..
Key Market Statistics
- CAGR (2024-2029) 7.9% CAGR
- Market Size, 2024 ~USD 168.9 Million
- Forecast, 2029 ~USD 247.4 Million
- Country Netherlands
Netherlands Underfloor Heating Market Overview
Market Valuation :
The Netherlands underfloor heating market is valued at USD 168.9 million in 2024, with strong growth momentum driven by increasing adoption of energy-efficient heating solutions in Dutch residential and commercial properties.
Projected Growth :
Expected to reach USD 247.4 million by 2029, representing a robust 7.9% CAGR, outpacing the global average of 7.3% and reflecting Netherlands' leadership in sustainable building technologies.
Energy Efficiency Focus :
Dutch commitment to EU energy directives and carbon neutrality goals is accelerating underfloor heating adoption as a preferred solution for reducing building energy consumption and operational costs.
Residential & Commercial Expansion :
Growth spans both residential renovations and new commercial construction projects, with increasing demand from property developers, contractors, and building owners seeking modern climate control solutions.
Netherlands Underfloor Heating Market Dynamics
- Dutch consumers and businesses increasingly recognize underfloor heating as a cost-effective alternative to traditional HVAC systems, particularly in renovation projects targeting older building stock.
- Government incentives for green building certifications and rising energy costs further support market penetration across urban and suburban regions. Technological advancements in smart heating controls and integration with renewable energy sources are creating new growth opportunities.
- The market will benefit from growing construction activity, increased awareness of indoor comfort benefits, and the transition toward all-electric heating systems.
- Strategic partnerships between heating manufacturers and Dutch construction firms will accelerate product adoption, positioning the Netherlands as a key European market for underfloor heating innovation..
Market Ecosystem
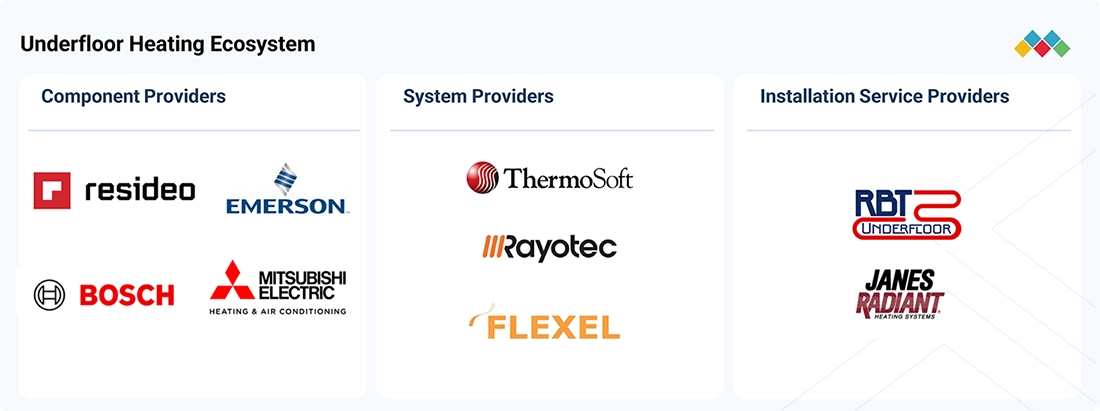
UNDERFLOOR HEATING MARKET SIZE, SHARE AND GROWTH: COMMERCIAL USE CASES ACROSS INDUSTRIES
| COMPANY | USE CASE DESCRIPTION | BENEFITS |
|---|---|---|
 |
Uponor supplies hydronic underfloor heating solutions integrated with Smatrix intelligent room controls and auto-balancing technology. The systems operate across residential homes, multi-family apartment buildings, and commercial facilities to provide automated low-temperature water distribution through cross-linked polyethylene (PEX) pipe networks. | Eliminates manual circuit balancing through automated algorithmic flow control | Lowers annual heating energy costs compared with traditional high-temperature radiator systems | Accelerates commissioning and installation speed for field contractors | Enables multi-zone individual room temperature management via cloud connectivity |
 |
Danfoss delivers digital underfloor heating platforms using the Icon2 main controller and smart room thermostats. The platform connects hydronic floor heating and cooling circuits across residential developments and light commercial properties, linking dynamic floor actuators directly with smart home systems. | Delivers automatic hydronic balancing across variable-length pipe loops without manual presetting | Lowers supply temperature requirements to optimize heat pump system performance | Simplifies installer setup via mobile app guided commissioning | Integrates seamlessly with third-party home automation protocols |
 |
REHAU provides radiant floor heating systems using RAUPEX PEXa cross-linked pipes and low-profile RAUPANEL dry-installation modules. The infrastructure supports new concrete slab construction, residential renovations, light commercial spaces, and outdoor snow melting applications. | Provides high resistance to pipe degradation and stress cracking using cross-linked polyethylene | Enables dry retrofit installations without requiring heavy concrete overpours | Delivers silent, uniform bottom-up heat distribution without circulating airborne dust or allergens | Secures reliable mechanical joints with long-term leak-free connection fittings |
 |
Resideo Technologies provides hydronic zoning platforms such as the Honeywell Home HCC100 multi-zone controller and connected thermostats. The system manages multi-room radiant underfloor circuits integrated with central heating systems, heat pumps, and motorized zone valves in modern dwellings. | Supports independent temperature scheduling for multiple distinct living zones | Coordinates heat demand directly with heat pumps and central boilers to reduce cycle losses | Provides flexible hybrid configurations supporting wired and wireless sensor endpoints | Optimizes indoor comfort through continuous two-way communication protocols |
 |
Watts manufactures stainless-steel radiant heating manifolds, mixing stations, and hydronic circulation modules for radiant floor projects. The equipment operates in custom residential homes, commercial office buildings, and institutional facilities to manage hot water distribution through sub-floor pipe circuits. | Delivers balanced hydraulic flow rates across all connected underfloor loops | Provides high corrosion resistance and mechanical strength with stainless-steel manifolds | Facilitates precise flow measurement and circuit monitoring through integrated flow meters | Integrates directly with secondary mixing shunts to maintain safe sub-floor fluid temperatures |
Logos and trademarks shown above are the property of their respective owners. Their use here is for informational and illustrative purposes only.
Related Ecosystem
Electronics System And Components
- Sensors
- Temperature Sensors
- Pressure Sensors
- Actuators
- Image Sensors
- Lenovo
- Samsung
- Texas Instruments Incorporated
- HONEYWELL INTERNATIONAL INC.
- Teledyne Technologies Incorporated
Smart Home
- Sensors
- Pressure Sensors
- Temperature Sensors
- Actuators
- Face Recognition
- HONEYWELL INTERNATIONAL INC.
- SCHNEIDER ELECTRIC SE
- Siemens ag
- Samsung
- Godrej Industries Limited
Key Takeaways
- Netherlands underfloor heating market valued at USD 168.9 million in 2024, expanding to USD 247.4 million by 2029.
- Netherlands demonstrates a 7.9% CAGR, outpacing global average of 7.3%, indicating strong regional market dynamics.
- Energy efficiency regulations and sustainability mandates in Netherlands drive adoption across residential and commercial properties.
- Smart home integration and retrofit demand in Netherlands create significant growth opportunities through 2029.
Underfloor Heating Market Report Scope
| Report Metric | Details |
|---|---|
| Base Year | 2024 |
| Fastest Growing Segment | SERVICES (Offering) |
| Forecast Period | 2024-2029 |
| Growth Rate | CAGR of 7.3% from 2024 to 2029 |
| Largest Segment | HARDWARE (Offering) |
| Market Size Base Year (Billions) | ~USD 5.34 (2024) |
| Revenue Forecast (Billions) | ~USD 7.6 (2029) |
| Segments Covered | Installation Type, Application, Offering, Product Type, Component Type |
Netherlands Underfloor Heating Market Report Segmentation
5 segment dimensions are covered across the global market.
By Installation Type
- New Installations
- Retrofit Installations
By Application
- Commercial
- Healthcare
- Industrial
- Residential
- Sports & Entertainment
By Offering
- Hardware
- Services
By Product Type
- Electric Underfloor Heating
- Hydronic Underfloor Heating
By Component Type
- Heating Cables
- Heating Mats
- Heating Pipes
- Manifolds And Valves
- Thermal Actuators
- Thermostats And Sensors
- Wiring Centers
- Zone Valves
Target Audience
- HVAC Manufacturers & Suppliers : Require Netherlands-specific market data to develop localized product strategies, establish distribution networks, and compete effectively in this high-growth European heating market.
- Construction & Real Estate Developers : Need market insights to understand demand trends, regulatory requirements, and customer preferences for underfloor heating in Dutch residential and commercial projects.
- Building Contractors & Installers : Seek market forecasts and segment analysis to plan service offerings, training programs, and business expansion within the Netherlands' growing underfloor heating installation sector.
- Energy Efficiency Consultants : Require detailed Netherlands market data to advise clients on sustainable heating solutions, cost-benefit analyses, and compliance with Dutch energy performance standards.
- Investment & Private Equity Firms : Need comprehensive market sizing and growth projections for Netherlands to evaluate investment opportunities in heating technology companies and construction-related ventures.
Reasons to Buy this Report
- Market-Specific Sizing Data : Access precise valuation figures for the Netherlands market (USD 168.9M in 2024) with detailed 5-year forecasts, enabling accurate budget allocation and investment planning for Dutch market entry or expansion.
- Competitive Landscape Intelligence : Understand Netherlands-specific market dynamics, key players, and competitive positioning within the Dutch underfloor heating sector to identify partnership and acquisition opportunities.
- Regulatory & Policy Insights : Gain comprehensive analysis of Dutch and EU energy efficiency regulations, government incentives, and sustainability mandates driving market growth and shaping product development strategies.
- Segment & Application Analysis : Detailed breakdown of residential versus commercial segments in Netherlands, including renovation trends, new construction demand, and emerging applications in Dutch property development.
- Strategic Growth Opportunities : Identify high-potential customer segments, geographic hotspots, and technology trends specific to Netherlands to optimize market penetration and maximize ROI in this premium European market.
Frequently asked questions
What is the current market size of underfloor heating in Netherlands?
The Netherlands underfloor heating market was valued at USD 168.9 million in 2024 and is projected to grow to USD 247.4 million by 2029.
What is the growth rate for underfloor heating in Netherlands?
Netherlands' underfloor heating market is growing at a compound annual growth rate (CAGR) of 7.9% from 2024 to 2029.
What factors are driving underfloor heating adoption in Netherlands?
Key drivers in Netherlands include stringent energy performance regulations, government sustainability incentives, high consumer purchasing power, and increasing demand for smart home heating solutions.
How does Netherlands compare to the global underfloor heating market?
Netherlands' 7.9% CAGR exceeds the global average of 7.3%, reflecting stronger regional market momentum and favorable regulatory conditions in the country.
What applications are growing fastest in Netherlands' underfloor heating market?
Retrofit applications and smart-integrated systems are experiencing the fastest growth in Netherlands, driven by renovation trends and consumer preference for connected home technologies.
RESEARCH METHODOLOGY
The research process for this study involved the systematic gathering, recording, and analysis of data on customers and companies operating in the underfloor heating market. This process involved the extensive use of secondary sources, directories, and databases (Factiva and OANDA) to identify and collect valuable information for a comprehensive, technical, market-oriented, and commercial study of the market. In-depth interviews were conducted with primary respondents, including experts from core and related industries, as well as preferred manufacturers, to obtain and verify critical qualitative and quantitative information and assess growth prospects. Key players were identified through secondary research, and their market rankings were determined through a combination of primary and secondary research. This research involved studying the annual reports of top players and conducting interviews with key industry experts, including CEOs, directors, and marketing executives.
Secondary Research
Various sources were utilized in the secondary research process to identify and collect information relevant to this study. These include company annual reports, press releases, investor presentations, white papers, technology journals, certified publications, articles by recognized authors, directories, and databases. Secondary research was primarily used to gather key information on the industry’s value chain, the total pool of market players, market classification by industry trends at the most detailed level, regional markets, and key developments from market- and technology-oriented perspectives.
Primary Research
Primary research was conducted to identify the segmentation types, key players, competitive landscape, and key market dynamics, including drivers, restraints, opportunities, challenges, and industry trends, as well as the key strategies adopted by players operating in the underfloor heating market. Extensive qualitative and quantitative analyses were conducted across the complete market engineering process to present key information and insights throughout the report.
Extensive primary research has been conducted following the acquisition of knowledge about the underfloor heating market scenarios through secondary research. Several primary interviews were conducted with experts from the demand side (application and region) and the supply side (product type, offering, and installation type) across four major geographic regions: North America, Europe, Asia Pacific, and RoW. Approximately 60% and 40% of the primary interviews were conducted from the supply and demand sides, respectively. These primary data have been collected through questionnaires, emails, and telephonic interviews.
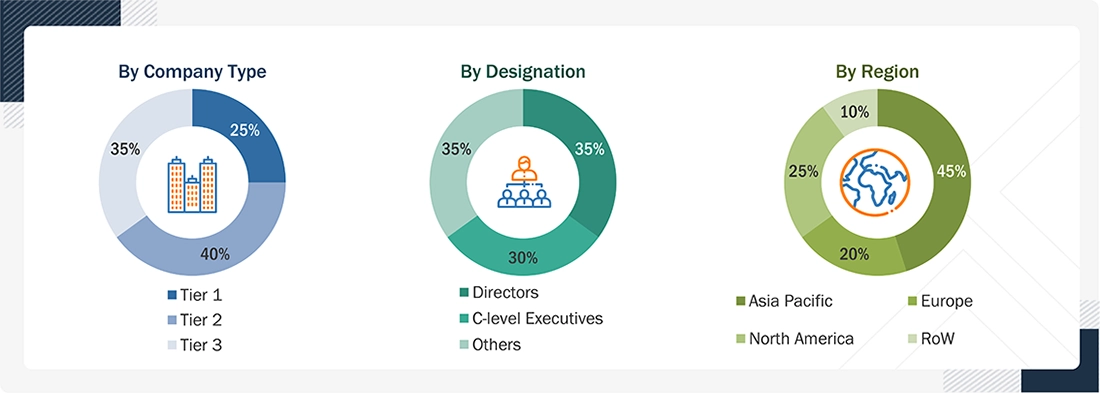
Notes: The three tiers of companies have been defined based on their total/segmental revenue as of 2025: Tier 1 = > USD 1 billion, Tier 2 = USD 1 billion–USD 500 million, and Tier 3 = < USD 500 million.
Other designations include sales, marketing, and product managers.
To know about the assumptions considered for the study, download the pdf brochure
Market Size Estimation
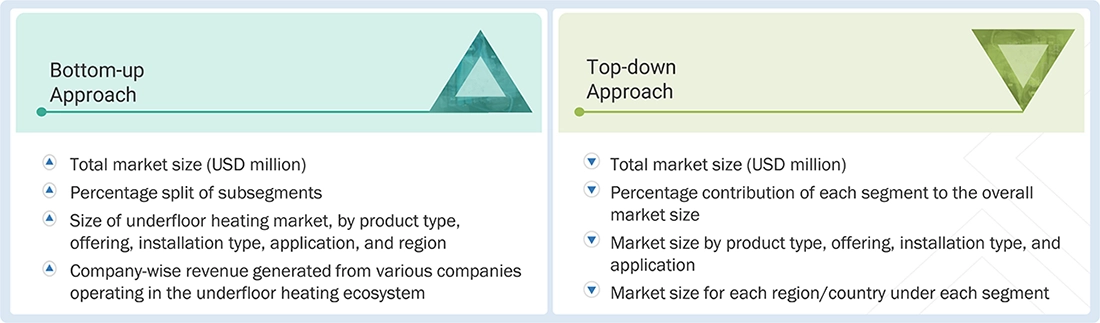
In the complete market engineering process, top-down and bottom-up approaches, along with several data triangulation methods, were used to estimate and validate the size of the underfloor heating market and various other dependent submarkets. Key players in the market were identified through secondary research, and their market share in each region was determined through a combination of primary and secondary research. This research methodology involved analyzing the annual and financial reports of the top players and conducting interviews with experts (CEOs, VPs, directors, and marketing executives) to gather key insights (quantitative and qualitative).
All percentage shares, splits, and breakdowns were determined using secondary sources and verified through primary sources. All possible parameters affecting the markets covered in this study were accounted for, examined in detail, verified through primary research, and analyzed to obtain final quantitative and qualitative data. This data was consolidated and supplemented with detailed inputs and analysis from MarketsandMarkets and presented in this report.
Underfloor Heating Market : Top-Down and Bottom-Up Approach
Data Triangulation
After determining the overall market size through the estimation process, as explained above, the total market was divided into several segments and subsegments. To complete the overall market engineering process and obtain precise statistics for all segments and subsegments, the data triangulation procedure was employed, as applicable. The data were triangulated by studying various factors and trends from the demand and supply sides. Additionally, the market has been validated using both top-down and bottom-up approaches.
Market Definition
The underfloor heating (UFH) system is a type of central heating system that regulates indoor temperature for thermal comfort using conduction, radiation, and convection methods. The underfloor heating market includes hydronic and electric underfloor heating systems. Hydronic UFH systems rely on hot water for in-floor heating, whereas electric UFH systems operate on electricity. Underfloor heating systems have many advantages over radiator heating systems and have become a viable method of space heating. The major players in the underfloor heating market include Uponor Corporation (Finland), Resideo Technologies Inc. (US), nVent (UK), Warmup Plc (UK), Rehau Ltd (Switzerland), Emerson Electric Co. (US), Robert Bosch GmbH (Germany), Danfoss (Denmark), Mitsubishi Electric Corporation (Japan), Siemens AG (Germany), Schneider Electric (France), and Incognito Heat Co. (UK).
Key Stakeholders
- End users
- Government bodies, venture capitalists, and private equity firms
- Underfloor heating manufacturers
- Underfloor heating distributors
- Underfloor heating industry associations
- Professional service/solution providers
- Research institutions and organizations
- Standards organizations and regulatory authorities
- System integrators
- Technology consultants
Report Objectives
- To describe and forecast the underfloor heating market, by offering, product type, installation type, application, and region, in terms of value
- To describe and forecast the underfloor heating market, by component type, in terms of volume
- To forecast the size of the market segments for four major regions, namely North America, Europe, Asia Pacific, and the Rest of the World (RoW), in terms of value
- To provide detailed information regarding the major factors influencing the growth of the market, such as drivers, restraints, opportunities, and challenges
- To offer an ecosystem analysis, case study analysis, patent analysis, technology analysis, pricing analysis, Porter’s Five Forces analysis, and regulations pertaining to the market
- To give a detailed overview of the value chain of the underfloor heating ecosystem
- To strategically analyze micromarkets with respect to individual growth trends, prospects, and contributions to the total market
- To strategically profile the key players and comprehensively analyze their market shares and core competencies
- To analyze the opportunities in the market for stakeholders and describe the competitive landscape of the market
- To study competitive developments, such as collaborations, partnerships, and product developments, in the market
- To provide the macroeconomic outlook for each region that has been covered in the report
Available customizations:
With the given market data, MarketsandMarkets offers customizations according to the company’s specific needs. The following customization options are available for the report:
Get the Full Underfloor Heating Market Report
Full forecast, segment splits, and company analysis for all Underfloor Heating Market.
- Canada Underfloor Heating Market
- Mexico Underfloor Heating Market
- US Underfloor Heating Market
- Belgium Underfloor Heating Market
- France Underfloor Heating Market
- Germany Underfloor Heating Market
- Poland Underfloor Heating Market
- Rest Of Europe Underfloor Heating Market
- UK Underfloor Heating Market
- China Underfloor Heating Market
- Japan Underfloor Heating Market
- Rest Of Asia Pacific Underfloor Heating Market
- South Korea Underfloor Heating Market
Need a Tailored Report?
Customize this report to your needs
Get 10% FREE Customization
Customize This Report