Pet Food Ingredients Market
Pet Food Ingredients Market by Ingredient (Meat & Meat Products, Cereals, Vegetables & Fruits, Fats, Additives), Source (Animal-based, Plant Derivatives, Synthetic), Pet (Dogs, Cats, Fish), Form, Nature, and Region - Global Forecast to 2031

OVERVIEW
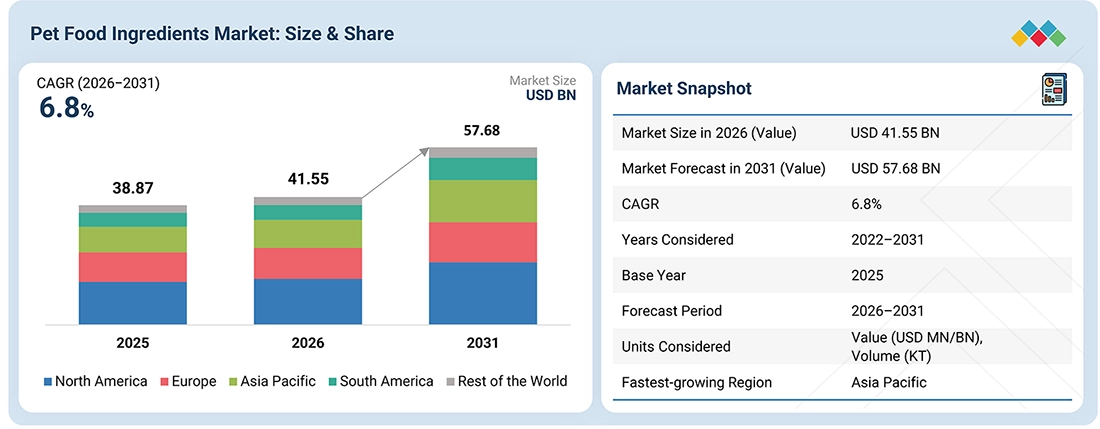
Source: Secondary Research, Interviews with Experts, MarketsandMarkets Analysis
The pet food ingredients market is projected to reach USD 57.68 billion by 2031 from USD 41.55 billion in 2026, at a CAGR of 6.8% from 2026 to 2031. The growth of this market is driven by rising pet ownership and pet humanization, increasing demand for premium and functional pet food, growing focus on pet health and nutrition, and expanding use of proteins, fibers, probiotics, vitamins, minerals, palatants, and other specialty ingredients across pet food, treats, and supplements.
KEY TAKEAWAYS
-
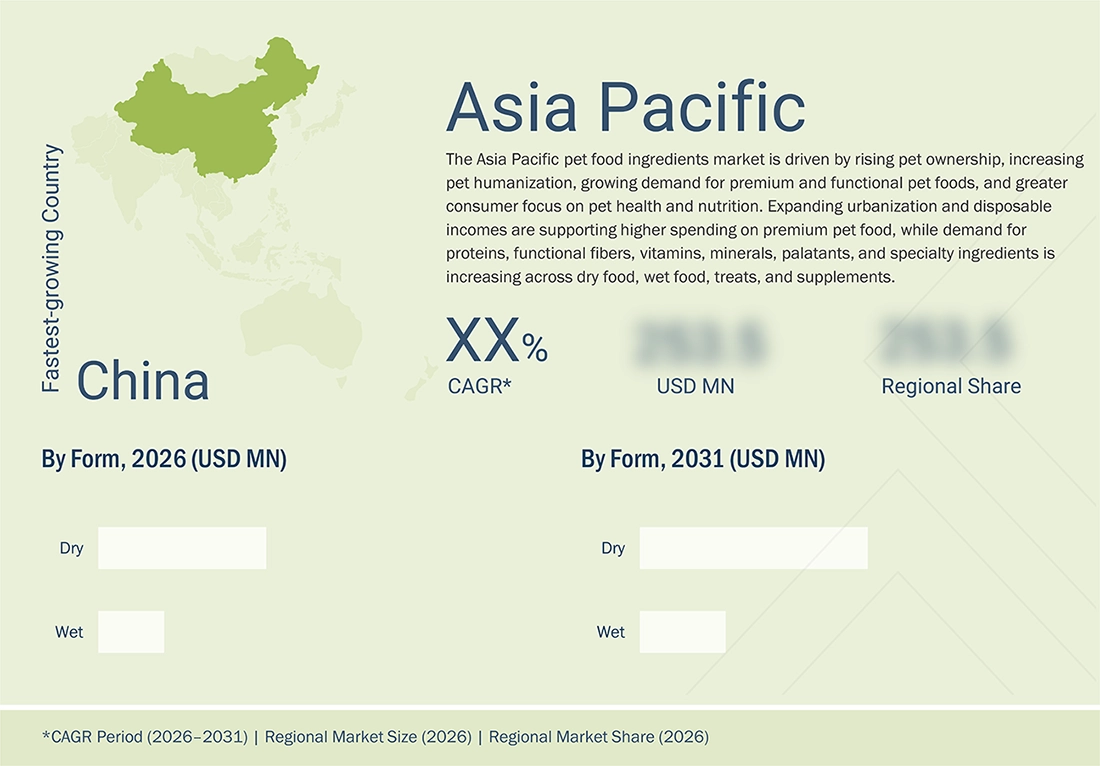
BY REGIONThe Asia Pacific region is estimated to account for 21.8% of the pet food ingredients market in 2026.
-
BY SOURCEBy source, the animal-based segment is estimated to lead the market with a share of 53.8% in 2026.
-
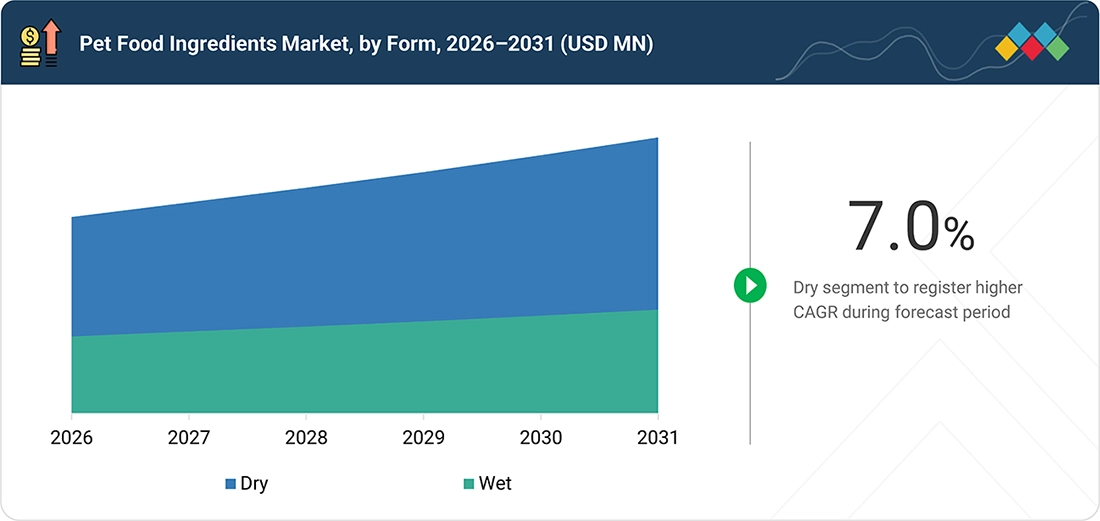
BY FORMBy form, the dry segment is projected to witness a higher CAGR of 7.0% from 2026 to 2031.
-
BY INGREDIENTBy ingredient, the meat & meat products segment is expected to hold a dominant market share during the forecast period.
-
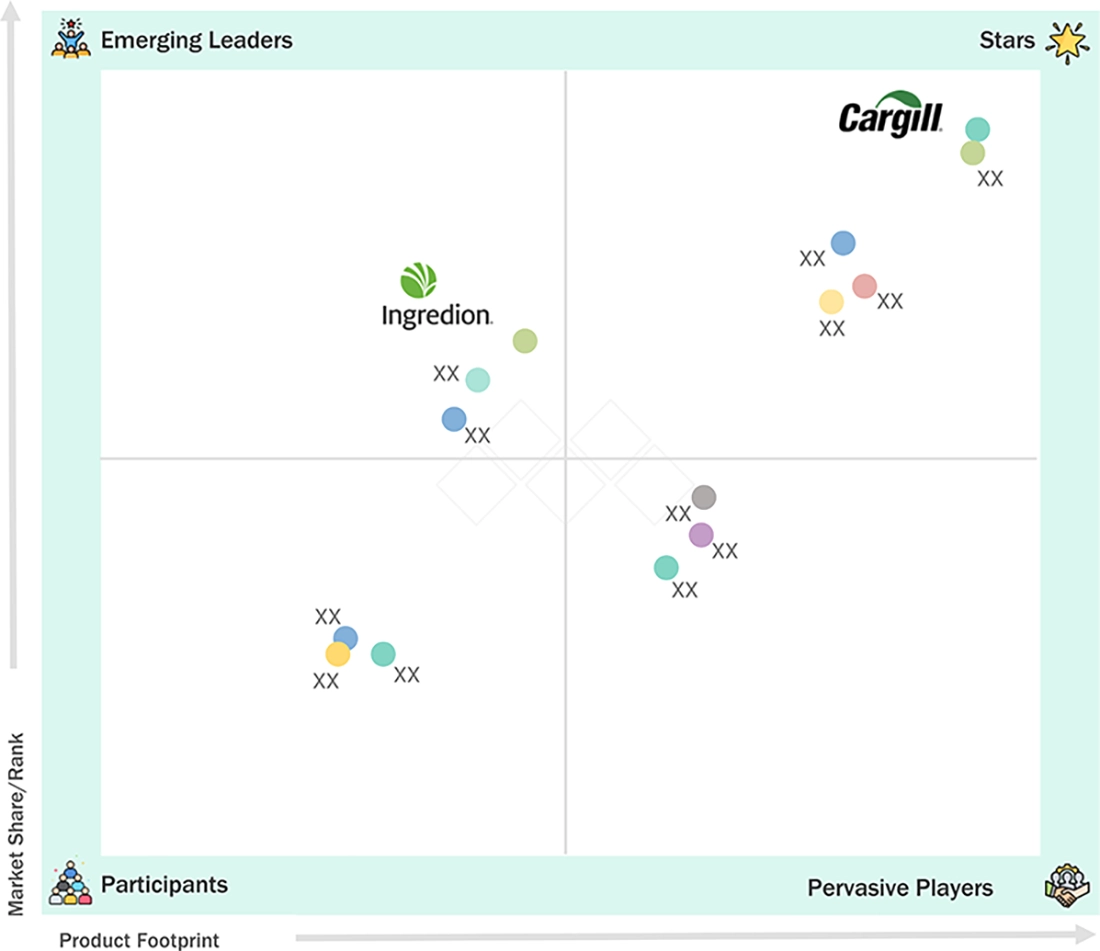
COMPETITIVE LANDSCAPE - KEY PLAYERSCargill, Incorporated (US), ADM (US), and dsm-firmenich (Netherlands) were identified as some of the star players in the pet food ingredients market (global), given their global presence and strong product footprint.
-
COMPETITIVE LANDSCAPE - STARTUPS/SMEsIngredion (US), among others, has distinguished itself among startups and SMEs by securing a strong foothold in specialized niche areas, underscoring its potential as an emerging market leader.
The pet food ingredients market is experiencing substantial growth. This is primarily driven by rising pet ownership and pet humanization, increasing demand for premium and functional pet food, a growing focus on pet health and nutrition, and the expanding use of proteins, fibers, vitamins, minerals, palatants, and other specialty ingredients across pet food, treats, and supplements.
TRENDS & DISRUPTIONS IMPACTING CUSTOMERS' CUSTOMERS
Customer business in the pet food ingredients market is influenced by the growing demand for premium, functional, natural, clean label, and sustainable pet nutrition solutions. Demand is shifting from conventional pet food ingredients toward value-added ingredient solutions, including high-quality animal proteins, plant-based proteins, functional fibers, probiotics, vitamins and minerals, and specialty nutritional ingredients. These trends are driving innovation across dry pet food, wet pet food, pet treats and snacks, veterinary diets, and specialty pet nutrition products, improving nutritional value, digestibility, palatability, pet health, ingredient transparency, and sustainability. As a result, they are influencing the revenues of pet food ingredient manufacturers, specialty ingredient suppliers, pet food brands, pet treat manufacturers, and pet food manufacturers.
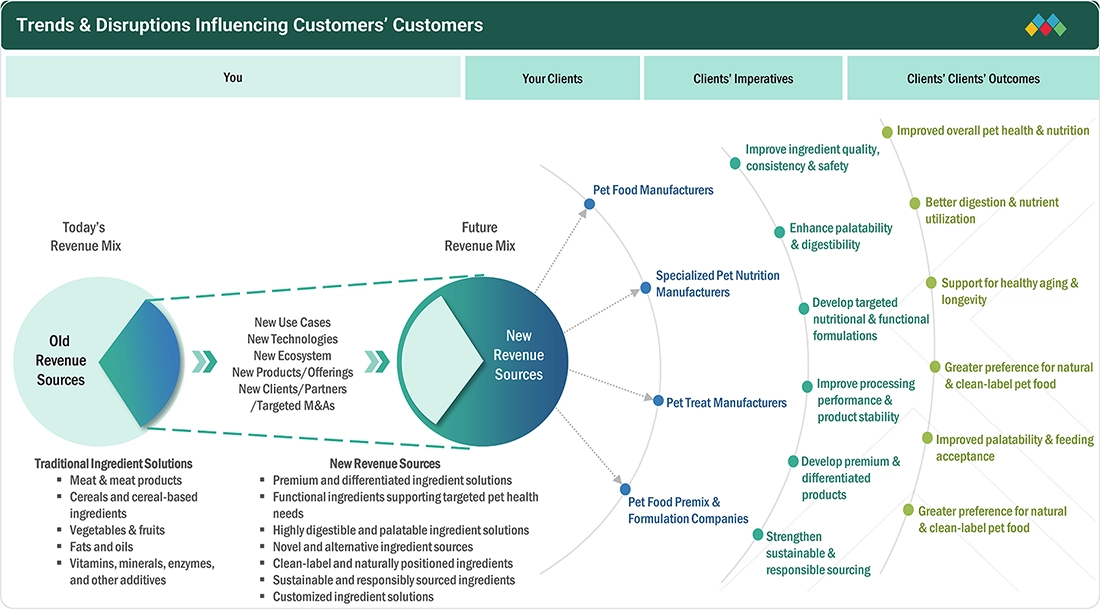
Source: Secondary Research, Interviews with Experts, MarketsandMarkets Analysis
MARKET DYNAMICS
Level
-
Increase in pet expenditure along with substantial rise in pet food expenditure

-
Growing consumer preference for natural, functional, and organic pet food ingredients

Level
-
Rising raw material price volatility and supply constraints

-
Non-uniformity of regulations hindering international trade

Level
-
Growing adoption of insect-based ingredients in pet food formulations

-
Technological advancements in ingredient development and processing

Level
-
High capital requirements for advanced ingredient processing technologies and production capacity

-
Ensuring ingredient authenticity and traceability across supply chains

Source: Secondary Research, Interviews with Experts, MarketsandMarkets Analysis
Driver: Increase in pet expenditure along with substantial rise in pet food expenditure
Rising pet ownership, pet humanization, and greater spending on premium and specialized pet nutrition are increasing demand for higher-value pet food ingredients.
Restraint: Rising raw material price volatility and supply constraints
Fluctuations in the prices and availability of meat, fish, grains, oilseeds, and other raw materials can increase ingredient production costs and create supply uncertainties.
Opportunity: Growing adoption of insect-based ingredients in pet food formulations
Increasing interest in sustainable and alternative protein sources is creating opportunities for insect-based ingredients as a protein-rich and resource-efficient option in pet food formulations.
Challenge: High capital requirements for advanced ingredient processing technologies and production capacity
Developing advanced processing, extraction, fermentation, and drying capabilities requires substantial investment in specialized equipment, facilities, and quality control infrastructure.
PET FOOD INGREDIENTS MARKET: COMMERCIAL USE CASES ACROSS INDUSTRIES
| COMPANY | USE CASE DESCRIPTION | BENEFITS |
|---|---|---|
 |
Lallemand develops and manufactures microbial and yeast-derived ingredients for companion animal nutrition. Its LALPROBIOME platform includes yeast and bacterial solutions for digestive health, immune support, antioxidant support, and other pet wellness applications, while its yeast-derived ingredients are also used as pet food palatants. | Supports digestive and immune health, pet wellbeing, palatability, and development of differentiated functional pet foods, treats, and supplements. |
 |
Kemin supplies palatants such as PALASURANCE, PALTEVA, and PALIVATE for dry and wet pet food. PALIVATE is specifically designed for wet pet food and is formulated to withstand retort processing while improving palatability. | Improves taste, aroma, and food acceptance while maintaining product integrity during processing; supports consistent consumption and product differentiation. |
Logos and trademarks shown above are the property of their respective owners. Their use here is for informational and illustrative purposes only.
MARKET ECOSYSTEM
The pet food ingredients market ecosystem is categorized into raw material suppliers, pet food ingredient manufacturers and processors, ingredient distributors and traders, pet food manufacturers and brands, specialty nutrition and formulation providers, regulatory bodies, research and testing organizations, and other demand-side stakeholders. The market is a dynamic and steadily expanding ecosystem characterized by diverse ingredient categories and growing applications across dry pet food, wet pet food, treats and snacks, veterinary diets, and specialty pet nutrition products. Established companies and emerging players are developing innovative ingredient solutions to meet increasing demand for high-quality animal-based proteins, functional ingredients, natural and clean label formulations, sustainable ingredients, and targeted pet nutrition.
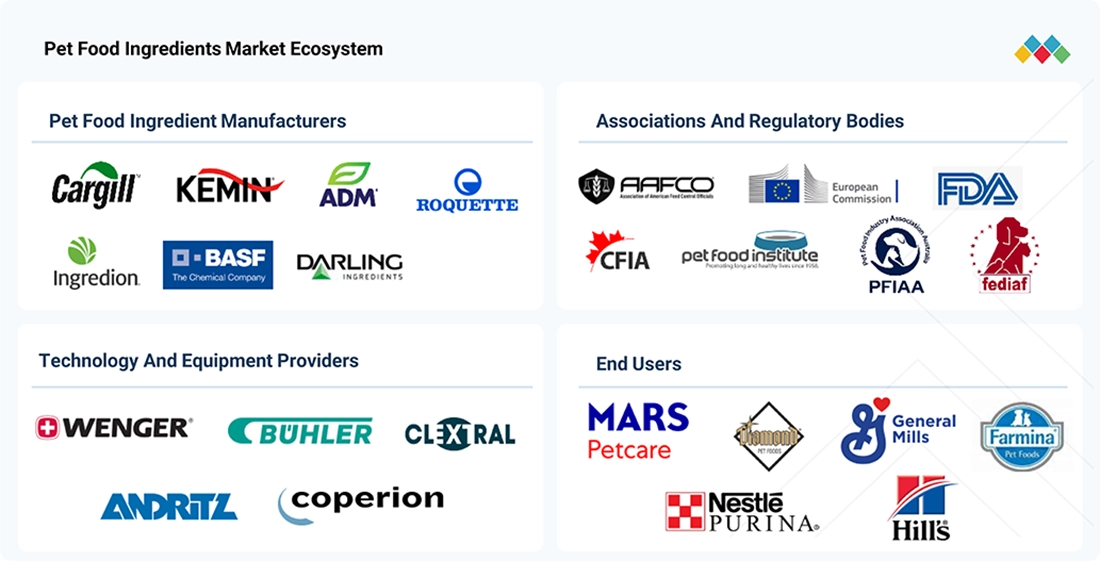
Logos and trademarks shown above are the property of their respective owners. Their use here is for informational and illustrative purposes only.
MARKET SEGMENTS
Source: Secondary Research, Interviews with Experts, MarketsandMarkets Analysis
Pet Food Ingredients Market, By Source
Animal-based ingredients dominate the market due to their high nutritional value, digestibility, palatability, and the widespread use of meat, poultry, fish, and animal-derived meals in pet food formulations.
Pet Food Ingredients Market, By Form
Dry ingredients dominate the market due to the widespread adoption of dry pet food, along with its convenience, longer shelf life, ease of storage, and cost-effectiveness for manufacturers and pet owners.
Pet Food Ingredients Market, By Ingredient
Meat & meat products dominate the market due to their high protein content, essential amino acids, palatability, and extensive use in commercial pet food formulations, particularly for dogs and cats.
REGION
Asia Pacific to be fastest-growing region in global pet food ingredients market during forecast period
The Asia Pacific pet food ingredients market is driven by rising pet ownership, increasing pet humanization, growing demand for premium and functional pet foods, and greater consumer focus on pet health and nutrition. Expanding urbanization and disposable incomes are supporting higher spending on premium pet food, while demand for proteins, functional fibers, vitamins, minerals, palatants, and specialty ingredients is increasing across dry food, wet food, treats, and supplements. The region’s expanding pet care industry and growing adoption of specialized nutrition products are further supporting market growth.
PET FOOD INGREDIENTS MARKET: COMPANY EVALUATION MATRIX
In the pet food ingredients market matrix, Cargill, Incorporated (US), ADM (US), and dsm-firmenich (Netherlands) (Stars) lead with a moderate market share and extensive product portfolios, driven by their strong global presence, strong global footprint, advanced processing capabilities, diversified application offerings, and continuous investments in innovation. Ingredion (US) (Emerging Leader) is gaining visibility through specialized solutions, strengthening its market position through innovation and expanding regional reach.
Source: Secondary Research, Interviews with Experts, MarketsandMarkets Analysis
KEY MARKET PLAYERS
- BASF SE (Germany)
- Darling Ingredients Inc. (US)
- Cargill, Incorporated (US)
- ADM (US)
- dsm-firmenich (Netherlands)
- International Flavors & Fragrances Inc. (US)
- Ingredion (US)
- Kemin Industries, Inc. (US)
- Novonesis Group (Denmark)
- Roquette Frères (France)
- The Scoular Company (US)
- Symrise (Germany)
- Mowi Nutrition (Norway)
- Lallemand Inc. (Canada)
- Phileo by Lesaffre (France)
MARKET SCOPE
| REPORT METRIC | DETAILS |
|---|---|
| Market Size in 2026 (Value) | USD 41.55 BN |
| Market Forecast in 2031 (Value) | USD 57.68 BN |
| Growth Rate | CAGR of 6.8% from 2026 to 2031 |
| Years Considered | 2022–2031 |
| Base Year | 2025 |
| Forecast Period | 2026–2031 |
| Units Considered | Value (USD Million/Billion), Volume (KT) |
| Report Coverage | Revenue Forecast, Company Ranking, Competitive Landscape, Growth Factors, and Trends |
| Segments Covered |
|
| Regions Covered | North America, Europe, Asia Pacific, South America, Rest of the World |
WHAT IS IN IT FOR YOU: PET FOOD INGREDIENTS MARKET REPORT CONTENT GUIDE
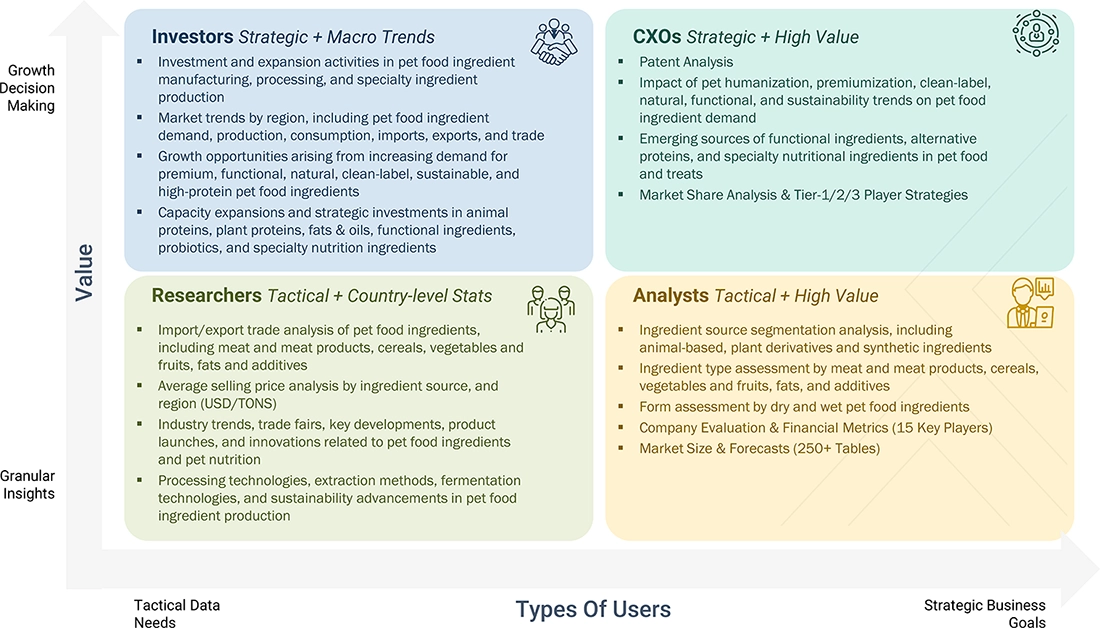
DELIVERED CUSTOMIZATIONS
We have successfully delivered the following deep-dive customizations:
| CLIENT REQUEST | CUSTOMIZATION DELIVERED | VALUE ADDS |
|---|---|---|
| Europe-based Pet Food Ingredients Manufacturer |
|
|
| Pet Food Ingredients Source Segment Assessment |
|
|
RECENT DEVELOPMENTS
- May 2026 : dsm-firmenich opened NextGen Itatiba, a fully dedicated pet nutrition premix facility in Itatiba, São Paulo, Brazil, developed in collaboration with Globalfood. The facility produces vitamin and mineral premixes for dogs and cats and serves as dsm-firmenich’s primary manufacturing and supply hub for pet nutrition in South America. The facility can blend a broad range of dry powder ingredients, enabling customized nutritional formulations for pet-food manufacturers.
- October 2025 : BASF launched Lutavit A/D3 1000/200 NXT, a next-generation animal nutrition ingredient that combines vitamin A and vitamin D3 in a single microencapsulated formulation. The product provides a consistent 5:1 vitamin A-to-D3 ratio, high stability in premixes and pellets, and an 18-month shelf life under standard storage conditions.
- January 2024 : Darling Ingredients completed the acquisition of Miropasz Group, a Polish rendering company, for a purchase price of approximately EUR 110 million (USD 119 million). Miropasz processes around 250,000 metric tons of poultry by-products annually through three rendering plants in southeastern Poland. The acquisition expanded Darling Ingredients’ rendering network in Poland and strengthened its supply of animal-derived raw materials for products including animal proteins, meals, and pet food ingredients.
Table of Contents
 Exclusive indicates content/data unique to MarketsandMarkets and not available with any competitors.
Methodology
This study involved two major approaches in estimating the current size of the pet food ingredients market. Exhaustive secondary research was conducted to collect information on the source, form, ingredient, pet, nature, and regional segments of the market. The next step involved validating these findings, assumptions, and sizing with industry experts across the value chain through primary research. Both top-down and bottom-up approaches were employed to estimate the complete market size. Thereafter, data triangulation was used to estimate the market size of segments and subsegments.
Secondary Research
This research study involved the use of extensive secondary sources—directories and databases such as Bloomberg Businessweek and Factiva—to identify and collect information useful for a technical, market-oriented, and commercial market study. In the secondary research process, sources such as annual reports, press releases & investor presentations of companies, white papers, pet food journals, certified publications, articles from recognized authors, directories, and databases were referred to to identify and collect information. Secondary research was mainly used to obtain key information about the industry’s supply chain, the pool of key players, and market classification and segmentation as per the industry trends to the bottom-most level, regional markets, and key developments from market- and technology-oriented perspectives.
Primary Research
Extensive primary research was conducted after obtaining information regarding the pet food ingredients market scenario through secondary research. Several primary interviews were conducted with market experts from the demand and supply sides across major countries of North America, Europe, Asia Pacific, South America, and the Rest of the World. Primary data were collected through questionnaires, emails, and telephonic interviews. The primary sources from the supply side included various industry experts, such as chief experience officers (CXOs), vice presidents (VPs), directors from business development, marketing, research, and development teams, and related key executives from distributors and key opinion leaders. Primary interviews were conducted to gather insights such as market statistics, data on revenue collected from the products and services, market breakdowns, market size estimations, market forecasting, and data triangulation. Primary research also helped understand the various trends related to the source, form, ingredient, pet, nature, and regional segments. Stakeholders from the demand side, such as pet food manufacturers, pet food brands, contract manufacturers, veterinary diet manufacturers, pet treat manufacturers, and pet nutrition product formulators, were interviewed to understand buyers’ perspectives on pet food ingredients, ingredient specifications, formulation requirements, quality and regulatory requirements, pricing, procurement practices, supply availability, and the outlook of their businesses, which will affect the overall market.
Breakdown Of Primary Interviews
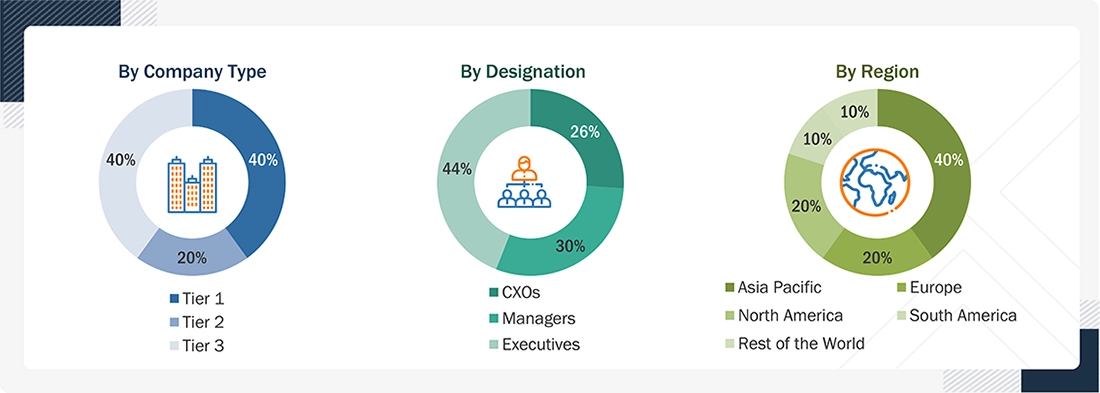
Note: The three tiers of the companies are defined based on their total revenues in 2024 or 2025, as per the availability of financial data: Tier 1: Revenue >USD 1 billion; Tier 2: USD 100 million ≤ revenue ≤ USD 1 billion; Tier 3: Revenue <USD 100 million. Rest of the World includes Africa and the Middle East.
|
COMPANY NAME |
DESIGNATION |
|
Cargill, Incorporated |
Product Development Manager |
|
dsm-firmenich |
Sales Head |
|
Kemin Industries Inc. |
Marketing Head |
|
Phileo by Lesaffre |
Sales Head |
|
Ingredion |
Senior Research Executive |
|
Lallemand Inc. |
Business Development Manager |
To know about the assumptions considered for the study, download the pdf brochure
Market Size Estimation
The top-down and bottom-up approaches were used to estimate and validate the total size of the pet food ingredients market. These approaches were also used extensively to determine the size of various subsegments in the market. The research methodology used to estimate the market size includes the following details:
- The key players in the industry and the overall market were identified through extensive secondary research.
- All shares, splits, and breakdowns were determined using secondary sources and verified through primary sources.
- All possible parameters that affect the market covered in this research study were accounted for, viewed in extensive detail, verified through primary research, and analyzed to obtain final quantitative and qualitative data.
- The research included the study of reports, reviews, and newsletters of top market players, along with extensive interviews for opinions from leaders, such as CEOs, directors, and marketing executives.
Pet Food Ingredients Market: Top-Down and Bottom-Up Approach

Data Triangulation
After determining the overall market size from the estimation process explained above, the total market was split into several segments and subsegments. The data triangulation procedure was employed, wherever applicable, to estimate the overall pet food ingredients market and arrive at the exact statistics for all segments and subsegments. The data were triangulated by studying various factors and trends from the demand and supply sides. The market size was also validated using both the top-down and bottom-up approaches.
Market Definition
According to the Association of American Feed Control Officials (AAFCO), a pet food manufacturer is allowed to claim its food as “complete and balanced” by meeting an AAFCO nutrient profile (dog or cat) or by passing a feeding trial. All ingredients used in pet food must be appropriate for the pet, and all pet food must be acceptable either by the AAFCO ingredients definition process or by the Food and Drug Administration–Center for Veterinary Medicine (FDA-CVM) or be self-affirmed Generally Recognized as Safe (GRAS).
Standard quality food ingredients provide the proper balance of nutrition to pets. It helps them to meet their need for a certain combination of proteins, carbohydrates, fats, vitamins, minerals, and water to function normally. A proper pet food ingredient has advantages such as improvement in muscle tone and body condition, keeping skin and haircoat healthy, enhancement in digestion, and prevention of diseases.
Key Stakeholders
- Raw material suppliers, including producers and processors of meat, animal by-products, fish, cereals, grains, vegetables, fruits, oilseeds, and other raw materials used in pet food ingredient production
- Pet food ingredient manufacturers and processors, including producers of animal-based proteins, meat meals, plant proteins, cereals, fats & oils, vitamins, minerals, enzymes, and other specialty ingredients
- Intermediate stakeholders, including ingredient distributors, traders, importers/ exporters, contract manufacturers, logistics providers, packaging suppliers, and storage providers
- Pet food manufacturers and brands, including producers of dry pet food, wet pet food, pet treats and snacks, veterinary diets, and specialty pet nutrition products
- Pet food ingredient solution providers and formulation specialists, including specialty ingredient manufacturers, premix providers, nutrition consultants, and formulation service providers
- Government organizations and regulatory authorities, responsible for pet food safety, ingredient approval, labeling, quality standards, feed safety, and regulatory compliance
- Research institutions, universities, veterinary institutions, and testing laboratories, involved in pet nutrition research, ingredient development, digestibility studies, efficacy evaluation, food safety, and quality testing
- Pet nutritionists, veterinarians, R&D scientists, formulation specialists, and quality assurance professionals, responsible for ingredient selection, formulation development, nutritional assessment, safety evaluation, and quality control
- Industry associations and certification organizations, promoting responsible sourcing, feed safety, sustainability, quality standards, and best practices across the pet food industry
-
Associations and industry bodies:
- Association of American Feed Control Officials (AAFCO)
- US Food and Drug Administration – Center for Veterinary Medicine (FDA-CVM)
- European Pet Food Industry Federation (FEDIAF)
- European Food Safety Authority (EFSA)
- US Department of Agriculture (USDA)
- Food and Agriculture Organization (FAO)
- Pet Food Institute (PFI)
- Global Alliance of Pet Food Associations (GAPFA)
- Pet Food Manufacturers' Association (PFMA), UK
- Pet Food Industry Association of Australia (PFIAA)
- International Organization for Standardization (ISO)
Report Objectives
- To determine and project the size of the pet food ingredients market based on source, form, ingredient, pet, nature, and region, over five years, ranging from 2026 to 2031
- To identify the attractive opportunities in the market by determining the largest and fastest-growing segments across regions
- To provide detailed information about the key factors influencing market growth (drivers, restraints, opportunities, and challenges)
- To analyze the opportunities in the market for stakeholders and provide details of the competitive landscape for market leaders
- To analyze the micromarkets with respect to individual growth trends, prospects, and their contribution to the total market
- To identify and profile the key players in the market
- To understand the competitive landscape and identify the major growth strategies adopted by players across the key regions
Available customizations:
With the given market data, MarketsandMarkets offers customizations according to company-specific scientific needs. The following customization options are available for the report:
Product Analysis
-
Product matrix, which gives a detailed comparison of the product portfolio of each company.
Geographic Analysis
- Further breakdown of the Rest of Europe pet food ingredients market into key countries
- Further breakdown of the Rest of Asia Pacific pet food ingredients market into key countries
- Further breakdown of the Rest of South America pet food ingredients market into key countries
Company Information
-
Detailed analyses and profiling of additional market players (up to five)

Personalize This Research
- Triangulate with your Own Data
- Get Data as per your Format and Definition
- Gain a Deeper Dive on a Specific Application, Geography, Customer or Competitor
- Any level of Personalization
Let Us Help You
- What are the Known and Unknown Adjacencies Impacting the Pet Food Ingredients Market
- What will your New Revenue Sources be?
- Who will be your Top Customer; what will make them switch?
- Defend your Market Share or Win Competitors
- Get a Scorecard for Target Partners

Custom Market Research Services
We Will Customise The Research For You, In Case The Report Listed Above Does Not Meet With Your Requirements
Get 10% Free CustomisationTESTIMONIALS

Business Innovation Director
US Based Leading Agribusiness,
Food and Ingredients ManufacturerI highly appreciate the team's efficiency for a well conducted study that helped us clarify some blind spots in food and agricultural niche markets. Although compiling information for B2B markets is very difficult, the MnM team pulled out the task successfully. The quality of research, level of insights, and responsiveness of team were commendable.
- Canada Pet Food Ingredients Market
- Mexico Pet Food Ingredients Market
- US Pet Food Ingredients Market
- China Pet Food Ingredients Market
- Japan Pet Food Ingredients Market
- India Pet Food Ingredients Market
- Germany Pet Food Ingredients Market
- Russia Pet Food Ingredients Market
- UK Pet Food Ingredients Market
- France Pet Food Ingredients Market
- Italy Pet Food Ingredients Market
- Brazil Pet Food Ingredients Market
- Argentina Pet Food Ingredients Market
- Rest Of Europe Pet Food Ingredients Market
- Rest Of Asia Pacific Pet Food Ingredients Market
- Rest Of South America Pet Food Ingredients Market
Growth opportunities and latent adjacency in Pet Food Ingredients Market


User
Jan, 2020
Interested to understand more about the regulatory environment by country for this Pet Food Ingredients Market..
Vanessa
Apr, 2019
Need data on imports of ingredients for pet food into the US..
Tom
Feb, 2019
Interested in market information regarding cut meat & meat Products by animal type - poultry, beef, lamb, seafood. What is the Deboned Poultry market worth?.
ELIZABETH
Sep, 2019
Interested in individual sections/tables from this report. .
William
Jul, 2019
Looking for more detailed information on the pet food ingredients market specific to each ingredient market segment and region..
Nourreddine
Jul, 2019
As a pet food manufacturer, interested in detailed market information.
Amey
Mar, 2018
Interested in company profiles of raw material suppliers and traders in India..
Hsiu-Ying
Feb, 2019
Interested in analyzing the market of products related to pet food industry..