Fungicides Market

Fungicides Market by Type (Chemical and Biological), Mode of Action (Contact and Systemic), Formulation (Liquid and Dry), Mode of Application (Foliar Spray, Seed Treatment, and Soil Treatment), Crop Type, and Region - Global Forecast To 2031


OVERVIEW
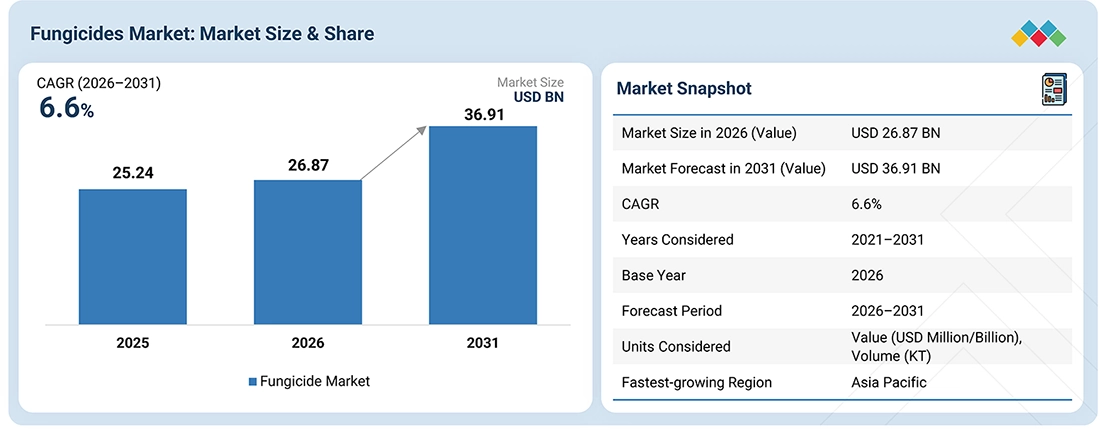
Source: Secondary Research, Interviews with Experts, MarketsandMarkets Analysis
The fungicides market is estimated at USD 26.87 billion in 2026 and is projected to reach USD 36.91 billion by 2031, at a CAGR of 6.6%. The fungicides market is expected to grow as farmers increasingly seek effective solutions to protect crops from fungal diseases and minimize yield losses.
KEY TAKEAWAYS
-
BY REGIONAsia Pacific is projected to contribute the largest share of 31.0% in 2026 in the fungicides market.
-
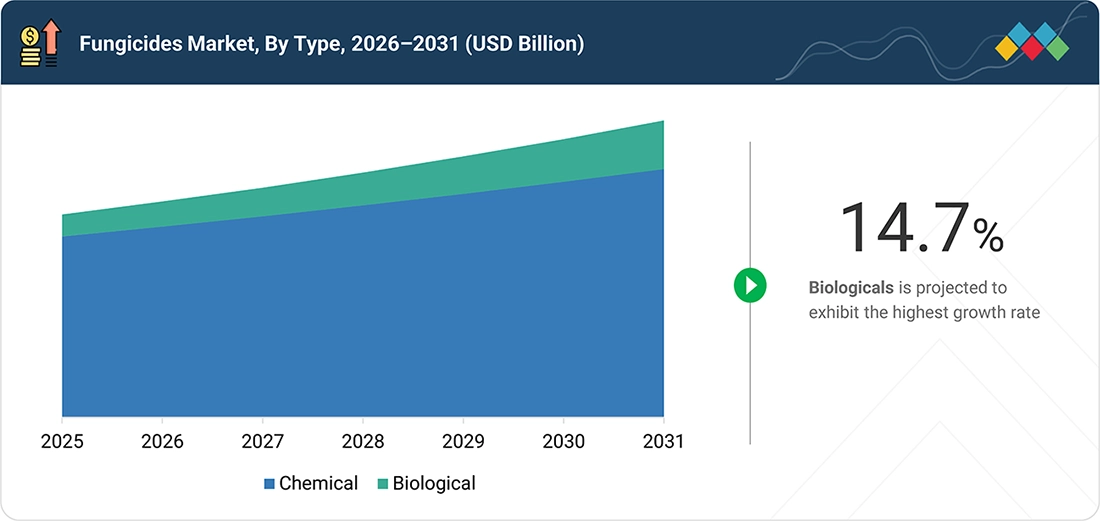
BY TYPEBased on type, the biological segment is anticipated to dominate the market, with a CAGR of 14.7% during the forecast period 2026–2031.
-
BY MODE OF APPLICATIONThe seed treatment segment of the fungicides market, by mode of application, is projected to witness the highest CAGR of 7.2% during the forecast period.
-
BY FORMULATIONLiquid is projected to contribute the largest share of 66.0% in 2026.
-
BY CROP TYPECereals and grains is projected to grow at the fastest CAGR of 6.8% from 2026 to 2031.
-
COMPETITIVE LANDSCAPE - KEY PLAYERSBASF SE (Germany), Bayer AG (Germany), Syngenta Group (Switzerland), Corteva Agriscience (US), FMC Corporation (US), UPL Limited (India), Nufarm Limited (Australia), Sumitomo Chemical Co., Ltd. (Japan), Nippon Soda Co., Ltd. (Japan), Kumiai Chemical Industry Co., Ltd. (Japan), American Vanguard Corporation (US), Albaugh LLC (US), Gowan Company (US), Sipcam Oxon (Italy), and Sharda Cropchem Limited (India).
-
COMPETITIVE LANDSCAPE - STARTUPS/SMESRobigo, Ascribe Bio, Biotalys, AgPlenus, and CEV S.A. are emerging players in the fungicides market, offering specialty active ingredients and expanding their presence across international markets.
The fungicides market is estimated at USD 26.87 billion in 2026 and is projected to reach USD 36.91 billion by 2031, at a CAGR of 6.6% from 2026 to 2031. The global fungicides market is expected to grow as rising food demand and the need to improve agricultural productivity increase the importance of effective crop disease management. Fungal diseases can significantly reduce crop yields, affect product quality, and cause post-harvest losses, encouraging farmers to adopt fungicides across cereals and grains, fruits and vegetables, oilseeds, and other crops.
TRENDS & DISRUPTIONS IMPACTING CUSTOMERS' CUSTOMERS
The fungicides market is evolving as agricultural input companies, agrochemical retailers, distributors, and precision agriculture solution providers respond to increasing demand for effective fungal disease control, resistance management, and sustainable crop protection. Today's revenue mix is primarily associated with conventional chemical fungicides, differentiated by type, formulation, crop type, mode of application, and source, while future revenue opportunities are expected to emerge from biological fungicides, novel modes of action, advanced formulations, and new crop protection technologies. Manufacturers are focusing on improving product performance, accelerating product development, and strengthening distribution networks to meet changing customer requirements. At the same time, clients increasingly prioritize improved crop yield and quality, regulatory compliance, residue management, formulation stability, product compatibility, and reliable supply.
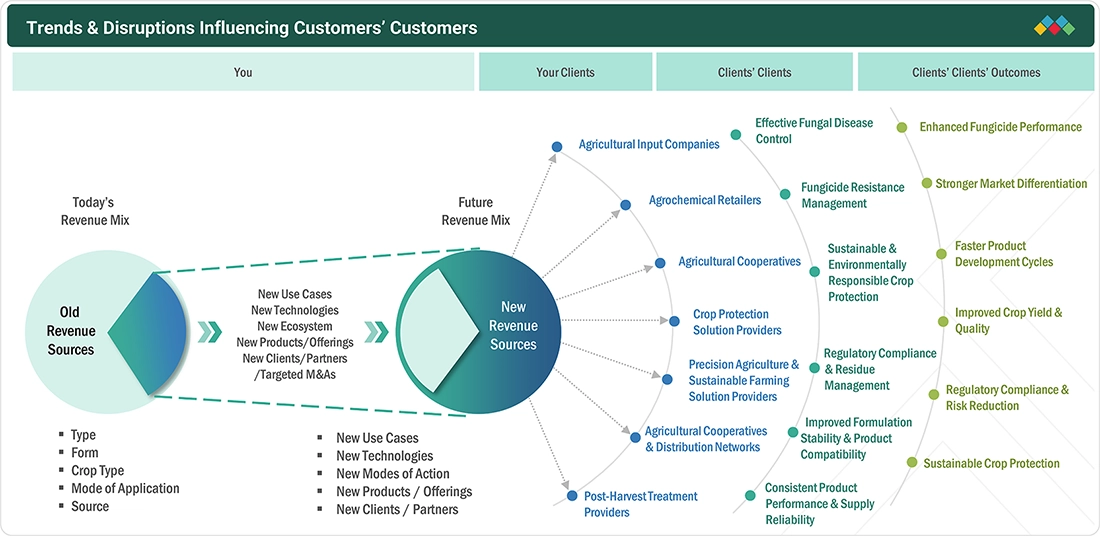
Source: Secondary Research, Interviews with Experts, MarketsandMarkets Analysis
MARKET DYNAMICS

Level
-
Rising temperatures and changing climatic conditions leading to outbreaks of crop diseases

-
Innovation and technological advancement


Level
-
Risk of exceeding maximum residue limits (MRLs) in agricultural produce

-
Fungicide residue concerns and increasing scrutiny of food safety and pesticide use


Level
-
Integration of fungicides with precision agriculture

-
Introduction of new biological fungicides


Level
-
Long approval periods for fungicide products

-
Growing resistance to fungicides

Source: Secondary Research, Interviews with Experts, MarketsandMarkets Analysis
Driver: Rising temperatures and changing climatic conditions leading to outbreaks of crop diseases
Rising temperatures and changing climatic conditions are increasing the risk of fungal diseases in agricultural crops, driving demand for effective fungicides. Increased disease pressure encourages farmers to adopt crop protection solutions to minimize yield losses and maintain crop quality.
Restraint: Risk of exceeding maximum residue limits (MRLs) in agricultural produce
The risk of exceeding maximum residue limits (MRLs) in agricultural produce restrains fungicide market growth. Residue concerns can limit the use of certain products, particularly in export-oriented crops, where compliance with food safety standards and regulatory requirements is essential.
Opportunity: Integration of fungicides with precision agriculture
The integration of fungicides with precision agriculture technologies presents growth opportunities for the market. Digital disease monitoring, targeted spraying, and data-driven application methods can help farmers optimize fungicide use, improve disease control, and reduce unnecessary applications.
Challenge: Long approval periods for fungicide products
Long approval and registration periods pose a challenge for fungicide manufacturers. Extensive testing and regulatory requirements can increase development costs, delay product launches, and make it more difficult for companies to introduce new active ingredients and innovative disease-control solutions.
FUNGICIDES MARKET: COMMERCIAL USE CASES ACROSS INDUSTRIES
| COMPANY | USE CASE DESCRIPTION | BENEFITS |
|---|---|---|
 |
Development and commercialization of chemical and biological fungicides for the prevention and control of fungal diseases across cereals, fruits, vegetables, and other field crops. | Improves disease control efficacy, protects crop yield and quality, supports resistance management, and enhances crop productivity through targeted disease protection solutions. |
 |
Development of fungicide active ingredients and formulated products for foliar disease control, seed treatment, and disease management across major agricultural crops. | Enhances disease suppression, supports consistent crop performance, improves yield protection, and provides farmers with effective solutions for managing fungicide resistance. |
 |
Commercialization of chemical and biological fungicides for integrated disease management in cereals, fruits, vegetables, and specialty crops. | Strengthens crop protection, reduces fungal disease-related yield losses, supports integrated crop management, and improves crop quality and production reliability. |
 |
Development and supply of conventional and biological fungicides for managing fungal diseases across field crops, horticultural crops, and plantation crops. | Broadens disease management options, supports integrated and sustainable crop protection, helps maintain crop health and yield, and provides solutions for diverse farming systems. |
Logos and trademarks shown above are the property of their respective owners. Their use here is for informational and illustrative purposes only.
MARKET ECOSYSTEM
The fungicides market ecosystem comprises four key stakeholder groups: fungicide manufacturers, raw material suppliers, regulatory bodies and associations, and research and academic institutes. Major manufacturers, including BASF, Syngenta, and Bayer, develop and commercialize fungicides for controlling fungal diseases across agricultural crops. Raw material suppliers such as Syensqo, Clariant, and Evonik provide chemical ingredients and formulation components that support fungicide manufacturing. Regulatory bodies, including the US Environmental Protection Agency (EPA), the European Food Safety Authority (EFSA), and Australia's Department of Agriculture, Fisheries and Forestry, oversee product registration, safety, and environmental compliance. Research organizations and industry associations, such as the Fungicide Resistance Action Committee (FRAC) and the American Phytopathological Society (APS), contribute to disease research, resistance management, and the advancement of crop protection practices. Together, these stakeholders support product development, regulatory compliance, innovation, and the effective use of fungicides.
Logos and trademarks shown above are the property of their respective owners. Their use here is for informational and illustrative purposes only.
MARKET SEGMENTS
Source: Secondary Research, Interviews with Experts, MarketsandMarkets Analysis
Fungicides Market, By Mode of Action
Contact fungicides are gaining traction because they provide protective coverage on plant surfaces and help prevent fungal pathogens from establishing infections. Their use in preventive disease management across various crops supports demand, although effectiveness depends on adequate coverage and timely application.
Fungicides Market, By Mode of Application
The seed treatment segment is growing as farmers increasingly adopt preventive crop protection to safeguard seeds and seedlings against seed- and soil-borne fungal diseases. Fungicide-treated seeds can support better crop establishment, reduce early disease-related losses, and provide targeted protection during the initial stages of plant growth.
Fungicides Market, By Type
Chemical fungicides are witnessing growth due to their established efficacy, broad disease-control capabilities, and widespread adoption in commercial agriculture. Continued development of new active ingredients, combination products, and resistance-management solutions supports their use across major crop categories.
Fungicides Market, By Formulation
The dry formulation segment is growing due to its ease of storage, handling, transportation, and application. Formulations such as wettable powders, water-dispersible granules, and dusts offer flexibility across different crop protection practices. Their relatively stable storage characteristics and suitability for various application methods support adoption among farmers, particularly in markets where cost-effective and convenient fungicide solutions are important.
Fungicides Market, By Crop Type
The cereals and grains segment is growing because these crops are essential to global food security and are vulnerable to fungal diseases that can reduce yields and grain quality. Rising demand for higher agricultural productivity and the need to manage diseases such as rusts, smuts, blights, and certain seed-borne infections are supporting fungicide use in these crops.
REGION
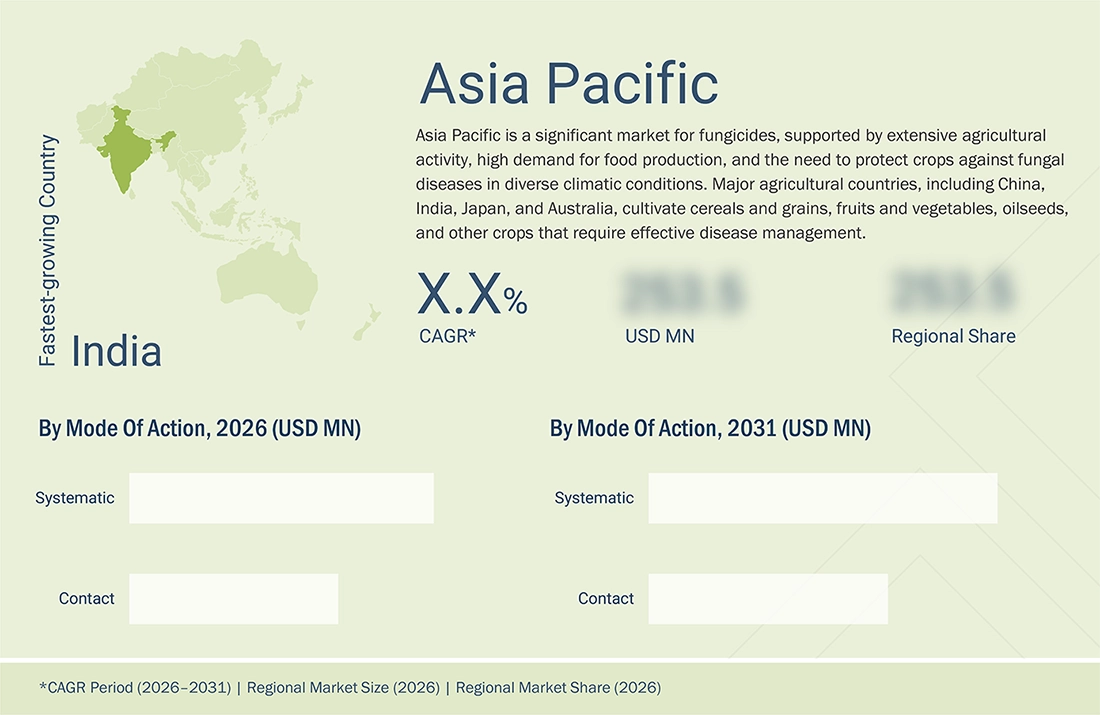
Asia Pacific to be the fastest-growing region in the fungicides market during the forecast period
The Asia Pacific fungicides market is growing due to extensive agricultural activity, rising food demand, and the increasing need to protect crops from fungal diseases. Countries such as China and India have large agricultural sectors, while diverse climatic conditions, including high humidity and monsoon rainfall, can increase disease pressure across major crops. Growing awareness of crop protection, increasing adoption of modern farming practices, and the need to improve crop yields and quality are further supporting fungicide demand. In addition, expanding agricultural production and the availability of chemical and biological crop protection solutions are creating opportunities for market growth across the region.
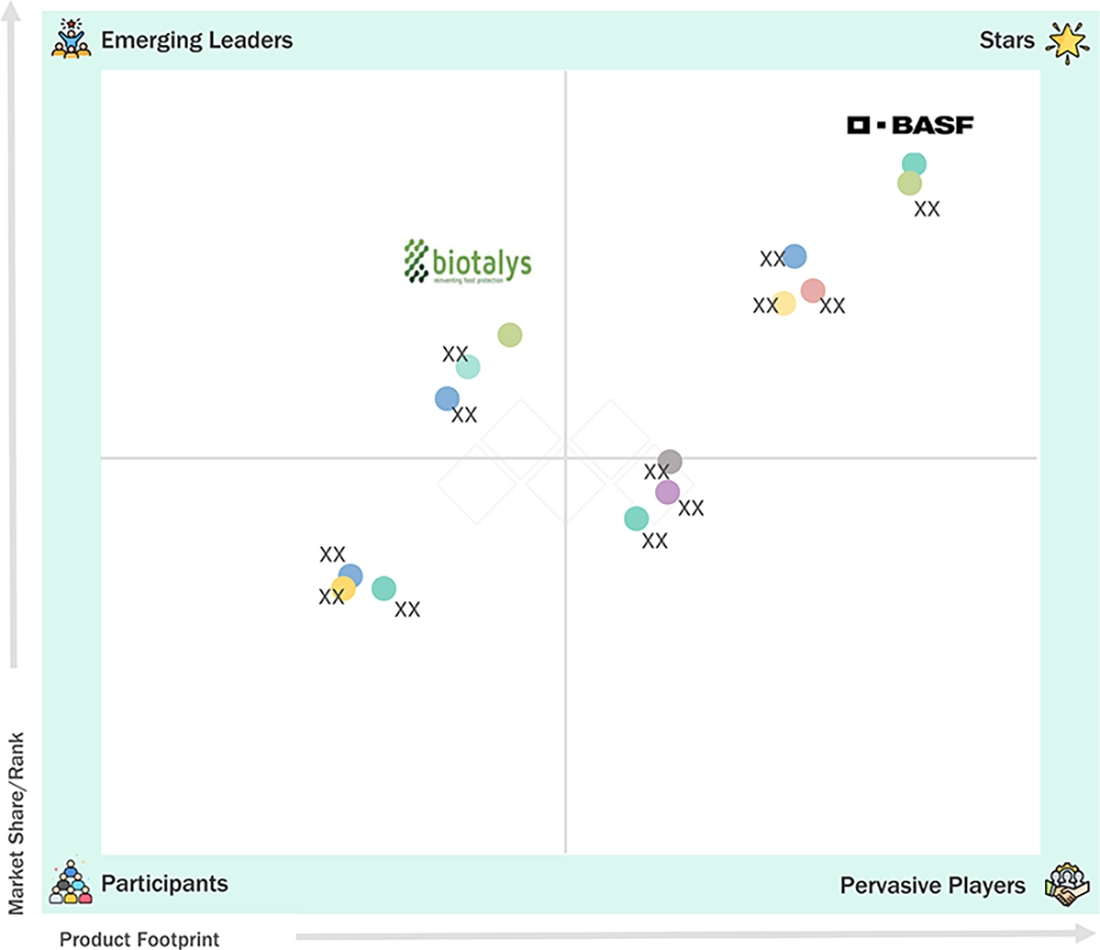
FUNGICIDES MARKET: COMPANY EVALUATION MATRIX
BASF SE is considered a star player in the global fungicides market, supported by its extensive crop protection portfolio, established global presence, and continued investment in research and development. The company offers fungicides for a wide range of crops and fungal diseases, focusing on product innovation, disease-control efficacy, and resistance management. In contrast, Biotalys is an emerging player developing protein-based biological crop protection solutions. Its technology platform aims to provide alternative approaches to managing crop diseases while supporting more sustainable agriculture.
Source: Secondary Research, Interviews with Experts, MarketsandMarkets Analysis
KEY MARKET PLAYERS
- BASF SE (Germany)
- Bayer AG (Germany)
- Syngenta Group (Switzerland)
- Corteva Agriscience (US)
- FMC Corporation (US)
- UPL Limited (India)
- Nufarm Limited (Australia)
- Sumitomo Chemical Co., Ltd. (Japan)
- Nippon Soda Co., Ltd. (Japan)
- Kumiai Chemical Industry Co., Ltd. (Japan)
- American Vanguard Corporation (US)
- Albaugh LLC (US)
- Gowan Company (US)
- Sipcam Oxon (Italy)
- Sharda Cropchem Limited (India)
MARKET SCOPE
| REPORT METRIC | DETAILS |
|---|---|
| Market Size in 2026 (Value) | USD 26.87 Billion |
| Market Forecast in 2031 (Value) | USD 36.91 Billion |
| Growth Rate | CAGR of 6.6% during 2026–2031 |
| Years Considered | 2021–2031 |
| Base Year | 2026 |
| Forecast Period | 2026–2031 |
| Units Considered | Value (USD Million/Billion), Volume (KT) |
| Report Coverage | Revenue forecast, company ranking, competitive landscape, growth factors, and trends |
| Segments Covered |
|
| Regions Covered | North America, South America, Europe, Asia Pacific, Rest of the World |
WHAT IS IN IT FOR YOU: FUNGICIDES MARKET REPORT CONTENT GUIDE
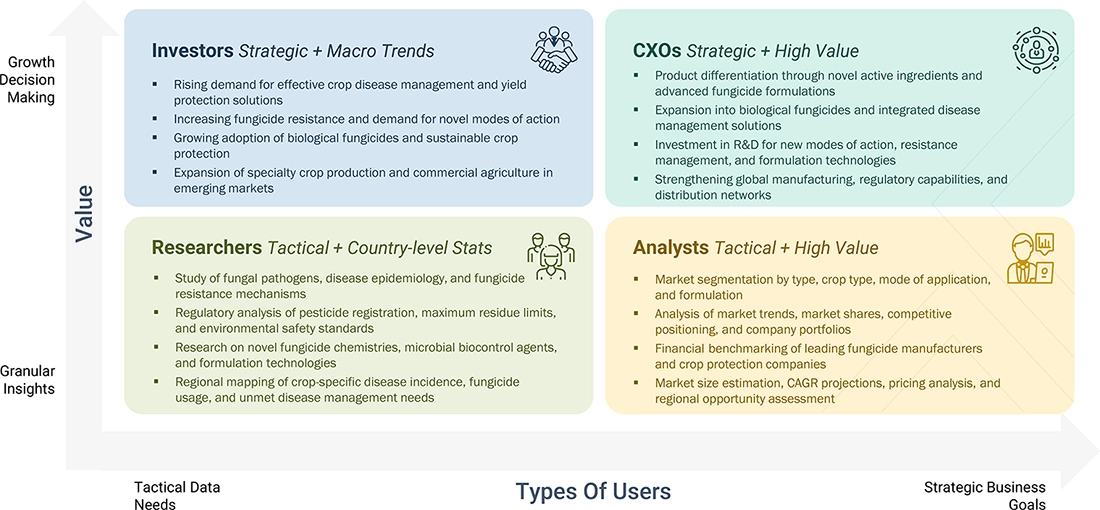
DELIVERED CUSTOMIZATIONS
We have successfully delivered the following deep-dive customizations:
| CLIENT REQUEST | CUSTOMIZATION DELIVERED | VALUE ADDS |
|---|---|---|
| Global Fungicide Manufacturer | Competitive benchmarking of leading chemical and biological fungicide players, including BASF, Bayer, Syngenta, Corteva, and FMC; regulatory compliance analysis across the US EPA, EU, and Asia Pacific; market segmentation by fungicide type, mode of action, formulation, crop type, application, and geography. | Identified growth opportunities across cereals and grains, fruits and vegetables, oilseeds and pulses, and other crops; tracked adoption of chemical and biological fungicides; highlighted novel modes of action, resistance management, advanced formulations, and sustainable crop protection trends. |
| Globally Focused Distributor | Evaluation of distribution channels, supplier networks, and partnerships across North America, Europe, and Asia Pacific; supply chain efficiency and logistics analysis; market mapping by fungicide type, crop, application, formulation, and geography. | Identified potential distribution partners and regional expansion opportunities; highlighted country-level demand for chemical and biological fungicides; provided insights into regional adoption trends, supply networks, product availability, and commercial strategies. |
| Global Crop Protection / Specialty Chemicals Company | Mapping of global R&D pipelines for chemical and biological fungicides; analysis of regulatory timelines, product registrations, and approvals across key markets; competitor strategy assessment covering portfolio expansion, manufacturing capacity, geographic expansion, and innovation. | Highlighted emerging companies and innovation opportunities in chemical and biological fungicides; identified opportunities related to resistance management and sustainable disease control; provided adoption trends across foliar application, seed treatment, soil treatment, and post-harvest disease management. |
| Investor / Private Equity Firm | Pipeline and innovation mapping of leading global fungicide companies; evaluation of M&A, joint ventures, partnerships, investments, and capacity expansions; financial, competitive, and market-positioning analysis of key players. | Identified potential acquisition targets across chemical fungicides, biological fungicides, and specialty crop protection segments; tracked opportunities in novel active ingredients, biological disease-control technologies, and advanced formulations; provided strategic insights to support investment decisions in the global fungicides market. |
RECENT DEVELOPMENTS
- April 2026 : Balaya®: BASF launched a dual-active fungicide in Australia, combining Revysol® and F500 to control more than 20 foliar diseases in cereals, pulses, and canola. The product provides up to seven weeks of residual protection and supports fungicide resistance management.
- February 2026 : Botanical-based biofungicide: Syngenta announced plans to bring a botanical-based biofungicide inspired by the saponin-rich bark traditionally used by the Mapuche people of Chile to the Americas, expanding its biological crop protection portfolio.
- January 2026 : Gilboa® fungicide: The companies entered into a co-development and commercialization agreement for fungicide formulations based on ADAMA's Gilboa (flumetylsulforim) active ingredient. The collaboration aims to develop disease management solutions for European cereal growers, with launches planned in Great Britain in 2027 and broader Europe in 2029, subject to registration.
- March 2023 : Vertellus acquired CENTAURI Technologies and simultaneously changed its corporate name and brand from Vertellus to Aurorium, adding specialty-material capabilities and manufacturing capacity.
Table of Contents
 Exclusive indicates content/data unique to MarketsandMarkets and not available with any competitors.
Methodology
The study involved four major activities in estimating the current size of the fungicides market. Exhaustive secondary research was done to collect information on the market, peer market, and parent market. The next step was to validate these findings, assumptions, and sizing with industry experts across the value chain through primary research. Both the top-down and bottom-up approaches were employed to estimate the complete market size. After that, data triangulation was used to estimate the market size of segments and subsegments.
Secondary Research
This research study involved the extensive use of secondary sources—directories and databases such as Bloomberg Businessweek and Factiva—to identify and collect information useful for a technical, market-oriented, and commercial study of the fungicides market.
In the secondary research process, various sources such as annual reports, press releases & investor presentations of companies, white papers, certified publications, articles from recognized authors, gold & silver standard websites, directories, and databases were referred to identify and collect information.
Secondary research was mainly used to obtain key information about the industry’s supply chain, the total pool of key players, and market classification and segmentation as per industry trends to the bottom-most level, regional markets, and key developments from both market- and technology-oriented perspectives.
Primary Research
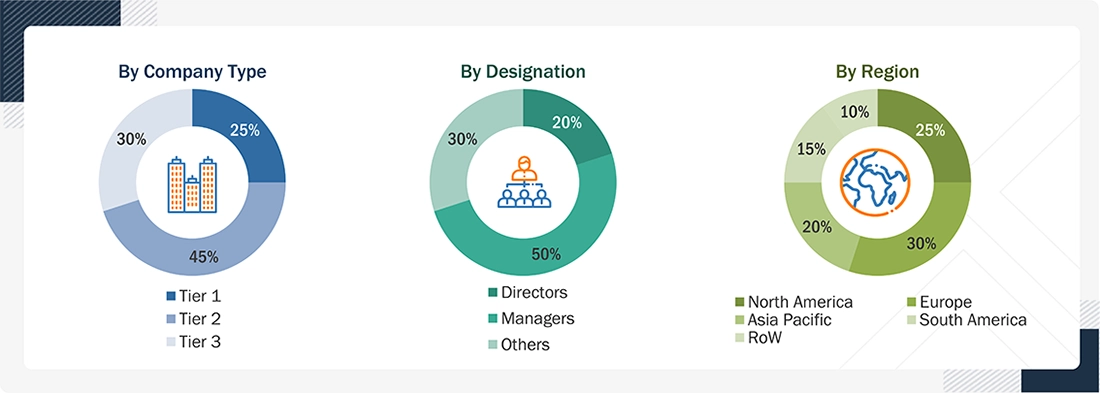
Extensive primary research was conducted after obtaining information regarding the fungicides market scenario through secondary research. Several primary interviews were conducted with market experts from both the demand and supply sides across major countries of North America, Europe, Asia Pacific, the Middle East & Africa, and South America. Primary data were collected through questionnaires, emails, and telephonic interviews. The primary sources from the supply side included various industry experts, such as Chief X Officers (CXOs), Vice Presidents (VPs), Directors from business development, marketing, research, and development teams, and related key executives from distributors and key opinion leaders. Primary interviews were conducted to gather insights such as market statistics, data on revenue collected from the products and services, market breakdowns, market size estimations, market forecasting, and data triangulation. Primary research also helped in understanding the various trends related to type, crop type, mode of application, mode of action, formulation, and region.
To know about the assumptions considered for the study, download the pdf brochure
Market Size Estimation
Both the top-down and bottom-up approaches were used to estimate and validate the total size of the fungicides market. These approaches were also used extensively to estimate the size of various dependent submarkets. The research methodology used to estimate the market size includes the following:
- Key players were identified through extensive secondary research.
- The industry’s value chain and market size were determined through primary and secondary research.
- All percentage share splits and breakdowns were determined using secondary sources and verified through primary sources.
- All the possible parameters that affect the markets covered in this research study were accounted for, viewed in extensive detail, verified through primary research, and analyzed to obtain the final quantitative and qualitative data.
- The following figure provides an illustrative representation of the complete market size estimation process implemented in this research study for an overall estimation of the fungicides market in a consolidated format.
The following sections (bottom-up & top-down) depict the overall market size estimation process employed for the purpose of this study.
Global Fungicides Market: Top-Down & Bottom-Up Approach

Data Triangulation
After arriving at the overall market size from the estimation process explained above, the total market was split into several segments and subsegments. Data triangulation and market breakdown procedures were employed, wherever applicable, to estimate the overall fungicides market and arrive at the exact statistics for all segments and subsegments. The data were triangulated by studying various factors and trends from the demand and supply sides. Along with this, the market size was validated using both the top-down and bottom-up approaches.
Market Definition
Fungicides are a type of pesticide used to destroy or prevent the growth of fungi and their spores. They are applied to crops to protect them from fungi, such as rust, mildew, mold, and blight. They function in different ways, though most damage fungal cell membranes or interfere with energy production within fungal cells.
Key Stakeholders
- Fungicide manufacturers, formulators, and blenders
- Pesticide traders, suppliers, distributors, importers, and exporters
- Raw material suppliers and technology providers to manufacturers
- Agricultural cooperative societies
- Fungicide associations and industry bodies:
- Food and Agriculture Organization (FAO)
- European Crop Protection Association (ECPA)
- Pesticides Manufacturers and Formulators Association (PMFAI)
- China Crop Protection Industry Association (CCPIA)
- Government agricultural departments and regulatory bodies:
- US Environmental Protection Agency (EPA)
- Canadian Food Inspection Agency (CFIA)
- US Department of Agriculture (USDA)
- European Chemicals Agency (ECHA)
- European Food Safety Authority (EFSA)
Report Objectives
MARKET INTELLIGENCE
- Determining and projecting the size of the fungicides market with respect to type, crop type, mode of application, mode of action, formulation, and region
- Identifying the attractive opportunities in the market by determining the largest and fastest-growing segments
- Providing detailed information about the key factors influencing the market growth (drivers, restraints, opportunities, and industry-specific challenges)
- Providing the regulatory framework and market entry process related to the fungicides market
- Analyzing the micro markets with respect to individual growth trends, prospects, and their contribution to the total market
COMPETITIVE INTELLIGENCE
- Identifying and profiling the key players in the fungicides market
- Providing a comparative analysis of market leaders based on the following:
- Product offerings
- Business strategies
- Strengths and weaknesses
- Key financials
- Understanding the competitive landscape and identifying the major growth strategies adopted by players across the country
- Providing insights on key product innovations and investments in the fungicides market
Available customizations:
With the given market data, MarketsandMarkets offers customizations according to company-specific scientific needs
The following customization options are available for the report:
PRODUCT ANALYSIS
- Product Matrix, which gives a detailed comparison of the product portfolio of each company
GEOGRAPHIC ANALYSIS
With the given market data, MarketsandMarkets offers customizations according to company-specific scientific needs
- Further breakdown of the Rest of Europe into Belgium, Poland, and Portugal
- Further breakdown of the Rest of Asia Pacific into Malaysia, South Korea, and Vietnam
- Further breakdown of the Rest of South America into Peru, Colombia, and Paraguay
COMPANY INFORMATION
- Detailed analyses and profiling of additional market players (up to five)

Personalize This Research
- Triangulate with your Own Data
- Get Data as per your Format and Definition
- Gain a Deeper Dive on a Specific Application, Geography, Customer or Competitor
- Any level of Personalization
Let Us Help You
- What are the Known and Unknown Adjacencies Impacting the Fungicides Market
- What will your New Revenue Sources be?
- Who will be your Top Customer; what will make them switch?
- Defend your Market Share or Win Competitors
- Get a Scorecard for Target Partners

Custom Market Research Services
We Will Customise The Research For You, In Case The Report Listed Above Does Not Meet With Your Requirements
Get 10% Free CustomisationTESTIMONIALS

Business Innovation Director
US Based Leading Agribusiness,
Food and Ingredients ManufacturerI highly appreciate the team's efficiency for a well conducted study that helped us clarify some blind spots in food and agricultural niche markets. Although compiling information for B2B markets is very difficult, the MnM team pulled out the task successfully. The quality of research, level of insights, and responsiveness of team were commendable.
- US Fungicides Market
- Canada Fungicides Market
- Mexico Fungicides Market
- Germany Fungicides Market
- UK Fungicides Market
- France Fungicides Market
- Spain Fungicides Market
- Italy Fungicides Market
- Russia Fungicides Market
- China Fungicides Market
- India Fungicides Market
- Japan Fungicides Market
- Australia Fungicides Market
- Indonesia Fungicides Market
- Brazil Fungicides Market
- Argentina Fungicides Market
- Rest Of Europe Fungicides Market
- Rest Of Asia Pacific Fungicides Market
- Rest Of South America Fungicides Market


Growth opportunities and latent adjacency in Fungicides Market