Saudi Arabia Armored Vehicles Market (2025-2030)
The Saudi Arabia Armored Vehicles Market was valued at $2018.9 Million in 2025 and projected to reach to $2507.2 Million by 2030, representing a compound annual growth rate of 4.4%. Saudi Arabia's armored vehicles market demonstrates robust growth potential driven by sustained geopolitical tensions in the Middle East and the kingdom's commitment to military modernization.

| Market Size in | USD 26.32 MN |
| Market Forecast in | |
| CAGR | |
| Forecast Period | |
| Units Considered | Value (USD MN) |
Saudi Arabia Armored Vehicles Market Trends and Insights
- This growth trajectory reflects Saudi Arabia's strategic investments in defense modernization and regional security infrastructure.
- Saudi Arabia's market expansion is driven by geopolitical tensions, border security requirements, and the Kingdom's Vision 2030 initiative, which prioritizes domestic defense capabilities and technological advancement. The armored vehicles sector in Saudi Arabia encompasses a diverse range of platforms, including light tactical vehicles, medium-weight personnel carriers, and heavy main battle tanks.
- Saudi Arabia's procurement strategy emphasizes both indigenous production capabilities and strategic partnerships with international defense manufacturers.
- Throughout the forecast period from 2025 to 2030, Saudi Arabia is expected to maintain robust demand for advanced armored platforms to support military modernization and counterterrorism operations..
Key Market Statistics
- CAGR (2025-2030) 4.4% CAGR
- Market Size, 2025 ~USD 2018.9 Million
- Forecast, 2030 ~USD 2507.2 Million
- Country Saudi Arabia
Saudi Arabia Armored Vehicles Market Overview
Market Size & Growth :
Saudi Arabia's armored vehicles market is valued at USD 2,018.9 million in 2025, expanding to USD 2,507.2 million by 2030 at a 4.4% CAGR, outpacing the global growth rate of 3.3%.
Defense Modernization :
Saudi Arabia's strategic investments in defense infrastructure and military modernization initiatives are primary drivers, supported by Vision 2030 economic diversification goals and enhanced domestic security capabilities.
Geopolitical Drivers :
Regional security tensions and cross-border threats continue to fuel demand for advanced armored vehicle platforms, including personnel carriers, tactical vehicles, and specialized defense systems.
Domestic & International Procurement :
Saudi Arabia balances domestic production capabilities with international partnerships, creating opportunities for both local manufacturers and global defense contractors in the armored vehicles segment.
Saudi Arabia Armored Vehicles Market Dynamics
- Government defense budgets remain substantial, with procurement programs emphasizing advanced protection systems and tactical mobility platforms.
- The market benefits from Vision 2030 initiatives promoting domestic defense manufacturing and technology transfer partnerships. Looking ahead to 2030, the market will likely see increased adoption of next-generation armored platforms with enhanced survivability features, integrated digital systems, and autonomous capabilities.
- Strategic partnerships with international defense contractors and investments in local production facilities will shape market dynamics, while regional security challenges ensure continued demand for sophisticated armored vehicle solutions across military and paramilitary applications..
Market Ecosystem
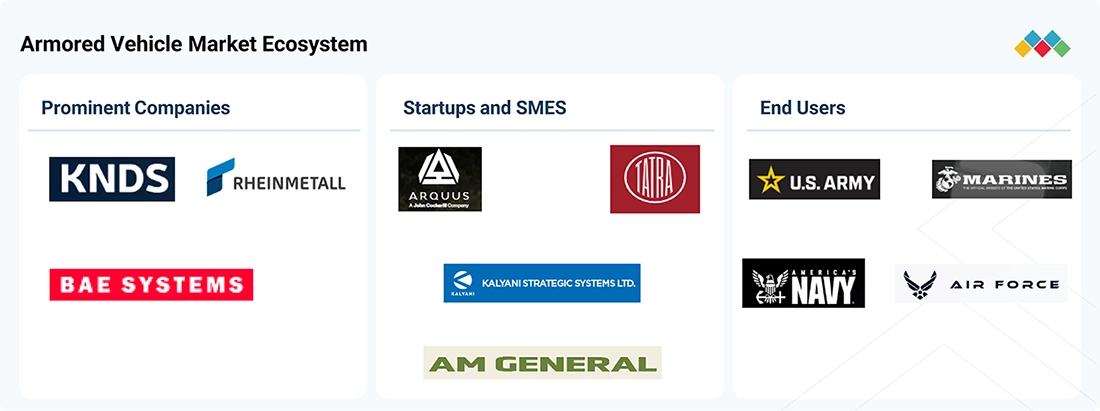
ARMORED VEHICLES MARKET SIZE, SHARE & TRENDS: COMMERCIAL USE CASES ACROSS INDUSTRIES
| COMPANY | USE CASE DESCRIPTION | BENEFITS |
|---|---|---|
 |
General Dynamics Land Systems’ Stryker A1 is used by the U.S. Army as an 8×8 armored vehicle platform for infantry transport and multiple combat-support missions. The upgraded configuration integrates improved survivability, mobility, electrical power, digital architecture, communications, and mission payloads, allowing the platform to support different battlefield roles. | Provides protected mobility while allowing different weapons, sensors, communications, and mission equipment to be integrated on a common vehicle platform. Its upgraded power and digital backbone also support future electronics and battlefield-network requirements. |
 |
KNDS’ LEOPARD 2 main battle tank is used by multiple armed forces for armored combat operations. The platform combines a 120 mm main gun, advanced protection, mobility, optronics, and command-and-information systems, with newer variants incorporating further improvements in survivability and battlefield connectivity. | Provides heavy direct-fire capability, crew protection, and cross-country mobility for high-intensity land operations. Its continuing upgrade path allows users to improve protection, firepower, electronics, and command capabilities without replacing the complete vehicle fleet. |
 |
Rheinmetall’s BOXER is a modular 8×8 armored vehicle used for troop transport, command, medical, engineering, reconnaissance, air-defense, and other mission roles. The platform combines a common drive module with interchangeable mission modules, allowing armed forces to configure vehicles for different operational requirements. | Enables multiple mission variants to use a common vehicle architecture, reducing fleet complexity and supporting common training, maintenance, and logistics. Interchangeable mission modules also allow users to adapt the platform as operational requirements change. |
 |
BAE Systems’ Armored Multi-Purpose Vehicle (AMPV) is being fielded by the U.S. Army to replace legacy M113 vehicles within Armored Brigade Combat Teams. The family supports roles such as general-purpose transport, mission command, medical evacuation, medical treatment, and mortar-carrier operations while operating alongside Abrams and Bradley vehicles. | Improves protection, mobility, reliability, and interoperability compared with the legacy M113 fleet. A common vehicle family also supports multiple battlefield functions while reducing dependence on separate legacy platforms. |
 |
Oshkosh Defense’s JLTV is used by U.S. and allied forces for protected troop transport, reconnaissance, patrol, convoy escort, and weapons-carrier missions. The vehicle combines scalable protection, TAK-4i independent suspension, integrated C4ISR capability, and configurable mission packages for different tactical requirements. | Provides protected tactical mobility across difficult terrain while supporting more than 100 mission-package configurations. Its modular design enables users to integrate weapons, communications, protection kits, and other equipment while maintaining mobility and transportability. |
Logos and trademarks shown above are the property of their respective owners. Their use here is for informational and illustrative purposes only.
Related Ecosystem
Defence Platforms And Systems
- Sensors
- Unmanned Ground Vehicles (UGV)
- Fighter Aircraft
- Special Mission Aircraft
- Antennas
- BAE Systems plc
- Thales group
- LOCKHEED MARTIN CORPORATION
- Northrop Grumman Corporation
- L3Harris Technologies, Inc.
Homeland Security
- Heat Pumps
- Humidifiers
- Ip Cameras
- Monitors
- Navigation Systems
- Thales group
- Elbit Systems Ltd.
- LOCKHEED MARTIN CORPORATION
- L3Harris Technologies, Inc.
- Northrop Grumman Corporation
Key Takeaways
- Saudi Arabia's armored vehicles market will grow from USD 2,018.9M (2025) to USD 2,507.2M (2030) at a 4.4% CAGR.
- Saudi Arabia's defense modernization and Vision 2030 initiative are primary catalysts for sustained market growth.
- Saudi Arabia prioritizes both international partnerships and domestic production capabilities for armored vehicle procurement.
- Regional security challenges and border defense requirements drive consistent demand for advanced armored platforms in Saudi Arabia.
Armored Vehicles Market Report Scope
| Report Metric | Details |
|---|---|
| Base Year | 2025 |
| Fastest Growing Segment | UNMANNED ARMORED GROUND VEHICLES (Platform) |
| Forecast Period | 2025–2030 |
| Growth Rate | CAGR of 3.3% from 2025 to 2030 |
| Largest Segment | MANNED (Mode Of Operation) |
| Market Size Base Year (Billions) | ~USD 51.6 (2025) |
| Revenue Forecast (Billions) | ~USD 60.7 (2030) |
| Segments Covered | Platform, Type, Mobility, Wheeled Mobility, Mode Of Operation, System, Point Of Sale |
Saudi Arabia Armored Vehicles Market Report Segmentation
7 segment dimensions are covered across the global market.
By Platform
- Combat Support Vehicles
- Combat Vehicles
- Unmanned Armored Ground Vehicles
By Type
- Conventional
- Conventional Armored Vehicles
- Conventional Armored Vehicles Armored Vehicles
- Electric
- Electric Armored Electric Vehicles
- Electric Armored Vehicles
By Mobility
- Tracked
- Wheeled
By Wheeled Mobility
- 4X4
- 6X6
- 8X8
By Mode Of Operation
- Manned
- Unmanned
By System
- Ammunition Handling Systems
- Armaments
- Ballistic Armors
- Command & Control Systems
- Countermeasure Systems
- Drive Systems
- Engines
- Fire Control Systems
- Hulls/Frames
- Navigation Systems
- Observation & Display Systems
- Power Systems
- Turret Drives
By Point Of Sale
- Aftermarket
- OEM
Target Audience
- Defense Contractors & OEMs : Global and regional armored vehicle manufacturers need Saudi Arabia-specific market intelligence to identify procurement opportunities, establish local partnerships, and align product offerings with kingdom defense requirements.
- Government & Military Procurement : Saudi defense ministry officials and military procurement teams require detailed market analysis to benchmark international capabilities, evaluate supplier options, and justify budget allocations for armored vehicle modernization programs.
- Investment & Private Equity Firms : Investors targeting Middle East defense sector growth need comprehensive Saudi Arabia market data to assess investment opportunities in domestic manufacturers, technology partnerships, and defense-related ventures.
- Strategic Consultants & Advisors : Management consulting firms advising defense clients require Saudi Arabia-specific market insights to develop competitive strategies, identify market gaps, and recommend optimal positioning in this high-growth regional segment.
- Market Research & Intelligence Teams : Corporate strategy and business development teams need detailed Saudi Arabia armored vehicles data to support competitive analysis, market entry decisions, and long-term strategic planning in the Middle East defense sector.
Key Companies in the Saudi Arabia Armored Vehicles Market
| Company | HQ | Ownership | Strongest segments |
|---|---|---|---|
| QINETIQ GROUP PLC | United Kingdom | Public Company | Test and Training,Mission Support and Operations,Research and Development, |
| WOODWARD, INC. | United States | Public Company | Aerospace OEM controls and actuation,Aerospace aftermarket and MRO services,Industrial turbine and engine controls (OEM), |
| ADLINK TECHNOLOGY INC. | Taiwan | Public Company | Edge computing platforms (industrial PCs, embedded computers, IoT/edge AI gateways, AI smart cameras, robotic controllers, SSDs),Computer-on-modules (COM Express, SMARC, Qseven, OSM, ETX, HPC),Rugged computing and transportation systems (CompactPCI, VPX, PC104, AVA railway, passenger information systems), |
| ENERSYS | United States | Public Company | |
| MEGGITT PLC | United Kingdom | Private Company | |
| CONSTELLIUM N.V | France | Public Company | |
| NORINCO GROUP | China | Private Company | |
| RHEINMETALL AG | Germany | Public Company | |
| GENERAL DYNAMICS CORPORATION | United States | Public Company | |
| OSHKOSH CORPORATION | United States | Public Company | |
| BAE SYSTEMS | United Kingdom | Public Company | |
| HANWHA GROUP | South Korea | Public Company | |
| NORTHROP GRUMMAN | United States | Public Company | |
| LOCKHEED MARTIN CORPORATION | United States | Public Company | |
| THALES | France | Public Company | |
| L3HARRIS TECHNOLOGIES, INC. | United States | Public Company | Space & Mission Systems (SMS),Communications & Spectrum Dominance (CSD),Missile Solutions (MSL), |
| ST ENGINEERING | Singapore | Public Company | Commercial Aerospace (MRO, P2F, aerostructures, asset management),Defence & Public Security (air, land, sea, C4ISR, homeland security),Urban Solutions & Satcom (smart mobility, smart city, energy, digital platforms), |
| ELBIT SYSTEMS LTD. | Israel | Public Company | Aerospace (airborne platforms, UAVs, avionics, training),C4I and Cyber,ISTAR & Electronic Warfare, |
| MITSUBISHI HEAVY INDUSTRIES, LTD. | Japan | Public Company | Thermal Power Generation Systems (Gas Turbine Combined Cycle & Steam),Nuclear Power & Fuel Cycle Solutions,Wind Power & Renewable-Adjacent Systems, |
| HYUNDAI ROTEM COMPANY | South Korea | Public Company | Railway vehicles and rail systems,Defense systems (tanks and armored vehicles),Plants, machinery, and industrial systems, |
| TEXTRON INC. | United States | Public Company | Textron Aviation (business, turboprop, piston, trainer, and defense aircraft plus services),Bell (military and commercial helicopters, tiltrotor, parts and services),Textron Systems (UAS, electronic systems, marine craft, weapons, armored vehicles), |
| OTOKAR OTOMOTIV VE SAVUNMA SANAYI | Turkey | Public Company | Wheeled & tracked armored vehicles,Turrets and defense subsystems,Buses & minibuses (public transportation), |
QINETIQ GROUP PLC
QinetiQ Group PLC is a United Kingdom-based public company founded in 2001, employing 7,378 people. The company operates in the defense and aerospace sectors.
WOODWARD, INC.
Woodward, Inc. is a United States-based public company founded in 1870 with 10,200 employees. The company specializes in aerospace and industrial control systems.
ADLINK TECHNOLOGY INC.
ADLINK Technology Inc. is a Taiwan-based public company founded in 1995 with 342 employees. The company operates in the technology and industrial computing sectors.
ENERSYS
EnerSys is a United States-based public company founded in 1991 with 9,682 employees. The company specializes in energy storage and power conversion solutions.
MEGGITT PLC
Meggitt PLC is a United Kingdom-based private company founded in 1947 with 9,270 employees. The company operates in the aerospace and defense engineering sectors.
CONSTELLIUM N.V
Constellium N.V. is a France-based public company founded in 2010 with 11,500 employees. The company specializes in aluminum rolled and extruded products.
NORINCO GROUP
NORINCO Group is a China-based private company founded in 1999. The company operates in the defense and industrial manufacturing sectors.
RHEINMETALL AG
Rheinmetall AG is a Germany-based public company founded in 1889 with 28,815 employees. The company operates in the defense, automotive, and industrial technology sectors.
GENERAL DYNAMICS CORPORATION
General Dynamics Corporation is a United States-based public company founded in 1899 with 117,000 employees. The company is a major defense contractor serving aerospace, combat systems, and information technology markets.
OSHKOSH CORPORATION
Oshkosh Corporation is a United States-based public company founded in 1915 with 18,400 employees. The company manufactures specialty vehicles and vehicle bodies for defense and commercial markets.
BAE SYSTEMS
BAE Systems is a United Kingdom-based public company founded in 1979 with 111,400 employees. The company is a major defense, aerospace, and security contractor.
HANWHA GROUP
Hanwha Group is a South Korea-based public company founded in 1952 with 3,493 employees. The company operates in the defense and industrial sectors.
NORTHROP GRUMMAN
Northrop Grumman is a United States-based public company founded in 1939 with 95,000 employees. The company is a major defense and aerospace contractor.
LOCKHEED MARTIN CORPORATION
Lockheed Martin Corporation is a United States-based public company founded in 1912 with 123,000 employees. The company is a leading global security and aerospace company.
THALES
Thales is a France-based public company founded in 1893 with 82,111 employees. The company operates in aerospace, defense, and security technology sectors.
L3HARRIS TECHNOLOGIES, INC.
L3Harris Technologies, Inc. is a United States-based public company founded in 1895 with 45,000 employees. The company provides defense and commercial technologies and services.
ST ENGINEERING
ST Engineering is a Singapore-based public company founded in 1967 with 27,000 employees. The company operates in aerospace, defense, and engineering sectors.
ELBIT SYSTEMS LTD.
Elbit Systems Ltd. is an Israel-based public company founded in 1966 with 20,000 employees. The company specializes in defense electronics and aerospace systems.
MITSUBISHI HEAVY INDUSTRIES, LTD.
Mitsubishi Heavy Industries, Ltd. is a Japan-based public company founded in 1884 with 78,793 employees. The company operates in aerospace, defense, power systems, and industrial machinery sectors.
HYUNDAI ROTEM COMPANY
Hyundai Rotem Company is a South Korea-based public company founded in 1977. The company manufactures defense systems and railway vehicles.
TEXTRON INC.
Textron Inc. is a United States-based public company founded in 1923 with 34,000 employees. The company operates in aerospace, defense, and industrial sectors.
OTOKAR OTOMOTIV VE SAVUNMA SANAYI
Otokar Otomotiv ve Savunma Sanayi is a Turkey-based public company founded in 1963 with 3,616 employees. The company manufactures defense vehicles and automotive products.
Reasons to Buy this Report
- Market-Specific Sizing & Forecasts : Access precise valuation data for Saudi Arabia's armored vehicles market with detailed 2025-2030 projections, enabling accurate budget allocation and investment planning specific to this high-growth regional market.
- Geopolitical & Strategic Context : Understand the unique drivers behind Saudi Arabia's armored vehicle demand, including regional security dynamics, Vision 2030 defense initiatives, and cross-border threat assessments influencing procurement decisions.
- Competitive Landscape Intelligence : Identify key suppliers, domestic manufacturers, and international defense contractors competing in Saudi Arabia's market, including partnership opportunities and technology transfer arrangements shaping competitive positioning.
- Procurement & Policy Insights : Gain actionable intelligence on Saudi government defense budgets, procurement timelines, localization requirements, and regulatory frameworks governing armored vehicle acquisitions and domestic production mandates.
- Strategic Market Entry Planning : Develop targeted go-to-market strategies for Saudi Arabia with segment-specific demand analysis, customer profiling, and growth opportunity identification across military, paramilitary, and security applications.
Frequently asked questions
What is the current size of Saudi Arabia's armored vehicles market?
Saudi Arabia's armored vehicles market is valued at USD 2,018.9 million in 2025.
What is the projected market size for Saudi Arabia's armored vehicles by 2030?
Saudi Arabia's armored vehicles market is forecast to reach USD 2,507.2 million by 2030.
What is the growth rate of Saudi Arabia's armored vehicles market?
Saudi Arabia's armored vehicles market is expected to grow at a CAGR of 4.4% from 2025 to 2030.
What factors are driving growth in Saudi Arabia's armored vehicles market?
Saudi Arabia's market growth is driven by defense modernization initiatives, Vision 2030 strategic priorities, regional security challenges, and border defense requirements.
What types of armored vehicles does Saudi Arabia procure?
Saudi Arabia procures a diverse range of armored platforms including light tactical vehicles, medium-weight personnel carriers, and heavy main battle tanks through both international partnerships and domestic production.
RESEARCH METHODOLOGY
The study used four main activities to estimate the current size of the armored vehicles market. First, detailed secondary research was conducted to collect information on military robotic platforms, manufacturers, system types, applications, defense programs, procurement contracts, military budgets, deliveries, deployments, and ongoing development programs. The collected information and key assumptions were then checked through primary interviews with industry participants and experts across the value chain. Demand-side analysis was used to estimate spending on armored vehicles by platform, application, end user, and region. Finally, market breakdown and data triangulation were used to calculate the size of each segment and subsegment.
Secondary Research
Secondary research included information from government procurement portals, defense ministries, armed forces, defense agencies, company annual reports, regulatory filings, investor presentations, product documents, press releases, technical papers, journals and recognized defense databases. Sources such as SIPRI were used to review military spending, equipment transfers and procurement activity, while government budget documents and procurement records were used to track armored vehicle programs, contracts, orders and deliveries. Company filings and official product information were used to study armored vehicle portfolios, revenues, contracts, technologies, applications, customers and geographical presence.
Primary Research
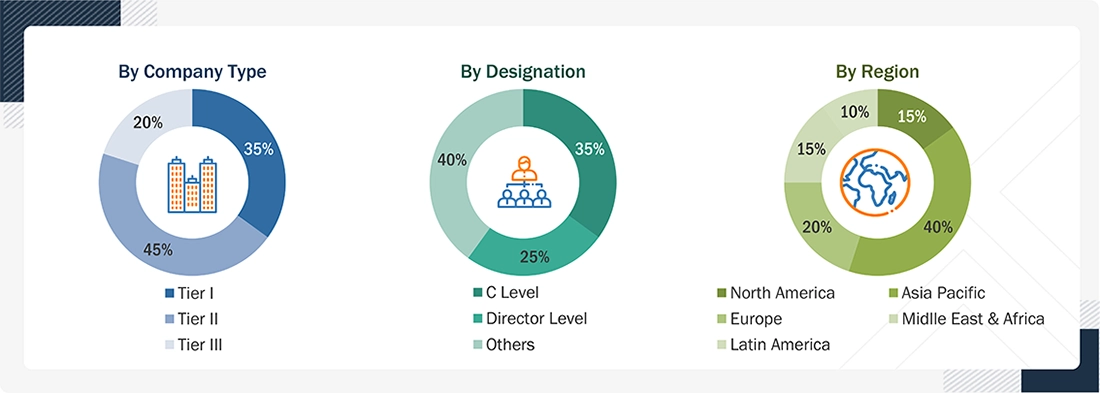
Primary research was conducted after completing the secondary research. Interviews were carried out with unmanned system manufacturers, component and payload suppliers, autonomy and software providers, system integrators, distributors, procurement officials, commercial operators, defense personnel and other industry participants. The interviews covered major countries across North America, Europe, Asia Pacific, the Middle East & Africa, and Latin America. Primary information was collected through questionnaires, emails, and telephone interviews and was used to check market estimates, procurement trends, platform demand, pricing, delivery patterns, applications, adoption rates, and segment-level assumptions.
The following is the breakdown of primary respondents:
To know about the assumptions considered for the study, download the pdf brochure
Market Size Estimation
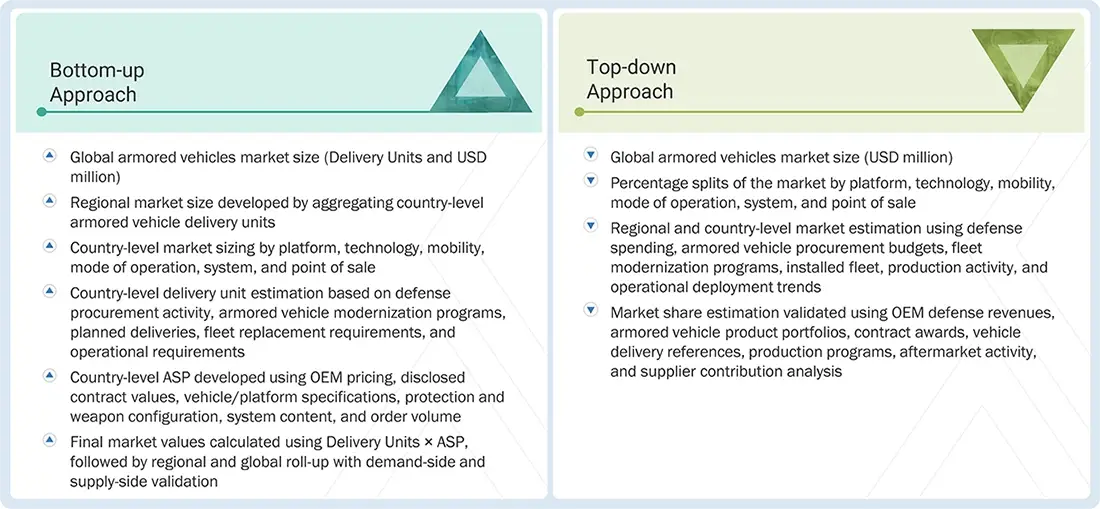
The top-down and bottom-up approaches were used to estimate and validate the size of the armored vehicles market. The research methodology used to estimate the size of the market included the following details:
- Key AV companies were identified through secondary research. Their market positions were estimated using company revenues, armored-vehicle portfolios, contract activity, production volumes, order backlogs, regional presence, and program participation. Annual reports, financial filings, product documents, procurement records, defense ministry sources, government budget documents, and interviews with company executives, engineers, system integrators, suppliers, military users, and other industry participants were used for the analysis. Rheinmetall, for example, reported approximately USD 5.72 billion in vehicle systems sales in 2025, while its segment backlog and vehicle-program order intake were used as additional indicators of market activity.
- Market shares, segment splits, regional shares, and growth rates were first estimated using secondary sources and then checked through primary interviews. The analysis covered the market by platform, by technology, by mobility, by mode of operation, by system, by point of sale, by weight class, and by end user, along with vehicle pricing, procurement volumes, deliveries, modernization programs, installed fleets, replacement cycles, and regional demand patterns.
- Demand for AVs across Army, Navy, Homeland Security, and Air Force users was considered. The analysis included new procurement, fleet modernization, vehicle replacement, survivability upgrades, localized production, sustainment requirements, and battlefield capability needs. For example, the U.S. FY2026 budget includes procurement of 86 Armored Multi-Purpose Vehicles and 91 Amphibious Combat Vehicles, while continuing investment in XM30, M1E3 Abrams, Stryker, Bradley, and other ground-combat programs.
- The collected information was compared and combined through data triangulation. Final market values were calculated using company-level revenues, vehicle delivery volumes, average selling prices, contract values, procurement activity, modernization spending, regional demand, installed fleet information, and primary-interview validation.
Armored Vehicle Market Size: Bottom-Up & Top-Down Approach
Data Triangulation
After determining the overall market size, the armored vehicles market was divided into its main segments and subsegments. Data triangulation and market breakdown were used to develop estimates for each segment and subsegment. The analysis considered factors from both the demand and supply sides, including defense procurement budgets, vehicle deliveries, platform replacement cycles, modernization programs, production capacity, company participation, contract values, vehicle pricing, installed fleets, localization programs, and regional defense requirements. Platform-specific indicators such as procurement of main battle tanks, infantry fighting vehicles, armored personnel carriers, artillery vehicles, engineering vehicles, recovery vehicles, and other protected platforms were also assessed.
Market Definition
The armored vehicles market comprises military and security vehicles designed with ballistic, blast, mine, and other forms of protective armor to safeguard personnel, equipment, and mission-critical systems during combat and security operations. These vehicles are used for a range of applications, including combat, troop transportation, protected mobility, reconnaissance, fire support, command and control, engineering, recovery, logistics, and other specialized missions.
Key Stakeholders
- Defense Ministries & Government Procurement Agencies
- Armies, Marines & Other Military End Users
- Armored Vehicle OEMs & Prime Contractors
- Armor, Weapon, Powertrain & Subsystem Suppliers
- Sensors, Vetronics, Communications & C4ISR Technology Providers
- AI, Autonomy & Software Technology Providers
- System Integrators & Engineering Service Providers
- Defense R&D, Testing & Certification Organizations
- Maintenance, Repair, Overhaul & Lifecycle Support Providers
- Defense Alliances & Standardization Bodies
Report Objectives
- To define, describe, segment, and forecast the size of the armored vehicles market based on platform, technology, mobility, mode of operation, system, point of sale, weight class, end user and region
- To forecast the size of the market segments across five regions: North America, Europe, Asia Pacific, the Middle East & Africa, and Latin America
- To identify and analyze key drivers, restraints, opportunities, and challenges influencing the growth of the market
- To identify industry trends, market trends, and technology trends in the armored vehicles market
- To analyze micro markets with respect to individual technology trends, growth prospects, and their contribution to the overall market
- To strategically profile key market players and analyze their market position and core capabilities
- To provide a detailed competitive landscape of the market and analyze competitive strategies such as product launches, partnerships, agreements, and collaborations adopted by key players
- To assess the financial position of key players along with their key products, unique offerings, and recent developments
Available customizations:
MarketsandMarkets offers the following customizations for this market report:
- Additional country-level analysis of the armored vehicles market
- Profiling of other market players (up to 5)
Product Analysis
- Product matrix, which provides a detailed comparison of the product portfolio of each company in the armored vehicles market
Get the Full Armored Vehicles Market Report
Full forecast, segment splits, and company analysis for all Armored Vehicles Market.
- Canada Armored Vehicles Market
- US Armored Vehicles Market
- UK Armored Vehicles Market
- Germany Armored Vehicles Market
- France Armored Vehicles Market
- Poland Armored Vehicles Market
- India Armored Vehicles Market
- Japan Armored Vehicles Market
- Australia Armored Vehicles Market
- South Korea Armored Vehicles Market
- UAE Armored Vehicles Market
- Middle East Armored Vehicles Market
- Rest Of Europe Armored Vehicles Market
- Rest Of Asia Pacific Armored Vehicles Market
- Rest Of Middle East Armored Vehicles Market
Need a Tailored Report?
Customize this report to your needs
Get 10% FREE Customization
Customize This Report