UAE Care Management Solutions Market (2026-2031)
The UAE Care Management Solutions Market was valued at $145.9 Million in 2026 and projected to reach to $306 Million by 2031, representing a compound annual growth rate of 16.0%. The UAE Care Management Solutions Market is positioned for sustained expansion through 2031, driven by government mandates for healthcare digitalization and Vision 2021 objectives.

| Market Size in | USD 26.32 MN |
| Market Forecast in | |
| CAGR | |
| Forecast Period | |
| Units Considered | Value (USD MN) |
UAE Care Management Solutions Market Trends and Insights
- This accelerated expansion reflects UAE's strategic investments in healthcare infrastructure modernization and digital health adoption across both public and private sectors.
- The UAE's commitment to Vision 2030 initiatives and enhanced patient-centric care delivery models are driving demand for integrated care management platforms. UAE's care management solutions market is benefiting from rising chronic disease prevalence, an aging population, and increased healthcare spending by government and private entities.
- The UAE's advanced regulatory environment and emphasis on healthcare innovation create favorable conditions for solution providers.
- Between 2026 and 2031, UAE is expected to see significant adoption of cloud-based care coordination, remote patient monitoring, and AI-driven clinical decision support systems.
- The market's growth trajectory outpaces global averages, positioning UAE as a key regional hub for care management technology deployment and innovation..
Key Market Statistics
- CAGR (2026-2031) 16.0% CAGR
- Market Size, 2026 ~USD 145.9 Million
- Forecast, 2031 ~USD 306 Million
- Country UAE
UAE Care Management Solutions Market Overview
Market Valuation Growth :
UAE Care Management Solutions Market valued at $145.9 million in 2026, expanding to $306.0 million by 2031, demonstrating strong investor confidence in digital health infrastructure.
Accelerated CAGR Performance :
UAE market growing at 16% CAGR, outpacing global average of 13.6%, driven by government healthcare digitalization initiatives and private sector adoption.
Healthcare Infrastructure Modernization :
Strategic investments in UAE's healthcare ecosystem, including EMR integration, telemedicine platforms, and patient engagement tools across Dubai, Abu Dhabi, and emerging emirates.
Public-Private Sector Collaboration :
Dual adoption across UAE's public healthcare entities (MOHAP, DHA) and private providers (NMC, Burjeel) accelerating care management solution implementation and digital transformation.
UAE Care Management Solutions Market Dynamics
- Increasing prevalence of chronic diseases, aging population demographics, and rising healthcare expenditure are compelling healthcare providers to adopt integrated care management platforms.
- The UAE's regulatory framework, including DHA and MOHAP standards, creates standardized adoption pathways.
- Private healthcare operators are investing heavily in patient-centric technologies, while public sector modernization initiatives ensure widespread market penetration across all emirates..
Market Ecosystem
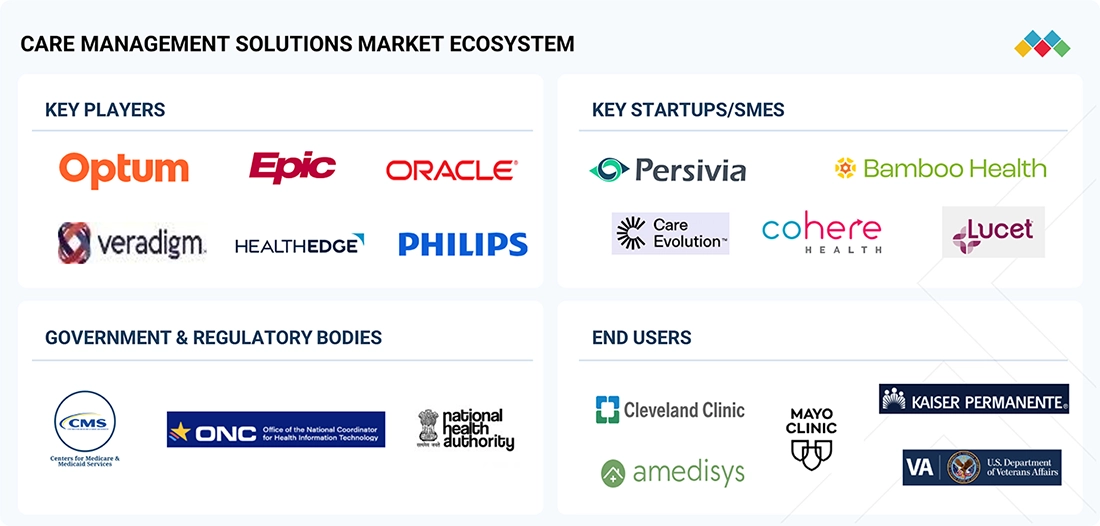
CARE MANAGEMENT SOLUTIONS MARKET: COMMERCIAL USE CASES ACROSS INDUSTRIES
| COMPANY | USE CASE DESCRIPTION | BENEFITS |
|---|---|---|
 |
Provides AI-enabled care management, population health management, risk stratification, utilization management, and care coordination solutions through Optum Insight and Optum Health platforms | Supports providers and payers in identifying high-risk populations, managing chronic conditions, and improving value-based care performance | Improved care coordination reduced total cost of care, enhanced population health outcomes, proactive risk management, optimized resource utilization, and improved quality performance |
 |
Delivers integrated care management capabilities through Healthy Planet, Care Everywhere, and MyChart, enabling chronic disease management, care coordination, transitional care, patient engagement, and population health management within a unified electronic health record ecosystem | Improved continuity of care, enhanced patient engagement, better chronic disease management, streamlined care transitions, reduced hospital readmissions, and improved clinical outcomes |
 |
Offers enterprise care management, population health, and care coordination capabilities through Oracle Health, integrating clinical, financial, and operational data to support longitudinal patient management, value-based care initiatives, and multidisciplinary care delivery | Enterprise-wide patient visibility, improved care coordination, enhanced interoperability, optimized care planning, improved operational efficiency, and better value-based care performance |
 |
Delivers data-driven care management, quality improvement, and population health solutions that integrate clinical and claims data to support chronic disease management, care gap identification, value-based care, and performance measurement across provider organizations | Improved quality reporting, enhanced population health management, better care gap closure, data-driven clinical insights, improved reimbursement performance, and stronger value-based care outcomes |
 |
Provides connected care solutions integrating remote patient monitoring, virtual care, chronic disease management, and care coordination through the Philips Connected Care portfolio, enabling continuous patient monitoring across hospital, home, and community care settings | Improved patient outcomes, reduced avoidable hospitalizations, enhanced care continuity, increased patient engagement, optimized remote care delivery, and improved operational efficiency |
Logos and trademarks shown above are the property of their respective owners. Their use here is for informational and illustrative purposes only.
Related Ecosystem
Healthcare It
- Computed Tomography (CT)
- Machine Learning
- Magnetic Resonance Imaging (MRI)
- Natural Language Processing (NLP)
- Predictive Analytics
- CERNER CORPORATION
- PHILIPS HEALTHCARE
- Oracle Corporation
- GE HealthCare Technologies Inc.
- Siemens healthineers
Key Takeaways
- UAE's care management solutions market will more than double from $145.9M (2026) to $306.0M (2031) at a 16.0% CAGR.
- UAE's healthcare digitalization initiatives and Vision 2030 goals are primary catalysts for care management solution adoption.
- The UAE market growth rate significantly exceeds global benchmarks, reflecting strong regional demand and investment.
- UAE's advanced healthcare infrastructure and regulatory framework position it as a leading market for innovative care management technologies.
Care Management Solutions Market Report Scope
| Report Metric | Details |
|---|---|
| Base Year | 2026 |
| Fastest Growing Segment | HEALTHCARE PAYERS (End User) |
| Forecast Period | 2026-2031 |
| Growth Rate | CAGR of 13.6% from 2026 to 2031 |
| Largest Segment | SOFTWARE (Component) |
| Market Size Base Year (Billions) | ~USD 22.53 (2026) |
| Revenue Forecast (Billions) | ~USD 42.62 (2031) |
| Segments Covered | Component, Type, Deployment Model, Application, End User, Segment |
UAE Care Management Solutions Market Report Segmentation
6 segment dimensions are covered across the global market.
By Component
- Services
- Software
By Type
- Ambulatory Care Centers
- Government Payers
- Home-Based Care Providers
- Hospitals & Health Systems
- Integrated Care Management Solutions
- Private Payers
- Standalone Care Management Solutions
- Third-Party Administrators (Tpas)
By Deployment Model
- Cloud-Based
- On-Premises
By Application
- Chronic Care Management
- Preventive Care Management
- Transitional Care Management
- Utilization Management
By End User
- Healthcare Payers
- Healthcare Providers
- Other End Users
By Segment
- Third-Party Administrators(Tpa)
Target Audience
- Healthcare IT Vendors : Software and platform providers need UAE-specific market data to develop localized solutions, understand regulatory requirements, and identify hospital and clinic procurement opportunities.
- Healthcare Providers & Hospital Networks : UAE-based hospitals, clinics, and healthcare networks require competitive benchmarking data and market trends to evaluate care management solution investments and digital transformation ROI.
- Private Equity & Investment Firms : Investors targeting UAE healthcare sector need market sizing, growth projections, and competitive analysis to evaluate acquisition targets and portfolio company expansion opportunities.
- Healthcare Consultants & System Integrators : Implementation partners and management consultants need detailed market intelligence to advise clients on technology selection, vendor evaluation, and digital health strategy in UAE.
- Government & Regulatory Bodies : UAE health authorities (DHA, MOHAP) and emirate health departments require market data to inform healthcare digitalization policies, procurement standards, and infrastructure planning.
Reasons to Buy this Report
- Market-Specific Growth Projections : Access detailed UAE market forecasts with 16% CAGR through 2031, enabling accurate business planning and investment decisions tailored to local market dynamics.
- Competitive Landscape Intelligence : Identify key players, market share distribution, and competitive positioning within UAE's public and private healthcare sectors to inform go-to-market strategies.
- Regulatory & Compliance Insights : Understand DHA, MOHAP, and emirate-specific healthcare regulations impacting care management solution adoption, licensing, and implementation requirements.
- Segment & Use Case Analysis : Detailed breakdown of care management applications across chronic disease management, patient engagement, care coordination, and population health in UAE healthcare settings.
- Investment & Partnership Opportunities : Identify high-growth segments, emerging healthcare providers, and strategic partnership opportunities within UAE's rapidly expanding digital health ecosystem.
Frequently asked questions
What is the current market size of care management solutions in UAE?
The UAE care management solutions market is valued at $145.9 million in 2026 and is projected to reach $306.0 million by 2031.
What is the expected growth rate for UAE's care management solutions market?
The UAE market is expected to grow at a compound annual growth rate (CAGR) of 16.0% from 2026 to 2031.
What factors are driving growth in the UAE care management solutions market?
Key drivers include UAE's Vision 2030 healthcare initiatives, rising chronic disease prevalence, digital health adoption, increased healthcare spending, and demand for integrated care coordination platforms.
How does UAE's care management market compare to global trends?
UAE's 16.0% CAGR significantly outpaces the global market CAGR of 13.6%, indicating stronger regional demand and investment in care management solutions.
Which technologies are gaining traction in UAE's care management market?
Cloud-based care coordination, remote patient monitoring, AI-driven clinical decision support systems, and integrated digital health platforms are experiencing significant adoption in UAE.
RESEARCH METHODOLOGY
The study involved five major activities to estimate the current size of the care management solutions market. Exhaustive secondary research was conducted to collect information on the market and its subsegments. The next step was to validate these findings, assumptions, and sizing with industry experts across the value chain through primary research. Both top-down and bottom-up approaches were employed to estimate the total market size. Thereafter, market breakdown and data triangulation procedures were used to estimate the market size of the segments and subsegments.
Secondary Research
This research study relied extensively on secondary sources, including directories, databases such as Bloomberg Business, Factiva, and Dun & Bradstreet, white papers, annual reports, company house documents, investor presentations, and SEC filings. Secondary research was used to identify and collect valuable information for this study. It was also used to obtain important information about the key players, market classification and segmentation according to industry trends down to the bottom-most level, and key market & technology developments. A database of the key industry leaders was also prepared using secondary research.
Some of the key secondary sources referred to for this study include:
- Healthcare Information and Management Systems Society (HIMSS)
- Centers for Medicare & Medicaid Services (CMS)
- American Medical Informatics Association (AMIA)
- Agency for Healthcare Research and Quality (AHRQ)
- National Committee for Quality Assurance (NCQA)
- Organization for Economic Co-operation and Development (OECD)
- World Health Organization (WHO)
- Centers for Disease Control and Prevention (CDC)
- European Federation for Medical Informatics (EFMI)
- Australian Healthcare and Hospitals Association
- Investor Presentations, SEC Filings, and Company Annual Reports
- White Papers, Journals/Magazines, and News Articles
- Paid Databases, such as Factiva, D&B Hoovers, and Bloomberg Business
Primary Research
Extensive primary research was conducted after acquiring basic knowledge of the global care management solutions market through secondary research. Several primary interviews were conducted with market experts from both the demand side (hospital directors, hospital vice presidents, department heads, and critical care specialists) and the supply side (C- and D-level executives, technology experts, product managers, marketing and sales managers, among others) across five major regions - North America, Europe, the Asia Pacific, Latin America, the Middle East, and Africa. This primary data was collected through questionnaires, emails, online surveys, personal interviews, and telephone interviews. In the primary research process, various supply and demand sources were interviewed to obtain qualitative and quantitative information for this report. Primary sources mainly included industry experts from core and related industries, solution providers, technology vendors, system integrators, researchers, and organizations across all segments of this industry’s value chain. In-depth interviews were conducted with various primary respondents, including key industry participants, subject-matter experts (SMEs), C-level executives of key market players, and industry consultants, among others, to obtain and verify critical qualitative and quantitative information and assess prospects. Primary research was conducted to identify segmentation types, industry trends, key players, and key market dynamics such as drivers, restraints, opportunities, challenges, and strategies adopted by key players.
The following is a breakdown of the primary respondents:
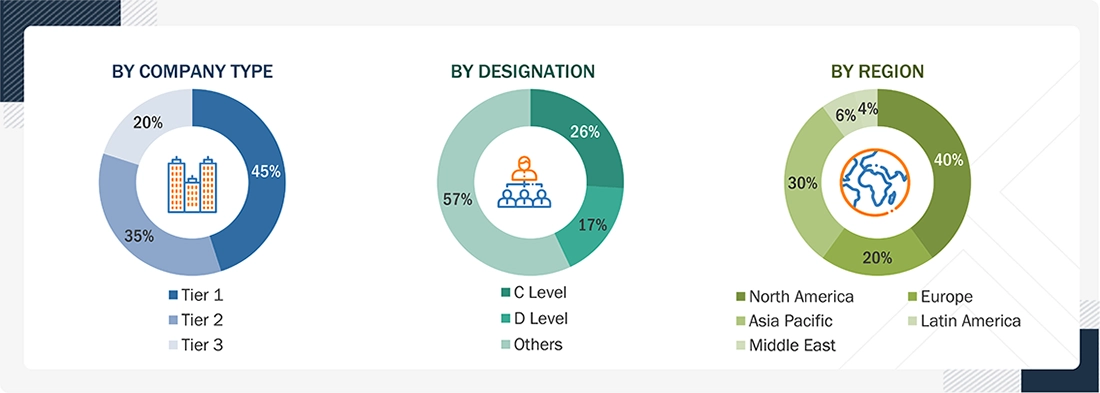
Note 1: C-level primaries include CEOs, CFOs, and COOs.
Note 2: Others include sales managers, marketing managers, business development managers, product managers, distributors, and suppliers.
Note 3: Companies are classified into tiers based on their total revenues. As of 2024, Tier 1 = >USD 2 billion, Tier 2 = USD 50 million to USD 2 billion, and Tier 3 = <USD 50 million.
To know about the assumptions considered for the study, download the pdf brochure
Market Size Estimation
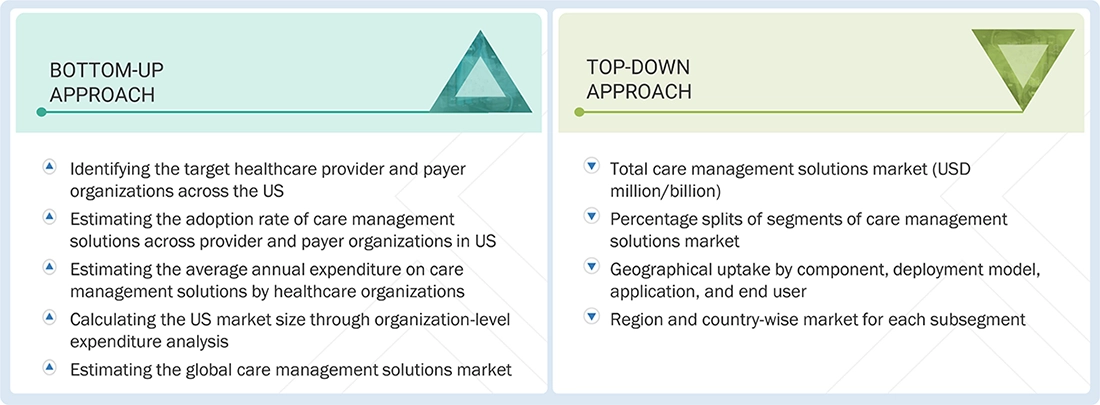
Both top-down and bottom-up approaches were used to estimate and validate the total size of the care management solutions market. These methods were also used extensively to estimate the size of various market subsegments.
Care Management Solutions Market : Top-Down and Bottom-Up Approach
Data Triangulation
After determining the overall market size using the market size estimation processes, the market was split into several segments and subsegments. To complete the overall market engineering process and arrive at the exact statistics for each market segment and subsegment, data triangulation and market breakdown procedures were employed wherever applicable. The data was triangulated by studying various factors and trends from both the demand and supply sides in the care management solutions market.
Market Definition
Care management solutions are healthcare information technology (HCIT) platforms that support the planning, coordination, monitoring, and delivery of patient care across the continuum of care. These solutions enable care teams to manage chronic diseases, coordinate care transitions, identify high-risk populations, and improve patient engagement through integrated clinical, administrative, and population health workflows. They help healthcare organizations improve clinical outcomes, optimize resource utilization, reduce healthcare costs, and support value-based care delivery.
Key Stakeholders
- Care Management Solutions and related Solutions Provider Companies
- Hospitals (Public and Private)
- Ambulatory Care Centers
- Home-based Care Providers
- Payers (Commercial and Government)
- Integrated Delivery Networks (IDNs)
- Healthcare Startups
- Government Healthcare Agencies
Report Objectives
- To define, describe, and forecast the global care management solutions market based on component, deployment model, application, end user, and region
- To provide detailed information regarding the major factors (such as drivers, restraints, opportunities, and challenges) influencing the market growth
- To strategically analyze micro-markets with respect to individual growth trends, prospects, and contributions to the overall care management solutions market
- To analyze opportunities in the market for stakeholders and provide details of the competitive landscape for market leaders
- To strategically analyze the market structure profile of the key players of the care management solutions market and comprehensively analyze their core competencies
- To forecast the size of the market segments with respect to five regions, namely, North America, Europe, Asia Pacific, Latin America, and the Middle East & Africa
- To track and analyze competitive developments such as product launches and enhancements and investments, partnerships, collaborations, acquisitions, expansions, agreements, sales contracts, and alliances in the care management solutions market during the forecast period
Available customizations:
With the given market data, MarketsandMarkets offers customizations as per the company’s specific needs. The following customization options are available for the report:
Product Analysis
- Product matrix, which gives a detailed comparison of the product portfolios of each company
Geographic Analysis
- Further breakdown of the Latin American care management solutions market into specific countries, the Middle East & Africa care management solutions market into specific countries, and further breakdown of the European care management solutions market into specific countries.
Get the Full Care Management Solutions Market Report
Full forecast, segment splits, and company analysis for all Care Management Solutions Market.
- Rest Of Latin America Care Management Solutions Market
- GCC Care Management Solutions Market
- Rest Of GCC Care Management Solutions Market
- Canada Care Management Solutions Market
- US Care Management Solutions Market
- Germany Care Management Solutions Market
- UK Care Management Solutions Market
- France Care Management Solutions Market
- Italy Care Management Solutions Market
- Spain Care Management Solutions Market
- China Care Management Solutions Market
- Japan Care Management Solutions Market
- India Care Management Solutions Market
- Australia Care Management Solutions Market
- South Korea Care Management Solutions Market
- Brazil Care Management Solutions Market
- Mexico Care Management Solutions Market
- Saudi Arabia Care Management Solutions Market
- South Africa Care Management Solutions Market
- Rest Of Europe Care Management Solutions Market
- Rest Of Asia Pacific Care Management Solutions Market
Need a Tailored Report?
Customize this report to your needs
Get 10% FREE Customization
Customize This Report