Japan Farm Equipment Market (2026-2031)

The Japan Farm Equipment Market was valued at $24 Million in 2026 and projected to reach to $31 Million by 2031, representing a compound annual growth rate of 3.4%. Japan's farm equipment market is poised for steady growth as agricultural modernization continues despite demographic headwinds.


| Market Size in | USD 26.32 MN |
| Market Forecast in | |
| CAGR | |
| Forecast Period | |
| Units Considered | Value (USD MN) |
Japan Farm Equipment Market Trends and Insights
- Japan's agricultural sector continues to modernize despite demographic challenges, with steady demand for mechanized farming solutions across both large-scale and small-scale operations.
- The market in Japan reflects the country's commitment to agricultural efficiency and technological advancement in farming practices. Driving growth in Japan are factors including aging farmer demographics spurring automation adoption, government support for agricultural modernization, and increasing labor costs that incentivize equipment investment.
- Japan's farm equipment market benefits from strong domestic manufacturing capabilities and a focus on precision agriculture technologies.
- Between 2026 and 2031, Japan is expected to see incremental market expansion as rural communities embrace equipment upgrades to maintain productivity levels..
Key Market Statistics
- CAGR (2026-2031) 3.4% CAGR
- Market Size, 2026 ~USD 24 Million
- Forecast, 2031 ~USD 31 Million
- Country Japan
Japan Farm Equipment Market Overview
Market Size & Growth :
Japan's farm equipment market is valued at $24.0 million in 2026, expanding to $31.0 million by 2031 at a CAGR of 3.4%, reflecting steady modernization of the agricultural sector.
Aging Farmer Demographics :
Japan's aging rural population drives demand for labor-saving mechanized farming solutions, creating opportunities for advanced equipment manufacturers targeting efficiency and ease of use.
Dual-Scale Operations :
The market serves both large-scale commercial farms and small-scale family operations, with equipment demand varying significantly by farm size and crop type across regions.
Technology Adoption :
Japanese farmers increasingly adopt precision agriculture and automation technologies, supported by government initiatives promoting sustainable and efficient farming practices.
Japan Farm Equipment Market Dynamics
- The country's aging farmer population creates sustained demand for mechanized solutions that reduce labor dependency and improve operational efficiency.
- Government support for agricultural innovation and sustainability initiatives further bolsters market expansion. The forecast period through 2031 will see increased adoption of advanced farming technologies, including precision equipment and automation systems.
- Market growth will be driven by replacement cycles for aging machinery, rising productivity requirements, and the need for equipment suited to Japan's diverse farming landscape, from rice paddies to vegetable cultivation..
Market Ecosystem
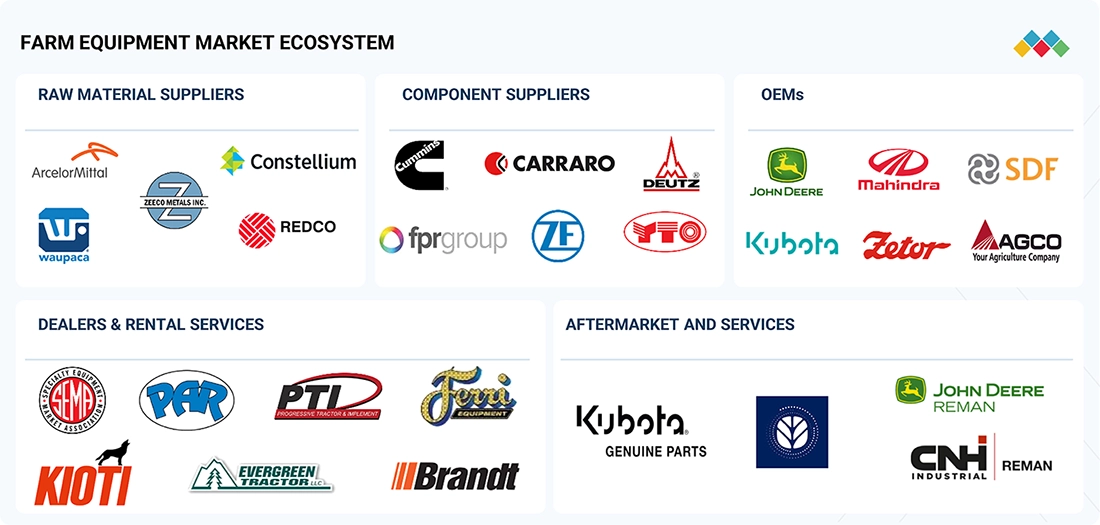
FARM EQUIPMENT MARKET SIZE, SHARE & ANALYSIS: COMMERCIAL USE CASES ACROSS INDUSTRIES
| COMPANY | USE CASE DESCRIPTION | BENEFITS |
|---|---|---|
 |
Deere offers precision agriculture solutions through its tractors, combines, and connected farming technologies. Farmers use Deere equipment for automated steering (AutoTrac with StarFire GNSS guidance), JDLink connectivity, variable-rate application, section control, field mapping, and real-time farm data management via the John Deere Operations Center to improve operational efficiency. | Improves productivity, reduces fuel and input costs, enables precise seeding and spraying, enhances decision-making through data analytics, and helps maximize crop yields |
 |
AGCO provides smart farming solutions through brands such as Fendt, Massey Ferguson, and Valtra. Its equipment are used for precision planting, harvesting, fleet management, and autonomous farming operations, supported by technologies such as FendtONE digital platform, Trimble-based guidance (AutoGuide/AutoSteer), Valtra SmartTouch controls, ISOBUS compatibility, and real-time telematics through AGCO Connectivity and PTx Trimble solutions for improved farm efficiency and automation. | Increases farm efficiency, reduces labor requirements, optimizes resource utilization, improves machine performance, and supports sustainable farming practices |
 |
CNH’s brands, including New Holland and Case IH, offer advanced tractors and digital farming platforms for planting, spraying, harvesting, and farm management applications, supported by precision farming technologies such as PLM (Precision Land Management), IntelliSteer auto-guidance, Raven precision systems, AFS (Advanced Farming Systems), ISOBUS compatibility, variable-rate technology (VRT), section control, telematics-based fleet monitoring, and real-time agronomic data analytics through connected platforms for improved productivity and input efficiency. | Enhances operational accuracy, lowers operating costs, improves field productivity, supports precision agriculture adoption, and increases overall farm profitability |
 |
Kubota specializes in compact and utility tractors widely used by small and medium-sized farms for land preparation, planting, mowing, material handling, and orchard operations, supported by precision farming and smart technologies such as Kubota Smart Farming solutions, GPS-based auto-steering, ISOBUS-compatible implements, Kubota Farm Management System (telemetry and fleet tracking), variable-rate application support (in select models), implement control systems, and basic automation features. | Provides affordable mechanization, improves labor efficiency, increases productivity on small farms, lowers maintenance costs, and offers versatile equipment for diverse agricultural tasks |
Logos and trademarks shown above are the property of their respective owners. Their use here is for informational and illustrative purposes only.
Related Ecosystem
Key Takeaways
- Japan's farm equipment market is valued at $24.0 million in 2026 and will reach $31.0 million by 2031 at a 3.4% CAGR.
- Japan's aging agricultural workforce is driving demand for automated and mechanized farming equipment solutions.
- Government initiatives in Japan support agricultural modernization and equipment adoption among farming communities.
- Japan's domestic manufacturing strength positions the country as a competitive hub for precision agriculture technology development.
Farm Equipment Market Report Scope
| Report Metric | Details |
|---|---|
| Base Year | 2026 |
| Fastest Growing Segment | BATTERY ELECTRIC (Propulsion) |
| Forecast Period | 2026–2031 |
| Growth Rate | CAGR of 4.5% from 2026 to 2031 |
| Largest Segment | 30–70 HP (Power Output) |
| Market Size Base Year (Billions) | ~USD 133.5 (2026) |
| Revenue Forecast (Billions) | ~USD 166.36 (2031) |
| Segments Covered | Power Output, Equipment Type, Function, Propulsion, Drive Type, Product Type |
Japan Farm Equipment Market Report Segmentation
6 segment dimensions are covered across the global market.
By Power Output
- 131–250 Hp
- 30–70 Hp
- 31–70 Hp
- 71–130 Hp
- <30 Hp
- >250 Hp
By Equipment Type
- Balers
- Cereal Combines
- Combines
- Feller Bunchers
- Forwarders
- Harvesters
- Loaders
- Non-Cereal Combines
- Other Equipment Type
- Other Equipment Types
- Other Rental Equipment
- Self-Propelled Sprayers
- Skidders
- Sprayers
- Swing Machines
- Tractor Mounted Sprayers
- Tractor-Mounted Sprayers
- Tractors
By Function
- Harvesting & Threshing
- Other Functions
- Plant Protection & Fertilizing
- Plowing & Cultivating
- Sowing & Planting
By Propulsion
- Battery Electric
- Hybrid Electric
- Hydrogen
By Drive Type
- 2Wd
- 4Wd
- Four-Wheel
- Two-Wheel
By Product Type
- Feller Bunchers
- Forwarders
- Harvesters
- Knuckleboom Loaders
- Other Forest Machinery
- Skidders
- Swing Machines
Target Audience
- Farm Equipment Manufacturers : Manufacturers need Japan-specific market data to assess market entry opportunities, competitive positioning, and product-market fit for both large-scale and small-scale farming segments.
- Agricultural Distributors & Dealers : Distributors require detailed market forecasts and demographic insights to optimize inventory planning, identify growth segments, and develop targeted sales strategies for Japanese farmers.
- Investment & Private Equity Firms : Investors evaluating agricultural technology companies need Japan market validation, growth trajectory analysis, and demographic trends to assess investment returns and portfolio company expansion potential.
- Government & Policy Makers : Agricultural policy officials and rural development agencies use market data to design subsidy programs, modernization initiatives, and sustainability policies aligned with actual equipment demand patterns.
- Agricultural Technology Startups : AgTech startups need Japan-specific market insights to validate business models, identify customer segments, and understand adoption barriers for precision agriculture and automation solutions.
Key Companies in the Japan Farm Equipment Market
| Company | HQ | Ownership | Strongest segments |
|---|---|---|---|
| DEERE & COMPANY | United States | Public Company | Production and Precision Agriculture,Small Agriculture and Turf,Construction and Forestry, |
| CNH INDUSTRIAL | United Kingdom | Public Company | Agriculture equipment and precision solutions,Construction equipment,Financial Services, |
| MAHINDRA & MAHINDRA | India | Public Company | Automotive (SUVs, pickups, LCVs, two-wheelers, construction equipment),Farm Equipment (tractors, implements, powerol, spares),Investments & Industrial/Consumer Services, |
| AGCO CORPORATION | United States | Public Company | High-horsepower tractors and application equipment,Utility and compact tractors,Combines and harvesting equipment, |
| KUBOTA CORPORATION | Japan | Public Company | Agricultural machinery (tractors, rice equipment, implements),Construction machinery (mini excavators, loaders, CTLs, SSLs),Engines and industrial machinery, |
| CLAAS KGAA | Germany | Private Company | Combine harvesters,Forage harvesters and forage harvesting machinery,Tractors, |
| ISEKI & CO., LTD. | Japan | Public Company | Cultivating machinery (tractors, tillers, high-clearance vehicles, mowers),Planting machinery (rice and vegetable transplanters),Harvesting machinery (combines, binders), |
| ESCORTS KUBOTA LIMITED | India | Public Company | Agricultural tractors,Implements and crop solutions,Construction and material handling equipment, |
| YANMAR HOLDINGS CO., LTD. | Japan | Private Company | Agricultural equipment (incl. smart agriculture),Industrial engines,Construction equipment, |
| DAEDONG CORPORATION | South Korea | Public Company | Tractors,Zero Turn Mowers,Utility Vehicles, |
DEERE & COMPANY
Deere & Company is a United States-based public company founded in 1837 with 73,100 employees. It is a leading manufacturer of agricultural and construction equipment.
CNH INDUSTRIAL
CNH Industrial is a United Kingdom-based public company founded in 1842 with 34,197 employees. It operates as a major producer of agricultural and construction machinery.
MAHINDRA & MAHINDRA
Mahindra & Mahindra is an India-based public company founded in 1945 with 26,765 employees. It is a significant manufacturer of tractors and agricultural equipment.
AGCO CORPORATION
AGCO Corporation is a United States-based public company founded in 1990 with 22,000 employees. It manufactures and distributes agricultural equipment and related products.
KUBOTA CORPORATION
Kubota Corporation is a Japan-based public company founded in 1890 with 52,503 employees. It is a major producer of tractors, engines, and agricultural machinery.
CLAAS KGAA
CLAAS KGAA is a Germany-based private company founded in 1913 with 11,654 employees. It manufactures agricultural machinery and harvesting equipment.
ISEKI & CO., LTD.
Iseki & Co., Ltd. is a Japan-based public company founded in 1926 with 5,199 employees. It produces tractors and agricultural equipment for domestic and international markets.
ESCORTS KUBOTA LIMITED
Escorts Kubota Limited is an India-based public company founded in 1944 with 4,323 employees. It manufactures tractors and agricultural machinery.
YANMAR HOLDINGS CO., LTD.
Yanmar Holdings Co., Ltd. is a Japan-based private company founded in 1912. It manufactures engines and agricultural equipment.
DAEDONG CORPORATION
Daedong Corporation is a South Korea-based public company founded in 1947 with 1,003 employees. It manufactures tractors and agricultural machinery.
Reasons to Buy this Report
- Precise Market Sizing : Access validated market size data for Japan ($24M in 2026) with accurate 5-year forecasts to 2031, enabling confident investment and expansion planning in this specific geography.
- Demographic Insights : Understand how Japan's aging farmer population drives equipment demand, helping you tailor product offerings and marketing strategies to address labor shortage solutions and ease-of-use requirements.
- Competitive Positioning : Benchmark your products against market trends specific to Japan's dual-scale farming operations, identifying gaps in small-scale and large-scale equipment segments for targeted growth.
- Technology Adoption Trends : Gain insights into precision agriculture and automation adoption rates in Japan, informing R&D priorities and go-to-market strategies for advanced farming solutions.
- Government Policy Context : Learn how Japanese agricultural policies and sustainability initiatives shape equipment demand, enabling alignment with regulatory trends and subsidy programs affecting market dynamics.
Frequently asked questions
What is the current size of Japan's farm equipment market?
Japan's farm equipment market is estimated at $24.0 million in 2026.
What is the projected market size for Japan's farm equipment by 2031?
Japan's farm equipment market is forecast to reach $31.0 million by 2031.
What is the CAGR for Japan's farm equipment market?
Japan's farm equipment market is expected to grow at a compound annual growth rate of 3.4% from 2026 to 2031.
What factors are driving growth in Japan's farm equipment market?
Key growth drivers in Japan include an aging farmer population requiring automation, rising labor costs, government agricultural modernization support, and increased adoption of precision farming technologies.
How does Japan's farm equipment market compare to other regions?
Japan's 3.4% CAGR is slightly below the global average of 4.5%, reflecting the country's mature agricultural sector and demographic constraints, though Japan maintains strong technological capabilities in farm equipment manufacturing.
RESEARCH METHODOLOGY
This research study involved extensive secondary sources, such as company annual reports/presentations, industry association publications, industry magazine articles, directories, technical handbooks, World Economic Outlook, technical articles, and databases, to identify and collect information on the farm equipment market. In-depth interviews were conducted with various primary respondents, including key industry participants, subject-matter experts, C-level executives of key market players (farm equipment OEMs, farm equipment system suppliers, and technology providers), and industry consultants, among other experts, to obtain and verify critical qualitative and quantitative information and assess market prospects.
Secondary Research
Secondary sources for this research study included farm equipment associations and organizations, corporate filings (such as annual reports, investor presentations, and financial statements), and trade, business, and industry associations. Secondary data was collected and analyzed to determine the overall market size, which was further validated by primary research.
Primary Research
Extensive primary research was conducted after understanding the farm equipment market scenario through secondary research. Several primary interviews were conducted with market experts across major regions, namely, North America, Europe, and Asia Oceania. Approximately 80% of primary interviews were conducted from the demand side and 20% interviews from the equipment providers. Primary data was collected through questionnaires, emails, and telephonic interviews.
The canvassing of primaries covered various departments within organizations, such as sales, operations, and marketing, to provide a holistic viewpoint in the report. After interacting with industry experts, brief sessions were conducted with highly experienced independent consultants to reinforce the findings from primaries. This and the opinions of in-house subject matter experts led to the conclusions described in the remainder of this report.

Notes: Farm equipment providers are the key suppliers for implements and additional equipment that are used along with tractors.
To know about the assumptions considered for the study, download the pdf brochure
Market Size Estimation
The bottom-up approach was used to estimate and validate the size of the farm tractor market in terms of power output. In this approach, country-wise sales data of farm tractors were calculated through secondary sources, and different industry associations and organizations' sales statistics were derived. Following this, secondary research was used to find the percentage penetration of power output in farm tractors per country. This was done by referring to publications from OEMs and country-level association magazines and company-wise model mapping of their tractor offerings. Country-level tractor sales were multiplied by the country-level penetration of each power output category to determine the market size of farm tractors by power output in terms of volume. The forecasting was made based on the following factors, such as the Middle East and Europe war conditions, GDP growth rate and government investments. In terms of volume, each power output category's country-level farm tractor market size was added to derive the regional market. All the regional markets were added to derive the power output from the global farm tractor market by power output.
The forecast of the country-wise tractors is based on multiple factors such as OEM investments in the country for tractor manufacturing plants, government support (subsidies, incentives for farm mechanization) and regulations toward emissions, technological landscape, economic conditions, farm industry growth, crop cultivation, and monsoon demand, and future model launch announcements.
The country-level farm tractor market was then multiplied by the country-level average selling price of tractors by each power output category, which resulted in the country-level market size.
The tractor ASP in terms of power output for each country was derived from secondary sources and model mapping and validated through primary sources. The addition of respective countries provides the regional-level market. Then, the summation of regional-level markets provides the global farm tractor market by power output in terms of value. A similar approach was used to derive the farm tractor market by equipment type and the rental market by equipment type. However, these submarkets were analyzed at the regional level.
Top-Down Approach
The top-down approach estimated and validated the market by drive type in terms of volume and value. The farm tractor market value (USD million) and volume (000' units) by region were derived from the global market. The penetration of each drive type at the regional level was derived from secondary sources and model mapping and validated through interviews with experts. The model mapping revealed information such as dominant drive type, model with drive type offerings by key OEMs, etc. The penetration of each drive type was multiplied by the regional farm tractor market to get the farm tractor market value and volume by drive type for each region. All region-wise markets were summated to derive the total farm tractor market value and volume by drive type. The top-down approach was followed by drive type, equipment type, implement, farm equipment rental, electric tractor, and propulsion segments

Data Triangulation
After arriving at the overall market size, the market was split into several segments and subsegments using the market size estimation processes explained above. Data triangulation and market breakdown procedures were employed to complete the overall market engineering process and arrive at the exact statistics of each market segment and subsegment, wherever applicable. The data was triangulated by studying various factors and trends from both the demand and supply sides.
Market Definition
Farm equipment are machines used on farmlands to perform various agricultural activities. These machines help enhance efficiency and productivity. Tractors, combines, sprayers, balers, and implements are the key farm equipment categories used in several farming activities, such as ploughing, planting and seeding, harvesting, crop care, and threshing.
Key Stakeholders
- Farm Equipment Manufacturers
- Tier 1 Suppliers (engine, suspension, brakes, etc.)
- Farm Equipment Component Suppliers
- Farm Equipment Rental Companies
- Farm Equipment Dealers and Distributors
- Government and Regulatory Authorities
- Research Professionals
- Farm Equipment Manufacturing Associations
- Farm Equipment Importers, Retailers, and Dealers
Report Objectives
- To segment and forecast the size of the farm equipment market in terms of volume (units) and value (USD million) from 2022 to 2033
- To define, describe, and forecast the farm tractor market by value and volume based on
- Power output (<30 HP, 31–70 HP, 71–130 HP, 131–250 HP, and >250 HP) at country and regional levels
- Drive type (two-wheel drive and four-wheel drive) at the regional level
- Region [Asia Oceania, Europe, North America, and the Rest of the World (RoW)], along with key countries in each of these regions
- To define, describe, and forecast the farm equipment market by value based on equipment type (cereal combines, non-cereal combines, balers, self-propelled sprayers, and tractor-mounted sprayers)
- To define, describe, and forecast the farm implements market by value, based on function (plowing & cultivating, sowing & planting, plant protection & fertilizing, harvesting & threshing, and others) at the regional level
- To define, describe, and forecast the farm equipment rental market by value based on equipment type (tractors, combines, sprayers, balers, and others) at the regional level
- To define, describe, and forecast the farm tractor rental market by value based on
- Power output (<30 HP, 31–70 HP, 71–130 HP, 131–250 HP, and >250 HP) at the regional level
- To define, describe, and forecast the electric tractor market, by value and volume, based on propulsion (battery electric, hybrid electric, hydrogen) at the regional level
- To define, describe, and forecast the forestry equipment market by value based on equipment type (feller buncher, harvester, forwarder, skidder, swing machines, knuckleboom loader, others)
- To understand the market dynamics (drivers, restraints, opportunities, and challenges) of the farm equipment market
- To strategically analyze markets concerning individual growth trends, prospects, and contributions to the total market
- To analyze the opportunities for stakeholders and details of the competitive landscape for market leaders
- To analyze the market share of the key players in the farm equipment market
- To strategically analyze the market with supply chain analysis, market ecosystem, trade analysis, case studies, ASP analysis, conferences and events, OEM analysis, OEM wise sales data for key countries, OEM wise sales data for combine harvester in key countries, patent analysis, Tractor models from top OEMs with price range, farm equipment market outlook by country, OEM strategy for future investment by the key players, total cost of ownership for electric and diesel tractor, total cost of ownership, investment and funding scenario, trends/disruptions impacting buyers, technology trends, and regulatory analysis
- To track and analyze competitive developments such as deals (joint ventures, mergers & acquisitions, partnerships, collaborations), new product developments, and other activities carried out by key industry participants
- To study the following concerning the market:
- Supply Chain Analysis
- Ecosystem Analysis
- Technology Analysis
- Trade Analysis
- Case Study Analysis
- Patent Analysis
- Regulatory Landscape
- Conferences and Events
- Average Selling Price Analysis
- Buying Criteria
- OEM Analysis
- OEM Sales Data for Tractor/Combines for Key Countries
- Farm Equipment Market Outlook, By Countries
- OEM Strategies: Future Investments by the Key Players
- Total Cost of Ownership: Farm Equipment Market
- To analyze opportunities for stakeholders and the competitive landscape for market leaders
- To track and analyze competitive developments such as product developments, deals, and others undertaken by the key industry participants
Available customizations:
With the given market data, MarketsandMarkets offers customizations based on the company's needs.
farm equipment MARKET, by drive Type & Country
-
Asia Oceania
- China
- India
- Japan
- South Korea
- Australia
- Rest of Asia Oceania
-
Europe
- Germany
- France
- UK
- Spain
- Russia
- Italy
- Poland
- Türkiye
- Rest of Europe
- North America
- US
- Canada
- Mexico
- Rest of the World
- Brazil
- Argentina
- Others
Agriculture Sprayer MARKET, by type
- Self-propelled sprayers
- Tractor-mounted sprayers
- Trailed sprayers
- Handheld sprayers
Profiling of additional market players (up to 5)
farm equipment MARKET, by power output & Country
- Asia Oceania
- China
- India
- Japan
- South Korea
- Australia
- Rest of Asia Oceania
- Europe
- Germany
- France
- UK
- Spain
- Russia
- Italy
- Poland
- Türkiye
- Rest of Europe
- North America
- US
- Canada
- Mexico
- Rest of the World
- Brazil
- Argentina
- Others
Get the Full Farm Equipment Market Report
Full forecast, segment splits, and company analysis for all Farm Equipment Market.
- Australia Farm Equipment Market
- China Farm Equipment Market
- India Farm Equipment Market
- South Korea Farm Equipment Market
- France Farm Equipment Market
- Germany Farm Equipment Market
- Italy Farm Equipment Market
- Poland Farm Equipment Market
- Russia Farm Equipment Market
- Spain Farm Equipment Market
- Turkey Farm Equipment Market
- UK Farm Equipment Market
- Canada Farm Equipment Market
- Mexico Farm Equipment Market
- US Farm Equipment Market
- Argentina Farm Equipment Market
- Brazil Farm Equipment Market
Need a Tailored Report?
Customize this report to your needs
Get 10% FREE Customization
Customize This Report
