Europe Green Data Center Market (2025-2030)

The Europe Green Data Center Market was valued at $11365.1 Million in 2025 and projected to reach to $35199.4 Million by 2030, representing a compound annual growth rate of CAGR 25.4%. Europe's green data center market is positioned for exceptional growth, driven by the continent's commitment to climate neutrality and digital sustainability.


| Market Size in | USD 26.32 MN |
| Market Forecast in | |
| CAGR | |
| Forecast Period | |
| Units Considered | Value (USD MN) |
Europe Green Data Center Market Trends and Insights
- This growth trajectory reflects Europe's stringent environmental regulations and corporate sustainability commitments driving adoption of energy-efficient data center infrastructure.
- Europe leads global initiatives in renewable energy integration, with major markets including Germany, the United Kingdom, and the Nordic region investing heavily in cooling technologies and power optimization solutions. The 25.4% compound annual growth rate (CAGR) through 2030 underscores Europe's commitment to decarbonization across the ICT sector.
- Europe's regulatory framework, including the EU Green Deal and Digital Europe Programme, accelerates green data center deployment among hyperscalers and enterprise operators.
- Data center operators across Europe are increasingly adopting renewable energy sources, liquid cooling systems, and AI-driven energy management to meet both regulatory requirements and stakeholder expectations for sustainable operations..
Key Market Statistics
- CAGR (2025-2030) CAGR 25.4%
- Market Size, 2025 ~USD 11365.1 Million
- Forecast, 2030 ~USD 35199.4 Million
- Geography Europe
Europe Green Data Center Market Overview
Regulatory Leadership :
Europe's stringent environmental regulations, including the EU Energy Efficiency Directive and Digital Operational Resilience Act, are driving mandatory adoption of green data center technologies across the region, creating sustained market demand.
Renewable Energy Integration :
European data centers are leading global initiatives in renewable energy adoption, with major operators committing to 100% renewable power by 2030, supported by abundant wind and hydroelectric resources across the continent.
Corporate Sustainability Commitments :
Major European enterprises and tech giants are implementing aggressive sustainability targets, requiring data center operators to invest in energy-efficient infrastructure, cooling innovations, and carbon-neutral operations.
Market Expansion Trajectory :
Europe's green data center market is projected to grow from $11,365.1 million in 2025 to $35,199.4 million by 2030, representing a 25.4% CAGR, outpacing many global regions in sustainable infrastructure investment.
Europe Green Data Center Market Dynamics
- Regulatory frameworks such as the EU's Green Deal and corporate ESG mandates are compelling data center operators to transition toward energy-efficient technologies, renewable energy sources, and innovative cooling solutions.
- The region's strong infrastructure base, combined with government incentives and private sector investments, creates a favorable ecosystem for green data center expansion. Looking ahead to 2030, Europe will continue to set global benchmarks for sustainable data center operations.
- Investment in advanced technologies like liquid cooling, AI-driven energy optimization, and waste heat recovery will accelerate adoption.
- The convergence of regulatory pressure, competitive differentiation, and stakeholder demand positions Europe as the world's leading market for environmentally responsible data center infrastructure..
Market Ecosystem
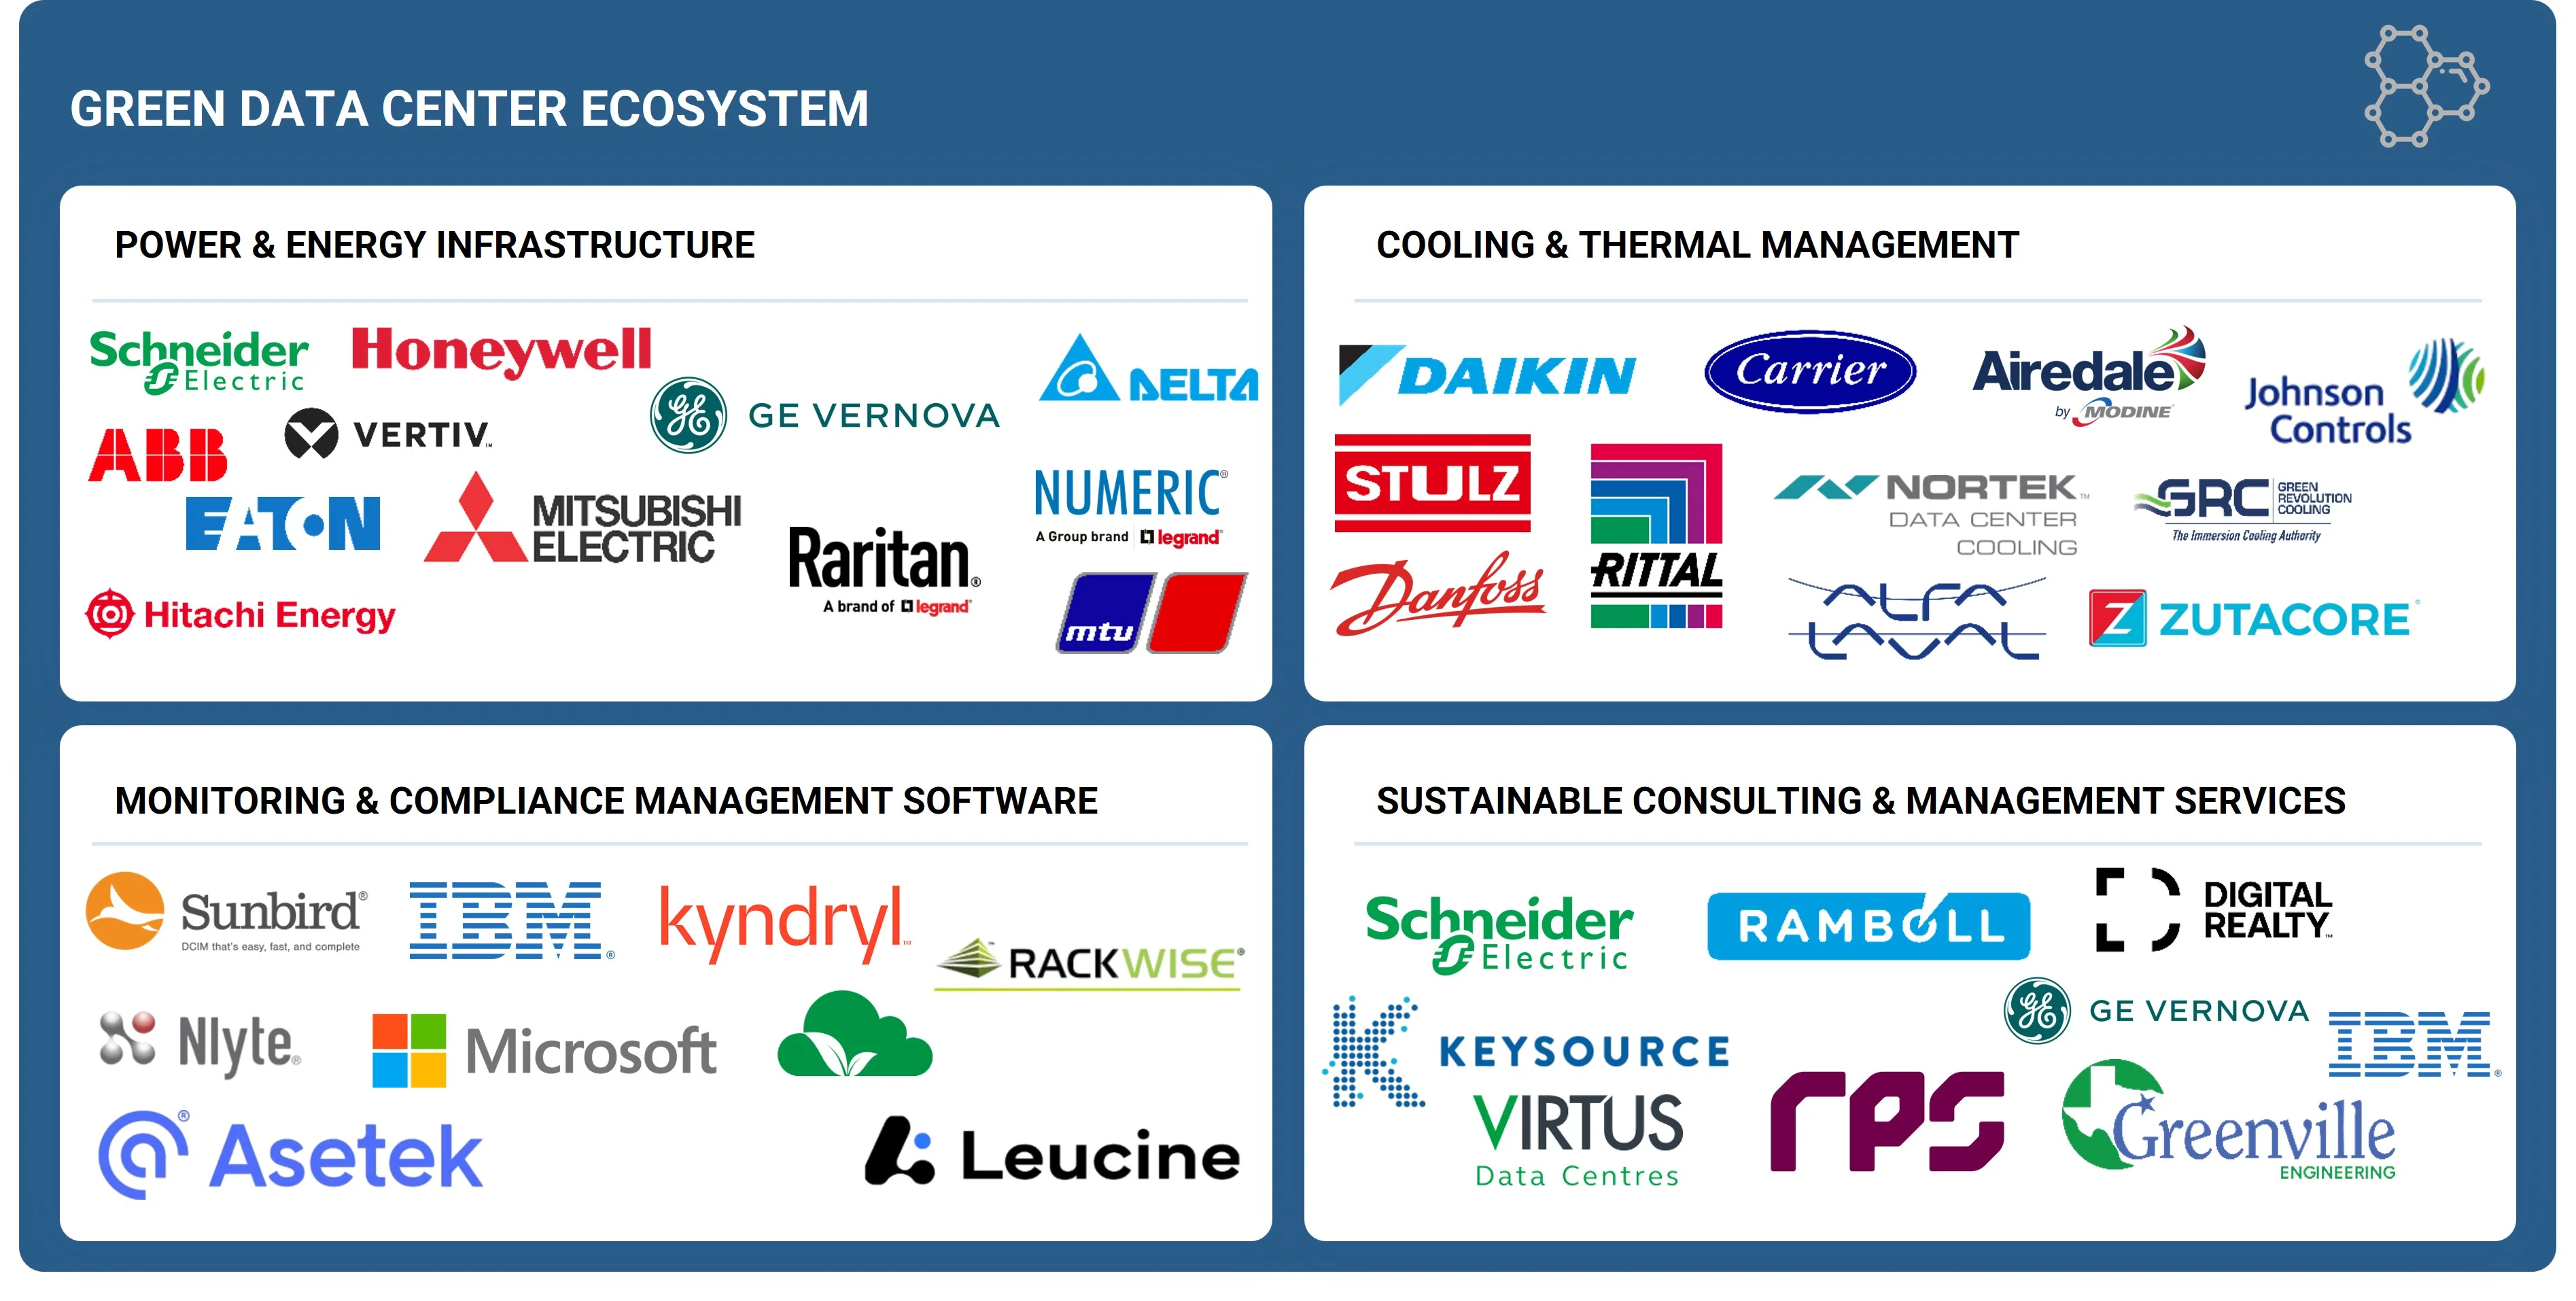
GREEN DATA CENTER MARKET: COMMERCIAL USE CASES ACROSS INDUSTRIES
| COMPANY | USE CASE DESCRIPTION | BENEFITS |
|---|---|---|
 |
Greenergy and A-Kaabel drive green data center growth with Vertiv rack PDUs | Seamless scaling from 4-6 kW racks to over 10 kW, improved energy efficiency with PUE reduced to 1.4, enhanced uptime performance surpassing 99.982% |
 |
Siemens supports BMO Financial Group with white space cooling optimization (WSCO) | Achieved 55% reduction in CRAH fan energy consumption, reduced the number of continuously operating CRAH units by 64%, improved thermal control & stability |
|
|
Siemens delivers AI-powered optimization at Greenergy Data Centers, Estonia | Improved cooling efficiency by 30%, achieved a PUE below 1.2, enabled AI-based predictive cooling, and reduced carbon footprint by reusing waste heat for office heating |
 |
Green Revolution Cooling enables green supercomputing at Texas Advanced Computing Center (TACC) with immersion cooling | Achieved a PUE of 1.1, significantly improving energy efficiency, reduced carbon footprint by up to 40%, enabled reliable cooling of 280W CPUs |
 |
Rittal lowers carbon footprint at Scottish Qualifications Authority (SQA) Data Centers | Reduced energy consumption and carbon footprint, freed up floor space by shifting to rack-mounted UPS and in-row cooling, enabled higher system reliability with N+1 redundancy in both cooling and UPS |
Logos and trademarks shown above are the property of their respective owners. Their use here is for informational and illustrative purposes only.
Related Ecosystem
Data Centre And Networking
- Software-Defined Networking (SDN)
- Mid-Sized Data Centers
- Small Data Centers
- Remote Monitoring
- Smart Healthcare
- Cisco Systems, Inc.
- HUAWEI TECHNOLOGIES CO LTD
- Hewlett Packard Enterprise Company
- MITSUBISHI ELECTRIC INFORMATION SYSTEMS CORPORATION
- MITSUBISHI ELECTRIC INFORMATION NETWORK CORPORATION
Key Takeaways
- Europe's green data center market will grow from $11.4B (2025) to $35.2B (2030) at a 25.4% CAGR, driven by regulatory mandates and sustainability goals.
- EU environmental policies and the Green Deal framework are primary catalysts accelerating green data center adoption across Europe.
- Europe's Nordic and Western European regions lead in renewable energy integration and advanced cooling technologies for data centers.
- Enterprise and hyperscaler investments in energy-efficient infrastructure position Europe as a global leader in sustainable data center innovation.
Green Data Center Market Report Scope
| Report Metric | Details |
|---|---|
| Base Year | 2025 |
| Fastest Growing Segment | GREEN LIQUID COOLING (Cooling Infrastructure) |
| Forecast Period | 2025–2030 |
| Growth Rate | CAGR of 26.4% from 2025 to 2030 |
| Largest Segment | LARGE & HYPERSCALE DATA CENTERS (50 MW & ABOVE) (Data Center Size & Capacity) |
| Market Size Base Year (Billions) | ~USD 48.27 (2025) |
| Revenue Forecast (Billions) | ~USD 155.75 (2030) |
| Segments Covered | Component, Infrastructure, Energy Infrastructure, Cooling Infrastructure, Software, Services, Data Center Size & Capacity, Data Center Type, Enterprise Data Center, Service |
Europe Green Data Center Market Report Segmentation
10 segment dimensions are covered across the global market.
By Component
- Infrastructure
- Services
- Software
- Solutions
By Infrastructure
- Cooling Infrastructure
- Energy Infrastructure
By Energy Infrastructure
- Energy-Effective Power Distribution
- Power Backup & Energy Storage
- Renewable Power Generators
By Cooling Infrastructure
- Green Air Cooling
- Green Liquid Cooling
By Software
- Building Management
- Compliance
- Data Center Infrastructure Management
- Data Center Infrastructure Management (Dcim)
- Other Software
By Services
- Eco-Friendly Integration & Deployment
- Other Services
- Others (Audit & Assessment, Migration And Decommissioning)
- Others Services
- Strategy Consulting & Energy Audits
- Strategy Consulting And Energy Audits
- Sustainable Operation & Maintenance Services
- Sustainable Operations & Maintenance Services
By Data Center Size & Capacity
- Edge & Micro Centers (1–5 Mw)
- Edge & Micro Data Centers (1–5 Mw)
- Large & Hyperscale Data Centers (50 Mw & Above)
- Medium Data Centers (5–50 Mw)
By Data Center Type
- Cloud & Hyperscale Data Centers
- Colocation Data Centers
- Enterprise Data Centers
By Enterprise Data Center
- Banking, Financial Services, & Insurance
- Banking, Financial Services, & Insurance (Bfsi)
- Bfsi
- Energy & Utilities
- Enterprise Data Center
- Enterprise Data Centers
- Government & Defense
- Healthcare & Life Sciences
- Manufacturing
- Media & Entertainment
- Other Enterprise Data Centers
- Retail & E-Commerce
- Technology & Software
- Telecommunications
By Service
- Eco-Friendly Integration & Deployment
- Other Services
- Strategy Consulting & Energy Audits
- Sustainable Operation & Maintenance Services
Target Audience
- Data Center Operators & Providers : European data center operators need this market intelligence to understand regulatory requirements, identify investment opportunities in green infrastructure, and develop competitive strategies aligned with sustainability mandates.
- Enterprise IT & Sustainability Leaders : Corporate decision-makers responsible for IT infrastructure and ESG commitments require detailed market insights to evaluate green data center providers, plan migrations, and meet corporate sustainability targets across European operations.
- Technology Vendors & Solution Providers : Suppliers of cooling systems, renewable energy solutions, and energy management technologies need market data to identify growth opportunities, target key accounts, and develop products aligned with European market demands.
- Investment & Financial Analysts : Investors, private equity firms, and financial analysts evaluating European data center investments require comprehensive market forecasts, growth drivers, and regional dynamics to assess portfolio opportunities and valuations.
- Government & Policy Makers : European regulatory bodies and government agencies need market intelligence to inform policy development, incentive programs, and infrastructure planning that support the region's digital and climate neutrality objectives.
Key Companies in the Europe Green Data Center Market
| Company | HQ | Ownership | Strongest segments |
|---|---|---|---|
| PCCW | Hong Kong | Public Company | Infrastructure – Power Backup & Energy Storage,Infrastructure – Green Air Cooling and Green Liquid Cooling,Infrastructure – Renewable Power Generator and Energy-Effective Power Distribution, |
| LATTICE SEMICONDUCTOR | United States | Public Company | Low-power and small FPGA platforms (Lattice Nexus, Nexus 2, Certus-NX, CertusPro, Certus-N2, MachXO, iCE, CrossLink families),Mid-range FPGA platform (Lattice Avant and Avant-G/Avant-E/Avant-X variants),Design software, solution stacks, IP licensing, and edge AI applications, |
| TELIA COMPANY | Sweden | Public Company | |
| COLT TECHNOLOGY SERVICES GROUP LIMITED | United Kingdom | Private Company | Data center interconnection and cross-connectivity into green facilities,Cloud access and managed connectivity overlaying green data centers,Voice, legacy services, and non-green-linked connectivity, |
| PC CONNECTION | United States | Public Company | |
| ZENSAR TECHNOLOGIES LTD | India | Public Company | Cloud Infrastructure and Security (including green data center–related services),Digital and Application Services,Data Engineering, Analytics, and AI Solutions, |
| NUTANIX INC | United States | Public Company | Nutanix Cloud Infrastructure & AOS/AHV,Nutanix Cloud Manager & Operations (including Cost Governance),Data Services & Storage (Unified Storage, Files, Objects, Volumes, Data Lens), |
| SCHNEIDER ELECTRIC | Canada | Public Company | Energy-Effective Power Distribution, Power Backup & Energy Storage,Green Air Cooling and Green Liquid Cooling,Renewable Power Generator and Microgrids, |
| VERTIV | United States | Public Company | Energy-Effective Power Distribution, Power Backup & Energy Storage,Green Air Cooling and Green Liquid Cooling,Software (DCIM, Building Management, Compliance) and Lifecycle Services, |
| EATON | Ireland | Public Company | |
| DAIKIN | Japan | Public Company | Green air cooling and HVAC for data centers,Emerging green liquid cooling and hybrid solutions,Power and software-adjacent offerings (BMS integration, controls, limited DCIM touchpoints), |
| ABB | India | Public Company | Renewable Power Generator & Energy-Effective Power Distribution,Power Backup & Energy Storage,Green Air & Liquid Cooling Infrastructure, |
| DELTA ELECTRONICS | Taiwan | Public Company | Power Electronics for Data Centers (UPS, power quality, renewable interfaces),Thermal Management and Cooling (air and liquid),Software and Building Management (DCIM-adjacent, BMS, compliance), |
| CARRIER | United States | Public Company | Green Air Cooling and Building-Linked HVAC,Building Management, Energy Management, and DCIM-Adjacent Software,Power Backup, Energy Storage, and Renewable-Linked Solutions, |
| SIEMENS | Germany | Public Company | Energy-Effective Power Distribution,Power Backup & Energy Storage,Renewable Power Generator Integration, |
| GE VERNOVA | United States | Public Company | Renewable Power Generator,Energy-Effective Power Distribution,Power Backup & Energy Storage, |
| JOHNSON CONTROLS | Ireland | Public Company | Green Air Cooling and HVAC for Data Centers,Building Management and Compliance Software for Data Centers,Energy-Effective Power Distribution, Power Backup, and Energy Storage Integration, |
| HONEYWELL INTERNATIONAL INC. | United States | Public Company | Energy-Effective Power Distribution & Power Backup Control,Green Air Cooling & Environmental Control,DCIM and Building Management Software for Data Centers, |
PCCW
PCCW is a Hong Kong-based public company founded in 1925 with 14,600 employees, operating as a major telecommunications and technology services provider in Asia.
LATTICE SEMICONDUCTOR
Lattice Semiconductor is a United States-based public company founded in 1983 with 1,174 employees, designing and manufacturing programmable logic devices and related semiconductors.
TELIA COMPANY
Telia Company is a Swedish public company founded in 1853 with 14,552 employees, operating as a major telecommunications and digital services provider in Northern Europe.
COLT TECHNOLOGY SERVICES GROUP LIMITED
Colt Technology Services Group Limited is a United Kingdom-based private company founded in 1992 with 42 employees, providing technology and telecommunications services.
PC CONNECTION
PC Connection is a United States-based public company founded in 1982 with 2,525 employees, operating as a distributor and reseller of information technology products and services.
ZENSAR TECHNOLOGIES LTD
Zensar Technologies Ltd is an India-based public company founded in 1963 with 10,066 employees, providing IT services, consulting, and digital transformation solutions.
NUTANIX INC
Nutanix Inc is a United States-based public company founded in 2009 with 7,800 employees, specializing in cloud computing and hyperconverged infrastructure software.
SCHNEIDER ELECTRIC
Schneider Electric is a Canada-based public company founded in 1836 with 158,122 employees, operating as a global leader in energy management and automation solutions.
VERTIV
Vertiv is a United States-based public company with 34,000 employees, providing critical infrastructure and continuity solutions for data centers and communication networks.
EATON
Eaton is an Ireland-based public company founded in 1911 with 97,303 employees, manufacturing diversified industrial products including electrical components and power management systems.
DAIKIN
Daikin is a Japan-based public company founded in 1924 with 104,095 employees, specializing in air conditioning, refrigeration, and heating systems.
ABB
ABB is an India-based public company founded in 1883 with 111,900 employees, providing robotics, power, and automation technology solutions globally.
DELTA ELECTRONICS
Delta Electronics is a Taiwan-based public company founded in 1971 with 85,684 employees, manufacturing power supplies, thermal management, and infrastructure solutions.
CARRIER
Carrier is a United States-based public company founded in 2019 with 47,000 employees, providing HVAC, refrigeration, fire and security solutions for residential and commercial markets.
SIEMENS
Siemens is a Germany-based public company founded in 1847 with 310,312 employees, operating as a global conglomerate in electrification, automation, and digitalization.
GE VERNOVA
GE Vernova is a United States-based public company founded in 2023 with 78,000 employees, focusing on energy transition and renewable power solutions.
JOHNSON CONTROLS
Huawei Digital Power Technologies Co., Ltd. is a China-based private company founded in 1987 with 10,000 employees, specializing in digital power and energy solutions.
HONEYWELL INTERNATIONAL INC.
Countries within Europe - compare and drill down
| Country | 2025 size (native) |
|---|---|
| UK | USD 9891 Million |
| Germany | USD 8694.3 Million |
| France | USD 4575.9 Million |
| Italy | USD 2112 Million |
| Rest Of Europe | USD 9926.2 Million |
Country market size visualization
Reasons to Buy this Report
- Regulatory Compliance Intelligence : Gain comprehensive insights into Europe's evolving regulatory landscape, including EU directives and national standards, enabling organizations to align data center operations with mandatory environmental requirements and avoid compliance risks.
- Market Sizing & Forecasting : Access detailed market projections showing Europe's green data center market expanding from $11.4B to $35.2B by 2030, providing strategic planning data for investment decisions and competitive positioning across the region.
- Country-Level Analysis : Understand market dynamics across key European markets including UK, Germany, France, and Italy, with granular data on market sizes, growth rates, and regional opportunities for targeted expansion strategies.
- Technology & Innovation Trends : Identify emerging green data center technologies gaining traction in Europe, including liquid cooling systems, renewable energy integration, and AI-powered energy optimization, to inform technology roadmaps and vendor selection.
- Competitive Landscape Mapping : Benchmark against European market leaders and emerging players in the green data center space, understanding competitive strategies, market share distribution, and differentiation opportunities specific to the region.
Frequently asked questions
What is the projected market size for green data centers in Europe by 2030?
Europe's green data center market is projected to reach $35,199.4 million by 2030, growing from $11,365.1 million in 2025.
What is the CAGR for Europe's green data center market?
Europe's green data center market is expected to grow at a compound annual growth rate (CAGR) of 25.4% from 2025 to 2030.
Which European regions are leading in green data center adoption?
The Nordic countries, Germany, the United Kingdom, and other Western European nations are leading in green data center deployment due to strong renewable energy infrastructure and regulatory support.
What regulatory factors are driving Europe's green data center market growth?
The EU Green Deal, Digital Europe Programme, and stringent environmental regulations are key drivers pushing data center operators across Europe to adopt sustainable and energy-efficient technologies.
What technologies are European data centers prioritizing for sustainability?
European data centers are increasingly adopting renewable energy sources, liquid cooling systems, AI-driven energy management, and power optimization solutions to reduce their environmental footprint.
RESEARCH METHODOLOGY
This research study involved the use of extensive secondary sources, directories, and databases, such as D&B Hoovers, Bloomberg Businessweek, and Factiva, to identify and collect information for a technical, market-oriented, and commercial study of the green data center market. Additionally, a few other market-related reports and analyses published by various industry associations and consortia, such as the National Security Agency (NSA) and SC Magazine, were considered while conducting extensive secondary research.
Secondary Research
The market size of companies offering green data centers was determined based on secondary data available through paid and unpaid sources, analyzing the product portfolios of major companies in the ecosystem, and rating the companies based on their product capabilities and business strategies. Various sources were referred to in the secondary research process to identify and collect information for the study. The secondary sources included annual reports, press releases, investor presentations of companies, product data sheets, white papers, journals, certified publications, and articles from recognized authors, government websites, directories, and databases.
Primary Research
In the primary research process, various primary sources from the supply and demand sides were interviewed to obtain qualitative and quantitative information for this report. The primary sources from the supply side included industry experts, such as chief executive officers (CEOs), vice presidents (VPs), marketing directors, technology and innovation directors, and related key executives from various key companies and organizations operating in the green data center market.
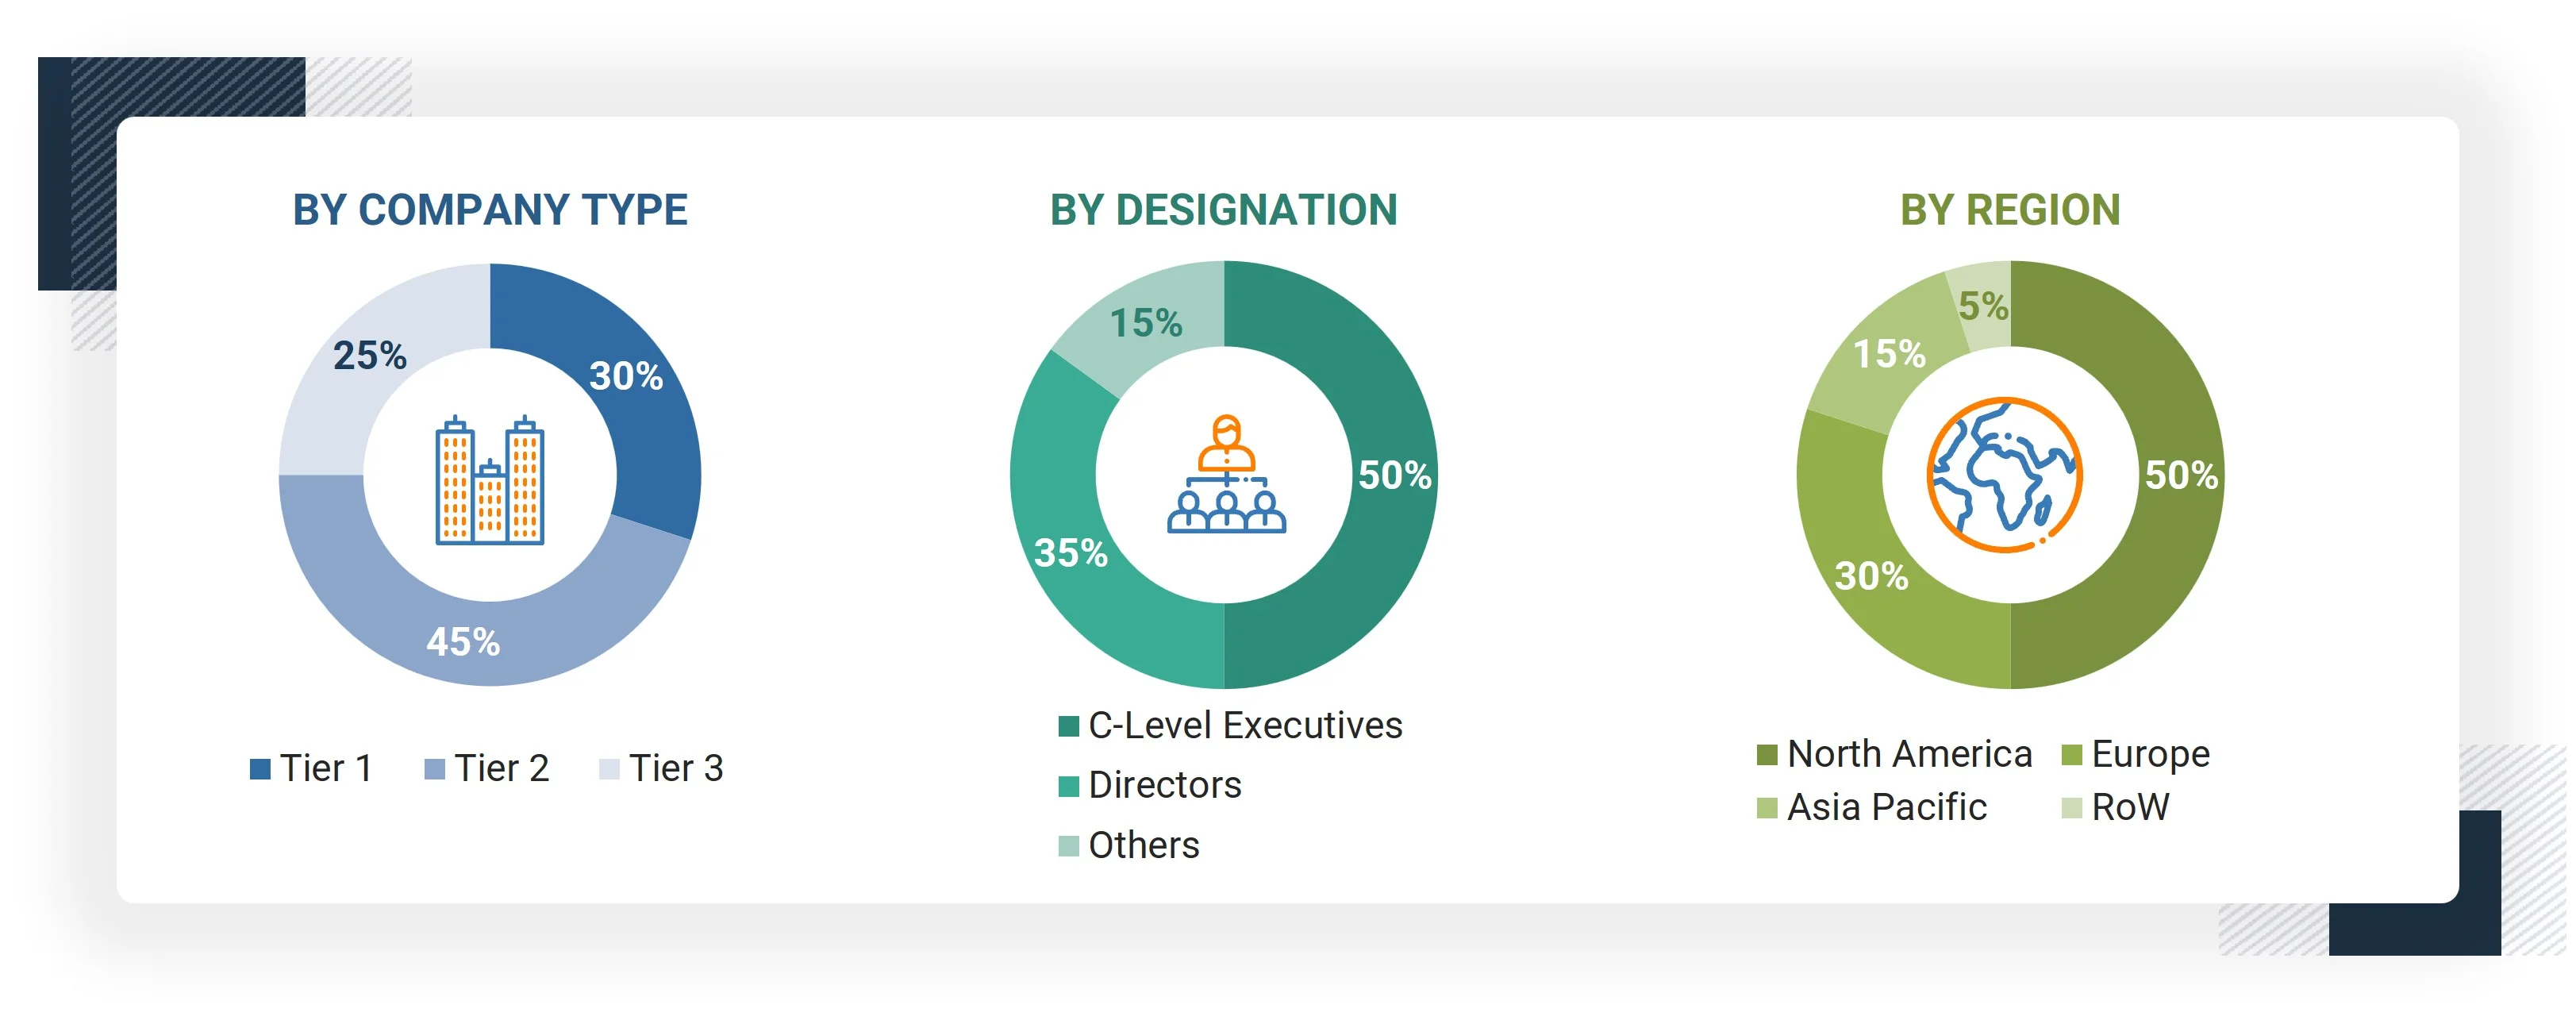
Note: Tier 1 companies’ revenues are more than USD 10 billion; tier 2 companies’ revenues range between USD 1 and 10 billion; and tier 3 companies’ revenues range between USD 500 million and USD 1 billion. Other designations include sales managers, marketing managers, and product managers.
Source: Industry Experts
To know about the assumptions considered for the study, download the pdf brochure
Market Size Estimation
Multiple approaches were adopted to estimate and forecast the green data center market. The first approach involved estimating the market size by companies’ revenue generated through the sale of green data center products.
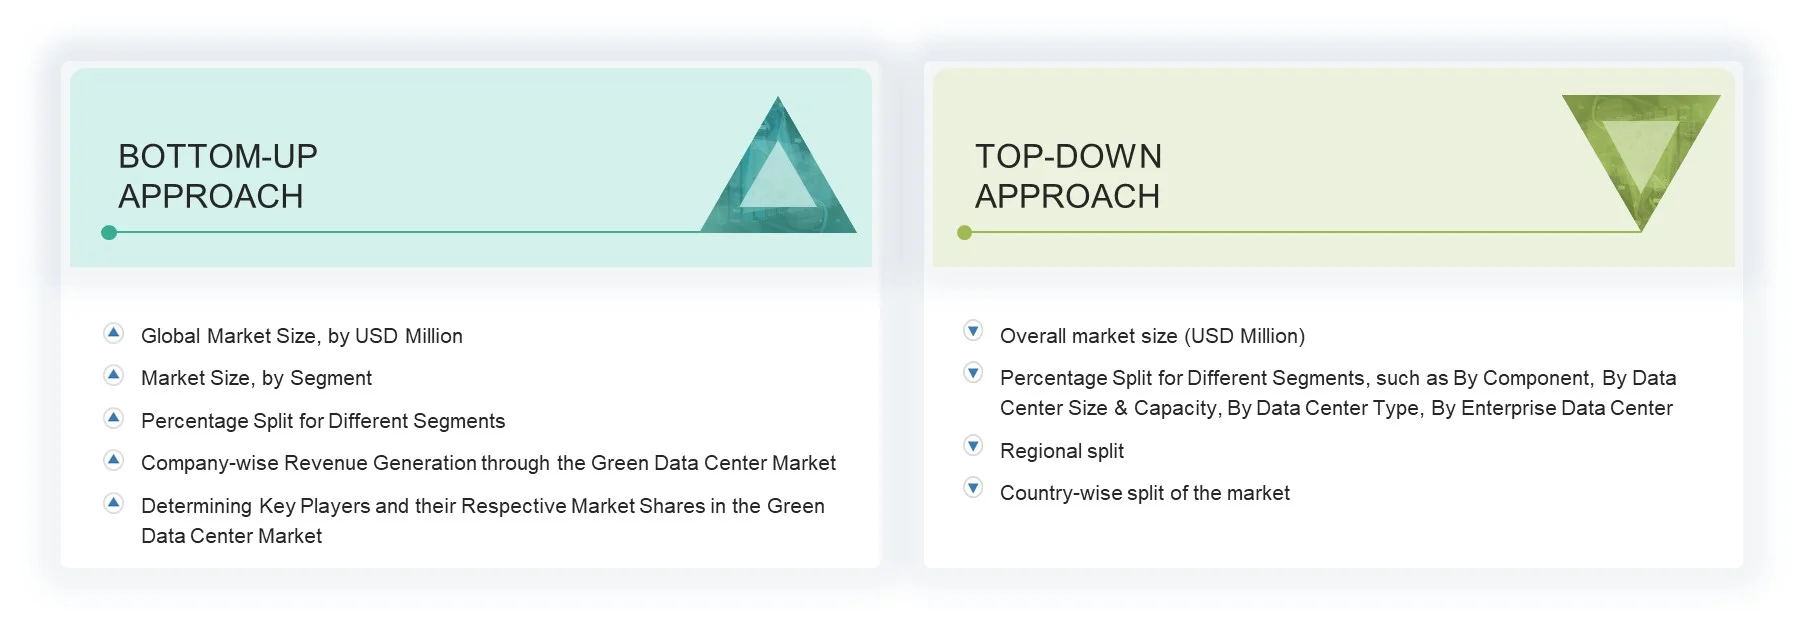
Market Size Estimation Methodology: Top-down Approach
The top-down methodology compiled a comprehensive database of all suppliers active within the green data center market. Revenue generation for these key industry players was assessed by analyzing annual financial statements, official press releases, capital investments, investor decks, premium market databases, and expert interviews. Every supplier's product portfolio was analyzed across parameters including architecture, level of tailorability, solution type, deployment scenario, vertical end user, and geographic location. Market estimates were cross-verified using a combination of primary and secondary intelligence gathering. The primary research phase involved detailed discussions to gather strategic perspectives from executive stakeholders, such as CIOs, CEOs, VPs, division heads, and commercial leads. Finally, the calculated market figures were cross-referenced against historical industry repositories for rigorous validation.
Market Size Estimation Methodology: Bottom-up Approach
The bottom-up methodology determined the deployment rate of green data center solutions across diverse industry verticals in major countries, accounting for regions that drive the majority of market share. To ensure cross-validation, the integration of eco-friendly data center infrastructure across enterprises and application scenarios within these regions was mapped and projected. Specific implementation cases across geographies were weighted to calculate total market valuation.
Driven by these market figures, geographic distribution was established using primary and secondary research insights. This framework incorporated an evaluation of regional market penetration for eco-friendly data centers. Through extensive secondary research, regional investments in Information and Communications Technology (ICT), national socioeconomic parameters, competitive vendor evaluation of key green data center providers, alongside organic and inorganic expansion strategies of global and regional stakeholders were quantified.
Data Triangulation
After determining the overall market size using the market size estimation processes as explained above, the market was split into several segments and subsegments. Data triangulation and market breakup procedures were employed, wherever applicable, to complete the overall market engineering process and arrive at the exact statistics of each market segment and subsegment. The overall market size was then used in the top-down procedure to estimate the size of other individual markets via percentage splits of the market segmentation.
Market Definition
Synthesizing perspectives from industry bodies and trade experts, MarketsandMarkets characterizes a green data center as a comprehensive ecosystem of power, thermal management, management software, and professional services tailored to drive sustainable, energy-efficient operations across data center environments. The power architecture encompasses green generation technologies, auxiliary energy storage, backup generators, and eco-friendly power distribution units, while thermal solutions feature advanced eco-air cooling and liquid cooling mechanisms. The software stack covers Data Center Infrastructure Management (DCIM), facility control systems, regulatory compliance monitoring, and related platforms. Supporting services incorporate sustainability consulting, energy assessment, green system integration, deployment, as well as ongoing eco-friendly maintenance. These technologies are integrated within hyperscale, colocation, and corporate facility environments to handle diverse compute workloads based on operational capacity.
According to IBM, a green data center—or eco-sustainable data center—denotes an operational facility built on highly efficient infrastructure that leverages clean technologies to optimize power consumption and minimize ecological footprints. Key evaluation metrics for sustainable data centers include facility footprint minimization, advanced thermal management efficiency, waste heat utilization, adoption of clean power alternatives, among other sustainability drivers.
Key Stakeholders
- Infrastructure & Equipment Vendors
- Software Solution Providers (DCIM, Energy Management, Compliance)
- Colocation Service Providers
- Hyperscale Cloud Providers
- Enterprises
- Renewable Energy Providers (Solar, Wind, Fuel Cells, etc.)
- Regulatory Bodies & Standards Organizations (ASHRAE, Uptime Institute, ISO, etc.)
- Consulting & Advisory Firms (Sustainability, Energy Audits, Certifications)
- Construction, Engineering & Real Estate Firms
- Investors and Real Estate Investment Trusts (REITs)
- System Integrators (SIs)
- Industry Alliances and Advocacy Groups
Report Objectives
- To define, describe, and forecast the green data center market based on component, data center size & capacity, data center type, and region
- To forecast the market size of the five major regional segments: North America, Europe, Asia Pacific, Middle East & Africa, and Latin America
- To strategically analyze the market subsegments concerning individual growth trends, prospects, and contributions to the total market
- To provide detailed information related to the major factors influencing market growth (drivers, restraints, opportunities, and challenges)
- To strategically analyze macro and micro markets1 with respect to growth trends, prospects, and their contribution to the overall market
- To analyze industry trends, patents and innovations, and pricing data related to the market
- To analyze the opportunities in the market for stakeholders and provide details of the competitive landscape for major players
- To profile key players in the market and comprehensively analyze their market share/ranking and core competencies2
- To track and analyze competitive developments, such as mergers & acquisitions, product developments, and partnerships & collaborations in the market
Available customizations:
With the given market data, MarketsandMarkets offers customizations as per the company’s specific needs. The following customization options are available for the report:
Product Analysis
- The product matrix provides a detailed comparison of the product portfolio of each company.y
Geographic Analysis based on feasibility
- Further breakup of the North American green data center market
- Further breakup of the European green data center market
- Further breakup of the Asia Pacific green data center market
- Further breakup of the Middle East & Africa green data center market
- Further breakup of the Latin American green data center market
Company Information
- Detailed analysis and profiling of additional market players (up to five)
Get the Full Green Data Center Market Report
Full forecast, segment splits, and company analysis for all Green Data Center Market.
- Canada Green Data Center Market
- US Green Data Center Market
- UK Green Data Center Market
- Germany Green Data Center Market
- France Green Data Center Market
- Italy Green Data Center Market
- China Green Data Center Market
- Japan Green Data Center Market
- India Green Data Center Market
- Saudi Arabia Green Data Center Market
- UAE Green Data Center Market
- South Africa Green Data Center Market
- Brazil Green Data Center Market
- Mexico Green Data Center Market
- Rest Of Europe Green Data Center Market
- Rest Of Asia Pacific Green Data Center Market
- Rest Of Latin America Green Data Center Market
- GCC Countries Green Data Center Market
- Rest Of GCC Countries Green Data Center Market
Need a Tailored Report?
Customize this report to your needs
Get 10% FREE Customization
Customize This Report
